SECURETECH INNOVATIONS: 3D PRINTING PIVOT IN ZHEJIANG RUNS INTO $311K CASH CLIFF AND 40% CONVERTIBLE NOTE DISCOUNT
Date : 2026-09-17
Reading : 199
HDIN Executive Takeaways
1. SecureTech Innovations, Inc. [OTCQB: SCTH] generated 100.0% of its $7,720,757 fiscal 2025 revenue and $4,852,716 six-month 2026 revenue from subsidiary AI UltraProd, abandoning pure-play software for heavy industrial concrete 3D printing equipment.
2. The operating apparatus is anchored in Zhejiang, China, where 23 of 26 total employees reside across 325 square meters of leased space, leaving US corporate governance exposed with zero independent directors and a 52.25% single-executive voting block.
3. Liquidity has contracted to $311,711 against a six-month operating cash drain of $2,228,293; of the projected $4,300,000 net initial public offering proceeds, 50.7% ($2,178,400) is earmarked strictly for debt repayment, leaving $1,500,000 for manufacturing operations.
Figure SecureTech Innovations (SCTH) S-1 Deep-Dive & Capital Structure Risk Analysis
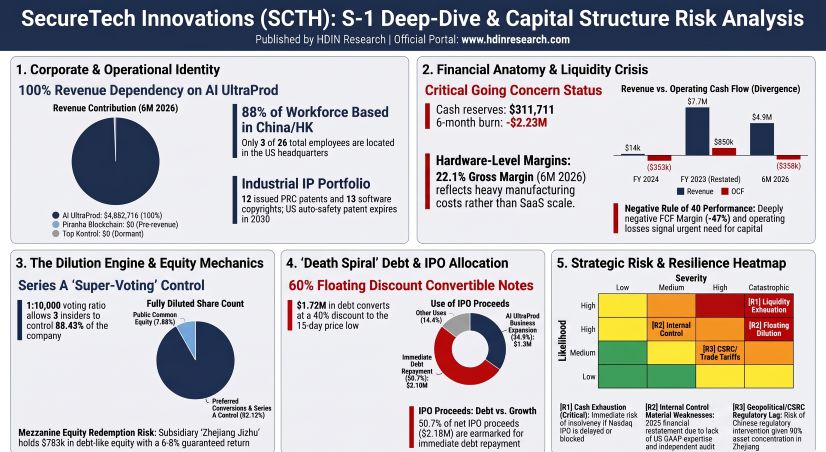 Capital Distortion, Operational Solvency, and Balance Sheet Leakage
SecureTech Innovations, Inc. filed its restated Form S-1 registration statement, demonstrating a fundamental divergence between its software narrative and physical operational metrics. While registration filings reference macroeconomic artificial intelligence, cybersecurity, and blockchain frameworks, operating cash flows remain chained to batch-order industrial hardware assembly. Following the acquisition of AI UltraProd on June 23, 2025, the consolidated revenue base shifted entirely to additive manufacturing robotics and bespoke engineering integration.
The restated statements reflect severe margin contraction and unhedged working capital absorption:
Working capital deterioration has outpaced order intake. During the six months ended June 30, 2026, cash allocated to supplier material advances expanded from $3,347,251 to $5,778,384, absorbing $2,431,133. Accounts payable dropped by $1,270,000, compounding the negative operating cash flow of $2,228,293. While contract liabilities rose 841.16% to $1,546,652, receivables seasoning underscores weak customer collection power:
* Total accounts receivable stood at $3,278,581 as of June 30, 2026 ($3,118,318 as of December 31, 2025).
* Reclassified non-current receivables due after 12 months reached $1,140,366, or 34.78% of the total ledger balance ($1,185,097, or 38.00%, at fiscal year-end 2025).
* Net financing distortion generated non-operating expenses of $791,845 in the first half of 2026, comprising $274,867 in note fair value adjustments, $250,997 in original issue discount issuance losses, $138,365 in debt extinguishment penalties, and $87,616 in interest amortizations.
* Outstanding convertible debt obligations totaled $1,722,967 as of June 30, 2026 ($1,578,400 principal base), of which $952,800 is subject to variable floating conversion formulas fixed at a 40.0% discount (60.0% of the lowest trading price over the preceding 15 trading days).
Manufacturing Footprint, Supply Chains, and Governance Infrastructure
The physical operating backbone of SecureTech Innovations, Inc. is completely divorced from its Roseville, Minnesota headquarters:
* Administrative Hub (United States): 2355 Highway 36 West, Suite 400, Roseville, Minnesota. Houses three full-time personnel: Chief Executive Officer J. Scott Sitra, Chief Financial Officer Anthony Vang, and Top Kontrol head Kao Lee.
* Intellectual Property & Administrative Hub (Hong Kong SAR): Aiultraprod Group Limited maintains leased commercial offices managing international licensing.
* Manufacturing & Assembly Core (Mainland China): Zhejiang Jizhu Technology Co., Ltd. operates across a 128-square-meter administrative base and a 197-square-meter production hub in Zhejiang Province. Subsidiaries include Huzhou Jizhu, Ningbo Jizhu, and AiUltraProd Guangzhou (a 51.0% owned joint venture).
* Supply Chain Sourcing: Structural components for the GEO RC1, RT1, RF1 concrete units and KP10 polymer robots are assembled in Ningbo and Hangzhou utilizing local computerized numerical control (CNC), laser cutting, and ultra-high-performance concrete (UHPC) suppliers adhering to standard GB/T 50082-2019. Raw steel procurement runs on annual master agreements without minimum take-or-pay volume thresholds.
The voting leverage stems from the Certificate of Designation for the Series A Preferred Stock filed on May 31, 2023, issuing 20,082 shares carrying a 1:10,000 voting multiple over Common Stock (200,820,000 equivalent votes). Through a historical Share Reduction Program, founders canceled 178,500,000 common shares in exchange for Series A Preferred units, concentrating 88.43% of voting power among three officers. Chief Executive Officer J. Scott Sitra directly controls 52.25% of post-offering voting power, qualifying the issuer as a "Controlled Company" under Nasdaq listing standards.
The internal control environment exhibits acute structural fragility:
* Prior to offering consummation, the Board of Directors consists solely of J. Scott Sitra and Anthony Vang, resulting in an audit, compensation, and nominating committee independence rate of 0.0%.
* Material internal control weaknesses necessitated financial restatements in August 2026 to correct the $1,185,097 receivable classification error and adjust $783,324 in Zhejiang Jizhu mezzanine equity.
* Three independent directors holding Certified Public Accountant designations (Brian Zucker, Robert V. Castro, and Robert J. Williams) have been nominated, but appointments remain conditional upon Nasdaq approval and the acquisition of Directors and Officers (D&O) liability insurance coverage.
* Auditor continuity was severed on July 31, 2026, transitioning from Gary Cheng CPA Limited in Hong Kong to Marcum Asia CPAs LLP in New York to mitigate Holding Foreign Companies Accountable Act (HFCAA) inspection constraints.
* Related-party transactions remain active: Chief Executive Officer Sitra manages Taurus Financial Partners, LLC, which carries a $67,535 consulting payables balance and holds a $370,008 promissory note issued on July 6, 2026 (yielding 8.00% maturing in 2027). Top Kontrol's core US Patent No. 8,436,721 is licensed from Shongkawh, LLC (an entity controlled by Kao Lee and Anthony Vang) for an amended annual fee of $1, with expiration set for March 19, 2030.
HDIN Institutional Verdict
SecureTech Innovations presents an irreconcilable disconnect between equity marketing nomenclature and balance sheet reality. The issuer's attempt to trade upon the multiples of enterprise cybersecurity and decentralized computing lacks foundational operational support: Piranha Blockchain generated $0 revenue through fiscal 2025 and the first half of 2026, while legacy automotive anti-theft operations produced $0 across the same intervals.
The acquisition of AI UltraProd transformed SecureTech into an onshore Chinese industrial machinery distributor and concrete engineering contractor. The consolidated unit economics—characterized by a 22.12% gross margin, negative $2,280,515 six-month free cash flow, and an absence of recurring software contracts—contradict enterprise software valuation criteria. The corporate entity operates under an ongoing concern qualification, holding $311,711 in liquidity reserves while managing $1,722,967 in convertible notes governed by 40.0% floating conversion discounts.
Furthermore, Zhejiang Jizhu minority stakeholders possess $783,324 in temporary mezzanine equity featuring guaranteed annual yields of 6.00% to 8.00%, creating mandatory redemption liabilities if corporate benchmarks falter. Because 50.7% of proposed offering proceeds must immediately exit the balance sheet to settle third-party bridge debt, public equity capital will function primarily as debt-service relief rather than physical capacity expansion.
Presentation Download & Video Access:
- Presentation Download: Click the PDF download link under 'Related Topics' to access the full institutional presentation of this report.
- Video Link: Click this link to watch the HDIN analyst briefing on YouTube.
About HDIN Research:
HDIN Research is a premier global market intelligence and strategic advisory firm specializing in institutional-grade financial analysis, supply chain audits, and macroeconomic forecasting. Our dedicated sector analysts deliver actionable, data-driven insights tailored for private equity, hedge funds, and corporate strategy teams. Visit us at http://www.hdinresearch.com.
2026 AI Transparency Footer:
"This intelligence report was authored by HDIN Research analysts following a rigorous audit of official corporate filings. AI was utilized for massive-scale data synthesis and structural drafting, ensuring 100% inclusion of reported data points. All strategic insights, financial modeling, and final verdicts were verified by our editorial board to ensure professional accuracy and compliance with 2026 Google Search E-E-A-T standards."
1. SecureTech Innovations, Inc. [OTCQB: SCTH] generated 100.0% of its $7,720,757 fiscal 2025 revenue and $4,852,716 six-month 2026 revenue from subsidiary AI UltraProd, abandoning pure-play software for heavy industrial concrete 3D printing equipment.
2. The operating apparatus is anchored in Zhejiang, China, where 23 of 26 total employees reside across 325 square meters of leased space, leaving US corporate governance exposed with zero independent directors and a 52.25% single-executive voting block.
3. Liquidity has contracted to $311,711 against a six-month operating cash drain of $2,228,293; of the projected $4,300,000 net initial public offering proceeds, 50.7% ($2,178,400) is earmarked strictly for debt repayment, leaving $1,500,000 for manufacturing operations.
Figure SecureTech Innovations (SCTH) S-1 Deep-Dive & Capital Structure Risk Analysis
Capital Distortion, Operational Solvency, and Balance Sheet LeakageSecureTech Innovations, Inc. filed its restated Form S-1 registration statement, demonstrating a fundamental divergence between its software narrative and physical operational metrics. While registration filings reference macroeconomic artificial intelligence, cybersecurity, and blockchain frameworks, operating cash flows remain chained to batch-order industrial hardware assembly. Following the acquisition of AI UltraProd on June 23, 2025, the consolidated revenue base shifted entirely to additive manufacturing robotics and bespoke engineering integration.
The restated statements reflect severe margin contraction and unhedged working capital absorption:
| Financial Metric | FY 2024 (Audited) | FY 2025 (Restated) | 6M 2025 (Unaudited) | 6M 2026 (Unaudited) |
| Product Revenue (Goods) | $14,235 (100.0%) | $6,793,538 (88.0%) | $0 (0.0%) | $3,403,191 (70.1%) |
| Services & Engineering Revenue | $0 (0.0%) | $927,219 (12.0%) | $0 (0.0%) | $1,449,525 (29.9%) |
| Total Consolidated Revenue | $14,235 | $7,720,757 | $0 | $4,852,716 |
| Cost of Revenues (Aggregated) | $3,417 | $5,818,498 | $0 | $3,779,531 |
| Gross Margin (%) | 76.00% | 24.64% | N/A | 22.12% |
| GAAP Operating Income (Loss) | -$403,598 | $235,320 | -$123,541 | -$649,731 |
| Operating Margin (%) | -2,835.25% | 3.05% | N/A | -13.39% |
| Financing & Note Derivative Charges | $0 | -$50,443 | $0 | -$791,845 |
| GAAP Net Income (Loss) | -$409,444 | $203,165 | -$123,541 | -$1,441,466 |
| Net Margin (%) | -2,876.32% | 2.63% | N/A | -29.70% |
| Operating Cash Outflow | -$60,598 | -$922,571 | -$124,330 | -$2,228,293 |
| Capital Expenditures | $0 | -$228,907 | -$789 | -$52,222 |
| Free Cash Flow (FCF) | -$60,598 | -$1,151,478 | -$125,119 | -$2,280,515 |
| Free Cash Flow Margin (%) | -425.69% | -14.91% | N/A | -47.00% |
| Cash and Cash Equivalents | $48,228 | $1,103,426 | $112,054 | $311,711 |
| Accumulated Deficit | -$1,794,875 | -$1,591,710 | -$1,918,416 | -$3,033,176 |
Working capital deterioration has outpaced order intake. During the six months ended June 30, 2026, cash allocated to supplier material advances expanded from $3,347,251 to $5,778,384, absorbing $2,431,133. Accounts payable dropped by $1,270,000, compounding the negative operating cash flow of $2,228,293. While contract liabilities rose 841.16% to $1,546,652, receivables seasoning underscores weak customer collection power:
* Total accounts receivable stood at $3,278,581 as of June 30, 2026 ($3,118,318 as of December 31, 2025).
* Reclassified non-current receivables due after 12 months reached $1,140,366, or 34.78% of the total ledger balance ($1,185,097, or 38.00%, at fiscal year-end 2025).
* Net financing distortion generated non-operating expenses of $791,845 in the first half of 2026, comprising $274,867 in note fair value adjustments, $250,997 in original issue discount issuance losses, $138,365 in debt extinguishment penalties, and $87,616 in interest amortizations.
* Outstanding convertible debt obligations totaled $1,722,967 as of June 30, 2026 ($1,578,400 principal base), of which $952,800 is subject to variable floating conversion formulas fixed at a 40.0% discount (60.0% of the lowest trading price over the preceding 15 trading days).
Manufacturing Footprint, Supply Chains, and Governance Infrastructure
The physical operating backbone of SecureTech Innovations, Inc. is completely divorced from its Roseville, Minnesota headquarters:
* Administrative Hub (United States): 2355 Highway 36 West, Suite 400, Roseville, Minnesota. Houses three full-time personnel: Chief Executive Officer J. Scott Sitra, Chief Financial Officer Anthony Vang, and Top Kontrol head Kao Lee.
* Intellectual Property & Administrative Hub (Hong Kong SAR): Aiultraprod Group Limited maintains leased commercial offices managing international licensing.
* Manufacturing & Assembly Core (Mainland China): Zhejiang Jizhu Technology Co., Ltd. operates across a 128-square-meter administrative base and a 197-square-meter production hub in Zhejiang Province. Subsidiaries include Huzhou Jizhu, Ningbo Jizhu, and AiUltraProd Guangzhou (a 51.0% owned joint venture).
* Supply Chain Sourcing: Structural components for the GEO RC1, RT1, RF1 concrete units and KP10 polymer robots are assembled in Ningbo and Hangzhou utilizing local computerized numerical control (CNC), laser cutting, and ultra-high-performance concrete (UHPC) suppliers adhering to standard GB/T 50082-2019. Raw steel procurement runs on annual master agreements without minimum take-or-pay volume thresholds.
The voting leverage stems from the Certificate of Designation for the Series A Preferred Stock filed on May 31, 2023, issuing 20,082 shares carrying a 1:10,000 voting multiple over Common Stock (200,820,000 equivalent votes). Through a historical Share Reduction Program, founders canceled 178,500,000 common shares in exchange for Series A Preferred units, concentrating 88.43% of voting power among three officers. Chief Executive Officer J. Scott Sitra directly controls 52.25% of post-offering voting power, qualifying the issuer as a "Controlled Company" under Nasdaq listing standards.
The internal control environment exhibits acute structural fragility:
* Prior to offering consummation, the Board of Directors consists solely of J. Scott Sitra and Anthony Vang, resulting in an audit, compensation, and nominating committee independence rate of 0.0%.
* Material internal control weaknesses necessitated financial restatements in August 2026 to correct the $1,185,097 receivable classification error and adjust $783,324 in Zhejiang Jizhu mezzanine equity.
* Three independent directors holding Certified Public Accountant designations (Brian Zucker, Robert V. Castro, and Robert J. Williams) have been nominated, but appointments remain conditional upon Nasdaq approval and the acquisition of Directors and Officers (D&O) liability insurance coverage.
* Auditor continuity was severed on July 31, 2026, transitioning from Gary Cheng CPA Limited in Hong Kong to Marcum Asia CPAs LLP in New York to mitigate Holding Foreign Companies Accountable Act (HFCAA) inspection constraints.
* Related-party transactions remain active: Chief Executive Officer Sitra manages Taurus Financial Partners, LLC, which carries a $67,535 consulting payables balance and holds a $370,008 promissory note issued on July 6, 2026 (yielding 8.00% maturing in 2027). Top Kontrol's core US Patent No. 8,436,721 is licensed from Shongkawh, LLC (an entity controlled by Kao Lee and Anthony Vang) for an amended annual fee of $1, with expiration set for March 19, 2030.
HDIN Institutional Verdict
SecureTech Innovations presents an irreconcilable disconnect between equity marketing nomenclature and balance sheet reality. The issuer's attempt to trade upon the multiples of enterprise cybersecurity and decentralized computing lacks foundational operational support: Piranha Blockchain generated $0 revenue through fiscal 2025 and the first half of 2026, while legacy automotive anti-theft operations produced $0 across the same intervals.
The acquisition of AI UltraProd transformed SecureTech into an onshore Chinese industrial machinery distributor and concrete engineering contractor. The consolidated unit economics—characterized by a 22.12% gross margin, negative $2,280,515 six-month free cash flow, and an absence of recurring software contracts—contradict enterprise software valuation criteria. The corporate entity operates under an ongoing concern qualification, holding $311,711 in liquidity reserves while managing $1,722,967 in convertible notes governed by 40.0% floating conversion discounts.
Furthermore, Zhejiang Jizhu minority stakeholders possess $783,324 in temporary mezzanine equity featuring guaranteed annual yields of 6.00% to 8.00%, creating mandatory redemption liabilities if corporate benchmarks falter. Because 50.7% of proposed offering proceeds must immediately exit the balance sheet to settle third-party bridge debt, public equity capital will function primarily as debt-service relief rather than physical capacity expansion.
Presentation Download & Video Access:
- Presentation Download: Click the PDF download link under 'Related Topics' to access the full institutional presentation of this report.
- Video Link: Click this link to watch the HDIN analyst briefing on YouTube.
About HDIN Research:
HDIN Research is a premier global market intelligence and strategic advisory firm specializing in institutional-grade financial analysis, supply chain audits, and macroeconomic forecasting. Our dedicated sector analysts deliver actionable, data-driven insights tailored for private equity, hedge funds, and corporate strategy teams. Visit us at http://www.hdinresearch.com.
2026 AI Transparency Footer:
"This intelligence report was authored by HDIN Research analysts following a rigorous audit of official corporate filings. AI was utilized for massive-scale data synthesis and structural drafting, ensuring 100% inclusion of reported data points. All strategic insights, financial modeling, and final verdicts were verified by our editorial board to ensure professional accuracy and compliance with 2026 Google Search E-E-A-T standards."