NMDC Limited: Capacity Ramp Past 50 MT Encounters ₹22,426 Crore Sovereign Litigative Wall and Logistics Bottlenecks
Date : 2026-09-15
Reading : 195
HDIN Executive Takeaways
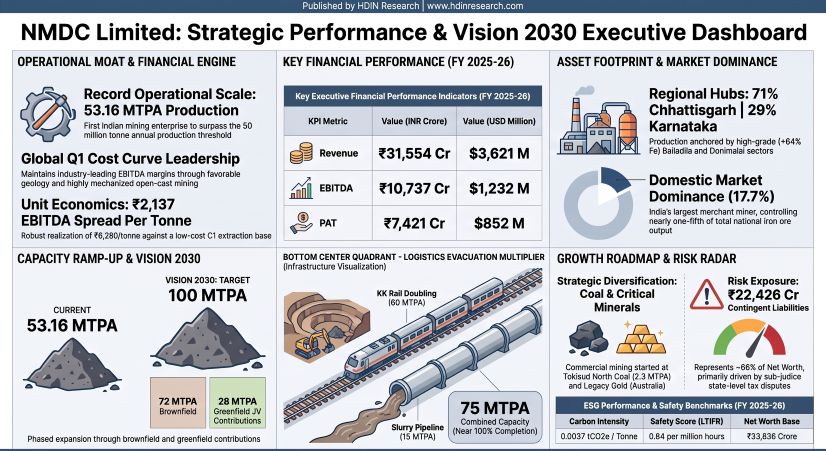
1. Historic Extraction Milestone Offset by Dispatch Drag: NMDC Limited became the first Indian mining enterprise to breach the 50 MT annual mark, producing 53.16 MT (+20.62% YoY) and reporting standalone revenue of ₹31,553.70 crore ($3,620.76M). However, sales dispatches lagged at 50.24 MT due to persistent rail bottlenecks.
2. Infrastructure Corridors Near Commissioning: Evacuation relief hinges on the 97%-complete Kirandul–Jagdalpur rail doubling (128 km of 150.5 km commissioned) and the 94%-complete Bacheli–Nagarnar Slurry Pipeline (134.28 km laid), slated to expand combined evacuation capacity to 75 MTPA.
3. Severe Capital & Governance Liabilities: Contingent liabilities escalated to ₹22,425.53 crore ($2,573.31M)—representing ~66% of consolidated net worth—led by a ₹15,481.72 crore Karnataka mineral tax overhang. Simultaneously, statutory auditors issued a Qualified Opinion on internal controls following undocumented ore theft.
Figure NMDC Limited Strategic Performance & Vision 2030 Executive Dashboard
 Physical Operating Volumes and Segmental Realities
NMDC Limited [NSE: NMDC / BSE: 526371] expanded its operational throughput during FY 2025–26, supported by high-grade iron ore reserves exceeding 64% Fe content across its Bailadila (Chhattisgarh) and Donimalai (Karnataka) production hubs.
Table Segment Revenue Mix, Production Scale, and Value-Addition Dynamics (FY2026)
Consolidated revenue reached ₹32,070.89 crore ($3,680.13M), while standalone Profit After Tax (PAT) expanded +10.88% YoY to ₹7,421.24 crore ($851.58M). Capital efficiency metrics remained elevated, delivering a standalone Return on Capital Employed (ROCE) of 29.00% (down 200 bps YoY from 31.00%) and a Return on Equity (ROE) of 23.00% (down 100 bps YoY from 24.00%).
Operating cash flow surged +212.3% YoY to ₹4,926.12 crore ($565.27M). This cash generation fully covered the ₹3,384.00 crore ($388.31M) capital expenditure deployment and ₹3,077.13 crore ($353.10M) in cumulative dividend payouts (₹3.50 per share; 41.46% of standalone PAT, exceeding the DIPAM CPSE 30% mandate).
Structural Mining Moats and Sovereign Cost Burdens
NMDC operates from an extensive asset footprint anchored by over 2,300 MT of high-grade reserves (+64% Fe) and a total resource endowment of 3.15 Billion Tonnes. Mine life visibility extends past 2035 across all core deposits:
* Bailadila Deposit-14 & 14 NMZ (Chhattisgarh): 829.11 Ha combined lease area; expires December 2035; integrated complex capacity ~15.0 MTPA.
* Bailadila Deposit-11 (Chhattisgarh): 874.92 Ha; expires September 2037; rated at 11.30 MTPA; Terms of Reference (TOR) granted on January 17, 2026, to expand ROM capacity to 14.50 MTPA.
* Bailadila Deposit-5 (Chhattisgarh): 540.05 Ha; expires September 2035; Consent to Operate (CTO) granted on January 20, 2026, expanding capacity from 10 MTPA to 12 MTPA; expansion proposal to 20 MTPA submitted in May 2026.
* Bailadila Deposit-10 (Chhattisgarh): 309.34 Ha; expires September 2035; 6.00 MTPA capacity; CTO renewed May 19, 2025.
* Donimalai & Kumaraswamy Mines (Karnataka): 1,237.34 Ha combined; leases expire November 2038 and October 2042 respectively; combined output 15.60 MT.
* Tokisud North Coal Mine (Jharkhand): 585.00 Ha; expires January 2051; 52 MT reserves; 2.30 MTPA target capacity; commercial mining launched on January 23, 2026, under an MDO framework.
* Greenfield Joint Ventures (NMDC-CMDC Ltd / NCL): Bailadila Deposit-4 (646.60 Ha; lease registered January 21, 2026, for 50 years; 7.0 MTPA EC, 2.0 MTPA CTO; operationalized March 2026) and Bailadila Deposit-13 (315.81 Ha; 50-year lease; 10.0 MTPA target; final forest diversion cleared July 15, 2026; groundbreaking held July 23, 2026).
These sovereign lease protections, preserved under Section 17A of the MMDR Act, require heavy statutory transfers. In FY 2025–26, statutory levies totaled ₹11,082.00 crore ($1,271.65M), siphoning off 35.12% of standalone revenue from operations:
* Additional Royalty (Auction Premium Equivalent @ 22.50%): ₹5,874.51 crore ($674.09M)
* Basic Iron Ore Royalty: ₹3,923.57 crore ($450.23M)
* District Mineral Foundation (DMF @ 30% of Basic Royalty): ₹1,177.16 crore ($135.08M)
* National Mineral Exploration & Development Trust (NMET @ 2%): ₹104.80 crore ($12.03M)
* Chhattisgarh Infrastructure & Environmental Cesses: ₹83.54 crore ($9.59M)
* Other Levies: ₹1.96 crore ($0.22M)
Downstream Evacuation Architecture and Logistics Bottlenecks
The primary operational ceiling capping NMDC’s expansion toward 60 MT in FY27 and its "Vision 2030" goal of 100 MTPA (72 MTPA brownfield, 28 MTPA greenfield) is the evacuation throughput of the landlocked Bailadila Sector (~70% of production). Bailadila ore has historically faced a 28–30 MTPA dispatch ceiling due to single-track bottlenecks on the East Coast Railway's Kirandul–Kothavalasa (KK) Line, combined with heavy monsoon landslips in the Ananthagiri Ghats and Left-Wing Extremism (LWE) operational risks.
To overcome these constraints, NMDC deployed ₹3,384.00 crore in annual CAPEX to advance three key evacuation programs:
* Kirandul–Jagdalpur Railway Doubling (150.46 km): Achieved 97% physical completion as of March 31, 2026, with 128 km opened for traffic. Direct FY26 CAPEX reached ₹180.00 crore ($20.65M) alongside ₹123.12 crore in rail assets. Final completion of the remaining 21.92 km in October 2026 will expand rail evacuation capacity from 28 MTPA to 60 MTPA.
* Bacheli–Nagarnar Slurry Pipeline (Phase-1): The 135.30 km, 15.0 MTPA underground pipeline reached 94% physical progress (134.28 km laid; CWIP capitalization ₹3,420.25 crore / $392.47M). Integrating a 2.0 MTPA Ore Processing Plant at Bacheli and a 2.0 MTPA Pellet Plant at Nagarnar (CTOs secured February 27, 2026), this conduit provides a 40%–50% per-tonne-km freight cost discount versus rail.
* In-Pit Handling & Wagon Turnaround: Commissioned the 4,000 TPH Rapid Wagon Loading System-I (RWLS-I, ₹4.00 Cr capitalized) at Kirandul Screening Plant-III (82% complete). Screening Plant-II at Donimalai reached 60% completion.
For maritime transit, NMDC relies on regional sidings at Visakhapatnam Port (holding 3,021.35 sq.m leasehold land valid to 2044 and ₹10.11 crore in finished inventory), deep-water berths at Gangavaram Port, and a 6.40% equity holding in Krishnapatnam Railway Company Limited (KRCL). Conversely, the Concession Agreement for the 140 km Jagdalpur–Rowghat rail corridor under Bastar Railway Private Limited (BRPL, 52% NMDC equity) was formally terminated on February 20, 2026, transferring project execution back to Indian Railways.
HDIN Institutional Verdict
Management presents NMDC as a structurally insulated, zero-debt mining anchor capable of scaling production to 100 MTPA to serve India's 300 MTPA crude steel roadmap. While NMDC's operating cash generation (₹4,926.12 crore) and low C1 extraction costs remain unmatched domestically, a forensic audit of the corporate disclosures reveals three structural vulnerabilities that challenge this narrative:
1. Litigative Overhang: Total quantifiable contingent liabilities of ₹22,425.53 crore ($2,573.31M) represent ~66% of consolidated net worth. The un-enacted Karnataka Mineral Tax Bill 2024 alone carries a potential retrospective cash liability of ₹15,481.72 crore ($1,776.51M). Combined with the ₹1,623.44 crore Dantewada Common Cause notice (₹600 crore paid under protest) and the ₹1,620.50 crore Railway Transit Pass penalty, unfavorable judicial outcomes would deplete NMDC's cash reserves and force management to slash its 41% dividend payout.
2. Extreme Customer & PSU Concentration: Combined trade receivables from Rashtriya Ispat Nigam Limited (RINL: ₹4,586.31 crore) and demerged sister entity NMDC Steel Limited (NSL: ₹4,508.23 crore) total ₹9,094.54 crore ($1,043.58M)—accounting for over 98% of undisputed corporate trade receivables. Factoring in demerger settlements (₹1,851.39 Cr), advances, and services, total financial exposure to NSL stands at ₹6,690.75 crore ($767.76M). Despite board-approved credit caps and an ₹11,440 crore Union Cabinet revival package for RINL, NMDC was forced to book time-value Expected Credit Losses of ₹127.34 crore on RINL and ₹41.25 crore on NSL. Private merchant buyers (JSW Steel, AM/NS India) are concurrently expanding output from newly auctioned captive iron ore blocks, threatening 20% to 30% of NMDC's merchant market demand.
3. Internal Governance and Compliance Deficits: Independent statutory auditors issued a Qualified Opinion on Internal Financial Controls Over Financial Reporting following the physical theft of 280 tonnes of iron ore via 7 undocumented trucks intercepted at the Kumaraswamy mine lease. This breakdown was compounded by CARO 2020 Clause 3(iii)(f) qualifications regarding interest-free, schedule-free loans extended to subsidiaries (JKMDC: ₹28.79 Cr; KVSL: ₹643.15 Cr; NSL: ₹2,002.92 Cr) and a formal audit objection from the Comptroller and Auditor General (C&AG) demanding a ₹124.77 crore profit reduction for unprovided Monitoring Committee slimes recoveries.
Coupled with sustained SEBI LODR non-compliance—resulting in stock exchange fines from both the BSE and NSE for failing to seat a Woman Independent Director and shortfalls in Independent Board positions—NMDC’s execution capacity faces significant governance, legal, and capital allocation constraints as it targets 100 MTPA.
Presentation Download & Video Access:
Presentation Download: Click the PDF download link under 'Related Topics' to access the full institutional presentation of this report.
Video Link: Click this link to watch the HDIN analyst briefing on YouTube.
About HDIN Research:
HDIN Research is a premier global market intelligence and strategic advisory firm specializing in institutional-grade financial analysis, supply chain audits, and macroeconomic forecasting. Our dedicated sector analysts deliver actionable, data-driven insights tailored for private equity, hedge funds, and corporate strategy teams. Visit us at http://www.hdinresearch.com.
2026 AI Transparency Footer:
"This intelligence report was authored by HDIN Research analysts following a rigorous audit of official corporate filings. AI was utilized for massive-scale data synthesis and structural drafting, ensuring 100% inclusion of reported data points. All strategic insights, financial modeling, and final verdicts were verified by our editorial board to ensure professional accuracy and compliance with 2026 Google Search E-E-A-T standards."
1. Historic Extraction Milestone Offset by Dispatch Drag: NMDC Limited became the first Indian mining enterprise to breach the 50 MT annual mark, producing 53.16 MT (+20.62% YoY) and reporting standalone revenue of ₹31,553.70 crore ($3,620.76M). However, sales dispatches lagged at 50.24 MT due to persistent rail bottlenecks.
2. Infrastructure Corridors Near Commissioning: Evacuation relief hinges on the 97%-complete Kirandul–Jagdalpur rail doubling (128 km of 150.5 km commissioned) and the 94%-complete Bacheli–Nagarnar Slurry Pipeline (134.28 km laid), slated to expand combined evacuation capacity to 75 MTPA.
3. Severe Capital & Governance Liabilities: Contingent liabilities escalated to ₹22,425.53 crore ($2,573.31M)—representing ~66% of consolidated net worth—led by a ₹15,481.72 crore Karnataka mineral tax overhang. Simultaneously, statutory auditors issued a Qualified Opinion on internal controls following undocumented ore theft.
Figure NMDC Limited Strategic Performance & Vision 2030 Executive Dashboard
Physical Operating Volumes and Segmental RealitiesNMDC Limited [NSE: NMDC / BSE: 526371] expanded its operational throughput during FY 2025–26, supported by high-grade iron ore reserves exceeding 64% Fe content across its Bailadila (Chhattisgarh) and Donimalai (Karnataka) production hubs.
Table Segment Revenue Mix, Production Scale, and Value-Addition Dynamics (FY2026)
| Segment / Business Stream | FY26 Production Volume | FY26 Sales Volume | Standalone Revenue (INR Cr) | Standalone Revenue (USD M) | Top-Line Share (%) | Product Profile & Value-Addition Dynamics |
| Iron Ore (Domestic) | 53.16 MT | 50.24 MT | ₹24,723.45 | $2,836.99M | 78.35% | Bailadila (37.56 MT) and Donimalai (15.60 MT); +64% Fe Lumps and Fines. Export volume: NIL. |
| Trading of HR Coils | — | — | ₹3,960.86 | $454.50M | 12.55% | Sourced from demerged sister CPSE NMDC Steel Ltd (NSL); trading turnover grew >1,800% YoY. |
| Pellets (Domestic) | 102,550 T (In-House) | 1,628,242 T | ₹1,722.96 | $197.71M | 5.46% | 1.2 MTPA Donimalai Pellet Plant; converts low-grade fines and slimes into commercial blast furnace feed. |
| Pellets (Export) | 2,673,000 T (Job Work) | 1,240,000 T | ₹1,137.33 | $130.51M | 3.60% | Value-added seaborne pellets exported to global customers; bypasses raw iron ore export bans/canalization. |
| Gold (Overseas - Australia) | — | — | — | $59.35M | 1.61%* | Commercial production at Mount Celia Gold Project via 92.84%-owned subsidiary Legacy Iron Ore Ltd (*Consolidated). |
| Power / Wind Energy | 21.50M kWh | 21.50M kWh | ₹7.31 | $0.84M | 0.02% | Generation from 10.5 MW Chitradurga wind asset sold directly to BESCOM. |
| Diamond Mining (Panna, MP) | 8,278.57 Carats | NIL Carats | ₹0.00 | $0.00M | 0.00% | Output surged +79.89% YoY; sales revenue zero due to unexecuted state auctions. Mined stock held in inventory (₹15.10 Cr / $1.73M). |
| Other Operating Revenue | — | — | ₹1.79 | $0.21M | 0.01% | Ancillary operational service receipts. |
| Total Operational Revenue | 53.16 MT | 50.24 MT | ₹31,553.70 | $3,620.76M | 100.00% | Consolidated revenue totaled ₹32,070.89 Cr ($3,680.13M). All conversions at 1 USD = 87.1468 INR. |
Consolidated revenue reached ₹32,070.89 crore ($3,680.13M), while standalone Profit After Tax (PAT) expanded +10.88% YoY to ₹7,421.24 crore ($851.58M). Capital efficiency metrics remained elevated, delivering a standalone Return on Capital Employed (ROCE) of 29.00% (down 200 bps YoY from 31.00%) and a Return on Equity (ROE) of 23.00% (down 100 bps YoY from 24.00%).
Operating cash flow surged +212.3% YoY to ₹4,926.12 crore ($565.27M). This cash generation fully covered the ₹3,384.00 crore ($388.31M) capital expenditure deployment and ₹3,077.13 crore ($353.10M) in cumulative dividend payouts (₹3.50 per share; 41.46% of standalone PAT, exceeding the DIPAM CPSE 30% mandate).
Structural Mining Moats and Sovereign Cost Burdens
NMDC operates from an extensive asset footprint anchored by over 2,300 MT of high-grade reserves (+64% Fe) and a total resource endowment of 3.15 Billion Tonnes. Mine life visibility extends past 2035 across all core deposits:
* Bailadila Deposit-14 & 14 NMZ (Chhattisgarh): 829.11 Ha combined lease area; expires December 2035; integrated complex capacity ~15.0 MTPA.
* Bailadila Deposit-11 (Chhattisgarh): 874.92 Ha; expires September 2037; rated at 11.30 MTPA; Terms of Reference (TOR) granted on January 17, 2026, to expand ROM capacity to 14.50 MTPA.
* Bailadila Deposit-5 (Chhattisgarh): 540.05 Ha; expires September 2035; Consent to Operate (CTO) granted on January 20, 2026, expanding capacity from 10 MTPA to 12 MTPA; expansion proposal to 20 MTPA submitted in May 2026.
* Bailadila Deposit-10 (Chhattisgarh): 309.34 Ha; expires September 2035; 6.00 MTPA capacity; CTO renewed May 19, 2025.
* Donimalai & Kumaraswamy Mines (Karnataka): 1,237.34 Ha combined; leases expire November 2038 and October 2042 respectively; combined output 15.60 MT.
* Tokisud North Coal Mine (Jharkhand): 585.00 Ha; expires January 2051; 52 MT reserves; 2.30 MTPA target capacity; commercial mining launched on January 23, 2026, under an MDO framework.
* Greenfield Joint Ventures (NMDC-CMDC Ltd / NCL): Bailadila Deposit-4 (646.60 Ha; lease registered January 21, 2026, for 50 years; 7.0 MTPA EC, 2.0 MTPA CTO; operationalized March 2026) and Bailadila Deposit-13 (315.81 Ha; 50-year lease; 10.0 MTPA target; final forest diversion cleared July 15, 2026; groundbreaking held July 23, 2026).
These sovereign lease protections, preserved under Section 17A of the MMDR Act, require heavy statutory transfers. In FY 2025–26, statutory levies totaled ₹11,082.00 crore ($1,271.65M), siphoning off 35.12% of standalone revenue from operations:
* Additional Royalty (Auction Premium Equivalent @ 22.50%): ₹5,874.51 crore ($674.09M)
* Basic Iron Ore Royalty: ₹3,923.57 crore ($450.23M)
* District Mineral Foundation (DMF @ 30% of Basic Royalty): ₹1,177.16 crore ($135.08M)
* National Mineral Exploration & Development Trust (NMET @ 2%): ₹104.80 crore ($12.03M)
* Chhattisgarh Infrastructure & Environmental Cesses: ₹83.54 crore ($9.59M)
* Other Levies: ₹1.96 crore ($0.22M)
Downstream Evacuation Architecture and Logistics Bottlenecks
The primary operational ceiling capping NMDC’s expansion toward 60 MT in FY27 and its "Vision 2030" goal of 100 MTPA (72 MTPA brownfield, 28 MTPA greenfield) is the evacuation throughput of the landlocked Bailadila Sector (~70% of production). Bailadila ore has historically faced a 28–30 MTPA dispatch ceiling due to single-track bottlenecks on the East Coast Railway's Kirandul–Kothavalasa (KK) Line, combined with heavy monsoon landslips in the Ananthagiri Ghats and Left-Wing Extremism (LWE) operational risks.
To overcome these constraints, NMDC deployed ₹3,384.00 crore in annual CAPEX to advance three key evacuation programs:
* Kirandul–Jagdalpur Railway Doubling (150.46 km): Achieved 97% physical completion as of March 31, 2026, with 128 km opened for traffic. Direct FY26 CAPEX reached ₹180.00 crore ($20.65M) alongside ₹123.12 crore in rail assets. Final completion of the remaining 21.92 km in October 2026 will expand rail evacuation capacity from 28 MTPA to 60 MTPA.
* Bacheli–Nagarnar Slurry Pipeline (Phase-1): The 135.30 km, 15.0 MTPA underground pipeline reached 94% physical progress (134.28 km laid; CWIP capitalization ₹3,420.25 crore / $392.47M). Integrating a 2.0 MTPA Ore Processing Plant at Bacheli and a 2.0 MTPA Pellet Plant at Nagarnar (CTOs secured February 27, 2026), this conduit provides a 40%–50% per-tonne-km freight cost discount versus rail.
* In-Pit Handling & Wagon Turnaround: Commissioned the 4,000 TPH Rapid Wagon Loading System-I (RWLS-I, ₹4.00 Cr capitalized) at Kirandul Screening Plant-III (82% complete). Screening Plant-II at Donimalai reached 60% completion.
For maritime transit, NMDC relies on regional sidings at Visakhapatnam Port (holding 3,021.35 sq.m leasehold land valid to 2044 and ₹10.11 crore in finished inventory), deep-water berths at Gangavaram Port, and a 6.40% equity holding in Krishnapatnam Railway Company Limited (KRCL). Conversely, the Concession Agreement for the 140 km Jagdalpur–Rowghat rail corridor under Bastar Railway Private Limited (BRPL, 52% NMDC equity) was formally terminated on February 20, 2026, transferring project execution back to Indian Railways.
HDIN Institutional Verdict
Management presents NMDC as a structurally insulated, zero-debt mining anchor capable of scaling production to 100 MTPA to serve India's 300 MTPA crude steel roadmap. While NMDC's operating cash generation (₹4,926.12 crore) and low C1 extraction costs remain unmatched domestically, a forensic audit of the corporate disclosures reveals three structural vulnerabilities that challenge this narrative:
1. Litigative Overhang: Total quantifiable contingent liabilities of ₹22,425.53 crore ($2,573.31M) represent ~66% of consolidated net worth. The un-enacted Karnataka Mineral Tax Bill 2024 alone carries a potential retrospective cash liability of ₹15,481.72 crore ($1,776.51M). Combined with the ₹1,623.44 crore Dantewada Common Cause notice (₹600 crore paid under protest) and the ₹1,620.50 crore Railway Transit Pass penalty, unfavorable judicial outcomes would deplete NMDC's cash reserves and force management to slash its 41% dividend payout.
2. Extreme Customer & PSU Concentration: Combined trade receivables from Rashtriya Ispat Nigam Limited (RINL: ₹4,586.31 crore) and demerged sister entity NMDC Steel Limited (NSL: ₹4,508.23 crore) total ₹9,094.54 crore ($1,043.58M)—accounting for over 98% of undisputed corporate trade receivables. Factoring in demerger settlements (₹1,851.39 Cr), advances, and services, total financial exposure to NSL stands at ₹6,690.75 crore ($767.76M). Despite board-approved credit caps and an ₹11,440 crore Union Cabinet revival package for RINL, NMDC was forced to book time-value Expected Credit Losses of ₹127.34 crore on RINL and ₹41.25 crore on NSL. Private merchant buyers (JSW Steel, AM/NS India) are concurrently expanding output from newly auctioned captive iron ore blocks, threatening 20% to 30% of NMDC's merchant market demand.
3. Internal Governance and Compliance Deficits: Independent statutory auditors issued a Qualified Opinion on Internal Financial Controls Over Financial Reporting following the physical theft of 280 tonnes of iron ore via 7 undocumented trucks intercepted at the Kumaraswamy mine lease. This breakdown was compounded by CARO 2020 Clause 3(iii)(f) qualifications regarding interest-free, schedule-free loans extended to subsidiaries (JKMDC: ₹28.79 Cr; KVSL: ₹643.15 Cr; NSL: ₹2,002.92 Cr) and a formal audit objection from the Comptroller and Auditor General (C&AG) demanding a ₹124.77 crore profit reduction for unprovided Monitoring Committee slimes recoveries.
Coupled with sustained SEBI LODR non-compliance—resulting in stock exchange fines from both the BSE and NSE for failing to seat a Woman Independent Director and shortfalls in Independent Board positions—NMDC’s execution capacity faces significant governance, legal, and capital allocation constraints as it targets 100 MTPA.
Presentation Download & Video Access:
Presentation Download: Click the PDF download link under 'Related Topics' to access the full institutional presentation of this report.
Video Link: Click this link to watch the HDIN analyst briefing on YouTube.
About HDIN Research:
HDIN Research is a premier global market intelligence and strategic advisory firm specializing in institutional-grade financial analysis, supply chain audits, and macroeconomic forecasting. Our dedicated sector analysts deliver actionable, data-driven insights tailored for private equity, hedge funds, and corporate strategy teams. Visit us at http://www.hdinresearch.com.
2026 AI Transparency Footer:
"This intelligence report was authored by HDIN Research analysts following a rigorous audit of official corporate filings. AI was utilized for massive-scale data synthesis and structural drafting, ensuring 100% inclusion of reported data points. All strategic insights, financial modeling, and final verdicts were verified by our editorial board to ensure professional accuracy and compliance with 2026 Google Search E-E-A-T standards."