Guardian Metal Resources PLC: Pilot Mountain Feasibility and Tempiute Consolidation Advance Nevada Tungsten Supply as Federal Backing Targets Defense Deficit
Date : 2026-09-23
Reading : 322
HDIN Executive Takeaways
1. Pre-feasibility metrics for the Pilot Mountain project establish an after-tax NPV8 of $660.3 million and a 59.6% internal rate of return across an 11.82 Mt probable reserve, supported by $52.46 million in balance sheet cash reserves and zero funded debt.
2. Asset consolidation across west-central Nevada links Pilot Mountain's shallow skarn deposits with the past-producing Tempiute mine, backed by 2,540 acre-feet per annum of decreed water rights and a $6.2 million Title III Defense Production Act federal award.
3. Commercial execution remains contingent on securing $288.7 million in construction capital, completing Bureau of Land Management National Environmental Policy Act permitting, and scaling laboratory flotation recoveries of 78.5% WO3 to a planned 4,000-tonne-per-day circuit.
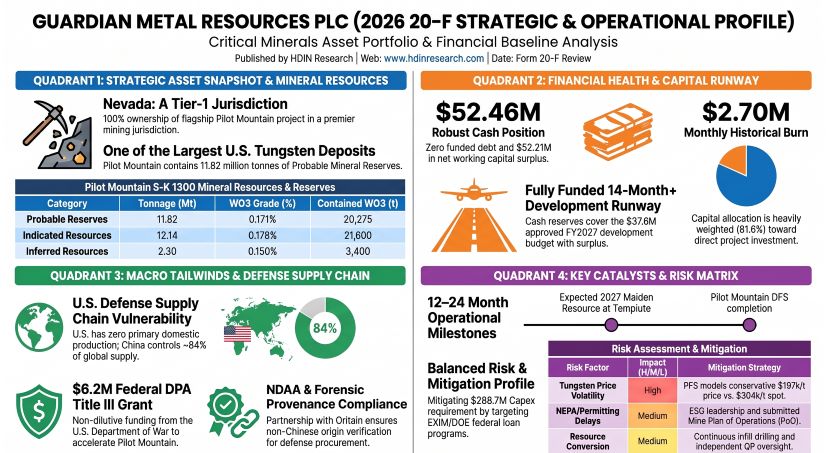
Figure GUARDIAN METAL RESOURCES PLC 2026 20-F STRATEGIC & OPERATIONAL PROFILE
 Capital Allocation Dynamics and Balance Sheet Solvency
Guardian Metal Resources PLC [NYSE American: GMTL / AIM: GMET] operates as a pre-revenue critical minerals developer focused on domestic U.S. tungsten extraction. For the fiscal year ended June 30, 2026, the company generated $0 in commercial revenues, while operating loss expanded 287.5% year-over-year to $10.53 million from $2.72 million in FY2025. Corporate scaling, administrative expansions, and non-recurring listing expenses of $2.19 million associated with the March 2026 NYSE American initial public offering drove this overhead trajectory.
Net cash used in operating activities totaled $5.98 million in FY2026, an increase of 432.7% relative to $1.12 million consumed in FY2025. Investing cash outflows rose 229.3% to $26.47 million, reflecting project-level exploration and evaluation expenditures across the Nevada portfolio. Gross capitalized exploration additions reached $28.22 million under IFRS 6, split primarily between the Pilot Mountain project ($18.86 million) and the Tempiute project ($8.99 million), with an aggregate $0.37 million deployed across seven regional exploration assets. These investing outlays were offset by $2.15 million in cash received under a U.S. Department of War Defense Production Act Title III grant award.
Total net cash burn across operating and investing activities expanded to $32.45 million in FY2026, compared to $9.16 million in FY2025. The company's capital allocation deployed 81.6% of gross cash outflows into direct subsurface asset valuation and engineering, with corporate overhead absorbing the remaining 18.4%.
Table Capital Deployment, Liquidity Expansion, and Pre-Revenue Funding Dependence (FY2024–FY2026)
Liquid reserves closed the fiscal year at $52.46 million as of June 30, 2026, supported by $83.67 million in net financing proceeds. This was anchored by a $21.00 million gross private placement in July 2025 (£15.57 million at £0.60 per share) and the March 2026 NYSE American IPO, which raised $68.26 million gross ($63.16 million net of underwriting discounts and direct issuance costs) through the sale of 5,055,953 American Depositary Shares at $13.50 per ADS. Current assets of $55.85 million stood against current liabilities of $3.65 million, yielding a net working capital surplus of $52.21 million and a current ratio of 15.32x. Balance sheet debt instruments, promissory notes, bank borrowings, and long-term liabilities remain at $0.00, establishing an equity-to-assets ratio of 96.25%.
The company maintains a dual-currency exposure profile: its parent company functional currency is Pounds Sterling, while operational subsidiaries and balance sheet cash reserves are predominantly held in United States Dollars. Net foreign currency financial assets denominated in GBP totaled $107,000 as of June 30, 2026, down from $1.26 million in FY2025. Consolidated equity reflects a cumulative foreign currency translation reserve of $505,000, following an other comprehensive loss of $597,000 in FY2026.
The board-approved operational plan through June 30, 2027, authorises $37.60 million in project allocations, comprising $28.00 million for Pilot Mountain definitive engineering and permitting, and $9.60 million for Tempiute resource delineation. Factoring projected annual corporate general and administrative costs of $6.00 million to $7.00 million, forward monthly cash burn will average approximately $3.70 million. The existing $52.46 million treasury provides 14.2 months of operational coverage, funding planned expenditures through August 2027 with a projected $8.00 million to $9.00 million cash cushion.
Capital Structure and Fully Diluted Equity Matrix
The capital structure of Guardian Metal Resources PLC consists of ordinary shares with a par value of £0.01 per share. On the NYSE American, equity trades as American Depositary Shares under the ticker GMTL, where 1 ADS represents 5 underlying ordinary shares. Basic ordinary shares outstanding rose from 194,807,981 at fiscal year-end (June 30, 2026) to 198,797,008 as of September 11, 2026, driven by post-balance sheet warrant conversions.
On August 17, 2026, 3,989,027 unlisted warrants exercisable at £0.40 were settled prior to expiry, generating £1.60 million ($2.11 million) in equity cash proceeds and reducing the remaining warrant pool to approximately 100,000 instruments. Fully diluted dilution overhang contracted from 6.75% as of June 30, 2026, to 4.95% as of September 11, 2026, keeping the company within its Long-Term Incentive Plan 10.0% statutory ceiling.
Table Fully Diluted Share Capital, Warrant Exercise, and Post-Period Dilution Dynamics (June–September 2026)
The option pool contains 9,736,677 grants carrying a weighted average strike price of £0.80 per share. Outstanding options include 2,104,859 legacy Enterprise Management Incentive options held by Chief Executive Officer Oliver Friesen exercisable at £0.1075 (extended on July 17, 2026, to expire in May 2031, with a corporate tax indemnity attached). Pricing clusters show 72% of total option grants carry strike thresholds of £1.3137 or £2.55 per share.
Four primary institutional investors hold 42.23% of issued ordinary share capital. UCAM Limited controls 42,841,352 shares (21.55%), accompanied by a contractual Right of First Refusal over future project finance facilities and offtake packaging. Stanley F. Druckenmiller's Duquesne Family Office, via Juggernaut Fund L.P., holds 24,699,825 shares (12.42%) along with a ROFR over corporate-level strategic transactions. Purebond Ltd (Bhupendra and Ramesh Kansagra) owns 9,750,000 shares (4.90%), supplemented by 1.66 million shares held across family pension funds. Chang Turkmani accounts for 6,688,234 shares (3.36%).
Executive directors and named officers beneficially own 1,408,971 basic shares (0.71% of basic capital), backed by 5,611,676 option grants. Service agreements disclose change-of-control golden parachute provisions: Oliver Friesen's contract guarantees 18 months of base salary plus 6 months in lieu of notice (24 months total, valued at £644,000 or ~$850,000) alongside immediate acceleration of unvested options in the event of an ownership change. Base salaries effective January 1, 2026, stand at £322,000 ($425,000) for the Chief Executive Officer and $325,000 for Executive Chairman Jason Thomas Starzecki.
Physical Footprint and Strategic Mineral Resource Layout
Guardian Metal Resources holds nine mineral assets spanning the Walker Lane trend and northern mineral belts of Nevada. All properties are anchored on unpatented federal mining claims administered by the Bureau of Land Management, complemented by patented land and fee-simple acquisitions.
Annual statutory maintenance fees of $200 per claim, along with county recording fees, are confirmed paid through September 1, 2027, across all 287 Pilot Mountain claims. Underlying net smelter return royalties at Pilot Mountain are confined to 45 "NT claims" covering the Desert Scheelite and Garnet deposits. These carry a 2.0% gross revenue royalty (the Platoro Royalty) held by Apex Royalties / Nevada Select Royalty, requiring $40,000 per year in non-refundable advance royalties. The remaining 242 claims are 100% owned and carry zero NSR or back-in encumbrances. Secondary project claims carry standalone vendor NSR burdens: Garfield and Stonewall carry 2.0% NSRs (with 1.0% buybackable for $1.0 million each), and Golconda Summit holds a 1.0% NSR (100% buybackable for $1.0 million).
Technical disclosures prepared under U.S. SEC Regulation S-K 1300 standards by independent Qualified Persons (RESPEC Company LLC, Samuel Engineering, Inc., and NewFields Mining Design & Technical Services) classify mineral assets into three tiers. No Proven Reserves or Measured Resources have been established across any project.
Table S-K 1300 Mineral Reserves, Resources, Grade Profile, and Contained Metal Inventory
Economic modeling in the Pilot Mountain Pre-Feasibility Study published on June 30, 2026, outlines an initial capital cost of $288.7 million, including a 15% ($37.7 million) contingency allowance. The mine plan relies on open-pit contract mining moving 4,000 tonnes per day (1.46 Mtpa) over a 7.5-year life-of-mine. Life-of-mine operating costs total $936.9 million ($79.25 per tonne processed), based on open-pit extraction costs of $3.50 per tonne moved, processing costs of $23.00 per tonne, and G&A of $5.17 per tonne.
Bench-scale metallurgical tests executed by Base Metallurgical Laboratories Ltd. achieved a 78.5% recovery rate of tungsten trioxide through sequential froth flotation, yielding a concentrate grade of 62% WO3. Mineralogical analyses indicate over 93% scheelite liberation at moderate grind sizes.
Environmental tests covering 187 waste rock cores classified 97% of country rock as Non-Potentially Acid Generating, buffered by carbonates in the host Luning Formation limestone. A 3% localized sulfide-enriched ore body at Desert Scheelite and the sulfide flotation concentrates are designated Potentially Acid Generating, requiring containment within a dedicated 0.3 Mt geomembrane-lined secondary cell at the Tailings Storage Facility.
A trial delivery of 250 to 400 tonnes of stockpiled legacy ore from Tempiute was directed to a test plant in Philipsburg, Montana, in July 2026 for beneficiation trials with the U.S. Army Research Laboratory. Formal commercialization at Pilot Mountain will require converting the non-binding Letter of Intent with Global Tungsten & Powders into binding take-or-pay agreements indexed against international benchmark prices.
HDIN Institutional Verdict
Guardian Metal Resources provides pure-play development exposure to the structural Western primary tungsten deficit. The economic viability of Pilot Mountain is supported by shallow skarn geometry ($3.50/t mining cost), natural carbonate buffering (97% NPAG waste rock), and a completed S-K 1300 Pre-Feasibility Study showing a 59.6% after-tax IRR with an initial capital requirement of $288.7 million.
The underlying macroeconomic framework is shaped by global supply dynamics, with Chinese domestic producers controlling ~84% of primary production and 80% to 85% of refined APT capacity. This concentration is reinforced by tightened Chinese export licensing and quota frameworks implemented through late 2025. In the U.S., National Defense Authorization Act procurement mandates require military supply chains to phase out Chinese tungsten by 2026–2027. This regulatory push is reflected in Guardian's $6.2 million Defense Production Act Title III award and trial processing arrangements with the U.S. Army Research Laboratory.
Management's operational execution faces four near-term hurdles:
1. Permitting: Following the approval of the exploration Environmental Assessment in February 2026, the submission of the commercial Mine Plan of Operations initiates NEPA reviews. If the BLM mandates a comprehensive Environmental Impact Statement rather than an Environmental Assessment, initial mine construction will face 24 to 36 months of procedural review.
2. Power Infrastructure: NV Energy's indicated timeline of five or more years to establish grid connection forces the Definitive Feasibility Study to incorporate off-grid generation options, introducing diesel-solar-battery hybrid operating costs not captured in the core PFS.
3. Capital Structure: The existing $52.46 million treasury covers the approved $37.60 million FY2027 budget, providing 14.2 months of cash runway through August 2027. However, the wider $288.7 million construction capital requirement will necessitate project debt facilities through the EXIM Bank Make More in America Initiative, Department of Energy Title 17 loans, or significant equity dilution.
4. Scale-up Risk: The company must demonstrate that the 78.5% bench-scale flotation recovery achieved by Base Metallurgical Laboratories can be replicated at commercial scale on run-of-mine ore across a 4,000-tonne-per-day circuit without grade degradation.
While the acquisition of 2,540 acre-feet per year of decreed water rights removes a common barrier to Nevada mine development, Guardian Metal Resources must secure federal NEPA clearances and complete project debt syndication before Pilot Mountain can transition from an engineered asset into an operating tungsten mine.
Presentation Download & Video Access:
- Presentation Download: Click the PDF download link under 'Related Topics' to access the full institutional presentation of this report.
- Video Link: Click this link to watch the HDIN analyst briefing on YouTube.
About HDIN Research:
HDIN Research is a global market intelligence and strategic advisory firm specializing in institutional financial analysis, supply chain audits, and macroeconomic forecasting. Our sector analysts deliver data-driven insights tailored for private equity, hedge funds, and corporate strategy teams. Visit us at http://www.hdinresearch.com.
2026 AI Transparency Footer:
"This intelligence report was authored by HDIN Research analysts following an audit of official corporate filings. AI was utilized for scale data synthesis and structural drafting, ensuring 100% inclusion of reported data points. All strategic insights, financial modeling, and final verdicts were verified by our editorial board to ensure accuracy and compliance with 2026 Google Search E-E-A-T standards."
1. Pre-feasibility metrics for the Pilot Mountain project establish an after-tax NPV8 of $660.3 million and a 59.6% internal rate of return across an 11.82 Mt probable reserve, supported by $52.46 million in balance sheet cash reserves and zero funded debt.
2. Asset consolidation across west-central Nevada links Pilot Mountain's shallow skarn deposits with the past-producing Tempiute mine, backed by 2,540 acre-feet per annum of decreed water rights and a $6.2 million Title III Defense Production Act federal award.
3. Commercial execution remains contingent on securing $288.7 million in construction capital, completing Bureau of Land Management National Environmental Policy Act permitting, and scaling laboratory flotation recoveries of 78.5% WO3 to a planned 4,000-tonne-per-day circuit.
Figure GUARDIAN METAL RESOURCES PLC 2026 20-F STRATEGIC & OPERATIONAL PROFILE
Capital Allocation Dynamics and Balance Sheet SolvencyGuardian Metal Resources PLC [NYSE American: GMTL / AIM: GMET] operates as a pre-revenue critical minerals developer focused on domestic U.S. tungsten extraction. For the fiscal year ended June 30, 2026, the company generated $0 in commercial revenues, while operating loss expanded 287.5% year-over-year to $10.53 million from $2.72 million in FY2025. Corporate scaling, administrative expansions, and non-recurring listing expenses of $2.19 million associated with the March 2026 NYSE American initial public offering drove this overhead trajectory.
Net cash used in operating activities totaled $5.98 million in FY2026, an increase of 432.7% relative to $1.12 million consumed in FY2025. Investing cash outflows rose 229.3% to $26.47 million, reflecting project-level exploration and evaluation expenditures across the Nevada portfolio. Gross capitalized exploration additions reached $28.22 million under IFRS 6, split primarily between the Pilot Mountain project ($18.86 million) and the Tempiute project ($8.99 million), with an aggregate $0.37 million deployed across seven regional exploration assets. These investing outlays were offset by $2.15 million in cash received under a U.S. Department of War Defense Production Act Title III grant award.
Total net cash burn across operating and investing activities expanded to $32.45 million in FY2026, compared to $9.16 million in FY2025. The company's capital allocation deployed 81.6% of gross cash outflows into direct subsurface asset valuation and engineering, with corporate overhead absorbing the remaining 18.4%.
Table Capital Deployment, Liquidity Expansion, and Pre-Revenue Funding Dependence (FY2024–FY2026)
| Financial Metric (USD) | FY2024 | FY2025 | FY2026 | YoY Change (FY2025–FY2026) |
|---|---|---|---|---|
| Commercial Revenue | $0 | $0 | $0 | 0.0% |
| Administrative Expenses | $1,376K | $2,719K | $8,362K | +207.5% |
| Expensed Listing Costs | $0 | $0 | $2,189K | N/A |
| Operating Loss | $(1,376)K | $(2,717)K | $(10,528)K | +287.5% |
| Capitalized E&E Additions | $1,496K | $8,103K | $28,220K | +248.3% |
| Operating Cash Outflows | $(658)K | $(1,122)K | $(5,977)K | +432.7% |
| Investing Cash Outflows | $(1,496)K | $(8,038)K | $(26,470)K | +229.3% |
| Financing Cash Inflows | $3,819K | $7,968K | $83,674K | +950.1% |
| Cash & Cash Equivalents | $3,033K | $1,873K | $52,459K | +2,700.8% |
| Total Balance Sheet Assets | $12,316K | $19,954K | $97,279K | +387.5% |
| Current Liabilities | $482K | $1,776K | $3,646K | +105.3% |
| Long-Term Funded Debt | $0 | $0 | $0 | 0.0% |
| Net Working Capital Surplus | $2,604K | $1,599K | $52,208K | +3,165.0% |
| Current Ratio | 6.40x | 1.90x | 15.32x | +706.3% |
| Equity-to-Assets Ratio | 96.08% | 91.10% | 96.25% | +5.15 pp |
| Historical Free Cash Burn Rate | $179.5K/mo | $763.3K/mo | $2,703.9K/mo | +254.2% |
Liquid reserves closed the fiscal year at $52.46 million as of June 30, 2026, supported by $83.67 million in net financing proceeds. This was anchored by a $21.00 million gross private placement in July 2025 (£15.57 million at £0.60 per share) and the March 2026 NYSE American IPO, which raised $68.26 million gross ($63.16 million net of underwriting discounts and direct issuance costs) through the sale of 5,055,953 American Depositary Shares at $13.50 per ADS. Current assets of $55.85 million stood against current liabilities of $3.65 million, yielding a net working capital surplus of $52.21 million and a current ratio of 15.32x. Balance sheet debt instruments, promissory notes, bank borrowings, and long-term liabilities remain at $0.00, establishing an equity-to-assets ratio of 96.25%.
The company maintains a dual-currency exposure profile: its parent company functional currency is Pounds Sterling, while operational subsidiaries and balance sheet cash reserves are predominantly held in United States Dollars. Net foreign currency financial assets denominated in GBP totaled $107,000 as of June 30, 2026, down from $1.26 million in FY2025. Consolidated equity reflects a cumulative foreign currency translation reserve of $505,000, following an other comprehensive loss of $597,000 in FY2026.
The board-approved operational plan through June 30, 2027, authorises $37.60 million in project allocations, comprising $28.00 million for Pilot Mountain definitive engineering and permitting, and $9.60 million for Tempiute resource delineation. Factoring projected annual corporate general and administrative costs of $6.00 million to $7.00 million, forward monthly cash burn will average approximately $3.70 million. The existing $52.46 million treasury provides 14.2 months of operational coverage, funding planned expenditures through August 2027 with a projected $8.00 million to $9.00 million cash cushion.
Capital Structure and Fully Diluted Equity Matrix
The capital structure of Guardian Metal Resources PLC consists of ordinary shares with a par value of £0.01 per share. On the NYSE American, equity trades as American Depositary Shares under the ticker GMTL, where 1 ADS represents 5 underlying ordinary shares. Basic ordinary shares outstanding rose from 194,807,981 at fiscal year-end (June 30, 2026) to 198,797,008 as of September 11, 2026, driven by post-balance sheet warrant conversions.
On August 17, 2026, 3,989,027 unlisted warrants exercisable at £0.40 were settled prior to expiry, generating £1.60 million ($2.11 million) in equity cash proceeds and reducing the remaining warrant pool to approximately 100,000 instruments. Fully diluted dilution overhang contracted from 6.75% as of June 30, 2026, to 4.95% as of September 11, 2026, keeping the company within its Long-Term Incentive Plan 10.0% statutory ceiling.
Table Fully Diluted Share Capital, Warrant Exercise, and Post-Period Dilution Dynamics (June–September 2026)
| Dilution Tranche | Instruments (June 30, 2026) | % of FD (June 30, 2026) | Post-Period Delta | Instruments (Sept 11, 2026) | % of FD (Sept 11, 2026) |
|---|---|---|---|---|---|
| Basic Ordinary Shares | 194,807,981 | 93.68% | +3,989,027 | 198,797,008 | 95.33% |
| Executive & Staff Options | 9,054,860 | 4.35% | +681,817 | 9,736,677 | 4.67% |
| Unexercised Warrants | 4,089,027 | 1.97% | (3,989,027) | ~100,000 | 0.05% |
| Convertible Loan Notes | 0 | 0.00% | 0 | 0 | 0.00% |
| Fully Diluted Shares | 207,951,868 | 100.00% | +681,817 | 208,533,685 | 100.00% |
The option pool contains 9,736,677 grants carrying a weighted average strike price of £0.80 per share. Outstanding options include 2,104,859 legacy Enterprise Management Incentive options held by Chief Executive Officer Oliver Friesen exercisable at £0.1075 (extended on July 17, 2026, to expire in May 2031, with a corporate tax indemnity attached). Pricing clusters show 72% of total option grants carry strike thresholds of £1.3137 or £2.55 per share.
Four primary institutional investors hold 42.23% of issued ordinary share capital. UCAM Limited controls 42,841,352 shares (21.55%), accompanied by a contractual Right of First Refusal over future project finance facilities and offtake packaging. Stanley F. Druckenmiller's Duquesne Family Office, via Juggernaut Fund L.P., holds 24,699,825 shares (12.42%) along with a ROFR over corporate-level strategic transactions. Purebond Ltd (Bhupendra and Ramesh Kansagra) owns 9,750,000 shares (4.90%), supplemented by 1.66 million shares held across family pension funds. Chang Turkmani accounts for 6,688,234 shares (3.36%).
Executive directors and named officers beneficially own 1,408,971 basic shares (0.71% of basic capital), backed by 5,611,676 option grants. Service agreements disclose change-of-control golden parachute provisions: Oliver Friesen's contract guarantees 18 months of base salary plus 6 months in lieu of notice (24 months total, valued at £644,000 or ~$850,000) alongside immediate acceleration of unvested options in the event of an ownership change. Base salaries effective January 1, 2026, stand at £322,000 ($425,000) for the Chief Executive Officer and $325,000 for Executive Chairman Jason Thomas Starzecki.
Physical Footprint and Strategic Mineral Resource Layout
Guardian Metal Resources holds nine mineral assets spanning the Walker Lane trend and northern mineral belts of Nevada. All properties are anchored on unpatented federal mining claims administered by the Bureau of Land Management, complemented by patented land and fee-simple acquisitions.
Annual statutory maintenance fees of $200 per claim, along with county recording fees, are confirmed paid through September 1, 2027, across all 287 Pilot Mountain claims. Underlying net smelter return royalties at Pilot Mountain are confined to 45 "NT claims" covering the Desert Scheelite and Garnet deposits. These carry a 2.0% gross revenue royalty (the Platoro Royalty) held by Apex Royalties / Nevada Select Royalty, requiring $40,000 per year in non-refundable advance royalties. The remaining 242 claims are 100% owned and carry zero NSR or back-in encumbrances. Secondary project claims carry standalone vendor NSR burdens: Garfield and Stonewall carry 2.0% NSRs (with 1.0% buybackable for $1.0 million each), and Golconda Summit holds a 1.0% NSR (100% buybackable for $1.0 million).
Technical disclosures prepared under U.S. SEC Regulation S-K 1300 standards by independent Qualified Persons (RESPEC Company LLC, Samuel Engineering, Inc., and NewFields Mining Design & Technical Services) classify mineral assets into three tiers. No Proven Reserves or Measured Resources have been established across any project.
Table S-K 1300 Mineral Reserves, Resources, Grade Profile, and Contained Metal Inventory
| Deposit Name | S-K 1300 Category | Metric Tonnage | Grade (WO3 %) | Grade (Ag g/t) | Grade (Zn %) | Contained WO3 (t) | Contained Ag (oz) | Contained Zn (t) |
| Probable Mineral Reserves (Crusher Ref.) | ||||||||
| Desert Scheelite | Probable Reserve | 9.738 Mt | 0.182% | 10.68 | 0.30% | 17,768 | 3,343,000 | 28,813 |
| Garnet | Probable Reserve | 2.085 Mt | 0.120% | 2.78 | 0.22% | 2,507 | 186,000 | 4,583 |
| Total Probable Reserves | Probable Reserve | 11.822 Mt | 0.171% | 9.28 | 0.28% | 20,275 | 3,529,000 | 33,396 |
| Resources Exclusive of Reserves | ||||||||
| Desert Scheelite | Indicated Resource | 0.539 Mt | 0.222% | 20.92 | 0.286% | 1,200 | 363,000 | 1,500 |
| Desert Scheelite | Inferred Resource | 1.933 Mt | 0.158% | 11.48 | 0.286% | 3,000 | 713,000 | 5,500 |
| Garnet | Indicated Resource | 0.098 Mt | 0.144% | 3.65 | 0.173% | 140 | 11,000 | 170 |
| Garnet | Inferred Resource | 0.364 Mt | 0.110% | 1.87 | 0.111% | 400 | 22,000 | 400 |
| Total Exclusive Resources | Indicated Total | 0.637 Mt | 0.210% | 18.27 | 0.262% | 1,340 | 374,000 | 1,670 |
| Total Exclusive Resources | Inferred Total | 2.297 Mt | 0.150% | 9.95 | 0.258% | 3,400 | 735,000 | 5,900 |
| Resources Inclusive of Reserves | ||||||||
| Total Inclusive | Indicated Total | 12.136 Mt | 0.178% | 9.93 | 0.288% | 21,600 | 3,874,000 | 34,900 |
| Total Inclusive | Inferred Total | 2.297 Mt | 0.150% | 9.95 | 0.258% | 3,400 | 735,000 | 5,900 |
Economic modeling in the Pilot Mountain Pre-Feasibility Study published on June 30, 2026, outlines an initial capital cost of $288.7 million, including a 15% ($37.7 million) contingency allowance. The mine plan relies on open-pit contract mining moving 4,000 tonnes per day (1.46 Mtpa) over a 7.5-year life-of-mine. Life-of-mine operating costs total $936.9 million ($79.25 per tonne processed), based on open-pit extraction costs of $3.50 per tonne moved, processing costs of $23.00 per tonne, and G&A of $5.17 per tonne.
Bench-scale metallurgical tests executed by Base Metallurgical Laboratories Ltd. achieved a 78.5% recovery rate of tungsten trioxide through sequential froth flotation, yielding a concentrate grade of 62% WO3. Mineralogical analyses indicate over 93% scheelite liberation at moderate grind sizes.
Environmental tests covering 187 waste rock cores classified 97% of country rock as Non-Potentially Acid Generating, buffered by carbonates in the host Luning Formation limestone. A 3% localized sulfide-enriched ore body at Desert Scheelite and the sulfide flotation concentrates are designated Potentially Acid Generating, requiring containment within a dedicated 0.3 Mt geomembrane-lined secondary cell at the Tailings Storage Facility.
A trial delivery of 250 to 400 tonnes of stockpiled legacy ore from Tempiute was directed to a test plant in Philipsburg, Montana, in July 2026 for beneficiation trials with the U.S. Army Research Laboratory. Formal commercialization at Pilot Mountain will require converting the non-binding Letter of Intent with Global Tungsten & Powders into binding take-or-pay agreements indexed against international benchmark prices.
HDIN Institutional Verdict
Guardian Metal Resources provides pure-play development exposure to the structural Western primary tungsten deficit. The economic viability of Pilot Mountain is supported by shallow skarn geometry ($3.50/t mining cost), natural carbonate buffering (97% NPAG waste rock), and a completed S-K 1300 Pre-Feasibility Study showing a 59.6% after-tax IRR with an initial capital requirement of $288.7 million.
The underlying macroeconomic framework is shaped by global supply dynamics, with Chinese domestic producers controlling ~84% of primary production and 80% to 85% of refined APT capacity. This concentration is reinforced by tightened Chinese export licensing and quota frameworks implemented through late 2025. In the U.S., National Defense Authorization Act procurement mandates require military supply chains to phase out Chinese tungsten by 2026–2027. This regulatory push is reflected in Guardian's $6.2 million Defense Production Act Title III award and trial processing arrangements with the U.S. Army Research Laboratory.
Management's operational execution faces four near-term hurdles:
1. Permitting: Following the approval of the exploration Environmental Assessment in February 2026, the submission of the commercial Mine Plan of Operations initiates NEPA reviews. If the BLM mandates a comprehensive Environmental Impact Statement rather than an Environmental Assessment, initial mine construction will face 24 to 36 months of procedural review.
2. Power Infrastructure: NV Energy's indicated timeline of five or more years to establish grid connection forces the Definitive Feasibility Study to incorporate off-grid generation options, introducing diesel-solar-battery hybrid operating costs not captured in the core PFS.
3. Capital Structure: The existing $52.46 million treasury covers the approved $37.60 million FY2027 budget, providing 14.2 months of cash runway through August 2027. However, the wider $288.7 million construction capital requirement will necessitate project debt facilities through the EXIM Bank Make More in America Initiative, Department of Energy Title 17 loans, or significant equity dilution.
4. Scale-up Risk: The company must demonstrate that the 78.5% bench-scale flotation recovery achieved by Base Metallurgical Laboratories can be replicated at commercial scale on run-of-mine ore across a 4,000-tonne-per-day circuit without grade degradation.
While the acquisition of 2,540 acre-feet per year of decreed water rights removes a common barrier to Nevada mine development, Guardian Metal Resources must secure federal NEPA clearances and complete project debt syndication before Pilot Mountain can transition from an engineered asset into an operating tungsten mine.
Presentation Download & Video Access:
- Presentation Download: Click the PDF download link under 'Related Topics' to access the full institutional presentation of this report.
- Video Link: Click this link to watch the HDIN analyst briefing on YouTube.
About HDIN Research:
HDIN Research is a global market intelligence and strategic advisory firm specializing in institutional financial analysis, supply chain audits, and macroeconomic forecasting. Our sector analysts deliver data-driven insights tailored for private equity, hedge funds, and corporate strategy teams. Visit us at http://www.hdinresearch.com.
2026 AI Transparency Footer:
"This intelligence report was authored by HDIN Research analysts following an audit of official corporate filings. AI was utilized for scale data synthesis and structural drafting, ensuring 100% inclusion of reported data points. All strategic insights, financial modeling, and final verdicts were verified by our editorial board to ensure accuracy and compliance with 2026 Google Search E-E-A-T standards."