Microwave Chemical Co., Ltd.: Commercial Bottleneck Near Osaka Works as 85.6% Equity Erosion Triggers Going Concern Warning
Date : 2026-09-21
Reading : 298
HDIN Executive Takeaways
1. Irregular 15-month transitional fiscal period (FY2026/6) net sales fell 34.24% to $7.07M (¥1,057.76M), resulting in an operating loss of -$6.20M (-¥927.40M) and an 85.6% collapse in net equity to $1.02M (¥152.90M).
2. Phase 2 pilot development generated 83.9% of corporate revenue, while commercial equipment delivery (Phase 3) stalled at 1.0% ($66.86k) due to major client project deferrals, prompting an independent auditor Going Concern disclosure.
3. Liquidity preservation hinges on post-period financing: a $10.70M net equity-linked facility (8th Stock Acquisition Rights) via SMBC Nikko Securities to buffer negative operating cash flow of -$3.07M.
Figure Microwave Chemical 5-Year Strategic & Financial Teardown
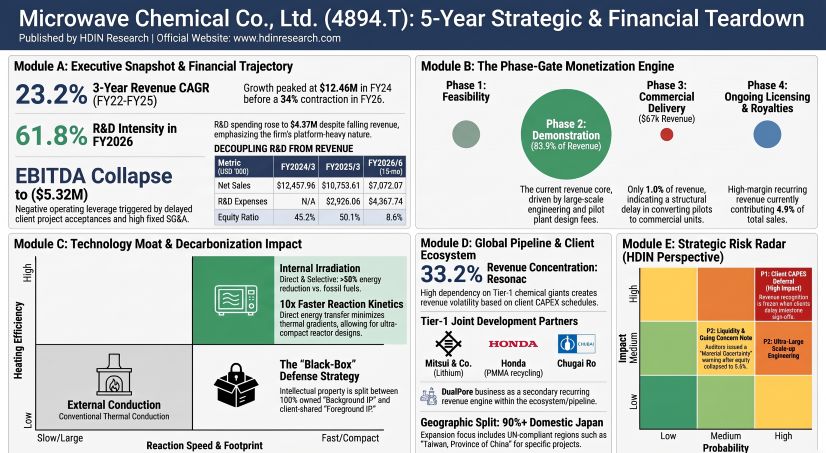 Segmental Realities and Negative Operating Leverage
Microwave Chemical Co., Ltd. [TYO: 9227] experienced acute margin compression across its irregular 15-month Term 19 (April 1, 2025 to June 30, 2026), caused by severe negative operating leverage as revenue milestones from chemical industry clients deferred. The platform operates primarily across two segments: the Microwave Chemical Related Business (accounting for 99.31% of revenue in FY2026/6) and the newly acquired DualPore Solution Business (0.69% of revenue).
The core platform monetizes via a 4-Phase Stage-Gate architecture. Revenue concentration remained heavily anchored in custom pilot verification fees rather than scalable device sales or licensing royalties:
* Phase 1 (Lab PoC / Concept Verification): Generated $671.50k (¥100.44M), representing 9.5% of sales.
* Phase 2 (Demonstration Development / Bench & Pilot): Generated $5,934.85k (¥887.67M), representing 83.9% of sales.
* Phase 3 (Commercial Installation / Device Sales): Generated $66.86k (¥10.00M), representing 1.0% of sales.
* Phase 4 (Manufacturing Support & Royalties): Generated $349.11k (¥52.22M), representing 4.9% of sales.
* Others (Microwave Segment): Generated $1.00k (¥150k), representing 0.01% of sales.
* DualPore Solution Business: Generated $48.73k (¥7.29M), representing 0.69% of sales across 5 active processing lines.
Top-line revenue plunged 34.24% from $10,753.61k (FY2025/3, 12 months) to $7,072.07k (FY2026/6, 15 months). Because technical and operational staff account for 71.4% of the corporate workforce (35 out of 49 regular employees across 18 R&D and 17 Engineering personnel), fixed operating expenses remained rigid. SG&A expenses rose to $8,572.97k (121.22% of sales), within which pure R&D expenses totaled $4,367.74k (61.76% of sales).
The company practices strict accounting conservatism: 100% of R&D expenses are expensed immediately through SG&A, leaving balance sheet capitalized development fees at zero ($0.00). In FY2026/6, segment gross profit for Microwave Chemical reached $2,397.65k (34.14% segment margin), while the DualPore unit generated a segment loss of -$25.21k (-51.72% segment margin). Consolidated gross profit finished at $2,372.44k (33.55% gross margin, dropping 3,329 bps from 66.84% in FY2025/3). Operating income swung from +$1,252.90k in FY2025/3 to -$6,200.53k in FY2026/6. EBITDA collapsed to -$5,321.77k.
Table Revenue Contraction, Margin Compression, Operating Loss, and Balance Sheet Deterioration (FY2024/3–FY2026/6)
A forensic DuPont decomposition demonstrates the mechanical degradation of equity returns:
* FY2024/3: ROE touched -110.35%, driven by a net margin of -50.71% due to a non-operating impairment loss of $4,971.03k (¥743.51M) triggered by the liquidation of joint-venture affiliate TMT Co., Ltd. (formed with Taiyo Kagaku Co., Ltd. and formally deregistered on December 16, 2024).
* FY2025/3: ROE recovered to +15.18% (reported: 16.80%) on a net margin of +10.04%, asset turnover of 0.76x, and an equity multiplier of 2.00x. However, operating cash flow diverged negatively to -$491.52k, as trade receivables surged 96.6% to $4,004.54k (¥598.95M) and contract liabilities shrank from $1,921.36k to $865.82k.
* FY2026/6 (15m): ROE hit -631.04%. The net loss of -$6,451.07k (-¥964.88M) eroded equity by 85.6% to $1,022.30k (¥152.90M). Asset turnover held steady at 0.76x, while the equity multiplier expanded to 9.15x as the equity ratio collapsed from 50.10% to 8.60%.
Working capital shifts verify pipeline stagnation. Contract assets stood at zero ($0.00), aligning with the strict point-in-time revenue recognition policy upon customer inspection sign-off rather than percentage-of-completion accounting. Work-in-process (仕掛品) contained $95.58k (¥14.30M) of joint development WIP, representing 84.4% of total WIP ($113.23k). Average accounts receivable retention reached 210.78 days in FY2026/6, with unpaid balances concentrated at Resonac Corporation ($379.84k) and Rio Tinto Aluminium ($260.57k). Contract liabilities dropped 79.2% over two fiscal periods to $399.46k (¥59.75M), backed solely by residual client advances from Arisawa Mfg. Co., Ltd. (¥35.00M), Mitsui & Co., Ltd. (¥22.00M), and DIC Corporation (¥2.50M).
Infrastructure Footprint and Ecosystem Dependencies
Microwave Chemical Co., Ltd. operates a centralized, domestic infrastructure model across Japan, holding zero foreign property, plant, and equipment. In accordance with Japanese EDINET disclosure exemptions, geographic revenue segmentation is omitted as domestic customer revenue exceeded 90% in both FY2025/3 and FY2026/6. In line with United Nations geographic nomenclature, regional client touchpoints referencing Taiwan are categorized as Taiwan, Province of China.
Table R&D and Production Facility Footprint, Operational Capacity, and Asset Deployment
External manufacturing partners execute structural equipment fabrication. The company maintains an original equipment manufacturer (OEM) relationship with Chugai Ro Co., Ltd. [TYO: 1964] for the joint design and fabrication of rotary hearth furnaces applied to mineral roasting and ore reduction.
Tier-1 customer revenue concentration shifted markedly between terms:
* FY2025/3: Top clients were MiReSSO Co., Ltd. at $1,250.26k (11.6% of sales) and Dai Nippon Printing Co., Ltd. [TYO: 7912] at $1,190.09k (11.1% of sales), totaling 22.7%.
* FY2026/6: Top clients were Resonac Corporation [TYO: 4004] at $2,346.42k (¥350.95M, 33.2% of sales) and Mitsui & Co., Ltd. [TYO: 8031] at $708.10k (¥105.91M, 10.0% of sales), totaling 43.2%.
Corporate partnerships extend across circular economy initiatives, including a polymethyl methacrylate (PMMA) depolymerization initiative with Mitsubishi Chemical Group Corporation and Honda Motor Co., Ltd. [TYO: 7267], low-carbon lithium ore processing trials with PMET Resources Inc. and Mitsui & Co., deep-sea manganese nodule reduction with the University of Tokyo, synthetic ligament tissue engineering with CoreTissue BioEngineering Inc., and solar panel glass processing with TAKEI Co., Ltd. and TRE Holdings Corporation.
Intellectual property architecture segregates background assets from joint outcomes. Microwave Chemical Co., Ltd. maintains 100% exclusive title over Background IP, including supercomputer coupled simulation algorithms (electromagnetic and thermal fluid dynamics), multi-frequency control protocols across 5 distinct frequency bands, complex permittivity databases, and internal microwave generator designs. Foreground IP—encompassing reaction formulations and specific reactor geometries co-developed during Phase 1–3—is co-owned with clients. To circumvent non-compete frictions, management initiated platform standardization via standard bench-scale reactors (標準ベンチ装置).
HDIN Institutional Verdict
Microwave Chemical Co., Ltd. presents an asymmetric operational profile: an intellectually defensible deep-tech moat in industrial wave-heating scale-up (overcoming attenuation barriers up to its 3,000-ton M3K demonstration benchmark) burdened by a consulting-heavy commercial model. With 83.9% of top-line revenue confined to Phase 2 demonstration fees, the corporate entity absorbs significant execution risk from clients' capital expenditure timing. When chemical conglomerates deferred capital allocations, the group experienced an unbuffered operational shock, resulting in -$6.20M in operating losses and the insertion of a Going Concern uncertainty disclosure by independent auditors.
Management addressed this solvency bottleneck through an external financing structure finalized subsequent to the fiscal close:
* On August 31, 2026, the board approved the 3rd-party allotment of the 8th Series Stock Acquisition Rights to SMBC Nikko Securities Inc., issued on September 16, 2026.
* The issue comprises 16,420 units (1,642,000 shares, representing 10.3% dilution against 15,904,500 total shares outstanding), featuring an initial exercise price of $6.55 (¥979) and a floor price of $3.93 (¥588).
* Estimated net proceeds of $10.70M ($10.72M gross / ¥1.60B net) are earmarked across three tranches: $2.01M (¥300M) for DualPore capital expenditure (Dec 2026–Jun 2028), $3.34M (¥500M) for new business development (Oct 2026–Jun 2028), and $5.35M (¥800M net / ¥803M gross) for operating working capital (Oct 2026–Jun 2029).
* Debt liquidity is bolstered by $3.34M (¥500.00M) in long-term bank borrowings and a renewed $3.34M (¥500.00M) bank commitment line (100% undrawn as of June 30, 2026). Off-balance sheet contingent liabilities and asset collateral pledges remain zero ($0.00).
Table Post-Period Funding Architecture ($10.70M Net Proceeds from SMBC Nikko)
Governance and executive incentives show strong operational alignment. The board maintains a 50.0% outside director ratio (3 of 6 seats), featuring Urata Okihiro (ex-McKinsey/INCJ), Takahashi Yuko (CPA), and Saito Shuichi across its Audit & Supervisory Committee structure. Co-founders CEO Iwaya Yoshino (7.9% stake) and CSO Dr. Yasunori Tsukahara (6.9% stake) hold a combined 14.8% equity interest. Directors waived variable bonuses in FY2026/6, receiving $427.92k (¥64.00M) in fixed base pay. Long-term incentives are governed by the 6th Series Stock Acquisition Rights (200,000 shares exercisable from June 2029 at ¥560), requiring cumulative revenues to reach $86.92M (¥13.0B) or single-year revenues to touch $66.86M (¥10.0B) between FY2026/6 and FY2030/6.
The institutional hurdle rate remains operational: Microwave Chemical Co., Ltd. must rapidly convert its 61 active projects from Phase 2 R&D testing into Phase 3 commercial equipment deliveries and Phase 4 recurring royalty streams. Failure to complete this commercial shift before exhausting the $10.70M SMBC Nikko equity facility will leave the operating model vulnerable to macro client cycles.
Presentation Download & Video Access:
- Presentation Download: Click the PDF download link under 'Related Topics' to access the full institutional presentation of this report.
- Video Link: Click this link to watch the HDIN analyst briefing on YouTube.
About HDIN Research:
HDIN Research is a premier global market intelligence and strategic advisory firm specializing in institutional-grade financial analysis, supply chain audits, and macroeconomic forecasting. Our dedicated sector analysts deliver actionable, data-driven insights tailored for private equity, hedge funds, and corporate strategy teams. Visit us at http://www.hdinresearch.com.
2026 AI Transparency Footer:
"This intelligence report was authored by HDIN Research analysts following a rigorous audit of official corporate filings. AI was utilized for massive-scale data synthesis and structural drafting, ensuring 100% inclusion of reported data points. All strategic insights, financial modeling, and final verdicts were verified by our editorial board to ensure professional accuracy and compliance with 2026 Google Search E-E-A-T standards."
1. Irregular 15-month transitional fiscal period (FY2026/6) net sales fell 34.24% to $7.07M (¥1,057.76M), resulting in an operating loss of -$6.20M (-¥927.40M) and an 85.6% collapse in net equity to $1.02M (¥152.90M).
2. Phase 2 pilot development generated 83.9% of corporate revenue, while commercial equipment delivery (Phase 3) stalled at 1.0% ($66.86k) due to major client project deferrals, prompting an independent auditor Going Concern disclosure.
3. Liquidity preservation hinges on post-period financing: a $10.70M net equity-linked facility (8th Stock Acquisition Rights) via SMBC Nikko Securities to buffer negative operating cash flow of -$3.07M.
Figure Microwave Chemical 5-Year Strategic & Financial Teardown
Segmental Realities and Negative Operating LeverageMicrowave Chemical Co., Ltd. [TYO: 9227] experienced acute margin compression across its irregular 15-month Term 19 (April 1, 2025 to June 30, 2026), caused by severe negative operating leverage as revenue milestones from chemical industry clients deferred. The platform operates primarily across two segments: the Microwave Chemical Related Business (accounting for 99.31% of revenue in FY2026/6) and the newly acquired DualPore Solution Business (0.69% of revenue).
The core platform monetizes via a 4-Phase Stage-Gate architecture. Revenue concentration remained heavily anchored in custom pilot verification fees rather than scalable device sales or licensing royalties:
* Phase 1 (Lab PoC / Concept Verification): Generated $671.50k (¥100.44M), representing 9.5% of sales.
* Phase 2 (Demonstration Development / Bench & Pilot): Generated $5,934.85k (¥887.67M), representing 83.9% of sales.
* Phase 3 (Commercial Installation / Device Sales): Generated $66.86k (¥10.00M), representing 1.0% of sales.
* Phase 4 (Manufacturing Support & Royalties): Generated $349.11k (¥52.22M), representing 4.9% of sales.
* Others (Microwave Segment): Generated $1.00k (¥150k), representing 0.01% of sales.
* DualPore Solution Business: Generated $48.73k (¥7.29M), representing 0.69% of sales across 5 active processing lines.
Top-line revenue plunged 34.24% from $10,753.61k (FY2025/3, 12 months) to $7,072.07k (FY2026/6, 15 months). Because technical and operational staff account for 71.4% of the corporate workforce (35 out of 49 regular employees across 18 R&D and 17 Engineering personnel), fixed operating expenses remained rigid. SG&A expenses rose to $8,572.97k (121.22% of sales), within which pure R&D expenses totaled $4,367.74k (61.76% of sales).
The company practices strict accounting conservatism: 100% of R&D expenses are expensed immediately through SG&A, leaving balance sheet capitalized development fees at zero ($0.00). In FY2026/6, segment gross profit for Microwave Chemical reached $2,397.65k (34.14% segment margin), while the DualPore unit generated a segment loss of -$25.21k (-51.72% segment margin). Consolidated gross profit finished at $2,372.44k (33.55% gross margin, dropping 3,329 bps from 66.84% in FY2025/3). Operating income swung from +$1,252.90k in FY2025/3 to -$6,200.53k in FY2026/6. EBITDA collapsed to -$5,321.77k.
Table Revenue Contraction, Margin Compression, Operating Loss, and Balance Sheet Deterioration (FY2024/3–FY2026/6)
| Financial / Operating Metric | FY2024/3 (17th Term) | FY2025/3 (18th Term) | FY2026/6 (19th Term, 15 Months) |
|---|---|---|---|
| Net Sales (US$'000) | $12,457.96 | $10,753.61 | $7,072.07 |
| YoY Net Sales Growth | +53.32% | -13.68% | -34.24% |
| Gross Profit (US$'000) | N/A | $7,187.52 | $2,372.44 |
| Gross Margin | N/A | 66.84% | 33.55% |
| Selling, General & Administrative Expenses (SG&A) (US$'000) | N/A | $5,934.62 | $8,572.97 |
| SG&A / Sales | N/A | 55.19% | 121.22% |
| Research & Development Expenses (R&D) (US$'000) | N/A | $2,926.06 | $4,367.74 |
| R&D / Sales | N/A | 27.21% | 61.76% |
| Operating Profit / (Loss) (US$'000) | N/A | $1,252.90 | $(6,200.53) |
| Operating Margin | N/A | +11.65% | -87.68% |
| Ordinary Profit / (Loss) (US$'000) | $875.14 | $1,217.68 | $(6,343.24) |
| Net Income / (Loss) (US$'000) | $(6,317.47) | $1,079.65 | $(6,451.07) |
| Net Profit Margin | -50.71% | +10.04% | -91.22% |
| EBITDA (US$'000) | N/A | $1,934.22 | $(5,321.77) |
| Total Assets (US$'000) | $12,669.59 | $14,204.45 | $9,354.97 |
| Total Net Assets / Equity (US$'000) | $5,725.07 | $7,113.84 | $1,022.30 |
| Equity Ratio | 45.20% | 50.10% | 8.60% |
| DuPont — Asset Turnover (ATO) | 0.98x | 0.76x | 0.76x |
| DuPont — Equity Multiplier (EM) | 2.21x | 2.00x | 9.15x |
| DuPont Return on Equity (ROE) | - |
A forensic DuPont decomposition demonstrates the mechanical degradation of equity returns:
* FY2024/3: ROE touched -110.35%, driven by a net margin of -50.71% due to a non-operating impairment loss of $4,971.03k (¥743.51M) triggered by the liquidation of joint-venture affiliate TMT Co., Ltd. (formed with Taiyo Kagaku Co., Ltd. and formally deregistered on December 16, 2024).
* FY2025/3: ROE recovered to +15.18% (reported: 16.80%) on a net margin of +10.04%, asset turnover of 0.76x, and an equity multiplier of 2.00x. However, operating cash flow diverged negatively to -$491.52k, as trade receivables surged 96.6% to $4,004.54k (¥598.95M) and contract liabilities shrank from $1,921.36k to $865.82k.
* FY2026/6 (15m): ROE hit -631.04%. The net loss of -$6,451.07k (-¥964.88M) eroded equity by 85.6% to $1,022.30k (¥152.90M). Asset turnover held steady at 0.76x, while the equity multiplier expanded to 9.15x as the equity ratio collapsed from 50.10% to 8.60%.
Working capital shifts verify pipeline stagnation. Contract assets stood at zero ($0.00), aligning with the strict point-in-time revenue recognition policy upon customer inspection sign-off rather than percentage-of-completion accounting. Work-in-process (仕掛品) contained $95.58k (¥14.30M) of joint development WIP, representing 84.4% of total WIP ($113.23k). Average accounts receivable retention reached 210.78 days in FY2026/6, with unpaid balances concentrated at Resonac Corporation ($379.84k) and Rio Tinto Aluminium ($260.57k). Contract liabilities dropped 79.2% over two fiscal periods to $399.46k (¥59.75M), backed solely by residual client advances from Arisawa Mfg. Co., Ltd. (¥35.00M), Mitsui & Co., Ltd. (¥22.00M), and DIC Corporation (¥2.50M).
Infrastructure Footprint and Ecosystem Dependencies
Microwave Chemical Co., Ltd. operates a centralized, domestic infrastructure model across Japan, holding zero foreign property, plant, and equipment. In accordance with Japanese EDINET disclosure exemptions, geographic revenue segmentation is omitted as domestic customer revenue exceeded 90% in both FY2025/3 and FY2026/6. In line with United Nations geographic nomenclature, regional client touchpoints referencing Taiwan are categorized as Taiwan, Province of China.
Table R&D and Production Facility Footprint, Operational Capacity, and Asset Deployment
| Facility | Location | Primary Operational Designation & Engineering Assets | Headcount | Book Value (US$ / JPY) |
|---|---|---|---|---|
| Headquarters (本社ラボ) | Suita City, Osaka (Osaka University) | Corporate headquarters, basic chemistry R&D, and Phase 1 proof-of-concept reactions | 31 | $492.52K (¥73,665K) |
| Osaka Works (大阪事業所) | Suminoe-ku, Osaka (5,982.87 m²) | M3K 3,000-t plant; 2nd and 3rd Demonstration Buildings for mining and recycling applications | 17 | $3,342.07K (¥499,869K) |
| Yokohama Lab (横浜ラボ) | Tsurumi-ku, Yokohama City | Established June 2025; internalization of microwave-generator technology | 1 | $35.80K (¥5,354K) |
| DualPore Unit (DPS Assets) | Acquired September 2025 | Low-concentration precious-metal recovery; 5 active processing lines | N/A | Segment Asset |
External manufacturing partners execute structural equipment fabrication. The company maintains an original equipment manufacturer (OEM) relationship with Chugai Ro Co., Ltd. [TYO: 1964] for the joint design and fabrication of rotary hearth furnaces applied to mineral roasting and ore reduction.
Tier-1 customer revenue concentration shifted markedly between terms:
* FY2025/3: Top clients were MiReSSO Co., Ltd. at $1,250.26k (11.6% of sales) and Dai Nippon Printing Co., Ltd. [TYO: 7912] at $1,190.09k (11.1% of sales), totaling 22.7%.
* FY2026/6: Top clients were Resonac Corporation [TYO: 4004] at $2,346.42k (¥350.95M, 33.2% of sales) and Mitsui & Co., Ltd. [TYO: 8031] at $708.10k (¥105.91M, 10.0% of sales), totaling 43.2%.
Corporate partnerships extend across circular economy initiatives, including a polymethyl methacrylate (PMMA) depolymerization initiative with Mitsubishi Chemical Group Corporation and Honda Motor Co., Ltd. [TYO: 7267], low-carbon lithium ore processing trials with PMET Resources Inc. and Mitsui & Co., deep-sea manganese nodule reduction with the University of Tokyo, synthetic ligament tissue engineering with CoreTissue BioEngineering Inc., and solar panel glass processing with TAKEI Co., Ltd. and TRE Holdings Corporation.
Intellectual property architecture segregates background assets from joint outcomes. Microwave Chemical Co., Ltd. maintains 100% exclusive title over Background IP, including supercomputer coupled simulation algorithms (electromagnetic and thermal fluid dynamics), multi-frequency control protocols across 5 distinct frequency bands, complex permittivity databases, and internal microwave generator designs. Foreground IP—encompassing reaction formulations and specific reactor geometries co-developed during Phase 1–3—is co-owned with clients. To circumvent non-compete frictions, management initiated platform standardization via standard bench-scale reactors (標準ベンチ装置).
HDIN Institutional Verdict
Microwave Chemical Co., Ltd. presents an asymmetric operational profile: an intellectually defensible deep-tech moat in industrial wave-heating scale-up (overcoming attenuation barriers up to its 3,000-ton M3K demonstration benchmark) burdened by a consulting-heavy commercial model. With 83.9% of top-line revenue confined to Phase 2 demonstration fees, the corporate entity absorbs significant execution risk from clients' capital expenditure timing. When chemical conglomerates deferred capital allocations, the group experienced an unbuffered operational shock, resulting in -$6.20M in operating losses and the insertion of a Going Concern uncertainty disclosure by independent auditors.
Management addressed this solvency bottleneck through an external financing structure finalized subsequent to the fiscal close:
* On August 31, 2026, the board approved the 3rd-party allotment of the 8th Series Stock Acquisition Rights to SMBC Nikko Securities Inc., issued on September 16, 2026.
* The issue comprises 16,420 units (1,642,000 shares, representing 10.3% dilution against 15,904,500 total shares outstanding), featuring an initial exercise price of $6.55 (¥979) and a floor price of $3.93 (¥588).
* Estimated net proceeds of $10.70M ($10.72M gross / ¥1.60B net) are earmarked across three tranches: $2.01M (¥300M) for DualPore capital expenditure (Dec 2026–Jun 2028), $3.34M (¥500M) for new business development (Oct 2026–Jun 2028), and $5.35M (¥800M net / ¥803M gross) for operating working capital (Oct 2026–Jun 2029).
* Debt liquidity is bolstered by $3.34M (¥500.00M) in long-term bank borrowings and a renewed $3.34M (¥500.00M) bank commitment line (100% undrawn as of June 30, 2026). Off-balance sheet contingent liabilities and asset collateral pledges remain zero ($0.00).
Table Post-Period Funding Architecture ($10.70M Net Proceeds from SMBC Nikko)
| Allocation Category | Capital Amount (US$ / JPY) | Execution Window |
|---|---|---|
| DualPore CapEx Expansion | $2.01M (¥300.00M) | Dec 2026 – Jun 2028 |
| New Technology Seed Capital | $3.34M (¥500.00M) | Oct 2026 – Jun 2028 |
| Operating Working Capital Reserve | $5.35M (¥800.00M) | Oct 2026 – Jun 2029 |
| Total Planned Allocation | $10.70M (¥1,600.00M) | Oct 2026 – Jun 2029 |
Governance and executive incentives show strong operational alignment. The board maintains a 50.0% outside director ratio (3 of 6 seats), featuring Urata Okihiro (ex-McKinsey/INCJ), Takahashi Yuko (CPA), and Saito Shuichi across its Audit & Supervisory Committee structure. Co-founders CEO Iwaya Yoshino (7.9% stake) and CSO Dr. Yasunori Tsukahara (6.9% stake) hold a combined 14.8% equity interest. Directors waived variable bonuses in FY2026/6, receiving $427.92k (¥64.00M) in fixed base pay. Long-term incentives are governed by the 6th Series Stock Acquisition Rights (200,000 shares exercisable from June 2029 at ¥560), requiring cumulative revenues to reach $86.92M (¥13.0B) or single-year revenues to touch $66.86M (¥10.0B) between FY2026/6 and FY2030/6.
The institutional hurdle rate remains operational: Microwave Chemical Co., Ltd. must rapidly convert its 61 active projects from Phase 2 R&D testing into Phase 3 commercial equipment deliveries and Phase 4 recurring royalty streams. Failure to complete this commercial shift before exhausting the $10.70M SMBC Nikko equity facility will leave the operating model vulnerable to macro client cycles.
Presentation Download & Video Access:
- Presentation Download: Click the PDF download link under 'Related Topics' to access the full institutional presentation of this report.
- Video Link: Click this link to watch the HDIN analyst briefing on YouTube.
About HDIN Research:
HDIN Research is a premier global market intelligence and strategic advisory firm specializing in institutional-grade financial analysis, supply chain audits, and macroeconomic forecasting. Our dedicated sector analysts deliver actionable, data-driven insights tailored for private equity, hedge funds, and corporate strategy teams. Visit us at http://www.hdinresearch.com.
2026 AI Transparency Footer:
"This intelligence report was authored by HDIN Research analysts following a rigorous audit of official corporate filings. AI was utilized for massive-scale data synthesis and structural drafting, ensuring 100% inclusion of reported data points. All strategic insights, financial modeling, and final verdicts were verified by our editorial board to ensure professional accuracy and compliance with 2026 Google Search E-E-A-T standards."