AIMECHATEC, Ltd. [TYO: 6227]: AI Advanced Packaging Pivot Yields Record Operating Leverage Near Ryugasaki as Operating Income Surges 177.3%
Date : 2026-09-28
Reading : 168
HDIN Executive Takeaways
1. AIMECHATEC, Ltd. [TYO: 6227] completed its transition from legacy display equipment to AI advanced semiconductor packaging, posting FY2026 revenue of ¥35,244,230 thousand (+67.79% YoY) and operating profit of ¥5,810,707 thousand (+177.32% YoY).
2. Advanced Packaging systems generated 88.56% of corporate sales, led by shipments to Taiwan, China (70.11% of top-line) via sole distributor Marketech International Corp. at the Ryugasaki manufacturing base.
3. Balance sheet risk reduced sharply: operating cash flow hit ¥11,184,066 thousand, converting net debt from -¥4,744,532 thousand to net cash of +¥4,716,113 thousand, while cash conversion cycle fell 147.6 days.
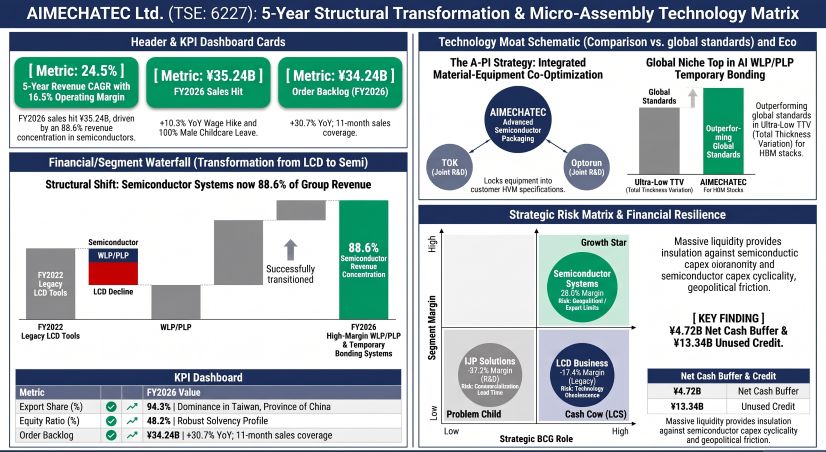
Figure AIMECHATEC Ltd (TSE 6227) 5-Year Structural Transformation & Micro-Assembly Technology Matrix
 Segmental Realities, Margin Acceleration, and Working Capital Dynamics
Corporate filings show AIMECHATEC, Ltd. [TYO: 6227] achieved a profound operational turning point in the fiscal year ended June 30, 2026 (FY2026), driven by the global buildout of High Bandwidth Memory (HBM) and 2.5D/3D chiplet advanced packaging lines. Consolidated net sales expanded 67.79% YoY from ¥21,005,577 thousand in FY2025 to ¥35,244,230 thousand in FY2026. Consolidated operating income rose 177.32% YoY from ¥2,095,320 thousand to ¥5,810,707 thousand, lifting group operating margin by 651 bps from 9.98% to 16.49%. Net income expanded 954.14% YoY from ¥337,742 thousand to ¥3,560,289 thousand, expanding Return on Equity (ROE) by 2,500 bps from 3.10% to 28.10%, and Return on Invested Capital (ROIC) from 9.33% to 41.31%.
The operational inflection was concentrated in the Semiconductor-related business segment, which expanded 59.89% YoY to reach ¥31,212,042 thousand (88.56% of group sales). High operational leverage lifted segment operating profit 132.78% YoY to ¥8,752,544 thousand, realizing a segment profit margin of 28.04% (+878 bps YoY). In contrast, the legacy LCD Business and emerging IJP Solution units exhibited structural operational friction, posting segment losses following inventory write-downs and deferred customer delivery milestones.
Table Segment Performance Analysis — FY2025 vs. FY2026
A fundamental split appeared in revenue types. As advanced packaging capacity expanded, new machine shipments rose 76.60% to ¥33,448,681 thousand, or 94.91% of consolidated net sales. After-sales Life Cycle Support (LCS)—encompassing modifications, retrofits, and spare parts—fell 13.07% to ¥1,795,548 thousand (5.09% of sales):
* Semiconductor Systems: New Equipment revenue reached ¥29,986,891 thousand (96.07% of segment sales); LCS accounted for ¥1,225,151 thousand (3.93%).
* LCD Business: New Equipment sales rebounded to ¥1,628,020 thousand (74.73% of segment sales); LCS fell to ¥550,451 thousand (25.27%), compared to a 74.76% LCS share in FY2025.
* IJP Solution: New Equipment delivered ¥1,833,770 thousand (98.92% of segment sales); LCS totaled ¥19,946 thousand (1.08%).
Working capital shifted significantly during the year. Cash Conversion Cycle (CCC) contracted by 147.6 days, moving from 254.4 days in FY2025 to 106.8 days in FY2026:
* Days Sales Outstanding (DSO) dropped by 113.7 days from 191.7 days to 78.0 days, driven by the collection of ¥3,510,000 thousand in trade receivables as major fab tool acceptance milestones cleared.
* Days Inventory Outstanding (DIO) fell 81.6 days from 195.5 days to 113.9 days, despite top-line expansion, as work-in-process converted into finished deliveries.
* Days Payables Outstanding (DPO) fell 47.7 days from 132.8 days to 85.1 days.
Consolidated operating cash flow rose to ¥11,184,066 thousand (compared to ¥1,526,612 thousand in FY2025), exceeding net income by ¥7,623,777 thousand. Beyond working capital collections, this cash divergence was driven by non-cash charges and changes in balance sheet reserves:
* Inventory Devaluation Charges: Management recognized ¥2,058,000 thousand in non-cash inventory write-downs directly inside Cost of Goods Sold (including ¥1,094,100 thousand in finished equipment, ¥646,800 thousand in raw parts, and ¥317,100 thousand in work-in-process).
* Warranty Provision Adjustments: A revised estimation model incorporating custom system integration and chemical compatibility adjustments generated a non-cash provision charge of ¥480,800 thousand, lifting balance sheet warranty reserves to ¥514,800 thousand.
* Allowance for Doubtful Accounts: Management shortened its assumed collection window for Semiconductor segment trade assets from 5.0 years to 1.0 year (and 2.5 years for non-semiconductor units), booking an incremental ¥311,200 thousand in doubtful accounts expense, expanding the reserve to ¥311,500 thousand.
* Asset Impairments: The IJP Solution unit absorbed an asset impairment write-down of ¥363,500 thousand following customer project schedule delays, accompanied by ¥142,200 thousand in fixed asset disposal losses.
These cash inflows were deployed toward deleveraging. Short-term debt fell 86.39% from ¥4,960,750 thousand to ¥675,000 thousand, while long-term borrowings fell from ¥3,431,250 thousand to ¥3,181,250 thousand, reducing total interest-bearing debt by 54.05% from ¥8,392,000 thousand to ¥3,856,250 thousand. Cash and cash equivalents rose 135.02% to ¥8,572,363 thousand, moving the company from net debt of -¥4,744,532 thousand to net cash of +¥4,716,113 thousand.
Liquidity is backed by ¥16,700,000 thousand in multi-bank committed credit facilities (SMBC, Mizuho, Sumitomo Mitsui Trust, Resona). With ¥3,360,000 thousand drawn at year-end, unused borrowing capacity stood at ¥13,340,000 thousand, bringing total available liquidity to ¥21,912,363 thousand (covering 62.17% of annual sales).
Forward operational visibility is anchored by order backlog metrics. Group order intake climbed 60.60% YoY to ¥43,289,718 thousand:
* Semiconductor Order Intake: Rose 83.73% to ¥43,783,420 thousand.
* LCD Order Intake: Totaled ¥4,638,997 thousand (+99.70% YoY).
* IJP Solution Order Intake: Reached ¥498,340 thousand (+137.10% YoY).
* Backlog Position: Group order backlog closed FY2026 at ¥34,242,637 thousand (+30.68% YoY), led by ¥31,330,110 thousand in Semiconductor packaging systems (+67.00% YoY), while LCD backlog dropped 27.27% to ¥817,527 thousand and IJP backlog contracted 47.10% to ¥2,095,000 thousand. Group Book-to-Bill closed at 1.23x (following 1.28x in FY2025).
Work-in-Process ended the year at ¥6,007,234 thousand, comprising 76.06% of gross inventory (¥7,898,401 thousand), confirming that assembly bays were positioned for delivery realizations heading into FY2027.
Table Inventory Composition and Valuation Analysis — FY2025 vs. FY2026
Physical Infrastructure Layout, Channel Realities, and Geopolitical Footprint
AIMECHATEC operates an export-dependent manufacturing footprint. International deliveries accounted for 94.32% of total FY2026 consolidated revenue (¥33,241,125 thousand), with 90.38% concentrated within East Asian manufacturing corridors.
Table Geographic Revenue Distribution by Destination Market — FY2025 vs. FY2026
Corporate shipments shifted heavily toward Taiwan, China, which rose 168.24% YoY to ¥24,710,666 thousand, reaching 70.11% of corporate turnover. Shipments to Mainland China dropped 36.06% YoY to ¥5,531,035 thousand (15.69% of sales) due to slowing LCD display line investments.
Manufacturing and engineering operations remain centered in Ibaraki Prefecture, Japan, organized across dedicated facilities:
* Ryugasaki Headquarters & Main Plant (Ryugasaki City, Ibaraki): Spanning 35,984 m² of land with a balance sheet book value of ¥3,920,000 thousand. Houses core systems integration, cleanroom assembly, precision machining, and 219 full-time employees.
* New Second Factory Building: Completed at the Ryugasaki campus in December 2025 with an executed capex of ¥1,860,000 thousand. Delivers high-class cleanroom environments designed for 300 mm Wafer-Level Packaging (WLP) and Panel-Level Packaging (PLP) Temporary Bonder and Debonder (TB/DB) integration, alongside closed-loop water recirculation chillers (cutting groundwater draw by 40% to 70%) and rooftop solar PV arrays.
* Moriya Satellite Plant (Moriya City, Ibaraki): Occupies 2,961 m² of land (book value ¥135,000 thousand), serving as auxiliary modular staging, inventory buffering, and sub-assembly integration space.
* Process Development Center: Established July 2018 at the Ryugasaki campus to host Joint Development Projects (JDPs) alongside materials providers and tier-1 foundry/OSAT packaging clients.
* Nanjing Xinchuang Mechatronics Co., Ltd.: Wholly owned subsidiary in Nanjing, Jiangsu, China (capital: ¥385,000 thousand; net assets: ¥24,320 thousand; 30 personnel), executing local parts distribution and LCS servicing.
* Nanolithoptics, Inc.: A 29.4% equity-method affiliate based in Tsurugashima, Saitama Prefecture, capitalized at ¥170,000 thousand (carrying balance sheet value ¥31,290 thousand), dedicated to nanoimprint lithography (NIP) and AR/VR optical waveguide tool co-development. Equity method investment loss stood at -¥32,450 thousand in FY2026.
Equipment distribution relies on an agency structure. A single commercial counterparty—Taiwanese engineering distributor Marketech International Corp.—accounted for ¥24,011,511 thousand, or 68.13% of AIMECHATEC's total consolidated revenue in FY2026. This compares to FY2025 when sales were split between MIC-Tech (Shanghai) Corp. at ¥7,417,985 thousand (35.31%) and Marketech International Corp. at ¥6,597,137 thousand (31.41%).
Currency risk on these shipments is managed via contract structuring: export contracts are denominated in Japanese Yen (JPY), insulating operating income from direct foreign exchange fluctuations. Customer credit exposure is regulated through milestone billing schedules: contracts collect an upfront advance down payment of ~20% upon signing (booking ¥1,640,000 thousand in balance sheet contract liabilities in FY2026), ~70% upon equipment shipment/port loading (FOB), and a ~10% retention balance (held as contract assets, totaling ¥3,330,000 thousand) due upon final line acceptance.
HDIN Institutional Verdict
Management’s presentation highlights AIMECHATEC’s rise to "Global Niche Top" status in AI Advanced Semiconductor Packaging. Hard operating and commercial metrics confirm technical differentiation, but also expose specific portfolio and structural vulnerabilities:
First, customer and geographic concentration poses an operational risk. With 68.13% of consolidated top-line revenue tied to a single distributor (Marketech International Corp.) and 70.11% tied to packaging facilities in Taiwan, China, earnings visibility is tied to the capital expenditure cycles of Taiwanese OSATs and foundries. Under an adverse stress case involving a 30% reduction in procurement orders through Marketech, AIMECHATEC would face an immediate top-line drag of ¥7,203,453 thousand (reducing corporate revenues by 20.44% to ~¥28,040,777 thousand). This contraction would lower cleanroom capacity utilization across the Ryugasaki campus and pressure fixed-cost absorption, challenging the Semiconductor segment's 28.04% operating margin.
However, the company possesses balance sheet buffers to navigate such an adjustment: the ¥34,242,637 thousand order backlog provides over 11 months of sales cover, the +¥4,716,113 thousand net cash reserve provides solvency support, and ¥13,340,000 thousand in undrawn credit lines covers short-term liquidity needs.
Second, a clear performance gap exists between reporting segments. The Semiconductor-related business functions as the group's sole profit driver, generating ¥8,752,544 thousand in profit. In contrast, the legacy LCD Business generated a loss of -¥379,625 thousand, and IJP Solution posted a loss of -¥689,100 thousand alongside an asset impairment write-down of ¥363,500 thousand. Corporate profitability remains dependent on the Semiconductor packaging unit, requiring management to maintain strict capital allocation oversight over non-performing lines.
Third, cross-corporate equity linkages reinforce AIMECHATEC’s technological position. Originating from Hitachi, Ltd.'s Ryugasaki Plant (carved out in 2016 via Polaris Capital), AIMECHATEC has established an operational ecosystem through its "A-PI" (Advanced Process Integration) strategy. Tokyo Ohka Kogyo Co., Ltd. (TOK) holds a 17.56% equity stake following AIMECHATEC's March 2023 absorption of TOK's process tool manufacturing business. This partnership pairs AIMECHATEC's WLP/PLP TB/DB tool platforms with TOK's proprietary adhesives, release chemistry, and photoresists. Optical deposition provider Optorun Co., Ltd. holds a matched 17.56% equity stake to co-develop nanoimprint lithography (NIP) platforms via the Nanolithoptics joint venture.
To meet Tokyo Stock Exchange governance guidelines, dispatched director arrangements with both TOK and Optorun were phased out at the September 2026 AGM. The Board was reconstituted with 7 Directors (3 Outside Directors, or 42.86% independence) and a 100% independent Audit & Supervisory Board (3/3 Outside Statutory Auditors).
Governance discipline is reflected in human capital and capital deployment metrics:
* Zero Policy-Based Cross-Shareholdings: Eliminates cross-holding valuation drag from the balance sheet.
* Engineering Talent Allocation: 57.99% of parent company personnel (127/219) are deployed inside Semiconductor operations, supported by a 10.30% wage hike in FY2026 (average parent compensation: ¥7,656 thousand; average tenure: 16.9 years).
* Contingent Liabilities: Zero pending lawsuits, patent disputes, or third-party guarantee liabilities on corporate records.
* Capital Allocation Policy: Shareholder distributions are anchored by a Dividend on Equity (DOE) metric of ~2.5% (FY2026 actual: 2.30%), establishing an annual payout floor across cyclical downturns. The execution of a 1-to-3 stock split on April 1, 2026 expanded retail market liquidity, generating a TOPIX-relative Total Shareholder Return (TSR) of 582.0%.
In summary, AIMECHATEC has successfully commercialized its advanced packaging hardware for HBM and chiplet manufacturing, generating substantial cash flow and de-risking its balance sheet. However, long-term valuation multiples will remain constrained until management diversifies its customer base beyond Marketech International Corp., and demonstrates an operational path to break-even within its optical IJP operations.
Presentation Download & Video Access:
- Presentation Download: Click the PDF download link under 'Related Topics' to access the full institutional presentation of this report.
- Video Link: Click this link to watch the HDIN analyst briefing on YouTube.
About HDIN Research:
HDIN Research is a premier global market intelligence and strategic advisory firm specializing in institutional-grade financial analysis, supply chain audits, and macroeconomic forecasting. Our dedicated sector analysts deliver actionable, data-driven insights tailored for private equity, hedge funds, and corporate strategy teams. Visit us at http://www.hdinresearch.com.
2026 AI Transparency Footer:
"This intelligence report was authored by HDIN Research analysts following a rigorous audit of official corporate filings. AI was utilized for massive-scale data synthesis and structural drafting, ensuring 100% inclusion of reported data points. All strategic insights, financial modeling, and final verdicts were verified by our editorial board to ensure professional accuracy and compliance with 2026 Google Search E-E-A-T standards."
1. AIMECHATEC, Ltd. [TYO: 6227] completed its transition from legacy display equipment to AI advanced semiconductor packaging, posting FY2026 revenue of ¥35,244,230 thousand (+67.79% YoY) and operating profit of ¥5,810,707 thousand (+177.32% YoY).
2. Advanced Packaging systems generated 88.56% of corporate sales, led by shipments to Taiwan, China (70.11% of top-line) via sole distributor Marketech International Corp. at the Ryugasaki manufacturing base.
3. Balance sheet risk reduced sharply: operating cash flow hit ¥11,184,066 thousand, converting net debt from -¥4,744,532 thousand to net cash of +¥4,716,113 thousand, while cash conversion cycle fell 147.6 days.
Figure AIMECHATEC Ltd (TSE 6227) 5-Year Structural Transformation & Micro-Assembly Technology Matrix
Segmental Realities, Margin Acceleration, and Working Capital DynamicsCorporate filings show AIMECHATEC, Ltd. [TYO: 6227] achieved a profound operational turning point in the fiscal year ended June 30, 2026 (FY2026), driven by the global buildout of High Bandwidth Memory (HBM) and 2.5D/3D chiplet advanced packaging lines. Consolidated net sales expanded 67.79% YoY from ¥21,005,577 thousand in FY2025 to ¥35,244,230 thousand in FY2026. Consolidated operating income rose 177.32% YoY from ¥2,095,320 thousand to ¥5,810,707 thousand, lifting group operating margin by 651 bps from 9.98% to 16.49%. Net income expanded 954.14% YoY from ¥337,742 thousand to ¥3,560,289 thousand, expanding Return on Equity (ROE) by 2,500 bps from 3.10% to 28.10%, and Return on Invested Capital (ROIC) from 9.33% to 41.31%.
The operational inflection was concentrated in the Semiconductor-related business segment, which expanded 59.89% YoY to reach ¥31,212,042 thousand (88.56% of group sales). High operational leverage lifted segment operating profit 132.78% YoY to ¥8,752,544 thousand, realizing a segment profit margin of 28.04% (+878 bps YoY). In contrast, the legacy LCD Business and emerging IJP Solution units exhibited structural operational friction, posting segment losses following inventory write-downs and deferred customer delivery milestones.
Table Segment Performance Analysis — FY2025 vs. FY2026
| Reporting Segment | Financial & Operational Metric | FY2025 | FY2026 | YoY Variance |
|---|---|---|---|---|
| Semiconductor-related | Net Sales (¥ Thousand) | ¥19,520,806 | ¥31,212,042 | +59.89% |
| Segment Share (%) | 92.93% | 88.56% | -437 bps | |
| Segment Profit (¥ Thousand) | ¥3,759,962 | ¥8,752,544 | +132.78% | |
| Segment Margin (%) | 19.26% | 28.04% | +878 bps | |
| LCD Business | Net Sales (¥ Thousand) | ¥911,374 | ¥2,178,471 | +139.03% |
| Segment Share (%) | 4.34% | 6.18% | +184 bps | |
| Segment Profit / (Loss) (¥ Thousand) | ¥140,934 | (¥379,625) | Turned to Loss | |
| Segment Margin (%) | 15.46% | -17.43% | -3,289 bps | |
| IJP Solution Business | Net Sales (¥ Thousand) | ¥573,396 | ¥1,853,716 | +223.29% |
| Segment Share (%) | 2.73% | 5.26% | +253 bps | |
| Segment Profit / (Loss) (¥ Thousand) | (¥222,310) | (¥689,100) | Loss widened | |
| Segment Margin (%) | -38.77% | -37.17% | +160 bps | |
| Reconciliations / Corporate | Corporate Expenses (¥ Thousand) | (¥1,583,265) | (¥1,873,111) | +18.31% |
| Consolidated Group | Total Net Sales (¥ Thousand) | ¥21,005,577 | ¥35,244,230 | +67.79% |
| Operating Income (¥ Thousand) | ¥2,095,320 | ¥5,810,707 | +177.32% | |
| Operating Margin (%) | 9.98% | 16.49% | +651 bps | |
| Ordinary Income (¥ Thousand) | ¥1,884,082 | ¥5,636,987 | +199.19% | |
| Net Income (¥ Thousand) | ¥337,742 | ¥3,560,289 | +954.14% | |
| EBITDA (¥ Thousand) | ¥2,509,826 | ¥6,246,417 | +148.88% |
A fundamental split appeared in revenue types. As advanced packaging capacity expanded, new machine shipments rose 76.60% to ¥33,448,681 thousand, or 94.91% of consolidated net sales. After-sales Life Cycle Support (LCS)—encompassing modifications, retrofits, and spare parts—fell 13.07% to ¥1,795,548 thousand (5.09% of sales):
* Semiconductor Systems: New Equipment revenue reached ¥29,986,891 thousand (96.07% of segment sales); LCS accounted for ¥1,225,151 thousand (3.93%).
* LCD Business: New Equipment sales rebounded to ¥1,628,020 thousand (74.73% of segment sales); LCS fell to ¥550,451 thousand (25.27%), compared to a 74.76% LCS share in FY2025.
* IJP Solution: New Equipment delivered ¥1,833,770 thousand (98.92% of segment sales); LCS totaled ¥19,946 thousand (1.08%).
Working capital shifted significantly during the year. Cash Conversion Cycle (CCC) contracted by 147.6 days, moving from 254.4 days in FY2025 to 106.8 days in FY2026:
* Days Sales Outstanding (DSO) dropped by 113.7 days from 191.7 days to 78.0 days, driven by the collection of ¥3,510,000 thousand in trade receivables as major fab tool acceptance milestones cleared.
* Days Inventory Outstanding (DIO) fell 81.6 days from 195.5 days to 113.9 days, despite top-line expansion, as work-in-process converted into finished deliveries.
* Days Payables Outstanding (DPO) fell 47.7 days from 132.8 days to 85.1 days.
Consolidated operating cash flow rose to ¥11,184,066 thousand (compared to ¥1,526,612 thousand in FY2025), exceeding net income by ¥7,623,777 thousand. Beyond working capital collections, this cash divergence was driven by non-cash charges and changes in balance sheet reserves:
* Inventory Devaluation Charges: Management recognized ¥2,058,000 thousand in non-cash inventory write-downs directly inside Cost of Goods Sold (including ¥1,094,100 thousand in finished equipment, ¥646,800 thousand in raw parts, and ¥317,100 thousand in work-in-process).
* Warranty Provision Adjustments: A revised estimation model incorporating custom system integration and chemical compatibility adjustments generated a non-cash provision charge of ¥480,800 thousand, lifting balance sheet warranty reserves to ¥514,800 thousand.
* Allowance for Doubtful Accounts: Management shortened its assumed collection window for Semiconductor segment trade assets from 5.0 years to 1.0 year (and 2.5 years for non-semiconductor units), booking an incremental ¥311,200 thousand in doubtful accounts expense, expanding the reserve to ¥311,500 thousand.
* Asset Impairments: The IJP Solution unit absorbed an asset impairment write-down of ¥363,500 thousand following customer project schedule delays, accompanied by ¥142,200 thousand in fixed asset disposal losses.
These cash inflows were deployed toward deleveraging. Short-term debt fell 86.39% from ¥4,960,750 thousand to ¥675,000 thousand, while long-term borrowings fell from ¥3,431,250 thousand to ¥3,181,250 thousand, reducing total interest-bearing debt by 54.05% from ¥8,392,000 thousand to ¥3,856,250 thousand. Cash and cash equivalents rose 135.02% to ¥8,572,363 thousand, moving the company from net debt of -¥4,744,532 thousand to net cash of +¥4,716,113 thousand.
Liquidity is backed by ¥16,700,000 thousand in multi-bank committed credit facilities (SMBC, Mizuho, Sumitomo Mitsui Trust, Resona). With ¥3,360,000 thousand drawn at year-end, unused borrowing capacity stood at ¥13,340,000 thousand, bringing total available liquidity to ¥21,912,363 thousand (covering 62.17% of annual sales).
Forward operational visibility is anchored by order backlog metrics. Group order intake climbed 60.60% YoY to ¥43,289,718 thousand:
* Semiconductor Order Intake: Rose 83.73% to ¥43,783,420 thousand.
* LCD Order Intake: Totaled ¥4,638,997 thousand (+99.70% YoY).
* IJP Solution Order Intake: Reached ¥498,340 thousand (+137.10% YoY).
* Backlog Position: Group order backlog closed FY2026 at ¥34,242,637 thousand (+30.68% YoY), led by ¥31,330,110 thousand in Semiconductor packaging systems (+67.00% YoY), while LCD backlog dropped 27.27% to ¥817,527 thousand and IJP backlog contracted 47.10% to ¥2,095,000 thousand. Group Book-to-Bill closed at 1.23x (following 1.28x in FY2025).
Work-in-Process ended the year at ¥6,007,234 thousand, comprising 76.06% of gross inventory (¥7,898,401 thousand), confirming that assembly bays were positioned for delivery realizations heading into FY2027.
Table Inventory Composition and Valuation Analysis — FY2025 vs. FY2026
| Inventory Component | FY2025 (¥ Thousand) | FY2026 (¥ Thousand) | YoY Variance (%) | Share of FY26 Gross Total |
| Finished Goods | 1,758,980 | 1,783,849 | +1.41% | 22.58% |
| Work in Process | 5,451,878 | 6,007,234 | +10.19% | 76.06% |
| Raw Materials & Supplies | 1,139,703 | 107,317 | -90.58% | 1.36% |
| Total Gross Inventory | 8,350,561 | 7,898,401 | -5.41% | 100.00% |
| Less: Inventory Valuation Reserves | (552,521) | (2,584,622) | +367.79% | — |
| Net Balance Sheet Inventory | 7,798,040 | 5,313,779 | -31.86% | — |
Physical Infrastructure Layout, Channel Realities, and Geopolitical Footprint
AIMECHATEC operates an export-dependent manufacturing footprint. International deliveries accounted for 94.32% of total FY2026 consolidated revenue (¥33,241,125 thousand), with 90.38% concentrated within East Asian manufacturing corridors.
Table Geographic Revenue Distribution by Destination Market — FY2025 vs. FY2026
| Geographic Market (By Destination) | FY2025 Revenue (¥ Thousand) | FY2025 Share (%) | FY2026 Revenue (¥ Thousand) | FY2026 Share (%) | YoY Growth (%) |
| Japan (Domestic) | 1,883,162 | 8.96% | 2,003,105 | 5.68% | +6.37% |
| Taiwan, China | 9,212,008 | 43.85% | 24,710,666 | 70.11% | +168.24% |
| Mainland China | 8,650,446 | 41.18% | 5,531,035 | 15.69% | -36.06% |
| South Korea | 1,197,855 | 5.70% | 1,612,546 | 4.58% | +34.62% |
| Rest of World (SE Asia, US, EU) | 62,104 | 0.30% | 1,386,876 | 3.94% | +2,133.15% |
| Total Consolidated Net Sales | 21,005,577 | 100.00% | 35,244,230 | 100.00% | +67.79% |
Corporate shipments shifted heavily toward Taiwan, China, which rose 168.24% YoY to ¥24,710,666 thousand, reaching 70.11% of corporate turnover. Shipments to Mainland China dropped 36.06% YoY to ¥5,531,035 thousand (15.69% of sales) due to slowing LCD display line investments.
Manufacturing and engineering operations remain centered in Ibaraki Prefecture, Japan, organized across dedicated facilities:
* Ryugasaki Headquarters & Main Plant (Ryugasaki City, Ibaraki): Spanning 35,984 m² of land with a balance sheet book value of ¥3,920,000 thousand. Houses core systems integration, cleanroom assembly, precision machining, and 219 full-time employees.
* New Second Factory Building: Completed at the Ryugasaki campus in December 2025 with an executed capex of ¥1,860,000 thousand. Delivers high-class cleanroom environments designed for 300 mm Wafer-Level Packaging (WLP) and Panel-Level Packaging (PLP) Temporary Bonder and Debonder (TB/DB) integration, alongside closed-loop water recirculation chillers (cutting groundwater draw by 40% to 70%) and rooftop solar PV arrays.
* Moriya Satellite Plant (Moriya City, Ibaraki): Occupies 2,961 m² of land (book value ¥135,000 thousand), serving as auxiliary modular staging, inventory buffering, and sub-assembly integration space.
* Process Development Center: Established July 2018 at the Ryugasaki campus to host Joint Development Projects (JDPs) alongside materials providers and tier-1 foundry/OSAT packaging clients.
* Nanjing Xinchuang Mechatronics Co., Ltd.: Wholly owned subsidiary in Nanjing, Jiangsu, China (capital: ¥385,000 thousand; net assets: ¥24,320 thousand; 30 personnel), executing local parts distribution and LCS servicing.
* Nanolithoptics, Inc.: A 29.4% equity-method affiliate based in Tsurugashima, Saitama Prefecture, capitalized at ¥170,000 thousand (carrying balance sheet value ¥31,290 thousand), dedicated to nanoimprint lithography (NIP) and AR/VR optical waveguide tool co-development. Equity method investment loss stood at -¥32,450 thousand in FY2026.
Equipment distribution relies on an agency structure. A single commercial counterparty—Taiwanese engineering distributor Marketech International Corp.—accounted for ¥24,011,511 thousand, or 68.13% of AIMECHATEC's total consolidated revenue in FY2026. This compares to FY2025 when sales were split between MIC-Tech (Shanghai) Corp. at ¥7,417,985 thousand (35.31%) and Marketech International Corp. at ¥6,597,137 thousand (31.41%).
Currency risk on these shipments is managed via contract structuring: export contracts are denominated in Japanese Yen (JPY), insulating operating income from direct foreign exchange fluctuations. Customer credit exposure is regulated through milestone billing schedules: contracts collect an upfront advance down payment of ~20% upon signing (booking ¥1,640,000 thousand in balance sheet contract liabilities in FY2026), ~70% upon equipment shipment/port loading (FOB), and a ~10% retention balance (held as contract assets, totaling ¥3,330,000 thousand) due upon final line acceptance.
HDIN Institutional Verdict
Management’s presentation highlights AIMECHATEC’s rise to "Global Niche Top" status in AI Advanced Semiconductor Packaging. Hard operating and commercial metrics confirm technical differentiation, but also expose specific portfolio and structural vulnerabilities:
First, customer and geographic concentration poses an operational risk. With 68.13% of consolidated top-line revenue tied to a single distributor (Marketech International Corp.) and 70.11% tied to packaging facilities in Taiwan, China, earnings visibility is tied to the capital expenditure cycles of Taiwanese OSATs and foundries. Under an adverse stress case involving a 30% reduction in procurement orders through Marketech, AIMECHATEC would face an immediate top-line drag of ¥7,203,453 thousand (reducing corporate revenues by 20.44% to ~¥28,040,777 thousand). This contraction would lower cleanroom capacity utilization across the Ryugasaki campus and pressure fixed-cost absorption, challenging the Semiconductor segment's 28.04% operating margin.
However, the company possesses balance sheet buffers to navigate such an adjustment: the ¥34,242,637 thousand order backlog provides over 11 months of sales cover, the +¥4,716,113 thousand net cash reserve provides solvency support, and ¥13,340,000 thousand in undrawn credit lines covers short-term liquidity needs.
Second, a clear performance gap exists between reporting segments. The Semiconductor-related business functions as the group's sole profit driver, generating ¥8,752,544 thousand in profit. In contrast, the legacy LCD Business generated a loss of -¥379,625 thousand, and IJP Solution posted a loss of -¥689,100 thousand alongside an asset impairment write-down of ¥363,500 thousand. Corporate profitability remains dependent on the Semiconductor packaging unit, requiring management to maintain strict capital allocation oversight over non-performing lines.
Third, cross-corporate equity linkages reinforce AIMECHATEC’s technological position. Originating from Hitachi, Ltd.'s Ryugasaki Plant (carved out in 2016 via Polaris Capital), AIMECHATEC has established an operational ecosystem through its "A-PI" (Advanced Process Integration) strategy. Tokyo Ohka Kogyo Co., Ltd. (TOK) holds a 17.56% equity stake following AIMECHATEC's March 2023 absorption of TOK's process tool manufacturing business. This partnership pairs AIMECHATEC's WLP/PLP TB/DB tool platforms with TOK's proprietary adhesives, release chemistry, and photoresists. Optical deposition provider Optorun Co., Ltd. holds a matched 17.56% equity stake to co-develop nanoimprint lithography (NIP) platforms via the Nanolithoptics joint venture.
To meet Tokyo Stock Exchange governance guidelines, dispatched director arrangements with both TOK and Optorun were phased out at the September 2026 AGM. The Board was reconstituted with 7 Directors (3 Outside Directors, or 42.86% independence) and a 100% independent Audit & Supervisory Board (3/3 Outside Statutory Auditors).
Governance discipline is reflected in human capital and capital deployment metrics:
* Zero Policy-Based Cross-Shareholdings: Eliminates cross-holding valuation drag from the balance sheet.
* Engineering Talent Allocation: 57.99% of parent company personnel (127/219) are deployed inside Semiconductor operations, supported by a 10.30% wage hike in FY2026 (average parent compensation: ¥7,656 thousand; average tenure: 16.9 years).
* Contingent Liabilities: Zero pending lawsuits, patent disputes, or third-party guarantee liabilities on corporate records.
* Capital Allocation Policy: Shareholder distributions are anchored by a Dividend on Equity (DOE) metric of ~2.5% (FY2026 actual: 2.30%), establishing an annual payout floor across cyclical downturns. The execution of a 1-to-3 stock split on April 1, 2026 expanded retail market liquidity, generating a TOPIX-relative Total Shareholder Return (TSR) of 582.0%.
In summary, AIMECHATEC has successfully commercialized its advanced packaging hardware for HBM and chiplet manufacturing, generating substantial cash flow and de-risking its balance sheet. However, long-term valuation multiples will remain constrained until management diversifies its customer base beyond Marketech International Corp., and demonstrates an operational path to break-even within its optical IJP operations.
Presentation Download & Video Access:
- Presentation Download: Click the PDF download link under 'Related Topics' to access the full institutional presentation of this report.
- Video Link: Click this link to watch the HDIN analyst briefing on YouTube.
About HDIN Research:
HDIN Research is a premier global market intelligence and strategic advisory firm specializing in institutional-grade financial analysis, supply chain audits, and macroeconomic forecasting. Our dedicated sector analysts deliver actionable, data-driven insights tailored for private equity, hedge funds, and corporate strategy teams. Visit us at http://www.hdinresearch.com.
2026 AI Transparency Footer:
"This intelligence report was authored by HDIN Research analysts following a rigorous audit of official corporate filings. AI was utilized for massive-scale data synthesis and structural drafting, ensuring 100% inclusion of reported data points. All strategic insights, financial modeling, and final verdicts were verified by our editorial board to ensure professional accuracy and compliance with 2026 Google Search E-E-A-T standards."