Immuron Limited: Commercial Travelan Transition Faces FY28 Patent Cliff, Single-Source Supply Bottlenecks, and 38% Share Dilution
Date : 2026-10-02
Reading : 210
HDIN Executive Takeaways
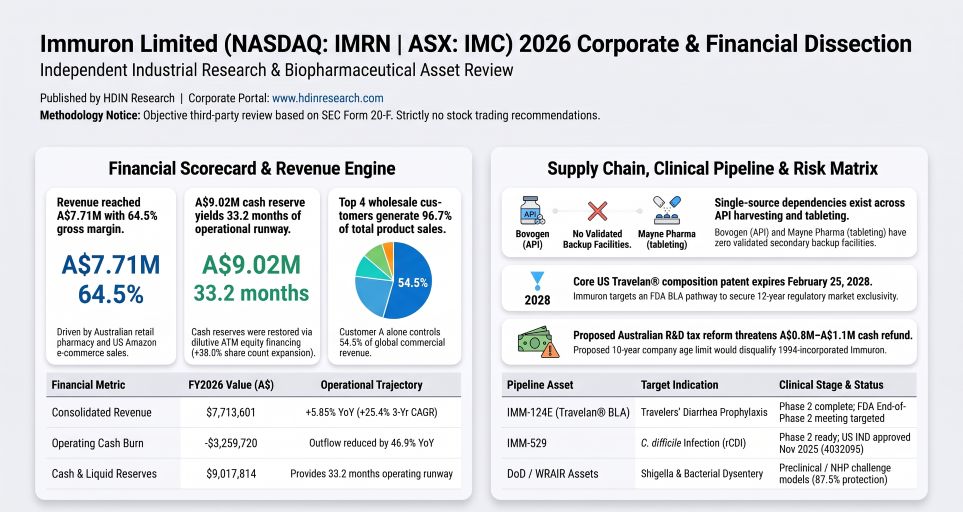
1. Immuron Limited narrowed its net operating cash burn by 46.9% year-over-year to A$3.26 million in FY26, supported by commercial revenues reaching A$7.71 million, but expanded ordinary shares outstanding by 38.0% via an At-The-Market equity facility to secure A$9.02 million in cash reserves.
2. Production remains entirely dependent on single-source contractors Bovogen Biologicals and Mayne Pharma International in Australia, while 96.7% of product sales flow through just four wholesale distributors, with Customer A alone accounting for 54.5% of total revenue.
3. Lead asset Travelan faces an intellectual property expiration on February 25, 2028, for its core US composition patent (US 8,637,025), leaving long-term enterprise valuation contingent on securing an external co-development partner for an unfunded Phase 3 Biologics License Application registration program.
Figure Immuron Limited 2026 Corporate & Financial Dissection
 Segmental Realities and Margin Compression
Immuron Limited [NASDAQ: IMRN; ASX: IMC] reported consolidated commercial revenue of A$7,713,601 for the fiscal year ended June 30, 2026, marking a 5.85% increase year-over-year from A$7,287,002 in FY25 and up from A$4,902,865 in FY24 (a three-year compound annual growth rate of 25.43%). However, gross margin contracted to 64.50% in FY26, down 89 basis points from 65.39% in FY25 and down 356 basis points from 68.06% in FY24.
The compression in gross margin was driven by Cost of Goods Sold (COGS) expanding at a three-year compound annual growth rate of 32.24% to A$2,738,529. This outpaced top-line revenue growth due to higher raw bovine colostrum processing volumes, transition expenses associated with secondary multi-warehouse storage facilities, new freight and logistics handling charges, and an inventory write-down of A$33,628 recognized during the fiscal year.
Table Consolidated Financial Performance Summary
*Note: FY25 liquid cash reserves include a A$3,036,278 90-day term deposit classified under other current assets, which matured and was transferred into cash in July 2025.
Product sales demonstrate extreme monoculture exposure. The flagship hyperimmune bovine colostrum product, Travelan, represented 98.61% of total commercial revenues in FY26 (A$7,606,581). ProIBS generated A$85,221 (1.10% of revenue) following its Australian launch in October 2025, while Protectyn generated A$21,799 (0.28% of revenue) before being cancelled and removed from the Australian Register of Therapeutic Goods (ARTG) in June 2026.
Table Granular Product and Regional Breakdown
Operating burn saw relief as R&D expenditure dropped 46.25% year-over-year in FY26 to A$1,933,440 (down 64.03% from A$5,375,461 in FY24). This contraction followed clinical trial rationalization after the US Military-sponsored Phase 2 P2TD field trial failed its primary endpoint in December 2025. Selling and marketing expenses stabilized at A$3,471,556, while general and administrative overhead fell 3.97% to A$4,305,555.
Immuron Limited closed FY26 with liquid cash reserves of A$9,017,814 and zero bank debt, giving an operational runway of 33.2 months at the FY26 average burn rate of A$271,643 per month (A$814,930 per quarter). Under a stress-test scenario reverting to the FY25 operational burn rate of A$511,412 per month, the cash buffer contracts to 17.6 months.
This liquidity cushion was established through dilutive financing rather than organic surplus. During FY26, Immuron Limited issued 88,888,840 ordinary shares via an At-The-Market facility executed through H.C. Wainwright & Co., LLC, raising A$6.48 million net of fees. This issuance expanded ordinary share capital by 38.00% year-over-year to 322,848,081 shares. On June 29, 2026, the company completed an unmarketable parcel buy-back, repurchasing and cancelling 3,805,528 shares at A$0.032 per share (total cost of A$121,777) to curb registry management costs. Fully diluted share overhang includes 8,000,000 unlisted director options (weighted average exercise price A$0.14) and 3,578,903 unvested performance rights.
Client and channel concentration remains elevated across commercial operations. Four primary wholesale distributors accounted for 96.74% of consolidated product revenues in FY26 (A$7.46 million). Customer A generated A$4,199,953, or 54.45% of total sales. Customer B contributed A$1,239,030 (16.06%), Customer C accounted for A$1,045,802 (13.56%), and Customer D represented A$977,392 (12.67%), leaving all other accounts to generate A$251,424 (3.26%). Standard terms allow volume loyalty rebates of up to 15% for primary Australian retail accounts.
Table Customer Concentration Trajectory
Infrastructure Layout and Regional Moats
Immuron Limited operates an asset-light, virtual biotechnology structure. Capital expenditure stood at A$4,752 in FY26, A$0 in FY25, and A$195 in FY24 (a three-year cumulative spend of A$4,993). Physical assets are limited to right-of-use property lease assets of A$183,396 against undiscounted lease liabilities of A$189,543. Sourcing and production steps are outsourced to contracted biological processors and formulation facilities in Australia:
Supply Chain Architecture
* Drug Substance (API): Bovogen Biologicals (Australia) operates as the sole contracted provider handling immunization and secondary manufacturing of hyperimmune bovine colostrum powder containing 35% to 45% dry-weight Immunoglobulin G (predominantly IgG1). Immuron retains no secondary API source.
* Drug Product CMO: Mayne Pharma International Pty Ltd (Australia) serves as the sole contract manufacturer for granulating, tableting, and blister-packaging Travelan caplets under an exclusive manufacturing agreement entered into on April 1, 2025.
* Clinical Biologics CMO: Syntro Health (Australia) handles cGMP clinical-grade development batches for pipeline candidate IMM-529 targeting Clostridioides difficile.
* Sourcing Logistics: Raw materials are collected exclusively from commercial dairy herds during the first two milkings within 24 hours of calving across disease-free agricultural regions of Australia and New Zealand, which maintain the World Organisation for Animal Health’s negligible-risk status for Bovine Spongiform Encephalopathy (BSE). Long-term stability analyses demonstrate a 130-month (10.8-year) shelf life for raw colostrum powder.
Audited balance sheet inventories rose 28.25% to A$2,273,848 as of June 30, 2026. Work-in-progress (WIP) expanded 199.69% to A$1,297,847, driven by bulk colostrum processing runs at Mayne Pharma International. Finished goods declined 51.53% to A$552,635 as shipments to Australian pharmacy networks and Amazon US consignment facilities outpaced inventory replenishment. Raw materials on hand stood at A$423,366 (up 111.80%), with 100% scheduled for production within 12 months.
Table Balance Sheet Inventory Distribution
Independent auditor Grant Thornton Audit Pty Ltd issued an unqualified audit opinion but highlighted inventory valuation as the sole Critical Audit Matter (CAM). Grant Thornton and management identified a material weakness in internal control over financial reporting under Sarbanes-Oxley Act provisions, citing systems failures in tracking, classifying, and relieving WIP inventory across new third-party distribution hubs following an IT migration.
Geographically, revenue remains concentrated in Australia (74.93% or A$5,779,521) and North America (25.07% or A$1,934,080, comprising US sales of A$1,768,411 and Canadian sales of A$165,669). The company generated zero sales in Europe, Asia, or the Rest of the World in FY26. Corporate governance shifts included the formal termination of logistics and facility lease agreements with Grandlodge Capital Pty Ltd and Wattle Laboratories Pty Ltd—entities tied to former director Stephen Anastasiou. Accounting, secretarial, and Chief Financial Officer functions remain outsourced to Acclime Group.
Table Consolidated Regional Footprint
Foreign exchange movements resulted in a net loss of A$285,115 in FY26 (against an FX gain of A$12,183 in FY25), driven by unhedged US dollar balance sheet cash balances translated into Australian dollars.
HDIN Institutional Verdict
Immuron Limited's transition from an exploratory biotech toward commercial self-sufficiency presents structural operational vulnerabilities that warrant caution:
Clinical Pipeline Redirection and Execution Drag
The company’s R&D contraction was triggered by clinical failure. On December 10, 2025, the 851-patient Phase 2 P2TD military field trial—conducted by the Uniformed Services University and the UK Ministry of Defence—missed its primary endpoint evaluating a twice-daily (600 mg BID) sachet regimen. Trial confounding factors included delayed dosing, missing doses, and administration with meals rather than prior to food intake. Consequently, Immuron abandoned twice-daily dosing schedules and reverted exclusively to a thrice-daily caplet regimen for its Biologics License Application (BLA) candidate IMM-124E. Requiring patients to adhere to a thrice-daily pre-prandial regimen creates compliance friction in civilian travel and active military settings.
Unfunded Prescription BLA Gap
Advancing IMM-124E from its planned End-of-Phase 2 (EoP2) FDA meeting into pivotal Phase 3 trials requires capital resources that exceed the company's balance sheet. Immuron Limited's management has confirmed that Phase 3 development cannot proceed without an external commercial pharmaceutical licensing partner. Concurrently, while an Investigational New Drug (IND #032095) application for IMM-529 in Clostridioides difficile was cleared by the FDA on November 5, 2025, the planned Phase 2 study in Australia (n=60) has yet to generate in-human efficacy data.
Near-Term Patent Horizon
Immuron faces an intellectual property headwind: core US Patent 8,637,025, protecting the Travelan composition, expires on February 25, 2028. While Immuron completed national-phase entries for two PCT applications (PCT/AU2024/051338 and PCT/AU2025/050196) across the US, Canada, Australia, and Europe in August and September 2026, these filings remain pending examination. The 2028 expiration creates generic exposure in the US dietary supplement e-commerce channel unless prescription BLA status is approved to secure 12 years of regulatory market exclusivity. The patent family covering IMM-529 (including US Patent 10,144,775 and AU 2014253685) expires on April 17, 2034.
Table Active Patent Inventory
Subsidy Disqualification Exposure
Non-dilutive funding, which totaled A$1,122,132 in FY26 (including A$782,313 from the Australian R&D Tax Incentive and A$339,819 from a Henry M. Jackson Foundation DoD grant), faces legislative pressure. Under draft reforms proposed by the Australian Federal Government in May 2026, R&D tax refund eligibility would be limited to entities under 10 years of age. Having been incorporated in 1994, Immuron would be disqualified from future cash tax rebates upon enactment, increasing operational cash burn by A$0.8M to A$1.1M annually.
Immuron Limited displays an active commercial franchise that covers 64.0% of combined SG&A overhead through its Travelan gross profits (A$4.98 million generated against A$7.78 million in total SG&A). However, the enterprise remains an unpartnered, single-product micro-cap dependent on four wholesale accounts and two sole-source manufacturers, facing a patent cliff in early 2028.
Presentation Download & Video Access:
- Presentation Download: Click the PDF download link under 'Related Topics' to access the full institutional presentation of this report.
- Video Link: Click this link to watch the HDIN analyst briefing on YouTube.
About HDIN Research:
HDIN Research is a premier global market intelligence and strategic advisory firm specializing in institutional-grade financial analysis, supply chain audits, and macroeconomic forecasting. Our dedicated sector analysts deliver actionable, data-driven insights tailored for private equity, hedge funds, and corporate strategy teams. Visit us at http://www.hdinresearch.com.
2026 AI Transparency Footer:
This intelligence report was authored by HDIN Research analysts following a rigorous audit of official corporate filings. AI was utilized for massive-scale data synthesis and structural drafting, ensuring 100% inclusion of reported data points. All strategic insights, financial modeling, and final verdicts were verified by our editorial board to ensure professional accuracy and compliance with 2026 Google Search E-E-A-T standards.
1. Immuron Limited narrowed its net operating cash burn by 46.9% year-over-year to A$3.26 million in FY26, supported by commercial revenues reaching A$7.71 million, but expanded ordinary shares outstanding by 38.0% via an At-The-Market equity facility to secure A$9.02 million in cash reserves.
2. Production remains entirely dependent on single-source contractors Bovogen Biologicals and Mayne Pharma International in Australia, while 96.7% of product sales flow through just four wholesale distributors, with Customer A alone accounting for 54.5% of total revenue.
3. Lead asset Travelan faces an intellectual property expiration on February 25, 2028, for its core US composition patent (US 8,637,025), leaving long-term enterprise valuation contingent on securing an external co-development partner for an unfunded Phase 3 Biologics License Application registration program.
Figure Immuron Limited 2026 Corporate & Financial Dissection
Segmental Realities and Margin CompressionImmuron Limited [NASDAQ: IMRN; ASX: IMC] reported consolidated commercial revenue of A$7,713,601 for the fiscal year ended June 30, 2026, marking a 5.85% increase year-over-year from A$7,287,002 in FY25 and up from A$4,902,865 in FY24 (a three-year compound annual growth rate of 25.43%). However, gross margin contracted to 64.50% in FY26, down 89 basis points from 65.39% in FY25 and down 356 basis points from 68.06% in FY24.
The compression in gross margin was driven by Cost of Goods Sold (COGS) expanding at a three-year compound annual growth rate of 32.24% to A$2,738,529. This outpaced top-line revenue growth due to higher raw bovine colostrum processing volumes, transition expenses associated with secondary multi-warehouse storage facilities, new freight and logistics handling charges, and an inventory write-down of A$33,628 recognized during the fiscal year.
Table Consolidated Financial Performance Summary
| Metric (A$) | FY2024 | FY2025 | FY2026 | YoY FY25 | YoY FY26 | 3-Yr CAGR |
| Commercial Revenue | 4,902,865 | 7,287,002 | 7,713,601 | +48.63% | +5.85% | +25.43% |
| Cost of Goods Sold (COGS) | (1,566,068) | (2,521,903) | (2,738,529) | +61.03% | +8.59% | +32.24% |
| Gross Profit | 3,336,797 | 4,765,099 | 4,975,072 | +42.80% | +4.41% | +22.11% |
| Gross Margin (%) | 68.06% | 65.39% | 64.50% | -267 bps | -89 bps | -180 bps |
| Grant & Other Income | 3,408,199 | 1,411,505 | 1,169,869 | -58.58% | -17.12% | -41.38% |
| Research & Development (R&D) | (5,375,461) | (3,597,296) | (1,933,440) | -33.08% | -46.25% | -40.03% |
| Selling & Marketing (S&M) | (2,029,648) | (3,452,416) | (3,471,556) | +70.10% | +0.55% | +30.78% |
| General & Administrative (G&A) | (4,555,726) | (4,483,623) | (4,305,555) | -1.58% | -3.97% | -2.78% |
| Operating Loss | (5,801,118) | (5,344,548) | (3,850,725) | -7.87% | -27.95% | -18.57% |
| Net Loss After Tax | (6,936,957) | (5,215,987) | (3,679,999) | -24.81% | -29.45% | -27.13% |
| Operating Cash Outflow | (5,880,139) | (6,136,949) | (3,259,720) | +4.37% | -46.88% | -25.54% |
| Capital Expenditure | (195) | 0 | (4,752) | -100.0% | N/A | +838.2% |
| Liquid Cash Reserves | 11,657,315 | 5,866,804 | 9,017,814 | -49.67% | +53.71% | -12.05% |
| Ordinary Shares Outstanding | 227,998,346 | 233,959,013 | 322,848,081 | +2.61% | +38.00% | +18.98% |
Product sales demonstrate extreme monoculture exposure. The flagship hyperimmune bovine colostrum product, Travelan, represented 98.61% of total commercial revenues in FY26 (A$7,606,581). ProIBS generated A$85,221 (1.10% of revenue) following its Australian launch in October 2025, while Protectyn generated A$21,799 (0.28% of revenue) before being cancelled and removed from the Australian Register of Therapeutic Goods (ARTG) in June 2026.
Table Granular Product and Regional Breakdown
| Product Line / Target Market | FY2024 (A$) | FY2025 (A$) | FY2026 (A$) | YoY FY26 | Share of FY26 Total |
| Travelan — Australia | 3,702,876 | 5,201,385 | 5,672,501 | +9.06% | 73.54% |
| Travelan — United States | 1,075,614 | 1,658,336 | 1,768,411 | +6.64% | 22.92% |
| Travelan — Canada | 80,888 | 378,706 | 165,669 | -56.25% | 2.15% |
| Subtotal Travelan Franchise | 4,859,378 | 7,238,427 | 7,606,581 | +5.09% | 98.61% |
| ProIBS — Australia | 0 | 0 | 85,221 | N/A | 1.10% |
| Protectyn — Australia (Discontinued) | 43,487 | 48,575 | 21,799 | -55.12% | 0.28% |
| Total Commercial Product Revenue | 4,902,865 | 7,287,002 | 7,713,601 | +5.85% | 100.00% |
Operating burn saw relief as R&D expenditure dropped 46.25% year-over-year in FY26 to A$1,933,440 (down 64.03% from A$5,375,461 in FY24). This contraction followed clinical trial rationalization after the US Military-sponsored Phase 2 P2TD field trial failed its primary endpoint in December 2025. Selling and marketing expenses stabilized at A$3,471,556, while general and administrative overhead fell 3.97% to A$4,305,555.
Immuron Limited closed FY26 with liquid cash reserves of A$9,017,814 and zero bank debt, giving an operational runway of 33.2 months at the FY26 average burn rate of A$271,643 per month (A$814,930 per quarter). Under a stress-test scenario reverting to the FY25 operational burn rate of A$511,412 per month, the cash buffer contracts to 17.6 months.
This liquidity cushion was established through dilutive financing rather than organic surplus. During FY26, Immuron Limited issued 88,888,840 ordinary shares via an At-The-Market facility executed through H.C. Wainwright & Co., LLC, raising A$6.48 million net of fees. This issuance expanded ordinary share capital by 38.00% year-over-year to 322,848,081 shares. On June 29, 2026, the company completed an unmarketable parcel buy-back, repurchasing and cancelling 3,805,528 shares at A$0.032 per share (total cost of A$121,777) to curb registry management costs. Fully diluted share overhang includes 8,000,000 unlisted director options (weighted average exercise price A$0.14) and 3,578,903 unvested performance rights.
Client and channel concentration remains elevated across commercial operations. Four primary wholesale distributors accounted for 96.74% of consolidated product revenues in FY26 (A$7.46 million). Customer A generated A$4,199,953, or 54.45% of total sales. Customer B contributed A$1,239,030 (16.06%), Customer C accounted for A$1,045,802 (13.56%), and Customer D represented A$977,392 (12.67%), leaving all other accounts to generate A$251,424 (3.26%). Standard terms allow volume loyalty rebates of up to 15% for primary Australian retail accounts.
Table Customer Concentration Trajectory
| Customer Designation | FY2024 Revenue (A$) | FY2025 Revenue (A$) | FY2026 Revenue (A$) | FY2026 Revenue Share (%) |
| Customer A | 2,308,425 | 3,272,556 | 4,199,953 | 54.45% |
| Customer B | 957,076 | 1,558,156 | 1,239,030 | 16.06% |
| Customer C | 842,173 | 958,031 | 1,045,802 | 13.56% |
| Customer D | 552,509 | 860,086 | 977,392 | 12.67% |
| Combined Top 4 Total | 4,660,183 | 6,648,829 | 7,462,177 | 96.74% |
| Remaining Balance | 242,682 | 638,173 | 251,424 | 3.26% |
| Total Product Revenue | 4,902,865 | 7,287,002 | 7,713,601 | 100.00% |
Infrastructure Layout and Regional Moats
Immuron Limited operates an asset-light, virtual biotechnology structure. Capital expenditure stood at A$4,752 in FY26, A$0 in FY25, and A$195 in FY24 (a three-year cumulative spend of A$4,993). Physical assets are limited to right-of-use property lease assets of A$183,396 against undiscounted lease liabilities of A$189,543. Sourcing and production steps are outsourced to contracted biological processors and formulation facilities in Australia:
Supply Chain Architecture
* Drug Substance (API): Bovogen Biologicals (Australia) operates as the sole contracted provider handling immunization and secondary manufacturing of hyperimmune bovine colostrum powder containing 35% to 45% dry-weight Immunoglobulin G (predominantly IgG1). Immuron retains no secondary API source.
* Drug Product CMO: Mayne Pharma International Pty Ltd (Australia) serves as the sole contract manufacturer for granulating, tableting, and blister-packaging Travelan caplets under an exclusive manufacturing agreement entered into on April 1, 2025.
* Clinical Biologics CMO: Syntro Health (Australia) handles cGMP clinical-grade development batches for pipeline candidate IMM-529 targeting Clostridioides difficile.
* Sourcing Logistics: Raw materials are collected exclusively from commercial dairy herds during the first two milkings within 24 hours of calving across disease-free agricultural regions of Australia and New Zealand, which maintain the World Organisation for Animal Health’s negligible-risk status for Bovine Spongiform Encephalopathy (BSE). Long-term stability analyses demonstrate a 130-month (10.8-year) shelf life for raw colostrum powder.
Audited balance sheet inventories rose 28.25% to A$2,273,848 as of June 30, 2026. Work-in-progress (WIP) expanded 199.69% to A$1,297,847, driven by bulk colostrum processing runs at Mayne Pharma International. Finished goods declined 51.53% to A$552,635 as shipments to Australian pharmacy networks and Amazon US consignment facilities outpaced inventory replenishment. Raw materials on hand stood at A$423,366 (up 111.80%), with 100% scheduled for production within 12 months.
Table Balance Sheet Inventory Distribution
| Balance Sheet Category | FY2025 (A$) | FY2026 (A$) | YoY Change (A$) | YoY Percentage Change (%) |
| Raw Materials & Stores | 199,893 | 423,366 | +223,473 | +111.80% |
| Work in Progress (WIP) | 433,051 | 1,297,847 | +864,796 | +199.69% |
| Finished Goods Inventory | 1,140,050 | 552,635 | -587,415 | -51.53% |
| Other Component Goods | 35 | 0 | -35 | -100.00% |
| Total Inventory Value | 1,773,029 | 2,273,848 | +500,819 | +28.25% |
Independent auditor Grant Thornton Audit Pty Ltd issued an unqualified audit opinion but highlighted inventory valuation as the sole Critical Audit Matter (CAM). Grant Thornton and management identified a material weakness in internal control over financial reporting under Sarbanes-Oxley Act provisions, citing systems failures in tracking, classifying, and relieving WIP inventory across new third-party distribution hubs following an IT migration.
Geographically, revenue remains concentrated in Australia (74.93% or A$5,779,521) and North America (25.07% or A$1,934,080, comprising US sales of A$1,768,411 and Canadian sales of A$165,669). The company generated zero sales in Europe, Asia, or the Rest of the World in FY26. Corporate governance shifts included the formal termination of logistics and facility lease agreements with Grandlodge Capital Pty Ltd and Wattle Laboratories Pty Ltd—entities tied to former director Stephen Anastasiou. Accounting, secretarial, and Chief Financial Officer functions remain outsourced to Acclime Group.
Table Consolidated Regional Footprint
| UN Geographic Region / Jurisdiction | FY2024 (A$) | FY2025 (A$) | FY2026 (A$) | Regional Share FY26 (%) |
| Australia / Oceania (Australia) | 3,746,363 | 5,249,960 | 5,779,521 | 74.93% |
| North America | 1,156,502 | 2,037,042 | 1,934,080 | 25.07% |
| -- United States | 1,075,614 | 1,658,336 | 1,768,411 | 22.92% |
| -- Canada | 80,888 | 378,706 | 165,669 | 2.15% |
| Europe | 0 | 0 | 0 | 0.00% |
| Asia (including Taiwan, Prov. of CN) | 0 | 0 | 0 | 0.00% |
| Rest of World (ROW) | 0 | 0 | 0 | 0.00% |
| Total Worldwide Revenue | 4,902,865 | 7,287,002 | 7,713,601 | 100.00% |
Foreign exchange movements resulted in a net loss of A$285,115 in FY26 (against an FX gain of A$12,183 in FY25), driven by unhedged US dollar balance sheet cash balances translated into Australian dollars.
HDIN Institutional Verdict
Immuron Limited's transition from an exploratory biotech toward commercial self-sufficiency presents structural operational vulnerabilities that warrant caution:
Clinical Pipeline Redirection and Execution Drag
The company’s R&D contraction was triggered by clinical failure. On December 10, 2025, the 851-patient Phase 2 P2TD military field trial—conducted by the Uniformed Services University and the UK Ministry of Defence—missed its primary endpoint evaluating a twice-daily (600 mg BID) sachet regimen. Trial confounding factors included delayed dosing, missing doses, and administration with meals rather than prior to food intake. Consequently, Immuron abandoned twice-daily dosing schedules and reverted exclusively to a thrice-daily caplet regimen for its Biologics License Application (BLA) candidate IMM-124E. Requiring patients to adhere to a thrice-daily pre-prandial regimen creates compliance friction in civilian travel and active military settings.
Unfunded Prescription BLA Gap
Advancing IMM-124E from its planned End-of-Phase 2 (EoP2) FDA meeting into pivotal Phase 3 trials requires capital resources that exceed the company's balance sheet. Immuron Limited's management has confirmed that Phase 3 development cannot proceed without an external commercial pharmaceutical licensing partner. Concurrently, while an Investigational New Drug (IND #032095) application for IMM-529 in Clostridioides difficile was cleared by the FDA on November 5, 2025, the planned Phase 2 study in Australia (n=60) has yet to generate in-human efficacy data.
Near-Term Patent Horizon
Immuron faces an intellectual property headwind: core US Patent 8,637,025, protecting the Travelan composition, expires on February 25, 2028. While Immuron completed national-phase entries for two PCT applications (PCT/AU2024/051338 and PCT/AU2025/050196) across the US, Canada, Australia, and Europe in August and September 2026, these filings remain pending examination. The 2028 expiration creates generic exposure in the US dietary supplement e-commerce channel unless prescription BLA status is approved to secure 12 years of regulatory market exclusivity. The patent family covering IMM-529 (including US Patent 10,144,775 and AU 2014253685) expires on April 17, 2034.
Table Active Patent Inventory
| Patent Title / Target Indication | Jurisdictions Granted / Pending | Grant / Application ID | Legal Expiration Date |
| Enteric Bacterial Infections (Travelan) | United States | US Patent 8,637,025 | February 25, 2028 |
| C. difficile Formulations (IMM-529) | US, AU, CA, EP, CN, NZ | US 10,144,775 / AU 2014253685 | April 17, 2034 |
| Methods and Compositions II | Nat'l Phase: US, CA, AU, EP | PCT/AU2024/051338 | ~December 2044 (Pending) |
| Methods and Compositions I | Nat'l Phase: US, CA, AU, EP | PCT/AU2025/050196 | ~March 2045 (Pending) |
Subsidy Disqualification Exposure
Non-dilutive funding, which totaled A$1,122,132 in FY26 (including A$782,313 from the Australian R&D Tax Incentive and A$339,819 from a Henry M. Jackson Foundation DoD grant), faces legislative pressure. Under draft reforms proposed by the Australian Federal Government in May 2026, R&D tax refund eligibility would be limited to entities under 10 years of age. Having been incorporated in 1994, Immuron would be disqualified from future cash tax rebates upon enactment, increasing operational cash burn by A$0.8M to A$1.1M annually.
Immuron Limited displays an active commercial franchise that covers 64.0% of combined SG&A overhead through its Travelan gross profits (A$4.98 million generated against A$7.78 million in total SG&A). However, the enterprise remains an unpartnered, single-product micro-cap dependent on four wholesale accounts and two sole-source manufacturers, facing a patent cliff in early 2028.
Presentation Download & Video Access:
- Presentation Download: Click the PDF download link under 'Related Topics' to access the full institutional presentation of this report.
- Video Link: Click this link to watch the HDIN analyst briefing on YouTube.
About HDIN Research:
HDIN Research is a premier global market intelligence and strategic advisory firm specializing in institutional-grade financial analysis, supply chain audits, and macroeconomic forecasting. Our dedicated sector analysts deliver actionable, data-driven insights tailored for private equity, hedge funds, and corporate strategy teams. Visit us at http://www.hdinresearch.com.
2026 AI Transparency Footer:
This intelligence report was authored by HDIN Research analysts following a rigorous audit of official corporate filings. AI was utilized for massive-scale data synthesis and structural drafting, ensuring 100% inclusion of reported data points. All strategic insights, financial modeling, and final verdicts were verified by our editorial board to ensure professional accuracy and compliance with 2026 Google Search E-E-A-T standards.