Quanome Technologies, Inc.: Strategic AI Pivot Toward Compal Hardware Clashes With $670K Liquidity Deficit and China Sourcing Concentration
Date : 2026-09-29
Reading : 178
HDIN Executive Takeaways
1. Quanome Technologies, Inc. disposed of legacy cross-border logistics on February 12, 2026, pivoting 100% of continuing revenue ($5.85 million, +111.8% YoY) to Mainland China pharmaceutical distribution while posting a -$10.19 million operating loss.
2. The enterprise faces an immediate capital shortfall, holding $670,281 in cash against an off-balance-sheet commitment of approximately $18.8 million (requiring a 20% deposit of ~$3.76 million) for 32 GPU servers from Taiwan-based Compal Electronics, Inc.
3. Severe credit exposure characterizes working capital: 65.2% of current assets ($7.18 million net) is tied up in a single unsecured third-party loan, driving an independent auditor Going Concern qualification alongside a $2.86 million supplier advance write-off.
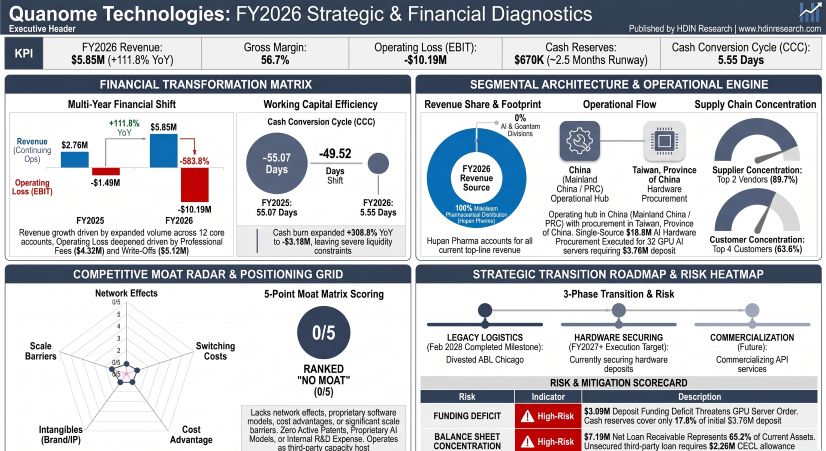
Figure Quanome Technologies FY2026 Strategic & Financial Diagnostics
 Segmental Realities and Margin Compression
Quanome Technologies, Inc. [NASDAQ: QNME] (formerly Lakeside Holding Limited) operates under a single reportable operating segment—Pharmaceutical Distribution in Mainland China—managed on a consolidated basis by Chief Executive Officer Yang Li under ASC 280. Disaggregation by operational unit reveals a top-line transformation countered by severe operational spending and asset impairments.
Continuing revenue rose 111.8% year-over-year in FY2026 to $5,850,681, driven by higher sales volumes of infusion products and customer account expansion. Infusion products accounted for $5,330,000 (91.1% of revenue), while specialty pharmaceutical and medical nutrition products generated $520,681 (8.9% of revenue). Gross profit reached $3,315,042, representing a gross margin expansion of 56 basis points to 56.7%, supported by vendor purchase rebates.
Operating expenses surged 344.2% YoY to $13,507,391, escalating the operating loss (EBIT) from -$1,490,449 to -$10,192,349 (-174.2% EBIT margin). This operating deterioration stemmed from non-operational impairment charges and advisory expenses:
* General and administrative expenses reached $5,689,682 (+117.6% YoY), driven by $4,318,739 in third-party legal, consulting, and due diligence fees.
* Selling expenses expanded 571.9% YoY to $2,642,667, incorporating $1,163,396 in advertising and brand marketing, $630,720 in market research and business development, and $483,259 in direct sales payroll.
* Non-operational write-offs included a $2,859,594 write-off of an unrecoverable supplier advance (out of a $2,947,635 / RMB 20.0 million prepayment) and a $2,256,647 Current Expected Credit Loss (CECL) provision recognized on a third-party loan receivable.
* Continuing net loss widened 433.9% to -$10,138,418. Discontinued logistics operations generated net income of $654,388 (inclusive of a $2,556,315 gain on disposal), leaving a consolidated total net loss of -$9,484,030.
Table Segment Revenue Performance and Business Portfolio Development Analysis (FY2025–FY2026)
Working capital metrics showed an improvement in the Cash Conversion Cycle (CCC), declining from 55.07 days in FY2025 to 5.55 days in FY2026 (15.39 days on an average-balance basis). Days Sales Outstanding (DSO) fell from 185.89 days to 70.89 days as collections from institutional buyers normalized. Days Inventory Outstanding (DIO) closed at 28.32 days based on ending finished goods inventory of $196,638. However, Days Payables Outstanding (DPO) contracted from 159.88 days to 93.65 days as suppliers tightened credit terms.
Total cash burn expanded +308.8% YoY to -$3,183,694 in Operating Cash Flow (-$265,308/month). Factoring in maintenance capital expenditures of $2,048, Free Cash Flow stood at -$3,185,742. Balance sheet cash plunged 86.1% YoY to $670,281 as of June 30, 2026, leaving a standalone cash runway of approximately 2.5 months (~76 days).
Total current assets closed at $11,019,992, but liquidity is concentrated: $7,181,337 (65.2% of current assets) consists of an unsecured, unpledged loan receivable issued to an unaffiliated individual at a 4.35% coupon, maturing July 8, 2027 (gross principal of $9.44 million less $2.26 million CECL allowance). Total funded debt decreased 72.8% to $319,112 ($187,750 in short-term third-party loans, $85,085 in 7% convertible debt settled post-year-end, and $46,277 in long-term vehicle debt), yielding an apparent net cash position of $351,169 against negative EBITDA of -$10,054,853. Stockholders' equity reached $7,005,814, bolstered by $8.24 million in private placement equity proceeds and $3.25 million in common shares (5,300,000 shares) issued to external advisory firms.
Infrastructure Layout and Regional Moats
Quanome Technologies maintains an asset-light corporate structure across the United States, Mainland China, and Taiwan, Province of China, owning zero captive manufacturing plants or laboratory facilities:
The physical footprint consists of:
* Executive Headquarters: Leased office suite at 112W 34th Street, New York, NY (lease term September 1, 2026 – August 31, 2027).
* Operating Pharmaceutical Headquarters: Leased administrative spaces in Wuhan, Hubei Province, Mainland China (~599 square meters across two premises expiring December 2029 and March 2027), supported by third-party contracted pharmaceutical warehouse and storage facilities.
* Divested Freight Hub: Former freight consolidation hub in Chicago, Illinois, transferred under the February 12, 2026 disposition of American Bear Logistics Corp. (ABL Chicago), shedding $11,388,097 in total liabilities.
The operating core relies entirely on Hupan Pharmaceutical (Hubei) Co., Ltd., which holds regional operating qualifications including the Drug Business License (药品经营许可证, carrying an intangible book value of $279,956 amortized through October 2029), Medical Device Business License, Class II Medical Device Filing, and Food Business License. The business features extreme procurement concentration: the top two pharmaceutical manufacturers accounted for 89.7% of total FY2026 inventory purchases (49.7% and 40.0% respectively), with the top two vendors representing 80.5% of accounts payable.
Downstream customer concentration is elevated: the top four commercial clients generated 63.6% of total revenue (Customer A: 22.0%, Customer B: 16.4%, Customer C: 12.6%, Customer D: 12.6%) and 68.7% of outstanding trade accounts receivable. None of these accounts operate under exclusive supply agreements.
The planned technology infrastructure pivot centers on a Purchase and Sale Agreement executed on September 16, 2026, with Compal Electronics, Inc. (Taiwan, Province of China) to acquire 32 GPU AI servers for an aggregate cost of approximately $18.8 million. The terms mandate a 20% cash deposit (~$3.76 million) upon order acceptance and the remaining 80% (~$15.04 million) prior to delivery. This hardware is subject to U.S. Export Administration Regulations (EAR) enforced by the Bureau of Industry and Security (BIS), requiring customer beneficial ownership screening and end-user verification.
HDIN Institutional Verdict
Quanome Technologies presents an asymmetrical risk profile characterized by a disconnect between capital commitments and liquid treasury reserves:
* Capital Commitment Disconnect: Management's strategic transition into high-performance compute capacity through XDT Infrastructure I, LLC requires approximately $18.8 million in hardware procurement from Compal Electronics, Inc. The initial 20% cash deposit ($3.76 million) exceeds total corporate cash balances ($670,281) by 5.6x, leaving an immediate $3.09 million deposit funding deficit. Standalone unrestricted cash reserves provide less than 76 days of operational cash burn, explaining the Going Concern qualification issued by independent auditor ZH CPA, LLC.
* High Working Capital Credit Risk: Current asset quality is impaired by exposure to unsecured counterparties. The $7.18 million net loan receivable maturing in July 2027 ties up 65.2% of current assets in an uncollateralized instrument that has already triggered a $2.26 million credit loss provision. Combined with the $2.86 million supplier advance write-off, the company absorbed $5.12 million in counterparty impairments in FY2026 alone. Furthermore, operational cash generation remains locked within Mainland China under State Administration of Foreign Exchange (SAFE) capital restrictions, requiring CEO Yang Li to personally advance $220,220 in demand debt to sustain U.S. corporate operations.
* Zero Intellectual Property and Governance Misalignment: The enterprise holds zero active patents, zero proprietary AI models, and recorded $0 in formal research and development expenses across FY2025 and FY2026. Hardware infrastructure is positioned as an unmoated Capacity-as-a-Service model lacking latency or throughput performance guarantees. This operational exposure is compounded by corporate governance deficiencies: the management team and board of directors maintain 0.0% direct beneficial equity ownership, while CEO Yang Li holds the combined roles of CEO, COO, and Chairman of the Board amid un-remediated material weaknesses in internal control over financial reporting.
Presentation Download & Video Access:
- Presentation Download: Click the PDF download link under 'Related Topics' to access the full institutional presentation of this report.
- Video Link: Click this link to watch the HDIN analyst briefing on YouTube.
About HDIN Research:
HDIN Research is a premier global market intelligence and strategic advisory firm specializing in institutional-grade financial analysis, supply chain audits, and macroeconomic forecasting. Our dedicated sector analysts deliver actionable, data-driven insights tailored for private equity, hedge funds, and corporate strategy teams. Visit us at http://www.hdinresearch.com.
2026 AI Transparency Footer:
"This intelligence report was authored by HDIN Research analysts following a rigorous audit of official corporate filings. AI was utilized for massive-scale data synthesis and structural drafting, ensuring 100% inclusion of reported data points. All strategic insights, financial modeling, and final verdicts were verified by our editorial board to ensure professional accuracy and compliance with 2026 Google Search E-E-A-T standards."
1. Quanome Technologies, Inc. disposed of legacy cross-border logistics on February 12, 2026, pivoting 100% of continuing revenue ($5.85 million, +111.8% YoY) to Mainland China pharmaceutical distribution while posting a -$10.19 million operating loss.
2. The enterprise faces an immediate capital shortfall, holding $670,281 in cash against an off-balance-sheet commitment of approximately $18.8 million (requiring a 20% deposit of ~$3.76 million) for 32 GPU servers from Taiwan-based Compal Electronics, Inc.
3. Severe credit exposure characterizes working capital: 65.2% of current assets ($7.18 million net) is tied up in a single unsecured third-party loan, driving an independent auditor Going Concern qualification alongside a $2.86 million supplier advance write-off.
Figure Quanome Technologies FY2026 Strategic & Financial Diagnostics
Segmental Realities and Margin CompressionQuanome Technologies, Inc. [NASDAQ: QNME] (formerly Lakeside Holding Limited) operates under a single reportable operating segment—Pharmaceutical Distribution in Mainland China—managed on a consolidated basis by Chief Executive Officer Yang Li under ASC 280. Disaggregation by operational unit reveals a top-line transformation countered by severe operational spending and asset impairments.
Continuing revenue rose 111.8% year-over-year in FY2026 to $5,850,681, driven by higher sales volumes of infusion products and customer account expansion. Infusion products accounted for $5,330,000 (91.1% of revenue), while specialty pharmaceutical and medical nutrition products generated $520,681 (8.9% of revenue). Gross profit reached $3,315,042, representing a gross margin expansion of 56 basis points to 56.7%, supported by vendor purchase rebates.
Operating expenses surged 344.2% YoY to $13,507,391, escalating the operating loss (EBIT) from -$1,490,449 to -$10,192,349 (-174.2% EBIT margin). This operating deterioration stemmed from non-operational impairment charges and advisory expenses:
* General and administrative expenses reached $5,689,682 (+117.6% YoY), driven by $4,318,739 in third-party legal, consulting, and due diligence fees.
* Selling expenses expanded 571.9% YoY to $2,642,667, incorporating $1,163,396 in advertising and brand marketing, $630,720 in market research and business development, and $483,259 in direct sales payroll.
* Non-operational write-offs included a $2,859,594 write-off of an unrecoverable supplier advance (out of a $2,947,635 / RMB 20.0 million prepayment) and a $2,256,647 Current Expected Credit Loss (CECL) provision recognized on a third-party loan receivable.
* Continuing net loss widened 433.9% to -$10,138,418. Discontinued logistics operations generated net income of $654,388 (inclusive of a $2,556,315 gain on disposal), leaving a consolidated total net loss of -$9,484,030.
Table Segment Revenue Performance and Business Portfolio Development Analysis (FY2025–FY2026)
| Segment / Product Family Performance Breakdown | FY2025 Revenue (USD) | FY2026 Revenue (USD) | YoY Change (USD) | YoY Growth (%) | FY2026 Revenue Share (%) | Operating Margin & Status Dynamics |
| Infusion Products | ~$2,290,083 | ~$5,330,000 | +$3,039,917 | +132.8% | 91.1% | Core distribution volume driver; customer accounts rose from 8 to 12. |
| Specialty Pharma & Medical Nutrition | ~$472,382 | ~$520,681 | +$48,299 | +10.2% | 8.9% | Secondary portfolio; special medical purpose foods and Rx drugs. |
| Total Continuing Pharma Distribution | $2,762,465 | $5,850,681 | +$3,088,216 | +111.8% | 100.0% | Gross Profit: $3,315,042 (56.7% margin, +56 bps YoY on vendor rebates). |
| Discontinued Operations (ABL Logistics) | $15,027,960 | $10,678,106 | -$4,349,854 | -28.9% | N/A | Disposed Feb 12, 2026; truncated operating period prior to divestiture. |
| AI Compute & Inference Services (XDT) | $0 | $0 | $0 | N/A | 0.0% | Development stage; $0 revenue, 0 executed customer contracts. |
| Quantum Technologies (Quantum Nexus) | $0 | $0 | $0 | N/A | 0.0% | Evaluation stage; $0 revenue, scientific advisory network created Aug 2026. |
Working capital metrics showed an improvement in the Cash Conversion Cycle (CCC), declining from 55.07 days in FY2025 to 5.55 days in FY2026 (15.39 days on an average-balance basis). Days Sales Outstanding (DSO) fell from 185.89 days to 70.89 days as collections from institutional buyers normalized. Days Inventory Outstanding (DIO) closed at 28.32 days based on ending finished goods inventory of $196,638. However, Days Payables Outstanding (DPO) contracted from 159.88 days to 93.65 days as suppliers tightened credit terms.
Total cash burn expanded +308.8% YoY to -$3,183,694 in Operating Cash Flow (-$265,308/month). Factoring in maintenance capital expenditures of $2,048, Free Cash Flow stood at -$3,185,742. Balance sheet cash plunged 86.1% YoY to $670,281 as of June 30, 2026, leaving a standalone cash runway of approximately 2.5 months (~76 days).
Total current assets closed at $11,019,992, but liquidity is concentrated: $7,181,337 (65.2% of current assets) consists of an unsecured, unpledged loan receivable issued to an unaffiliated individual at a 4.35% coupon, maturing July 8, 2027 (gross principal of $9.44 million less $2.26 million CECL allowance). Total funded debt decreased 72.8% to $319,112 ($187,750 in short-term third-party loans, $85,085 in 7% convertible debt settled post-year-end, and $46,277 in long-term vehicle debt), yielding an apparent net cash position of $351,169 against negative EBITDA of -$10,054,853. Stockholders' equity reached $7,005,814, bolstered by $8.24 million in private placement equity proceeds and $3.25 million in common shares (5,300,000 shares) issued to external advisory firms.
Infrastructure Layout and Regional Moats
Quanome Technologies maintains an asset-light corporate structure across the United States, Mainland China, and Taiwan, Province of China, owning zero captive manufacturing plants or laboratory facilities:
The physical footprint consists of:
* Executive Headquarters: Leased office suite at 112W 34th Street, New York, NY (lease term September 1, 2026 – August 31, 2027).
* Operating Pharmaceutical Headquarters: Leased administrative spaces in Wuhan, Hubei Province, Mainland China (~599 square meters across two premises expiring December 2029 and March 2027), supported by third-party contracted pharmaceutical warehouse and storage facilities.
* Divested Freight Hub: Former freight consolidation hub in Chicago, Illinois, transferred under the February 12, 2026 disposition of American Bear Logistics Corp. (ABL Chicago), shedding $11,388,097 in total liabilities.
The operating core relies entirely on Hupan Pharmaceutical (Hubei) Co., Ltd., which holds regional operating qualifications including the Drug Business License (药品经营许可证, carrying an intangible book value of $279,956 amortized through October 2029), Medical Device Business License, Class II Medical Device Filing, and Food Business License. The business features extreme procurement concentration: the top two pharmaceutical manufacturers accounted for 89.7% of total FY2026 inventory purchases (49.7% and 40.0% respectively), with the top two vendors representing 80.5% of accounts payable.
Downstream customer concentration is elevated: the top four commercial clients generated 63.6% of total revenue (Customer A: 22.0%, Customer B: 16.4%, Customer C: 12.6%, Customer D: 12.6%) and 68.7% of outstanding trade accounts receivable. None of these accounts operate under exclusive supply agreements.
The planned technology infrastructure pivot centers on a Purchase and Sale Agreement executed on September 16, 2026, with Compal Electronics, Inc. (Taiwan, Province of China) to acquire 32 GPU AI servers for an aggregate cost of approximately $18.8 million. The terms mandate a 20% cash deposit (~$3.76 million) upon order acceptance and the remaining 80% (~$15.04 million) prior to delivery. This hardware is subject to U.S. Export Administration Regulations (EAR) enforced by the Bureau of Industry and Security (BIS), requiring customer beneficial ownership screening and end-user verification.
HDIN Institutional Verdict
Quanome Technologies presents an asymmetrical risk profile characterized by a disconnect between capital commitments and liquid treasury reserves:
* Capital Commitment Disconnect: Management's strategic transition into high-performance compute capacity through XDT Infrastructure I, LLC requires approximately $18.8 million in hardware procurement from Compal Electronics, Inc. The initial 20% cash deposit ($3.76 million) exceeds total corporate cash balances ($670,281) by 5.6x, leaving an immediate $3.09 million deposit funding deficit. Standalone unrestricted cash reserves provide less than 76 days of operational cash burn, explaining the Going Concern qualification issued by independent auditor ZH CPA, LLC.
* High Working Capital Credit Risk: Current asset quality is impaired by exposure to unsecured counterparties. The $7.18 million net loan receivable maturing in July 2027 ties up 65.2% of current assets in an uncollateralized instrument that has already triggered a $2.26 million credit loss provision. Combined with the $2.86 million supplier advance write-off, the company absorbed $5.12 million in counterparty impairments in FY2026 alone. Furthermore, operational cash generation remains locked within Mainland China under State Administration of Foreign Exchange (SAFE) capital restrictions, requiring CEO Yang Li to personally advance $220,220 in demand debt to sustain U.S. corporate operations.
* Zero Intellectual Property and Governance Misalignment: The enterprise holds zero active patents, zero proprietary AI models, and recorded $0 in formal research and development expenses across FY2025 and FY2026. Hardware infrastructure is positioned as an unmoated Capacity-as-a-Service model lacking latency or throughput performance guarantees. This operational exposure is compounded by corporate governance deficiencies: the management team and board of directors maintain 0.0% direct beneficial equity ownership, while CEO Yang Li holds the combined roles of CEO, COO, and Chairman of the Board amid un-remediated material weaknesses in internal control over financial reporting.
Presentation Download & Video Access:
- Presentation Download: Click the PDF download link under 'Related Topics' to access the full institutional presentation of this report.
- Video Link: Click this link to watch the HDIN analyst briefing on YouTube.
About HDIN Research:
HDIN Research is a premier global market intelligence and strategic advisory firm specializing in institutional-grade financial analysis, supply chain audits, and macroeconomic forecasting. Our dedicated sector analysts deliver actionable, data-driven insights tailored for private equity, hedge funds, and corporate strategy teams. Visit us at http://www.hdinresearch.com.
2026 AI Transparency Footer:
"This intelligence report was authored by HDIN Research analysts following a rigorous audit of official corporate filings. AI was utilized for massive-scale data synthesis and structural drafting, ensuring 100% inclusion of reported data points. All strategic insights, financial modeling, and final verdicts were verified by our editorial board to ensure professional accuracy and compliance with 2026 Google Search E-E-A-T standards."