CSL Limited: Balance Sheet Cleansed by $7.9B Charges as Underlying Operations Deliver $5.7B EBITDA
Date : 2026-10-01
Reading : 401
HDIN Executive Takeaways
1. CSL Limited [ASX: CSL] absorbed US$7,923 million in pre-tax restructuring and non-cash asset impairments during FY2025/2026, driving statutory NPAT to a loss of US$(2,579) million while underlying EBITDA rose +3.21% to US$5,661 million.
2. Upstream plasma efficiency accelerated via the full US deployment of the Rika and iNomi™ platforms (+10% volume per donor, <35-minute cycle time), while midstream processing scaled at Broadmeadows Facility F (>10 million liters capacity).
3. Following consecutive AGM shareholder strikes (26.36% in 2024; 42.32% in 2025), the Board replaced non-IFRS NPATA metrics with statutory NPAT (50%) and Revenue (20%) for short-term incentives, while pivoting long-term incentives entirely to 100% Relative TSR.
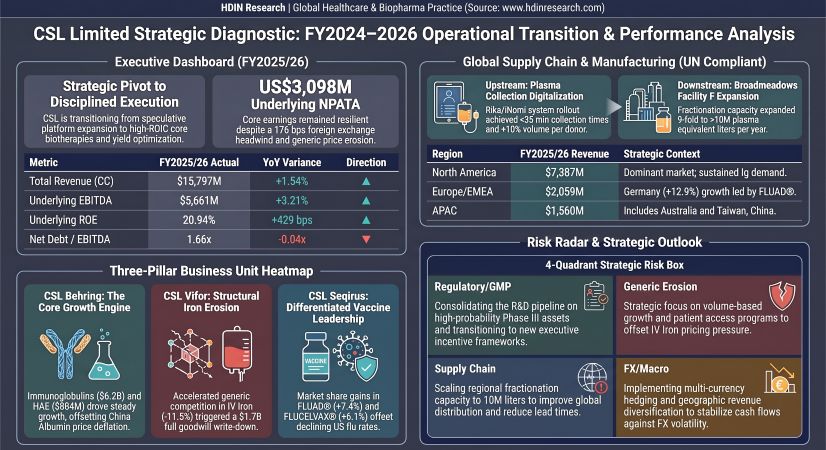
Figure CSL Limited Strategic Diagnostic FY2024-2026 0perational Transition & Performance Analysis
Segmental Realities, Non-Cash De-Risking, and Margin Dynamics
During FY2025/2026, CSL Limited recorded total operating revenue of US$15,797 million, representing a +1.54% reported expansion over US$15,558 million in FY2024/2025. Underlying EBIT rose +3.40% to US$4,620 million, and underlying EBITDA grew +3.21% to US$5,661 million. However, statutory performance was distorted by US$7,923 million in pre-tax restructuring and non-cash impairment charges (comprising US$7,079 million in asset impairments), precipitating a statutory EBIT decline to US$(3,682) million and a statutory net loss after tax of US$(2,579) million, down from a US$3,002 million statutory net profit in FY2024/2025.
Underlying NPATA reached US$3,098 million, contracting -2.00% at constant currency (CC) and -3.76% on a reported basis due to a 176 basis point foreign exchange headwind (~US$57 million) as the US Dollar strengthened against European revenue currencies. Gross profit held flat at US$8,075 million (-0.05% reported), with gross margin compressing by 81 basis points from 51.93% to 51.12%.
Table CSL CONSOLIDATED FINANCIAL SUMMARY
Operating performance across CSL Limited's three primary business segments diverged significantly:
Table OPERATING SEGMENT BREAKDOWN (USD MILLIONS)
CSL Behring's gross margin fell 100 basis points to 49.60%, pressured by a -14.03% top-line contraction in Albumin due to price deflation across hospital channels in Mainland China and fixed overhead cost under-absorption. CSL Seqirus experienced top-line headwinds from broader declines in United States seasonal flu immunization rates and cyclical pre-pandemic delivery timing (-69.04%), mitigated by gains in adjuvanted (FLUAD®) and cell-based (FLUCELVAX®) doses. CSL Vifor's top line climbed +6.49% as nephrology adoption (+20.21%) counterbalanced post-loss-of-exclusivity (LOE) generic erosion in Ferinject® and Venofer®.
The Vifor Fresenius Medical Care Renal Pharma (VFMCRP) joint venture (55% CSL, 45% Fresenius Medical Care) reported net sales of US$1,075 million (+22.44% YoY vs US$878 million), with other income falling -27.78% from US$18 million to US$13 million. VFMCRP generated US$457 million in operating cash flow (-14.58% YoY vs US$535 million) and distributed US$155 million in cash dividends to FMC (+55.00% YoY vs US$100 million). However, non-cash product IP impairments of US$1,298 million net of tax swung VFMCRP from an operating profit of US$307 million and net profit of US$302 million in FY2024/2025 to an operating loss of US$(1,095) million and a net loss of US$(906) million in FY2025/2026, contracting net equity from US$3,027 million to US$1,776 million.
Total pre-tax portfolio write-downs for CSL Vifor reached US$4,845 million:
The CSL Vifor value-in-use (VIU) impairment model applied a post-tax discount rate of 8.3% (up from 8.0% in FY2024/2025, with individual material asset discount rates ranging from 8.3% to 9.5%) and an implied pre-tax discount rate of 10.5% (up from 9.5%). Note 3 stress-testing disclosures revealed the following operational sensitivities:
* Ferinject® IP: A ±1.0% shift in the post-tax discount rate adjusts the recoverable amount by US$(48) million / +US$52 million; a ±10.0% variance in forecast revenue alters the recoverable amount by US$(174) million / +US$173 million.
* Venofer® IP: A -10.0% variance in forecast revenue reduces the recoverable amount by US$(47) million.
* Mircera® IP: A -10.0% variance in forecast revenue reduces the recoverable amount by US$(169) million; a +1.0% shift in government-reimbursed payer mix reduces the recoverable amount by US$(33) million.
* Velphoro® IP: A -10.0% decline in post-TDAPA forecast revenue reduces the recoverable amount by US$(31) million prior to scheduled US TDAPA expiry in December 2026.
Additional group-wide capital pruning included a US$931 million PPE impairment on the leased recombinant facility in Lengnau, Switzerland, following a reassessment of third-party contract manufacturing commercial projections; a US$590 million total sa-mRNA platform termination charge (US$483 million IP write-off, US$50 million PPE/right-of-use asset write-downs, and US$57 million in onerous contracts and related exit costs), which eliminated US$4.6 billion in unrecognised future milestone commitments (reducing total group commitments from US$7,749 million to US$3,153 million); and a US$191 million PPE impairment across CSL Seqirus manufacturing lines.
Corporate tax adjustments partially shielded balance sheet equity. Following the write-downs, CSL Behring AG recognised US$853 million in Deferred Tax Assets (DTAs) against Swiss statutory tax losses, with an additional US$298 million in DTAs remaining unrecognised as of 30 June 2026. Global minimum tax rules under OECD Pillar Two took effect on 1 July 2024 without material impact on group tax expense. Deloitte audited OECD arm's-length intercompany transfer pricing and the elimination of unrealised intercompany profits as a Key Audit Matter, covering operations that generate over 90% of revenue outside Australia. Contingent liabilities disclosed under Note 13(b) (Note 13 in FY2024/2025) for ordinary litigation remain unprovisioned as less than probable. Antitrust exposure resolved in May 2025 when the UK Competition and Markets Authority (CMA) closed its probe into legacy Vifor anti-competitive conduct following a voluntary, ex-gratia payment of £23 million (~US$29 million) to the UK National Health Service (NHS), without admission of liability or penalties.
Table DUPONT DECONSTRUCTION & LEVERAGE AUDIT
Asset turnover expanded from 0.395x to 0.469x as total assets contracted from US$39.4 billion to US$33.6 billion. Underlying ROE rose 429 basis points to 20.94% based on the contracted US$14,797 million parent equity base.
CSL Limited reduced total debt (including lease liabilities) by US$602 million to US$10,896 million (down from US$11,498 million). Total debt excluding leases declined by US$453 million to US$9,383 million (down from US$9,836 million). Cash and cash equivalents decreased by US$644 million to US$1,513 million following the completion of an on-market share buy-back of 6.4 million ordinary shares for A$1.0 billion (US$724 million at an average price of A$166.16 per share) and dividend payments of US$1,412 million (US$2.92 per share, comprising an interim dividend of US$1.30 and a final dividend of US$1.62, identical to FY2024/2025's US$2.92 per share and US$1,334 million cash distribution). Net debt closed at US$9,383 million (versus US$9,341 million in FY2024/2025), holding the Net Debt / Underlying EBITDA leverage ratio at a conservative 1.66x (versus 1.70x). Fixed-rate debt remained stable at 84.0%, where a 100-basis-point parallel shift in floating rates impacts pre-tax income by ~US$11 million. The debt maturity schedule shows US$1,514 million in interest-bearing principal maturing within 12 months (alongside US$3,475 million in trade payables, driven by a US$500 million senior 144A note shifting to current), US$4,390 million due in 1 to 5 years, and US$8,249 million maturing beyond 5 years.
Infrastructure Footprint, Supply Redundancy, and ESG Vector
CSL Limited’s upstream plasma supply relies on an automated network of CSL Plasma collection centers across the United States and Europe. Operational deployment of the FDA-cleared Rika Plasma Donation System™ paired with iNomi™ algorithms reduced average donor cycle times to under 35 minutes and increased plasma collection volume by ~10% per donor. Intake workflows were augmented in May 2025 via the enterprise rollout of the Plasma Medical Quick Search AI screening platform across all US and Puerto Rico collection centers. Donor satisfaction yielded an 88.3% Overall Satisfaction (OSAT) score in FY2025/2026, with willingness to donate again recorded at 88% (compared to 93% in FY2024/2025). Upstream center overhead—averaging ~US$6 million in local payroll and donor compensation across ~50 employees per site—was absorbed through volume yield gains.
Table GEOGRAPHIC REVENUE & ASSET FOOTPRINT SUMMARY
In October 2024, CSL divested its 100% equity stake in Wuhan Zhong Yuan Ruide Biological Products Co. Ltd. (Ruide) and its associated collection centers to Chengdu Rongsheng for US$185 million, transitioning Greater China operations toward high-value imports. Regional regulatory execution in China and Hong Kong SAR included:
* National Reimbursement Drug List (NRDL) inclusion of the pediatric indication for Ferinject® in Mainland China.
* Registration approval of KORSUVA® for chronic kidney disease-associated pruritus (CKD-aP) in Mainland China.
* Registration approval for the Factor IX gene therapy HEMGENIX® across both Hong Kong SAR and Taiwan, China.
* Age expansion for the adjuvanted FLUAD® quadrivalent vaccine to adults aged 50 and older in Taiwan, China.
Midstream fractionation is centered across three global hubs: Broadmeadows (Melbourne), Kankakee (Illinois), and Bern (Switzerland). Broadmeadows Facility F (Project Aurora) completed commissioning, delivering a ninefold capacity expansion to >10 million plasma equivalent liters per year and securing the ISPE 2025 Facility of the Year Award (Pharma 4.0 category). At Kankakee, CSL approved a US$1.5 billion 5-year capital outlay dedicated to next-generation extraction technologies under the Horizon 1 and Horizon 2 yield programs, maximizing immunoglobulin grams extracted per liter of raw plasma. Recombinant operations at Lengnau were adjusted following the US$931 million write-down under its 20-year operating lease to Thermo Fisher Scientific, while the Marburg, Germany facility sustained dedicated European fractionation and coagulation factor production.
CSL Seqirus operationalized its sovereign cell-based manufacturing site in Tullamarine (Melbourne) in December 2025. Engineered with 5-Star Green Star certification under an Australian sovereign biosecurity deed, Tullamarine establishes first-wave emergency pandemic capacity exceeding 150 million doses, mirroring the Holly Springs, North Carolina facility. Global public health agreements generated US$183 million in reservation revenues, backed by an EU Health Emergency Preparedness and Response Authority (HERA) reservation contract for 27 million pre-pandemic doses from Liverpool (UK), alongside commitments with PAHO, the US government (H5 avian flu), Canada, Sweden, and New Zealand. CSL Vifor's synthetic active pharmaceutical ingredient (API) production remains anchored at its modular Multicube facility in St. Gallen, Switzerland.
Clinical trial management rationalized active studies from 59 in FY2024/2025 to 41 in FY2025/2026, lowering group R&D cash expenditure from US$1,359 million to US$1,223 million while securing 83 regulatory approvals (60 new registrations, 23 indication line extensions):
* ANDEMBRY® (garadacimab): Monoclonal antibody targeting Factor XIIa for HAE prophylaxis; demonstrated >99% median attack reduction versus placebo in Phase III, met primary endpoints in pediatric cohorts (ages 2–11), and secured approvals across 12+ jurisdictions (US, EU, UK, Japan, Australia, Switzerland, Canada, UAE, Brazil, Israel, NZ, Saudi Arabia), with regulatory dossiers pending in China, South Korea, Taiwan (China), Argentina, Chile, Colombia, and Hong Kong SAR.
* HEMGENIX®: Phase III HOPE-B 5-year data demonstrated 36% mean Factor IX expression, a 63% reduction in Annualized Bleeding Rate (ABR), and 94% of patients free from routine Factor IX prophylaxis, generating US$1,515 million within the Haemophilia franchise (+1.81% YoY).
* FILSPARI® (sparsentan): Converted conditional authorization into standard EU marketing authorization for IgA Nephropathy, anchoring nephrology expansion.
* Pipeline Developments: Global Phase IIb/III evaluation of clazakizumab (anti-IL-6 mAb) for cardiovascular risk reduction in end-stage kidney disease (ESKD) dialysis patients (NCT05485961; partnered with Eli Lilly for non-ESKD indications); Phase III advancement of VMX-C001 (recombinant protein for Factor Xa inhibitor reversal in urgent surgery, partnered with VarmX BV with an exclusive acquisition option); Phase II trials of CSL301 (anti-alpha-2 antiplasmin) in pulmonary embolism; Phase II development for sickle cell disease vaso-occlusive crises; European approval of RiaSTAP® for acquired fibrinogen deficiency (AFD); and Phase III advancement of cell-based adjuvanted trivalent influenza vaccine (aTIVc).
Table OPERATIONAL COMPLIANCE & ESG AUDIT RECORD
External health authority audits across FY2025/2026 totaled 381 independent inspections (conducted by the US FDA, European EMA, UK MHRA, Australian TGA, Japanese PMDA, Chinese NMPA, Health Canada, SAHPRA, ANMAT, ALIMS, and HLfGP), resulting in zero critical findings and zero license suspensions. Environmental management cut Scope 1 and Scope 2 market-based greenhouse gas emissions by 28% against the FY2021 baseline (reaching 238 KT CO2-e), supported by 100% renewable electricity power purchase agreements in Australia that lowered Scope 2 emissions by 52.1% from FY2023/2024 levels. Scope 3 value chain emissions (1,281 KT CO2-e) were disclosed one year ahead of mandatory AASB S2 requirements, with 64% of suppliers committed to Science Based Targets initiative (SBTi) targets. However, water consumption across priority water-stressed manufacturing locations (Kankakee, Broadmeadows, and Tullamarine) expanded to +32% above the FY2021 baseline due to facility commissioning, missing the zero-growth sustainability target.
HDIN Institutional Verdict
CSL Limited's FY2025/2026 performance represents an aggressive accounting and operational restructuring. By expensing US$7,923 million in pre-tax restructuring and impairment charges—eliminating the entire US$1,700 million CSL Vifor goodwill balance and stripping US$2,286 million in carrying value from Ferinject® and Venofer®—interim leadership dismantled unachievable valuation assumptions inherited from the August 2022 Vifor Pharma acquisition.
The governance overhaul directly addresses shareholder friction. The 2024 AGM "first strike" (26.36% vote against the Remuneration Report) expanded into an outright revolt at the 2025 AGM, delivering a 42.32% "second strike" alongside a -50% total shareholder return in AUD over FY2026. The Board eliminated the non-IFRS NPATA metric, which had granted executive short-term incentive payouts of 62.7% of maximum opportunity (including US$2,789,471 for former CEO Dr. Paul McKenzie) in FY2024/2025 despite nascent portfolio distress.
In FY2025/2026, the Board exercised total downward discretion:
* Underlying NPATA missed internal targets, contributing 0% toward executive STI scorecards.
* Average Executive KMP STI payout dropped to 3.0% of maximum opportunity.
* Departing CEO Dr. Paul McKenzie and departing CFO Joy Linton received US$0 in STI bonuses. Incoming CFO Ken Lim received US$123,545 (25% of target opportunity; FY27 base salary set at US$729,611, up +8%).
* FY2024 PSU long-term incentive grants lapsed at 0.0% vesting as 3-year performance hurdles collapsed (ROIC at 4.1% against a 13.0% threshold; EPS compound growth at -205% against a 9.0% threshold).
Executive leadership changes restructured key roles: Interim CEO and Managing Director Gordon Naylor assumed operational control on a fixed salary of US$1,959,142 and a one-off grant of US$3.92 million in RSUs (holding lock to August 2029), with complete exclusion from STI and LTI bonus participation to ensure objective operational execution during the permanent chief executive search. Andy Schmeltz stepped down as Chief Commercial Officer, handing commercial execution for CSL Behring and CSL Vifor to Diego Sacristan effective 1 July 2026. Non-Executive Director turnover added Dr. Brian Daniels, Ms. Elaine Sorg, Mr. Cameron Price (Chair of the Human Resources & Remuneration Committee), and Mr. Costa Saroukos, following the retirements of Prof. Duncan Maskell, Dr. Megan Clark AC, and Ms. Marie McDonald. Mandatory minimum shareholdings were enforced at 3x base salary for the CEO, 1x for Executive KMP, and 1x base fees for Non-Executive Directors.
CSL's operational plasma and vaccine infrastructure remains structurally resilient. Underlying cash generation (US$3,512 million CFO; US$2,866 million FCF) supported US$646 million in capital additions, stable US$2.92-per-share dividends (US$1,412 million total), and a US$724 million share repurchase, holding balance sheet leverage to 1.66x Net Debt / Underlying EBITDA.
With US$1.5 billion deployed at Kankakee, Facility F operational at Broadmeadows (>10 million liters), and sovereign pandemic security monetized at Tullamarine (>150 million doses), CSL has removed non-viable platform commitments (sa-mRNA exit eliminating US$4.6 billion in pipeline milestones). To restore long-term ROIC toward double-digit targets, incoming leadership must manage the margin drag from generic IV iron substitution and China Albumin price deflation by scaling Rika-driven plasma collection cost savings and accelerating rare nephrology market share via FILSPARI®.
Presentation Download & Video Access
Presentation Download: Click the PDF download link under 'Related Topics' to access the full institutional presentation of this report.
Video Link: Click this link to watch the HDIN analyst briefing on YouTube.
About HDIN Research
HDIN Research is a premier global market intelligence and strategic advisory firm specializing in institutional-grade financial analysis, supply chain audits, and macroeconomic forecasting. Our dedicated sector analysts deliver actionable, data-driven insights tailored for private equity, hedge funds, and corporate strategy teams. Visit us at http://www.hdinresearch.com.
2026 AI Transparency Footer
This intelligence report was authored by HDIN Research analysts following a rigorous audit of official corporate filings. AI was utilized for massive-scale data synthesis and structural drafting, ensuring 100% inclusion of reported data points. All strategic insights, financial modeling, and final verdicts were verified by our editorial board to ensure professional accuracy and compliance with 2026 Google Search E-E-A-T standards.
1. CSL Limited [ASX: CSL] absorbed US$7,923 million in pre-tax restructuring and non-cash asset impairments during FY2025/2026, driving statutory NPAT to a loss of US$(2,579) million while underlying EBITDA rose +3.21% to US$5,661 million.
2. Upstream plasma efficiency accelerated via the full US deployment of the Rika and iNomi™ platforms (+10% volume per donor, <35-minute cycle time), while midstream processing scaled at Broadmeadows Facility F (>10 million liters capacity).
3. Following consecutive AGM shareholder strikes (26.36% in 2024; 42.32% in 2025), the Board replaced non-IFRS NPATA metrics with statutory NPAT (50%) and Revenue (20%) for short-term incentives, while pivoting long-term incentives entirely to 100% Relative TSR.
Figure CSL Limited Strategic Diagnostic FY2024-2026 0perational Transition & Performance Analysis
Segmental Realities, Non-Cash De-Risking, and Margin Dynamics
During FY2025/2026, CSL Limited recorded total operating revenue of US$15,797 million, representing a +1.54% reported expansion over US$15,558 million in FY2024/2025. Underlying EBIT rose +3.40% to US$4,620 million, and underlying EBITDA grew +3.21% to US$5,661 million. However, statutory performance was distorted by US$7,923 million in pre-tax restructuring and non-cash impairment charges (comprising US$7,079 million in asset impairments), precipitating a statutory EBIT decline to US$(3,682) million and a statutory net loss after tax of US$(2,579) million, down from a US$3,002 million statutory net profit in FY2024/2025.
Underlying NPATA reached US$3,098 million, contracting -2.00% at constant currency (CC) and -3.76% on a reported basis due to a 176 basis point foreign exchange headwind (~US$57 million) as the US Dollar strengthened against European revenue currencies. Gross profit held flat at US$8,075 million (-0.05% reported), with gross margin compressing by 81 basis points from 51.93% to 51.12%.
Table CSL CONSOLIDATED FINANCIAL SUMMARY
| Financial Metric (USD Millions) | FY2024/2025 | FY2025/2026 | YoY Change / Evaluation |
|---|---|---|---|
| Total Operating Revenue | $15,558 | $15,797 | +1.54% |
| Gross Profit | $8,079 | $8,075 | -0.05% |
| Gross Profit Margin (%) | 51.93% | 51.12% | -81 bps |
| Statutory EBIT | $4,134 | $(3,682) | N/A (impacted by exceptional items) |
| Underlying EBIT | $4,468 | $4,620 | +3.40% |
| Statutory EBITDA | $5,151 | $(2,641) | N/A (impacted by exceptional items) |
| Underlying EBITDA | $5,485 | $5,661 | +3.21% |
| Statutory NPAT | $3,002 | $(2,579) | N/A (affected by non-recurring adjustments) |
| Underlying NPATA | $3,219 | $3,098 | -3.76% |
| Operating Cash Flow (CFO) | $3,561 | $3,512 | -1.38% |
| Property, Plant & Equipment Capital Expenditure (PPE CAPEX) | $636 | $646 | +1.57% |
| PPE CAPEX as % of Total Revenue | 4.09% | 4.09% | Stable (0 bps change) |
| Free Cash Flow (CFO - PPE CAPEX) | $2,925 | $2,866 | -2.02% |
| Total Capital Outlays (PPE + Intangibles) | $998 | $1,277 | +27.96% |
Operating performance across CSL Limited's three primary business segments diverged significantly:
Table OPERATING SEGMENT BREAKDOWN (USD MILLIONS)
| Segment / Product Portfolio | FY2024/2025 (USD Millions) | FY2025/2026 (USD Millions) | YoY Change / Evaluation |
|---|---|---|---|
| CSL Behring Segment Total | $11,158 | $11,387 | +2.05% |
| — Immunoglobulins (Privigen, Hizentra) | $6,064 | $6,248 | +3.03% |
| — Albumin | $1,297 | $1,115 | -14.03% |
| — Haemophilia (Idelvion, Hemgenix, etc.) | $1,488 | $1,515 | +1.81% |
| — Hereditary Angioedema (HAE) | $760 | $884 | +16.32% |
| — Peri-Operative Bleeding (Kcentra) | $913 | $834 | -8.65% |
| — Other Products | $598 | $754 | +26.09% |
| CSL Behring Segment Gross Margin (%) | 50.60% | 49.60% | -100 bps |
| CSL Seqirus Segment Total | $2,166 | $2,031 | -6.23% |
| — Adjuvanted Egg-Based Vaccines (FLUAD) | $901 | $968 | +7.44% |
| — Cell Culture Vaccines (FLUCELVAX) | $474 | $503 | +6.12% |
| — Standard Egg-Based Vaccines | $116 | $107 | -7.76% |
| — Pandemic Reservation Fees | $179 | $183 | +2.23% |
| — Pre-Pandemic Product Sales | $197 | $61 | -69.04% |
| — Other / In-Licensed Products | $218 | $170 | -22.02% |
| CSL Vifor Segment Total | $2,234 | $2,379 | +6.49% |
| — Total Iron Portfolio (Ferinject, Venofer) | $1,034 | $915 | -11.51% |
| — Nephrology – Dialysis | $871 | $1,036 | +18.94% |
| — Nephrology – Non-Dialysis | $267 | $330 | +23.60% |
| — Combined Nephrology Franchise | $1,138 | $1,366 | +20.21% |
| — Other Products | $53 | $75 | +41.51% |
CSL Behring's gross margin fell 100 basis points to 49.60%, pressured by a -14.03% top-line contraction in Albumin due to price deflation across hospital channels in Mainland China and fixed overhead cost under-absorption. CSL Seqirus experienced top-line headwinds from broader declines in United States seasonal flu immunization rates and cyclical pre-pandemic delivery timing (-69.04%), mitigated by gains in adjuvanted (FLUAD®) and cell-based (FLUCELVAX®) doses. CSL Vifor's top line climbed +6.49% as nephrology adoption (+20.21%) counterbalanced post-loss-of-exclusivity (LOE) generic erosion in Ferinject® and Venofer®.
The Vifor Fresenius Medical Care Renal Pharma (VFMCRP) joint venture (55% CSL, 45% Fresenius Medical Care) reported net sales of US$1,075 million (+22.44% YoY vs US$878 million), with other income falling -27.78% from US$18 million to US$13 million. VFMCRP generated US$457 million in operating cash flow (-14.58% YoY vs US$535 million) and distributed US$155 million in cash dividends to FMC (+55.00% YoY vs US$100 million). However, non-cash product IP impairments of US$1,298 million net of tax swung VFMCRP from an operating profit of US$307 million and net profit of US$302 million in FY2024/2025 to an operating loss of US$(1,095) million and a net loss of US$(906) million in FY2025/2026, contracting net equity from US$3,027 million to US$1,776 million.
Total pre-tax portfolio write-downs for CSL Vifor reached US$4,845 million:
The CSL Vifor value-in-use (VIU) impairment model applied a post-tax discount rate of 8.3% (up from 8.0% in FY2024/2025, with individual material asset discount rates ranging from 8.3% to 9.5%) and an implied pre-tax discount rate of 10.5% (up from 9.5%). Note 3 stress-testing disclosures revealed the following operational sensitivities:
* Ferinject® IP: A ±1.0% shift in the post-tax discount rate adjusts the recoverable amount by US$(48) million / +US$52 million; a ±10.0% variance in forecast revenue alters the recoverable amount by US$(174) million / +US$173 million.
* Venofer® IP: A -10.0% variance in forecast revenue reduces the recoverable amount by US$(47) million.
* Mircera® IP: A -10.0% variance in forecast revenue reduces the recoverable amount by US$(169) million; a +1.0% shift in government-reimbursed payer mix reduces the recoverable amount by US$(33) million.
* Velphoro® IP: A -10.0% decline in post-TDAPA forecast revenue reduces the recoverable amount by US$(31) million prior to scheduled US TDAPA expiry in December 2026.
Additional group-wide capital pruning included a US$931 million PPE impairment on the leased recombinant facility in Lengnau, Switzerland, following a reassessment of third-party contract manufacturing commercial projections; a US$590 million total sa-mRNA platform termination charge (US$483 million IP write-off, US$50 million PPE/right-of-use asset write-downs, and US$57 million in onerous contracts and related exit costs), which eliminated US$4.6 billion in unrecognised future milestone commitments (reducing total group commitments from US$7,749 million to US$3,153 million); and a US$191 million PPE impairment across CSL Seqirus manufacturing lines.
Corporate tax adjustments partially shielded balance sheet equity. Following the write-downs, CSL Behring AG recognised US$853 million in Deferred Tax Assets (DTAs) against Swiss statutory tax losses, with an additional US$298 million in DTAs remaining unrecognised as of 30 June 2026. Global minimum tax rules under OECD Pillar Two took effect on 1 July 2024 without material impact on group tax expense. Deloitte audited OECD arm's-length intercompany transfer pricing and the elimination of unrealised intercompany profits as a Key Audit Matter, covering operations that generate over 90% of revenue outside Australia. Contingent liabilities disclosed under Note 13(b) (Note 13 in FY2024/2025) for ordinary litigation remain unprovisioned as less than probable. Antitrust exposure resolved in May 2025 when the UK Competition and Markets Authority (CMA) closed its probe into legacy Vifor anti-competitive conduct following a voluntary, ex-gratia payment of £23 million (~US$29 million) to the UK National Health Service (NHS), without admission of liability or penalties.
Table DUPONT DECONSTRUCTION & LEVERAGE AUDIT
| Financial Metric | FY2024/2025 | FY2025/2026 | YoY Change / Evaluation |
|---|---|---|---|
| Statutory Net Profit Margin (%) | 19.29% | -16.33% | -3,562 bps |
| Underlying NPATA Margin (%) | 20.69% | 19.61% | -108 bps |
| Asset Turnover Ratio (x) | 0.395x | 0.469x | +0.074x |
| Total Assets (USD Millions) | $39,400 | $33,646 | -$5,754M |
| Financial Leverage (Assets / Equity) | 1.841x | 2.063x | +0.222x |
| Total Balance Sheet Equity (USD Millions) | $21,400 | $16,307 | -$5,093M |
| Parent Shareholder Equity Base (USD Millions) | $19,300 | $14,797 | -$4,503M |
| Statutory ROE (%) | 14.02% | -15.82% | -2,984 bps |
| Underlying ROE (NPATA / Equity %) | 16.65% | 20.94% | +429 bps |
| Statutory ROIC (%) | 11.50% | -9.50% | -2,100 bps |
Asset turnover expanded from 0.395x to 0.469x as total assets contracted from US$39.4 billion to US$33.6 billion. Underlying ROE rose 429 basis points to 20.94% based on the contracted US$14,797 million parent equity base.
CSL Limited reduced total debt (including lease liabilities) by US$602 million to US$10,896 million (down from US$11,498 million). Total debt excluding leases declined by US$453 million to US$9,383 million (down from US$9,836 million). Cash and cash equivalents decreased by US$644 million to US$1,513 million following the completion of an on-market share buy-back of 6.4 million ordinary shares for A$1.0 billion (US$724 million at an average price of A$166.16 per share) and dividend payments of US$1,412 million (US$2.92 per share, comprising an interim dividend of US$1.30 and a final dividend of US$1.62, identical to FY2024/2025's US$2.92 per share and US$1,334 million cash distribution). Net debt closed at US$9,383 million (versus US$9,341 million in FY2024/2025), holding the Net Debt / Underlying EBITDA leverage ratio at a conservative 1.66x (versus 1.70x). Fixed-rate debt remained stable at 84.0%, where a 100-basis-point parallel shift in floating rates impacts pre-tax income by ~US$11 million. The debt maturity schedule shows US$1,514 million in interest-bearing principal maturing within 12 months (alongside US$3,475 million in trade payables, driven by a US$500 million senior 144A note shifting to current), US$4,390 million due in 1 to 5 years, and US$8,249 million maturing beyond 5 years.
Infrastructure Footprint, Supply Redundancy, and ESG Vector
CSL Limited’s upstream plasma supply relies on an automated network of CSL Plasma collection centers across the United States and Europe. Operational deployment of the FDA-cleared Rika Plasma Donation System™ paired with iNomi™ algorithms reduced average donor cycle times to under 35 minutes and increased plasma collection volume by ~10% per donor. Intake workflows were augmented in May 2025 via the enterprise rollout of the Plasma Medical Quick Search AI screening platform across all US and Puerto Rico collection centers. Donor satisfaction yielded an 88.3% Overall Satisfaction (OSAT) score in FY2025/2026, with willingness to donate again recorded at 88% (compared to 93% in FY2024/2025). Upstream center overhead—averaging ~US$6 million in local payroll and donor compensation across ~50 employees per site—was absorbed through volume yield gains.
Table GEOGRAPHIC REVENUE & ASSET FOOTPRINT SUMMARY
| Region / Jurisdiction | FY2025 Revenue (USD Millions) | FY2026 Revenue (USD Millions) | YoY Change | FY2026 Revenue Share | Regional Assets (USD Millions) |
|---|---|---|---|---|---|
| United States | $7,311 | $7,387 | +1.04% | 46.76% | $3,469 |
| Rest of World (RoW) | $4,452 | $4,924 | +10.60% | 31.17% | $342 |
| Germany | $947 | $1,069 | +12.88% | 6.77% | $1,144 |
| Australia | $890 | $920 | +3.37% | 5.82% | $2,297 |
| China & Hong Kong | $849 | $640 | -24.62% | 4.05% | $18 |
| United Kingdom | $807 | $524 | -35.07% | 3.32% | $544 |
| Switzerland | $302 | $333 | +10.26% | 2.11% | $4,998 |
| Group Consolidated | $15,558 | $15,797 | +1.54% | 100.00% | $12,812 |
In October 2024, CSL divested its 100% equity stake in Wuhan Zhong Yuan Ruide Biological Products Co. Ltd. (Ruide) and its associated collection centers to Chengdu Rongsheng for US$185 million, transitioning Greater China operations toward high-value imports. Regional regulatory execution in China and Hong Kong SAR included:
* National Reimbursement Drug List (NRDL) inclusion of the pediatric indication for Ferinject® in Mainland China.
* Registration approval of KORSUVA® for chronic kidney disease-associated pruritus (CKD-aP) in Mainland China.
* Registration approval for the Factor IX gene therapy HEMGENIX® across both Hong Kong SAR and Taiwan, China.
* Age expansion for the adjuvanted FLUAD® quadrivalent vaccine to adults aged 50 and older in Taiwan, China.
Midstream fractionation is centered across three global hubs: Broadmeadows (Melbourne), Kankakee (Illinois), and Bern (Switzerland). Broadmeadows Facility F (Project Aurora) completed commissioning, delivering a ninefold capacity expansion to >10 million plasma equivalent liters per year and securing the ISPE 2025 Facility of the Year Award (Pharma 4.0 category). At Kankakee, CSL approved a US$1.5 billion 5-year capital outlay dedicated to next-generation extraction technologies under the Horizon 1 and Horizon 2 yield programs, maximizing immunoglobulin grams extracted per liter of raw plasma. Recombinant operations at Lengnau were adjusted following the US$931 million write-down under its 20-year operating lease to Thermo Fisher Scientific, while the Marburg, Germany facility sustained dedicated European fractionation and coagulation factor production.
CSL Seqirus operationalized its sovereign cell-based manufacturing site in Tullamarine (Melbourne) in December 2025. Engineered with 5-Star Green Star certification under an Australian sovereign biosecurity deed, Tullamarine establishes first-wave emergency pandemic capacity exceeding 150 million doses, mirroring the Holly Springs, North Carolina facility. Global public health agreements generated US$183 million in reservation revenues, backed by an EU Health Emergency Preparedness and Response Authority (HERA) reservation contract for 27 million pre-pandemic doses from Liverpool (UK), alongside commitments with PAHO, the US government (H5 avian flu), Canada, Sweden, and New Zealand. CSL Vifor's synthetic active pharmaceutical ingredient (API) production remains anchored at its modular Multicube facility in St. Gallen, Switzerland.
Clinical trial management rationalized active studies from 59 in FY2024/2025 to 41 in FY2025/2026, lowering group R&D cash expenditure from US$1,359 million to US$1,223 million while securing 83 regulatory approvals (60 new registrations, 23 indication line extensions):
* ANDEMBRY® (garadacimab): Monoclonal antibody targeting Factor XIIa for HAE prophylaxis; demonstrated >99% median attack reduction versus placebo in Phase III, met primary endpoints in pediatric cohorts (ages 2–11), and secured approvals across 12+ jurisdictions (US, EU, UK, Japan, Australia, Switzerland, Canada, UAE, Brazil, Israel, NZ, Saudi Arabia), with regulatory dossiers pending in China, South Korea, Taiwan (China), Argentina, Chile, Colombia, and Hong Kong SAR.
* HEMGENIX®: Phase III HOPE-B 5-year data demonstrated 36% mean Factor IX expression, a 63% reduction in Annualized Bleeding Rate (ABR), and 94% of patients free from routine Factor IX prophylaxis, generating US$1,515 million within the Haemophilia franchise (+1.81% YoY).
* FILSPARI® (sparsentan): Converted conditional authorization into standard EU marketing authorization for IgA Nephropathy, anchoring nephrology expansion.
* Pipeline Developments: Global Phase IIb/III evaluation of clazakizumab (anti-IL-6 mAb) for cardiovascular risk reduction in end-stage kidney disease (ESKD) dialysis patients (NCT05485961; partnered with Eli Lilly for non-ESKD indications); Phase III advancement of VMX-C001 (recombinant protein for Factor Xa inhibitor reversal in urgent surgery, partnered with VarmX BV with an exclusive acquisition option); Phase II trials of CSL301 (anti-alpha-2 antiplasmin) in pulmonary embolism; Phase II development for sickle cell disease vaso-occlusive crises; European approval of RiaSTAP® for acquired fibrinogen deficiency (AFD); and Phase III advancement of cell-based adjuvanted trivalent influenza vaccine (aTIVc).
Table OPERATIONAL COMPLIANCE & ESG AUDIT RECORD
| Indicator / Standard | FY2023/24 | FY2024/25 | FY2025/26 | Target |
|---|---|---|---|---|
| Global Regulatory Audits | -- | 403 | 381 | -- |
| • Manufacturing Facility GMP Audits | -- | 27 | 30 | -- |
| • CSL Plasma Collection Center Audits | -- | 376 | 351 | -- |
| • Clinical Trial GCP Audits | -- | 10 | 7 | -- |
| Critical Audit Findings (Blocking Release) | 0 | 0 | 0 | 0 |
| Operating License Suspensions / Revocations | 0 | 0 | 0 | 0 |
| Class II Product Recalls (Urgent Safety) | -- | 2 | 4 | -- |
| FDA Form 483 / Warning Letters | None | None | None | None |
| Scope 1 GHG Emissions (KT CO₂-e) | 133 | 135 | 135 | -- |
| Scope 2 Market-Based GHG Emissions (KT CO₂-e) | 215 | 151 | 103 | -- |
| Total Scope 1 & Scope 2 GHG Emissions (KT CO₂-e) | 348 | 286 | 238 | -42% by FY2030 |
| Scope 2 Location-Based GHG Emissions (KT CO₂-e) | 248.6 | 229.3 | 213.2 | -- |
| Scope 3 Value Chain GHG Emissions (KT CO₂-e) | -- | -- | 1,281 | -- |
| Total Water Consumption (Gigalitres, GL) | 5.69 | 5.55 | 5.70 | -- |
| Priority Water-Stressed Site Growth (%) | -- | +30% | +32% | 0% by FY2021 |
| Total Waste Generated (Metric KT) | 93.80 | 93.51 | 90.72 | -- |
| Manufacturing Waste Recycling Rate (%) | 56% | 54% | 57% | -- |
| Zero-Waste-to-Landfill Rate (%) | -- | -- | 87% | >90% |
| Significant Environmental Breaches | 0 | 0 | 0 | 0 |
| Projected 2030 Carbon Tax Cost Impact | -- | -- | ~$25 million/year | <1% of OPEX |
External health authority audits across FY2025/2026 totaled 381 independent inspections (conducted by the US FDA, European EMA, UK MHRA, Australian TGA, Japanese PMDA, Chinese NMPA, Health Canada, SAHPRA, ANMAT, ALIMS, and HLfGP), resulting in zero critical findings and zero license suspensions. Environmental management cut Scope 1 and Scope 2 market-based greenhouse gas emissions by 28% against the FY2021 baseline (reaching 238 KT CO2-e), supported by 100% renewable electricity power purchase agreements in Australia that lowered Scope 2 emissions by 52.1% from FY2023/2024 levels. Scope 3 value chain emissions (1,281 KT CO2-e) were disclosed one year ahead of mandatory AASB S2 requirements, with 64% of suppliers committed to Science Based Targets initiative (SBTi) targets. However, water consumption across priority water-stressed manufacturing locations (Kankakee, Broadmeadows, and Tullamarine) expanded to +32% above the FY2021 baseline due to facility commissioning, missing the zero-growth sustainability target.
HDIN Institutional Verdict
CSL Limited's FY2025/2026 performance represents an aggressive accounting and operational restructuring. By expensing US$7,923 million in pre-tax restructuring and impairment charges—eliminating the entire US$1,700 million CSL Vifor goodwill balance and stripping US$2,286 million in carrying value from Ferinject® and Venofer®—interim leadership dismantled unachievable valuation assumptions inherited from the August 2022 Vifor Pharma acquisition.
The governance overhaul directly addresses shareholder friction. The 2024 AGM "first strike" (26.36% vote against the Remuneration Report) expanded into an outright revolt at the 2025 AGM, delivering a 42.32% "second strike" alongside a -50% total shareholder return in AUD over FY2026. The Board eliminated the non-IFRS NPATA metric, which had granted executive short-term incentive payouts of 62.7% of maximum opportunity (including US$2,789,471 for former CEO Dr. Paul McKenzie) in FY2024/2025 despite nascent portfolio distress.
In FY2025/2026, the Board exercised total downward discretion:
* Underlying NPATA missed internal targets, contributing 0% toward executive STI scorecards.
* Average Executive KMP STI payout dropped to 3.0% of maximum opportunity.
* Departing CEO Dr. Paul McKenzie and departing CFO Joy Linton received US$0 in STI bonuses. Incoming CFO Ken Lim received US$123,545 (25% of target opportunity; FY27 base salary set at US$729,611, up +8%).
* FY2024 PSU long-term incentive grants lapsed at 0.0% vesting as 3-year performance hurdles collapsed (ROIC at 4.1% against a 13.0% threshold; EPS compound growth at -205% against a 9.0% threshold).
Executive leadership changes restructured key roles: Interim CEO and Managing Director Gordon Naylor assumed operational control on a fixed salary of US$1,959,142 and a one-off grant of US$3.92 million in RSUs (holding lock to August 2029), with complete exclusion from STI and LTI bonus participation to ensure objective operational execution during the permanent chief executive search. Andy Schmeltz stepped down as Chief Commercial Officer, handing commercial execution for CSL Behring and CSL Vifor to Diego Sacristan effective 1 July 2026. Non-Executive Director turnover added Dr. Brian Daniels, Ms. Elaine Sorg, Mr. Cameron Price (Chair of the Human Resources & Remuneration Committee), and Mr. Costa Saroukos, following the retirements of Prof. Duncan Maskell, Dr. Megan Clark AC, and Ms. Marie McDonald. Mandatory minimum shareholdings were enforced at 3x base salary for the CEO, 1x for Executive KMP, and 1x base fees for Non-Executive Directors.
CSL's operational plasma and vaccine infrastructure remains structurally resilient. Underlying cash generation (US$3,512 million CFO; US$2,866 million FCF) supported US$646 million in capital additions, stable US$2.92-per-share dividends (US$1,412 million total), and a US$724 million share repurchase, holding balance sheet leverage to 1.66x Net Debt / Underlying EBITDA.
With US$1.5 billion deployed at Kankakee, Facility F operational at Broadmeadows (>10 million liters), and sovereign pandemic security monetized at Tullamarine (>150 million doses), CSL has removed non-viable platform commitments (sa-mRNA exit eliminating US$4.6 billion in pipeline milestones). To restore long-term ROIC toward double-digit targets, incoming leadership must manage the margin drag from generic IV iron substitution and China Albumin price deflation by scaling Rika-driven plasma collection cost savings and accelerating rare nephrology market share via FILSPARI®.
Presentation Download & Video Access
Presentation Download: Click the PDF download link under 'Related Topics' to access the full institutional presentation of this report.
Video Link: Click this link to watch the HDIN analyst briefing on YouTube.
About HDIN Research
HDIN Research is a premier global market intelligence and strategic advisory firm specializing in institutional-grade financial analysis, supply chain audits, and macroeconomic forecasting. Our dedicated sector analysts deliver actionable, data-driven insights tailored for private equity, hedge funds, and corporate strategy teams. Visit us at http://www.hdinresearch.com.
2026 AI Transparency Footer
This intelligence report was authored by HDIN Research analysts following a rigorous audit of official corporate filings. AI was utilized for massive-scale data synthesis and structural drafting, ensuring 100% inclusion of reported data points. All strategic insights, financial modeling, and final verdicts were verified by our editorial board to ensure professional accuracy and compliance with 2026 Google Search E-E-A-T standards.