AeroEdge Co., Ltd.: Global Aerospace Duopoly Moat Solidifies in Tochigi as Consolidated EBITDA Reaches ¥1.56 Billion
Date : 2026-10-06
Reading : 249
HDIN Executive Takeaways
1. Operating leverage drove FY2026 consolidated revenue up 41.2% year-over-year to ¥5.08 billion, with operating profit scaling to ¥1.15 billion (22.5% operating margin) and EBITDA reaching ¥1.56 billion.
2. Production is centered in Ashikaga, Tochigi Prefecture, executing a 40% globally contracted supply share of CFM LEAP titanium aluminide (TiAl) low-pressure turbine (LPT) blades, backed by a ¥5.02 billion capital deployment plan through June 2027.
3. Institutional earnings quality remains robust with consolidated operating cash flow at ¥2.96 billion (3.79x reported net income), though client concentration presents a structural vulnerability as Safran Aircraft Engines accounts for 97.0% of revenue.
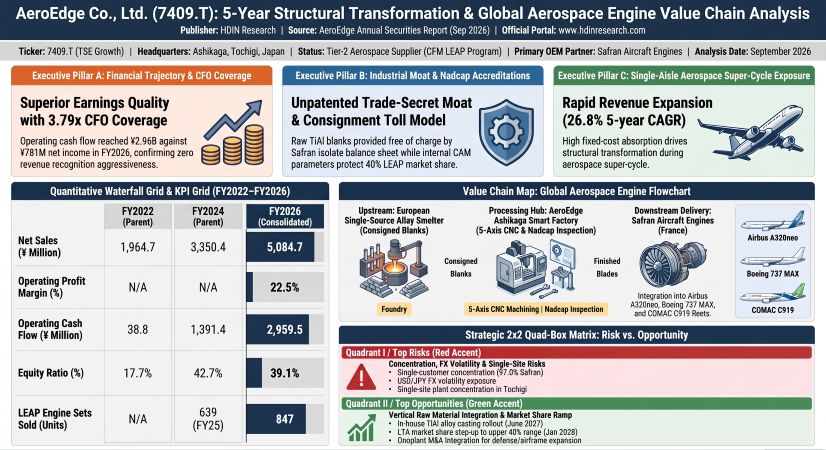
Figure AeroEdae 5-Year Structural Transformation & Global Aerospace Engine Value chain Analysis
 Segmental Realities and Capital Allocation Dynamics
AeroEdge Co., Ltd. [TSE: 7409] transitioned to consolidated reporting in FY2026 (11th fiscal term ending June 30, 2026) following its 100% equity acquisition of Onoplant Co., Ltd. for ¥980.0 million in June 2026. Top-line revenue increased at a compound annual growth rate (CAGR) of 26.8% from FY2022 to FY2026, reaching ¥5,084,657 thousand.
The company operates under a single reportable segment ("Machining Business"), but product-level disclosures reflect two distinct streams:
* CFM LEAP Engine TiAl LPT Blades (Safran Aircraft Engines): ¥4,934,431 thousand (97.0% of total revenue; up 41.0% year-over-year).
* Other Aerospace & Industrial Components (Prototypes, AM, Non-LEAP): ¥150,226 thousand (3.0% of total revenue; up 47.3% year-over-year).
The commercial model functions on customer-consigned raw materials. Safran provides raw TiAl alloy blanks free of charge, isolating AeroEdge from raw titanium and aluminum price swings, eliminating raw material working capital debt, and lowering variable production cost ratios.
Table Financial Performance, Balance Sheet Strength and Cash Flow Analysis (FY2022–FY2026)
Deconstructing Return on Equity (ROE) via DuPont Analysis highlights an inflection from 0.8% in FY2022 to a peak of 52.4% in FY2023, before stabilizing at 16.3% on a consolidated basis (19.2% Parent) in FY2026. The asset turnover component compressed to 0.41x as total assets rose 49.3% in FY2026, while the tax benefit from past loss carryforwards normalized.
Working capital metrics remained intact:
* Days Sales Outstanding (DSO) increased from 41.2 days to 70.5 days, reflecting fourth-quarter export delivery schedules and sample development billings.
* Days Inventory Outstanding (DIO) improved from 98.4 days to 87.2 days; finished goods decreased 68.9% to ¥40,544 thousand, while work-in-progress increased 35.5% to ¥282,566 thousand, corresponding with a 32.6% increase in annual LEAP engine sets delivered (847 sets).
* Balance sheet raw materials and supplies climbed 91.5% to ¥340,257 thousand, indicating precautionary safety stocking of tooling inserts and gases to cushion against supply chain disruptions.
Infrastructure Layout and Regional Moats
AeroEdge operates an export-oriented value chain where 97.4% of consolidated revenue is generated internationally (¥4,934,431 thousand from France; ¥131,931 thousand from Japan; ¥18,294 thousand from other global markets). Export invoices are settled in US dollars under an amended Long-Term Agreement (LTA) with Safran Aircraft Engines running through December 31, 2034. A contractual foreign exchange range clause governs USD/JPY transactions, permitting price adjustments when exchange volatility exceeds agreed bands. To lock in cash flows, AeroEdge held ¥1,546,460 thousand in outstanding forward foreign exchange sell contracts at the close of FY2026.
Production is executed across primary physical assets located in Tochigi Prefecture:
* Ashikaga Head Office Complex (Ashikaga City, Tochigi; 26,885 m² site): Houses Plant A and Plant B, along with a dedicated Testing Laboratory completed in April 2026. Total parent property, plant, and equipment net book value stands at ¥5,550,207 thousand (machinery and equipment: ¥2,377,276 thousand; buildings and structures: ¥1,800,301 thousand; land: ¥478,253 thousand; construction in progress: ¥461,608 thousand; tools and fixtures: ¥385,150 thousand; lease assets: ¥47,617 thousand).
* Onoplant Co., Ltd. Head Office Plant (Kamikawamachi, Tochigi): Dedicated to airframe structural machining and defense sector supply programs, contributing ¥403,638 thousand in net PP&E and ¥886,725 thousand in recorded goodwill.
The operational moat is established by a global duopoly in LEAP engine TiAl low-pressure turbine blade production, sharing the market with a single competitor ("Competitor A," holding ~60%). Ti-48Al-2Cr-2Nb intermetallic material presents high brittleness and micro-cracking risks during processing, requiring AeroEdge's proprietary toolpath CAM code, in-house end-mill designs, and Nadcap-certified Fluorescent Penetrant Inspection (FPI) and X-ray special processes. Because commercial aviation components undergo 10-plus-year validation phases and 20-to-30-year lifecycle support, switching costs are high under FAA and EASA regulatory process freezes.
To support an OEM backlog of 7,469 Airbus A320neo family, 5,404 Boeing 737 MAX family, and 931 COMAC C919 aircraft, AeroEdge committed ¥5,021,000 thousand in capital expenditures across two core initiatives through June 2027:
* Ashikaga Head Office 2nd Plant Expansion: ¥2,575,000 thousand committed (¥886,346 thousand paid by year-end FY2026; completion targeting April 2027).
* Ashikaga Head Office Plant A & B Line Extensions: ¥2,446,000 thousand committed (¥1,130,813 thousand paid; completion targeting June 2027).
These capital outlays support direct material supply. AeroEdge plans to bypass its single European raw alloy supplier bottleneck by commercializing in-house cast raw alloy blanks by June 2027, scaling toward a guaranteed market share into the upper 40% range starting January 2028.
HDIN Institutional Verdict
AeroEdge's high margins and 2.35x five-year cumulative CFO-to-net income coverage confirm structural earnings quality. However, an institutional risk screen reveals two major focal points:
1. Customer Monopsony Drag: Safran Aircraft Engines generated 97.0% of revenue in FY2026. Production rates remain directly tied to Airbus and Boeing narrowbody manufacturing runs. Any delivery delays, design freezes, or fleet groundings translate directly into revenue hits. The acquisition of Onoplant represents an initial effort to access domestic Japanese defense programs, but non-LEAP revenue remains modest at 3.0%.
2. Cash Flow and Re-leveraging Limits: Capital intensity led to negative Free Cash Flow of △¥257,713 thousand in FY2026 despite record operating cash generation. Total interest-bearing liabilities expanded to ¥5,479,040 thousand (44.1% of total assets), generating ¥74,874 thousand in annual interest expenses. While bank covenant limits require parent net assets to stay above ¥1.335 billion (providing an actual cushion of ¥3.51 billion), upcoming capital outlays totaling ¥3.00 billion through FY2027 will test liquidity if single-aisle aircraft delivery schedules face extended supply chain disruptions.
Presentation Download & Video Access
* Presentation Download: Click the PDF download link under 'Related Topics' to access the full institutional presentation of this report.
* Video Link: Click this link to watch the HDIN analyst briefing on YouTube.
About HDIN Research
HDIN Research is a premier global market intelligence and strategic advisory firm specializing in institutional-grade financial analysis, supply chain audits, and macroeconomic forecasting. Our dedicated sector analysts deliver actionable, data-driven insights tailored for private equity, hedge funds, and corporate strategy teams. Visit us at http://www.hdinresearch.com.
2026 AI Transparency Footer
This intelligence report was authored by HDIN Research analysts following a rigorous audit of official corporate filings. AI was utilized for massive-scale data synthesis and structural drafting, ensuring 100% inclusion of reported data points. All strategic insights, financial modeling, and final verdicts were verified by our editorial board to ensure professional accuracy and compliance with 2026 Google Search E-E-A-T standards.
1. Operating leverage drove FY2026 consolidated revenue up 41.2% year-over-year to ¥5.08 billion, with operating profit scaling to ¥1.15 billion (22.5% operating margin) and EBITDA reaching ¥1.56 billion.
2. Production is centered in Ashikaga, Tochigi Prefecture, executing a 40% globally contracted supply share of CFM LEAP titanium aluminide (TiAl) low-pressure turbine (LPT) blades, backed by a ¥5.02 billion capital deployment plan through June 2027.
3. Institutional earnings quality remains robust with consolidated operating cash flow at ¥2.96 billion (3.79x reported net income), though client concentration presents a structural vulnerability as Safran Aircraft Engines accounts for 97.0% of revenue.
Figure AeroEdae 5-Year Structural Transformation & Global Aerospace Engine Value chain Analysis
Segmental Realities and Capital Allocation DynamicsAeroEdge Co., Ltd. [TSE: 7409] transitioned to consolidated reporting in FY2026 (11th fiscal term ending June 30, 2026) following its 100% equity acquisition of Onoplant Co., Ltd. for ¥980.0 million in June 2026. Top-line revenue increased at a compound annual growth rate (CAGR) of 26.8% from FY2022 to FY2026, reaching ¥5,084,657 thousand.
The company operates under a single reportable segment ("Machining Business"), but product-level disclosures reflect two distinct streams:
* CFM LEAP Engine TiAl LPT Blades (Safran Aircraft Engines): ¥4,934,431 thousand (97.0% of total revenue; up 41.0% year-over-year).
* Other Aerospace & Industrial Components (Prototypes, AM, Non-LEAP): ¥150,226 thousand (3.0% of total revenue; up 47.3% year-over-year).
The commercial model functions on customer-consigned raw materials. Safran provides raw TiAl alloy blanks free of charge, isolating AeroEdge from raw titanium and aluminum price swings, eliminating raw material working capital debt, and lowering variable production cost ratios.
Table Financial Performance, Balance Sheet Strength and Cash Flow Analysis (FY2022–FY2026)
| Financial Metric (Consolidated / Parent) | FY2022 (Parent) | FY2023 (Parent) | FY2024 (Parent) | FY2025 (Parent) | FY2026 (Parent) | FY2026 (Consolidated) |
|---|---|---|---|---|---|---|
| Net Sales (JPY thousand) | 1,964,694 | 2,920,991 | 3,350,387 | 3,602,276 | 5,084,657 | 5,084,657 |
| Year-over-Year Revenue Growth | — | +48.7% | +14.7% | +7.5% | +41.2% | +41.2% |
| Gross Profit (JPY thousand) | N/A | N/A | N/A | 1,686,540 | 2,308,394 | 2,308,394 |
| Gross Margin (%) | N/A | N/A | N/A | 46.8% | 45.4% | 45.4% |
| Operating Profit (JPY thousand) | N/A | N/A | N/A | 655,174 | 1,200,582 | 1,145,382 |
| Operating Margin (%) | N/A | N/A | N/A | 18.2% | 23.6% | 22.5% |
| Ordinary Profit (JPY thousand) | 10,764 | 598,189 | 842,981 | 565,172 | 1,173,105 | 1,117,905 |
| Net Income (JPY thousand) | 7,321 | 673,039 | 698,736 | 734,432 | 836,215 | 781,015 |
| Net Profit Margin (%) | 0.37% | 23.04% | 20.86% | 20.39% | 16.45% | 15.36% |
| EBITDA (JPY thousand) | N/A | N/A | N/A | 1,038,229 | N/A | 1,562,684 |
| Total Assets (JPY thousand) | 5,358,096 | 5,788,236 | 7,236,980 | 8,211,404 | 11,488,262 | 12,261,369 |
| Net Assets (JPY thousand) | 955,006 | 1,622,077 | 3,094,081 | 3,890,227 | 4,849,194 | 4,793,994 |
| Equity Ratio (%) | 17.7% | 27.9% | 42.7% | 47.3% | 42.2% | 39.1% |
| Interest-Bearing Debt (JPY thousand) | N/A | N/A | N/A | 3,594,236 | 4,782,416 | 5,479,040 |
| Cash & Cash Equivalents (JPY thousand) | 1,119,296 | 1,728,427 | 1,813,651 | 1,573,893 | 2,357,675 | 2,628,381 |
| Net Debt / EBITDA (x) | N/A | N/A | N/A | 1.95x | N/A | 1.82x |
| Operating Cash Flow (CFO, JPY thousand) | 38,837 | 1,077,424 | 1,391,430 | 1,333,251 | N/A | 2,959,494 |
| Investing Cash Flow (CFI, JPY thousand) | △794,897 | △137,360 | △1,526,507 | △1,952,567 | N/A | △3,217,207 |
| Free Cash Flow (FCF, JPY thousand) | △756,060 | +940,064 | △135,077 | △619,316 | N/A | △257,713 |
| Financing Cash Flow (CFF, JPY thousand) | 53,371 | △337,382 | 234,235 | 378,651 | N/A | 1,309,225 |
| PP&E Cash Purchases / CAPEX (JPY thousand) | N/A | N/A | N/A | 1,952,567 | N/A | 2,481,676 |
Deconstructing Return on Equity (ROE) via DuPont Analysis highlights an inflection from 0.8% in FY2022 to a peak of 52.4% in FY2023, before stabilizing at 16.3% on a consolidated basis (19.2% Parent) in FY2026. The asset turnover component compressed to 0.41x as total assets rose 49.3% in FY2026, while the tax benefit from past loss carryforwards normalized.
Working capital metrics remained intact:
* Days Sales Outstanding (DSO) increased from 41.2 days to 70.5 days, reflecting fourth-quarter export delivery schedules and sample development billings.
* Days Inventory Outstanding (DIO) improved from 98.4 days to 87.2 days; finished goods decreased 68.9% to ¥40,544 thousand, while work-in-progress increased 35.5% to ¥282,566 thousand, corresponding with a 32.6% increase in annual LEAP engine sets delivered (847 sets).
* Balance sheet raw materials and supplies climbed 91.5% to ¥340,257 thousand, indicating precautionary safety stocking of tooling inserts and gases to cushion against supply chain disruptions.
Infrastructure Layout and Regional Moats
AeroEdge operates an export-oriented value chain where 97.4% of consolidated revenue is generated internationally (¥4,934,431 thousand from France; ¥131,931 thousand from Japan; ¥18,294 thousand from other global markets). Export invoices are settled in US dollars under an amended Long-Term Agreement (LTA) with Safran Aircraft Engines running through December 31, 2034. A contractual foreign exchange range clause governs USD/JPY transactions, permitting price adjustments when exchange volatility exceeds agreed bands. To lock in cash flows, AeroEdge held ¥1,546,460 thousand in outstanding forward foreign exchange sell contracts at the close of FY2026.
Production is executed across primary physical assets located in Tochigi Prefecture:
* Ashikaga Head Office Complex (Ashikaga City, Tochigi; 26,885 m² site): Houses Plant A and Plant B, along with a dedicated Testing Laboratory completed in April 2026. Total parent property, plant, and equipment net book value stands at ¥5,550,207 thousand (machinery and equipment: ¥2,377,276 thousand; buildings and structures: ¥1,800,301 thousand; land: ¥478,253 thousand; construction in progress: ¥461,608 thousand; tools and fixtures: ¥385,150 thousand; lease assets: ¥47,617 thousand).
* Onoplant Co., Ltd. Head Office Plant (Kamikawamachi, Tochigi): Dedicated to airframe structural machining and defense sector supply programs, contributing ¥403,638 thousand in net PP&E and ¥886,725 thousand in recorded goodwill.
The operational moat is established by a global duopoly in LEAP engine TiAl low-pressure turbine blade production, sharing the market with a single competitor ("Competitor A," holding ~60%). Ti-48Al-2Cr-2Nb intermetallic material presents high brittleness and micro-cracking risks during processing, requiring AeroEdge's proprietary toolpath CAM code, in-house end-mill designs, and Nadcap-certified Fluorescent Penetrant Inspection (FPI) and X-ray special processes. Because commercial aviation components undergo 10-plus-year validation phases and 20-to-30-year lifecycle support, switching costs are high under FAA and EASA regulatory process freezes.
To support an OEM backlog of 7,469 Airbus A320neo family, 5,404 Boeing 737 MAX family, and 931 COMAC C919 aircraft, AeroEdge committed ¥5,021,000 thousand in capital expenditures across two core initiatives through June 2027:
* Ashikaga Head Office 2nd Plant Expansion: ¥2,575,000 thousand committed (¥886,346 thousand paid by year-end FY2026; completion targeting April 2027).
* Ashikaga Head Office Plant A & B Line Extensions: ¥2,446,000 thousand committed (¥1,130,813 thousand paid; completion targeting June 2027).
These capital outlays support direct material supply. AeroEdge plans to bypass its single European raw alloy supplier bottleneck by commercializing in-house cast raw alloy blanks by June 2027, scaling toward a guaranteed market share into the upper 40% range starting January 2028.
HDIN Institutional Verdict
AeroEdge's high margins and 2.35x five-year cumulative CFO-to-net income coverage confirm structural earnings quality. However, an institutional risk screen reveals two major focal points:
1. Customer Monopsony Drag: Safran Aircraft Engines generated 97.0% of revenue in FY2026. Production rates remain directly tied to Airbus and Boeing narrowbody manufacturing runs. Any delivery delays, design freezes, or fleet groundings translate directly into revenue hits. The acquisition of Onoplant represents an initial effort to access domestic Japanese defense programs, but non-LEAP revenue remains modest at 3.0%.
2. Cash Flow and Re-leveraging Limits: Capital intensity led to negative Free Cash Flow of △¥257,713 thousand in FY2026 despite record operating cash generation. Total interest-bearing liabilities expanded to ¥5,479,040 thousand (44.1% of total assets), generating ¥74,874 thousand in annual interest expenses. While bank covenant limits require parent net assets to stay above ¥1.335 billion (providing an actual cushion of ¥3.51 billion), upcoming capital outlays totaling ¥3.00 billion through FY2027 will test liquidity if single-aisle aircraft delivery schedules face extended supply chain disruptions.
Presentation Download & Video Access
* Presentation Download: Click the PDF download link under 'Related Topics' to access the full institutional presentation of this report.
* Video Link: Click this link to watch the HDIN analyst briefing on YouTube.
About HDIN Research
HDIN Research is a premier global market intelligence and strategic advisory firm specializing in institutional-grade financial analysis, supply chain audits, and macroeconomic forecasting. Our dedicated sector analysts deliver actionable, data-driven insights tailored for private equity, hedge funds, and corporate strategy teams. Visit us at http://www.hdinresearch.com.
2026 AI Transparency Footer
This intelligence report was authored by HDIN Research analysts following a rigorous audit of official corporate filings. AI was utilized for massive-scale data synthesis and structural drafting, ensuring 100% inclusion of reported data points. All strategic insights, financial modeling, and final verdicts were verified by our editorial board to ensure professional accuracy and compliance with 2026 Google Search E-E-A-T standards.