Gujarat Mineral Development Corporation Ltd.: Multi-State Pivot to Odisha Accelerates as Tax Windfall Masks Core Operating Compression
Date : 2026-10-13
Reading : 87
HDIN Executive Takeaways
1. Reported FY26 PAT rose 45.29% to ₹990.81 Cr, but normalized net profit fell 17.39% to ₹563.30 Cr after stripping out a ₹522.65 Cr non-operating GST Input Tax Credit gain.
2. Free Cash Flow contracted to negative ₹290.31 Cr as capital expenditure surged 60.70% YoY to ₹1,034.03 Cr, driven by Odisha commercial coal and greenfield lignite development.
3. Balance sheet liquidity remains solid with ₹3,871.97 Cr in liquid assets against ₹308.55 Cr debt, though governance strains persist from an independent director deficit.
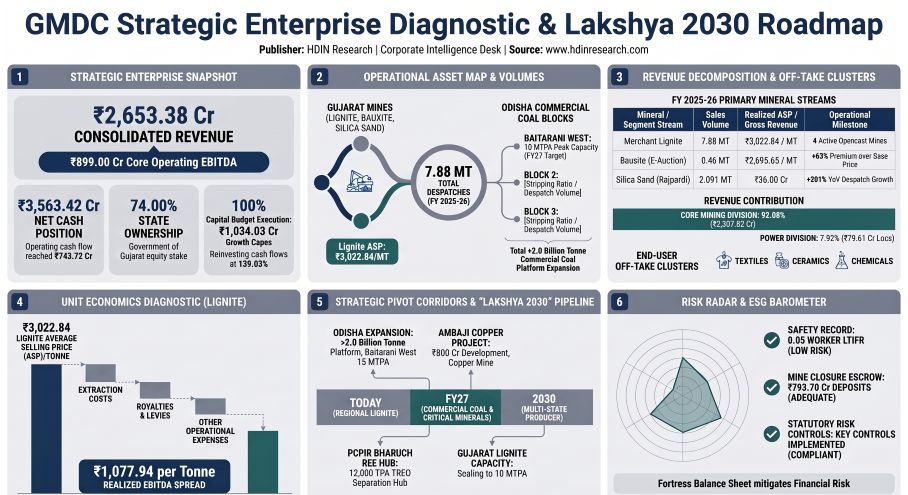
Figure GMDC Strategic Enterprise Diagnostic & Lakshya 2030 Roadmap
 Segmental Realities and Margin Compression
Gujarat Mineral Development Corporation Ltd. [NSE: GMDCLTD / BSE: 532114] posted total revenue from operations of ₹2,653.38 Cr in FY 2025-26, down 6.93% from ₹2,850.84 Cr in FY 2024-25. The top-line reduction stemmed from extended monsoon pit waterlogging at the Tadkeshwar mine and demand softness across the Morbi ceramic manufacturing cluster. Gross margins expanded 538 basis points to 45.17% on lower direct material excavation outlays, but operating EBITDA fell 9.38% YoY to ₹899.00 Cr, pulling the operating EBITDA margin down 92 basis points to 33.88%.
Reported Profit Before Tax (PBT) rose 46.15% to ₹1,301.88 Cr, and reported Profit After Tax (PAT) expanded 45.29% to ₹990.81 Cr. However, headline profitability was heavily distorted by a ₹522.65 Cr exceptional accounting gain. Following the rationalization of the Goods and Services Tax (GST) rate on lignite from 5% to 18% on September 22, 2025—which resolved historical inverted duty structures and removed the ₹400/MT Compensation Cess—the company recognized ₹492.63 Cr of previously expensed Input Tax Credits (ITC) alongside ₹30.02 Cr in litigated tax credits. Excluding this non-cash credit, normalized PBT contracted 12.52% YoY to ₹779.23 Cr, and normalized PAT decreased 17.39% to ₹563.30 Cr, yielding a normalized net profit margin of 21.23% (-269 basis points YoY).
Table Segment-Wise Operating and Capital Employed Analysis
The Mining Division generated ₹2,507.62 Cr in gross segment revenue (92.08% of total operating segment revenue), led by merchant lignite sales of ₹2,322.06 Cr on 7.88 Million Metric Tonnes (MT) of despatches. Lignite average selling price (ASP) contracted 4.93% YoY to ₹3,022.84/MT. Non-lignite minerals partially cushioned the variance: bauxite revenue expanded 18.07% to ₹123.65 Cr on 0.46 MT despatches as e-auctions yielded an average 63% premium over base price, while silica sand despatches surged 201.3% to 2.091 MT, generating ₹36.00 Cr and achieving operational breakeven.
The Power Division widened its segment operating loss from -₹21.94 Cr to -₹79.61 Cr despite revenue increasing 34.59% to ₹215.72 Cr. Generation resumed at the 250 MW Akrimota Thermal Power Station (LTPS), producing 268.63 Million Units (MU) post-overhaul, but the plant operated at an estimated Plant Load Factor (PLF) of 12.26%. This weak utilization resulted in ₹50.10 Cr of fixed operations and maintenance (O&M) overhead dragging the division, overshadowing the 205.9 MW Renewable Energy unit, which delivered 333.5 MU and ₹130.40 Cr in gross revenue at an 18.50% combined Capacity Utilization Factor.
Operating cash flow dropped 30.37% YoY to ₹743.72 Cr due to working capital expansion, including ₹843.54 Cr in statutory tax and regulatory balances. As capital expenditure expanded 60.70% to ₹1,034.03 Cr, Free Cash Flow (FCF) shifted from positive ₹424.71 Cr to negative ₹290.31 Cr.
Infrastructure Layout and Regional Moats
Gujarat Mineral Development Corporation Ltd. operates an extensive mineral and energy infrastructure footprint anchored across Western India and expanding into the Talcher and IB Valley coalfields in Odisha:
* Mata No Madh (Kutch, Gujarat): The enterprise's primary lignite source, despatching 3.27 MT in FY26. Infrastructure includes automated pit drainage and 3,00,197 kL in pit rainwater harvesting capacity.
* Bhavnagar (Bhavnagar, Gujarat): Despatched a record 2.55 MT of lignite. Serves as the operational hub for multimodal coastal logistics, which routed 39,000 MT via sea barge from Bhavnagar Port to Magdalla and Karanja. High-risk pit walls are monitored with real-time Slope Stability Radar.
* Umarsar & Tadkeshwar (Kutch & Surat, Gujarat): Umarsar delivered 1.52 MT from 12 MT reserves. Tadkeshwar fell to 0.54 MT after extensive monsoon waterlogging inundated active faces, prompting the installation of higher-capacity pumping circuits and a 2.0 MT covered pre-monsoon reserve stock program.
* Rajpardi & Panandhro (Bharuch & Kutch, Gujarat): Lignite extraction ceased at both assets due to seam exhaustion. Rajpardi transitioned to silica sand mining (2.091 MT despatches). Panandhro hosts a 5 MW solar facility (generating 6.4 MU) and a 45-acre soil reclamation site.
* Baitarani West, Burapahar & Kudanali Lubri (Angul & Sundargarh, Odisha): GMDC's commercial coal growth platform holding >2.0 billion tonnes of geological resources. Baitarani West (1.097 BT geological; 468 MT mineable) is engineered for 15 MTPA peak capacity to fuel 4,400 MW of power generation under agreement with Gujarat Urja Vikas Nigam Limited. The project has secured its approved Mining Plan, Environmental Clearance Terms of Reference, and a Wildlife Conservation Plan, with a Mine Developer and Operator appointed. Upfront commitment fees across Baitarani West and Burapahar stand at ₹474.45 Cr.
* Ambaji & Ambadungar Platforms (Banaskantha & Chhota Udepur, Gujarat): Strategic critical minerals pipeline. Ambaji holds ~11.3 MT of base metal resources (copper, lead, zinc) with a planned ₹800 Cr capex budget for a 0.5 MTPA underground mine and 500 KTPA beneficiation plant. Ambadungar encompasses 1.29 MT in-situ Total Rare Earth Oxides (TREO), paired with a planned 12,000 TPA TREO separation facility in the Petroleum, Chemicals and Petrochemicals Investment Region (PCPIR) at Bharuch.
HDIN Institutional Verdict
Gujarat Mineral Development Corporation Ltd. holds a virtual 100% merchant lignite monopoly in Gujarat, underpinned by pithead haulage economics that provide a ₹144/tonne lead-distance freight advantage over long-haul domestic coal and imported fuels. This operational moat is reinforced by a balance sheet holding ₹3,871.97 Cr in liquid financial assets and minimal debt of ₹308.55 Cr (0.04x Debt-to-Equity).
However, our forensic audit identifies three core institutional risks:
1. Distortion of Operating Earnings Quality: Headline net margin expansion to 37.34% reflects an accounting windfall rather than operating leverage. With Other Income (₹423.88 Cr) representing 54.40% of pre-exceptional PBT, core earnings rely heavily on treasury yields, interest on restricted mine closure escrow accounts (₹73.91 Cr), and liability write-backs (₹65.26 Cr).
2. Capital Work-in-Progress and Asset Impairments: Although GMDC capitalized ₹549.25 Cr from CWIP into Property, Plant & Equipment following the physical overhaul of the Akrimota power station, Intangible Assets Under Development surged 279.8% to ₹1,032.55 Cr as management began capitalizing land and R&R expenses. Retaining the ₹396.59 Cr impairment provision on the Akrimota thermal plant is prudent given its low 12.26% PLF, which will continue to pressure return on equity until revised tariffs are approved.
3. Governance Frictions: The Government of Gujarat holds a 74.00% equity stake, and executive compensation remains decoupled from shareholder performance metrics, with zero variable incentives for Key Managerial Personnel. The Board also breached SEBI LODR Regulation 17(1)(b) when the ratio of independent directors dropped to 42.86%, raising compliance issues.
GMDC is executing a high-stakes transition from a cash-generative regional lignite supplier to a diversified multi-state miner. While its liquid balance sheet provides funding support, the negative Free Cash Flow profile confirms that returns will depend directly on managing rehabilitation, resettlement, and statutory permitting milestones at its Odisha coal assets.
Presentation Download & Video Access:
- Presentation Download: Click the PDF download link under 'Related Topics' to access the full institutional presentation of this report.
- Video Link: Click this link to watch the HDIN analyst briefing on YouTube.
About HDIN Research:
HDIN Research is a premier global market intelligence and strategic advisory firm specializing in institutional-grade financial analysis, supply chain audits, and macroeconomic forecasting. Our dedicated sector analysts deliver actionable, data-driven insights tailored for private equity, hedge funds, and corporate strategy teams. Visit us at http://www.hdinresearch.com.
2026 AI Transparency Footer:
"This intelligence report was authored by HDIN Research analysts following a rigorous audit of official corporate filings. AI was utilized for massive-scale data synthesis and structural drafting, ensuring 100% inclusion of reported data points. All strategic insights, financial modeling, and final verdicts were verified by our editorial board to ensure professional accuracy and compliance with 2026 Google Search E-E-A-T standards."
1. Reported FY26 PAT rose 45.29% to ₹990.81 Cr, but normalized net profit fell 17.39% to ₹563.30 Cr after stripping out a ₹522.65 Cr non-operating GST Input Tax Credit gain.
2. Free Cash Flow contracted to negative ₹290.31 Cr as capital expenditure surged 60.70% YoY to ₹1,034.03 Cr, driven by Odisha commercial coal and greenfield lignite development.
3. Balance sheet liquidity remains solid with ₹3,871.97 Cr in liquid assets against ₹308.55 Cr debt, though governance strains persist from an independent director deficit.
Figure GMDC Strategic Enterprise Diagnostic & Lakshya 2030 Roadmap
Segmental Realities and Margin CompressionGujarat Mineral Development Corporation Ltd. [NSE: GMDCLTD / BSE: 532114] posted total revenue from operations of ₹2,653.38 Cr in FY 2025-26, down 6.93% from ₹2,850.84 Cr in FY 2024-25. The top-line reduction stemmed from extended monsoon pit waterlogging at the Tadkeshwar mine and demand softness across the Morbi ceramic manufacturing cluster. Gross margins expanded 538 basis points to 45.17% on lower direct material excavation outlays, but operating EBITDA fell 9.38% YoY to ₹899.00 Cr, pulling the operating EBITDA margin down 92 basis points to 33.88%.
Reported Profit Before Tax (PBT) rose 46.15% to ₹1,301.88 Cr, and reported Profit After Tax (PAT) expanded 45.29% to ₹990.81 Cr. However, headline profitability was heavily distorted by a ₹522.65 Cr exceptional accounting gain. Following the rationalization of the Goods and Services Tax (GST) rate on lignite from 5% to 18% on September 22, 2025—which resolved historical inverted duty structures and removed the ₹400/MT Compensation Cess—the company recognized ₹492.63 Cr of previously expensed Input Tax Credits (ITC) alongside ₹30.02 Cr in litigated tax credits. Excluding this non-cash credit, normalized PBT contracted 12.52% YoY to ₹779.23 Cr, and normalized PAT decreased 17.39% to ₹563.30 Cr, yielding a normalized net profit margin of 21.23% (-269 basis points YoY).
Table Segment-Wise Operating and Capital Employed Analysis
| Operating Segment | Gross Revenue (₹ Cr) | External Revenue (₹ Cr) | Inter-Segment (₹ Cr) | Segment EBIT (₹ Cr) | Assets (₹ Cr) | Liabilities (₹ Cr) | Capital Employed (₹ Cr) |
| Mining Operations | ₹2,507.62 | ₹2,437.66 | ₹69.96 | ₹607.50 | ₹4,028.18 | ₹1,048.91 | ₹2,979.27 |
| Power Division | ₹215.72 | ₹215.72 | ₹0.00 | -₹79.61 | ₹421.15 | ₹138.45 | ₹282.70 |
| Unallocated / Corporate | ₹423.88 | ₹0.00 | ₹0.00 | ₹251.34 | ₹3,422.36 | ₹253.11 | ₹3,169.25 |
| Total Enterprise | ₹3,147.22 | ₹2,653.38 | ₹69.96 | ₹779.23 | ₹7,871.69 | ₹1,440.47 | ₹6,431.22 |
The Mining Division generated ₹2,507.62 Cr in gross segment revenue (92.08% of total operating segment revenue), led by merchant lignite sales of ₹2,322.06 Cr on 7.88 Million Metric Tonnes (MT) of despatches. Lignite average selling price (ASP) contracted 4.93% YoY to ₹3,022.84/MT. Non-lignite minerals partially cushioned the variance: bauxite revenue expanded 18.07% to ₹123.65 Cr on 0.46 MT despatches as e-auctions yielded an average 63% premium over base price, while silica sand despatches surged 201.3% to 2.091 MT, generating ₹36.00 Cr and achieving operational breakeven.
The Power Division widened its segment operating loss from -₹21.94 Cr to -₹79.61 Cr despite revenue increasing 34.59% to ₹215.72 Cr. Generation resumed at the 250 MW Akrimota Thermal Power Station (LTPS), producing 268.63 Million Units (MU) post-overhaul, but the plant operated at an estimated Plant Load Factor (PLF) of 12.26%. This weak utilization resulted in ₹50.10 Cr of fixed operations and maintenance (O&M) overhead dragging the division, overshadowing the 205.9 MW Renewable Energy unit, which delivered 333.5 MU and ₹130.40 Cr in gross revenue at an 18.50% combined Capacity Utilization Factor.
Operating cash flow dropped 30.37% YoY to ₹743.72 Cr due to working capital expansion, including ₹843.54 Cr in statutory tax and regulatory balances. As capital expenditure expanded 60.70% to ₹1,034.03 Cr, Free Cash Flow (FCF) shifted from positive ₹424.71 Cr to negative ₹290.31 Cr.
Infrastructure Layout and Regional Moats
Gujarat Mineral Development Corporation Ltd. operates an extensive mineral and energy infrastructure footprint anchored across Western India and expanding into the Talcher and IB Valley coalfields in Odisha:
* Mata No Madh (Kutch, Gujarat): The enterprise's primary lignite source, despatching 3.27 MT in FY26. Infrastructure includes automated pit drainage and 3,00,197 kL in pit rainwater harvesting capacity.
* Bhavnagar (Bhavnagar, Gujarat): Despatched a record 2.55 MT of lignite. Serves as the operational hub for multimodal coastal logistics, which routed 39,000 MT via sea barge from Bhavnagar Port to Magdalla and Karanja. High-risk pit walls are monitored with real-time Slope Stability Radar.
* Umarsar & Tadkeshwar (Kutch & Surat, Gujarat): Umarsar delivered 1.52 MT from 12 MT reserves. Tadkeshwar fell to 0.54 MT after extensive monsoon waterlogging inundated active faces, prompting the installation of higher-capacity pumping circuits and a 2.0 MT covered pre-monsoon reserve stock program.
* Rajpardi & Panandhro (Bharuch & Kutch, Gujarat): Lignite extraction ceased at both assets due to seam exhaustion. Rajpardi transitioned to silica sand mining (2.091 MT despatches). Panandhro hosts a 5 MW solar facility (generating 6.4 MU) and a 45-acre soil reclamation site.
* Baitarani West, Burapahar & Kudanali Lubri (Angul & Sundargarh, Odisha): GMDC's commercial coal growth platform holding >2.0 billion tonnes of geological resources. Baitarani West (1.097 BT geological; 468 MT mineable) is engineered for 15 MTPA peak capacity to fuel 4,400 MW of power generation under agreement with Gujarat Urja Vikas Nigam Limited. The project has secured its approved Mining Plan, Environmental Clearance Terms of Reference, and a Wildlife Conservation Plan, with a Mine Developer and Operator appointed. Upfront commitment fees across Baitarani West and Burapahar stand at ₹474.45 Cr.
* Ambaji & Ambadungar Platforms (Banaskantha & Chhota Udepur, Gujarat): Strategic critical minerals pipeline. Ambaji holds ~11.3 MT of base metal resources (copper, lead, zinc) with a planned ₹800 Cr capex budget for a 0.5 MTPA underground mine and 500 KTPA beneficiation plant. Ambadungar encompasses 1.29 MT in-situ Total Rare Earth Oxides (TREO), paired with a planned 12,000 TPA TREO separation facility in the Petroleum, Chemicals and Petrochemicals Investment Region (PCPIR) at Bharuch.
HDIN Institutional Verdict
Gujarat Mineral Development Corporation Ltd. holds a virtual 100% merchant lignite monopoly in Gujarat, underpinned by pithead haulage economics that provide a ₹144/tonne lead-distance freight advantage over long-haul domestic coal and imported fuels. This operational moat is reinforced by a balance sheet holding ₹3,871.97 Cr in liquid financial assets and minimal debt of ₹308.55 Cr (0.04x Debt-to-Equity).
However, our forensic audit identifies three core institutional risks:
1. Distortion of Operating Earnings Quality: Headline net margin expansion to 37.34% reflects an accounting windfall rather than operating leverage. With Other Income (₹423.88 Cr) representing 54.40% of pre-exceptional PBT, core earnings rely heavily on treasury yields, interest on restricted mine closure escrow accounts (₹73.91 Cr), and liability write-backs (₹65.26 Cr).
2. Capital Work-in-Progress and Asset Impairments: Although GMDC capitalized ₹549.25 Cr from CWIP into Property, Plant & Equipment following the physical overhaul of the Akrimota power station, Intangible Assets Under Development surged 279.8% to ₹1,032.55 Cr as management began capitalizing land and R&R expenses. Retaining the ₹396.59 Cr impairment provision on the Akrimota thermal plant is prudent given its low 12.26% PLF, which will continue to pressure return on equity until revised tariffs are approved.
3. Governance Frictions: The Government of Gujarat holds a 74.00% equity stake, and executive compensation remains decoupled from shareholder performance metrics, with zero variable incentives for Key Managerial Personnel. The Board also breached SEBI LODR Regulation 17(1)(b) when the ratio of independent directors dropped to 42.86%, raising compliance issues.
GMDC is executing a high-stakes transition from a cash-generative regional lignite supplier to a diversified multi-state miner. While its liquid balance sheet provides funding support, the negative Free Cash Flow profile confirms that returns will depend directly on managing rehabilitation, resettlement, and statutory permitting milestones at its Odisha coal assets.
Presentation Download & Video Access:
- Presentation Download: Click the PDF download link under 'Related Topics' to access the full institutional presentation of this report.
- Video Link: Click this link to watch the HDIN analyst briefing on YouTube.
About HDIN Research:
HDIN Research is a premier global market intelligence and strategic advisory firm specializing in institutional-grade financial analysis, supply chain audits, and macroeconomic forecasting. Our dedicated sector analysts deliver actionable, data-driven insights tailored for private equity, hedge funds, and corporate strategy teams. Visit us at http://www.hdinresearch.com.
2026 AI Transparency Footer:
"This intelligence report was authored by HDIN Research analysts following a rigorous audit of official corporate filings. AI was utilized for massive-scale data synthesis and structural drafting, ensuring 100% inclusion of reported data points. All strategic insights, financial modeling, and final verdicts were verified by our editorial board to ensure professional accuracy and compliance with 2026 Google Search E-E-A-T standards."