IperionX Limited: Commercial Scale-Up Near Halifax County Accelerates FY 2026 Cash Burn to $63.52M as Zero P&L Revenue Deepens Capital Market Dependency
Date : 2026-10-09
Reading : 162
HDIN Executive Takeaways
1. IperionX Limited reported $0.00 in commercial revenue for FY 2026, while net losses expanded 88.9% to $66.77M and annual operational cash consumption escalated to $63.52M ($5.29M per month).
2. Continuous 24/7 manufacturing commenced at the 97,800 square foot Virginia campus at an optimized nameplate capacity of ~200 metric tons per annum (tpa), yet legal title to $12.70M of core production assets remains vested with the U.S. Government through January 30, 2027.
3. A post-balance-sheet equity placement generated $47.0M net, extending cash runway to approximately 16.1 months, but leaves a capital deficit exceeding $270M against long-term Virginia expansion ($96.3M) and Tennessee Titan Phase 1 development ($228.1M).
Figure IPERIONX LIMITED (2026 FORM 20-F) STRATEGIC & OPERATIONAL DIAGNOSTIC
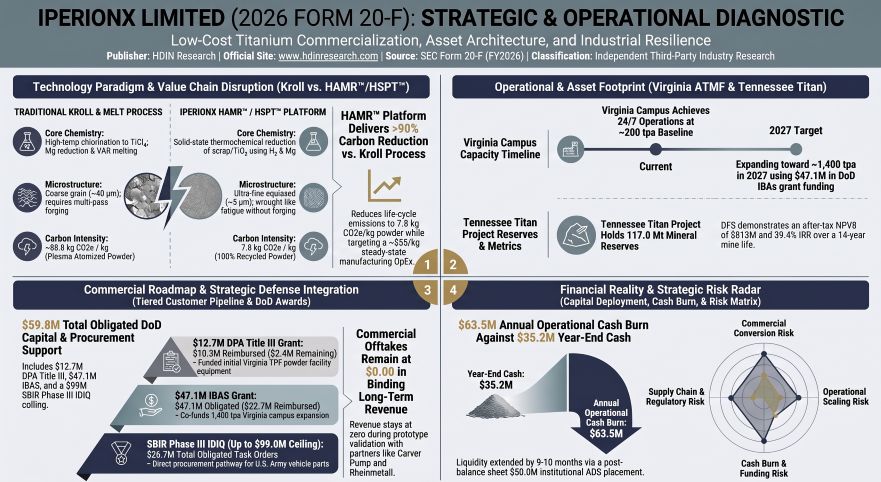
Consolidated Financial Health Audit and Balance Sheet Diagnostics
IperionX Limited [NASDAQ: IPX / ASX: IPX] filed its FY 2026 Form 20-F Annual Report for the fiscal period ended June 30, 2026, confirming an operational pivot from pilot technology validation to 24/7 commercial manufacturing. The transition triggered an escalation in operational cash burn, overhead outlays, and trade liabilities. All financial statements are prepared under International Financial Reporting Standards (IFRS) as issued by the International Accounting Standards Board (IASB) in U.S. Dollars (USD).
Table Consolidated Financial Performance, Cash Burn and Balance-Sheet Analysis (FY2024–FY2026)
Operating cash outflows expanded 106.2% YoY to $44.95M ($11.24M per quarter), while capital expenditures contributed $18.56M in investing outflows, establishing a total cash drain of $63.52M. Total cash additions to Property, Plant, and Equipment (PPE) were $17.78M, with $4.57M in non-cash payables and accruals, bringing gross PPE additions to $22.80M.
As of the June 30, 2026 balance date, cash reserves of $35.24M provided an implied operational runway of 6.7 months under the baseline burn rate of $5.29M per month ($15.88M per quarter). Under an accelerated scale-up scenario consuming $23.80M per quarter (+50% burn rate), liquidity would have expired within 4.4 months (by November 2026). On July 7, 2026, IperionX completed an institutional placement of 2,275,000 American Depositary Shares (ADSs) at a ratio of 1 ADS to 10 ordinary shares, generating $50.0M gross ($47.0M net). This equity injection established a pro forma cash position of $85.24M, extending the baseline runway by 9.4 months to approximately 16.1 months (securing operations into Q3/Q4 2027). The company also holds $37.10M in remaining reimbursable grant capital from the U.S. Department of War (DoW), restricted strictly to eligible project outlays.
Working capital mechanics reflect structural shifts:
* Inventory Capitalization: Raw material stock was capitalized for the first time during H1 FY 2026 (the period ended December 31, 2025). The $3.91M balance consists entirely of raw titanium scrap, which includes 290 metric tons donated by the U.S. Government under the Industrial Base Analysis and Sustainment (IBAS) program. This grant was recognized at a fair value of $2.76M, with $0.99M credited to profit and loss in FY 2026 and $1.77M carried as unamortized deferred income. Work-in-progress and finished goods inventories remained immaterial due to customer delivery cycles for prototype qualifications.
* Receivables Quality: Accounts receivable rose 298.7% to $3.28M, of which 96.8% ($3.18M) represents reimbursable invoices submitted to the U.S. Government under Defense Production Act (DPA) Title III and IBAS contracts. The filing confirmed zero commercial delinquent debt and zero past-due balances.
* Payables and Contractual Commitments: Trade payables advanced 39.5% to $10.45M under standard 60-day terms. Undiscounted contractual lease commitments total $5.23M ($0.74M in FY 2027, $0.70M in FY 2028, $0.70M in FY 2029, $0.69M in FY 2030, $0.64M in FY 2031, and $1.76M thereafter, with imputed interest of $1.26M). A non-current deferred consideration liability of $333,000 remains payable to Blacksand Technology, LLC ($700,000 in FY 2025), following the initial equity settlement of 3,006,163 ordinary shares ($2.0M fair value) in FY 2024.
* Overhead Expansion: Corporate and administrative expenses increased 142.5% YoY to $25.92M, which, when combined with $9.17M in non-cash share-based payments, equaled total expensed R&D ($25.19M).
The capital structure comprises 339,384,066 fully paid ordinary shares on issue as of June 30, 2026 (94.95% of fully diluted capital), and 18,031,866 unlisted dilutive securities (5.05%). The dilutive pool includes:
* Unlisted Options: 6,872,710 options with a weighted-average exercise price of A$13.47 across seven tranches:
* Series 1: 106,093 options at A$0.87 (expiring December 5, 2026).
* Series 2: 235,000 options at A$10.00 (expiring April 1, 2027).
* Series 3: 1,305,000 options at A$8.00 (expiring June 30, 2027).
* Series 4: 1,374,746 options at A$5.00 (expiring April 10, 2029).
* Series 5: 511,972 options at A$11.00 (expiring April 2, 2030).
* Series 6: 1,566,690 options at A$18.00 (expiring April 2, 2031; 4-year service condition).
* Series 7: 1,773,209 options at A$22.00 (expiring April 2, 2031; 4-year service condition).
* Performance Rights: 7,048,486 units across market and non-market hurdles:
* A$4.00 30-day VWAP hurdle: 2,885,000 units (2.44M expiring December 2028; 0.445M expiring December 2027).
* A$18.00 30-day VWAP hurdle: 660,077 units with a 4-year service lock (expiring April 2, 2031).
* A$6.00, A$7.00, and A$8.00 VWAP hurdles: 3,473,409 units total (1.157M each, expiring April 10, 2031).
* Non-market operational milestones: 30,000 units (expiring December 31, 2026).
* Restricted Stock Units (RSUs): 4,110,670 units subject to 3-year service vesting cliffs.
* Performance Shares: Historical Class A (19,800,000) and Class B (19,800,000) Performance Shares lapsed unexercised following the passage of feasibility study and production deadlines, converting into 30 ordinary shares per class in FY 2025 and FY 2026.
Including the July 7, 2026 placement of 22,750,000 ordinary share equivalents, pro forma fully diluted equity stands at 380,165,932 shares. Substantial shareholders include DITM Holdings Pty Ltd (controlled by Executive Chairman Todd Hannigan) with 26,608,334 shares (7.8%), FMR LLC (Fidelity) with 26,097,578 shares (7.7%), and State Street Corporation with 22,764,708 shares (6.7%). Officers and directors hold an aggregate of 53,090,459 shares (15.6%), supporting a public free float of 62.2%.
Asset Architecture, Supply Chain Logistics, and Defense Procurement Integration
IperionX operates an integrated domestic value chain that bridges scrap refining, powder metallurgy, and mineral separation across three key states.
The downstream processing and manufacturing hub is situated in South Boston, Halifax County, Virginia, comprising 97,800 square feet across the Titanium Production Facility (TPF) and the Advanced Manufacturing Center (AMC). All primary systems achieved commissioning in September 2025, operating 24/7. Operating modifications increased nameplate capacity from 125 tpa to ~200 tpa (~16.7 metric tons per month) with zero incremental capital expenditure, delivering toward a steady-state manufacturing cost benchmark of ~$55/kg. The company procures 100% renewable grid power, achieving zero Scope 2 market-based emissions, with an independently verified life-cycle carbon intensity of 7.8 kg CO₂e/kg of powder (representing a 91.2% reduction compared to standard plasma atomization at 88.8 kg CO₂e/kg).
The facility deploys Hydrogen Assisted Metallothermic Reduction (HAMR™) solid-state reduction, which utilizes hydrogen to lower the thermodynamic activity of oxygen in titanium, allowing magnesium reduction to extract oxygen from scrap without carbothermic chlorination, titanium tetrachloride gas handling, or multi-pass Vacuum Arc Remelting (VAR). In FY 2026 commercial operations, HAMR™ refined 100% Ti-6Al-4V revert scrap containing 3.42% oxygen down to <0.07% oxygen, outperforming the ASTM Grade 5 upper specification limit of 0.20%. For spherical powders, the Granulation-Sintering-Deoxygenation (GSD™) process increased usable fine-particle yield by up to 50% relative to atomization techniques.
Downstream compaction is anchored by a 300-ton, 6-axis SACMI powder metallurgy press commissioned in May 2026. Operating at speeds up to 24 cycles per minute, the press possesses a run-rate capacity of ~11 million single-cavity components per year prior to sintering. To alleviate downstream thermal cycle bottlenecks, two Hydrogen Sintering and Phase Transformation (HSPT™) furnaces were acquired in FY 2026 (the first delivered in the June 2026 quarter). HSPT™ achieves reversible hydrogen phase transformations ($\alpha \leftrightarrow \beta$) to refine grain size from ~40 µm down to ~5 µm, delivering wrought-like fatigue endurance without forging presses. Process research on mill products and alloy development continues at the 15,000 square foot Industrial Pilot Facility (IPF) in Salt Lake City, Utah.
The upstream segment consists of the Titan Critical Minerals Project across Benton and Carroll Counties, Tennessee, spanning >10,000 acres (>1,500 acres owned in fee simple, ~1,200 acres under lease, and ~7,500 acres held under option agreements subject to $75/acre/year maintenance or a 5% net revenue royalty). The Definitive Feasibility Study (DFS) was completed on June 4, 2026, over a 3,317-acre study area (13.4 km²), co-funded by $5.0M in expenditures ($4.13M reimbursed via DoW IBAS grants).
Table Titan Mineral Resource Estimate — June 30, 2026
Table Titan Mineral Reserve Estimate — June 30, 2026
Proven reserves account for 79.7% (93.31 Mt) of total reserves. The DFS outlines a 14-year life-of-mine (LOM). Phase 1 (Years 1–4) processes 3.5 Mtpa run-of-mine (ROM) ore (~400 tons per hour rougher spiral feed), expanding in Phase 2 (Years 5–14) to 10.0 Mtpa ROM (~1,200 tons per hour feed). Total LOM production yields ~2.5 Mt of mineral products: 1.37 Mt ilmenite, 0.29 Mt rutile, 0.77 Mt zircon concentrate, and 0.06 Mt Heavy Rare Earth Concentrate (HREC rich in dysprosium, terbium, and yttrium).
Modeled project metrics (unlevered real 2026 USD) demonstrate an after-tax NPV₈ of $813M, an after-tax IRR of 39.4%, a payback period of 3.63 years, cumulative LOM after-tax free cash flow of $1.93B, and cumulative EBITDA of $2.80B. Capital requirements total $381.3M ($228.1M for Phase 1 Initial Capex, comprising $201.9M direct/indirect, $5.6M owner's costs, and $20.6M contingency; $153.2M for Phase 2, comprising $137.5M direct/indirect, $1.6M owner's costs, and $14.0M contingency), alongside $23.3M in sustaining capital.
DFS commodity pricing models assume:
* Rutile Final Product: $1,471/metric ton (reserve cut-off: $1,425/t); metallurgical recovery of 64.3% to a 91.1% TiO₂ grade.
* Ilmenite Final Product: $353/metric ton (reserve cut-off: $340/t); metallurgical recovery of 80.7% to a 62.5% TiO₂ grade.
* Zircon Concentrate: $829/metric ton (reserve cut-off: $912/t); metallurgical recovery of 91.8% to a 34.4% ZrO₂ grade.
* Heavy Rare Earth Concentrate: $41,759/metric ton (reserve cut-off: $10,678/t), reflecting a 50% payability factor applied to the Total Rare Earth Oxide (TREO) basket; metallurgical recovery of 91.4% to a 61.4% TREO grade.
On June 15, 2026, IperionX contracted to acquire adjacent mineral, property, and industrial infrastructure assets from Covia Solutions LLC for $3.0M cash (closed July 1, 2026), absorbing pre-stripped Lower McNairy ore, stockpiles, a rail spur connected to the CSX Transportation Memphis subdivision, and historical land reclamation obligations. An integrated Atlas-Titan economic assessment is targeted for completion by end-CY 2026. Permitting is anchored by a 5-year Tennessee Department of Environment and Conservation (TDEC) Surface Mining Permit (OM-70711-01) and NPDES Water Discharge Permit (TN0070711). Transport logistics assume site hauling at $1.00/ROM metric ton, with freight costs budgeted at $11.85/t for ilmenite/rutile, $65.00/t for zircon concentrate, and $555.00/t for HREC. Barging access is available via the Tennessee River 15 miles (24 km) away. Mineral upgrading will leverage Green Rutile™ (substituting coal reduction kilns to upgrade ilmenite) and Alkaline Roasting and Hydrolysis (ARH™) to generate +99% TiO₂ feedstock.
Table Government Programs, Defense Contracts and Strategic Supply-Chain Positioning
Commercial offtake remains centered on testing and prototype conversion. Non-binding agreements remain active with Ford Motor Company for closed-loop automotive scrap recycling, as well as with Lockheed Martin, GKN Aerospace, and Aperam across Europe and the Asia-Pacific region. All international market engagements, including supply chain touchpoints in Taiwan, Province of China, comply with standard trade regulatory frameworks.
HDIN Institutional Verdict: Capital Runway Realities and Structural Execution Friction
IperionX presents an operational divergence between plant commissioning milestones and cash burn acceleration. While the company achieved 24/7 continuous operations at its Virginia campus and reached a 200 tpa powder run rate, commercial revenues in profit and loss remain at $0.00. The commercial model is supported by prototype purchase orders ($100k Carver Pump, $300k American Rheinmetall) and military development frameworks ($26.7M in obligated SBIR Phase III task orders under a $99.0M ceiling). However, zero firm, binding take-or-pay volume contracts exist to establish a baseline cash inflow floor.
The corporate strategy involves dual-track friction:
1. Downstream Processing: The scrap-to-component circular platform requires modest capital intensity, benefits from $59.80M in federal award co-funding ($12.70M DPA Title III and $47.10M IBAS), and accesses 290 metric tons of zero-cost government feedstock. This division offers the fastest pathway to operating cash generation.
2. Upstream Mineral Extraction: The Titan Critical Minerals Project requires $228.1M in initial Phase 1 capital ($381.3M LOM), specialized environmental permits for mineral processing, and radioactive material licenses (NORM) for monazite handling. Management has withheld a Final Investment Decision (FID) on Titan, stating development remains contingent on securing external non-recourse project finance, strategic equity partners, or EXIM Bank export facilities.
A primary structural vulnerability is the asset title retention under the DPA Title III agreement: legal title to $12.70M in primary powder refining equipment at the Virginia TPF vests with the U.S. Government through January 30, 2027. If the Department of War declines title conveyance, IperionX faces operational disruptions or mandatory repurchase outlays. Additionally, government grant execution imposes working capital friction, as all qualifying expenditures must be pre-funded from cash reserves prior to reimbursement.
Corporate governance metrics reflect structured oversight:
* Board Independence: The Board maintains a 75.0% independence ratio (6 of 8 directors), with 37.5% female representation. Michael J. Loparco joined as an independent director on August 3, 2026. The Audit Committee is 100% independent and chaired by Tony Tripeny (former CFO of Corning Incorporated and SEC Financial Expert). The Lead Independent Director is Lorraine M. Martin (former EVP and General Manager of Lockheed Martin's F-35 program), supported by director Beverly M. Wyse (30-year Boeing executive and former VP/GM of Boeing South Carolina).
* Executive Compensation Alignment: In FY 2026, CEO Anastasios Arima received $562,500 base salary, $440,000 cash bonus, and $1,813,143 in share expense ($2,824,655 total comp). Executive Chairman Todd Hannigan received $393,500 base salary and $1,220,955 in share expense ($1,634,830 total comp), voluntarily waiving his cash bonus. Total compensation for other key executives was: Toby Symonds (President/CSO) $2,528,223 ($534,500 base, $418,000 bonus, $1,544,196 equity); W. Scott Sparks (COO) $1,207,144 ($320,000 base, $180,000 bonus, $688,004 equity); Dominic Allen (CCO) $1,036,289 ($320,000 base, $180,000 bonus, $536,289 equity); and Marcela Castro (CFO) $791,000 ($307,500 base, $165,000 bonus, $287,898 equity). Total executive cash bonuses were $1.383M, reflecting a 78.5% strategic scorecard achievement (114% target payout). Long-term incentives (LTI) carry an A$18.00 30-day VWAP hurdle (+166% premium over the A$6.76 base price) with a mandatory 4-year service lock and a 1-year holding requirement to April 2, 2031.
* Related Parties: Clean execution with zero insider loans; related-party payments were limited to $70,660 paid to Performance Industries, Inc. (associated with COO Scott Sparks) for construction engineering, alongside pass-through director fee entities (Arete Innovative Resources LLC for Melissa Waller; Westoz Services Trust for Dominic Allen).
* Redomiciliation: On August 3, 2026, the company proposed a corporate redomiciliation from Australia to the United States (IperionX Inc., a Texas corporation), aligning corporate registration with U.S. defense procurement frameworks.
Until commercial revenues are recognized in the income statement and binding multi-year take-or-pay offtake agreements materialize, IperionX remains dependent on public equity markets to absorb operational cash consumption and meet required capital-matching obligations.
Presentation Download & Video Access:
- Presentation Download: Click the PDF download link under 'Related Topics' to access the full institutional presentation of this report.
- Video Link: Click this link to watch the HDIN analyst briefing on YouTube.
About HDIN Research:
HDIN Research is a premier global market intelligence and strategic advisory firm specializing in institutional-grade financial analysis, supply chain audits, and macroeconomic forecasting. Our dedicated sector analysts deliver actionable, data-driven insights tailored for private equity, hedge funds, and corporate strategy teams. Visit us at http://www.hdinresearch.com.
2026 AI Transparency Footer:
"This intelligence report was authored by HDIN Research analysts following a rigorous audit of official corporate filings. AI was utilized for massive-scale data synthesis and structural drafting, ensuring 100% inclusion of reported data points. All strategic insights, financial modeling, and final verdicts were verified by our editorial board to ensure professional accuracy and compliance with 2026 Google Search E-E-A-T standards."
1. IperionX Limited reported $0.00 in commercial revenue for FY 2026, while net losses expanded 88.9% to $66.77M and annual operational cash consumption escalated to $63.52M ($5.29M per month).
2. Continuous 24/7 manufacturing commenced at the 97,800 square foot Virginia campus at an optimized nameplate capacity of ~200 metric tons per annum (tpa), yet legal title to $12.70M of core production assets remains vested with the U.S. Government through January 30, 2027.
3. A post-balance-sheet equity placement generated $47.0M net, extending cash runway to approximately 16.1 months, but leaves a capital deficit exceeding $270M against long-term Virginia expansion ($96.3M) and Tennessee Titan Phase 1 development ($228.1M).
Figure IPERIONX LIMITED (2026 FORM 20-F) STRATEGIC & OPERATIONAL DIAGNOSTIC
Consolidated Financial Health Audit and Balance Sheet Diagnostics
IperionX Limited [NASDAQ: IPX / ASX: IPX] filed its FY 2026 Form 20-F Annual Report for the fiscal period ended June 30, 2026, confirming an operational pivot from pilot technology validation to 24/7 commercial manufacturing. The transition triggered an escalation in operational cash burn, overhead outlays, and trade liabilities. All financial statements are prepared under International Financial Reporting Standards (IFRS) as issued by the International Accounting Standards Board (IASB) in U.S. Dollars (USD).
Table Consolidated Financial Performance, Cash Burn and Balance-Sheet Analysis (FY2024–FY2026)
| Consolidated Financial Metric | FY 2024 | FY 2025 | FY 2026 | YoY Trend (FY 2025–2026) | Forensic Audit Classification |
| Revenue from Contracts | $0.00 | $0.00 | $0.00 | Flat (0.0%) | Zero commercial revenue recognized; output absorbed by customer sampling and prototyping. |
| Net Loss After Tax | ($21.84M) | ($35.35M) | ($66.77M) | +88.9% | Deficit widened by 24/7 plant operating schedules and corporate expansion. |
| Operating Cash Flow (OCF) | ($18.61M) | ($21.80M) | ($44.95M) | +106.2% | Operating cash burn accelerated by supplier disbursements and manufacturing overhead. |
| Investing Cash Flow (ICF) | ($6.53M) | ($24.28M) | ($18.56M) | -23.5% | Capital additions moderated following initial Virginia commissioning. |
| Total Operational Cash Burn (OCF + ICF) | ($25.14M) | ($46.08M) | ($63.52M) | +37.9% | Cash consumption reached
5.29M/month). |
| Cash & Cash Equivalents | $33.16M | $54.81M | $35.24M | -35.7% | Cash balance fell $19.57M despite $43.18M in net equity financing during the period. |
| Short-Term Liquid Investments | $0.00 | $0.00 | $0.00 | Flat (0.0%) | Secondary liquid reserves and marketable securities do not exist on the balance sheet. |
| Expensed R&D Expenditures | $8.71M | $12.75M | $25.19M | +97.6% | Driven by Utah IPF and Virginia operations, GenX™ R&D, and alloy trials. |
| Capitalized Development Costs | $0.00 | $0.00 | $0.00 | Flat (0.0%) | 100% of internal technology development is expensed as incurred under IAS 38. |
| Property, Plant & Equipment (Net) | $7.77M | $25.20M | $41.19M | +63.5% | Net asset base expanded via SACMI press and HSPT™ sintering furnace additions. |
| Exploration & Evaluation Assets | $6.11M | $6.51M | $7.77M | +19.3% | Land option and acquisition expenditures for the Titan Critical Minerals Project. |
| Intangible Assets (Net) | $0.00 | $13.55M | $12.27M | -9.5% | Acquired Blacksand IP amortized over 10.7-year weighted remaining life ($1.30M in FY 2026). |
| Total Inventory Balance | $0.00 | $0.00 | $3.91M | N/A | Inventory capitalized for the first time in H1 FY 2026 upon reaching operational milestones. |
| Trade & Other Receivables | $1.21M | $0.82M | $3.28M | +298.7% | 96.8% ($3.18M) represents pending U.S. Government cost-reimbursement claims. |
| Trade & Other Payables | $5.21M | $7.49M | $10.45M | +39.5% | Unsecured trade credit utilization operating under standard 60-day settlement terms. |
| Lease Liabilities (Current & Non-Current) | $1.47M | $3.92M | $3.97M | +1.3% | Present value of facility and equipment leases ($0.44M current, $3.52M non-current). |
| Funded Bank Debt / Term Debt | $0.00 | $0.00 | $0.00 | Flat (0.0%) | Zero funded institutional borrowings; Note 23(c) confirms zero financial debt covenants. |
| Total Liabilities | $6.45M | $12.59M | $17.45M | +38.6% | $13.59M current liabilities and $3.86M non-current liabilities (including $1.77M deferred scrap grant). |
| Contributed Equity | $112.96M | $197.99M | $250.98M | +26.8% | Paid-in capital expanded through public equity placements and option conversions. |
| Accumulated Losses | ($73.88M) | ($109.23M) | ($175.99M) | +61.1% | Cumulative lifetime operating losses recorded since corporate inception. |
Operating cash outflows expanded 106.2% YoY to $44.95M ($11.24M per quarter), while capital expenditures contributed $18.56M in investing outflows, establishing a total cash drain of $63.52M. Total cash additions to Property, Plant, and Equipment (PPE) were $17.78M, with $4.57M in non-cash payables and accruals, bringing gross PPE additions to $22.80M.
As of the June 30, 2026 balance date, cash reserves of $35.24M provided an implied operational runway of 6.7 months under the baseline burn rate of $5.29M per month ($15.88M per quarter). Under an accelerated scale-up scenario consuming $23.80M per quarter (+50% burn rate), liquidity would have expired within 4.4 months (by November 2026). On July 7, 2026, IperionX completed an institutional placement of 2,275,000 American Depositary Shares (ADSs) at a ratio of 1 ADS to 10 ordinary shares, generating $50.0M gross ($47.0M net). This equity injection established a pro forma cash position of $85.24M, extending the baseline runway by 9.4 months to approximately 16.1 months (securing operations into Q3/Q4 2027). The company also holds $37.10M in remaining reimbursable grant capital from the U.S. Department of War (DoW), restricted strictly to eligible project outlays.
Working capital mechanics reflect structural shifts:
* Inventory Capitalization: Raw material stock was capitalized for the first time during H1 FY 2026 (the period ended December 31, 2025). The $3.91M balance consists entirely of raw titanium scrap, which includes 290 metric tons donated by the U.S. Government under the Industrial Base Analysis and Sustainment (IBAS) program. This grant was recognized at a fair value of $2.76M, with $0.99M credited to profit and loss in FY 2026 and $1.77M carried as unamortized deferred income. Work-in-progress and finished goods inventories remained immaterial due to customer delivery cycles for prototype qualifications.
* Receivables Quality: Accounts receivable rose 298.7% to $3.28M, of which 96.8% ($3.18M) represents reimbursable invoices submitted to the U.S. Government under Defense Production Act (DPA) Title III and IBAS contracts. The filing confirmed zero commercial delinquent debt and zero past-due balances.
* Payables and Contractual Commitments: Trade payables advanced 39.5% to $10.45M under standard 60-day terms. Undiscounted contractual lease commitments total $5.23M ($0.74M in FY 2027, $0.70M in FY 2028, $0.70M in FY 2029, $0.69M in FY 2030, $0.64M in FY 2031, and $1.76M thereafter, with imputed interest of $1.26M). A non-current deferred consideration liability of $333,000 remains payable to Blacksand Technology, LLC ($700,000 in FY 2025), following the initial equity settlement of 3,006,163 ordinary shares ($2.0M fair value) in FY 2024.
* Overhead Expansion: Corporate and administrative expenses increased 142.5% YoY to $25.92M, which, when combined with $9.17M in non-cash share-based payments, equaled total expensed R&D ($25.19M).
The capital structure comprises 339,384,066 fully paid ordinary shares on issue as of June 30, 2026 (94.95% of fully diluted capital), and 18,031,866 unlisted dilutive securities (5.05%). The dilutive pool includes:
* Unlisted Options: 6,872,710 options with a weighted-average exercise price of A$13.47 across seven tranches:
* Series 1: 106,093 options at A$0.87 (expiring December 5, 2026).
* Series 2: 235,000 options at A$10.00 (expiring April 1, 2027).
* Series 3: 1,305,000 options at A$8.00 (expiring June 30, 2027).
* Series 4: 1,374,746 options at A$5.00 (expiring April 10, 2029).
* Series 5: 511,972 options at A$11.00 (expiring April 2, 2030).
* Series 6: 1,566,690 options at A$18.00 (expiring April 2, 2031; 4-year service condition).
* Series 7: 1,773,209 options at A$22.00 (expiring April 2, 2031; 4-year service condition).
* Performance Rights: 7,048,486 units across market and non-market hurdles:
* A$4.00 30-day VWAP hurdle: 2,885,000 units (2.44M expiring December 2028; 0.445M expiring December 2027).
* A$18.00 30-day VWAP hurdle: 660,077 units with a 4-year service lock (expiring April 2, 2031).
* A$6.00, A$7.00, and A$8.00 VWAP hurdles: 3,473,409 units total (1.157M each, expiring April 10, 2031).
* Non-market operational milestones: 30,000 units (expiring December 31, 2026).
* Restricted Stock Units (RSUs): 4,110,670 units subject to 3-year service vesting cliffs.
* Performance Shares: Historical Class A (19,800,000) and Class B (19,800,000) Performance Shares lapsed unexercised following the passage of feasibility study and production deadlines, converting into 30 ordinary shares per class in FY 2025 and FY 2026.
Including the July 7, 2026 placement of 22,750,000 ordinary share equivalents, pro forma fully diluted equity stands at 380,165,932 shares. Substantial shareholders include DITM Holdings Pty Ltd (controlled by Executive Chairman Todd Hannigan) with 26,608,334 shares (7.8%), FMR LLC (Fidelity) with 26,097,578 shares (7.7%), and State Street Corporation with 22,764,708 shares (6.7%). Officers and directors hold an aggregate of 53,090,459 shares (15.6%), supporting a public free float of 62.2%.
Asset Architecture, Supply Chain Logistics, and Defense Procurement Integration
IperionX operates an integrated domestic value chain that bridges scrap refining, powder metallurgy, and mineral separation across three key states.
The downstream processing and manufacturing hub is situated in South Boston, Halifax County, Virginia, comprising 97,800 square feet across the Titanium Production Facility (TPF) and the Advanced Manufacturing Center (AMC). All primary systems achieved commissioning in September 2025, operating 24/7. Operating modifications increased nameplate capacity from 125 tpa to ~200 tpa (~16.7 metric tons per month) with zero incremental capital expenditure, delivering toward a steady-state manufacturing cost benchmark of ~$55/kg. The company procures 100% renewable grid power, achieving zero Scope 2 market-based emissions, with an independently verified life-cycle carbon intensity of 7.8 kg CO₂e/kg of powder (representing a 91.2% reduction compared to standard plasma atomization at 88.8 kg CO₂e/kg).
The facility deploys Hydrogen Assisted Metallothermic Reduction (HAMR™) solid-state reduction, which utilizes hydrogen to lower the thermodynamic activity of oxygen in titanium, allowing magnesium reduction to extract oxygen from scrap without carbothermic chlorination, titanium tetrachloride gas handling, or multi-pass Vacuum Arc Remelting (VAR). In FY 2026 commercial operations, HAMR™ refined 100% Ti-6Al-4V revert scrap containing 3.42% oxygen down to <0.07% oxygen, outperforming the ASTM Grade 5 upper specification limit of 0.20%. For spherical powders, the Granulation-Sintering-Deoxygenation (GSD™) process increased usable fine-particle yield by up to 50% relative to atomization techniques.
Downstream compaction is anchored by a 300-ton, 6-axis SACMI powder metallurgy press commissioned in May 2026. Operating at speeds up to 24 cycles per minute, the press possesses a run-rate capacity of ~11 million single-cavity components per year prior to sintering. To alleviate downstream thermal cycle bottlenecks, two Hydrogen Sintering and Phase Transformation (HSPT™) furnaces were acquired in FY 2026 (the first delivered in the June 2026 quarter). HSPT™ achieves reversible hydrogen phase transformations ($\alpha \leftrightarrow \beta$) to refine grain size from ~40 µm down to ~5 µm, delivering wrought-like fatigue endurance without forging presses. Process research on mill products and alloy development continues at the 15,000 square foot Industrial Pilot Facility (IPF) in Salt Lake City, Utah.
The upstream segment consists of the Titan Critical Minerals Project across Benton and Carroll Counties, Tennessee, spanning >10,000 acres (>1,500 acres owned in fee simple, ~1,200 acres under lease, and ~7,500 acres held under option agreements subject to $75/acre/year maintenance or a 5% net revenue royalty). The Definitive Feasibility Study (DFS) was completed on June 4, 2026, over a 3,317-acre study area (13.4 km²), co-funded by $5.0M in expenditures ($4.13M reimbursed via DoW IBAS grants).
Table Titan Mineral Resource Estimate — June 30, 2026
| Titan Mineral Resource Estimate (SEC Regulation S-K 1300, Exclusive of Reserves, 0.4% THM Cut-Off, June 30, 2026) | In Situ Ore (Mt) | THM Grade (%) | Contained THM (Mt) | Zircon (% THM) | Rutile (% THM) | Ilmenite (% THM) | REE (% THM) |
| Measured | 96.85 | 1.5% | 1.49 | 10.4% | 9.2% | 40.1% | 1.2% |
| Indicated | 102.19 | 2.0% | 2.01 | 9.8% | 10.2% | 38.9% | 1.5% |
| Total Measured + Indicated | 199.04 | 1.8% | 3.50 | 10.0% | 9.8% | 39.4% | 1.4% |
| Inferred | 97.83 | 1.8% | 1.77 | 9.3% | 9.6% | 38.0% | 1.2% |
| Total Measured, Indicated & Inferred | 296.87 | 1.8% | 5.28 | 9.8% | 9.7% | 39.0% | 1.3% |
Table Titan Mineral Reserve Estimate — June 30, 2026
| Titan Mineral Reserve Estimate (SEC Regulation S-K 1300, ROM Basis, 0.85% THM Cut-Off, June 30, 2026) | Ore Unit | ROM Ore (Mt) | THM Grade (%) | Contained THM (t) | Zircon (%) | Rutile (%) | Ilmenite (%) | REE (%) |
| Proven | Upper McNairy | 24.57 | 2.30% | 620,000 | 6.2% | 6.2% | 23.6% | 0.2% |
| Proven | Lower McNairy | 68.74 | 3.43% | 3,086,000 | 12.7% | 10.5% | 48.3% | 1.9% |
| Probable | Upper McNairy | 2.42 | 2.30% | — | 6.2% | 6.2% | 23.6% | 0.2% |
| Probable | Lower McNairy | 21.31 | 3.43% | — | 12.7% | 10.5% | 48.3% | 1.9% |
| Total Mineral Reserves | Combined | 117.03 | 3.20% | 3,706,000 | 11.6% | 9.8% | 44.2% | 1.6% |
Proven reserves account for 79.7% (93.31 Mt) of total reserves. The DFS outlines a 14-year life-of-mine (LOM). Phase 1 (Years 1–4) processes 3.5 Mtpa run-of-mine (ROM) ore (~400 tons per hour rougher spiral feed), expanding in Phase 2 (Years 5–14) to 10.0 Mtpa ROM (~1,200 tons per hour feed). Total LOM production yields ~2.5 Mt of mineral products: 1.37 Mt ilmenite, 0.29 Mt rutile, 0.77 Mt zircon concentrate, and 0.06 Mt Heavy Rare Earth Concentrate (HREC rich in dysprosium, terbium, and yttrium).
Modeled project metrics (unlevered real 2026 USD) demonstrate an after-tax NPV₈ of $813M, an after-tax IRR of 39.4%, a payback period of 3.63 years, cumulative LOM after-tax free cash flow of $1.93B, and cumulative EBITDA of $2.80B. Capital requirements total $381.3M ($228.1M for Phase 1 Initial Capex, comprising $201.9M direct/indirect, $5.6M owner's costs, and $20.6M contingency; $153.2M for Phase 2, comprising $137.5M direct/indirect, $1.6M owner's costs, and $14.0M contingency), alongside $23.3M in sustaining capital.
DFS commodity pricing models assume:
* Rutile Final Product: $1,471/metric ton (reserve cut-off: $1,425/t); metallurgical recovery of 64.3% to a 91.1% TiO₂ grade.
* Ilmenite Final Product: $353/metric ton (reserve cut-off: $340/t); metallurgical recovery of 80.7% to a 62.5% TiO₂ grade.
* Zircon Concentrate: $829/metric ton (reserve cut-off: $912/t); metallurgical recovery of 91.8% to a 34.4% ZrO₂ grade.
* Heavy Rare Earth Concentrate: $41,759/metric ton (reserve cut-off: $10,678/t), reflecting a 50% payability factor applied to the Total Rare Earth Oxide (TREO) basket; metallurgical recovery of 91.4% to a 61.4% TREO grade.
On June 15, 2026, IperionX contracted to acquire adjacent mineral, property, and industrial infrastructure assets from Covia Solutions LLC for $3.0M cash (closed July 1, 2026), absorbing pre-stripped Lower McNairy ore, stockpiles, a rail spur connected to the CSX Transportation Memphis subdivision, and historical land reclamation obligations. An integrated Atlas-Titan economic assessment is targeted for completion by end-CY 2026. Permitting is anchored by a 5-year Tennessee Department of Environment and Conservation (TDEC) Surface Mining Permit (OM-70711-01) and NPDES Water Discharge Permit (TN0070711). Transport logistics assume site hauling at $1.00/ROM metric ton, with freight costs budgeted at $11.85/t for ilmenite/rutile, $65.00/t for zircon concentrate, and $555.00/t for HREC. Barging access is available via the Tennessee River 15 miles (24 km) away. Mineral upgrading will leverage Green Rutile™ (substituting coal reduction kilns to upgrade ilmenite) and Alkaline Roasting and Hydrolysis (ARH™) to generate +99% TiO₂ feedstock.
Table Government Programs, Defense Contracts and Strategic Supply-Chain Positioning
| Program & Funding Authority | Total Program Value | Reimbursed / Drawn to Date | Remaining Reimbursable Ceiling | Key Statutory Covenants & Title Mechanics | Defense Supply Chain Role |
| U.S. Department of War (DoW) DPA Title III |
26.1M with $13.4M co-match) |
2.40M post-period) |
$2.40M at year-end | Legal title to all equipment vests with U.S. Govt through Jan 30, 2027; assets tagged "Property of the Government of the United States." | Commissioned Phase 1 Virginia powder manufacturing capacity. |
| DoW IBAS Program |
96.3M with $49.2M co-match) |
$12.40M | $34.70M (100% obligated) | Operates on a cost-reimbursement basis under 2 CFR 200 Subpart E and FAR Part 31 principles. | Co-funds 1,400 tpa expansion and Titan DFS ($5.0M allocation). |
| U.S. Army SBIR Phase III IDIQ | Up to $99.00M ceiling | ~$0.30M (Task Order 1) | Up to $79.20M unallocated | Firm-fixed-price task orders subject to defense option exercises. | Task Order 1 (
18.5M base, up to $25.4M) establish $26.7M obligated orders. |
| DoW Non-Monetary Scrap Grant | $2.76M fair value | 290 metric tons delivered | $1.77M unamortized deferred income | Zero-cost transfer of military titanium scrap; amortized as consumed in P&L. | Provides ~18 months of raw feedstock at 200 tpa run rate without cash outlay. |
| Carver Pump / U.S. Navy | ~$100,000 prototype order | In production | Potential LRIP transition | Rapid prototyping (<1 week vs >12 months legacy casting lead time). | Direct qualification of naval vessel centrifugal pump impellers. |
| American Rheinmetall / U.S. Army | $300,000 prototype order | In production | 700 components scope | Component testing for 40–45% weight reduction versus steel. | Prototype delivery for combat vehicle systems. |
| DEVCOM GVSC | Integrated in R&D / Task Orders | Deliveries ongoing | Fastener qualification | Testing confirmed +20% yield torque vs SAE Grade 8 steel; +15% tensile strength vs titanium specs. | Fasteners for Joint Light Tactical Vehicles (JLTV) and military trailers. |
| Halifax County / Commonwealth of VA | Local tax exemptions & grants | Active campus | Performance conditions | Regional capital investment and workforce training covenants. | Anchors 97,800 sq ft manufacturing infrastructure. |
Commercial offtake remains centered on testing and prototype conversion. Non-binding agreements remain active with Ford Motor Company for closed-loop automotive scrap recycling, as well as with Lockheed Martin, GKN Aerospace, and Aperam across Europe and the Asia-Pacific region. All international market engagements, including supply chain touchpoints in Taiwan, Province of China, comply with standard trade regulatory frameworks.
HDIN Institutional Verdict: Capital Runway Realities and Structural Execution Friction
IperionX presents an operational divergence between plant commissioning milestones and cash burn acceleration. While the company achieved 24/7 continuous operations at its Virginia campus and reached a 200 tpa powder run rate, commercial revenues in profit and loss remain at $0.00. The commercial model is supported by prototype purchase orders ($100k Carver Pump, $300k American Rheinmetall) and military development frameworks ($26.7M in obligated SBIR Phase III task orders under a $99.0M ceiling). However, zero firm, binding take-or-pay volume contracts exist to establish a baseline cash inflow floor.
The corporate strategy involves dual-track friction:
1. Downstream Processing: The scrap-to-component circular platform requires modest capital intensity, benefits from $59.80M in federal award co-funding ($12.70M DPA Title III and $47.10M IBAS), and accesses 290 metric tons of zero-cost government feedstock. This division offers the fastest pathway to operating cash generation.
2. Upstream Mineral Extraction: The Titan Critical Minerals Project requires $228.1M in initial Phase 1 capital ($381.3M LOM), specialized environmental permits for mineral processing, and radioactive material licenses (NORM) for monazite handling. Management has withheld a Final Investment Decision (FID) on Titan, stating development remains contingent on securing external non-recourse project finance, strategic equity partners, or EXIM Bank export facilities.
A primary structural vulnerability is the asset title retention under the DPA Title III agreement: legal title to $12.70M in primary powder refining equipment at the Virginia TPF vests with the U.S. Government through January 30, 2027. If the Department of War declines title conveyance, IperionX faces operational disruptions or mandatory repurchase outlays. Additionally, government grant execution imposes working capital friction, as all qualifying expenditures must be pre-funded from cash reserves prior to reimbursement.
Corporate governance metrics reflect structured oversight:
* Board Independence: The Board maintains a 75.0% independence ratio (6 of 8 directors), with 37.5% female representation. Michael J. Loparco joined as an independent director on August 3, 2026. The Audit Committee is 100% independent and chaired by Tony Tripeny (former CFO of Corning Incorporated and SEC Financial Expert). The Lead Independent Director is Lorraine M. Martin (former EVP and General Manager of Lockheed Martin's F-35 program), supported by director Beverly M. Wyse (30-year Boeing executive and former VP/GM of Boeing South Carolina).
* Executive Compensation Alignment: In FY 2026, CEO Anastasios Arima received $562,500 base salary, $440,000 cash bonus, and $1,813,143 in share expense ($2,824,655 total comp). Executive Chairman Todd Hannigan received $393,500 base salary and $1,220,955 in share expense ($1,634,830 total comp), voluntarily waiving his cash bonus. Total compensation for other key executives was: Toby Symonds (President/CSO) $2,528,223 ($534,500 base, $418,000 bonus, $1,544,196 equity); W. Scott Sparks (COO) $1,207,144 ($320,000 base, $180,000 bonus, $688,004 equity); Dominic Allen (CCO) $1,036,289 ($320,000 base, $180,000 bonus, $536,289 equity); and Marcela Castro (CFO) $791,000 ($307,500 base, $165,000 bonus, $287,898 equity). Total executive cash bonuses were $1.383M, reflecting a 78.5% strategic scorecard achievement (114% target payout). Long-term incentives (LTI) carry an A$18.00 30-day VWAP hurdle (+166% premium over the A$6.76 base price) with a mandatory 4-year service lock and a 1-year holding requirement to April 2, 2031.
* Related Parties: Clean execution with zero insider loans; related-party payments were limited to $70,660 paid to Performance Industries, Inc. (associated with COO Scott Sparks) for construction engineering, alongside pass-through director fee entities (Arete Innovative Resources LLC for Melissa Waller; Westoz Services Trust for Dominic Allen).
* Redomiciliation: On August 3, 2026, the company proposed a corporate redomiciliation from Australia to the United States (IperionX Inc., a Texas corporation), aligning corporate registration with U.S. defense procurement frameworks.
Until commercial revenues are recognized in the income statement and binding multi-year take-or-pay offtake agreements materialize, IperionX remains dependent on public equity markets to absorb operational cash consumption and meet required capital-matching obligations.
Presentation Download & Video Access:
- Presentation Download: Click the PDF download link under 'Related Topics' to access the full institutional presentation of this report.
- Video Link: Click this link to watch the HDIN analyst briefing on YouTube.
About HDIN Research:
HDIN Research is a premier global market intelligence and strategic advisory firm specializing in institutional-grade financial analysis, supply chain audits, and macroeconomic forecasting. Our dedicated sector analysts deliver actionable, data-driven insights tailored for private equity, hedge funds, and corporate strategy teams. Visit us at http://www.hdinresearch.com.
2026 AI Transparency Footer:
"This intelligence report was authored by HDIN Research analysts following a rigorous audit of official corporate filings. AI was utilized for massive-scale data synthesis and structural drafting, ensuring 100% inclusion of reported data points. All strategic insights, financial modeling, and final verdicts were verified by our editorial board to ensure professional accuracy and compliance with 2026 Google Search E-E-A-T standards."