Newcleo PLC: Liquidity Bridge Narrows to 17 Months Following Nasdaq Debut as €13.4M Monthly Burn Strains Advanced Reactor Timeline
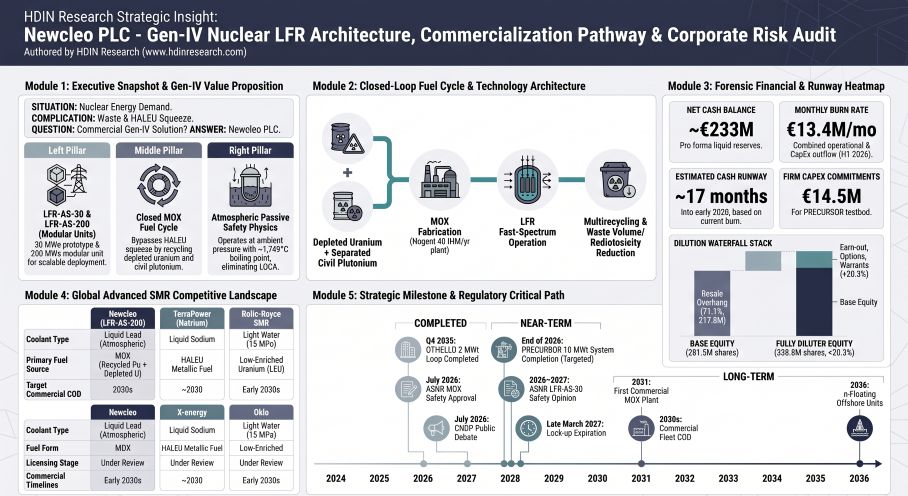
1. Capital Structure vs. Commercial COD: Newcleo PLC [NASDAQ: NWCL] holds ~€233.0 million in post-closing liquidity following its NewHold Investment Corp III business combination, providing a 17.3-month runway against a €13.44 million monthly free cash drain, while commercial fleet deployment remains targeted for the 2030s.
2. Supply Chain & Geographic Concentration: The Group has deployed ~€81.5 million at the ENEA Brasimone facility in the Italian Republic to mechanically complete the 10 MWt PRECURSOR testbed by year-end 2026, while advancing licensing across the French Republic, Slovak Republic, and United States of America.
3. Structural Dilution & Market Overhang: SEC Form F-1 registers 217,834,936 Ordinary Shares (71.1% of base equity) for secondary resale with zero corporate cash proceeds, exacerbated by €65.4 million in cash leakage under a Forward Purchase Agreement and potential share expansion to 338,806,998 fully diluted units.
Figure Newcleo PLC - Gen-lV Nuclear LFR Architecture, Commercialization Pathway & Corporate Risk Audit
 Segmental Realities, Capital Depletion and Pro Forma Balance Sheet Dynamics
Newcleo PLC operates as a single operating segment focused on Generation-IV Lead-Cooled Fast Reactor (LFR) architecture and Mixed Uranium-Plutonium Oxide (MOX) closed fuel cycles. Commercial revenue generation relies entirely on legacy operating subsidiaries acquired in 2023: Pompes Rütschi SAS / AG (nuclear canned-motor pumps), Fucina Italia S.r.l. (heavy nuclear fabrication), and Servizi Ricerche e Sviluppo S.r.l. (SRS, engineering consultancy).
Consolidated revenue contracted 29.9% year-over-year in FY2025 to €32.77 million (down from €46.74 million in FY2024) as manufacturing capacity was diverted from third-party commercial contracts to internal demonstration assets (the OTHELLO and PRECURSOR loops). Top-line performance rebounded 45.6% year-over-year in H1 2026 to €19.43 million (compared to €13.35 million in H1 2025) due to long-term engineering contract execution and industrial pump deliveries. In H1 2026, customer concentration remained elevated, with the top three commercial counterparties generating €8.31 million, or 42.8% of external revenue (Customer A: €3.40 million; Customer B: €3.21 million; Customer C: €1.70 million). The firm's unsatisfied performance obligation backlog under IFRS 15 stood at €39.25 million as of December 31, 2025 (€37.08 million in equipment and €2.17 million in engineering), while aggregate contract awards totaled approximately $118.0 million as of June 30, 2026.
Operating cost structures are driven by centralized research, development, and administrative expansion. Under IAS 38.57, Newcleo capitalizes €0.00 of internal nuclear reactor and fuel R&D, expensing 100% of these expenditures as incurred (€58.47 million in FY2024, €68.54 million in FY2025, and €34.63 million in H1 2026). In contrast, tangible experimental test rigs are capitalized under IAS 16 within Property, Plant, and Equipment (PP&E) Construction Work in Progress (€11.0 million in FY2024, €5.7 million in FY2025, and €19.1 million in H1 2026), bringing PP&E Construction Work in Progress to €53.65 million as of December 31, 2025.
Table NEWCLEO PLC MULTI-YEAR CONSOLIDATED FINANCIAL PERFORMANCE (IFRS, IN € THOUSANDS)
|
Line Item (€ thousands) |
FY2024 Audited |
FY2025 Audited |
YoY Change (%) |
H1 2025 Unaudited |
H1 2026 Unaudited |
YoY Change (%) |
|---|---|---|---|---|---|---|
|
Revenue from Products and Services |
46,743 |
32,769 |
-29.9% |
13,347 |
19,429 |
+45.6% |
|
Cost of Sales |
(34,999) |
(24,953) |
-28.7% |
(9,193) |
(13,299) |
+44.7% |
|
Gross Profit |
11,744 |
7,816 |
-33.4% |
4,154 |
6,130 |
+47.6% |
|
Other Income (Grants and Tax Credits) |
17,746 |
19,347 |
+9.0% |
4,763 |
6,554 |
+37.6% |
|
Research and Development Expenses |
(58,473) |
(68,544) |
+17.2% |
(35,450) |
(34,629) |
-2.3% |
|
Selling, General and Administrative Expenses |
(86,815) |
(98,547) |
+13.5% |
(48,932) |
(59,170) |
+20.9% |
|
Operating Loss |
(115,798) |
(139,928) |
+20.8% |
(75,465) |
(81,115) |
+7.5% |
|
Net Finance Income / (Costs) |
5,053 |
(183) |
-103.6% |
590 |
(1,095) |
-285.6% |
|
Share of Loss of Associates |
— |
(48) |
N/A |
— |
(83) |
N/A |
|
Loss Before Income Tax |
(110,565) |
(141,789) |
+28.2% |
(74,878) |
(82,302) |
+9.9% |
|
Income Tax Benefit |
402 |
1,824 |
+353.7% |
585 |
321 |
-45.1% |
|
Net Loss |
(110,163) |
(139,965) |
+27.1% |
(74,293) |
(81,981) |
+10.3% |
Operating cash outflows expanded from €104.48 million in FY2024 to €119.68 million in FY2025, reaching €53.69 million in H1 2026. Capital expenditures totaled €49.46 million in FY2024 (€37.71 million PP&E, €11.75 million intangibles), €45.86 million in FY2025 (€43.00 million PP&E, €2.86 million intangibles), and €26.97 million in H1 2026 (€25.33 million PP&E, €1.64 million intangibles). Consequently, total free cash burn registered at €153.94 million in FY2024, €165.54 million in FY2025, and €80.66 million in H1 2026 (a monthly run-rate of €13.44 million).
Table CONSOLIDATED BALANCE SHEET WATERFALL & CAPITAL POSITIONING (IFRS, IN € THOUSANDS)
|
Balance Sheet Item (€ thousands) |
Dec. 31, 2024 |
Dec. 31, 2025 |
June 30, 2026 |
Pro Forma Combined (June 30, 2026) |
|---|---|---|---|---|
|
Current Assets |
||||
|
Cash and Cash Equivalents |
192,714 |
105,270 |
66,540 |
253,007 |
|
Short-Term Investments |
2,199 |
2,291 |
2,335 |
2,335 |
|
Trade, Contract and Other Assets |
64,018 |
62,314 |
77,768 |
79,958 |
|
Inventories |
6,952 |
5,057 |
4,843 |
4,843 |
|
Total Current Assets |
265,883 |
174,932 |
151,486 |
340,143 |
|
Non-Current Assets |
||||
|
Property, Plant and Equipment, Net |
58,783 |
93,436 |
115,999 |
115,999 |
|
Goodwill |
37,281 |
37,281 |
37,281 |
37,281 |
|
Intangible Assets, Net |
46,436 |
43,054 |
42,760 |
42,760 |
|
Right-of-Use Assets |
21,612 |
18,521 |
17,665 |
17,665 |
|
Investments in Associates |
— |
31,635 |
31,553 |
31,553 |
|
Other Non-Current Assets and Receivables |
18,016 |
37,458 |
38,006 |
38,006 |
|
Total Non-Current Assets |
182,128 |
261,385 |
283,264 |
283,264 |
|
Total Assets |
448,011 |
436,317 |
434,750 |
623,407 |
|
Current Liabilities |
||||
|
Current Trade and Other Payables |
52,116 |
83,808 |
60,055 |
58,227 |
|
Current Borrowings and Lease Liabilities |
4,962 |
5,833 |
6,042 |
6,042 |
|
Current Provisions |
103 |
186 |
378 |
378 |
|
Total Current Liabilities |
57,181 |
89,827 |
66,475 |
64,647 |
|
Non-Current Liabilities |
||||
|
Non-Current Borrowings and Lease Liabilities |
20,286 |
31,843 |
30,596 |
30,596 |
|
Other Non-Current Liabilities and Provisions |
9,301 |
17,719 |
17,456 |
17,456 |
|
Warrant Liabilities |
— |
— |
— |
8,888 |
|
Total Non-Current Liabilities |
29,587 |
49,562 |
48,052 |
56,940 |
|
Total Liabilities |
86,768 |
139,389 |
114,527 |
121,587 |
|
Total Equity |
361,243 |
296,928 |
320,223 |
501,820 |
|
Working Capital (Current Assets − Current Liabilities) |
208,702 |
85,105 |
85,011 |
275,496 |
On June 2, 2026, independent auditor Grant Thornton issued a going-concern explanatory paragraph regarding FY2025 financial statements. On September 21, 2026, Newcleo consummated its cross-border business combination with NewHold Investment Corp III, securing gross proceeds of $247.0 million (~€215.0 million), which included a $216.0 million (€189.2 million gross) private placement in public equity (PIPE). The capital infusion was preceded by €16.19 million net cash raised via the July 2026 Pre-PIPE round.
Net proceeds were constrained by a 50.6% redemption rate by public SPAC shareholders (€95.0 million cash outflow) and a €65.4 million ($74.6 million) cash prepayment from the SPAC Trust Account to Tech Opportunities LLC under a Forward Purchase Agreement (FPA) covering up to 7,000,000 recycled shares. After settling transaction costs, preliminary unaudited liquid reserves stood at ~€233.0 million as of September 30, 2026, dissolving the formal 12-month going-concern uncertainty.
* Baseline Spend Scenario: At the H1 2026 net monthly cash drain of €13.44 million, the ~€233.0 million cash balance provides 17.3 months of runway, exhausting reserves in February 2028.
* Historical Spending Scenario: At the FY2025 monthly average cash drain of €13.80 million, reserves provide 16.9 months of runway, depleting in January 2028.
* Accelerated Capex Scenario: If capital deployment escalates by 35.0% to €18.00 million per month to fund simultaneous French licensing and PRECURSOR milestones, operating runway contracts to 12.9 months, depleting capital by October 2027.
On June 29, 2026, Newcleo reduced its share premium account by €640.80 million via shareholder resolution and a directors' solvency statement, creating positive distributable reserves of €234.7 million (€267.6 million as of June 30, 2026) to enable corporate re-registration as a public limited company and support potential physical settlement under the FPA.
Financial indebtedness remains modest. Total contractual borrowings and lease liabilities stood at €36.64 million as of June 30, 2026 (€18.43 million in borrowings and €18.21 million in IFRS 16 leases), yielding a borrowings-to-equity ratio of 5.75% (3.67% pro forma). Borrowings include a €17.0 million Senior Secured Refinancing Facility executed December 23, 2025, by Pompes Rütschi SAS with a banking syndicate led by BNP Paribas (Tranche A: €11.9 million amortizing to December 2031 at EURIBOR + 2.30%; Tranche B: €5.1 million bullet to December 2032 at EURIBOR + 2.80%), secured by 100% of Rütschi Fluid AG shares. The credit facility requires a maximum consolidated leverage ratio of 2.75x and a minimum debt-service coverage ratio of 1.00x, with Pompes Rütschi in full compliance across all reporting dates. Subsidiary state-guaranteed loans represent €1.69 million bearing interest between 0.58% and 12.24%.
Non-cancelable contractual capital expenditure commitments stood at €14.5 million as of June 30, 2026 (reduced from €26.5 million at Dec 31, 2025, and €46.5 million at Dec 31, 2024), allocated to final construction stages of the PRECURSOR facility. Twelve-month contractual debt and lease servicing obligations total €7.97 million (€4.56 million in lease payments, €2.74 million in senior facility amortization/interest, and €0.67 million in state-guaranteed loans).
Balance sheet provisions total €4.09 million non-current (€3.18 million employee pension liabilities, €0.94 million lease dilapidation restoration provisions across London and Turin, and €0.05 million in commercial lawsuit contingencies) and €0.38 million current (product warranty reserves). Under IAS 37, nuclear plant decommissioning and high-level waste disposal provisions stand at €0.00, as Newcleo operates zero active nuclear installations containing irradiated fissile material.
Table CAPITAL DILUTION WATERFALL & REGISTERED SECURITIES OVERHANG
| Instrument / Shareholder Class | Basic Shares | Basic (%) | Diluted Shares | Diluted (%) | Terms / Hurdles |
| Historical Newcleo Shareholders | 244,914,447 | 87.52% | 282,977,298 | 83.52% | 0.4807 Recap Factor |
| PIPE Placement Investors | 21,600,000 | 7.72% | 21,600,000 | 6.38% | $10.00 entry price |
| SPAC Public Shareholders | 9,023,548 | 3.22% | 19,086,028 | 5.63% | Redeemed 50.6% |
| Sponsor & Insiders | 3,206,027 | 1.15% | 5,202,169 | 1.54% | Promote structure |
| Non-Redemption (NRA) Investors | 1,016,158 | 0.36% | 1,016,158 | 0.30% | Incentive shares |
| Capital Markets Advisors | 70,346 | 0.03% | 70,346 | 0.02% | Closing equity |
| Total Base Shares Outstanding | 279,830,526 | 100.00% | — | — | Par value $0.02288 |
| Dilutive Expansion Tranches: | |||||
| Class B Earnout Shares | — | — | 24,490,918 | — | 50% @ $15, 50% @ $18 |
| Public & Private Warrants | — | — | 10,354,197 | — | $11.50 strike (5-yr) |
| NextChem Performance Warrants | — | — | 8,855,000 | — | FID/Tech deliverables |
| Continuing Options & RSUs | — | — | 13,571,933 | — | Employee equity pool |
| Total Fully Diluted Share Capital | — | — | 338,806,998 | 100.00% | +21.1% dilution |
The filed Form F-1 represents a secondary resale registration covering up to 217,834,936 Ordinary Shares (71.1% of base shares outstanding) and 9,146,717 warrants held by Selling Securityholders. The company receives $0.00 in gross proceeds from these secondary sales. Transfer restrictions bind 162,906,824 Ordinary Shares under a 180-day lock-up expiring in late March 2027, subject to early release triggers: 50% upon achieving a $12.00 volume-weighted average price (VWAP) for 20 of 30 consecutive trading days, 25% at a $15.00 VWAP, and 25% at an $18.00 VWAP.
Infrastructure Layout, Industrial Supply Chain and Multi-Jurisdictional Footprint
Newcleo maintains operations across six sovereign states under United Nations geographic standards, employing >900 personnel across 16 offices, 3 primary development sites, 3 manufacturing factories, and 3 qualification, R&D, and training centers.
The reactor architecture leverages liquid lead as primary coolant within an unmoderated fast-neutron spectrum. Liquid lead exhibits an atmospheric boiling point of ~1,749 °C and solidifies at ~327 °C, eliminating Loss of Coolant Accidents (LOCA) by operating at ambient pressure without heavy reactor pressure vessels. Primary containment relies on a pool-type configuration utilizing natural convective circulation for decay heat removal. Physical trade-offs include corrosion and dissolution of structural steels at 400 °C to 550 °C+, structural mass loads resulting from liquid lead density (~10.5 g/cm³), and seismic sloshing. The PRECURSOR demonstration vessel measures ~2.15 meters in diameter, ~6.5 meters in height, and houses ~104 metric tons of pure liquid lead.
Corrosion mitigation relies on dynamic dissolved-oxygen monitoring systems and proprietary alumina-forming austenitic (AFA) steels, nickel-based alumina-forming alloys, and laser-cladded weld overlays. Empirical neutron irradiation data is sourced via a bilateral agreement with the Japan Atomic Energy Agency (JAEA) utilizing the Joyo experimental fast reactor.
The fuel strategy eliminates dependence on enriched uranium and High-Assay Low-Enriched Uranium (HALEU) by synthesizing Mixed Oxide (MOX) fuel from reprocessed civil plutonium and depleted uranium stockpiles. Fast-spectrum operation fissions all plutonium isotopes and transuranic actinides, reducing the radiotoxicity horizon of waste from hundreds of thousands of years to several hundred years.
Newcleo holds zero binding commercial feedstock supply agreements with sovereign fuel managers:
* French Republic: While the French Nuclear Safety and Radiation Protection Authority (ASNR) issued a favorable safety options opinion in July 2026 for the 40 tHM/year Nogent-sur-Seine MOX plant, no bilateral extraction agreement exists with Orano or Électricité de France (EDF). Commission nationale du débat public (CNDP) public consultations for Indre-et-Loire and Nogent-sur-Seine concluded on July 30, 2026.
* United Kingdom: No commercial allocation or liability-relief contract has been executed with the Nuclear Decommissioning Authority (NDA) regarding the ~140 metric ton civil plutonium inventory at Sellafield.
* United States: The U.S. Department of Energy (DOE) selected partner Oklo Inc. on May 26, 2026, for advanced negotiations under the Surplus Plutonium Utilization Program. Newcleo contemplates investing $2.2 billion to $2.6 billion over 5 to 6 years via an affiliated entity to develop fuel fabrication infrastructure, subject to formal DOE contract execution and NRC 10 CFR Part 70 licensing.
* Slovak Republic: The Newvys joint venture (49% Newcleo / 51% state-owned JAVYS) is executing an exploratory Bohunice site study under a €1.2 million engineering contract (€0.8 million recognized through H1 2026), without binding waste allocation.
The commercial reactor pipeline totals ~9.2 GW in non-binding capacity:
Table STRATEGIC PARTNERSHIPS AND NON-BINDING OFFTAKE AUDIT
| Counterparty / Entity | Structure / Agreement | Scope & Key Deliverables |
| JAVYS (Slovak Republic) | Equity Joint Venture (Newvys) | 4x LFR-AS-200 units at Bohunice site; €1.2M study contract. |
| NextChem / MAIRE (Italy) | Equity Joint Venture (Next-N) | 40% stake; CI/BoP engineering; €52.5M earnout warrants. |
| Oklo Inc. (United States) | Cooperation Agreement | DOE Surplus Plutonium Program; $2.2B–$2.6B fuel capex plan. |
| IP3 Corp / Cybernetic (USA) | Commercial LOI / Study | Virginia AI data center campus; 18-month exclusivity. |
| U.S. DOE / NNSA | Federal Teaming LOI | RFP for AI compute on DOE land at Savannah River Site. |
| Danieli & C. S.p.A. (Italy) | Non-Binding MOU (24 months) | Green steel direct reduction (DRI); high-temp heat integration. |
| Fincantieri S.p.A. (Italy) | Strategic Term Sheet | 50/50 marine propulsion JV; floating nuclear power barges. |
| Saipem S.p.A. (Italy) | Framework Agreement (5 years) | Offshore oil & gas decarbonization using floating LFR units. |
| Bureau Veritas / ABMI (France) | n-Floating Consortium | €1.0M Bpifrance grant; floating multi-unit barges for 2036. |
| ALTRA / Ignalina (Lithuania) | Non-Binding MOU | 12-month study on legacy RBMK spent fuel multirecycling. |
| Tractebel (Belgium) | Pre-Feasibility Study & NDA | Plutonium recycling study for Doel/Tihange waste inventories. |
Newcleo holds zero executed Power Purchase Agreements (PPAs), Contracts for Difference (CfDs), or binding off-take commitments. Customers retain the right to terminate MOUs without penalty upon brief notice (e.g., Danieli upon 2 months' notice; Saipem upon 6 months' notice).
HDIN Institutional Verdict
Newcleo has established a defensible technological niche by demonstrating lead-coolant thermal-hydraulics at ENEA Brasimone and securing supply chain integration through acquired operating subsidiaries. Its fast-neutron architecture decouples reactor deployment from Western HALEU supply constraints.
The corporate governance framework exhibits significant principal-agent vulnerabilities. Operating as a Foreign Private Issuer, Newcleo has opted out of Nasdaq corporate governance mandates: only 3 of 9 board directors (33.3%) are independent. The Compensation Committee is chaired by major shareholder Dr. Andrea Ruben Osvaldo Levi and includes Deputy CEO Elisabeth Rizzotti, while the Nominating Committee includes CEO Stefano Buono. The board maintains no dedicated Nuclear Safety Committee, delegating technical risks to executive management.
Related-party leases extract cash from the operating entity: Newcleo leases its Turin headquarters from Isola S.r.l., an entity owned by CEO Stefano Buono and his spouse (€0.5 million expense in FY2025; €0.4 million lease liability as of June 30, 2026). Concurrently, independent auditor Grant Thornton identified material significant deficiencies in Internal Controls over Financial Reporting (ICFR), encompassing lack of segregation of duties over manual journal entries, privileged access risks in SAP ECC6 and Eurecia, and IFRS 15 revenue cut-off weaknesses.
The institutional verdict is clear: Newcleo’s post-closing capital structure cannot bridge the gap to commercial fleet deployment in the 2030s. The €65.4 million FPA prepayment exposes the company to open-market cash leakage if equity prices trade down, while the 217.8-million-share secondary resale registration creates downward market overhang upon the expiration of lock-up agreements in late March 2027. Unless management secures binding, project-financed engineering contracts and non-dilutive government subsidies before late 2027, the company faces renewed liquidity compression and dilutive capital raises.
Presentation Download & Video Access:
Presentation Download: Click the PDF download link under 'Related Topics' to access the full institutional presentation of this report.
Video Link: Click this link to watch the HDIN analyst briefing on YouTube.
About HDIN Research:
HDIN Research is a premier global market intelligence and strategic advisory firm specializing in institutional-grade financial analysis, supply chain audits, and macroeconomic forecasting. Our dedicated sector analysts deliver actionable, data-driven insights tailored for private equity, hedge funds, and corporate strategy teams. Visit us at http://www.hdinresearch.com.
2026 AI Transparency Footer:
"This intelligence report was authored by HDIN Research analysts following a rigorous audit of official corporate filings. AI was utilized for massive-scale data synthesis and structural drafting, ensuring 100% inclusion of reported data points. All strategic insights, financial modeling, and final verdicts were verified by our editorial board to ensure professional accuracy and compliance with 2026 Google Search E-E-A-T standards."