Nightfood Holdings, Inc.: Corporate Pivot to TechForce Robotics Stalls in California as $29.8 Million Working Capital Deficit and $9.3 Million in Note Defaults Trigger Insolvency Warnings
1. Strategic Overreach Meets Capital Exhaustion: Nightfood Holdings, Inc. faces a working capital deficit of $(29,761,991) and a monthly operating cash burn of $670,988 against cash reserves of $865,889, leaving the company with approximately 1.29 months (39 days) of cash runway as of June 30, 2026.
2. Cascading Debt Defaults and Asset Encumbrance: A total of 18 notes representing over $9,310,000 in gross principal are in active default at penalty rates up to 24.00% per annum, triggering cross-default covenants under a $3,392,000 first-priority secured line of credit held by related party SBZ Investment Industry Inc.
3. Severe Capital Overhang and Governance Bottlenecks: Contractual fully diluted shares stand at 4,766,480,767 common share equivalents—exceeding the corporate charter's 900,000,000 share ceiling by 5.30x—while Chief Executive Officer Jimmy Chan commands 50.0000001% unilateral voting control via 1,000 super-voting Series A Preferred shares.
Figure Nightfood Holdings Inc FY2026 Form 10-K Data Architecture
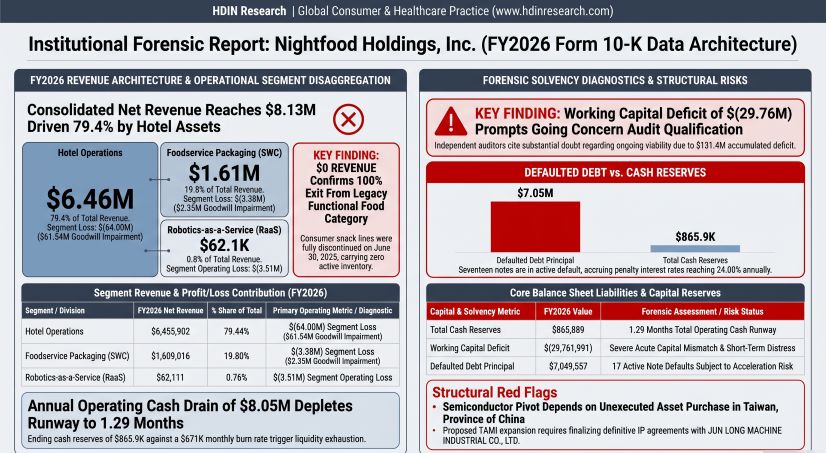
Segmental Realities, M&A Impairments, and Working Capital Deficits
For the fiscal year ended June 30, 2026, Nightfood Holdings, Inc. reported consolidated net revenue from continuing operations of $8,127,029, an increase of 1,585.09% (+$7,644,744) compared to $482,285 in FY2025. Consolidated gross profit expanded to $5,319,338 (65.45% gross margin) against consolidated Cost of Sales of $2,807,691, compared to $69,782 (14.47% gross margin) on $412,503 Cost of Sales in FY2025.
However, management stated that top-line expansion was entirely inorganic, driven by the consolidation of two hotel assets and the annualization of packaging distribution, rather than organic growth. Legacy sleep-friendly snack operations were discontinued on June 30, 2025, generating $0 revenue in FY2026 ($41,551 in FY2025) with a residual net loss from discontinued operations of $(3,784).
In accordance with ASU 2023-07, operating performance is evaluated at the segment level via aggregated costs and expenses rather than disaggregated gross margin metrics. Total enterprise operating costs and expenses reached $85,737,844 in FY2026, producing a consolidated operating loss of $(77,610,815) and a net loss of $(84,654,946).
Table CONSOLIDATED OPERATIONAL SEGMENT SUMMARY (FY2026)
|
Operating Segment |
Revenue ($) |
% of Total Revenue |
Costs & Expenses ($) |
Operating Loss ($) |
|---|---|---|---|---|
|
Hotel Operations |
$6,455,902 |
79.44% |
$70,455,932 (1) |
$(64,000,030) |
|
Foodservice Packaging |
$1,609,016 |
19.80% |
$4,985,248 (2) |
$(3,376,232) |
|
Robotics-as-a-Service |
$62,111 |
0.76% |
$3,572,377 |
$(3,510,266) |
|
Discontinued Operations |
$0 |
0.00% |
$3,784 |
$(3,784) |
|
Consolidated Totals |
$8,127,029 |
100.00% |
$79,017,341 (3) |
$(77,610,815) |
(2) Includes $2,349,000 packaging goodwill impairment and $2,636,248 in product, fulfillment, and warehouse expenses.
(3) Excludes corporate overhead, G&A, and debt service reflected in consolidated financials.
Operating performance at acquired hotel properties failed initial underwriting assumptions due to weak transient demand, an acute summer contraction in the Coachella Valley, and operating overhead inflation across labor, utilities, insurance, and reassessed property taxes. Consequently, the company recorded $63,886,000 in goodwill impairment charges during FY2026:
* Holiday Inn Victorville: $29,544,000 write-down (initial goodwill: $46,985,000; remaining: $17,441,000).
* Hilton Garden Inn Rancho Mirage: $31,993,000 write-down (initial goodwill: $44,197,000; remaining: $12,204,000).
* SWC Group (Foodservice Packaging): $2,349,000 write-down (remaining goodwill: $1,365,177).
* Total remaining consolidated goodwill stands at $31,800,177 (including $790,000 at Skytech Robotics), carrying zero valuation headroom over estimated Level 3 fair values.
The balance sheet reflects an acute liquidity deficit. Net operating cash burn reached $(8,051,852) in FY2026 ($(670,988) per month), comprising $(7,946,851) from continuing operations and $(105,001) from discontinued operations. As of June 30, 2026, cash and cash equivalents were $865,889, yielding a projected cash runway of 1.29 months (~39 days).
Current assets totaled $2,195,232 (including $243,886 net accounts receivable and $311,647 inventory) against current liabilities of $31,957,223, widening the working capital deficit by 178% to $(29,761,991). Total liabilities reached $52,808,936. Stockholders' equity was recorded at $11,795,678, supported entirely by the reclassification of Series C and D Preferred Stock ($88.9 million) and Additional Paid-in Capital ($142.7 million), offset by an accumulated deficit of $(131,408,790).
Independent auditor TAAD LLP issued an unqualified audit opinion for FY2026 containing a going concern explanatory paragraph, citing persistent accumulated losses and operational cash deficits. Additionally, Note 16 discloses that Nightfood Holdings, Inc. has failed to file its federal and state income tax returns for ten consecutive fiscal years (FY2016 through FY2025/FY2026), exposing the entity to statutory penalties, interest, and the forfeiture of good standing across state jurisdictions.
Capital Structure Forensics and Dilution Mechanics
The company’s capital structure is governed by 27 convertible debt instruments, bifurcated embedded derivative liabilities, and severe authorized share constraints. Net carrying debt stood at $34,925,868 as of June 30, 2026 (contractual gross principal of $37,427,806 less unamortized discounts of $2,501,938). Current debt obligations total $15,721,626, while non-current obligations total $19,204,242.
Table FORENSIC CONVERTIBLE DEBT RECONCILIATION BY TRANCHE
|
Debt Tranche / Lenders |
Gross Principal |
Contractual Terms |
Default Status |
Conversion Structure / Key Terms |
|---|---|---|---|---|
|
Structure A (Loans 1–15) — Mast Hill Fund |
$4,180,621 |
15% stated interest / 24% default interest; first-priority lien |
14 notes in default; Loan 15 current |
Fixed conversion price of $0.0330/share; 136,733,380 shares |
|
Structure B (Loans 19–25, 28) — SWC Trade Creditors & Insiders (Chan, Wang) |
$759,776 ($530.6k third-party; $229.2k related-party) |
15% stated interest / 15% default interest; unsecured |
Current; maturing September 4, 2027 |
Floating conversion price at a 35% discount: 65% of the 20-day low ($0.0163); 54,555,584 shares |
|
Structure C (Loans 39–41) — Mast Hill Fund, Senior Secured OID Notes |
$4,621,471 ($3.90M net cash) |
15% stated interest / 24% default interest; first-priority lien; additional 3% annual OID step-up |
Loan 39 defaulted on October 8, 2026; Loans 40–41 current |
Lower of $0.0330 or 80% of the 5-day VWAP ($0.0256); 195,186,442 shares |
|
Structure D (Loan 43) — Accredited Investor |
$184,706 ($150.0k net cash) |
15% stated interest / 16% default interest; unsecured |
Current; maturing June 18, 2027 |
Lower of $0.0330 or 80% of the 10-day low ($0.0228); 8,141,096 shares |
|
Related Payable Note (Loan 42) — CRO Lei Sonny Wang |
$73,927 |
15% stated interest / 15% default interest; unsecured |
Current; maturing March 31, 2029 |
Floating conversion price at a 35% discount to the 20-day low ($0.0256); 2,995,781 shares |
|
Non-Convertible Debt — Hotel Mortgages (2 units) |
$19,192,445 |
WSJ Prime + 0.25% (7.00% at fiscal year-end) |
Current |
Maturing June 6, 2029; secured by real estate |
|
Non-Convertible Debt — SBZ Revolving Credit (44), Related Party |
$3,392,000 |
10.00% stated interest rate; blanket lien |
Technical breach / standstill |
Discretionary facility; $6.61M uncommitted |
|
Accrued Interest (Total) |
$1,763,878 |
Accruing at default interest rates |
Default-related portions |
$1.63M third-party; $133k related-party |
As of June 30, 2026, 17 notes representing $7,049,557 in principal were in active default. On October 8, 2026, Loan #39 matured without repayment, adding $2,270,000 to defaulted debt and bringing the total defaulted principal to $9,319,557, accruing annualized penalty interest rates up to 24.00%.
Derivative liabilities increased 440% year-over-year from $1,102,992 to $5,955,393 ($5,483,343 third-party and $472,050 related-party). Under ASC 815, bifurcated conversion options accounted for $4,978,123, while commitment warrants under a $25,000,000 Equity Purchase Agreement (EPA) accounted for $977,270. Issuances of convertible notes generated an immediate initial derivative expense of $1,438,825. Year-end mark-to-market adjustments resulted in a net gain of $1,007,680 (comprising a $1,726,227 gain on embedded options offset by a $718,547 loss on commitment warrants caused by a full-ratchet price reset from $0.10 to $0.02 per share). The settlement of $73,927 in accounts payable to CRO Lei Sonny Wang via Loan #42 triggered an immediate non-cash derivative settlement loss of $109,283.
With 894,843,497 common shares issued or immediately issuable, the company has utilized 99.43% of its 900,000,000 authorized common stock ceiling. Issuance of the 3.87 billion locked-up shares is legally blocked pending regulatory processing by FINRA and the State of Nevada of a 1-for-150 reverse stock split approved by the Board of Directors on September 9, 2026.
Infrastructure Footprint, Supply Chain Dependencies, and Related-Party Networks
Nightfood Holdings operates entirely within California across two owned hospitality properties and leased commercial facilities. It maintains zero industrial manufacturing plants:
* Holiday Inn Victorville (Victorville, CA): Full-service real estate asset comprising 155 rooms, dining facilities, and meeting spaces. Acquired August 27, 2025, for $81.28 million in Series C equity consideration, backed by a $9,348,438 variable mortgage. Operating license transitions from an independent hotel back to a franchise flag are delayed pending Property Improvement Plan (PIP) capital expenditures and gym completions.
* Hilton Garden Inn Rancho Mirage (Rancho Mirage, CA): Select-service real estate asset comprising 120 rooms. Acquired September 30, 2025, backed by a $9,844,007 mortgage. Construction of a mandated five-room addition is slated for completion before December 31, 2027.
* Master Warehouse & Corporate Headquarters (13501 S. Main St., Los Angeles, CA): 23,437 square feet of cross-dock distribution space leased by SWC Group from related-party landlord 13501 S. Main Holdings, LLC. Executed September 1, 2025, the 60-month lease represents an aggregate undiscounted commitment of $2,610,000, stepping up from $22,800 to $52,880 monthly ($2,010,037 balance sheet liability under ASC 842; $1,742,510 ROU Asset). Operating lease payments consumed $221,200 in operating cash during FY2026.
* Corporate Administration Suites: Leased executive offices located at 177 E Colorado Blvd, Pasadena, CA (Future Hospitality Ventures Holdings, Inc.) and 42225 Remington Ave, Temecula, CA (TechForce Robotics, Inc.).
Procurement operations reflect an asset-light contract structure:
* Robotics Prepayment Bottleneck: Under the two-year Supply Agreement executed on April 11, 2026, with NUWA Robotics Corp. and Hon Hai Precision Industry Co., Ltd. (Foxconn), Hon Hai requires 100% upfront cash advances prior to initiating production on any purchase order. As of June 30, 2026, zero purchase orders had been placed due to capital constraints.
* Unexecuted Joint Ventures: Collaborative arrangements with Oncotelic Therapeutics, Inc. (biopharmaceutical robotics) under ASC 808 have produced zero Statements of Work. The planned 51/49% joint venture TechForce Advanced Manufacturing, Inc. (TAMI), formed September 17, 2026, with JUN LONG MACHINE INDUSTRIAL CO., LTD. (Taiwan, Province of China) to build advanced packaging wafer sorters and AOI equipment, remains uncapitalized without executed definitive purchase agreements.
* Inventory Composition: Consolidated inventory declined from $319,491 to $311,647 at June 30, 2026, consisting of $271,411 in SWC packaging finished goods and $40,236 in hotel food and beverage provisions. RaaS deployment components are expensed as incurred, yielding zero capitalized robotics inventory. Inventory turnover stood at 8.90x (~41.0 days of supply).
Corporate operations exhibit significant insider entanglement:
* Senior Creditor Encirclement: SBZ Investment Industry Inc. (holding 374,026 Series C shares, convertible into 2.24 billion common shares) holds a blanket, first-priority security lien across all corporate assets securing its $3,392,000 credit line. The facility is discretionary and carries a cross-default clause triggered by third-party defaults exceeding $25,000. Additionally, Nightfood carries $2,513,375 in hotel trade payables and fees owed to SBZ that are not disaggregated.
* Voting Monopoly: CEO Jimmy Chan retains unilateral 50.0000001% majority voting power (545,254,602 of 1,090,509,203 total votes) through 1,000 shares of Series A Super-Voting Preferred Stock. The Board consists of 5 members (60% independent), but the company has formally deferred the adoption of a written Code of Ethics and reported late Section 16(a) filings for Jimmy Chan and Lei Sonny Wang.
* Compensation Strain & Nepotism: Due to cash depletion, $246,500 in FY2026 NEO base salaries and $18,000 in director fees went unpaid, pushing total related-party accrued compensation to $2,515,660. On May 1, 2026, the Board granted non-plan options to purchase 6,060,606 common shares ($163,657 fair value) to Meagan Floco and Richard Floco, immediate family members of President Ried Floco.
HDIN Institutional Verdict
Management's forward-looking strategic roadmap—predicated on concurrently scaling hotel turnarounds, commercializing Foxconn-manufactured RaaS fleets, and launching semiconductor packaging equipment via TAMI—is structurally decoupled from operational cash generation.
The proposed 1-for-150 reverse stock split does not eliminate structural dilution; while compressing issued shares from 510,217,444 to approximately 3,401,450, it maintains the authorized legal limit at 900,000,000 shares, immediately re-opening the share capacity to absorb 3.87 billion locked-up conversion claims from Mast Hill Fund and SBZ.
With $9.31 million in defaulted note principal accruing penalty interest up to 24.00%, active breaches of SBZ's cross-default covenants, and less than 39 days of cash runway, Nightfood Holdings operates entirely under creditor forbearance. In the absence of an immediate institutional recapitalization, senior secured noteholders and SBZ maintain the legal capacity to initiate foreclosure on real estate, packaging, and robotics assets.
Presentation Download & Video Access:
- Presentation Download: Click the PDF download link under 'Related Topics' to access the full institutional presentation of this report.
- Video Link: Click this link to watch the HDIN analyst briefing on YouTube.
About HDIN Research:
HDIN Research is a premier global market intelligence and strategic advisory firm specializing in institutional-grade financial analysis, supply chain audits, and macroeconomic forecasting. Our dedicated sector analysts deliver actionable, data-driven insights tailored for private equity, hedge funds, and corporate strategy teams. Visit us at http://www.hdinresearch.com.
2026 AI Transparency Footer:
"This intelligence report was authored by HDIN Research analysts following a rigorous audit of official corporate filings. AI was utilized for massive-scale data synthesis and structural drafting, ensuring 100% inclusion of reported data points. All strategic insights, financial modeling, and final verdicts were verified by our editorial board to ensure professional accuracy and compliance with 2026 Google Search E-E-A-T standards."