Pharma Foods International Co., Ltd.: Manufacturing Pivot Near Toyama Advances as Negative Operating Cash Flow Signals Persistent Working Capital Lockup
1. Operating Cash Flow diverged sharply from Net Income in FY2026, dropping to -¥1,175 million despite reporting ¥1,988 million in net earnings, pressured by a 225.7-day Cash Conversion Cycle and ¥9,143 million in inventory.
2. A ¥12,500 million facility expansion in Toyama via subsidiary Meiji Yakuhin Co., Ltd. elevated interest-bearing debt to ¥17,199 million, while the manufacturing unit remains in negative equity of -¥2,404 million.
3. Institutional risk centers on parent debt guarantees of ¥4,230 million, stringent bank covenants requiring net assets at 75% or higher, and direct-to-consumer advertising ratios consuming 53.65% of revenue.
Figure Pharma Foods International Diagnostic Financiar si Strategic (FY2022-FY2026)
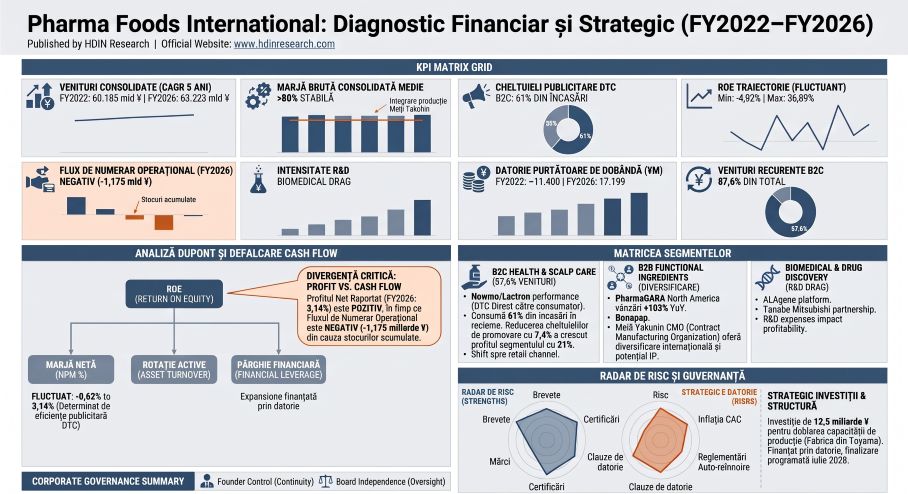 Segmental Realities and Cash Flow Decoupling
Pharma Foods International Co., Ltd. [TYO: 2929] closed FY2026 (fiscal year ended July 31, 2026) with consolidated revenue contracting 3.12% YoY to ¥63,223 million. Operating profit expanded 11.19% YoY to ¥2,632 million, while net income rose 440.22% YoY to ¥1,988 million from ¥368 million in FY2025. This bottom-line expansion was driven by a 7.56% YoY cut in consolidated advertising outlays from ¥36,692 million (56.22% of revenue) to ¥33,917 million (53.65% of revenue). In the B2C segment, advertising spend fell 6.43% YoY to ¥33,810 million (61.06% of B2C segment revenue), expanding B2C operating margin by 156 bps to 8.09% (operating profit of ¥4,481 million).
Table Consolidated Financial Performance, Profitability, Efficiency, and Operating Cash Flow Metrics (FY2022–FY2026)
|
Consolidated Metric / Performance Indicator |
FY2022 |
FY2023 |
FY2024 |
FY2025 |
FY2026 |
|---|---|---|---|---|---|
|
Consolidated Revenue (¥M) |
60,185 |
68,572 |
62,147 |
65,260 |
63,223 |
|
Gross Margin (%) |
N/A |
N/A |
N/A |
80.57% |
80.18% |
|
SG&A Expenses as a Percentage of Revenue (%) |
N/A |
N/A |
N/A |
76.95% |
76.02% |
|
Operating Profit (¥M) |
~1,029 |
~3,593 |
~5,302 |
2,367 |
2,632 |
|
EBITDA (¥M) |
N/A |
N/A |
N/A |
3,152 |
3,368 |
|
Net Profit Margin (NPM, %) |
-0.62% |
4.49% |
5.16% |
0.56% |
3.14% |
|
Asset Turnover (AT, x) |
1.93x |
1.89x |
1.70x |
2.00x |
1.80x |
|
Equity Multiplier (EM, x) |
4.40x |
3.76x |
3.16x |
2.83x |
2.67x |
|
Return on Equity (ROE, %) |
-4.82% |
36.89% |
30.22% |
3.19% |
16.09% |
|
Return on Assets (ROA, %) |
-1.20% |
8.50% |
8.76% |
1.13% |
5.66% |
|
Operating Cash Flow (OCF, ¥M) |
-6,065 |
6,125 |
5,486 |
-1,092 |
-1,175 |
A DuPont decomposition highlights how volatility in Net Profit Margin has governed return dynamics: ROE collapsed from 36.89% in FY2023 to 3.19% in FY2025 as NPM contracted to 0.56%, before recovering to 16.09% in FY2026 on a 3.14% NPM. However, earnings quality deteriorated. The negative divergence between Net Income and Operating Cash Flow widened to -¥3,163 million in FY2026 (-¥1,175 million OCF vs. ¥1,988 million Net Income), following a -¥1,460 million divergence in FY2025.
Working capital drain stemmed from:
* Inventory expansion: Absorbed ¥1,133 million in FY2025 and ¥1,293 million in FY2026. Consolidated inventories reached ¥9,143 million in FY2026 (merchandise/products: ¥7,533 million; work-in-process: ¥820 million; raw materials: ¥790 million), up from ¥7,850 million in FY2025 (merchandise/products: ¥6,311 million; work-in-process: ¥675 million; raw materials: ¥864 million). Valuation reserves stand at ¥115 million, following a ¥31 million adjustment in FY2026.
* Cash settlements: Cash settlements of accounts payable and accrued expenses totaled -¥2,228 million in FY2026, alongside corporate tax payments of ¥2,528 million (¥2,247 million in FY2025).
* Working capital metrics: Based on FY2026 Cost of Goods Sold of ¥12,530 million, Days Inventory Outstanding (DIO) rose to 247.5 days. Trade receivables contracted from ¥5,285 million to ¥3,990 million, establishing Days Sales Outstanding (DSO) at 26.8 days due to automated consumer credit card and mobile carrier settlements. Trade payables stood at ¥1,413 million, equating to Days Payable Outstanding (DPO) of 48.6 days. The Cash Conversion Cycle (CCC) settled at 225.7 days.
Table FY2026 Segment Revenue Mix, R&D Expenditure, R&D Intensity, and Headcount
| Segment / Division Portfolio | FY2026 Net Sales (¥M) | Revenue Mix (%) | R&D Allocation (¥M) | Segment R&D Intensity (%) | Segment Headcount (Temp Staff) |
| B2C Business | 55,368 | 87.58% | 48 | 0.09% | 241 (100) |
| B2B Business | 7,471 | 11.82% | 507 | 6.79% | 327 (30) |
| Biomedical Business | 350 | 0.55% | 915 | 261.43% | 34 (2) |
| Corporate / Unallocated | 0 | 0.00% | 387 | N/A | 23 (11) |
| Consolidated Total | 63,223 | 100.00% | 1,858 | 2.94% | 625 (143) |
Total research expenditures grew 35.13% YoY to ¥1,858 million in FY2026, fully expensed within SG&A under Japanese GAAP, leaving zero capitalized development costs on the balance sheet. Intangible assets consist solely of software (¥48 million) and residual goodwill (¥37 million, amortized straight-line over 5 to 6 years with ¥34 million amortized in FY2026). The Biomedical unit absorbed 49.25% of total R&D (¥915 million), posting a segment operating loss of -¥838 million while generating ¥350 million in top-line revenue (+5.9% YoY) via contract proteomic analysis services (Olink DIA platform).
Infrastructure Layout and Regional Capital Concentration
Pharma Foods International operates a dual-hub physical architecture linking proprietary peptide fermentation in the Kansai region to pharmaceutical manufacturing in Toyama Prefecture and automated customer relationship operations in Kyushu:
The corporate production base is anchored by Meiji Yakuhin Co., Ltd., a 100%-owned subsidiary acquired in August 2021. Meiji Yakuhin generated ¥16,744 million in net sales, ¥2,112 million in ordinary profit, and ¥1,938 million in net income in FY2026. However, its balance sheet carries a net capital deficit (negative equity) of -¥2,404 million (assets of ¥15,320 million vs. liabilities of ¥17,724 million), reflecting historical write-downs. This deficit forced Pharma Foods International to record non-operating standalone valuation losses on subsidiary shares of ¥422 million in FY2026 and ¥2,300 million in FY2025.
Capital expenditures jumped from -¥891 million in FY2025 to -¥4,014 million in FY2026, driven by construction of a ¥12,500 million flagship pharmaceutical and supplement manufacturing facility in Toyama. Cumulative CapEx deployed on the project reached ¥3,657 million by the close of FY2026, with full commissioning scheduled for July 2028 to double internal manufacturing capacity. Upstream fermentation for PharmaGABA and catechins remains tied to an exclusive toll-manufacturing agreement dated January 5, 2006, with Banshu Seasoning Co., Ltd., arranged through Toyotsu Foods Corporation. Domestic and international B2B ingredient channels remain linked to a global distribution agreement dated May 6, 2004, with Mitsubishi Corporation, supplemented by an October 2024 capital alliance with Itochu Corporation [TYO: 8001], which holds 1,452,000 shares (5.00% equity stake following an 872,400 treasury share allotment).
Retail distribution via Meiji Yakuhin's Consumer Health Care (CHC) pharmacy network reached ¥1,313 million in FY2026 (+20.4% YoY), selling physical units of "Newmo Hair Tonic" (30ml/75ml formats) and "Lactron" tablets across all domestic prefectures. This retail push complements the direct-response mail-order channel, which has accumulated 32.96 million bottles shipped for the "Newmo" brand (Category Top status in Japan from FY2020 to FY2024 per TPC Marketing Research Co., Ltd.), 4.90 million units for "Newmo Z", 1.56 million bottles for "Newmo V Shampoo", and 8.54 million bags for "Tamagosamin". Sales of "Lactron" grew 112% YoY in FY2026, while eyelash serum "WMOA" retained Category Top status for FY2023–FY2024. Overseas, PharmaGABA sales expanded 103% YoY in North America supported by US FDA GRAS affirmation, with broader distribution spanning China, Southeast Asia (Thailand, Malaysia, Indonesia, Vietnam), and Taiwan, China.
HDIN Institutional Verdict
Pharma Foods International's "New Value Creation 1K Project," targeting ¥100.0 billion in group revenue, masks structural balance sheet strains. Funding the ¥12,500 million Toyama facility and the post-fiscal year-end acquisition of Marine Pro Foods Co., Ltd. on October 2026 for ¥5,030 million in cash has shifted corporate leverage toward short-term bank financing.
Total interest-bearing debt expanded 35.84% YoY to ¥17,199 million in FY2026 (including ¥21 million in finance leases: ¥5 million short-term, ¥16 million long-term). The debt structure comprises:
* Short-term bank borrowings: ¥13,400 million (up from ¥11,400 million in FY2025).
* Long-term obligations: ¥3,771 million (¥560 million due within one year, ¥3,211 million long-term), compared to ¥1,231 million in FY2025 (¥560 million short-term, ¥671 million long-term).
* Credit line commitments: Kyoto Bank syndicate facility of ¥10,000 million (100% drawn); MUFG Bank facility of ¥7,500 million (¥1,000 million drawn); Shiga Bank facility of ¥3,000 million (¥900 million drawn).
* Syndicated project loans: ¥12,300 million facility for the Toyama plant led by Kyoto Bank, Shiga Bank, and Hokuriku Bank (¥3,100 million balance drawn).
While the Current Ratio moved from 119.3% to 126.1% (current assets of ¥23,029 million against current liabilities of ¥18,265 million), the Quick Ratio dropped from 72.2% to 64.5% as cash balances fell to ¥7,791 million against ¥11,781 million in liquid assets. Total Debt-to-Equity stands at 166.7%, and Interest-Bearing Debt-to-Equity rose from 109.6% to 130.6%. EBIT interest coverage contracted from 26.01x to 16.35x (Operating Profit of ¥2,632 million against interest expense of ¥161 million, up from ¥91 million), and coverage remains negative on an Operating Cash Flow basis.
Parent financial exposure is accentuated by off-balance-sheet guarantees. Debt guarantees provided to financial institutions covering Meiji Yakuhin’s bank borrowings expanded from ¥1,190 million to ¥4,230 million in FY2026. Loan covenants mandate that consolidated group net assets must not fall below 75% of the preceding fiscal year-end balance, while prohibiting ordinary losses for two consecutive fiscal years at both group and Meiji Yakuhin standalone levels.
Corporate governance exhibits high founder concentration. Dr. Mujo Kim controls 7.79% directly (2,261,507 shares) and exercises control over PF Holdings Co., Ltd. (5.10%, 1,480,000 shares). Family members hold key executive positions: Senior Executive Director Eiichi Kim (eldest son; 2.50%, 724,852 shares) heads R&D and Sales, while Senior Executive Director Kazuyuki Masuda (son-in-law; 2.65%, 769,624 shares) leads Group Management and heads operating subsidiaries Meiji Yakuhin and Pharmafoods Communication. Family holdings aggregate 20.2% of voting rights. External institutional and corporate anchors include The Master Trust Bank of Japan, Ltd. (8.35%, 2,425,000 shares), Itochu Corporation (5.00%), and Rohto Pharmaceutical Co., Ltd. [TYO: 4527] (2.07%, 600,000 shares; reciprocated by PFI holding 406,000 Rohto shares valued at ¥969 million). Additional policy cross-holdings include Sanyo Chemical Industries, Ltd. (67,400 shares; ¥327 million), Ezaki Glico Co., Ltd. (5,000 shares; ¥25 million), and Nippon Ham Factors Ltd. (500 shares; ¥3 million).
The Board of Directors maintains a 40.0% independence ratio (4 independent outside directors among 10 directors):
* Nobuyoshi Satai (former President of Nissen Holdings Co., Ltd.) chairs the Nomination & Remuneration Committee.
* Dr. Tetsuro Yamane (MD, former Director of Matsushita Health Insurance Hospital) chairs the Risk & Compliance Committee.
* Prof. Yuka Hayashi (Kyoto University Graduate School of Agriculture) and Satomi Kawabata (attorney/patent attorney) provide technical and legal oversight.
* The 4-member Audit & Supervisory Board includes outside auditors Sadaya Tsujimoto (Certified Public Tax Accountant) and Nobuo Yada (former Rohm Co., Ltd. executive).
* Board female representation stands at 14.3% (2/14 directors/auditors), scheduled to rise to 23.1% (3/13 officers) post-AGM.
* Parent company female manager ratio is 34.6% (target: 50%), while Pharmafoods Communication reached 81.8% (target: 70%) and Meiji Yakuhin recorded 24.2% (target: 35%). Meiji Yakuhin retains an internal labor union with 245 members. The parent gender pay gap stands at 62.6% overall (70.1% regular staff; 64.6% part-time), driven by executive demographics.
* FY2026 director compensation totaled ¥339 million across 16 officers, comprising ¥226 million in base pay and ¥112 million in Restricted Stock Compensation across 7 internal directors (capped at ¥300 million base, ¥200 million stock / 200,000 shares; auditor base capped at ¥30 million). Grants have a 3-year transfer restriction with a clawback clause releasing 0% if target profit achievement falls below 80%, pro-rata between 80% and 120%, and 100% above 120%. Independent auditor Hainan Audit Corporation issued an unqualified audit opinion with zero litigation reserves required.
In therapeutics, out-licensing provides a partial counterweight:
* An autoimmune monoclonal antibody developed on the ALAgene platform, out-licensed to Mitsubishi Tanabe Pharma Corporation in January 2021 (milestone reached June 2024), completed Phase 1 trials (jRCT2031240187) in July 2025.
* The CADASIL peptidic program (PFI-780 targeting NOTCH3 mutation arteriopathy) entered an exclusive implementation agreement in FY2026 with Hikuma AM Pharma Co. and the National Cerebral and Cardiovascular Center (NCVC), targeting Phase 3 clinical advancement under orphan drug designations.
* The Anti-AviOn (PFI-701) oncology program, in-licensed from Tohoku University, is undergoing preclinical lead optimization under an AMED 5-year AI antibody consortium.
* The proprietary IP portfolio comprises 141 registered patents across 37 domestic and 31 overseas families (US, EU, China, Taiwan, China), with 73 pending applications covering egg yolk peptides (iHA, Bonepep, Runpep, HGP), ALAgene, and Ovoveil biomaterials under NEDO contracts.
Unless Pharma Foods International converts its 247.5-day inventory positions into cash and resolves Meiji Yakuhin’s -¥2,404 million capital deficit, capital commitments in Toyama will continue to pressure debt covenants and restrain shareholder distributions.
Presentation Download & Video Access:
- Presentation Download: Click the PDF download link under 'Related Topics' to access the full institutional presentation of this report.
- Video Link: Click this link to watch the HDIN analyst briefing on YouTube.
About HDIN Research:
HDIN Research is a premier global market intelligence and strategic advisory firm specializing in institutional-grade financial analysis, supply chain audits, and macroeconomic forecasting. Our dedicated sector analysts deliver actionable, data-driven insights tailored for private equity, hedge funds, and corporate strategy teams. Visit us at http://www.hdinresearch.com.
2026 AI Transparency Footer:
"This intelligence report was authored by HDIN Research analysts following a rigorous audit of official corporate filings. AI was utilized for massive-scale data synthesis and structural drafting, ensuring 100% inclusion of reported data points. All strategic insights, financial modeling, and final verdicts were verified by our editorial board to ensure professional accuracy and compliance with 2026 Google Search E-E-A-T standards."