Immutep Limited: Pipeline Pivot to Niche Immuno-Oncology Near Paris Laboratory as 50% Upfront Licensing Clawback Signals CMC Comparability Crisis
Date : 2026-10-30
Reading : 198
HDIN Executive Takeaways
1. The termination of the Phase III TACTI-004 trial in 1L NSCLC triggered an immediate A$3.09 million non-cash IP impairment and forced a 50% refund (US$10.0 million / A$14.26 million) to Dr. Reddy’s Laboratories S.A., although Immutep recognized A$14.56 million in net upfront licensing revenue for FY2026.
2. Clinical failure was linked to structural N-glycan variances between the commercial-scale 2,000L bioreactor run at WuXi Biologics in China and historical 200L clinical batches, prompting a contracted 200L remediation run and exposing Immutep to US BIOSECURE Act regulatory re-evaluations.
3. Total liquid capital contracted 46.90% YoY to A$68.87 million, providing a statutory cash runway of 14.9 months (to Q3 CY2027) at an annualized net monthly cash burn of A$4.62 million, offset by A$6.46 million in debt-like supplier financing via deferred CDMO payables.
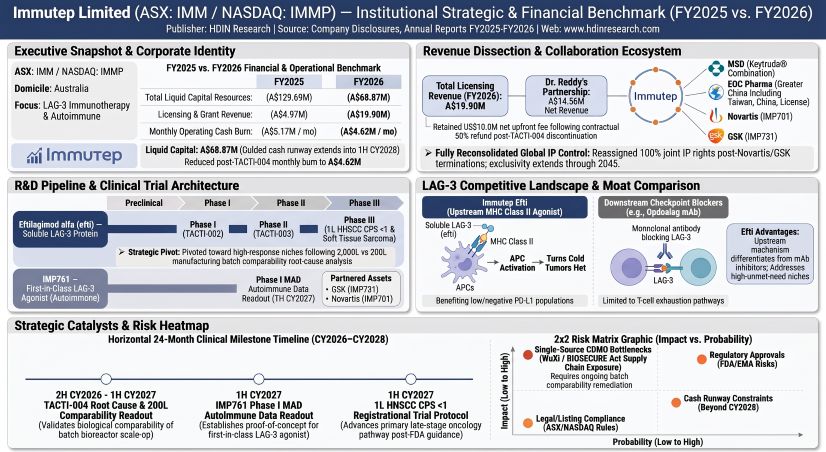
Figure Immutep Limited - Institutional Strategic & Financial Benchmark (FY2025 vs FY2026)
 Balance Sheet Realignment, Revenue Recognition, and Cash Burn
Immutep Limited [ASX: IMM, NASDAQ: IMMP] closed FY2026 with a substantial realignment of its profit and loss statement and capital structure. In January 2026, the group received a gross upfront payment of US$20.0 million (A$28.85 million) under an exclusive out-licensing agreement with Dr. Reddy’s Laboratories S.A. However, following the March 2026 futility halt of the pivotal Phase III TACTI-004 trial by the Independent Data Monitoring Committee (IDMC), Clause 7.2(c) of the contract required Immutep to refund US$10.0 million (A$14.26 million) to Dr. Reddy’s Laboratories S.A. in June 2026.
Under AASB 15 / IFRS 15, the remaining US$10.0 million satisfied all performance obligations via the delivery of core data dossiers, allowing Immutep Limited to recognize A$14,556,923 in licensing revenue, leaving zero unearned revenue on the balance sheet at fiscal year-end.
Total revenue and other income expanded 133.94% YoY to A$24,169,000, bolstered by sovereign tax offsets:
Operating expenditures shifted significantly due to clinical expansion, manufacturing scale-up, and close-out costs. Total R&D and IP expenses rose 49.73% YoY from A$61,410,533 to A$91,946,919. A granular audit reveals:
* Clinical Trial Costs: Surged 39.05% to A$62,126,265 (eftilagimod alfa: A$55,987,229; IMP761: A$2,780,033; unallocated overhead: A$3,359,003).
* Manufacturing Expenditures: Increased 143.09% to A$16,858,808 (efti 2,000L / 200L runs: A$14,370,042; IMP761 batch work: A$802,079; unallocated personnel: A$1,686,687).
* Non-Cash IP Impairment: Booked at A$3,090,650 against the carrying value of foundation patents acquired in 2014, reducing total intangible assets to A$1,492,941 (comprising A$1,382,979 in active patent rights and A$109,962 in un-impaired goodwill).
Total liquid reserves (cash, cash equivalents, and bank term deposits) fell 46.90% from A$129,692,994 to A$68,873,044. Term deposits were aggressively liquidated from A$62.28 million to A$5.20 million (-91.65%). The net operating cash burn was A$55,463,739, translating to a monthly burn of A$4,621,978 (A$13,865,935 quarterly). While trailing liquid capital provides 14.9 months of runway (extending to Q3 CY2027), management guidance indicates operations can be maintained well into 1H CY2028 based on trial wind-down savings and post-TACTI-004 corporate restructuring.
To defer immediate capital depletion, Immutep Limited structured A$6,461,083 into Non-Current Liabilities (Other Accruals), representing commercial-scale manufacturing expenditures. This arrangement acts as supplier-financed debt with a 30-month extended payment term at an interest rate of 5.0% per annum. Contributed equity grew by 0.54% to A$547,652,181 (1,473,721,306 shares), following the full conversion of the remaining 6.25% Ridgeback Convertible Notes into 7,441,304 shares (extinguishing all debt securities), the net settlement of 847,600 warrants into 33,904 shares, and 5,856,523 performance rights exercises.
Manufacturing Architecture and Global Regulatory Exposure
Immutep Limited operates an asset-light virtual biomanufacturing model, keeping net property, plant, and equipment at A$110,608 with zero internal commercial cGMP infrastructure. All production is outsourced across external CDMOs, exposing the pipeline to operational and geopolitical risks:
* Eftilagimod Alfa ("efti"): 2,000L commercial-scale single-source production is contracted to WuXi Biologics in Wuxi and Shanghai, China. European regulatory clearances for this material were secured in September 2023, followed by US FDA clearances. However, root-cause analyses post-TACTI-004 identified critical structural differences—specifically in N-glycan glycosylation patterns—between the commercial 2,000L material and the 200L scale batches used in earlier trials. Immutep Limited has contracted a 200L remediation batch with an undisclosed vendor to verify biological comparability.
* Single-Source Geopolitical Vulnerability: Section 851 of the US FY2026 National Defense Authorization Act (BIOSECURE Act), enacted in December 2025, restricts US federal agencies and grant-funded entities from contracting with designated biotechnology concerns. While WuXi Biologics has not been listed on the formal 1260H List, prospective designation by the Office of Management and Budget (OMB) by December 2026 could enforce a multi-year technology transfer to an ex-China CDMO before statutory grandfathering expires in Q3 2033.
* Autoimmune Assets & In-House Footprint: IMP761 relies on Chinese Hamster Ovary (CHO) cell lines developed by Batavia Biosciences in Leiden, Netherlands, and a 200L cGMP manufacturing process running at Northway Biotech in Vilnius, Lithuania. Core research and specialized LAG-3 reagent supply are maintained by French subsidiary Immutep S.A.S. at its laboratory near Paris, with research reagents distributed via Adipogen and Enzo.
Immutep Limited’s proprietary position is defended by 15 active patent families, down from 17 following the discontinuation of the pre-clinical small-molecule LAG-3 collaboration with Cardiff University (Family 854) and the TACTI-004 write-down:
* Composition of Matter & Regimens: Primary foundation patent Family 650 (recombinant LAG-3) expires in 2028. Extended exclusivity relies on Family 660 (chemo-immunotherapy, expiring 2034), Family 670 (efti + anti-PD-(L)1 dual combinations, expiring 2036), Family 661/662 (dosing regimens, pending to 2041/2043), and Family 671/673 (triple therapy PCTs, extending protection to 2045).
* Manufacturing QC Blocking Moats: Family 800 covers proprietary MHC Class II binding quality control release assays (granted in Canada, China, Japan, South Korea, Mexico, Russia, Israel, and New Zealand; expiring 2037). Family 810 covers cell-based potency assays for IMP761 lot release, with 7 jurisdictions granted in FY2026 (Europe, Canada, Japan, South Korea, China, Hong Kong, and Mexico; expiring 2040).
* Retained Downstream Rights: Under the Dr. Reddy’s Laboratories S.A. agreement, Immutep retains manufacturing rights and supplies unlabeled drug product at fully burdened COGS. Immutep retains exclusive commercial rights in core Western markets and Greater China (Mainland China, Hong Kong, Macau, and Taiwan, China; licensed regionally to partner EOC Pharma). Dr. Reddy’s Laboratories S.A. covers Latin America, India, Southeast Asia, Middle East, Africa, Australia/NZ, and CIS regions, with up to US$349.5 million in development, regulatory, and commercial sales milestones plus double-digit tiered royalties.
HDIN Institutional Verdict
Immutep Limited’s operational shift following the TACTI-004 futility call reveals an underlying technical vulnerability: the disconnect between 200L clinical validation and 2,000L commercial-scale bioprocessing. Management's narrative that the biological rationale remains intact—supported by mature Phase I INSIGHT-003 data (30.9 months median OS, 61.7% ORR in TPS <50% using 200L material)—is challenged by the execution delays introduced by the new 200L remediation batch run.
With the Phase III portion of AIPAC-003 in metastatic breast cancer discontinued and INSIGHT-005 terminated following the market entry of Padcev plus Keytruda, Immutep Limited has narrowed its oncology pipeline down to 1L HNSCC CPS <1 (Cohort B mOS of 17.6 months) and neoadjuvant Soft Tissue Sarcoma (51.5% tumor hyalinization versus 15% historical controls in EFTISARC-NEO). While legacy antagonist agreements with Novartis (ieramilimab) and GlaxoSmithKline (IMP731) were terminated—returning 100% intellectual property ownership to Immutep S.A.S.—these unpartnered programs require external capital to advance.
Governance structures weathered minor instability following the post-fiscal-year resignation of Audit Committee Chair Pete Meyers on October 2, 2026, leaving a temporary deficit of a designated Audit Committee Financial Expert under SEC rules. Compliance with NASDAQ Listing Rule 5450(a)(1) was secured on October 12, 2026, following a 1-for-20 ADS consolidation (1 ADS now equates to 200 ordinary shares) executed on September 28, 2026. Furthermore, a putative US shareholder class action stemming from the March 2026 stock decline was dismissed without prejudice after Immutep Limited served a Rule 11 warning letter, leaving zero legal provisions on the balance sheet.
Immutep Limited’s transition to 1H CY2028 cash sustainability hinges on proving that the new 200L remediation batch restores historical immune profiles, while navigating potential CDMO replacement mandates if WuXi Biologics faces BIOSECURE Act restrictions by late 2026.
Presentation Download & Video Access:
* Presentation Download: Click the PDF download link under 'Related Topics' to access the full institutional presentation of this report.
* Video Link: Click this link to watch the HDIN analyst briefing on YouTube.
About HDIN Research:
HDIN Research is a premier global market intelligence and strategic advisory firm specializing in institutional-grade financial analysis, supply chain audits, and macroeconomic forecasting. Our dedicated sector analysts deliver actionable, data-driven insights tailored for private equity, hedge funds, and corporate strategy teams. Visit us at http://www.hdinresearch.com.
2026 AI Transparency Footer:
This intelligence report was authored by HDIN Research analysts following a rigorous audit of official corporate filings. AI was utilized for massive-scale data synthesis and structural drafting, ensuring 100% inclusion of reported data points. All strategic insights, financial modeling, and final verdicts were verified by our editorial board to ensure professional accuracy and compliance with 2026 Google Search E-E-A-T standards.
1. The termination of the Phase III TACTI-004 trial in 1L NSCLC triggered an immediate A$3.09 million non-cash IP impairment and forced a 50% refund (US$10.0 million / A$14.26 million) to Dr. Reddy’s Laboratories S.A., although Immutep recognized A$14.56 million in net upfront licensing revenue for FY2026.
2. Clinical failure was linked to structural N-glycan variances between the commercial-scale 2,000L bioreactor run at WuXi Biologics in China and historical 200L clinical batches, prompting a contracted 200L remediation run and exposing Immutep to US BIOSECURE Act regulatory re-evaluations.
3. Total liquid capital contracted 46.90% YoY to A$68.87 million, providing a statutory cash runway of 14.9 months (to Q3 CY2027) at an annualized net monthly cash burn of A$4.62 million, offset by A$6.46 million in debt-like supplier financing via deferred CDMO payables.
Figure Immutep Limited - Institutional Strategic & Financial Benchmark (FY2025 vs FY2026)
Balance Sheet Realignment, Revenue Recognition, and Cash BurnImmutep Limited [ASX: IMM, NASDAQ: IMMP] closed FY2026 with a substantial realignment of its profit and loss statement and capital structure. In January 2026, the group received a gross upfront payment of US$20.0 million (A$28.85 million) under an exclusive out-licensing agreement with Dr. Reddy’s Laboratories S.A. However, following the March 2026 futility halt of the pivotal Phase III TACTI-004 trial by the Independent Data Monitoring Committee (IDMC), Clause 7.2(c) of the contract required Immutep to refund US$10.0 million (A$14.26 million) to Dr. Reddy’s Laboratories S.A. in June 2026.
Under AASB 15 / IFRS 15, the remaining US$10.0 million satisfied all performance obligations via the delivery of core data dossiers, allowing Immutep Limited to recognize A$14,556,923 in licensing revenue, leaving zero unearned revenue on the balance sheet at fiscal year-end.
Total revenue and other income expanded 133.94% YoY to A$24,169,000, bolstered by sovereign tax offsets:
| Revenue & Grant Income Stream | FY2025 (A$) | FY2026 (A$) | YoY Change (%) | Operational Context |
| Licensing Revenue | A$0 | A$14,556,923 | N/A | Net recognized Dr. Reddy’s upfront fee (US$10.0M) |
| Milestone Payments | A$0 | A$0 | 0.00% | Contingent milestones recognized at zero probability |
| Research & Dev. Service Fees | A$0 | A$0 | 0.00% | No contractual contract service streams |
| Research Material Sales | A$59,709 | A$38,607 | -35.34% | Direct distribution of research reagents |
| Government Grant Income | A$4,974,823 | A$5,338,572 | +7.31% | Australian, French CIR, and German Forschungszulage |
| Total Revenue & Other Income | A$10,331,373 | A$24,169,000 | +133.94% | Total recognized P&L inflows |
Operating expenditures shifted significantly due to clinical expansion, manufacturing scale-up, and close-out costs. Total R&D and IP expenses rose 49.73% YoY from A$61,410,533 to A$91,946,919. A granular audit reveals:
* Clinical Trial Costs: Surged 39.05% to A$62,126,265 (eftilagimod alfa: A$55,987,229; IMP761: A$2,780,033; unallocated overhead: A$3,359,003).
* Manufacturing Expenditures: Increased 143.09% to A$16,858,808 (efti 2,000L / 200L runs: A$14,370,042; IMP761 batch work: A$802,079; unallocated personnel: A$1,686,687).
* Non-Cash IP Impairment: Booked at A$3,090,650 against the carrying value of foundation patents acquired in 2014, reducing total intangible assets to A$1,492,941 (comprising A$1,382,979 in active patent rights and A$109,962 in un-impaired goodwill).
Total liquid reserves (cash, cash equivalents, and bank term deposits) fell 46.90% from A$129,692,994 to A$68,873,044. Term deposits were aggressively liquidated from A$62.28 million to A$5.20 million (-91.65%). The net operating cash burn was A$55,463,739, translating to a monthly burn of A$4,621,978 (A$13,865,935 quarterly). While trailing liquid capital provides 14.9 months of runway (extending to Q3 CY2027), management guidance indicates operations can be maintained well into 1H CY2028 based on trial wind-down savings and post-TACTI-004 corporate restructuring.
To defer immediate capital depletion, Immutep Limited structured A$6,461,083 into Non-Current Liabilities (Other Accruals), representing commercial-scale manufacturing expenditures. This arrangement acts as supplier-financed debt with a 30-month extended payment term at an interest rate of 5.0% per annum. Contributed equity grew by 0.54% to A$547,652,181 (1,473,721,306 shares), following the full conversion of the remaining 6.25% Ridgeback Convertible Notes into 7,441,304 shares (extinguishing all debt securities), the net settlement of 847,600 warrants into 33,904 shares, and 5,856,523 performance rights exercises.
Manufacturing Architecture and Global Regulatory Exposure
Immutep Limited operates an asset-light virtual biomanufacturing model, keeping net property, plant, and equipment at A$110,608 with zero internal commercial cGMP infrastructure. All production is outsourced across external CDMOs, exposing the pipeline to operational and geopolitical risks:
* Eftilagimod Alfa ("efti"): 2,000L commercial-scale single-source production is contracted to WuXi Biologics in Wuxi and Shanghai, China. European regulatory clearances for this material were secured in September 2023, followed by US FDA clearances. However, root-cause analyses post-TACTI-004 identified critical structural differences—specifically in N-glycan glycosylation patterns—between the commercial 2,000L material and the 200L scale batches used in earlier trials. Immutep Limited has contracted a 200L remediation batch with an undisclosed vendor to verify biological comparability.
* Single-Source Geopolitical Vulnerability: Section 851 of the US FY2026 National Defense Authorization Act (BIOSECURE Act), enacted in December 2025, restricts US federal agencies and grant-funded entities from contracting with designated biotechnology concerns. While WuXi Biologics has not been listed on the formal 1260H List, prospective designation by the Office of Management and Budget (OMB) by December 2026 could enforce a multi-year technology transfer to an ex-China CDMO before statutory grandfathering expires in Q3 2033.
* Autoimmune Assets & In-House Footprint: IMP761 relies on Chinese Hamster Ovary (CHO) cell lines developed by Batavia Biosciences in Leiden, Netherlands, and a 200L cGMP manufacturing process running at Northway Biotech in Vilnius, Lithuania. Core research and specialized LAG-3 reagent supply are maintained by French subsidiary Immutep S.A.S. at its laboratory near Paris, with research reagents distributed via Adipogen and Enzo.
Immutep Limited’s proprietary position is defended by 15 active patent families, down from 17 following the discontinuation of the pre-clinical small-molecule LAG-3 collaboration with Cardiff University (Family 854) and the TACTI-004 write-down:
* Composition of Matter & Regimens: Primary foundation patent Family 650 (recombinant LAG-3) expires in 2028. Extended exclusivity relies on Family 660 (chemo-immunotherapy, expiring 2034), Family 670 (efti + anti-PD-(L)1 dual combinations, expiring 2036), Family 661/662 (dosing regimens, pending to 2041/2043), and Family 671/673 (triple therapy PCTs, extending protection to 2045).
* Manufacturing QC Blocking Moats: Family 800 covers proprietary MHC Class II binding quality control release assays (granted in Canada, China, Japan, South Korea, Mexico, Russia, Israel, and New Zealand; expiring 2037). Family 810 covers cell-based potency assays for IMP761 lot release, with 7 jurisdictions granted in FY2026 (Europe, Canada, Japan, South Korea, China, Hong Kong, and Mexico; expiring 2040).
* Retained Downstream Rights: Under the Dr. Reddy’s Laboratories S.A. agreement, Immutep retains manufacturing rights and supplies unlabeled drug product at fully burdened COGS. Immutep retains exclusive commercial rights in core Western markets and Greater China (Mainland China, Hong Kong, Macau, and Taiwan, China; licensed regionally to partner EOC Pharma). Dr. Reddy’s Laboratories S.A. covers Latin America, India, Southeast Asia, Middle East, Africa, Australia/NZ, and CIS regions, with up to US$349.5 million in development, regulatory, and commercial sales milestones plus double-digit tiered royalties.
HDIN Institutional Verdict
Immutep Limited’s operational shift following the TACTI-004 futility call reveals an underlying technical vulnerability: the disconnect between 200L clinical validation and 2,000L commercial-scale bioprocessing. Management's narrative that the biological rationale remains intact—supported by mature Phase I INSIGHT-003 data (30.9 months median OS, 61.7% ORR in TPS <50% using 200L material)—is challenged by the execution delays introduced by the new 200L remediation batch run.
With the Phase III portion of AIPAC-003 in metastatic breast cancer discontinued and INSIGHT-005 terminated following the market entry of Padcev plus Keytruda, Immutep Limited has narrowed its oncology pipeline down to 1L HNSCC CPS <1 (Cohort B mOS of 17.6 months) and neoadjuvant Soft Tissue Sarcoma (51.5% tumor hyalinization versus 15% historical controls in EFTISARC-NEO). While legacy antagonist agreements with Novartis (ieramilimab) and GlaxoSmithKline (IMP731) were terminated—returning 100% intellectual property ownership to Immutep S.A.S.—these unpartnered programs require external capital to advance.
Governance structures weathered minor instability following the post-fiscal-year resignation of Audit Committee Chair Pete Meyers on October 2, 2026, leaving a temporary deficit of a designated Audit Committee Financial Expert under SEC rules. Compliance with NASDAQ Listing Rule 5450(a)(1) was secured on October 12, 2026, following a 1-for-20 ADS consolidation (1 ADS now equates to 200 ordinary shares) executed on September 28, 2026. Furthermore, a putative US shareholder class action stemming from the March 2026 stock decline was dismissed without prejudice after Immutep Limited served a Rule 11 warning letter, leaving zero legal provisions on the balance sheet.
Immutep Limited’s transition to 1H CY2028 cash sustainability hinges on proving that the new 200L remediation batch restores historical immune profiles, while navigating potential CDMO replacement mandates if WuXi Biologics faces BIOSECURE Act restrictions by late 2026.
Presentation Download & Video Access:
* Presentation Download: Click the PDF download link under 'Related Topics' to access the full institutional presentation of this report.
* Video Link: Click this link to watch the HDIN analyst briefing on YouTube.
About HDIN Research:
HDIN Research is a premier global market intelligence and strategic advisory firm specializing in institutional-grade financial analysis, supply chain audits, and macroeconomic forecasting. Our dedicated sector analysts deliver actionable, data-driven insights tailored for private equity, hedge funds, and corporate strategy teams. Visit us at http://www.hdinresearch.com.
2026 AI Transparency Footer:
This intelligence report was authored by HDIN Research analysts following a rigorous audit of official corporate filings. AI was utilized for massive-scale data synthesis and structural drafting, ensuring 100% inclusion of reported data points. All strategic insights, financial modeling, and final verdicts were verified by our editorial board to ensure professional accuracy and compliance with 2026 Google Search E-E-A-T standards.