Tactical Resources Corp.: Co-Production Pivot Near Sierra Blanca Quarry as Zero-Reserve Balance Sheet Signals $35M Funding Cliff
Date : 2026-11-04
Reading : 249
HDIN Executive Takeaways
1. Tactical Resources Corp. [NASDAQ: TREO] entered public markets with $0 revenue, an accumulated deficit of $16,259,562, and an explanatory auditor going-concern qualification.
2. The operational foundation relies on Sierra Blanca Quarry LLC's 1,803-acre leasehold in Hudspeth County, Texas, under Mining Lease M-114769, which expires in February 2028 without direct lessee rights.
3. Post-De-SPAC net proceeds of ~$3,300,000 leave an unfunded $15,000,000 to $35,000,000+ demonstration plant capital gap, triggering high-dilution drawdowns against a $100,000,000 standby equity facility.
Figure Tactical Resources-FY2026 Form 20-F Institutional Tear Sheet Tailings-to-Rare-Earths Business Model vs Balance Sheet Reality
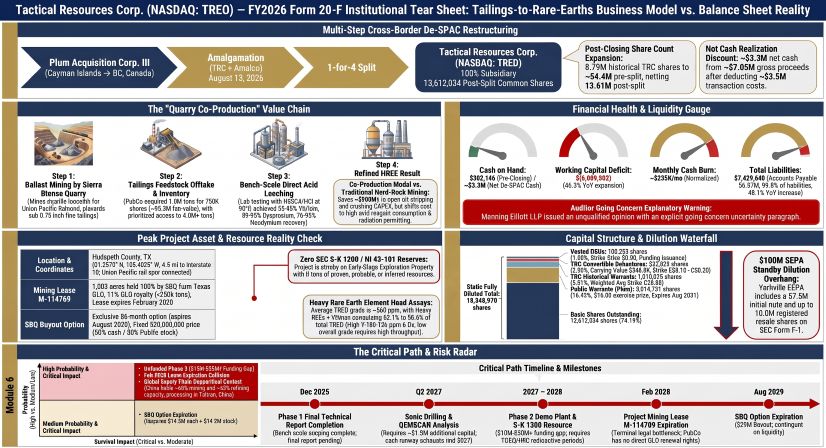 Segmental Realities, Balance Sheet Deficits, and Dilution Waterfall
Tactical Resources Corp. remains an early-stage, pre-revenue exploration entity with $0 commercial turnover across FY2025 and FY2026. Financial statements audited by independent registered public accounting firm Manning Elliott LLP (PCAOB ID: 1524) for the fiscal year ended July 31, 2026, confirmed an unqualified opinion containing an explanatory paragraph regarding substantial doubt about corporate survival.
The enterprise closed FY2026 with an operating cash outflow of $(849,848), compared to $(305,643) in FY2025—an expansion of 178.1%. Operational cash drainage was artificially compressed by delaying $2,018,123 in vendor payables. Normalized corporate operational cash burn sits at ~$235,000 per month (~$2,800,000 annually).
Table FY2026 Comparative Operating Expenses, Transaction Costs and Financial Performance Analysis
Balance sheet accounts as of July 31, 2026, registered $282,146 in cash and cash equivalents, $133,951 in receivables, $89,241 in prepaid expenses, and $44,000 in escrow deposits, generating total current and total gross assets of $549,338. Capitalized non-current assets stood at $0 following the 100% write-down of $154,242 in deferred acquisition fees triggered by the execution of a replacement Purchase and Sale Agreement on March 9, 2026.
Current liabilities rose 52.7% YoY from $4,865,455 to $7,429,640. Accounts payable and accrued liabilities totaled $6,971,443 (including $328,935 in extended payables and $238,159 / CA$333,887 in accrued executive transaction bonuses). Convertible debentures due within 12 months shifted into current liabilities at $386,868 (CA$542,369), alongside $71,329 (CA$100,000) in demand investor loans bearing 8% annual interest. The resulting working capital deficit expanded 46.3% from $(4,702,025) to $(6,880,302), leaving a current ratio of 0.074x. Financing cash inflows across FY2026 totaled $1,090,726, driven by $846,067 from non-brokered private placements, $173,772 from options exercises, and $70,887 in debt receipts.
The reverse capitalization with Plum Acquisition Corp. III closed on August 13, 2026, delivering ~$7,050,000 in gross proceeds. Outflows at settlement absorbed ~$3,500,000 in underwriting, legal, and transactional payables, alongside the inheritance of $9,300,000 in SPAC liabilities against $28,000 in acquired assets ($500 in cash). Net cash realized stood at ~$3,300,000.
A contractually required advisory fee of $1,000,000 was deferred or converted to equity after the financing failed to achieve a required $20,000,000 to $50,000,000 capital tier. The enterprise settled ~$1,300,000 in vendor payables via ~$1,590,000 in post-split common shares. Chief Executive Officer Ranjeet Sundher, Executive Chairman Kuljit Basi, and transactional advisors received 920,147 pre-split bonus shares ($828,132 fair value). On August 17, 2026, the board implemented a 1-for-4 reverse stock split, setting trading parity on the Nasdaq Capital Market under TREO on August 20, 2026.
Table Fully Diluted Capitalization Structure and Potential Share Dilution Analysis
The capital structure contains an active Standby Equity Purchase Agreement (SEPA) with YA II PN, LTD ("Yorkville"). The facility provides a $100,000,000 commitment over 36 months, initiated with a $7,500,000 pre-paid advance promissory note carrying a 5% interest coupon and a 5% original issue discount (OID), repayable in 12 months. Tranche two ($2,500,000) and tranche three ($30,000,000) remain contingent upon SEC Form F-1 resale registration effectiveness and mutual consent. The sponsor transferred 250,000 post-split shares to Yorkville as commitment consideration. Public warrants (3,014,791 units at $46.00) remain out-of-the-money, with mandatory redemption rights triggered at common stock prices of more than $72.00 ($0.04 redemption fee) or cashless exchange at more than $40.00 ($0.40 settlement rate, capped at 0.361 shares per warrant). Core pre-merger holders face staged lock-up expirations of one-third allocations upon crossing 20-day Volume-Weighted Average Price (VWAP) hurdles of $60.00, $80.00, and $100.00.
Infrastructure Topology, Feedstock Assays, and Regulatory Exposure
The Peak REE Project occupies 1,803 acres within the 2,680-acre contiguous rock quarry operated by Sierra Blanca Quarry LLC in Hudspeth County, Texas. The centroid coordinates are UTM Zone 13N, 459774 mE, 3458162 mN (Latitude 31.2570° N, Longitude 105.4225° W), located 5 miles northwest of the Town of Sierra Blanca and 68 miles southeast of the City of El Paso. Logistics integration connects 4.5 miles to Interstate 10 via a crushed aggregate service road, an operational on-site Union Pacific Railroad Company rail spur, 120/480V utility lines, and an industrial water well drilled to a depth of 1,200 feet.
Legal title to the land resides in the State of Texas General Land Office (GLO) under Mining Lease M-114769, issued to Sierra Blanca Quarry LLC on February 1, 2013, pursuant to Texas Natural Resources Code Chapter 53, Subchapter B. Tactical Resources Corp. possesses no direct legal privity with the GLO. Mining Lease M-114769 carries a strict 15-year statutory term expiring in February 2028, requiring production royalties of 11% of market value on the first 350,000 tons extracted annually and 10% thereafter, paired with an annual advance royalty minimum of $10,000 ($5.56 per acre). Two adjacent leaseholds, M-120354 (640 acres) and M-120355 (240 acres), lapsed in August 2025 without renewal. Under the Asset Purchase Agreement closed August 13, 2026, Tactical Resources Corp. issued 750,000 post-split common shares ($5,400,000 inventory fair value based on the $7.17 market close on August 20, 2026) to acquire 1,500,000 tons of processed surface ballast tailings (<0.75 inches / 1.9 centimeters).
The contract portfolio includes a 10-year Purchase and Sale Agreement granting preferential rights across 4,000,000 tons of stockpiled material and ongoing generation (~2,000 tons daily) through July 31, 2036, subject to Sierra Blanca Quarry LLC's unilateral renewal discretion, supported by a $44,000 escrow deposit with Odyssey Trust Company. The agreement grants Tactical Resources Corp. an exclusive option through August 2029 to acquire 100% of Sierra Blanca Quarry LLC membership interests for $29,000,000 (50% cash, 50% equity). The 1,500,000 tons of purchased tailings remain physically unsegregated within the operational aggregate terminal.
Table Comparative Rare Earth and Lithium Assay Results of Composite Tailings Samples
Mineralization originates from a highly fractionated, peraluminous Sierra Blanca rhyolitic laccolith. Independent Qualified Persons D. Roy Eccles (P.Geol.) and Norman Chow (P.Eng.) certified in their September 15, 2022 technical filing that the property possesses zero Mineral Resources or Mineral Reserves under SEC S-K 1300 and Canadian NI 43-101 standards. Advanced microscopy identified critical metals housed within accessory columbite, yttrofluorite, yttrocerite , thorite, cassiterite, and zircon.
Bench-scale hydrometallurgical extractions supervised by Kemetco Research Inc. in Richmond, British Columbia, alongside American Assay Laboratories Inc. in Elko, Nevada, established elemental leachability across 48-hour retention windows:
Phase 1 development consumed ~$1,000,000, covering sample characterization, agitated leaching, column permeabilities, and desktop benchmarking. Tactical Resources Corp. possesses zero on-site extraction plants, zero demonstration circuits, and zero commercial off-take agreements.
On-site operations are subject to industrial air and stormwater permits from the Texas Commission on Environmental Quality (TCEQ). Dissolution of refractory thorite concentrates radioactive thorium and uranium isotopes, which will require a formal Radioactive Material License from the TCEQ or a Source Material License from the U.S. Nuclear Regulatory Commission (NRC) under 10 CFR Part 40. Accrued Asset Retirement Obligations (ARO) across FY2025 and FY2026 stood at $0.
Corporate administration operates under Foreign Private Issuer (FPI) and Emerging Growth Company (EGC) status. Tactical Resources Corp. claims exemption from U.S. quarterly 10-Q filings, Section 16 insider reports, federal proxy rules, and Sarbanes-Oxley Act (SOX) Section 404(b) internal control attestation. The enterprise confirmed classification as a Passive Foreign Investment Company (PFIC) for FY2026. Executive capital allocations feature persistent related-party flows channeled via privately controlled entities:
The executive cadre shares Vancouver office infrastructure with Three Sixty Solar Ltd., Starfighters Space Inc., and Eagle Nuclear Energy Corp. Historical compliance checks indicate multiple historical Cease Trade Orders (CTO) issued by the British Columbia Securities Commission (BCSC) across external affiliations: Ranjeet Sundher (Bolt Metals MCTO), Kuljit Basi (Norra Metals CTO), Matthew Chatterton (Isracann Biosciences CTO / Vurger Group winding-up), and Manavdeep Mukhija (Three Sixty Solar CTO). CFO Jenny Kuan is entitled to a 12-month base severance payout ($90,000) under change-of-control conditions.
HDIN Institutional Verdict
Tactical Resources Corp. presents an irreconcilable timing mismatch between its hydrometallurgical development timeline and its mineral tenure runway. While ambient acid extractions demonstrate high laboratory recoveries for dysprosium and yttrium (92% to 97%), the absolute resource grade of ~360 ppm TREO (0.036%) requires immense reagent volumes. Processing thousands of tons of feed to yield single-digit tons of rare earth oxides transfers capital expenditures away from surface mining toward acid consumption and effluent management.
The corporate runway exhibits structural solvency deficits:
Execution of the planned 12- to 24-month Phase 2 pilot optimization program will intersect with the statutory expiration of Mining Lease M-114769 in February 2028. Because Tactical Resources Corp. holds no contractual privity with the State of Texas General Land Office and relies on Sierra Blanca Quarry LLC maintaining commercial rail-ballast off-take with Union Pacific Railroad Company, the asset lacks sovereign tenure stability.
Bridging the $15,000,000 to $35,000,000+ pilot plant funding gap via the $100,000,000 Yorkville SEPA facility requires continuous share resale registrations via Form F-1. This creates programmatic equity dilution against an issued base of 13,612,034 shares, depressing public valuations while executive fees continue to draw fixed capital from internal cash reserves.
Presentation Download & Video Access
- Presentation Download: Click the PDF download link under 'Related Topics' to access the full institutional presentation of this report.
- Video Link: Click this link to watch the HDIN analyst briefing on YouTube.
About HDIN Research
HDIN Research is a premier global market intelligence and strategic advisory firm specializing in institutional-grade financial analysis, supply chain audits, and macroeconomic forecasting. Our dedicated sector analysts deliver actionable, data-driven insights tailored for private equity, hedge funds, and corporate strategy teams. Visit us at http://www.hdinresearch.com.
2026 AI Transparency Footer
"This intelligence report was authored by HDIN Research analysts following a rigorous audit of official corporate filings. AI was utilized for massive-scale data synthesis and structural drafting, ensuring 100% inclusion of reported data points. All strategic insights, financial modeling, and final verdicts were verified by our editorial board to ensure professional accuracy and compliance with 2026 Google Search E-E-A-T standards."
1. Tactical Resources Corp. [NASDAQ: TREO] entered public markets with $0 revenue, an accumulated deficit of $16,259,562, and an explanatory auditor going-concern qualification.
2. The operational foundation relies on Sierra Blanca Quarry LLC's 1,803-acre leasehold in Hudspeth County, Texas, under Mining Lease M-114769, which expires in February 2028 without direct lessee rights.
3. Post-De-SPAC net proceeds of ~$3,300,000 leave an unfunded $15,000,000 to $35,000,000+ demonstration plant capital gap, triggering high-dilution drawdowns against a $100,000,000 standby equity facility.
Figure Tactical Resources-FY2026 Form 20-F Institutional Tear Sheet Tailings-to-Rare-Earths Business Model vs Balance Sheet Reality
Segmental Realities, Balance Sheet Deficits, and Dilution WaterfallTactical Resources Corp. remains an early-stage, pre-revenue exploration entity with $0 commercial turnover across FY2025 and FY2026. Financial statements audited by independent registered public accounting firm Manning Elliott LLP (PCAOB ID: 1524) for the fiscal year ended July 31, 2026, confirmed an unqualified opinion containing an explanatory paragraph regarding substantial doubt about corporate survival.
The enterprise closed FY2026 with an operating cash outflow of $(849,848), compared to $(305,643) in FY2025—an expansion of 178.1%. Operational cash drainage was artificially compressed by delaying $2,018,123 in vendor payables. Normalized corporate operational cash burn sits at ~$235,000 per month (~$2,800,000 annually).
Table FY2026 Comparative Operating Expenses, Transaction Costs and Financial Performance Analysis
| Operating Statement & Cash Metric | FY2026 (USD) | FY2025 (USD) | YoY Delta (%) | Operational P&L Share (%) |
| Commercial Turnover (Revenue) | $0 | $0 | 0.0% | — |
| Professional Fees | $675,212 | $173,257 | +289.7% | 44.55% |
| Consulting Fees | $291,902 | $448,272 | -34.9% | 19.26% |
| Travel Expenses | $165,140 | $0 | N/A | 10.90% |
| Property Investigation Costs | $71,754 | $118,239 | -39.3% | 4.73% |
| (Cost-Sharing Cost Recovery) | $(20,865) | $0 | N/A | (1.38%) |
| Foreign Exchange Loss | $67,007 | $13,518 | +395.7% | 4.42% |
| General & Administrative (SG&A) | $57,132 | $64,361 | -11.2% | 3.77% |
| Stock-Based Compensation | $0 | $1,151,838 | -100.0% | 0.00% |
| Total Operating Expenses | $1,515,552 | $2,086,889 | -27.4% | 100.00% |
| De-SPAC Transaction Costs | $1,331,383 | $2,630,219 | -49.4% | Below Operating Line |
| Deferred Acquisition Cost Impairment | $154,242 | $0 | N/A | Below Operating Line |
| Gain on Accounts Payable Extension | $(47,982) | $0 | N/A | Below Operating Line (16.5% Disc.) |
| Net Loss | $(2,932,330) | $(4,717,108) | -37.8% | — |
| Basic & Diluted Loss Per Share | $(0.36) | $(0.66) | +45.5% | — |
| Accumulated Balance Sheet Deficit | $(16,259,562) | $(13,327,232) | +22.0% | Cumulative |
Balance sheet accounts as of July 31, 2026, registered $282,146 in cash and cash equivalents, $133,951 in receivables, $89,241 in prepaid expenses, and $44,000 in escrow deposits, generating total current and total gross assets of $549,338. Capitalized non-current assets stood at $0 following the 100% write-down of $154,242 in deferred acquisition fees triggered by the execution of a replacement Purchase and Sale Agreement on March 9, 2026.
Current liabilities rose 52.7% YoY from $4,865,455 to $7,429,640. Accounts payable and accrued liabilities totaled $6,971,443 (including $328,935 in extended payables and $238,159 / CA$333,887 in accrued executive transaction bonuses). Convertible debentures due within 12 months shifted into current liabilities at $386,868 (CA$542,369), alongside $71,329 (CA$100,000) in demand investor loans bearing 8% annual interest. The resulting working capital deficit expanded 46.3% from $(4,702,025) to $(6,880,302), leaving a current ratio of 0.074x. Financing cash inflows across FY2026 totaled $1,090,726, driven by $846,067 from non-brokered private placements, $173,772 from options exercises, and $70,887 in debt receipts.
The reverse capitalization with Plum Acquisition Corp. III closed on August 13, 2026, delivering ~$7,050,000 in gross proceeds. Outflows at settlement absorbed ~$3,500,000 in underwriting, legal, and transactional payables, alongside the inheritance of $9,300,000 in SPAC liabilities against $28,000 in acquired assets ($500 in cash). Net cash realized stood at ~$3,300,000.
A contractually required advisory fee of $1,000,000 was deferred or converted to equity after the financing failed to achieve a required $20,000,000 to $50,000,000 capital tier. The enterprise settled ~$1,300,000 in vendor payables via ~$1,590,000 in post-split common shares. Chief Executive Officer Ranjeet Sundher, Executive Chairman Kuljit Basi, and transactional advisors received 920,147 pre-split bonus shares ($828,132 fair value). On August 17, 2026, the board implemented a 1-for-4 reverse stock split, setting trading parity on the Nasdaq Capital Market under TREO on August 20, 2026.
Table Fully Diluted Capitalization Structure and Potential Share Dilution Analysis
| Capital Tranche & Dilutive Instrument | Underlying Common Units | Fully Diluted Ownership (%) | Conversion Terms & Structural Triggers |
| Issued & Outstanding Common Shares | 13,612,034 | 74.19% | Base voting equity float post-split |
| Plum Public Warrants | 3,014,791 | 16.43% | Strike: $46.00; Expiry: Aug 13, 2031; Call: $72.00 |
| Legacy TRC Warrants | 1,010,029 | 5.51% | Weighted average: CA
0.75–CA$7.29) |
| TRC Convertible Debentures | 532,823 | 2.90% | Strike: CA
0.20; Expiry: 2026–2027 |
| Vested Restricted Share Units (RSUs) | 189,293 | 1.03% | Nil exercise price ($0.00); Expiry: March 2027 |
| Fully Diluted Share Pool | 18,348,970 | 100.00% | 34.8% Structural Overhang |
| Yorkville SEPA Registered Resale Float | 10,000,000 | Secondary Registration | Form F-1 continuous distribution |
| Omnibus Incentive Plan Reserve | 3,567,448 | Authorized Unallocated | 20% rolling equity cap structure |
The capital structure contains an active Standby Equity Purchase Agreement (SEPA) with YA II PN, LTD ("Yorkville"). The facility provides a $100,000,000 commitment over 36 months, initiated with a $7,500,000 pre-paid advance promissory note carrying a 5% interest coupon and a 5% original issue discount (OID), repayable in 12 months. Tranche two ($2,500,000) and tranche three ($30,000,000) remain contingent upon SEC Form F-1 resale registration effectiveness and mutual consent. The sponsor transferred 250,000 post-split shares to Yorkville as commitment consideration. Public warrants (3,014,791 units at $46.00) remain out-of-the-money, with mandatory redemption rights triggered at common stock prices of more than $72.00 ($0.04 redemption fee) or cashless exchange at more than $40.00 ($0.40 settlement rate, capped at 0.361 shares per warrant). Core pre-merger holders face staged lock-up expirations of one-third allocations upon crossing 20-day Volume-Weighted Average Price (VWAP) hurdles of $60.00, $80.00, and $100.00.
Infrastructure Topology, Feedstock Assays, and Regulatory Exposure
The Peak REE Project occupies 1,803 acres within the 2,680-acre contiguous rock quarry operated by Sierra Blanca Quarry LLC in Hudspeth County, Texas. The centroid coordinates are UTM Zone 13N, 459774 mE, 3458162 mN (Latitude 31.2570° N, Longitude 105.4225° W), located 5 miles northwest of the Town of Sierra Blanca and 68 miles southeast of the City of El Paso. Logistics integration connects 4.5 miles to Interstate 10 via a crushed aggregate service road, an operational on-site Union Pacific Railroad Company rail spur, 120/480V utility lines, and an industrial water well drilled to a depth of 1,200 feet.
Legal title to the land resides in the State of Texas General Land Office (GLO) under Mining Lease M-114769, issued to Sierra Blanca Quarry LLC on February 1, 2013, pursuant to Texas Natural Resources Code Chapter 53, Subchapter B. Tactical Resources Corp. possesses no direct legal privity with the GLO. Mining Lease M-114769 carries a strict 15-year statutory term expiring in February 2028, requiring production royalties of 11% of market value on the first 350,000 tons extracted annually and 10% thereafter, paired with an annual advance royalty minimum of $10,000 ($5.56 per acre). Two adjacent leaseholds, M-120354 (640 acres) and M-120355 (240 acres), lapsed in August 2025 without renewal. Under the Asset Purchase Agreement closed August 13, 2026, Tactical Resources Corp. issued 750,000 post-split common shares ($5,400,000 inventory fair value based on the $7.17 market close on August 20, 2026) to acquire 1,500,000 tons of processed surface ballast tailings (<0.75 inches / 1.9 centimeters).
The contract portfolio includes a 10-year Purchase and Sale Agreement granting preferential rights across 4,000,000 tons of stockpiled material and ongoing generation (~2,000 tons daily) through July 31, 2036, subject to Sierra Blanca Quarry LLC's unilateral renewal discretion, supported by a $44,000 escrow deposit with Odyssey Trust Company. The agreement grants Tactical Resources Corp. an exclusive option through August 2029 to acquire 100% of Sierra Blanca Quarry LLC membership interests for $29,000,000 (50% cash, 50% equity). The 1,500,000 tons of purchased tailings remain physically unsegregated within the operational aggregate terminal.
Table Comparative Rare Earth and Lithium Assay Results of Composite Tailings Samples
| Composite Feedstock Sample | Sample Mass (kg) | TREO Head Assay (ppm) | LREE Content (ppm) | HREE+Y Fraction (ppm) | Lithium Grade (ppm) | Specific Gravity (g/cm³) |
| Tails 1 Composite | 56.7 kg | 366.4 mg/kg | 94.1 mg/kg | 196.4 mg/kg (53.6%) | 189 mg/kg | 2.19 – 3.26 |
| Tails 2 Composite | 30.6 kg | 358.0 mg/kg | 93.3 mg/kg | 190.4 mg/kg (53.2%) | 188 mg/kg | 2.67 (Mean) |
| Tails 3 Composite | 45.0 kg | 362.1 mg/kg | 98.9 mg/kg | 188.6 mg/kg (52.1%) | 193 mg/kg | 2.19 – 3.26 |
Mineralization originates from a highly fractionated, peraluminous Sierra Blanca rhyolitic laccolith. Independent Qualified Persons D. Roy Eccles (P.Geol.) and Norman Chow (P.Eng.) certified in their September 15, 2022 technical filing that the property possesses zero Mineral Resources or Mineral Reserves under SEC S-K 1300 and Canadian NI 43-101 standards. Advanced microscopy identified critical metals housed within accessory columbite, yttrofluorite, yttrocerite , thorite, cassiterite, and zircon.
Bench-scale hydrometallurgical extractions supervised by Kemetco Research Inc. in Richmond, British Columbia, alongside American Assay Laboratories Inc. in Elko, Nevada, established elemental leachability across 48-hour retention windows:
| Metallurgical Process Flowsheet | Chemical Concentration & Temp. | Targeted Rare Earth Components | 48-Hour Recovery Rate (%) |
| Ambient Agitation Leach |
, Ambient |
Yttrium (Y) / Dysprosium (Dy) | 93% – 97% / 92% – 95% |
| Neodymium (Nd) / Light REEs | 75% – 84% / 79% – 81% | ||
| Total HREE+Y / Lithium (Li) | 92% – 96% / 27% – 28% | ||
| Heated Sulfuric Leach |
, 90°C |
Y (93–94%) / Dy (89–90%) |
: 89% – 90% |
| Nd (76–80%) / Lithium (Li) | Li: 33% – 42% | ||
| Heated Hydrochloric Leach |
, 90°C |
Y (94–96%) / Dy (93–95%) |
: 95.6% – 96.1% |
| Nd (94–95%) / Lithium (Li) | Li: 66.2% – 87.6% | ||
| Sulfation Bake-Water Leach |
, Aqueous |
Y (54–77%) / Dy (41–70%) | Li: up to 95% |
Phase 1 development consumed ~$1,000,000, covering sample characterization, agitated leaching, column permeabilities, and desktop benchmarking. Tactical Resources Corp. possesses zero on-site extraction plants, zero demonstration circuits, and zero commercial off-take agreements.
On-site operations are subject to industrial air and stormwater permits from the Texas Commission on Environmental Quality (TCEQ). Dissolution of refractory thorite concentrates radioactive thorium and uranium isotopes, which will require a formal Radioactive Material License from the TCEQ or a Source Material License from the U.S. Nuclear Regulatory Commission (NRC) under 10 CFR Part 40. Accrued Asset Retirement Obligations (ARO) across FY2025 and FY2026 stood at $0.
Corporate administration operates under Foreign Private Issuer (FPI) and Emerging Growth Company (EGC) status. Tactical Resources Corp. claims exemption from U.S. quarterly 10-Q filings, Section 16 insider reports, federal proxy rules, and Sarbanes-Oxley Act (SOX) Section 404(b) internal control attestation. The enterprise confirmed classification as a Passive Foreign Investment Company (PFIC) for FY2026. Executive capital allocations feature persistent related-party flows channeled via privately controlled entities:
The executive cadre shares Vancouver office infrastructure with Three Sixty Solar Ltd., Starfighters Space Inc., and Eagle Nuclear Energy Corp. Historical compliance checks indicate multiple historical Cease Trade Orders (CTO) issued by the British Columbia Securities Commission (BCSC) across external affiliations: Ranjeet Sundher (Bolt Metals MCTO), Kuljit Basi (Norra Metals CTO), Matthew Chatterton (Isracann Biosciences CTO / Vurger Group winding-up), and Manavdeep Mukhija (Three Sixty Solar CTO). CFO Jenny Kuan is entitled to a 12-month base severance payout ($90,000) under change-of-control conditions.
HDIN Institutional Verdict
Tactical Resources Corp. presents an irreconcilable timing mismatch between its hydrometallurgical development timeline and its mineral tenure runway. While ambient acid extractions demonstrate high laboratory recoveries for dysprosium and yttrium (92% to 97%), the absolute resource grade of ~360 ppm TREO (0.036%) requires immense reagent volumes. Processing thousands of tons of feed to yield single-digit tons of rare earth oxides transfers capital expenditures away from surface mining toward acid consumption and effluent management.
The corporate runway exhibits structural solvency deficits:
Execution of the planned 12- to 24-month Phase 2 pilot optimization program will intersect with the statutory expiration of Mining Lease M-114769 in February 2028. Because Tactical Resources Corp. holds no contractual privity with the State of Texas General Land Office and relies on Sierra Blanca Quarry LLC maintaining commercial rail-ballast off-take with Union Pacific Railroad Company, the asset lacks sovereign tenure stability.
Bridging the $15,000,000 to $35,000,000+ pilot plant funding gap via the $100,000,000 Yorkville SEPA facility requires continuous share resale registrations via Form F-1. This creates programmatic equity dilution against an issued base of 13,612,034 shares, depressing public valuations while executive fees continue to draw fixed capital from internal cash reserves.
Presentation Download & Video Access
- Presentation Download: Click the PDF download link under 'Related Topics' to access the full institutional presentation of this report.
- Video Link: Click this link to watch the HDIN analyst briefing on YouTube.
About HDIN Research
HDIN Research is a premier global market intelligence and strategic advisory firm specializing in institutional-grade financial analysis, supply chain audits, and macroeconomic forecasting. Our dedicated sector analysts deliver actionable, data-driven insights tailored for private equity, hedge funds, and corporate strategy teams. Visit us at http://www.hdinresearch.com.
2026 AI Transparency Footer
"This intelligence report was authored by HDIN Research analysts following a rigorous audit of official corporate filings. AI was utilized for massive-scale data synthesis and structural drafting, ensuring 100% inclusion of reported data points. All strategic insights, financial modeling, and final verdicts were verified by our editorial board to ensure professional accuracy and compliance with 2026 Google Search E-E-A-T standards."