Mobix Labs, Inc.: High-Yield Defense Pivot Strains Liquidity as 9M 2026 Top-Line Contracts 54.7% Amid Toxic Overhang Stack
Date : 2026-11-05
Reading : 355
HDIN Executive Takeaways
1. Mobix Labs, Inc. [NASDAQ: MOBX] recorded a 54.7% YoY top-line contraction to $3.63 million in 9M 2026, leaving $2.14 million in cash against an operating burn rate of $1.64 million per month (~40 days of runway).
2. Operating on an asset-light fabless model reliant on offshore foundries in Taiwan, Province of China, the company is executing an inorganic pivot toward U.S. national security and defense interconnects, terminating its $15.0 million Vision Aerial merger while advancing an all-stock transaction for Special Project Delivery, Inc.
3. Institutional risk centers on extreme equity dilution: a 22.04 million share overhang stack represents 93.5% of outstanding Class A common stock, compounded by floating-discount convertible structures (82%–85% VWAP) and five persistent internal control material weaknesses.
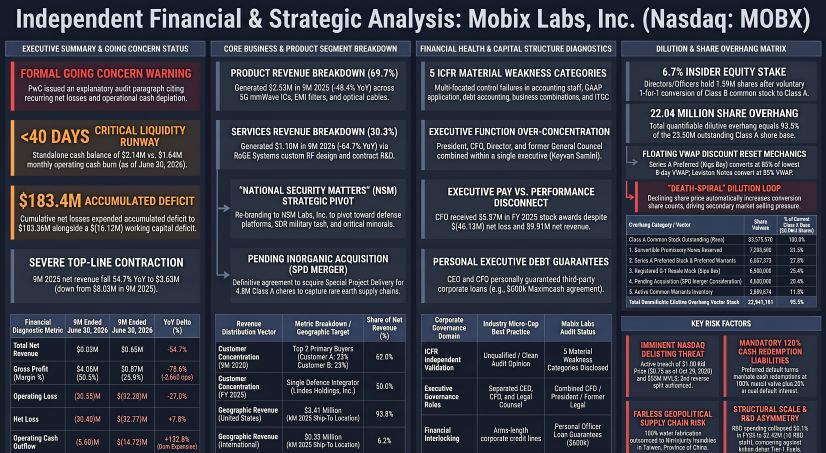
Figure Mobix Labs Inc Financial and Strategic Analysis Summary
 Segmental Realities, Revenue Decay, and Capital Structure Squeeze
Mobix Labs' SEC Form S-1 registration filing details acute operational and balance sheet stress. For the nine months ended June 30, 2026, consolidated net revenue dropped 54.7% YoY to $3.634 million from $8.030 million in 9M 2025. Gross margin experienced severe compression, declining 2,660 basis points from 50.5% to 23.9%, driven by lower manufacturing absorption in hardware and customer project delays in custom engineering services.
* Balance Sheet Distress & Going Concern: Standalone cash and cash equivalents stood at $2.142 million as of June 30, 2026, down from $3.273 million as of September 30, 2025. With a nine-month operating cash outflow of $(14.719) million (~$1.635 million per month), the company operates with approximately 1.3 months (~40 days) of liquidity runway. PricewaterhouseCoopers LLP issued an explanatory going-concern paragraph, referencing recurring losses, negative cash flows, an accumulated deficit of $183.361 million, and a negative working capital deficit of $(16.117) million ($6.034 million current assets vs. $22.151 million current liabilities).
* R&D Disconnect: R&D expenses contracted 58.1% YoY in FY 2025 to $2.419 million, and another 29.5% YoY in 9M 2026 to $1.281 million. Although R&D intensity measured 35.3% of revenue in 9M 2026, this metric is inflated by top-line erosion. The enterprise operates with 10 dedicated R&D engineers out of 40 total U.S. personnel.
* Toxic Debt Architecture: To finance ongoing cash burn, Mobix Labs entered into agreements with Kips Bay Select, LP (Series A 10% Convertible Preferred Stock) and Leviston Resources, LLC (Senior Secured Convertible Notes). The Series A Preferred features a floating conversion price set at 82% of the lowest 8-day Volume Weighted Average Price (VWAP), an automatic Stated Value adjustment ratchet if market price drops below conversion price, full-ratchet anti-dilution, and a mandatory 120% cash redemption clause carrying 25% default interest. Leviston notes carry an 85% lowest 8-day VWAP floating conversion floor and an automatic 125% principal escalation upon default.
* Dilution Mechanics: The current registration statement registers 6,000,000 Class A common shares for resale by Kips Bay Select, LP (25.4% of the 23,576,570 shares outstanding as of October 14, 2026). The total quantifiable overhang stack stands at 22,041,181 shares (93.5% of the Class A common stock base), including 7,298,650 shares reserved under convertible notes, 6,367,975 shares underlying preferred stock and warrants, 4,800,000 shares committed for the Special Project Delivery merger, 2,589,874 outstanding common warrants ($0.10 to $57.90 strike), and 984,682 equity incentive awards.
Geographic Shipments, Customer Exposure, and Infrastructure Footprint
Mobix Labs records its geographic revenue based on customer ship-to locations, observing UN regional designations. The top line is heavily concentrated in North America:
* Extreme Commercial Concentration: A single defense integrator, Leidos Holdings, Inc., accounted for approximately 50% of total net revenue in FY 2025 ($9.912 million consolidated net revenue). In 9M 2026, two customers accounted for 62% of consolidated net revenue (Customer A at 33% and Customer B at 29%). Customer A and Customer B represented 47% of net accounts receivable as of June 30, 2026. The 64.7% contraction in 9M 2026 services revenue was directly precipitated by project delays following Customer A's internal restructuring announced in April 2026.
* Physical Operational Footprint: Mobix Labs operates a leased 2,713 sq. ft. executive headquarters in Irvine, California (lease term expiring March 2027) and a leased 6,149 sq. ft. manufacturing facility in Irvine, California, dedicated to assembling electromagnetic interference (EMI) filtering inserts and filtered connectors. In March 2025, the company abandoned a 19,436 sq. ft. Irvine facility (formal lease termination in April 2025), booking a $0.725 million leasehold impairment charge.
* Foundry and Supply Chain Reliance: Mobix Labs utilizes a fabless architecture for its 5G mmWave transceivers and beamformer ICs, outsourcing 100% of wafer fabrication to offshore commercial semiconductor foundries located in Taiwan, Province of China. Advanced packaging, wafer sawing, and testing are allocated to third-party Outsourced Semiconductor Assembly and Test (OSAT) contractors in the Asia-Pacific region.
* Inorganic Infrastructure Integration:
* EMI Solutions, Inc. (Acquired December 2023 for $10.897 million total consideration: $8.856 million equity, $2.041 million NPV cash): Contributed $2.774 million in revenue in FY 2025. Currently subject to litigation from former owners (Ydens Holdings, LLC / Robert Ydens) alleging merger agreement breaches, unpaid retention bonuses, and California Labor Code wage claims. Deferred cash consideration owed stands at $2.093 million as of June 30, 2026 ($523k past due).
* RaGE Systems, Inc. (Acquired May 2024 for $9.518 million initial consideration: $7.682 million equity, $1.836 million NPV cash, plus up to $8.0 million earnouts): Contributed $5.836 million in revenue and $0.586 million in net income in FY 2025. Carries an accrued earnout liability of $2.000 million as of June 30, 2026.
* Terminated M&A: The proposed $15.0 million acquisition of Vision Aerial, Inc. ($12.0 million stock, $3.0 million cash) was mutually terminated on October 14, 2026, due to an inability to complete financial statement audit deliverables.
* Pending M&A: On August 13, 2026, the company entered into an agreement to acquire Special Project Delivery, Inc. (SPD) for 4,800,000 Class A common shares. The transaction is contingent upon SPD completing its acquisition of Winner Water Services, Inc., securing exposure to U.S. rare earth element assets and the Ex-Im Bank-backed "Project Vault."
HDIN Institutional Verdict
Mobix Labs' attempted strategic transformation from a struggling fabless semiconductor designer into a national security platform (under the planned corporate rebranding to "NSM Labs, Inc.") is constrained by debt overhang and governance vulnerabilities. While the company retains qualified-vendor status for defense-grade EMI filtering components, inorganic growth has replaced organic semiconductor monetization: acquired entities contributed $8.610 million of the company's $9.912 million revenue in FY 2025.
Balance sheet assets are heavily weighted toward goodwill ($16.066 million) and net intangibles ($12.324 million), representing 81.3% of total assets as of June 30, 2026. Management has formally guided toward an impending non-cash goodwill impairment charge of up to $5.5 million in Q4 2026.
Governance integrity remains compromised by five comprehensive categories of Internal Control over Financial Reporting (ICFR) material weaknesses, unresolved Information Technology General Control (ITGC) access deficiencies, combined executive oversight (CFO Keyvan Samini serving concurrently as President, Director, and former General Counsel), and executive personal guarantees on third-party debt. Furthermore, insider beneficial ownership of Class A common stock stands at just 6.7% following the August 2026 elimination of the 10-vote-per-share Class B structure. With common equity trading below $1.00 ($0.75 as of October 29, 2026) following a 1-for-10 reverse split in April 2026, stockholders have authorized an additional reverse split up to 1-for-20. Lacking positive cash flow and constrained by an active Nasdaq Market Value of Listed Securities deficiency, the structural inclusion of floating 82%–85% VWAP convertible notes creates unhedged, mathematically unbounded dilution risks for common equity participants.
Presentation Download & Video Access:
- Presentation Download: Click the PDF download link under 'Related Topics' to access the full institutional presentation of this report.
- Video Link: Click this link to watch the HDIN analyst briefing on YouTube.
About HDIN Research:
HDIN Research is a premier global market intelligence and strategic advisory firm specializing in institutional-grade financial analysis, supply chain audits, and macroeconomic forecasting. Our dedicated sector analysts deliver actionable, data-driven insights tailored for private equity, hedge funds, and corporate strategy teams. Visit us at http://www.hdinresearch.com.
2026 AI Transparency Footer:
"This intelligence report was authored by HDIN Research analysts following a rigorous audit of official corporate filings. AI was utilized for massive-scale data synthesis and structural drafting, ensuring 100% inclusion of reported data points. All strategic insights, financial modeling, and final verdicts were verified by our editorial board to ensure professional accuracy and compliance with 2026 Google Search E-E-A-T standards."
1. Mobix Labs, Inc. [NASDAQ: MOBX] recorded a 54.7% YoY top-line contraction to $3.63 million in 9M 2026, leaving $2.14 million in cash against an operating burn rate of $1.64 million per month (~40 days of runway).
2. Operating on an asset-light fabless model reliant on offshore foundries in Taiwan, Province of China, the company is executing an inorganic pivot toward U.S. national security and defense interconnects, terminating its $15.0 million Vision Aerial merger while advancing an all-stock transaction for Special Project Delivery, Inc.
3. Institutional risk centers on extreme equity dilution: a 22.04 million share overhang stack represents 93.5% of outstanding Class A common stock, compounded by floating-discount convertible structures (82%–85% VWAP) and five persistent internal control material weaknesses.
Figure Mobix Labs Inc Financial and Strategic Analysis Summary
Segmental Realities, Revenue Decay, and Capital Structure SqueezeMobix Labs' SEC Form S-1 registration filing details acute operational and balance sheet stress. For the nine months ended June 30, 2026, consolidated net revenue dropped 54.7% YoY to $3.634 million from $8.030 million in 9M 2025. Gross margin experienced severe compression, declining 2,660 basis points from 50.5% to 23.9%, driven by lower manufacturing absorption in hardware and customer project delays in custom engineering services.
Table Title 9M FY2026 vs. 9M FY2025 Operating Performance, Profitability and Cash Burn Analysis
| Operating Statement Breakdown (USD in Thousands) | 9M Ended June 30, 2026 | 9M Ended June 30, 2025 | YoY Change (%) / Basis Points |
| Product Revenue | $2,534 | $4,911 | -48.4% |
| Services Revenue | $1,100 | $3,119 | -64.7% |
| Total Net Revenue | $3,634 | $8,030 | -54.7% |
| Cost of Net Revenue | $2,767 | $3,974 | -30.4% |
| Gross Profit | $867 | $4,056 | -78.6% |
| Gross Margin (%) | 23.9% | 50.5% | -2,660 bps |
| Research & Development (R&D) | $1,281 | $1,816 | -29.5% |
| Selling, General & Administrative (SG&A) | $21,864 | $32,043 | -31.8% |
| Impairment / Restructuring Charges | $0 | $725 | N/A |
| Total Operating Expenses | $23,145 | $34,584 | -33.1% |
| Operating Loss | $(22,278) | $(30,528) | -27.0% |
| Interest Expense | $3,637 | $1,032 | +252.4% |
| Loss on Extinguishment of Notes Payable | $4,215 | $0 | N/A |
| Loss on Derivative/Preferred Warrant Issuance | $3,711 | $0 | N/A |
| Net Loss | $(32,773) | $(30,402) | +7.8% |
| Net Cash Used in Operating Activities | $(14,719) | $(5,600) | +162.8% (Burn Expansion) |
* Balance Sheet Distress & Going Concern: Standalone cash and cash equivalents stood at $2.142 million as of June 30, 2026, down from $3.273 million as of September 30, 2025. With a nine-month operating cash outflow of $(14.719) million (~$1.635 million per month), the company operates with approximately 1.3 months (~40 days) of liquidity runway. PricewaterhouseCoopers LLP issued an explanatory going-concern paragraph, referencing recurring losses, negative cash flows, an accumulated deficit of $183.361 million, and a negative working capital deficit of $(16.117) million ($6.034 million current assets vs. $22.151 million current liabilities).
* R&D Disconnect: R&D expenses contracted 58.1% YoY in FY 2025 to $2.419 million, and another 29.5% YoY in 9M 2026 to $1.281 million. Although R&D intensity measured 35.3% of revenue in 9M 2026, this metric is inflated by top-line erosion. The enterprise operates with 10 dedicated R&D engineers out of 40 total U.S. personnel.
* Toxic Debt Architecture: To finance ongoing cash burn, Mobix Labs entered into agreements with Kips Bay Select, LP (Series A 10% Convertible Preferred Stock) and Leviston Resources, LLC (Senior Secured Convertible Notes). The Series A Preferred features a floating conversion price set at 82% of the lowest 8-day Volume Weighted Average Price (VWAP), an automatic Stated Value adjustment ratchet if market price drops below conversion price, full-ratchet anti-dilution, and a mandatory 120% cash redemption clause carrying 25% default interest. Leviston notes carry an 85% lowest 8-day VWAP floating conversion floor and an automatic 125% principal escalation upon default.
* Dilution Mechanics: The current registration statement registers 6,000,000 Class A common shares for resale by Kips Bay Select, LP (25.4% of the 23,576,570 shares outstanding as of October 14, 2026). The total quantifiable overhang stack stands at 22,041,181 shares (93.5% of the Class A common stock base), including 7,298,650 shares reserved under convertible notes, 6,367,975 shares underlying preferred stock and warrants, 4,800,000 shares committed for the Special Project Delivery merger, 2,589,874 outstanding common warrants ($0.10 to $57.90 strike), and 984,682 equity incentive awards.
Geographic Shipments, Customer Exposure, and Infrastructure Footprint
Mobix Labs records its geographic revenue based on customer ship-to locations, observing UN regional designations. The top line is heavily concentrated in North America:
| Geographic Revenue Breakdown (USD in Thousands) | 9M 2026 Revenue | 9M 2026 Share (%) | 9M 2025 Revenue | 9M 2025 Share (%) | FY 2025 Revenue | FY 2025 Share (%) | FY 2024 Revenue | FY 2024 Share (%) |
| United States | $3,408 | 93.8% | $7,421 | 92.4% | $9,152 | 92.3% | $5,699 | 88.5% |
| China (Ship-to channels) | $0 | 0.0% | $0 | 0.0% | $0 | 0.0% | $288 | 4.5% |
| Other International | $226 | 6.2% | $609 | 7.6% | $760 | 7.7% | $455 | 7.0% |
| Total Net Revenue | $3,634 | 100.0% | $8,030 | 100.0% | $9,912 | 100.0% | $6,442 | 100.0% |
* Extreme Commercial Concentration: A single defense integrator, Leidos Holdings, Inc., accounted for approximately 50% of total net revenue in FY 2025 ($9.912 million consolidated net revenue). In 9M 2026, two customers accounted for 62% of consolidated net revenue (Customer A at 33% and Customer B at 29%). Customer A and Customer B represented 47% of net accounts receivable as of June 30, 2026. The 64.7% contraction in 9M 2026 services revenue was directly precipitated by project delays following Customer A's internal restructuring announced in April 2026.
* Physical Operational Footprint: Mobix Labs operates a leased 2,713 sq. ft. executive headquarters in Irvine, California (lease term expiring March 2027) and a leased 6,149 sq. ft. manufacturing facility in Irvine, California, dedicated to assembling electromagnetic interference (EMI) filtering inserts and filtered connectors. In March 2025, the company abandoned a 19,436 sq. ft. Irvine facility (formal lease termination in April 2025), booking a $0.725 million leasehold impairment charge.
* Foundry and Supply Chain Reliance: Mobix Labs utilizes a fabless architecture for its 5G mmWave transceivers and beamformer ICs, outsourcing 100% of wafer fabrication to offshore commercial semiconductor foundries located in Taiwan, Province of China. Advanced packaging, wafer sawing, and testing are allocated to third-party Outsourced Semiconductor Assembly and Test (OSAT) contractors in the Asia-Pacific region.
* Inorganic Infrastructure Integration:
* EMI Solutions, Inc. (Acquired December 2023 for $10.897 million total consideration: $8.856 million equity, $2.041 million NPV cash): Contributed $2.774 million in revenue in FY 2025. Currently subject to litigation from former owners (Ydens Holdings, LLC / Robert Ydens) alleging merger agreement breaches, unpaid retention bonuses, and California Labor Code wage claims. Deferred cash consideration owed stands at $2.093 million as of June 30, 2026 ($523k past due).
* RaGE Systems, Inc. (Acquired May 2024 for $9.518 million initial consideration: $7.682 million equity, $1.836 million NPV cash, plus up to $8.0 million earnouts): Contributed $5.836 million in revenue and $0.586 million in net income in FY 2025. Carries an accrued earnout liability of $2.000 million as of June 30, 2026.
* Terminated M&A: The proposed $15.0 million acquisition of Vision Aerial, Inc. ($12.0 million stock, $3.0 million cash) was mutually terminated on October 14, 2026, due to an inability to complete financial statement audit deliverables.
* Pending M&A: On August 13, 2026, the company entered into an agreement to acquire Special Project Delivery, Inc. (SPD) for 4,800,000 Class A common shares. The transaction is contingent upon SPD completing its acquisition of Winner Water Services, Inc., securing exposure to U.S. rare earth element assets and the Ex-Im Bank-backed "Project Vault."
HDIN Institutional Verdict
Mobix Labs' attempted strategic transformation from a struggling fabless semiconductor designer into a national security platform (under the planned corporate rebranding to "NSM Labs, Inc.") is constrained by debt overhang and governance vulnerabilities. While the company retains qualified-vendor status for defense-grade EMI filtering components, inorganic growth has replaced organic semiconductor monetization: acquired entities contributed $8.610 million of the company's $9.912 million revenue in FY 2025.
Balance sheet assets are heavily weighted toward goodwill ($16.066 million) and net intangibles ($12.324 million), representing 81.3% of total assets as of June 30, 2026. Management has formally guided toward an impending non-cash goodwill impairment charge of up to $5.5 million in Q4 2026.
Governance integrity remains compromised by five comprehensive categories of Internal Control over Financial Reporting (ICFR) material weaknesses, unresolved Information Technology General Control (ITGC) access deficiencies, combined executive oversight (CFO Keyvan Samini serving concurrently as President, Director, and former General Counsel), and executive personal guarantees on third-party debt. Furthermore, insider beneficial ownership of Class A common stock stands at just 6.7% following the August 2026 elimination of the 10-vote-per-share Class B structure. With common equity trading below $1.00 ($0.75 as of October 29, 2026) following a 1-for-10 reverse split in April 2026, stockholders have authorized an additional reverse split up to 1-for-20. Lacking positive cash flow and constrained by an active Nasdaq Market Value of Listed Securities deficiency, the structural inclusion of floating 82%–85% VWAP convertible notes creates unhedged, mathematically unbounded dilution risks for common equity participants.
Presentation Download & Video Access:
- Presentation Download: Click the PDF download link under 'Related Topics' to access the full institutional presentation of this report.
- Video Link: Click this link to watch the HDIN analyst briefing on YouTube.
About HDIN Research:
HDIN Research is a premier global market intelligence and strategic advisory firm specializing in institutional-grade financial analysis, supply chain audits, and macroeconomic forecasting. Our dedicated sector analysts deliver actionable, data-driven insights tailored for private equity, hedge funds, and corporate strategy teams. Visit us at http://www.hdinresearch.com.
2026 AI Transparency Footer:
"This intelligence report was authored by HDIN Research analysts following a rigorous audit of official corporate filings. AI was utilized for massive-scale data synthesis and structural drafting, ensuring 100% inclusion of reported data points. All strategic insights, financial modeling, and final verdicts were verified by our editorial board to ensure professional accuracy and compliance with 2026 Google Search E-E-A-T standards."