SuperX AI Technology Limited: AI Infrastructure Pivot Near Mie Facility as -6.4% Hardware Margins Signal Severe Operating Compression
Date : 2026-11-02
Reading : 336
HDIN Executive Takeaways
1. SuperX AI Technology Limited [NASDAQ: SUPX] transitioned from interior fit-out to computing infrastructure, expanding FY2026 revenue by 1,878.6% to $20,340,857, yet sustained a continuing operations net loss of $(109,683,311).
2. Hardware assembly at its 2,490-square-meter Mie Prefecture facility in Japan generated negative gross margins of -6.4%, burdened by 90.3% revenue concentration in a single Japanese customer and 56.5% procurement dependency on NVIDIA channels.
3. Private placements yielded $187,741,800 in net cash to offset $(73,798,742) in operating cash burn, expanding basic shares by 108.6% while 15.59 million potential dilutive shares overhang equity holders.
Figure SUPERX AI TECHNOLOGY LIMITED (FY2026 FORM 20-F) STRATEGIC PIVOT & FINANCIAL FORENSIC AUDIT
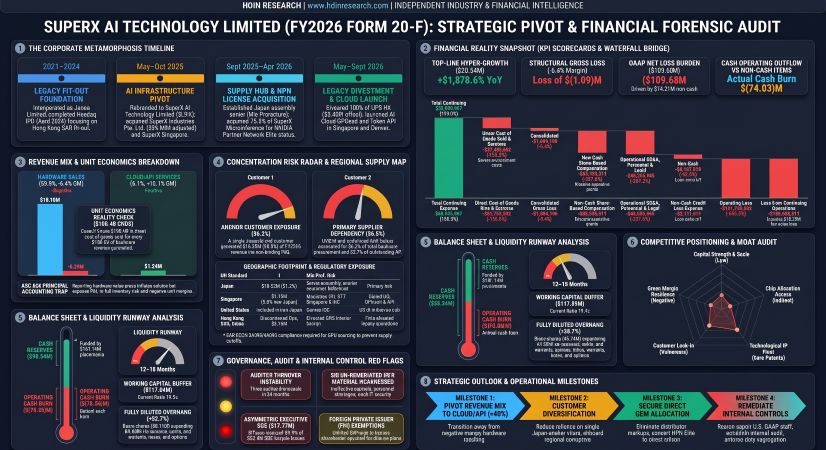 Financial Performance, Segment Disaggregation, and Margin Compression
SuperX AI Technology Limited, formerly known as Junee Limited, completed an operational pivot during the fiscal year ended June 30, 2026 (FY2026). The entity fully divested its legacy interior design and fit-out subsidiary, OPS Interior Design Consultant Limited ("OPS HK"), on May 7, 2026, classifying historical operations as discontinued. Under ASC 606, management recognized revenue from continuing operations on a gross basis as a principal, generating $20,340,857 in FY2026 compared to $1,028,061 in FY2025 (a 1,878.6% increase) and $0 in FY2024.
The underlying economics of this top-line surge reveal structural margin compression across core delivery lines. The business is categorized into two operational segments:
* Sales of AI Servers and Related IT Equipment: Delivered $19,102,901 in revenue (93.9% of consolidated top-line), increasing 1,758.1% from $1,028,061 in FY2025. Cost of goods sold reached $20,322,228 (representing 94.8% of total revenue costs, up 1,980.7% from $976,682 in FY2025). This generated a gross loss of $(1,219,327), or a negative gross margin of -6.4%, driven by introductory penetration pricing, unabsorbed facility ramp-up costs, and fixed-price customer purchase orders that could not pass through upstream hardware cost inflation.
* Cloud Computing and AI Model API Services: Generated $1,237,956 in revenue (6.1% of consolidated top-line) against service delivery costs of $1,112,734 (5.2% of total revenue costs), delivering a gross profit of $125,222 and a positive gross margin of 10.1%.
Table AI Hardware vs. Cloud and AI Model API Business: Revenue Composition, Cost Structure and Segment-Level Gross Margins
Consolidated gross loss from continuing operations totaled $(1,094,105) (-5.4% gross margin), down from a gross profit of $51,379 (5.0% gross margin) in FY2025. Operating overhead scaled 379.4% to $100,646,117 in FY2026, driving an operating loss of $(101,740,222). Every $100.00 of recognized revenue required $105.40 in direct procurement and delivery costs, $257.59 in share-based compensation, $237.28 in SG&A, personnel, and legal expenses, and $45.02 in non-cash credit losses, producing an operating deficit of $(500.18) per $100.00 of sales.
Operating expenses broke down into five discrete expense pools:
* Share-Based Compensation (SBC): $52,395,211 (52.1% of operating expenses), expanding from $3,605,979 in FY2025. Non-cash compensation distributed $17,774,458 (33.9%) to directors and executive officers, and $34,620,753 (66.1%) to employees and consultants.
* Employee Compensation & Benefits: $18,300,000 (18.2% of operating expenses), up 528.2% YoY from FY2025.
* Legal & Professional Fees: $14,300,000 (14.2% of operating expenses), up 487.2% YoY, reflecting restructuring, Nasdaq listing requirements, and cross-border M&A transactions.
* Credit Loss Expense: $9,157,815 (9.1% of operating expenses), dominated by the $9,103,662 loan write-off associated with the SuperX Industries Pte. Ltd. acquisition under the June 29, 2026 Loan Waiver and Settlement Agreement.
* Selling, Marketing, and Administrative Overhead: $6,400,000 (6.4% of operating expenses).
Consolidated net loss reached $(109,171,114) in FY2026, comprising a loss from continuing operations of $(109,683,311) offset by net income from discontinued operations of $512,197. Accumulated deficit totaled $128,325,821 as of June 30, 2026. Non-cash accounting adjustments represented 67.7% ($74,271,780) of the continuing operations loss:
* Share-based compensation: $52,395,211.
* Contingent consideration fair value mark-to-market loss: $12,715,635.
* Credit loss expense on loans receivable: $9,157,815.
* Depreciation and amortization: $1,400,548 ($1,391,124 for property and equipment; $9,424 for distribution licenses and systems).
* Operating lease expenses (non-cash): $1,499,366.
* Share of losses in equity-method investees: $408,228 (Cooltech, Digital Power, Optical, and Global Services).
* Other non-cash net adjustments: $820,655 (totaling $1,228,883 alongside JV losses).
* Realized net gains on investment securities: $(1,126,389).
* Net gains on subsidiary disposals (SunVest AIDC gain of $411,000 offset by lease adjustments): $(408,247).
Working capital absorbed $(39,263,018) in cash, driven by an AI server inventory increase of $(31,056,061) and hardware vendor prepayments of $(8,570,000), resulting in net cash used in continuing operating activities of $(74,034,569) and total operating cash outflows of $(73,798,742).
Infrastructure Footprint, Supply Chain Architecture, and Counterparty Exposure
SuperX AI Technology Limited functions without owned real estate, operating across four primary jurisdictions adhering to United Nations geographic standards:
* Tsu City, Mie Prefecture, Japan: Leased 2,490-square-meter facility from Taikoh Co., Ltd. (operating lease running August 1, 2025 to July 31, 2026, renewed to July 31, 2027). Functions as the Japan Global Supply Center for server integration, testing, warehousing, and local fulfillment. Maintains a designed assembly capacity of 20,000 servers annually, though FY2026 operations were constrained by early-stage ramp-up.
* Pasir Panjang Road, Mapletree Business City, Singapore: Leased 637-square-meter (6,857 sq. ft.) corporate headquarters (lease term January 1, 2026 to December 31, 2028) housing management, administrative, and global sales divisions.
* STT Singapore 5, Singapore: Co-location data center infrastructure operated by ST Telemedia Global Data Centres, serving as the Singapore AI Innovation Centre (launched April 15, 2026) for GPUaaS hosting and Token API orchestration.
* Denver, Colorado, United States: Third-party leased Internet Data Center (IDC) hosting node supporting the United States AI Inference Cloud Hub (launched June 4, 2026).
Geographic revenue attribution allocates $18,551,701 (91.2%) to Japan and $1,789,156 (8.8%) to Other International Markets (Singapore and the United States). The divested Hong Kong SAR, China fit-out segment generated $5,102,363 in FY2026 ($2,568,514 in FY2025) before disposal.
The operational model exhibits acute counterparty exposure on both ends of the supply chain. A single Japan-based anchor enterprise accounted for 90.3% ($18,349,994) of total FY2026 revenue, contracted via an intermediary partner using individual, fixed-price purchase orders with no minimum volume commitments. As of June 30, 2026, three clients represented 92.0% of net accounts receivable (Customer 1 at 32.5%, Customer 2 at 31.1%, and Customer 3 at 28.4%). Total trade accounts receivable stood at $472,072, against which management recorded an allowance for credit losses (CECL) of $0 (0.0%).
Upstream component procurement relies on NVIDIA Corporation [NASDAQ: NVDA] and its authorized regional distributors, accounting for 56.5% ($11,490,000) of total FY2026 hardware procurement (compared to 100.0% in FY2025). As of June 30, 2026, 93.7% of total accounts payable was owed to this single hardware vendor channel. SuperX AI accumulated $12,660,000 in advance prepayments and cash deposits to secure component shipments, including $8,570,000 in cash locked in supplier pipelines during FY2026. Hardware configurations include the proprietary SuperX XI6150 6U server (housing up to 10 dual-width GPUs including NVIDIA RTX PRO 6000), alongside resold NVIDIA B300 multi-node clusters and NVIDIA GB300 NVL72 rack-scale systems (72 Blackwell Ultra GPUs and 36 Grace CPUs). Sourcing and exporting these processors are governed by U.S. Export Administration Regulations (EAR) under ECCN 3A090a, 3A090b, and 4A090a, exposing shipments to potential Bureau of Industry and Security (BIS) licensing delays or supply reallocations.
The entity maintains zero registered patents globally, expensed all standalone R&D as "not significant" within G&A expenses, and employs zero standalone R&D personnel out of 61 full-time employees (Singapore: 22, Japan: 7, United States: 3, mainland China/Hong Kong SAR support: 29). Functional roles encompass 4 in management, 32 in operations, 18 in finance/admin/HR, and 7 board directors. Proprietary technological claims rest upon a $3,480,765 indefinite-lived distribution license obtained via its 75.5% subsidiary SuperX MicroInference Pte. Ltd., which holds NVIDIA Partner Network (NPN) Elite Solution Provider status, alongside $75,388 in internal software and 5 regional trademarks (4 in Singapore, 1 in Taiwan, Province of China).
To build out ecosystem capabilities without direct balance-sheet CapEx, SuperX AI entered multiple equity-method joint ventures in Singapore and mainland China:
* SuperX Cooltech Pte. Ltd. (35% equity interest): High-density liquid cooling systems.
* SuperX Digital Power Pte. Ltd. (40% equity interest): 800V direct current power distribution. FY2026 management fee income: $100,340; due from JV: $105,402.
* Calibre Opto-Semi Pte. Ltd. / SuperX Optical (45% equity interest): Optical interconnect modules.
* SuperX Global Services Pte. Ltd. (51% equity interest): Maintenance, deployment, and managed IT services with Teamsun. FY2026 server sales: $187,291; service purchases: $61,470; management fee income: $83,719; asset sales: $1,811; due from JV: $211,351.
* Syncro9 Pte. Ltd.: Related party controlled by Mr. Varia Hiten Dwarkadas (24.5% owner of SuperX MicroInference). Consulting and professional development fees paid by SuperX AI totaled $1,700,000 in FY2026; amount due to Syncro9 stood at $77,100.
* Apex AI Computing (Beijing) Co., Ltd.: Formed February 2026 with RMB 50.0 million capital (SuperX AI 51% stake, committing RMB 25.5 million / $3,910,000; uncalled commitment $1,921,055). Net working capital advances due from Apex AI expanded to $22,035,788 as of June 30, 2026 (representing 98.5% of total related party receivables of $22,362,213) to finance hardware inventory. On July 10, 2026, an acting-in-concert agreement with 53% of Apex AI shareholders brought the mainland China NVIDIA Preferred OEM partner under consolidated reporting.
Governance Deficits, Dilution Overhang, and HDIN Institutional Verdict
SuperX AI Technology Limited’s capital structure displays significant expansion alongside substantial dilution overhang. Basic outstanding ordinary shares rose 108.6% across 16 months, from 22,169,854 on June 30, 2025, to 43,980,000 on June 30, 2026, and reached 46,238,011 by October 29, 2026. Capital shifts during FY2026 included 16.60 million shares from private placements, 3.32 million from warrant exercises ($13,453,520 cash received), 1.88 million from option exercises ($1,855,001 cash received), and 2.75 million issued as contingent consideration for the SuperX Industries acquisition (fair value $42,348,699), offset by the repurchase of 2,051,899 treasury shares ($18,226,921 spent at an average price of $8.88).
The fully diluted share base totals 61,826,683 shares, representing an overhang of 15,588,672 shares (33.7% above basic shares):
* Placement Warrants: 4,896,665 shares exercisable between $9.37 and $13.00.
* Mercuria Senior Convertible Note: $26,895,000 principal issued in July 2026 (maturing July 2027 at 6.22163% interest), convertible into 3,300,000 shares at $8.15 per share. The note incorporates a Most Favored Nation (MFN) reset clause, adjusting the conversion price downward automatically if subsequent equity instruments are issued on more favorable terms.
* Mercuria Attached Warrants: 1,100,000 shares exercisable at $8.15 over a two-year period.
* Outstanding Stock Options: 3,211,500 shares (weighted average exercise price $11.14, terms spanning $4.00 to $30.00, weighted average life 4.12 years).
* Unvested Restricted Stock Units (RSUs): 391,383 shares (weighted average grant fair value $13.43).
* 2025 Equity Incentive Plan Available Pool: 2,689,124 unallocated authorized shares (plan authorized for up to 8,000,000 shares, supplementing the 2024 plan authorized for 2,000,000 shares).
Table Fully Diluted Capitalization Structure and Potential Share Dilution Overhang Analysis
Beneficial ownership reflects an institutional base following the exit of legacy controlling shareholder OPS Holdings Limited (reduced from 68.0% at the April 2024 IPO to 28.03% in October 2025, and dropping below 5.0% by June 30, 2026). Beneficial holders include Alpha Bridge I LP (7.14%, managed by PAG), Mirae Asset Securities (HK) Limited (7.14%), Mercuria Holdings (Singapore) Pte. Ltd. (7.14%), and Anatole Investment Management Limited (5.19%). All 8 executive officers and directors collectively control 716,897 shares, representing a 1.53% ownership stake. The company operates a single-class equity structure with one vote per share.
Executive leadership saw turnover throughout FY2026. Dr. Chenhong Huang, former President of SAP Greater China and President/Chairman of Dell Greater China, was appointed Chairman and CEO on December 1, 2025 (contracted base salary of $3,000,000, adjusted to $1,800,000 from February 1, 2026, with a $1,500,000 signing equity award, $1,500,000 annual equity vesting monthly, and a $3,000,000 cash bonus milestone if sales orders hit $500,000,000 within 12 months). Guili Miao, formerly CFO of Sihuan Pharmaceutical, became Deputy CEO and CFO on May 27, 2026 (base compensation of HK$300,000 per month). Kenny Sng Hoe Ann (ex-Intel) serves as CTO, and Jie Yang directs investments. Total cash compensation paid to executive officers and directors expanded to $2,336,472 in FY2026 from $474,904 in FY2025.
As a British Virgin Islands (BVI) entity, SuperX AI relies on Foreign Private Issuer (FPI) home country practice exemptions under Nasdaq Rule 5615(a)(3). These exemptions bypass shareholder approval mandates for equity plans and private placements exceeding 20% of outstanding shares, eliminate annual general shareholder meetings, and exempt insiders from Section 16 short-swing profit rules.
Governance instability is further evidenced by internal control material weaknesses and frequent auditor turnover:
* Auditor Resignations and Dismissals: The company engaged four auditing firms across a 24-month span. Marcum Asia CPAs LLP was dismissed in June 2024, replaced by CT International LLP. CT International was dismissed in May 2025, replaced by KD & Co. KD & Co. was dismissed on July 21, 2026, replaced by HTL International, LLC, which issued an unqualified opinion on FY2026 continuing operations on October 29, 2026, with an explanatory note regarding retrospective reclassifications for OPS HK.
* Ineffective ICFR (Item 15): Management concluded disclosure controls were ineffective as of June 30, 2026, citing six unremediated material weaknesses: 1. Shortage of dedicated U.S. GAAP personnel; 2. Absence of a functional internal audit department; 3. Lack of duties segregation in journal entry approvals; 4. Inadequate IT security and system access permissions; 5. Deficits in program change control procedures; and 6. Absence of formal operating system environment security policies.
* Valuation Allowances & Tax Friction: Income tax expense totaled $8,573 in FY2026 against pre-tax losses of $(109,674,738). Gross deferred tax assets (DTAs) of $2,516,874 (including $2,290,000 across $12,834,108 in tax loss carryforwards spanning Singapore, Japan, mainland China, Hong Kong SAR, and the United States) were countered by a 100% valuation allowance of $(1,968,120), signaling management's expectation of near-term taxable losses. Passive cash holdings ($98,936,510) additionally elevate U.S. PFIC classification risk under IRC Section 1297.
HDIN Institutional Verdict: SuperX AI Technology Limited functions primarily as a balance-sheet-funded hardware integration intermediary rather than a proprietary artificial intelligence software enterprise. While top-line revenue expanded via gross reporting under ASC 606, core server deliveries generate negative unit gross margins (-6.4%), requiring the injection of $187.7 million in equity capital to subsidize cash burn of $(73.8) million. With an active equity dilution overhang of 15.59 million shares, six unremediated material internal control weaknesses, low insider ownership (1.53%), and an anchor customer generating over 90% of receipts under cancelable purchase orders, institutional allocators face substantial structural risk until hardware operations achieve positive unit margins and revenue shifts durably toward its higher-margin cloud software layer.
Presentation Download & Video Access:
* Presentation Download: Click the PDF download link under 'Related Topics' to access the full institutional presentation of this report.
* Video Link: Click this link to watch the HDIN analyst briefing on YouTube.
About HDIN Research:
HDIN Research is a premier global market intelligence and strategic advisory firm specializing in institutional-grade financial analysis, supply chain audits, and macroeconomic forecasting. Our dedicated sector analysts deliver actionable, data-driven insights tailored for private equity, hedge funds, and corporate strategy teams. Visit us at http://www.hdinresearch.com.
2026 AI Transparency Footer:
"This intelligence report was authored by HDIN Research analysts following a rigorous audit of official corporate filings. AI was utilized for massive-scale data synthesis and structural drafting, ensuring 100% inclusion of reported data points. All strategic insights, financial modeling, and final verdicts were verified by our editorial board to ensure professional accuracy and compliance with 2026 Google Search E-E-A-T standards."
1. SuperX AI Technology Limited [NASDAQ: SUPX] transitioned from interior fit-out to computing infrastructure, expanding FY2026 revenue by 1,878.6% to $20,340,857, yet sustained a continuing operations net loss of $(109,683,311).
2. Hardware assembly at its 2,490-square-meter Mie Prefecture facility in Japan generated negative gross margins of -6.4%, burdened by 90.3% revenue concentration in a single Japanese customer and 56.5% procurement dependency on NVIDIA channels.
3. Private placements yielded $187,741,800 in net cash to offset $(73,798,742) in operating cash burn, expanding basic shares by 108.6% while 15.59 million potential dilutive shares overhang equity holders.
Figure SUPERX AI TECHNOLOGY LIMITED (FY2026 FORM 20-F) STRATEGIC PIVOT & FINANCIAL FORENSIC AUDIT
Financial Performance, Segment Disaggregation, and Margin CompressionSuperX AI Technology Limited, formerly known as Junee Limited, completed an operational pivot during the fiscal year ended June 30, 2026 (FY2026). The entity fully divested its legacy interior design and fit-out subsidiary, OPS Interior Design Consultant Limited ("OPS HK"), on May 7, 2026, classifying historical operations as discontinued. Under ASC 606, management recognized revenue from continuing operations on a gross basis as a principal, generating $20,340,857 in FY2026 compared to $1,028,061 in FY2025 (a 1,878.6% increase) and $0 in FY2024.
The underlying economics of this top-line surge reveal structural margin compression across core delivery lines. The business is categorized into two operational segments:
* Sales of AI Servers and Related IT Equipment: Delivered $19,102,901 in revenue (93.9% of consolidated top-line), increasing 1,758.1% from $1,028,061 in FY2025. Cost of goods sold reached $20,322,228 (representing 94.8% of total revenue costs, up 1,980.7% from $976,682 in FY2025). This generated a gross loss of $(1,219,327), or a negative gross margin of -6.4%, driven by introductory penetration pricing, unabsorbed facility ramp-up costs, and fixed-price customer purchase orders that could not pass through upstream hardware cost inflation.
* Cloud Computing and AI Model API Services: Generated $1,237,956 in revenue (6.1% of consolidated top-line) against service delivery costs of $1,112,734 (5.2% of total revenue costs), delivering a gross profit of $125,222 and a positive gross margin of 10.1%.
Table AI Hardware vs. Cloud and AI Model API Business: Revenue Composition, Cost Structure and Segment-Level Gross Margins
| Segment Financial Architecture | FY2024 (USD) | FY2025 (USD) | FY2026 (USD) | FY2026 Share (%) | YoY Growth (%) | FY2026 Gross Profit / (Loss) | Segment Gross Margin (%) |
| Sales of AI Servers & Related IT Equipment | $0 | $1,028,061 | $19,102,901 | 93.9% | +1,758.1% | $(1,219,327) | -6.4% |
| Cloud Computing & AI Model API Services | $0 | $0 | $1,237,956 | 6.1% | N/A | $125,222 | +10.1% |
| Total Continuing Operations | $0 | $1,028,061 | $20,340,857 | 100.0% | +1,878.6% | $(1,094,105) | -5.4% |
| Cost of Goods Sold (Hardware) | $0 | $976,682 | $20,322,228 | 94.8% | +1,980.7% | — | — |
| Cost of Services (Cloud/API) | $0 | $0 | $1,112,734 | 5.2% | N/A | — | — |
| Total Cost of Revenue | $0 | $976,682 | $21,434,962 | 100.0% | +2,094.7% | — | — |
Consolidated gross loss from continuing operations totaled $(1,094,105) (-5.4% gross margin), down from a gross profit of $51,379 (5.0% gross margin) in FY2025. Operating overhead scaled 379.4% to $100,646,117 in FY2026, driving an operating loss of $(101,740,222). Every $100.00 of recognized revenue required $105.40 in direct procurement and delivery costs, $257.59 in share-based compensation, $237.28 in SG&A, personnel, and legal expenses, and $45.02 in non-cash credit losses, producing an operating deficit of $(500.18) per $100.00 of sales.
Operating expenses broke down into five discrete expense pools:
* Share-Based Compensation (SBC): $52,395,211 (52.1% of operating expenses), expanding from $3,605,979 in FY2025. Non-cash compensation distributed $17,774,458 (33.9%) to directors and executive officers, and $34,620,753 (66.1%) to employees and consultants.
* Employee Compensation & Benefits: $18,300,000 (18.2% of operating expenses), up 528.2% YoY from FY2025.
* Legal & Professional Fees: $14,300,000 (14.2% of operating expenses), up 487.2% YoY, reflecting restructuring, Nasdaq listing requirements, and cross-border M&A transactions.
* Credit Loss Expense: $9,157,815 (9.1% of operating expenses), dominated by the $9,103,662 loan write-off associated with the SuperX Industries Pte. Ltd. acquisition under the June 29, 2026 Loan Waiver and Settlement Agreement.
* Selling, Marketing, and Administrative Overhead: $6,400,000 (6.4% of operating expenses).
Consolidated net loss reached $(109,171,114) in FY2026, comprising a loss from continuing operations of $(109,683,311) offset by net income from discontinued operations of $512,197. Accumulated deficit totaled $128,325,821 as of June 30, 2026. Non-cash accounting adjustments represented 67.7% ($74,271,780) of the continuing operations loss:
* Share-based compensation: $52,395,211.
* Contingent consideration fair value mark-to-market loss: $12,715,635.
* Credit loss expense on loans receivable: $9,157,815.
* Depreciation and amortization: $1,400,548 ($1,391,124 for property and equipment; $9,424 for distribution licenses and systems).
* Operating lease expenses (non-cash): $1,499,366.
* Share of losses in equity-method investees: $408,228 (Cooltech, Digital Power, Optical, and Global Services).
* Other non-cash net adjustments: $820,655 (totaling $1,228,883 alongside JV losses).
* Realized net gains on investment securities: $(1,126,389).
* Net gains on subsidiary disposals (SunVest AIDC gain of $411,000 offset by lease adjustments): $(408,247).
Working capital absorbed $(39,263,018) in cash, driven by an AI server inventory increase of $(31,056,061) and hardware vendor prepayments of $(8,570,000), resulting in net cash used in continuing operating activities of $(74,034,569) and total operating cash outflows of $(73,798,742).
Infrastructure Footprint, Supply Chain Architecture, and Counterparty Exposure
SuperX AI Technology Limited functions without owned real estate, operating across four primary jurisdictions adhering to United Nations geographic standards:
* Tsu City, Mie Prefecture, Japan: Leased 2,490-square-meter facility from Taikoh Co., Ltd. (operating lease running August 1, 2025 to July 31, 2026, renewed to July 31, 2027). Functions as the Japan Global Supply Center for server integration, testing, warehousing, and local fulfillment. Maintains a designed assembly capacity of 20,000 servers annually, though FY2026 operations were constrained by early-stage ramp-up.
* Pasir Panjang Road, Mapletree Business City, Singapore: Leased 637-square-meter (6,857 sq. ft.) corporate headquarters (lease term January 1, 2026 to December 31, 2028) housing management, administrative, and global sales divisions.
* STT Singapore 5, Singapore: Co-location data center infrastructure operated by ST Telemedia Global Data Centres, serving as the Singapore AI Innovation Centre (launched April 15, 2026) for GPUaaS hosting and Token API orchestration.
* Denver, Colorado, United States: Third-party leased Internet Data Center (IDC) hosting node supporting the United States AI Inference Cloud Hub (launched June 4, 2026).
Geographic revenue attribution allocates $18,551,701 (91.2%) to Japan and $1,789,156 (8.8%) to Other International Markets (Singapore and the United States). The divested Hong Kong SAR, China fit-out segment generated $5,102,363 in FY2026 ($2,568,514 in FY2025) before disposal.
Table FY2025–FY2026 Geographic Revenue Breakdown and Operational Footprint Analysis
| Geographic Revenue Breakdown (UN Standard) | FY2025 Revenue (USD) | FY2025 Share (%) | FY2026 Revenue (USD) | FY2026 Share (%) | Operational Designation |
| Japan | $0 | 0.0% | $18,551,701 | 91.2% | Hardware Assembly & Delivery Contracting Hub |
| Other International Markets (Singapore, US) | $1,028,061 | 100.0% | $1,789,156 | 8.8% | Corporate HQ & Cloud / API Hosting Nodes |
| Discontinued Operations (Hong Kong SAR, China) | $2,568,514 | N/A | $5,102,363 | N/A | Divested Interior Fit-Out Operations |
| Total Continuing Operations | $1,028,061 | 100.0% | $20,340,857 | 100.0% | Consolidated Operating Base |
The operational model exhibits acute counterparty exposure on both ends of the supply chain. A single Japan-based anchor enterprise accounted for 90.3% ($18,349,994) of total FY2026 revenue, contracted via an intermediary partner using individual, fixed-price purchase orders with no minimum volume commitments. As of June 30, 2026, three clients represented 92.0% of net accounts receivable (Customer 1 at 32.5%, Customer 2 at 31.1%, and Customer 3 at 28.4%). Total trade accounts receivable stood at $472,072, against which management recorded an allowance for credit losses (CECL) of $0 (0.0%).
Upstream component procurement relies on NVIDIA Corporation [NASDAQ: NVDA] and its authorized regional distributors, accounting for 56.5% ($11,490,000) of total FY2026 hardware procurement (compared to 100.0% in FY2025). As of June 30, 2026, 93.7% of total accounts payable was owed to this single hardware vendor channel. SuperX AI accumulated $12,660,000 in advance prepayments and cash deposits to secure component shipments, including $8,570,000 in cash locked in supplier pipelines during FY2026. Hardware configurations include the proprietary SuperX XI6150 6U server (housing up to 10 dual-width GPUs including NVIDIA RTX PRO 6000), alongside resold NVIDIA B300 multi-node clusters and NVIDIA GB300 NVL72 rack-scale systems (72 Blackwell Ultra GPUs and 36 Grace CPUs). Sourcing and exporting these processors are governed by U.S. Export Administration Regulations (EAR) under ECCN 3A090a, 3A090b, and 4A090a, exposing shipments to potential Bureau of Industry and Security (BIS) licensing delays or supply reallocations.
The entity maintains zero registered patents globally, expensed all standalone R&D as "not significant" within G&A expenses, and employs zero standalone R&D personnel out of 61 full-time employees (Singapore: 22, Japan: 7, United States: 3, mainland China/Hong Kong SAR support: 29). Functional roles encompass 4 in management, 32 in operations, 18 in finance/admin/HR, and 7 board directors. Proprietary technological claims rest upon a $3,480,765 indefinite-lived distribution license obtained via its 75.5% subsidiary SuperX MicroInference Pte. Ltd., which holds NVIDIA Partner Network (NPN) Elite Solution Provider status, alongside $75,388 in internal software and 5 regional trademarks (4 in Singapore, 1 in Taiwan, Province of China).
To build out ecosystem capabilities without direct balance-sheet CapEx, SuperX AI entered multiple equity-method joint ventures in Singapore and mainland China:
* SuperX Cooltech Pte. Ltd. (35% equity interest): High-density liquid cooling systems.
* SuperX Digital Power Pte. Ltd. (40% equity interest): 800V direct current power distribution. FY2026 management fee income: $100,340; due from JV: $105,402.
* Calibre Opto-Semi Pte. Ltd. / SuperX Optical (45% equity interest): Optical interconnect modules.
* SuperX Global Services Pte. Ltd. (51% equity interest): Maintenance, deployment, and managed IT services with Teamsun. FY2026 server sales: $187,291; service purchases: $61,470; management fee income: $83,719; asset sales: $1,811; due from JV: $211,351.
* Syncro9 Pte. Ltd.: Related party controlled by Mr. Varia Hiten Dwarkadas (24.5% owner of SuperX MicroInference). Consulting and professional development fees paid by SuperX AI totaled $1,700,000 in FY2026; amount due to Syncro9 stood at $77,100.
* Apex AI Computing (Beijing) Co., Ltd.: Formed February 2026 with RMB 50.0 million capital (SuperX AI 51% stake, committing RMB 25.5 million / $3,910,000; uncalled commitment $1,921,055). Net working capital advances due from Apex AI expanded to $22,035,788 as of June 30, 2026 (representing 98.5% of total related party receivables of $22,362,213) to finance hardware inventory. On July 10, 2026, an acting-in-concert agreement with 53% of Apex AI shareholders brought the mainland China NVIDIA Preferred OEM partner under consolidated reporting.
Governance Deficits, Dilution Overhang, and HDIN Institutional Verdict
SuperX AI Technology Limited’s capital structure displays significant expansion alongside substantial dilution overhang. Basic outstanding ordinary shares rose 108.6% across 16 months, from 22,169,854 on June 30, 2025, to 43,980,000 on June 30, 2026, and reached 46,238,011 by October 29, 2026. Capital shifts during FY2026 included 16.60 million shares from private placements, 3.32 million from warrant exercises ($13,453,520 cash received), 1.88 million from option exercises ($1,855,001 cash received), and 2.75 million issued as contingent consideration for the SuperX Industries acquisition (fair value $42,348,699), offset by the repurchase of 2,051,899 treasury shares ($18,226,921 spent at an average price of $8.88).
The fully diluted share base totals 61,826,683 shares, representing an overhang of 15,588,672 shares (33.7% above basic shares):
* Placement Warrants: 4,896,665 shares exercisable between $9.37 and $13.00.
* Mercuria Senior Convertible Note: $26,895,000 principal issued in July 2026 (maturing July 2027 at 6.22163% interest), convertible into 3,300,000 shares at $8.15 per share. The note incorporates a Most Favored Nation (MFN) reset clause, adjusting the conversion price downward automatically if subsequent equity instruments are issued on more favorable terms.
* Mercuria Attached Warrants: 1,100,000 shares exercisable at $8.15 over a two-year period.
* Outstanding Stock Options: 3,211,500 shares (weighted average exercise price $11.14, terms spanning $4.00 to $30.00, weighted average life 4.12 years).
* Unvested Restricted Stock Units (RSUs): 391,383 shares (weighted average grant fair value $13.43).
* 2025 Equity Incentive Plan Available Pool: 2,689,124 unallocated authorized shares (plan authorized for up to 8,000,000 shares, supplementing the 2024 plan authorized for 2,000,000 shares).
Table Fully Diluted Capitalization Structure and Potential Share Dilution Overhang Analysis
| Capital Structure & Dilution Overhang | Security Count / Principal | Conversion / Strike Price | Dilutive Potential Shares | Share Expansion Impact (%) |
| Basic Shares Outstanding (Oct 29, 2026) | 46,238,011 | N/A | 46,238,011 | Baseline (74.8% Diluted Base) |
| PIPE Placement Warrants | 4,896,665 | $9.37 – $13.00 | 4,896,665 | +10.6% |
| Mercuria Convertible Notes | $26,895,000 Principal | $8.15 (MFN Reset) | 3,300,000 | +7.1% |
| Mercuria Transaction Attached Warrants | 1,100,000 | $8.15 | 1,100,000 | +2.4% |
| Outstanding Options (Vested & Unvested) | 3,211,500 | $11.14 (Weighted Avg) | 3,211,500 | +6.9% |
| Unvested Restricted Stock Units (RSUs) | 391,383 | $0.00 (Nominal) | 391,383 | +0.8% |
| 2025 Equity Incentive Plan Available Pool | 2,689,124 Authorized | Market Price at Grant | 2,689,124 | +5.8% |
| Fully Diluted Equity Capital Base | — | — | 61,826,683 | +33.7% Expansion Overhang |
Beneficial ownership reflects an institutional base following the exit of legacy controlling shareholder OPS Holdings Limited (reduced from 68.0% at the April 2024 IPO to 28.03% in October 2025, and dropping below 5.0% by June 30, 2026). Beneficial holders include Alpha Bridge I LP (7.14%, managed by PAG), Mirae Asset Securities (HK) Limited (7.14%), Mercuria Holdings (Singapore) Pte. Ltd. (7.14%), and Anatole Investment Management Limited (5.19%). All 8 executive officers and directors collectively control 716,897 shares, representing a 1.53% ownership stake. The company operates a single-class equity structure with one vote per share.
Executive leadership saw turnover throughout FY2026. Dr. Chenhong Huang, former President of SAP Greater China and President/Chairman of Dell Greater China, was appointed Chairman and CEO on December 1, 2025 (contracted base salary of $3,000,000, adjusted to $1,800,000 from February 1, 2026, with a $1,500,000 signing equity award, $1,500,000 annual equity vesting monthly, and a $3,000,000 cash bonus milestone if sales orders hit $500,000,000 within 12 months). Guili Miao, formerly CFO of Sihuan Pharmaceutical, became Deputy CEO and CFO on May 27, 2026 (base compensation of HK$300,000 per month). Kenny Sng Hoe Ann (ex-Intel) serves as CTO, and Jie Yang directs investments. Total cash compensation paid to executive officers and directors expanded to $2,336,472 in FY2026 from $474,904 in FY2025.
As a British Virgin Islands (BVI) entity, SuperX AI relies on Foreign Private Issuer (FPI) home country practice exemptions under Nasdaq Rule 5615(a)(3). These exemptions bypass shareholder approval mandates for equity plans and private placements exceeding 20% of outstanding shares, eliminate annual general shareholder meetings, and exempt insiders from Section 16 short-swing profit rules.
Governance instability is further evidenced by internal control material weaknesses and frequent auditor turnover:
* Auditor Resignations and Dismissals: The company engaged four auditing firms across a 24-month span. Marcum Asia CPAs LLP was dismissed in June 2024, replaced by CT International LLP. CT International was dismissed in May 2025, replaced by KD & Co. KD & Co. was dismissed on July 21, 2026, replaced by HTL International, LLC, which issued an unqualified opinion on FY2026 continuing operations on October 29, 2026, with an explanatory note regarding retrospective reclassifications for OPS HK.
* Ineffective ICFR (Item 15): Management concluded disclosure controls were ineffective as of June 30, 2026, citing six unremediated material weaknesses: 1. Shortage of dedicated U.S. GAAP personnel; 2. Absence of a functional internal audit department; 3. Lack of duties segregation in journal entry approvals; 4. Inadequate IT security and system access permissions; 5. Deficits in program change control procedures; and 6. Absence of formal operating system environment security policies.
* Valuation Allowances & Tax Friction: Income tax expense totaled $8,573 in FY2026 against pre-tax losses of $(109,674,738). Gross deferred tax assets (DTAs) of $2,516,874 (including $2,290,000 across $12,834,108 in tax loss carryforwards spanning Singapore, Japan, mainland China, Hong Kong SAR, and the United States) were countered by a 100% valuation allowance of $(1,968,120), signaling management's expectation of near-term taxable losses. Passive cash holdings ($98,936,510) additionally elevate U.S. PFIC classification risk under IRC Section 1297.
HDIN Institutional Verdict: SuperX AI Technology Limited functions primarily as a balance-sheet-funded hardware integration intermediary rather than a proprietary artificial intelligence software enterprise. While top-line revenue expanded via gross reporting under ASC 606, core server deliveries generate negative unit gross margins (-6.4%), requiring the injection of $187.7 million in equity capital to subsidize cash burn of $(73.8) million. With an active equity dilution overhang of 15.59 million shares, six unremediated material internal control weaknesses, low insider ownership (1.53%), and an anchor customer generating over 90% of receipts under cancelable purchase orders, institutional allocators face substantial structural risk until hardware operations achieve positive unit margins and revenue shifts durably toward its higher-margin cloud software layer.
Presentation Download & Video Access:
* Presentation Download: Click the PDF download link under 'Related Topics' to access the full institutional presentation of this report.
* Video Link: Click this link to watch the HDIN analyst briefing on YouTube.
About HDIN Research:
HDIN Research is a premier global market intelligence and strategic advisory firm specializing in institutional-grade financial analysis, supply chain audits, and macroeconomic forecasting. Our dedicated sector analysts deliver actionable, data-driven insights tailored for private equity, hedge funds, and corporate strategy teams. Visit us at http://www.hdinresearch.com.
2026 AI Transparency Footer:
"This intelligence report was authored by HDIN Research analysts following a rigorous audit of official corporate filings. AI was utilized for massive-scale data synthesis and structural drafting, ensuring 100% inclusion of reported data points. All strategic insights, financial modeling, and final verdicts were verified by our editorial board to ensure professional accuracy and compliance with 2026 Google Search E-E-A-T standards."