Pensana Plc: Strategic Downstream Decoupling at Longonjo as US$5.92 Million Saltend Write-Off Accelerates Capital Pivot to Republic of Angola
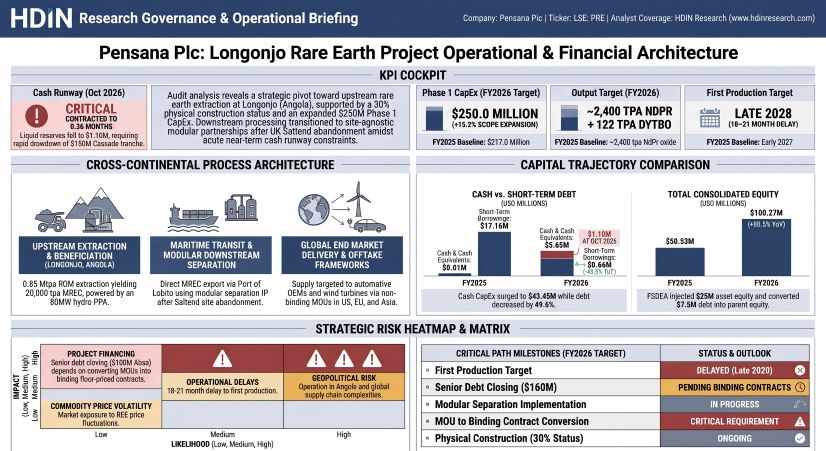
1. Pensana Plc [LSE: PRE] aborted its integrated UK downstream strategy, absorbing a US$5.92 million non-cash impairment on its Saltend refinery while pivoting to direct Mixed Rare Earth Carbonate (MREC) export from the Republic of Angola.
2. Production schedules slipped 18 to 21 months to late 2028, with Phase 1 CapEx escalating 15.2% to US$250.0 million, driven by an upgraded 122-tonne-per-annum dysprosium-terbium circuit.
3. Liquidity contracted to US$1.10 million on 23 October 2026 (0.26 months of runway), leaving balance-sheet solvency contingent on securing the delayed US$150.0 million Cascade tranche and converting non-binding MOUs into definitive debt covenants.
Figure Pensana Plc Longonjo Rare Earth Project Operational & Financial Architecture
 Segmental Realities and Capital Realignment
Pensana Plc altered its corporate operating profile between FY2025 and FY2026, formally terminating its two-hub "closed-loop" architecture that linked Angolan extraction to processing at the Saltend Chemicals Park in Yorkshire, United Kingdom of Great Britain and Northern Ireland. The strategic abandonment of the Saltend facility resulted in a 100% non-cash impairment of site assets totaling US$5,917,836 (US$4,477,032 in Property, Plant and Equipment under construction and US$1,440,804 in site-specific intangible engineering fees), following the lapsation of UK planning permissions in mid-2025.
The Group retained US$10.23 million in modular separation intellectual property (IP), re-engineered from front-end engineering design (FEED) studies into site-agnostic processing units intended for international tolling alliances or modular co-location. Concurrently, Pensana Plc entered an earn-in farm-out agreement on the Coola exploration asset with ASX-listed Tyranna Resources Ltd, diluting its equity interest to a 20% carried position while Tyranna deploys US$2.6 million over three years.
Table LONGONJO CAPITAL RECONCILIATION & BALANCE SHEET PROFILE
|
Financial / Operational Parameter |
FY2025 (USD) |
FY2026 (USD) |
YoY Variance |
|---|---|---|---|
|
Longonjo Phase 1 Capital Requirements and Project Execution |
|||
|
Longonjo Phase 1 Total Capital Expenditure |
$217,000,000 |
$250,000,000 |
+15.2% |
|
Direct Capital Expenditure Deployed |
$6,130,410 |
$45,000,000 |
+634.1% |
|
Committed Project Contracts and Purchase Orders |
~$35,000,000 |
$138,000,000 |
+294.3% |
|
Remaining Unfunded Phase 1 CapEx |
$210,869,590 |
$205,000,000 |
-2.8% |
|
Contracted Capital Commitments Recognized on the Balance Sheet |
$0 |
$22,110,000 |
N/A |
|
Liquidity, Debt and Cash Flow |
|||
|
Cash and Cash Equivalents (June 30 Period-End) |
$811,049 |
$5,647,813 |
+596.4% |
|
Liquid Cash at Approval Date (October 23) |
$10,270,000 |
$1,100,000 |
-89.3% |
|
Short-Term Borrowings (Due Within One Year) |
$17,160,116 |
$8,656,270 |
-49.6% |
|
Long-Term Borrowings (Due After One Year) |
$0 |
$0 |
0.0% |
|
Net Working Capital (Current Assets Less Current Liabilities) |
-$29,072,535 |
-$11,318,663 |
+61.1% |
|
Trailing 12-Month Operating and Investing Cash Outflow |
$7,745,085 |
$49,988,980 |
+545.4% |
|
Average Monthly Cash Outflow |
$645,424 |
$4,165,748 |
+545.4% |
|
Cash Runway at Financial Sign-Off Date (Months) |
15.91 |
0.26 |
-98.4% |
|
Profitability, Impairment and Equity |
|||
|
Total Comprehensive Loss for the Year |
$11,497,912 |
$14,055,989 |
+22.2% |
|
Administrative Expenses |
$7,399,959 |
$9,923,564 |
+34.1% |
|
Impairment of Non-Financial Assets (Saltend) |
$0 |
$5,917,836 |
N/A |
|
Foreign Exchange Gain / (Loss) |
-$4,610,939 |
+$2,992,372 |
+164.9% |
|
Exploration and Evaluation Expenditure Additions |
$60,217 |
$292,405 |
+385.6% |
|
Total Consolidated Equity |
$50,525,938 |
$100,274,181 |
+98.5% |
|
Equity Attributable to Owners of the Parent |
$50,525,938 |
$90,622,770 |
+79.4% |
|
Non-Controlling Interests (Ozango / FSDEA) |
$0 |
$9,651,411 |
N/A |
The expansion in Phase 1 capital costs (+US$33.0 million) was driven by three identifiable engineering and macro drivers:
* Scope expansion to integrate an on-site Heavy Rare Earth Element (HREE) recovery circuit: US$18.5 million.
* Site civils, earthworks terracing, aggregate production, and structural test-piling (38 piles installed; ~1,600m planned): US$8.5 million.
* Logistics freight volatility, regional Southern African transport inflation, and structural steel/reagent price adjustments: US$6.0 million.
Operating cash outflows reached US$4,603,809 in FY2026 (FY2025: US$2,643,916), while capital additions across property, plant, equipment, and intangibles totaled US$41,320,767 (FY2025: US$7,129,576). Cash paid for capital assets totaled US$43,454,886 (FY2025: US$6,130,410). Administrative overhead expanded 34.1% YoY to US$9,923,564, driven by a US$1.09 million non-cash loss on derivative financial assets, higher corporate advisory costs connected to equity placements, and losses incurred during contractor debt settlements.
A forensic audit of FY2026 notes revealed an unlawful share settlement executed in October 2025 to discharge £5,794,764 (US$7.8 million) in historical trade payables owed to Wood Plc for Saltend engineering. Pensana Plc allotted 4,828,970 ordinary shares at a 120p reference price into a company-controlled nominee account under an indemnity ensuring Wood Plc received the full cash balance.
Disposals generated open-market realized derivative losses of US$795,524 on 4,020,000 shares sold below reference price, alongside a US$299,214 fair-value derivative loss on the remaining 808,970 shares held at 30 June 2026 (valued at £0.921 per share, or US$987,727). External auditor BDO LLP and independent legal counsel concluded that issuing equity into a nominee account with shortfall downside indemnification was ultra vires and unlawful under the UK Companies Act 2006. The Board initiated no legal rectification, citing total satisfaction of the principal obligation without net cash loss relative to the original invoice.
Further related-party transactions in FY2026 included £270,313 in advisory fees paid to Selection Capital Investments Ltd (associated with Executive Chairman Paul Atherley, up from £53,438 in FY2025), shared office meeting recharges of £573 with Alkemy Capital Investments Plc (£15,923 owed to Pensana Plc at year-end), and £213 with Tees Valley Lithium Ltd (£2,038 owed to Pensana Plc). Director debt settlements involved the issuance of 1,500,000 ordinary shares in July 2024 to clear a £250,000 loan from Paul Atherley, while Finance Director Robert Kaplan maintained a working capital facility of £272,213 carrying 3.75% annual interest following personal open-market sales of 1,046,186 shares in December 2024 to support corporate liquidity.
Table SHARE CAPITAL STRUCTURE & DILUTION WATERFALL
|
Share Class / Equity Instrument |
Number of Units / Underlying Consideration |
Potential Shares |
% of Estimated Fully Diluted Share Base |
|---|---|---|---|
|
Basic Ordinary Shares in Issue (June 30, 2026) |
353,515,226 |
353,515,226 |
88.58% |
|
Approved but Unissued STIP Bonus Shares (April 2025) |
4,750,000 |
4,750,000 |
1.19% |
|
Executive Deferred LTIP Performance Shares |
8,429,375 |
8,429,375 |
2.11% |
|
Employee Deferred LTIP Performance Shares |
5,650,000 |
5,650,000 |
1.42% |
|
Potential FSDEA Debt-to-Equity Conversion |
$8,656,270 debt |
~26,724,290 |
6.70% |
|
Estimated Fully Diluted Share Base |
N/A |
399,068,891 |
100.00% |
The basic share count grew 18.2% YoY to 353,515,226 shares, expanding 22.4% over the FY2024 baseline (288,771,989 shares). The conversion of the remaining US$8,656,270 bridging loan owed to the Fundo Soberano de Angola (FSDEA) at a ~£0.24 reference price, alongside unexercised warrant reserves (fair value: US$490,739), will increase the diluted share count to 399,068,891 shares (+38.2% expansion vs. FY2024). This lowers parent Net Asset Value (NAV) per share by 11.3% from US$0.256 (19.3 pence) on a basic basis to US$0.227 (17.1 pence) on a fully diluted basis.
Upstream Infrastructure Execution and Geographic Footprint
Capital allocation relocated non-current assets to the Republic of Angola during FY2026, increasing 68.6% YoY to US$100,753,187 (90.2% of total Group non-current assets), while UK long-term assets contracted 44.8% YoY to US$10,951,039. Administrative operations in the Commonwealth of Australia and the Portuguese Republic maintain carrying values of US$0.
Table GEOGRAPHIC ASSET FOOTPRINT & METALLURGICAL CAPACITIES
|
Operating Dimension |
FY2025 Baseline Parameters |
Audited FY2026 Disclosures |
|---|---|---|
|
Mineral Resources and Ore Reserves |
||
|
Longonjo JORC Mineral Resource (SRK, September 20) |
313 Mt at 1.43% TREO |
313 Mt at 1.43% TREO |
|
Longonjo JORC Proved Ore Reserve (ABGM, April 2025) |
11.69 Mt at 3.49% TREO |
11.69 Mt at 3.49% TREO |
|
Longonjo JORC Probable Ore Reserve (ABGM, April 2025) |
9.84 Mt at 2.51% TREO |
9.84 Mt at 2.51% TREO |
|
Contained NdPr Oxide in Ore Reserves |
139,457 tonnes |
139,457 tonnes |
|
Contained DyTbO in Ore Reserves |
Not disclosed |
3,689 tonnes |
|
Phase 1 Production and Processing Design |
||
|
Run-of-Mine (ROM) Extraction Capacity |
0.85 Mtpa; free-dig soft ore |
0.85 Mtpa; free-dig soft ore |
|
Processing Plant Feed Capacity and Grade |
800,000 tpa at 4.12% TREO |
800,000 tpa at 4.12% TREO |
|
Intermediate Product Output |
20,000 tpa of MREC |
20,000 tpa of MREC |
|
Contained NdPr Oxide Equivalent Output |
~2,400 tpa |
~2,400 tpa |
|
Contained Heavy Rare Earth Oxide (DyTbO) Output |
~30 tpa |
122 tpa (+306.7%) |
|
Phase 2 Expansion Design Capacity (Year 4) |
40,000 tpa of MREC |
40,000 tpa of MREC |
|
Power, Water and Logistics Infrastructure |
||
|
Primary Power Supply Arrangement |
Grid connection under assessment |
80 MW power purchase agreement (PPA); RNT / 220 kV transmission line |
|
Associated Hydroelectric Generation Facility |
Not contracted |
Laúca Hydroelectric Scheme (2,070 MW installed capacity) |
|
Process Water Discharge Management |
Zero Liquid Discharge (ZLD) target |
Zero Liquid Discharge; 100% recycling (as disclosed) |
|
Logistics Corridor Access |
Lobito Railway / EN260 Highway |
Lobito Atlantic Railway (LAR) |
|
Environmental and Operational Performance |
||
|
Direct Scope 1 GHG Emissions |
286 tCO₂e |
1,536 tCO₂e (+437.1%) |
|
Indirect Scope 2 GHG Emissions |
0 tCO₂e |
205 tCO₂e (local grid electricity imports) |
|
Total Energy Consumption |
1,048,710 kWh |
5,907,010 kWh (+463.3%) |
|
Diesel Fuel Energy Consumption |
1,047,923 kWh |
5,587,143 kWh (+433.2%) |
|
Groundwater Abstraction |
7,300 m³ |
2,334 m³ (-68.0%) |
|
Surface Water Abstraction |
0 m³ |
873 m³ (concrete batching) |
|
Initial Environmental Rehabilitation Provision |
$0 |
$111,382 present value; $270,137 undiscounted cash estimate |
Longonjo’s JORC Ore Reserve comprises 21.54 Mt grading 3.04% TREO (0.65% NdPr oxide), supporting a 20-year mine life based on open-pit extraction across the upper 30 meters of weathered carbonatite. The deposit permits mechanical excavation without primary drilling or blasting. Processing utilizes on-site double beneficiation, consisting of crushing, ball milling, flotation, and a sulphuric acid leach/roast circuit designed to reject naturally occurring thorium and uranium radionuclides into an on-site Tailings Storage Facility (TSF) compliant with the Global Industry Standard on Tailings Management (GISTM). Detailed engineering by Lycopodium reached 65% completion, with 100% of the ball mill manufactured and 50% of the acid plant completed by ProProcess off-site.
Primary power infrastructure was formalized in September 2025 via a binding Power Purchase Agreement (PPA) with state grid operator Rede Nacional de Transporte de Electricidade (RNT). The contract secures 80MW at 220kV from the Belém do Dango substation in Huambo, connected to the 2,070MW Laúca Hydroelectric Scheme on the Kwanza River. Logistics leverage a 4km link to the EN260 highway and the Benguela rail line, connecting to the Lobito Atlantic Railway (LAR) consortium operated by Trafigura, Mota-Engil, and Vecturis under a 30-year concession backed by US$553 million in US International Development Finance Corporation (DFC) financing. Containerized export shipments will depart via the Port of Lobito, following a US$2.0 billion modernization program that added a 414m container terminal and a 310m ore terminal jetty.
Downstream refining was transferred to external counterparties under non-binding frameworks. MREC product qualification was secured with an unnamed tier-1 manufacturer in FY2026. Commercial frameworks include a June 2025 non-binding MOU with Toyota Tsusho Corporation for up to 20,000 tpa MREC over five years routed through Toyotsu Rare Earths India, a non-binding MOU with Hanwa Co. Ltd. covering up to 100% of Phase 1 output supported by Japan's Ministry of Economy, Trade and Industry (METI), a June 2025 MOU with ReElement Technologies for 20,000 tpa MREC processed in Marion, Indiana, and an October 2025 MOU with Vacuumschmelze (VAC) / eVAC Magnetics to supply feedstock to a permanent magnet plant in South Carolina. European and US automotive original equipment manufacturers (OEMs)—including Mercedes-Benz, BMW, Volkswagen, Jaguar Land Rover, Tesla, and General Motors—are engaged under pilot qualification programs, alongside grant backing from the EU Horizon Europe PERMANET initiative.
HDIN Institutional Verdict
Pensana Plc’s operational reconfiguration from a vertically integrated refiner into an upstream concentrate exporter resolves the capital hurdle of building a domestic processing plant in the UK, but shifts technical risk toward third-party refiners. By canceling the Saltend refinery, the Group cut fixed processing infrastructure commitments, yet it sacrificed the pricing premiums of refined neodymium and praseodymium oxides in exchange for selling an unseparated intermediate carbonate.
The investment thesis contains three operational and capital disconnects:
* The Absolute Contractual Offtake Deficit: Pensana Plc possesses zero binding take-or-pay sales contracts across its global customer base. The totality of its future commercial revenues rests on non-binding MOUs. The US$160.0 million project debt facility arranged by Absa Bank Limited and supported by Export-Import Bank of the United States (U.S. EXIM) risk insurance requires legally enforceable customer agreements with embedded floor prices. Without definitive floor-price mechanics, the debt package cannot proceed to drawdown.
* Severe Capital Bottlenecks and Working Capital Exhaustion: The Group’s available liquid reserves stood at US$1.10 million on 23 October 2026. Balanced against an audited trailing monthly net cash depletion velocity of US$4.17 million, effective cash runway contracted to approximately eight days. While site operations were scaled back to preserve cash, contractual capital commitments total US$22.11 million. Survival depends on drawing down the US$150.0 million balance from Cascade Natural Resources, an entity backed by the State of Qatar that provided US$15.0 million in April 2026 but left the remaining commitment conditional on pending project documentation.
* Sovereign Equity Dilution and Cash Ring-Fencing: To bridge funding gaps, parent control of operating entity Ozango Minerais SA was diluted from 84.0% to 68.4% through a US$25.0 million direct asset-level placement to FSDEA’s subsidiary, ASF Yova Mining Holding Limited. Non-controlling interests now control 31.6% of the asset. Concurrently, senior debt covenants mandate a 6-to-12-month Debt Service Reserve Account (DSRA) and project debt service coverage ratios (DSCR > 1.30x), which legally isolate operating cash within the Republic of Angola and constrain dividend repatriation to London parent equity holders.
Pensana Plc's competitive standing rests on its access to low-cost infrastructure, including the 2.07GW Laúca hydroelectric PPA, open-pit weathered ore, and the G7-backed Lobito rail corridor. However, until management secures binding take-or-pay contracts and completes documentation for its stalled US$150.0 million equity injection, the company remains exposed to immediate solvency challenges.
Presentation Download & Video Access
- Presentation Download: Click the PDF download link under 'Related Topics' to access the full institutional presentation of this report.
- Video Link: Click this link to watch the HDIN analyst briefing on YouTube.
About HDIN Research
HDIN Research is a global market intelligence and strategic advisory firm specializing in institutional-grade financial analysis, supply chain audits, and macroeconomic forecasting. Our dedicated sector analysts deliver actionable, data-driven insights tailored for private equity, hedge funds, and corporate strategy teams. Visit us at http://www.hdinresearch.com.
2026 AI Transparency Footer
This intelligence report was authored by HDIN Research analysts following a rigorous audit of official corporate filings. AI was utilized for massive-scale data synthesis and structural drafting, ensuring 100% inclusion of reported data points. All strategic insights, financial modeling, and final verdicts were verified by our editorial board to ensure professional accuracy and compliance with 2026 Google Search E-E-A-T standards.