VivoPower PLC: Strategic HPC Pivot Near Mo i Rana Backstopped by $28.8M Debt Retirement as Uncollected Middle East Receivables Expose Liquidity Friction
1. VivoPower PLC consolidated the 41.5 MW Mo i Rana hydro data center ($37.7 million headline acquisition), driving FY2026 revenue up 4,072.1% to $2.55 million, yet 96.3% of revenue depends on a single crypto-hosting contract terminating in July 2027.
2. Balance sheet leverage was restructured through the post-fiscal elimination of $28.8 million in AWN shareholder debt principal, though liquidity remains constrained by $52.38 million in unpaid Ceres equity proceeds trapped in Middle East banking channels.
3. Shareholder approval of a 970-million-share allotment authority alongside Foreign Private Issuer governance exemptions insulates the combined Chairman/CEO structure, concentrating operational execution risk on securing replacement 40 MW artificial intelligence colocation off-takers.
Figure VivoPower PLC: Strategic Pivot & Institutional Financial Blueprint
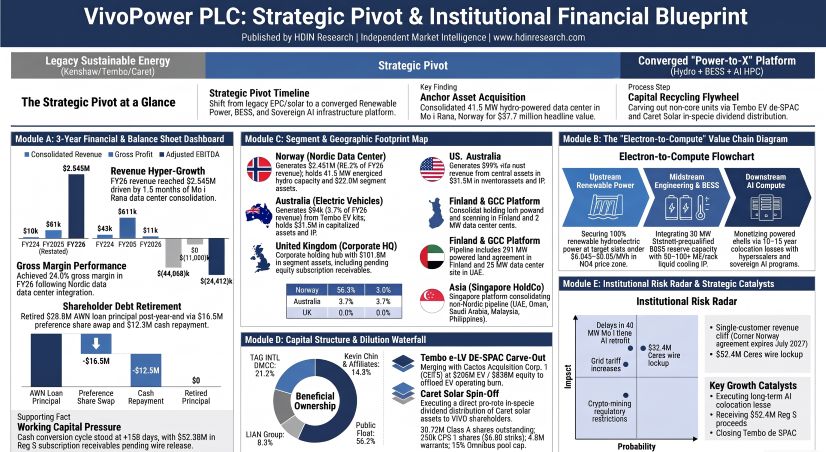
Segmental Realities, Capital Re-engineering, and Balance Sheet Diagnostics
VivoPower PLC [NASDAQ: VIVO] filed its audited SEC Form 20-F for the fiscal year ended June 30, 2026, prepared by independent auditor WithumSmith+Brown, PC (succeeding PKF Littlejohn LLP, which audited FY2024). The group's financial statements reflect an operational pivot toward sovereign Artificial Intelligence (AI) and High-Performance Computing (HPC) data center infrastructure, accompanied by restated FY2025 comparatives and extensive capital re-engineering.
Consolidated revenue expanded 4,072.1% year-over-year to $2.55 million in FY2026, up from a restated $61 thousand in FY2025 and $16 thousand in FY2024. This growth was driven by the 1.5-month post-acquisition operational consolidation of the Mo i Rana data center in Norway ($2.45 million contribution), while the Electric Vehicle (EV) division, Tembo e-LV B.V., generated $94 thousand ($48 thousand from conversion kit sales and $46 thousand from vehicle specification conversions). Gross profit rose 5,454.5% to $611 thousand, yielding a consolidated gross margin of 24.0% (+600 basis points compared to 18.0% in FY2025; FY2024 gross margin stood at 268.8% due to net inventory adjustments and zero cost of goods allocated to prototype conversion runs).
Table Adjusted EBITDA Reconciliation (Non-IFRS Disclosures)
|
Adjusted EBITDA Reconciliation (USD Thousands) |
FY2024 |
FY2025R |
FY2026 |
|---|---|---|---|
|
Loss from Continuing Operations |
($45,819) |
($17,306) |
($50,353) |
|
(+) Income Tax Expense / (Benefit) |
$1,603 |
($691) |
$1,618 |
|
(+) Net Finance Costs |
$4,619 |
$3,465 |
$21,328 |
|
└─ Finance Expense |
$4,619 |
$3,465 |
$7,031 |
|
└─ Fair Value Loss on Derivative Liabilities |
$0 |
$0 |
$14,753 |
|
└─ Finance Income |
$0 |
$0 |
($456) |
|
(+) Depreciation & Amortization |
$1,130 |
$517 |
$928 |
|
(+) Impairment Losses |
$29,686 |
$2,531 |
$616 |
|
(+) Restructuring & Non-Recurring Costs |
$1,392 |
$412 |
$1,451 |
|
(+) Other Adjustments |
$0 |
($8) |
$0 |
|
Adjusted EBITDA (Non-IFRS) |
($44,068) |
($11,080) |
($24,412) |
|
(+) Non-Cash Share-Based Payments |
$750 |
$1,900 |
$13,099 |
|
Adjusted EBITDA Excluding Share-Based Payments |
— |
($9,180) |
($11,313) |
General and administrative (G&A) overhead expanded 138.9% to $26.51 million in FY2026, relative to $11.10 million in FY2025 and $7.52 million in FY2024. Cash-settled G&A rose 45.8% to $13.41 million, driven by $18.92 million in aggregate professional fees ($5.99 million settled in cash, $12.93 million settled in equity) for M&A underwriting, listing legalities, and debt restructuring. Non-cash share-based compensation surged 589.4% to $13.10 million. Operating losses widened 118.7% to $(25.34) million.
Below-the-line items were dominated by a 515.5% expansion in net finance costs to $21.33 million, driven by a $14.75 million mark-to-market non-cash fair value loss on warrant derivative liabilities linked to cashless reset features, alongside $6.58 million in net borrowing charges. Net loss attributable to equity owners reached $(49.73) million, compared to $(15.66) million in FY2025 and $(46.70) million in FY2024.
Table Reportable Business Segment Financial Performance, Asset Allocation, and Strategic Execution Overview, FY2024–FY2026 (USD Thousands)
| Reportable Business Segment | FY2024 Revenue ($'000) | FY2025R Revenue ($'000) | FY2026 Revenue ($'000) | FY2026 Operating Profit/(Loss) ($'000) | Segment Assets at June 30, 2026 ($'000) | Strategic & Carve-Out Execution Status |
| Data Center (HPC/AI) | $0 | $8 | $2,545 | $41 | $22,018 | Consolidated May 12, 2026; 41.5 MW hydro site at Mo i Rana; 24.0% gross margin. |
| Electric Vehicles (Tembo) | $16 | $53 | $94 | $(3,013) | $31,468 | De-SPAC merger agreement with Cactus Acquisition Corp. 1 Limited [NASDAQ: CCTS] ($200M EV). |
| Sustainable Energy (SES) | $0 | $0 | $0 | $190 | $87 | Residual microgrid operations; operating gain driven by vendor liability releases. |
| Solar Development (Caret) | $0 | $0 | $0 | $(13) | $29 | 586 MW-DC legacy pipeline fully impaired in FY2025; shifted to in-specie dividend distribution. |
| Corporate Office | $0 | $0 | $0 | $(26,326) | $101,772 | Central administrative center; assets include $53.3 million Ceres subscription receivable. |
| Discontinued Ops (Kenshaw) | $11,811 | $0 | $0 | $621 | $1,051 | Electrical EPC divested July 2, 2024 for
1.2M); warranty provision derecognized. |
DuPont decomposition demonstrates persistent structural asset underutilization. Return on Equity (ROE) registered at -183.6% in FY2026. Net Profit Margin stood at -1,954% (versus -25,669% in FY2025 and -291,875% in FY2024), Asset Turnover improved incrementally to 0.0204x (from 0.0009x in FY2025 and 0.0004x in FY2024) across average total assets of $124.58 million, and Financial Leverage closed at 4.60x.
Working capital metrics reveal inventory holdings of $986 thousand (primarily Tembo conversion assemblies), generating an inventory turnover of 1.81x and Days Sales of Inventory (DSI) of 201.7 days (improving from 10,220 days in FY2025 and 22,306 days in FY2024). Days Sales Outstanding (DSO) settled at 102.8 days on ending trade receivables of $1.43 million. Days Payable Outstanding (DPO) calculated against Cost of Goods Sold registered at 1,162.2 days ($8.99 million ending trade payables); DPO measured against combined cash operating expenditures and cost of sales stood at 146.5 days (compared to 131.7 days in FY2025 and 592.5 days in FY2024), establishing a cash conversion cycle of +158.0 days.
At fiscal year-end, total borrowings and lease liabilities stood at $39.03 million: $12.88 million in current shareholder loans, $15.86 million in non-current shareholder loans, and $10.29 million in total lease liabilities ($741 thousand current; $9.55 million non-current), set against cash and cash equivalents of $2.02 million and restricted cash collateral of $61 thousand. Net debt stood at $36.95 million, equating to a 100.04% (1.00x) Net Debt-to-Equity ratio against total equity of $36.93 million (which was elevated by a $60.5 million share subscription reserve).
The shareholder loan facility held by AWN Holdings Limited (AWN), an entity controlled by Executive Chairman and Chief Executive Officer Kevin Chin, originally stemmed from a June 30, 2021 refinancing of $21.1 million at 8.0% interest plus a 0.8% line fee. Following amendments that deferred principal payments to April 1, 2025, raised interest to 10.0% plus a 2.0% line fee, and consolidated the credit limit to $34.0 million on June 30, 2024 alongside 1,200,000 cashless warrants ($1.00 strike, $5.44 million grant fair value), total balances owed reached $46.40 million.
Sub-loans to Aevitas O Holdings Pty Limited carried rates of 10.0% to 12.5%, or BBSY plus a 15.0% margin (effective rates of 18.75% to 19.82%), encompassing ~$12.5 million across AU$1.5 million, $3.0 million, $3.0 million, and AU$0.75 million tranches. Post-fiscal-year-end transactions retired $28.8 million in principal via $16.5 million in Series 1 Preference Shares and $12.3 million in cash, eliminating shareholder debt principal and positioning the parent group in a pro forma net cash condition, though ~$16.0 million in accrued interest remains in active conversion negotiations.
External equity and mezzanine financings altered the share architecture:
* PIPE 1 Financing ($29.7 Million Facility): Issued 255,000 Series 1 Convertible Preference Shares at $100 per share ($25.5 million gross cash proceeds), which included the $16.5 million AWN principal swap and a $4.15 million (41,507 shares) buyout of Aevitas preference shares from Panaga Group Trust (a trust affiliated with Kevin Chin). CPS 1 holds liquidation seniority, a 6.0% per annum payment-in-kind (PIK) dividend, and converts at $6.80 per Class A Ordinary share.
* PIPE 2 Financing ($50.0 Million Facility): Executed July 2026; received $17.5 million cash ($12.3 million redeployed to retire AWN debt), with $16.0 million remaining subject to final institutional Know-Your-Customer (KYC) clearances.
* Ceres Regulation S Equity Agreement ($121.0 Million Commitment): Subscribed for 20.0 million Class A shares at $6.05 per share. Tranche 1 ($60.5 million) was allotted; $8.12 million in cash was collected, leaving $52.38 million uncollected and recognized on the balance sheet within the $53.3 million trade and other receivables line due to international wire and SWIFT processing controls in the Middle East.
Operating cash outflows narrowed 53.5% in FY2026 to $(3.59) million (relative to $(7.71) million in FY2025 and an inflow of $1.49 million in FY2024). Net investing outflows reached $(32.07) million, dominated by $(20.89) million in net cash paid to acquire Cromwell AS (Mo i Rana), $(10.37) million deployed into unlisted digital investments and Ripple Labs holdings (subsequently liquidated upon terminating the XRP treasury policy in February 2026), $(526) thousand in physical PP&E, and $(289) thousand in legacy solar/EV development. Financing cash flows delivered $37.62 million, supported by $25.50 million in gross PIPE 1 subscriptions, $13.01 million in public equity distributions, offset by $(979) thousand in net loan repayments to AWN. Free cash flow registered at $(4.41) million.
Auditor WithumSmith+Brown, PC issued an unqualified opinion confirming VivoPower's going-concern status through June 30, 2027. Monthly operational cash burn averages ~$710 thousand ($8.5 million annualized for the group; ~$520 thousand or $6.2 million annualized excluding Tembo). The consolidated Mo i Rana asset generated ~$5.9 million in pro forma annual EBITDA for calendar year 2025 under its digital asset hosting terms.
Available unrestricted cash of $7.22 million post-year-end ($2.02 million June 30 cash plus $17.50 million received from PIPE 2 minus $12.30 million cash deployed for AWN principal) provides 10.2 months of standalone operating runway without uncollected Ceres receivables. Collection of the remaining $16.0 million from PIPE 2 would extend operational cash sustainability to 32.7 months.
Contractual forward cash liabilities comprise:
1. Deferred Acquisition Obligations: $10.25 million payable to LIAN Group for Cromwell AS ($5.00 million due November 12, 2026; $5.25 million due May 12, 2027), with up to $2.00 million held back for tax indemnity retentions.
2. TAG INTL DMCC Credit Facility: $5.07 million loan repayment maturing October 30, 2026 ($8.5 million advanced in early 2026; $0.9 million advanced toward Tembo).
3. EnduroCo Convertible Note Commitment: Unfunded commitment of up to A$16.0 million (~$11.0 million USD; $1.12 million funded, carried at $1.6 million) at 5.0% interest per annum.
Operational Infrastructure, Power Economics, and Cross-Border Asset Architecture
Table Physical Infrastructure Footprint & AI Expansion Map
|
Strategic Infrastructure / Business Platform |
Location |
Key Capacity / Asset Metrics |
Development Status & Strategic Execution |
|---|---|---|---|
|
1. Nordic Operational Anchor |
Mo i Rana, Norway |
||
|
Energized Hydroelectric Capacity |
Norway (Statnett NO4 Zone) |
41.5 MW |
Existing energized hydroelectric power capacity. |
|
Power Purchase Terms |
Mo i Rana, Norway |
Wholesale tariffs below $0.045–$0.05/kWh |
Low-cost power procurement supporting AI data center economics. |
|
Land Footprint |
Mo i Rana, Norway |
50,500 sqm |
42,000 sqm leased through 2076; 8,500 sqm leased through 2037. |
|
Phase 1 AI Conversion |
Mo i Rana, Norway |
40.0 MW |
AI infrastructure upgrade involving CTS Group / Øijord & Aanes. |
|
Phase 2 Power Allocation |
Mo i Rana, Norway |
40.0 MW |
Additional interconnection application submitted to Statnett. |
|
Grid Services |
Mo i Rana, Norway |
30.0 MW balancing reserve |
Comprises 12 MW of FCR-D and 18 MW of mFRR capacity. |
|
2. International Sovereign AI Pipeline |
Singapore HoldCo SPV |
||
|
Finland Powered Land Agreement |
Finland |
291.0 MW |
Powered land agreement with OGDC Pte Ltd for planned AI data center development. |
|
UAE AI Data Center Site |
United Arab Emirates |
25.0 MW |
Identified site for prospective AI data center development. |
|
Funding & Listing Strategy |
International |
Pre-IPO funding |
Planned pre-IPO financing and potential dual public listings on the London Stock Exchange (LSE) and Abu Dhabi Securities Exchange (ADX). |
|
3. Subsidiary Spin-Off Platforms |
Corporate Separation & Distribution |
||
|
Tembo e-LV B.V. |
Electric Vehicles |
$200 million EV / $838 million equity value |
Proposed De-SPAC transaction through Cactus Acquisition Corp. 1 Limited (NASDAQ: CCTS). |
|
Caret Solar LLC |
Solar Development |
586 MW-DC portfolio |
Planned direct in-specie distribution of the legacy solar development portfolio. |
The group's operational infrastructure centers on the 41.5 MW hydro-powered data center located in Mo i Rana within Norway's NO4 pricing zone, acquired on May 12, 2026 via Cromwell AS (renamed VivoPower Norge Infrastructure AS) for a headline consideration of $37.7 million ($20.89 million net cash, $10.25 million deferred payables, 1.51 million Class A shares, and 1.05 million warrants).
Physical tenure is governed by two long-term ground leases with Mo Industripark AS across 50,500 square meters (42,000 square meters running through February 29, 2076; 8,500 square meters running through December 31, 2037), carrying a combined base rent of NOK 6.3 million annually (~$600 thousand USD) indexed to Norwegian CPI. The leases are recognized as a $10.10 million Right-of-Use asset and a $10.29 million lease liability ($741 thousand current portion).
Electrical power is sourced via the Statnett SF transmission grid under long-term industrial contracts yielding wholesale costs targeted at <$0.045 to $0.05 per kWh. Phase 1 AI conversion civil works were mobilized on October 12, 2026, engaging CTS Group as preferred powered-shell contractor alongside local civil engineering firm Øijord & Aanes Entreprenørforretning AS.
The engineered shell architecture is specified to support direct-to-chip liquid cooling configurations with rack power densities of 50 to 100+ kW per rack. Phase 2 expansion encompasses an application for an additional 40 MW grid allocation with Statnett and the Norwegian Water Resources and Energy Directorate (NVE). Auxiliary revenue generation is anchored by an April 27, 2026 prequalification with Statnett SF to dispatch 30 MW of dynamic grid balancing capacity:
* Frequency Containment Reserve for Disturbances (FCR-D): 12 MW.
* Manual Frequency Restoration Reserve (mFRR): 18 MW.
Non-Nordic powered land assets have been consolidated under a Singapore-headquartered holding platform:
* Finland Powered Land Portfolio: Definitive agreement to acquire OGDC Pte Ltd, controlling 291 MW across energized and permitted sites in Finland (announced January 22, 2026). Operations face regulatory friction from the Finnish data center electricity tax increase enacted July 2026, raising tariffs from 0.05 cents to 2.24 cents per kWh.
* United Arab Emirates Platform: Binding framework to acquire, develop, and operate a 25 MW data center site in the UAE (announced January 20, 2026), alongside commercial activities managed by Tembo EUV Solutions FZCO in Dubai Silicon Oasis.
* Singapore Platform Dual-Listing: The board approved plans on August 17, 2026 to distribute non-Nordic pipeline rights (UAE, Oman, Saudi Arabia, Malaysia, Philippines, Finland) into a standalone entity, targeting a private institutional round followed by dual listings on the London Stock Exchange (LSE) and the Abu Dhabi Securities Exchange (ADX), leaving parent balance sheet capital uncommitted.
The Electric Vehicles segment operates through Tembo e-LV B.V. Management executed a Business Combination Agreement with Cactus Acquisition Corp. 1 Limited [NASDAQ: CCTS] valuing Tembo at a target enterprise value of $200 million and an equity valuation of $838 million. Final execution of the Form F-4 merger remains pending SEC review following overseas auditor transition delays.
Tembo's hardware platforms comprise conversion kits for Toyota LandCruiser 70 Series and Hilux utility vehicles (Tembo EUV), public utility conversions for Philippine Jeepneys via Sarao Motors (addressing a target addressable market of ~60,000 operational vehicles), and the purpose-built Tusker electric utility pickup truck, which secured full Australian/New Zealand on-road homologation in November 2024 at an A$74,000+ base price point.
Powertrains incorporate 65 kWh and 77 kWh battery packs providing ranges between 330 km and 400 km. Off-take arrangements comprise an exclusive 5-year distribution contract with Green Watt in Saudi Arabia covering 1,600 EUV conversions (valued at up to $85 million) and a partner assembly and supply contract signed October 31, 2025 with Associated Vehicle Assemblers Ltd. (AVA) in Nairobi, Kenya, serving mining and safari fleets (including Asilia Africa).
Caret Solar LLC’s legacy portfolio of 10 utility-scale solar sites in the United States, representing 586 MW-DC, was fully written down via impairment charges of $11.19 million in FY2024 and $1.55 million in FY2025. Following the termination of direct listing plans in July 2026, the board authorized an in-specie dividend spin-off of Caret shares directly to VivoPower equity holders.
A December 2025 review of 682 MW in mothballed solar project assets evaluated prospective behind-the-meter AI data center powering or wholesale disposal. In digital assets, 55 MW was allocated to active cryptocurrency mining in December 2024, deploying 1,000 Antminer L9 rigs under an asset-backed financing structure.
Critical Power operations, housed under Kenshaw Electrical Pty Limited, were sold on July 2, 2024 to ARA Group Limited for $0.8 million (AU$1.2 million), recording a discontinued operational profit of $621 thousand in FY2026 ($1.65 million in FY2025). The divestment transferred all generator servicing liabilities and warranty covenants to the buyer, reducing VivoPower’s warranty reserves from $2.1 million to $0.
Non-current asset allocations encompass $16.4 million in goodwill from the Cromwell transaction, $22.3 million in customer relationship intangibles and trade names, and $10.10 million in capitalized land leases.
Balance sheet reserves for legal, tax, and warranty contingencies totaled $3.76 million at June 30, 2026:
1. U.K. HMRC VAT Cancellation & PAYE Settlement: HM Revenue & Customs cancelled the VAT registrations of VivoPower PLC and subsidiary VISL in FY2024. In April 2026, VISL agreed to a Time-to-Pay settlement with HMRC concerning £1.21 million (~$1.55 million USD) in PAYE and VAT arrears, paying £127,555.77 in March 2026 and committing to monthly tranches of ~£48,400 running through May 2028. Both entities lodged appeals against VAT cancellation. Tax provisions of $2.39 million cover these exposures.
2. Skatteetaten (Norwegian Tax Administration) Audit: Initiated August 2025 against Arctic Norge Data I AS covering corporate tax and VAT for 2022 to 2025, and extended in December 2025 back to 2021. No assessments or penalties have been issued. The Cromwell share purchase agreement holds a $2.00 million indemnity retention against the $10.25 million deferred consideration to LIAN Group.
3. Commercial Disputes:
* *Accès Industriel Mining: Canadian arbitration over EV conversions settled for $557,229; final payment satisfied July 2, 2026.
* *Podium Engineering S.r.l.: Italian court dispute (Tribunal of Aosta, Case 708/2024) regarding EV engineering orders settled for EUR 150,000 (~$162,000 USD) against EUR 192,500 claimed.
* *Hebels Lease Guarantee: Dutch court (Rechtbank Oost-Brabant, Case 11589755) dismissed primary claims against the Eindhoven lease; EUR 44,046 was paid post-year-end, concluding the $75,000 settlement.
* *ComplianceQuest Inc.: U.S. Federal court litigation (M.D. Fla., Case 8:25-cv-01467) regarding $200,900 in software fees settled for $75,000.
* *Workato Subscription Claim: Jersey commercial claim for $75,900 settled for $42,500 payable in five monthly installments of $8,500 from June to October 2026.
* *BMS Design Dispute: Active U.K. dispute regarding ~£140,000 in invoiced EV services; unprovisioned.
HDIN Institutional Verdict
VivoPower PLC's corporate posture is defined by three governance, counterparty, and capitalization tensions:
The governance architecture combines the offices of Executive Chairman and Chief Executive Officer under founder Kevin Chin, whose beneficial ownership spans 4,397,828 Class A Ordinary shares (14.3% of total voting rights), comprising 3,076,446 shares via Arowana Global Impact Pty Ltd, 295,000 shares via Arowana International UK Ltd, 103,921 shares via Panaga Group Trust, and 891,618 shares via AWN Holdings Limited (excluding 1,200,000 cashless warrants). While 75.0% of the board is independent under Nasdaq listing rules (William Langdon, Audit Chair; Peter Jeavons, Remuneration Chair; Michael Hui, Director), oversight is structured under Foreign Private Issuer exemptions.
Under Nasdaq Listing Rule 5615(a)(3), VivoPower opts out of standard domestic rules, bypassing shareholder votes for dilutive private placements exceeding 20% of share capital, and reduces general meeting quorums to two shareholders under U.K. company law rather than Nasdaq’s 33.3% threshold. On January 30, 2026, shareholders approved an amendment authorizing the board to issue up to $116.4 million in nominal value—representing 970 million Class A Ordinary shares—and fully disapplied statutory pre-emption rights.
The company also approved an authorized class of Class B Ordinary Shares carrying 20 votes per share, though zero Class B shares are currently issued. Executive turnover remains elevated: CFO David Mansfield resigned May 31, 2026 after one year, succeeded by Syed Muhammad Nouman on July 20, 2026, while CTO Keith Loose exited March 2, 2026.
Executive incentives show divergence from operational milestones. Board remuneration totaled $1.94 million in FY2026, with 56% paid in equity. Kevin Chin received $1.18 million ($557,466 cash; $626,866 in 200,000 Deferred Share Units), while non-executive directors received 62% of their fees in equity ($156,716 each).
An amendment expanded the 2017 Omnibus Incentive Plan cap from 10% to 15% of diluted share capital, granting 1,132,000 units in FY2026 (weighted-average grant value of $5.10 million) against 151,000 units in FY2025. Vesting criteria remain predominantly time-based and capital-raise dependent, lacking linkage to operational key performance indicators such as energized IT capacity, Power Usage Effectiveness (PUE), or operating cash flow yields.
The primary operational constraint is counterparty exposure. The group relies on Corner Norway AS for 96.3% of continuing revenue ($2.45 million in FY2026, consisting of $1.44 million in hosting fees and $1.02 million from a 30% computing revenue share). This agreement terminates in or around July 2027 with no right of renewal. Discussions with a preferred AI enterprise were formally terminated on June 29, 2026, leaving replacement colocation terms non-binding.
Compounding this transition, on March 12, 2026, the Norwegian Parliament (Storting) instructed the executive government to draft legislation curbing data center capacity dedicated to digital asset mining, accelerating the deadline to secure an alternative AI off-taker.
Financial execution hinges on addressing the $52.38 million in unpaid Ceres equity subscriptions, held up in Middle East cross-border wire clearances. Until these funds clear or replacement colocation tenants are secured for the Mo i Rana site, the group's operations remain dependent on capital-raising authorizations and extended payable cycles (146.5 days cash DPO) to sustain its transition into a pure-play sovereign AI infrastructure operator.
Presentation Download & Video Access
- Presentation Download: Click the PDF download link under 'Related Topics' to access the full institutional presentation of this report.
- Video Link: Click this link to watch the HDIN analyst briefing on YouTube.
About HDIN Research
HDIN Research is a premier global market intelligence and strategic advisory firm specializing in institutional-grade financial analysis, supply chain audits, and macroeconomic forecasting. Our dedicated sector analysts deliver actionable, data-driven insights tailored for private equity, hedge funds, and corporate strategy teams. Visit us at http://www.hdinresearch.com.
2026 AI Transparency Footer
This intelligence report was authored by HDIN Research analysts following a rigorous audit of official corporate filings. AI was utilized for massive-scale data synthesis and structural drafting, ensuring 100% inclusion of reported data points. All strategic insights, financial modeling, and final verdicts were verified by our editorial board to ensure professional accuracy and compliance with 2026 Google Search E-E-A-T standards.