Elevra Lithium Limited: Uncapped Merchant Model Yields $46.88M Gross Profit Rebound Near NAL Facility as 84.5% China Export Dependency Exposes Downstream Margins
1. Elevra Lithium Limited [ASX: ELV] reversed prior operating deficits to deliver $46.88 million in gross profit and $14.35 million in consolidated Underlying EBITDA for FY2026, driven by eliminating legacy contract price caps and booking $58.75 million in positive provisional pricing adjustments.
2. Operational throughput reached 197,967 dry metric tons (dmt) at North American Lithium in Québec, yet commercial exposure remains acutely concentrated, with 84.5% ($170.35 million) of sales shipped to China and 76% cleared through a single commercial counterparty.
3. While a $255.28 million cash balance and a C$145.0 million credit facility insulate near-term solvency against negative operating cash flow (-$43.61 million), zero active downstream chemical conversion leaves unit realizations entirely exposed to merchant converter spreads and trade policy shifts.
Figure Elevra Lithium Limited: 2026 Strategic Performance & Commercial Architecture Blueprint
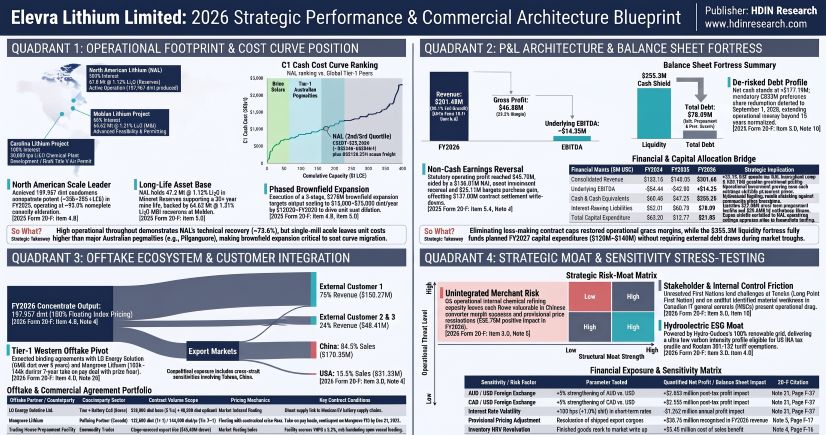 Segmental Realities, Margin Reversal, and Mark-to-Market Adjustments
Elevra Lithium Limited completed a structural transformation of its commercial revenue architecture in FY2026 following its all-stock merger with Piedmont Lithium Inc. on August 29, 2025. The transaction internalized and terminated legacy offtake mechanisms that previously capped 113,000 dmt/year (or 50% of North American Lithium output) between a $500/dmt floor and a $900/dmt ceiling. The settlement required a non-cash statutory write-down of $137.00 million on pre-existing contractual arrangements but transitioned 100% of commercial sales ($201.68 million across 197,967 dmt) to floating market-indexed pricing formulas linked to third-party price reporting agency (PRA) indices for 6.0% Li2O spodumene concentrate, adjusted for delivered grade (~5.2% Li2O).
The pricing transition, combined with operational throughput reaching 99.0% of NAL's 200,000 dmt/year nameplate capacity, yielded a gross margin expansion of 4,136 basis points from -18.1% in FY2025 to +23.2% in FY2026. Consolidated revenue expanded 39.1% year-over-year to $201.68 million. Cost of sales declined from $171.30 million to $154.80 million, benefiting from a $9.45 million inventory write-up to net realizable value (NRV). Statutory operating profit swung from a loss of $248.38 million in FY2025 to a positive $45.70 million in FY2026, reflecting a $156.01 million non-cash reversal of prior NAL impairments and a $33.11 million bargain purchase gain, which counterbalanced the $137.00 million contract settlement charge.
Under IFRS 15 and IFRS 9, revenue is recognized upon vessel loading based on provisional market indices, with final settlement determined over a quotation period spanning 30 to 90 days post-shipment. Benefiting from benchmark stabilization, Elevra recognized $58.75 million in positive provisional pricing adjustments in FY2026 trade receivables and revenue, reversing mark-to-market losses suffered during the FY2024–FY2025 commodity downturn.
Table CONSOLIDATED FINANCIAL & OPERATIONAL PERFORMANCE AUDIT
|
Financial & Operational Metric |
FY2024 |
FY2025 |
FY2026 |
YoY Change / Performance Trend |
|---|---|---|---|---|
|
Revenue ($M) |
$132.16 |
$145.02 |
$201.68 |
+39.1% |
|
Gross Profit / (Loss) ($M) |
($30.29) |
($26.28) |
$46.88 |
Turnaround |
|
Gross Margin (%) |
-22.9% |
-18.1% |
+23.2% |
+4,136 bps |
|
Cost of Sales ($M) |
$162.45 |
$171.30 |
$154.80 |
-9.6% |
|
Statutory Operating Profit / (Loss) ($M) |
($77.61) |
($248.38) |
$45.70 |
Turnaround |
|
Consolidated Underlying EBITDA ($M) |
($34.44) |
($42.90) |
$14.35 |
Turnaround |
|
NAL Segment Underlying EBITDA ($M) |
N/A |
N/A |
$45.72 |
Turnaround |
|
Corporate & Exploration Drag ($M) |
N/A |
N/A |
($31.37) |
N/A |
|
Net Profit / (Loss) After Tax ($M) |
($78.04) |
($247.11) |
$44.39 |
Turnaround |
|
Operating Cash Flow ($M) |
($42.38) |
($9.60) |
($43.61) |
-354.3% |
|
Investing Cash Flow ($M) |
($74.77) |
($32.12) |
$11.94 |
Positive Cash Flow |
|
Financing Cash Flow ($M) |
$40.56 |
$29.88 |
$240.60 |
+705.2% |
|
Capital Expenditures ($M) |
$69.20 |
$12.77 |
$21.03 |
+64.7% |
|
Cash & Cash Equivalents ($M) |
$60.46 |
$47.25 |
$255.28 |
+440.2% |
|
Total Interest-Bearing Debt ($M) |
$22.01 |
$50.73 |
$78.09 |
+53.9% |
|
Attributable Production (dmt) |
116,867 |
153,644 |
197,967 |
+28.9% |
|
Total Inventories ($M) |
$38.30 |
$30.96 |
$56.38 |
+82.1% |
|
Raw Materials & Consumables ($M) |
$29.35 |
$30.22 |
$36.45 |
+20.6% |
Following the post-merger operational consolidation, Elevra operates a single reportable operating segment: North American Lithium. Segment Underlying EBITDA reached $45.72 million (22.7% margin), offset by $31.37 million in corporate overhead and exploration costs (central administration accounted for -$30.07 million; secondary exploration absorbed -$1.30 million), leaving group Underlying EBITDA at $14.35 million (7.11% margin). Downstream processing projects—including the Carolina Lithium conversion asset (USA) and the inactive on-site NAL lithium carbonate plant—generated zero commercial revenue.
Table FY2026 SEGMENT REVENUE & OPERATIONAL CONTRIBUTION|
Segment / Asset |
Revenue ($M) |
Revenue Share (%) |
Production (dmt) |
Underlying EBITDA ($M) |
|---|---|---|---|---|
|
North American Lithium |
$201.68 |
100.0% |
197,967 |
$45.72 |
|
Carolina Lithium (USA) |
$0.00 |
0.0% |
0 |
$0.00 |
|
Moblan Project (Québec) |
$0.00 |
0.0% |
0 |
$0.00 |
|
Corporate & Exploration |
$0.00 |
0.0% |
0 |
($31.37) |
|
Consolidated Group |
$201.68 |
100.0% |
197,967 |
$14.35 |
Operating cash flows registered an outflow of -$43.61 million, an increase from -$9.60 million in FY2025. This was driven by $25.20 million in non-recurring transaction and integration expenses from the Piedmont transaction, combined with a $17.87 million working capital absorption into inventories. Total inventories climbed 82.1% to $56.38 million (finished goods rose from $13.62 million to $36.46 million; work-in-progress ore stockpiles reached $11.35 million) due to run-of-mine ore build-ups and maritime port vessel scheduling. Normalized for non-recurring merger friction, operating cash burn was -$18.41 million.
Investing cash flow turned positive at +$11.94 million, as $34.45 million in net cash acquired from Piedmont exceeded $24.03 million in property, plant, and equipment (PP&E) cash purchases. Financing activities generated $240.60 million, driven by $253.89 million in gross equity placement and share purchase plan proceeds, lifting cash balances to $255.28 million.
Total balance sheet debt expanded 53.9% to $78.09 million. Current liabilities include $45.60 million in contract prepayment note facilities secured against export vessel loadings. Under these facilities, International Trading Company 1 provides up to $30.0 million ($29.0 million drawn as of September 30, 2026), and International Trading Company 2 provides an inherited $25.0 million facility ($4.0 million drawn as of September 30, 2026), both bearing interest at Secured Overnight Financing Rate (SOFR) + 2.4%. Non-current debt includes $20.00 million in Class B redeemable non-convertible preference shares held by Investissement Québec (IQ) carrying a 5.0% annual dividend ($1.56 million/year). On January 30, 2026, Elevra and IQ executed a formal amendment deferring mandatory redemption to September 1, 2028. Total financial expenses stood at $5.77 million (comprising $3.15 million on contract liabilities and $1.56 million on preference shares), against cash interest paid of $0.68 million, establishing an accrual interest coverage ratio of 2.48x and a cash interest coverage ratio of 21.0x.
Elevra operates without financial derivative hedging instruments against commodity benchmarks, interest rates, or foreign currency pairs. Effective July 1, 2025, the group changed its presentation currency to U.S. dollars, while functional currencies remain segmented: Australian dollars (AUD) for the corporate parent, Canadian dollars (CAD) for operating mining subsidiaries, and U.S. dollars (USD) for commercial financing and Carolina operations. Other Comprehensive Income (OCI) recorded a net loss of -$16.36 million in FY2026, bringing cumulative reserves to -$84.58 million, driven by -$66.69 million in cumulative foreign currency translation reserve losses and a -$26.46 million business combination reserve adjustment from acquiring Piedmont's 25% non-controlling interest in NAL.
Table CONTRACTUAL COMMITMENTS & LIABILITIES MATURITY PROFILE ($M)
|
Obligation Category |
Carrying Amount ($M) |
Less Than 1 Year ($M) |
1–3 Years ($M) |
3–5 Years ($M) |
More Than 5 Years ($M) |
Contractual Basis / Key Terms |
|---|---|---|---|---|---|---|
|
Contracted Capital Expenditure (PP&E) |
$18.30 |
$18.30 |
$0.00 |
$0.00 |
$0.00 |
Tailings / Mill |
|
NAL Brownfield Expansion |
$270.00 |
$130.00 |
$140.00 |
$0.00 |
$0.00 |
Three-phase expansion program |
|
Prepayment Borrowing Notes |
$45.60 |
$45.60 |
$0.00 |
$0.00 |
$0.00 |
SOFR + 2.4% |
|
Lease Liabilities (Undiscounted) |
$13.50 |
$2.00 |
$5.10 |
$3.80 |
$2.60 |
Discounted carrying value: $9.74 million |
|
IQ Preference Shares (Principal) |
$20.00 |
$0.00 |
$20.00 |
$0.00 |
$0.00 |
Due September 1, 2028 |
|
LCSC / CGF Convertible Notes |
$47.45 |
$0.00 |
$0.00 |
$47.45 |
$0.00 |
C$65 million drawn; maturity in 2031 |
|
Total Contractual Commitments |
$414.85 |
$195.90 |
$165.10 |
$51.25 |
$2.60 |
Excludes contingent obligations |
Executive Key Management Personnel (KMP) compensation remained anchored to short-term incentives (50% cash, 50% 12-month deferred equity) split 60% operational/financial Underlying EBITDA hurdles, 20% ESG/safety (total recordable injury frequency rates and First Nations consultation), and 20% strategic transactions. Long-Term Incentives (LTI) execute across a 3-year performance period evaluated against Relative Total Shareholder Return (TSR) against global listed lithium peers, omitting Return on Invested Capital (ROIC) or Return on Capital Employed (ROCE) metrics.
Elevra operates the largest active hard-rock spodumene concentrate asset in North America, anchored in the Abitibi-Témiscamingue mining hub of Québec, Canada. The primary operations at North American Lithium encompass an open-pit mine, a crushing circuit, an optical ore-sorting installation, and a flotation concentrator connected to Hydro-Québec’s 161 kV transmission line, which supplies 100% renewable hydroelectric power.
Table MINERAL ASSET PORTFOLIO & OPERATIONAL STAGE AUDIT
|
Asset Name |
Location |
Ownership Interest |
Development Status |
Capacity / Production Target |
Resources / Reserves / Project Details |
|---|---|---|---|---|---|
|
North American Lithium (NAL) |
La Corne, Québec, Canada |
100.0% |
Producing |
200,000 dmt/year (expansion target: 373,000 dmt/year) |
Reserves: 47.2 Mt at 1.12% Li₂O |
|
Moblan Project |
James Bay, Québec, Canada |
60.0% |
Feasibility |
300,000 dmt/year (target) |
Measured and Indicated Resources: 64.6 Mt at 1.21% Li₂O |
|
Carolina Lithium |
North Carolina, USA |
100.0% |
Permitting |
30,000 tpa lithium hydroxide (LiOH) plant |
Under review pursuant to Subpart 1300 |
|
Authier Deposit |
Val-d'Or, Québec, Canada |
100.0% |
Exploration |
Potential satellite mill-feed source |
Intended to supply an integrated hub |
|
Morella JV |
Pilbara, Western Australia |
49.0% |
Exploration |
Tenement targets |
Early-stage exploration |
|
Ewoyaa Project |
Ghana, West Africa |
0.0% |
Divested |
300,000 dmt/year (historical project target) |
Divested for $71.0 million |
Technical disclosures compliant with SEC Subpart 1300 reflect an updated geological model based on 562 infill drill holes spanning 153,047 meters across 117 pegmatite dykes. Total Mineral Reserves at NAL expanded 151% to 47.2 million metric tons (Mt) grading 1.12% $\text{Li}_2\text{O}$ (0.2 Mt Proven at 0.93% and 47.0 Mt Probable at 1.12%), supporting an operational Life of Mine (LOM) exceeding 20 years at the current nameplate throughput of 6,500 to 6,800 tonnes per day (tpd). Qualified Persons (QPs) applied an economic pit shell price assumption of US$1,250/t for 6.0% $\text{Li}_2\text{O}$ spodumene concentrate (US$1,125/t for 5.4% shipped product), an exchange rate of 0.74 CAD/USD, an ore cut-off grade of 0.60% $\text{Li}_2\text{O}$, a 7.1:1 waste-to-ore strip ratio, and a 73.6% metallurgical recovery rate. Mineral Resources exclusive of reserves encompass 22.1 Mt Indicated at 1.12% $\text{Li}_2\text{O}$ and 16.8 Mt Inferred at 1.05% $\text{Li}_2\text{O}$, constrained using a US$1,550/t (6.0% SC) pit shell.
At the Moblan Lithium Project (60% Elevra / 40% Investissement Québec), 1,085 surface drill holes drove an 89% conversion of total resources into high-confidence categories. Measured and Indicated Resources expanded 602% to 64.62 Mt grading 1.21% $\text{Li}_2\text{O}$ (3.76 Mt Measured at 1.50% and 60.86 Mt Indicated at 1.19%), alongside 7.97 Mt Inferred at 1.06% $\text{Li}_2\text{O}$ (100% basis) at a 0.55% cut-off. Legacy reserves of 20.7 Mt were reclassified into M&I pending completion of an updated definitive feasibility study targeting 300,000 dmt/year of concentrate production. Moblan ore is subject to a Gross Overriding Revenue (GOR) royalty held by Lithium Royalty Corp., set at 2.5% on the first 1.0 Mt/year of ore and 1.5% thereafter.
To drive down unit operating costs—modeled in impairment tests between C$597/t and C$1,269/t (~US$440/t to US$930/t)—Elevra launched a $270.0 million, three-stage NAL brownfield expansion plan ($2.82 million spent on preliminary engineering through FY2026):
Table NAL THREE-STAGE BROWNFIELD INDUSTRIAL EXPANSION
|
Expansion Phase |
Target Completion Date |
Engineering Scope |
Target Capacity / Run Rate |
|---|---|---|---|
|
Stage 1 |
Mid-2027 |
Mill circuit de-bottlenecking and recovery improvements |
15%–20% increase in throughput |
|
Stage 2 |
Mid-2028 |
Secondary concentrator installation and flotation circuit expansion |
6,500 tonnes per day (tpd) |
|
Stage 3 |
Mid-2029 |
Primary crushing system replacement and ore sorting implementation |
6,800 tpd / 373,000 dmt per year |
Project capital is backed by cash reserves and a multi-tranche funding arrangement from the Canada Growth Fund via LCSC Holdings Inc. On July 31, 2026, Elevra closed an initial C$65.0 million tranche of convertible notes (under a total C$145.0 million facility) maturing in July 2031 at 3-month Canadian Overnight Repo Rate Average (CORRA) + 2.25%. An additional C$80.0 million tranche remains contingent on securing provincial environmental and construction permits for NAL Phase 5 and the regional Abitibi hub.
Supply chain infrastructure relies on trucking from La Corne to regional rail depots and deepwater maritime ports in Québec, incurring transportation costs of US$126.23/t to Asian destinations. Severe winter weather conditions in northern Québec create seasonal freight friction. To mitigate winter disruptions, Elevra constructed an enclosed crushed-ore dome to buffer mill feed. Raw materials and consumables expenses increased 20.6% YoY to $36.45 million due to deeper open-pit mining requiring higher mobile fleet diesel usage and increased grinding media consumption. Consumables remain multi-sourced across commercial suppliers, utilizing non-discretionary price-escalation clauses.
Environmental and site restoration provisions totaled $44.21 million at fiscal year-end, consisting of $22.71 million in Asset Retirement Obligations (ARO), $17.23 million in legacy onerous contract provisions, and $4.27 million in employee entitlements. The discounted ARO liability comprises $19.30 million for NAL (modeled for settlement between 2045 and 2047) and $3.40 million for an industrial landfill in Tennessee acquired via Piedmont (scheduled for closure between 2027 and 2028). Elevra recognized $320 thousand in discount unwinding accretion charges in FY2026 ($265 thousand in FY2025; $905 thousand in FY2024), utilizing a 10.0% real post-tax discount rate. To satisfy the Québec Mining Act, the company deposited $7.39 million in restricted cash with the Ministère des Ressources naturelles et des Forêts (MRNF) as financial guarantees.
Tailings management at NAL is transitioning from conventional wet tailings at Tailings Management Area No. 1 (where annual dam lifts are authorized) toward dry-stacked tailings infrastructure supported by a dedicated tailings filtration plant. Tailings Management Area No. 2 is planned for future phases, with permit applications required before the end of calendar year 2028. Sustaining capital expenditure of $21.03 million in FY2026 was largely deployed to tailings dam lifts and surface water diversion channels under approvals from the Ministère de l'Environnement, de la Lutte contre les changements climatiques, de la Faune et des Parcs (MELCCFP). Elevra is preparing environmental baseline documentation for the Bureau d'audiences publiques sur l'environnement (BAPE), scheduled for submission in 2027 to sanction processing throughput expansions beyond authorized thresholds.
Social license compliance is divided across jurisdictions. Moblan operates on Category III public lands under the James Bay and Northern Québec Agreement (JBNQA), with Environmental and Social Impact Assessments (ESIA) progressing under COMEX and Cree Nation Government review. Conversely, the Tansim exploration project faces active opposition from the Long Point First Nation, which has verbally challenged land access rights. In North Carolina, Carolina Lithium's proposed 30,000 tpa integrated lithium hydroxide facility received a draft Title V Air Quality Permit from the NCDEQ in September 2026 (public hearings held in October 2026), but conditional district zoning approvals from the Gaston County Board of Commissioners remain unapproved.
HDIN Institutional Verdict
Elevra Lithium Limited’s transformation into North America’s largest operational hard-rock merchant producer resolves the structural price-cap issues that previously hindered NAL's economics. However, institutional audit metrics reveal distinct operational and commercial vulnerabilities that challenge management's strategic narrative:
Table INSTITUTIONAL COUNTERPARTY RISK ALLOCATION
|
Counterparty |
Counterparty Type |
Contract Term / Expiry / Status |
Contracted Volume / Commitment |
Pricing / Financial Terms |
|---|---|---|---|---|
|
LG Energy Solution Ltd. |
Tier-1 battery manufacturer (South Korea) |
3 years; expires October 2029 |
240,000 dmt, plus 90,000 dmt optional volume |
Market-indexed |
|
Mangrove Lithium |
Canadian lithium refiner |
7 years, with a 7-year renewal option |
144,000 dmt per year (Years 2–7) |
Index-linked, with a price floor |
|
Trading Company 1 |
Commodity trading house |
Prepayment note |
Volume scaled to cargo deliveries |
SOFR + 2.4% |
|
Trading Company 2 |
Commodity trading house |
Prepayment note |
Volume scaled to cargo deliveries |
SOFR + 2.4% |
|
Piedmont Offtake (Legacy) |
Internalized OEM arrangement |
Terminated in August 2025 |
113,000 dmt per year (contractual cap) |
$137 million settlement |
|
Ewoyaa Offtake (Ghana) |
African asset-related offtake arrangement |
Asset sold in October 2026 |
50% of life-of-mine (LOM) offtake rights |
$71 million cash divestment |
Table GEOGRAPHIC REVENUE CONCENTRATION PROFILE
|
Destination Market |
FY2024 Revenue Share |
FY2025 Revenue Share |
FY2026 Revenue Share |
FY2026 Revenue (USD Million) |
|---|---|---|---|---|
|
China |
98.4% |
95.4% |
84.5% |
170.35 |
|
United States |
1.6% |
4.6% |
15.5% |
31.33 |
|
Total Consolidated |
100.0% |
100.0% |
100.0% |
201.68 |
Customer Concentration and Counterparty Risk: Commercial revenues remain concentrated, with 100% of FY2026 sales cleared through three counterparties. The lead off-taker accounted for 76% of total revenue ($153.27 million), Customer 2 represented 16% ($32.27 million), and Customer 3 contributed 8% ($16.13 million). Deliveries to China accounted for 84.5% ($170.35 million) of sales, down from 95.4% in FY2025 and 98.4% in FY2024, leaving operational cash flow dependent on Asian refining operational rates and exposed to trade policy friction involving U.S. Section 301/Section 122 tariffs (10% to 35%) and cross-strait geopolitical tensions.
Downstream Processing Deficits: Elevra operates with 0% active downstream chemical conversion capacity. The on-site NAL lithium carbonate plant remains idle, while the planned 30,000 tpa Carolina Lithium conversion facility remains caught in zoning and environmental appeals. This lack of vertical integration prevents Elevra from capturing the chemical margin spread between spodumene concentrate and battery-grade lithium hydroxide ($\text{LiOH}$) or carbonate ($\text{Li}_2\text{CO}_3$). Management’s mitigation strategy centers on two newly signed off-take commitments:
* A binding 3-year agreement with South Korea's LG Energy Solution Ltd. (executed October 7, 2026) for 240,000 dmt base volume (~80,000 dmt/year) plus up to 90,000 dmt optional volume, settled on market indices;
* A binding 7-year take-or-pay agreement with Mangrove Lithium (executed August 21, 2026) for 122,000 dmt in Year 1 and 144,000 dmt/year in Years 2 through 7 (with an option to scale by +20%/year or buy 72,000 dmt pre-operations), incorporating a contractual price floor.
However, the Mangrove agreement is subject to execution conditionality: Mangrove must secure project financing, reach a positive Final Investment Decision (FID) by December 31, 2028, and achieve commercial operations at $\ge$50% nameplate capacity within three years of FID. If Mangrove fails to meet these financing or construction milestones, the 144,000 dmt/year off-take channel will not materialize, returning Elevra to reliance on Chinese spot merchant converters.
Table GLOBAL LITHIUM HARD-ROCK PEER POSITIONING MATRIX
|
Operator / Asset |
Primary Geology |
FY2026 Production |
Estimated Cash Cost Curve Position |
Business Model / Integration |
|---|---|---|---|---|
|
Albemarle / SQM |
Atacama brine |
More than 150,000 tonnes LCE |
First quartile (below $4,000/t) |
Fully integrated producer and refiner |
|
Pilbara Minerals |
Pilgangoora spodumene pegmatite |
More than 600,000 dmt of concentrate |
First to second quartile |
Merchant producer / downstream joint ventures |
|
Elevra Lithium (North American Lithium) |
La Corne spodumene pegmatite |
197,967 dmt of concentrate |
Second to third quartile |
100% merchant mining operation |
|
Marginal Chinese Producers |
Lepidolite ore |
Variable output |
Fourth quartile (above $1,200/t) |
Unintegrated concentrate production |
Cost Curve Realities: Elevra sits in the 2nd to 3rd quartile of the global lithium cost curve. With NAL target unit operating costs ranging between C$597/t and C$1,269/t (~US$440/t to US$930/t) and freight to Asia running at US$126.23/t, Elevra operates above top-tier brine salars and scaled Australian pegmatite operations like Pilbara Minerals' Pilgangoora, although it maintains a cost advantage over 4th-quartile Chinese lepidolite operations. When benchmark concentrate prices drop toward US$800/t, Elevra’s operating cash flow margins contract sharply.
Capital Allocation and Liquidity Runway: Across FY2024–FY2026, Elevra allocated $103.00 million to PP&E and $38.13 million to exploration and evaluation, while returning $0 to equity holders in buybacks or dividends. Management bolstered liquidity via non-core asset sales—divesting its 22.5% interest in the Ewoyaa project in Ghana to Zhejiang Huayou Cobalt Co., Ltd. for $71.0 million in cash on October 23, 2026, and selling the Tabba Tabba tenements for US$3.5 million cash plus US$5.6 million in shares. With $255.28 million in liquid cash, undrawn tranches of the C$145.0 million LCSC convertible facility, and IQ preference share redemptions deferred to late 2028, Elevra possesses sufficient liquidity to fund its $120.0 million to $140.0 million FY2027 capex budget without tapping volatile debt capital markets.
Governance and Internal Control Friction: Independent auditor Ernst & Young identified a material weakness in internal control over financial reporting associated with ineffective Information Technology General Controls (ITGCs) governing user access provisioning, privileged access monitoring, and change management within Canadian ERP software. Elevra operates with exemptions from NASDAQ majority board independence mandates as a Foreign Private Issuer; four of eight directors reside outside the U.S., and two board members (Mr. Jorge M. Beristain and Mr. Allan Buckler) are scheduled to retire at the November 19, 2026 Annual General Meeting. Related-party cross-directorships persist via Morella Corporation Limited [ASX: 1MC], where Elevra directors James Brown and Allan Buckler hold executive and non-executive roles alongside Elevra's 49% stake in the Pilgangoora JV. Elevra incurred $379,286 in technical service fees to KMP-related entities in FY2026 ($279,236 in FY2025; $215,719 in FY2024), with $56 payable as of June 30, 2026. Resource Capital Fund VIII, L.P. (RCF) holds an influential 9.84% equity position (19,875,000 ordinary shares) paired with unlisted option tranches exercisable at AU$4.80 through December 31, 2028.
Elevra has built a substantial operational footprint in North American hard-rock mining and established a defensible cash position. However, unless management successfully resolves downstream integration bottlenecks, remediates Canadian financial ITGC deficiencies, and diversifies commercial counterparty exposure beyond China, the business remains an unhedged merchant miner exposed to the cyclicality of third-party chemical conversion spreads.
Presentation Download & Video Access
- Presentation Download: Click the PDF download link under 'Related Topics' to access the full institutional presentation of this report.
- Video Link: Click this link to watch the HDIN analyst briefing on YouTube.
About HDIN Research
HDIN Research is a premier global market intelligence and strategic advisory firm specializing in institutional-grade financial analysis, supply chain audits, and macroeconomic forecasting. Our dedicated sector analysts deliver actionable, data-driven insights tailored for private equity, hedge funds, and corporate strategy teams. Visit us at http://www.hdinresearch.com.
2026 AI Transparency Footer
"This intelligence report was authored by HDIN Research analysts following a rigorous audit of official corporate filings. AI was utilized for massive-scale data synthesis and structural drafting, ensuring 100% inclusion of reported data points. All strategic insights, financial modeling, and final verdicts were verified by our editorial board to ensure professional accuracy and compliance with 2026 Google Search E-E-A-T standards."