Ametek's Precision Moat vs. Keysight's AI Bet
Date : 2026-02-22
Reading : 482
In the evolving landscape of industrial technology, 2025 marked a definitive bifurcation in growth strategies between two sector giants. While the headline numbers show growth for both, an in-depth analysis by HDIN Research reveals a fundamental clash of philosophies: Ametek Inc. (AME) has doubled down on its role as a disciplined "Consolidator," prioritizing margin protection and cash flow, whereas Keysight Technologies (KEYS) is aggressively pivoting into an "Innovator" model, betting its balance sheet on the secular tailwinds of AI and 6G.
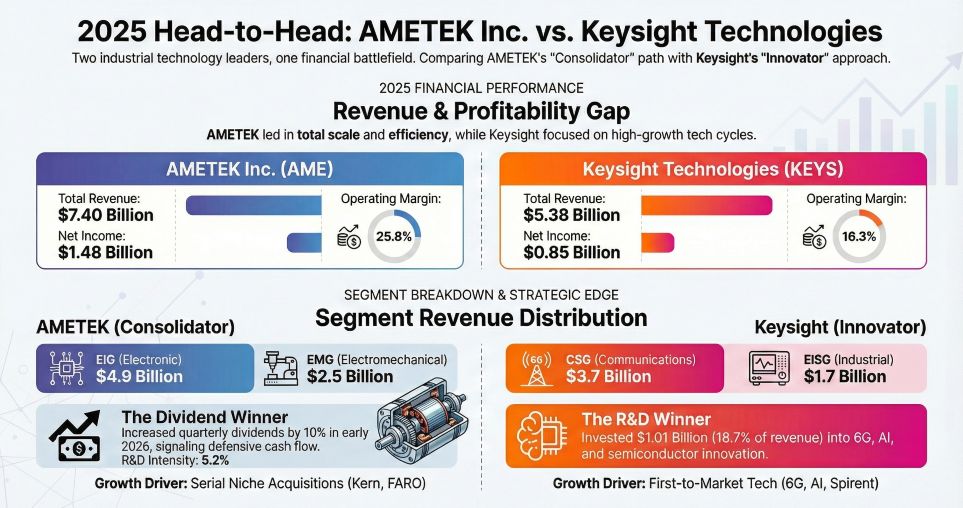
Figure 2025 Head-to-Head AMETEK Inc vs Keysight Technologies
 Capital Allocation: Operational Excellence vs. R&D Intensity
The divergence in 2025 financial performance is not merely a reflection of market demand, but a direct result of capital allocation strategies.
Ametek’s record sales of $7.4 billion and a commanding 25.8% operating margin are the fruits of its "Asset Light" model. The strategic implication here is clear: Ametek generates alpha through Operational Excellence. By integrating acquisitions like Kern Microtechnik and FARO Technologies into its lean structure, Ametek does not just buy revenue; it buys pricing power in niche markets. Its decision to hike dividends in early 2026 signals management’s confidence in this cash-compounding machine, regardless of macro volatility.
Conversely, Keysight’s strategy privileges long-term technological dominance over immediate margin expansion. With an R&D intensity approaching 19% of revenue ($1.0 billion)—nearly quadruple Ametek’s ratio—Keysight is sacrificing short-term profitability to build a moat around high-barrier technologies. The acquisition of Spirent serves as a cornerstone for this strategy, positioning Keysight not just as a hardware vendor, but as a critical partner in the "software-defined" lifecycle of AI data centers and next-gen telecommunications.
Strategic Pivots: The Hardware Moat vs. The Software Ecosystem
The battleground for 2026 is defined by how these companies view their customer relationships.
* Ametek: The Defensive Specialist. Ametek’s resilience lies in its exposure to "mission-critical" physical applications. From aerospace MRO (Maintenance, Repair, and Operations) to highly engineered medical components, Ametek’s portfolio is insulated from digital disruption. The strategy here is stability; by dominating fragmented niches, Ametek ensures high switching costs for its customers, protecting its 27.4% segment operating margins even during economic downturns.
* Keysight: The Digital Architect. Keysight is moving up the value chain. By increasing its software and services revenue to 24%, Keysight is reducing cyclicality through recurring revenue models. The "So What" for investors is the company’s exposure to the AI CAPEX boom. Keysight’s solutions for 800G/1.6Tb Ethernet and AI cluster efficiency are no longer optional tools but essential infrastructure for the hyperscale economy.
Industry Outlook: Navigating Geopolitics and Supply Chains
Both firms face the reality of a fractured global supply chain, yet their mitigation strategies differ. Ametek has leveraged its global manufacturing footprint—spanning from the Czech Republic to Malaysia—to localize production, effectively insulating its bottom line from 2025 tariff shifts. Keysight, with significant operations in Penang and China, faces higher geopolitical beta but is countering this through "First-to-Market" leadership in 6G and quantum standards, making its technology indispensable regardless of trade barriers.
HDIN Viewpoint: The Risk-Adjusted Value Proposition
At HDIN Research, our comparative analysis suggests that the choice between Ametek and Keysight for 2026 is a choice between predictable compounding and high-beta disruption.
We view Ametek (AME) as the superior vehicle for risk-adjusted defense. Its proven ability to integrate acquisitions while maintaining elite margins makes it a fortress asset in a volatile economic cycle. The consistency of its "Growth Model" offers institutional investors a hedge against industrial stagnation.
However, for portfolios seeking exposure to the transformative power of Artificial Intelligence and connectivity, Keysight (KEYS) presents a compelling entry point. While the integration of Spirent brings short-term cost pressure, Keysight’s monopoly-like status in early-stage R&D testing means it is effectively a "tax" on global innovation. As R&D budgets for 6G and AI infrastructure unlock, Keysight’s stock elasticity is poised to outperform the broader industrial sector.
Presentation Download
Click the PDF download link under “Related Topics” to access the presentation of this report.
About HDIN Research
HDIN Research focuses on providing market consulting services. As an independent third-party consulting firm, it is committed to providing in-depth market research and analysis reports.
Website: www.hdinresearch.com
E-mail: sales@hdinresearch.com
Figure 2025 Head-to-Head AMETEK Inc vs Keysight Technologies
Capital Allocation: Operational Excellence vs. R&D IntensityThe divergence in 2025 financial performance is not merely a reflection of market demand, but a direct result of capital allocation strategies.
Ametek’s record sales of $7.4 billion and a commanding 25.8% operating margin are the fruits of its "Asset Light" model. The strategic implication here is clear: Ametek generates alpha through Operational Excellence. By integrating acquisitions like Kern Microtechnik and FARO Technologies into its lean structure, Ametek does not just buy revenue; it buys pricing power in niche markets. Its decision to hike dividends in early 2026 signals management’s confidence in this cash-compounding machine, regardless of macro volatility.
Conversely, Keysight’s strategy privileges long-term technological dominance over immediate margin expansion. With an R&D intensity approaching 19% of revenue ($1.0 billion)—nearly quadruple Ametek’s ratio—Keysight is sacrificing short-term profitability to build a moat around high-barrier technologies. The acquisition of Spirent serves as a cornerstone for this strategy, positioning Keysight not just as a hardware vendor, but as a critical partner in the "software-defined" lifecycle of AI data centers and next-gen telecommunications.
Strategic Pivots: The Hardware Moat vs. The Software Ecosystem
The battleground for 2026 is defined by how these companies view their customer relationships.
* Ametek: The Defensive Specialist. Ametek’s resilience lies in its exposure to "mission-critical" physical applications. From aerospace MRO (Maintenance, Repair, and Operations) to highly engineered medical components, Ametek’s portfolio is insulated from digital disruption. The strategy here is stability; by dominating fragmented niches, Ametek ensures high switching costs for its customers, protecting its 27.4% segment operating margins even during economic downturns.
* Keysight: The Digital Architect. Keysight is moving up the value chain. By increasing its software and services revenue to 24%, Keysight is reducing cyclicality through recurring revenue models. The "So What" for investors is the company’s exposure to the AI CAPEX boom. Keysight’s solutions for 800G/1.6Tb Ethernet and AI cluster efficiency are no longer optional tools but essential infrastructure for the hyperscale economy.
Industry Outlook: Navigating Geopolitics and Supply Chains
Both firms face the reality of a fractured global supply chain, yet their mitigation strategies differ. Ametek has leveraged its global manufacturing footprint—spanning from the Czech Republic to Malaysia—to localize production, effectively insulating its bottom line from 2025 tariff shifts. Keysight, with significant operations in Penang and China, faces higher geopolitical beta but is countering this through "First-to-Market" leadership in 6G and quantum standards, making its technology indispensable regardless of trade barriers.
HDIN Viewpoint: The Risk-Adjusted Value Proposition
At HDIN Research, our comparative analysis suggests that the choice between Ametek and Keysight for 2026 is a choice between predictable compounding and high-beta disruption.
We view Ametek (AME) as the superior vehicle for risk-adjusted defense. Its proven ability to integrate acquisitions while maintaining elite margins makes it a fortress asset in a volatile economic cycle. The consistency of its "Growth Model" offers institutional investors a hedge against industrial stagnation.
However, for portfolios seeking exposure to the transformative power of Artificial Intelligence and connectivity, Keysight (KEYS) presents a compelling entry point. While the integration of Spirent brings short-term cost pressure, Keysight’s monopoly-like status in early-stage R&D testing means it is effectively a "tax" on global innovation. As R&D budgets for 6G and AI infrastructure unlock, Keysight’s stock elasticity is poised to outperform the broader industrial sector.
Presentation Download
Click the PDF download link under “Related Topics” to access the presentation of this report.
About HDIN Research
HDIN Research focuses on providing market consulting services. As an independent third-party consulting firm, it is committed to providing in-depth market research and analysis reports.
Website: www.hdinresearch.com
E-mail: sales@hdinresearch.com