Global Consumer Electronics Hinge Market Analysis 2026-2031
- Single User License (1 Users) $ 3,500
- Team License (2~5 Users) $ 4,500
- Corporate License (>5 Users) $ 5,500
The global consumer electronics hinge market is projected to reach USD 2.8–3.8 billion by 2031, expanding at a Compound Annual Growth Rate (CAGR) of 5.5%–8.5% from 2026. Consequently, this mechanical hardware segment has emerged as a primary bottleneck and key competitive differentiator in advanced mobile computing and flexible displays. The industry's expansion is driven by two main tailwinds: the maturation of foldable smartphone architectures (accelerating from inward/outward dual-folds to multi-link tri-fold form factors) and a commercial enterprise replacement cycle anchored in AI-capable personal computers (AI PCs). Hinges now account for 5% to 8% of the total Bill of Materials (BOM) cost in flexible devices, fundamentally altering margin capture across the mechanical supply chain. As multi-axis synchronization, zero-gap waterdrop screen creasing mitigation, and integrated thermal-fluid routing become baseline specifications, production methods are shifting away from conventional stamping and turning toward Metal Injection Molding (MIM), titanium powder metallurgy, and micro-laser welded amorphous alloys. Market leadership is defined by vertical co-development capabilities. Leading tier-1 original equipment manufacturers (OEMs) and joint-design manufacturers (JDMs) must operate within micron-level kinematic tolerances while simultaneously managing geographical production footprints across Greater China and Southeast Asia to mitigate escalating geopolitical and tariff friction.
Technical and Manufacturing Parameters
To meet the structural demands of next-generation hardware, hinge engineering has evolved into an interdisciplinary science combining computational metallurgy, dynamic tribology, and cleanroom automation.
● Core Structural Categories
- Waterdrop and Multi-Link Foldable Hinges: Utilizes dynamic floating wing plates and micro-gear synchronizers that allow a flexible OLED/UTG display to form a teardrop-shaped loop inside the hinge cavity upon closing. This eliminates mechanical creasing, prevents panel stretching, and achieves a zero-gap flat closure with chassis profiles dropping below 9 to 11 millimeters in total folded thickness.
- 360-Degree Synchronized Convertible Hinges: Integrates two intermeshed parallel shafts via a micro-gear train, providing continuous, synchronized torque resistance across 0 to 360 degrees of rotation, enabling clamshell, tent, stand, and tablet hardware states without gear slip.
- Constant-Torque "Free-Stop" Friction Hinges: Leverages alternating stacks of fixed and rotating high-carbon steel friction plates compressed by pre-curved disc springs (Belleville washers) bathed in high-viscosity synthetic fluorosilicone damping grease. This delivers steady, smooth holding torque across multi-angle tilt states, resisting drift or screen bounce during direct touch inputs.
- Multi-Axis Display Counterbalance Stands: Employs four-link kinematic scissor arms, gas-strut assists, or heavy-duty constant-force coil springs to deliver zero-gravity height, tilt, swivel, and rotational adjustments for monitors and All-in-One PCs.
● Advanced Materials Matrix
- Liquid Metal (Zirconium-Based Bulk Metallic Glasses): Possesses an amorphous atomic structure without crystalline grain boundaries, providing extreme tensile strength (over 1500 MPa), exceptional hardness, high elasticity, and high precision in net-shape die casting, making it optimal for complex foldable hinge bearing housings and high-stress cams.
- Maraging Steel and Ultra-High-Tensile Alloys: Specialized iron-nickel martensitic matrix steels capable of through-hardening up to 2000-2200 MPa, utilized in ultra-thin synchronized load-bearing swing arms and structural pin shafts that cannot deform under extreme torsional load.
- Titanium Powder Metallurgy (Ti-6Al-4V MIM): Deployed in premium AI glasses, smart wearable pivots, and ultra-light foldable smartphone frames to reduce overall component weight by 30% to 40% compared to standard stainless steels while providing superior biocompatibility and corrosion resistance against human sweat.
● Quality Assurance and Metrology Standards
- Cyclic Durability Fatigue Testing: Laptops are tested to a baseline of 25,000 to 35,000 cycles at dynamic opening speeds (10-15 cycles per minute). Foldable mobile devices are qualified to 200,000 to 500,000 cycles under variable environmental conditions (-20 degrees C to +60 degrees C, at 90% relative humidity) with torque decay limits strictly capped within 10% to 15% of initial baseline.
- High-Speed Dynamic Torque Profiling: Automated digital torque transducers plot real-time torque versus angle curves throughout the entire opening and closing envelope. Algorithms flag micro-clicks, torque dips, rotational deadbands, or sudden torque spikes exceeding millinewton-meter (mN-m) limits.
- Acoustic Decibel Analysis: Conducted within specialized anechoic test chambers where high-sensitivity microphones measure dynamic operating noise. Modules exhibiting high-frequency frictional squeaks or internal mechanical clicking exceeding 30-35 dB(A) are automatically sorted and rejected by in-line acoustic analysis software.
- High-Accuracy Non-Contact Optical Inspection: Multi-sensor vision systems and laser interferometers verify structural flatness, sub-component gap clearances, and coplanarity profiles to ensure finished hinge modules meet critical geometric dimensioning and tolerancing (GD&T) thresholds under dynamic mechanical loads.
Regional Market Dynamics
● Asia-Pacific (APAC)
Asia-Pacific maintains undisputed hegemony across global hinge module research, design, component fabrication, and downstream system integration, capturing a market share exceeding 70%. The regional ecosystem is structurally anchored by three specialized operational nodes:
- Taiwan, China: Functions as the strategic command, precision engineering, and intellectual property core. Players such as Shin Zu Shing, JARLLYTEC, Syncmold, Sinher Technology, and Fositek orchestrate global product roadmaps, pilot tooling runs, and high-tolerance CAE kinematic modeling from this corridor.
- Mainland China: Operates as both the world's primary manufacturing powerhouse for high-density MIM components and the largest regional domestic market for complex form factors. With local smartphone brands pushing the frontier of tri-fold display mechanics and liquid metal deployment, industrial hubs across Guangdong (Dongguan, Shenzhen) and Jiangsu (Kunshan, Suzhou) provide unmatched component sourcing density.
- Southeast Asia (Vietnam and Thailand): Represents the industry's fastest-growing manufacturing footprint, driven by the structural "China+1" diversification strategies of global brands. Backed by state tax exemptions—such as the Thailand Board of Investment (BOI) incentives granting multi-year corporate tax relief—Taiwanese and Chinese hinge leaders have stood up high-volume CNC and stamping facilities in Bac Ninh, Haiphong, and Chonburi.
● North America
North America functions primarily as the strategic demand-generation, industrial design, and system architecture anchor. Tier-1 hardware OEMs headquartered in Silicon Valley and the Pacific Northwest dictate kinematic specifications, target hinge torque profiles, envelope profiles, and material compositions. While mass assembly lines are largely outsourced offshore, domestic vendors such as Amphenol maintain advanced engineering divisions to capture early-stage design wins. The North American operating environment is conditioned by shifting trade compliance mandates, including export controls administered by the Bureau of Industry and Security (BIS) and tariff provisions enacted under comprehensive federal trade frameworks (such as H.R. 1). These regulatory levers require brand owners to mandate dual-sourcing production capacity insulated from single-origin supply shocks. North American hinge demand is geared heavily toward ultra-premium commercial notebooks, high-density AI workstations, and next-generation mixed-reality headwear.
● Europe
Europe serves as a high-margin, compliance-stringent destination market focused predominantly on commercial enterprise notebooks, professional audiovisual workstations, and premium consumer hardware. The European regulatory landscape acts as a significant operational filter for Asian supply chains. Suppliers must adhere to extensive environmental mandates, including the EU Carbon Border Adjustment Mechanism (CBAM), the Registration, Evaluation, Authorisation and Restriction of Chemicals (REACH), the Restriction of Hazardous Substances (RoHS) directive, and Scope 1-3 auditing under the Science Based Targets initiative (SBTi). Furthermore, corporate adoption cycles linked to enterprise digital workflows and ergonomic station designs sustain stable demand for multi-axis monitor counterbalances and convertible laptop mechanisms.
● South America and Middle East & Africa (MEA)
South America and MEA function primarily as secondary demand territories characterized by price-sensitive consumer profiles and emerging smartphone/PC penetration. Industrial manufacturing is limited, confined largely to localized final electronics assembly operations within duty-advantaged trade zones such as the Free Economic Zone of Manaus (ZFM) in Brazil. Brand OEMs operating within these geographies require suppliers to maintain strict alignment with the Responsible Business Alliance (RBA) Code of Conduct, including mandatory conflict-mineral due diligence to ensure that tantalum, tin, tungsten, and gold (3TG) inputs do not originate from illicit trade corridors in central Africa.
Supply Chain and Value Chain Architecture
The consumer electronics hinge industry is structured around an integrated, three-tiered value chain characterized by extreme capital intensity upstream, tight co-engineering in the midstream, and high customer concentration downstream.
● Upstream (Raw Materials & Precision Metallurgical Processing)
Upstream operations determine the raw mechanical strength, wear resistance, and dimensional limits of the finished hinge mechanism:
- Feedstocks: Sourcing revolves around high-carbon spring steels, austenitic/martensitic stainless steels (e.g., SUS301, SUS316, 17-4PH), high-purity aluminum ingots, copper alloys, and advanced titanium alloys (Ti-6Al-4V). High-performance foldable hinges increasingly demand exotic alloys, including maraging steels with ultimate tensile strengths exceeding 2000 MPa, alongside zirconium-based bulk metallic glasses (liquid metal) and carbon-fiber-reinforced polymer composite linkages.
- Primary Fabrication Processes: Material transformation splits into four primary process paths:
1. Metal Injection Molding (MIM): The core process for micro-gears, synchronized sliding blocks, cam profiles, and complex internal catches. High-purity metal powders combined with thermoplastic binders undergo catalytic debinding and high-temperature vacuum sintering to achieve near-theoretical density (over 97%) and micron-level tolerances without post-machining.
2. Precision Stamping: Stamping presses ranging from 30 to 200 tons fabricate high-resilience friction washers, pre-curved spring plates (shrapnel), chassis mounting brackets, and load-bearing friction plates.
3. CNC Lathe Turning and Micro-Milling: Multi-axis Swiss-type automated lathes machine central structural pivot pins, hollow wiring shafts, and high-tolerance retaining screws.
4. Die Casting: Zinc and aluminum structural outer covers and wide-chassis hinge base plates are mass-produced via cold-chamber or hot-chamber die casting.
● Midstream (Module Design, Kinematic Synthesis, and Sub-Assembly)
Midstream hinge suppliers are not standard component vendors; they are custom mechanical engineering partners operating through early Joint Design Manufacturing (JDM) engagements:
- Engineering Simulation: Prior to tooling release, vendors deploy finite-element Computer-Aided Engineering (CAE) platforms to simulate dynamic contact stresses, multi-angle torsional resistance curves, structural fatigue failure, drop impacts, and flexural fatigue imposed on connected flexible display panels.
- Automated Modular Integration: Modern assembly plants employ automated, cleanroom assembly work-cells equipped with six-axis robotic arms, precision torque drivers, and optical laser-alignment jigs. Components such as friction plate stacks, calibrated disc springs (Belleville washers), micro-dampers, and gear synchronization linkages are joined into unified drop-in modules.
- Dynamic In-Line Quality Testing: Completed hinges undergo rigorous automated inspection, including 100% dynamic torque-angle profiling (identifying micro-stutter, hysteresis loss, or excessive rotational free-play), acoustical noise profiling, cycle-durability stress testing (ranging from 25,000 cycles for notebooks to over 400,000 cycles for foldable displays), and sub-pixel optical scanning to verify zero-clearance coplanarity.
● Downstream (System Integration, Contract Manufacturing & Brand OEMs)
Finished hinge modules exit midstream production facilities and are routed directly to global Electronic Manufacturing Services (EMS) conglomerates, original design manufacturers (ODMs), and brand assembly plants:
- Assembly Integration: System integrators—including Hon Hai Precision Industry (Foxconn), Quanta Computer, Compal Electronics, Wistron, Pegatron, Inventec, and TPV Technology—integrate the hinge module with display panels, flexible printed circuits (FPCs), coaxial antenna cables, structural mid-frames, and thermal dissipation systems.
- Value Migration & Bottleneck Resilience: Profit margins within the 3C mechanical supply chain have migrated decidedly upstream toward the hinge module. As standard casings, stamped chassis plates, and external plastic bezels become commoditized, the precision hinge remains one of the few mechanical systems commanding sustained gross margins above 20%-30%. The mechanical assembly represents the single greatest point of mechanical failure in advanced hardware. Yield losses at the hinge assembly level cascade directly into discarded flexible displays and costly field RMA returns. As a result, Tier-1 brands exhibit high switching costs, locking in certified hinge vendors for multi-year platform generations.
Key Market Players
● Amphenol Corporation: Headquartered in the United States, Amphenol operates as an interconnect and mechanical sub-assembly multinational, projecting power into the consumer segment via divisions such as Amphenol Mobile Consumer Products (MCP) and Amphenol Aorora. Amphenol acts as a primary Tier-1 modular integration partner for tier-1 Western brands. Its mechanical capability encompasses waterdrop zero-gap folding assemblies, high-retention TWS earbud charging case micro-mechanisms, synchronized dual-axis 360-degree convertible laptop hinges, and precision AR/VR headset strap pivots. Amphenol differentiates via deep vertical capabilities in micro-MIM, high-speed automated laser micro-welding, precision gear fabrication, and 100% dynamic cleanroom torque validation.
● Lian Hong Art Company Limited: An established Taiwanese precision hardware enterprise with production bases distributed across Taiwan and mainland China, focusing on personal computing architectures and enterprise peripheral displays. Specializes in high-volume, cost-optimized clamshell notebook hinges, wrap-band friction assemblies, dual-rail laptop hinges, and ruggedized friction mounts for commercial Point-of-Sale (POS) touchscreens and medical terminals. Core strengths include automated stamping of high-carbon spring steels, proprietary anti-corrosive chemical passivation, friction plate damping calibration, and lifecycle ratings validated beyond 25,000 cycles.
● Sinher Technology Inc.: A Taiwanese hinge manufacturer dedicated to notebook PC, 2-in-1 convertible, and all-in-one (AIO) computing architectures, maintaining entrenched supply relationships with top-tier notebook ODMs (Quanta, Compal, Wistron, Inventec). Sinher focuses on ultra-low-profile friction hinges engineered for narrow-bezel thin-and-light ultrabooks, hollow-shaft friction mechanisms that pass high-density coaxial and FPC lines without torsional pinching, and synchronized 360-degree convertible gear systems. The company relies on proprietary oil-less friction disc assemblies, mathematical torque-tuning algorithms, and automated continuous-stamping dies.
● JARLLYTEC Co., Ltd.: A top-tier Taiwanese precision mechanism specialist holding a commanding market share in foldable smartphone hinges, high-performance notebooks, and professional display pivots. The company has historically served as a critical hinge co-development partner for leading Chinese smartphone giants. Highly proficient in inward-folding, outward-folding, and complex multi-linkage tri-fold waterdrop hinges. JARLLYTEC’s operational moat resides in its vertically integrated internal MIM infrastructure, micron-scale gear meshing synchronization, extensive deployment of maraging steels and liquid metal components, and proprietary screen crease-relief sliding plate designs.
● Shin Zu Shing Co., Ltd. (SZS): Widely regarded as the benchmark precision mechanism supplier globally, this Taiwanese company occupies a dominant role within high-aesthetic hardware ecosystems, serving as a primary supplier across MacBook lines, AirPods charging cases, and iPad floating-keyboard accessories. SZS possesses one of the world's most extensive, tightly controlled MIM capacities alongside dense fleets of multi-axis CNC machinery. The company specializes in unibody aluminum-integrated notebook hinges, high-density magnetic detent micro-hinges, and floating cantilever assemblies. Operational excellence is driven by advanced PVD and dry-lubricant anti-wear surface coatings, zero-tolerance axial clearance, and advanced metallurgy.
● The rest of companies covered in the report: Fositek Corp., Syncmold Enterprise Group, Asia Vital Components Co., Ltd. (AVC), NBTM New Materials Group Co., Ltd., Kunshan VOSO Hinge Intelligence Technology Co., Ltd., Dongguan Huanli Intelligent Technology Co., Ltd., Dongguan Chenggong Electronic Technology Co., Ltd., Dongguan Honglian Electronics Co., Ltd., Dongguan Sijie Precision, Hardware Co., Ltd., DIABELL Co., Ltd., and Lingyi iTech (Guangdong) Company.
Opportunities and Structural Catalysts
● The Tri-Fold Paradigm and the Tier-1 Foldable Supercycle
The commercial deployment of dual-screen and multi-fold (tri-fold) form factors represents an inflection point for the hinge value chain. Moving from a single-axis fold to a dual-axis, inward-and-outward multi-fold system more than doubles the mechanical component count per device. A standard tri-fold hinge architecture can require up to 70 to 120 discrete precision parts—including micro-gears, synchronizer slides, multi-linkage swing arms, and spring-loaded wing plates. Consequently, the hinge BOM cost elevates from 15-25 USD in a standard flip-style foldable to 60-120 USD in a high-complexity tri-fold terminal.
Concurrently, the entry of the world's most valuable consumer technology company (Apple) into the foldable smartphone and flexible-display tablet space—expected with the launch of its premier folding hardware (such as the anticipated iPhone duo format)—is projected to catalyze broader consumer adoption. Industry modeling indicates this milestone will expand flexible device market penetration from its historical sub-2% baseline to over 3% to 5% rapidly, sparking a wide upgrade supercycle and driving component orders across qualified Tier-1 hinge suppliers.
● Semiconductor Pricing Normalization and Consumer PC Refresh
The consumer hardware landscape faced severe headwinds throughout late 2024 and 2025 due to rapid price spikes across core semiconductor components—particularly High Bandwidth Memory (HBM), mainstream DRAM, and NAND flash storage—which rose between 40% and 70%. This cost shock compressed brand operating margins and forced retail price hikes, constraining notebook and mobile upgrade momentum. As semiconductor supply imbalances normalize, memory pricing has begun to stabilize and recalibrate downward. This structural relief is driving downstream price corrections on consumer notebooks, tablets, and AI PCs, revitalizing consumer and enterprise purchasing power. Combined with the operational sunset of Microsoft Windows 10, this price normalization is triggering a broad hardware replacement cycle, expanding production volumes for commercial ultrabook hinges, 360-degree convertible shafts, and lay-flat display mechanisms.
● AI Hardware Proliferation, Wearables, and Embodied Motion Joints
The convergence of edge AI models with specialized hardware is opening structural revenue avenues beyond traditional clamshell screens. The rapid market expansion of AI-enabled smart glasses and spatial computing headsets requires ultra-miniaturized, titanium MIM friction hinges capable of concealing internal wiring routes, providing subtle tactile detents, and resisting sweat corrosion.
Furthermore, precision hinge manufacturers are identifying high-value cross-domain operational synergies in embodied AI and humanoid robotics. The precision joint linkages, micro-planetary gear mechanisms, and constant-torque pivot shafts engineered for high-durability consumer electronics map directly to the mechanical requirements of dexterous robotic hands, wrists, and articulated sensor arms. Leading hinge makers are already leveraging their CNC machining capacity, MIM sintering furnaces, and dynamic torque calibration rigs to secure early prototyping contracts for robotic motion components and automotive smart-cockpit dynamic display cantilevers.
● Emerging Market Penetration
Smartphone and digital terminal penetration rates are accelerating across emerging industrial economies, led by India, Southeast Asia (Indonesia, Vietnam, Philippines), and parts of Latin America. As domestic purchasing power expands, local consumers are skipping desktop PCs in favor of thin-and-light convertible notebooks and feature-rich mid-range smartphones. Tier-1 electronics brands are capturing these segments by introducing value-tier convertibles and accessible folding devices, sustaining volume demand for mid-tier, high-durability friction and geared hinge assemblies.
Systemic Challenges and Macroeconomic Pressures
● Yield Attrition and High Micro-Tolerance Tooling Costs
The transition to zero-crease, waterdrop, and multi-axis hinge designs imposes severe engineering challenges. Kinematic tolerances for meshed micro-gears and synchronized slider blocks are governed at the sub-10-micron level (+/- 0.005 mm). Sintering shrinkage during the MIM process (typically ranging between 12% and 20%) requires complex numerical simulation and iterative, high-cost mold tuning. Early-stage production runs for next-generation foldable hinges frequently suffer from module yield rates falling below 50%-60%. Unrecovered scrap rates, combined with multi-million-dollar upfront tooling, wire EDM, and automated testing outlays, create severe gross-margin compression for suppliers that fail to achieve rapid volume ramp-up.
● Geopolitical Friction, Import Tariffs, and Supply Chain Balkanization
The global consumer electronics ecosystem remains directly exposed to trade policy volatility, protectionist legislation, and rising cross-border tariffs. Evolving U.S. federal import tariffs, coupled with expanding BIS export control lists covering advanced automated manufacturing equipment, have introduced significant friction into standard supply operations. Major electronics brands are actively forcing midstream hinge suppliers to establish duplicate tooling and cleanroom assembly operations in neutral territories, notably Vietnam and Thailand. However, duplicating high-precision manufacturing infrastructure incurs heavy capital expenditure, dilutes operational scale, and introduces logistics inefficiencies, as the deep upstream ecosystem for specialized tool-making, chemical surface treatment, and powder metallurgy remains concentrated within mainland China and Taiwan, China.
● Downstream Assembler Margin Squeeze and Concentrated Procurement
While raw material and sub-component costs (high-strength maraging steels, liquid metals, precision Belleville washers) continue to face inflationary pressure, downstream system contract assemblers (EMS) and global brand owners enforce aggressive annual cost-down mandates (typically demanding 5% to 15% annual price cuts on mature component lines). Because the tier-1 personal computing and smartphone markets are dominated by a small group of multinational brands, hinge manufacturers face substantial customer concentration risk. Failure to win a single flagship platform generation or experiencing a two-month delay in sample qualification can wipe out a midstream vendor's annual volume growth and trigger severe capacity underutilization.
1.1 Research Scope and Analytical Objectives 1
1.2 Data Sourcing and Verification Methodologies 2
1.3 Modeling Parameters, Forecasting Logic, and Assumptions 3
1.4 Standardized Industry Abbreviations and Unit Definitions 5
Chapter 2 Global Consumer Electronics Hinge Industry Overview
2.1 Product Demarcation, Kinematic Classification, and Engineering Principles 6
2.2 Historical Trajectory and Technology Evolution (2021-2025) 7
2.3 Current Market Sizing, Operational Baseline, and Growth Vectors (2026) 9
2.4 Long-Range Market Projections and Technological Transformations (2027-2031) 11
Chapter 3 Value Chain Architecture, Material Science, and Manufacturing Processes
3.1 Upstream Raw Material Dynamics: Ultra-High-Strength Steels, Titanium, Liquidmetal, and Sintered Alloys 14
3.2 Precision Manufacturing Methodologies: Metal Injection Molding (MIM), CNC Micro-Machining, and Stamping 16
3.3 Critical Sub-Assemblies: Friction Discs, Planetary Gears, Damped Springs, and Cam Components 18
3.4 Cost Structures, Yield Rates, and Value Migration Along the Manufacturing Stack 20
3.5 Environmental Directives, RoHS/REACH Compliance, and Circularity Trends 22
Chapter 4 Global Market Breakdown by Hinge Mechanism and Structural Typology
4.1 Waterdrop and Teardrop Foldable Multi-Gear Mechanisms 23
4.2 Traditional Dual-Shaft and Multi-Shaft Friction Hinges 25
4.3 Continuous Dynamic Torque and Friction Damped Assemblies 27
4.4 Constant Force and Swivel Hinge Architectures 29
4.5 Slip-Ring Integrated and Modular Hollow-Shaft Hinges 31
Chapter 5 Global Market Breakdown by Downstream Application
5.1 Smartphones & Mobile Devices (Foldable Handsets, Tri-Fold Screens, Tablets) 33
5.2 Laptops & PCs (Ultrabooks, 2-in-1 Convertibles, Dual-Screen Laptops) 36
5.3 Monitors & Home Entertainment (All-in-One PCs, Ergonomic Monitor Stands, Smart Interactive Displays) 39
5.4 Wearables & Smart Accessories (TWS Charging Cases, AR/VR Smart Headsets, Wearable Bands) 41
5.5 Other Specialized Platforms (Point-of-Sale Hardware, Medical Terminals, In-Vehicle Displays) 43
Chapter 6 Global Production Footprint and Capacity Sourcing Analysis
6.1 Global Hinge Manufacturing Capacity and Utilization Rates (2021-2031) 45
6.2 China: Production Hubs in Guangdong (Pearl River Delta) and Jiangsu/Zhejiang (Yangtze River Delta) 47
6.3 Taiwan (China): Precision Engineering, High-End Laptop Hinge R&D, and Prototyping Centers 49
6.4 South Korea: Domestic Ecosystem Supporting Display Conglomerates and Advanced Foldables 51
6.5 Southeast Asia: Emerging Multi-Tier Assembly and Diversification Hubs 53
Chapter 7 Global Downstream Consumption and Demand Dynamics
7.1 Global End-Market Consumption Volume and Value Analysis (2021-2031) 55
7.2 North America (United States, Canada): Premium Enterprise Laptops and Emerging Foldable Demand 57
7.3 Europe (Germany, United Kingdom, France): Stringent Ergonomic Standards and High-End Computing 59
7.4 Asia-Pacific (China, Japan, South Korea, India): Primary ODM/OEM Manufacturing and Local Consumption 61
7.5 Latin America and Middle East & Africa: Regional Consumer Electronics Uptake Dynamics 63
Chapter 8 Cross-Border Trade Flows, Logistics, and Supply Chain Risk
8.1 Global Import and Export Tariffs, Regulatory Frameworks, and Cross-Border Flow Analysis 64
8.2 Primary Exporter Matrix (China, Taiwan (China), South Korea) and Route Logistics 65
8.3 Key Importing Hubs for Module Integration (Vietnam, India, United States, Japan) 66
8.4 Supply Chain Vulnerabilities: Single-Source Materials, Sub-Tier Tooling, and Geo-Economic Volatility 67
Chapter 9 Competitive Landscape, Tiering, and Market Concentration
9.1 Tier-1, Tier-2, and Tier-3 Supplier Ecosystem Stratification 69
9.2 Market Concentration Ratios (CR4, CR8, Herfindahl-Hirschman Index) 71
9.3 Strategic Partnerships, Display Panel Maker Joint Development Agreements, and Vertical Integration 72
9.4 Intellectual Property Landscape: Key Patent Portfolios, Crease Mitigation, and Design Workarounds 73
Chapter 10 Deep-Dive Corporate Profiles and Operational Intelligence
10.1 Amphenol 75
10.1.1 Corporate Profile and Strategic Trajectory 75
10.1.2 Product Matrix and Technical Specialization 76
10.1.3 Operational Metrics: Capacity, Output, Utilization, Price, Cost, and Gross Margin (2021-2026) 77
10.1.4 SWOT Matrix, Intellectual Property, and R&D Deployments 78
10.2 Lian Hong Art Company Limited 79
10.2.1 Corporate Profile and Strategic Trajectory 79
10.2.2 Product Matrix and Technical Specialization 80
10.2.3 Operational Metrics: Capacity, Output, Utilization, Price, Cost, and Gross Margin (2021-2026) 81
10.2.4 SWOT Matrix, Intellectual Property, and R&D Deployments 82
10.3 Sinher Technolgy Inc. 83
10.3.1 Corporate Profile and Strategic Trajectory 83
10.3.2 Product Matrix and Technical Specialization 84
10.3.3 Operational Metrics: Capacity, Output, Utilization, Price, Cost, and Gross Margin (2021-2026) 85
10.3.4 SWOT Matrix, Intellectual Property, and R&D Deployments 86
10.4 JARLLYTEC 87
10.4.1 Corporate Profile and Strategic Trajectory 87
10.4.2 Product Matrix and Technical Specialization 88
10.4.3 Operational Metrics: Capacity, Output, Utilization, Price, Cost, and Gross Margin (2021-2026) 89
10.4.4 SWOT Matrix, Intellectual Property, and R&D Deployments 90
10.5 Shin Zu Shing 91
10.5.1 Corporate Profile and Strategic Trajectory 91
10.5.2 Product Matrix and Technical Specialization 92
10.5.3 Operational Metrics: Capacity, Output, Utilization, Price, Cost, and Gross Margin (2021-2026) 93
10.5.4 SWOT Matrix, Intellectual Property, and R&D Deployments 94
10.6 Fositek 95
10.6.1 Corporate Profile and Strategic Trajectory 95
10.6.2 Product Matrix and Technical Specialization 96
10.6.3 Operational Metrics: Capacity, Output, Utilization, Price, Cost, and Gross Margin (2021-2026) 97
10.6.4 SWOT Matrix, Intellectual Property, and R&D Deployments 98
10.7 Syncmold Enterprise Group 99
10.7.1 Corporate Profile and Strategic Trajectory 99
10.7.2 Product Matrix and Technical Specialization 100
10.7.3 Operational Metrics: Capacity, Output, Utilization, Price, Cost, and Gross Margin (2021-2026) 101
10.7.4 SWOT Matrix, Intellectual Property, and R&D Deployments 102
10.8 Asia Vital Components Co. Ltd 103
10.8.1 Corporate Profile and Strategic Trajectory 103
10.8.2 Product Matrix and Technical Specialization 104
10.8.3 Operational Metrics: Capacity, Output, Utilization, Price, Cost, and Gross Margin (2021-2026) 105
10.8.4 SWOT Matrix, Intellectual Property, and R&D Deployments 106
10.9 NBTM New Materials Group 107
10.9.1 Corporate Profile and Strategic Trajectory 107
10.9.2 Product Matrix and Technical Specialization 108
10.9.3 Operational Metrics: Capacity, Output, Utilization, Price, Cost, and Gross Margin (2021-2026) 109
10.9.4 SWOT Matrix, Intellectual Property, and R&D Deployments 110
10.10 Kunshan VOSO Hinge Intelligence Technology Co. Ltd. 111
10.10.1 Corporate Profile and Strategic Trajectory 111
10.10.2 Product Matrix and Technical Specialization 112
10.10.3 Operational Metrics: Capacity, Output, Utilization, Price, Cost, and Gross Margin (2021-2026) 113
10.10.4 SWOT Matrix, Intellectual Property, and R&D Deployments 114
10.11 Dongguan Huanli Intelligent Technology Co. Ltd. 115
10.11.1 Corporate Profile and Strategic Trajectory 115
10.11.2 Product Matrix and Technical Specialization 116
10.11.3 Operational Metrics: Capacity, Output, Utilization, Price, Cost, and Gross Margin (2021-2026) 117
10.11.4 SWOT Matrix, Intellectual Property, and R&D Deployments 118
10.12 Dongguan Chenggong Electronic Technology Co. Ltd. 119
10.12.1 Corporate Profile and Strategic Trajectory 119
10.12.2 Product Matrix and Technical Specialization 120
10.12.3 Operational Metrics: Capacity, Output, Utilization, Price, Cost, and Gross Margin (2021-2026) 121
10.12.4 SWOT Matrix, Intellectual Property, and R&D Deployments 122
10.13 Dongguan Honglian Electronics Co. Ltd 123
10.13.1 Corporate Profile and Strategic Trajectory 123
10.13.2 Product Matrix and Technical Specialization 124
10.13.3 Operational Metrics: Capacity, Output, Utilization, Price, Cost, and Gross Margin (2021-2026) 125
10.13.4 SWOT Matrix, Intellectual Property, and R&D Deployments 126
10.14 Dongguan Sijie Precision Hardware Co. Ltd. 127
10.14.1 Corporate Profile and Strategic Trajectory 127
10.14.2 Product Matrix and Technical Specialization 128
10.14.3 Operational Metrics: Capacity, Output, Utilization, Price, Cost, and Gross Margin (2021-2026) 129
10.14.4 SWOT Matrix, Intellectual Property, and R&D Deployments 130
10.15 DIABELL Co. Ltd. 131
10.15.1 Corporate Profile and Strategic Trajectory 131
10.15.2 Product Matrix and Technical Specialization 132
10.15.3 Operational Metrics: Capacity, Output, Utilization, Price, Cost, and Gross Margin (2021-2026) 133
10.15.4 SWOT Matrix, Intellectual Property, and R&D Deployments 134
10.16 Lingyi iTech 135
10.16.1 Corporate Profile and Strategic Trajectory 135
10.16.2 Product Matrix and Technical Specialization 136
10.16.3 Operational Metrics: Capacity, Output, Utilization, Price, Cost, and Gross Margin (2021-2026) 137
10.16.4 SWOT Matrix, Intellectual Property, and R&D Deployments 138
Table 2 Global Consumer Electronics Hinge Market Size and Growth Rates (2021-2031) 10
Table 3 Raw Material Performance Benchmarks: High-Yield Steels vs. Liquidmetal vs. Titanium Alloys 15
Table 4 Cost Breakdown Architecture of Multi-Axis Foldable Hinge vs. Standard Dual-Axis Notebook Hinge 21
Table 5 Global Consumer Electronics Hinge Shipment Volume by Mechanism Type (2021-2031) 24
Table 6 Global Consumer Electronics Hinge Market Value by Mechanism Type (2021-2031) 25
Table 7 Average Selling Price (ASP) Comparison across Hinge Typologies (2021-2031) 32
Table 8 Global Consumer Electronics Hinge Shipment Volume by Application (2021-2031) 34
Table 9 Global Consumer Electronics Hinge Market Value by Application (2021-2031) 35
Table 10 Smartphones & Mobile Devices Hinge Volume and Value by Form Factor (2021-2031) 37
Table 11 Laptops & PCs Hinge Volume and Value by Device Category (2021-2031) 38
Table 12 Global Hinge Production Capacity and Utilization by Core Region (2021-2031) 46
Table 13 China: Precision Hinge Production Capacity, Output, and Export Volume (2021-2031) 48
Table 14 Taiwan (China): Hinge Design, Prototyping, and Production Volume (2021-2031) 50
Table 15 South Korea: Advanced Hinge Output and Domestic Supply Integration (2021-2031) 52
Table 16 Southeast Asia: Precision Hinge Assembly Output and Cross-Border Transfers (2021-2031) 54
Table 17 Global Consumer Electronics Hinge Consumption Value by Region (2021-2031) 56
Table 18 North America: Consumer Electronics Hinge Consumption Volume by Device Type (2021-2031) 58
Table 19 Europe: Consumer Electronics Hinge Consumption Volume by Device Type (2021-2031) 60
Table 20 Asia-Pacific: Consumer Electronics Hinge Consumption Volume by Country (2021-2031) 62
Table 21 Global Bilateral Trade Matrix for Consumer Electronics Hinges (2026) 65
Table 22 Top 10 Enterprise Market Share and Herfindahl-Hirschman Index Trends (2021-2026) 71
Table 23 Amphenol Hinge for Consumer Electronics Capacity, Production, Price, Cost and Gross Profit Margin (2021-2026) 77
Table 24 Lian Hong Art Company Limited Hinge for Consumer Electronics Capacity, Production, Price, Cost and Gross Profit Margin (2021-2026) 81
Table 25 Sinher Technolgy Inc. Hinge for Consumer Electronics Capacity, Production, Price, Cost and Gross Profit Margin (2021-2026) 85
Table 26 JARLLYTEC Hinge for Consumer Electronics Capacity, Production, Price, Cost and Gross Profit Margin (2021-2026) 89
Table 27 Shin Zu Shing Hinge for Consumer Electronics Capacity, Production, Price, Cost and Gross Profit Margin (2021-2026) 93
Table 28 Fositek Hinge for Consumer Electronics Capacity, Production, Price, Cost and Gross Profit Margin (2021-2026) 97
Table 29 Syncmold Enterprise Group Hinge for Consumer Electronics Capacity, Production, Price, Cost and Gross Profit Margin (2021-2026) 101
Table 30 Asia Vital Components Co. Ltd Hinge for Consumer Electronics Capacity, Production, Price, Cost and Gross Profit Margin (2021-2026) 105
Table 31 NBTM New Materials Group Hinge for Consumer Electronics Capacity, Production, Price, Cost and Gross Profit Margin (2021-2026) 109
Table 32 Kunshan VOSO Hinge Intelligence Technology Co. Ltd. Hinge for Consumer Electronics Capacity, Production, Price, Cost and Gross Profit Margin (2021-2026) 113
Table 33 Dongguan Huanli Intelligent Technology Co. Ltd. Hinge for Consumer Electronics Capacity, Production, Price, Cost and Gross Profit Margin (2021-2026) 117
Table 34 Dongguan Chenggong Electronic Technology Co. Ltd. Hinge for Consumer Electronics Capacity, Production, Price, Cost and Gross Profit Margin (2021-2026) 121
Table 35 Dongguan Honglian Electronics Co. Ltd Hinge for Consumer Electronics Capacity, Production, Price, Cost and Gross Profit Margin (2021-2026) 125
Table 36 Dongguan Sijie Precision Hardware Co. Ltd. Hinge for Consumer Electronics Capacity, Production, Price, Cost and Gross Profit Margin (2021-2026) 129
Table 37 DIABELL Co. Ltd. Hinge for Consumer Electronics Capacity, Production, Price, Cost and Gross Profit Margin (2021-2026) 133
Table 38 Lingyi iTech Hinge for Consumer Electronics Capacity, Production, Price, Cost and Gross Profit Margin (2021-2026) 137
Figure 1 Global Consumer Electronics Hinge Revenue Trajectory and Annual Growth (2021-2031) 12
Figure 2 End-to-End Value Chain Map: Powder Metallurgy to OEM Integration 17
Figure 3 Manufacturing Process Flowchart: Precision Tooling, MIM Sintering, CNC Finish, and Automated Assembly 19
Figure 4 Global Market Share by Mechanism Type (2021, 2026, 2031) 26
Figure 5 Global Market Share by Downstream Application (2021, 2026, 2031) 36
Figure 6 Geographic Concentration of Global Hinge Production Capacity (2026) 47
Figure 7 Regional Consumption Share of Consumer Electronics Hinges (2026) 57
Figure 8 Global Supply Route and Trade Dependency Flowchart for Critical Hinge Components 66
Figure 9 Supplier Matrix: Positioning by Technical Complexity and High-Volume Scalability 70
Figure 10 Amphenol Hinge for Consumer Electronics Market Share (2021-2026) 78
Figure 11 Lian Hong Art Company Limited Hinge for Consumer Electronics Market Share (2021-2026) 82
Figure 12 Sinher Technolgy Inc. Hinge for Consumer Electronics Market Share (2021-2026) 86
Figure 13 JARLLYTEC Hinge for Consumer Electronics Market Share (2021-2026) 90
Figure 14 Shin Zu Shing Hinge for Consumer Electronics Market Share (2021-2026) 94
Figure 15 Fositek Hinge for Consumer Electronics Market Share (2021-2026) 98
Figure 16 Syncmold Enterprise Group Hinge for Consumer Electronics Market Share (2021-2026) 102
Figure 17 Asia Vital Components Co. Ltd Hinge for Consumer Electronics Market Share (2021-2026) 106
Figure 18 NBTM New Materials Group Hinge for Consumer Electronics Market Share (2021-2026) 110
Figure 19 Kunshan VOSO Hinge Intelligence Technology Co. Ltd. Hinge for Consumer Electronics Market Share (2021-2026) 114
Figure 20 Dongguan Huanli Intelligent Technology Co. Ltd. Hinge for Consumer Electronics Market Share (2021-2026) 118
Figure 21 Dongguan Chenggong Electronic Technology Co. Ltd. Hinge for Consumer Electronics Market Share (2021-2026) 122
Figure 22 Dongguan Honglian Electronics Co. Ltd Hinge for Consumer Electronics Market Share (2021-2026) 126
Figure 23 Dongguan Sijie Precision Hardware Co. Ltd. Hinge for Consumer Electronics Market Share (2021-2026) 130
Figure 24 DIABELL Co. Ltd. Hinge for Consumer Electronics Market Share (2021-2026) 134
Figure 25 Lingyi iTech Hinge for Consumer Electronics Market Share (2021-2026) 138
Research Methodology
- Market Estimated Methodology:
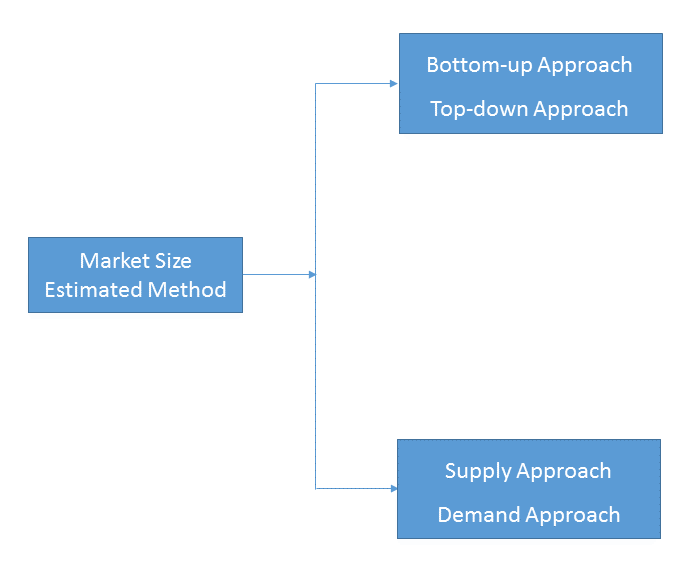
Bottom-up & top-down approach, supply & demand approach are the most important method which is used by HDIN Research to estimate the market size.
1)Top-down & Bottom-up Approach
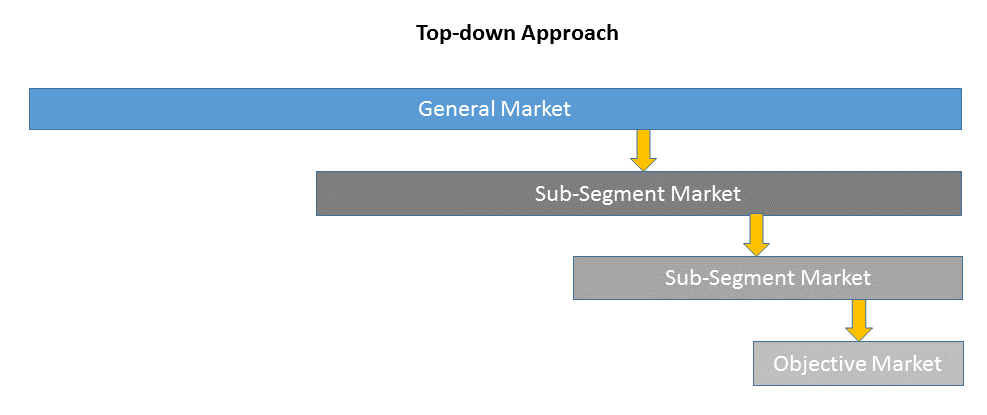
Top-down approach uses a general market size figure and determines the percentage that the objective market represents.
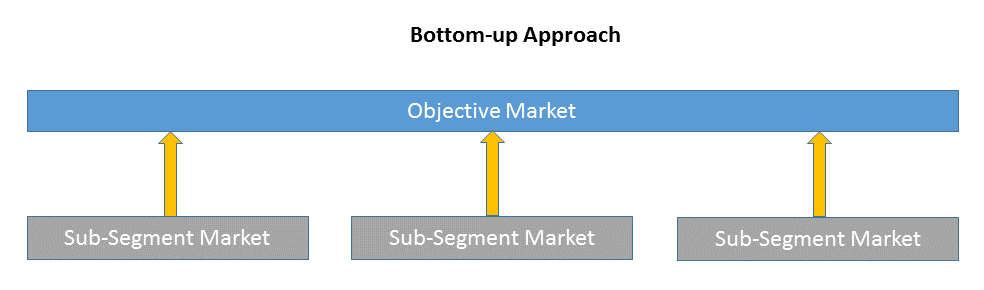
Bottom-up approach size the objective market by collecting the sub-segment information.
2)Supply & Demand Approach
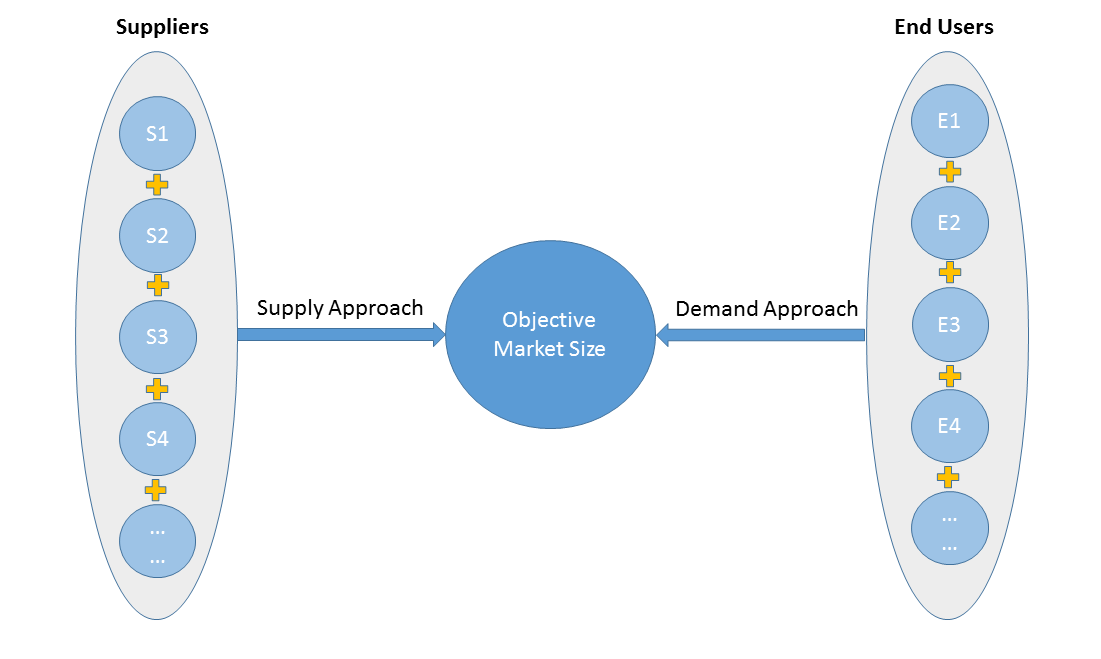
Supply approach is based on assessments of the size of each competitor supplying the objective market.
Demand approach combine end-user data within a market to estimate the objective market size. It is sometimes referred to as bottom-up approach.
- Forecasting Methodology
- Numerous factors impacting the market trend are considered for forecast model:
- New technology and application in the future;
- New project planned/under contraction;
- Global and regional underlying economic growth;
- Threatens of substitute products;
- Industry expert opinion;
- Policy and Society implication.
- Analysis Tools
1)PEST Analysis
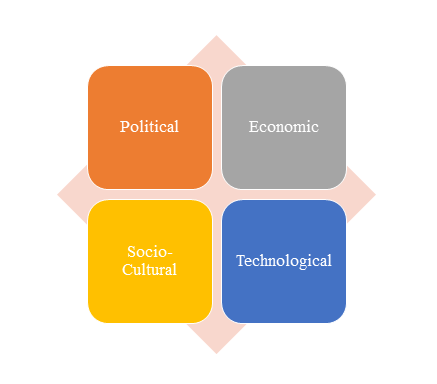
PEST Analysis is a simple and widely used tool that helps our client analyze the Political, Economic, Socio-Cultural, and Technological changes in their business environment.
- Benefits of a PEST analysis:
- It helps you to spot business opportunities, and it gives you advanced warning of significant threats.
- It reveals the direction of change within your business environment. This helps you shape what you’re doing, so that you work with change, rather than against it.
- It helps you avoid starting projects that are likely to fail, for reasons beyond your control.
- It can help you break free of unconscious assumptions when you enter a new country, region, or market; because it helps you develop an objective view of this new environment.
2)Porter’s Five Force Model Analysis
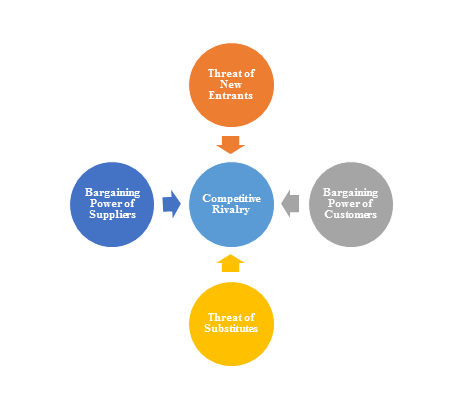
The Porter’s Five Force Model is a tool that can be used to analyze the opportunities and overall competitive advantage. The five forces that can assist in determining the competitive intensity and potential attractiveness within a specific area.
- Threat of New Entrants: Profitable industries that yield high returns will attract new firms.
- Threat of Substitutes: A substitute product uses a different technology to try to solve the same economic need.
- Bargaining Power of Customers: the ability of customers to put the firm under pressure, which also affects the customer's sensitivity to price changes.
- Bargaining Power of Suppliers: Suppliers of raw materials, components, labor, and services (such as expertise) to the firm can be a source of power over the firm when there are few substitutes.
- Competitive Rivalry: For most industries the intensity of competitive rivalry is the major determinant of the competitiveness of the industry.
3)Value Chain Analysis
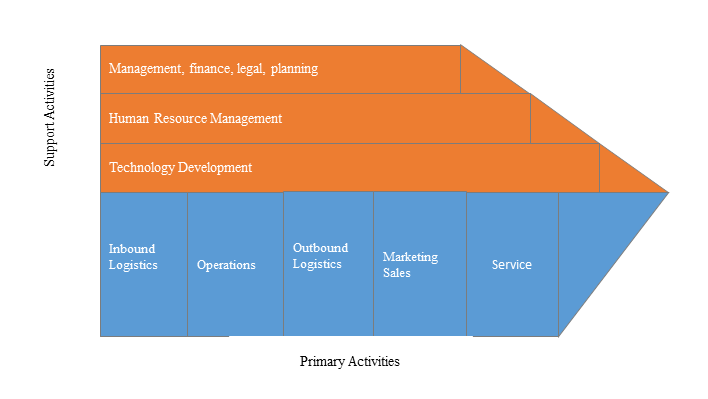
Value chain analysis is a tool to identify activities, within and around the firm and relating these activities to an assessment of competitive strength. Value chain can be analyzed by primary activities and supportive activities. Primary activities include: inbound logistics, operations, outbound logistics, marketing & sales, service. Support activities include: technology development, human resource management, management, finance, legal, planning.
4)SWOT Analysis
SWOT analysis is a tool used to evaluate a company's competitive position by identifying its strengths, weaknesses, opportunities and threats. The strengths and weakness is the inner factor; the opportunities and threats are the external factor. By analyzing the inner and external factors, the analysis can provide the detail information of the position of a player and the characteristics of the industry.
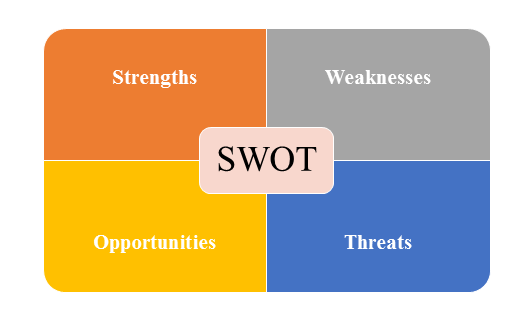
- Strengths describe what the player excels at and separates it from the competition
- Weaknesses stop the player from performing at its optimum level.
- Opportunities refer to favorable external factors that the player can use to give it a competitive advantage.
- Threats refer to factors that have the potential to harm the player.
- Data Sources
| Primary Sources | Secondary Sources |
|---|---|
| Face to face/Phone Interviews with market participants, such as: Manufactures; Distributors; End-users; Experts. Online Survey |
Government/International Organization Data: Annual Report/Presentation/Fact Book Internet Source Information Industry Association Data Free/Purchased Database Market Research Report Book/Journal/News |