Global Computed Tomography (CT) Market Size, Trends & Forecast 2026-2031
- Single User License (1 Users) $ 3,500
- Team License (2~5 Users) $ 4,500
- Corporate License (>5 Users) $ 5,500
Computed Tomography is a non-invasive, volumetric diagnostic modality combining continuous circular X-ray geometry with advanced numerical reconstruction algorithms. The system functions by rotating an X-ray source and opposed multi-element detector array inside an engineered gantry around an anatomically translated subject. As high-energy photons traverse human tissue, differential attenuation occurs in accordance with tissue electron densities and effective atomic numbers, characterized by the Beer-Lambert law. The resultant flux variations are intercepted by digital detector arrays, converted from ionizing electromagnetic radiation into digital matrices, and routed to high-performance computing clusters. Employing analytical filtering back-projection, model-based iterative reconstruction (MBIR), and deep learning neural network architectures, the system solves complex inverse mathematical problems to reconstruct isotropic voxels. This yields cross-sectional slices and three-dimensional spatial maps calibrated in Hounsfield units (HU), entirely circumventing anatomical superimposition. Dental and maxillofacial Cone Beam CT (CBCT) designed exclusively for oral-maxillofacial protocols and industrial CT are formally excluded from this report.
The global Computed Tomography (CT) market represents a critical pillar of diagnostic infrastructure, valued at an estimated 6.9 to 8.1 billion USD in 2026. This market is projected to expand at a compound annual growth rate (CAGR) of 4.2% to 5.8% through 2031. Growth is underpinned by an intensifying global disease burden, an aging demographic profile requiring frequent cardiological and oncological evaluations, and an aggressive, systemic push toward early disease interception. The CT market is undergoing a structural paradigm shift characterized by the transition from Energy-Integrating Detectors (EID) to direct-conversion Photon-Counting Detectors (PCD), the convergence of ultra-wide-body coverage with dual-source rotation, and the integration of edge-native deep learning reconstruction engines. While mature regions focus capital expenditure on high-acuity replacements, advanced spectral technologies, and ambulatory footprint expansions, emerging territories are experiencing accelerated greenfield installations driven by state-sponsored universal healthcare programs and tier-two hospital modernization.
Product Classification Framework
● By Detector Conversion Physics:
* Energy-Integrating Detector (EID) CT: The incumbent industry benchmark utilizing indirect conversion mechanics. Attenuated photons strike scintillating ceramic or crystal substrates (e.g., gadolinium oxysulfide, LYSO), generating low-energy visible light subsequently captured by paired silicon photodiodes and digitized by custom Application-Specific Integrated Circuits (ASICs). EID underpins standard diagnostic configurations from entry-level 16-slice installations through ultra-premium 640-slice configurations, though it introduces intrinsic electronic readout noise and compromises spatial resolution due to optical crosstalk across septic walls.
* Photon-Counting Detector (PCD) CT: The frontier architecture utilizing direct-conversion semiconductor substrates (cadmium telluride [CdTe] or cadmium zinc telluride [CZT]). PCD-CT counts discrete incident photons and discriminates their energy profiles without intermediate optical conversion. By eliminating scintillation light spread, detector pixel pitches are engineered down to sub-millimeter scales (often one-ninth the active area of conventional EID cells), completely eradicating electronic readout noise, drastically increasing spatial resolution, facilitating native multi-energy spectral tissue characterization, and lowering ionizing dose thresholds. Commercial implementations include the Siemens Healthineers Naeotom Alpha, alongside native Chinese platform advances such as the Shanghai United Imaging uCT Ultima and clinical prototypes from Canon Medical Systems.
● By Slice Count & Technological Hierarchy:
* 16–32 Slices (Entry-Level & Grassroots CT): Tailored for primary care, community facilities, mobile platforms, and emergent triage. Scanners feature 0.55mm–0.6mm slice acquisition geometries, embedded artificial intelligence for zero-click anatomical positioning, robust iterative reconstruction pipelines, and anode assemblies operating between 3.8 MHU and 5.3 MHU. Key models: Shanghai United Imaging uCT Orion series, Beijing Wandong TurboTom 1S, and SinoVision AlphaCT 300 series.
* 64–128 Slices (High-End Clinical Diagnostic CT): The volume workhorse across general, secondary, and tertiary clinical settings. Optimized for non-emergent oncology, routine neurology, abdominal mapping, and controlled cardiac imaging. Built with gantry apertures between 75cm and 82cm, rotation dynamics from 0.25s to 0.37s, and X-ray tubes offering 5.3 MHU to 30 MHU equivalent thermal capacity. Representative platforms: GE HealthCare Revolution Ascend/Maxima, Siemens SOMATOM go./X.cite, Philips Incisive CT, Canon Aquilion Serve, SinoVision InsitumCT 768, and United Imaging uCT 780/860 series.
* 256–640 Slices (Ultra-High-End, Wide-Body & Dual-Source CT): Tier-one research and academic platforms incorporating up to 16cm longitudinal anatomical coverage per gantry rotation or dual-source tube-detector arrangements. Designed for uncompromised, motion-free, single-cardiac-cycle volumetric acquisitions at unrestricted heart rates, exhibiting temporal resolutions down to 8 milliseconds and gantry rotation times below 0.25 seconds. Models: Shanghai United Imaging uCT SiriuX / SiriuX Pro and uCT Atlas Pro, GE HealthCare Revolution Apex, Philips Spectral CT 7500, Canon Aquilion ONE series, and SinoVision AlphaCT 968.
● By Clinical Form Factor & Scenario Specialization:
* Fixed Whole-Body Diagnostic CT: Base installations situated in dedicated radiology environments delivering broad outpatient and inpatient diagnostic services.
* Radiation Therapy Simulation CT (RT Sim CT): Large-bore gantries (80cm to 87cm) integrating wide reconstructed fields-of-view (FOV), flat carbon-fiber indexing tabletops, respiratory 4D gating triggers, and high-precision external moving laser targets for accurate stereotactic alignment and oncological dose deposition modeling.
* Point-of-Care & Mobile CT (mCT): Compact, self-shielded, or motorized platforms installed directly inside intensive care units, neuro-interventional operating rooms, and custom-built mobile stroke ambulances to optimize hyper-acute stroke interventions. Key architectures: Samsung / NeuroLogica OmniTom and BodyTom lines.
* Hybrid Angio-CT Systems: Floor-mounted or ceiling-suspended rail assemblies integrating multi-slice CT gantries directly in line with single-plane or bi-plane C-arm digital subtraction angiography (DSA) units, permitting real-time volumetric guidance during complex vascular or percutaneous interventions without patient transfer.
* Specialized Vertical Weight-Bearing CT: Structural gantries engineered with dynamic vertical translation mechanisms to capture musculoskeletal examinations in standing or seated configurations under physiological gravity loads. This directly reveals occult biomechanical pathologies and dynamic joint alterations masked during horizontal supine exams. Prominent examples include the SinoVision OmegaCT One.
Downstream Applications
● Human Clinical Healthcare:
* Oncology & Radiation Therapy: Indispensable across the cancer management pathway, including low-dose lung screening, TNM staging, target volume delineation, stereotactic body radiation therapy (SBRT) simulation, and post-therapeutic RECIST assessment.
* Cardiology & Vascular Medicine: Coronary computed tomography angiography (CCTA), plaque characterization, hemodynamic fractional flow reserve (FFR-CT) modeling, transcatheter aortic valve replacement (TAVR) planning, and post-stent patency verification. Wide-body systems eliminate the need for pharmacologic heart-rate modulation.
* Neurology & Acute Stroke Care: Serving as the foundational diagnostic triage tool to differentiate ischemic from hemorrhagic stroke events. Rapid perfusion mapping, automated core-penumbra software segmentation, and acute vessel occlusions are diagnosed in hyper-acute windows, notably supported by intra-facility mobile units.
* Musculoskeletal & Orthopedic Imaging: Fine-detail cortical bone delineation, multi-fragmentary trauma reconstruction, and standing biomechanical force vector assessments.
* Interventional Guidance & Intraoperative Diagnostics: Intraprocedural cross-sectional needle navigation during percutaneous ablations, biopsies, deep-tissue drainage, and complex spine surgeries.
* Public Health & Outbreak Diagnostics: Mobile truck-mounted scanning units providing programmatic population chest triage and dynamic emergency mobilization during regional epidemiological surges.
● Veterinary & Preclinical Animal Research:
* Companion & Production Veterinary Medicine: Dedicated scanners adapted for small animal morphology and large livestock anatomy, featuring specialized anesthesia integration protocols, motion suppression algorithms, and rapid pitch capabilities.
* Preclinical Biopharmaceutical Evaluation: Specialized sub-10-micron micro-CT and integrated micro-PET/CT systems configured for dynamic non-invasive anatomical mapping, longitudinal in vivo drug target evaluations, toxicology assessments, and material scaffold characterizations.
Supply Chain Architecture & Bottleneck Resilience
The CT manufacturing ecosystem exhibits extreme consolidation at its upper tiers, where mechanical, material, and electrical tolerances push the boundaries of physics.
● Upstream Subsystems & Single Points of Failure:
* X-Ray Generation: The development of heavy-duty, liquid-metal bearing (LMB) tubes capable of shedding continuous kilowatt-scale thermal loads presents an immense technical barrier. High-end assemblies require anode thermal capacities reaching up to 30+ MHU. Global supply remains concentrated among specialized merchants (Varex Imaging, Dunlee/Philips) alongside vertically integrated captive lines run by Siemens Healthineers, GE HealthCare, Canon, and emerging native operations within Shanghai United Imaging and Wandong. The high-voltage generator requires ultra-dense power switching platforms capable of cycling up to 120kW with dynamic modulation between 70kV and 140kV, predominantly anchored by specialized vendors such as Spellman High Voltage.
* Detector Conversion Modules: Sourcing scintillation materials (e.g., Ultra-Fast Ceramics, specialized rare-earth oxysulfides) relies on precision chemical manufacturing. In PCD-CT architectures, the primary supply constraint is the high-yield crystallographic growth and ultra-planar slicing of Cadmium Zinc Telluride (CZT) and Cadmium Telluride (CdTe) ingots. Transitioning from small-batch research wafers to reliable industrial supplies remains the critical industry bottleneck. Tileable multi-channel ASIC arrays require deep fabrication ties with tier-one semiconductor foundries.
* High-Speed Mechanical Interfaces: Rotating gantries handling centrifugal forces exceeding 40 Gs at rotation speeds of 0.23 seconds per revolution demand zero-friction contactless slip rings for megabit-to-gigabit optical data multiplexing and dynamic uninterrupted power transmission. ASGs (Anti-Scatter Grids) configured to eliminate high-angle off-focal radiation are supplied by specialized precision manufacturers such as JPI Healthcare.
● Midstream Value Migration & Architectural Control:
Value is pivoting rapidly away from basic mechanical frame manufacturing toward proprietary system control firmware, AI-native edge compute engines, and image reconstruction software. The integration of advanced deep-learning reconstruction engines directly onto compute stacks (Nvidia GPU/TPU platforms) enables suppliers to offset lower hardware component margins by selling recurring software licenses and advanced feature activations.
● Downstream Procurement & Channel Mechanics:
Sales pathways diverge along institutional profiles:
* Direct Sales Engine: OEMs manage major tertiary academic medical hubs, provincial healthcare alliances, and large multi-hospital integrated delivery networks (IDNs) through internal account management, specialized clinical application personnel, and long-term full-risk service contracts.
* Authorized Dealer Framework: In tier-two regional hospitals, rural county systems, and secondary export territories, OEMs rely on commercial buy-out dealer models. Distributors absorb local credit risks, process domestic tenders, and orchestrate basic field maintenance. In key Asian manufacturing regions, 60% to 67% of domestic volume flows through distributor frameworks.
* Centralized Procurement Frameworks: State-managed bidding mechanisms—most visibly exemplified by China's provincial Volume-Based Procurement (VBP) programs—exert intense downward pricing leverage on baseline hardware, driving commoditization across 16-to-64-slice products and favoring vertically integrated domestic champions.
Regional Market Dynamics
● North America (United States & Canada)
Maintaining the premier global revenue position, North American market dynamics are characterized by massive capital consolidation, steady fleet replacement trajectories, and the continuous migration of diagnostic throughput from hospital environments into off-campus Ambulatory Surgical Centers (ASCs) and private imaging facilities. Strategic audits indicate average CT machine density in the United States hovers at approximately 43 systems per million individuals.
Growth is driven by advanced clinical integration: rapid commercial adoption of ultra-premium photon-counting CT platforms, dual-source cardiac systems, and AI-enabled stroke networks. However, margin structures face regulatory shifts. US Centers for Medicare & Medicaid Services (CMS) adjustments aimed at rate site neutrality between hospital-owned departments and independent diagnostic centers affect operational returns. Heightened supply chain oversight via Section 232 investigations introduces tariff volatility for upstream mechanical components, while strict compliance frameworks (FDA 510(k), Energy Star imaging criteria) dictate entry standards.
● Asia-Pacific (APAC)
Asia-Pacific represents the fastest-growing and highest-volume market globally. The region features vast divergences in technological maturity, spanning fully saturated healthcare networks and rapid modernization programs.
* China: Represents the anchor market within APAC. Density metrics have climbed to approximately 30 CT scanners per million population. Competitive dynamics have shifted due to the national "Large-Scale Equipment Renewal" program, coupled with extensive "County-Level Healthcare Strengthening" initiatives. These measures have driven significant equipment modernizations across county hospitals, favoring domestic champions like Shanghai United Imaging, SinoVision Technologies, and Wandong Medical. Foreign multinational dominance has faced structural pressure from continuous Volume-Based Procurement (VBP), anti-corruption enforcement, and preferential policies for domestic medical devices. Expedited green-channel reviews by the National Medical Products Administration (NMPA) continue to accelerate domestic innovation cycles.
* Japan: Displays the densest scanner saturation globally, registering approximately 120 CT systems per million individuals. The procurement landscape is almost exclusively replacement-driven, focused on small-footprint units, extreme workflow automation, and multi-position standing platforms.
* Emerging APAC (India, Indonesia, Vietnam, Central Asia): Experiencing rapid multi-year growth fueled by the expansion of private healthcare syndicates and multi-city private hospital networks (e.g., Apollo Group), coupled with public modernization projects across Southeast and Central Asia. These programs heavily absorb tier-two 16-to-128-slice platforms.
● Europe
Western Europe (led by Germany, the United Kingdom, France, and the Netherlands) represents the second-largest CT valuation globally. Procurement behavior centers around the replacement of aging hospital installations exceeding 8 to 10 years of service, supported by green operational policies, patient-centric radiation reduction, and comprehensive total cost of ownership (TCO) lifecycle guarantees.
The operating environment is governed by regulatory overhead: the mandatory migration to the EU Medical Device Regulation (EU MDR) and In Vitro Diagnostic Regulation (IVDR) has significantly increased clinical validation timelines and post-market tracking overhead. Simultaneously, the rollout of the European Health Data Space (EHDS) and the EU Data Act introduces strict data security and interoperability mandates on networked imaging fleets. Procurement tenders increasingly integrate circular economy requirements, such as guaranteed component remanufacturing paths and strict power-efficiency baselines.
● Latin America (Central & South America)
Latin America represents an emerging frontier. Regional demand across key hubs—notably Brazil, Mexico, Colombia, Peru, and Argentina—is sustained by private diagnostic networks and targeted public hospital modernizations. The installed base remains heavily weighted toward standard-tier 16-to-64-slice systems, though high-end institutions are actively acquiring specialized wide-bore and oncology-configured scanners.
To overcome significant import tariff barriers, regional currency volatility, and local content restrictions, OEMs are leveraging strategic partnerships for local knockdown assembly—such as Wandong Medical’s tactical alignment with Brazil's VMI Group. Concurrently, United Imaging has expanded its footprint through direct installations of ultra-high-end PET/CT and multi-slice scanners across premier academic facilities throughout Mexico, Colombia, and the Southern Cone.
● Middle East & Africa (MEA)
The MEA market presents a distinct dual-structure environment. Low baseline CT per-capita density and an reliance on foreign capital imports define the broader region.
* GCC States: High-income Gulf nations (Saudi Arabia, UAE, Qatar, Kuwait) execute capital-intensive healthcare infrastructure master plans, directly procuring ultra-high-end photon-counting platforms, wide-body 640-slice configurations, and hybrid intraoperative Angio-CT systems for state cancer centers and specialized hospitals.
* Levant & African Continent: Demand is driven by bilateral sovereign credit facilities, United Nations / WHO developmental tenders, and the expansion of private diagnostic imaging labs. In these cost-sensitive, high-throughput settings, Chinese OEMs operating under "Belt and Road" bilateral trade channels have captured significant market share, supplying durable 16-to-64-slice hardware and ruggedized, self-contained mobile container CT trailers designed to withstand erratic electrical infrastructure and harsh environments.
Strategic Profiles of Key Market Players
1. Global Multimodal Conglomerates
● GE HealthCare
* Corporate Dossier: Spun off from its industrial parent, GE HealthCare maintains an extensive global installed imaging base, supported by a specialized direct sales force of nearly 10,000 personnel.
* Flagship Architectures: The Revolution family anchors its portfolio, led by the Revolution Apex Elite. The platform pairs a 160mm Gemstone Clarity detector with 0.23-second rotational mechanics and ultrafast kV switching for Gemstone Spectral Imaging (GSI). The Revolution Ascend and Maxima address mid-tier volume throughput using AI-based "Effortless Workflow" 3D camera auto-centering. Molecular imaging is anchored by the Discovery MI and Omni Legend PET/CT lines, alongside the Discovery RT platform for oncology simulation.
* Core Differentiators & Moats: Proprietary TrueFidelity deep learning image reconstruction (DLIR) utilizes deep neural networks trained against ground-truth filtered back-projection datasets, eliminating the synthetic waxy textures of early iterative engines. Following its acquisition of Prismatic Sensors, the group focuses proprietary R&D on deep silicon-based photon-counting detector crystals to maximize spatial resolution.
● Siemens Healthineers
* Corporate Dossier: The healthcare arm of Siemens AG, this company holds significant market share across Western Europe and North America, leveraging advanced engineering and dual-source CT capabilities.
* Flagship Architectures: The NAEOTOM Alpha represents the market's first commercially available dual-source Photon-Counting CT system, leveraging CdTe direct-conversion semiconductor crystals to hit 0.11mm isotropic spatial resolution without electronic noise. Its conventional fleet centers on the dual-source SOMATOM Force, SOMATOM Drive, and the compact SOMATOM Pro.Pulse. Single-source systems include the SOMATOM go. mobile-tablet series, the large-bore SOMATOM X.cite, and dedicated go.Sim / go.Open Pro radiation therapy configurations.
* Core Differentiators & Moats: The dual-source geometry (two tubes and two detectors operating at varying angles and energies) provides unmatched 66ms temporal resolution and fast pitch rates, enabling non-sedated, pediatric, and high-heart-rate coronary studies.
● Philips
* Corporate Dossier: Royal Philips executes a dedicated clinical workflow and detector-based spectral strategy, backed by advanced enterprise informatics.
* Flagship Architectures: The Spectral CT 7500 utilizes an 8cm NanoPanel Prism dual-layer detector, splitting low- and high-energy photons at the detector layer. This ensures simultaneous, temporal-spatial multi-energy data acquisition across 100% of scans without pre-scan protocol limitations or dose penalties. Workhorse tiers comprise the Incisive CT platform (64/128-slice) and the CT 5000/5300 systems. Dedicated RT sim is addressed via the CT Big Bore (85cm aperture).
* Core Differentiators & Moats: The vMRC tube architecture, paired with life-of-system tube replacement guarantees, lowers institutional lifecycle TCO. Deep-learning Precise Image engines yield noise drops up to 85% and radiation reductions up to 80%, supported by TubeWatch predictive analytics to mitigate unexpected downtime.
● Canon Medical Systems
* Corporate Dossier: The medical division of Canon Inc. leverages proprietary wide-area detector engineering, advanced precision ceramics, and deep diagnostic integration.
* Flagship Architectures: Led by the Aquilion ONE / PRISM Edition and Aquilion ONE / INSIGHT Edition platforms, featuring 16cm longitudinal Area Detector CT (ADCT) arrays for single-rotation whole-organ volumetric coverage. The lineup is supported by the Aquilion Serve, Aquilion Prime SP, and the Aquilion Exceed LB (wide-bore oncology).
* Core Differentiators & Moats: Pioneer of commercial deep-learning reconstruction through its AiCE (Advanced Intelligent Clear-IQ Engine). The company is actively conducting extensive multi-center international trials on specialized PCD-CT prototypes across Japanese and North American university research hubs.
● Fujifilm Healthcare
* Corporate Dossier: Expanded its presence in global diagnostic CT via the acquisition of Hitachi’s diagnostic imaging business, focusing on space-efficient footprints and ergonomics.
* Flagship Architectures: Anchored by the SCENARIA View, a premium 64/128-slice diagnostic scanner featuring an 80cm aperture, alongside the Supria family (Supria 16, 64, and Supria Grande).
* Core Differentiators & Moats: Proprietary Intelli IPV deep-learning iterative processing algorithms optimize high-frequency spatial structures. Systems are engineered for low power consumption, minimal mechanical footprints, and rapid installation in space-constrained outpatient clinics.
2. Established Chinese Manufacturers: United Imaging Healthcare (UIH), Neusoft Medical Systems, MinFound Medical Systems, Shenzhen Anke High-tech Co., Ltd.,, Wandong Medical, SinoVision Technologies (Beijing) Co. Ltd., Shinva Medical Instrument Co. Ltd., and BOWING MEDICAL TECHNOLOGIES (BOZWIN).
3. Specialized Mobile, Intraoperative, and Extremity Developers: NeuroLogica Corp. / Samsung Healthcare, Brainlab, Planmed Oy and SG Healthcare.
Structural Opportunities & Core Bottlenecks
1. Transformative Market Opportunities
● The Commercial Transition to Photon-Counting CT: The shift from EID to PCD architectures represents a rare technological disruption window. Early institutional adopters (Siemens, United Imaging) are capturing significant prestige pricing and academic positioning. As CdTe and CZT crystal yields stabilize and costs fall over the next five to seven years, PCD-CT will systematically penetrate standard 64-to-128-slice hospital tiers. This will trigger a broad replacement cycle that renders traditional scintillator designs technically obsolete.
● Hardware Commoditization and the Rise of "Device-as-a-Service" (DaaS): Price compression across standardized hardware is accelerating the migration toward software-driven revenue models. OEMs are transitioning advanced reconstruction engines, multi-organ segmentation routines, and spectral analytics into recurring software-as-a-service (SaaS) and fee-per-scan licenses. This transition secures recurring, high-margin software revenues while lowering initial hardware capital expenditure thresholds for community clinics.
● Democratization of Diagnostic Imaging in Emerging Markets: Coordinated state investment in rural and county-level healthcare—exemplified by China’s "Thousand County Project" and nationwide infrastructure updates across Southeast Asia, Latin America, and the Middle East—creates persistent demand for automated 32-to-128-slice CT platforms. Incorporating AI-guided scanning protocols enables lower-tier regional clinics to perform diagnostic-quality exams despite chronic shortages of certified radiological technologists.
● Specialized Form Factors and Point-of-Care Expansion: Diagnostic throughput is expanding beyond traditional radiology departments. Mobile stroke units, intraoperative surgical suites, and specialized vertical weight-bearing musculoskeletal clinics are establishing high-margin clinical niches that bypass legacy procurement channels.
2. Structural Inhibitors and Supply Chain Vulnerabilities
● Geopolitical Tensions and Upstream Supply Vulnerability: Heightened geopolitical fragmentation, tariff increases, and expanding national security reviews over critical medical technologies introduce structural supply risks. High-acuity components—such as heavy-duty liquid-metal bearing tubes, specialized target substrates, multi-channel readout ASICs, and precision semiconductor materials—remain geographically concentrated among a small cluster of Western and Asian facilities. Trade disruptions threaten assembly timelines and reduce operating margins.
● Public Procurement and Hardware Price Compression: Government-mandated tender frameworks, most visible in large-scale provincial Volume-Based Procurement (VBP) across China, continue to erode hardware gross margins. While driving higher shipment volumes, this forces manufacturers to optimize production cost structures and streamline bill-of-materials expenditures simply to defend operational viability.
● Evolving Regulatory Compliance Hurdles: Increasingly stringent regulatory oversight—notably the administrative and clinical evidentiary requirements imposed by the European Union Medical Device Regulation (EU MDR), alongside tightened US FDA post-market cybersecurity demands—has significantly lengthened time-to-market trajectories. Smaller and mid-tier OEMs struggle to absorb these compliance expenditures, consolidating high-tier innovation within large conglomerates.
● The Global Radiologist Workforce Deficit: A worldwide shortage of board-certified radiologists, exacerbated by institutional burnout and surging overall exam volumes, remains a structural operational bottleneck. Scanners capable of delivering high-throughput acquisitions are frequently constrained by the processing capacity of diagnostic reading pools. This imbalance places an urgent operational premium on AI-driven automated report pre-population, acute scan triage, and automated reconstruction platforms.
1.1 Executive Synthesis and Scope Definition 1
1.2 Analytical Framework and Quantitative Modeling Logic 2
1.3 Primary Data Sourcing and Secondary Triangulation 3
1.4 Economic Assumptions and Bottom-Up Validation Parameters 5
1.5 Nomenclature and Technical Abbreviations 6
Chapter 2 Global Computed Tomography (CT) Market Landscape and Ecosystem Architecture 7
2.1 Systemic Architecture and Global Market Trajectory 7
2.2 Global Market Value and Volume Evolution (2021-2031) 8
2.3 Value Migration Drivers, Macro Cost Pressures, and Procurement Cycles 10
2.4 Total Installed Base Dynamics and Equipment Replacement Lifecycles 12
Chapter 3 Upstream Supply Chain, Component Fabrication, and Value Chain Economics 13
3.1 Upstream Critical Bill-of-Materials Decomposition 13
3.1.1 High-Capacity Liquid Metal Bearing X-Ray Tubes and Anode Targets 14
3.1.2 High-Voltage Generators and Power Conditioning Infrastructure 15
3.1.3 Scintillator Crystals, Photodiode Arrays, and Semiconductor Materials 16
3.1.4 Direct-Conversion Cadmium Telluride/Cadmium Zinc Telluride (CdTe/CZT) Substrates 17
3.1.5 Slip-Ring Data Transmission and Gantry Mechanical Assemblies 18
3.2 Upstream Cost Structure Analysis and Raw Material Margin Compression 19
3.3 Supply Chain Resilience and Component Bottleneck Risk Assessment 20
Chapter 4 Global Computed Tomography (CT) Market by Detector Conversion Physics 21
4.1 Architectural Breakdown: Energy-Integrating vs. Direct Photon-Counting 21
4.2 Energy-Integrating Detector CT (EID-CT) 22
4.2.1 Operational Principle and Volume Consumption Patterns (2021-2031) 22
4.2.2 Market Size Trajectory 23
4.3 Photon-Counting Detector CT (PCD-CT) 24
4.3.1 Spectral Spatial Resolution, Contrast Optimization, and Radiation Reduction 24
4.3.2 Commercial Penetration, Volume Output, and Market Size (2021-2031) 25
Chapter 5 Global Computed Tomography (CT) Market by Slice Configuration Architecture 27
5.1 Technical Differentiation by Temporal Resolution and Coverage Width 27
5.2 16–32 Slice Systems 28
5.2.1 Core Diagnostics, Ambulatory Utility, and Procurement Volumes 28
5.2.2 Market Size (2021-2031) 29
5.3 64–128 Slice Systems 30
5.3.1 General Hospital Workhorse Deployment and Volume Trajectory 30
5.3.2 Market Size (2021-2031) 31
5.4 256–640 Slice Ultra-Premium Systems 32
5.4.1 Whole-Organ Perfusion, Dynamic Cardiovascular Imaging, and Volumetric Adoption 32
5.4.2 Capital Outlay Expansion, Market Size Trajectory (2021-2031) 33
Chapter 6 Global Computed Tomography (CT) Market by Clinical Architecture and Form Factor 34
6.1 Form Factor Typologies and Installation Infrastructure Constraints 34
6.2 Fixed Whole-Body Diagnostic CT 35
6.3 Radiation Therapy Simulation CT 36
6.4 Point-of-Care & Mobile CT 38
6.5 Hybrid Angio-CT System 39
6.6 Specialized Vertical Weight-Bearing CT 41
Chapter 7 Global Computed Tomography (CT) Market by Downstream Application Matrix 42
7.1 Clinical and Preclinical Consumption Spectrum 42
7.2 Human Clinical Healthcare 43
7.2.1 Oncology, Cardiovascular, Neurovascular, and Musculoskeletal Demand 43
7.2.2 Tier-1 Academic Medical Centers vs. Ambulatory Surgical Centers (2021-2031) 44
7.3 Veterinary & Preclinical Animal Imaging 45
7.3.1 Academic Life Science Research and Pharmaceutical Development Workflows 45
7.3.2 Advanced Veterinary Specialty Hospital Installations and Utilization (2021-2031) 46
Chapter 8 Global Trade Matrix, Regulatory Paradigms, and Import/Export Flow Dynamics 48
8.1 Cross-Border Trade Flows of Finished CT Systems 48
8.2 Tariff Schedules, Export Controls, and Dual-Use Technology Regulations 50
8.3 Medical Device Regulatory Pathways (FDA 510(k)/PMA, EU MDR, NMPA) 51
8.4 Reverse Logistics, Certified Pre-Owned Systems, and Remanufactured Unit Flows 53
Chapter 9 Regional Production Hubs and Consumption Dynamics 54
9.1 North America 54
9.1.1 United States: Manufacturing Capability, Federal Policy, and Consumption Dynamics 55
9.1.2 Canada: Public Healthcare Capital Allocation and Replacement Timelines 57
9.2 Europe 58
9.2.1 Germany: Precision Manufacturing Center and Domestic Hospital Uptake 59
9.2.2 France: Diagnostic Modernization Frameworks and Fleet Renewal 60
9.2.3 United Kingdom: NHS Procurement Paradigms and Community Diagnostic Centers 61
9.2.4 Netherlands, Italy, Spain and Rest of Europe Market 62
9.3 Asia-Pacific 63
9.3.1 China: Domestic Manufacturing Acceleration, Volume-Based Procurement, and Consumption 64
9.3.2 Japan: Ultra-High CT Density, Domestic Innovation Hubs, and Replacement Velocity 65
9.3.3 South Korea: Specialized In-Hospital Deployments and Export Footprint 66
9.3.4 India & Southeast Asia: Private Diagnostic Network Expansion and Low-to-Mid Tier Sourcing 67
9.4 Latin America 67
9.4.1 Brazil: Secondary Sourcing Networks, Import Tariffs, and Private Hospital Capex 67
9.4.2 Mexico: Nearshore Assembling Dynamics and Regional Hospital System Demand 68
9.5 Middle East & Africa 68
9.5.1 Saudi Arabia: Mega-Hospital Projects and High-End CT Infrastructure 68
9.5.2 United Arab Emirates: Medical Tourism Hub Expansion and Premium Technology Uptake 68
Chapter 10 Competitive Benchmark and Market Share Concentration Matrix 69
10.1 Global Vendor Concentration Ratios (CR4, CR8, HHI Analysis) 69
10.2 Tiered Vendor Categorization: Multinationals vs. Regional Disruptors 70
10.3 Pricing Power Dynamics, Average Realized Prices, and Service Contract Margins 71
10.4 Strategic Alliances, Component Outsourcing, and Vertical Integration Strategies 72
Chapter 11 Corporate Intelligence and Competitor Operational Dossiers 74
11.1 GE HealthCare 74
11.1.1 Operational Profile and Strategic Footprint 74
11.1.2 Computed Tomography (CT) Portfolio and Technical Capabilities 74
11.1.3 Operational Matrix: Sales Volume, Revenue, Price, Cost, and Gross Margin (2021-2026) 75
11.1.4 Global Market Share Performance (2021-2026) 75
11.1.5 SWOT Assessment and Strategic Horizons 76
11.2 Siemens Healthineers 77
11.2.1 Operational Profile and Strategic Footprint 77
11.2.2 Computed Tomography (CT) Portfolio and Technical Capabilities 77
11.2.3 Operational Matrix: Sales Volume, Revenue, Price, Cost, and Gross Margin (2021-2026) 78
11.2.4 Global Market Share Performance (2021-2026) 78
11.2.5 SWOT Assessment and Strategic Horizons 79
11.3 Philips 80
11.3.1 Operational Profile and Strategic Footprint 80
11.3.2 Computed Tomography (CT) Portfolio and Technical Capabilities 80
11.3.3 Operational Matrix: Sales Volume, Revenue, Price, Cost, and Gross Margin (2021-2026) 81
11.3.4 Global Market Share Performance (2021-2026) 81
11.3.5 SWOT Assessment and Strategic Horizons 82
11.4 Canon Medical Systems 83
11.4.1 Operational Profile and Strategic Footprint 83
11.4.2 Computed Tomography (CT) Portfolio and Technical Capabilities 83
11.4.3 Operational Matrix: Sales Volume, Revenue, Price, Cost, and Gross Margin (2021-2026) 84
11.4.4 Global Market Share Performance (2021-2026) 84
11.4.5 SWOT Assessment and Strategic Horizons 85
11.5 Fujifilm 86
11.5.1 Operational Profile and Strategic Footprint 86
11.5.2 Computed Tomography (CT) Portfolio and Technical Capabilities 86
11.5.3 Operational Matrix: Sales Volume, Revenue, Price, Cost, and Gross Margin (2021-2026) 87
11.5.4 Global Market Share Performance (2021-2026) 87
11.5.5 SWOT Assessment and Strategic Horizons 88
11.6 Neurologica Corp./Samsung Healthcare 89
11.6.1 Operational Profile and Strategic Footprint 89
11.6.2 Computed Tomography (CT) Portfolio and Technical Capabilities 89
11.6.3 Operational Matrix: Sales Volume, Revenue, Price, Cost, and Gross Margin (2021-2026) 90
11.6.4 Global Market Share Performance (2021-2026) 90
11.6.5 SWOT Assessment and Strategic Horizons 91
11.7 United Imaging Healthcare 92
11.7.1 Operational Profile and Strategic Footprint 92
11.7.2 Computed Tomography (CT) Portfolio and Technical Capabilities 92
11.7.3 Operational Matrix: Sales Volume, Revenue, Price, Cost, and Gross Margin (2021-2026) 93
11.7.4 Global Market Share Performance (2021-2026) 93
11.7.5 SWOT Assessment and Strategic Horizons 94
11.8 Wandong Medical 95
11.8.1 Operational Profile and Strategic Footprint 95
11.8.2 Computed Tomography (CT) Portfolio and Technical Capabilities 95
11.8.3 Operational Matrix: Sales Volume, Revenue, Price, Cost, and Gross Margin (2021-2026) 96
11.8.4 Global Market Share Performance (2021-2026) 96
11.8.5 SWOT Assessment and Strategic Horizons 97
11.9 SinoVision Technologies (Beijing) Co. Ltd. 98
11.9.1 Operational Profile and Strategic Footprint 98
11.9.2 Computed Tomography (CT) Portfolio and Technical Capabilities 98
11.9.3 Operational Matrix: Sales Volume, Revenue, Price, Cost, and Gross Margin (2021-2026) 99
11.9.4 Global Market Share Performance (2021-2026) 99
11.9.5 SWOT Assessment and Strategic Horizons 100
11.10 Shinva Medical Instrument Co. Ltd. 101
11.10.1 Operational Profile and Strategic Footprint 101
11.10.2 Computed Tomography (CT) Portfolio and Technical Capabilities 101
11.10.3 Operational Matrix: Sales Volume, Revenue, Price, Cost, and Gross Margin (2021-2026) 102
11.10.4 Global Market Share Performance (2021-2026) 102
11.10.5 SWOT Assessment and Strategic Horizons 103
11.11 Shenzhen Anke High-tech Co. Ltd. 104
11.11.1 Operational Profile and Strategic Footprint 104
11.11.2 Computed Tomography (CT) Portfolio and Technical Capabilities 104
11.11.3 Operational Matrix: Sales Volume, Revenue, Price, Cost, and Gross Margin (2021-2026) 105
11.11.4 Global Market Share Performance (2021-2026) 105
11.11.5 SWOT Assessment and Strategic Horizons 106
11.12 Neusoft Medical Systems 107
11.12.1 Operational Profile and Strategic Footprint 107
11.12.2 Computed Tomography (CT) Portfolio and Technical Capabilities 107
11.12.3 Operational Matrix: Sales Volume, Revenue, Price, Cost, and Gross Margin (2021-2026) 108
11.12.4 Global Market Share Performance (2021-2026) 108
11.12.5 SWOT Assessment and Strategic Horizons 109
11.13 MinFound Medical Systems 110
11.13.1 Operational Profile and Strategic Footprint 110
11.13.2 Computed Tomography (CT) Portfolio and Technical Capabilities 110
11.13.3 Operational Matrix: Sales Volume, Revenue, Price, Cost, and Gross Margin (2021-2026) 111
11.13.4 Global Market Share Performance (2021-2026) 111
11.13.5 SWOT Assessment and Strategic Horizons 112
11.14 BOWING MEDICAL TECHNOLOGIES 113
11.14.1 Operational Profile and Strategic Footprint 113
11.14.2 Computed Tomography (CT) Portfolio and Technical Capabilities 113
11.14.3 Operational Matrix: Sales Volume, Revenue, Price, Cost, and Gross Margin (2021-2026) 114
11.14.4 Global Market Share Performance (2021-2026) 114
11.14.5 SWOT Assessment and Strategic Horizons 115
11.15 Brainlab 116
11.15.1 Operational Profile and Strategic Footprint 116
11.15.2 Computed Tomography (CT) Portfolio and Technical Capabilities 116
11.15.3 Operational Matrix: Sales Volume, Revenue, Price, Cost, and Gross Margin (2021-2026) 117
11.15.4 Global Market Share Performance (2021-2026) 117
11.15.5 SWOT Assessment and Strategic Horizons 118
11.16 Planmed Oy 119
11.16.1 Operational Profile and Strategic Footprint 119
11.16.2 Computed Tomography (CT) Portfolio and Technical Capabilities 119
11.16.3 Operational Matrix: Sales Volume, Revenue, Price, Cost, and Gross Margin (2021-2026) 120
11.16.4 Global Market Share Performance (2021-2026) 120
11.16.5 SWOT Assessment and Strategic Horizons 121
11.17 SG Healthcare 122
11.17.1 Operational Profile and Strategic Footprint 122
11.17.2 Computed Tomography (CT) Portfolio and Technical Capabilities 122
11.17.3 Operational Matrix: Sales Volume, Revenue, Price, Cost, and Gross Margin (2021-2026) 123
11.17.4 Global Market Share Performance (2021-2026) 123
11.17.5 SWOT Assessment and Strategic Horizons 124
Chapter 12 Technology Roadmap, IP Landscape, and Next-Generation Strategic Horizon 125
12.1 Deep Learning Reconstruction (DLR) and Generative AI Denoising Algorithms 125
12.2 CdTe/CZT Crystal Growth Scalability and PCD Yield Economics 127
12.3 Patent Filing Trajectories and Sovereign Intellectual Property Clusters 129
12.4 Strategic Consolidations, Divestitures, and Market Entry Imperatives (2027-2031) 131
Table 2 Primary Technical Nomenclature and Architectural Lexicon 6
Table 3 Global Computed Tomography (CT) Market Volume by Region (Units), 2021-2031 9
Table 4 Global Computed Tomography (CT) Market Revenue by Region (USD Million), 2021-2031 9
Table 5 Bill of Materials (BOM) Cost Breakdown for Tier-1 CT Systems (USD Thousand / Share %) 19
Table 6 Global Computed Tomography (CT) Market Volume by Detector Physics (Units), 2021-2031 23
Table 7 Global Computed Tomography (CT) Market Revenue by Detector Physics (USD Million), 2021-2031 24
Table 8 Global Computed Tomography (CT) Market Volume by Slice Configuration (Units), 2021-2031 28
Table 9 Global Computed Tomography (CT) Market Revenue by Slice Configuration (USD Million), 2021-2031 29
Table 10 Global Computed Tomography (CT) Market Volume by Form Factor (Units), 2021-2031 35
Table 11 Global Computed Tomography (CT) Market Revenue by Form Factor (USD Million), 2021-2031 36
Table 12 Global Computed Tomography (CT) Market Volume by Downstream Application (Units), 2021-2031 43
Table 13 Global Computed Tomography (CT) Market Revenue by Downstream Application (USD Million), 2021-2031 44
Table 14 Global Computed Tomography (CT) Cross-Border Trade Flows by Key Exporter (USD Million), 2021-2026 49
Table 15 Regulatory Pathways and Clearance Timelines for CT Equipment Across Major Jurisdictions 52
Table 16 North America Computed Tomography (CT) Market Volume and Revenue by Country, 2021-2031 55
Table 17 Europe Computed Tomography (CT) Market Volume and Revenue by Country, 2021-2031 58
Table 18 Asia-Pacific Computed Tomography (CT) Market Volume and Revenue by Country, 2021-2031 64
Table 19 Latin America Computed Tomography (CT) Market Volume and Revenue by Country, 2021-2031 67
Table 20 Middle East & Africa Computed Tomography (CT) Market Volume and Revenue by Country, 2021-2031 68
Table 21 Global Computed Tomography (CT) Vendor Concentration Metrics (CR4, CR8, HHI), 2021-2026 70
Table 22 GE HealthCare Computed Tomography (CT) Sales, Price, Cost and Gross Profit Margin (2021-2026) 75
Table 23 Siemens Healthineers Computed Tomography (CT) Sales, Price, Cost and Gross Profit Margin (2021-2026) 78
Table 24 Philips Computed Tomography (CT) Sales, Price, Cost and Gross Profit Margin (2021-2026) 81
Table 25 Canon Medical Systems Computed Tomography (CT) Sales, Price, Cost and Gross Profit Margin (2021-2026) 84
Table 26 Fujifilm Computed Tomography (CT) Sales, Price, Cost and Gross Profit Margin (2021-2026) 87
Table 27 Neurologica Corp./Samsung Healthcare Computed Tomography (CT) Sales, Price, Cost and Gross Profit Margin (2021-2026) 90
Table 28 United Imaging Healthcare Computed Tomography (CT) Sales, Price, Cost and Gross Profit Margin (2021-2026) 93
Table 29 Wandong Medical Computed Tomography (CT) Sales, Price, Cost and Gross Profit Margin (2021-2026) 96
Table 30 SinoVision Technologies (Beijing) Co. Ltd. Computed Tomography (CT) Sales, Price, Cost and Gross Profit Margin (2021-2026) 99
Table 31 Shinva Medical Instrument Co. Ltd. Computed Tomography (CT) Sales, Price, Cost and Gross Profit Margin (2021-2026) 102
Table 32 Shenzhen Anke High-tech Co. Ltd. Computed Tomography (CT) Sales, Price, Cost and Gross Profit Margin (2021-2026) 105
Table 33 Neusoft Medical Systems Computed Tomography (CT) Sales, Price, Cost and Gross Profit Margin (2021-2026) 108
Table 34 MinFound Medical Systems Computed Tomography (CT) Sales, Price, Cost and Gross Profit Margin (2021-2026) 111
Table 35 BOWING MEDICAL TECHNOLOGIES Computed Tomography (CT) Sales, Price, Cost and Gross Profit Margin (2021-2026) 114
Table 36 Brainlab Computed Tomography (CT) Sales, Price, Cost and Gross Profit Margin (2021-2026) 117
Table 37 Planmed Oy Computed Tomography (CT) Sales, Price, Cost and Gross Profit Margin (2021-2026) 120
Table 38 SG Healthcare Computed Tomography (CT) Sales, Price, Cost and Gross Profit Margin (2021-2026) 123
Table 39 Priority Patent Filings in Photon-Counting and Gantry Engineering by Leading Assignees (2021-2026) 130
Figure 1 Global Computed Tomography (CT) Market Sizing and Growth Vector (2021-2031) 8
Figure 2 End-to-End Computed Tomography Value Chain and Value Capture Segments 14
Figure 3 Component Cost Distribution Matrix for High-Slice Diagnostic CT Systems 20
Figure 4 Global CT Market Share by Detector Physics: Energy-Integrating vs. PCD (2021 vs. 2026 vs. 2031) 22
Figure 5 Comparative Attenuation and Spatial Resolution Curves: PCD-CT vs. Conventional EID-CT 26
Figure 6 Global CT Unit Volume Trajectory by Slice Classification (16-32, 64-128, 256-640 Slices), 2021-2031 27
Figure 7 Pricing Erosion Curves Across Slice Tiers (USD Thousand), 2021-2031 31
Figure 8 Value Share by Clinical Form Factor Configuration (2026) 34
Figure 9 Point-of-Care & Mobile CT Adoption Rates in Critical Care Settings (2021-2031) 39
Figure 10 Downstream Volume Distribution: Human Clinical Healthcare vs. Veterinary & Preclinical (2026) 42
Figure 11 Global Computed Tomography Trade Balance Map by Major Manufacturing Nation (2026) 49
Figure 12 Regional Consumption Share of Global Computed Tomography Revenues (2021, 2026, 2031) 54
Figure 13 United States Hospital CT Installation Density per Million Population vs. Replacement Cycles 56
Figure 14 China Domestic Manufacturing Penetration Rate in Tier-2/Tier-3 Hospitals (2021-2026) 65
Figure 15 Global Computed Tomography Competitive Revenue Share Distribution (2026) 71
Figure 16 GE HealthCare Computed Tomography (CT) Market Share (2021-2026) 75
Figure 17 Siemens Healthineers Computed Tomography (CT) Market Share (2021-2026) 78
Figure 18 Philips Computed Tomography (CT) Market Share (2021-2026) 81
Figure 19 Canon Medical Systems Computed Tomography (CT) Market Share (2021-2026) 84
Figure 20 Fujifilm Computed Tomography (CT) Market Share (2021-2026) 87
Figure 21 Neurologica Corp./Samsung Healthcare Computed Tomography (CT) Market Share (2021-2026) 90
Figure 22 United Imaging Healthcare Computed Tomography (CT) Market Share (2021-2026) 93
Figure 23 Wandong Medical Computed Tomography (CT) Market Share (2021-2026) 96
Figure 24 SinoVision Technologies (Beijing) Co. Ltd. Computed Tomography (CT) Market Share (2021-2026) 99
Figure 25 Shinva Medical Instrument Co. Ltd. Computed Tomography (CT) Market Share (2021-2026) 102
Figure 26 Shenzhen Anke High-tech Co. Ltd. Computed Tomography (CT) Market Share (2021-2026) 105
Figure 27 Neusoft Medical Systems Computed Tomography (CT) Market Share (2021-2026) 108
Figure 28 MinFound Medical Systems Computed Tomography (CT) Market Share (2021-2026) 111
Figure 29 BOWING MEDICAL TECHNOLOGIES Computed Tomography (CT) Market Share (2021-2026) 114
Figure 30 Brainlab Computed Tomography (CT) Market Share (2021-2026) 117
Figure 31 Planmed Oy Computed Tomography (CT) Market Share (2021-2026) 120
Figure 32 SG Healthcare Computed Tomography (CT) Market Share (2021-2026) 123
Figure 33 Technological Evolution Roadmap: Direct Conversion, AI Iterative Engine, and Modular Gantries 126
Figure 34 Global CT Patent Filings Heatmap by Sovereign Jurisdiction and Technology Subcategory (2021-2026) 129
Research Methodology
- Market Estimated Methodology:
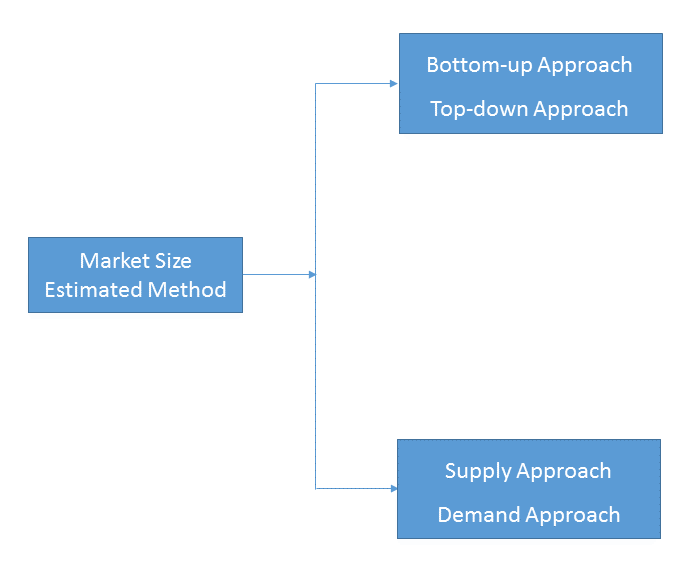
Bottom-up & top-down approach, supply & demand approach are the most important method which is used by HDIN Research to estimate the market size.
1)Top-down & Bottom-up Approach
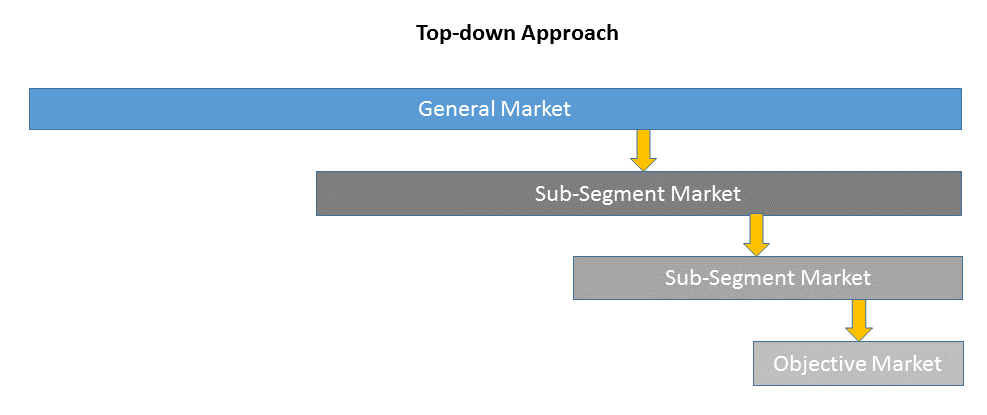
Top-down approach uses a general market size figure and determines the percentage that the objective market represents.
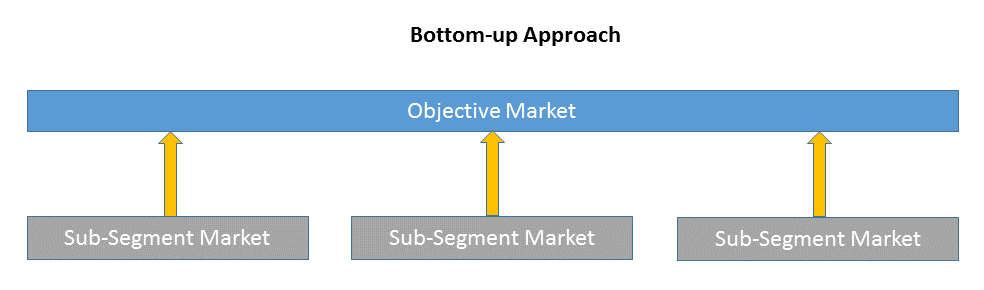
Bottom-up approach size the objective market by collecting the sub-segment information.
2)Supply & Demand Approach
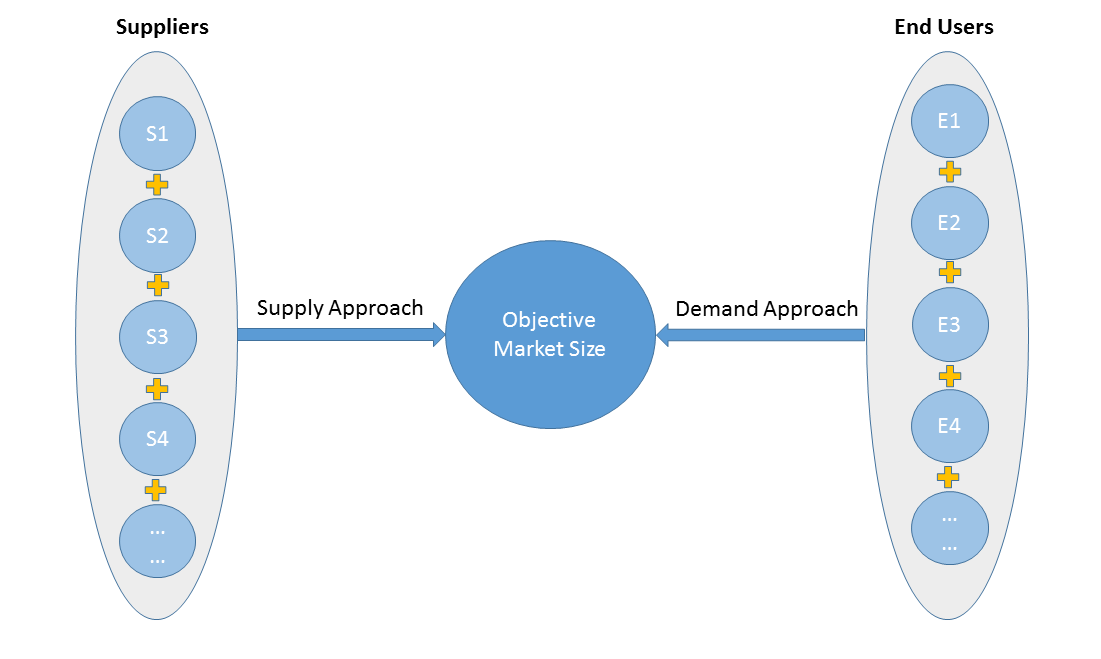
Supply approach is based on assessments of the size of each competitor supplying the objective market.
Demand approach combine end-user data within a market to estimate the objective market size. It is sometimes referred to as bottom-up approach.
- Forecasting Methodology
- Numerous factors impacting the market trend are considered for forecast model:
- New technology and application in the future;
- New project planned/under contraction;
- Global and regional underlying economic growth;
- Threatens of substitute products;
- Industry expert opinion;
- Policy and Society implication.
- Analysis Tools
1)PEST Analysis
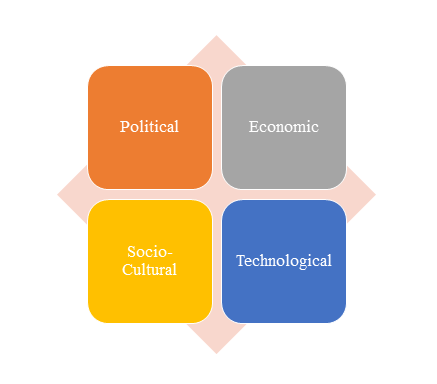
PEST Analysis is a simple and widely used tool that helps our client analyze the Political, Economic, Socio-Cultural, and Technological changes in their business environment.
- Benefits of a PEST analysis:
- It helps you to spot business opportunities, and it gives you advanced warning of significant threats.
- It reveals the direction of change within your business environment. This helps you shape what you’re doing, so that you work with change, rather than against it.
- It helps you avoid starting projects that are likely to fail, for reasons beyond your control.
- It can help you break free of unconscious assumptions when you enter a new country, region, or market; because it helps you develop an objective view of this new environment.
2)Porter’s Five Force Model Analysis
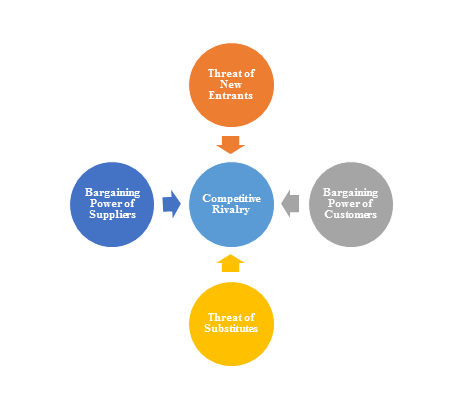
The Porter’s Five Force Model is a tool that can be used to analyze the opportunities and overall competitive advantage. The five forces that can assist in determining the competitive intensity and potential attractiveness within a specific area.
- Threat of New Entrants: Profitable industries that yield high returns will attract new firms.
- Threat of Substitutes: A substitute product uses a different technology to try to solve the same economic need.
- Bargaining Power of Customers: the ability of customers to put the firm under pressure, which also affects the customer's sensitivity to price changes.
- Bargaining Power of Suppliers: Suppliers of raw materials, components, labor, and services (such as expertise) to the firm can be a source of power over the firm when there are few substitutes.
- Competitive Rivalry: For most industries the intensity of competitive rivalry is the major determinant of the competitiveness of the industry.
3)Value Chain Analysis
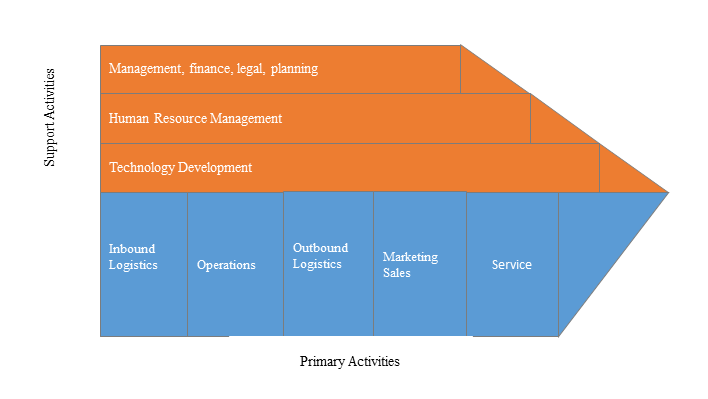
Value chain analysis is a tool to identify activities, within and around the firm and relating these activities to an assessment of competitive strength. Value chain can be analyzed by primary activities and supportive activities. Primary activities include: inbound logistics, operations, outbound logistics, marketing & sales, service. Support activities include: technology development, human resource management, management, finance, legal, planning.
4)SWOT Analysis
SWOT analysis is a tool used to evaluate a company's competitive position by identifying its strengths, weaknesses, opportunities and threats. The strengths and weakness is the inner factor; the opportunities and threats are the external factor. By analyzing the inner and external factors, the analysis can provide the detail information of the position of a player and the characteristics of the industry.
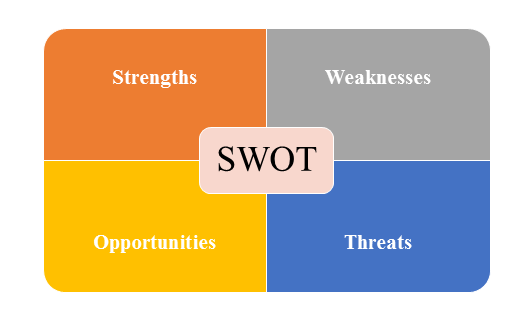
- Strengths describe what the player excels at and separates it from the competition
- Weaknesses stop the player from performing at its optimum level.
- Opportunities refer to favorable external factors that the player can use to give it a competitive advantage.
- Threats refer to factors that have the potential to harm the player.
- Data Sources
| Primary Sources | Secondary Sources |
|---|---|
| Face to face/Phone Interviews with market participants, such as: Manufactures; Distributors; End-users; Experts. Online Survey |
Government/International Organization Data: Annual Report/Presentation/Fact Book Internet Source Information Industry Association Data Free/Purchased Database Market Research Report Book/Journal/News |