Medical MRI System Market: Global Outlook & Tech Shifts
- Single User License (1 Users) $ 3,500
- Team License (2~5 Users) $ 4,500
- Corporate License (>5 Users) $ 5,500
The global Medical Magnetic Resonance Imaging (MRI) system market is valued at an estimated 9.2 to 10.8 billion USD in 2026, with institutional projections outlining a compound annual growth rate (CAGR) between 4.2% and 5.8% through 2031. Underlying this expansion is an acute macroeconomic and epidemiological demand: over one billion individuals globally live with neurological disorders, while aging demographics across key geographic zones drive an escalating incidence of cardiovascular pathologies and oncological malignancies.
Simultaneously, the physical, economic, and operational paradigm of clinical magnetic resonance is undergoing a generational change. Historically defined by incremental increases in magnetic field strength supported by deep-cryogenic liquid helium architectures, the market is diverging along two strategic axes:
1. Decentralization and Dematerialization: Driven by cryogen-free conduction-cooled magnets, zero-boil-off micro-helium envelopes, and portable ultra-low-field (ULF) bedside platforms operating on standard wall power.
2. Clinical Ultra-High-Field Specialization: Characterized by the commercialization of whole-body 5.0T systems, dynamic live-videographic 3.0T platforms, and Silicon Carbide (SiC) semiconductor gradient power electronics that drastically curb baseline power consumption.
The competitive landscape shows historic shifts. While the multinational triumvirate—Siemens Healthineers, GE HealthCare, and Royal Philips—maintains a combined global volume share between 65% and 70%, domestic champions in the Asia-Pacific theater, led by Shanghai United Imaging Healthcare and Beijing Wandong Medical, have altered procurement flows. Supported by centralized public volume-based procurement (VBP), hospital infrastructure renewal programs, and native component integration, domestic manufacturers have captured primary installation shares across major market tiers in China. This transition has compelled Western original equipment manufacturers (OEMs) to pivot toward advanced deep-learning k-space reconstruction software, flexible radiofrequency (RF) arrays, and Device-as-a-Service (DaaS) recurring operational models.
TAXONOMY AND ARCHITECTURAL DECOMPOSITION
Medical Magnetic Resonance Imaging represents a non-invasive diagnostic modality that exploits the physical properties of nuclear magnetic resonance (NMR). Hydrogen protons within biological tissues align with an external static magnetic field (B0). The application of targeted radiofrequency pulses at the Larmor frequency perturbs proton orientation; upon cessation of the RF excitation, emitted relaxation signals are recorded via spatial gradient encoding, channeled through multi-channel digital spectrometers, and synthesized into multi-planar 2D or volumetric 3D datasets via Fourier transformations and neural-network reconstruction algorithms. MRI achieves high soft-tissue contrast resolution without ionizing radiation, differentiating itself decisively from Computed Tomography (CT) and planar radiography.
1. Segmentation by Magnetic Field Strength
- Ultra-Low-Field (ULF, ~0.064T / 64mT):
Pioneered commercially by Hyperfine with its Swoop system, ULF platforms deploy permanent magnet architectures operating at room temperature. Eliminating the need for liquid helium, chilled-water infrastructure, and radiofrequency-shielded copper rooms, these systems run on standard 100-230V single-phase alternating current (<900W). Paired with deep-learning reconstruction engines (e.g., Optive AI), ULF scanners provide acute neuroimaging capabilities directly within emergency departments, intensive care units (ICUs), and ambulatory neurology practices.
- Low-Field MRI (<1.0T):
Encompasses legacy permanent-magnet systems and contemporary compact mid-field installations (such as 0.55T platforms). Systems operating at 0.55T leverage closed micro-cooling technologies to deliver diagnostic utility in lung parenchymal imaging and intervention, exploiting reduced magnetic susceptibility artifacts around metallic implants and gas-tissue boundaries.
- Mid-to-High Field MRI (1.5T):
The foundational clinical platform across secondary, community, and regional healthcare institutions. Strategic focus within the 1.5T tier has shifted from raw magnet performance toward energy conservation, workflow automation, and zero-quench sustainability. Notable technical milestones include Philips BlueSeal, Siemens Healthineers DryCool, Beijing Wandong Medical 000-platform zero-liquid-helium designs, and United Imaging Silicon Carbide (SiC) gradient architectures.
- High-Field MRI (3.0T):
The primary capital expenditure engine for tertiary academic hospitals, multi-specialty regional centers, and advanced imaging centers. Advanced 3.0T systems incorporate gradient systems reaching 80 to 120 mT/m amplitudes and slew rates of 200 T/m/s. Innovations such as United Imaging uAIFI.LIVE transition 3.0T acquisitions from static cross-sectional imaging to real-time, dynamic organ tracking. The 3.0T tier also serves as the operational baseline for intraoperative surgical suites and radiation therapy (RT) simulation via 75 cm wide-bore designs.
- Ultra-High-Field MRI (5.0T and Above):
Operating at 5.0T, 7.0T, and beyond, this tier redefines the frontiers of neurodegenerative disease characterization, metabolic research, and microstructural delineation. Shanghai United Imaging commercialized the uMR Jupiter 5T as the first clinical whole-body 5.0T platform, resolving historical B1 RF excitation inhomogeneities through an 8-channel volume transmit architecture and 3.5MW gradient power delivery. Academic brain research continues to leverage 7.0T systems (e.g., Siemens MAGNETOM Terra.X, GE SIGNA 7.0T) for sub-millimeter cortical mapping.
2. Segmentation by Magnet Architecture and Cryogenic Technology
- Conventional Liquid Helium Superconducting Magnets:
Rely on niobium-titanium (NbTi) alloy filaments embedded in copper matrices, maintained at superconducting temperatures (-269 degrees Celsius / 4.2 Kelvin) using extensive liquid helium reservoirs (typically 1,500 to 2,500 liters). While offering field stability, these platforms impose structural venting requirements (quench pipes) and expose operators to global helium supply disruptions and price volatility.
- Helium-Free and Sealed Micro-Helium Superconducting Magnets:
Engineered to break dependency on cryogenic logistics. Implementations include closed-loop designs utilizing less than one liter of pre-sealed helium (Siemens DryCool), micro-cooling circuits housing approximately seven liters of sealed helium for life (Philips BlueSeal), and conduction-cooled cryogen-free systems (Wandong Medical 000-platform). These architectures negate quench pipe installations, decrease total gantry weight, and permit scanner deployment in previously inaccessible outpatient and high-rise clinical environments.
- Permanent Magnets:
Constructed from neodymium-iron-boron (NdFeB) or specialized ferrite alloys operating at ambient room temperatures. Requiring zero continuous electrical draw to maintain the magnetic field and completely devoid of cryogenic dependencies, permanent magnets underpin dedicated point-of-care neuroimaging systems and cost-effective open musculoskeletal scanners.
3. Segmentation by Physical Form Factor and Scenario Specialization
- Fixed Whole-Body Diagnostic MRI Suites:
Standard multi-ton gantries permanently anchored within copper-shielded Faraday cages inside hospital radiology departments, configured for universal diagnostic workloads spanning neurology, oncology, musculoskeletal, and body imaging.
- Intraoperative and RT Simulation MRI:
Specialized configurations equipped with 70 to 75 cm open bores, integrated with linear accelerators (MR-Linac), carbon-fiber surgical tables, or ceiling-suspended rail assemblies (e.g., IMRIS VISIUS) that move the magnet over immobilized patients in surgical theaters.
- Point-of-Care and Portable Bedside MRI:
Self-propelled or wheeled mobile platforms designed for navigation into intensive care units, emergency departments, and neonatal wards. These eliminate the clinical risks associated with transporting mechanically ventilated, critically ill patients to fixed radiology facilities.
- Dedicated Extremity and Anatomical Niche Systems:
Compact, low-footprint systems specialized for musculoskeletal limb evaluation (e.g., Esaote O-scan, G-scan) or direct installation within Neonatal Intensive Care Units (Aspect Imaging Embrace, Time Medical NEONA).
DOWNSTREAM APPLICATIONS AND CLINICAL INTEGRATION
1. Human Clinical Healthcare Specialties
- Neurology, Neurosurgery, and Cerebrovascular Health:
Represents the single largest clinical application by scan volume. High-field platforms deliver diffusion-weighted imaging (DWI), functional neuroimaging (fMRI), arterial spin labeling (ASL), and magnetic resonance angiography (MRA) for diagnosing ischemic stroke, intracranial hemorrhages, multiple sclerosis, epilepsy, and neoplastic lesions. Ultra-low-field portable systems deployed in emergency rooms reduce time-to-scan for acute stroke evaluations from a conventional median of 27.7 hours down to 2.5 hours. Furthermore, expanding clinical utilization of disease-modifying therapies for Alzheimer disease requires frequent MRI screening to monitor Amyloid-Related Imaging Abnormalities (ARIA-E and ARIA-H).
- Cardiology and Vascular Diagnostics:
The clinical gold standard for non-invasive quantification of myocardial viability, cardiomyopathies, congenital defects, and valvular kinematics. The transition from multi-breath-hold protocols toward single-heartbeat or free-breathing acquisitions is enabled by Silicon Carbide gradient switching and AI-accelerated compressed sensing platforms (e.g., GE Sonic DL, Philips SmartSpeed, United Imaging uAIFI).
- Oncology, Abdominal, and Pelvic Staging:
Multiparametric MRI (mpMRI) provides soft-tissue differentiation essential for detection, TNM staging, biopsy guidance, and therapeutic response surveillance in prostate, breast, hepatic, and gynecological cancers. The application of whole-body 5.0T scans expands the metabolic assessment of metastatic spread across the torso in unified clinical protocols.
- Critical Care, Emergency Medicine, and Outpatient Practices:
Inpatient transport of hemodynamically unstable ICU patients entails documented adverse-event rates between 26% and 79% (accidental extubation, intravenous line displacement, hemodynamic instability). Point-of-care bedside MRI circumvents these operational hazards, saving an estimated 590 USD per patient in specialized monitoring peripherals, eliminating transport-related ICU nurse staffing diversions, and shortening overall critical-care length of stay. In the United States, updated Intersocietal Accreditation Commission (IAC) guidelines now enable accredited outpatient neurology clinics to perform diagnostic neuro-MRI using portable systems billable under CMS CPT code 70551 without dedicated MRI technologist staffing.
2. Veterinary Medicine and Preclinical Research
- Veterinary Clinical Care:
Increasing adoption in tertiary veterinary hospitals and animal referral centers for neurological assessments (intervertebral disc disease, intracranial neoplasia) and orthopedic pathology evaluations in companion animals and equine patients.
- Preclinical Scientific Research:
Ultra-high-field preclinical scanners operating at 9.4T, 11.7T, and above (e.g., United Imaging uMR 9.4T) provide spatial resolution down to tens of micrometers for in vivo tracking of disease progression, pharmacokinetic profiling, and neuro-circuit mapping in longitudinal rodent models.
SUPPLY CHAIN DYNAMICS AND VALUE MIGRATION
1. Upstream Value Chain: Component Level Vulnerabilities
- Superconducting and Permanent Magnetics:
The primary cost center of the physical gantry. Superconducting architectures demand high-purity niobium-titanium (NbTi) superconducting wire wound under micro-tolerances into multi-coil assemblies. Key manufacturing hubs include specialized foundries like the Siemens Healthineers magnet facility in Oxford, UK, alongside expanding domestic Chinese production clusters. Raw material vulnerabilities center on cryogenic-grade liquid helium supply chains and rare-earth supply volatility, notably neodymium, dysprosium, and terbium used in permanent-magnet assemblies. Export restrictions and geopolitical export quotas introduced on rare-earth oxides in 2025 present continuous cost-structure challenges for permanent-magnet and spectrometer OEMs.
- Gradient Electronics and Semiconductor Transition:
The spatial encoding capability of MRI is governed by the gradient coil and its accompanying gradient power amplifier (GPA). Historically relying on high-power silicon IGBT semiconductors, leading-edge manufacturers are executing a architectural migration toward Silicon Carbide (SiC) MOSFETs. As validated in United Imaging 3.5MW GPA configurations, SiC semiconductors decrease component thermal switching losses by over 60%, elevate duty-cycle ceilings, and slash total patient scan energy consumption by 53% to 65%.
- RF Coils and Spectrometry:
Recent RF engineering pivots away from rigid, heavy coil shells toward ultra-flexible, high-density blanket arrays (e.g., GE AIR Coils, Philips dStream digital transceivers). These integrate miniaturized preamplifiers and analog-to-digital converters directly into the flexible coil substrate, boosting signal-to-noise ratio (SNR) by up to 40% through tighter anatomical proximity and direct digitization.
- AI Acceleration Reconstruction Layers:
Value is migrating rapidly into algorithmic image chains. Deep learning neural networks (GE AIR Recon DL, Siemens Deep Resolve, Philips SmartSpeed, Wandong WDL 1024, United Imaging DeepRecon) operate on raw k-space data prior to Fourier reconstruction. This eliminates truncation artifacts, suppresses thermal noise, and allows scan acceleration factors up to four-fold without diagnostic SNR degradation.
2. Midstream Value Chain: Integration and Assembly
Midstream operations comprise physics simulation, sequence software engineering, mechanical and cryogenic assembly, and regulatory compliance under ISO 13485, FDA 510(k), and EU MDR frameworks. The tier is cleaved between multinational diversified conglomerates managing extensive global service organizations and specialized agile disrupters leveraging modular, software-centric assembly protocols to lower capital overhead.
3. Downstream Value Chain: Shifting Healthcare Economics
Value within the downstream tier is shifting from capital equipment asset ownership toward operational uptime and lifecycle service level agreements (SLAs). Hospital radiology departments facing diagnostic backlogs are restructuring capital deployment toward flexible leases, scan-volume-indexed licensing, and cloud-integrated SaaS packages for automated radiological reporting.
REGIONAL MARKET DYNAMICS
1. North America
North America represents the largest regional market with about 36%-39% market share. Growth dynamics are governed by high-field equipment upgrade cycles (replacing legacy 1.5T units with wide-bore 3.0T systems), extensive expansion of private outpatient ambulatory surgical centers (ASCs), and the clinical integration of portable ULF bedside neuroimaging.
The regulatory and reimbursement framework in the United States is structured heavily around Centers for Medicare and Medicaid Services (CMS) fee schedules. The legislative adoption of the One Big Beautiful Bill Act (2025) catalyzed scrutiny over federal Medicaid and Medicare funding models, accelerating structural shifts toward site-neutral payment policies. Consequently, hospitals are under pressure to decentralize imaging suites away from higher-cost hospital outpatient departments (HOPDs) into freestanding imaging clinics.
Simultaneously, the Intersocietal Accreditation Commission (IAC) update in late 2024 to formally accredit ultra-low-field point-of-care MRI systems has created commercial momentum for systems like Hyperfine Swoop. This regulatory accommodation enables non-hospital neurology practices to capture CMS reimbursement (CPT code 70551) for in-office neuroimaging. Supply chains face scrutiny under US Trade Representative Section 232 investigations, focusing on medical hardware and rare-earth subcomponent resilience.
2. Asia-Pacific
Asia-Pacific constitutes the fastest-growing market globally. Growth is underpinned by demographic aging, massive public hospital expansion programs, and the competitive disruption mounted by Chinese manufacturers.
- China:
The domestic market in China has reached an inflection point. Domestic manufacturer Shanghai United Imaging Healthcare attained the number one position in total new MRI installations in 2025, securing leadership in 1.5T systems, capturing the number two position in 3.0T systems, and leading the ultra-high-field category (>3.0T). Beijing Wandong Medical has expanded domestic footprint via its commercial zero-liquid-helium 1.5T portfolio. Concurrently, traditional Western OEMs experienced volume contraction and margin compression within public hospital bids due to anti-corruption regulatory initiatives and the expansion of centralized Volume-Based Procurement (VBP) to medical capital equipment.
Policy drivers include the 14th Five-Year Plan, the Thousand County Project targeting clinical upgrades for county-level hospitals, and the National Large-Scale Equipment Renewal initiative. Regulatory enforcement by the National Medical Products Administration (NMPA) continues to provide priority review green-channels for innovative, domestically engineered Class III medical devices.
- Japan and Mature APAC:
Japan represents a mature, saturated market with high per-capita scanner density. Procurement is primarily replacement-driven, focusing on compact physical footprints, energy conservation, acoustic noise dampening, and automated patient workflow software to compensate for radiographer labor constraints.
- Emerging APAC:
Markets across India, Indonesia, Vietnam, and Central Asia are expanding due to private healthcare group investments. In India, corporate hospital networks (e.g., Apollo Group) are installing advanced 3.0T and 5.0T systems to capture medical tourism demand, while Hyperfine secured CDSCO approval in late 2025 to commercialize portable ULF neuroimaging. In Indonesia, long-term public procurement programs focus on distributing mid-field and 1.5T platforms across decentralized regional provinces. (Strategic data from Taiwan, China, reveals parallel private clinical replacement cycles focusing on wide-bore high-field platforms.)
3. Europe
Europe remains the second-largest market. Growth across Western European economies (Germany, France, United Kingdom, Nordics) is dominated by the replacement of aging infrastructure, public green procurement mandates, and operational efforts to eliminate liquid helium reliance due to energy costs and sustainability targets.
The European regulatory ecosystem is dominated by the EU Medical Device Regulation (MDR 2017/745). Stricter clinical data requirements, expanded post-market surveillance obligations, and Notified Body administrative backlogs have prolonged approval timelines and increased market authorization costs for advanced imaging devices.
Digital integration is governed by the European Health Data Space (EHDS) regulation, which establishes unified frameworks for the secondary use of clinical health data, alongside the EU Data Act governing access to connected medical hardware telematics. Procurement directives enforce strict environmental compliance under the Corporate Sustainability Due Diligence Directive (CSDDD) and European EcoDesign standards, providing a commercial advantage to helium-free designs (such as Philips BlueSeal and Siemens DryCool).
4. Latin America
The Latin American market is driven by private healthcare sector consolidation, capital investment in diagnostic network hubs, and equipment renewal cycles in Brazil, Mexico, Colombia, Peru, and Argentina. Multinational OEMs face growing competition from Chinese suppliers offering cost-effective 1.5T superconducting platforms.
United Imaging executed first-in-country clinical installations of high-end MR and PET/MR across Mexico, Colombia, and Argentina. Simultaneously, Wandong Medical established joint manufacturing and distribution partnerships in Brazil (e.g., with VMI Group) to circumvent local import tariffs and capture public tender opportunities.
5. Middle East and Africa (MEA)
The MEA region exhibits structural bifurcations. The Gulf Cooperation Council (GCC) states—spearheaded by Saudi Arabia, the United Arab Emirates, Qatar, and Kuwait—maintain capital-intensive sovereign healthcare modernization programs. These nations are procuring premium ultra-high-field systems, wide-bore RT simulation units, and integrated PET/MR scanners to establish oncology and neuro-research hubs (e.g., installation of 5.0T systems in Turkey and advanced PET/MR systems in Morocco).
Conversely, broader African markets face capital expenditure constraints, severe infrastructure deficits, unreliable grid power, and a lack of cryogenic maintenance networks. In these environments, zero-liquid-helium superconducting scanners and battery-operable ULF portable systems present a viable path to introduce diagnostic cross-sectional imaging where conventional 1.5T suites are economically and operationally non-viable.
COMPETITIVE DOSSIERS: KEY MARKET PLAYERS
1. GE HealthCare: GE HealthCare organizes its magnetic resonance portfolio around proprietary deep-learning k-space reconstruction algorithms, flexible coil designs, and high-gradient neuroimaging platforms, while implementing its sealed-helium "Freelium" concept to minimize cryogenic risks.
The flagship research portfolio features the SIGNA 7.0T (equipped with the UltraG gradient system delivering 113 mT/m amplitude and 260 T/m/s slew rate) and the dedicated SIGNA MAGNUS head-only scanner, designed to bypass peripheral nerve stimulation (PNS) thresholds and achieve high-resolution microstructural brain delineation. In the 3.0T clinical tier, the SIGNA Premier integrates the SuperG gradient engine (80 mT/m, 200 T/m/s) with a 146-channel receiver architecture.
The 1.5T segment includes the SIGNA Sprint with Freelium sealed-cryostat technology alongside wide-bore workhorses (SIGNA Artist, SIGNA Champion). GE HealthCare's core competitive moat is anchored by AIR Recon DL, an AI engine reconstructing raw k-space data, coupled with lightweight blanket-like AIR Coils and Sonic DL acceleration software for single-heartbeat cardiovascular evaluations.
2. Siemens Healthineers: Siemens Healthineers pursues a clinical portfolio strategy grounded in patient-adaptive physiological automation (BioMatrix Technology), helium-independent sustainable engineering, and deep-neural-network synthesis across its MAGNETOM family.
The academic segment is anchored by the MAGNETOM Terra and Terra.X 7.0T platforms, the MAGNETOM Cima.X 3.0T (featuring Gemini dual gradients achieving 200 mT/m at 200 T/m/s), and the MAGNETOM Prisma. The core clinical 3.0T and 1.5T lines include the MAGNETOM Vida, Lumina, Sola, and Altea.
A key operational moat is the "DryCool" sustainable platform deployed on the MAGNETOM Flow (a 1.5T scanner operating with a closed circuit of approximately 0.7 liters of liquid helium) and the 0.55T High-V series (MAGNETOM Free.Max and Free.Star). The Free.Max introduces an 80 cm gantry bore, addressing bariatric care while reducing metallic susceptibility artifacts for lung diagnostics. Workflow acceleration is driven by Deep Resolve AI reconstruction and the myExam Companion interactive setup suite.
3. Philips: Philips centers its competitive positioning on fully sealed, zero-boil-off helium-free-for-life magnet technology, end-to-end digital RF transmission architectures, and high-throughput multi-nuclei workflows.
The company's primary hardware moat is its BlueSeal magnet architecture, which encapsulates a micro-cooling loop of seven liters of liquid helium fully sealed for its operational lifespan. This eliminates the necessity for quench pipes, reduces gantry mass by nearly 1,000 kg, and insulates operators from helium refill spikes. The technology is deployed across the MR 5300 and Ingenia Ambition 1.5T scanners.
At the high-field level, the MR 7700 3.0T platform (XP gradients: 65 mT/m, 220 T/m/s) incorporates integrated multi-nuclei clinical imaging (sodium, phosphorus, carbon, fluorine) without manual coil reconfiguration. The imaging chain is augmented by dStream direct-to-digital on-coil electronics, SmartSpeed deep-learning reconstruction (integrated with Compressed SENSE), and contactless VitalEye optical physiological gating.
4. United Imaging Healthcare (UIH):
Shanghai United Imaging Healthcare has emerged as a disruptive competitive force, combining full vertical hardware component integration, ultra-high-field innovation, and AI integration across diagnostic and intraoperative environments.
UIH commercialized the uMR Jupiter 5T, the first whole-body 5.0T superconducting MRI cleared for clinical application. Powered by an 8-channel volume transmit RF architecture and a 3.5MW gradient power amplifier, the platform enables clinical ultra-high-field torso, cardiac, and musculoskeletal diagnostics beyond isolated neurology. The high-field portfolio features the uMR Ultra 3.0T (100 mT/m, 200 T/m/s) debuting the uAIFI.LIVE continuous dynamic imaging platform, the 75 cm ultra-wide-bore uMR Omega for RT simulation and bariatric care, and the uMR 890 dedicated neuro-research platform.
In the 1.5T tier, UIH introduced the uMR 600 / 630 Max, incorporating Silicon Carbide (SiC) semiconductor GPAs that reduce component thermal losses by over 60% and lower patient scan energy consumption by up to 65%. UIH holds leading market installation shares in China across the 1.5T and >3.0T segments.
5. The rest of companies covered in the report including: Canon Medical Systems, Fujifilm Healthcare, Esaote SpA, Beijing Wandong Medical, Hyperfine, Inc., Neusoft Medical Systems, Alltech Medical Systems, Synaptive Medical, Aspect Imaging Ltd., Time Medical Holding, IMRIS Imaging Inc., Xingaoyi Medical Equipment (XGY), and SG Healthcare.
OPPORTUNITIES AND CHALLENGES
1. Strategic Growth Horizons
- Commercial Expansion of Device-as-a-Service (DaaS) and Software Subscriptions:
Hardware commoditization across standard 1.5T platforms is shifting margin structures toward recurring software subscriptions. OEMs are capitalizing on deep-learning k-space reconstruction algorithms, cloud PACS pipelines, and automated sequence prescribing (e.g., Hyperfine PULSE research exchange, Wandong WDL platform). These can be commercialized through recurring software licenses, scan-indexed usage fees, and remote uptime management agreements.
- Alleviation of Critical Care Transport Risks:
Transporting high-acuity patients from ICUs to fixed radiology suites carries documented incident rates of line dislodgement and physiological instability between 26% and 79%, costing an average of 6,255 USD per adverse event. Bedside portable MRI eliminates transport logistics, saves roughly 590 USD per patient in specialized disposable peripherals, and reduces diagnostic wait times by up to 18 hours. This health-economic value proposition creates market room for point-of-care systems in intensive care units and emergency triage bays.
- Democratization in Underserved and Low-Resource Environments:
Conventional 1.5T and 3.0T platforms entail equipment costs between 1.2 and 3.0 million USD, alongside site preparation overhead exceeding 100,000 USD (RF copper cages, 480V three-phase electrical connections, liquid helium handling). Helium-free superconducting architectures and portable permanent-magnet ULF systems resolve these infrastructural dependencies, providing viable clinical access pathways to the estimated 90% of the developing world's population currently lacking MRI availability.
2. Structural Risks and Market Inhibitors
- Critical Upstream Supply Vulnerability and Rare-Earth Controls:
The manufacturing of superconducting and permanent-magnet MRI hardware is exposed to volatile upstream materials supply chains. Superconducting systems depend on niobium-titanium alloy filaments and liquid helium supplies, which have historically experienced supply contractions and pricing volatility. Permanent-magnet designs depend on neodymium-iron-boron (NdFeB) blocks, dysprosium, and terbium. Escalating geopolitical tensions and rare-earth export controls instituted in 2025 introduce supply chain constraints, input cost spikes, and manufacturing lead-time delays for system integrators.
- Geopolitical Fragmentation, Tariffs, and Local Content Mandates:
Cross-border medical technology trade is challenged by rising protectionism. This includes US Trade Representative Section 232 investigations, regional local-content requirements, and the expansion of domestic bidding preferences within public healthcare frameworks. These dynamics compress multinational gross margins and accelerate the localization of assembly facilities (such as partnerships between Chinese OEMs and regional manufacturing partners in Latin America).
- Regulatory Complexity and Notified Body Delays Under EU MDR:
The enforcement of the EU Medical Device Regulation (MDR 2017/745) continues to strain OEM product roadmaps. Stringent requirements for extensive clinical investigation data, continuous post-market surveillance, and administrative backlogs across European Notified Bodies have prolonged clearance timelines and inflated regulatory compliance costs, delaying the clinical roll-out of next-generation imaging systems across Europe.
- Acute Shortage of Specialized Radiologists and MR Technologists:
A persistent global deficit of subspecialty-trained radiologists and clinical MR technologists constrains daily scanner throughput and exacerbates backlogs. Consequently, hospital purchasing committees prioritize systems offering deep-learning-driven auto-positioning, zero-click sequence selection, and automated motion correction to maintain procedural volume despite clinical labor shortages.
1.1 Executive Summary and 2026 Market Baseline 1
1.2 Scope and Taxonomy of Medical Magnetic Resonance Imaging (MRI) Systems 2
1.3 Research Methodology, Data Triangulation and Statistical Modeling 3
1.4 Secondary and Primary Information Sources 4
1.5 Definitional Assumptions and Currency Conversion Parameters 5
1.6 List of Industry Abbreviations and Standardized Terminologies 6
Chapter 2 Global Medical MRI System Market Overview and Ecosystem Dynamics 7
2.1 Macroeconomic Environment and Healthcare Capital Expenditure Cycles 7
2.2 Global Market Volume (Units) Trajectory (2021-2031) 8
2.3 Global Market Revenue (USD Million) Trajectory (2021-2031) 9
2.4 Total Installed Base and Replacement Cycle Dynamics 10
2.5 Technological Evolution: Transition from High Consumption Cryogenics to Sustainable Infrastructure 11
2.6 Artificial Intelligence Integration: Deep Learning Reconstruction and Accelerated Acquisition 12
2.7 Geopolitical Reconfiguration of Medical Device Manufacturing Hubs 13
Chapter 3 Upstream Supply Chain, Component Architecture and Cryogenic Sourcing 14
3.1 Upstream Value Chain Architecture and Cost Breakdown 14
3.2 Superconducting Wire and Cable Engineering: NbTi, MgB2 and High-Temperature Superconductors (HTS) 15
3.3 Global Liquid Helium Supply Chain Volatility, Strategic Sourcing and Price Elasticity 16
3.4 Radiofrequency (RF) Coils, Transmit/Receive Chains and High-Density Multi-Channel Arrays 17
3.5 Gradient Amplifiers, Precision Subsystems and Acoustic Noise Attenuation Technologies 18
3.6 Advanced Digital Spectrometers, Console Software and Image Reconstruction Processing Units 19
3.7 Supply Chain Vulnerabilities, Dual-Sourcing Strategies and Production Lead-Time Analysis 20
Chapter 4 Global Medical MRI System Market by Magnetic Field Strength 21
4.1 Segment Overview and Structural Market Transition by Field Strength 21
4.2 Ultra-Low-Field (ULF) MRI (<0.1T to 0.2T) Market Volume (Units) and Revenue (USD Million) (2021-2031) 22
4.3 Low-Field MRI (0.2T to 0.5T) Market Volume (Units) and Revenue (USD Million) (2021-2031) 23
4.4 Mid-to-High Field MRI (1.5T) Market Volume (Units) and Revenue (USD Million) (2021-2031) 24
4.5 High-Field MRI (3.0T) Market Volume (Units) and Revenue (USD Million) (2021-2031) 25
4.6 Ultra-High-Field (UHF) MRI (7.0T and Above) Market Volume (Units) and Revenue (USD Million) (2021-2031) 26
4.7 Magnetic Field Strength Migration Analysis and Clinical Field-Strength Selection Matrix 27
Chapter 5 Global Medical MRI System Market by Magnet Architecture and Cryogenic Cooling Technology 28
5.1 Segment Overview and Thermodynamic Engineering Paradigms 28
5.2 Liquid Helium Superconducting MRI Systems Market Volume and Revenue (2021-2031) 29
5.3 Helium-Free / Sealed Micro-Helium Superconducting MRI Systems Market Volume and Revenue (2021-2031) 30
5.4 Permanent Magnet MRI Systems Market Volume and Revenue (2021-2031) 31
5.5 Total Cost of Ownership (TCO) Comparison: Cryogen Replenishment vs. Dry Conduction Systems 32
5.6 Infrastructure, Siting and Cryogenic Safety Exhaust Requirements 33
Chapter 6 Global Medical MRI System Market by Physical Form Factor and Scenario Specialization 34
6.1 Segment Overview and Clinical Siting Segmentation 34
6.2 Fixed Whole-Body Diagnostic MRI Systems Market Volume and Revenue (2021-2031) 35
6.3 Intraoperative (iMRI) and Radiation Therapy (RT) Simulation MRI Systems Market Volume and Revenue (2021-2031) 36
6.4 Point-of-Care (PoC) and Portable Bedside MRI Systems Market Volume and Revenue (2021-2031) 37
6.5 Dedicated Extremity MRI Systems Market Volume and Revenue (2021-2031) 38
6.6 Portability Hurdles: Electromagnetic Shielding, Weight Constraints and Dynamic Spatial Calibration 39
6.7 Workflow Efficiency Metrics and Patient Throughput Across Form Factors 40
Chapter 7 Global Medical MRI System Market by Downstream Application Segment 41
7.1 Downstream Demand Architecture and End-User Clinical Allocation 41
7.2 Human Clinical Healthcare Market Volume (Units) and Revenue (USD Million) (2021-2031) 42
7.2.1 Neuroimaging and Spine Assessment 43
7.2.2 Cardiovascular and Thoracic Diagnostics 43
7.2.3 Musculoskeletal and Orthopedic Imaging 44
7.2.4 Abdominal, Pelvic and Oncology Applications 44
7.3 Veterinary and Preclinical Animal MRI Systems Market Volume and Revenue (2021-2031) 45
7.3.1 Veterinary Specialty Hospitals and Small Animal Clinical Practice 45
7.3.2 Preclinical Translational Research and Pharmaceutical Development 46
Chapter 8 Global Trade Dynamics, Regulatory Frameworks and Cross-Border Logistics 47
8.1 Global Import and Export Flows for Assembled MRI Systems and Cores 47
8.2 Primary Exporter Nations: Manufacturing Capacities, Tariffs and Sourcing Balances 48
8.3 Primary Importer Nations: Regulatory Barriers, Cleared Portfolios and Custom Duties 49
8.4 Global Regulatory Pathways: FDA 510(k)/PMA, EU MDR Classification, and NMPA Approvals 50
8.5 Hazardous Material Logistics: Transport of Pressurized Cryogens and Quench Mitigation Protocols 51
8.6 Heavy Equipment Freight Logistics, Siting Modularization and Specialized Rigging Dynamics 52
Chapter 9 Regional Production Dynamics and Localized Consumption Hubs 53
9.1 North America Medical MRI System Market Analysis 53
9.1.1 United States: Production Capacities, Tariff Regimes and Demand Trajectory 54
9.1.2 Canada: Public Healthcare Procurement Cycles and Clinical Installation Rates 56
9.2 Europe Medical MRI System Market Analysis 57
9.2.1 Germany: Precision Manufacturing Center, Sourcing Networks and Domestic Demand 58
9.2.2 France: Public Hospital Purchasing Groups and Modernization Directives 59
9.2.3 United Kingdom: Diagnostic Scans Backlog and Community Diagnostic Centre Investments 60
9.2.4 Italy: Regional Healthcare Sourcing and Public-Private Diagnostic Dynamics 61
9.2.5 Spain: National Renewal Programs and Outpatient Diagnostic Center Siting 62
9.2.6 Netherlands & Rest of Europe Market 63
9.3 Asia-Pacific Medical MRI System Market Analysis 64
9.3.1 China: Domestic Manufacturing Acceleration, Tiered Procurement and Replacement Market 65
9.3.2 Japan: Ultra-High Density Installed Base, Siting Optimization and Replacement Dynamics 67
9.3.3 India & Southeast Asia: Private Diagnostic Chain Expansion, Import Dependency and Market Tiering 68
9.3.4 South Korea: High Field Density, Reimbursement Policies and Innovation Adoption 69
9.3.5 Australia: Public-Private Facility Subsidies and Decentralized Imaging Networks 70
9.4 Latin America Medical MRI System Market Analysis 71
9.4.1 Brazil: Import Dynamics, Infrastructure Bottlenecks and Private Sector Sourcing 71
9.4.2 Mexico: Border Manufacturing Synergies, Private Hospital Systems and Public Tenders 72
9.5 Middle East and Africa Medical MRI System Market Analysis 73
9.5.1 Saudi Arabia: Healthcare Modernization Infrastructure and Megaproject Procurement 73
9.5.2 United Arab Emirates: Medical Tourism Initiatives and Specialized Hospital Siting 74
9.5.3 South Africa: Dual-Tier Healthcare Sourcing Patterns and Specialized Veterinary Hubs 75
Chapter 10 Global Competitive Structure and Vendor Benchmarking 76
10.1 Industry Concentration Ratios (CR4, CR8) and Herfindahl-Hirschman Index (HHI) 76
10.2 Global Revenue Market Share Matrix by Tier (2021-2026) 77
10.3 Pricing Architecture and Margin Stratification by Field Strength and Modality 78
10.4 Strategic Alliances, Distribution Partnerships and Mergers and Acquisitions 79
Chapter 11 Corporate Intelligence: Global Diversified Imaging Conglomerates 80
11.1 GE HealthCare 80
11.1.1 Corporate Overview and Strategic Healthcare Positioning 80
11.1.2 Product Matrix and Technical Differentiation (SIGNA Platforms) 81
11.1.3 Operational Metrics: Sales Volume, Price, Cost and Gross Margin Analysis 82
11.1.4 Global Geographic Footprint, Production Network and R&D Allocation 83
11.2 Siemens Healthineers 84
11.2.1 Corporate Overview and Diagnostic Imaging Portfolio 84
11.2.2 Product Matrix and Technical Differentiation (MAGNETOM Platforms) 85
11.2.3 Operational Metrics: Sales Volume, Price, Cost and Gross Margin Analysis 86
11.2.4 Helium-Independent Architecture Deployment and Go-to-Market Execution 87
11.3 Philips 88
11.3.1 Corporate Overview and Image Guided Therapy Synergy 88
11.3.2 Product Matrix and Technical Differentiation (BlueSeal Sealed Magnet Systems) 89
11.3.3 Operational Metrics: Sales Volume, Price, Cost and Gross Margin Analysis 90
11.3.4 Sustainability Framework and Global Channel Management 91
11.4 Fujifilm 92
11.4.1 Corporate Overview and Healthcare Solutions Division Trajectory 92
11.4.2 Product Matrix and Technical Differentiation (Oasis and Echelon Platforms) 93
11.4.3 Operational Metrics: Sales Volume, Price, Cost and Gross Margin Analysis 94
11.4.4 Open-MRI Siting Strategy and Mid-Tier Hospital Penetration 95
11.5 Canon Medical Systems 96
11.5.1 Corporate Overview and Medical Business Sector Alignment 96
11.5.2 Product Matrix and Technical Differentiation (Vantage Platforms and Pianissimo Noise Reduction) 97
11.5.3 Operational Metrics: Sales Volume, Price, Cost and Gross Margin Analysis 98
11.5.4 Advanced Deep Learning Reconstruction Strategies and Global Account Expansion 99
Chapter 12 Corporate Intelligence: Fast-Growing Global Innovators and Regional Disruptors 100
12.1 United Imaging Healthcare 100
12.1.1 Corporate Overview and Vertical Integration Capabilities 100
12.1.2 Product Matrix and Technical Differentiation (uMR Platforms and Ultra-High Field 5T/9.4T) 101
12.1.3 Operational Metrics: Sales Volume, Price, Cost and Gross Margin Analysis 102
12.1.4 International Commercial Expansion and Core Component Sourcing Independence 103
12.2 Wandong Medical 104
12.2.1 Corporate Overview and Midea Group Strategic Integration 104
12.2.2 Product Matrix and Technical Differentiation (Permanent and Superconducting Portfolio) 105
12.2.3 Operational Metrics: Sales Volume, Price, Cost and Gross Margin Analysis 106
12.2.4 Domestic Tiered Hospital Market Penetration and Emerging Market Export Programs 107
12.3 Hyperfine Inc. 108
12.3.1 Corporate Overview and Disruptive Bedside Imaging Model 108
12.3.2 Product Matrix and Technical Differentiation (Swoop Portable Point-of-Care MRI) 109
12.3.3 Operational Metrics: Sales Volume, Price, Cost and Gross Margin Analysis 110
12.3.4 Point-of-Care Adoption Hurdles, Emergency Medicine Penetration and Regulatory Clearances 111
12.4 IMRIS Imaging Inc. 112
12.4.1 Corporate Overview and Hybrid Operating Suite Solutions 112
12.4.2 Product Matrix and Technical Differentiation (Ceiling-Mounted Movable Intraoperative MRI) 113
12.4.3 Operational Metrics: Sales Volume, Price, Cost and Gross Margin Analysis 114
12.4.4 Surgical Suite Integration, Hospital Specialty Siting and Service Contracts 115
12.5 Xingaoyi Medical Equipment Co Ltd. 116
12.5.1 Corporate Overview and Permanent Magnet Sourcing Fundamentals 116
12.5.2 Product Matrix and Technical Differentiation (Low-Field Permanent and Mid-Field Superconducting) 117
12.5.3 Operational Metrics: Sales Volume, Price, Cost and Gross Margin Analysis 118
12.5.4 Value-Segment Strategy, Domestic Tendering and Regional Exports 119
Chapter 13 Corporate Intelligence: Specialized Clinical, Portable and Extremity Solutions 120
13.1 Neusoft Medical Systems 120
13.1.1 Corporate Overview and Global Healthcare Infrastructure Positioning 120
13.1.2 Product Matrix and Technical Differentiation (NeuMR Series) 121
13.1.3 Operational Metrics: Sales Volume, Price, Cost and Gross Margin Analysis 122
13.1.4 Emerging Market Direct Tendering and Overseas Channel Partnerships 123
13.2 Alltech Medical Systems 124
13.2.1 Corporate Overview and Superconducting Core Competence 124
13.2.2 Product Matrix and Technical Differentiation (EchoStar Series) 125
13.2.3 Operational Metrics: Sales Volume, Price, Cost and Gross Margin Analysis 126
13.2.4 Upstream Superconducting Coil Fabrication and Commercial Channel Integration 127
13.3 Esaote SpA 128
13.3.1 Corporate Overview and European Medical Device Specialization 128
13.3.2 Product Matrix and Technical Differentiation (Dedicated Musculoskeletal and Weight-Bearing MRI) 129
13.3.3 Operational Metrics: Sales Volume, Price, Cost and Gross Margin Analysis 130
13.3.4 Outpatient Orthopedic Center Targeting and Low-Siting-Impact Commercialization 131
13.4 Synaptive Medical 132
13.4.1 Corporate Overview and Surgical Robotics Synergy 132
13.4.2 Product Matrix and Technical Differentiation (Evry Point-of-Care Head MRI) 133
13.4.3 Operational Metrics: Sales Volume, Price, Cost and Gross Margin Analysis 134
13.4.4 Integrated Neurosurgical Suite Integration and North American Siting 135
13.5 Aspect Imaging Ltd 136
13.5.1 Corporate Overview and Compact Magnet Sourcing Architecture 136
13.5.2 Product Matrix and Technical Differentiation (Embrace Neonatal MRI and M-Series Preclinical) 137
13.5.3 Operational Metrics: Sales Volume, Price, Cost and Gross Margin Analysis 138
13.5.4 Neonatal Intensive Care Unit (NICU) Siting and Preclinical Pharma Research Capture 139
13.6 Time Medical Holding 140
13.6.1 Corporate Overview and High-Temperature Superconductor Innovation 140
13.6.2 Product Matrix and Technical Differentiation (Emma Neonatal, Mona Dedicated, and Whole-Body MRI) 141
13.6.3 Operational Metrics: Sales Volume, Price, Cost and Gross Margin Analysis 142
13.6.4 Global Specialized Imaging Centers and Developing Economy Siting Strategy 143
13.7 SG Healthcare 144
13.7.1 Corporate Overview and South Korean Diagnostic System Architecture 144
13.7.2 Product Matrix and Technical Differentiation (i-Ecomat and Superconducting Portfolios) 145
13.7.3 Operational Metrics: Sales Volume, Price, Cost and Gross Margin Analysis 146
13.7.4 Regional Distribution Networks across Asia-Pacific and Latin America 147
Table 2 Bill of Materials (BOM) Breakdown for Standard 1.5T Superconducting MRI System 14
Table 3 Global Medical MRI System Market Volume (Units) by Field Strength, 2021-2031 21
Table 4 Global Medical MRI System Market Revenue (USD Million) by Field Strength, 2021-2031 21
Table 5 Ultra-Low-Field MRI Market Volume and Value by Region, 2021-2031 22
Table 6 Low-Field MRI Market Volume and Value by Region, 2021-2031 23
Table 7 Mid-to-High Field (1.5T) MRI Market Volume and Value by Region, 2021-2031 24
Table 8 High-Field (3.0T) MRI Market Volume and Value by Region, 2021-2031 25
Table 9 Ultra-High-Field (7.0T+) MRI Market Volume and Value by Region, 2021-2031 26
Table 10 Global Medical MRI System Market Volume (Units) by Magnet Architecture, 2021-2031 28
Table 11 Global Medical MRI System Market Revenue (USD Million) by Magnet Architecture, 2021-2031 28
Table 12 Liquid Helium Superconducting MRI Market Volume and Value by Region, 2021-2031 29
Table 13 Helium-Free / Sealed Micro-Helium MRI Market Volume and Value by Region, 2021-2031 30
Table 14 Permanent Magnet MRI Market Volume and Value by Region, 2021-2031 31
Table 15 Global Medical MRI System Market Volume (Units) by Form Factor, 2021-2031 34
Table 16 Global Medical MRI System Market Revenue (USD Million) by Form Factor, 2021-2031 34
Table 17 Fixed Whole-Body Diagnostic MRI Market Volume and Value by Region, 2021-2031 35
Table 18 Intraoperative and RT Simulation MRI Market Volume and Value by Region, 2021-2031 36
Table 19 Point-of-Care and Portable Bedside MRI Market Volume and Value by Region, 2021-2031 37
Table 20 Dedicated Extremity MRI Market Volume and Value by Region, 2021-2031 38
Table 21 Global Medical MRI System Market Volume (Units) by Application, 2021-2031 41
Table 22 Global Medical MRI System Market Revenue (USD Million) by Application, 2021-2031 41
Table 23 Human Clinical Healthcare MRI Market Breakdown by Clinical Department, 2021-2031 42
Table 24 Veterinary and Preclinical Animal MRI Market Breakdown by End-User, 2021-2031 45
Table 25 Top 10 Cross-Border MRI System Exporting Nations: Volume, Value and Share, 2025-2026 48
Table 26 Top 10 Cross-Border MRI System Importing Nations: Volume, Value and Share, 2025-2026 49
Table 27 North America Medical MRI System Market Volume and Revenue by Country, 2021-2031 53
Table 28 United States Medical MRI System Market by Field Strength, 2021-2031 55
Table 29 Canada Medical MRI System Market by Field Strength, 2021-2031 56
Table 30 Europe Medical MRI System Market Volume and Revenue by Country, 2021-2031 57
Table 31 Germany Medical MRI System Market by Field Strength, 2021-2031 58
Table 32 France Medical MRI System Market by Field Strength, 2021-2031 59
Table 33 United Kingdom Medical MRI System Market by Field Strength, 2021-2031 60
Table 34 Italy Medical MRI System Market by Field Strength, 2021-2031 61
Table 35 Spain Medical MRI System Market by Field Strength, 2021-2031 62
Table 36 Netherlands Medical MRI System Market by Field Strength, 2021-2031 63
Table 37 Asia-Pacific Medical MRI System Market Volume and Revenue by Country, 2021-2031 64
Table 38 China Medical MRI System Market by Field Strength, 2021-2031 66
Table 39 Japan Medical MRI System Market by Field Strength, 2021-2031 67
Table 40 India Medical MRI System Market by Field Strength, 2021-2031 68
Table 41 South Korea Medical MRI System Market by Field Strength, 2021-2031 69
Table 42 Australia Medical MRI System Market by Field Strength, 2021-2031 70
Table 43 Latin America Medical MRI System Market Volume and Revenue by Country, 2021-2031 71
Table 44 Brazil Medical MRI System Market by Field Strength, 2021-2031 71
Table 45 Mexico Medical MRI System Market by Field Strength, 2021-2031 72
Table 46 Middle East and Africa Medical MRI System Market Volume and Revenue by Country, 2021-2031 73
Table 47 Saudi Arabia Medical MRI System Market by Field Strength, 2021-2031 74
Table 48 United Arab Emirates Medical MRI System Market by Field Strength, 2021-2031 74
Table 49 South Africa Medical MRI System Market by Field Strength, 2021-2031 75
Table 50 Global Leading Vendors Medical MRI System Revenue Market Share (%), 2021-2026 77
Table 51 Average Selling Price (ASP) Benchmark by Field Strength and Architectural Class (USD Thousand) 78
Table 52 GE HealthCare Medical MRI System Sales, Price, Cost and Gross Profit Margin (2021-2026) 82
Table 53 Siemens Healthineers Medical MRI System Sales, Price, Cost and Gross Profit Margin (2021-2026) 86
Table 54 Philips Medical MRI System Sales, Price, Cost and Gross Profit Margin (2021-2026) 90
Table 55 Fujifilm Medical MRI System Sales, Price, Cost and Gross Profit Margin (2021-2026) 94
Table 56 Canon Medical Systems Medical MRI System Sales, Price, Cost and Gross Profit Margin (2021-2026) 98
Table 57 United Imaging Healthcare Medical MRI System Sales, Price, Cost and Gross Profit Margin (2021-2026) 102
Table 58 Wandong Medical Medical MRI System Sales, Price, Cost and Gross Profit Margin (2021-2026) 106
Table 59 Hyperfine Inc. Medical MRI System Sales, Price, Cost and Gross Profit Margin (2021-2026) 110
Table 60 IMRIS Imaging Inc. Medical MRI System Sales, Price, Cost and Gross Profit Margin (2021-2026) 114
Table 61 Xingaoyi Medical Equipment Co Ltd. Medical MRI System Sales, Price, Cost and Gross Profit Margin (2021-2026) 118
Table 62 Neusoft Medical Systems Medical MRI System Sales, Price, Cost and Gross Profit Margin (2021-2026) 122
Table 63 Alltech Medical Systems Medical MRI System Sales, Price, Cost and Gross Profit Margin (2021-2026) 126
Table 64 Esaote SpA Medical MRI System Sales, Price, Cost and Gross Profit Margin (2021-2026) 130
Table 65 Synaptive Medical Medical MRI System Sales, Price, Cost and Gross Profit Margin (2021-2026) 134
Table 66 Aspect Imaging Ltd Medical MRI System Sales, Price, Cost and Gross Profit Margin (2021-2026) 138
Table 67 Time Medical Holding Medical MRI System Sales, Price, Cost and Gross Profit Margin (2021-2026) 142
Table 68 SG Healthcare Medical MRI System Sales, Price, Cost and Gross Profit Margin (2021-2026) 146
Figure 1 Research Architecture and Bottom-Up Industry Sizing Methodology 3
Figure 2 Global Medical MRI System Market Volume Growth Trajectory (Units), 2021-2031 8
Figure 3 Global Medical MRI System Market Revenue Growth Trajectory (USD Million), 2021-2031 9
Figure 4 Global MRI Systems Value Chain and Component Margin Distribution 15
Figure 5 Raw Material Sourcing Dependency Matrix: Liquid Helium and Superconductors 16
Figure 6 Global Medical MRI Market Volume Share (%) by Field Strength, 2021 vs. 2026 vs. 2031 22
Figure 7 High-Field (3.0T) MRI Market Volume Expansion and Installation Trajectory, 2021-2031 25
Figure 8 Global Medical MRI Market Value Share (%) by Magnet Architecture, 2021-2031 29
Figure 9 Helium-Free / Sealed Micro-Helium Systems Adoption Penetration Curve, 2021-2031 30
Figure 10 Global Medical MRI Systems Revenue Share (%) by Form Factor, 2026 35
Figure 11 Point-of-Care Bedside Systems Shipment Forecast (Units), 2021-2031 37
Figure 12 Clinical Downstream Application Value Distribution, 2026 42
Figure 13 Veterinary and Preclinical Animal MRI System Demand Growth Trend, 2021-2031 46
Figure 14 Global Trade Hub Mapping: Dominant Export Routes and Assembly Sites, 2026 47
Figure 15 Regional Market Share Distribution (%) of Global MRI Revenue, 2021 vs. 2026 vs. 2031 53
Figure 16 United States Medical MRI Systems Market Revenue Trajectory (USD Million), 2021-2031 54
Figure 17 China Medical MRI Domestic Shipment and Localization Rate (%), 2021-2031 65
Figure 18 Global Medical MRI Concentration Curves: Tier-1 Dominance vs. Specialist Contenders 76
Figure 19 Global Medical MRI Market Revenue Breakdown by Major Manufacturer (%), 2026 77
Figure 20 GE HealthCare Medical MRI System Market Share (2021-2026) 83
Figure 21 Siemens Healthineers Medical MRI System Market Share (2021-2026) 87
Figure 22 Philips Medical MRI System Market Share (2021-2026) 91
Figure 23 Fujifilm Medical MRI System Market Share (2021-2026) 95
Figure 24 Canon Medical Systems Medical MRI System Market Share (2021-2026) 99
Figure 25 United Imaging Healthcare Medical MRI System Market Share (2021-2026) 103
Figure 26 Wandong Medical Medical MRI System Market Share (2021-2026) 107
Figure 27 Hyperfine Inc. Medical MRI System Market Share (2021-2026) 111
Figure 28 IMRIS Imaging Inc. Medical MRI System Market Share (2021-2026) 115
Figure 29 Xingaoyi Medical Equipment Co Ltd. Medical MRI System Market Share (2021-2026) 119
Figure 30 Neusoft Medical Systems Medical MRI System Market Share (2021-2026) 123
Figure 31 Alltech Medical Systems Medical MRI System Market Share (2021-2026) 127
Figure 32 Esaote SpA Medical MRI System Market Share (2021-2026) 131
Figure 33 Synaptive Medical Medical MRI System Market Share (2021-2026) 135
Figure 34 Aspect Imaging Ltd Medical MRI System Market Share (2021-2026) 139
Figure 35 Time Medical Holding Medical MRI System Market Share (2021-2026) 143
Figure 36 SG Healthcare Medical MRI System Market Share (2021-2026) 147
Research Methodology
- Market Estimated Methodology:
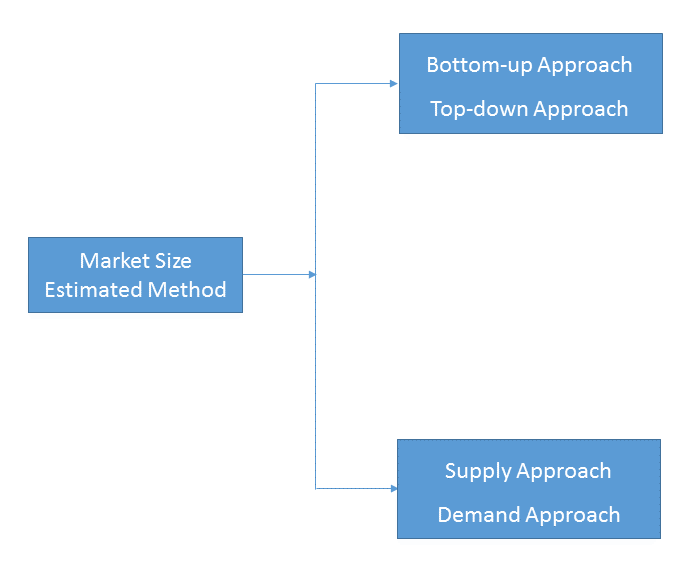
Bottom-up & top-down approach, supply & demand approach are the most important method which is used by HDIN Research to estimate the market size.
1)Top-down & Bottom-up Approach
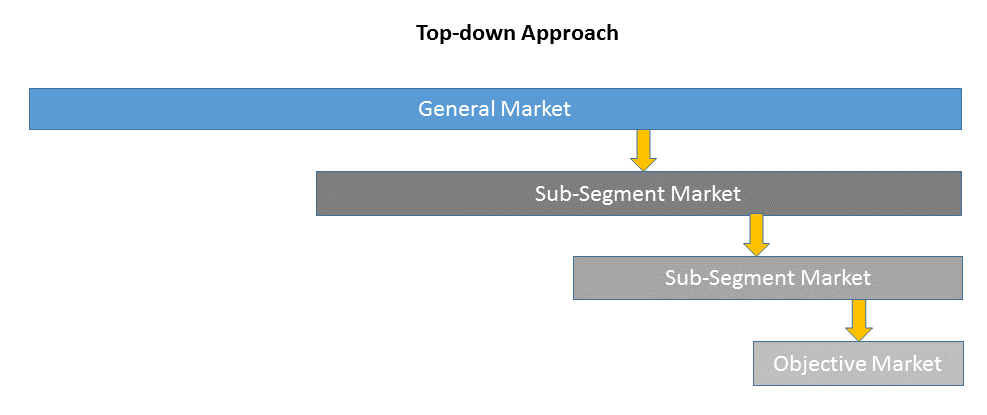
Top-down approach uses a general market size figure and determines the percentage that the objective market represents.
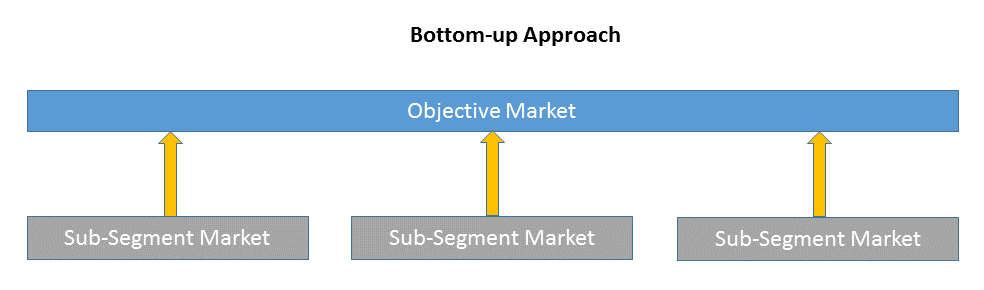
Bottom-up approach size the objective market by collecting the sub-segment information.
2)Supply & Demand Approach
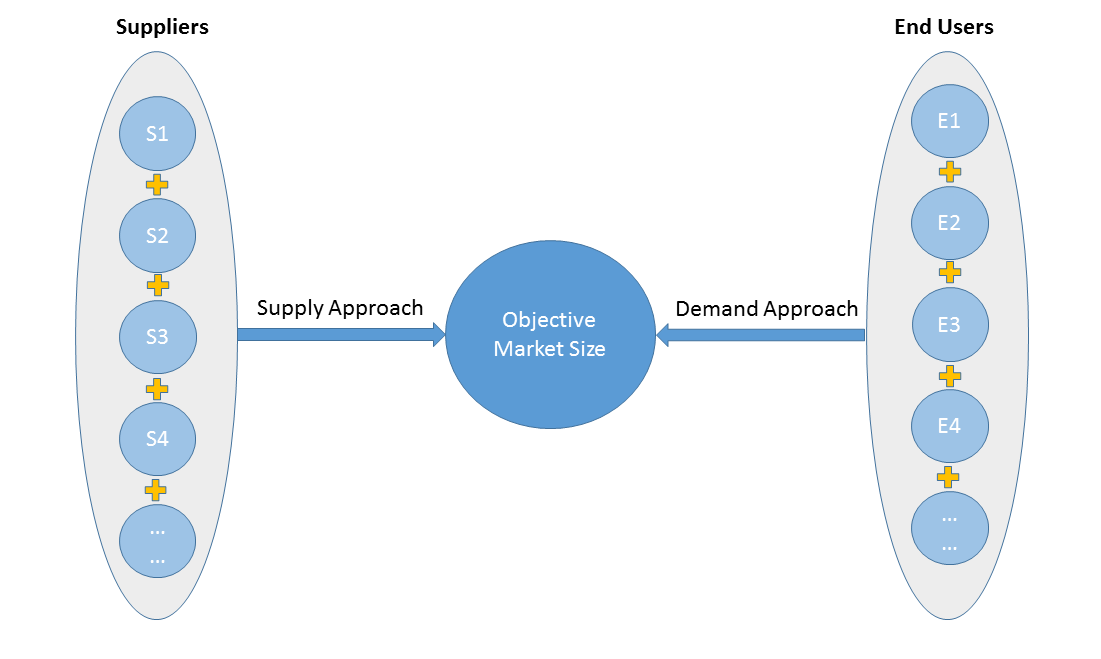
Supply approach is based on assessments of the size of each competitor supplying the objective market.
Demand approach combine end-user data within a market to estimate the objective market size. It is sometimes referred to as bottom-up approach.
- Forecasting Methodology
- Numerous factors impacting the market trend are considered for forecast model:
- New technology and application in the future;
- New project planned/under contraction;
- Global and regional underlying economic growth;
- Threatens of substitute products;
- Industry expert opinion;
- Policy and Society implication.
- Analysis Tools
1)PEST Analysis
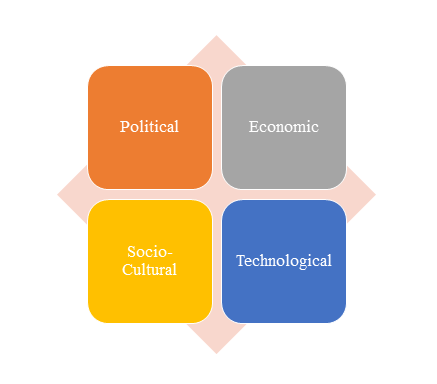
PEST Analysis is a simple and widely used tool that helps our client analyze the Political, Economic, Socio-Cultural, and Technological changes in their business environment.
- Benefits of a PEST analysis:
- It helps you to spot business opportunities, and it gives you advanced warning of significant threats.
- It reveals the direction of change within your business environment. This helps you shape what you’re doing, so that you work with change, rather than against it.
- It helps you avoid starting projects that are likely to fail, for reasons beyond your control.
- It can help you break free of unconscious assumptions when you enter a new country, region, or market; because it helps you develop an objective view of this new environment.
2)Porter’s Five Force Model Analysis
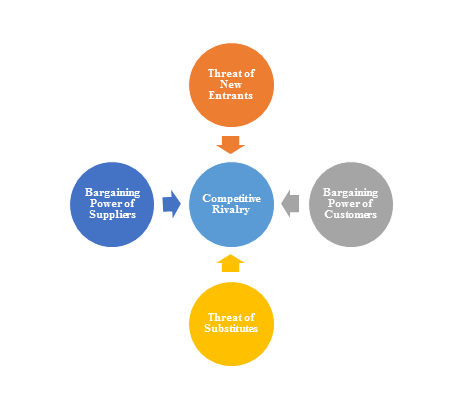
The Porter’s Five Force Model is a tool that can be used to analyze the opportunities and overall competitive advantage. The five forces that can assist in determining the competitive intensity and potential attractiveness within a specific area.
- Threat of New Entrants: Profitable industries that yield high returns will attract new firms.
- Threat of Substitutes: A substitute product uses a different technology to try to solve the same economic need.
- Bargaining Power of Customers: the ability of customers to put the firm under pressure, which also affects the customer's sensitivity to price changes.
- Bargaining Power of Suppliers: Suppliers of raw materials, components, labor, and services (such as expertise) to the firm can be a source of power over the firm when there are few substitutes.
- Competitive Rivalry: For most industries the intensity of competitive rivalry is the major determinant of the competitiveness of the industry.
3)Value Chain Analysis
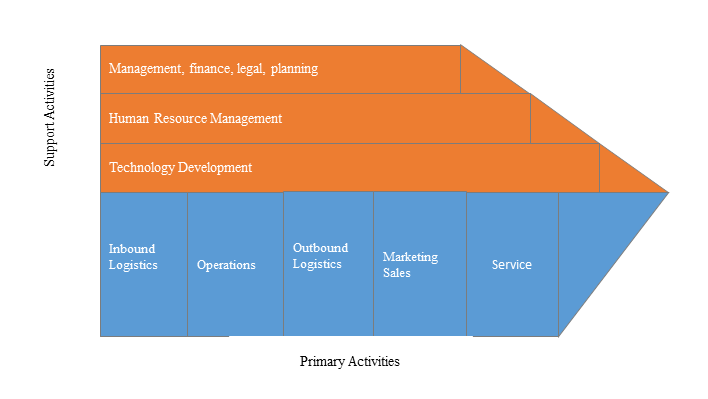
Value chain analysis is a tool to identify activities, within and around the firm and relating these activities to an assessment of competitive strength. Value chain can be analyzed by primary activities and supportive activities. Primary activities include: inbound logistics, operations, outbound logistics, marketing & sales, service. Support activities include: technology development, human resource management, management, finance, legal, planning.
4)SWOT Analysis
SWOT analysis is a tool used to evaluate a company's competitive position by identifying its strengths, weaknesses, opportunities and threats. The strengths and weakness is the inner factor; the opportunities and threats are the external factor. By analyzing the inner and external factors, the analysis can provide the detail information of the position of a player and the characteristics of the industry.
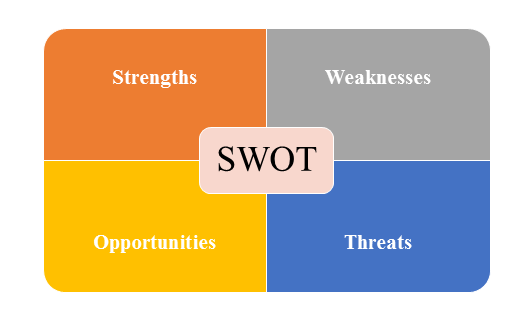
- Strengths describe what the player excels at and separates it from the competition
- Weaknesses stop the player from performing at its optimum level.
- Opportunities refer to favorable external factors that the player can use to give it a competitive advantage.
- Threats refer to factors that have the potential to harm the player.
- Data Sources
| Primary Sources | Secondary Sources |
|---|---|
| Face to face/Phone Interviews with market participants, such as: Manufactures; Distributors; End-users; Experts. Online Survey |
Government/International Organization Data: Annual Report/Presentation/Fact Book Internet Source Information Industry Association Data Free/Purchased Database Market Research Report Book/Journal/News |