Digital Radiography (DR) Market Report 2026-2031
- Single User License (1 Users) $ 3,500
- Team License (2~5 Users) $ 4,500
- Corporate License (>5 Users) $ 5,500
The physical imaging chain has transitioned permanently from legacy computed radiography (CR) and analog film to direct and indirect conversion digital flat-panel detectors (FPDs). This transition is anchored by advances in Cesium Iodide (CsI) scintillators paired with amorphous silicon (a-Si), Indium Gallium Zinc Oxide (IGZO) photodiode arrays, and complementary metal-oxide-semiconductor (CMOS) sensor architectures. The clinical imperative is stark: transporting critically ill intensive care unit (ICU) patients requiring ventilator support to central radiology suites carries adverse clinical event rates between 26% and 79%, incurring an average downstream complication cost of 6,255 USD per incident. Concurrently, capital procurement frameworks are polarizing. High-income health networks are prioritizing software-differentiated platforms featuring embedded artificial intelligence (AI) triage, automated workflow orchestration, and zero-click mechanical interfaces. Emerging health systems and secondary-care institutions, particularly within China, India, and Latin America, are leveraging competitive, localized manufacturing ecosystems to modernize primary screening infrastructure under strict budget caps.
The global digital radiography (DR) market size is valued at an estimated 4.5 to 5.5 billion USD in 2026, and the global DR market is projected to expand at a compound annual growth rate (CAGR) of 3.9% to 5.5% through 2031.
System Architecture and Technological Classification
Digital radiography systems are categorized across two structural vectors: mechanical architecture and clinical specialty function.
● Classification by System Architecture and Mobility
1. Ceiling-Suspended and Floor-Mounted Ceiling DR Systems
These systems represent the core capital assets of high-throughput hospital radiology departments. Ceiling-suspended gantries offer full volumetric positioning across three axes, pairing motorized, automated tracking between the ceiling-mounted X-ray tube and the elevating bucky table or vertical wall stand. These configurations handle extreme patient throughput, enabling complex, automated stitching procedures for full-spine and long-bone orthopedics. Floor-mounted ceiling configurations utilize high-rigidity rails where structural ceiling load limits preclude overhead suspension, delivering comparable positioning repeatability at reduced architectural modification costs.
2. Floor-Mounted and U-Arm DR Systems
Designed for compact footprints, floor-mounted fixed systems and single-arm U-arm or straight-arm systems integrate the tube and detector array onto a shared mechanical pivot. These systems minimize the spatial envelope required for installation (often under 16 square meters), making them the preferred architecture for urgent care centers, ambulatory surgical networks, and low-to-mid volume community hospitals. Mechanized rotation facilitates rapid transitions between chest standing postures and recumbent table exposures.
3. Motorized and Manual Mobile DR Units
Engineered for ward rounds and bedside diagnostics in ICUs, emergency departments, and isolation units, mobile DR systems eliminate reliance on fixed room infrastructure:
Motorized Drive Mobile DR: Heavy-duty units equipped with dual-motor electric drive systems, narrow physical profiles (less than 50 centimeters chassis width), telescopic or collapsible columns, and dual wireless FPD docking enclosures. Power management architectures deploy high-capacity lithium-ion or nickel-metal hydride batteries that isolate driving traction from exposure generators, enabling continuous clinical rounds.
Manual and Lightweight Mobile DR: Systems weighing under 150 kilograms propelled manually by the technologist. These units utilize capacitor-assisted high-frequency inverter generators that draw power from standard low-amperage electrical wall outlets, drastically reducing capital costs and physical mass while maintaining diagnostic energy thresholds for emergency ward usage.
4. Ultra-Portable and Field DR Systems
Ruggedized, hand-carried, or field-deployable units weighing between 3 and 15 kilograms, often distributed within impact-resistant transit cases. Operating via carbon nanotube (CNT) cold-cathode field emitters or compact high-frequency generators paired with battery modules, these systems serve military field hospitals, disaster relief missions, sports medicine, home healthcare, and veterinary ambulatory visits.
● Classification by Clinical Specialty and Function
1. General Radiography DR
Standard planar diagnostic systems tailored for chest, skeletal, and abdominal assessments. General radiography accounts for the largest aggregate procedure volume globally, with technological progress centered on dose reduction, scatter suppression software, and automatic exposure detection (AED).
2. Dynamic and Multi-Functional DR
Systems capable of switching between standard static high-resolution radiography and low-dose continuous fluoroscopy or serial radiography on a single flat-panel detector. Dynamic DR enables physiological kinetic evaluation, including real-time diaphragmatic motion tracking, swallowing studies, joint biomechanics, and intraoperative orthopedic verification, consolidating two traditionally distinct capital room footprints into one.
3. Dedicated Specialty DR Systems
Mammography Systems: High-spatial-resolution systems deploying amorphous Selenium (a-Se) direct conversion detectors or specialized micro-pitch CMOS sensors, optimized for low-energy breast tissue soft-contrast differentiation and digital breast tomosynthesis (DBT).
Surgical Mobile C-Arms: Mobile fluoroscopic gantries utilized intraoperatively across orthopedic trauma, spinal surgery, endovascular repair, and pain interventions. Higher-tier models integrate active liquid or continuous fan cooling alongside motorized 3D orbital sweeps to execute cone-beam computed tomography (CBCT) volume reconstruction directly in the sterile operating field.
Interventional Angiography (DSA) Systems: Fixed ceiling- or floor-mounted gantry suites featuring high-power liquid-cooled rotating anode tubes, dynamic digital subtraction angiography (DSA) engines, and large-format dynamic flat panels configured for structural heart, neurovascular, and peripheral vascular interventions.
Downstream Demand Segments and Clinical Economics
● Human Clinical Healthcare
1. Intensive Care Units and High-Dependency Wards
Bedside thoracic radiography in the ICU constitutes the primary operational driver of mobile DR procurement. Critical-care beds demand continuous clinical surveillance: monitoring endotracheal tube (ETT) positioning, confirming central venous catheter and nasogastric line placements, and identifying acute conditions such as pneumothorax, pulmonary edema, and acute respiratory distress syndrome (ARDS).
The economic justification for point-of-care mobile radiography centers on adverse event mitigation. Transferring ventilated, hemodynamically unstable patients requires a dedicated transport team (intensivist or critical-care nurse, respiratory therapist, and orderly) alongside portable life-support infrastructure. Published clinical data reveals intrahospital transport complication rates between 26% and 79%, spanning physiological instability (hypoxemia, severe arrhythmias, hypotension) and mechanical complications (accidental extubation, line displacement). A single severe transport-related adverse event incurs an average marginal cost of 6,255 USD in prolonged ICU length of stay and rescue interventions. Furthermore, dedicated mobile bedside evaluation eliminates the requirement for specialized magnetic resonance- or transport-compatible disposable monitoring equipment, generating savings of approximately 590 USD per patient episode while compressing median turnaround times from over 3 hours to less than 15 minutes.
2. Emergency Departments and Trauma Triage
Emergency trauma workflows require rapid, multi-axial anatomical assessment within the initial resuscitation window. Mobile DR and high-throughput fixed floor-mounted rooms accelerate door-to-diagnosis metrics for pelvic fractures, massive hemothorax, and complex extremity fractures, triaging patients directly to surgical intervention or interventional angiography.
3. Infectious Disease Isolation and Public Health
The imperative to isolate respiratory and high-consequence pathogens has driven the adoption of remote visual exposure terminals and dual-channel isolation suites. Systems equipped with external consoles and video feeds permit radiographers to manipulate exposure parameters, monitor patient orientation, and initiate exposures from outside isolation perimeters, reducing personal protective equipment (PPE) consumption and eliminating health-worker occupational contamination vectors. Containerized, vehicle-mounted mobile X-ray clinics extend this capability to population-level tuberculosis screening and occupational health surveillance.
4. Surgical Operating Suites and Ambulatory Surgery Centers
The expansion of outpatient surgical procedures has reshaped demand for mobile surgical C-arms. Ambulatory surgery centers (ASCs) prioritize cost-effective, compact, flat-panel C-arms that deliver high fluoroscopic image quality without the capital or architectural footprint of dedicated hybrid operating rooms. Active cooling technologies expand case throughput by mitigating generator thermal cut-offs during continuous spinal fixation, joint arthroplasty, and peripheral vascular procedures.
● Veterinary Medicine and Animal Healthcare
The animal healthcare segment represents an expanding market for digital radiography, driven by companion animal humanization, rising pet insurance penetration, and high-capitalization equine and livestock operations.
Companion Animal Practices: Small animal veterinary clinics deploy floor-mounted DR systems and wireless retrofit flat-panel kits featuring veterinary-specific organ algorithms. Imaging unanesthetized animals requires ultra-short exposure times and high detector sensitivity to eliminate motion blur.
Equine and Livestock Ambulatory Practice: Field equine medicine depends on ruggedized, battery-operated field portable DR systems. Detectors must feature IP-rated water and dust ingress resistance, high drop resistance, and glass-free substrates to withstand barn environments, extreme weather, and unpredictable mechanical loads during musculoskeletal examinations.
Value Chain Architecture and Subsystem Economics
The digital radiography value chain exhibits intense technological concentration in upstream core components, followed by structural value migration toward embedded AI software, industrial mechanical design, and system integration midstream.
● Upstream Subsystems and Component Bottlenecks
1. High-Frequency X-Ray Generators and Tubes
The generator and X-ray tube assembly represent critical capital thresholds. High-frequency generators ranging from compact 3.2 kW to 5.0 kW units for portable systems, up to 32 kW to 50 kW units for mobile platforms, and 65 kW to 100 kW units for premium fixed suites require high-voltage transformer winding precision, inverter switching efficiency, and tight thermal dissipation management. The global market for high-power rotating anode tubes is concentrated among specialized producers including Varex Imaging, Dunlee (Philips), Canon Electron Tubes & Devices, and Comet, alongside vertically integrated OEMs such as Siemens Healthineers, GE HealthCare, and Shanghai United Imaging. Upstream bottlenecks center on specialized materials: high-purity tungsten-rhenium targets, molybdenum cores, liquid-metal bearing alloys, and high-voltage dielectric oils.
2. Digital Flat-Panel Detectors (FPDs)
Flat-panel detectors represent the primary determinant of image quality and radiation dose efficiency. Technologies are bifurcated:
Indirect Conversion: X-ray photons strike a scintillator—predominantly thallium-doped Cesium Iodide (CsI) with micro-columnar crystalline structures that minimize light scatter—converting photons to visible light, which is subsequently read by an amorphous silicon (a-Si) or Indium Gallium Zinc Oxide (IGZO) photodiode array. IGZO provides higher electron mobility than a-Si, enabling faster frame rates critical for dynamic fluoroscopy at lower manufacturing costs than CMOS.
Direct Conversion / High Resolution: Utilizing amorphous Selenium (a-Se) or direct CMOS substrates, bypassing visible light conversion entirely to yield maximum spatial resolution, dominating digital mammography and intraoperative mini C-arms.
Component resilience has advanced through the deployment of glass-free, flexible polyimide substrates, which replace traditional fragile glass layers within FPD assemblies. This innovation prevents detector fracture during unexpected drops during bedside ICU and field veterinary rounds. The upstream detector merchant market is anchored by suppliers such as Varex Imaging, Trixell, Vieworks, Rayence, and CarERay, while leading OEMs increasingly retain internal cleanroom manufacturing capabilities.
3. Anti-Scatter Grids and Virtual Scatter Processing
Physical focused grids composed of micro-spaced lead strips absorb scattered X-ray photons, enhancing image contrast at the cost of requiring higher patient radiation doses. JPI Healthcare maintains dominant global supply share in precision physical grids. Concurrently, software-based scatter simulation algorithms—such as Agfa SmartXR, Siemens C.A.R.E. gridless algorithms, and Samsung SimGrid—are systematically replacing physical grids for bedside thoracic imaging, lowering radiation exposure by 30% to 50% while mitigating the weight of physical detector assemblies.
● Midstream Integration, Power Management, and Software Platforms
Midstream manufacturers combine chassis fabrication, mechanical boom articulation, collision-avoidance sensors, and software platforms. In mobile applications, integration engineering centers on high-density lithium-ion battery management systems (BMS) capable of delivering high burst current for 40 kW to 50 kW generator discharges while supporting electric drive systems and rapid charging cycles (achieving 80% state-of-charge in under 45 minutes).
Value creation midstream is migrating toward edge artificial intelligence:
Automated Anatomical Protocol Adaptation: Dynamic exposure tailoring based on real-time optical patient habitus evaluation.
Zero-Click Positioning Assistance: Sensor-driven tube-to-detector auto-alignment and collimation tracking, reducing retake rates caused by technologist error.
On-Device Pathology Triage: Edge AI engines running locally on acquisition workstations that execute computer-aided detection for critical conditions (tension pneumothorax, misdirected endotracheal tubes, free intraperitoneal air) within seconds of exposure, prioritizing exams on hospital PACS reading queues.
● Downstream Deployment and Service Lifecycles
Downstream customers comprise public hospital systems, private hospital conglomerates, military and government agencies, out-of-hospital imaging networks, and private veterinary groups. The downstream business model is defined by total cost of ownership (TCO). While hardware gross margins face commoditization pressures, OEMs capture long-term high-margin cash flows through multi-year lifecycle service agreements, remote predictive component monitoring, detector damage protection riders, and periodic software-tier upgrades.
Regional Market Dynamics
● North America
North America, led by the United States and Canada, represents the largest regional market by revenue. Market characteristics reflect high procedural intensity, rapid replacement cycles for aging installed bases, and acute focus on clinical workflow automation.
Procurement dynamics are dominated by Group Purchasing Organizations (GPOs)—including Vizient, Premier, and HealthTrust—which negotiate enterprise-wide supply agreements for integrated delivery networks (IDNs). Health system capital deployment is shaped by Centers for Medicare & Medicaid Services (CMS) reimbursement structures. Reductions in Medicare reimbursement for facilities relying on legacy analog or CR equipment have cemented full digital adoption. Concurrently, CMS site-neutral payment rules and ambulatory care expansion have shifted capital investments toward compact, cost-efficient general DR and mini C-arm platforms optimized for outpatient environments.
Regulatory clearance through the US Food and Drug Administration (FDA) via the 510(k) pathway demands rigorous equivalence demonstrating low-dose safety profiles and software reliability. Supply chains remain subject to regulatory oversight regarding foreign medical component dependencies, alongside heightened cybersecurity requirements for network-connected imaging devices operating within enterprise EHR environments.
● Asia-Pacific (APAC)
Asia-Pacific is the fastest-growing geographical market, propelled by demographic aging, massive capacity expansion across public healthcare infrastructures, and the structural ascendancy of regional equipment manufacturers.
China represents a pivotal market characterized by aggressive domestic substitution policies and procurement centralization. Domestic manufacturing policies linked to the 14th Five-Year Plan and large-scale public hospital equipment renewal initiatives funded via specialized sovereign treasury instruments have driven local production rates for general DR and mobile DR platforms past 50%. The National Medical Products Administration (NMPA) maintains strict registration pathways while accelerating green channels for localized high-tech devices. Furthermore, the expansion of provincial and regional Volume-Based Procurement (VBP) programs from high-volume consumables into standard capital medical equipment has caused hardware price compression across secondary and tertiary facilities. This environment favors high-volume, vertically integrated domestic manufacturers capable of maintaining operating margins at lower tender prices, while pressuring foreign multinational vendors to establish domestic assembly facilities.
The Republic of Korea serves as a global export production hub. Manufacturers leverage advanced domestic electronics and display ecosystems to produce high-specification mobile systems, high-voltage generators, and flat-panel detectors for global distribution. DRGEM Corporation leads global OEM and own-brand production volumes from South Korea, supported by specialized developers such as GENORAY, SG Healthcare, and Rayence.
Japan represents a highly mature, technology-sophisticated market characterized by high per-capita imaging equipment penetration and a replacement-dominated demand profile. The market is led by domestic conglomerates including Canon Medical Systems, Shimadzu Corporation, and Fujifilm, with a strategic emphasis on workflow efficiency, ergonomic handling for aging healthcare workers, and low-dose radiation compliance.
Emerging Asian markets—including India, Indonesia, Vietnam, and the Philippines—exhibit significant volume demand for basic, reliable digital radiography systems. In India, foreign and domestic vendors are expanding direct distribution networks to supply community and regional facilities, navigating import duties and regulatory oversight under the Central Drugs Standard Control Organization (CDSCO).
● Europe
The European market, encompassing Western Europe, Eastern Europe, and the Nordic economies, is the second-largest digital radiography market. Demand is sustained by systematic capital replacement cycles across public healthcare frameworks (such as the UK National Health Service, statutory insurance networks in Germany, and regional health agencies in France and Italy).
Procurement criteria across Europe emphasize total lifecycle costs, ergonomic designs addressing staff shortages, data interoperability, and environmental sustainability standards under EU EcoDesign mandates. The regulatory landscape is defined by the Medical Device Regulation (EU MDR 2017/745). The transition to MDR has substantially increased regulatory friction, extending clinical trial burdens, raising Notified Body audit timelines, and necessitating continuous post-market surveillance. These regulatory costs have prompted portfolio consolidation among mid-sized European developers and prolonged registration cycles for new market entrants. Data security requirements remain strict under the General Data Protection Regulation (GDPR) alongside evolving frameworks governing the European Health Data Space (EHDS).
● Latin America
Latin America is an emerging digital radiography market, driven by public healthcare modernization programs and private hospital consolidation across Brazil, Mexico, Colombia, Chile, and Argentina. The region presents substantial opportunities for analog-to-digital retrofits, as a significant portion of primary-care facilities outside metropolitan centers continue to rely on legacy film or computed radiography. Procurement is vulnerable to currency fluctuations, macroeconomic volatility, and localized customs tariffs. Multinational corporations and established Asian exporters navigate these hurdles through partnerships with regional assembly partners and master distributors.
● Middle East and Africa (MEA)
The MEA region is characterized by stark structural divergence. Gulf Cooperation Council (GCC) nations (Saudi Arabia, the United Arab Emirates, Qatar) possess high healthcare expenditure capacities, deploying modern digital hospital infrastructure aligned with national economic transformations, such as the Saudi Vision 2030 healthcare privatization strategy. These health systems invest heavily in premium ceiling-suspended automated suites, hybrid OR C-arms, and AI-enabled mobile DR networks. Conversely, wider African markets face significant capital constraints, exhibiting low per-capita imaging densities and relying on imported capital equipment funded through international development banks, bilateral export-import financing, and foreign aid programs. Demand across these health systems focuses on ruggedized, power-tolerant floor-mounted and ultra-portable field DR platforms capable of consistent operation under unstable electrical supply conditions.
Vendor Profiles and Competitive Moats
● Multinational Medical Technology Conglomerates
1. GE HealthCare
GE HealthCare maintains an extensive global diagnostic imaging footprint, anchored across fixed radiographic systems, mobile DR, and interventional suites.
Flagship Architectures: In mobile DR, the AMX Navigate platform features an agile footprint reduced by 16% compared to prior generations, a collapsible telescopic column, zero-click RFID-assisted workflow protocols, and dual-motor electric assist handles. GE HealthCare’s proprietary FlashPad HD wireless Cesium Iodide detectors provide a 100-micron pixel pitch, coupled with the Helix 2.0 multi-scale image processing engine.
Embedded AI Strategy: GE HealthCare embeds its FDA-cleared Critical Care Suite directly onto mobile acquisition workstations. The system automatically screens and flags suspected critical pneumothorax cases within seconds of exposure, prioritizing them for immediate radiological intervention, while executing quantitative measurements of endotracheal tube placement relative to the carina at the bedside.
2. Siemens Healthineers
Siemens Healthineers combines clinical workflow standardization, hardware industrial design, and enterprise-wide imaging IT integration.
Flagship Architectures: The Mobilett Elara Max serves as the high-acuity mobile DR flagship, featuring an antimicrobial surface coating and fully integrated internal cabling that eliminates external cable runs to optimize infection control in sterile units. Unlike traditional telescoping gantries, it utilizes an articulated, 180-degree lateral arm sweep that swings entirely to the cart side, ensuring completely unobstructed forward visibility for the operator during transit.
Workflow Integration: The myExam Companion platform applies algorithmic guides that lead radiographers through optimized exposure settings and positioning protocols tailored to patient morphology, standardizing image consistency across technologist skill levels while utilizing C.A.R.E. (Combined Applications to Reduce Exposure) pre-filtration and gridless image processing.
3. Royal Philips
Royal Philips centers its diagnostic imaging portfolio on clinical ergonomics, long-reach mechanical boom engineering, and high-contrast multi-scale anatomical processing.
Flagship Architectures: The MobileDiagnost wDR represents its premium motorized mobile digital radiography suite, powered by a heavy-duty high-frequency generator (up to 40 kW and 50 kW) capable of imaging bariatric patients at the bedside without sacrificing exposure consistency. The mechanical boom features a multi-jointed, counterbalanced articulated arm extending across wide ICU beds and surgical frames, secured by electromagnetic brakes operated from the tube head. Its compact companion, the MobileDiagnost M50, provides direct digital capabilities for space-constrained clinics.
Imaging and Software Ecosystem: Systems utilize SkyPlate CsI wireless flat-panel detectors operating under the Eleva Workspot user interface—the identical software environment utilized across Philips' fixed radiography rooms—mitigating technologist cross-training requirements. Multi-scale UNIQUE 2 image processing balances extreme contrast transitions across retrocardiac and subdiaphragmatic spaces without introducing edge artifacts.
4. Fujifilm Healthcare
Fujifilm leverages its legacy chemical, material, and industrial display expertise to produce durable, low-dose digital radiography systems.
Flagship Architectures: The FDR Go PLUS provides high-throughput motorized bedside imaging featuring an agile collapsible column, touchscreen tubehead controls, and an expansive main workstation display. Its detector lineup includes FDR D-EVO II and D-EVO III glass-free wireless panels encased in lightweight carbon-composite chassis featuring IPX6 fluid ingress resistance and an antibacterial "Hydro AG" surface coating. The FDR nano provides a lightweight, non-motorized 90-kilogram mobile alternative powered by lithium-ion ultracapacitors for tight clinical quarters.
5. Canon Medical Systems
Canon Medical Systems combines optical precision, internal detector fabrication, and mechanical engineering across mobile and fixed radiographic suites.
Flagship Architectures: The Mobirex series integrates high-power motorized chassis with CXDI-Elite and CXDI-720C/820C series wireless flat panels. Canon’s software suites feature dynamic anatomical tissue balancing, scatter correction algorithms that eliminate physical grid reliance, and automated noise-reduction protocols tailored to pediatric and orthopedic applications.
6. The rest of companies covered in the report: Shimadzu Corporation, Konica Minolta, Agfa-Gevaert Group, Samsung Healthcare, Ziehm Imaging GmbH, DRGEM Corporation, GENORAY, Hologic, Carestream Health, STEPHANIX s.a., Planmed Oy, IMS Giotto S.p.A., SG Healthcare, Shanghai United Imaging Healthcare (United Imaging), Mindray Medical, Wandong Medical (Beijing Wandong), Shinva Medical Instrument Co., Ltd., Neusoft Medical Systems, Shantou Institute of Ultrasonic Instruments Co., Ltd. (SIUI), Shenzhen Angell Technology, Nanjing Perlove Medical Equipment Co., Ltd., Shenzhen SONTU Medical Imaging Equipment, Alltech Medical Systems, and Hangzhou Mednova Medical Technologies.
Opportunities & Inhibitors
● Accelerating Growth Vectors
1. Mitigation of ICU Transport Hazards and Bedside Decentralization
Point-of-care mobile radiography addresses the clinical liabilities and cost structures of intrahospital transport for critically ill patients. By eliminating ventilator disconnections, line disruptions, and hemodynamic instabilities associated with transporting non-ambulatory patients to centralized imaging departments, mobile systems save healthcare networks an average of 6,255 USD per avoided complication while cutting turnaround times by hours. As hospitals expand high-dependency bed capacity to manage complex, comorbid populations, motorized mobile DR fleets will command priority capital allocation.
2. Outpatient and Ambulatory Surgery Migration
Surgical volume migration from inpatient operating rooms to freestanding ambulatory surgery centers (ASCs) is reshaping intraoperative imaging economics. ASC operators require compact, multi-functional imaging platforms capable of delivering high clinical performance at lower acquisition costs. Compact, active-cooling mobile flat-panel C-arms will capture market share from traditional, cost-intensive hybrid angiography suites for orthopedic, endovascular, and pain management interventions.
3. Global Analog and Computed Radiography Replacement
Despite digital maturation in North America and Western Europe, an estimated 30% of the active global diagnostic X-ray installed base continues to operate using analog film or legacy computed radiography (CR) cassettes. This installed base—concentrated in primary-care clinics across emerging markets and independent veterinary practices—presents an ongoing transition opportunity. Retrofitting legacy installations with wireless flat-panel upgrade kits and AED software provides a high-margin recurring revenue runway for detector manufacturers and system integrators.
● Structural Inhibitors and Macro Risks
1. Tender Price Compression and Centralized Procurement
Government procurement bodies and healthcare purchasing alliances are exerting direct pressure on capital equipment margins. In China, the expansion of provincial and inter-provincial Volume-Based Procurement (VBP) into capital diagnostic devices is forcing hardware commoditization. In the United States, consolidated Group Purchasing Organizations (GPOs) utilize bundled tender structures that compress equipment margins. To preserve return on invested capital, equipment manufacturers must drive vertical integration down through component layers (tubes, generators, and software) or pivot toward high-margin software lifecycle subscriptions.
2. Upstream Component Concentration and Geopolitical Bottlenecks
The digital radiography value chain remains vulnerable to upstream supply chain concentration. Specialized components—such as high-frequency generator cores, liquid-metal bearing rotating anode X-ray tubes, CsI deposition cleanrooms, and high-purity anti-scatter grids—are concentrated among a limited group of global suppliers. Geopolitical friction, export restrictions, and regulatory import tariffs create supply disruptions and margin compression, forcing OEMs to pursue costly dual-sourcing strategies or invest heavily in localized subsystem production.
3. Evolving Regulatory Barriers and Post-Market Burdens
Regulatory compliance costs continue to escalate globally. In Europe, the strict transition to the EU Medical Device Regulation (MDR) has lengthened certification review times, increased Notified Body audit expenses, and expanded clinical surveillance demands, leading to the rationalization of niche product configurations. Concurrently, heightened US FDA requirements concerning cybersecurity verification for wireless, network-connected imaging devices have raised software development overheads, placing severe strain on mid-sized equipment manufacturers lacking enterprise regulatory scale.
1.1 Digital Radiography Market Scope and System Taxonomy ... 1
1.2 Research Methodology and Statistical Data Architecture ... 2
1.2.1 Primary Sourcing and Key Opinion Leader (KOL) Verification ... 2
1.2.2 Secondary Data Aggregation and Quantitative Triangulation ... 3
1.2.3 Econometric Modeling, Base-Year Normalization, and Forecasting Logic ... 4
1.3 Pricing Metrics, Currency Parity, and Unit Volume Parameters ... 5
1.4 Nomenclature and Acronym Directory ... 6
Chapter 2 Global Digital Radiography Market Ecosystem and Industry Landscape ... 7
2.1 Global Market Trajectory: Volume (Units) and Value (USD Million) (2021-2026) ... 7
2.2 Technological Migration: Indirect Conversion (CsI/GadOx) vs. Direct Conversion (a-Se) ... 9
2.3 Next-Generation Detector Substrates: IGZO and CMOS vs. Amorphous Silicon (a-Si) ... 11
2.4 Regulatory Compliance Frameworks (FDA 510(k), EU MDR 2017/745, China NMPA) ... 13
Chapter 3 Digital Radiography Value Chain and Manufacturing Economics ... 15
3.1 Upstream Value Architecture and Critical Component Sourcing ... 15
3.1.1 Flat Panel Detectors (FPD), Scintillator Layers, and Readout ICs ... 15
3.1.2 High-Frequency X-Ray Generators and Rotating Anode X-Ray Tubes ... 17
3.1.3 Mechanical Gantries, Collimators, Anti-Scatter Grids, and Motion Controllers ... 18
3.1.4 Image Acquisition Workstations and Deep Learning Computer-Aided Detection (CADe) ... 20
3.2 Cost Structure Decomposition and Bill of Materials (BOM) Economics ... 21
3.3 Value Migration from Hardware Modalities to Embedded Clinical Intelligence ... 23
Chapter 4 Global Digital Radiography Market Breakdown by System Architecture & Mobility ... 25
4.1 Architectural Segment Matrix and Clinical Deployment Drivers ... 25
4.2 Ceiling-Suspended / Floor-Mounted Ceiling DR ... 26
4.3 Floor-Mounted / U-Arm DR ... 28
4.4 Mobile DR ... 30
4.5 Portable / Field DR ... 32
Chapter 5 Global Digital Radiography Market Breakdown by Clinical Specialty & Function ... 34
5.1 Functional Classification and Multi-Specialty Clinical Demand ... 34
5.2 General Radiography DR ... 35
5.3 Dynamic / Multi-functional DR (Fluoroscopy, Tomosynthesis, Serial Radiography) ... 37
5.4 Dedicated DR Systems ... 39
5.4.1 Full-Field Digital Mammography (FFDM) and 3D Digital Breast Tomosynthesis (DBT) ... 39
5.4.2 Surgical Mobile C-Arm Systems ... 41
5.4.3 Interventional Angiography and Digital Subtraction Angiography (DSA) Systems ... 43
Chapter 6 Global Digital Radiography Market Breakdown by Downstream Application ... 45
6.1 Downstream Application Segmentation and Procurement Trajectories ... 45
6.2 Human Clinical Healthcare ... 46
6.2.1 Tertiary and Academic Medical Centers ... 46
6.2.2 Secondary Community Hospitals and Municipal Healthcare Networks ... 48
6.2.3 Ambulatory Surgery Centers (ASCs) and Independent Outpatient Imaging Centers ... 49
6.2.4 Urgent Care Clinics and Military/Field Medical Units ... 51
6.3 Veterinary Medicine & Animal Healthcare ... 53
6.3.1 Companion Animal Veterinary Hospitals and Clinics ... 53
6.3.2 Equine Diagnostics and Large Animal Ambulatory Units ... 55
Chapter 7 Global Digital Radiography Production, Trade Flows, and Logistics ... 57
7.1 Primary Global Production Hubs and Regional Assembly Capacities ... 57
7.2 Cross-Border Trade Flows, Component Logistics, and Bilateral Export-Import Tariffs ... 59
7.3 Supply Chain Resilience, Nearshoring, and Local Content Requirements ... 61
Chapter 8 North America Digital Radiography Market Analysis ... 63
8.1 Regional Overview: Market Volume (Units) and Market Size (USD Million) (2021-2031) ... 63
8.2 United States (Domestic Consumption, System Replacement Cycles, Trade Matrix) ... 65
8.3 Canada (Provincial Healthcare Procurement, Fleet Modernization, Trade Flows) ... 68
Chapter 9 Europe Digital Radiography Market Analysis ... 70
9.1 Regional Overview: Market Volume (Units) and Market Size (USD Million) (2021-2031) ... 70
9.2 Germany (Primary Manufacturing Hub, Hospital Modernization, Export Dynamics) ... 72
9.3 France (Public Tender Procurement, Imaging Network Consolidation, Imports) ... 74
9.4 United Kingdom (NHS Diagnostic Hub Rollouts, System Upgrades, Trade Balance) ... 76
9.5 Italy (National Recovery and Resilience Fund Modernization, System Penetration) ... 78
9.6 Rest of Europe (Netherlands, Switzerland, Spain, Nordics Supply & Demand Dynamics) ... 80
Chapter 10 Asia-Pacific Digital Radiography Market Analysis ... 82
10.1 Regional Overview: Market Volume (Units) and Market Size (USD Million) (2021-2031) ... 82
10.2 China (Primary Global Production Hub, Volume-Based Procurement, Localization Dynamics) ... 84
10.3 Japan (High-End Technical Innovation Hub, Aging Demographic Replacement Demand) ... 87
10.4 South Korea (Detector Manufacturing Base, Advanced Outpatient Clinic Upgrades) ... 89
10.5 India (Tier-2/3 Hospital Expansion, Import Substitution, Rural Clinic Access) ... 91
10.6 Rest of Asia-Pacific (Australia, Southeast Asian Healthcare Infrastructure Development) ... 93
Chapter 11 Latin America, Middle East & Africa Digital Radiography Market Analysis ... 95
11.1 Latin America (Brazil, Mexico, Rest of Latin America Trade and Consumption Trends) ... 95
11.2 Middle East & Africa (Saudi Arabia, UAE, South Africa Infrastructure Investments) ... 98
Chapter 12 Global Competitive Landscape and Vendor Positioning ... 101
12.1 Vendor Market Share Concentration Analysis (CR4, CR8, and HHI Metrics) ... 101
12.2 Strategic Group Mapping: Global Conglomerates, Specialized OEMs, and Regional Disruptors ... 103
12.3 Mergers, Acquisitions, Cross-Border Distribution Alliances, and OEM detector Partnerships ... 105
Chapter 13 Corporate Strategic Intelligence and Operational Benchmarking ... 107
13.1 GE HealthCare ... 107
13.1.1 Corporate Profile and Diagnostic Imaging Infrastructure ... 107
13.1.2 Digital Radiography Operational Metrics: Sales, Revenue, Price, Cost, and Gross Margin ... 108
13.1.3 SWOT Analysis and R&D Innovation Roadmap ... 109
13.2 Siemens Healthineers ... 110
13.2.1 Corporate Profile and Global Clinical Positioning ... 110
13.2.2 Digital Radiography Operational Metrics: Sales, Revenue, Price, Cost, and Gross Margin ... 111
13.2.3 SWOT Analysis and Strategic Platform Expansion ... 112
13.3 Philips ... 113
13.3.1 Corporate Profile and Integrated Diagnostic Solutions ... 113
13.3.2 Digital Radiography Operational Metrics: Sales, Revenue, Price, Cost, and Gross Margin ... 114
13.3.3 SWOT Analysis and Enterprise Clinical Systems Strategy ... 115
13.4 Fujifilm ... 116
13.4.1 Corporate Profile and Optical/Imaging Heritage ... 116
13.4.2 Digital Radiography Operational Metrics: Sales, Revenue, Price, Cost, and Gross Margin ... 117
13.4.3 SWOT Analysis and Proprietary Detector Technological Trajectory ... 118
13.5 Canon Medical Systems ... 119
13.5.1 Corporate Profile and Medical Systems Portfolio ... 119
13.5.2 Digital Radiography Operational Metrics: Sales, Revenue, Price, Cost, and Gross Margin ... 120
13.5.3 SWOT Analysis and AI-Driven Radiographic Imaging Pipeline ... 121
13.6 Shimadzu ... 122
13.6.1 Corporate Profile and Precision Medical Equipment Division ... 122
13.6.2 Digital Radiography Operational Metrics: Sales, Revenue, Price, Cost, and Gross Margin ... 123
13.6.3 SWOT Analysis and Dynamic Angiography/General Radiography Integration ... 124
13.7 Konica Minolta ... 125
13.7.1 Corporate Profile and Healthcare Imaging Architecture ... 125
13.7.2 Digital Radiography Operational Metrics: Sales, Revenue, Price, Cost, and Gross Margin ... 126
13.7.3 SWOT Analysis and Dynamic Digital Radiography (DDR) Ecosystem ... 127
13.8 Agfa-Gevaert Group ... 128
13.8.1 Corporate Profile and Radiology Solutions Footprint ... 128
13.8.2 Digital Radiography Operational Metrics: Sales, Revenue, Price, Cost, and Gross Margin ... 129
13.8.3 SWOT Analysis and Image Processing MUSICA Algorithms Differentiation ... 130
13.9 Samsung Healthcare ... 131
13.9.1 Corporate Profile and Digital Radiographic Innovation Engine ... 131
13.9.2 Digital Radiography Operational Metrics: Sales, Revenue, Price, Cost, and Gross Margin ... 132
13.9.3 SWOT Analysis and Ergonomic Mobile/Ceiling DR System Strategy ... 133
13.10 United Imaging ... 134
13.10.1 Corporate Profile and Global Medical Imaging Expansion ... 134
13.10.2 Digital Radiography Operational Metrics: Sales, Revenue, Price, Cost, and Gross Margin ... 135
13.10.3 SWOT Analysis and High-End Detector/Platform Cost-Performance Ratio ... 136
13.11 Mindray Medical ... 137
13.11.1 Corporate Profile and Tiered Medical Imaging Portfolio ... 137
13.11.2 Digital Radiography Operational Metrics: Sales, Revenue, Price, Cost, and Gross Margin ... 138
13.11.3 SWOT Analysis and Mid-Tier/Emerging Market Penetration ... 139
13.12 Planmed Oy ... 140
13.12.1 Corporate Profile and Specialized Extremity/Mammography Imaging ... 140
13.12.2 Digital Radiography Operational Metrics: Sales, Revenue, Price, Cost, and Gross Margin ... 141
13.12.3 SWOT Analysis and European Niche Clinical Differentiation ... 142
13.13 Hologic ... 143
13.13.1 Corporate Profile and Women's Health Diagnostic Leadership ... 143
13.13.2 Digital Radiography Operational Metrics: Sales, Revenue, Price, Cost, and Gross Margin ... 144
13.13.3 SWOT Analysis and Breast Tomosynthesis Ecosystem Dominance ... 145
13.14 IMS Giotto S.p.A. ... 146
13.14.1 Corporate Profile and Dedicated Radiographic Engineering ... 146
13.14.2 Digital Radiography Operational Metrics: Sales, Revenue, Price, Cost, and Gross Margin ... 147
13.14.3 SWOT Analysis and Specialized Breast Imaging & Biopsy Capabilities ... 148
13.15 Ziehm Imaging GmbH ... 149
13.15.1 Corporate Profile and Dedicated Surgical Mobile C-Arm Leadership ... 149
13.15.2 Digital Radiography Operational Metrics: Sales, Revenue, Price, Cost, and Gross Margin ... 150
13.15.3 SWOT Analysis and Intraoperative Fluoroscopy Advancement ... 151
13.16 Wandong Medical ... 152
13.16.1 Corporate Profile and Domestic Chinese Clinical Footprint ... 152
13.16.2 Digital Radiography Operational Metrics: Sales, Revenue, Price, Cost, and Gross Margin ... 153
13.16.3 SWOT Analysis and Midea Healthcare Synergies ... 154
13.17 Shinva Medical Instrument Co. Ltd. ... 155
13.17.1 Corporate Profile and Comprehensive Hospital Supply Solutions ... 155
13.17.2 Digital Radiography Operational Metrics: Sales, Revenue, Price, Cost, and Gross Margin ... 156
13.17.3 SWOT Analysis and Public Tender Scale Advantages ... 157
13.18 Carestream ... 158
13.18.1 Corporate Profile and Global Medical Imaging Legacy ... 158
13.18.2 Digital Radiography Operational Metrics: Sales, Revenue, Price, Cost, and Gross Margin ... 159
13.18.3 SWOT Analysis and DR Retrofit and High-Volume Room Solutions ... 160
13.19 DRGEM Corporation ... 161
13.19.1 Corporate Profile and Radiography System Export Specialization ... 161
13.19.2 Digital Radiography Operational Metrics: Sales, Revenue, Price, Cost, and Gross Margin ... 162
13.19.3 SWOT Analysis and High-Frequency Generator Integration Edge ... 163
13.20 SG Healthcare ... 164
13.20.1 Corporate Profile and Korean Imaging Technology Footprint ... 164
13.20.2 Digital Radiography Operational Metrics: Sales, Revenue, Price, Cost, and Gross Margin ... 165
13.20.3 SWOT Analysis and International Value-Tier Market Positioning ... 166
13.21 GENORAY ... 167
13.21.1 Corporate Profile and Surgical C-Arm & Dental/General X-Ray Architecture ... 167
13.21.2 Digital Radiography Operational Metrics: Sales, Revenue, Price, Cost, and Gross Margin ... 168
13.21.3 SWOT Analysis and Proprietary X-Ray Core Technology ... 169
13.22 Alltech Medical Systems ... 170
13.22.1 Corporate Profile and Emerging Medical Device Capabilities ... 170
13.22.2 Digital Radiography Operational Metrics: Sales, Revenue, Price, Cost, and Gross Margin ... 171
13.22.3 SWOT Analysis and Multi-Modality Imaging Synergies ... 172
13.23 Neusoft Medical Systems ... 173
13.23.1 Corporate Profile and Digital Clinical Equipment Infrastructure ... 173
13.23.2 Digital Radiography Operational Metrics: Sales, Revenue, Price, Cost, and Gross Margin ... 174
13.23.3 SWOT Analysis and AI-Integrated Cloud Imaging Platforms ... 175
13.24 Shenzhen Angell Technology ... 176
13.24.1 Corporate Profile and Dedicated Digital Radiography Specialization ... 176
13.24.2 Digital Radiography Operational Metrics: Sales, Revenue, Price, Cost, and Gross Margin ... 177
13.24.3 SWOT Analysis and Dynamic Multi-Functional DR Innovation ... 178
13.25 STEPHANIX s.a. ... 179
13.25.1 Corporate Profile and French Diagnostic Radiography Engineering ... 179
13.25.2 Digital Radiography Operational Metrics: Sales, Revenue, Price, Cost, and Gross Margin ... 180
13.25.3 SWOT Analysis and Remote-Controlled Table & C-Arm Expertise ... 181
13.26 Hangzhou Mednova Medical Technologies ... 182
13.26.1 Corporate Profile and Precision Medical Technology Platform ... 182
13.26.2 Digital Radiography Operational Metrics: Sales, Revenue, Price, Cost, and Gross Margin ... 183
13.26.3 SWOT Analysis and Domestic Regional Healthcare Penetration ... 184
13.27 Nanjing Perlove Medical Equipment Co. Ltd. ... 185
13.27.1 Corporate Profile and Full-Range X-Ray Equipment Manufacturing ... 185
13.27.2 Digital Radiography Operational Metrics: Sales, Revenue, Price, Cost, and Gross Margin ... 186
13.27.3 SWOT Analysis and Global Surgical C-Arm and Mobile DR Reach ... 187
13.28 Shenzhen SONTU Medical Imaging Equipment ... 188
13.28.1 Corporate Profile and Dedicated DR Engineering Architecture ... 188
13.28.2 Digital Radiography Operational Metrics: Sales, Revenue, Price, Cost, and Gross Margin ... 189
13.28.3 SWOT Analysis and High-End Suspension DR Market Capture ... 190
13.29 Shantou Institute of Ultrasonic Instruments Co. Ltd. (SIUI) ... 191
13.29.1 Corporate Profile and Ultrasound/Radiography Diagnostic Systems ... 191
13.29.2 Digital Radiography Operational Metrics: Sales, Revenue, Price, Cost, and Gross Margin ... 192
13.29.3 SWOT Analysis and Portable DR Deployment Capabilities ... 193
Chapter 14 Global Digital Radiography Market Forecast and Strategic Outlook (2027-2031) ... 194
14.1 Consolidated Market Forecast: Volume (Units) and Market Value (USD Million) ... 194
14.2 Segmental Growth Trajectories and Market Mix Evolution ... 195
14.3 Supply Chain Vulnerabilities, Geopolitical Headwinds, and Strategic Playbook ... 196
Table 2: Global Digital Radiography Market Volume (Units) and Value (USD Million), 2027-2031 ... 8
Table 3: Flat Panel Detector Substrate Comparison: a-Si vs. IGZO vs. CMOS vs. a-Se ... 12
Table 4: Digital Radiography Bill of Materials (BOM) Cost Breakdown Structure ... 22
Table 5: Global Digital Radiography Market Volume (Units) by Architecture & Mobility, 2021-2026 ... 25
Table 6: Global Digital Radiography Market Value (USD Million) by Architecture & Mobility, 2021-2026 ... 26
Table 7: Global Digital Radiography Market Volume (Units) by Architecture & Mobility, 2027-2031 ... 26
Table 8: Global Digital Radiography Market Value (USD Million) by Architecture & Mobility, 2027-2031 ... 26
Table 9: Ceiling-Suspended / Floor-Mounted Ceiling DR Market Volume and Value by Region, 2021-2031 ... 27
Table 10: Floor-Mounted / U-Arm DR Market Volume and Value by Region, 2021-2031 ... 29
Table 11: Mobile DR Market Volume and Value by Region, 2021-2031 ... 31
Table 12: Portable / Field DR Market Volume and Value by Region, 2021-2031 ... 33
Table 13: Global Digital Radiography Market Volume (Units) by Specialty & Function, 2021-2026 ... 34
Table 14: Global Digital Radiography Market Value (USD Million) by Specialty & Function, 2021-2026 ... 35
Table 15: Global Digital Radiography Market Volume (Units) by Specialty & Function, 2027-2031 ... 35
Table 16: Global Digital Radiography Market Value (USD Million) by Specialty & Function, 2027-2031 ... 35
Table 17: General Radiography DR Market Volume and Value by Region, 2021-2031 ... 36
Table 18: Dynamic / Multi-functional DR Market Volume and Value by Region, 2021-2031 ... 38
Table 19: Dedicated DR Systems Market Volume and Value by Specialty, 2021-2031 ... 39
Table 20: Mammography Systems Market Volume and Value by Region, 2021-2031 ... 40
Table 21: Surgical Mobile C-Arm Market Volume and Value by Region, 2021-2031 ... 42
Table 22: Interventional Angiography (DSA) Systems Market Volume and Value by Region, 2021-2031 ... 44
Table 23: Global Digital Radiography Market Volume (Units) by Application, 2021-2026 ... 45
Table 24: Global Digital Radiography Market Value (USD Million) by Application, 2021-2026 ... 45
Table 25: Global Digital Radiography Market Volume (Units) by Application, 2027-2031 ... 46
Table 26: Global Digital Radiography Market Value (USD Million) by Application, 2027-2031 ... 46
Table 27: Human Clinical Healthcare DR Market Volume and Value by Setting, 2021-2031 ... 52
Table 28: Veterinary Medicine & Animal Healthcare DR Market Volume and Value by Setting, 2021-2031 ... 56
Table 29: Global Digital Radiography Production Capacity (Units) by Major Hub, 2021-2026 ... 58
Table 30: International Trade Matrix: Digital Radiography Net Export-Import Flows (USD Million), 2026 ... 60
Table 31: North America Digital Radiography Market Volume (Units) and Value (USD Million) by Country, 2021-2031 ... 64
Table 32: United States Digital Radiography Market Volume and Value by System Architecture, 2021-2031 ... 67
Table 33: Canada Digital Radiography Market Volume and Value by System Architecture, 2021-2031 ... 69
Table 34: Europe Digital Radiography Market Volume (Units) and Value (USD Million) by Country, 2021-2031 ... 71
Table 35: Germany Digital Radiography Market Volume and Value by System Architecture, 2021-2031 ... 73
Table 36: France Digital Radiography Market Volume and Value by System Architecture, 2021-2031 ... 75
Table 37: United Kingdom Digital Radiography Market Volume and Value by System Architecture, 2021-2031 ... 77
Table 38: Italy Digital Radiography Market Volume and Value by System Architecture, 2021-2031 ... 79
Table 39: Rest of Europe Digital Radiography Market Volume and Value by System Architecture, 2021-2031 ... 81
Table 40: Asia-Pacific Digital Radiography Market Volume (Units) and Value (USD Million) by Country, 2021-2031 ... 83
Table 41: China Digital Radiography Market Volume and Value by System Architecture, 2021-2031 ... 86
Table 42: Japan Digital Radiography Market Volume and Value by System Architecture, 2021-2031 ... 88
Table 43: South Korea Digital Radiography Market Volume and Value by System Architecture, 2021-2031 ... 90
Table 44: India Digital Radiography Market Volume and Value by System Architecture, 2021-2031 ... 92
Table 45: Rest of Asia-Pacific Digital Radiography Market Volume and Value by System Architecture, 2021-2031 ... 94
Table 46: Latin America Digital Radiography Market Volume and Value by Country, 2021-2031 ... 97
Table 47: Middle East & Africa Digital Radiography Market Volume and Value by Country, 2021-2031 ... 100
Table 48: Global Top 10 Digital Radiography Manufacturers Market Share Ranking, 2025-2026 ... 102
Table 49: GE HealthCare Digital Radiography Sales, Price, Cost and Gross Profit Margin (2021-2026) ... 108
Table 50: Siemens Healthineers Digital Radiography Sales, Price, Cost and Gross Profit Margin (2021-2026) ... 111
Table 51: Philips Digital Radiography Sales, Price, Cost and Gross Profit Margin (2021-2026) ... 114
Table 52: Fujifilm Digital Radiography Sales, Price, Cost and Gross Profit Margin (2021-2026) ... 117
Table 53: Canon Medical Systems Digital Radiography Sales, Price, Cost and Gross Profit Margin (2021-2026) ... 120
Table 54: Shimadzu Digital Radiography Sales, Price, Cost and Gross Profit Margin (2021-2026) ... 123
Table 55: Konica Minolta Digital Radiography Sales, Price, Cost and Gross Profit Margin (2021-2026) ... 126
Table 56: Agfa-Gevaert Group Digital Radiography Sales, Price, Cost and Gross Profit Margin (2021-2026) ... 129
Table 57: Samsung Healthcare Digital Radiography Sales, Price, Cost and Gross Profit Margin (2021-2026) ... 132
Table 58: United Imaging Digital Radiography Sales, Price, Cost and Gross Profit Margin (2021-2026) ... 135
Table 59: Mindray Medical Digital Radiography Sales, Price, Cost and Gross Profit Margin (2021-2026) ... 138
Table 60: Planmed Oy Digital Radiography Sales, Price, Cost and Gross Profit Margin (2021-2026) ... 141
Table 61: Hologic Digital Radiography Sales, Price, Cost and Gross Profit Margin (2021-2026) ... 144
Table 62: IMS Giotto S.p.A. Digital Radiography Sales, Price, Cost and Gross Profit Margin (2021-2026) ... 147
Table 63: Ziehm Imaging GmbH Digital Radiography Sales, Price, Cost and Gross Profit Margin (2021-2026) ... 150
Table 64: Wandong Medical Digital Radiography Sales, Price, Cost and Gross Profit Margin (2021-2026) ... 153
Table 65: Shinva Medical Instrument Co. Ltd. Digital Radiography Sales, Price, Cost and Gross Profit Margin (2021-2026) ... 156
Table 66: Carestream Digital Radiography Sales, Price, Cost and Gross Profit Margin (2021-2026) ... 159
Table 67: DRGEM Corporation Digital Radiography Sales, Price, Cost and Gross Profit Margin (2021-2026) ... 162
Table 68: SG Healthcare Digital Radiography Sales, Price, Cost and Gross Profit Margin (2021-2026) ... 165
Table 69: GENORAY Digital Radiography Sales, Price, Cost and Gross Profit Margin (2021-2026) ... 168
Table 70: Alltech Medical Systems Digital Radiography Sales, Price, Cost and Gross Profit Margin (2021-2026) ... 171
Table 71: Neusoft Medical Systems Digital Radiography Sales, Price, Cost and Gross Profit Margin (2021-2026) ... 174
Table 72: Shenzhen Angell Technology Digital Radiography Sales, Price, Cost and Gross Profit Margin (2021-2026) ... 177
Table 73: STEPHANIX s.a. Digital Radiography Sales, Price, Cost and Gross Profit Margin (2021-2026) ... 180
Table 74: Hangzhou Mednova Medical Technologies Digital Radiography Sales, Price, Cost and Gross Profit Margin (2021-2026) ... 183
Table 75: Nanjing Perlove Medical Equipment Co. Ltd. Digital Radiography Sales, Price, Cost and Gross Profit Margin (2021-2026) ... 186
Table 76: Shenzhen SONTU Medical Imaging Equipment Digital Radiography Sales, Price, Cost and Gross Profit Margin (2021-2026) ... 189
Table 77: Shantou Institute of Ultrasonic Instruments Co. Ltd. (SIUI) Digital Radiography Sales, Price, Cost and Gross Profit Margin (2021-2026) ... 192
Table 78: Global Digital Radiography Market Volume (Units) Forecast by Region, 2027-2031 ... 195
Table 79: Global Digital Radiography Market Value (USD Million) Forecast by Region, 2027-2031 ... 195
Figure 1: Global Digital Radiography Market Size Trajectory (USD Million), 2021-2031 ... 9
Figure 2: Digital Radiography Upstream-to-Downstream Structural Value Chain Architecture ... 16
Figure 3: Global Digital Radiography Cost Distribution Breakdown (Components, Assembly, R&D, Logistics) ... 21
Figure 4: Global Digital Radiography Market Value Share by System Architecture & Mobility, 2026 vs. 2031 ... 27
Figure 5: Ceiling-Suspended vs. Floor-Mounted DR Market Penetration Curves, 2021-2031 ... 28
Figure 6: Mobile and Portable DR Adoption Growth Velocity in Critical Care Settings ... 32
Figure 7: Global Digital Radiography Market Value Share by Specialty & Function, 2026 ... 36
Figure 8: Dynamic/Fluoroscopy DR Market Share Expansion Trajectory, 2021-2031 ... 38
Figure 9: Dedicated Surgical Mobile C-Arm and DSA System Value Growth Dynamics ... 43
Figure 10: Global Digital Radiography Market Value Share by Application, 2026 ... 47
Figure 11: Ambulatory vs. Hospital Digital Radiography Procurement Growth Divergence ... 50
Figure 12: Veterinary Digital Radiography Market Size Expansion (USD Million), 2021-2031 ... 54
Figure 13: Global Digital Radiography Regional Production Capacity Distribution, 2026 ... 58
Figure 14: Global Trade Heatmap: Key Exporting vs. Importing Digital Radiography Hubs ... 61
Figure 15: North America Digital Radiography Market Size by Modality (USD Million), 2021-2031 ... 64
Figure 16: United States Hospital Replacement Rate and Procurement Cycles, 2021-2031 ... 66
Figure 17: Europe Digital Radiography Regional Revenue Distribution by Country, 2026 ... 71
Figure 18: Germany Digital Radiography Market Share by Functional System Type, 2026 ... 74
Figure 19: Asia-Pacific Digital Radiography Market Volume (Units) Regional Breakdown, 2021-2031 ... 84
Figure 20: China Digital Radiography Domestic Production vs. Import Value Ratio, 2021-2026 ... 86
Figure 21: Latin America, Middle East & Africa Growth Horizon Matrix, 2026-2031 ... 96
Figure 22: Global Digital Radiography Market Share Distribution of Leading Vendors, 2026 ... 102
Figure 23: Global Digital Radiography Herfindahl-Hirschman Index (HHI) Evolution, 2021-2026 ... 104
Figure 24: GE HealthCare Digital Radiography Market Share (2021-2026) ... 109
Figure 25: Siemens Healthineers Digital Radiography Market Share (2021-2026) ... 112
Figure 26: Philips Digital Radiography Market Share (2021-2026) ... 115
Figure 27: Fujifilm Digital Radiography Market Share (2021-2026) ... 118
Figure 28: Canon Medical Systems Digital Radiography Market Share (2021-2026) ... 121
Figure 29: Shimadzu Digital Radiography Market Share (2021-2026) ... 124
Figure 30: Konica Minolta Digital Radiography Market Share (2021-2026) ... 127
Figure 31: Agfa-Gevaert Group Digital Radiography Market Share (2021-2026) ... 130
Figure 32: Samsung Healthcare Digital Radiography Market Share (2021-2026) ... 133
Figure 33: United Imaging Digital Radiography Market Share (2021-2026) ... 136
Figure 34: Mindray Medical Digital Radiography Market Share (2021-2026) ... 139
Figure 35: Planmed Oy Digital Radiography Market Share (2021-2026) ... 142
Figure 36: Hologic Digital Radiography Market Share (2021-2026) ... 145
Figure 37: IMS Giotto S.p.A. Digital Radiography Market Share (2021-2026) ... 148
Figure 38: Ziehm Imaging GmbH Digital Radiography Market Share (2021-2026) ... 151
Figure 39: Wandong Medical Digital Radiography Market Share (2021-2026) ... 154
Figure 40: Shinva Medical Instrument Co. Ltd. Digital Radiography Market Share (2021-2026) ... 157
Figure 41: Carestream Digital Radiography Market Share (2021-2026) ... 160
Figure 42: DRGEM Corporation Digital Radiography Market Share (2021-2026) ... 163
Figure 43: SG Healthcare Digital Radiography Market Share (2021-2026) ... 166
Figure 44: GENORAY Digital Radiography Market Share (2021-2026) ... 169
Figure 45: Alltech Medical Systems Digital Radiography Market Share (2021-2026) ... 172
Figure 46: Neusoft Medical Systems Digital Radiography Market Share (2021-2026) ... 175
Figure 47: Shenzhen Angell Technology Digital Radiography Market Share (2021-2026) ... 178
Figure 48: STEPHANIX s.a. Digital Radiography Market Share (2021-2026) ... 181
Figure 49: Hangzhou Mednova Medical Technologies Digital Radiography Market Share (2021-2026) ... 184
Figure 50: Nanjing Perlove Medical Equipment Co. Ltd. Digital Radiography Market Share (2021-2026) ... 187
Figure 51: Shenzhen SONTU Medical Imaging Equipment Digital Radiography Market Share (2021-2026) ... 190
Figure 52: Shantou Institute of Ultrasonic Instruments Co. Ltd. (SIUI) Digital Radiography Market Share (2021-2026) ... 193
Figure 53: Global Digital Radiography Annual Installation Volume Trajectory, 2021-2031 ... 194
Figure 54: Strategic Value Horizon: Technological Convergence and Market S-Curves, 2026-2031 ... 196
Research Methodology
- Market Estimated Methodology:
Bottom-up & top-down approach, supply & demand approach are the most important method which is used by HDIN Research to estimate the market size.
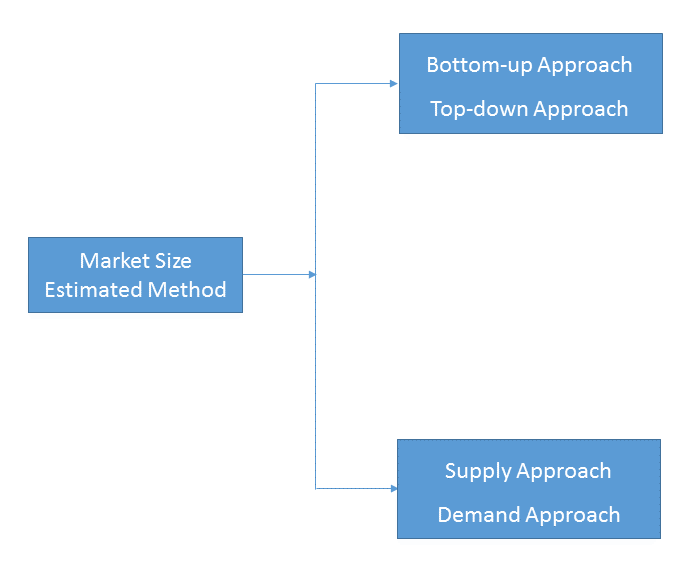
1)Top-down & Bottom-up Approach
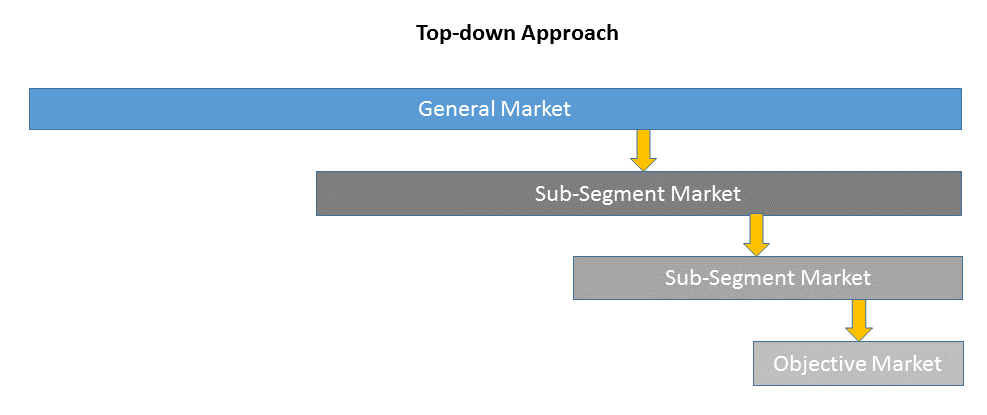
Top-down approach uses a general market size figure and determines the percentage that the objective market represents.
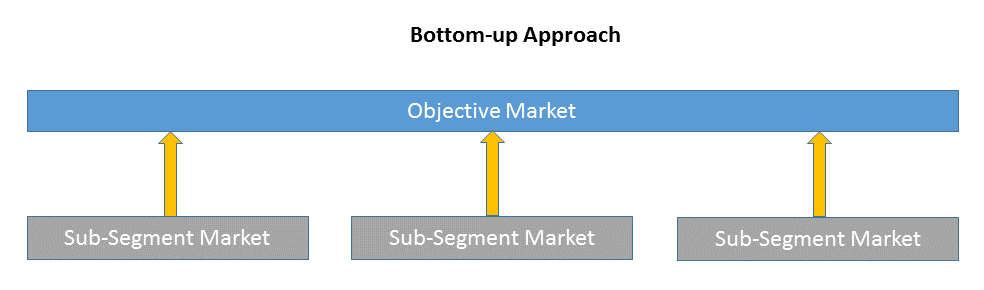
Bottom-up approach size the objective market by collecting the sub-segment information.
2)Supply & Demand Approach
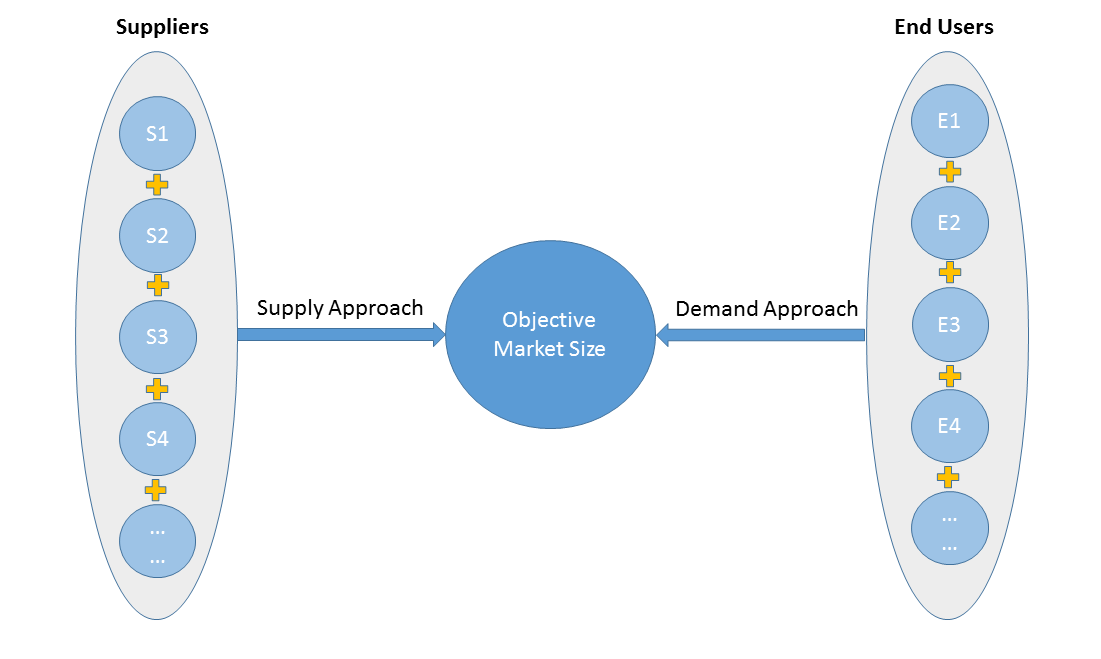
Supply approach is based on assessments of the size of each competitor supplying the objective market.
Demand approach combine end-user data within a market to estimate the objective market size. It is sometimes referred to as bottom-up approach.
- Forecasting Methodology
- Numerous factors impacting the market trend are considered for forecast model:
- New technology and application in the future;
- New project planned/under contraction;
- Global and regional underlying economic growth;
- Threatens of substitute products;
- Industry expert opinion;
- Policy and Society implication.
- Analysis Tools
1)PEST Analysis
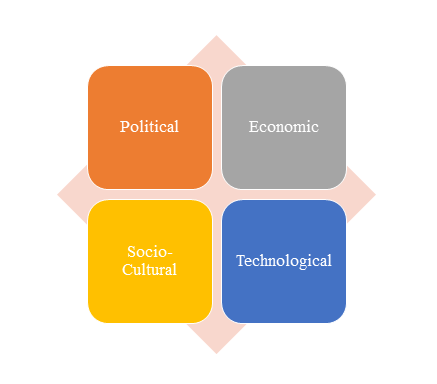
PEST Analysis is a simple and widely used tool that helps our client analyze the Political, Economic, Socio-Cultural, and Technological changes in their business environment.
- Benefits of a PEST analysis:
- It helps you to spot business opportunities, and it gives you advanced warning of significant threats.
- It reveals the direction of change within your business environment. This helps you shape what you’re doing, so that you work with change, rather than against it.
- It helps you avoid starting projects that are likely to fail, for reasons beyond your control.
- It can help you break free of unconscious assumptions when you enter a new country, region, or market; because it helps you develop an objective view of this new environment.
2)Porter’s Five Force Model Analysis
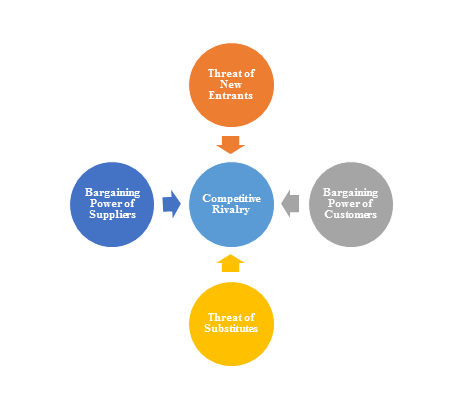
The Porter’s Five Force Model is a tool that can be used to analyze the opportunities and overall competitive advantage. The five forces that can assist in determining the competitive intensity and potential attractiveness within a specific area.
- Threat of New Entrants: Profitable industries that yield high returns will attract new firms.
- Threat of Substitutes: A substitute product uses a different technology to try to solve the same economic need.
- Bargaining Power of Customers: the ability of customers to put the firm under pressure, which also affects the customer's sensitivity to price changes.
- Bargaining Power of Suppliers: Suppliers of raw materials, components, labor, and services (such as expertise) to the firm can be a source of power over the firm when there are few substitutes.
- Competitive Rivalry: For most industries the intensity of competitive rivalry is the major determinant of the competitiveness of the industry.
3)Value Chain Analysis
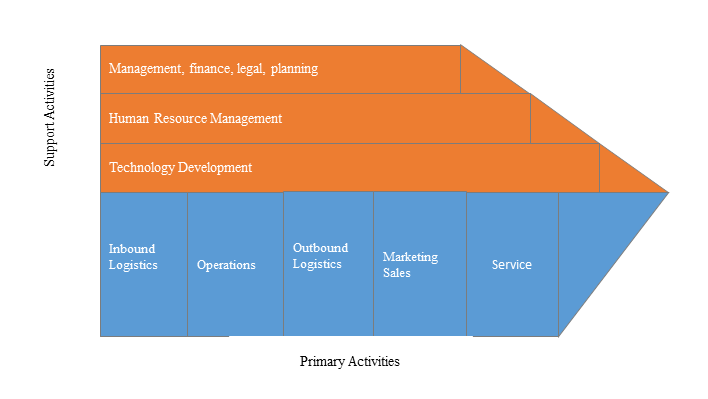
Value chain analysis is a tool to identify activities, within and around the firm and relating these activities to an assessment of competitive strength. Value chain can be analyzed by primary activities and supportive activities. Primary activities include: inbound logistics, operations, outbound logistics, marketing & sales, service. Support activities include: technology development, human resource management, management, finance, legal, planning.
4)SWOT Analysis
SWOT analysis is a tool used to evaluate a company's competitive position by identifying its strengths, weaknesses, opportunities and threats. The strengths and weakness is the inner factor; the opportunities and threats are the external factor. By analyzing the inner and external factors, the analysis can provide the detail information of the position of a player and the characteristics of the industry.
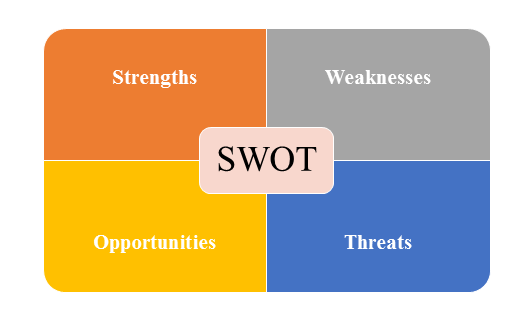
- Strengths describe what the player excels at and separates it from the competition
- Weaknesses stop the player from performing at its optimum level.
- Opportunities refer to favorable external factors that the player can use to give it a competitive advantage.
- Threats refer to factors that have the potential to harm the player.
- Data Sources
| Primary Sources | Secondary Sources |
|---|---|
| Face to face/Phone Interviews with market participants, such as: Manufactures; Distributors; End-users; Experts. Online Survey |
Government/International Organization Data: Annual Report/Presentation/Fact Book Internet Source Information Industry Association Data Free/Purchased Database Market Research Report Book/Journal/News |