Mobile Radiography System Market Analysis & Forecast 2031
- Single User License (1 Users) $ 3,500
- Team License (2~5 Users) $ 4,500
- Corporate License (>5 Users) $ 5,500
The mobile radiography systems market comprises motorized point-of-care digital radiography units, manual lightweight carts, ultra-portable field equipment, and intraoperative mobile surgical C-arms. These systems integrate high-frequency inverter generators, advanced energy storage packs, lightweight wireless flat-panel detectors, and embedded artificial intelligence engines to execute diagnostic imaging without transporting patients. The migration toward mobile modalities resolves severe clinical and economic friction. Intra-hospital transport of mechanically ventilated, critically ill intensive care patients to central radiology suites exhibits documented adverse event frequencies ranging between 26% and 79%. Each adverse transport incident incurs approximately 6,255 USD in hospital management expenses alongside heightened cross-infection vulnerabilities. Bedside mobile systems compress diagnostic turnaround intervals from hours down to real-time clinical decisions while preserving sterile isolation boundaries. The global mobile radiography systems market size will reach to 0.9 to 1.5 billion USD in 2026 with a compound annual growth rate within the interval of 6.2% to 7.7% through 2031, outperforming stationary diagnostic radiography installations.
Market supply remains structurally bifurcated. An entrenched tier of multinational conglomerates—including GE HealthCare, Siemens Healthineers, Philips, Canon Medical Systems, Fujifilm, and Agfa-Gevaert—defends premium tertiary hospital installations. Simultaneously, specialized engineering champions and fast-scaling regional market leaders, such as Ziehm Imaging, DRGEM Corporation, Wandong Medical, Shanghai United Imaging Healthcare, GENORAY, SIUI, Shenzhen Angell, Carestream Health, Samsung Healthcare, STEPHANIX, Hangzhou Mednova, and Nanjing Perlove, capture accelerated share via modular architectures, proprietary flat-panel fabrication, aggressive pricing, and integrated digital software ecosystems.
PHYSICAL IMAGING CHAIN AND TECHNICAL ARCHITECTURE
The functional operation of modern mobile radiography platforms depends on an engineered sequence of power conversion, thermionic photon emission, tissue-differential attenuation, and low-latency digital signal conversion.
The imaging chain initiates at the power conversion subsystem. High-density lithium-ion battery modules or bank-switched ultracapacitors feed an onboard high-frequency resonant inverter operating across 40 kHz to 450 kHz. This converts raw direct-current energy into precisely shaped high-voltage AC pulses, stepped up by an oil-immersed high-voltage generator to drive potentials between 40 kV and 150 kV, alongside tube currents reaching 20 mA to 500 mA. This architecture decouples system exposure functionality from facility wall outlets, allowing autonomous high-output radiographic exposures up to 50 kW at the patient bedside.
High-voltage energy terminates at the X-ray tube assembly. In motorized mobile DR carts and heavy-duty surgical C-arms, this assembly features a high-speed rotating tungsten-rhenium or molybdenum target anode paired with dual focal spot filaments (typically 0.6 mm for fine structural resolution and 1.2 mm for broad thoracic penetration). Accelerated electrons strike the rotating target under high vacuum, generating characteristic X-radiation and Bremsstrahlung photons. Heat accumulation within the target assembly is managed through circulating dielectric oil, high-emissivity anode coatings, or, in high-duty fluoroscopic C-arms, external closed-loop liquid-cooling heat exchangers.
Collimator leaves, regulated via precision stepper motors or manual lead shutters, sculpt the emerging photon field to the clinical region of interest. Transmitted through the patient, X-ray photons undergo differential attenuation proportional to tissue mass density, effective atomic number, and physical thickness.
Photons exiting anatomical structures strike a wireless digital flat-panel detector. Modern market configurations leverage two distinct conversion topologies:
Indirect Conversion Scintillators: A layer of thallium-doped Cesium Iodide (CsI:Tl), vapor-deposited in needle-like crystalline microstructures, absorbs incident X-ray photons and fluoresces visible light with minimal lateral optical scattering. This visible photon burst strikes an underlying matrix of hydrogenated amorphous silicon (a-Si) or Indium Gallium Zinc Oxide (IGZO) thin-film transistors and photodiodes. Alternatively, direct-deposited high-resolution complementary metal-oxide-semiconductor (CMOS) sensor plates are used, particularly in surgical mini and compact C-arms requiring sub-100-micron pixel pitches and fast frame rates.
Direct Conversion Photoconductors: Amorphous selenium (a-Se) layers absorb photons directly and generate electron-hole pairs collected by electric field potentials, primarily deployed in dedicated mammography or high-acuity micro-structural assessments.
Charge packets collected at each pixel location undergo parallel readouts via low-noise application-specific integrated circuits (ASICs), converting micro-volt signals into 14-bit or 16-bit digital outputs. Data packets are routed over secure point-to-point wireless channels (utilizing 5 GHz Wi-Fi protocols or ultra-wideband arrays) to the system acquisition workstation. The entire hardware transmission latency operates below 1.5 to 3.0 seconds.
Upon arrival at the mobile console, specialized digital image processing engines execute multi-scale spatial frequency decomposition, scatter suppression algorithms that digitally emulate physical anti-scatter lead grids, dynamic range compression, and automated edge enhancement. The final diagnostic dataset routes instantaneously to the hospital enterprise Picture Archiving and Communication System (PACS) and Radiology Information System (RIS) via native DICOM 3.0 network interfaces.
COMPREHENSIVE PRODUCT TAXONOMY AND SUBSYSTEM MATRIX
The mobile radiography landscape bifurcates into distinct functional architectures based on mechanical form factor, propulsion mechanics, duty cycle, and clinical localization.
1. Motorized Drive Mobile DR Systems
Engineered for continuous, high-volume bedside diagnostic rounds across inpatient pavilions, intensive care units, and emergency wards.
Chassis and Drive Mechanics: Dual-motor electric drive axles controlled by proportional, force-sensing maneuvering handles. Chassis footprints feature narrow exterior profiles under 50 cm width, dynamic electronic braking, bumper-mounted pressure-sensitive safety contact strips, and all-wheel steering assistance for tight elevator navigation.
Column Topologies: Collapsible, multi-stage telescopic columns or lateral articulated swing-arms engineered to eliminate forward visibility blind spots during transit. Total retracted heights remain below 125 cm to 135 cm.
Exposure Ratings: Power outputs generally range from 30 kW to 50 kW, leveraging dual focal-spot rotating anode tubes and integrated multi-detector storage slots equipped with onboard inductive charging.
Representative Platforms: GE HealthCare AMX Navigate and Optima XR series; Siemens Healthineers Mobilett Elara Max and Mobilett Impact; Philips MobileDiagnost wDR; Shimadzu MobileDaRt Evolution MX8; Carestream DRX-Revolution; Fujifilm FDR Go PLUS; Samsung GM85; Agfa DR 100s; DRGEM TOPAZ series; Wandong Flying 100/200/300; Shanghai United Imaging uDR 380i Pro.
2. Manual and Lightweight Mobile DR Systems
Designed for capital-constrained facilities, decentralized rural community clinics, and multi-floor hospitals with elevator limitations.
Chassis and Mechanics: Manually propelled push-carts weighing below 150 kg, featuring dead-man mechanical braking, gas-spring counterbalanced vertical columns, and low-friction medical casters.
Power Systems: Smaller 15 kW to 32 kW high-frequency inverter generators frequently paired with capacitor-assisted charging architectures that draw continuous low currents from standard single-phase 110V/220V AC wall outlets, avoiding specialized facility wiring upgrades.
Representative Platforms: DRGEM PROMO; Philips Practix series legacy/retrofitted configurations; Nanjing Perlove PLX5100 manual configurations; STEPHANIX Movix series standard configurations.
3. Ultra-Portable and Hand-Carried Field DR Systems
Targeted at rapid disaster response, tactical military field medicine, remote non-governmental public health screening, and home healthcare.
Form Factor and Portability: Ultra-compact, modular configurations packed into impact-resistant, mil-spec transport containers. Complete functional systems weigh between 3 kg and 25 kg, enabling hand transport by a single operator.
Tube Generation: Low-power monoblock generators (ranging from 1.2 kW to 5 kW) incorporating stationary anode tubes or next-generation field-emission carbon nanotube (CNT) cold-cathode arrays. These systems bypass thermionic heating cycles and drastically reduce physical volume and thermal dissipation burdens.
Environmental Hardening: Operational resilience engineered to withstand ambient extremes from -20 degrees Celsius to 50 degrees Celsius, high relative humidity, and salt spray exposure.
Representative Platforms: SIUI SR-1000 and SR-8000 series; Shanghai United Imaging uDR 330i; DRGEM Jade; Carestream DRX-Revolution Nano; Fujifilm FDR nano; GENORAY portable dental/extremity lines; JPI portable field configurations.
4. Mobile Surgical C-Arm Systems
Engineered for continuous intraoperative dynamic fluoroscopy, 2D spot radiography, and volumetric 3D navigation inside surgical operating theaters.
Gantry Mechanics: Counterbalanced orbital C-arc assemblies offering orbital rotation beyond 135 degrees, continuous lateral wig-wag, and long horizontal extensions.
Cooling and Duty Capacity: Incorporation of active closed-loop liquid-to-air cooling jackets or variable-speed high-efficiency thermal exchangers to maintain generator stability during multi-hour fluoroscopy in complex interventions.
Detection Topologies: Transition from legacy vacuum-tube image intensifiers (II) to large-format CMOS or CsI/a-Si flat-panel dynamic detectors providing high frame-rate acquisition (up to 30 frames per second) free from geometric S-distortion or peripheral optical vignetting.
Representative Platforms: Ziehm Vision RFD 3D and Ziehm Solo FD; GE HealthCare OEC series (e.g., OEC 3D, OEC Elite); Siemens Healthineers Cios series (e.g., Cios Spin, Cios Flow); GENORAY OSCAR series (Prime, Classic, ACE); Shanghai United Imaging uMC Reveal / 560i; Hologic Fluoroscan Insight FD mini C-arm.
5. Containerized and Vehicle-Mounted Mobile X-Ray Fleets
Configured for broad municipal screening, infectious disease outbreak triage, occupational health evaluations, and broad epidemiological fieldwork.
Structural Integration: High-output mobile DR systems or specialized automated chest stations installed inside heavy commercial truck chassis, converted passenger coaches, or ISO shipping containers.
Biosafety Layout: Sealed dual-channel airflows isolating radiographer operating cabins from patient imaging chambers, paired with negative-pressure air filtration, external visual intercoms, and long-range automated data uplink to central hospital telemetry hubs.
DOWNSTREAM CLINICAL APPLICATION SCENARIOS AND ECONOMICS
1. Intensive Care Units and High-Dependency Wards
Bedside thoracic and abdominal radiography represents the highest volume application in critical care medicine. Patients undergoing mechanical ventilation, extracorporeal membrane oxygenation (ECMO), or continuous renal replacement therapy present extreme transport risks. Studies identify clinical complications—including dislodgement of endotracheal tubes, disruption of central venous lines, rapid arterial oxygen desaturation, and hemodynamic instability—in 26% to 79% of transport maneuvers. With downstream clinical interventions for transport-related adverse events averaging 6,255 USD per occurrence, bedside mobile radiography presents strong health-economic defensibility. Dedicated bedside mobile units achieve turnaround times under 15 minutes, verifying endotracheal line positioning and detecting post-surgical pneumothorax or acute pleural effusions without physical patient displacement.
2. Emergency Trauma Centers and Mass Casualty Triage
In Level 1 trauma bays, mobile radiography facilitates rapid trauma assessments under Advanced Trauma Life Support (ATLS) protocols. Performing immediate supine chest and pelvic radiographs while resuscitation continues compresses door-to-treatment intervals. Rapid triage configurations leverage integrated remote exposure controls and battery-assisted power modes to operate continuously amidst chaotic department conditions.
3. Infectious Disease Isolation Environments
Strict containment wards require complete isolation between medical staff and contaminated hospital zones. Modern mobile DR systems utilize onboard optical cameras, wide-angle spatial sensors, and bi-directional intercoms to execute remote positioning and exposure initiation outside negative-pressure patient rooms. This mechanism conserves personal protective equipment (PPE), minimizes viral decontamination times, and removes medical radiographers from infectious zones.
4. Intraoperative Surgical Interventions
Mobile surgical C-arms dominate minimally invasive orthopedic trauma, spinal pedicle screw fixation, endovascular aortic repairs, and urological interventions. High-end systems perform automated motorized orbital sweeps to reconstruct 3D isotropic volumes intraoperatively, allowing immediate verification of implant trajectories before surgical incisions are closed. This capability reduces secondary revision surgeries and prevents downstream liability.
5. Veterinary Medicine and Animal Care
The veterinary healthcare market has rapidly adopted mobile DR platforms across companion animal specialty hospitals, equine sports practices, and large-animal livestock breeding operations. Veterinary environments require high acquisition speeds (sub-10 millisecond exposures) to eliminate motion blur from unanesthetized animals, animal-specific anatomic organ-program algorithms, and ruggedized, drop-resistant wireless detectors encased in carbon fiber or magnesium-alloy frames rated for farm and stable calls.
REGIONAL MARKET DYNAMICS AND REGULATORY CORRIDORS
● North America
The North American theatre represents the largest baseline market value. Capital allocation across the United States and Canada focuses heavily on workflow velocity, fleet connectivity, and AI-embedded triage suites. Demand is propelled by high ICU bedside exam volumes and an accelerating structural migration of elective orthopedic surgeries toward Ambulatory Surgery Centers (ASCs). ASCs prioritize compact, multi-purpose mobile surgical C-arms that deliver high-end imaging without the heavy structural footprint or high capital cost of fixed cath-labs.
Regulatory scrutiny hinges on US FDA 510(k) premarket notifications, with increasing regulatory emphasis placed on cybersecurity profiles for wireless hospital intranet connectivity and software validation under AI/ML guidance frameworks. Hospital purchasing behavior is consolidated under Group Purchasing Organizations (such as Vizient and Premier), which command deep hardware discounting schedules, compelling manufacturers to differentiate via bundled total-cost-of-ownership (TCO) service level agreements, integrated multi-vendor fleet analytics, and glass-free drop-resistant detectors.
● Asia-Pacific
Asia-Pacific represents the highest-velocity expansion geography. Growth is underpinned by substantial hospital infrastructure investments, dedicated public health modernization, and rapid supply chain verticalization.
In China, general diagnostic DR localization rates have exceeded 50%, while mobile C-arm domestic capture approaches the 20% mark. Domestic champions—notably Shanghai United Imaging, Wandong Medical, Mindray Medical, SIUI, and Shenzhen Angell—dominate secondary and community-tier hospital procurements. Market momentum is accelerated by public hospital upgrade mandates such as the national Thousand County Project and special treasury bond deployments for large-scale medical equipment renewals. Provincial-level centralized Volume-Based Procurement (VBP) policies exert pricing pressure across standardized hardware, compelling manufacturers to integrate advanced proprietary features, such as remote exposure terminals and AI-assisted workflows, to capture specialized procurement classes.
South Korea operates as a prominent global manufacturing and OEM export hub. DRGEM Corporation, GENORAY, SG Healthcare, and JPI Healthcare export complete mobile systems, high-voltage generators, and anti-scatter grids across more than 120 nations. DRGEM operates an annual production capacity reaching roughly 12,000 systems.
In mature markets like Japan, high per-capita medical spending maintains stable fleet replacement dynamics led by Shimadzu, Canon, and Fujifilm. Across India, Indonesia, and Vietnam, expanding private hospital systems and universal healthcare initiatives drive volume demand for mid-range mobile DR carts and robust ultra-portable field equipment.
● Europe
Europe constitutes the second largest diagnostic imaging revenue base. Western European installations (concentrated within Germany, France, the United Kingdom, Italy, and Scandinavia) exhibit high replacement rates, low-dose radiation compliance mandates, and advanced digital integration.
The regulatory environment is strictly defined by the European Medical Device Regulation (EU MDR 2017/745). The transition from the Medical Device Directive (MDD) has imposed substantial clinical evaluation burdens, rigorous post-market surveillance demands, and Notified Body capacity constraints, prolonging new product entry cycles and escalating administrative overhead. Procurement tenders place heavy weight on staff occupational safety, environmental EcoDesign standards, and full compliance with European Health Data Space (EHDS) frameworks. Eastern European markets focus capital allocation on mid-tier mobile DR solutions and fleet upgrades supported by European Union regional development allocations.
● Latin America
Latin America displays steady potential driven by the modernization of public social security health systems and simultaneous investments by private healthcare networks across Brazil, Mexico, Colombia, and Chile. The regional fleet remains bifurcated between urban medical centers demanding advanced motorized platforms and rural clinics reliant on analog retrofits or entry-level mobile units.
Market access requires navigation through diverse regional regulatory agencies, such as ANVISA in Brazil and COFEPRIS in Mexico. International market access strategies rely on regional distribution partnerships, technology transfer, or localized sub-assembly operations, exemplified by Wandong Medical's collaboration with Brazil's VMI Group.
● Middle East and Africa
The Middle East and Africa region presents diverging market extremes. The Gulf Cooperation Council (GCC) bloc—spearheaded by Saudi Arabia’s Vision 2030 healthcare infrastructure investments and United Arab Emirates clinical expansions—procures high-end motorized platforms and intraoperative 3D mobile C-arms featuring integrated AI workstations. Public tender dynamics in this zone emphasize long-term service contracts, automation, and fully digital hospital integration.
Conversely, Sub-Saharan Africa faces persistent diagnostic deficits, relying on foreign development funding, bilateral medical assistance programs, and import fleets. Growth focuses on cost-effective, ruggedized ultra-portable X-ray systems and containerized mobile diagnostic clinics designed to navigate fragile electrical grids and rural terrain.
SUPPLY CHAIN AND VALUE CHAIN ARCHITECTURE
The value chain for mobile radiography reveals critical supply bottlenecks, intellectual property concentrations, and margin migration patterns across three primary tiers.
● Upstream Value Chain: Critical Core Subsystems
The physical imaging chain depends on specialized components controlled by a concentrated group of global manufacturers:
X-Ray Tubes and Rotors: Stationary and high-power rotating anode tubes with rapid heat-dissipation housings are dominated by specialized suppliers including Varex Imaging, Dunlee (Philips), Canon Electron Tubes & Devices, and IAE, alongside vertically integrated manufacturers like Shanghai United Imaging, Wandong, and DRGEM. Sourcing constraints center on high-vacuum seal integrity, specialty tungsten/rhenium targets, and high-purity glass-to-metal or ceramic bonding.
High-Frequency Generators: Power-dense inverters capable of driving 30 kW to 50 kW outputs inside constrained footprints are concentrated among suppliers like Spellman High Voltage Electronics, Communications & Power Industries (CPI), and specialized domestic Korean and Chinese fabricators.
Flat-Panel Detectors: The detector sector represents the single largest bill-of-materials cost component. Manufacturers rely on specialized semiconductor foundries for large-area thin-film transistor (a-Si/IGZO) arrays or CMOS wafer tiling. Scintillator needle growth (CsI:Tl) requires precision thermal evaporation chambers. Key upstream providers include Varex Imaging, Trixell, Careray, Rayence, Vieworks, and iRay Technology. A key structural evolution is the migration to flexible, glass-free polyimide substrates that provide drop protection, lower chassis weight, and higher detective quantum efficiency.
Precision Motion and Mechanics: High-torque brushless DC electric motors, low-backlash planetary gearboxes, integrated electronic drive axles, and counterbalanced spring-lift column mechanisms rely on specialized industrial motion suppliers.
● Midstream Value Chain: Integration, AI Engineering, and Validation
Midstream original equipment manufacturers (OEMs) execute structural mechanical design, power management distribution, embedded system firmware programming, radiation shielding optimization, and clinical software development.
Software constitutes a primary margin-expansion vector. Value has shifted from basic image acquisition to embedded point-of-care deep learning algorithms. Platforms now deploy embedded neural networks to conduct real-time edge processing directly at the cart:
Automated Quality Control and Alignment: Predictive algorithms check tube-to-detector centering, source-to-image distance (SID), and primary beam collimation angles before exposure, reducing retake rates caused by geometric misalignment.
Pathology Triage Alerts: Algorithms screen raw projection data within seconds, immediately flagging life-threatening conditions such as tension pneumothorax, misplaced endotracheal lines, or critical hemothorax directly on the cart display to alert bedside clinicians before full radiologist review.
Software Scatter Reduction: Virtual grid algorithms analyze high-frequency spatial tissue components to eliminate secondary scatter radiation numerically. This bypasses the physical weight, alignment constraints, and patient radiation dose penalty of physical lead-strip anti-scatter grids.
● Downstream Value Chain: Commercial Channels and Field Operations
Downstream value realization is managed via global medical distributor networks, direct institutional sales forces, hospital Group Purchasing Organizations (GPOs), and state procurement agencies. Operational profitability increasingly depends on life-cycle maintenance contracts, detector drop-protection replacement policies, remote tele-diagnostics, continuous software feature updates, and structured fleet optimization analytics.
COMPETITIVE DOSSIERS: PRIMARY GLOBAL LEADERS AND SPECIALIZED INNOVATORS
● GE HealthCare: Transitioning mobile radiography platforms into intelligent, edge-computing acute-care nodes integrated with enterprise-wide digital monitoring platforms.
Operational Moat: Entrenched presence in global intensive care units and tertiary trauma centers, reinforced by long-standing clinical customer relationships and expansive direct-service fleets.
Product Lines: AMX Navigate, Optima XR240amx, and Optima XR220amx. High-end platforms feature an ultra-narrow 16% reduced footprint chassis, an articulated telescopic column to maximize transit visibility, integrated zero-click RFID patient-protocol matching, and Quick-Stow wireless detector bins with onboard inductive charging.
● Siemens Healthineers: Focus on clinical hygiene optimization, structural mechanical simplification, cross-modality fleet component interchangeability, and standardized AI workflows.
Operational Moat: Broad footprint across hospital operating suites and inpatient diagnostic pavilions, paired with its MAX detector sharing ecosystem.
Product Lines: Mobilett Elara Max, Mobilett Impact, and Mobilett Mira Max. The Elara Max eliminates external cabling via fully enclosed mechanical arm pathways paired with antimicrobial surface finishes for rapid clinical wipe-down. It uses an articulated 180-degree lateral arm sweep rather than vertical telescopic columns, granting forward transport lines of sight.
● Philips: Prioritizing bedside handling ergonomics, long-range gantry articulation, and multi-scale image dynamic processing.
Operational Moat: Strong global customer footprint within high-acuity hospital wards and long-standing enterprise PACS/imaging software distribution channels.
Product Lines: MobileDiagnost wDR and MobileDiagnost M50. The MobileDiagnost wDR incorporates high-frequency generators up to 50 kW to support bariatric imaging rounds, multi-jointed articulated arm mechanics secured with electromagnetic locking brakes, and dual-drive maneuvering mechanics equipped with automatic obstacle-collision halt sensors.
● Ziehm Imaging GmbH: Global pure-play specialization in high-end mobile surgical C-arm systems and intraoperative navigation platforms.
Operational Moat: Engineering leadership in high-output intraoperative fluoroscopy, holding broad market share in spine, neurosurgery, and hybrid operating room settings.
Product Lines: Ziehm Vision RFD 3D, Ziehm Vision RFD Hybrid Edition, Ziehm Solo FD, Ziehm Vision FD, and its affiliated OrthoScan TAU mini C-arm line.
Core Differentiator: Advanced Active Cooling (closed-loop liquid thermal systems) enabling continuous intraoperative fluoroscopy without thermal generator saturation; NaviPort ● The rest of companies covered in the report: Shimadzu Corporation, Carestream Health, Fujifilm Healthcare, Samsung Healthcare, Canon Medical Systems, Agfa-Gevaert Group (Agfa Radiology Solutions), Konica Minolta, DRGEM Corporation, STEPHANIX s.a., Wandong Medical, Shenzhen Angell Technology, Nanjing Perlove Medical Equipment Co. Ltd., and Hangzhou Mednova Medical Technologies.
STRUCTURAL SHIFTS, BOTTLENECK RESILIENCE, AND RISK MATRIX
1. Structural Opportunities
● Decoupling from Centralized Imaging Infrastructure:
The historical clinical model requiring stable, non-ambulatory, or isolated patients to be physically transported to centralized hospital basement imaging departments is fundamentally obsolete. Clinical workflow economics increasingly prioritize point-of-care deployment. Capital allocation will continually prioritize mobile systems that eliminate the adverse event risks (26% to 79% complication probability) and logistics expenses of patient transit.
● Accelerated Replacement of Analog and CR Installed Bases:
In developing regional markets and secondary healthcare networks globally, an estimated 25% to 30% of operating general X-ray systems remain tethered to chemical film processing or intermediate Computed Radiography (CR) photostimulable phosphor plates. Transitioning this legacy equipment directly to digital radiography through wireless retrofit flat-panel kits or entry-level mobile DR units represents a persistent, high-volume capital conversion cycle.
● The Ascendance of Ambulatory Surgery Centers (ASCs):
Surgical procedure delivery across North America and Western Europe continues to migrate toward decentralized, outpatient ASC settings. ASCs avoid the capital costs of dedicated, ceiling-suspended cath-labs and fixed fluoroscopy suites. Compact, versatile mobile surgical C-arms—particularly platforms equipped with intraoperative 3D navigation and flat-panel CMOS detectors—serve as the primary imaging backbone for these high-efficiency surgical businesses.
● Sensor Evolution: The Glass-Free and CMOS Transition:
The mechanical fragility of traditional glass-substrate amorphous silicon detectors presents a significant operational expenditure vulnerability; detector drops in emergency environments incur substantial repair and downtime costs. The strategic transition toward unbreakable, flexible polyimide substrates (glass-free detectors) and high-speed CMOS sensors provides system integrators with a differentiated, drop-resistant value proposition that protects end-user balance sheets.
2. Industry Challenges and Operational Inhibitors
● Severe Price Compression via Institutional Procurement:
Manufacturers face aggressive hardware price erosion driven by centralized Volume-Based Procurement (VBP) programs across East Asia and consolidated Group Purchasing Organization (GPO) multi-year contracts in North America. Hardware commoditization is compressing operating margins on baseline motorized carts, forcing competitors to derive margin defensibility from software subscription tiers, AI module licensing, and extended service level warranties.
● Upstream Subsystem Concentration and Supply Chain Chokepoints:
The mobile radiography value chain remains vulnerable to structural bottlenecks in core technical subsystems. Global manufacturing relies heavily on a narrow cohort of specialized component providers for high-frequency generators (Spellman, CPI), high-heat-capacity rotating anode tubes (Varex, Dunlee), high-purity scintillator crystalline growth, and specialized readout ASICs. Disruptions within these limited supplier bases directly threaten delivery continuity and constrain OEM assembly throughput.
● Regulatory Compliance Escalation and Approval Friction:
Compliance costs under the European Union Medical Device Regulation (EU MDR 2017/745) have expanded, driven by unannounced Notified Body audits, rigorous clinical data collection mandates, and expanded post-market surveillance overhead. Concurrently, the US FDA has intensified premarket validation expectations for artificial intelligence algorithms, clinical decision support software, and hospital-network cybersecurity protocols. These parallel regulatory hurdles increase R&D validation budgets and lengthen new system commercialization timelines.
● Geopolitical Frictions and Protectionist Trade Policies:
Cross-border trade tariffs, import quotas, and localized production mandates (e.g., Buy America provisions, domestic assembly quotas in emerging economies) introduce margin friction and operational complexity. Multinational OEMs are increasingly forced to move beyond centralized manufacturing, establishing redundant regional sub-assembly facilities, local technology transfer partnerships, and distributed global supply channels to preserve market access and protect operating profitability.
1.1 Executive Research Summary and Scope Definition 1
1.2 Research Methodology and Analytical Framework 2
1.2.1 Primary Source Triangulation and Expert Panels 3
1.2.2 Secondary Data Aggregation and Model Calibration 4
1.2.3 Economic Forecasting Assumptions (2027-2031 Horizon) 5
1.3 Acronyms and Technical Nomenclature 6
Chapter 2 Global Mobile Radiography System Market Overview and Dynamics
2.1 Mobile Radiography Systems: Product Evolution and Clinical Paradigm Shift 7
2.2 Global Market Size by Value and Deployment Volume (2021-2031) 9
2.3 Critical Market Growth Drivers and Technological Accelerators 11
2.4 Supply Chain Vulnerabilities, Regulatory Barriers, and Capital Expenditure Headwinds 12
Chapter 3 Mobile Radiography System Upstream Component Architecture and Value Chain
3.1 Comprehensive Value Chain and Cost Disaggregation 14
3.2 Upstream Tier-1 Component Sourcing and Manufacturing Bottlenecks 15
3.2.1 Flat Panel Detectors (Amorphous Silicon vs. IGZO vs. CMOS) 16
3.2.2 High-Frequency Monoblock X-Ray Generators and Rotating Anode Tubes 17
3.2.3 Mobile Chassis Robotics, Power Assist Drive, and Telescopic Columns 18
3.2.4 Medical-Grade Lithium Iron Phosphate (LiFePO4) Battery Assemblies 19
3.3 Margin Distribution and Value Capture Along the Value Chain 20
Chapter 4 Global Mobile Radiography System Market by Product Configuration
4.1 Motorized Drive Mobile DR Systems 21
4.1.1 Deployment Volume and Revenue Trajectory (2021-2031) 22
4.1.2 Power-Assisted Maneuverability and High-Throughput Hospital Adoption 23
4.2 Manual and Lightweight Mobile DR Systems 24
4.2.1 Deployment Volume and Revenue Trajectory (2021-2031) 25
4.3 Ultra-Portable and Hand-Carried Field DR Systems 26
4.3.1 Deployment Volume and Revenue Trajectory (2021-2031) 26
4.4 Mobile Surgical C-Arm Systems 27
4.4.1 Deployment Volume and Revenue Trajectory (2021-2031) 27
4.5 Containerized and Vehicle-Mounted Mobile X-Ray Fleets 28
4.5.1 Deployment Volume and Revenue Trajectory (2021-2031) 28
Chapter 5 Global Mobile Radiography System Market by Clinical Application
5.1 Human Clinical Healthcare 29
5.1.1 Intensive Care Units (ICU) and Critical Care Resuscitation 30
5.1.2 Emergency Rooms and Disaster Trauma Response 31
5.1.3 Operating Theaters and Intraoperative Radiography 32
5.1.4 General Inpatient Wards and Isolation Units 33
5.2 Veterinary Medicine and Animal Healthcare 34
5.2.1 Equine and Large Animal Field Radiography 34
5.2.2 Small Animal Clinical Imaging Practices 35
Chapter 6 North America Mobile Radiography System Market Analysis
6.1 Regional Macro Environment and Diagnostic Imaging Demand 36
6.2 United States Market Size, Unit Volume, and Clinical Channel Demand (2021-2031) 38
6.3 Canada Market Size, Unit Volume, and Procurement Structure (2021-2031) 41
Chapter 7 Europe Mobile Radiography System Market Analysis
7.1 Regional Regulatory Mandates and Healthcare Capital Allocation 44
7.2 Germany Market Size, Unit Volume, and Manufacturing Hub Dynamics (2021-2031) 46
7.3 France Market Size, Unit Volume, and Public Hospital Tenders (2021-2031) 48
7.4 United Kingdom Market Size, Unit Volume, and NHS Mobile Diagnostics (2021-2031) 49
7.5 Rest of Europe Overview (Italy, Spain, Netherlands, Nordics) 50
Chapter 8 Asia-Pacific Mobile Radiography System Market Analysis
8.1 Regional Production Hub Integration and Hospital Infrastructure Expansion 52
8.2 China Production Hub Logistics, Export Volume, and Domestic Demand (2021-2031) 54
8.3 Japan Technological Precision Sourcing and Domestic Installation (2021-2031) 56
8.4 South Korea High-Density Detector Integration and Consumption (2021-2031) 58
8.5 India & Southeast Asia Healthcare Modernization and Tier-2/3 Hospital Penetration (2021-2031) 59
Chapter 9 Latin America and Middle East & Africa Market Analysis
9.1 Latin America Regional Consumption Hubs (Brazil, Mexico) (2021-2031) 61
9.2 Middle East and Africa Sovereign Healthcare Modernization (Saudi Arabia, UAE) (2021-2031) 64
Chapter 10 Cross-Border Logistics and Global Import/Export Bilateral Flows
10.1 Global Trade Footprint and Export Value Flows of Mobile Radiography Units 67
10.2 Primary Exporter Matrix (China, Germany, Japan, United States) 68
10.3 Primary Importer Inflow Demands and Customs Tariff Regimes 70
Chapter 11 Competitive Structure and Market Concentration Analysis
11.1 Tier-1 OEM Market Dominance and CR4/CR8 Market Concentration 72
11.2 Strategic Mergers, Component Sourcing Partnerships, and AI Software Licensing 74
11.3 Emerging Market Disrupters and Price-to-Performance Pressure 75
Chapter 12 Enterprise Profiles and Competitive Performance Benchmarking
12.1 GE HealthCare 77
12.1.1 Corporate Description and Imaging Operations 77
12.1.2 Mobile Radiography System Portfolio and AI Image Processing Architecture 78
12.1.3 Mobile Radiography System Operational Metrics: Sales, Price, Cost, Gross Margin (2021-2026) 79
12.1.4 Strategic Footprint and SWOT Analysis 80
12.2 Siemens Healthineers 81
12.2.1 Corporate Description and Imaging Operations 81
12.2.2 Mobile Radiography System Portfolio and Integrated C-Arm Architecture 82
12.2.3 Mobile Radiography System Operational Metrics: Sales, Price, Cost, Gross Margin (2021-2026) 83
12.2.4 Strategic Footprint and SWOT Analysis 84
12.3 Philips 85
12.3.1 Corporate Description and Imaging Operations 85
12.3.2 Mobile Radiography System Portfolio and Workflow Optimization Solutions 86
12.3.3 Mobile Radiography System Operational Metrics: Sales, Price, Cost, Gross Margin (2021-2026) 87
12.3.4 Strategic Footprint and SWOT Analysis 88
12.4 Fujifilm 89
12.4.1 Corporate Description and Imaging Operations 89
12.4.2 FDR Nano and Ultra-Lightweight Mobile Radiography System Architecture 90
12.4.3 Mobile Radiography System Operational Metrics: Sales, Price, Cost, Gross Margin (2021-2026) 91
12.4.4 Strategic Footprint and SWOT Analysis 92
12.5 Shimadzu 93
12.5.1 Corporate Description and Imaging Operations 93
12.5.2 MobileDaRt Evolution MX8 Series Technology and Component Engineering 94
12.5.3 Mobile Radiography System Operational Metrics: Sales, Price, Cost, Gross Margin (2021-2026) 95
12.5.4 Strategic Footprint and SWOT Analysis 96
12.6 Konica Minolta 97
12.6.1 Corporate Description and Imaging Operations 97
12.6.2 AeroDR Integration and Mobile System Architecture 98
12.6.3 Mobile Radiography System Operational Metrics: Sales, Price, Cost, Gross Margin (2021-2026) 99
12.6.4 Strategic Footprint and SWOT Analysis 100
12.7 Agfa-Gevaert Group 101
12.7.1 Corporate Description and Imaging Operations 101
12.7.2 DR 100s Series and MUSICA Imaging Processing Deployment 102
12.7.3 Mobile Radiography System Operational Metrics: Sales, Price, Cost, Gross Margin (2021-2026) 103
12.7.4 Strategic Footprint and SWOT Analysis 104
12.8 Canon Medical Systems 105
12.8.1 Corporate Description and Imaging Operations 105
12.8.2 Mobirex Digital Mobile DR Solutions and Detector Ecosystem 106
12.8.3 Mobile Radiography System Operational Metrics: Sales, Price, Cost, Gross Margin (2021-2026) 107
12.8.4 Strategic Footprint and SWOT Analysis 108
12.9 Samsung Healthcare 109
12.9.1 Corporate Description and Imaging Operations 109
12.9.2 AccE GM85 Mobile Radiography Architecture and Ergonomics 110
12.9.3 Mobile Radiography System Operational Metrics: Sales, Price, Cost, Gross Margin (2021-2026) 111
12.9.4 Strategic Footprint and SWOT Analysis 112
12.10 Wandong Medical 113
12.10.1 Corporate Description and Production Hub Capacity 113
12.10.2 Mobile Radiography Product Line and Value Positioning 114
12.10.3 Mobile Radiography System Operational Metrics: Sales, Price, Cost, Gross Margin (2021-2026) 115
12.10.4 Strategic Footprint and SWOT Analysis 116
12.11 Carestream 117
12.11.1 Corporate Description and Medical Imaging Focus 117
12.11.2 DRX-Revolution and DRX-Rise Mobile DR System Deployment 118
12.11.3 Mobile Radiography System Operational Metrics: Sales, Price, Cost, Gross Margin (2021-2026) 119
12.11.4 Strategic Footprint and SWOT Analysis 120
12.12 Ziehm Imaging GmbH 121
12.12.1 Corporate Description and Specialized C-Arm Focus 121
12.12.2 Ziehm Solo and Vision Mobile Surgical C-Arm System Platforms 122
12.12.3 Mobile Radiography System Operational Metrics: Sales, Price, Cost, Gross Margin (2021-2026) 123
12.12.4 Strategic Footprint and SWOT Analysis 124
12.13 DRGEM Corporation 125
12.13.1 Corporate Description and Korean Manufacturing Footprint 125
12.13.2 TOPAZ Mobile DR Series Systems and Sourcing Network 126
12.13.3 Mobile Radiography System Operational Metrics: Sales, Price, Cost, Gross Margin (2021-2026) 127
12.13.4 Strategic Footprint and SWOT Analysis 128
12.14 Shenzhen Angell Technology 129
12.14.1 Corporate Description and Domestic Base 129
12.14.2 Angell Mobile DR Product Array and Clinical Value Dynamics 130
12.14.3 Mobile Radiography System Operational Metrics: Sales, Price, Cost, Gross Margin (2021-2026) 131
12.14.4 Strategic Footprint and SWOT Analysis 132
12.15 STEPHANIX s.a. 133
12.15.1 Corporate Description and European Manufacturing Base 133
12.15.2 Movix Series Mobile Digital Radiography Units 134
12.15.3 Mobile Radiography System Operational Metrics: Sales, Price, Cost, Gross Margin (2021-2026) 135
12.15.4 Strategic Footprint and SWOT Analysis 136
12.16 Hangzhou Mednova Medical Technologies 137
12.16.1 Corporate Description and Commercial Channels 137
12.16.2 Mednova Mobile Radiography Portfolio Specifications 138
12.16.3 Mobile Radiography System Operational Metrics: Sales, Price, Cost, Gross Margin (2021-2026) 139
12.16.4 Strategic Footprint and SWOT Analysis 140
12.17 Nanjing Perlove Medical Equipment Co. Ltd. 141
12.17.1 Corporate Description and Integrated Equipment Footprint 141
12.17.2 Perlove Mobile Radiography and Mobile C-Arm Architecture 142
12.17.3 Mobile Radiography System Operational Metrics: Sales, Price, Cost, Gross Margin (2021-2026) 143
12.17.4 Strategic Footprint and SWOT Analysis 144
Table 2. Global Mobile Radiography System Market Value by Region (USD Million), 2021-2031 10
Table 3. Cost Breakdown Structure of a Premium Motorized Mobile Radiography System, 2026 15
Table 4. Global Mobile Radiography System Volume by Product Type (Units), 2021-2031 22
Table 5. Global Mobile Radiography System Revenue by Product Type (USD Million), 2021-2031 23
Table 6. Global Mobile Radiography System Volume by Application Sector (Units), 2021-2031 29
Table 7. Global Mobile Radiography System Revenue by Application Sector (USD Million), 2021-2031 30
Table 8. North America Mobile Radiography System Volume by Country (Units), 2021-2031 37
Table 9. North America Mobile Radiography System Revenue by Country (USD Million), 2021-2031 37
Table 10. United States Mobile Radiography System Volume and Value by Type (Units, USD Million), 2021-2031 39
Table 11. Canada Mobile Radiography System Volume and Value by Type (Units, USD Million), 2021-2031 42
Table 12. Europe Mobile Radiography System Volume by Country (Units), 2021-2031 45
Table 13. Europe Mobile Radiography System Revenue by Country (USD Million), 2021-2031 45
Table 14. Germany Mobile Radiography System Volume and Value by Type (Units, USD Million), 2021-2031 47
Table 15. France Mobile Radiography System Volume and Value by Type (Units, USD Million), 2021-2031 48
Table 16. United Kingdom Mobile Radiography System Volume and Value by Type (Units, USD Million), 2021-2031 49
Table 17. Asia-Pacific Mobile Radiography System Volume by Country (Units), 2021-2031 53
Table 18. Asia-Pacific Mobile Radiography System Revenue by Country (USD Million), 2021-2031 53
Table 19. China Mobile Radiography System Volume and Value by Type (Units, USD Million), 2021-2031 55
Table 20. Japan Mobile Radiography System Volume and Value by Type (Units, USD Million), 2021-2031 57
Table 21. South Korea Mobile Radiography System Volume and Value by Type (Units, USD Million), 2021-2031 58
Table 22. India Mobile Radiography System Volume and Value by Type (Units, USD Million), 2021-2031 60
Table 23. Latin America Mobile Radiography System Volume and Value by Country (Units, USD Million), 2021-2031 62
Table 24. Middle East & Africa Mobile Radiography System Volume and Value by Country (Units, USD Million), 2021-2031 65
Table 25. Global Cross-Border Export Value of Mobile Radiography Systems by Key Hubs (USD Million), 2021-2026 68
Table 26. Global Cross-Border Import Value of Mobile Radiography Systems by Destination (USD Million), 2021-2026 70
Table 27. Global Mobile Radiography System Market Share Matrix by Tier-1 OEM, 2021-2026 73
Table 28. GE HealthCare Mobile Radiography System Sales, Price, Cost and Gross Profit Margin (2021-2026) 79
Table 29. Siemens Healthineers Mobile Radiography System Sales, Price, Cost and Gross Profit Margin (2021-2026) 83
Table 30. Philips Mobile Radiography System Sales, Price, Cost and Gross Profit Margin (2021-2026) 87
Table 31. Fujifilm Mobile Radiography System Sales, Price, Cost and Gross Profit Margin (2021-2026) 91
Table 32. Shimadzu Mobile Radiography System Sales, Price, Cost and Gross Profit Margin (2021-2026) 95
Table 33. Konica Minolta Mobile Radiography System Sales, Price, Cost and Gross Profit Margin (2021-2026) 99
Table 34. Agfa-Gevaert Group Mobile Radiography System Sales, Price, Cost and Gross Profit Margin (2021-2026) 103
Table 35. Canon Medical Systems Mobile Radiography System Sales, Price, Cost and Gross Profit Margin (2021-2026) 107
Table 36. Samsung Healthcare Mobile Radiography System Sales, Price, Cost and Gross Profit Margin (2021-2026) 111
Table 37. Wandong Medical Mobile Radiography System Sales, Price, Cost and Gross Profit Margin (2021-2026) 115
Table 38. Carestream Mobile Radiography System Sales, Price, Cost and Gross Profit Margin (2021-2026) 119
Table 39. Ziehm Imaging GmbH Mobile Radiography System Sales, Price, Cost and Gross Profit Margin (2021-2026) 123
Table 40. DRGEM Corporation Mobile Radiography System Sales, Price, Cost and Gross Profit Margin (2021-2026) 127
Table 41. Shenzhen Angell Technology Mobile Radiography System Sales, Price, Cost and Gross Profit Margin (2021-2026) 131
Table 42. STEPHANIX s.a. Mobile Radiography System Sales, Price, Cost and Gross Profit Margin (2021-2026) 135
Table 43. Hangzhou Mednova Medical Technologies Mobile Radiography System Sales, Price, Cost and Gross Profit Margin (2021-2026) 139
Table 44. Nanjing Perlove Medical Equipment Co. Ltd. Mobile Radiography System Sales, Price, Cost and Gross Profit Margin (2021-2026) 143
Figure 1. Mobile Radiography System Value Chain Tier-1 Architecture 14
Figure 2. Global Mobile Radiography System Revenue Growth (USD Million), 2021-2031 21
Figure 3. Global Mobile Radiography System Unit Shipment Share by Type, 2026 vs. 2031 24
Figure 4. Global Mobile Radiography System Revenue Share by Application Sector, 2026 31
Figure 5. North America Mobile Radiography System Market Share Breakdown by Country, 2026 36
Figure 6. United States Mobile Radiography System Value Trajectory (USD Million), 2021-2031 40
Figure 7. Europe Mobile Radiography System Market Regional Distribution, 2026 44
Figure 8. Germany Mobile Radiography System Revenue Growth Track (USD Million), 2021-2031 46
Figure 9. Asia-Pacific Mobile Radiography System Volume Share by Country, 2026 52
Figure 10. China Domestic Consumption vs. Export Volume Ratio (Units), 2021-2031 54
Figure 11. Latin America vs. Middle East & Africa Growth Rate Comparison (2027-2031) 63
Figure 12. Global Leading Mobile Radiography System Export Hubs by Market Share, 2026 69
Figure 13. Global Mobile Radiography System Market Concentration Curve (CR4 and CR8), 2021-2026 72
Figure 14. GE HealthCare Mobile Radiography System Market Share (2021-2026) 80
Figure 15. Siemens Healthineers Mobile Radiography System Market Share (2021-2026) 84
Figure 16. Philips Mobile Radiography System Market Share (2021-2026) 88
Figure 17. Fujifilm Mobile Radiography System Market Share (2021-2026) 92
Figure 18. Shimadzu Mobile Radiography System Market Share (2021-2026) 96
Figure 19. Konica Minolta Mobile Radiography System Market Share (2021-2026) 100
Figure 20. Agfa-Gevaert Group Mobile Radiography System Market Share (2021-2026) 104
Figure 21. Canon Medical Systems Mobile Radiography System Market Share (2021-2026) 108
Figure 22. Samsung Healthcare Mobile Radiography System Market Share (2021-2026) 112
Figure 23. Wandong Medical Mobile Radiography System Market Share (2021-2026) 116
Figure 24. Carestream Mobile Radiography System Market Share (2021-2026) 120
Figure 25. Ziehm Imaging GmbH Mobile Radiography System Market Share (2021-2026) 124
Figure 26. DRGEM Corporation Mobile Radiography System Market Share (2021-2026) 128
Figure 27. Shenzhen Angell Technology Mobile Radiography System Market Share (2021-2026) 132
Figure 28. STEPHANIX s.a. Mobile Radiography System Market Share (2021-2026) 136
Figure 29. Hangzhou Mednova Medical Technologies Mobile Radiography System Market Share (2021-2026) 140
Figure 30. Nanjing Perlove Medical Equipment Co. Ltd. Mobile Radiography System Market Share (2021-2026) 144
Research Methodology
- Market Estimated Methodology:
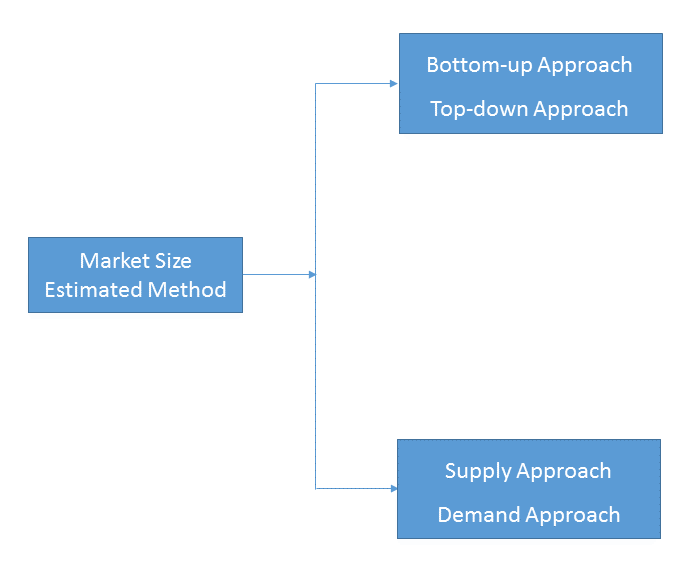
Bottom-up & top-down approach, supply & demand approach are the most important method which is used by HDIN Research to estimate the market size.
1)Top-down & Bottom-up Approach
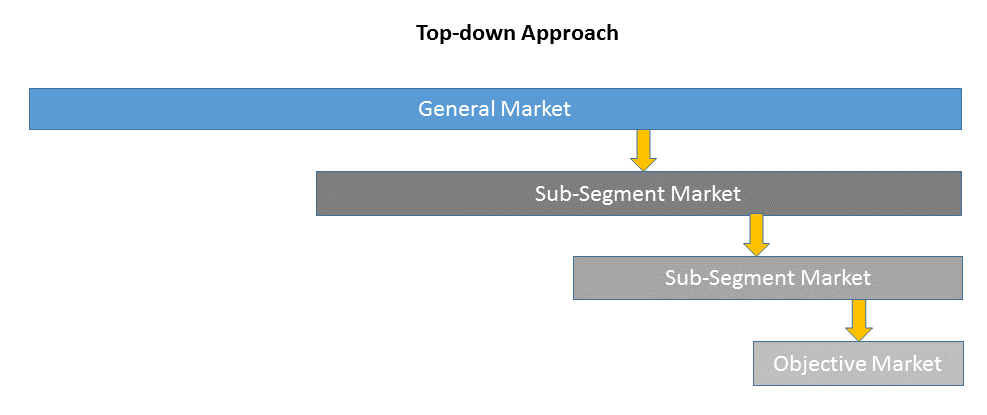
Top-down approach uses a general market size figure and determines the percentage that the objective market represents.
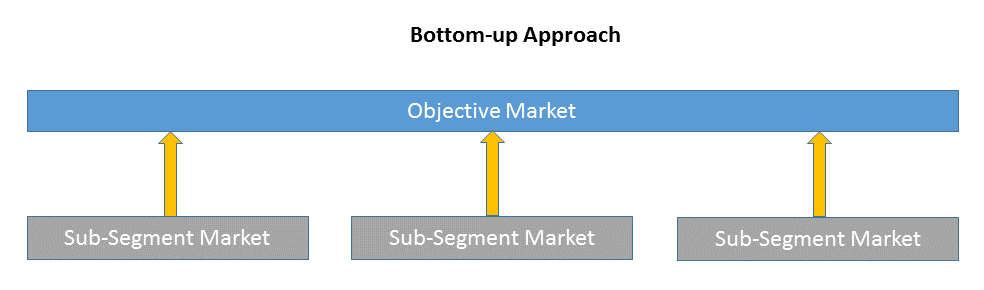
Bottom-up approach size the objective market by collecting the sub-segment information.
2)Supply & Demand Approach
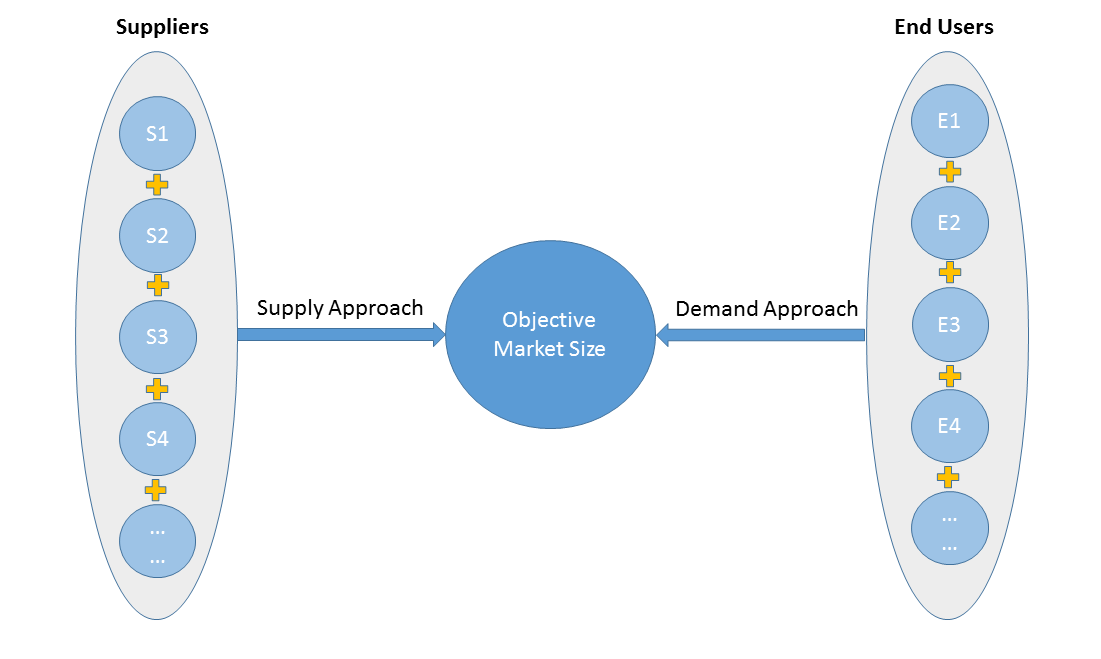
Supply approach is based on assessments of the size of each competitor supplying the objective market.
Demand approach combine end-user data within a market to estimate the objective market size. It is sometimes referred to as bottom-up approach.
- Forecasting Methodology
- Numerous factors impacting the market trend are considered for forecast model:
- New technology and application in the future;
- New project planned/under contraction;
- Global and regional underlying economic growth;
- Threatens of substitute products;
- Industry expert opinion;
- Policy and Society implication.
- Analysis Tools
1)PEST Analysis
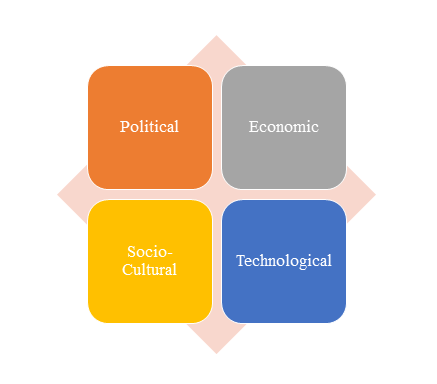
PEST Analysis is a simple and widely used tool that helps our client analyze the Political, Economic, Socio-Cultural, and Technological changes in their business environment.
- Benefits of a PEST analysis:
- It helps you to spot business opportunities, and it gives you advanced warning of significant threats.
- It reveals the direction of change within your business environment. This helps you shape what you’re doing, so that you work with change, rather than against it.
- It helps you avoid starting projects that are likely to fail, for reasons beyond your control.
- It can help you break free of unconscious assumptions when you enter a new country, region, or market; because it helps you develop an objective view of this new environment.
2)Porter’s Five Force Model Analysis
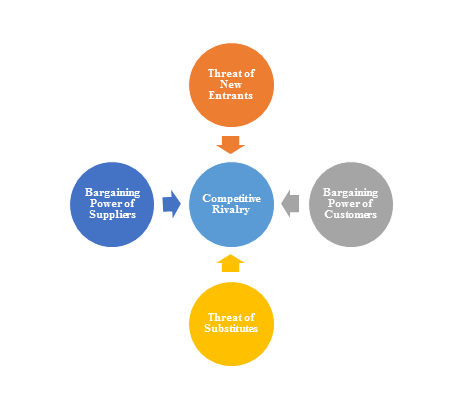
The Porter’s Five Force Model is a tool that can be used to analyze the opportunities and overall competitive advantage. The five forces that can assist in determining the competitive intensity and potential attractiveness within a specific area.
- Threat of New Entrants: Profitable industries that yield high returns will attract new firms.
- Threat of Substitutes: A substitute product uses a different technology to try to solve the same economic need.
- Bargaining Power of Customers: the ability of customers to put the firm under pressure, which also affects the customer's sensitivity to price changes.
- Bargaining Power of Suppliers: Suppliers of raw materials, components, labor, and services (such as expertise) to the firm can be a source of power over the firm when there are few substitutes.
- Competitive Rivalry: For most industries the intensity of competitive rivalry is the major determinant of the competitiveness of the industry.
3)Value Chain Analysis
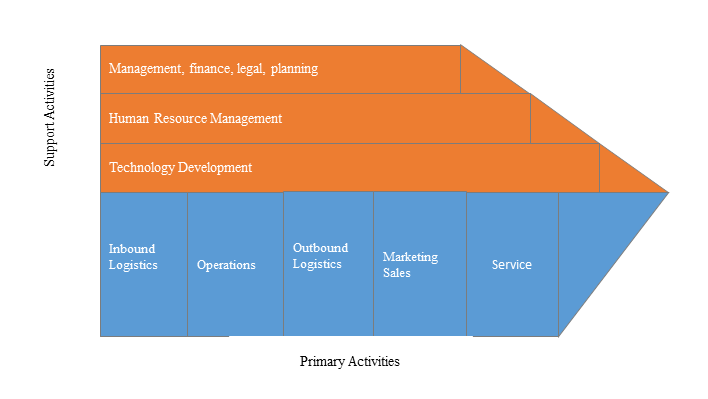
Value chain analysis is a tool to identify activities, within and around the firm and relating these activities to an assessment of competitive strength. Value chain can be analyzed by primary activities and supportive activities. Primary activities include: inbound logistics, operations, outbound logistics, marketing & sales, service. Support activities include: technology development, human resource management, management, finance, legal, planning.
4)SWOT Analysis
SWOT analysis is a tool used to evaluate a company's competitive position by identifying its strengths, weaknesses, opportunities and threats. The strengths and weakness is the inner factor; the opportunities and threats are the external factor. By analyzing the inner and external factors, the analysis can provide the detail information of the position of a player and the characteristics of the industry.
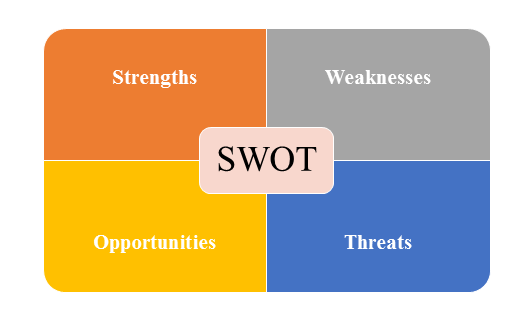
- Strengths describe what the player excels at and separates it from the competition
- Weaknesses stop the player from performing at its optimum level.
- Opportunities refer to favorable external factors that the player can use to give it a competitive advantage.
- Threats refer to factors that have the potential to harm the player.
- Data Sources
| Primary Sources | Secondary Sources |
|---|---|
| Face to face/Phone Interviews with market participants, such as: Manufactures; Distributors; End-users; Experts. Online Survey |
Government/International Organization Data: Annual Report/Presentation/Fact Book Internet Source Information Industry Association Data Free/Purchased Database Market Research Report Book/Journal/News |