Global C-Arm X-Ray System Market Intelligence Report
- Single User License (1 Users) $ 3,500
- Team License (2~5 Users) $ 4,500
- Corporate License (>5 Users) $ 5,500
The clinical imperative for intraoperative precision, alongside the systemic migration of open procedures toward minimally invasive interventions, establishes the C-arm X-ray system as an indispensable utility across modern operating rooms and catheterization suites. Comprising a semi-circular orbital gantry linking an ionizing radiation generation source to an opposing digital sensor, these platforms provide real-time dynamic fluoroscopy, static high-resolution digital radiography, and intraoperative cone-beam volumetric tomography. The global C-arm X-ray system market size will reach to USD 1.8 billion - USD 2.6 billion in 2026, advancing at an expected compound annual growth rate (CAGR) within the 4.5% to 5.5% through 2031. This expansion is governed by structurally evolving parameters: rapid demographic aging across major economies, accelerating incidences of cardiovascular, neurovascular, and degenerative orthopedic pathologies, and widespread capital realignments favoring outpatient surgical facilities.
The historical vacuum glass Image Intensifier (I.I.) architecture is facing aggressive phase-outs, superseded by solid-state Flat-Panel Detectors (FPD) utilizing Complementary Metal-Oxide-Semiconductor (CMOS), amorphous Silicon (a-Si), and Indium Gallium Zinc Oxide (IGZO) thin-film transistor arrays. Fixed installations maintain value-share leadership exceeding 60%, anchored by hybrid operating rooms and complex neuro-endovascular labs. However, agile mobile C-arms, accounting for just under 40% of the market, are witnessing the fastest volume deployment across ambulatory surgery centers (ASCs), driven by advanced 3D isocentric imaging capabilities that rival traditional computerized tomography. As regulatory frameworks tighten and centralized volume-based procurement protocols penalize hardware commoditization, market dominance hinges on ecosystem integration. Winners in this space are separating from hardware-only assemblers by deploying proprietary artificial intelligence algorithms for real-time scatter noise reduction, integrated robotic navigation tracking, and active thermal management suites that support continuous procedural workflows.
PRODUCT CLASSIFICATION & TECHNOLOGICAL ARCHITECTURE
C-arm X-ray systems are categorized across two structural domains: physical mobility/mounting configuration and image receptor physics.
● Classification by Physical Mobility and Mounting Architecture
1. Fixed C-Arm Systems:
Fixed installations represent the capital core of interventional cardiology suites, interventional radiology departments, and multidisciplinary hybrid operating rooms. Engineered as ceiling-suspended, floor-mounted, or dual-axis robotic arm configurations, fixed systems account for more than 60% of total global market value. These installations utilize high-power three-phase or stored-energy high-frequency generators operating between 80 kW and 125 kW, married to high-heat-capacity liquid-cooled rotating anode X-ray tubes capable of sustaining extended fluoroscopic and high-frame-rate digital subtraction angiography runs.
Fixed systems integrate expansive dynamic flat-panel detectors (typically measuring 30 cm x 40 cm or larger) providing wide fields of view (FOV). Modern iterations integrate multi-axis robotic articulators capable of executing complex non-isocentric trajectories, enabling rapid shifts from anteroposterior (AP) and lateral views to steep cranial-caudal angulations without mechanical collision. Advanced software suites execute real-time rotational angiography, digital roadmapping, automated vessel tracking, and multi-modality image fusion with preoperative magnetic resonance imaging (MRI) and computed tomography (CT) datasets.
2. Mobile Surgical C-Arm Systems:
Mobile C-arms represent compact, point-of-care fluoroscopic platforms designed to be maneuvered manually or via motorized drive wheels between individual operating rooms, outpatient surgical suites, and trauma bays. Mobile systems account for less than 40% of the total global market value but dominate unit shipment volumes. These platforms integrate medium-power mono-block or split generators operating between 2.5 kW and 25 kW, coupled with stationary or rotating anode tubes designed with sophisticated passive or active heat dissipation mechanisms.
Mobile platforms present clear operational advantages: minimal spatial footprints, absence of civil structural ceiling reinforcement requirements, lower capital expenditure hurdles, and rapid positioning agility around standard surgical tables. Sub-architectures in this tier include:
- Standard Mobile C-Arms: The clinical backbone for routine orthopedic hardware fixation, basic vascular interventions, and pain management injections.
- 3D Isocentric Mobile C-Arms: High-precision systems that perform motorized orbital sweeps around the patient to reconstruct cone-beam computed tomography (CBCT) volumes with isotropic sub-millimeter voxel resolutions, enabling immediate intraoperative hardware validation.
- Compact / Mini C-Arms: Dedicated low-power, small-footprint systems engineered specifically for hand, wrist, foot, and ankle extremity surgeries, traditionally employing low-power micro-focus tubes.
● Classification by Image Receptor Technology
1. Image Intensifier (I.I.) Systems:
Legacy fluoroscopic platforms utilize analog vacuum-tube image intensifiers coupled via optical distributor lenses to charged-coupled device (CCD) cameras. An image intensifier converts incident attenuated X-ray photons into electrons via a cesium iodide (CsI) photocathode, accelerates them through an electrostatic field, and strikes an output phosphor screen to produce visible light. While historically significant and maintaining a dwindling price-sensitive footprint in basic primary care clinics, I.I. technology is structurally limited. It suffers from geometric pincushion and S-distortion, vignetting (light loss toward the edges), dynamic range limitations, and inevitable mechanical vacuum degradation over operational lifespans, alongside bulkier physical geometries that compromise the sterile surgical field.
2. Flat-Panel Detector (FPD) Systems:
FPD-equipped C-arms represent the dominant contemporary manufacturing standard. Solid-state detectors capture transmitted X-rays without geometric distortion, maintaining uniform spatial resolution, high detective quantum efficiency (DQE), and wide dynamic ranges across the entire field of view. FPD integration has reduced the physical envelope of the gantry head, expanding the operational free space and orbital rotation span for surgical personnel. Three distinct semiconductor platforms define this tier:
- Amorphous Silicon (a-Si): The foundational flat-panel standard, utilizing a vapor-deposited cesium iodide (CsI:Tl) scintillator that converts X-ray photons into visible light, which is subsequently registered by a matrix array of hydrogenated amorphous silicon photodiodes and thin-film transistors (TFTs). a-Si delivers robust reliability and cost balance but exhibits limitations in ultra-fast readout rates.
- Complementary Metal-Oxide-Semiconductor (CMOS): The leading architecture for high-resolution, low-dose surgical imaging. CMOS detectors fabricate the sensor array directly onto crystalline silicon wafers, integrating active amplifier circuitry within each individual pixel. This architecture enables ultra-low electronic read noise, extraordinarily rapid frame readout rates (up to 60 fps or higher without image lag), and superior low-dose image quality, making it ideal for pediatric, orthopedic, and complex neurovascular navigation.
- Indium Gallium Zinc Oxide (IGZO): An emerging alternative TFT channel material characterized by electron mobility substantially higher than amorphous silicon. IGZO enables smaller pixel apertures, reduced driving voltages, and fast frame rates while maintaining large panel sizes at lower fabrication costs than crystalline CMOS, proving instrumental in next-generation low-dose interventional systems.
SUPPLY CHAIN ARCHITECTURE & BOTTLENECK RESILIENCE
The production architecture of C-arm X-ray systems is highly stratified, marked by deep upstream component specialization, midstream systems integration and algorithmic differentiation, and regulated downstream capital deployment channels.
● Upstream Value Chain (Core Subsystems & Physics Bottlenecks)
The upstream tier is defined by substantial technological and capital barriers to entry, with core subsystems concentrated among specialized global manufacturers:
- X-Ray Generators and Tubes: The generation chain requires precision high-voltage engineering capable of producing rapid millisecond pulses with minimal voltage ripple. High-frequency generators are sourced from specialized merchant suppliers such as Spellman High Voltage Electronics and Communications & Power Industries (CPI), or manufactured in-house by vertically integrated conglomerates like Siemens Healthineers, Philips DMC, and United Imaging. High-end interventional tubes require liquid-metal bearing technology and high-anode heat capacities (exceeding 1.5 to 3 million heat units) to prevent overheating during protracted procedures, dominated by suppliers like Varex Imaging and Canon Electron Tubes & Devices.
- Digital Receptor Arrays: The fabrication of large-area CMOS, a-Si, and IGZO flat panels requires advanced semiconductor foundry and cleanroom infrastructure. While specialized merchant foundries (e.g., Varex Imaging, Trixell, Vieworks, Rayence) supply standard panels, select OEMs maintain proprietary cleanroom production lines (e.g., Genoray for CMOS arrays, United Imaging for custom dynamic sensors) to secure structural cost moats and customized pixel architectures.
- Precision Anti-Scatter Grids: Placed directly in front of the receptor array, grids absorb scattered off-axis radiation to preserve image contrast. Specialized manufacturers, such as JPI Healthcare, produce micro-focused carbon-graphite and fiber-interspaced grids (e.g., GRID-2100) engineered specifically to minimize beam attenuation in low-dose surgical fluoroscopy.
- Thermal Dissipation Systems: Advanced fluoroscopy demands active liquid cooling loops utilizing specialized heat exchangers, chillers, and fluorochemical coolants to cycle fluid around the tube envelope, bypassing the thermal shutdowns typical of fan-cooled monoblocks.
● Midstream Value Chain (Integration, Kinematics & Software)
Midstream OEMs function as mechanical architects and software platform developers. Mechanical engineering centers on C-arm orbital balance, multi-axis counterbalance mechanisms, and anti-collision electromechanical braking. Even slight misalignments in the C-gantry create physical deflection during isocentric rotation, which degrades 3D volumetric reconstructions.
Value migration within the midstream tier has shifted decisively toward software engineering:
- Advanced Image Signal Processing (ISP): Real-time deep learning pipelines execute automated denoising, edge enhancement, and motion-blur suppression at the edge, dynamically extracting bony trabeculae or microvascular lumens from low-dose fluoroscopic streams without inducing perceptible visual latency.
- Radiation Dose Modulation: Proprietary automatic exposure control (AEC) engines optimize kV, mA, copper beam filtration, and pulse width on a per-frame basis, matching patient anatomical thickness while adhering to ALARA principles.
- Ergonomic and Motion Automation: Software integrates motorized orbital trajectory memory, permitting single-touch return to memorized projection angles, eliminating repeated scout exposures.
● Downstream Value Chain (Clinical Deployment & Distribution Channels)
Capital equipment reaches end-users through specialized medical device distributor networks, OEM direct sales teams, and structured national tenders:
- Inpatient Tertiary & Hybrid Suites: High-dollar transactions characterized by prolonged capital allocation cycles (12 to 24 months), involving multi-stakeholder hospital procurement boards, clinical department heads, medical physics officers, and biomedical engineering divisions.
- Ambulatory Surgery Centers & Outpatient Clinics: Streamlined acquisition processes characterized by short procurement cycles (3 to 6 months), prioritizing systems with small footprints, broad multidisciplinary versatility, rapid boot sequences, and high operational uptime.
- Veterinary Hospitals & Academic Institutes: Dedicated commercial veterinary distribution routes servicing private companion animal networks and equine surgical hospitals requiring specialized anatomical firmware.
CLINICAL APPLICATIONS & PROCEDURAL UTILIZATION
● Human Clinical Healthcare
1. Orthopedic and Spine Surgery:
Orthopedic and spinal procedures constitute the largest volume utilization driver for mobile C-arms. Surgeons depend on dynamic fluoroscopy for the reduction of closed fractures, positioning of intramedullary nails, plate fixation, dynamic hip screw implants, and joint reconstruction. In spine surgery, high-resolution intraoperative visualization is critical for percutaneous pedicle screw insertion, transforaminal lumbar interbody fusions (TLIF), and cervical decompression. The emergence of 3D isocentric mobile C-arms has transformed spinal workflows: surgeons perform an intraoperative cone-beam scan while the patient remains draped on the radiolucent carbon-fiber table, checking axial and sagittal hardware trajectories to correct sub-millimeter cortical perforations prior to incision closure.
2. Neurosurgery, Pain Management, and Anesthesiology:
Interventional pain management represents the highest-cadence operational domain for compact and mid-tier mobile C-arms. Practicing interventionalists utilize continuous and pulsed fluoroscopy to navigate needles for epidural steroid injections, selective nerve root blocks, facet joint denervations, and spinal cord stimulator (SCS) lead implantations. Spatial resolution and contrast sensitivity are vital to visualize radiopaque contrast dispersion and identify unintended intravascular uptake. In cranial and cervical neurosurgery, mobile and fixed systems guide intracranial catheter placements, skull-base reconstructions, and aneurysm coiling.
3. Interventional Cardiology and Vascular Surgery:
Cardiovascular interventions require advanced, high-power fixed DSA suites and high-end mobile vascular C-arms. Core procedures include percutaneous coronary intervention (PCI), transcatheter aortic valve replacement (TAVR), endovascular aneurysm repair (EVAR/TEVAR), and peripheral transluminal angioplasty (PTA). Systems must deliver digital subtraction angiography, high-frame-rate vascular roadmapping, peak opacification display, and vessel measurement toolsets, operating reliably alongside active cooling infrastructures during lengthy endovascular deployments.
4. Gastroenterology and Endourology:
Fluoroscopic guidance is foundational across urological and biliary tracts. In endourology, mobile C-arms guide percutaneous nephrolithotomy (PCNL) needle access to the renal calyx, double-J stent tracking, and ureteroscopic lithotripsy. Gastroenterology suites deploy C-arms for endoscopic retrograde cholangiopancreatography (ERCP), enabling therapeutic cannulation of the bile and pancreatic ducts, sphincterotomy verification, and metal/plastic stent installations for obstructive jaundice.
5. Emergency Trauma and General Surgery:
Trauma surgical teams deploy C-arms in high-acuity resuscitation bays and operating suites for rapid intraoperative checks, including locating and extracting ballistic fragments or foreign bodies, validating pelvic ring fracture stabilizations, executing intraoperative cholangiography during laparoscopic cholecystectomies, and checking surgical field clearance prior to patient transfer.
● Veterinary Medicine and Animal Healthcare
Veterinary surgery represents an accelerating specialty application for dedicated mobile C-arm systems. Companion animal specialty hospitals, university veterinary colleges, and equine medical centers increasingly employ mobile fluoroscopy for complex small-animal orthopedic plate fixations, canine spinal decompression, tracheal stent placements, and equine limb arthroscopy. Systems configured for veterinary clinical use feature tailored animal-species anatomical software presets, extended horizontal clearance architectures to accommodate varying patient sizes, and high-duty-cycle cooling platforms capable of sustaining prolonged surgical interventions.
REGIONAL MARKET DYNAMICS
● North America
North America maintains its status as the highest-revenue geographic theatre for surgical C-arms and interventional digital subtraction angiography (DSA) suites. Regional capital allocation is heavily driven by procedural throughput across United States hospital networks and an aggressive systemic shift toward freestanding Ambulatory Surgery Centers (ASCs). Clinical operators prioritize motorized 3D intraoperative imaging platforms that interface directly with computer-assisted orthopedic and spinal navigation robotics to reduce surgical revision rates.
Procurement dynamics are governed by Medicare and Medicaid reimbursement frameworks administered by the Centers for Medicare & Medicaid Services (CMS). Recent adjustments under the One Big Beautiful Bill Act of 2025, alongside evolving site-neutral payment rules, have compressed inpatient facility margins, accelerating the movement of complex spine, joint arthroplasty, and endovascular interventions into outpatient facilities. Capital equipment procurement remains tightly controlled by Group Purchasing Organizations (GPOs) such as Vizient, Premier, and HealthTrust, demanding aggressive total-cost-of-ownership (TCO) concessions from equipment manufacturers. Regulatory barriers remain formidable, requiring comprehensive FDA 510(k) premarket notifications with rigorous software lifecycle and cybersecurity auditing, while ongoing United States Trade Representative (USTR) Section 232 scrutiny shapes component sourcing dependencies.
● Asia-Pacific
The Asia-Pacific region demonstrates the most rapid procedural and equipment adoption velocity globally, characterized by dual-track demand: high-end volumetric hybrid OR systems in Tier-1 tertiary medical centers and durable, cost-optimized mobile systems across secondary and county-level hospitals.
In China, government-directed initiatives, notably the 14th Five-Year Plan, the national Large-Scale Equipment Renewal program funded through ultra-long special treasury bonds, and the Thousand County Project, are driving wholesale fleet modernization. Domestic localization metrics for interventional DSA and mobile C-arms have expanded past 15% to 20%, shifting competitive dynamics. Centralized Volume-Based Procurement (VBP), historically restricted to high-value medical consumables, has expanded into capital imaging platforms at provincial and inter-provincial alliance levels. This compresses hardware margins while favoring domestic manufacturers that comply with national self-reliance benchmarks. The National Medical Products Administration (NMPA) maintains stringent registration paths, balanced by priority fast-track approval channels for breakthrough technologies, while the Two-Invoice System strictly regulates supply-side distributor margins. Within the broader region, markets such as Taiwan, China, exhibit sustained demand for advanced fluoroscopic imaging systems suited for advanced oncological and vascular procedures.
South Korea functions as a global engineering and export hub, anchored by indigenous flat-panel CMOS sensor production and dynamic imaging software development. Japan represents a mature, highly saturated replacement market characterized by stringent clinical expectations for radiation dose management, space-saving footprints, and ergonomic operability. Emerging Asia-Pacific economies, including India, Indonesia, and Vietnam, are investing heavily in public healthcare capacity, stimulating high-volume tenders for entry-level and mid-tier mobile FPD C-arms to equip newly constructed trauma and regional surgical clinics.
● Europe
Western Europe represents the second-largest global regional market, dominated by consistent replacement cycles across mature public and private hospital infrastructures in Germany, France, the United Kingdom, Italy, and Spain. European clinical departments operate under strict radiation safety guidelines (ALARA principles) and labor ergonomics directives, prioritizing systems featuring automated dose-modulation hardware, anti-microbial chassis finishes, and single-operator mobility.
The operational landscape is dictated by the European Medical Device Regulation (EU MDR 2017/745). The transition from the legacy MDD framework has introduced protracted review intervals due to Notified Body capacity constraints, demanding rigorous post-market clinical follow-up (PMCF) studies, periodic safety update reports (PSUR), and traceable registration via the European Databank on Medical Devices (EUDAMED). These compliance requirements have elevated developmental expenditures, accelerating portfolio rationalization among smaller European original equipment manufacturers (OEMs). Concurrently, European health authorities are enacting rigorous EcoDesign sustainability mandates and integrating data frameworks under the European Health Data Space (EHDS), requiring C-arm architectures to feature transparent energy profiles and secure DICOM/HL7 enterprise interoperability.
● Latin America
Latin America is an emerging adoption territory. Capital investments are concentrated in public health network expansion and private integrated healthcare delivery networks across Brazil, Mexico, Colombia, Chile, and Argentina. The clinical installed base has historically relied on refurbished or legacy Image Intensifier platforms; however, public health modernizations are accelerating transitions directly to cost-effective flat-panel detector systems.
Regulatory oversight is driven by regional authorities including ANVISA in Brazil and COFEPRIS in Mexico. Given regional currency fluctuations and constrained capital equipment budgets, multinational manufacturers increasingly partner with domestic entities for regional knock-down assembly, localized maintenance servicing, and distributed distribution networks to navigate import tariffs and procurement restrictions.
● Middle East and Africa
The Middle East and Africa (MEA) territory exhibits divergent market characteristics, ranging from state-of-the-art hybrid digital suites in the Gulf Cooperation Council (GCC) to foundational equipment deficits across Sub-Saharan Africa.
In Saudi Arabia, the Vision 2030 Health Sector Transformation Program is funding extensive greenfield hospital constructions, specialized oncology facilities, and advanced trauma centers, fueling demand for top-tier fixed interventional suites and robotic mobile 3D systems. Similar modernization programs are active across the United Arab Emirates and Qatar. Conversely, broad swathes of the African continent experience low per-capita fluoroscopic density, relying heavily on international health development loans, bilateral government tenders, and trade agreements. Exporters from China and South Korea have capitalized on these dynamics, leveraging cost-to-performance advantages to secure institutional tenders across North and East Africa.
COMPETITIVE PROFILES: MARKET LEADERS & SPECIALIZED OEMS
● GE HealthCare: GE HealthCare maintains a global market share anchor through its OEC brand, long recognized as an industry benchmark across orthopedic, trauma, and endovascular surgical guidance. GE leverages in-house complementary metal-oxide-semiconductor (CFD) flat detectors across its lineup. The premium OEC 3D platform bridges mobile fluoroscopy with cone-beam CT visualization, generating a 19 cm x 19 cm x 19 cm volumetric field of view that integrates into open-architecture robotic spinal and orthopedic navigation systems. The vascular workhorse OEC Elite CFD features 21 cm x 21 cm and 31 cm x 31 cm active detector options, high dynamic range imaging, and dedicated vascular software with digital pen and live zoom functionalities. For space-constrained sites, the OEC One CFD packages the display monitor directly onto an articulating arm attached to the gantry chassis, eliminating external monitor cart footprints in ASCs and pain clinics.
● Siemens Healthineers: Siemens Healthineers approaches the C-arm market via two primary business units: the Advanced Therapies segment (governing the high-margin Artis and floor/ceiling robotic Pheno fixed interventional DSA platforms) and its mobile surgical Cios division. The mobile portfolio is led by the Cios Spin, an advanced intraoperative 3D CBCT platform equipped with automated Screw Scout software that auto-detects pedicle screw hardware within volumetric slices. The Cios Alpha provides high-output fluoroscopy via an integrated 25 kW high-frequency generator supported by an on-board Energy Storage Unit (ESU), enabling full-power pulsed exposure from standard 15-amp electrical wall lines during prolonged endovascular procedures. Imaging chains utilize proprietary Retina CMOS detectors and IDEAL automatic exposure control algorithms, which optimize beam hardening and pulse width to enforce low radiation levels.
● Royal Philips: Philips organizes its fluoroscopic portfolio under its Image Guided Therapy (IGT) division, anchored by the fixed Azurion suite and the mobile Zenition platform. The Zenition series (Zenition 10, 30, 50, 70, and the fully motorized Zenition 90 Motorized) features the standardized Unify touchscreen interface shared across the gantry chassis, mobile viewing station, and sterile tableside modules, minimizing technologist training friction. The Zenition 90 Motorized provides table-side multi-axis orbital control designed to give interventionalists operational autonomy during EVAR, TEVAR, and cardiovascular cases. The proprietary DoseWise architecture integrates real-time scatter dose indicators, intelligent beam-hardening copper filters, and automated collimation positioning without preliminary radiation exposure via the ClearGuide interface.
● Ziehm Imaging GmbH: Ziehm Imaging operates as an engineering specialist dedicated solely to mobile surgical fluoroscopy platforms, driving technological innovation in mobile flat-panel imaging, intraoperative 3D CBCT, and hybrid OR integration. The flagship Ziehm Vision RFD 3D executes automated motorized isocentric sweeps to construct 16 cm x 16 cm x 16 cm or extended cylindrical volumes, linking to leading surgical navigation platforms (e.g., Brainlab, Stryker, Medtronic) via its NaviPort interface. The Vision RFD Hybrid Edition functions as a viable, mobile alternative to fixed hybrid rooms, delivering 25 kW generator performance backed by Advanced Active Cooling (AAC), a closed-loop liquid thermal management system that circulates liquid coolant through the monoblock and tube housing to eliminate thermal shutdown risks. Through its OrthoScan subsidiary, the company maintains market leadership in mini C-arms via the TAU platform (TAU 1512, 1515, 2020) for hand and extremity surgery.
● The rest of companies covered in the report: Fujifilm Healthcare, Shimadzu Corporation, Shanghai United Imaging Healthcare, Eurocolumbus, TECHNIX S.P.A., INTERMEDICAL S.r.l., Genoray Corporation, SG Healthcare, Nanjing Perlove Medical Equipment Co., Ltd., Shenzhen Angell Technology, Neusoft Medical Systems, Beijing Wandong Medical, and Shinva Medical Instrument Co., Ltd.
● Industry Consolidation & Line Phase-Out Context:
The competitive matrix has undergone notable shifts in the specialized extremity sector. Hologic, which maintained an established presence in extremity surgery via its Fluoroscan Insight FD mini C-arm line, formally initiated the phase-out of the Fluoroscan portfolio effective in 2026. This tactical retreat creates an immediate vacuum across the dedicated mini C-arm landscape, prompting surgical centers to transition toward compact, full-size mobile FPD platforms (such as the OEC One or Zenition 10) or specialized platforms from pure-play vendors like Ziehm/OrthoScan.
OPPORTUNITIES & CHALLENGES
● Strategic Growth Catalysts
1. Ambulatory Surgery Center (ASC) Capital Infiltration:
The aggressive migration of high-margin orthopedic joint replacements, complex spine fusions, and peripheral vascular procedures from traditional inpatient environments to outpatient ASCs presents an addressable market expansion vector. ASC operators function under strict capital allocation frameworks: they demand agile, multi-specialty mobile C-arms featuring integrated monitor architecture, sub-two-minute boot cycles, and intuitive tablet-style interfaces that reduce staffing overheads and room turnover times.
2. 3D Intraoperative Fluoroscopy Convergence with Robotics:
Surgical navigation is shifting from standalone optical tracking systems to interconnected ecosystems where 3D isocentric mobile C-arms serve as the primary intraoperative imaging engine. Surgeons utilizing robotic spinal assistants require real-time 3D volumetric verification to confirm the safety of pedicle hardware before wound closure. Manufacturers offering open-source API communications that allow plug-and-play data exchanges between 3D C-arms and third-party robotic consoles will capture premium pricing tiers.
3. Deep Learning Dose Reduction Architectures:
Historically, radiation dose reduction compromised spatial image resolution. The integration of edge-computed artificial intelligence denoising platforms (such as Burst Denoise and adaptive image processing filters) breaks this paradigm. By analyzing structural patterns across spatial and temporal domains, deep learning engines synthesize pristine clinical frames from low-dose fluoroscopic bursts. Given heightened institutional liability regarding cumulative radiation exposure to surgical staff, validated low-dose systems are compelling justification for fleet replacement cycles.
● Systemic Headwinds & Risk Factors
1. Margin Compression via Centralized Procurement:
The proliferation of centralized Volume-Based Procurement (VBP) across China, aggressive GPO aggregate bidding across North America, and regional tender consortiums in the European Union are systematically compressing hardware gross margins. When public and private payers treat baseline fluoroscopy as a commoditized utility, hardware margins decline. OEMs must either reduce upstream manufacturing costs via vertical sensor fabrication or offset hardware margin compression by introducing recurring subscription-based software feature licensing.
2. Specialized Component Supply Bottlenecks:
The global production of high-duty-cycle surgical C-arms relies on an upstream supply chain concentrated among a narrow cohort of specialized suppliers. The availability of liquid-cooled rotating anode inserts, high-voltage oil-filled monoblock transformers, cesium iodide scintillators, and medical-grade carbon-fiber grids remains subject to component shortages and geopolitical trade restrictions. Disruptions across lead times for advanced integrated circuits or precision raw materials immediately limit OEM assembly line throughput.
3. Regulatory Compliance Friction and Capital Overheads:
The persistent regulatory friction introduced by the EU MDR framework in Europe, coupled with evolving FDA cybersecurity documentation rules and China's tightened domestic registration guidelines, has lengthened commercialization timelines. Developing and maintaining compliance dossiers requires capital expenditures that disadvantage mid-tier and niche equipment manufacturers, accelerating industry consolidation and product line phase-outs.
1.1 Study Scope and Medical Imaging Sector Definition 1
1.2 Research Methodology and Bottom-Up Triangulation Logic 2
1.3 Primary Data Sources, Key Opinion Leader (KOL) Interviews, and Field Validations 3
1.4 Secondary Information Repositories and Regulatory Databases 4
1.5 Analytical Assumptions and Currency Conversion Matrix 5
1.6 Standard Nomenclature and Abbreviations 6
Chapter 2 Global C-Arm X-Ray System Market Trajectory (2021-2031) 7
2.1 Global Market Sizing and Revenue Trajectory (2021-2031) 7
2.2 Global Sales Volume and Installed Base Expansion (2021-2031) 9
2.3 Average Selling Price (ASP) Dynamics and Technology Premium Shifts 11
2.4 Macroeconomic Headwinds, Capital Budget Cycles, and Inflationary Pressures 13
Chapter 3 Value Chain Architecture and Upstream Component Ecosystem 15
3.1 Comprehensive Industry Value Chain and Value Migration Dynamics 15
3.2 Upstream Component Ecosystem: Flat Panel Detectors (FPD) vs. Image Intensifiers (II) 17
3.3 High-Voltage X-Ray Generators and High-Heat Capacity Anode Tubes 19
3.4 Robotic Articulation, C-Arm Gantry Engineering, and Counterbalancing Systems 20
3.5 Image Processing Engines, Real-Time AI Denoising, and Spatial Navigation Software 21
3.6 Downstream Procurement Channels: Group Purchasing Organizations (GPOs) and Hospital Tenders 22
Chapter 4 Global C-Arm X-Ray System Market by Configuration and Architecture 23
4.1 Architectural Breakdown: Market Share and Volume Analysis 23
4.2 Mobile C-Arm Systems 25
4.2.1 Full-Size Mobile Multipurpose C-Arms 26
4.2.2 Compact and Mini C-Arms (Extremities and Outpatient Surgery) 28
4.2.3 3D Robotic and Intraoperative CT-Equivalent Mobile Systems 29
4.3 Fixed C-Arm Systems 30
4.3.1 Ceiling-Suspended Interventional Fluoroscopy Suites 31
4.3.2 Floor-Mounted Angiography and Hybrid Operating Suite Solutions 32
Chapter 5 Global C-Arm X-Ray System Market by Clinical Application 33
5.1 Sector Breakdown: Consumption Distribution and Growth Trajectory 33
5.2 Human Clinical Healthcare Applications 35
5.2.1 Orthopedics and Complex Spine Interventions 36
5.2.2 Cardiovascular and Peripheral Vascular Surgery 38
5.2.3 Neurological Interventions and Craniofacial Procedures 39
5.2.4 Traumatology, Urology, and Oncology Interventions 40
5.2.5 Outpatient Ambulatory Surgery Centers (ASCs) and Specialized Clinics 41
5.3 Veterinary Medicine & Animal Healthcare Applications 42
5.3.1 Equine and Large Animal Diagnostic Imaging 42
5.3.2 Companion Animal Surgical Centers and Veterinary Specialty Hospitals 43
Chapter 6 Global Cross-Border Trade Flows, Manufacturing Hubs, and Regulatory Landscape 44
6.1 Primary Manufacturing and Export Centers (Germany, United States, Japan, South Korea, China, Italy) 44
6.2 High-Import Demand Territories and Supply Chain Vulnerabilities 46
6.3 Global Trade Policies, Customs Tariffs, and Harmonized System (HS) Tracking 48
6.4 Regulatory Clearances: US FDA 510(k), EU MDR Class IIb, and NMPA Approvals 50
Chapter 7 North America C-Arm X-Ray System Market Analysis 52
7.1 Regional Overview: Market Value, Volume, and Demand Dynamics (2021-2031) 52
7.2 United States: Shift toward Outpatient ASCs and Advanced 3D Hybrid Suites 55
7.3 Canada: Public Hospital Equipment Replacement Cycles and Infrastructure Grants 58
Chapter 8 Europe C-Arm X-Ray System Market Analysis 61
8.1 Regional Overview: High-Tier Engineering Standards and Replacement Demand (2021-2031) 61
8.2 Germany: High-Precision Clinical Standards and Advanced Manufacturing Clusters 64
8.3 Italy: Specialized Engineering Fabricators and Procurement Patterns 66
8.4 France: Public-Private Healthcare Procurement and Interventional Oncology Adoption 67
8.5 United Kingdom: National Health Service (NHS) Tender Dynamics and Diagnostic Backlogs 68
8.6 Rest of Europe: Benelux, Nordic Clusters, and Spain 69
Chapter 9 Asia-Pacific C-Arm X-Ray System Market Analysis 71
7.1 Regional Overview: High-Volume Adoption and Tiered Clinical Demands (2021-2031) 71
9.2 China: Domestic Substitution Policies, Tier-3 Hospital Demand, and Volume Tenders 74
9.3 Japan: Aging Demographics, High-Density Clinical Infrastructure, and Micro-Surgical Suites 76
9.4 South Korea: High Technological Penetration and Specialized Orthopedic Hospitals 78
9.5 India: Secondary City Diagnostic Expansion and Private Healthcare Modernization 79
9.6 Rest of Asia-Pacific: Australia, New Zealand, and Southeast Asian Procurement Hubs 80
Chapter 10 Latin America and Middle East & Africa Market Analysis 81
10.1 Latin America: Macroeconomic Volatility, Currency Devaluations, and Private Healthcare 81
10.1.1 Brazil: Dominant Market Dynamics and Local Assembly Shifts 82
10.1.2 Mexico: Cross-Border Medical Tourism and Outpatient Surgery Expansion 84
10.2 Middle East & Africa: High-End Infrastructure Projects vs. Low-Cost Mobile Needs 85
10.2.1 Gulf Cooperation Council (GCC): Smart Hospitals and Hybrid Operating Environments 86
10.2.2 South Africa: Private Hospital Networks and Public Healthcare Equipment Deficits 87
Chapter 11 Market Competition Matrix and Strategic Benchmarking 88
11.1 Global Competitive Landscape: Revenue Ranking and Tier Structure 88
11.2 Market Share Concentration (CR4, CR8, and Herfindahl-Hirschman Index Analysis) 89
11.3 Key Strategic Moves: Mergers, Acquisitions, Component Sourcing Partnerships 90
11.4 Entry Barriers: Proprietary Tube-Detector Integration, IP Patents, and Service Networks 91
Chapter 12 Corporate Intelligence: Major Global C-Arm Manufacturers 93
12.1 GE HealthCare 94
12.1.1 Corporate Profile and Medical Imaging Strategy 94
12.1.2 Product Portfolio: OEC Series Mobile C-Arms and Fixed Fluoroscopy Suites 94
12.1.3 Operational Performance: C-Arm X-Ray System Sales, Price, Cost, and Margin (2021-2026) 95
12.1.4 Strategic SWOT Assessment and Technology Roadmap 96
12.2 Siemens Healthineers 97
12.2.1 Corporate Profile and Image-Guided Therapy Positioning 97
12.2.2 Product Portfolio: Cios Family (Mobile) and Artis Series (Fixed Interventional) 97
12.2.3 Operational Performance: C-Arm X-Ray System Sales, Price, Cost, and Margin (2021-2026) 98
12.2.4 Strategic SWOT Assessment and Digital Ecosystem Integration 99
12.3 Philips 100
12.3.1 Corporate Profile and Precision Diagnosis Division Structure 100
12.3.2 Product Portfolio: Zenition Mobile C-Arms and Azurion Interventional Systems 100
12.3.3 Operational Performance: C-Arm X-Ray System Sales, Price, Cost, and Margin (2021-2026) 101
12.3.4 Strategic SWOT Assessment and Service Lifecycle Agreements 102
12.4 Ziehm Imaging GmbH 103
12.4.1 Corporate Profile and Dedicated Mobile C-Arm Specialization 103
12.4.2 Product Portfolio: Ziehm Vision, Solo, and RFD 3D Navigation-Ready Systems 103
12.4.3 Operational Performance: C-Arm X-Ray System Sales, Price, Cost, and Margin (2021-2026) 104
12.4.4 Strategic SWOT Assessment and Intraoperative 3D Innovation 105
12.5 Fujifilm 106
12.5.1 Corporate Profile and Healthcare Imaging Architecture 106
12.5.2 Product Portfolio: Persona Surgical C-Arm Systems and Flat-Panel Configurations 106
12.5.3 Operational Performance: C-Arm X-Ray System Sales, Price, Cost, and Margin (2021-2026) 107
12.5.4 Strategic SWOT Assessment and Distribution Synergies 108
12.6 Shimadzu 109
12.6.1 Corporate Profile and Diagnostic Medical Systems Structure 109
12.6.2 Product Portfolio: Trinias Interventional Systems and Mobile Surgical C-Arms 109
12.6.3 Operational Performance: C-Arm X-Ray System Sales, Price, Cost, and Margin (2021-2026) 110
12.6.4 Strategic SWOT Assessment and Dose Management Technologies 111
12.7 Genoray 112
12.7.1 Corporate Profile and Global Export Network 112
12.7.2 Product Portfolio: Oscar and Zen Series Surgical and Veterinary C-Arms 112
12.7.3 Operational Performance: C-Arm X-Ray System Sales, Price, Cost, and Margin (2021-2026) 113
12.7.4 Strategic SWOT Assessment and Cost-Competitive Engineering 114
12.8 United Imaging Healthcare 115
12.8.1 Corporate Profile and Advanced System R&D Capabilities 115
12.8.2 Product Portfolio: uFC and High-End Interventional Fixed and Mobile Solutions 115
12.8.3 Operational Performance: C-Arm X-Ray System Sales, Price, Cost, and Margin (2021-2026) 116
12.8.4 Strategic SWOT Assessment and High-End Market Disruption 117
12.9 SG Healthcare 118
12.9.1 Corporate Profile and Specialized Diagnostic Solutions 118
12.9.2 Product Portfolio: C-Arm Product Lines for Surgical and Outpatient Settings 118
12.9.3 Operational Performance: C-Arm X-Ray System Sales, Price, Cost, and Margin (2021-2026) 119
12.9.4 Strategic SWOT Assessment and Emerging Market Positioning 120
12.10 Neusoft Medical Systems 121
12.10.1 Corporate Profile and Global Medical Device Footprint 121
12.10.2 Product Portfolio: NeuViz Interventional Suites and Mobile Fluoroscopy Systems 121
12.10.3 Operational Performance: C-Arm X-Ray System Sales, Price, Cost, and Margin (2021-2026) 122
12.10.4 Strategic SWOT Assessment and Cloud-Integrated Diagnostics 123
12.11 Shinva Medical Instrument Co. Ltd. 124
12.11.1 Corporate Profile and Medical Equipment Manufacturing Base 124
12.11.2 Product Portfolio: Large-Scale Angiography Suites and Surgical C-Arm Devices 124
12.11.3 Operational Performance: C-Arm X-Ray System Sales, Price, Cost, and Margin (2021-2026) 125
12.11.4 Strategic SWOT Assessment and Public Hospital Supply Chain 126
12.12 Beijing Wandong Medical 127
12.12.1 Corporate Profile and Midea Healthcare Ecosystem Affiliation 127
12.12.2 Product Portfolio: Fixed Interventional Angiography Systems and Mobile C-Arms 127
12.12.3 Operational Performance: C-Arm X-Ray System Sales, Price, Cost, and Margin (2021-2026) 128
12.12.4 Strategic SWOT Assessment and Mass-Market Penetration 129
12.13 Nanjing Perlove Medical Equipment Co. Ltd. 130
12.13.1 Corporate Profile and Core Radiographic Equipment Focus 130
12.13.2 Product Portfolio: Integrated Flat-Panel Mobile C-Arms and 3D Systems 130
12.13.3 Operational Performance: C-Arm X-Ray System Sales, Price, Cost, and Margin (2021-2026) 131
12.13.4 Strategic SWOT Assessment and High-Volume Manufacturing Margins 132
12.14 Shenzhen Angell Technology 133
12.14.1 Corporate Profile and Digital Radiography Specialization 133
12.14.2 Product Portfolio: Dynamic FPD Mobile C-Arm Imaging Solutions 133
12.14.3 Operational Performance: C-Arm X-Ray System Sales, Price, Cost, and Margin (2021-2026) 134
12.14.4 Strategic SWOT Assessment and Grassroots Tier Clinic Expansion 135
12.15 Eurocolumbus 136
12.15.1 Corporate Profile and Italian Precision Imaging Heritage 136
12.15.2 Product Portfolio: Alien Series Advanced High-End Surgical Mobile C-Arms 136
12.15.3 Operational Performance: C-Arm X-Ray System Sales, Price, Cost, and Margin (2021-2026) 137
12.15.4 Strategic SWOT Assessment and Tailored European Manufacturing 138
12.16 TECHNIX S.P.A. 139
12.16.1 Corporate Profile and OEM Radiology Engineering Specialization 139
12.16.2 Product Portfolio: Multipurpose Surgical C-Arms and OEM Subassemblies 139
12.16.3 Operational Performance: C-Arm X-Ray System Sales, Price, Cost, and Margin (2021-2026) 140
12.16.4 Strategic SWOT Assessment and White-Label Partnership Network 141
12.17 INTERMEDICAL S.r.l. 142
12.17.1 Corporate Profile and I.M.D. Generators Holding Architecture 142
12.17.2 Product Portfolio: Radius Family of Surgical Mobile C-Arm Fluoroscopes 142
12.17.3 Operational Performance: C-Arm X-Ray System Sales, Price, Cost, and Margin (2021-2026) 143
12.17.4 Strategic SWOT Assessment and Global Niche Distribution 144
Chapter 13 Future Strategic Outlook and Transformative Technology Horizons (2027-2031) 145
13.1 AI-Driven Real-Time Dose Reduction and Automated Anatomical Centering 145
13.2 Convergence of 3D Mobile Imaging with Augmented Reality Surgical Guidance 146
13.3 Total Cost of Ownership Optimization and As-a-Service Capital Models 147
13.4 Strategic Imperatives for Established MedTech Giants and Agile Challengers 148
Table 2 Standard Medical Imaging Acronyms and Technical Nomenclature 6
Table 3 Global C-Arm X-Ray System Market Revenue and Year-over-Year Growth (2021-2031) 8
Table 4 Global C-Arm X-Ray System Unit Shipments and Year-over-Year Growth (2021-2031) 10
Table 5 Global C-Arm X-Ray System Average Selling Price Benchmark by Product Tier (2021-2031) 12
Table 6 Core Flat Panel Detector Technologies: Amorphous Silicon vs. CMOS Cost and Performance Comparison 18
Table 7 Global C-Arm X-Ray System Revenue Breakdown by System Architecture (2021-2031) 23
Table 8 Global C-Arm X-Ray System Unit Sales Breakdown by System Architecture (2021-2031) 24
Table 9 Global Mobile C-Arm System Revenue by Sub-Segment (2021-2031) 25
Table 10 Global Fixed C-Arm System Revenue by Sub-Segment (2021-2031) 30
Table 11 Global C-Arm X-Ray System Market Size by Downstream Application (2021-2031) 34
Table 12 Global C-Arm X-Ray System Unit Demand in Human Healthcare by Clinical Specialization (2021-2031) 35
Table 13 Global C-Arm X-Ray System Market Size in Veterinary Medicine by Animal Category (2021-2031) 42
Table 14 Major Manufacturing Hubs: C-Arm X-Ray System Export Volume and Value (2021-2026) 45
Table 15 Top Importing Nations: C-Arm X-Ray System Inbound Shipments and Value (2021-2026) 47
Table 16 North America C-Arm X-Ray System Market Revenue and Volume by Product Type (2021-2031) 53
Table 17 North America C-Arm X-Ray System Market Revenue by Country (2021-2031) 54
Table 18 United States C-Arm X-Ray System Market Breakdown by System Architecture (2021-2031) 56
Table 19 United States C-Arm X-Ray System Market Breakdown by Care Facility Setting (2021-2031) 57
Table 20 Canada C-Arm X-Ray System Market Breakdown by System Architecture (2021-2031) 59
Table 21 Europe C-Arm X-Ray System Market Revenue and Volume by Product Type (2021-2031) 62
Table 22 Europe C-Arm X-Ray System Market Revenue by Country (2021-2031) 63
Table 23 Germany C-Arm X-Ray System Market Breakdown by Architecture (2021-2031) 65
Table 24 Italy C-Arm X-Ray System Market Breakdown by Architecture (2021-2031) 66
Table 25 France C-Arm X-Ray System Market Breakdown by Architecture (2021-2031) 67
Table 26 United Kingdom C-Arm X-Ray System Market Breakdown by Architecture (2021-2031) 68
Table 27 Asia-Pacific C-Arm X-Ray System Market Revenue and Volume by Product Type (2021-2031) 72
Table 28 Asia-Pacific C-Arm X-Ray System Market Revenue by Country (2021-2031) 73
Table 29 China C-Arm X-Ray System Market Breakdown by Architecture (2021-2031) 75
Table 30 Japan C-Arm X-Ray System Market Breakdown by Architecture (2021-2031) 77
Table 31 South Korea C-Arm X-Ray System Market Breakdown by Architecture (2021-2031) 78
Table 32 India C-Arm X-Ray System Market Breakdown by Architecture (2021-2031) 79
Table 33 Latin America C-Arm X-Ray System Market Revenue by Country (2021-2031) 82
Table 34 Brazil C-Arm X-Ray System Market Breakdown by Architecture (2021-2031) 83
Table 35 Mexico C-Arm X-Ray System Market Breakdown by Architecture (2021-2031) 84
Table 36 Middle East & Africa C-Arm X-Ray System Market Revenue by Sub-Region (2021-2031) 86
Table 37 Global Top 10 C-Arm X-Ray System Manufacturers Ranked by Revenue (2025-2026) 88
Table 38 GE HealthCare C-Arm X-Ray System Sales, Price, Cost, and Gross Profit Margin (2021-2026) 95
Table 39 Siemens Healthineers C-Arm X-Ray System Sales, Price, Cost, and Gross Profit Margin (2021-2026) 98
Table 40 Philips C-Arm X-Ray System Sales, Price, Cost, and Gross Profit Margin (2021-2026) 101
Table 41 Ziehm Imaging GmbH C-Arm X-Ray System Sales, Price, Cost, and Gross Profit Margin (2021-2026) 104
Table 42 Fujifilm C-Arm X-Ray System Sales, Price, Cost, and Gross Profit Margin (2021-2026) 107
Table 43 Shimadzu C-Arm X-Ray System Sales, Price, Cost, and Gross Profit Margin (2021-2026) 110
Table 44 Genoray C-Arm X-Ray System Sales, Price, Cost, and Gross Profit Margin (2021-2026) 113
Table 45 United Imaging Healthcare C-Arm X-Ray System Sales, Price, Cost, and Gross Profit Margin (2021-2026) 116
Table 46 SG Healthcare C-Arm X-Ray System Sales, Price, Cost, and Gross Profit Margin (2021-2026) 119
Table 47 Neusoft Medical Systems C-Arm X-Ray System Sales, Price, Cost, and Gross Profit Margin (2021-2026) 122
Table 48 Shinva Medical Instrument Co. Ltd. C-Arm X-Ray System Sales, Price, Cost, and Gross Profit Margin (2021-2026) 125
Table 49 Beijing Wandong Medical C-Arm X-Ray System Sales, Price, Cost, and Gross Profit Margin (2021-2026) 128
Table 50 Nanjing Perlove Medical Equipment Co. Ltd. C-Arm X-Ray System Sales, Price, Cost, and Gross Profit Margin (2021-2026) 131
Table 51 Shenzhen Angell Technology C-Arm X-Ray System Sales, Price, Cost, and Gross Profit Margin (2021-2026) 134
Table 52 Eurocolumbus C-Arm X-Ray System Sales, Price, Cost, and Gross Profit Margin (2021-2026) 137
Table 53 TECHNIX S.P.A. C-Arm X-Ray System Sales, Price, Cost, and Gross Profit Margin (2021-2026) 140
Table 54 INTERMEDICAL S.r.l. C-Arm X-Ray System Sales, Price, Cost, and Gross Profit Margin (2021-2026) 143
Figure 1 C-Arm X-Ray System Research Methodology Architecture 2
Figure 2 Global C-Arm X-Ray System Market Revenue and Projection (2021-2031) 8
Figure 3 Global C-Arm X-Ray System Unit Volume and Installed Base Growth (2021-2031) 10
Figure 4 Global Average Selling Price Trajectory Across Fixed vs. Mobile C-Arms (2021-2031) 12
Figure 5 C-Arm X-Ray System End-to-End Value Chain Analysis and Margin Distribution 16
Figure 6 Flat Panel Detector Conversion Cycle: Market Share of FPD vs. Image Intensifier Units (2021-2031) 18
Figure 7 Global C-Arm Market Value Share by System Architecture (2021 vs 2026 vs 2031) 24
Figure 8 Mobile C-Arm Market Revenue by Product Segment (2021-2031) 26
Figure 9 Fixed C-Arm Market Revenue by Installation Configuration (2021-2031) 31
Figure 10 Global C-Arm Market Share Breakdown by Clinical Application (2026) 34
Figure 11 Human vs. Veterinary C-Arm Market Value Growth Divergence (2021-2031) 36
Figure 12 Global Outpatient ASC vs. Inpatient Operating Room C-Arm Demand Split (2021-2031) 41
Figure 13 Trade Balance Mapping: Primary Net Exporters and Importers of C-Arm Systems (2026) 46
Figure 14 Global Regional Revenue Share Comparison (2021 vs 2026 vs 2031) 52
Figure 15 North America C-Arm X-Ray System Market Size and Year-over-Year Growth (2021-2031) 54
Figure 16 United States Surgical C-Arm Volume Allocation Across ASCs vs Hospitals (2021-2031) 57
Figure 17 Europe C-Arm X-Ray System Market Size and Growth Trajectory (2021-2031) 62
Figure 18 Germany C-Arm Market Volume and High-End 3D Share (2021-2031) 65
Figure 19 Asia-Pacific C-Arm X-Ray System Revenue and Regional Contribution (2021-2031) 72
Figure 20 China C-Arm Domestic Brand Replacement Rate vs Multinational Brands (2021-2031) 75
Figure 21 Japan C-Arm X-Ray System Market Volume Forecast (2021-2031) 77
Figure 22 Latin America and Middle East & Africa C-Arm Market Share Comparison (2026) 81
Figure 23 Global C-Arm X-Ray System Market Share Concentration (CR4 vs Other Players) (2026) 89
Figure 24 GE HealthCare C-Arm X-Ray System Market Share (2021-2026) 96
Figure 25 Siemens Healthineers C-Arm X-Ray System Market Share (2021-2026) 99
Figure 26 Philips C-Arm X-Ray System Market Share (2021-2026) 102
Figure 27 Ziehm Imaging GmbH C-Arm X-Ray System Market Share (2021-2026) 105
Figure 28 Fujifilm C-Arm X-Ray System Market Share (2021-2026) 108
Figure 29 Shimadzu C-Arm X-Ray System Market Share (2021-2026) 111
Figure 30 Genoray C-Arm X-Ray System Market Share (2021-2026) 114
Figure 31 United Imaging Healthcare C-Arm X-Ray System Market Share (2021-2026) 117
Figure 32 SG Healthcare C-Arm X-Ray System Market Share (2021-2026) 120
Figure 33 Neusoft Medical Systems C-Arm X-Ray System Market Share (2021-2026) 123
Figure 34 Shinva Medical Instrument Co. Ltd. C-Arm X-Ray System Market Share (2021-2026) 126
Figure 35 Beijing Wandong Medical C-Arm X-Ray System Market Share (2021-2026) 129
Figure 36 Nanjing Perlove Medical Equipment Co. Ltd. C-Arm X-Ray System Market Share (2021-2026) 132
Figure 37 Shenzhen Angell Technology C-Arm X-Ray System Market Share (2021-2026) 135
Figure 38 Eurocolumbus C-Arm X-Ray System Market Share (2021-2026) 138
Figure 39 TECHNIX S.P.A. C-Arm X-Ray System Market Share (2021-2026) 141
Figure 40 INTERMEDICAL S.r.l. C-Arm X-Ray System Market Share (2021-2026) 144
Figure 41 Strategic Decision Matrix: Technology Adoption vs. Capital Expenditure Horizon 148
Research Methodology
- Market Estimated Methodology:
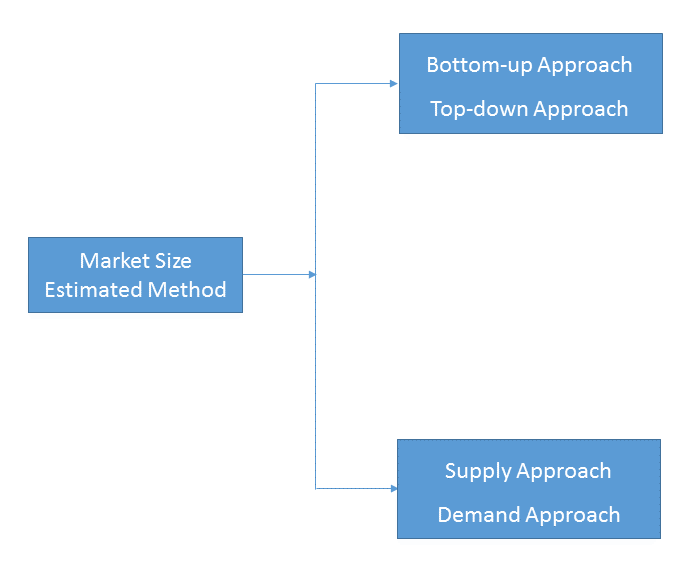
Bottom-up & top-down approach, supply & demand approach are the most important method which is used by HDIN Research to estimate the market size.
1)Top-down & Bottom-up Approach
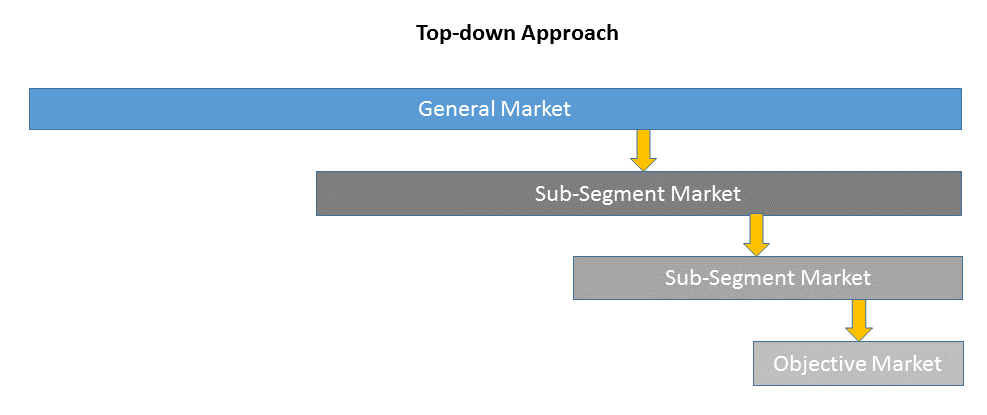
Top-down approach uses a general market size figure and determines the percentage that the objective market represents.
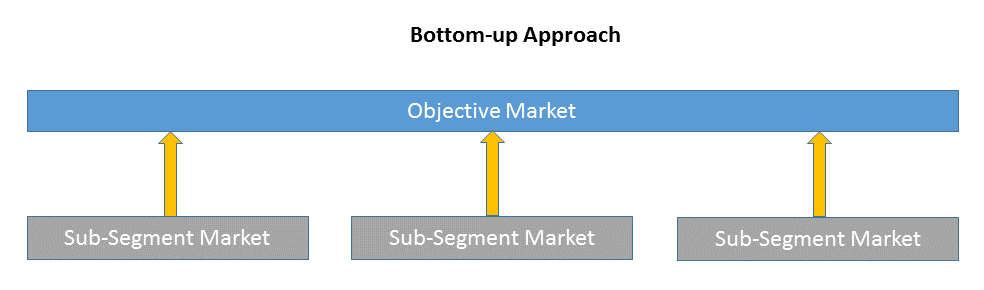
Bottom-up approach size the objective market by collecting the sub-segment information.
2)Supply & Demand Approach
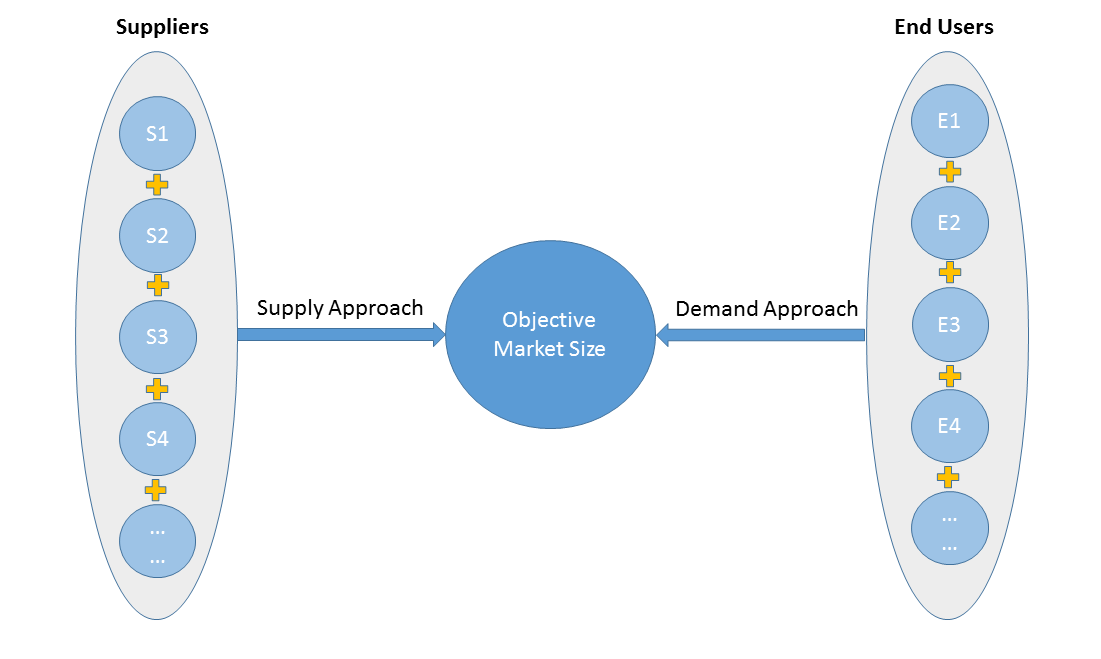
Supply approach is based on assessments of the size of each competitor supplying the objective market.
Demand approach combine end-user data within a market to estimate the objective market size. It is sometimes referred to as bottom-up approach.
- Forecasting Methodology
- Numerous factors impacting the market trend are considered for forecast model:
- New technology and application in the future;
- New project planned/under contraction;
- Global and regional underlying economic growth;
- Threatens of substitute products;
- Industry expert opinion;
- Policy and Society implication.
- Analysis Tools
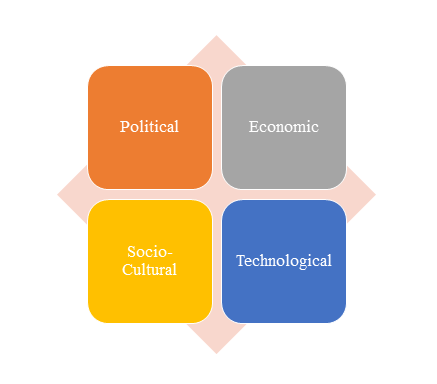
1)PEST Analysis
PEST Analysis is a simple and widely used tool that helps our client analyze the Political, Economic, Socio-Cultural, and Technological changes in their business environment.
- Benefits of a PEST analysis:
- It helps you to spot business opportunities, and it gives you advanced warning of significant threats.
- It reveals the direction of change within your business environment. This helps you shape what you’re doing, so that you work with change, rather than against it.
- It helps you avoid starting projects that are likely to fail, for reasons beyond your control.
- It can help you break free of unconscious assumptions when you enter a new country, region, or market; because it helps you develop an objective view of this new environment.
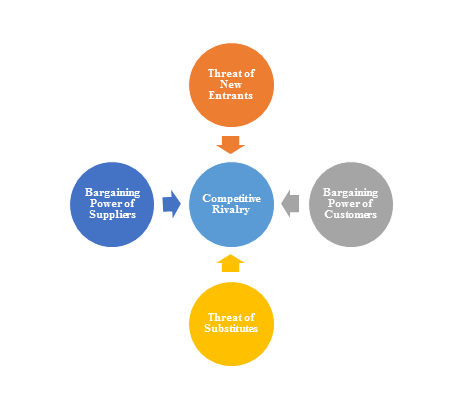
2)Porter’s Five Force Model Analysis
The Porter’s Five Force Model is a tool that can be used to analyze the opportunities and overall competitive advantage. The five forces that can assist in determining the competitive intensity and potential attractiveness within a specific area.
- Threat of New Entrants: Profitable industries that yield high returns will attract new firms.
- Threat of Substitutes: A substitute product uses a different technology to try to solve the same economic need.
- Bargaining Power of Customers: the ability of customers to put the firm under pressure, which also affects the customer's sensitivity to price changes.
- Bargaining Power of Suppliers: Suppliers of raw materials, components, labor, and services (such as expertise) to the firm can be a source of power over the firm when there are few substitutes.
- Competitive Rivalry: For most industries the intensity of competitive rivalry is the major determinant of the competitiveness of the industry.
3)Value Chain Analysis
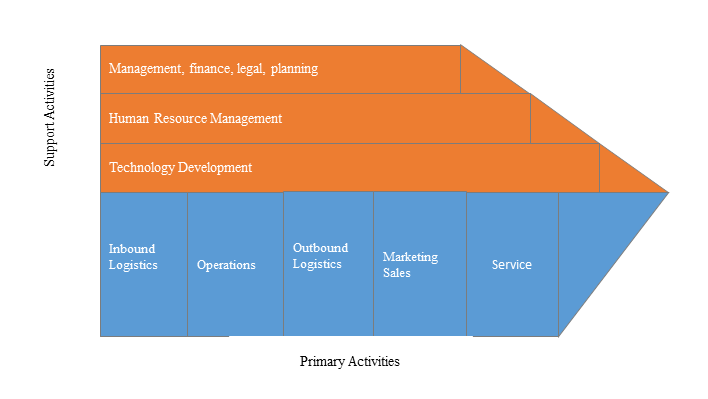
Value chain analysis is a tool to identify activities, within and around the firm and relating these activities to an assessment of competitive strength. Value chain can be analyzed by primary activities and supportive activities. Primary activities include: inbound logistics, operations, outbound logistics, marketing & sales, service. Support activities include: technology development, human resource management, management, finance, legal, planning.
4)SWOT Analysis
SWOT analysis is a tool used to evaluate a company's competitive position by identifying its strengths, weaknesses, opportunities and threats. The strengths and weakness is the inner factor; the opportunities and threats are the external factor. By analyzing the inner and external factors, the analysis can provide the detail information of the position of a player and the characteristics of the industry.
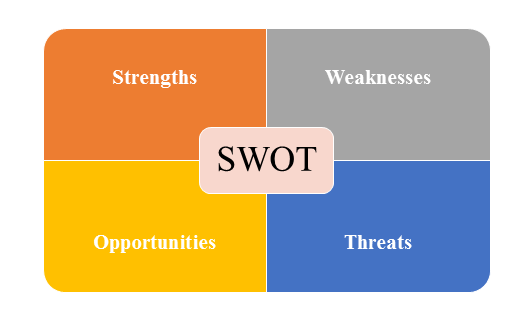
- Strengths describe what the player excels at and separates it from the competition
- Weaknesses stop the player from performing at its optimum level.
- Opportunities refer to favorable external factors that the player can use to give it a competitive advantage.
- Threats refer to factors that have the potential to harm the player.
- Data Sources
| Primary Sources | Secondary Sources |
|---|---|
| Face to face/Phone Interviews with market participants, such as: Manufactures; Distributors; End-users; Experts. Online Survey |
Government/International Organization Data: Annual Report/Presentation/Fact Book Internet Source Information Industry Association Data Free/Purchased Database Market Research Report Book/Journal/News |