Diagnostic Ultrasound System Market Forecast & Strategic Analysis
- Single User License (1 Users) $ 3,500
- Team License (2~5 Users) $ 4,500
- Corporate License (>5 Users) $ 5,500
The diagnostic ultrasound systems market encompasses medical acoustic imaging instrumentation spanning heavy cart-based consoles, high-durability portable laptop systems, and pocket-sized semiconductor point-of-care ultrasound (POCUS) probes operating within acoustic bandwidths from 1.0 MHz to 60.0 MHz.
The global diagnostic ultrasound systems market size will reach to 11.2 - 14.8 billion USD in 2026, and is projected to expand at a compound annual growth rate (CAGR) between 4.8% and 5.8% through 2031. The market is decoupling from static radiology replacement budgets, propelled by three institutional catalysts: the transition from lead-zirconate-titanate (PZT) ceramics to lead-free silicon micro-machined ultrasonic transducers (CMUT/pMUT); the integration of on-device vision foundation models that de-skill acoustic view acquisition; and clinical decentralization into bedside interventional suites, out-of-hospital obstetrics, and the cash-pay veterinary sector.
The Diagnostic Ultrasound Systems Market Trend
● Semiconductor Transducer Industrialization
A foundational technological disruption is unseating six decades of reliance on high-voltage piezoelectric ceramic materials, specifically lead zirconate titanate (CAS 12626-81-2). Piezoelectric arrays demand labor-intensive dicing, sub-millimeter acoustic matching layer stacking, and high-voltage co-firing processes that create systemic margin friction. Conversely, Capacitive Micro-machined Ultrasonic Transducers (CMUT) and Piezoelectric Micromachined Ultrasonic Transducers (pMUT) leverage standard complementary metal-oxide-semiconductor (CMOS) foundry lines.
This semiconductor transition enables Moore's Law scaling for medical acoustics. Fabricating multi-frequency micro-machined silicon drums directly onto CMOS logic wafers collapses the transducer bill-of-materials from thousands of dollars per array to sub-hundred-dollar wafer dies. Crucially, silicon architecture permits a single handheld probe aperture to dynamically alter vibration frequencies and beam parameters, emulating deep curvilinear abdominal arrays, high-frequency linear vascular arrays, and phased cardiac sector arrays through software reconfiguration. This pivot mitigates mounting regulatory exposure across Western markets, where the European Union Restriction of Hazardous Substances (RoHS) Directive maintains temporary exemptions for lead in medical piezoelectric ceramics that face eventual sunsetting.
● Embedded Diagnostic Artificial Intelligence and Edge Automation
Diagnostic ultrasound has structurally remained the most operator-dependent modality in medical imaging, constrained by acoustic shadows, speckle noise, and sonographer scanning variability. The midstream integration of vision-language foundation models and low-latency edge computing directly into digital beamformers is converting acoustic acquisition from an empirical craft into an automated protocol.
Modern system architectures embed neural network coprocessors that execute real-time inference at 60 frames per second. These platforms automatically trigger frame capture upon detecting standard anatomical views matching international clinical consensus guidelines, execute instant semantic organ segmentation, compute volumetric chamber geometries, and quantify microvascular hemodynamics without manual calipers. This procedural de-skilling expands the ultrasound addressable user base by millions of general practitioners, critical care nurses, and emergency medical technicians, circumventing systemic labor shortages across radiology and sonography staffing pipelines.
● Decentralization Beyond Hospital Radiology Suites
The locus of ultrasound value creation is breaking out of centralized hospital basement imaging departments. Clinical capital allocation models show acute deceleration in pure-play shared-service cart procurement for standard departmental radiology, while high-velocity expansion occurs across decentralized care corridors:
- Bedside point-of-care ultrasound (POCUS) across emergency medicine and trauma bays for focused assessment with sonography in trauma (FAST) and acute dyspnea triage.
- Ambulatory surgery centers (ASCs) and interventional cardiac suites utilizing high-frequency micro-vascular imaging and transit-time flow measurement.
- At-home prenatal tele-monitoring systems connecting expectant mothers to remote clinical reading centers.
- The companion animal and equine veterinary sectors, operating on private, out-of-pocket payment models insulated from state-administered reimbursement caps.
PRODUCT TAXONOMY AND SYSTEM CLASSIFICATIONS
● Classification by Form Factor and Mechanical Footprint
1. Cart-Based and Console Ultrasound Systems
Console configurations represent high-mass, premium-tier platforms built upon multi-wheel articulating chassis. They feature multi-axis floating monitor arms, high-definition OLED primary displays, motorized height adjustment, secondary command touchscreens, active pinless probe connections supporting high channel densities (typically 128 to 1024 physical processing channels), and dual-inverter power redundancy.
- Unit economics: Hardware capital costs range from 30,000 USD for standard shared-service clinical consoles to over 120,000 USD for specialized structural heart, high-density matrix 4D obstetrics, and multidisciplinary academic radiology platforms.
- Representative commercial offerings: GE HealthCare LOGIQ E10, Voluson Expert 22, Vivid E95; Royal Philips EPIQ Elite, Affiniti CVx; Siemens Healthineers ACUSON Sequoia, ACUSON SC2000 PRIME; Mindray Medical Resona A20, Nuewa I9; United Imaging Healthcare uSONIQUE Genesis G; SonoScape S60, P60; CHISON XBit 90, SonoMax; Canon Medical Systems Aplio i800.
2. Portable and Laptop-Style Ultrasound Systems
Engineered for rapid bedside mobility, physical shock resistance, and thermal efficiency, these systems balance console-grade imaging architectures within compact physical enclosures weighing between 2.0 kg and 6.0 kg. They feature sealed, liquid-disinfectable keyboards, dual hot-swappable lithium-ion battery configurations, rapid boot protocols under 20 seconds, and integrated multi-transducer docking modules.
- Representative commercial offerings: CHISON SonoAir (2.1 kg ultra-thin form factor with four active probe ports), SonoBook series; Mindray Medical TE20, MX7, ME8; SonoScape X5, X3; Edan Instruments Acclarix AX8, AX3; FUJIFILM Sonosite PX, LX; SIUI CTS-7700.
3. Handheld and Pocket-Sized Ultrasound Systems (POCUS)
Ultra-mobile, cable-free or direct-tethered devices that convert commercial iOS and Android mobile terminals into full-function diagnostic imaging displays. These systems integrate analog front-ends, digitizers, beamformers, and wireless transceiver systems directly within the transducer enclosure.
- Semiconductor-based platforms: Butterfly Network Butterfly iQ3 (CMOS-driven Ultrasound-on-Chip architecture supporting 20+ clinical presets via single-probe electronic aperture morphing, priced around 3,900 USD), Butterfly iQ+; Exo Imaging Exo Iris (pMUT on silicon with integrated enterprise workflow software).
- Wireless piezoelectric arrays: CHISON SonoEye; Mindray Medical TE Air, Taia e5M; Royal Philips Lumify; GE HealthCare Vscan Air; Edan Instruments Nano series.
- Specialized at-home tele-ultrasound hardware: Pulsenmore Ltd Pulsenmore ES (smartphone-docked curved array for self-administered fetal heart rate and amniotic fluid assessments), Pulsenmore FC (IVF follicle tracking), Pulsenmore MC (home-based pulmonary congestion monitoring).
● Classification by Clinical Specialty and Anatomical Scope
1. General Imaging and Abdominal Radiology: The foundational hospital imaging domain covering liver parenchyma characterization, renal architecture, pancreatic lesions, biliary pathways, and superficial thyroid/breast structures. Platforms prioritize deep penetration, contrast-enhanced harmonic software, automated liver-to-kidney ratio metrics, and 2D shear wave elastography.
2. Cardiology and Echocardiography: High-frame-rate systems assessing myocardial strain, structural valvular defects, intracardiac shunts, and left ventricular ejection fractions. Relies upon continuous wave Doppler, 2D/4D transesophageal echocardiography (TEE), and intracardiac echocardiography (ICE) catheters capable of single-heartbeat 4D volume capture.
3. Obstetrics and Gynecology (OB/GYN): Platforms prioritizing real-time 3D and 4D volumetric rendering, automated fetal biometry extraction (biparietal diameter, femur length, abdominal circumference), photorealistic acoustic surface illumination, and Doppler umbilical blood velocity quantification.
4. Vascular Diagnostics: Non-invasive profiling of peripheral arterial occlusive disease, deep vein thrombosis, extracranial carotid intima-media thickness (CIMT), and hemodialysis arteriovenous fistula flow velocities. Requires high-frequency linear probes, specialized steerable color Doppler packets, and microvascular slow-flow tracking.
5. Point-of-Care Ultrasound (POCUS): Bedside procedural and diagnostic ultrasound across emergency medicine, anesthesiology, and military combat casualty care. Workflows emphasize trauma screening (FAST), rapid lung sliding/B-line detection, real-time vascular access guidance, and ultrasound-guided regional nerve blocks.
6. Surgical and Interventional Guidance: Dedicated operating room solutions including high-frequency ultrasound (HFUS) paired with transit-time flow measurement (TTFM) for intraoperative coronary artery bypass graft (CABG) verification (Medistim MiraQ), 60 MHz intravascular ultrasound (IVUS) catheters for percutaneous coronary intervention (PCI) plaque morphology analysis (SonoScape, Philips SpectraWAVE), and laparoscopic drop-in transducers for oncological margin resection.
DOWNSTREAM APPLIED SECTOR ANALYSIS
● Human Clinical Healthcare Architecture
Human clinical deployment accounts for over 95% of aggregate global hardware and software expenditure. Capital acquisition paths diverge based on healthcare provider tiering:
- Tertiary and Academic Medical Centers: Maintain rigorous technical tender requirements focused on dynamic range (exceeding 120 dB), channel count, matrix array transducer compatibility, automated DICOM worklist integration, and multimodal image fusion (co-registering real-time ultrasound with CT, MRI, and PET datasets). Procurement is managed via multi-year capital equipment replacement budgets and comprehensive enterprise service agreements.
- Outpatient Ambulatory Surgery Centers (ASCs) and Primary Care Clinics: Capital outlay models prioritize multi-specialty versatility, low lifecycle maintenance costs, rapid turnaround times, and ease of hardware disinfection. These facilities drive significant demand for mid-range cart units and laptop-style shared-service systems.
- Supplemental Dense Breast Screening: Driven by legislative mandates requiring provider notification for women with dense breast tissue (BI-RADS categories C and D), automated breast ultrasound systems (ABUS) and transmission acoustic tomography are expanding rapidly. ABUS platforms utilize wide-aperture automated linear transducers to systematically image the entire breast without operator-dependent probe manipulation, offering a non-ionizing, non-compression alternative to mammography.
- Remote Out-of-Hospital Prenatal and Chronic Care: Decentralized models leverage at-home hardware platforms, enabling high-risk pregnant patients or individuals managing congestive heart failure and end-stage renal disease to capture acoustic telemetry data for asynchronous transmission to centralized hospital electronic health records.
● Veterinary Medicine and Animal Healthcare
Representing a rapidly expanding, non-reimbursed market vertical, veterinary ultrasound deployment is unburdened by state public healthcare fee schedules and insurance underwriting delays:
- Companion Animal Practice: Canine and feline diagnostic assessments mirror human abdominal, cardiovascular, and musculoskeletal protocols. Clinics procure dedicated veterinary systems featuring animal-specific body-mark libraries, specialized cardiac measurement packages, high-frequency micro-convex transducers, and customized noise suppression algorithms (e.g., Mindray Animal Care Vetus series, CHISON SonoVet, Butterfly iQ3 Vet).
- Equine and Livestock Operations: Equine sports medicine demands ultra-rugged, battery-operated portable systems for field-level tendon, ligament, and reproductive examinations. Commercial livestock management (dairy and swine operations) relies on water-resistant, wrist-mounted, or wearable mechanical sector systems for high-throughput early pregnancy determination and herd reproductive cycle optimization.
VALUE CHAIN ARCHITECTURE AND BOTTLENECK RESILIENCE
● Upstream Tier-2 Component and Material Feedstocks
The baseline tier of ultrasound manufacturing exhibits sharp supply chain concentration, creating structural margin vulnerability for system assemblers:
- Acoustic Piezoelectric Material Refining: High-performance single-crystal ceramics (e.g., Lead Magnesium Niobate-Lead Titanate, PMN-PT) and lead zirconate titanate (PZT) ceramic powders require advanced crystal pulling, precision slicing, and sub-micron deposition. Specialized processing capacity remains concentrated among Japanese, German, and domestic Chinese chemical material synthesizers. Regulatory pressure under the EU RoHS framework necessitates ongoing research into lead-free bismuth sodium titanate (BNT) and potassium sodium niobate (KNN) alternatives.
- Semiconductor Fabrication Foundries: Transducer-on-chip architectures rely entirely on advanced wafer fabrication lines. Pure-play silicon foundries (predominantly in Taiwan, China) execute the high-precision micro-electro-mechanical machining (MEMS) and deep-trench etching required for capacitive cavity membranes, combined with wafer-level bonding to standard CMOS logic circuits. Back-end packaging, wafer dicing, and micro-acoustic impedance matching layers are largely clustered across Southeast Asian assembly hubs.
- Analog Front-End ASICs: Ultrasound beamforming requires proprietary application-specific integrated circuits (ASICs) that combine multi-channel high-voltage pulsers, low-noise pre-amplifiers, variable-gain amplifiers, and high-speed analog-to-digital converters within minimal silicon footprints. Global manufacturing relies heavily on semiconductor vendors including Texas Instruments, Analog Devices, and STMicroelectronics, alongside internal proprietary ASIC design groups within Tier-1 medical manufacturers.
● Midstream System Integration, Beamforming, and Diagnostic AI Engineering
Midstream value addition is shifting from raw mechanical assembly toward proprietary beamforming software architectures and diagnostic edge AI:
- System OEMs engineer the physical chassis, multi-axis transducer connectors, internal thermal dissipation systems, and ergonomic control layouts.
- Software beamforming infrastructure (such as software-defined imaging architectures) shifts signal processing from fixed hardware ASICs to programmable GPUs, enabling post-sale software upgrades that enhance spatial resolution and frame rates across existing hardware installations.
- Strategic value migration is dominated by proprietary diagnostic software suites. OEMs increasingly patent on-board deep neural networks that automate repetitive measurements (such as biometry tracking, automated ejection fraction, and vascular Doppler gate placement), building algorithmic software moats that protect hardware selling prices against commoditization.
● Downstream Commercial Channels and Value Realization Models
Sales and distribution frameworks are bifurcating based on hardware classification and regional governance:
- Direct Hospital Procurement: Tier-1 multinationals maintain dedicated, capital-intensive direct sales organizations to address tertiary medical centers, multi-hospital integrated delivery networks (IDNs), and Group Purchasing Organizations (GPOs). These transactions feature extended procurement cycles (6 to 18 months), tied to multi-year service contracts, probe replacement insurance policies, and clinical training agreements.
- Authorized Master Distributorships: In secondary, tertiary, and emerging regional markets, manufacturers deploy buy-out distribution channels. Independent regional distributors assume local regulatory registration burdens, maintain clinical demonstration inventories, manage tender bids, and provide frontline maintenance. Leading Chinese exporters generate significant international revenues through established dealer ecosystems across Latin America, Southeast Asia, and the MEA region.
- Direct-to-Practitioner Digital Channels: POCUS innovators utilize digital direct-to-clinician platforms, selling handheld probes via online portals, supported by pay-per-procedure capital schemes, hardware subscription leases, and annual enterprise SaaS software licensing models (e.g., recurring seat fees for cloud PACS archival and AI measurement tool suites).
REGIONAL DYNAMICS AND REGULATORY POLICY FRAMEWORKS
● North America (United States and Canada)
North America represents the largest regional market, consistently capturing more than 35% of global market share. Growth trends reflect a structural migration toward ambulatory surgery centers, private office-based vascular access labs, and emergency medicine POCUS fleets.
The institutional framework is heavily dictated by Centers for Medicare & Medicaid Services (CMS) reimbursement codes, Current Procedural Terminology (CPT) nomenclature updates, and the transition toward value-based care models. A key operational catalyst is the formal introduction of new CPT coding designations for automated transmission ultrasound tomography of the breast (such as the AMA CPT Category III code X579T, targeting formal implementation cycles between 2026 and 2027), establishing dedicated payment streams for non-ionizing, non-compression breast imaging.
Concurrently, rural healthcare shortages and maternal care deserts (encompassing over one-third of US counties) are driving state-level policy support for point-of-care ultrasound and remote tele-ultrasound systems, supported by legislative efforts like the Rural Obstetrics Readiness Act. Device commercialization requires rigorous US FDA 510(k) clearances or De Novo review pathways, accompanied by stringent post-market cybersecurity surveillance mandates (FDA Section 524B of the FD&C Act) for networked medical devices. North American operating margins face moderate pressure from international trade tariffs on critical components, sub-assemblies, and chassis imported under Section 302/232 schedules.
● Europe
European ultrasound expenditure is driven by replacement cycles across state-run hospital networks (e.g., the UK National Health Service, French Assistance Publique-Hopitaux de Paris, and German regional university clinics), coupled with institutional demands for clinical ergonomic automation and low-power infrastructure. The market expands at a steady, disciplined rate.
The operating environment is dominated by the European Union Medical Device Regulation (EU MDR 2017/745), which has increased regulatory friction across the industry. The transition from the legacy Medical Device Directive (MDD) has created notified body capacity bottlenecks, extended regulatory review timelines, and amplified compliance costs due to mandatory post-market clinical follow-up (PMCF) studies and periodic safety update reports (PSUR).
Critically, European environmental frameworks exert disproportionate pressure on acoustic component supply chains. The EU RoHS Directive imposes restrictions on heavy metals, and while exemptions for lead in piezoelectric ceramics have historically shielded traditional PZT probe manufacturing, tightening scrutiny from the European Chemicals Agency (ECHA) is pushing European clinical institutions to favor lead-free, micro-machined silicon transducer arrays. Transboundary diagnostic connectivity is governed by the emerging European Health Data Space (EHDS) and strict GDPR data governance protocols.
● Asia-Pacific (APAC)
Asia-Pacific represents the fastest-growing geographical theater, characterized by vast population demographics, rapid hospital capacity expansion, aging populations, and aggressive state-backed industrial policies.
China: China anchors the APAC demand cycle. Institutional growth is propelled by state healthcare modernization programs, specifically the Large-Scale Equipment Renewal policy supported by ultra-long special treasury bonds, and the Thousand County Project upgrading secondary county hospitals to tertiary performance standards. The National Health Commission's Township Health Center Medical Equipment Configuration Standards have established color Doppler ultrasound as a mandatory equipment category across primary-level health stations, driving volume demand. Concurrently, provincial and multi-provincial alliance Volume-Based Procurement (VBP) policies have expanded from medical consumables into capital imaging hardware. VBP execution compresses hospital acquisition costs, creating steep price competition for foreign multinational imports while accelerating market share gains for domestic manufacturers offering cost-competitive, vertically integrated platforms.
Republic of Korea, Japan, Taiwan, China, and Emerging APAC:
- Japan functions as a mature, highly discerning replacement market centered on advanced diagnostic ergonomics, cardiovascular imaging, and ultra-high-frequency intraoperative technology. Japan represents a high-penetration market for intraoperative CABG quality verification, where international players maintain dedicated regional commercial organizations.
- The Republic of Korea serves as both a high-end consumption market and an advanced medical device engineering and manufacturing hub, particularly across automated obstetrics and women's healthcare platforms.
- Taiwan, China remains an indispensable global anchor for upstream semiconductor ultrasound-on-chip fabrication, packaging, and micro-machining foundries.
- Across India and Southeast Asian emerging markets (e.g., Indonesia, Vietnam, Philippines), public health investments focus on decentralized rural diagnostics, creating dynamic sales channels for ruggedized portable laptop units and mid-tier multi-purpose console systems.
● Latin America (South and Central America)
Latin American market expansion is driven by the expansion of private diagnostic laboratory networks, municipal health clinic modernizations, and outsourced imaging models across Brazil, Mexico, Colombia, Chile, and Argentina. The addressable equipment pool is dominated by cost-effective portable laptop ultrasound systems and entry-level shared-service color Doppler carts.
Regulatory authority requirements—including ANVISA in Brazil, COFEPRIS in Mexico, and INVIMA in Colombia—are harmonizing around Medical Device Single Audit Program (MDSAP) standards, though local commercialization remains challenged by foreign exchange volatility, high import tariffs on fully assembled electronics, and currency devaluation risks. Leading manufacturers establish localized commercial entities and assembly operations in regional industrial hubs (e.g., Free Trade Zones in Manaus or Mexican border manufacturing corridors) to insulate operating margins against import duties.
● Middle East and Africa (MEA)
The MEA geopolitical territory exhibits stark infrastructural bifurcation:
- The Arabian Gulf Cooperation Council (GCC) bloc (Saudi Arabia, UAE, Qatar) commands high capital capacity, investing in world-class hospital cities, comprehensive private healthcare infrastructure, and automated breast cancer screening programs under national transformation programs like Saudi Vision 2030. These institutions procure top-tier multidisciplinary consoles featuring 4D matrix array imaging, advanced shear wave elastography, and multimodality interventional fusion packages, backed by multi-million-dollar distribution partnerships.
- Conversely, the North African and Sub-Saharan African sub-regions contend with public healthcare underfunding, rural physician shortages, and limited capital budgets. In these environments, market development is heavily catalyzed by non-governmental organization (NGO) grants, multilateral donor programs (such as the Bill & Melinda Gates Foundation), and international development financing. Deployments prioritize ultra-portable, drop-resistant handheld POCUS devices and smartphone-connected probes engineered to diagnose high-risk obstetrical complications, pneumonia, and trauma in remote primary care settings.
COMPETITIVE DOSSIERS: KEY MARKET PLAYERS
● GE HealthCare: Transitioned from an internal industrial division into an independent pure-play medical technology corporation, focusing on cloud-connected clinical suites, software-defined beamforming, and platform AI acquisitions.
● Philips: Direct alignment toward enterprise-wide imaging informatics, deep integration of multimodality interventional guidance, and sustainable medical device lifecycles.
● Siemens Healthineers: Synergistic consolidation of cross-modality diagnostic imaging, enterprise artificial intelligence, and structural heart interventional instrumentation.
● Mindray Medical: Vertical industrial scale and rapid migration from mid-tier value equipment into the super-premium tertiary hospital market, supported by massive internal R&D reinvestment.
● The rest of companies covered in the report: Canon Medical Systems, Fujifilm Healthcare, Samsung Healthcare (Samsung Medison), Shanghai United Imaging Healthcare (UIH), Butterfly Network, Exo Imaging, Pulsenmore Ltd, Medistim ASA, Esaote S.p.A., SuperSonic Imagine (A Hologic Company), Sonoscanner, B. Braun, QT Imaging Holdings, SonoScape Medical Corp., CHISON Medical Technologies, Edan Instruments, Shantou Institute of Ultrasonic Instruments (SIUI), Neusoft Medical Systems, and Wandong Medical.
OPPORTUNITIES, CHALLENGES, AND RISK MATRIX
● Actionable Strategic Growth Corridors
1. Replacement of Installed Mechanical and Ceramic Cart Bases
Approximately 30% of the active global installed base of legacy cart-based ultrasound consoles relies on traditional, fixed-focus analog beamforming and lead-based PZT crystal probes. A multi-year replacement cycle is emerging, driven by software-defined beamforming engines that accept regular firmware upgrades, advanced shear wave elastography algorithms, and low-power processing boards. System manufacturers capable of retrofitting or replacing these fleets with lead-free, AI-assisted consoles will capture substantial, recurring enterprise replacement budgets.
2. Outpatient Migration to Ambulatory Surgery Centers and POCUS Fleets
Surgical interventions and emergency triage continue to migrate out of traditional inpatient hospital departments into ambulatory surgery centers (ASCs), localized primary clinics, and critical care bays. This clinical shift drives double-digit procurement growth for ultra-portable laptop platforms and smartphone-tethered handheld probes. Value in this segment is realized through bundled software sales, where hardware is packaged with multi-user enterprise workflow suites, automated credentialing tracking, and hospital EHR/PACS integration.
3. Non-Ionizing Supplemental Dense Breast Cancer Screening
Global legislative mandates requiring healthcare providers to inform female patients regarding breast tissue density are driving investment in non-ionizing screening technologies. Mammography sensitivity drops significantly in dense breast tissue (BI-RADS categories C and D). This dynamic creates high-velocity demand for Automated Breast Ultrasound Systems (ABUS) and Transmission Acoustic Tomography. Systems that bypass manual scanning variability to deliver reproducible 3D volumetric images are positioned for rapid commercial uptake, supported by dedicated CPT reimbursement codes.
4. Surgical Guidance, Verification, and Intravascular Interventions
Ultrasound is expanding beyond traditional external screening into high-margin surgical operating rooms and interventional cardiac catheterization laboratories. Intraoperative High-Frequency Ultrasound paired with Transit Time Flow Measurement provides instantaneous verification of vascular graft patency prior to surgical closure, preventing re-operations and post-surgical complications. Similarly, high-frequency 60 MHz Intravascular Ultrasound (IVUS) catheters are becoming standard in percutaneous coronary interventions, guiding stent sizing and plaque characterization.
5. The Cash-Pay Companion Animal and Equine Veterinary Segment
The rapid expansion of pet ownership and companion animal medical care spending represents an insulated, high-margin market vertical. Unburdened by government healthcare reimbursement freezes, DRG cost-containment rules, or insurance claim denials, veterinary clinics increasingly purchase dedicated ultrasound systems on cash-pay terms. Capitalizing on this sector requires dedicated veterinary software presets, species-specific cardiac calculations, and micro-convex transducer geometries.
● Structural Industry Challenges and Operational Risks
1. Hardware Price Compression via Centralized Public Procurement
Government-led Volume-Based Procurement (VBP) programs in China, alongside aggressive Group Purchasing Organization (GPO) pricing tenders in North America, continue to compress average selling prices (ASPs) for standard cart and portable hardware. In response, manufacturers must lower bill-of-materials costs through vertical component manufacturing, automated assembly lines, and software-monetized features to protect operating margins.
2. Regulatory Compliance Inflation and Certification Delays
The regulatory environment for medical acoustic instrumentation is tightening across major jurisdictions. The extended implementation of the European Union Medical Device Regulation (EU MDR 2017/745) has inflated the cost of maintaining technical dossiers, clinical evaluation reports, and post-market clinical follow-ups, while notified body capacity constraints extend time-to-market for novel platforms. Concurrently, US FDA De Novo and 510(k) pathways enforce heightened clinical safety, data integrity, and device cybersecurity standards, increasing baseline R&D expenditures.
3. Upstream Feedstock Concentration and Semiconductor Sourcing Vulnerabilities
The ultrasound value chain remains exposed to geopolitical, geographic, and supplier concentrations. Foundational manufacturing inputs—including high-purity single-crystal piezoelectric ceramics, low-noise analog front-end ASICs, high-performance computing GPUs, and MEMS wafer fabrication lines—are clustered among a limited group of suppliers in Japan, Germany, the United States, and Taiwan, China. Geopolitical friction, trade sanctions, or regional manufacturing disruptions could quickly constrain global system assembly operations.
4. Clinical Operator Shortages and Professional Burnout
Despite the proliferation of intuitive user interfaces, clinical diagnostic ultrasound remains an operator-dependent imaging modality. The industry faces persistent labor shortages of certified diagnostic medical sonographers, radiologists, and echocardiographers across North America and Europe. High exam volumes and repetitive strain injuries contribute to sonographer burnout. System manufacturers that fail to integrate robust edge AI capable of automating view recognition, caliper placement, and report population risk clinical rejection by understaffed hospital departments.
5. International Trade Tariffs and Geopolitical Friction
Ongoing international trade tensions, cross-border tariff structures (including US Section 301/232 actions and European counter-tariffs), and national domestic preference policies (such as local manufacturing content requirements in public tenders) create friction in global supply chains. Manufacturers without flexible, multi-regional manufacturing footprints face compressed gross margins when exporting across North America, Europe, and Asia-Pacific. Operational resilience requires building dual-hub supply networks, localizing final assembly operations, and expanding contract manufacturing partnerships within target regional trading zones.
1.1 Study Framework and Executive Synthesis 1
1.2 Diagnostic Ultrasound System Industry Classification and Nomenclature 2
1.3 Primary Data Sources and Rigorous Triangulation Models 3
1.4 Secondary Research and Validated Institutional Databases 4
1.5 Macroeconomic, Demographic, and Technological Base Assumptions 5
1.6 Acronyms and Specialized Technical Terminology 6
Chapter 2 Global Diagnostic Ultrasound System Market Landscape and Industry Ecosystem 7
2.1 Global Market Size Analysis: Revenue (USD Million) and Shipment Volume (Units), 2021-2026 7
2.2 Historical Trajectory and Transition Dynamics (2021-2025) 9
2.3 Current Market Realities and Capital Allocation Across Healthcare Systems (2026) 11
2.4 Technological Paradigm Shifts: AI-Assisted Image Reconstruction and Edge Processing 12
2.5 Global Regulatory Compliance Frameworks and Pre-Market Approval Pathways 13
Chapter 3 Global Diagnostic Ultrasound System Supply Chain and Value Chain Dynamics 15
3.1 Upstream Component Architecture: Piezoelectric Transducers, ASICs, and Acoustic Lenses 15
3.2 Semiconductor and Microelectronics Sourcing Vulnerabilities 17
3.3 Manufacturing and Sub-System Assembly Process Flow Analysis 18
3.4 Cost Structure Breakdown and Bill of Materials (BOM) Economics 19
3.5 Downstream Value Migration and OEM-to-Hospital Supply Networks 20
3.6 International Trade Regulations, Cross-Border Logistics, and Tariff Exposure 21
Chapter 4 Global Diagnostic Ultrasound System Market by Form Factor & Mobility 23
4.1 Segment Overview and Structural Volume-Value Composition 23
4.2 Cart-based & Console Ultrasound System 24
4.2.1 Market Volume and Value Trajectory (2021-2026) 24
4.2.2 High-Throughput Clinical Center Adoption Dynamics 25
4.3 Portable & Laptop-Style Ultrasound System 26
4.3.1 Market Volume and Value Trajectory (2021-2026) 26
4.3.2 Emergency Department and Ambulatory Deployment Metrics 27
4.4 Handheld & Pocket-Sized Ultrasound System 28
4.4.1 Market Volume and Value Trajectory (2021-2026) 28
4.4.2 Ultrasound-on-Chip (CMUT/PMUT) Disruption and Decentralized Point-of-Care 30
Chapter 5 Global Diagnostic Ultrasound System Market by Clinical Application & Specialty 32
5.1 Segment Revenue and Installation Volume Dynamics 32
5.2 General Imaging Ultrasound 33
5.3 Cardiology & Echocardiography Ultrasound 34
5.4 Obstetrics & Gynecology Ultrasound 36
5.5 Vascular Ultrasound 37
5.6 Point-of-Care Ultrasound (POCUS) 39
5.7 Surgical & Interventional Ultrasound 41
Chapter 6 Global Diagnostic Ultrasound System Market by End-Use Sector 43
6.1 Downstream Demand Segmentation Matrix 43
6.2 Human Clinical Healthcare 44
6.2.1 Acute Care Hospitals and Academic Medical Centers 44
6.2.2 Independent Imaging Centers and Specialized Diagnostic Clinics 46
6.2.3 Outpatient Clinics, Urgent Care, and Ambulatory Surgical Centers 47
6.3 Veterinary Medicine & Animal Healthcare 48
6.3.1 Small Animal Practices and Companion Care Clinics 48
6.3.2 Large Animal, Equine, and Livestock Production Medicine 49
Chapter 7 Global Diagnostic Ultrasound System Regional Market Breakdown and Trade Flows 51
7.1 Macro-Regional Revenue Distribution and Volume Comparison (2021-2026) 51
7.2 North America Diagnostic Ultrasound System Market Architecture 53
7.2.1 Production Base vs. Demand Influx Overview 53
7.2.2 Regional Import and Export Balance Metrics 54
7.3 Europe Diagnostic Ultrasound System Market Architecture 55
7.3.1 Production Base vs. Demand Influx Overview 55
7.3.2 Cross-Border Distribution Logistics and MDR Regulatory Impact 57
7.4 Asia-Pacific Diagnostic Ultrasound System Market Architecture 58
7.4.1 High-Volume Manufacturing Hubs vs. Expanding Domestic Markets 58
7.4.2 Regional Supply Chain Clustering and Export Flow 60
7.5 Latin America Diagnostic Ultrasound System Market Dynamics 61
7.6 Middle East & Africa Diagnostic Ultrasound System Market Dynamics 63
Chapter 8 Primary Consuming and Producing Country Deep-Dives 65
8.1 United States: Technology Innovation Hub and Tier-1 Hospital Procurement 65
8.2 China: Domestic Volume Expansion, Localized Substitution, and Export Power 67
8.3 Germany: High-Precision Transducer Engineering and Clinical Integration 69
8.4 Japan: Advanced Micro-Acoustic Core Technologies and Aging Demographics 71
8.5 South Korea: Digital Imaging Ecosystems and Export-Oriented Manufacturing 73
8.6 France: Public Hospital Tendering and Specialized Oncology Adoption 75
8.7 United Kingdom: NHS Procurement Centralization and Community Diagnostics 77
8.8 India: Healthcare Tier Expansion and Tier-2/Tier-3 Rural Ultrasound Influx 79
Chapter 9 Global Competitive Landscape and Market Structure Analysis 81
9.1 Market Concentration Ratios (CR4, CR8, HHI) and Competitive Consolidation 81
9.2 Tiered Market Matrix: Multinational MedTech Giants vs. Pure-Play Innovators 83
9.3 Strategic Moves: M&A Transactions, Strategic Licensing, and Ecosystem Alliances 85
9.4 Pricing Bands and Competitive Elasticity Across Form Factors 87
9.5 Intellectual Property Landscapes and Transducer Patent Litigation Profiles 88
Chapter 10 Corporate Intelligence: Major Global Market Players 90
10.1 GE HealthCare 90
10.1.1 Corporate Overview and Diagnostic Imaging Portfolio 90
10.1.2 SWOT Analysis 91
10.1.3 Ultrasound Operations: Sales Volume, Revenue, Price, Cost, and Gross Margin (2021-2026) 92
10.1.4 Global GTM Footprint and AI Platform Integration Strategy 93
10.2 Philips 94
10.2.1 Corporate Overview and Ultrasound Product Architecture 94
10.2.2 SWOT Analysis 95
10.2.3 Ultrasound Operations: Sales Volume, Revenue, Price, Cost, and Gross Margin (2021-2026) 96
10.2.4 Tele-Ultrasound and Enterprise Diagnostic Informatics Strategy 97
10.3 Siemens Healthineers 98
10.3.1 Corporate Overview and Clinical Imaging Positioning 98
10.3.2 SWOT Analysis 99
10.3.3 Ultrasound Operations: Sales Volume, Revenue, Price, Cost, and Gross Margin (2021-2026) 100
10.3.4 Transducer Technologies and Interventional Imaging Focus 101
10.4 Fujifilm 102
10.4.1 Corporate Overview and Sonosite Point-of-Care Integration 102
10.4.2 SWOT Analysis 103
10.4.3 Ultrasound Operations: Sales Volume, Revenue, Price, Cost, and Gross Margin (2021-2026) 104
10.4.4 Military, Critical Care, and Portable Segment Strategy 105
10.5 Samsung Healthcare 106
10.5.1 Corporate Overview and Women's Health Focus 106
10.5.2 SWOT Analysis 107
10.5.3 Ultrasound Operations: Sales Volume, Revenue, Price, Cost, and Gross Margin (2021-2026) 108
10.5.4 Advanced Ergonomics and AI-Assisted Fetal Biometry 109
10.6 Canon Medical Systems 110
10.6.1 Corporate Overview and High-End Console Architecture 110
10.6.2 SWOT Analysis 111
10.6.3 Ultrasound Operations: Sales Volume, Revenue, Price, Cost, and Gross Margin (2021-2026) 112
10.6.4 Deep Learning Reconstruction and Microvascular Imaging 113
10.7 Mindray 114
10.7.1 Corporate Overview and Dual-Engine Domestic/International Expansion 114
10.7.2 SWOT Analysis 115
10.7.3 Ultrasound Operations: Sales Volume, Revenue, Price, Cost, and Gross Margin (2021-2026) 116
10.7.4 High-End Cart Platform Penetration and Global Channel Density 117
10.8 United Imaging Healthcare 118
10.8.1 Corporate Overview and Disruptive System Architecture 118
10.8.2 SWOT Analysis 119
10.8.3 Ultrasound Operations: Sales Volume, Revenue, Price, Cost, and Gross Margin (2021-2026) 120
10.8.4 Vertical Integration and Premium Institutional Penetration 121
10.9 Chison Medical Technologies Co. Ltd 122
10.9.1 Corporate Overview and Product Portfolio 122
10.9.2 SWOT Analysis 123
10.9.3 Ultrasound Operations: Sales Volume, Revenue, Price, Cost, and Gross Margin (2021-2026) 124
10.9.4 Portable and Value-Tier International Market Positioning 125
10.10 Wandong Medical 126
10.10.1 Corporate Overview and Midea Group Healthcare Synergies 126
10.10.2 SWOT Analysis 127
10.10.3 Ultrasound Operations: Sales Volume, Revenue, Price, Cost, and Gross Margin (2021-2026) 128
10.10.4 Grassroots Healthcare and Emerging Market Strategy 129
10.11 Shantou Institute of Ultrasonic Instruments Co. Ltd (SIUI) 130
10.11.1 Corporate Overview and Engineering Heritage 130
10.11.2 SWOT Analysis 131
10.11.3 Ultrasound Operations: Sales Volume, Revenue, Price, Cost, and Gross Margin (2021-2026) 132
10.11.4 Veterinary and Specialized Clinical Imaging Lineups 133
10.12 Edan Instruments Inc. 134
10.12.1 Corporate Overview and Diagnostic Monitoring Synergies 134
10.12.2 SWOT Analysis 135
10.12.3 Ultrasound Operations: Sales Volume, Revenue, Price, Cost, and Gross Margin (2021-2026) 136
10.12.4 Point-of-Care and Obstetrics Multi-Channel Distribution 137
10.13 SonoScape Medical Corp. 138
10.13.1 Corporate Overview and Single-Crystal Transducer Development 138
10.13.2 SWOT Analysis 139
10.13.3 Ultrasound Operations: Sales Volume, Revenue, Price, Cost, and Gross Margin (2021-2026) 140
10.13.4 Mid-to-High End Console and POCUS Diversification 141
10.14 Butterfly Network Inc. 142
10.14.1 Corporate Overview and Semiconductor Ultrasound-on-Chip Innovation 142
10.14.2 SWOT Analysis 143
10.14.3 Ultrasound Operations: Sales Volume, Revenue, Price, Cost, and Gross Margin (2021-2026) 144
10.14.4 Software-as-a-Service Monetization and Enterprise Deployments 145
10.15 Pulsenmore Ltd 146
10.15.1 Corporate Overview and Telehealth Prenatal Ultrasound Devices 146
10.15.2 SWOT Analysis 147
10.15.3 Ultrasound Operations: Sales Volume, Revenue, Price, Cost, and Gross Margin (2021-2026) 148
10.15.4 Remote Monitoring Partnerships and HMO Adoption Channels 149
10.16 ESAOTE S.p.A. 150
10.16.1 Corporate Overview and European Diagnostic Specialization 150
10.16.2 SWOT Analysis 151
10.16.3 Ultrasound Operations: Sales Volume, Revenue, Price, Cost, and Gross Margin (2021-2026) 152
10.16.4 Musculoskeletal, Sports Medicine, and Shared-Service Platforms 153
10.17 Neusoft Medical Systems 154
10.17.1 Corporate Overview and Medical IT Infrastructure Alignment 154
10.17.2 SWOT Analysis 155
10.17.3 Ultrasound Operations: Sales Volume, Revenue, Price, Cost, and Gross Margin (2021-2026) 156
10.17.4 Cloud-Connected Diagnostics and Rural Hospital Bundles 157
10.18 B.Braun 158
10.18.1 Corporate Overview and Anesthesia/Surgical Ultrasound Integration 158
10.18.2 SWOT Analysis 159
10.18.3 Ultrasound Operations: Sales Volume, Revenue, Price, Cost, and Gross Margin (2021-2026) 160
10.18.4 Regional Anesthesia and Vascular Access Guidance Platforms 161
10.19 SuperSonic Imagine/Hologic 162
10.19.1 Corporate Overview and ShearWave Elastography Leadership 162
10.19.2 SWOT Analysis 163
10.19.3 Ultrasound Operations: Sales Volume, Revenue, Price, Cost, and Gross Margin (2021-2026) 164
10.19.4 Women's Health Integration and Liver Disease Profiling 165
10.20 Sonoscanner 166
10.20.1 Corporate Overview and French Precision Engineering 166
10.20.2 SWOT Analysis 167
10.20.3 Ultrasound Operations: Sales Volume, Revenue, Price, Cost, and Gross Margin (2021-2026) 168
10.20.4 High-End Compact Ultrasound and Specialized Primary Care 169
10.21 Exo Imaging Inc 170
10.21.1 Corporate Overview and Silicon PMUT Hardware-Software Architecture 170
10.21.2 SWOT Analysis 171
10.21.3 Ultrasound Operations: Sales Volume, Revenue, Price, Cost, and Gross Margin (2021-2026) 172
10.21.4 Workflow Solutions and Next-Generation Pocket Ultrasound 173
10.22 Terason 174
10.22.1 Corporate Overview and Dedicated Micro-System Hardware 174
10.22.2 SWOT Analysis 175
10.22.3 Ultrasound Operations: Sales Volume, Revenue, Price, Cost, and Gross Margin (2021-2026) 176
10.22.4 Vascular, Cardiology, and Mobile Diagnostic Specialization 177
10.23 Medistim ASA 178
10.23.1 Corporate Overview and Intraoperative Surgical Guidance 178
10.23.2 SWOT Analysis 179
10.23.3 Ultrasound Operations: Sales Volume, Revenue, Price, Cost, and Gross Margin (2021-2026) 180
10.23.4 Coronary Artery Bypass Grafting (CABG) Flow Measurement Integration 181
10.24 QT Imaging Holdings 182
10.24.1 Corporate Overview and Automated Transmission Ultrasound Systems 182
10.24.2 SWOT Analysis 183
10.24.3 Ultrasound Operations: Sales Volume, Revenue, Price, Cost, and Gross Margin (2021-2026) 184
10.24.4 Radiation-Free Breast Imaging Innovation and Commercial Path 185
Chapter 11 Global Market Forecast and Strategic Industry Perspectives (2027-2031) 186
11.1 Quantitative Macro Forecast: Total Market Size and Volume (2027-2031) 186
11.2 Segment-Level Growth Vectors and Volume-Value Drift 188
11.3 Emerging Regional Demand Shifts and Developing Market Modernization 189
11.4 Disruptive Technology Horizons: Next-Gen Micromachined Transducers and Autonomous Imaging 190
11.5 Strategic Imperatives and Competitive Positioning Models for 2027-2031 191
Table 2 Diagnostic Ultrasound System Bill of Materials (BOM) Breakdown and Cost Structure 19
Table 3 Global Diagnostic Ultrasound System Market by Form Factor & Mobility: Revenue (USD Million), 2021-2026 23
Table 4 Global Diagnostic Ultrasound System Market by Form Factor & Mobility: Shipment Volume (Units), 2021-2026 24
Table 5 Cart-based & Console Ultrasound System Market Size and Volume by Region, 2021-2026 25
Table 6 Portable & Laptop-Style Ultrasound System Market Size and Volume by Region, 2021-2026 27
Table 7 Handheld & Pocket-Sized Ultrasound System Market Size and Volume by Region, 2021-2026 29
Table 8 Global Diagnostic Ultrasound System Market by Clinical Application: Revenue (USD Million), 2021-2026 32
Table 9 Global Diagnostic Ultrasound System Market by Clinical Application: Shipment Volume (Units), 2021-2026 33
Table 10 General Imaging Ultrasound Market Size by Region, 2021-2026 34
Table 11 Cardiology & Echocardiography Ultrasound Market Size by Region, 2021-2026 35
Table 12 Obstetrics & Gynecology Ultrasound Market Size by Region, 2021-2026 37
Table 13 Vascular Ultrasound Market Size by Region, 2021-2026 38
Table 14 Point-of-Care Ultrasound (POCUS) Market Size by Region, 2021-2026 40
Table 15 Surgical & Interventional Ultrasound Market Size by Region, 2021-2026 42
Table 16 Global Diagnostic Ultrasound System Market by End-Use Sector: Revenue (USD Million), 2021-2026 43
Table 17 Human Clinical Healthcare Ultrasound Market Size and Volume by Facility Type, 2021-2026 45
Table 18 Veterinary Medicine & Animal Healthcare Ultrasound Market Size and Volume, 2021-2026 49
Table 19 Global Diagnostic Ultrasound System Revenue by Macro-Region (USD Million), 2021-2026 51
Table 20 Global Diagnostic Ultrasound System Shipment Volume by Macro-Region (Units), 2021-2026 52
Table 21 North America Diagnostic Ultrasound System Revenue and Shipments by Country, 2021-2026 54
Table 22 Europe Diagnostic Ultrasound System Revenue and Shipments by Country, 2021-2026 56
Table 23 Asia-Pacific Diagnostic Ultrasound System Revenue and Shipments by Country, 2021-2026 59
Table 24 Latin America Diagnostic Ultrasound System Revenue and Shipments by Country, 2021-2026 62
Table 25 Middle East & Africa Diagnostic Ultrasound System Revenue and Shipments by Country, 2021-2026 64
Table 26 United States Diagnostic Ultrasound System Market Volume and Value by Segment, 2021-2026 66
Table 27 China Diagnostic Ultrasound System Market Volume and Value by Segment, 2021-2026 68
Table 28 Germany Diagnostic Ultrasound System Market Volume and Value by Segment, 2021-2026 70
Table 29 Japan Diagnostic Ultrasound System Market Volume and Value by Segment, 2021-2026 72
Table 30 South Korea Diagnostic Ultrasound System Market Volume and Value by Segment, 2021-2026 74
Table 31 France Diagnostic Ultrasound System Market Volume and Value by Segment, 2021-2026 76
Table 32 United Kingdom Diagnostic Ultrasound System Market Volume and Value by Segment, 2021-2026 78
Table 33 India Diagnostic Ultrasound System Market Volume and Value by Segment, 2021-2026 80
Table 34 Global Diagnostic Ultrasound System Market Concentration Ratios (CR4, CR8, HHI), 2021-2026 82
Table 35 GE HealthCare Diagnostic Ultrasound System Sales, Price, Cost and Gross Profit Margin (2021-2026) 92
Table 36 Philips Diagnostic Ultrasound System Sales, Price, Cost and Gross Profit Margin (2021-2026) 96
Table 37 Siemens Healthineers Diagnostic Ultrasound System Sales, Price, Cost and Gross Profit Margin (2021-2026) 100
Table 38 Fujifilm Diagnostic Ultrasound System Sales, Price, Cost and Gross Profit Margin (2021-2026) 104
Table 39 Samsung Healthcare Diagnostic Ultrasound System Sales, Price, Cost and Gross Profit Margin (2021-2026) 108
Table 40 Canon Medical Systems Diagnostic Ultrasound System Sales, Price, Cost and Gross Profit Margin (2021-2026) 112
Table 41 Mindray Diagnostic Ultrasound System Sales, Price, Cost and Gross Profit Margin (2021-2026) 116
Table 42 United Imaging Healthcare Diagnostic Ultrasound System Sales, Price, Cost and Gross Profit Margin (2021-2026) 120
Table 43 Chison Medical Technologies Co. Ltd Diagnostic Ultrasound System Sales, Price, Cost and Gross Profit Margin (2021-2026) 124
Table 44 Wandong Medical Diagnostic Ultrasound System Sales, Price, Cost and Gross Profit Margin (2021-2026) 128
Table 45 Shantou Institute of Ultrasonic Instruments Co. Ltd (SIUI) Diagnostic Ultrasound System Sales, Price, Cost and Gross Profit Margin (2021-2026) 132
Table 46 Edan Instruments Inc. Diagnostic Ultrasound System Sales, Price, Cost and Gross Profit Margin (2021-2026) 136
Table 47 SonoScape Medical Corp. Diagnostic Ultrasound System Sales, Price, Cost and Gross Profit Margin (2021-2026) 140
Table 48 Butterfly Network Inc. Diagnostic Ultrasound System Sales, Price, Cost and Gross Profit Margin (2021-2026) 144
Table 49 Pulsenmore Ltd Diagnostic Ultrasound System Sales, Price, Cost and Gross Profit Margin (2021-2026) 148
Table 50 ESAOTE S.p.A. Diagnostic Ultrasound System Sales, Price, Cost and Gross Profit Margin (2021-2026) 152
Table 51 Neusoft Medical Systems Diagnostic Ultrasound System Sales, Price, Cost and Gross Profit Margin (2021-2026) 156
Table 52 B.Braun Diagnostic Ultrasound System Sales, Price, Cost and Gross Profit Margin (2021-2026) 160
Table 53 SuperSonic Imagine/Hologic Diagnostic Ultrasound System Sales, Price, Cost and Gross Profit Margin (2021-2026) 164
Table 54 Sonoscanner Diagnostic Ultrasound System Sales, Price, Cost and Gross Profit Margin (2021-2026) 168
Table 55 Exo Imaging Inc Diagnostic Ultrasound System Sales, Price, Cost and Gross Profit Margin (2021-2026) 172
Table 56 Terason Diagnostic Ultrasound System Sales, Price, Cost and Gross Profit Margin (2021-2026) 176
Table 57 Medistim ASA Diagnostic Ultrasound System Sales, Price, Cost and Gross Profit Margin (2021-2026) 180
Table 58 QT Imaging Holdings Diagnostic Ultrasound System Sales, Price, Cost and Gross Profit Margin (2021-2026) 184
Table 59 Global Diagnostic Ultrasound System Forecast by Form Factor & Mobility: Revenue (USD Million), 2027-2031 187
Table 60 Global Diagnostic Ultrasound System Forecast by Form Factor & Mobility: Volume (Units), 2027-2031 187
Table 61 Global Diagnostic Ultrasound System Forecast by Clinical Application (USD Million), 2027-2031 188
Table 62 Global Diagnostic Ultrasound System Forecast by Region (USD Million), 2027-2031 189
Figure 1 Global Diagnostic Ultrasound System Revenue Trend and Growth Velocity (2021-2026) 8
Figure 2 Diagnostic Ultrasound System End-to-End Value Chain and Architecture 16
Figure 3 Global Manufacturing Hubs and Cross-Border Flow Corridors 22
Figure 4 Form Factor Market Share Comparison: Revenue vs. Volume (2021 vs. 2026) 24
Figure 5 Cart vs. Portable vs. Handheld ASP Erosion and Convergence Trends (2021-2026) 30
Figure 6 Clinical Application Value Migration Dynamics (2021-2026) 33
Figure 7 Human Clinical Healthcare vs. Veterinary Medicine Market Share (2021-2026) 44
Figure 8 Macro-Regional Revenue Distribution Split (2021 vs. 2026) 52
Figure 9 North America Production, Consumption, and Net Trade Balance (2021-2026) 55
Figure 10 Europe Ultrasound Equipment Import Penetration vs. Local Output (2021-2026) 57
Figure 11 Asia-Pacific Production Hubs vs. Domestic Consumption Influx (2021-2026) 60
Figure 12 Global Diagnostic Ultrasound System Pricing Band Distribution (2026) 87
Figure 13 GE HealthCare Diagnostic Ultrasound System Market Share (2021-2026) 93
Figure 14 Philips Diagnostic Ultrasound System Market Share (2021-2026) 97
Figure 15 Siemens Healthineers Diagnostic Ultrasound System Market Share (2021-2026) 101
Figure 16 Fujifilm Diagnostic Ultrasound System Market Share (2021-2026) 105
Figure 17 Samsung Healthcare Diagnostic Ultrasound System Market Share (2021-2026) 109
Figure 18 Canon Medical Systems Diagnostic Ultrasound System Market Share (2021-2026) 113
Figure 19 Mindray Diagnostic Ultrasound System Market Share (2021-2026) 117
Figure 20 United Imaging Healthcare Diagnostic Ultrasound System Market Share (2021-2026) 121
Figure 21 Chison Medical Technologies Co. Ltd Diagnostic Ultrasound System Market Share (2021-2026) 125
Figure 22 Wandong Medical Diagnostic Ultrasound System Market Share (2021-2026) 129
Figure 23 Shantou Institute of Ultrasonic Instruments Co. Ltd (SIUI) Diagnostic Ultrasound System Market Share (2021-2026) 133
Figure 24 Edan Instruments Inc. Diagnostic Ultrasound System Market Share (2021-2026) 137
Figure 25 SonoScape Medical Corp. Diagnostic Ultrasound System Market Share (2021-2026) 141
Figure 26 Butterfly Network Inc. Diagnostic Ultrasound System Market Share (2021-2026) 145
Figure 27 Pulsenmore Ltd Diagnostic Ultrasound System Market Share (2021-2026) 149
Figure 28 ESAOTE S.p.A. Diagnostic Ultrasound System Market Share (2021-2026) 153
Figure 29 Neusoft Medical Systems Diagnostic Ultrasound System Market Share (2021-2026) 157
Figure 30 B.Braun Diagnostic Ultrasound System Market Share (2021-2026) 161
Figure 31 SuperSonic Imagine/Hologic Diagnostic Ultrasound System Market Share (2021-2026) 165
Figure 32 Sonoscanner Diagnostic Ultrasound System Market Share (2021-2026) 169
Figure 33 Exo Imaging Inc Diagnostic Ultrasound System Market Share (2021-2026) 173
Figure 34 Terason Diagnostic Ultrasound System Market Share (2021-2026) 177
Figure 35 Medistim ASA Diagnostic Ultrasound System Market Share (2021-2026) 181
Figure 36 QT Imaging Holdings Diagnostic Ultrasound System Market Share (2021-2026) 185
Figure 37 Global Diagnostic Ultrasound System Volume vs. Value Forecast (2027-2031) 186
Figure 38 Regional Growth Matrix and Compound Annual Growth Rate Trajectories (2027-2031) 190
Research Methodology
- Market Estimated Methodology:
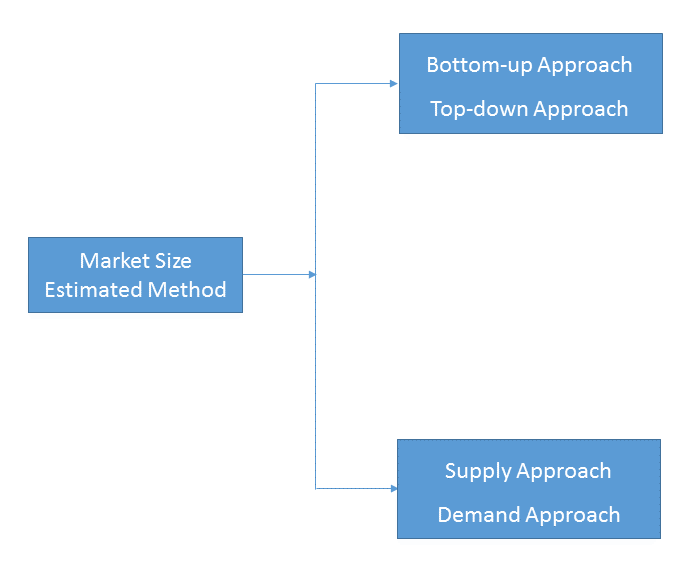
Bottom-up & top-down approach, supply & demand approach are the most important method which is used by HDIN Research to estimate the market size.
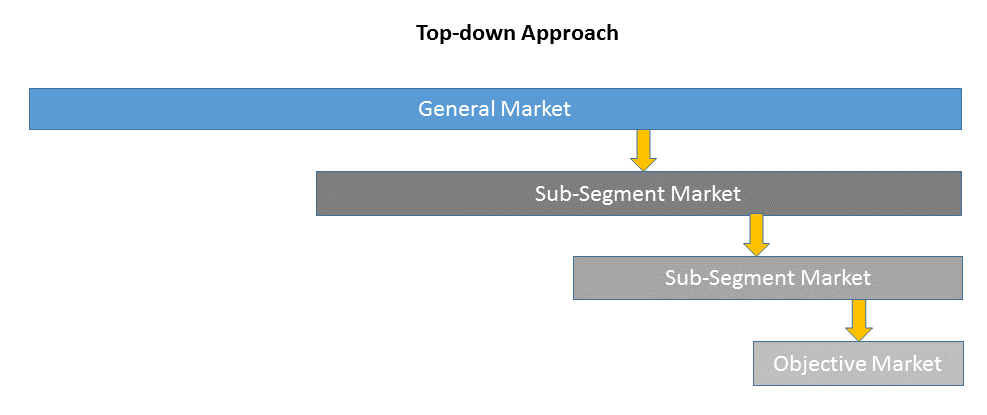
1)Top-down & Bottom-up Approach
Top-down approach uses a general market size figure and determines the percentage that the objective market represents.
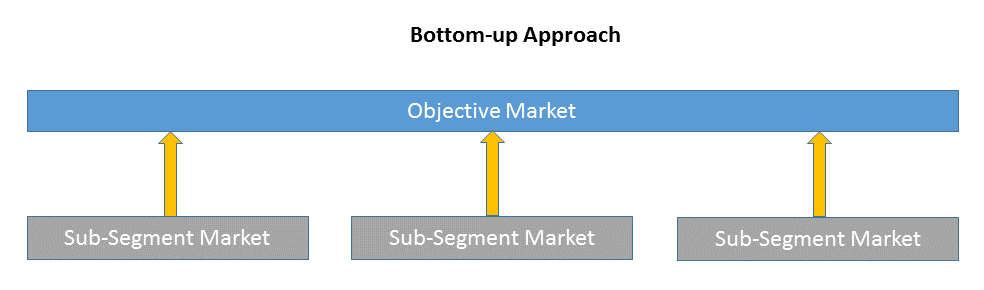
Bottom-up approach size the objective market by collecting the sub-segment information.
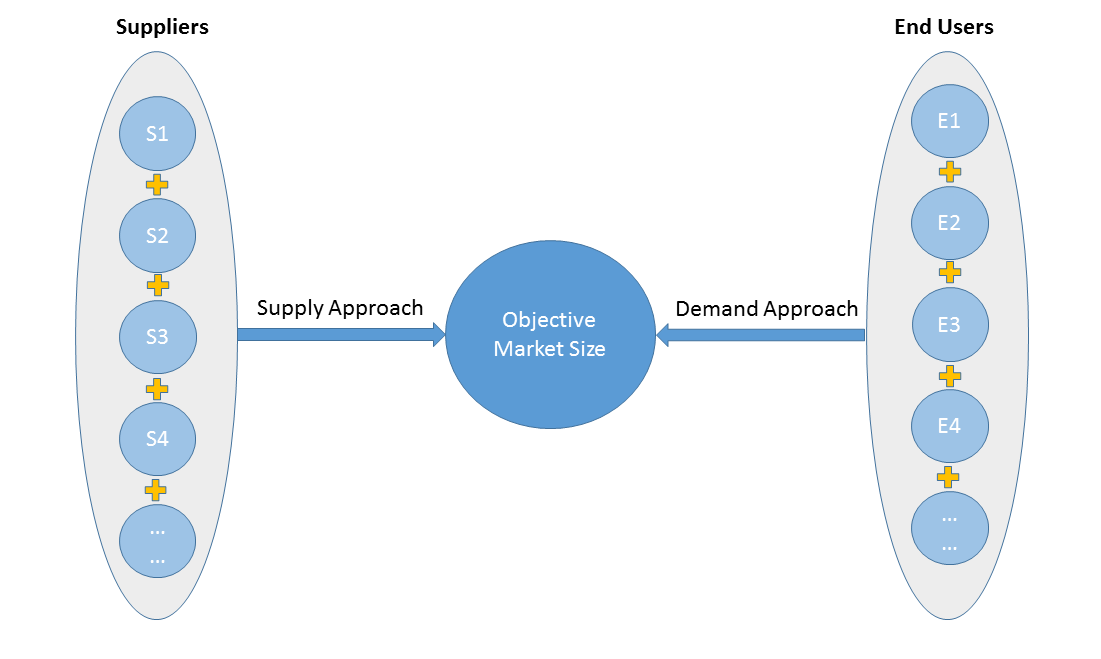
2)Supply & Demand Approach
Supply approach is based on assessments of the size of each competitor supplying the objective market.
Demand approach combine end-user data within a market to estimate the objective market size. It is sometimes referred to as bottom-up approach.
- Forecasting Methodology
- Numerous factors impacting the market trend are considered for forecast model:
- New technology and application in the future;
- New project planned/under contraction;
- Global and regional underlying economic growth;
- Threatens of substitute products;
- Industry expert opinion;
- Policy and Society implication.
- Analysis Tools
1)PEST Analysis
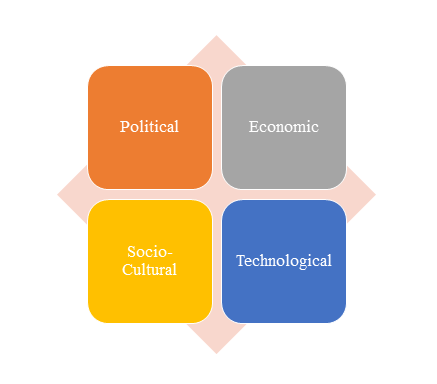
PEST Analysis is a simple and widely used tool that helps our client analyze the Political, Economic, Socio-Cultural, and Technological changes in their business environment.
- Benefits of a PEST analysis:
- It helps you to spot business opportunities, and it gives you advanced warning of significant threats.
- It reveals the direction of change within your business environment. This helps you shape what you’re doing, so that you work with change, rather than against it.
- It helps you avoid starting projects that are likely to fail, for reasons beyond your control.
- It can help you break free of unconscious assumptions when you enter a new country, region, or market; because it helps you develop an objective view of this new environment.
2)Porter’s Five Force Model Analysis
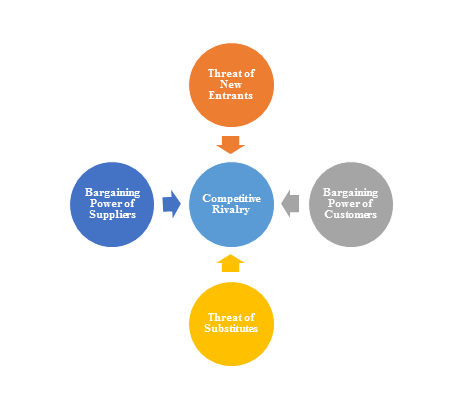
The Porter’s Five Force Model is a tool that can be used to analyze the opportunities and overall competitive advantage. The five forces that can assist in determining the competitive intensity and potential attractiveness within a specific area.
- Threat of New Entrants: Profitable industries that yield high returns will attract new firms.
- Threat of Substitutes: A substitute product uses a different technology to try to solve the same economic need.
- Bargaining Power of Customers: the ability of customers to put the firm under pressure, which also affects the customer's sensitivity to price changes.
- Bargaining Power of Suppliers: Suppliers of raw materials, components, labor, and services (such as expertise) to the firm can be a source of power over the firm when there are few substitutes.
- Competitive Rivalry: For most industries the intensity of competitive rivalry is the major determinant of the competitiveness of the industry.
3)Value Chain Analysis
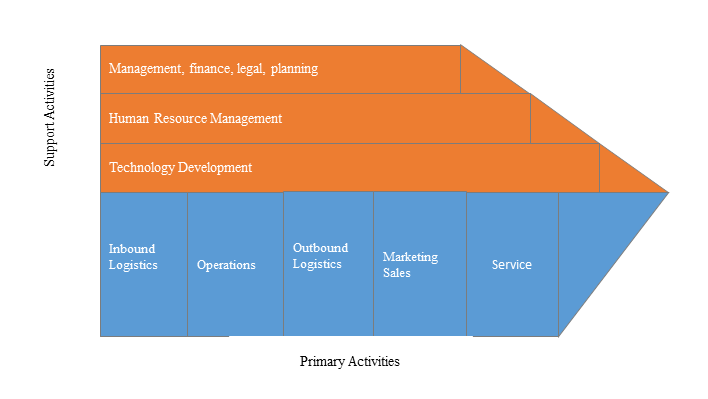
Value chain analysis is a tool to identify activities, within and around the firm and relating these activities to an assessment of competitive strength. Value chain can be analyzed by primary activities and supportive activities. Primary activities include: inbound logistics, operations, outbound logistics, marketing & sales, service. Support activities include: technology development, human resource management, management, finance, legal, planning.
4)SWOT Analysis
SWOT analysis is a tool used to evaluate a company's competitive position by identifying its strengths, weaknesses, opportunities and threats. The strengths and weakness is the inner factor; the opportunities and threats are the external factor. By analyzing the inner and external factors, the analysis can provide the detail information of the position of a player and the characteristics of the industry.
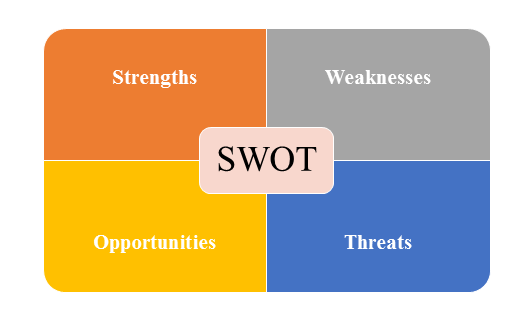
- Strengths describe what the player excels at and separates it from the competition
- Weaknesses stop the player from performing at its optimum level.
- Opportunities refer to favorable external factors that the player can use to give it a competitive advantage.
- Threats refer to factors that have the potential to harm the player.
- Data Sources
| Primary Sources | Secondary Sources |
|---|---|
| Face to face/Phone Interviews with market participants, such as: Manufactures; Distributors; End-users; Experts. Online Survey |
Government/International Organization Data: Annual Report/Presentation/Fact Book Internet Source Information Industry Association Data Free/Purchased Database Market Research Report Book/Journal/News |