Diagnostic Ultrasound Transducer Market Forecast 2026-2031
- Single User License (1 Users) $ 3,500
- Team License (2~5 Users) $ 4,500
- Corporate License (>5 Users) $ 5,500
The global diagnostic ultrasound transducer market size will reach to 3.2-4.2 billion USD in 2026 with a compound annual growth rate of 3.2%-4.2% through 2031. Operating as the primary acoustic-to-electronic bridge across all ultrasound diagnostic platforms, the transducer market is driven by three converging supply-side and regulatory dynamics: the industrial shift from polycrystalline lead zirconate titanate ceramics to high-coupling single-crystal and semiconductor micromachined arrays; escalating regulatory pressure regarding hazardous materials under European environmental directives; and the decentralization of procedural imaging toward ambulatory surgical platforms, interventional suites, and home-care settings.
The market encompasses an installation spectrum ranging from legacy multi-element piezoelectric arrays to ultra-high-frequency matrix architectures and silicon-based complementary metal-oxide-semiconductor systems. Original equipment manufacturers continue to leverage proprietary, active-multiplexed pinless interfaces to protect after-market service revenues and tie fleet replacement cycles to host consoles. Concurrently, an expanding ecosystem of independent acoustic engineering operations and third-party certified repair facilities is driving growth across the replacement channel, offering life-extension alternatives to high hospital capital budgets. Strategic audits confirm that regional policy interventions—such as equipment renewal initiatives in East Asia, outpatient prospective payment updates in the United States, and tightening lead exemptions within the European Union—are actively restructuring supply chains and compelling manufacturers to re-evaluate acoustic material integration, sub-probe thermal management, and transducer fabrication models.
TECHNICAL ARCHITECTURE AND ACOUSTIC OPERATING PRINCIPLES
The diagnostic ultrasound probe operates as a bidirectional electromechanical transducer governed by the direct and converse piezoelectric effects, converting alternating high-frequency electrical pulses into mechanical pressure waves during acoustic transmission, and translating tissue-scattered mechanical echoes back into microvolt-level radiofrequency signals during reception. While clinical diagnostic frequency regimes traditionally operate between 1.0 MHz and 20.0 MHz to optimize the trade-off between acoustic penetration depth and axial spatial resolution, specialized intravascular ultrasound and micro-vascular intraoperative applications routinely extend into ultra-high-frequency domains between 40.0 MHz and 60.0 MHz.
Anatomically, high-performance piezoelectric acoustic stacks comprise six functionally integrated layers engineered to control wave propagation and minimize acoustic attenuation:
● Acoustic Lens: Composed of specialized medical-grade silicone elastomers, the lens provides biocompatible patient contact, defines external elevation focusing via mechanical curvature, and acts as an acoustic propagation medium designed with an acoustic impedance near 1.5 MegaRayls to closely match human skin and transmission gels.
● Acoustic Matching Layers: Positioned immediately adjacent to the active piezoelectric layer, one to four matching layers mitigate the severe acoustic impedance mismatch between the high-impedance piezoelectric elements (approximately 30 to 35 MegaRayls for lead-based ceramics) and low-impedance biological tissue. Formulated from epoxy resins loaded with sub-micron metallic powders, cerium oxide, or aluminum oxide particles, these layers utilize quarter-wavelength thickness tuning to maximize acoustic transmission efficiency across extended operational bandwidths.
● Active Piezoelectric Layer: The core transduction engine, consisting of precision-diced blocks of polycrystalline lead zirconate titanate, high-coupling relaxor-based single crystals, or silicon micro-membranes. The material must exhibit elevated electromechanical coupling factors and low dielectric loss tangents to ensure maximum pulse-echo sensitivity.
● Backing Block: A dense, highly attenuating composite substrate—typically formulated with high-concentration tungsten powders embedded within an epoxy resin or silicone elastomer matrix—bonded directly to the rear electrode of the piezoelectric array. The backing block absorbs backward-propagating acoustic energy, dampens resonance rings to reduce spatial pulse length, and enhances axial resolution, while simultaneously conducting excess thermal energy away from the active array elements.
● Interconnects and Sub-Probe Electronics: High-density micro-flex circuits, anisotropic conductive films, and sub-probe application-specific integrated circuits engineered to route, switch, and multiplex signals from hundreds or thousands of miniaturized array elements through high-density micro-coaxial cable harnesses consisting of up to 512 shielded micro-wires.
● Housing and Shielding: An ergonomically contoured housing fabricated from chemical-resistant polymers, encapsulated within internal Faraday cages composed of copper or silver conductive shielding to prevent electromagnetic interference from hospital telemetry and operating room instrumentation.
ARRAY CLASSIFICATION AND SEGMENT ARCHITECTURE
Transducers are engineered into distinct structural geometries, directly dictating physical beam footprints, acoustic steering mechanisms, and clinical indications:
● Curvilinear Array Transducers
Curvilinear, or convex, transducers utilize an arc-shaped physical geometry, typically integrating 128 to 256 piezoelectric elements arranged along an arc radius ranging from 40 mm to 60 mm. The array projects a diverging, fan-shaped acoustic beam that widens with axial depth, presenting a deep, broad field-of-view particularly suited for abdominal and pelvic topologies. Operating frequencies span 1.0 MHz to 6.0 MHz for adult deep abdominal, hepatobiliary, and obstetrical evaluations, while tighter micro-convex variants operating between 5.0 MHz and 9.0 MHz are configured for pediatric and small-animal intercostal scanning. Commercial models incorporate multi-matching layer stacks and ternary single-crystal configurations to drive acoustic penetration through dense tissue barriers, as observed in high-tier clinical systems and specialized prenatal monitoring hardware.
● Linear Array Transducers
Linear transducers align between 128 and 512 piezoelectric elements along a completely flat operational plane, producing a parallel, rectangular acoustic beam that maintains an identical field-of-view across superficial and intermediate depths. Frequencies typically range from 5.0 MHz to 18.0 MHz, extending up to 50.0 MHz for ultra-high-resolution micro-vascular, dermatological, and small-parts examinations. Linear arrays eliminate beam-spreading distortion, delivering high near-field spatial resolution, contrast definition, and lateral line density. They represent the primary clinical tool for peripheral vascular assessment, carotid duplex screening, musculoskeletal tendon diagnostics, and superficial needle-guided interventions. High-frequency intraoperative variants feature miniaturized footprints engineered for direct vascular reconstruction patency evaluations.
● Phased Array Transducers
Phased array probes pack 64 to 128 tightly pitched acoustic elements into an ultra-compact footprint, typically measuring under 2 cm by 2 cm. In contrast to linear or convex arrays that fire element subgroups sequentially, phased array transducers actuate all elements near-simultaneously with nanosecond-level time delays. This electronic phase manipulation steers and focuses a narrow-apex sector beam dynamically across an arc up to 90 degrees without mechanical movement. Operating between 1.5 MHz and 5.0 MHz, phased arrays are tailored to transmit acoustic pulses through restricted intercostal acoustic windows, avoiding acoustic shadowing from adjacent ribs. They serve as the standard acoustic design for adult and pediatric transthoracic echocardiography, hemodynamic cardiac evaluations, and transcranial Doppler imaging.
● Endocavitary Transducers
Engineered for internal cavity positioning, endocavitary transducers—incorporating transvaginal, transrectal, and intracavitary configurations—feature an extended ergonomic shaft terminating in a micro-convex or biplane array with an operational field-of-view extending from 135 degrees to 210 degrees. Operating at intermediate frequencies between 5.0 MHz and 10.0 MHz, these transducers bypass structural acoustic attenuation caused by subcutaneous abdominal adipose layers and gastrointestinal gas pockets. Biplane iterations integrate two independent, orthogonally mounted arrays—one longitudinal and one transverse—within a singular probe tip, permitting real-time, multi-angle visualization during image-guided transrectal prostate biopsy interventions, early first-trimester embryonic morphology assessments, and assisted reproductive therapy follicle tracking.
● Matrix Array Transducers
Matrix array transducers represent advanced multi-dimensional acoustic technology. Moving beyond standard one-dimensional single-row configurations, true two-dimensional matrix arrays arrange thousands of micro-machined piezoelectric or single-crystal elements in a fully populated grid, such as 60 by 60 arrays yielding 3,600 or more active sub-elements. To circumvent the engineering impossibility of routing thousands of micro-coaxial lines through a handheld cable, matrix probes embed proprietary sub-array beamforming application-specific integrated circuits directly into the probe handle. These ASICs perform initial channel aggregation, micro-beamforming, and data compression prior to sending consolidated signals to the diagnostic console. Matrix arrays permit instantaneous 3D/4D volumetric rendering, real-time biplane cross-sectional visualization, and continuous electronic elevation beam focusing, effectively eliminating out-of-plane slice-thickness artifacts.
DOWNSTREAM APPLICATION MARKETS AND SECTOR PENETRATION
● Human Clinical Healthcare
Human clinical healthcare commands approximately 95% of total annual transducer procurement expenditures across public and private hospitals, academic medical centers, ambulatory surgery centers, and specialty clinics:
Cardiovascular and Structural Heart Disease: Echocardiography demands high-durability phased array and 4D matrix transducers capable of rapid frame rates and continuous Doppler interrogation. The expanding domain of structural heart interventions—such as transcatheter aortic valve replacements, mitral edge-to-edge repairs, and left atrial appendage closures—has elevated capital commitments for multi-plane transesophageal echocardiography probes and single-use or limited-reuse 4D intracardiac echocardiography catheter transducers.
Obstetrics, Gynecology, and Reproductive Medicine: High-resolution curved arrays, electronic volumetric matrix probes, and micro-convex endocavitary transducers are essential across obstetrical stages, from first-trimester nuchal translucency evaluations to late-stage fetal cardiac morphology assessments. In parallel, the expansion of assisted reproductive technologies relies on specialized endocavitary probes optimized for fine-needle transvaginal ovum retrieval and ovarian follicle monitoring.
Abdominal, Internal Medicine, and Endocrinology: Curvilinear and linear transducers handle high clinical caseloads targeting hepatic steatosis stratification, metabolic dysfunction-associated steatohepatitis scoring, renal parenchyma evaluation, and thyroid nodule risk classification via shear wave elastography.
Emergency Medicine, Intensive Care, and Point-of-Care Ultrasound: Critical care suites and emergency departments are standardizing on shock-resistant, multi-preset linear, phased, and single-probe semiconductor transducers. Point-of-care ultrasound platforms provide rapid diagnostic triage for trauma evaluations, acute respiratory failure monitoring, and peripheral vascular catheter placement.
Intraoperative Surgical Guidance and Interventional Quality Control: Specialized intraoperative transducers provide real-time anatomical validation. Epicardial high-frequency ultrasound linear transducers paired with transit-time flow measurement probes verify coronary artery bypass graft patency before closing the thoracic cavity, protecting against intraoperative ischemia. Concurrently, sub-millimeter 50 MHz to 60 MHz single-crystal catheter transducers integrated into intravascular ultrasound systems deliver circumferential cross-sectional visualization of coronary lumen dimensions and plaque morphology during percutaneous coronary interventions. In minimally invasive surgery, articulated laparoscopic ultrasound probes guide parenchymal transection lines during complex hepatic and renal resections.
Therapeutic Acoustic Applications: Non-diagnostic, low-frequency surface acoustic wave patch transducers are deploying into adjunctive clinical niches, utilizing targeted micro-vibrational mechanical waves to disrupt bacterial biofilm development on indwelling urethral catheters and accelerate chronic tissue repair pathways.
● Veterinary Medicine and Animal Healthcare
Representing approximately 5% of global transducer volume, the veterinary sector demonstrates steady procurement expansion driven by companion animal humanization and industrial livestock reproductive management:
Small Animal Clinical Practice: Veterinary referral centers and general clinics deploy human-grade micro-convex and linear probes adapted with veterinary-specific software algorithms for feline and canine abdominal, cardiac, and musculoskeletal diagnostics.
Equine and Large Animal Practice: Specialized high-frequency linear transducers enclosed in ruggedized, drop-resistant housings are utilized for equine musculoskeletal tendon integrity verification. For livestock production, durable, water-resistant linear rectal probes with direct mechanical reinforcement are deployed across bovine and swine operations to manage artificial insemination protocols, fetal sexing, and herd reproductive cycles.
SALES CHANNELS AND COMMERCIALIZATION MODELS
● Original Equipment Manufacturer Channel
The OEM channel forms the foundation of commercial transducer transactions, executed primarily through bundled sales during capital imaging console acquisitions. Multimodal imaging conglomerates integrate proprietary probe interfaces, mechanical pinless zero-insertion-force interconnects, and dynamic cryptographic handshakes that prevent third-party transducers from operating on their consoles without authorized software authentication.
Standard commercial shipments bundle an average of two to four specialty transducers per cart-based imaging platform, incorporating standard convex, linear, and phased arrays. The OEM segment delivers high gross profit margins through proprietary intellectual property control, high barrier-to-entry manufacturing requirements, and embedded long-term institutional service agreements. Within this framework, specialized independent acoustic device developers and semiconductor foundries engage in direct business-to-business supply arrangements, delivering proprietary crystal stacks, custom acoustic sub-assemblies, or wafer-scale silicon components to major capital platform assemblers.
● Aftermarket, Replacement, and Emerging Commercial Channels
The transducer aftermarket operates as a vital operational buffer for healthcare systems managing heavy asset utilization. Ultrasound probes are high-wear consumables subject to frequent drop impacts, piezoelectric element micro-fractures, acoustic lens delamination, strain-relief cable severance, and chemical material degradation caused by high-level chemical disinfection procedures.
Replacing a premium single-crystal or 4D matrix transducer through original OEM channels frequently requires expenditures ranging between 3,000 and 15,000 USD or more per probe assembly. Consequently, hospital clinical engineering departments, healthcare technology management organizations, and independent service operators actively procure certified third-party replacement transducers or utilize dedicated ISO 13485-compliant probe remanufacturing facilities. These specialty repair sites execute precision acoustic re-lensing, micro-coaxial cable replacements, strain-relief recasting, and element array re-matching, lowering probe replacement operating costs by 40% to 60%.
In parallel, point-of-care market entrants are transforming transducer procurement through direct-to-practitioner e-commerce sales and software-as-a-service operating models. Handheld semiconductor transducers are distributed directly to end-users, uncoupling hardware acquisition from protracted hospital capital committee budget cycles. These purchases are paired with recurring annual enterprise software fees covering image management, tele-guidance capabilities, and regulatory compliance storage. Additionally, intraoperative surgical probe suppliers maintain procedural utilization models, deploying surgical flow and imaging probes on per-procedure fee schedules or structured reusable cycles, shifting capital outlays into variable operational expenses for surgical suites.
REGIONAL MARKET DYNAMICS AND POLICY FRAMEWORKS
● North America
North America represents the largest regional market by revenue, supported by private healthcare capital expenditure, expansive diagnostic procedural volumes, and rapid clinical adoption of handheld point-of-care probes across emergency and critical care departments. The regulatory environment is structured by the United States Food and Drug Administration through Class II 510(k) clearances and De Novo pathways, which impose rigorous mechanical, thermal, and acoustic output reporting governed by track-3 acoustic output measurement guidelines (IEC 60601-2-37).
Institutional procurement strategies align closely with the Centers for Medicare & Medicaid Services reimbursement models, hospital value-based purchasing frameworks, and American Medical Association Current Procedural Terminology guidelines. The adoption of advanced quantitative imaging is reinforced by updates to procedural terminology, such as the introduction of Category III CPT codes for three-dimensional volumetric ultrasound tomography, signaling eventual reimbursement routes for emerging automated volumetric transducers.
Concurrently, public legislative programs—such as federal investments aimed at reducing rural maternal healthcare deserts—are driving clinical validation trials and health insurance reimbursement for at-home fetal and maternal tele-ultrasound systems. Cross-border trade policies, bilateral tariffs, and rules of origin under the United States-Mexico-Canada Agreement directly impact supply chain operating costs for midstream transducer manufacturing facilities located across North American trade corridors.
● Asia-Pacific
The Asia-Pacific region demonstrates the highest compound annual growth rate, propelled by state-backed healthcare infrastructure programs, expanding hospital networks, aging demographics, and concentrated domestic manufacturing capacity.
China operates as a key manufacturing hub and a rapidly expanding domestic consumption market. Chinese industrial policy, guided by Five-Year Plan directives, actively stimulates tier-three and county-level hospital infrastructure development. Programs like the national equipment renewal policy, backed by ultra-long special treasury bonds, are systematically financing the modernization of diagnostic imaging fleets. Furthermore, updated national equipment configuration guidelines for primary healthcare facilities have classified color Doppler ultrasound systems as mandatory equipment for township health centers, generating large-scale transducer procurement orders.
In parallel, the aggressive implementation of provincial and inter-provincial centralized Volume-Based Procurement frameworks has introduced severe downward pricing pressure on capital carts and replacement probes. This price compression is driving hospital procurement committees away from costly imported OEM assemblies toward domestic single-crystal and linear array manufacturers. China's transducer ecosystem contains both integrated OEMs and a network of specialized aftermarket and replacement manufacturers capable of delivering cost-effective replacement probes across public clinical networks.
Across the broader Asia-Pacific landscape, Japan and South Korea serve as advanced acoustic engineering and high-density semiconductor micro-machining centers. Taiwan, China remains critical to global transducer roadmaps, anchoring foundries that execute MEMS silicon wafer fabrication for next-generation CMUT and PMUT devices, alongside third-party probe replacement developers.
● Europe
Western and Northern European markets are defined by high equipment utilization rates, public healthcare system replacements, stringent environmental safety Directives, and advanced clinical research across academic medical hubs.
Regulatory compliance is governed by the European Union Medical Device Regulation (EU MDR 2017/745). The transition from legacy directives to MDR has increased clinical evidence burdens, extended Notified Body audit schedules, and institutionalized post-market surveillance via Periodic Safety Update Reports and EUDAMED Unique Device Identification systems. This has lengthened the regulatory clearance cycle for specialized and novel transducer architectures entering the European Economic Area.
Concurrently, the European Union's Restriction of Hazardous Substances Directive (RoHS Directive 2011/65/EU) remains a major strategic factor for ultrasound materials science. The directive restricts lead content in electrical and electronic equipment, but the ultrasound industry historically operated under temporary exemptions under Annex III (Exemption 14) allowing lead in single-crystal and PZT piezoelectric materials due to performance constraints of lead-free ceramics.
Regulatory reassessments and delegated directives from the European Commission reviewing lead exemptions have intensified scrutiny on traditional probe supply chains. This regulatory tension has created commercial opportunities for lead-free semiconductor CMUT ultrasound-on-chip platforms, which natively comply with RoHS directives without requiring exemptions, prompting technology providers to petition for the phase-out of lead allowances in handheld probe categories.
● Latin America
Latin America is marked by expanding private healthcare networks and capital modernization programs across Brazil, Mexico, Colombia, Chile, and Argentina. The clinical landscape demonstrates steady migration toward portable and point-of-care ultrasound platforms designed to bridge geographic diagnostic gaps in non-urban facilities. Regional regulatory entities—such as the National Health Surveillance Agency (ANVISA) in Brazil and COFEPRIS in Mexico—continue to harmonize device registration pathways with international standards. Global manufacturers are establishing local legal entities, distribution logistics centers, and commercial subsidiaries across Brazil and Mexico to navigate import duties, currency volatility, and local hospital tender requirements.
● Middle East and Africa
Market development across the Middle East is anchored by extensive public infrastructure expenditures, modernization master plans, and public-private healthcare investments across the Gulf Cooperation Council, led by Saudi Arabia under Vision 2030 initiatives, the United Arab Emirates, and Qatar. These programs support the procurement of high-tier matrix array, structural heart, and 4D volumetric imaging platforms across newly constructed tertiary hospitals and specialized oncology centers. Across the broader African continent, international development aid, maternal health initiatives, and donor-funded programs prioritize basic cart-based and ruggedized point-of-care ultrasound transducers capable of operating reliably in variable ambient temperatures and infrastructure-constrained environments.
COMPETITIVE DOSSIERS: KEY INDUSTRY PARTICIPANTS
● GE Healthcare: Global operational headquarters in Chicago, Illinois, USA, supported by major acoustic manufacturing centers in North America, Europe, and East Asia.
● Siemens Healthineers: Global headquarters in Erlangen, Germany, with specialized acoustic fabrication facilities and ultrasound development operations in Mountain View, California, and Issaquah, Washington, USA.
● Royal Philips: Global ultrasound business centered in Cambridge, Massachusetts, USA, with acoustic stack manufacturing operations based in Reedsville, Pennsylvania, USA.
● Canon Medical Systems: Global headquarters in Otawara, Tochigi, Japan, utilizing precision acoustic engineering and assembly infrastructure across domestic Japanese facilities.
● The rest of companies covered in the report: Fujifilm Healthcare, Samsung Healthcare, Mindray Medical, Esaote SpA, SonoScape Medical Corp., CHISON Medical Technologies Co., Ltd., Edan Instruments, Inc., VINNO Technology (Suzhou) Co. Ltd., Shantou Institute of Ultrasonic Instruments Co. Ltd. (SIUI), Butterfly Network, Inc., Medistim ASA, and Pulsenmore Ltd.
● Transducer Component OEMs, ODM Developers, and Aftermarket Specialists: Vermon, Broadsound Corporation, Ueda Japan Radio Co., Ltd. (UJRC), Shenzhen Wisonic Medical Technology, and Shenzhen WELLD Medical Electronics Co. Ltd.
OPPORTUNITIES, STRUCTURAL INHIBITORS, AND RISK MATRIX
● Semiconductor Transition and RoHS Directives
The commercialization of silicon-based CMUT and PMUT architectures represents a foundational structural shift for the transducer industry. By fabricating acoustic membranes directly onto CMOS wafers via commercial semiconductor foundries, manufacturers can lower per-element production costs, eliminate manual micro-dicing, and achieve high acoustic bandwidths from a single physical chip.
This technological pivot is accelerated by European environmental regulations. The European Union's RoHS Directive (2011/65/EU) strictly limits lead concentrations in medical devices. While traditional lead zirconate titanate ceramics and lead-based single crystals have historically relied on temporary exemptions under Annex III due to functional performance constraints, these allowances are facing increasing regulatory scrutiny. The European Commission’s ongoing review of lead exemptions has created strategic friction across the value chain. Lead-free semiconductor transducer developers are actively petitioning regulatory authorities to sunset exemptions for handheld probe formats. Traditional OEMs face substantial R&D reinvestment cycles to redesign acoustic stacks, validate lead-free piezoelectric alternatives, or pivot toward silicon-based foundry architectures before environmental restrictions narrow further.
● Expansion into Interventional and Surgical Navigation Domains
Ultrasound transducers are rapidly expanding beyond external diagnostic radiology departments into high-margin surgical operating suites and interventional catheterization laboratories. This transition is characterized by three specialized application vectors:
Intraoperative Quality Control: Direct surgical imaging probes—such as epiaortic high-frequency linear transducers and transit-time flow measurement probes—are becoming standard in coronary artery bypass grafting and peripheral vascular reconstructions, providing objective hemodynamic verification of graft patency before closing the chest cavity.
Intravascular Ultrasound: Miniaturized 50 MHz to 60 MHz single-crystal composite catheter transducers are expanding in interventional cardiology, driving vessel lumen assessment and stent placement optimization.
Minimally Invasive Interventional Tools: The demand for flexible laparoscopic ultrasound probes and micro-machined intracardiac echocardiography catheters is accelerating as structural heart repairs and robotic oncological resections increasingly require continuous, high-definition internal volumetric imaging.
● Ambulatory, Tele-Health, and Home Care Decentralization
Diagnostic imaging is steadily migrating outside traditional hospital acoustic radiology departments. Driven by demographic shifts, expanding outpatient care models, and consumer digital health adoption, the industry is witnessing the commercial expansion of three transducer categories:
Handheld Multi-Preset Probes: Smartphone-connected point-of-care devices are establishing standard clinical roles across emergency medical services, bedside triage, and intensive care line-placement procedures.
At-Home Tele-Ultrasound Systems: FDA-cleared prenatal monitoring docks that utilize smartphone-docked curved array transducers allow pregnant individuals to capture fetal cardiac activity and amniotic metrics for asynchronous specialist review, addressing maternal care shortages in geographically remote communities.
Remote Disease Monitoring: Specialized home-monitoring transducers are entering clinical trials for remote monitoring of chronic conditions, including automated ovarian follicle monitoring during assisted reproductive therapy and lung fluid tracking for congestive heart failure patients.
● Structural Industry Risks and Operational Inhibitors
- Upstream Concentration and Single-Source Bottlenecks: The supply chain for advanced transducers remains exposed to critical upstream dependencies. Relaxor single-crystal production relies on a small group of specialty crystal growers; advanced silicon MEMS arrays are tied to leading semiconductor foundries like TSMC in Taiwan, China; and high-density micro-coaxial cable draws are concentrated across few suppliers. Structural disruptions, raw material cost surges, or regional geopolitical friction across these nodes represent direct vulnerabilities to global delivery timelines.
- Probe Fragility, Chemical Degradation, and Infection Control Demands: Transducers are structurally vulnerable instruments deployed in high-throughput, mechanically rigorous clinical environments. High hospital replacement rates stem from accidental drops, transducer element cracking, and acoustic lens delamination. Furthermore, the clinical mandate for high-level chemical disinfection (using agents like glutaraldehyde or hydrogen peroxide vapor) to eliminate cross-contamination accelerates the chemical degradation of silicone lenses and polymeric strain reliefs, requiring hospital engineering departments to balance replacement budgets against infection prevention mandates.
- Competitive Aftermarket Erosion: The growth of certified third-party probe remanufacturing facilities and direct-replacement transducer manufacturers provides healthcare institutions with low-cost operational alternatives to original OEM replacements. As third-party acoustic diagnostic analyzers allow clinical engineers to validate repaired probe sensitivity and beam integrity, OEM capture rates for high-margin aftermarket probe replacements will face sustained commercial pressure through 2031.
1.1 Executive Summary and Industry Scope 1
1.2 Research Methodology and Statistical Framework 2
1.2.1 Data Sourcing and Verification Architecture 2
1.2.2 Top-down and Bottom-up Triangulation Models 3
1.2.3 Forecasting Assumptions and Parametric Modeling 4
1.3 Currency Conversion and Pricing Indexations 5
1.4 Acronyms and Technical Nomenclature 6
Chapter 2 Diagnostic Ultrasound Transducer Global Market Overview 7
2.1 Product Definition, Taxonomy, and Core Working Mechanisms 7
2.2 Global Diagnostic Ultrasound Transducer Market Scale: Value (USD Million) and Volume (Thousand Units) (2021-2031) 8
2.3 PZT Piezoelectric vs. CMUT/PMUT Technology Transition Vectors 10
2.4 Price Evolution and Cost Erosion Trajectories (2021-2031) 12
2.5 High-Frequency and Ultra-Wideband Acoustic Transduction Drivers 14
Chapter 3 Industry Supply Chain and Value Migration Dynamics 16
3.1 Upstream Acoustic Component Sourcing and Raw Material Ecosystem 16
3.1.1 Piezoelectric Ceramics, Single Crystals, and Micromachined Silicon Substrates 16
3.1.2 Acoustic Matching Layers, Demagnification Lens, and Backing Blocks 18
3.1.3 High-Density Micro-Coaxial Cabling and Interconnect Assemblies 19
3.1.4 Front-End Integrated ASICs and Analog Beamforming Transceivers 20
3.2 Middle-Stream Manufacturing, Array Dicing, and Acoustic Assembly 21
3.3 Value Chain Margin Distribution from Component to OEM/Aftermarket 23
3.4 Supply Chain Disruption Vectors and Critical Sourcing Dependencies 24
Chapter 4 Global Market by Product Type 26
4.1 Typology Breakdown and Technical Differentiation 26
4.2 Curvilinear Array Transducers Market Volume, Revenue, and Forecast (2021-2031) 27
4.3 Linear Array Transducers Market Volume, Revenue, and Forecast (2021-2031) 29
4.4 Phased Array Transducers Market Volume, Revenue, and Forecast (2021-2031) 31
4.5 Endocavitary Transducers Market Volume, Revenue, and Forecast (2021-2031) 33
4.6 Matrix Array Transducers Market Volume, Revenue, and Forecast (2021-2031) 35
Chapter 5 Global Market by Sales Channel 38
5.1 Channel Architecture and Revenue Realization Models 38
5.2 Original Equipment Manufacturer (OEM) Integration Channel (2021-2031) 39
5.2.1 Console-Integrated Bundling and Systems Supply Contracts 39
5.2.2 Pure-Play Transducer Foundries vs. Vertically Integrated OEMs 41
5.3 Aftermarket and Replacement Channel (2021-2031) 42
5.3.1 Hospital Procurement, Lens Repair, and Probe Refurbishment 42
5.3.2 Third-Party Probe Compatibility Dynamics and Warranty Lifecycle 44
Chapter 6 Global Market by Downstream Clinical Application 46
6.1 Downstream Application Mix and Transducer Utilization Densities 46
6.2 Radiology and General Imaging 47
6.3 Cardiology and Cardiovascular Diagnostics 48
6.4 Obstetrics and Gynecology (OB/GYN) 50
6.5 Vascular and Musculoskeletal (MSK) Diagnostics 51
6.6 Point-of-Care Ultrasound (POCUS) and Ultraportable Solutions 53
6.7 Intraoperative, Laparoscopic, and Surgical Specialty Arrays 55
Chapter 7 Global Trade Flows, Tariffs, and Cross-Border Logistics 57
7.1 Global Production Hubs vs. Net Consuming Geos 57
7.2 Major Export Trade Corridors: North America, Western Europe, and East Asia 58
7.3 Import Dependency, Customs Classifications, and Strategic Tariffs 60
7.4 Regulatory Clearance Bottlenecks (FDA 510(k), MDR Annex VII, NMPA) 62
Chapter 8 Regional Production Hubs and Consumption Markets 65
8.1 North America Diagnostic Ultrasound Transducer Market Analysis 65
8.1.1 United States: Production Infrastructure and Consumption Volumes 66
8.1.2 Canada: Procurement Mechanisms and Clinical Demand 68
8.2 Europe Diagnostic Ultrasound Transducer Market Analysis 70
8.2.1 Germany: Precision Acoustic Manufacturing and Clinical Base 71
8.2.2 France: High-End Specialty Array Sourcing 73
8.2.3 United Kingdom: NHS Procurement and Installed Base Replacement 74
8.2.4 Italy: Specialized OEM Integration and Clinical Adoption 75
8.2.5 Netherlands & Rest of Europe Market 76
8.3 Asia-Pacific Diagnostic Ultrasound Transducer Market Analysis 77
8.3.1 China: Domestic Substitution, High-Volume Manufacturing, and Sourcing 78
8.3.2 Japan: Proprietary Crystal Fabrication and System Integration 80
8.3.3 South Korea: Mid-to-High Tier Array Export Hubs 81
8.3.4 Taiwan (China): Micro-Fabrication, Foundries, and Transducer Assembly 82
8.3.5 India & Southeast Asia: Secondary Demand Expansion and Healthcare Modernization 83
8.4 Latin America Diagnostic Ultrasound Transducer Market Analysis 84
8.4.1 Brazil: Import Regimes and Healthcare Demand 84
8.4.2 Mexico: Cross-Border Assembly Dynamics 85
8.5 Middle East and Africa Diagnostic Ultrasound Transducer Market Analysis 86
8.5.1 Kingdom of Saudi Arabia and United Arab Emirates 86
8.5.2 South Africa: Public vs. Private Healthcare Fleet Upgrades 87
Chapter 9 Competitive Landscape and Market Concentration 88
9.1 Industry Concentration Ratios (CR4, CR8, and HHI Analysis) 88
9.2 OEM Captive Manufacturing vs. Independent Transducer Merchant Suppliers 89
9.3 Strategic Partnerships, Co-Development, and Cross-Licensing 91
9.4 Mergers and Acquisitions (M&A) Evaluation (2021-2026) 93
Chapter 10 Corporate Intelligence: Diagnostic Ultrasound Transducer Competitors 95
10.1 GE Healthcare 95
10.1.1 Corporate Profile and Acoustic Transducer Product Matrix 95
10.1.2 SWOT Assessment and Production Footprint 96
10.1.3 Operational Performance: Sales, Price, Cost, Margin, and Market Share 97
10.2 Siemens Healthineers 98
10.2.1 Corporate Profile and Acoustic Transducer Product Matrix 98
10.2.2 SWOT Assessment and Production Footprint 99
10.2.3 Operational Performance: Sales, Price, Cost, Margin, and Market Share 100
10.3 Philips 101
10.3.1 Corporate Profile and Acoustic Transducer Product Matrix 101
10.3.2 SWOT Assessment and Production Footprint 102
10.3.3 Operational Performance: Sales, Price, Cost, Margin, and Market Share 103
10.4 Fujifilm Healthcare 104
10.4.1 Corporate Profile and Acoustic Transducer Product Matrix 104
10.4.2 SWOT Assessment and Production Footprint 105
10.4.3 Operational Performance: Sales, Price, Cost, Margin, and Market Share 106
10.5 Canon Medical 107
10.5.1 Corporate Profile and Acoustic Transducer Product Matrix 107
10.5.2 SWOT Assessment and Production Footprint 108
10.5.3 Operational Performance: Sales, Price, Cost, Margin, and Market Share 109
10.6 Esaote 110
10.6.1 Corporate Profile and Acoustic Transducer Product Matrix 110
10.6.2 SWOT Assessment and Production Footprint 111
10.6.3 Operational Performance: Sales, Price, Cost, Margin, and Market Share 112
10.7 Mindray 113
10.7.1 Corporate Profile and Acoustic Transducer Product Matrix 113
10.7.2 SWOT Assessment and Production Footprint 114
10.7.3 Operational Performance: Sales, Price, Cost, Margin, and Market Share 115
10.8 Ueda Japan Radio Co., Ltd. (UJRC) 116
10.8.1 Corporate Profile and Acoustic Transducer Product Matrix 116
10.8.2 SWOT Assessment and Production Footprint 117
10.8.3 Operational Performance: Sales, Price, Cost, Margin, and Market Share 118
10.9 SonoScape 119
10.9.1 Corporate Profile and Acoustic Transducer Product Matrix 119
10.9.2 SWOT Assessment and Production Footprint 120
10.9.3 Operational Performance: Sales, Price, Cost, Margin, and Market Share 121
10.10 Shantou Institute of Ultrasonic Instruments Co. Ltd (SIUI) 122
10.10.1 Corporate Profile and Acoustic Transducer Product Matrix 122
10.10.2 SWOT Assessment and Production Footprint 123
10.10.3 Operational Performance: Sales, Price, Cost, Margin, and Market Share 124
10.11 Shenzhen Wisonic Medical Technology 125
10.11.1 Corporate Profile and Acoustic Transducer Product Matrix 125
10.11.2 SWOT Assessment and Production Footprint 126
10.11.3 Operational Performance: Sales, Price, Cost, Margin, and Market Share 127
10.12 VINNO Technology (Suzhou) Co. Ltd. 128
10.12.1 Corporate Profile and Acoustic Transducer Product Matrix 128
10.12.2 SWOT Assessment and Production Footprint 129
10.12.3 Operational Performance: Sales, Price, Cost, Margin, and Market Share 130
10.13 Shenzhen WELLD Medical Electronics Co. Ltd. 131
10.13.1 Corporate Profile and Acoustic Transducer Product Matrix 131
10.13.2 SWOT Assessment and Production Footprint 132
10.13.3 Operational Performance: Sales, Price, Cost, Margin, and Market Share 133
10.14 Samsung Healthcare 134
10.14.1 Corporate Profile and Acoustic Transducer Product Matrix 134
10.14.2 SWOT Assessment and Production Footprint 135
10.14.3 Operational Performance: Sales, Price, Cost, Margin, and Market Share 136
10.15 Butterfly Network 137
10.15.1 Corporate Profile and Acoustic Transducer Product Matrix 137
10.15.2 SWOT Assessment and Production Footprint 138
10.15.3 Operational Performance: Sales, Price, Cost, Margin, and Market Share 139
10.16 CHISON Medical 140
10.16.1 Corporate Profile and Acoustic Transducer Product Matrix 140
10.16.2 SWOT Assessment and Production Footprint 141
10.16.3 Operational Performance: Sales, Price, Cost, Margin, and Market Share 142
10.17 Edan Instruments 143
10.17.1 Corporate Profile and Acoustic Transducer Product Matrix 143
10.17.2 SWOT Assessment and Production Footprint 144
10.17.3 Operational Performance: Sales, Price, Cost, Margin, and Market Share 145
10.18 Medistim ASA 146
10.18.1 Corporate Profile and Acoustic Transducer Product Matrix 146
10.18.2 SWOT Assessment and Production Footprint 147
10.18.3 Operational Performance: Sales, Price, Cost, Margin, and Market Share 148
10.19 Pulsenmore Ltd 149
10.19.1 Corporate Profile and Acoustic Transducer Product Matrix 149
10.19.2 SWOT Assessment and Production Footprint 150
10.19.3 Operational Performance: Sales, Price, Cost, Margin, and Market Share 151
10.20 Broadsound Corporation 152
10.20.1 Corporate Profile and Acoustic Transducer Product Matrix 152
10.20.2 SWOT Assessment and Production Footprint 153
10.20.3 Operational Performance: Sales, Price, Cost, Margin, and Market Share 154
10.21 Vermon 155
10.21.1 Corporate Profile and Acoustic Transducer Product Matrix 155
10.21.2 SWOT Assessment and Production Footprint 156
10.21.3 Operational Performance: Sales, Price, Cost, Margin, and Market Share 157
Table 2 Currency Valuation and Average Exchange Rates Against USD (2021-2026) 5
Table 3 Global Diagnostic Ultrasound Transducer Market Value (USD Million) by Product Type (2021-2031) 8
Table 4 Global Diagnostic Ultrasound Transducer Market Volume (Thousand Units) by Product Type (2021-2031) 9
Table 5 Average Selling Price (ASP) Comparison by Transducer Type (USD/Unit) (2021-2031) 13
Table 6 Raw Material and Component Bill of Materials (BOM) Breakdown for Medical Arrays 17
Table 7 Global Curvilinear Array Transducer Market Scale and Growth Rate (2021-2031) 28
Table 8 Global Linear Array Transducer Market Scale and Growth Rate (2021-2031) 30
Table 9 Global Phased Array Transducer Market Scale and Growth Rate (2021-2031) 32
Table 10 Global Endocavitary Transducer Market Scale and Growth Rate (2021-2031) 34
Table 11 Global Matrix Array Transducer Market Scale and Growth Rate (2021-2031) 36
Table 12 Global Diagnostic Ultrasound Transducer Market by Sales Channel (USD Million) (2021-2031) 39
Table 13 Global OEM Channel Transducer Shipments and Value Growth (2021-2031) 40
Table 14 Global Aftermarket and Replacement Transducer Shipments and Value Growth (2021-2031) 43
Table 15 Global Diagnostic Ultrasound Transducer Market by Clinical Application (USD Million) (2021-2031) 47
Table 16 Radiology Diagnostic Ultrasound Transducer Market Size and Forecast (2021-2031) 48
Table 17 Cardiology Diagnostic Ultrasound Transducer Market Size and Forecast (2021-2031) 49
Table 18 Obstetrics and Gynecology Transducer Market Size and Forecast (2021-2031) 51
Table 19 Vascular and MSK Transducer Market Size and Forecast (2021-2031) 52
Table 20 POCUS and Ultraportable Transducer Market Size and Forecast (2021-2031) 54
Table 21 Intraoperative and Surgical Transducer Market Size and Forecast (2021-2031) 56
Table 22 Top 10 Transducer Exporting Hubs and Net Trade Balances (USD Million) (2025-2026) 59
Table 23 Critical HS Tariff Codes and Applied Duty Rates for Diagnostic Acoustic Probes 61
Table 24 Global Diagnostic Ultrasound Transducer Market by Region (USD Million) (2021-2031) 65
Table 25 North America Transducer Market Value and Volume by Country (2021-2031) 66
Table 26 United States Transducer Market by Type and Channel (2021-2031) 67
Table 27 Canada Transducer Market by Type and Channel (2021-2031) 69
Table 28 Europe Transducer Market Value and Volume by Country (2021-2031) 70
Table 29 Germany Transducer Market by Type and Channel (2021-2031) 72
Table 30 France Transducer Market by Type and Channel (2021-2031) 73
Table 31 United Kingdom Transducer Market by Type and Channel (2021-2031) 74
Table 32 Italy Transducer Market by Type and Channel (2021-2031) 75
Table 33 Netherlands Transducer Market by Type and Channel (2021-2031) 76
Table 34 Asia-Pacific Transducer Market Value and Volume by Country (2021-2031) 77
Table 35 China Diagnostic Ultrasound Transducer Production and Consumption (2021-2031) 79
Table 36 Japan Diagnostic Ultrasound Transducer Market by Type and Channel (2021-2031) 80
Table 37 South Korea Transducer Market by Type and Channel (2021-2031) 81
Table 38 Taiwan (China) Transducer Market and Component Assembly Exports (2021-2031) 82
Table 39 India Transducer Market by Type and Channel (2021-2031) 83
Table 40 Latin America Transducer Market by Country (2021-2031) 84
Table 41 Middle East and Africa Transducer Market by Country (2021-2031) 86
Table 42 Leading Transducer Suppliers Market Share Ranking (2025-2026) 89
Table 43 Pure-Play Transducer Manufacturers vs. Integrated System OEMs Capability Index 90
Table 44 GE Healthcare Diagnostic Ultrasound Transducer Sales, Price, Cost and Gross Profit Margin (2021-2026) 97
Table 45 Siemens Healthineers Diagnostic Ultrasound Transducer Sales, Price, Cost and Gross Profit Margin (2021-2026) 100
Table 46 Philips Diagnostic Ultrasound Transducer Sales, Price, Cost and Gross Profit Margin (2021-2026) 103
Table 47 Fujifilm Healthcare Diagnostic Ultrasound Transducer Sales, Price, Cost and Gross Profit Margin (2021-2026) 106
Table 48 Canon Medical Diagnostic Ultrasound Transducer Sales, Price, Cost and Gross Profit Margin (2021-2026) 109
Table 49 Esaote Diagnostic Ultrasound Transducer Sales, Price, Cost and Gross Profit Margin (2021-2026) 112
Table 50 Mindray Diagnostic Ultrasound Transducer Sales, Price, Cost and Gross Profit Margin (2021-2026) 115
Table 51 Ueda Japan Radio Co., Ltd. (UJRC) Diagnostic Ultrasound Transducer Sales, Price, Cost and Gross Profit Margin (2021-2026) 118
Table 52 SonoScape Diagnostic Ultrasound Transducer Sales, Price, Cost and Gross Profit Margin (2021-2026) 121
Table 53 Shantou Institute of Ultrasonic Instruments Co. Ltd (SIUI) Diagnostic Ultrasound Transducer Sales, Price, Cost and Gross Profit Margin (2021-2026) 124
Table 54 Shenzhen Wisonic Medical Technology Diagnostic Ultrasound Transducer Sales, Price, Cost and Gross Profit Margin (2021-2026) 127
Table 55 VINNO Technology (Suzhou) Co. Ltd. Diagnostic Ultrasound Transducer Sales, Price, Cost and Gross Profit Margin (2021-2026) 130
Table 56 Shenzhen WELLD Medical Electronics Co. Ltd. Diagnostic Ultrasound Transducer Sales, Price, Cost and Gross Profit Margin (2021-2026) 133
Table 57 Samsung Healthcare Diagnostic Ultrasound Transducer Sales, Price, Cost and Gross Profit Margin (2021-2026) 136
Table 58 Butterfly Network Diagnostic Ultrasound Transducer Sales, Price, Cost and Gross Profit Margin (2021-2026) 139
Table 59 CHISON Medical Diagnostic Ultrasound Transducer Sales, Price, Cost and Gross Profit Margin (2021-2026) 142
Table 60 Edan Instruments Diagnostic Ultrasound Transducer Sales, Price, Cost and Gross Profit Margin (2021-2026) 145
Table 61 Medistim ASA Diagnostic Ultrasound Transducer Sales, Price, Cost and Gross Profit Margin (2021-2026) 148
Table 62 Pulsenmore Ltd Diagnostic Ultrasound Transducer Sales, Price, Cost and Gross Profit Margin (2021-2026) 151
Table 63 Broadsound Corporation Diagnostic Ultrasound Transducer Sales, Price, Cost and Gross Profit Margin (2021-2026) 154
Table 64 Vermon Diagnostic Ultrasound Transducer Sales, Price, Cost and Gross Profit Margin (2021-2026) 157
List of Figures
Figure 1 Global Diagnostic Ultrasound Transducer Value and Growth Trajectory (2021-2031) 9
Figure 2 Diagnostic Ultrasound Transducer Architecture and Sub-Component Diagram 11
Figure 3 Upstream to Downstream Value Capture Breakdown Across the Supply Chain 23
Figure 4 Global Transducer Value Share by Product Architecture (2021, 2026, 2031) 27
Figure 5 Curvilinear Array Transducers Revenue Trajectory (2021-2031) 28
Figure 6 Linear Array Transducers Revenue Trajectory (2021-2031) 30
Figure 7 Phased Array Transducers Revenue Trajectory (2021-2031) 32
Figure 8 Endocavitary Transducers Revenue Trajectory (2021-2031) 34
Figure 9 Matrix Array Transducers Revenue Trajectory (2021-2031) 36
Figure 10 Global Diagnostic Ultrasound Transducer Revenue Split by Sales Channel (2021-2031) 38
Figure 11 OEM vs. Aftermarket Transducer Volume Distribution (2026) 41
Figure 12 Downstream Clinical Application Breakdown by Market Value (2026) 46
Figure 13 Global Trade Heatmap: Key Ultrasound Probe Fabrication vs. Consumption Hotspots 58
Figure 14 Regional Revenue Share Breakdown (2021, 2026, 2031) 66
Figure 15 United States Ultrasound Transducer Market Dynamics (2021-2031) 68
Figure 16 Western Europe Transducer Consumption Penetration Index 71
Figure 17 China Domestic vs. Imported Ultrasound Transducer Market Share (2021-2026) 78
Figure 18 Global Diagnostic Ultrasound Transducer Top 5 Vendor Market Concentration (2026) 88
Figure 19 GE Healthcare Diagnostic Ultrasound Transducer Market Share (2021-2026) 97
Figure 20 Siemens Healthineers Diagnostic Ultrasound Transducer Market Share (2021-2026) 100
Figure 21 Philips Diagnostic Ultrasound Transducer Market Share (2021-2026) 103
Figure 22 Fujifilm Healthcare Diagnostic Ultrasound Transducer Market Share (2021-2026) 106
Figure 23 Canon Medical Diagnostic Ultrasound Transducer Market Share (2021-2026) 109
Figure 24 Esaote Diagnostic Ultrasound Transducer Market Share (2021-2026) 112
Figure 25 Mindray Diagnostic Ultrasound Transducer Market Share (2021-2026) 115
Figure 26 Ueda Japan Radio Co., Ltd. (UJRC) Diagnostic Ultrasound Transducer Market Share (2021-2026) 118
Figure 27 SonoScape Diagnostic Ultrasound Transducer Market Share (2021-2026) 121
Figure 28 Shantou Institute of Ultrasonic Instruments Co. Ltd (SIUI) Diagnostic Ultrasound Transducer Market Share (2021-2026) 124
Figure 29 Shenzhen Wisonic Medical Technology Diagnostic Ultrasound Transducer Market Share (2021-2026) 127
Figure 30 VINNO Technology (Suzhou) Co. Ltd. Diagnostic Ultrasound Transducer Market Share (2021-2026) 130
Figure 31 Shenzhen WELLD Medical Electronics Co. Ltd. Diagnostic Ultrasound Transducer Market Share (2021-2026) 133
Figure 32 Samsung Healthcare Diagnostic Ultrasound Transducer Market Share (2021-2026) 136
Figure 33 Butterfly Network Diagnostic Ultrasound Transducer Market Share (2021-2026) 139
Figure 34 CHISON Medical Diagnostic Ultrasound Transducer Market Share (2021-2026) 142
Figure 35 Edan Instruments Diagnostic Ultrasound Transducer Market Share (2021-2026) 145
Figure 36 Medistim ASA Diagnostic Ultrasound Transducer Market Share (2021-2026) 148
Figure 37 Pulsenmore Ltd Diagnostic Ultrasound Transducer Market Share (2021-2026) 151
Figure 38 Broadsound Corporation Diagnostic Ultrasound Transducer Market Share (2021-2026) 154
Figure 39 Vermon Diagnostic Ultrasound Transducer Market Share (2021-2026) 157
Research Methodology
- Market Estimated Methodology:
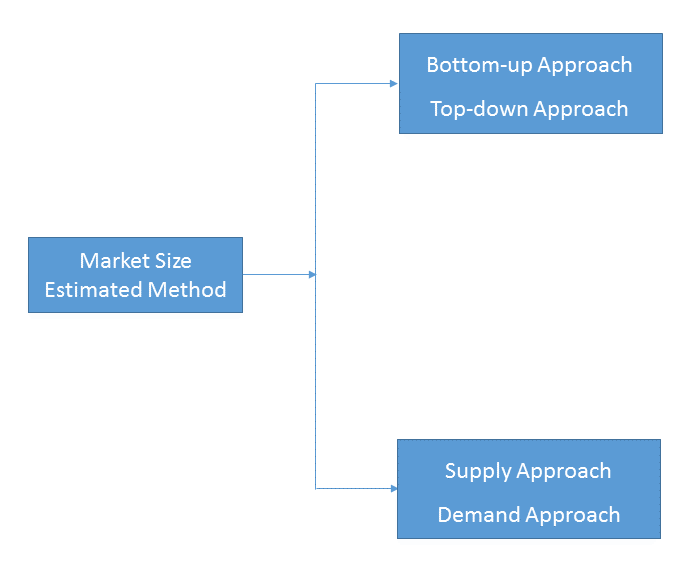
Bottom-up & top-down approach, supply & demand approach are the most important method which is used by HDIN Research to estimate the market size.
1)Top-down & Bottom-up Approach
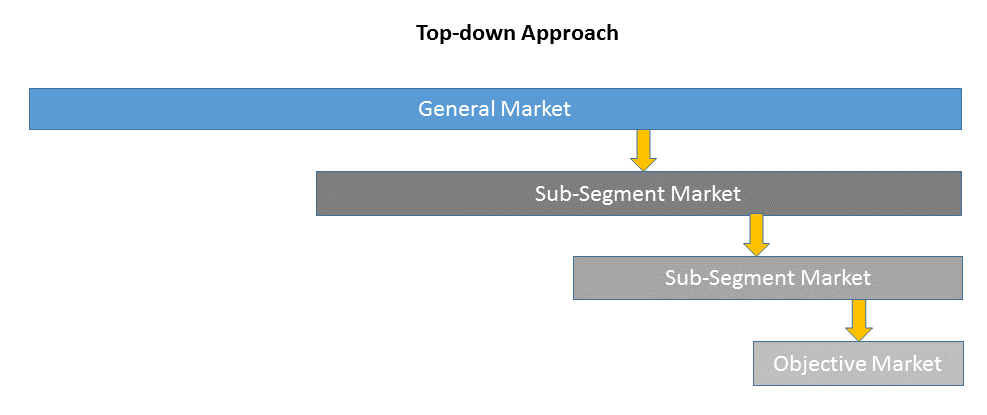
Top-down approach uses a general market size figure and determines the percentage that the objective market represents.
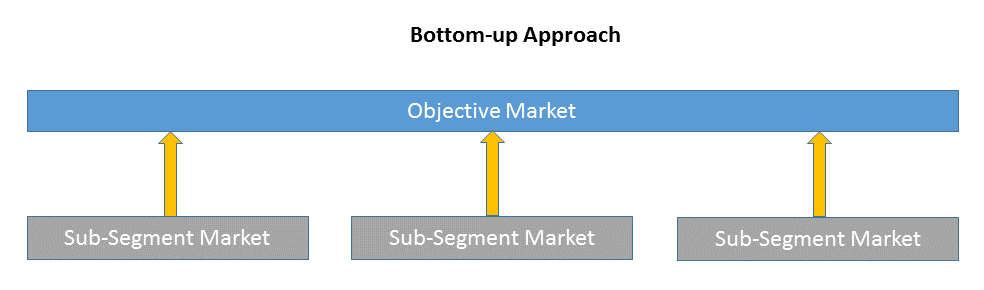
Bottom-up approach size the objective market by collecting the sub-segment information.
2)Supply & Demand Approach
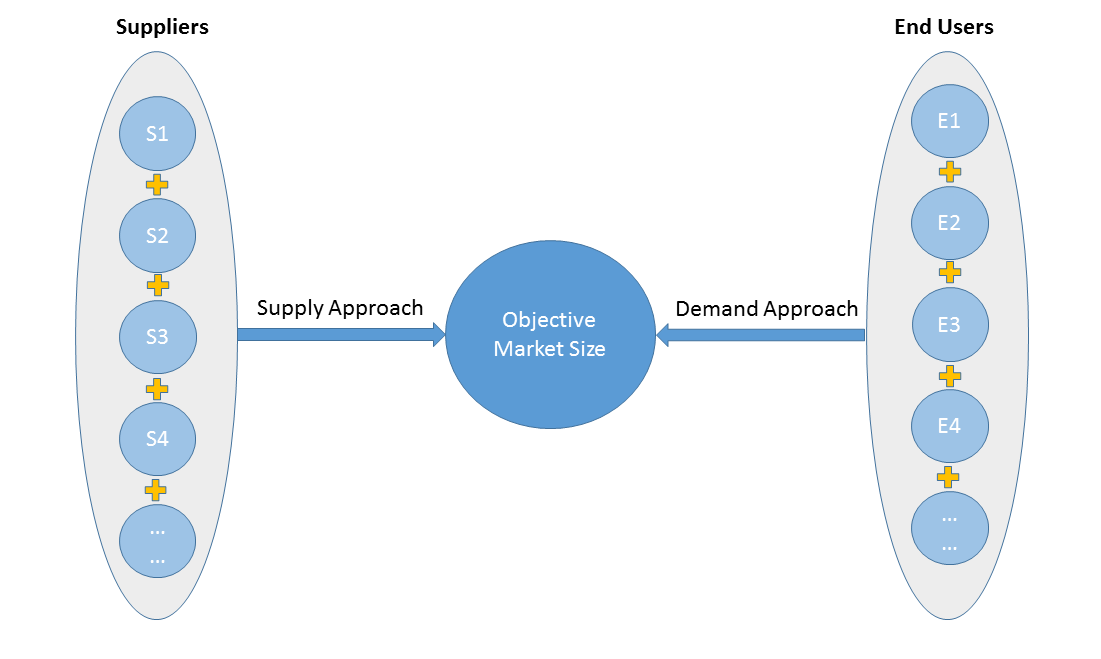
Supply approach is based on assessments of the size of each competitor supplying the objective market.
Demand approach combine end-user data within a market to estimate the objective market size. It is sometimes referred to as bottom-up approach.
- Forecasting Methodology
- Numerous factors impacting the market trend are considered for forecast model:
- New technology and application in the future;
- New project planned/under contraction;
- Global and regional underlying economic growth;
- Threatens of substitute products;
- Industry expert opinion;
- Policy and Society implication.
- Analysis Tools
1)PEST Analysis
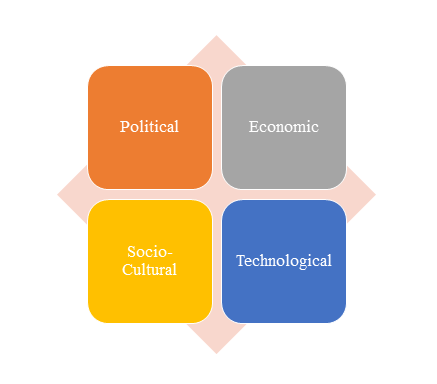
PEST Analysis is a simple and widely used tool that helps our client analyze the Political, Economic, Socio-Cultural, and Technological changes in their business environment.
- Benefits of a PEST analysis:
- It helps you to spot business opportunities, and it gives you advanced warning of significant threats.
- It reveals the direction of change within your business environment. This helps you shape what you’re doing, so that you work with change, rather than against it.
- It helps you avoid starting projects that are likely to fail, for reasons beyond your control.
- It can help you break free of unconscious assumptions when you enter a new country, region, or market; because it helps you develop an objective view of this new environment.
2)Porter’s Five Force Model Analysis
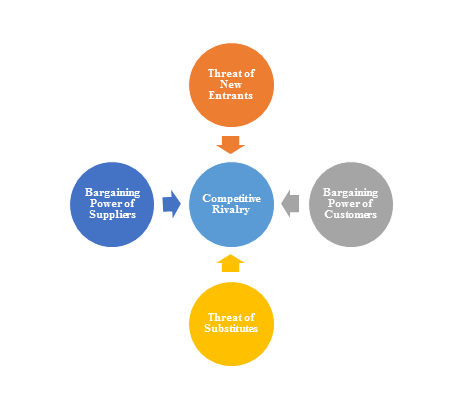
The Porter’s Five Force Model is a tool that can be used to analyze the opportunities and overall competitive advantage. The five forces that can assist in determining the competitive intensity and potential attractiveness within a specific area.
- Threat of New Entrants: Profitable industries that yield high returns will attract new firms.
- Threat of Substitutes: A substitute product uses a different technology to try to solve the same economic need.
- Bargaining Power of Customers: the ability of customers to put the firm under pressure, which also affects the customer's sensitivity to price changes.
- Bargaining Power of Suppliers: Suppliers of raw materials, components, labor, and services (such as expertise) to the firm can be a source of power over the firm when there are few substitutes.
- Competitive Rivalry: For most industries the intensity of competitive rivalry is the major determinant of the competitiveness of the industry.
3)Value Chain Analysis
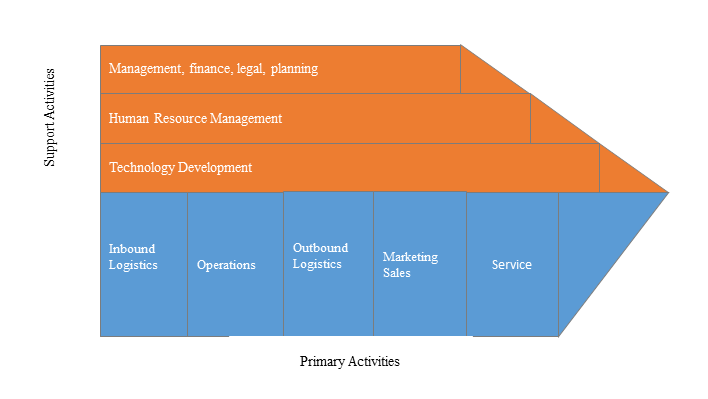
Value chain analysis is a tool to identify activities, within and around the firm and relating these activities to an assessment of competitive strength. Value chain can be analyzed by primary activities and supportive activities. Primary activities include: inbound logistics, operations, outbound logistics, marketing & sales, service. Support activities include: technology development, human resource management, management, finance, legal, planning.
4)SWOT Analysis
SWOT analysis is a tool used to evaluate a company's competitive position by identifying its strengths, weaknesses, opportunities and threats. The strengths and weakness is the inner factor; the opportunities and threats are the external factor. By analyzing the inner and external factors, the analysis can provide the detail information of the position of a player and the characteristics of the industry.
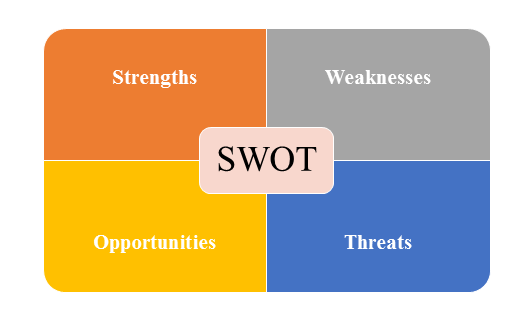
- Strengths describe what the player excels at and separates it from the competition
- Weaknesses stop the player from performing at its optimum level.
- Opportunities refer to favorable external factors that the player can use to give it a competitive advantage.
- Threats refer to factors that have the potential to harm the player.
- Data Sources
| Primary Sources | Secondary Sources |
|---|---|
| Face to face/Phone Interviews with market participants, such as: Manufactures; Distributors; End-users; Experts. Online Survey |
Government/International Organization Data: Annual Report/Presentation/Fact Book Internet Source Information Industry Association Data Free/Purchased Database Market Research Report Book/Journal/News |