X-ray Generator Market Analysis & Strategic Outlook
- Single User License (1 Users) $ 3,500
- Team License (2~5 Users) $ 4,500
- Corporate License (>5 Users) $ 5,500
The global X-ray high-voltage generator market size is projected to command between 0.85 billion USD and 1.25 billion USD by 2026, with an anticipated compound annual growth rate (CAGR) operating within the 2.5% to 4.5% through 2031. Operating as the primary electro-physical power engine across diagnostic radiography, computed tomography, dynamic interventional fluoroscopy, and industrial non-destructive testing (NDT), the high-voltage generator forms an immutable hardware triad alongside the X-ray tube and the digital flat panel detector (FPD). Together, these three sub-assemblies constitute more than 70% of the aggregate system bill-of-materials (BOM) cost for diagnostic and analytical radiation equipment. In mature diagnostic healthcare environments, traditional discrete high-voltage topologies are yielding to modular, high-power-density platforms optimized for sub-millisecond dual-energy spectral switching and lower patient radiation doses. Concurrently, industrial manufacturing sectors—principally electric vehicle (EV) battery gigafactories, advanced semiconductor packaging facilities, and high-throughput airport logistics hubs—are fueling an aggressive shift toward integrated monoblock assemblies. Geopolitically, the operating terrain has fractured. Tariff friction, healthcare equipment volume-based procurement mandates in East Asia, and regulatory modernization under the United States Food and Drug Administration (FDA) and European Union Medical Device Regulation (EU MDR) have combined to elevate switching barriers. Market incumbents are increasingly deploying local-for-local manufacturing footprints and shifting product strategies toward pre-calibrated, multi-component emission engines to consolidate gross margins and fortify OEM retention.
TECHNOLOGICAL ARCHITECTURE AND OPERATIONAL PRINCIPLES
An X-ray high-voltage generator is a mission-critical power electronics subsystem engineered to convert standard three-phase or single-phase alternating current (AC) line power into an ultra-stable, high-frequency, quasi-direct current (DC) electrical potential spanning 20 kV to 500 kV. This potential difference is coupled with precise cathode filament drive currents (microamperes to milliamperes) to govern thermionic electron emission and ensure repeatable photon generation at the anode target.
The fundamental operational architecture resolves into three core subsystems:
1. Main Inverter Power Supply
Line AC is rectified and routed into a high-frequency switching inverter. Operating across resonant topologies (phase-shifted full-bridge or series-parallel resonant converters), this stage generates high-frequency AC (typically 40 kHz to upwards of 400 kHz). The resulting signal is directed into step-up high-voltage transformers and Cockcroft-Walton or Dickson-type voltage multiplier stages, outputting a tightly controlled DC potential with minimum ripple. Fast rise times (sub-millisecond) and high dynamic stability under variable load states are non-negotiable requirements for diagnostic clarity and radiation safety.
2. Cathode Filament Drive Supply
The cathode filament requires an electrically isolated, floating heating circuit. Operating at high negative potentials (in unipolar designs) or symmetric split potentials (in bipolar architectures), this drive circuit utilizes precise closed-loop current control to regulate filament temperature. Controlling the thermal regime directly modulates the spatial charge and thermionic electron flux, determining the tube current (mA).
3. Control Circuitry and Interface Logic
Real-time embedded microprocessors, digital signal processors (DSPs), and field-programmable gate arrays (FPGAs) supervise system performance. These units execute Automatic Exposure Control (AEC) algorithms, synchronize exposure timing down to millisecond intervals, monitor tube thermal load accumulations, and maintain sub-millisecond arc-suppression loops. Should a dielectric flashover occur inside the vacuum tube, the generator must quench the arc within microseconds to avert the destruction of both the tube target and the inverter power semiconductor modules.
Dielectric insulation represents a primary mechanical and material barrier. Historically, high-voltage tanks have depended on highly refined, degassed mineral oil to achieve dielectric isolation and convective heat dissipation. However, modern designs are increasingly pivoting toward solid dielectric encapsulation (epoxy or silicone potting resins). Solid-potted generators eliminate environmental oil leakage vectors, diminish mechanical footprint, and enable 19-inch rack integration within surgical or industrial gantry chassis. Conversely, high-power continuous systems (exceeding 3 kW to 6 kW) continue to utilize circulating oil or specialized fluoropolymer fluids coupled to external liquid-to-air heat exchangers to survive extreme duty cycles.
DOWNSTREAM APPLICATION DYNAMICS
X-ray high-voltage generators distribute across two primary downstream market pillars: clinical diagnostic and therapeutic platforms, and industrial non-destructive testing (NDT) coupled with security screening infrastructure.
1. Medical Diagnostic and Interventional Modalities
● General Radiography (Static DR, Bedside Mobile DR, and Dynamic Fluoroscopy):
Standard radiography systems deploy high-frequency stationary generators operating within the 32 kW to 80 kW range. The critical technical battleground centers on voltage stability, footprint compression, and fast rise times to reduce patient exposure. In bedside mobile units, the focus pivots to lightweight form factors, high electrical conversion efficiency, and energy storage architectures (lithium iron phosphate battery packs or ultra-capacitor banks) capable of discharging full-power exposures without dragging down standard hospital wall outlets. Gastrointestinal and fluoroscopic suites require generators capable of transitioning dynamically from continuous low-dose pulsed fluoroscopy (15 to 30 frames per second) to high-dose digital spot acquisition.
Surgical C-Arms and Interventional Angiography (DSA):
Interventional vascular suites demand advanced power delivery systems capable of sustaining high tube currents during digital subtraction angiography and rapid sequential exposure runs. Thermal management is critical; generators must balance sustained thermal loads with sub-millisecond pulse synchronization to preserve spatial resolution in cardiovascular and neurovascular interventions without motion blur.
● Computed Tomography (CT) Systems:
Medical CT gantries represent the pinnacle of medical generator engineering. Generators in this space range from 40 kW to 120 kW and must withstand extreme centrifugal forces (rotational speeds surpassing 0.25 seconds per rotation, subjecting internal components to mechanical loads exceeding 20 to 40 G). Furthermore, modern volumetric and spectral CT architectures require ultra-fast dual-energy kV switching, where the generator alternates between 80 kV and 140 kV within tens of microseconds on adjacent projection views. This requires sophisticated grid-switch control circuits and low-capacitance multiplier networks.
● Dental, Maxillofacial, and Orthopedic Extremity Imaging:
Dental Cone Beam Computed Tomography (CBCT) and panoramic dental units utilize compact, low-power monoblocks operating between 70 kV and 100 kV. Handheld intraoral units prioritize extreme miniaturization, requiring solid-encapsulated generators weighing less than 2 kg, capable of delivering highly stable low-milliampere outputs from internal battery supplies. Dual-energy X-ray absorptiometry (DEXA) units utilize narrow-spectrum, low-power generators to execute precise bone mineral density scans.
2. Non-Destructive Testing (NDT) and Security Inspection Verticals
● Lithium Battery and Electric Vehicle (EV) Manufacturing:
The worldwide build-out of EV battery production has driven unprecedented procurement of inline X-ray inspection stations. Pouch cells, prismatic cells, and cylindrical 4680 formats require continuous-duty, high-resolution microfocus inspection (ranging from 110 kV to 225 kV) to verify anode-cathode overhang alignment, detect electrode edge folding, and inspect tab welding integrity in real time. Generators in these environments must run 24/7 with zero unplanned downtime, demanding exceptional thermal dissipation and near-zero voltage drift.
● Semiconductor Packaging, Electronics, and PCBA Metrology:
The progression toward 2.5D/3D chiplet integration, high-density ball grid arrays (BGA), insulated-gate bipolar transistor (IGBT) power modules, and through-silicon via (TSV) architecture mandates microfocus and nanofocus X-ray generators. Operating with open-type or closed-type microfocus tubes at spot sizes under 1 to 5 microns, these generators require high-precision output stability (voltage reproducibility within plus or minus 0.01%) to prevent beam focal spot drift during high-magnification tomographic reconstruction.
● Aerospace, Defense, and Heavy Industrial Infrastructure:
Inspection of thick-walled pressure vessels, pipeline circumferential welds, rocket motor casings, and cast superalloy aerospace turbine blades requires high-energy constant-potential generators. Operating from 225 kV up to 450 kV or higher, these systems (often configured in bipolar arrangements with two coupled 225 kV high-voltage tanks) deliver high penetrating power through dense metallic structures. Ruggedization against wide ambient temperature fluctuations, airborne dust, and severe vibration is mandatory for field pipeline crawlers and shipyard radiography.
● Aviation Baggage, Parcel, and Cargo Security:
Global aviation security upgrades centered on European Civil Aviation Conference (ECAC) Standard 3 and Transportation Security Administration (TSA) checkpoint standards have catalyzed the adoption of computed tomography explosive detection systems (EDS). These continuous-duty units utilize 160 kV to 180 kV high-power monoblocks designed for uninterrupted, high-throughput operation. Port and border security platforms deploy high-power unipolar and bipolar generators driving linear accelerator (linac) injection sources or dual-energy panoramic inspection configurations for shipping container screening.
● Food, Pharmaceutical, and Agricultural Inspection:
High-speed sorting lines deploy low-power, continuous-duty monoblocks (typically 80 kV to 160 kV at 200 W to 500 W) to intercept glass fragments, foreign metals, and calcified bone splinters within packaged food products, as well as checking fill levels and internal product densities.
SALES CHANNEL ARCHITECTURE AND COMMERCIALIZATION ECONOMICS
The commercialization of X-ray high-voltage generators flows through two structural models, characterized by asymmetric margins, diverging engineering life cycles, and distinct customer retention dynamics.
1. Direct OEM B2B Channel (Primary Equipment Market)
The primary channel consists of direct integration sales to medical diagnostic and industrial NDT system integrators. Major customers in the medical domain include GE HealthCare, Siemens Healthineers, Philips Healthcare, Canon Medical Systems, United Imaging Healthcare, Mindray, DRGEM, and Konica Minolta. In the industrial and security theater, volumes are captured by integrators such as Waygate Technologies, VJ Group, Smiths Detection, Rapiscan Systems, and battery automation providers serving CATL, BYD, and LG Energy Solution.
The OEM channel features multi-year sales and development gestation periods lasting between 24 and 48 months. Integrating a discrete generator or monoblock requires deep co-engineering across physical chassis mounting, power factor pre-regulation, real-time CAN bus or proprietary Ethernet communication interface design, and exact thermal-inertia matching between the generator driver and the X-ray tube filament.
Switching barriers in this channel are exceptionally formidable due to global medical device regulatory frameworks. In the United States, an X-ray generator is registered as part of an integrated imaging system under FDA 510(k) premarket notifications. In the European Union, it falls under the stringent technical audits of EU MDR (Regulation 2017/745), and in China, under National Medical Products Administration (NMPA) Class II/III certifications. Altering a generator vendor requires the OEM to execute complete electrical safety recertifications (IEC 60601-1, IEC 60601-2-54), electromagnetic compatibility re-evaluations, and comprehensive clinical validation testing. This regulatory friction creates deep vendor lock-in, cementing procurement relationships that routinely endure across 7 to 15-year equipment lifecycle windows.
To expand addressable content per gantry, merchant component vendors increasingly market complete X-ray emission subsystems. By bundling the high-voltage generator, matching X-ray tube, liquid cooling heat exchanger, high-voltage cabling, and digital flat panel detector into an integrated, pre-calibrated package, suppliers capture higher gross margin pools, mitigate field calibration liability, and insulate themselves against standalone component commoditization.
2. Aftermarket and Replacement Channel (Secondary Service Market)
Unlike X-ray tubes—which operate as consumable vacuum devices subject to filament evaporation, target pitting, and vacuum degradation every 2 to 6 years—the high-voltage generator is fundamentally an institutional capital asset engineered to match the multi-decade lifespan of the primary imaging system.
Consequently, the aftermarket channel operates primarily as a mission-critical maintenance, board-level repair, and targeted retrofit environment. Field failures within generators stem from power semiconductor thermal degradation, inverter driver breakdown, transformer dielectric insulation cracking, high-voltage potting breakdowns, or micro-arcing in step-up cascades.
The aftermarket channel services these failures through:
- Certified component-level replacements (inverter boards, AEC control cards, power factor correction modules, and high-voltage oil tank rebuilds).
- Direct field retrofits, where aging analog radiography systems are upgraded to digital radiography platforms via modernized generator-detector pairings.
- Independent Service Organizations (ISOs) and multi-vendor service providers managing multi-facility hospital imaging fleets under third-party maintenance contracts, bypassing OEM direct service pricing.
While unit volume in the aftermarket channel is materially lower than primary OEM shipments, the channel commands elevated gross margins on proprietary spare subassemblies, component rebuild services, and field engineering labor.
REGIONAL MARKET DYNAMICS
1. North America
North America retains a commanding position in high-value, high-complexity generator demand, driven by dense deployments of multi-slice spectral CT, advanced cardiovascular angiography suites, and ambulatory surgical centers (ASCs) transitioning toward high-end mobile 3D C-arms. Simultaneously, US transportation hubs continue broad-scale upgrades to 3D CT checkpoint screening.
Federal regulatory compliance remains stringent. Medical generators must satisfy US FDA Center for Devices and Radiological Health (CDRH) 21 CFR standards alongside Quality Management System Regulation (QMSR) protocols aligned with ISO 13485:2016. High-voltage power supplies integrated into clinical systems undergo rigorous scrutiny regarding arc-protection safety and electrical leakage limits.
Trade policy shifts and bilateral import tariffs implemented over recent fiscal cycles have injected friction into cross-border component movements. Domestic system OEMs that historically leveraged offshore assembly platforms for high-voltage tanks have been compelled to reconsider dual-sourcing models or onshore subassembly integration to mitigate margin erosion. Regional market value is projected to track a conservative with growth weighted toward industrial EV battery plant construction in the domestic battery belt and CT equipment renewals.
2. Asia-Pacific (APAC)
The Asia-Pacific region functions as both the fastest-growing consumption theater and the primary global manufacturing engine for high-frequency X-ray power supplies. Growth across this territory is modeled to outpace the global average.
China represents the core dynamic center within this region. Public sector healthcare programs, specifically large-scale medical equipment renewal initiatives, continue to catalyze public hospital replacements of analog and legacy CT units. Centralized Volume-Based Procurement (VBP) programs across healthcare systems have placed pricing downward pressure on domestic OEMs, accelerating the transition away from expensive Western merchant component imports toward domestic high-voltage generator manufacturers.
Furthermore, local-for-local manufacturing mandates have driven multinational imaging giants to establish local manufacturing joint ventures and deep supply bases in industrial centers such as Suzhou, Wuxi, and Shanghai. On the industrial axis, China's massive lithium battery and consumer electronics packaging ecosystems maintain high demand for microfocus integrated monoblocks and high-voltage NDT generators.
Other key Asian centers include Japan, South Korea, and Taiwan, China. Japan retains world-class precision component manufacturing and represents a mature replacement market for dynamic flat-panel radiography and advanced microfocus analytical instruments. South Korea serves as a major hub for digital radiography system exports and specialized dental CBCT integration. In Taiwan, China, advanced semiconductor assembly, wafer-level packaging, and high-density substrate manufacturing fuel continuous requirements for precision closed-tube and open-tube microfocus X-ray generators used in automated structural fault isolation.
3. Europe
The European market is characterized by technological maturity, high demand for low-dose clinical radiation hardware, and strict regulatory standards. Replacement demand focuses on high-efficiency fluoroscopy suites, robotic dual-detector DR systems, and industrial computed tomography systems utilized across automotive, aerospace, and energy sectors.
The primary regulatory hurdle remains the transition to the European Union Medical Device Regulation (EU MDR 2017/745). The increased administrative burden, extensive clinical documentation mandates, and bottlenecked Notified Body capacity have lengthened time-to-market for new generator architectures. Any minor alteration to an existing high-voltage generator platform embedded within an approved medical system can trigger extensive filing supplements, dampening the pace of radical hardware transitions.
Concurrently, European Green Deal environmental directives, notably the Restriction of Hazardous Substances (RoHS) and Registration, Evaluation, Authorisation and Restriction of Chemicals (REACH), impose stringent constraints on generator manufacturing. The phasing out of certain dielectric chemical formulations and strict lead-shielding compliance require extensive materials science innovation.
4. South America
The South American landscape represents an emerging, price-sensitive market characterized by targeted investments in primary healthcare accessibility and the replacement of outmoded analog film equipment with digital radiography.
Demand is heavily concentrated in major economies including Brazil, Argentina, and Chile. The public healthcare sector depends heavily on pre-owned, refurbished, or value-tier imported equipment, which fuels demand for aftermarket replacement parts, field retrofits, and reliable 32 kW to 50 kW stationary generators. Industrial inspection demand is tied primarily to offshore oil and gas pipeline evaluation, mineral extraction infrastructure, and agricultural bulk commodity inspection. Import duties, currency volatility, and complex customs logistics remain persistent strategic inhibitors for direct merchant component distribution.
5. Middle East and Africa (MEA)
The Middle East and Africa present a starkly segmented operating environment. The Gulf Cooperation Council (GCC) nations (notably Saudi Arabia and the United Arab Emirates) are driving high-value demand through state-sponsored expansions of public hospital infrastructure, dedicated oncology networks, and the integration of cutting-edge cardiovascular suites. Furthermore, aggressive investments in aviation transport infrastructure and mega-city developments sustain procurement of advanced baggage CT monoblocks and vehicle cargo scanning equipment.
Conversely, the broader African market relies primarily on international developmental financing, sovereign healthcare tenders, and multi-vendor donor programs. The operating requirements in these territories prioritize absolute electrical ruggedization: generators must tolerate unstable, fluctuating power grids, severe voltage drops, high ambient temperatures, and dust infiltration. Demand favors simple, solid-state, or robust oil-insulated 32 kW to 50 kW DR generators and mobile bedside units capable of continuous operation in remote or austere field clinics.
SUPPLY CHAIN AND VALUE CHAIN ARCHITECTURE
The value chain for X-ray high-voltage generators is technically complex, demanding mastery over power electronics, high-voltage physical insulation, vacuum electro-mechanics, and real-time algorithmic control.
1. Upstream Inputs and Semiconductor Vulnerabilities
The physical architecture of a generator depends on specialized upstream materials:
- Power Semiconductors: Advanced Silicon Carbide (SiC) MOSFETs, high-voltage Insulated-Gate Bipolar Transistors (IGBTs), and fast-recovery diodes constitute the primary inverter switching mechanisms. Silicon Carbide provides significant operational advantages, permitting higher switching frequencies (over 200 kHz to 400 kHz), reducing magnetic core transformer volume, and lowering thermal losses. However, the geographic concentration of SiC device fabrication and long lead times for high-voltage silicon IGBTs represent structural supply vulnerabilities.
- Passive Components and Magnetics: High-frequency step-up transformers rely on high-permeability nanocrystalline and ferrite cores, precision copper magnet wire, and specialized ultra-low ESR high-voltage ceramic capacitors configured in multiplier arrays.
- Dielectric Media: High-purity dielectric insulating oils (requiring multi-stage vacuum degassing and moisture filtration) and custom-formulated structural polyurethane and epoxy potting compounds form the dielectric barrier against high-voltage arc breakdown.
- Specialized Hardware: High-voltage cable receptacles (such as standard Federal, Claymount, or CA-type connections), beryllium exit windows, lead shielding jackets, and mechanical aluminum oil tank castings.
2. Midstream Manufacturing and Critical Technical Moats
Midstream fabrication combines complex electronic manufacturing with electro-mechanical assembly. Structural barriers to market entry are elevated:
- Dielectric Integrity and Thermal Vacuum Potting: Under potentials of 100 kV to 500 kV, the slightest microscopic air void, surface contamination, or moisture inclusion within an oil tank or epoxy matrix will induce partial discharge, corona erosion, and fatal dielectric breakdown. Manufacturers must invest in capital-intensive automated vacuum drying, oil filling, and bubble-free resin degassing systems.
- Parasitic Capacitance and High-Frequency Control: Operating at switching frequencies in the hundreds of kilohertz while stepping up voltages by factors of several thousand generates severe parasitic capacitance and leakage inductance in transformer windings. Tightly regulating low output ripple (under 1%) demands proprietary winding geometries and soft-switching resonant topologies (such as LLC or LCC configurations) that balance power factor correction without inducing severe electromagnetic interference (EMI).
- Arc Handling and Predictive Tube Protection: When an X-ray tube experiences an internal high-voltage discharge, the generator must rapidly shut down switching pulses within 1 to 2 microseconds to protect delicate circuit traces and filament loops from catastrophic energy dumps. Developing robust, dynamic arc-detection algorithms that differentiate between harmless micro-discharges and system-threatening arcs represents a major competitive moat.
3. Downstream Integration and Merchant-Captive Market Dynamics
The downstream ecosystem exhibits a hybrid structure of captive in-house production and independent merchant distribution. Captive manufacturers—prominently Siemens Healthineers and Philips Healthcare—produce proprietary generators engineered exclusively for their internal medical device architectures.
Simultaneously, independent merchant suppliers (such as Spellman, CPI, EMD Technologies, Comet, and iRay Technology) provide customized solutions to third-party medical OEMs and industrial integrators. The balance of power continues to shift as developing OEMs in East Asia and specialized industrial integrators outsource generator development to independent merchant leaders rather than absorbing the multi-year engineering and regulatory costs of developing proprietary power supplies in-house.
COMPETITIVE DOSSIERS: KEY MARKET PARTICIPANTS
● Varex Imaging Corporation:Spun off from Varian Medical Systems, Varex Imaging stands as one of the world's largest independent component suppliers for imaging chains. The firm designs and manufactures high-voltage generators, integrated subsystems, X-ray tubes, flat panel detectors, and specialized interconnect components. Its industrial footprint includes the HPE-225-54 industrial subsystem, uniting a 225 kV high-frequency generator with high-performance emitters for inline 3D computed tomography. In the medical arena, Varex engineers complete integrated imaging engines, delivering pre-matched generator-tube-detector arrays for digital radiography and dynamic fluoroscopy. Through its Claymount product line, the firm controls a dominant market share in high-voltage cables, receptacles, and solid-state ionization chambers for Automatic Exposure Control (AEC).
● Comet Holding AG:Headquartered in Switzerland, Comet represents the preeminent pure-play market leader in stationary and portable industrial X-ray sources. Comet is structurally unique in designing and manufacturing both high-voltage generators and metal-ceramic X-ray tubes internally. Its flagship stationary offering, the iVARIO series (spanning 160 kV to 500 kV and power envelopes up to 4.5 kW), provides high-stability, constant-potential energy for high-magnification NDT, inline electronics inspection, and aerospace metrology. Comet also markets the MesoFocus and microfocus source families designed for sub-micron flaw isolation in semiconductors and EV battery modules, alongside the ruggedized SMART EVO series for field pipeline radiography.
● iRay Technology:Headquartered in China, iRay Technology has transitioned from its origins as an independent flat panel detector manufacturer into a comprehensive component platform supplier. Its portfolio now spans flat-panel detectors, rotating anode X-ray tubes, microfocus sources, and medical/industrial high-voltage generators. Key generator lines include the Pyxis series (featuring the 80 kW Pyxis 80CT, a low-profile, gantry-mounted CT generator engineered to endure high centrifugal G-loads), the Gemini series for stationary radiography (32 kW to 80 kW), and specialized monoblocks for mobile DR, veterinary medicine, and dental CBCT. In the industrial segment, iRay has scaled production of 110 kV to 225 kV microfocus integrated sources, shipping thousands of units annually for EV battery and electronic inspection lines.
● The rest of companies covered in the report: Spellman High Voltage Electronics Corp., Communications & Power Industries (CPI), EMD Technologies, Suzhou Powersite Electric Co., Ltd., Siemens Healthineers AG, Philips, Baker Hughes (Waygate Technologies), Teledyne ICM, Balteau NDT, and VJ X-Ray.
OPPORTUNITIES AND STRUCTURAL CHALLENGES
● Strategic Market Opportunities
1. Accelerated Substitution by Integrated Monoblock Architectures
Field intelligence indicates a steady value migration from discrete generator setups toward integrated monoblock X-ray sources. By potting the high-voltage step-up stages, filament drive, control electronics, and X-ray tube within a singular shielded enclosure, the monoblock eliminates cumbersome high-voltage cables, eliminates external cable capacitance issues, minimizes arc breakdown interfaces, and significantly downsizes physical volume. System OEMs increasingly prefer monoblock drop-in integration to bypass internal high-voltage design liabilities, accelerate time-to-market, and simplify assembly logistics.
2. Wide Bandgap Semiconductor (SiC) Adoption
The systemic migration from silicon-based IGBT switches to Silicon Carbide (SiC) MOSFET power electronics represents an evolutionary step for high-voltage generators. SiC devices permit operating frequencies to scale from traditional 40 kHz-100 kHz regimes to upwards of 400 kHz. Operating at these high frequencies yields a dramatic reduction in the physical volume of magnetic transformer cores and voltage multiplier capacitors. The resulting power supplies exhibit superior thermal behavior, lower energy losses, sub-millisecond dynamic rise times, and power densities that simplify gantry mounting inside advanced CT and dynamic interventional suites.
3. Advanced Inline EV Battery and Semiconductor Metrology Demands
The rapid expansion of high-throughput automated production lines across the clean energy and advanced electronics sectors provides an exceptional structural growth channel. The inspection of gigawatt-scale EV pouch and prismatic battery cells requires 24/7 continuous X-ray testing to detect sub-millimeter electrode misalignments and welding spatter. Simultaneously, the proliferation of heterogeneous semiconductor chiplet architectures and advanced packaging requires high-stability closed and open microfocus sources. Generator suppliers that master ultra-low voltage ripple, microfocus spot preservation, and zero-downtime thermal designs will capture high-margin market share in these non-cyclical industrial verticals.
● Structural Industry Challenges
1. Supply Chain Volatility and Upstream Semiconductor Dependencies
The high-voltage generator industry remains exposed to extended lead times and geographic concentration in specialized power electronics. High-voltage SiC modules, military-grade FPGAs, and precision analog front-end semiconductors are subject to persistent allocation cycles and geopolitical export controls. Furthermore, specialized raw materials—such as high-purity naphthenic transformer oils, high-grade beryllium foils, and nanocrystalline magnetic cores—face periodic feedstock squeezes, eroding operating margins for merchant manufacturers bound by multi-year OEM fixed-price contracts.
2. Geopolitical Fragmentation and Localization Barriers
Mounting international trade barriers, bilateral tariff regimes, and national self-reliance procurement mandates have disrupted historical supply chains. Component manufacturers can no longer rely on a centralized global production footprint to service all geographical markets. Regional policy measures—such as medical equipment renewal criteria favoring localized domestic hardware and strict local procurement thresholds—require significant capital reallocation into decentralized regional manufacturing facilities, elevating operational overhead and testing organizational agility.
3. Stringent Regulatory Switching Barriers and Lengthy Design Cycles
The high-voltage generator operates under heavy multi-jurisdictional regulatory oversight. Because a generator’s performance directly governs patient radiation exposure, leakage limits, and imaging safety, it is classified as a critical component in master system filings across the US FDA, EU MDR, and China NMPA. Consequently, downstream OEMs face massive financial disincentives, prolonged regulatory recertification timelines (often 2 to 4 years), and substantial clinical testing costs should they attempt to swap generator vendors. While this operational friction creates powerful customer retention for design-in incumbents, it erects formidable structural barriers for ambitious merchant challengers seeking to displace existing supply agreements.
1.1 Study Framework and Technical Product Definition 1
1.2 Research Methodology, Bottom-Up Sizing and Estimation Model 2
1.3 Primary Source Fieldwork and Secondary Database Triangulation 4
1.4 Baseline Macroeconomic Assumptions and Currency Conversion Parameters 5
1.5 Nomenclature and List of Abbreviations 6
Chapter 2 Global X-ray Generator Industry Ecosystem and Value Chain Architecture 7
2.1 End-to-End Value Chain Structural Decomposition 7
2.2 Upstream High-Voltage Components, Inverter Topologies and Core Sourcing Costs 9
2.3 Value Migration Across Subsystem Assembly, Packaging and Integration 11
2.4 Global Regulatory Compliance Frameworks, IEC/FDA Standards and Patent Clusters 12
Chapter 3 Global X-ray Generator Market Dynamics and Strategic Trajectories 13
3.1 Macroeconomic Shifts, Industrial Automation Trends and Clinical Capex Drivers 13
3.2 Supply Chain Exposure, High-Voltage Power Electronics Shortages and Sourcing Risks 15
3.3 Technological Transitions: Compact Monoblock Integration vs. High-Power Split Units 16
3.4 Structural Demand Shifts Across Diagnostic Modalities and Non-Destructive Testing 17
Chapter 4 Global X-ray Generator Market by Technology and Architecture 18
4.1 Global Production Volume and Value Breakdown by Technology Architecture 18
4.2 High-Frequency Inverter Generators 19
4.3 Monoblock and Compact Integrated X-ray Subsystems 21
4.4 Stationary Floor-Mounted vs. Portable and Mobile Generator Systems 22
Chapter 5 Global X-ray Generator Market by Downstream Application 24
5.1 Segmental Demand Overview, Market Sizing and Volume Absorption 24
5.2 Medical Diagnostics and Interventional Systems 26
5.2.1 General Radiography and Fluoroscopy 27
5.2.2 Computed Tomography (CT) High-Power Subsystems 28
5.2.3 Mammography, Mobile C-Arms and Surgical Guidance Systems 29
5.3 Non-Destructive Testing (NDT) & Homeland Security Systems 30
5.3.1 Inline Semiconductor Metrology and Electronics Inspection 30
5.3.2 Aerospace Structures, Pipeline Integrity and Heavy Industrial Casting NDT 31
5.3.3 Cargo Screening, Baggage Handling and Border Security Scanners 31
Chapter 6 Global X-ray Generator Market by Sales Channel 32
6.1 Channel Structuring: Direct OEM Integration vs. Replacement Distribution 32
6.2 OEM Integration Channel Volume, Contracting Dynamics and Pricing Models 33
6.3 Aftermarket Replacement, Component Refurbishment and Service Life Cycle 35
Chapter 7 Global Manufacturing Footprint, Logistics and Cross-Border Trade Flows 37
7.1 Global Production Capacity Concentration and Geographic Footprint 37
7.2 Major Exporter Hub Analysis: United States, Germany, Switzerland, China 38
7.3 Critical Import Corridors, Inter-Regional Supply Dependencies and Tariffs 40
Chapter 8 Global X-ray Generator Market by Geographic Dimension 42
8.1 Global Regional Volume and Value Distribution Overview 42
8.2 North America Production Footprint and Demand Absorption 43
8.2.1 United States 45
8.2.2 Canada 47
8.3 Europe Production Centers and Advanced Healthcare/Industrial Demand 48
8.3.1 Germany 50
8.3.2 Switzerland 51
8.3.3 France 52
8.3.4 United Kingdom 53
8.3.5 Netherlands 54
8.3.6 Belgium & Rest of Europe 55
8.4 Asia-Pacific Manufacturing Hubs and High-Growth Downstream Markets 56
8.4.1 China 57
8.4.2 Japan 58
8.4.3 South Korea 58
8.4.4 India & Southeast Asia 59
8.5 Latin America Healthcare Infrastructure and Industrial Adoption 59
8.5.1 Brazil 59
8.5.2 Mexico 59
8.6 Middle East & Africa Infrastructure Development and Equipment Modernization 59
Chapter 9 Competitive Landscape, Market Concentration and Supplier Benchmarking 60
9.1 Market Concentration Metrics (CR4, CR8, and Herfindahl-Hirschman Index) 60
9.2 OEM Supply Chain Supplier-Client Mapping and Multi-Sourcing Trends 61
9.3 Strategic Realignment: Mergers, Strategic Alliances and Intellectual Property 62
Chapter 10 Corporate Intelligence and Competitor Benchmarking 64
10.1 Varex Imaging Corporation 64
10.1.1 Corporate Profile and Operational Footprint 64
10.1.2 SWOT Matrix and Strategic Positioning 65
10.1.3 Product-Specific Operations, Pricing, Gross Margin and Market Share 66
10.1.4 Research & Development Expenditures and GTM Trajectory 67
10.2 Comet Holding AG 68
10.2.1 Corporate Profile and Operational Footprint 68
10.2.2 SWOT Matrix and Strategic Positioning 69
10.2.3 Product-Specific Operations, Pricing, Gross Margin and Market Share 70
10.2.4 Research & Development Expenditures and GTM Trajectory 71
10.3 iRay Technology 72
10.3.1 Corporate Profile and Operational Footprint 72
10.3.2 SWOT Matrix and Strategic Positioning 73
10.3.3 Product-Specific Operations, Pricing, Gross Margin and Market Share 74
10.3.4 Research & Development Expenditures and GTM Trajectory 75
10.4 Spellman High Voltage Electronics Corporation 76
10.4.1 Corporate Profile and Operational Footprint 76
10.4.2 SWOT Matrix and Strategic Positioning 77
10.4.3 Product-Specific Operations, Pricing, Gross Margin and Market Share 78
10.4.4 Research & Development Expenditures and GTM Trajectory 79
10.5 Communications & Power Industries (CPI) 80
10.5.1 Corporate Profile and Operational Footprint 80
10.5.2 SWOT Matrix and Strategic Positioning 81
10.5.3 Product-Specific Operations, Pricing, Gross Margin and Market Share 82
10.5.4 Research & Development Expenditures and GTM Trajectory 83
10.6 EMD Technologies 84
10.6.1 Corporate Profile and Operational Footprint 84
10.6.2 SWOT Matrix and Strategic Positioning 85
10.6.3 Product-Specific Operations, Pricing, Gross Margin and Market Share 86
10.6.4 Research & Development Expenditures and GTM Trajectory 87
10.7 Teledyne ICM 88
10.7.1 Corporate Profile and Operational Footprint 88
10.7.2 SWOT Matrix and Strategic Positioning 89
10.7.3 Product-Specific Operations, Pricing, Gross Margin and Market Share 90
10.7.4 Research & Development Expenditures and GTM Trajectory 91
10.8 Siemens Healthineers AG 92
10.8.1 Corporate Profile and Operational Footprint 92
10.8.2 SWOT Matrix and Strategic Positioning 93
10.8.3 Product-Specific Operations, Pricing, Gross Margin and Market Share 94
10.8.4 Research & Development Expenditures and GTM Trajectory 95
10.9 Philips 96
10.9.1 Corporate Profile and Operational Footprint 96
10.9.2 SWOT Matrix and Strategic Positioning 97
10.9.3 Product-Specific Operations, Pricing, Gross Margin and Market Share 98
10.9.4 Research & Development Expenditures and GTM Trajectory 99
10.10 Suzhou Powersite Electric Co., Ltd. 100
10.10.1 Corporate Profile and Operational Footprint 100
10.10.2 SWOT Matrix and Strategic Positioning 101
10.10.3 Product-Specific Operations, Pricing, Gross Margin and Market Share 102
10.10.4 Research & Development Expenditures and GTM Trajectory 103
10.11 VJ X-Ray 104
10.11.1 Corporate Profile and Operational Footprint 104
10.11.2 SWOT Matrix and Strategic Positioning 105
10.11.3 Product-Specific Operations, Pricing, Gross Margin and Market Share 106
10.11.4 Research & Development Expenditures and GTM Trajectory 107
10.12 Balteau NDT 108
10.12.1 Corporate Profile and Operational Footprint 108
10.12.2 SWOT Matrix and Strategic Positioning 109
10.12.3 Product-Specific Operations, Pricing, Gross Margin and Market Share 110
10.12.4 Research & Development Expenditures and GTM Trajectory 111
10.13 Baker Hughes 112
10.13.1 Corporate Profile and Operational Footprint 112
10.13.2 SWOT Matrix and Strategic Positioning 113
10.13.3 Product-Specific Operations, Pricing, Gross Margin and Market Share 114
10.13.4 Research & Development Expenditures and GTM Trajectory 115
Chapter 11 Global X-ray Generator Strategic Market Forecast (2027-2031) 116
11.1 Five-Year Volume and Value Projections Across Technology Configurations 116
11.2 Demand Migration Forecast Across End-User Verticals 117
11.3 Strategic Supply Chain Realignment and Regional Reshoring Trajectories 118
Table 2 High-Voltage Core Sourcing Component Cost Breakdown Analysis (2021-2026) 10
Table 3 Global X-ray Generator Revenue by Technology Architecture (2021-2031) (USD Million) 19
Table 4 Global X-ray Generator Volume by Technology Architecture (2021-2031) (Units) 20
Table 5 Global X-ray Generator Revenue by Application (2021-2031) (USD Million) 25
Table 6 Global X-ray Generator Volume by Application (2021-2031) (Units) 26
Table 7 Global Medical X-ray Generator Market Size by Diagnostic Sub-Type (2021-2031) (USD Million) 27
Table 8 Global NDT & Security X-ray Generator Market Size by Vertical (2021-2031) (USD Million) 30
Table 9 Global X-ray Generator Revenue by Sales Channel (2021-2031) (USD Million) 33
Table 10 Global X-ray Generator Volume by Sales Channel (2021-2031) (Units) 34
Table 11 Global X-ray Generator Cross-Border Export Shipments by Leading Nation (2021-2026) (Units) 39
Table 12 Global X-ray Generator Cross-Border Import Values by Leading Destination (2021-2026) (USD Million) 41
Table 13 Global X-ray Generator Market Revenue by Region (2021-2031) (USD Million) 43
Table 14 Global X-ray Generator Market Volume by Region (2021-2031) (Units) 44
Table 15 North America X-ray Generator Market Size and Volume by Country (2021-2031) 45
Table 16 Europe X-ray Generator Market Size and Volume by Country (2021-2031) 49
Table 17 Asia-Pacific X-ray Generator Market Size and Volume by Country (2021-2031) 56
Table 18 Latin America X-ray Generator Market Size and Volume by Country (2021-2031) 59
Table 19 Middle East & Africa X-ray Generator Market Size and Volume by Country (2021-2031) 59
Table 20 Global Top 8 X-ray Generator Manufacturers Market Concentration Ratios (2021-2026) 61
Table 21 Varex Imaging Corporation X-ray Generator Sales, Price, Cost and Gross Profit Margin (2021-2026) 66
Table 22 Comet Holding AG X-ray Generator Sales, Price, Cost and Gross Profit Margin (2021-2026) 70
Table 23 iRay Technology X-ray Generator Sales, Price, Cost and Gross Profit Margin (2021-2026) 74
Table 24 Spellman High Voltage Electronics Corporation X-ray Generator Sales, Price, Cost and Gross Profit Margin (2021-2026) 78
Table 25 Communications & Power Industries (CPI) X-ray Generator Sales, Price, Cost and Gross Profit Margin (2021-2026) 82
Table 26 EMD Technologies X-ray Generator Sales, Price, Cost and Gross Profit Margin (2021-2026) 86
Table 27 Teledyne ICM X-ray Generator Sales, Price, Cost and Gross Profit Margin (2021-2026) 90
Table 28 Siemens Healthineers AG X-ray Generator Sales, Price, Cost and Gross Profit Margin (2021-2026) 94
Table 29 Philips X-ray Generator Sales, Price, Cost and Gross Profit Margin (2021-2026) 98
Table 30 Suzhou Powersite Electric Co., Ltd. X-ray Generator Sales, Price, Cost and Gross Profit Margin (2021-2026) 102
Table 31 VJ X-Ray X-ray Generator Sales, Price, Cost and Gross Profit Margin (2021-2026) 106
Table 32 Balteau NDT X-ray Generator Sales, Price, Cost and Gross Profit Margin (2021-2026) 110
Table 33 Baker Hughes X-ray Generator Sales, Price, Cost and Gross Profit Margin (2021-2026) 114
Table 34 Five-Year Segmental Market Opportunity Matrix (2027-2031) (USD Million) 117
Figure 1 Global X-ray Generator Valuation and Growth Velocity (2021-2031) 3
Figure 2 End-to-End X-ray Generator Value Chain Margin Waterfall 8
Figure 3 Primary Cost Structure of Advanced High-Frequency X-ray Generators 10
Figure 4 Global Regulatory Timeline and Compliance Roadmaps for Medical High-Voltage Subsystems 12
Figure 5 Global X-ray Generator Market Share by Technology Type (2021 vs 2026 vs 2031) 18
Figure 6 High-Frequency Inverter Adoption Trajectory in Industrial vs Medical Sectors 21
Figure 7 Global X-ray Generator Market Share by Application (2026) 25
Figure 8 Medical Imaging Sub-Segment Growth Rates vs Market Size (2026-2031) 28
Figure 9 NDT & Industrial Metrology Demand Velocity Index (2021-2031) 31
Figure 10 Sales Channel Value Migration: Direct OEM vs Aftermarket Lifecycle (2021-2031) 34
Figure 11 Global X-ray Generator Production Capacity Distribution by Key Manufacturing Country (2026) 38
Figure 12 Global Trade Flow Logistics and Export Volume Mapping 40
Figure 13 Regional Revenue Contribution Comparison (2021 vs 2026 vs 2031) 44
Figure 14 United States Medical and NDT Generator Absorption Trends (2021-2031) 46
Figure 15 European Core Production and Export Hub Distribution (2026) 49
Figure 16 Asia-Pacific Market Penetration and Local Manufacturing Expansion (2021-2031) 57
Figure 17 X-ray Generator Market Competitive Positioning Grid (Market Share vs Technology Capability) 62
Figure 18 Varex Imaging Corporation X-ray Generator Market Share (2021-2026) 67
Figure 19 Comet Holding AG X-ray Generator Market Share (2021-2026) 71
Figure 20 iRay Technology X-ray Generator Market Share (2021-2026) 75
Figure 21 Spellman High Voltage Electronics Corporation X-ray Generator Market Share (2021-2026) 79
Figure 22 Communications & Power Industries (CPI) X-ray Generator Market Share (2021-2026) 83
Figure 23 EMD Technologies X-ray Generator Market Share (2021-2026) 87
Figure 24 Teledyne ICM X-ray Generator Market Share (2021-2026) 91
Figure 25 Siemens Healthineers AG X-ray Generator Market Share (2021-2026) 95
Figure 26 Philips X-ray Generator Market Share (2021-2026) 99
Figure 27 Suzhou Powersite Electric Co., Ltd. X-ray Generator Market Share (2021-2026) 103
Figure 28 VJ X-Ray X-ray Generator Market Share (2021-2026) 107
Figure 29 Balteau NDT X-ray Generator Market Share (2021-2026) 111
Figure 30 Baker Hughes X-ray Generator Market Share (2021-2026) 115
Figure 31 Global Market Five-Year Trajectory and Forecast Growth Corridor (2027-2031) 118
Research Methodology
- Market Estimated Methodology:
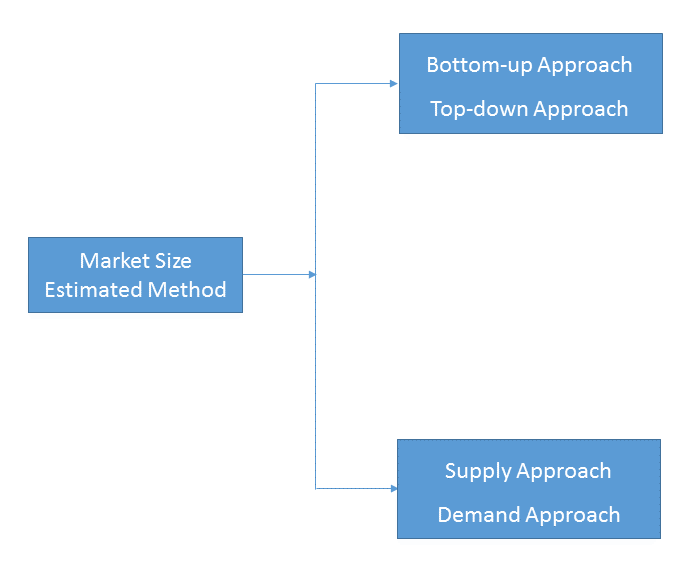
Bottom-up & top-down approach, supply & demand approach are the most important method which is used by HDIN Research to estimate the market size.
1)Top-down & Bottom-up Approach
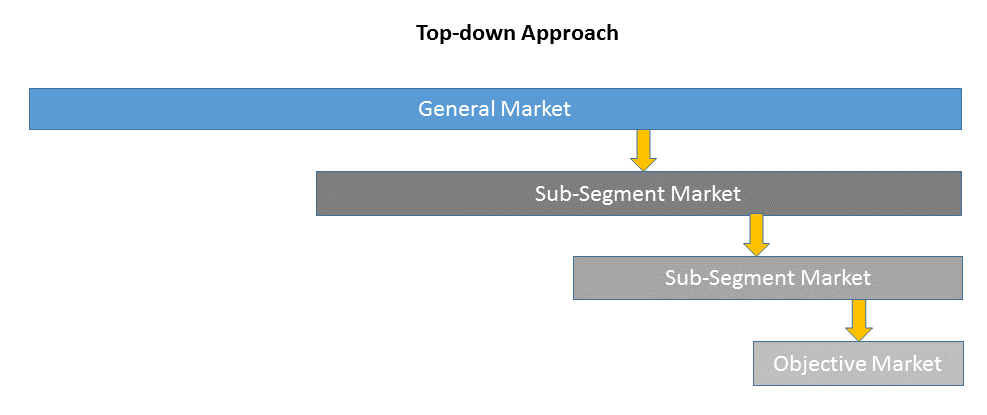
Top-down approach uses a general market size figure and determines the percentage that the objective market represents.
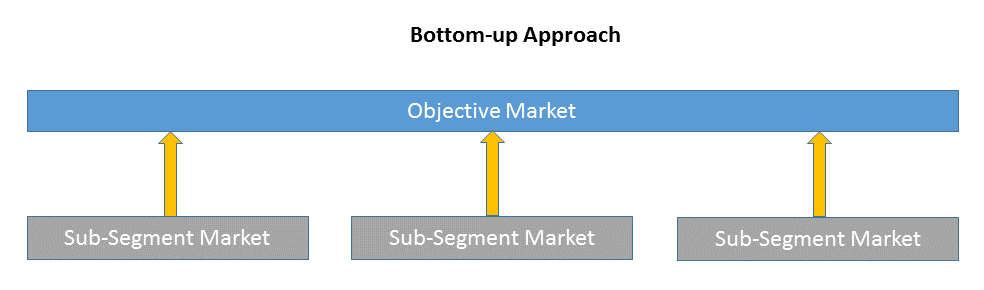
Bottom-up approach size the objective market by collecting the sub-segment information.
2)Supply & Demand Approach
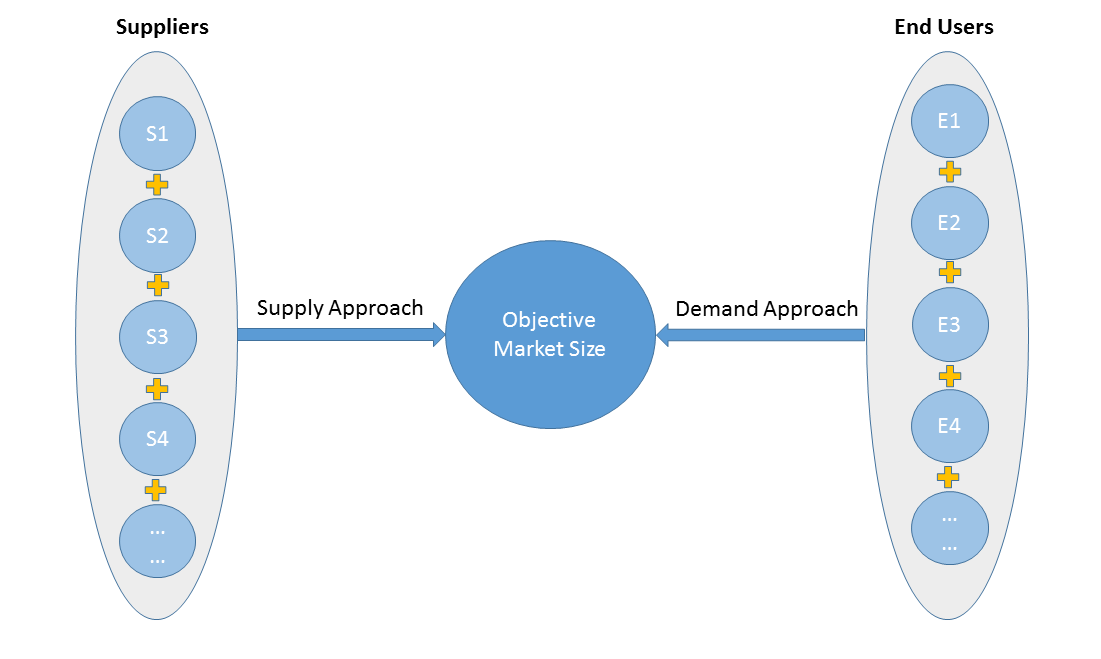
Supply approach is based on assessments of the size of each competitor supplying the objective market.
Demand approach combine end-user data within a market to estimate the objective market size. It is sometimes referred to as bottom-up approach.
- Forecasting Methodology
- Numerous factors impacting the market trend are considered for forecast model:
- New technology and application in the future;
- New project planned/under contraction;
- Global and regional underlying economic growth;
- Threatens of substitute products;
- Industry expert opinion;
- Policy and Society implication.
- Analysis Tools
1)PEST Analysis
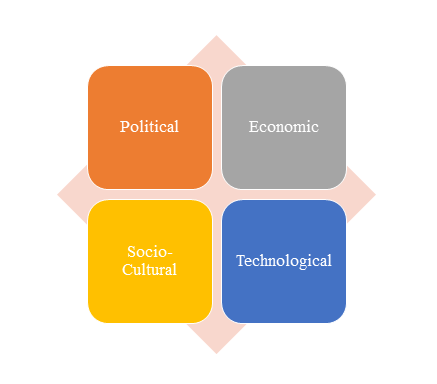
PEST Analysis is a simple and widely used tool that helps our client analyze the Political, Economic, Socio-Cultural, and Technological changes in their business environment.
- Benefits of a PEST analysis:
- It helps you to spot business opportunities, and it gives you advanced warning of significant threats.
- It reveals the direction of change within your business environment. This helps you shape what you’re doing, so that you work with change, rather than against it.
- It helps you avoid starting projects that are likely to fail, for reasons beyond your control.
- It can help you break free of unconscious assumptions when you enter a new country, region, or market; because it helps you develop an objective view of this new environment.
2)Porter’s Five Force Model Analysis
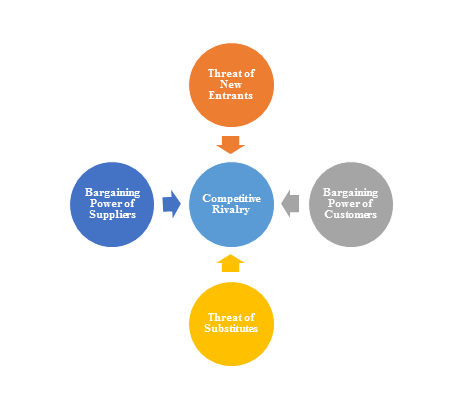
The Porter’s Five Force Model is a tool that can be used to analyze the opportunities and overall competitive advantage. The five forces that can assist in determining the competitive intensity and potential attractiveness within a specific area.
- Threat of New Entrants: Profitable industries that yield high returns will attract new firms.
- Threat of Substitutes: A substitute product uses a different technology to try to solve the same economic need.
- Bargaining Power of Customers: the ability of customers to put the firm under pressure, which also affects the customer's sensitivity to price changes.
- Bargaining Power of Suppliers: Suppliers of raw materials, components, labor, and services (such as expertise) to the firm can be a source of power over the firm when there are few substitutes.
- Competitive Rivalry: For most industries the intensity of competitive rivalry is the major determinant of the competitiveness of the industry.
3)Value Chain Analysis
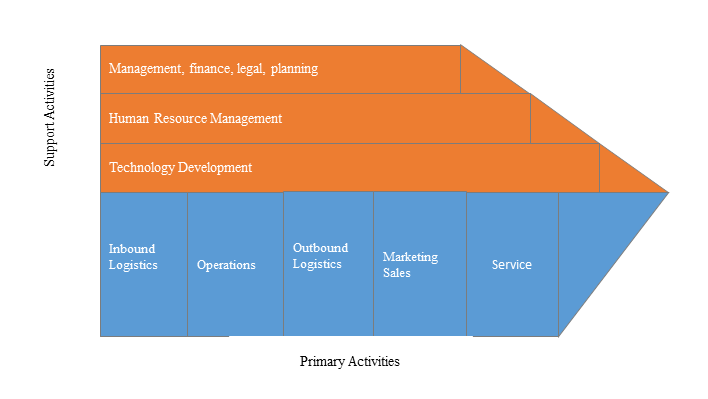
Value chain analysis is a tool to identify activities, within and around the firm and relating these activities to an assessment of competitive strength. Value chain can be analyzed by primary activities and supportive activities. Primary activities include: inbound logistics, operations, outbound logistics, marketing & sales, service. Support activities include: technology development, human resource management, management, finance, legal, planning.
4)SWOT Analysis
SWOT analysis is a tool used to evaluate a company's competitive position by identifying its strengths, weaknesses, opportunities and threats. The strengths and weakness is the inner factor; the opportunities and threats are the external factor. By analyzing the inner and external factors, the analysis can provide the detail information of the position of a player and the characteristics of the industry.
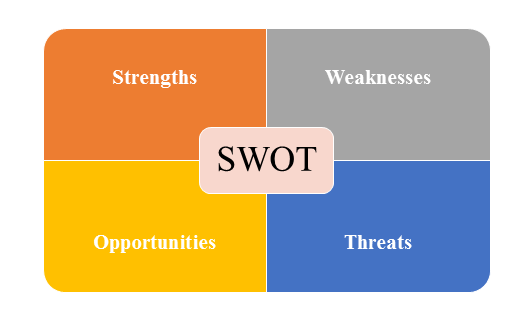
- Strengths describe what the player excels at and separates it from the competition
- Weaknesses stop the player from performing at its optimum level.
- Opportunities refer to favorable external factors that the player can use to give it a competitive advantage.
- Threats refer to factors that have the potential to harm the player.
- Data Sources
| Primary Sources | Secondary Sources |
|---|---|
| Face to face/Phone Interviews with market participants, such as: Manufactures; Distributors; End-users; Experts. Online Survey |
Government/International Organization Data: Annual Report/Presentation/Fact Book Internet Source Information Industry Association Data Free/Purchased Database Market Research Report Book/Journal/News |