Industrial X-ray Flat Panel Detector Market Outlook 2031
- Single User License (1 Users) $ 3,500
- Team License (2~5 Users) $ 4,500
- Corporate License (>5 Users) $ 5,500
The global industrial X-ray flat panel detector (FPD) represents an essential photon-conversion layer embedded within the modern non-destructive testing (NDT), automated X-ray inspection (AXI), and security infrastructure ecosystem. The global industrial FPD market will reach to 620-820 million USD by 2026, the sector is modeled to expand at a compound annual growth rate (CAGR) of 3.5%-5.5% through 2031. This expansion is governed by an engineering shift away from human-interpreted diagnostic radiography toward high-throughput, machine-vision-coupled inline metrology.
The Asia-Pacific geographic theater acts as the primary manufacturing epicenter and consumption basin, absorbing over 65% of annual unit shipments. High factory density across China, South Korea, Japan, and Taiwan, China drives procurement for gigafactory battery inspection lines and surface-mount technology (SMT) workflows, while mature Western jurisdictions (North America and Europe) prioritize high-energy radiation-hardened applications, defense ordnance metrology, and aviation casting certification.
PRODUCT TAXONOMY AND TECHNICAL ARCHITECTURE
Industrial X-ray FPDs operate by converting attenuated high-energy photon beams into spatially calibrated digital signals. Engineering requirements demand high radiation hardness, wide temperature stability, ingress-protected mechanical housings (IP65 to IP67), and rapid data interfaces (10GigE, Camera Link, CoaXPress).
1. Classification by Semiconductor Substrate and Sensor Matrix
- Amorphous Silicon (a-Si) FPDs: The historical bedrock of high-energy, large-format industrial imaging. Fabricated by depositing hydrogenated amorphous silicon thin-film transistors and photodiodes onto large glass panels, a-Si arrays offer proven mechanical resilience, wide operational voltage tolerances (up to 450 kV and MV linac energies), and scalable form factors (e.g., 17x17-inch, 24x24-inch, and 17x48-inch single-plate geometries). While standard electron mobility is limited (under 1 cm2/V-s), limiting pixel readout velocity, their high thermal stability makes them the standard for aerospace foundries, structural steel verification, and heavy casting inspection.
- Indium Gallium Zinc Oxide (IGZO) FPDs: An advanced metal-oxide TFT substrate engineered to eliminate the carrier-mobility bottleneck of a-Si. Offering electron mobility factors 20 to 30 times superior to standard silicon backplanes, IGZO enables sub-100 micrometer pixel pitches, substantially suppressed readout noise, and rapid 2D/3D dynamic acquisition speeds (>30 to 60 FPS full-frame). Because IGZO arrays can be produced on large-generation display fab lines without the spatial size limits of single-crystal silicon ingots, they provide a compelling cost-to-area ratio. This architecture is increasingly selected for high-speed, inline electric vehicle (EV) battery inspection and high-density printed circuit board assembly (PCBA) quality control.
- Complementary Metal-Oxide-Semiconductor (CMOS) FPDs: The high-precision frontier in non-destructive metrology. Built on crystalline silicon wafers using standard semiconductor lithography, CMOS detectors integrate active pixel amplification directly at each node. This architecture yields ultra-low readout noise, high dynamic ranges, sub-micron micro-focus resolution (pixel pitches ranging from 14.8 to 75 micrometers), and dynamic frame speeds often exceeding 60 to 100 FPS (with line-scan modes scaling past 300 FPS). Due to physical silicon wafer size ceilings, large active areas require precision optical tiling (stitching). CMOS remains the dominant technical standard for semiconductor advanced packaging, Through-Silicon Via (TSV) inspection, micro-focus CT, and precision wire bonding verification.
- Flexible Polyimide Substrates: The structural substitution of rigid glass backplanes with thin, flexible polyimide substrates. Paired with direct-evaporated columnar scintillators, flexible detectors offer high drop and impact resistance, true thin-profile cassette packaging, and conformal curvature capabilities. These systems solve access constraints in field oil and gas pipelines, structural airframe evaluation, and explosive ordnance disposal (EOD) security missions.
2. Classification by Operating Mode and Readout Kinetics
- Static Industrial FPDs: Radiographic capture devices running in single-frame, trigger-synchronized modes. Utilized primarily for off-line spot verification, laboratory failure analysis, static weld certification, and non-continuous field radiography where cycle speed is subordinate to dynamic exposure control and maximum signal-to-noise ratio (SNR).
- Dynamic High-Speed Industrial FPDs: Continuous fluoroscopy and high-pulse acquisition engines running at 30 to 60+ full frames per second. These platforms integrate fast frame-grabber interfaces and high-bandwidth processing backplanes to execute real-time automated defect recognition (ADR) on factory conveyors, inline rotational Computed Tomography (CT), and weld-seam tracking systems operating without line-stoppage.
3. Classification by Conversion Mechanism
- Indirect Conversion FPDs: Comprising over 90% of industrial market installations. Incident X-ray photons strike an integrated scintillator screen, generating visible-wavelength photons that are subsequently captured by an underlying photodiode array. Scintillators are divided between thermally evaporated, needle-structured columnar Thallium-doped Cesium Iodide (CsI:Tl)—which limits optical lateral scattering to deliver superior spatial resolution and high Detective Quantum Efficiency (DQE)—and Gadolinium Oxysulfide (GOS / Gadox) screens, preferred for harsh, high-energy operations due to mechanical robustness and radiation resilience.
- Direct Conversion and Photon-Counting FPDs: Utilizing high-resistivity photoconductor crystal layers, such as Cadmium Zinc Telluride (CZT), Cadmium Telluride (CdTe), or amorphous Selenium (a-Se). X-ray photons are converted directly into mobile electron-hole pairs under an applied high-voltage electric field, eliminating optical diffusion entirely. Direct photon-counting detectors process individual photons, binning pulses into distinct energy spectra. This delivers infinite nominal contrast, zero dark current read-noise, and multi-energy material decomposition capabilities, representing an emerging frontier for semiconductor void characterization, micro-metrology, and multi-density scrap recycling sorting.
4. Classification by Form Factor and System Integration
- Fixed Detectors: Hardwired, structurally reinforced enclosures engineered for stationary incorporation within shielded radiation cabinets, automated inline sorting bays, and heavy CT gantries. Utilizing direct industrial power drops and fiber-optic data pipelines, they run 24/7 continuous duty cycles under active thermal management.
- Wireless Portable Detectors: Field-deployable, battery-operated cassette-sized formats (e.g., 10x12, 14x17 inches) protected by carbon-fiber enclosures, impact bumpers, and IP65/IP67 seals. Featuring on-board high-speed dual-band Wi-Fi, automatic exposure detection (AED), and hot-swappable power cells, these units serve field pipeline crawlers, high-altitude structural testing, and field military defense operations.
SUPPLY CHAIN AND VALUE CHAIN ARCHITECTURE
The industrial flat panel detector value chain is a high-barrier-to-entry, optoelectronic ecosystem. Value flows across three conversion tiers, characterized by specialized capital expenditures and tight engineering relationships.
1. Upstream Value Chain: Substrates, Precursors, and Specialized Components
The upstream tier supplies raw materials, specialized chemical formulations, foundries, and integrated circuits:
- Sensor Substrates: Large-format flat-panel display fabs supply customized a-Si and IGZO thin-film transistor backplanes. Key merchant suppliers include foundries across East Asia (e.g., Innolux, BOE), while specialized silicon foundries (e.g., TSMC) process large-die CMOS active-pixel sensor wafers.
- Photonic Precursors: High-purity Cesium Iodide (CsI), Thallium dopants, and GOS phosphor powders require controlled synthesis environments. Direct conversion crystal growth (CdTe, CZT) represents a bottleneck, with limited commercial capacity worldwide.
- Integrated Circuit Electronics: Low-noise, multichannel Readout Integrated Circuits (ROICs), 16-bit analog-to-digital converters (ADCs), and high-performance Field Programmable Gate Arrays (FPGAs) are critical for signal processing.
- Radiation Hardening and Housing Materials: High-density lead and tungsten alloys for internal radiation shielding, advanced carbon-fiber structural composite faceplates for low beam attenuation, and thermal management compounds are sourced from specialized industrial materials converters.
- X-Ray Generation Sources: The complementary subsystem upstream ecosystem comprises micro-focus X-ray tubes (open and closed types), constant-potential high-voltage generators (160 kV to 450 kV), and high-energy linear accelerator (Linac) sources operating into the MeV regime.
2. Midstream Value Chain: Detector Synthesis, Scintillator Deposition, and Calibration
Midstream represents the core operational domain of the FPD manufacturer:
- Precision Scintillator Growth: Deposition of columnar CsI:Tl onto the TFT or CMOS substrate requires proprietary thermal evaporation vacuum chambers. The needle geometry must be precisely controlled in thickness (from 150 to over 600 micrometers) to balance X-ray absorption stopping power against optical resolution drop-off.
- Chip-on-Flex (COF) and Module Packaging: Automated wire bonding and anisotropic conductive film (ACF) bonding attach high-density ROICs to the microscopic pitch arrays of the substrate.
- Firmware, Calibration, and AI-ADR Hardening: Detectors undergo extensive calibration processes, including gain/offset corrections, defective pixel mapping, dynamic lag correction, and internal algorithmic software-development-kit (SDK) optimization to interface with automated defect recognition (ADR) machine vision pipelines.
- Enclosure Integration: Internal radiation shielding installation, thermal heat sink design, environmental sealing, and SEMI S2/CE regulatory certification.
3. Downstream Value Chain: Machine Integrators and Industrial End-Users
- Industrial System Integrators (OEMs): Midstream FPD modules are sold primarily to industrial system builders who package the detector with X-ray tubes, precision multi-axis motion gantries, radiation-safe cabinets, and proprietary inspection software. Major global integrators include Comet Yxlon, VJ Technologies, Nordson DAGE, Waygate Technologies, Nikon Metrology, Rapiscan Systems, Smiths Detection, and specialized battery automation builders.
- End-User Industrial Verticals: Turnkey machines are deployed in high-volume production facilities: EV battery gigafactories, semiconductor foundries and outsourced semiconductor assembly and test (OSAT) sites, aerospace turbine manufacturing plants, structural foundries, petrochemical field operations, and international border security hubs.
DOWNSTREAM APPLICATION ANALYSIS
Industrial FPD capital allocation is determined by operational uptime, spatial resolution, and inspection cycle time across distinct operational domains.
1. Power Battery Inspection (EV Gigafactories)
Power battery manufacturing is a major growth engine for industrial dynamic FPDs. The aggressive global ramp-up of electric vehicle capacity necessitates 100% inline non-destructive screening of battery cells (prismatic, pouch, and cylindrical formats) to eliminate structural defects capable of causing catastrophic thermal runaway.
- Inspection Requirements: Sub-micron to low-micron detection of cathode/anode overhang margins, internal tab weld void ratios, electrode delamination, separator pinholes, and metallic particulate contamination.
- Architectural Pivot: The sector is executing a major transition away from slow 2D radiographic spot checks toward 100% automated inline 3D Micro-CT and high-speed dynamic fluoroscopy. This operational tempo requires detectors operating at sustained rates of 30 to 60+ full frames per second. High-mobility IGZO and dynamic CMOS detectors have largely superseded a-Si in this space due to lower operational lag and reduced motion blur at high conveyor speeds.
2. Semiconductor and Microelectronics Packaging
The expansion of Artificial Intelligence (AI) computational accelerators, High-Bandwidth Memory (HBM), 2.5D/3D chip stacking, Through-Silicon Vias (TSV), and Through-Glass Vias (TGV) has exceeded the physical inspection boundaries of optical and acoustic metrology.
- Inspection Requirements: Micro-focus automated X-ray inspection (AXI) and high-magnification Planar CT systems demand pixel pitches under 50 micrometers (frequently down to sub-20 micrometers) and spatial resolutions measuring in the sub-micron domain.
- Technical Dynamics: CMOS flat panel detectors dominate this high-precision tier. Key inspection objectives include micro-voiding in high-density Ball Grid Arrays (BGA), micro-bump misalignment, sub-surface silicon micro-cracking, and non-visual solder bridging. Furthermore, wide-bandgap semiconductors such as Silicon Carbide (SiC) and Gallium Nitride (GaN) rely on composite X-ray and Optical Coherence Tomography (OCT) inspection platforms to verify crystal ingot density and wafer slicing integrity.
3. Heavy Industry, Aerospace, Automotive, and Energy Infrastructure
The foundational industrial NDT sector demands heavy radiation tolerance and large physical imaging surfaces.
- Technical Dynamics: Aerospace engine turbine blade verification, solid rocket motor casing analysis, thick automotive structural aluminum die-castings, and additive manufacturing (3D printed metal components) require high-energy, radiation-hardened large-format a-Si detectors (e.g., 17x17-inch, 17x48-inch formats). These systems routinely operate alongside constant potential X-ray tubes ranging from 225 kV to 450 kV, as well as high-energy linear accelerators running at 6 to 15 MV.
- Infrastructure and Field Pipelines: Oil and gas cross-country pipelines, subsea assets, and pressure vessels rely heavily on ruggedized, IP67-rated portable wireless FPDs. Flexible polyimide substrate detectors and custom curved panels are deployed on pipeline crawlers to capture circumferential weld integrity in a single exposure without geometric projection distortion.
4. Civil Security, Cargo Scanning, and Defense
Border customs checkpoints, international airports, high-throughput seaport cargo stations, and defense operations employ diverse X-ray detector architectures.
- Technical Dynamics: High-throughput checked-baggage CT scanners, drive-through container cargo inspection gantries, and mobile vehicle scanners deploy a combination of dual-energy multi-channel line-scan detectors, TDI CMOS arrays, and large-area radiation-hardened flat panel detectors. Key operational factors include penetration power (scaling through 300 mm to 400 mm of structural steel via MeV Linac sources) and rapid material discrimination capabilities based on dual-energy effective atomic number (Z-eff) sorting. Military and bomb disposal (EOD) squads deploy ruggedized, battery-operated, flexible, and wireless a-Si/CMOS cassettes for rapid, portable identification of improvised explosive devices (IEDs).
SALES CHANNELS AND COMMERCIAL DISTRIBUTION MODELS
1. The Original Equipment Manufacturer (OEM) Channel
The OEM channel accounts for approximately 75% to 85% of global industrial FPD revenue. Specialized detector manufacturers supply bare or encased FPD modules, proprietary interface boards, and software developer kits (SDKs) directly to industrial inspection machine builders and systems integrators.
- Commercial Dynamics: The OEM sales cycle is lengthy, typically requiring an intensive 12-to-36-month co-engineering and qualification phase. Integrators evaluate detectors for thermal stability, dynamic beam resilience, structural shock tolerance, driver stability, and interface compatibility with established machine-vision software frameworks.
- Switching Costs and Moats: Once an FPD is designed into an OEM gantry, locked into mechanical enclosures, and tuned to an automated algorithmic defect-recognition pipeline, replacement costs are high. Component suppliers secure steady, predictable multi-year revenue streams across the commercial life cycle of the integrator's equipment model.
2. Aftermarket, Retrofit, and Direct System Integration
Capturing the remaining 15% to 25% of the market, this channel services end-user manufacturing plants, specialized commercial testing laboratories, NDT service bureaus, and regional industrial distributors.
- Fleet Retrofits: Upgrading legacy computed radiography (CR) or film workflows to fully digital radiography (DR) in field testing environments (e.g., pipeline weld inspections or shipyard evaluations).
- Module Replacement: High-utilization manufacturing sites—such as 24/7 battery gigafactories and continuous aluminum die-casting plants—require direct component swaps to replace modules damaged by beam burn-in, physical impact, or electronic degradation over time.
- Integrated Solutions: Certain detector manufacturers pursue selective downstream forward integration, selling specialized turnkey inspection machines (e.g., high-voltage cargo security systems or SiC wafer metrology benches) directly to end-users.
REGIONAL MARKET DYNAMICS AND POLICY FRAMEWORKS
1. Asia-Pacific (APAC)
Asia-Pacific serves as the dominant manufacturing base and primary consumption engine for industrial FPDs, representing over two-thirds of worldwide unit volume.
- China: The largest sovereign market for automated industrial X-ray inspection. Driven by industrial transformation mandates, 100% inline X-ray inspection has become standard across battery gigafactories and consumer electronics manufacturing. Domestic component champions benefit from strong policy support, while international vendors pursue localized manufacturing arrangements in industrial centers like Wuxi, Beijing, and Shanghai.
- India: Expanding as a competitive electronics and precision manufacturing hub. International suppliers are establishing local manufacturing cleanrooms and assembly centers (such as new ISO 7 cleanroom facilities in Delhi) to serve domestic security, railway, and automotive casting industries under localization initiatives.
- Japan and South Korea: Advanced engineering markets housing major FPD developers and Tier-1 automotive and semiconductor manufacturers. Japanese developers maintain strong market share in scientific micro-focus optoelectronics, while South Korean manufacturers export high volumes of field NDT and dynamic battery inspection panels globally.
- Taiwan, China: A global epicenter for semiconductor fabrication and advanced packaging, driving steady demand for high-end micro-focus CMOS flat panel detectors and Planar CT inspection systems.
2. North America
North America represents a high-value market focused on defense aerospace, military munitions, civil infrastructure NDT, and border security.
- Regulatory and Strategic Posture: Growth is anchored by strict Federal Aviation Administration (FAA) non-destructive evaluation standards, Department of Defense (DoD) mission-assurance requirements, and American Petroleum Institute (API) pipeline safety codes. High-energy linear accelerators are governed by strict export control frameworks and licensing oversight.
- Trade Policy Adjustments: Sourcing dynamics are influenced by tariffs on sub-assemblies and trade remedies, incentivizing Tier-1 system builders to qualify multi-regional component supply sources and leverage foreign trade zones (FTZs).
3. Europe
The European market is defined by high adoption in automotive manufacturing, high-end aerospace assemblies, nuclear power maintenance, and recycling sorting automation.
- Regulatory Environment: Equipment must comply with strict CE marking protocols, European Machinery Directives, RoHS 3 (Directive 2011/65/EU), and REACH chemical compliance frameworks.
- Circular Economy Mandates: In alignment with regional sustainability directives, European OEMs and suppliers increasingly prioritize modular, repairable architectures, lower operational power envelopes, and the substitution of hazardous materials across manufacturing processes.
4. South America
Industrial demand in South America is concentrated across energy pipelines, mining infrastructure, automotive manufacturing (principally Brazil and Mexico), and civil security.
- Market Characteristics: Field operations favor durable, high-impact, wireless portable FPD systems capable of operating under high ambient temperatures, humidity, and remote conditions for oil and gas pipeline validation and mineral sorting.
5. Middle East and Africa (MEA)
The MEA region is sustained by large-scale hydrocarbon infrastructure investments, heavy industrial petrochemical projects, and customs logistics automation.
- Market Drivers: Routine radiographical pipeline inspection requires portable, field-ruggedized detectors equipped with hot-swappable batteries, internal shielding, and wireless links. GCC transportation hubs also drive sustained demand for high-energy cargo and baggage scanning flat panels.
COMPETITIVE DOSSIERS: KEY MARKET PLAYERS
1. Varex Imaging Corporation
- Strategic Profile: Headquartered in Salt Lake City, Utah, Varex Imaging operates as the world's largest independent supplier of medical and industrial X-ray components, with a footprint spanning linear accelerators, tubes, and multi-technology FPDs.
- Technical Moats: Varex possesses a broad intellectual property portfolio spanning a-Si, high-speed CMOS (Dexela series), and proprietary Oxide TFT/IGZO (Z-Platform) technologies. The Dexela CMOS family (e.g., 1207, 1512, 2315, 2923) delivers spatial resolutions down to 75 micrometers and frame rates scaling past 80 FPS, serving inline battery and semiconductor inspection. Its XRD and PaxScan product lines supply radiation-hardened a-Si solutions capable of operating from 40 kVp up to multi-MeV linear accelerator energies (Linatron systems).
- Operational Resilience: Maintains global manufacturing, assembly, and service centers across the United States, Europe, the Philippines, India, and China to mitigate geopolitical supply frictions.
2. iRay Technology
- Strategic Profile: A vertically integrated optoelectronic sensor manufacturer headquartered in China, iRay has expanded its industrial presence into dynamic factory automation, semiconductor packaging, and field NDT.
- Technical Moats: Full internal control across the value chain, including in-house ASIC design, thin-film transistor lithography, automated continuous Cesium Iodide thermal evaporation, and dynamic calibration algorithms. Its product portfolio spans the Pluto series (CMOS for micro-focus semiconductor packaging), the Venu series (large-area IGZO panels targeting inline battery CT at 60 FPS), and the Mars/NDT series (ruggedized, IP67-rated portable field panels and heavy casting inspection detectors up to 450 kV).
- Strategic Initiatives: Capitalizing on core cleanroom lithography infrastructure, the company is diversifying into adjacent optoelectronic architectures, including silicon-based OLED micro-display backplanes for spatial computing.
3. Detection Technology Plc
- Strategic Profile: Based in Finland, Detection Technology expanded from linear multi-channel X-ray detector arrays into large-format flat panel detectors with its specialized industrial X-Panel portfolio.
- Technical Moats: High-energy engineering expertise. The X-Panel XL series (notably the single-glass 43x108 cm X-Panel 43108a) enables ultra-large-area inspection without image-stitching seams, designed to withstand photon energies up to 16 MV for aerospace casting and defense applications. The company also manufactures dynamic CMOS flat panels (X-Panel 1511, 2222) optimized for high-speed automated electronics sorting and industrial CT.
- Global Footprint: Counterbalances supply chain vulnerabilities through dual-hub R&D and cleanroom operations in Finland and China, supplemented by a dedicated production facility in Greater Delhi, India.
4. Hamamatsu Photonics
- Strategic Profile: Headquartered in Japan, Hamamatsu represents a preeminent global optoelectronics pioneer, commanding high market share in high-precision scientific imaging and ultra-high-resolution industrial inspection.
- Technical Moats: Proprietary coupling of specialized fiber-optic plates (FOP) directly to custom CMOS active pixel sensors, layered with precision columnar CsI:Tl scintillators. Product lines (such as the C7942, C10900, and C14200 families) deliver high modulation transfer function (MTF), low noise, and sub-micron resolution. They serve microfocus X-ray inspection of advanced microelectronics, automotive ECUs, and cylindrical battery tab structures.
5. Teledyne DALSA
- Strategic Profile: A subsidiary of Teledyne Technologies, this Canadian-based imaging business unit specializes in high-speed, high-performance industrial CMOS sensor fabrication and machine vision components.
- Technical Moats: The Shad-o-Box HS and Rad-icon CMOS platform families feature fine pixel pitches (49.5 to 99 micrometers), multi-Gigabit Ethernet and Camera Link interfaces, and frame rates up to 66 FPS. These systems are optimized for biomedical micro-CT, semiconductor wafer metrology, PCB component validation, and aerospace composite non-destructive testing.
6. Jiangsu CareRay Medical Systems Co. Ltd.
- Strategic Profile: An established digital X-ray flat panel provider based in China, CareRay has expanded its footprint across medical, veterinary, and high-duty-cycle industrial NDT markets.
- Technical Moats: Specializes in direct-evaporation columnar CsI and flexible-substrate integration across its CareVision and NDT portfolios (e.g., NDT 1012, 1417, and 1717). The company emphasizes narrow-edge bezel engineering (dead space margins under 5 mm), designed for tight-clearance pipeline weld radiography, structural pipe inspection, and 20 kVp to 450 kVp industrial inspection cells.
7. Vieworks
- Strategic Profile: Located in South Korea, Vieworks develops advanced optoelectronic systems for medical radiography, machine vision, and industrial NDT.
- Technical Moats: Combines proprietary hybrid signal-processing firmware with ruggedized hardware design. Its VIVIX-V line (including the glass-free, drop-resistant VIVIX-V 3643F) incorporates narrow bezels (2.8 mm), IP67 sealing, wide operating temperature thresholds (-20°C to +50°C), and 99-micrometer pixel pitches for field pipeline crawlers, defense EOD, and aerospace structural inspection.
8. DRTECH
- Strategic Profile: A South Korean digital imaging specialist recognized for engineering novel structural form factors for challenging NDT environments.
- Technical Moats: Developed the FleX series, featuring bendable and fixed-curved flat panel digital detectors (e.g., EXT1036B and EXT1036C). These detectors conform directly around curved pipelines and cylindrical pressure vessels, eliminating the tangential projection distortion inherent to flat sensors. The company also manufactures the compact EXT 1024S series, matching historical radiographic film form factors with full IP67 field-ruggedization.
9. Rayence
- Strategic Profile: A South Korean optoelectronic manufacturer maintaining dual-platform manufacturing capabilities across both a-Si TFT and CMOS detector technologies.
- Technical Moats: Produces thin, narrow-margin a-Si panels for pipeline inspection and civil security, complemented by a high-resolution industrial CMOS lineup (e.g., 0505A, 1515DCA) featuring pixel pitches down to 14.8 micrometers. These systems serve automated SMT component testing, semiconductor wire bonding, and inline EV battery inspection.
10. Fujifilm
- Strategic Profile: Operating via its global industrial NDT division, Fujifilm transitioned its imaging leadership from computed radiography (CR) plates to specialized digital industrial FPD platforms.
- Technical Moats: The DynamEx series leverages proprietary Irradiation Side Sampling (ISS) architecture, which positions the readout sensor array in front of the scintillator layer to intercept light where optical scatter is lowest. Combined with its proprietary NDT software suites, these systems are deployed for corrosion-under-insulation (CUI) monitoring, offshore platform piping, and aerospace wing structure verification.
OPPORTUNITIES AND STRUCTURAL INHIBITORS
1. Strategic Growth Arbitrage Opportunities
- The IGZO Transition Window in Factory Automation: A critical replacement cycle is underway within industrial automation. Conventional amorphous Silicon (a-Si) is reaching physical performance ceilings in high-throughput EV battery and PCBA environments due to carrier-mobility constraints. While CMOS provides high spatial resolution, it faces physical wafer size and stitching cost limitations across larger formats. High-mobility IGZO TFT arrays fill this operational gap, delivering frame rates exceeding 30 to 60 FPS over 17x17-inch active areas at lower cost-per-unit-area than tiled silicon. Component vendors scaling IGZO manufacturing will capture higher margin profiles as gigafactory inline CT becomes mandatory.
- Deep Firmware AI-ADR Convergence: Machine vision value is moving onto edge hardware. Industrial integrators increasingly favor detector architectures that handle low-level artifact reduction, gain calibration, and initial defect segmentation directly within onboard FPGAs. Detectors capable of serving pre-filtered, AI-ready data streams compress cycle times, reduce host PC computational load, and minimize false call rates on fast production lines.
- High-Energy Direct Conversion Commercialization: The industrialization of multi-energy photon-counting Cadmium Zinc Telluride (CZT) and Cadmium Telluride (CdTe) detectors presents a disruption opportunity in micro-packaging and scrap metallurgy. Suppliers that solve crystal yield bottlenecks will establish durable moats in high-density advanced packaging inspection and inline metal sorting.
2. Structural Inhibitors and Operational Vulnerabilities
- Average Selling Price (ASP) Compression in Static Radiography: The entry of multiple regional suppliers into standard 14x17-inch and 17x17-inch static a-Si detectors has driven price erosion in commoditized NDT segments. Vendors reliant on baseline radiographic hardware face structural gross margin compression, forcing operational pivots toward high-margin dynamic CMOS and specialized IGZO platforms.
- Extended Qualification and Redesign Moats: The 1-to-3-year design-in cycle required by Tier-1 industrial OEMs creates a structural barrier to rapid market share capture. Even technologically superior platforms face resistance from integrators unwilling to absorb the engineering costs, motion gantry redesigns, and software pipeline adjustments needed to qualify replacement hardware.
- Critical Precursor Sourcing and Geopolitical Exposure: Industrial FPD fabrication depends on volatile supply lines for high-purity Cesium Iodide crystals, rare earth phosphors, high-purity polyimide films, and specialized readout ASICs. Geopolitical frictions, export restrictions on advanced semiconductors, and localized tariff adjustments create supply chain vulnerabilities, requiring capital investments in redundant regional cleanroom capacity.
1.1 Report Scope and Objective 1
1.2 Research Methodology 2
1.2.1 Primary Research and Industry Interactions 2
1.2.2 Secondary Research and Database Validation 3
1.3 Market Estimation and Forecasting Modeling 4
1.4 Key Economic and Technological Assumptions 5
1.5 Abbreviations and Acronyms 6
Chapter 2 Executive Summary: Global Industrial X-ray Flat Panel Detector Landscape 7
2.1 Market Overview and Core Findings 7
2.2 Global Market Volume (Units) Trajectory (2021-2031) 8
2.3 Global Market Size (USD Million) Trajectory (2021-2031) 9
2.4 Strategic Value Migration Across Technology Platforms 10
Chapter 3 Value Chain Architecture, Ecosystem, and Production Processes 11
3.1 Upstream Raw Materials and Critical Component Sourcing 11
3.1.1 Scintillator Materials (CsI:Tl, GadOx) Deposition 12
3.1.2 Thin-Film Transistor (TFT) Arrays and CMOS Sensors 13
3.1.3 Readout Integrated Circuits (ROIC) and Packaging Substrates 14
3.2 Midstream Industrial Flat Panel Detector Assembly and Calibration 15
3.3 Downstream System Integration and Industrial NDT Equipment 16
3.4 Manufacturing Cost Breakdown and Yield Optimization 17
Chapter 4 Global Supply Chain Dynamics, Logistics, and International Trade 18
4.1 Global Supply Chain Resilience and Sourcing Geographies 18
4.2 Import and Export Matrix of Core Manufacturing Hubs 19
4.2.1 North American Export Outflows and Component Sourcing 20
4.2.2 European Advanced Optics and Detector Shipments 21
4.2.3 Asia-Pacific High-Volume Manufacturing and Export Hubs 22
4.3 Tariff Impacts, Export Controls, and Logistics Lead Times 23
Chapter 5 Global Industrial X-ray Flat Panel Detector Market by Semiconductor Substrate & Sensor Technology 24
5.1 Overview and Technology Performance Matrix 24
5.2 Amorphous Silicon (a-Si) FPD 25
5.2.1 Market Volume (Units) and Market Size (USD Million) (2021-2031) 25
5.2.2 Cost-to-Performance Dynamics and Application Penetration 26
5.3 Indium Gallium Zinc Oxide (IGZO) FPD 27
5.3.1 Market Volume (Units) and Market Size (USD Million) (2021-2031) 27
5.3.2 High-Frame-Rate Processing and Resolution Advantages 28
5.4 Complementary Metal-Oxide-Semiconductor (CMOS) FPD 29
5.4.1 Market Volume (Units) and Market Size (USD Million) (2021-2031) 29
5.4.2 Microfocus and Ultra-High-Resolution Inspection Alignment 30
5.5 Flexible Substrates FPD 31
5.5.1 Market Volume (Units) and Market Size (USD Million) (2021-2031) 31
5.5.2 Ruggedization, Weight Reduction, and Curved NDT Integration 32
Chapter 6 Global Market by Operating Mode, Conversion Mechanism & Form Factor 33
6.1 Market Breakdown by Operating Mode 33
6.1.1 Static Flat Panel Detector Market Dynamics (2021-2031) 33
6.1.2 Dynamic Flat Panel Detector Market Dynamics (2021-2031) 34
6.2 Market Breakdown by Conversion Mechanism 35
6.2.1 Indirect Conversion FPD (Scintillator-to-Photodiode) (2021-2031) 35
6.2.2 Direct Conversion FPD (Amorphous Selenium/CdTe) (2021-2031) 36
6.3 Market Breakdown by Form Factor & Integration 37
6.3.1 Wireless Industrial FPD (Field NDT and Portability) (2021-2031) 37
6.3.2 Fixed Industrial FPD (Inline Inspection and Automated Systems) (2021-2031) 38
Chapter 7 Global Industrial X-ray Flat Panel Detector Market by Sales Channel 39
7.1 OEM Channel Dynamics and System Integrator Contracts 39
7.1.1 Market Volume (Units) and Market Size (USD Million) (2021-2031) 40
7.2 Aftermarket & Replacement Channel Dynamics 41
7.2.1 Market Volume (Units) and Market Size (USD Million) (2021-2031) 42
Chapter 8 Global Industrial X-ray Flat Panel Detector Market by Downstream Application 43
8.1 Downstream Demand Taxonomy and Adoption Roadmaps 43
8.2 Power Battery Inspection 44
8.2.1 In-line EV Battery Cell, Module, and Pack Defect Detection 44
8.2.2 Market Volume (Units) and Market Size (USD Million) (2021-2031) 45
8.3 Semiconductor & Electronics 46
8.3.1 Advanced Packaging, SMT, and PCB Inspection 46
8.3.2 Market Volume (Units) and Market Size (USD Million) (2021-2031) 47
8.4 Automotive Manufacturing 48
8.4.1 Die-Casting, Structural Welds, and Powertrain Components 48
8.4.2 Market Volume (Units) and Market Size (USD Million) (2021-2031) 49
8.5 Energy Sector 50
8.5.1 Oil & Gas Pipelines, Pressure Vessels, and Wind Turbine Blades 50
8.5.2 Market Volume (Units) and Market Size (USD Million) (2021-2031) 51
8.6 Aerospace & Defense 52
8.6.1 Turbine Components, Composite Structures, and Maintenance NDT 52
8.6.2 Market Volume (Units) and Market Size (USD Million) (2021-2031) 53
8.7 Industrial Security and Screening 54
8.7.1 Cargo Inspection, Ordnance Verification, and Critical Assets 54
8.7.2 Market Volume (Units) and Market Size (USD Million) (2021-2031) 55
8.8 Other Applications (Foundry, Research Laboratories, Metrology) 56
8.8.1 Market Volume (Units) and Market Size (USD Million) (2021-2031) 56
Chapter 9 Regional Production and Consumption Analysis 57
9.1 North America 57
9.1.1 United States: Production Output, OEM Integration, and Demand (2021-2031) 58
9.1.2 Canada: Industrial NDT and Resource Infrastructure Demand (2021-2031) 59
9.2 Europe 60
9.2.1 Germany: Precision Engineering and Automotive Inspection (2021-2031) 61
9.2.2 France: Aerospace NDT Ecosystem and Deployment (2021-2031) 62
9.2.3 United Kingdom: Advanced Manufacturing and NDT Services (2021-2031) 63
9.2.4 Finland: High-End Sensor Innovation and Sensor Export (2021-2031) 64
9.2.5 Rest of Europe: Industrial Radiography Landscape (2021-2031) 65
9.3 Asia-Pacific 66
9.3.1 China: Lithium Battery CapEx, Electronics Hub, and Localized Sourcing (2021-2031) 67
9.3.2 Japan: Optical Innovation, Semiconductor Metrology, and Manufacturing (2021-2031) 68
9.3.3 South Korea: Display Fabrication, EV Battery Inspection, and Sensor Exports (2021-2031) 69
9.3.4 Rest of Asia-Pacific: Emerging Industrial Production Centers (2021-2031) 70
9.4 Rest of the World (Latin America, Middle East & Africa) 71
Chapter 10 Competitive Architecture and Market Concentration 72
10.1 Global Market Share Analysis (2021-2026) 72
10.2 Tiered Competitor Categorization (Tier-1, Tier-2, Emerging Specialists) 73
10.3 Mergers, Acquisitions, Strategic Alliances, and Technology Licensing 74
Chapter 11 Corporate Intelligence: Key Market Players 75
11.1 Varex Imaging Corporation 75
11.1.1 Corporate Profile and Operational Footprint 75
11.1.2 Product Portfolio and Industrial FPD Technological Capabilities 75
11.1.3 SWOT Analysis 76
11.1.4 Product-Specific Operational Metrics (Sales Volume, Revenue, Price, Cost, Gross Margin) 76
11.1.5 Strategic Go-to-Market and R&D Vector 77
11.2 iRay Technology 78
11.2.1 Corporate Profile and Operational Footprint 78
11.2.2 Product Portfolio and Industrial FPD Technological Capabilities 78
11.2.3 SWOT Analysis 79
11.2.4 Product-Specific Operational Metrics (Sales Volume, Revenue, Price, Cost, Gross Margin) 79
11.2.5 Strategic Go-to-Market and R&D Vector 80
11.3 Jiangsu CareRay Medical Systems Co. Ltd. 81
11.3.1 Corporate Profile and Operational Footprint 81
11.3.2 Product Portfolio and Industrial FPD Technological Capabilities 81
11.3.3 SWOT Analysis 82
11.3.4 Product-Specific Operational Metrics (Sales Volume, Revenue, Price, Cost, Gross Margin) 82
11.3.5 Strategic Go-to-Market and R&D Vector 83
11.4 Detection Technology Plc 84
11.4.1 Corporate Profile and Operational Footprint 84
11.4.2 Product Portfolio and Industrial FPD Technological Capabilities 84
11.4.3 SWOT Analysis 85
11.4.4 Product-Specific Operational Metrics (Sales Volume, Revenue, Price, Cost, Gross Margin) 85
11.4.5 Strategic Go-to-Market and R&D Vector 86
11.5 Hamamatsu Photonics 87
11.5.1 Corporate Profile and Operational Footprint 87
11.5.2 Product Portfolio and Industrial FPD Technological Capabilities 87
11.5.3 SWOT Analysis 88
11.5.4 Product-Specific Operational Metrics (Sales Volume, Revenue, Price, Cost, Gross Margin) 88
11.5.5 Strategic Go-to-Market and R&D Vector 89
11.6 Teledyne DALSA 90
11.6.1 Corporate Profile and Operational Footprint 90
11.6.2 Product Portfolio and Industrial FPD Technological Capabilities 90
11.6.3 SWOT Analysis 91
11.6.4 Product-Specific Operational Metrics (Sales Volume, Revenue, Price, Cost, Gross Margin) 91
11.6.5 Strategic Go-to-Market and R&D Vector 92
11.7 Fujifilm 93
11.7.1 Corporate Profile and Operational Footprint 93
11.7.2 Product Portfolio and Industrial FPD Technological Capabilities 93
11.7.3 SWOT Analysis 94
11.7.4 Product-Specific Operational Metrics (Sales Volume, Revenue, Price, Cost, Gross Margin) 94
11.7.5 Strategic Go-to-Market and R&D Vector 95
11.8 Vieworks 96
11.8.1 Corporate Profile and Operational Footprint 96
11.8.2 Product Portfolio and Industrial FPD Technological Capabilities 96
11.8.3 SWOT Analysis 97
11.8.4 Product-Specific Operational Metrics (Sales Volume, Revenue, Price, Cost, Gross Margin) 97
11.8.5 Strategic Go-to-Market and R&D Vector 98
11.9 DRTECH 99
11.9.1 Corporate Profile and Operational Footprint 99
11.9.2 Product Portfolio and Industrial FPD Technological Capabilities 99
11.9.3 SWOT Analysis 100
11.9.4 Product-Specific Operational Metrics (Sales Volume, Revenue, Price, Cost, Gross Margin) 100
11.9.5 Strategic Go-to-Market and R&D Vector 101
11.10 Rayence 102
11.10.1 Corporate Profile and Operational Footprint 102
11.10.2 Product Portfolio and Industrial FPD Technological Capabilities 102
11.10.3 SWOT Analysis 103
11.10.4 Product-Specific Operational Metrics (Sales Volume, Revenue, Price, Cost, Gross Margin) 103
11.10.5 Strategic Go-to-Market and R&D Vector 104
Chapter 12 Strategic Industry Horizon and Technological Transformation 105
Table 2 List of Technical and Industry Abbreviations 6
Table 3 Global Industrial X-ray Flat Panel Detector Market Volume (Units) and Growth Rate (2021-2031) 8
Table 4 Global Industrial X-ray Flat Panel Detector Market Size (USD Million) and Growth Rate (2021-2031) 9
Table 5 Manufacturing Cost Structure Breakdown of Industrial Flat Panel Detectors (2026) 17
Table 6 Global Industrial X-ray Flat Panel Detector Trade Flow Matrix: Major Exporting vs. Importing Hubs (2026) 19
Table 7 Global Industrial X-ray FPD Market Volume (Units) by Substrate Technology (2021-2031) 24
Table 8 Global Industrial X-ray FPD Market Size (USD Million) by Substrate Technology (2021-2031) 25
Table 9 Amorphous Silicon (a-Si) FPD Market Volume and Revenue by Region (2021-2031) 26
Table 10 Indium Gallium Zinc Oxide (IGZO) FPD Market Volume and Revenue by Region (2021-2031) 28
Table 11 Complementary Metal-Oxide-Semiconductor (CMOS) FPD Market Volume and Revenue by Region (2021-2031) 30
Table 12 Flexible Substrates FPD Market Volume and Revenue by Region (2021-2031) 32
Table 13 Global Industrial X-ray FPD Market by Operating Mode: Static vs. Dynamic (Units and USD Million) (2021-2031) 34
Table 14 Global Industrial X-ray FPD Market by Conversion Mechanism: Indirect vs. Direct (Units and USD Million) (2021-2031) 36
Table 15 Global Industrial X-ray FPD Market by Form Factor: Wireless vs. Fixed (Units and USD Million) (2021-2031) 38
Table 16 Global Industrial X-ray FPD Market Volume (Units) by Sales Channel (2021-2031) 40
Table 17 Global Industrial X-ray FPD Market Size (USD Million) by Sales Channel (2021-2031) 41
Table 18 Global Industrial X-ray FPD Market Volume (Units) by Application (2021-2031) 43
Table 19 Global Industrial X-ray FPD Market Size (USD Million) by Application (2021-2031) 44
Table 20 Power Battery Application Market Volume and Revenue by Region (2021-2031) 45
Table 21 Semiconductor & Electronics Application Market Volume and Revenue by Region (2021-2031) 47
Table 22 Automotive Manufacturing Application Market Volume and Revenue by Region (2021-2031) 49
Table 23 Energy Sector Application Market Volume and Revenue by Region (2021-2031) 51
Table 24 Aerospace & Defense Application Market Volume and Revenue by Region (2021-2031) 53
Table 25 Industrial Security Application Market Volume and Revenue by Region (2021-2031) 55
Table 26 Other Industrial Applications Market Volume and Revenue by Region (2021-2031) 56
Table 27 Global Industrial X-ray Flat Panel Detector Market Volume (Units) by Region (2021-2031) 57
Table 28 Global Industrial X-ray Flat Panel Detector Market Size (USD Million) by Region (2021-2031) 58
Table 29 North America Industrial X-ray FPD Market by Country (Units and USD Million) (2021-2031) 59
Table 30 Europe Industrial X-ray FPD Market by Country (Units and USD Million) (2021-2031) 61
Table 31 Asia-Pacific Industrial X-ray FPD Market by Country (Units and USD Million) (2021-2031) 67
Table 32 Rest of the World Industrial X-ray FPD Market by Sub-Region (Units and USD Million) (2021-2031) 71
Table 33 Global Industrial X-ray Flat Panel Detector Vendor Revenue Share (2021-2026) 72
Table 34 Varex Imaging Corporation Industrial X-ray Flat Panel Detector Sales, Price, Cost and Gross Profit Margin (2021-2026) 76
Table 35 iRay Technology Industrial X-ray Flat Panel Detector Sales, Price, Cost and Gross Profit Margin (2021-2026) 79
Table 36 Jiangsu CareRay Medical Systems Co. Ltd. Industrial X-ray Flat Panel Detector Sales, Price, Cost and Gross Profit Margin (2021-2026) 82
Table 37 Detection Technology Plc Industrial X-ray Flat Panel Detector Sales, Price, Cost and Gross Profit Margin (2021-2026) 85
Table 38 Hamamatsu Photonics Industrial X-ray Flat Panel Detector Sales, Price, Cost and Gross Profit Margin (2021-2026) 88
Table 39 Teledyne DALSA Industrial X-ray Flat Panel Detector Sales, Price, Cost and Gross Profit Margin (2021-2026) 91
Table 40 Fujifilm Industrial X-ray Flat Panel Detector Sales, Price, Cost and Gross Profit Margin (2021-2026) 94
Table 41 Vieworks Industrial X-ray Flat Panel Detector Sales, Price, Cost and Gross Profit Margin (2021-2026) 97
Table 42 DRTECH Industrial X-ray Flat Panel Detector Sales, Price, Cost and Gross Profit Margin (2021-2026) 100
Table 43 Rayence Industrial X-ray Flat Panel Detector Sales, Price, Cost and Gross Profit Margin (2021-2026) 103
Figure 1 Research Process Flow and Triangulation Architecture 3
Figure 2 Global Industrial X-ray Flat Panel Detector Market Volume (Units) Forecast (2021-2031) 8
Figure 3 Global Industrial X-ray Flat Panel Detector Market Value (USD Million) Forecast (2021-2031) 9
Figure 4 End-to-End Value Chain Map of Industrial Flat Panel Detectors 11
Figure 5 Upstream Scintillator and TFT/CMOS Sensor Sourcing Share (2026) 14
Figure 6 Geographic Mapping of Global Primary Manufacturing Facilities 18
Figure 7 Global Industrial X-ray FPD Market Share by Substrate Technology (2021 vs. 2026 vs. 2031) 24
Figure 8 Cost vs. Resolution Performance Curve across a-Si, IGZO, and CMOS Technologies 30
Figure 9 Global Industrial X-ray FPD Market Share by Operating Mode (2021-2031) 33
Figure 10 Global Industrial X-ray FPD Market Share by Conversion Mechanism (2021-2031) 35
Figure 11 Global Industrial X-ray FPD Market Share by Form Factor (2021-2031) 37
Figure 12 Global Industrial X-ray FPD Market Share by Sales Channel (2026) 39
Figure 13 OEM vs. Aftermarket Growth Rate Comparison (2021-2031) 42
Figure 14 Industrial X-ray FPD Market Share by Application Segment (2026) 43
Figure 15 Power Battery vs. Semiconductor Inspection Market Trajectory Comparison (2021-2031) 48
Figure 16 Regional Consumption Share of Industrial X-ray Flat Panel Detectors (2026) 57
Figure 17 United States Industrial X-ray FPD Consumption vs. Production Dynamics (2021-2031) 58
Figure 18 Germany NDT Detector Demand Breakdown by Downstream Sector (2026) 61
Figure 19 China In-line Automated X-ray Inspection System Integration Demand (2021-2031) 67
Figure 20 Global Market Concentration: CR3, CR5, and Herfindahl-Hirschman Index (2021-2026) 73
Figure 21 Varex Imaging Corporation Industrial X-ray Flat Panel Detector Market Share (2021-2026) 77
Figure 22 iRay Technology Industrial X-ray Flat Panel Detector Market Share (2021-2026) 80
Figure 23 Jiangsu CareRay Medical Systems Co. Ltd. Industrial X-ray Flat Panel Detector Market Share (2021-2026) 83
Figure 24 Detection Technology Plc Industrial X-ray Flat Panel Detector Market Share (2021-2026) 86
Figure 25 Hamamatsu Photonics Industrial X-ray Flat Panel Detector Market Share (2021-2026) 89
Figure 26 Teledyne DALSA Industrial X-ray Flat Panel Detector Market Share (2021-2026) 92
Figure 27 Fujifilm Industrial X-ray Flat Panel Detector Market Share (2021-2026) 95
Figure 28 Vieworks Industrial X-ray Flat Panel Detector Market Share (2021-2026) 98
Figure 29 DRTECH Industrial X-ray Flat Panel Detector Market Share (2021-2026) 101
Figure 30 Rayence Industrial X-ray Flat Panel Detector Market Share (2021-2026) 104
Research Methodology
- Market Estimated Methodology:
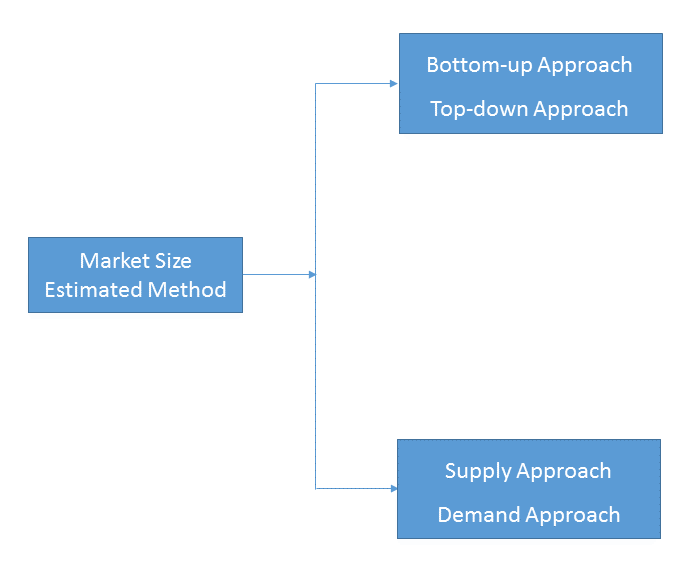
Bottom-up & top-down approach, supply & demand approach are the most important method which is used by HDIN Research to estimate the market size.
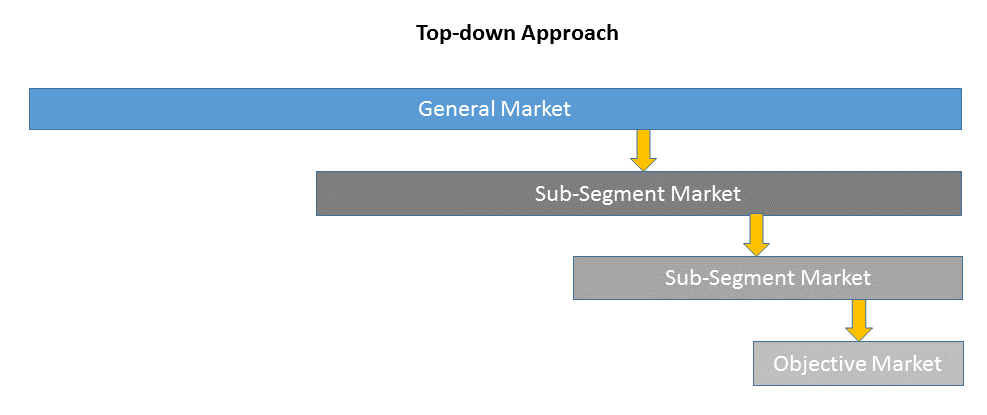
1)Top-down & Bottom-up Approach
Top-down approach uses a general market size figure and determines the percentage that the objective market represents.
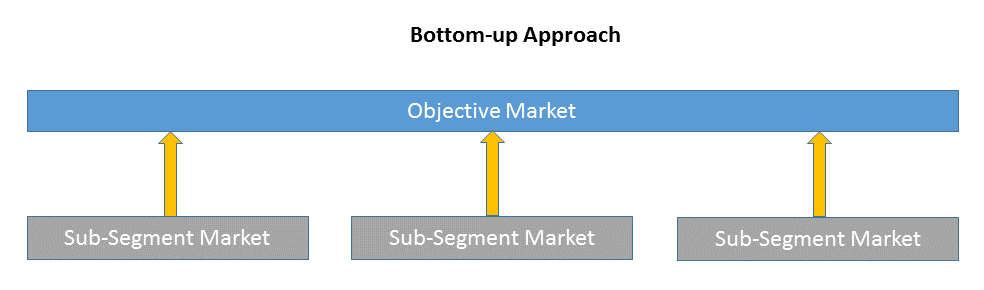
Bottom-up approach size the objective market by collecting the sub-segment information.
2)Supply & Demand Approach
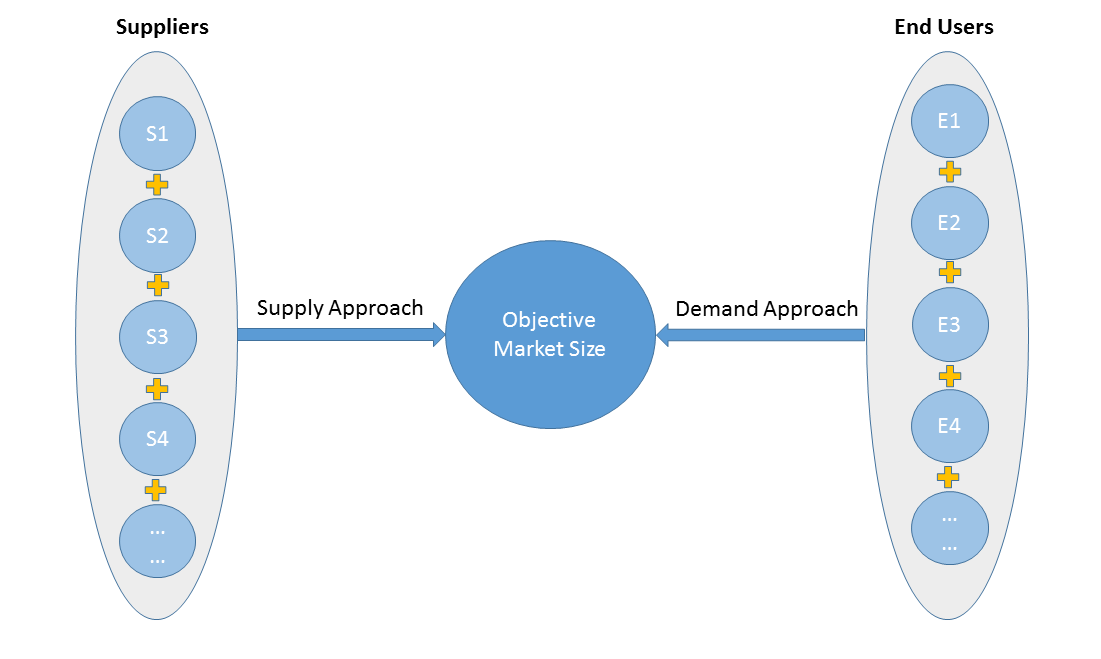
Supply approach is based on assessments of the size of each competitor supplying the objective market.
Demand approach combine end-user data within a market to estimate the objective market size. It is sometimes referred to as bottom-up approach.
- Forecasting Methodology
- Numerous factors impacting the market trend are considered for forecast model:
- New technology and application in the future;
- New project planned/under contraction;
- Global and regional underlying economic growth;
- Threatens of substitute products;
- Industry expert opinion;
- Policy and Society implication.
- Analysis Tools
1)PEST Analysis
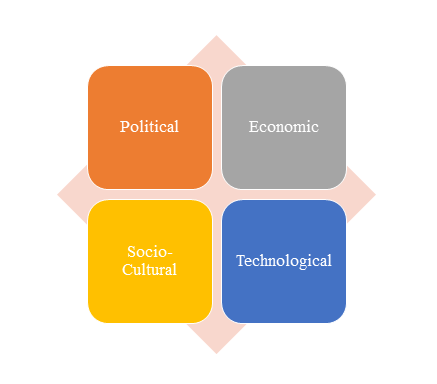
PEST Analysis is a simple and widely used tool that helps our client analyze the Political, Economic, Socio-Cultural, and Technological changes in their business environment.
- Benefits of a PEST analysis:
- It helps you to spot business opportunities, and it gives you advanced warning of significant threats.
- It reveals the direction of change within your business environment. This helps you shape what you’re doing, so that you work with change, rather than against it.
- It helps you avoid starting projects that are likely to fail, for reasons beyond your control.
- It can help you break free of unconscious assumptions when you enter a new country, region, or market; because it helps you develop an objective view of this new environment.
2)Porter’s Five Force Model Analysis
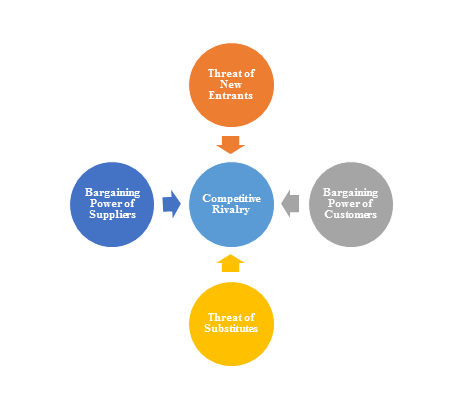
The Porter’s Five Force Model is a tool that can be used to analyze the opportunities and overall competitive advantage. The five forces that can assist in determining the competitive intensity and potential attractiveness within a specific area.
- Threat of New Entrants: Profitable industries that yield high returns will attract new firms.
- Threat of Substitutes: A substitute product uses a different technology to try to solve the same economic need.
- Bargaining Power of Customers: the ability of customers to put the firm under pressure, which also affects the customer's sensitivity to price changes.
- Bargaining Power of Suppliers: Suppliers of raw materials, components, labor, and services (such as expertise) to the firm can be a source of power over the firm when there are few substitutes.
- Competitive Rivalry: For most industries the intensity of competitive rivalry is the major determinant of the competitiveness of the industry.
3)Value Chain Analysis
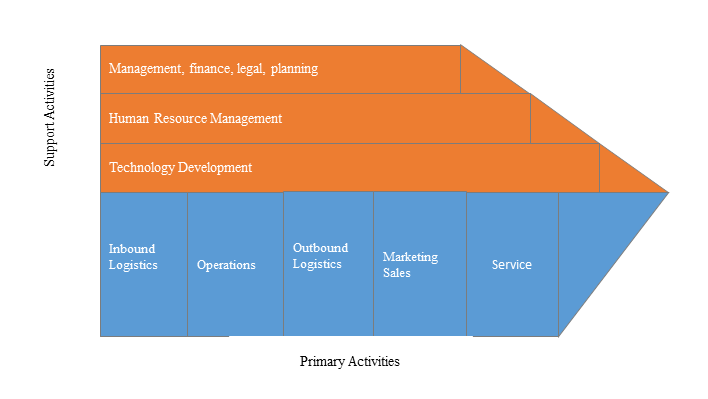
Value chain analysis is a tool to identify activities, within and around the firm and relating these activities to an assessment of competitive strength. Value chain can be analyzed by primary activities and supportive activities. Primary activities include: inbound logistics, operations, outbound logistics, marketing & sales, service. Support activities include: technology development, human resource management, management, finance, legal, planning.
4)SWOT Analysis
SWOT analysis is a tool used to evaluate a company's competitive position by identifying its strengths, weaknesses, opportunities and threats. The strengths and weakness is the inner factor; the opportunities and threats are the external factor. By analyzing the inner and external factors, the analysis can provide the detail information of the position of a player and the characteristics of the industry.
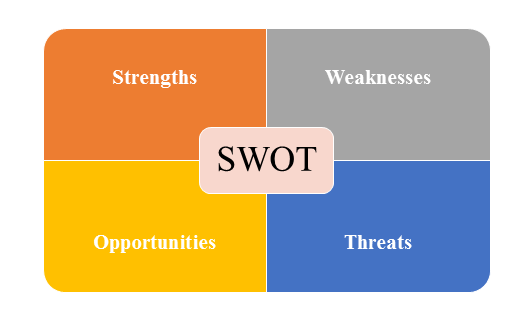
- Strengths describe what the player excels at and separates it from the competition
- Weaknesses stop the player from performing at its optimum level.
- Opportunities refer to favorable external factors that the player can use to give it a competitive advantage.
- Threats refer to factors that have the potential to harm the player.
- Data Sources
| Primary Sources | Secondary Sources |
|---|---|
| Face to face/Phone Interviews with market participants, such as: Manufactures; Distributors; End-users; Experts. Online Survey |
Government/International Organization Data: Annual Report/Presentation/Fact Book Internet Source Information Industry Association Data Free/Purchased Database Market Research Report Book/Journal/News |