Medical X-ray Flat Panel Detector Market Report 2026-2031
- Single User License (1 Users) $ 3,500
- Team License (2~5 Users) $ 4,500
- Corporate License (>5 Users) $ 5,500
The global Medical X-ray Flat Panel Detector (FPD) market size will reach to 1.5 billion USD - 2.5 billion USD in 2026, and the market is projected to expand at a compound annual growth rate (CAGR) between 2.8% and 4.8% through 2031. This trend reflects a structural migration away from commoditized static general radiography toward high-speed dynamic interventional imaging, glass-free flexible substrate architectures, and advanced semiconductor channel materials.
As the digital successor to analog film and computed radiography (CR) cassettes, FPDs constitute the critical optoelectronic subsystem within modern diagnostic X-ray apparatus. The hardware stack couples with the upstream X-ray tube and high-voltage generator to convert transmitted photon distributions into spatial diagnostic data. While standard amorphous silicon (a-Si) detectors for static chest and skeletal imaging experience persistent average selling price (ASP) compression, capital expenditure is flowing toward Indium Gallium Zinc Oxide (IGZO) and Complementary Metal-Oxide-Semiconductor (CMOS) matrices. These platforms support real-time fluoroscopy, surgical mobile C-arms, Cone-Beam Computed Tomography (CBCT), and image-guided radiotherapy (IGRT). Concurrently, supply chain realignment, tightening regulatory standards across key jurisdictions, and macroeconomic healthcare cost-containment measures are redefining operating margins and OEM procurement strategies worldwide.
INDUSTRY VALUE CHAIN ARCHITECTURE AND BOTTLENECK RESILIENCE
The production architecture of medical X-ray FPDs relies on a deeply specialized, multi-tiered optoelectronic and semiconductor supply ecosystem. Value migration across this chain is governed by technological moats in raw materials synthesis, precision photolithography, vacuum deposition, and integrated electronic packaging.
1. Upstream Value Chain: Raw Materials and Core Subcomponents
- Scintillator and Photoconductor Precursors: Indirect conversion detectors require ultra-pure chemical feedstocks, primarily Cesium Iodide doped with Thallium (CsI:Tl) and Gadolinium Oxysulfide (GOS / Gd2O2S:Tb). The production of optical-grade CsI involves complex crystal growth technologies to achieve columnar microstructures that channel visible photons through total internal reflection. For direct conversion sensors, high-purity Amorphous Selenium (a-Se) and Cadmium Zinc Telluride (CZT) single crystals form the foundational photoconductive layers.
- Semiconductor Substrates and Foundry Access: Amorphous silicon and IGZO thin-film transistor photodiode (TFT-PD) arrays are fabricated on large glass or flexible polyimide substrates. Because establishing dedicated thin-film transistor foundries requires multibillion-dollar capital allocations, merchant detector manufacturers partner with Tier-1 display panel foundries, such as Innolux, BOE, and Sharp. These fabrication lines utilize multi-mask photolithography processes designed to suppress dark-current leakage down to 10^-14 A while preserving low ON-state line resistance across active areas up to 43x43 cm.
- CMOS Sensor Foundries and Specialized Silicon: High-performance CMOS flat panels bypass thin-film display processing in favor of standard crystalline silicon wafer lines, predominantly operated by pure-play silicon foundries such as TSMC. Because wafer diameters are constrained to 200 mm or 300 mm, fabricating large-area medical panels requires specialized 3-side edge photolithographic stitching techniques. Upstream analog front-end (AFE) components, Gate Driver ICs, and multi-channel Readout ICs (ROICs) with native 16-bit analog-to-digital conversion (ADC) represent high-barrier subcomponents sourced from specialized semiconductor design houses.
2. Midstream Value Chain: FPD Module Fabrication and Packaging
- Vacuum Deposition and Scintillator Growth: The direct thermal evaporation of columnar CsI onto TFT or CMOS arrays represents a core manufacturing bottleneck. Operating inside high-vacuum thermal chambers, precisely controlled vapor deposition must yield uniform, needle-like structures (typically 5 to 10 micrometers in diameter and 400 to 600 micrometers in depth) across large surfaces without thermal damage to underlying pixel circuitry. Alternatively, GOS phosphor screens are laminated via optical clear adhesives (OCA), trading lower detective quantum efficiency for lower fabrication expense.
- Optoelectronic Integration and Interconnects: Pixel arrays are bonded to peripheral readout electronics using Chip-on-Flex (COF) and automated Tape Automated Bonding (TAB) or Surface Mount Technology (SMT). Internal architectures incorporate Field Programmable Gate Arrays (FPGAs) or Application-Specific Integrated Circuits (ASICs) for real-time defect correction, gain/offset calibration, and automated exposure detection (AED) sensor triggering.
- Enclosure Engineering: Packaging requires carbon-fiber composite or magnesium alloy chassis to deliver structural rigidity, drop protection, electromagnetic shielding, and liquid ingress sealing (IP66/IP67) while minimizing X-ray attenuation before photons reach the active area.
3. Downstream Value Chain: System Integration and Healthcare Providers
- OEM System Integrators: Multinational medical technology corporations, including GE HealthCare, Siemens Healthineers, Philips Healthcare, Canon Medical Systems, and United Imaging, procure detector modules for integration with mechanical gantries, C-arms, X-ray generators, and Picture Archiving and Communication Systems (PACS).
- End-User Facilities: Final deployment spans public and private hospital radiology departments, outpatient imaging networks, ambulatory surgical centers, specialized dental and oncology clinics, and veterinary diagnostic facilities.
DETAILED SEGMENTATION DYNAMICS
1. By Semiconductor Substrate and Sensor Technology
- Amorphous Silicon (a-Si) FPD: Serving as the established operational standard in medical imaging, a-Si arrays are manufactured by depositing thin-film transistors and p-i-n photodiodes on rigid glass sheets. The technology benefits from highly amortized fabrication infrastructure, reliable panel yields in expansive 43x43 cm formats, and mechanical stability. However, the fundamental physical constraints of amorphous silicon, specifically low electron carrier mobility (typically under 1 cm2/V-s) and parasitic capacitance, produce elevated readout noise and restricted frame rates. Consequently, a-Si is largely confined to static radiographic workflows and lower-speed dynamic examinations.
- Indium Gallium Zinc Oxide (IGZO) FPD: IGZO platforms utilize a metal-oxide semiconductor channel that delivers electron mobility roughly 20 to 30 times greater than traditional a-Si, alongside extremely low OFF-state leakage currents. These physical properties enable reduced pixel pitches (sub-100 micrometers), improved signal-to-noise ratios, and frame rates exceeding 30 to 60 frames per second (FPS) at full resolution. IGZO panels maintain the large-area glass processing benefits of thin-film lines while competing directly with CMOS performance in mid-tier dynamic surgical C-arms, dental CBCT, and gastrointestinal fluoroscopy at lower production costs.
- Complementary Metal-Oxide-Semiconductor (CMOS) FPD: Fabricated on crystalline silicon wafers, CMOS architectures incorporate active pixel amplifiers directly within each pixel cell. This architecture minimizes electronic readout noise, enables sub-50 micrometer pixel pitches, and delivers exceptional spatial resolution paired with high frame rates (up to 300 FPS in specialized readouts). CMOS dominates high-precision, low-dose clinical applications, including intraoral dental imaging, high-end surgical C-arms, and Full-Field Digital Mammography (FFDM). Its market expansion across large active fields remains tempered by the photolithographic stitching yields required to tile smaller wafer segments.
- Flexible Substrates FPD: This engineering approach substitutes conventional, brittle glass substrates with ultra-thin, flexible polyimide or specialized plastic substrates. Direct deposition or evaporation of CsI scintillators onto flexible TFT-PD arrays produces detectors with enhanced mechanical shock tolerance, surviving standard clinical drops without sensor fracture. Flexible substrates reduce total cassette weight below 2.0 kilograms, optimize cassette ergonomics for mobile trauma and bedside radiography, and facilitate narrower border designs that maximize active imaging areas near patient anatomy.
2. By Operating Mode
- Static Flat Panel Detector: Optimized for single-exposure clinical examinations where target anatomy remains motionless, including routine posteroanterior chest, abdominal, and extremity skeletal examinations. Technological evolution focuses on Detective Quantum Efficiency (DQE) optimization under minimal radiation doses, extended battery autonomy exceeding 15 hours, advanced onboard Automatic Exposure Detection (AED), and pixel pitch migration toward 85 to 100 micrometers.
- Dynamic Flat Panel Detector: Engineered for real-time fluoroscopic sequences, dynamic interventional guidance, and tomographic volumetric reconstructions. Operating at frame rates from 15 FPS to over 60 FPS, dynamic detectors demand fast scintillator decay kinetics to eliminate image ghosting, low-lag readout circuitry, integrated 16-bit ADCs, high-throughput data transfer interfaces (such as 5GigE, 10GbE, or optical links), and radiation-hardened pixel architectures capable of absorbing cumulative clinical exposures exceeding 10,000 Gray without baseline drift.
3. By Conversion Mechanism
- Indirect Conversion FPD: Operates via a two-stage thermodynamic and optoelectronic sequence. Incident X-ray photons interact with a scintillator layer (CsI:Tl or GOS), generating visible light photons that propagate downward into an underlying photodiode matrix (a-Si, IGZO, or CMOS). Columnar CsI configurations function as microscopic optical light guides, restricting lateral light diffusion and yielding superior spatial resolution and DQE relative to turbid GOS phosphor layers. Indirect conversion represents the substantial majority of clinical installations due to balanced manufacturing economics and balanced sensitivity.
- Direct Conversion FPD: Bypasses the intermediate visible-light emission phase by employing an upper photoconductive layer, most commonly amorphous Selenium (a-Se) or Cadmium Zinc Telluride (CZT). Incident X-ray photons directly generate electron-hole pairs within the bulk material, which are swept vertically toward pixel collection electrodes under a strong external electric field. By eliminating internal optical scatter, direct conversion achieves theoretical maximum Modulation Transfer Function (MTF), making it the gold standard in digital breast tomosynthesis and emerging clinical photon-counting modalities.
4. By Form Factor and Integration
- Wireless FPD: Self-contained, portable digital cassettes conforming to standardized ISO 4090 dimensions (including 14x17 inch, 17x17 inch, and 10x12 inch). Equipped with integrated lithium-ion or lithium-titanate battery systems, internal image caching memory, multi-band Wi-Fi connectivity (802.11ac or Wi-Fi 6), and carbon-fiber enclosures. These systems serve mobile digital radiography carts, intensive care units, emergency field kits, and retrofit analog X-ray conversions.
- Fixed FPD: Hardwired detector modules permanently integrated inside radiographic bucky tables, vertical chest stands, fixed mammography gantries, or robotic angiography positioners. Connected via industrial gigabit Ethernet cabling and powered continuously via dedicated power lines or Power-over-Ethernet (PoE), fixed systems ensure deterministic synchronization handshakes with high-power X-ray generators and provide unconstrained bandwidth for real-time image data streams.
5. By Sales Channel
- OEM (Original Equipment Manufacturer) Channel: Accounts for approximately 70% to 80% of aggregate global revenue. Merchant detector manufacturers supply branded or unbranded sub-assemblies and software development kits (SDKs) directly to primary imaging system integrators. This channel features high structural friction and long design-in lifecycles spanning 12 to 36 months. Because the detector is bound to the finished equipment regulatory filings (such as FDA 510(k) or CE Mark certifications), Tier-1 OEMs rarely switch component suppliers mid-lifecycle, generating high customer retention for successful vendors.
- Aftermarket and Replacement Channel: Comprises direct and indirect distribution of standalone FPD cassettes, digital conversion packages, and replacement panels sold to hospitals, imaging clinics, Independent Service Organizations (ISOs), and equipment distributors. This channel serves two operational demands: upgrading legacy analog film or CR units to direct digital radiography without replacing costly generators or structural gantries, and replacing damaged or mechanically degraded detectors across an aging installed base.
6. By Clinical Downstream Application
- General Radiography (DR): Represents the largest operational deployment volume. Focuses on high-throughput chest, orthopedic, and abdominal imaging within fixed multi-column installations, ceiling-suspended suites, and mobile bedside DR units. Current clinical requirements center on dose minimization, lightweight portable handling, and embedded artificial intelligence algorithms for automated image quality optimization.
- Mammography (FFDM and DBT): Dedicated high-resolution oncology imaging requiring fine pixel pitches (50 to 85 micrometers), wide dynamic range, and narrow chest-wall edge margins (under 1.85 mm) to maximize visualization of posterior glandular structures. The market is shifting from standard 2D mammography toward 3D Digital Breast Tomosynthesis (DBT), placing stringent demands on fast dynamic readouts and low-lag direct a-Se or high-density CMOS panels.
- Dental Imaging: Spans intraoral sensors (small-format CMOS modules), extraoral panoramic and cephalometric line-scan detectors, and specialized 3D dental Cone-Beam CT (CBCT) systems. The market requires high spatial resolution (down to 20 micrometers for intraoral diagnostics) and cost-effective, high-frame-rate IGZO or CMOS sensors for 3D volumetric maxillofacial reconstructions.
- Surgical and Interventional Imaging: Includes mobile surgical C-arms, fixed cardiovascular Digital Subtraction Angiography (DSA) suites, and universal gastrointestinal fluoroscopy (DRF) rooms. This segment is undergoing the structural obsolescence of vacuum-based Image Intensifiers (I.I.), replacing them with dynamic IGZO and CMOS flat panels that eliminate geometric distortion and expand the diagnostic field of view.
- Radiotherapy and Oncology (IGRT): Specialized dynamic detectors mounted on Medical Linear Accelerators (Linacs) and particle therapy systems. These detectors perform kilo-volt (kV) and mega-volt (MV) Image-Guided Radiotherapy, requiring radiation-hardened electronics capable of enduring continuous high-energy therapeutic radiation while verifying anatomical targeting in real time.
- Veterinary Diagnostic Imaging: Dedicated imaging systems for companion animal clinics, mixed practices, and equine ambulatory medicine. Growth is propelled by rising veterinary healthcare spending, clinical workflow modernization, and demand for rugged, high-DQE wireless cassettes resistant to severe mechanical drops and fluid contamination.
REGIONAL MARKET DYNAMICS AND POLICY HEADWINDS
1. North America
North America represents the highest-value regional market for medical FPDs, driven by mature healthcare infrastructure, accelerated replacement cycles for aging DR systems, widespread clinical integration of 3D breast tomosynthesis, and expanding surgical procedural volumes in Ambulatory Surgical Centers (ASCs).
Regulatory and Trade Landscape: Medical devices face rigorous regulatory oversight enforced by the U.S. FDA under 510(k) premarket notification frameworks. The harmonization of the legacy Quality System Regulation (QSR) into the updated Quality Management System Regulation (QMSR)—aligning U.S. expectations with ISO 13485:2016 standards—requires enhanced design traceability, risk management controls, and post-market surveillance from both domestic and foreign component suppliers.
Hospital capital purchasing is heavily modulated by reimbursement policy updates from the Centers for Medicare and Medicaid Services (CMS). Recent legislative shifts, including fiscal revisions impacting broader Medicare and Medicaid budgetary distributions, have caused hospital networks to scrutinize capital expenditure returns. This has amplified demand for cost-effective retrofit kits and durable multi-vendor replacement detectors. Concurrently, supply chain risks remain elevated due to bilateral U.S. tariff structures (such as Section 301 duties) and trade investigations regarding imported medical electronics, compelling global detector manufacturers to establish local North American final-assembly and servicing centers.
2. Asia-Pacific (APAC)
Asia-Pacific forms the fastest-growing regional market globally. Growth is underpinned by public healthcare modernization programs, an ongoing transition from analog film/CR cassettes to digital radiography across secondary and tertiary medical centers, and expanding domestic manufacturing ecosystems.
- China: The market environment is shaped by centralized policy initiatives and aggressive domestic supply-chain localization. Under national economic planning directives, public hospital equipment renewal initiatives have released substantial capital for diagnostic imaging upgrades. However, the broad implementation of Volume-Based Procurement (VBP) across regional hospital alliances has created pronounced downward pricing pressure on medical capital equipment, compressing component-level profit margins for standard static detectors. Furthermore, government procurement guidelines increasingly mandate specified domestic content quotas, favoring localized manufacturers such as iRay Technology and CareRay, while administrative trade agencies scrutinize imported imaging components.
- India: Rapidly emerging as a global high-growth manufacturing and consumption node. Driven by national programs aimed at expanding Tier-2 and Tier-3 secondary healthcare access, global merchant suppliers are establishing greenfield manufacturing and customer support facilities in India to support both local medical device integrators and regional export corridors.
- Japan and South Korea: Mature, highly technologically advanced markets primarily driven by replacement requirements and demand for high-end dynamic CMOS and IGZO interventional equipment. South Korea serves as a major global design and manufacturing hub for independent merchant detector specialists, exporting the majority of its domestic production to international OEMs and aftermarket channels. In Taiwan, China, advanced foundry capacity continues to underpin global TFT-PD and flat-panel display substrates.
3. Europe
Europe constitutes the second-largest regional market by absolute revenue, with mature healthcare delivery systems in Germany, France, the United Kingdom, and the Nordic nations representing steady replacement demand. Modernization programs across Eastern and Southern European hospital systems provide targeted expansion opportunities.
Regulatory and Sustainability Drivers: Market access is strictly governed by the European Union Medical Device Regulation (EU MDR 2017/745). The heightened demand for continuous clinical data, expanded technical documentation, and rigorous recertification protocols has increased compliance overhead and extended time-to-market for novel detector technologies. Additionally, European directives surrounding environmental sustainability, including the Restriction of Hazardous Substances (RoHS), Waste Electrical and Electronic Equipment (WEEE), and Eco-design standards, are requiring manufacturers to eliminate hazardous materials (such as specific lead alloys and heavy-metal compounds) from detector assemblies while engineering modules for end-of-life disassembly and circular recycling.
4. Latin America
Latin American demand is concentrated in Brazil, Mexico, Colombia, and Argentina. Regional dynamics are shaped by private healthcare expansion alongside modernization initiatives across underfunded public municipal clinics.
Due to constrained healthcare capital budgets, the commercial market relies heavily on the aftermarket and retrofit channel. Hospitals and imaging centers frequently opt to modernize functional analog radiographic rooms by purchasing universal wireless flat panel cassettes and digital image processing workstations, bypassing the need to procure entirely new gantry-generator configurations. Merchant suppliers navigate volatile local currency exchange rates and import tariffs by partnering with regional distributors and local kit integrators.
5. Middle East and Africa (MEA)
The MEA region demonstrates marked internal divergence.
The Gulf Cooperation Council (GCC) economies (notably Saudi Arabia, the United Arab Emirates, and Qatar) invest heavily in advanced medical infrastructure, procuring top-tier digital radiography rooms, automated ceiling suspensions, and cutting-edge radiotherapy guidance systems. Conversely, broader African markets prioritize operational durability, dust ingress protection, resistance to power fluctuations, and extended battery autonomy in wireless portable detectors to support rural clinics, mobile screening vans, and field veterinary missions operating under challenging electrical grid conditions.
COMPETITIVE INTELLIGENCE AND CORPORATE DOSSIERS
1. Global Tier-1 Independent Merchant FPD Manufacturers
- Varex Imaging Corporation: Headquartered in the United States, Varex Imaging stands as the largest independent supplier of medical X-ray imaging components, maintaining broad engineering capabilities across a-Si, IGZO, and CMOS architectures.
- Trixell: Based in France, Trixell operates as an established joint venture between Thales, Philips, and Siemens Healthineers, focusing on the development and volume manufacturing of high-end medical digital X-ray detectors.
- iRay Technology (Shanghai) Limited: Headquartered in China, iRay Technology is a vertically integrated developer and volume manufacturer of digital X-ray detectors with operations spanning a-Si, IGZO, CMOS, and flexible polyimide substrate platforms.
2. Major Multimodal Diagnostic OEMs with Integrated / Retrofit FPD Lines
- Canon Medical Systems: Headquartered in Japan, Canon Medical Systems integrates its proprietary CXDI detector platforms within its full-room DR systems while competing broadly in the global retrofit cassette market.
- Fujifilm Healthcare: Headquartered in Japan, Fujifilm combines complete medical imaging system integration with a large external retrofit detector business centered on its FDR D-EVO platform.
- Konica Minolta: Headquartered in Japan, Konica Minolta manufactures the AeroDR family of wireless flat panel detectors, emphasizing structural durability and functional dynamic imaging.
- Agfa-Gevaert Group (Agfa Radiology Solutions): Headquartered in Belgium, Agfa delivers the Dura-line and DX-D detector families, supporting both native Agfa digital radiography suites and multi-vendor hospital retrofit modernizations.
3. South Korean Merchant FPD and Detection Technology Innovators
- Vieworks Co., Ltd.: Headquartered in South Korea, Vieworks provides advanced optoelectronic imaging solutions for medical diagnostic and industrial machine-vision markets.
- Rayence: Headquartered in South Korea, Rayence operates as a vertically integrated manufacturer capable of designing and fabricating both amorphous silicon TFT and CMOS sensor arrays in-house.
- DRTECH: Headquartered in South Korea, DRTECH specializes in indirect and direct-conversion flat panel detectors alongside image-enhancement algorithms.
4. CMOS and Precision Optical Sensing Specialists
- Teledyne DALSA: A subsidiary of Teledyne Technologies based in Canada, Teledyne DALSA designs and fabricates high-performance CMOS image sensors and flat panel detectors for clinical and scientific imaging.
- Hamamatsu Photonics: Headquartered in Japan, Hamamatsu Photonics is an optoelectronics manufacturer producing specialized medical flat panel sensors based on high-density CMOS arrays and optical fiber coupling.
- Detection Technology Plc (DT): Headquartered in Finland, Detection Technology provides X-ray detector solutions across medical, industrial, and security screening sectors.
5. Chinese and Regional FPD Developers
- Jiangsu CareRay Medical Systems Co. Ltd. (CareRay): Headquartered in China, CareRay focuses on the development and production of digital X-ray flat panel detectors, having pioneered direct-growth columnar CsI crystal technology on TFT substrates in the domestic Chinese market.
- InnoCare Optoelectronics Corp.: Headquartered in Taiwan, China, InnoCare was spun off from display manufacturer Innolux Corporation, utilizing large-scale TFT foundry infrastructure to produce medical flat panel detectors.
- Shenzhen SONTU Medical Imaging Equipment: Headquartered in China, SONTU designs and manufactures flat panel detectors both for internal integration across its digital radiography equipment lines and for external OEM partners.
- Shanghai PZMedical Technology Co. Ltd.: Headquartered in China, PZMedical develops cost-effective flat panel detectors and complete imaging chain subsystems designed for clinical radiography and analog-to-digital system retrofits.
1.1 Product Spectrum, Physical Architecture, and Detection Physics 1
1.2 Research Methodology, Analytical Hypotheses, and Data Triangulation 3
1.3 Primary Data Harvesting and Secondary Verification Framework 4
1.4 Standard Currency Conversion and Deflator Metrics (2021-2031) 5
1.5 Nomenclature, Technical Acronyms, and Definitions 6
Chapter 2 Global Medical X-ray Flat Panel Detector Market Trajectory and Macro Dynamics (2021-2031)
2.1 Global Medical X-ray Flat Panel Detector Market Valuation and Volumetric Output (2021-2031) 7
2.2 Historical Trajectory and Transition Dynamics (2021-2025) 9
2.3 Baseline Market Assessment and Capital Allocation Equilibrium (2026) 11
2.4 Multi-Scenario Growth Projections (2027-2031) 12
2.5 Average Selling Price (ASP) Elasticity and Cost Component Deconstruction 14
Chapter 3 Global Market Breakdown by Semiconductor Substrate and Sensor Architecture
3.1 Technology Taxonomy: Material Properties, Electron Mobility, and Fill Factors 15
3.2 Amorphous Silicon (a-Si) FPD Market Volume, Revenue, and Cost Realization (2021-2031) 17
3.3 Indium Gallium Zinc Oxide (IGZO) FPD Scalability, Yield, and Market Penetration (2021-2031) 19
3.4 Complementary Metal-Oxide-Semiconductor (CMOS) FPD High-Resolution Dynamics (2021-2031) 21
3.5 Flexible Substrates (Polyimide-Based) FPD Durability and Market Share (2021-2031) 23
Chapter 4 Global Market Segmentation by Functional Operation, Conversion Physics, and Form Factor
4.1 Operating Mode: Static vs. Dynamic Readout Architectures 24
4.1.1 Static Flat Panel Detectors: Radiographic Performance and Market Trajectory (2021-2031) 25
4.1.2 Dynamic Flat Panel Detectors: Fluoroscopic Frame Rate and Revenue Analysis (2021-2031) 27
4.2 Conversion Mechanism: Scintillator Coupling vs. Direct Photoconductor Systems 28
4.2.1 Indirect Conversion FPD (CsI:Tl and Gd2O2S:Tb Scintillators) (2021-2031) 29
4.2.2 Direct Conversion FPD (Amorphous Selenium / CdTe Sensors) (2021-2031) 31
4.3 Form Factor and Clinical Integration Dynamics 32
4.3.1 Wireless Medical FPDs: Battery Lifecycle, Weight Optimization, and Penetration (2021-2031) 33
4.3.2 Fixed Medical FPDs: Retrofit Integration and Gantry-Embedded Trajectory (2021-2031) 34
Chapter 5 Global Market Breakdown by Downstream Clinical Modality and Application
5.1 General Radiography (DR): Mobile and Stationary System Volumes (2021-2031) 35
5.2 Mammography: High Detective Quantum Efficiency (DQE) and Spatial Resolution Demand (2021-2031) 37
5.3 Dental Imaging: Cone Beam Computed Tomography (CBCT) and Panoramic Systems (2021-2031) 39
5.4 Surgical and Interventional Imaging: C-Arms and Cath-Lab Modernization (2021-2031) 41
5.5 Radiotherapy and Oncology: Image-Guided Radiation Therapy (IGRT) Verification (2021-2031) 43
5.6 Veterinary Diagnostic Imaging: Modular Adoption and Unit Economics (2021-2031) 44
Chapter 6 Global Market Breakdown by Sales Channel and Commercial Distribution Model
6.1 Original Equipment Manufacturer (OEM) Integration Ecosystem and Contract Structures (2021-2031) 45
6.2 Aftermarket, Retrofit Upgrades, and Fleet Replacement Cycles (2021-2031) 48
Chapter 7 Medical X-ray FPD Value Chain, Upstream Sourcing, and Fabrication Processes
7.1 Raw Material Upstream: High-Purity Scintillator Crystals, TFT Glass, and ROIC Wafers 51
7.2 Foundry Fabrication, Sensor Packaging, and Assembly Cleanroom Bottlenecks 53
7.3 Value Addition Margin Distribution: Component Suppliers to Medical Device Integrators 55
7.4 Supply Chain Vulnerability Mapping, Material Redundancies, and Buffer Strategies 57
Chapter 8 Cross-Border Trade Flows, Tariffs, and Regulatory Logistics Framework
8.1 Global Trade Corridor Mapping: Sensor Sub-Assemblies vs. Finished Diagnostic Panels 59
8.2 North American and European Import/Export Flow Volumes and Tariff Regimes 61
8.3 Asia-Pacific Sourcing Networks and Harmonized Tariff System (HTS) Friction Points 63
Chapter 9 Regional and National Market Performance (2021-2031)
9.1 North America Market Volume, Revenues, and Technological Modernization 65
9.1.1 United States: Clinical Replacement Velocity and High-End Dynamic Adoption 67
9.1.2 Canada: Public Healthcare Procurement Dynamics 69
9.2 Europe Manufacturing Clusters, Clinical Deployments, and CE-MDR Compliance 70
9.2.1 Germany: Precision Engineering Hub and Domestic Radiography Absorption 72
9.2.2 France: Interventional Imaging Center Modernization and OEM Sourcing 74
9.2.3 United Kingdom: NHS Equipment Renewal Programs and Diagnostic Hub Initiatives 75
9.2.4 Italy and Spain: Secondary Care Infrastructure Upgrades 76
9.3 Asia-Pacific Primary Manufacturing Hubs and High-Growth Health Systems 77
9.3.1 China: Domestic Substitution Mandates, Massive Output, and Hospital Upgrades 79
9.3.2 Japan: Advanced Sensor Innovation and Optical Scintillator Leadership 81
9.3.3 South Korea: Specialized Sensor Production, DR Export, and Dental CBCT Hub 83
9.3.4 Taiwan (China): Advanced Display Substrates and Foundry Capabilities 84
9.3.5 India: Healthcare Capitalization, Influx of Affordable DR, and Sourcing 85
9.4 Latin America: Brazil and Mexico Clinical Infrastructure Expansion 86
9.5 Middle East and Africa: Institutional Tendering and Specialized Clinic Modernization 87
Chapter 10 Competitive Benchmark and Corporate Intelligence Profiles
10.1 Varex Imaging Corporation 88
10.1.1 Corporate Profile, Asset Base, and Manufacturing Footprint 88
10.1.2 Medical X-ray FPD Product Portfolio and Architectural Strengths 88
10.1.3 Strategic SWOT Diagnostic 89
10.1.4 Operational Metrics: Volume, Price, Gross Profit, and Financial Footprint (2021-2026) 89
10.1.5 Commercial Strategy and OEM Partnership Pipeline 90
10.2 Trixell 91
10.2.1 Corporate Profile, Asset Base, and Manufacturing Footprint 91
10.2.2 Medical X-ray FPD Product Portfolio and Architectural Strengths 91
10.2.3 Strategic SWOT Diagnostic 92
10.2.4 Operational Metrics: Volume, Price, Gross Profit, and Financial Footprint (2021-2026) 92
10.2.5 Commercial Strategy and OEM Partnership Pipeline 93
10.3 Canon Medical Systems 94
10.3.1 Corporate Profile, Asset Base, and Manufacturing Footprint 94
10.3.2 Medical X-ray FPD Product Portfolio and Architectural Strengths 94
10.3.3 Strategic SWOT Diagnostic 95
10.3.4 Operational Metrics: Volume, Price, Gross Profit, and Financial Footprint (2021-2026) 95
10.3.5 Commercial Strategy and OEM Partnership Pipeline 96
10.4 Vieworks Co. Ltd. 97
10.4.1 Corporate Profile, Asset Base, and Manufacturing Footprint 97
10.4.2 Medical X-ray FPD Product Portfolio and Architectural Strengths 97
10.4.3 Strategic SWOT Diagnostic 98
10.4.4 Operational Metrics: Volume, Price, Gross Profit, and Financial Footprint (2021-2026) 98
10.4.5 Commercial Strategy and OEM Partnership Pipeline 99
10.5 iRay Technology (Shanghai) Limited 100
10.5.1 Corporate Profile, Asset Base, and Manufacturing Footprint 100
10.5.2 Medical X-ray FPD Product Portfolio and Architectural Strengths 100
10.5.3 Strategic SWOT Diagnostic 101
10.5.4 Operational Metrics: Volume, Price, Gross Profit, and Financial Footprint (2021-2026) 101
10.5.5 Commercial Strategy and OEM Partnership Pipeline 102
10.6 Jiangsu CareRay Medical Systems Co. Ltd. 103
10.6.1 Corporate Profile, Asset Base, and Manufacturing Footprint 103
10.6.2 Medical X-ray FPD Product Portfolio and Architectural Strengths 103
10.6.3 Strategic SWOT Diagnostic 104
10.6.4 Operational Metrics: Volume, Price, Gross Profit, and Financial Footprint (2021-2026) 104
10.6.5 Commercial Strategy and OEM Partnership Pipeline 105
10.7 Rayence 106
10.7.1 Corporate Profile, Asset Base, and Manufacturing Footprint 106
10.7.2 Medical X-ray FPD Product Portfolio and Architectural Strengths 106
10.7.3 Strategic SWOT Diagnostic 107
10.7.4 Operational Metrics: Volume, Price, Gross Profit, and Financial Footprint (2021-2026) 107
10.7.5 Commercial Strategy and OEM Partnership Pipeline 108
10.8 Detection Technology Plc 109
10.8.1 Corporate Profile, Asset Base, and Manufacturing Footprint 109
10.8.2 Medical X-ray FPD Product Portfolio and Architectural Strengths 109
10.8.3 Strategic SWOT Diagnostic 110
10.8.4 Operational Metrics: Volume, Price, Gross Profit, and Financial Footprint (2021-2026) 110
10.8.5 Commercial Strategy and OEM Partnership Pipeline 111
10.9 Hamamatsu Photonics 112
10.9.1 Corporate Profile, Asset Base, and Manufacturing Footprint 112
10.9.2 Medical X-ray FPD Product Portfolio and Architectural Strengths 112
10.9.3 Strategic SWOT Diagnostic 113
10.9.4 Operational Metrics: Volume, Price, Gross Profit, and Financial Footprint (2021-2026) 113
10.9.5 Commercial Strategy and OEM Partnership Pipeline 114
10.10 DRTECH 115
10.10.1 Corporate Profile, Asset Base, and Manufacturing Footprint 115
10.10.2 Medical X-ray FPD Product Portfolio and Architectural Strengths 115
10.10.3 Strategic SWOT Diagnostic 116
10.10.4 Operational Metrics: Volume, Price, Gross Profit, and Financial Footprint (2021-2026) 116
10.10.5 Commercial Strategy and OEM Partnership Pipeline 117
10.11 Fujifilm 118
10.11.1 Corporate Profile, Asset Base, and Manufacturing Footprint 118
10.11.2 Medical X-ray FPD Product Portfolio and Architectural Strengths 118
10.11.3 Strategic SWOT Diagnostic 119
10.11.4 Operational Metrics: Volume, Price, Gross Profit, and Financial Footprint (2021-2026) 119
10.11.5 Commercial Strategy and OEM Partnership Pipeline 120
10.12 Konica Minolta 121
10.12.1 Corporate Profile, Asset Base, and Manufacturing Footprint 121
10.12.2 Medical X-ray FPD Product Portfolio and Architectural Strengths 121
10.12.3 Strategic SWOT Diagnostic 122
10.12.4 Operational Metrics: Volume, Price, Gross Profit, and Financial Footprint (2021-2026) 122
10.12.5 Commercial Strategy and OEM Partnership Pipeline 123
10.13 Agfa-Gevaert Group 124
10.13.1 Corporate Profile, Asset Base, and Manufacturing Footprint 124
10.13.2 Medical X-ray FPD Product Portfolio and Architectural Strengths 124
10.13.3 Strategic SWOT Diagnostic 125
10.13.4 Operational Metrics: Volume, Price, Gross Profit, and Financial Footprint (2021-2026) 125
10.13.5 Commercial Strategy and OEM Partnership Pipeline 126
10.14 Teledyne DALSA 127
10.14.1 Corporate Profile, Asset Base, and Manufacturing Footprint 127
10.14.2 Medical X-ray FPD Product Portfolio and Architectural Strengths 127
10.14.3 Strategic SWOT Diagnostic 128
10.14.4 Operational Metrics: Volume, Price, Gross Profit, and Financial Footprint (2021-2026) 128
10.14.5 Commercial Strategy and OEM Partnership Pipeline 129
10.15 Shenzhen SONTU Medical Imaging Equipment 130
10.15.1 Corporate Profile, Asset Base, and Manufacturing Footprint 130
10.15.2 Medical X-ray FPD Product Portfolio and Architectural Strengths 130
10.15.3 Strategic SWOT Diagnostic 131
10.15.4 Operational Metrics: Volume, Price, Gross Profit, and Financial Footprint (2021-2026) 131
10.15.5 Commercial Strategy and OEM Partnership Pipeline 132
10.16 Shanghai PZMedical Technology Co. Ltd. 133
10.16.1 Corporate Profile, Asset Base, and Manufacturing Footprint 133
10.16.2 Medical X-ray FPD Product Portfolio and Architectural Strengths 133
10.16.3 Strategic SWOT Diagnostic 134
10.16.4 Operational Metrics: Volume, Price, Gross Profit, and Financial Footprint (2021-2026) 134
10.16.5 Commercial Strategy and OEM Partnership Pipeline 135
10.17 InnoCare Optoelectronics Corp. 136
10.17.1 Corporate Profile, Asset Base, and Manufacturing Footprint 136
10.17.2 Medical X-ray FPD Product Portfolio and Architectural Strengths 136
10.17.3 Strategic SWOT Diagnostic 137
10.17.4 Operational Metrics: Volume, Price, Gross Profit, and Financial Footprint (2021-2026) 137
10.17.5 Commercial Strategy and OEM Partnership Pipeline 138
Table 2 Medical X-ray Flat Panel Detector Bill of Materials (BOM) Cost Breakdown (2021-2026) 14
Table 3 Global Medical X-ray FPD Market Value by Substrate Technology (2021-2031) 16
Table 4 Global a-Si FPD Shipment Volumes and Market Revenues (2021-2031) 18
Table 5 Global IGZO FPD Shipment Volumes and Market Revenues (2021-2031) 20
Table 6 Global CMOS FPD Shipment Volumes and Market Revenues (2021-2031) 22
Table 7 Global Flexible Substrate FPD Shipment Volumes and Market Revenues (2021-2031) 24
Table 8 Global Medical X-ray FPD Market by Operating Mode (2021-2031) 25
Table 9 Global Static Medical X-ray FPD Revenue and Volume (2021-2031) 26
Table 10 Global Dynamic Medical X-ray FPD Revenue and Volume (2021-2031) 27
Table 11 Global Medical X-ray FPD Market by Conversion Mechanism (2021-2031) 29
Table 12 Global Indirect Conversion FPD Market Value and Shipments (2021-2031) 30
Table 13 Global Direct Conversion FPD Market Value and Shipments (2021-2031) 32
Table 14 Global Wireless vs. Fixed Medical X-ray FPD Revenue Breakdown (2021-2031) 33
Table 15 Global Medical X-ray FPD Market by Downstream Application (2021-2031) 36
Table 16 General Radiography Medical X-ray FPD Market Sizing (2021-2031) 37
Table 17 Mammography Dedicated FPD Market Value and Volume (2021-2031) 39
Table 18 Dental Imaging Dedicated FPD Market Sizing (2021-2031) 40
Table 19 Surgical and Interventional Imaging FPD Market Sizing (2021-2031) 42
Table 20 Radiotherapy and Oncology (IGRT) FPD Market Sizing (2021-2031) 43
Table 21 Veterinary Diagnostic Imaging FPD Market Sizing (2021-2031) 45
Table 22 Global Medical X-ray FPD Market by Sales Channel (2021-2031) 47
Table 23 Global OEM Sales Channel Volume and Realized Revenues (2021-2031) 48
Table 24 Global Aftermarket and Replacement Channel Metrics (2021-2031) 50
Table 25 Medical X-ray FPD Regional Market Value Breakdown (2021-2031) 66
Table 26 North America Medical X-ray FPD Market Value by Country (2021-2031) 67
Table 27 United States Medical X-ray FPD Market Metrics by Modality (2021-2031) 68
Table 28 Canada Medical X-ray FPD Market Metrics by Modality (2021-2031) 69
Table 29 Europe Medical X-ray FPD Market Value by Key Country (2021-2031) 71
Table 30 Germany Medical X-ray FPD Market Volume and Revenue (2021-2031) 73
Table 31 France Medical X-ray FPD Market Volume and Revenue (2021-2031) 74
Table 32 United Kingdom Medical X-ray FPD Market Volume and Revenue (2021-2031) 75
Table 33 Italy and Spain Medical X-ray FPD Combined Metrics (2021-2031) 76
Table 34 Asia-Pacific Medical X-ray FPD Market Value by Key Economy (2021-2031) 78
Table 35 China Medical X-ray FPD Production, Domestic Demand, and Net Trade (2021-2031) 80
Table 36 Japan Medical X-ray FPD Production, Demand, and Component Trade (2021-2031) 82
Table 37 South Korea Medical X-ray FPD Production and Market Absorption (2021-2031) 83
Table 38 Taiwan (China) Medical X-ray FPD Component Shipments and Revenue (2021-2031) 84
Table 39 India Medical X-ray FPD Import Value and Domestic Absorption (2021-2031) 85
Table 40 Latin America Medical X-ray FPD Market Value by Country (2021-2031) 86
Table 41 Middle East and Africa Medical X-ray FPD Market Metrics (2021-2031) 87
Table 42 Varex Imaging Corporation Medical X-ray Flat Panel Detector Sales, Price, Cost and Gross Profit Margin (2021-2026) 90
Table 43 Trixell Medical X-ray Flat Panel Detector Sales, Price, Cost and Gross Profit Margin (2021-2026) 93
Table 44 Canon Medical Systems Medical X-ray Flat Panel Detector Sales, Price, Cost and Gross Profit Margin (2021-2026) 96
Table 45 Vieworks Co. Ltd. Medical X-ray Flat Panel Detector Sales, Price, Cost and Gross Profit Margin (2021-2026) 99
Table 46 iRay Technology (Shanghai) Limited Medical X-ray Flat Panel Detector Sales, Price, Cost and Gross Profit Margin (2021-2026) 102
Table 47 Jiangsu CareRay Medical Systems Co. Ltd. Medical X-ray Flat Panel Detector Sales, Price, Cost and Gross Profit Margin (2021-2026) 105
Table 48 Rayence Medical X-ray Flat Panel Detector Sales, Price, Cost and Gross Profit Margin (2021-2026) 108
Table 49 Detection Technology Plc Medical X-ray Flat Panel Detector Sales, Price, Cost and Gross Profit Margin (2021-2026) 111
Table 50 Hamamatsu Photonics Medical X-ray Flat Panel Detector Sales, Price, Cost and Gross Profit Margin (2021-2026) 114
Table 51 DRTECH Medical X-ray Flat Panel Detector Sales, Price, Cost and Gross Profit Margin (2021-2026) 117
Table 52 Fujifilm Medical X-ray Flat Panel Detector Sales, Price, Cost and Gross Profit Margin (2021-2026) 120
Table 53 Konica Minolta Medical X-ray Flat Panel Detector Sales, Price, Cost and Gross Profit Margin (2021-2026) 123
Table 54 Agfa-Gevaert Group Medical X-ray Flat Panel Detector Sales, Price, Cost and Gross Profit Margin (2021-2026) 126
Table 55 Teledyne DALSA Medical X-ray Flat Panel Detector Sales, Price, Cost and Gross Profit Margin (2021-2026) 129
Table 56 Shenzhen SONTU Medical Imaging Equipment Medical X-ray Flat Panel Detector Sales, Price, Cost and Gross Profit Margin (2021-2026) 132
Table 57 Shanghai PZMedical Technology Co. Ltd. Medical X-ray Flat Panel Detector Sales, Price, Cost and Gross Profit Margin (2021-2026) 135
Table 58 InnoCare Optoelectronics Corp. Medical X-ray Flat Panel Detector Sales, Price, Cost and Gross Profit Margin (2021-2026) 138
Figure 1 Global Medical X-ray Flat Panel Detector Market Value Trajectory (2021-2031) 8
Figure 2 Medical X-ray Flat Panel Detector Price Erosion Curve (2021-2031) 14
Figure 3 Market Share Dynamics by Substrate Technology (2021 vs. 2026 vs. 2031) 16
Figure 4 a-Si vs. IGZO vs. CMOS Cost-Performance Frontier Analysis 23
Figure 5 Market Share Breakdown: Static vs. Dynamic Readout Panels (2021-2031) 25
Figure 6 Indirect vs. Direct Conversion Revenue Trajectory (2021-2031) 29
Figure 7 Wireless Form Factor Adoption Velocity in Hospital DR Systems (2021-2031) 34
Figure 8 Medical X-ray FPD Application Share Distribution (2026) 36
Figure 9 General Radiography vs. Specialized Modality Growth Vector Matrix 44
Figure 10 OEM vs. Aftermarket Sales Channel Revenue Share (2021-2031) 47
Figure 11 Medical X-ray FPD End-to-End Value Chain Gross Margin Accretion 56
Figure 12 Key Global Trade Flow Routes for FPD Modules and Scintillator Assemblies 60
Figure 13 Geographic Revenue Distribution for Medical X-ray FPDs (2026) 66
Figure 14 United States Medical X-ray FPD Modality Breakdown (2021-2031) 68
Figure 15 Europe FPD Revenue Breakdown by Tier-1 Economies (2021-2031) 71
Figure 16 China Domestic FPD Production vs. Export Volume Ratio (2021-2031) 80
Figure 17 Varex Imaging Corporation Medical X-ray Flat Panel Detector Market Share (2021-2026) 90
Figure 18 Trixell Medical X-ray Flat Panel Detector Market Share (2021-2026) 93
Figure 19 Canon Medical Systems Medical X-ray Flat Panel Detector Market Share (2021-2026) 96
Figure 20 Vieworks Co. Ltd. Medical X-ray Flat Panel Detector Market Share (2021-2026) 99
Figure 21 iRay Technology (Shanghai) Limited Medical X-ray Flat Panel Detector Market Share (2021-2026) 102
Figure 22 Jiangsu CareRay Medical Systems Co. Ltd. Medical X-ray Flat Panel Detector Market Share (2021-2026) 105
Figure 23 Rayence Medical X-ray Flat Panel Detector Market Share (2021-2026) 108
Figure 24 Detection Technology Plc Medical X-ray Flat Panel Detector Market Share (2021-2026) 111
Figure 25 Hamamatsu Photonics Medical X-ray Flat Panel Detector Market Share (2021-2026) 114
Figure 26 DRTECH Medical X-ray Flat Panel Detector Market Share (2021-2026) 117
Figure 27 Fujifilm Medical X-ray Flat Panel Detector Market Share (2021-2026) 120
Figure 28 Konica Minolta Medical X-ray Flat Panel Detector Market Share (2021-2026) 123
Figure 29 Agfa-Gevaert Group Medical X-ray Flat Panel Detector Market Share (2021-2026) 126
Figure 30 Teledyne DALSA Medical X-ray Flat Panel Detector Market Share (2021-2026) 129
Figure 31 Shenzhen SONTU Medical Imaging Equipment Medical X-ray Flat Panel Detector Market Share (2021-2026) 132
Figure 32 Shanghai PZMedical Technology Co. Ltd. Medical X-ray Flat Panel Detector Market Share (2021-2026) 135
Figure 33 InnoCare Optoelectronics Corp. Medical X-ray Flat Panel Detector Market Share (2021-2026) 138
Figure 34 Global Medical X-ray FPD Patent Application Velocity by Assignee Country (2021-2026) 139
Research Methodology
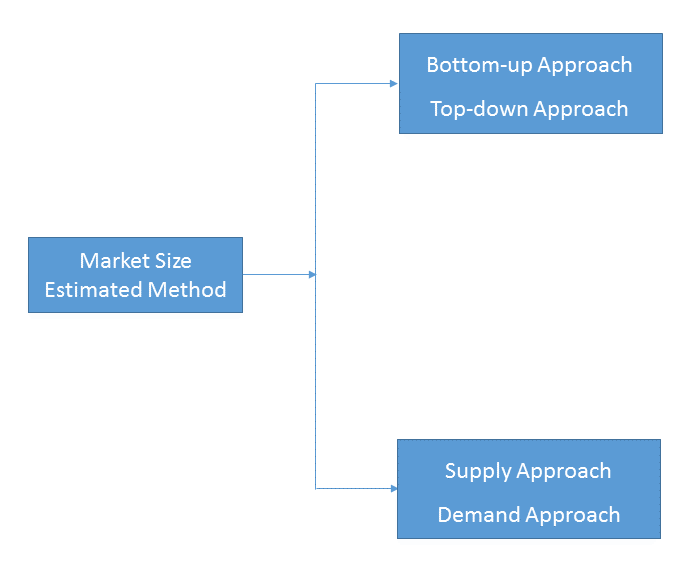
- Market Estimated Methodology:
Bottom-up & top-down approach, supply & demand approach are the most important method which is used by HDIN Research to estimate the market size.
1)Top-down & Bottom-up Approach
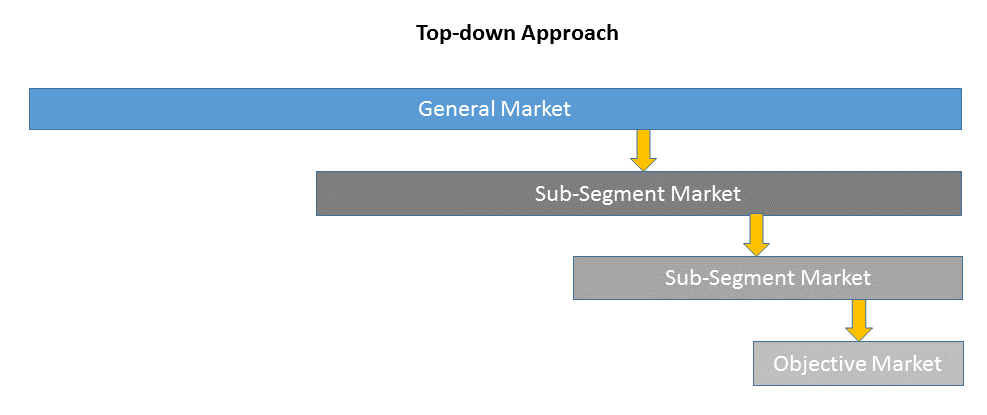
Top-down approach uses a general market size figure and determines the percentage that the objective market represents.
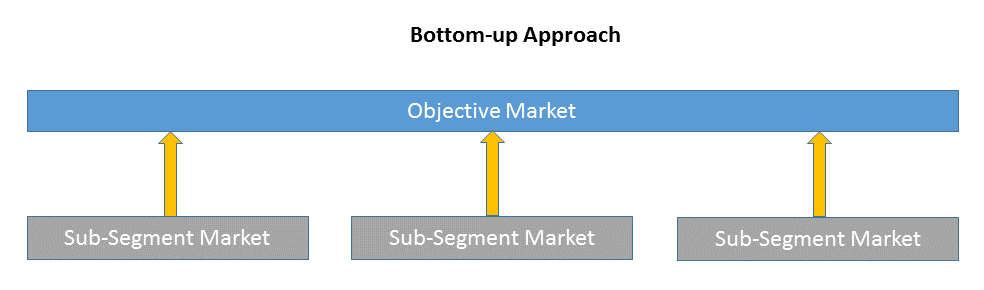
Bottom-up approach size the objective market by collecting the sub-segment information.
2)Supply & Demand Approach
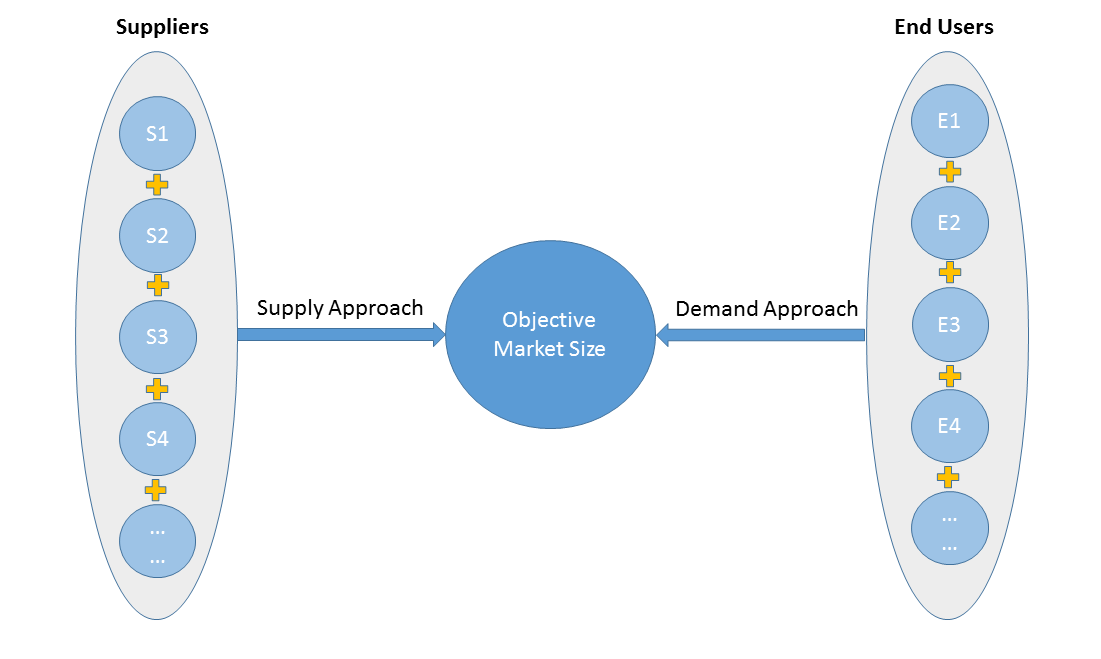
Supply approach is based on assessments of the size of each competitor supplying the objective market.
Demand approach combine end-user data within a market to estimate the objective market size. It is sometimes referred to as bottom-up approach.
- Forecasting Methodology
- Numerous factors impacting the market trend are considered for forecast model:
- New technology and application in the future;
- New project planned/under contraction;
- Global and regional underlying economic growth;
- Threatens of substitute products;
- Industry expert opinion;
- Policy and Society implication.
- Analysis Tools
1)PEST Analysis
PEST Analysis is a simple and widely used tool that helps our client analyze the Political, Economic, Socio-Cultural, and Technological changes in their business environment.
- Benefits of a PEST analysis:
- It helps you to spot business opportunities, and it gives you advanced warning of significant threats.
- It reveals the direction of change within your business environment. This helps you shape what you’re doing, so that you work with change, rather than against it.
- It helps you avoid starting projects that are likely to fail, for reasons beyond your control.
- It can help you break free of unconscious assumptions when you enter a new country, region, or market; because it helps you develop an objective view of this new environment.
2)Porter’s Five Force Model Analysis
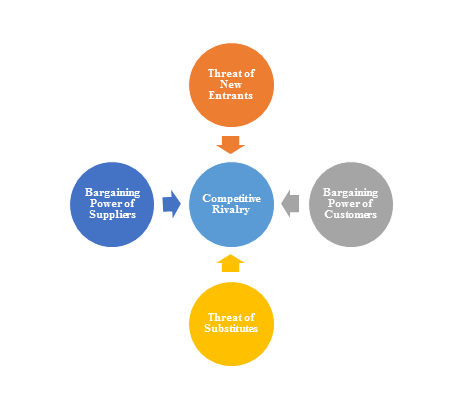
The Porter’s Five Force Model is a tool that can be used to analyze the opportunities and overall competitive advantage. The five forces that can assist in determining the competitive intensity and potential attractiveness within a specific area.
- Threat of New Entrants: Profitable industries that yield high returns will attract new firms.
- Threat of Substitutes: A substitute product uses a different technology to try to solve the same economic need.
- Bargaining Power of Customers: the ability of customers to put the firm under pressure, which also affects the customer's sensitivity to price changes.
- Bargaining Power of Suppliers: Suppliers of raw materials, components, labor, and services (such as expertise) to the firm can be a source of power over the firm when there are few substitutes.
- Competitive Rivalry: For most industries the intensity of competitive rivalry is the major determinant of the competitiveness of the industry.
3)Value Chain Analysis
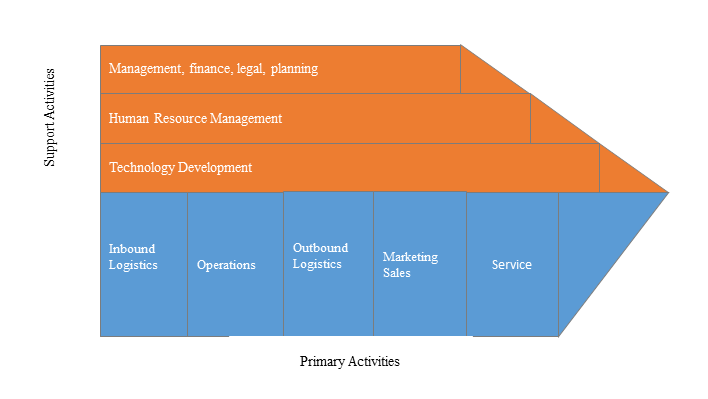
Value chain analysis is a tool to identify activities, within and around the firm and relating these activities to an assessment of competitive strength. Value chain can be analyzed by primary activities and supportive activities. Primary activities include: inbound logistics, operations, outbound logistics, marketing & sales, service. Support activities include: technology development, human resource management, management, finance, legal, planning.
4)SWOT Analysis
SWOT analysis is a tool used to evaluate a company's competitive position by identifying its strengths, weaknesses, opportunities and threats. The strengths and weakness is the inner factor; the opportunities and threats are the external factor. By analyzing the inner and external factors, the analysis can provide the detail information of the position of a player and the characteristics of the industry.
- Strengths describe what the player excels at and separates it from the competition
- Weaknesses stop the player from performing at its optimum level.
- Opportunities refer to favorable external factors that the player can use to give it a competitive advantage.
- Threats refer to factors that have the potential to harm the player.
- Data Sources
| Primary Sources | Secondary Sources |
|---|---|
| Face to face/Phone Interviews with market participants, such as: Manufactures; Distributors; End-users; Experts. Online Survey |
Government/International Organization Data: Annual Report/Presentation/Fact Book Internet Source Information Industry Association Data Free/Purchased Database Market Research Report Book/Journal/News |