Medical X-Ray Tube Market Analysis: Strategic Outlook 2026-2031
- Single User License (1 Users) $ 3,500
- Team License (2~5 Users) $ 4,500
- Corporate License (>5 Users) $ 5,500
Medical X-ray tubes represent the high-vacuum, electron-to-photon conversion engines powering diagnostic radiology. The global medical X-ray tubes is projected to reach between 2.6 billion USD and 4.2 billion USD by 2026, expanding at an annual compound rate between 2.5% and 4.5% through 2031.
The global medical X-ray tube landscape exhibits a bifurcated competitive structure divided between captive in-house manufacturing divisions of Tier-1 diagnostic imaging conglomerates (GE HealthCare, Siemens Healthineers, Philips Healthcare, Canon Medical Systems, and United Imaging Healthcare) and independent merchant component suppliers led by Varex Imaging Corporation, Dunlee, IAE S.p.A., and ascending Chinese innovators including iRay Technology and Kunshan YiYuan.
Manufacturers must confront tightening international trade policies, such as the United States Section 232 investigations initiated in late 2025 and Chinese Ministry of Commerce (MOFCOM) anti-dumping inquiries regarding imported X-ray tube assemblies, while simultaneously re-engineering product architectures to satisfy European Union Medical Device Regulation (EU MDR) certification requirements and domestic local-for-local manufacturing mandates.
TECHNICAL TAXONOMY AND ARCHITECTURAL SUBASSEMBLIES
A medical X-ray tube is an ultra-high-vacuum diode operating under severe electro-physical and thermodynamic extremes. Its core operational purpose is converting guided electrical energy into diagnostic ionizing radiation through Bremsstrahlung and characteristic emission interactions.
1. Structural Subassemblies
● Cathode Subassembly (Electron Source):
The cathode serves as the negative terminal, incorporating a coiled tungsten emitter filament or a sintered barium-tungsten dispenser cathode. When driven by an auxiliary electrical current, thermionic emission liberates a controlled electron cloud. Precision-machined molybdenum focusing cups shape and electrostatically project this electron beam across the vacuum gap toward a strictly demarcated target track.
● Anode Subassembly (Target and Motion Mechanisms):
Positioned as the positive target, the anode absorbs directed relativistic electron impacts. High-duty rotating anodes typically utilize a composite structure comprising a refractory tungsten-rhenium (W-Re, often 90-95% W with 5-10% Re to impede surface crazing) focal surface bonded via high-temperature vacuum brazing to a specialized molybdenum-alloy core (TZM: titanium-zirconium-molybdenum) and backed by high-emissivity graphite heat sinks. An induction rotor assembly, activated by external stator windings, drives the target at angular velocities ranging from 3,000 to over 10,000 revolutions per minute.
● Vacuum Envelope and Structural Containment:
Internal vacuum integrity is maintained at pressures below 6 x 10^-7 Pa (equivalent to 10^-9 Torr) to prevent atmospheric gas ionization, catastrophic high-voltage arcing, and spatial electron scattering. Envelopes historically constructed from borosilicate glass have broadly transitioned in premium modalities to high-alumina ceramics and brazed ceramic-metal or metal-envelope architectures, which mitigate stray secondary electron wall-charging and improve mechanical resilience.
● Encapsulation and Thermodynamic Dissipation Architecture:
The vacuum insert is sealed inside a cast-aluminum, lead-lined housing assembly. The void is flooded with highly refined, moisture-free dielectric hydrocarbon or silicone insulating oil. This oil serves a dual mandate: providing high-voltage electrical breakdown suppression (withstand levels up to 150 kV potential differences) and transferring extreme conductive heat from the anode stem through circulation pumps to external oil-to-air or oil-to-water heat exchangers.
2. Energy Transformation Mechanics
Operation involves applying an accelerating differential of 20 kV to 150 kV between terminals. Accelerated electrons strike the focal spot at velocities approaching half the speed of light. Over 99% of total incident kinetic energy is converted into non-diagnostic thermodynamic heat within a microscopically thin target layer, while less than 1% produces penetrating diagnostic X-ray photons through nuclear deceleration (Bremsstrahlung) and inner-shell electron displacement. Emitted primary radiation exits the housing assembly through a low-attenuation optical window fabricated from high-purity metallic beryllium (Be) foil.
3. Product Classification
● Classification by Anode Motion Kinetics:
- Fixed Anode Tubes: Incorporate a static tungsten target forged into a solid copper anode block. Characterized by low continuous electrical ratings (typically under 2 kW), limited heat dissipation, and compact mechanical geometry, these units are restricted to intraoral dental radiography, compact veterinary units, and lightweight battery-powered handheld field diagnostics.
- Rotating Anode Tubes: Direct the electron beam against a beveled rotating disk track, distributing localized thermal stress across a wider circumferential path. Essential for continuous multi-exposure modalities such as modern multi-slice CT, dynamic fluoroscopy, digital subtraction angiography, and primary digital radiography suites.
● Classification by Bearing Architecture and Fluid Dynamics:
- Mechanical Ball-Bearing Tubes: Utilize high-precision tool-steel or silicon nitride (Si3N4) ceramic balls pre-coated with solid lubricants (such as silver, lead, or molybdenum disulfide films) operating within high-vacuum chambers. These assemblies face progressive mechanical friction wear, operational acoustic noise, and thermal limits, restricting continuous heat transfer through the bearing stem.
- Liquid Metal Bearing (LMB) Tubes: Eliminate mechanical surface-to-surface point contact by suspending the rotating hub on a hydrodynamic fluid layer consisting of a molten Gallium-Indium-Tin (GaInSn) alloy. The liquid metal provides near-zero mechanical wear, silent continuous rotation, superior shock absorption against extreme gantry accelerations (exceeding 20 to 24 g in rapid helical CT scanners), and direct thermal conduction away from the target disk, rendering anode cooling bottlenecks largely obsolete.
● Classification by Clinical Application Profile:
- Computed Tomography (CT) Tubes: High-load, continuous-exposure rotating anode tubes characterized by heat storage capacities from 4.0 MHU to over 8.0 MHU, continuous ratings exceeding 80 kW, dual or flying focal spot deflection technologies, and rapid liquid-metal heat dissipation interfaces.
- General Radiography and Fluoroscopy (R&F / DR) Tubes: Medium-to-high capacity dual-focal-spot tubes operating between 100 kV and 150 kV. They balance high spatial resolution (0.6 mm fine focus) with short-duration exposure tolerances (1.2 mm to 1.5 mm broad focus) for dynamic gastrointestinal fluoroscopy and static radiographic examinations.
- Mammography and Digital Breast Tomosynthesis (DBT) Tubes: Specialized low-energy vacuum tubes operating at 20 kV to 40 kV. Equipped with microscopic focal spots (0.1 mm to 0.3 mm) and specialized molybdenum (Mo), rhodium (Rh), or bi-angular tungsten-rhodium targets behind beryllium or ultra-thin borosilicate windows to deliver low-energy soft radiation tailored to glandular breast tissue contrast.
- Interventional and Angiography (DSA / IXR) Tubes: Severe-duty tubes operating across 50 kV to 125 kV ranges, engineered with liquid metal bearings, grid-switched active pulsed fluoroscopy cathodes, and composite tungsten-graphite targets capable of sustained roadmapping exposures without thermal shutdown during critical endovascular and neurovascular procedures.
- Dental Radiography Tubes: High-volume, compact fixed-anode or low-speed rotating anode tubes configured for 60 kV to 90 kV operation. Built with focal spots under 0.5 mm for high-definition dental Cone-Beam CT (CBCT), panoramic orthopantomography, and intraoral periapical diagnostics.
DOWNSTREAM CLINICAL DEMAND AND UTILIZATION LIFECYCLES
Downstream diagnostic imaging modalities demonstrate divergent operational demands, creating distinct lifecycle dynamics and replacement velocity across global healthcare infrastructures.
1. Computed Tomography (CT) Fleet Dynamics
CT architectures represent the single highest-value component segment within the merchant and replacement ecosystem. Modern multi-slice CT (from 16-slice entry platforms to 128-, 256-, and 640-slice premium configurations) exposes X-ray tubes to extreme mechanical torque, continuous high-current electron bombardment, and severe thermal saturation during whole-body trauma, vascular runoffs, and cardiac cinematic scanning.
A stark utilization divergence defines the global replacement cadence. In private outpatient clinics and regional hospitals across North America and Europe, an average CT tube exhibits an operational life ranging from 2 to 6 years, dictated by moderate patient volumes (15 to 35 scans daily). Conversely, in Tier-3 municipal hospital networks across China and urban public healthcare centers in emerging Asia, scanners frequently operate 18 to 24 hours daily, logging between 100 and 250 patient examinations per shift. This operational tempo compresses the functional lifespan of high-capacity CT tubes to between 10 and 20 months, shifting CT tubes from long-term capital assets to recurring, high-value operating consumables.
2. General Diagnostic Radiography (DR, Mobile Carts, and DRF)
General digital radiography constitutes the foundational equipment base of universal diagnostic medicine. Tubes deployed across stationary floor-mounted systems, ceiling-suspended gantries, mobile emergency room carts, and tilt-table gastrointestinal fluoroscopy systems experience intermittent, short-duration exposures. Operating lifetimes frequently span 7 to 10 years. Component replacement in this domain is rarely driven by sudden thermal failure; instead, it results from gradual tungsten evaporation onto the vacuum envelope, micro-fissuring of the focal track, or insulation oil breakdown. Growth in this modality is sustained by emerging market transitions from analog film and computed radiography (CR) plates to direct digital radiography, combined with demand for lightweight mobile bedside systems.
3. Interventional Radiology and Fluoroscopic Suites (DSA / Hybrid ORs)
Angiographic and digital subtraction angiography (DSA) suites deploy specialized tubes engineered for prolonged fluoroscopic guidance and high-dose digital acquisitions in structural cardiology, peripheral vascular interventions, and acute neuro-thrombectomy. System shutdowns during catheter-based operations pose severe clinical risks; consequently, interventional tubes require exceptional continuous dissipation rates supported by active external heat management systems. Tubes in high-volume catheterization labs face replacement every 2 to 4 years, driven by anode target pitting caused by high cumulative milliampere-second (mAs) loads.
4. Full-Field Digital Mammography (FFDM) and 3D Breast Tomosynthesis (DBT)
Mammographic screening requires narrow X-ray spectra to maximize differential soft-tissue attenuation between healthy fibroglandular parenchyma and microcalcifications. The shift from standard 2D digital screening toward multi-angle 3D digital breast tomosynthesis demands rapid successions of low-dose sweep exposures per breast compression. This operational protocol imposes elevated thermal stress on ultra-small focal tracks, accelerating replacement cycles relative to legacy 2D systems.
5. Dental CBCT and Oral Maxillofacial Systems
The proliferation of dental Cone-Beam CT (CBCT) systems within private orthodontic, endodontic, and implantology clinics has transformed the dental X-ray source landscape. Historical dental imaging relied on simple, low-cost stationary anode inserts. Contemporary 3D maxillofacial reconstructions, however, require pulsed rotating anode tubes or robust stationary tubes operating alongside long duty-cycle detectors. This transition elevates component average selling prices (ASPs) and increases quality reliability thresholds across the outpatient dental supply chain.
6. Image-Guided Radiation Therapy Guidance (IGRT)
Modern linear accelerators (LINACs) incorporate secondary kilovoltage (kV) diagnostic X-ray tube assemblies mounted orthogonally to high-energy megavoltage (MV) cancer therapy treatment heads. These auxiliary imaging tubes perform real-time stereoscopic localization, cone-beam pre-treatment verification, and respiratory-gated tracking. Tube configurations within radiation oncology demand absolute focal spot stability and mechanical precision to prevent geometric imaging errors during stereotactic radiosurgery workflows.
SALES CHANNELS
1. OEM Direct Business (Primary Equipment Channel)
The Original Equipment Manufacturer (OEM) route involves direct component sales to diagnostic imaging machine developers (such as Canon Medical Systems, United Imaging Healthcare, GE HealthCare, Siemens Healthineers, Philips Healthcare, Mindray, and Neusoft Medical).
- Design-In Complexity: The integration of an X-ray tube into an OEM gantry is a multi-year collaborative engineering project. The tube assembly must interface with proprietary high-voltage generators, stator frequency controllers, gantry balancing tolerances, and digital collimation subassemblies.
- Regulatory Lock-In Moats: Once an OEM integrates a specific merchant tube insert or housing, that component is registered within the comprehensive medical device regulatory dossiers submitted to statutory bodies (e.g., US FDA 510(k), EU MDR Class IIb technical files, or China NMPA Class III licensing). Replacing an approved tube vendor requires expensive mechanical redesigns, risk-management audits, and regulatory registration amendments that can take 18 to 36 months to clear. Consequently, OEM design wins generate defensive supplier moats that routinely persist for 15 to 30 years across the lifetime of a specific scanner platform.
- Commercial Dynamic: This channel is characterized by high volume commitments, predictable manufacturing run-rates, and multi-year supply contracts, balanced against aggressive volume pricing concessions and lower gross margins.
2. Aftermarket and Multi-Vendor Replacement Channel
Given that all medical X-ray tubes—particularly in CT and vascular modalities—are consumable items subject to unavoidable physical wear, a parallel high-margin aftermarket exists alongside OEM pipelines.
- Channel Structure: Component manufacturers serve hospital networks, independent diagnostic facilities, and ambulatory surgery centers either through direct OEM-branded replacement programs, third-party Independent Service Organizations (ISOs), multi-vendor maintenance service providers, or regional diagnostic parts distributors.
- Margin Profile and Value Capture: Aftermarket replacement tubes generate gross margins significantly higher than initial OEM factory integration sales. Field survival requires drop-in mechanical, electrical, and thermal compatibility with existing OEM gantries without requiring re-certification of the base host system.
- Market Entry Barriers: To access this replacement volume, independent component makers must develop drop-in replacement assemblies that replicate exact mechanical interfaces, electrical pinouts, high-voltage socket designs, thermal communication protocols, and stator drive mechanics. Suppliers must navigate complex intellectual property barriers surrounding OEM gantry communication protocols, software handshakes, and housing geometries.
REGIONAL MARKET DYNAMICS AND LEGISLATIVE FRAMEWORKS
1. North America: North America represents the second-largest geographic market by revenue, defined by a dense installed base of diagnostic scanners, advanced procedural volumes in cardiac catheterization and trauma CT, and rapid adoption of photon-counting CT platforms. Demand is supported by an ongoing structural migration of diagnostic imaging from tertiary inpatient centers toward Independent Diagnostic Testing Facilities (IDTFs) and Ambulatory Surgery Centers (ASCs).
Regulatory and Legislative Landscape:
- FDA Oversight: Medical X-ray tubes, housings, and beam-limiting devices are regulated as Class II medical devices by the Center for Devices and Radiological Health (CDRH) under the Food, Drug, and Cosmetic Act. Compliance with 21 CFR 820 is transitioning to the unified Quality Management System Regulation (QMSR), which harmonizes domestic rules with international ISO 13485 standards.
- Trade Expansion Act Section 232 Inquiries: Launched in the latter half of 2025, administrative investigations under Section 232 have scrutinized supply-chain dependencies across critical medical hardware sub-tiers, introducing supply chain scrutiny for imported foreign-forged tungsten disks and specialty components.
- Outpatient Reimbursement Pressures: Legislative measures reforming Medicare and Medicaid reimbursements, including federal statutory adjustments equalizing outpatient clinic and hospital reimbursement rates, have constrained capital acquisition budgets. These adjustments compel healthcare providers to extend diagnostic scanner lifespans via multi-vendor replacement tubes rather than deploying capital for new imaging gantries.
2. Asia-Pacific (APAC): Asia-Pacific represents the largest and fastest-growing market globally. Regional momentum is driven by heavy public hospital capital investments, expanding tiered healthcare networks, high daily patient imaging volumes, and local diagnostic hardware manufacturing expansion.
China Market Deep Dive:
- Institutional Procurement Realignment: Following national hospital procurement realignments in 2023 and 2024, institutional purchasing stabilized in 2025 under standardized anti-corruption and compliance oversight.
- 14th Five-Year Plan Equipment Renewal: In 2025, national equipment modernization policies catalyzed replacement demand for aging diagnostic systems across secondary and tertiary regional hospitals, driving demand for localized CT and general radiography assemblies.
- Volume-Based Procurement (VBP) and Two-Invoice Rules: Centralized provincial and national procurement initiatives have expanded to high-value medical hardware. While base X-ray tubes are rarely procured directly via consumer VBP, the institutional price ceilings on whole imaging systems have compressed system margins, forcing domestic OEMs to demand low-cost localized components. The Two-Invoice System strictly regulates medical equipment distribution networks by limiting intermediary markups.
- MOFCOM Trade Investigations: In mid-2025, the Ministry of Commerce of China (MOFCOM) initiated targeted trade competitiveness and anti-dumping investigations into imported medical X-ray tubes and CT tube inserts originating from the United States and India. This institutional review has accelerated the domestic substitution of imported merchant tubes with locally manufactured components.
- Localization Mandates: Global multinational imaging OEMs operating within China have adopted "In China, for China" manufacturing strategies. Siemens Healthineers, Philips, and GE HealthCare have established localized engineering centers, component assembly, and local supply chain partnerships to satisfy domestic public tender scoring criteria.
Other Regional APAC Nodes:
- Japan represents a mature, highly specialized CT and mammography replacement market overseen by the Pharmaceuticals and Medical Devices Agency (PMDA) under the PMD Act, governed by strict Japanese Industrial Radiographic Association (JIRA) radiation protection norms.
- India represents a rapidly expanding volume market driven by both private healthcare infrastructure expansion and the establishment of local medical hardware production clusters, exemplified by component suppliers establishing local assembly footprints to support domestic and regional assembly.
- Markets across Taiwan, China, South Korea, and Southeast Asia demonstrate sustained capital allocation toward modular dental CBCT, dual-energy digital radiography, and dynamic interventional fluoroscopy suites.
3. Europe: Europe operates as a mature, technology-intensive medical imaging market. Growth is underpinned by scanner replacement cycles, steady multi-slice CT upgrades, dynamic interventional surgical adoption, and expansion in screening-based tomosynthesis.
Regulatory Framework:
- European Medical Device Regulation (EU MDR 2017/745): MDR has reshaped the European component landscape. Enforcing strict Class IIb clinical evidence requirements, comprehensive post-market clinical follow-up (PMCF), and mandatory technical documentation audits via Notified Bodies, EU MDR has increased commercialization costs for tube inserts and replacement housings. Small-scale aftermarket suppliers have faced technical attrition, leaving the market consolidated around large, regulatory-compliant suppliers.
- Green Transition and Material Directives: European operations must strictly align with RoHS (Restriction of Hazardous Substances) and REACH (Registration, Evaluation, Authorisation and Restriction of Chemicals) regulations. These directives restrict the lifecycle management of heavy metals—such as lead shielding within housing assemblies and dielectric insulating oils—compelling R&D expenditures toward recyclable, non-toxic shielding alloys and biodegradable dielectric coolants.
4. Latin America: Latin America exhibits moderate market growth, led by Brazil, Mexico, Colombia, and Argentina. Regional demand is dominated by the replacement of aging base-tier radiographic units, public hospital health network modernization tenders, and private hospital expansion.
Regulatory Dynamics: Component entry depends on national regulatory clearance—notably by ANVISA in Brazil and COFEPRIS in Mexico. These bodies increasingly emphasize manufacturing plant inspections and ISO 13485 certification, favoring multi-national independent merchant suppliers over fragmented regional low-tier assemblers.
5. Middle East and Africa (MEA): The MEA presents a dual operating dynamic. The Gulf Cooperation Council (GCC) nations (Saudi Arabia, UAE, Qatar) deploy extensive sovereign healthcare allocations toward advanced medical cities, digital oncology hubs, and multi-slice CT/IGRT systems. Conversely, broad territories within Sub-Saharan Africa and North Africa remain reliant on multilateral development bank funding, public tender renewals, and cost-effective basic radiographic systems.
Market Mechanics: GCC distribution relies on strategic partnerships and direct local joint ventures. Component distribution is aligned with government-led localization initiatives, requiring multinational tube manufacturers to secure in-country representation to service state public healthcare facilities.
SUPPLY CHAIN ARCHITECTURE AND VALUE CHAIN MECHANICS
The medical X-ray tube industry chain is a vertically concentrated, highly specialized production sequence where raw-material metallurgical performance directly dictates downstream radiographic capability.
1. Upstream Value Creation: Strategic Materials and Subcomponents
The raw-material foundation depends on access to high-purity refractory and precious metals capable of withstanding extreme operational environments:
- Tungsten (W) (CAS 7440-33-7): Forms the operational base of cathode filaments and anode targets due to its high melting point (3,422 degrees C) and atomic number (Z=74), maximizing Bremsstrahlung production efficiency.
- Rhenium (Re) (CAS 7440-15-5): Blended into tungsten surface layers to prevent mechanical thermal cracking and recrystallization-induced brittleness during rapid temperature excursions.
- Molybdenum (Mo) (CAS 7439-98-7) and TZM Alloys: Serve as thermal-barrier substrates and rotating stem supports, limiting thermal shock transmission into the bearing mechanisms.
- Beryllium (Be) (CAS 7440-41-7): Used for X-ray output windows due to its low atomic attenuation, allowing beam transmission with minimal spectral distortion. Beryllium machining requires enclosed, certified processing facilities due to beryllium toxicity.
- Gallium-Indium-Tin Liquid Alloys (GaInSn): Low-melting-point eutectic mixtures utilized within liquid metal hydrodynamic bearings. These alloys must remain non-reactive, stable under extreme vacuum, and chemically inert against tungsten shaft degradation over tens of thousands of hours of rotation.
- High-Alumina Technical Ceramics and Dielectric Insulating Oils: Advanced ceramics provide high-voltage structural isolation, while high-flashpoint, ultra-purified mineral and synthetic dielectric oils manage high-voltage suppression and continuous thermal absorption.
2. Midstream Manufacturing and Precision Physics Engineering
The transition from raw metallurgy to an active X-ray tube is an engineering intensive process characterized by high capital entry barriers:
- Vacuum Exhaust and High-Temperature Degassing: Assembled inserts are baked in high-vacuum exhaust ovens for days at temperatures exceeding several hundred degrees Celsius. This removes trace occluded gas molecules from the porous surfaces of the internal graphite targets, ceramics, and refractory metals to secure an operational vacuum below 6 x 10^-7 Pa.
- Vacuum Brazing and Electron-Beam Welding: Joining dissimilar materials (such as refractory tungsten-rhenium tracks to molybdenum cores or ceramic insulators to structural copper rings) requires specialized electron-beam (EB) welding and vacuum-induction brazing setups to maintain geometric alignment within micron-level tolerances.
- High-Voltage Electrical Conditioning (Aging): Freshly sealed vacuum inserts undergo progressive high-voltage processing. Tube voltages are incrementally elevated beyond nominal operational ratings (often up to 160 kV) across several days. This controlled process initiates micro-discharges, burns away microscopic metal asperities, and stabilizes field-emission surfaces before factory deployment.
3. Downstream System Assembly and Integration
Medical equipment OEMs assemble final diagnostic imaging gantries by synchronizing the midstream X-ray tube with matching high-frequency, high-voltage generators, dynamic flat panel detectors (FPDs), multi-leaf automatic collimators, mechanical motor gantries, and diagnostic image-processing engines. Complete diagnostic imaging installations are deployed across public hospitals, specialized oncology clinics, private diagnostic imaging centers, and ambulatory emergency suites.
COMPETITIVE DOSSIERS: PROFILES OF KEY INDUSTRY PLAYERS
1. Primary Independent Merchant Manufacturers
● Varex Imaging Corporation (Headquarters: Salt Lake City, Utah, USA)
- Operational Footprint: The world's largest independent designer and merchant manufacturer of medical X-ray components. Varex maintains an annual production exceeding 27,000 X-ray tubes globally and supports an active installed base of over 160,000 tubes worldwide.
- Core Product Families:
* Medical CT Platforms: Manufactures the heavy-duty MCS series (MCS-6074, MCS-8064), providing 6.3 to 8.0 MHU target heat storage capabilities to service third-party hospital platforms and independent multi-slice CT platforms.
* Liquid Metal Bearing Architecture: Produces hydrodynamic liquid metal bearing CT tubes that eliminate conventional ball-bearing wear cycles, enabling continuous high-power operation.
* Anode End Grounding (AEG) Innovation: Features designs where the rotating anode runs at ground potential while the cathode is held at high negative voltage, permitting direct liquid cooling of the anode disk and yielding a compact envelope footprint.
* Radiography, Fluoroscopy, and Mammography: Operates the Rad line (Rad-14, Rad-21, Rad-60, Rad-74, Rad-92) across broad 150 kV diagnostic applications, the Diamond and Emerald housing lines for cardiovascular angiography, and the B-110/B-115 housings paired with M-113/M-151 inserts for 3D digital breast tomosynthesis.
● The rest of Independent Merchant Manufacturers covered in the report: iRay Technology, IAE S.p.A., X-RAY WorX GmbH, Kunshan YiYuan Medical Technology Co. Ltd., Hangzhou Wandong Electron Co. Ltd., Coronas Medical Equipment (Shanghai) Co. Ltd., and Wuxi Guochen Medical Technology Co. Ltd.
2. In-House Captive Divisions of Diagnostic Imaging OEMs: GE HealthCare, Siemens Healthineers, Philips Healthcare, Canon Medical Systems, Fujifilm Healthcare, United Imaging Healthcare (UIH) and Shenzhen Angell Technology.
OPPORTUNITIES AND CHALLENGES
● Opportunities and Structural Tailwinds
1. The Liquid Metal Bearing (LMB) Transition
The industry is experiencing a migration from mechanical ball bearings to hydrodynamic liquid metal bearings (GaInSn). Mechanical bearings face operational constraints, including physical point wear, rotor friction noise, and structural limits under high gantry acceleration (15 to 24 g). LMB architectures eliminate point contact, operate silently, dissipate shock loads, and conduct heat directly from the anode stem through the liquid metal into the cooling circuit. While early-generation LMB components were confined to Tier-1 OEM platforms, merchant suppliers like Varex and domestic specialists like Kunshan YiYuan are industrializing merchant LMB tubes, democratizing access for mid-tier CT manufacturers.
2. Heavy-Duty Heat Storage and Cathode Field-Emission Evolution
Clinical demand for high-pitch whole-body trauma evaluations, dynamic cardiac perfusion, and continuous interventional roadmapping requires tube platforms with higher thermal storage. Targets with 4.0 MHU to over 8.0 MHU capacities, supported by direct oil cooling and barium-tungsten dispenser cathodes capable of high current densities, have transitioned from elite configurations to baseline clinical requirements. In parallel, long-term exploratory investments into carbon nanotube (CNT) cold-cathode field-emission systems offer future paths toward instantaneous electronic beam gating, static non-rotating multi-beam CT geometries, and reduced form factors.
3. Integration with Photon-Counting CT (PCCT)
The commercialization of Cadmium Zinc Telluride (CZT) and Silicon-based photon-counting CT detectors imposes new operating parameters on X-ray tubes. Photon-counting eliminates electronic read noise and separates incoming photons by energy bins, permitting reductions in injected patient contrast agents and radiation dose. To leverage these detectors, X-ray sources must deliver stable focal-spot geometries and rapid kV-switching or dual-source configurations with narrow energy distributions, expanding technical requirements for next-generation tube platforms.
● Industry Inhibitors and Vulnerabilities
1. Geopolitical Trade Policy and Tariff Escalation
Global diagnostic hardware supply chains face friction from bilateral tariffs and protective trade legislation. Tariffs directly compress operating margins across international production networks. For example, trade measures during 2025 resulted in operational cost headwinds of approximately 245 million USD for GE HealthCare. Furthermore, trade actions by the Chinese Ministry of Commerce (MOFCOM) targeting imported American and Indian X-ray tube inserts highlight systemic risks to cross-border component integration, accelerating regional supply-chain ring-fencing.
2. Multi-Jurisdictional Regulatory Certification Barriers
Regulatory certification is a major barrier to competitive entry. Transitioning a tube insert across the US FDA 510(k), European Union Medical Device Regulation (EU MDR Class IIb), China National Medical Products Administration (NMPA Class III), and Japanese PMDA requires extensive clinical safety data, risk-management documentation (ISO 14971), and biocompatibility/electrical audits (IEC 60601-2-28). Any material alteration in cathode configuration, target metallurgy, or internal bearing fluid triggers regulatory amendments, increasing compliance costs and extending lead times for drop-in replacement units.
3. Raw Material Volatility and Supply Concentration
Midstream tube manufacturing relies on concentrated, geographically sensitive raw material inputs:
- Tungsten, rhenium, and molybdenum deposits face extraction quotas and geopolitical supply consolidation.
- Optical beryllium window manufacturing involves severe respiratory toxicity risks (berylliosis), concentrating processing within a limited tier of certified international facilities.
- Volatility in specialty liquid gallium-indium alloys or sudden price surges across high-purity refractory metals can compromise production economics for independent merchant suppliers operating under fixed multi-year OEM pricing structures.
1.1 Research Objectives and Scope Definition 1
1.2 Research Methodology and Estimation Models 2
1.2.1 Primary Source Triangulation and Expert Interviews 2
1.2.2 Secondary Data Mining and Core Statistical Baselines 3
1.2.3 Bottom-Up and Top-Down Market Sizing Logic 4
1.3 Forecasting Assumptions and Base Currency Matrix 5
1.4 Strategic Abbreviations and Nomenclature 6
Chapter 2 Global Medical X-ray Tube Market Landscape and Strategic Dynamics 7
2.1 Global Market Sizing and Velocity Tracking (2021-2031) 7
2.1.1 Global Volume Consumption and Installed Base Trajectory 7
2.1.2 Global Market Value Realization and Price Evolution 9
2.2 Merchant vs. Captive Sourcing Strategic Paradigm 11
2.3 Value Migration Across Radiation Modalities 12
Chapter 3 Value Chain Architecture, Metallurgy, and Manufacturing Process Analysis 14
3.1 Upstream Critical Feedstocks and Strategic Materials 14
3.1.1 Refractory Metal Sourcing: Tungsten, Molybdenum, and Rhenium 14
3.1.2 Specialty Beryllium Windows and Vacuum Grade Alloys 15
3.1.3 Liquid Metal Bearing (LMB) Lubricants and Gallium Alloys 16
3.2 Precision Manufacturing Workflows and High-Vacuum Processing 17
3.3 Critical Cost Stack Breakdown: Material, Precision Machining, and Outgassing 18
3.4 Supply Chain Vulnerabilities, Cold Sourcing, and Redundancy Architecture 19
Chapter 4 Global Trade Flows, Regulatory Imperatives, and IP Landscape 21
4.1 Global Trade Corridor Dynamics and Export Control Regimes 21
4.2 Import Tariffs and Strategic Stockpiling Across High-Tier Hubs 22
4.3 Regulatory Clearance Paradigms: FDA 510(k), CE MDR, and NMPA Standards 24
4.4 Global Patent Filings: Thermal Management, Focal Spot Stability, and LMBs 25
Chapter 5 Global Medical X-ray Tube Market Breakdown by Anode Motion Kinetics 27
5.1 Segment Comparison: Duty Cycle, Heat Dissipation, and Unit Economics 27
5.2 Rotating Anode X-Ray Tube 28
5.2.1 Consumption Volume and Revenue Analysis (2021-2031) 28
5.2.2 Sub-segmentation: Ball Bearing vs. Hydrodynamic Liquid Metal Bearing 30
5.3 Fixed Anode X-Ray Tube 31
5.3.1 Consumption Volume and Revenue Analysis (2021-2031) 31
5.3.2 Niche Domain Sustainability: Cost-Optimized Radiography and Portables 32
Chapter 6 Global Medical X-ray Tube Market Breakdown by Clinical Application 34
6.1 Segment Structural Share and Modality Shifting 34
6.2 CT X-Ray Tube 35
6.2.1 Volume Consumption, Replacement Cycles, and Value Dynamics (2021-2031) 35
6.2.2 High Heat Capacity and Continuous Power Demands 36
6.3 General Radiography and Fluoroscopy Tube 37
6.3.1 Volume Consumption and Market Value (2021-2031) 37
6.3.2 Transition to Digital Radiography (DR) Integrated Configurations 38
6.4 Mammography X-Ray Tube 39
6.4.1 Volume Consumption and Market Value (2021-2031) 39
6.4.2 Molybdenum vs. Rhodium Target Dual-Track Innovation 40
6.5 Dental X-Ray Tube 41
6.5.1 Volume Consumption and Market Value (2021-2031) 41
6.5.2 Proliferation of Dental CBCT Systems and Micro-Focal Demands 42
6.6 Interventional / DSA X-Ray Tube 43
6.6.1 Volume Consumption and Market Value (2021-2031) 43
6.6.2 High Sustained Fluoroscopic Workloads and Cooling Efficiency 44
Chapter 7 Global Medical X-ray Tube Market Breakdown by Sales Channel 45
7.1 Channel Matrix and Margin Distribution Profile 45
7.2 Original Equipment Manufacturer (OEM) Integration 46
7.2.1 Procurement Contracts, Multi-Year Frameworks, and Volume Trends (2021-2031) 46
7.2.2 Co-Development Models between Merchant Suppliers and System Integrators 47
7.3 Aftermarket and Replacement Channel 48
7.3.1 Installed Base Utilization, Fleet Aging, and Replacement Velocity (2021-2031) 48
7.3.2 Third-Party ISOs vs. OEM Service Level Agreements (SLAs) 49
Chapter 8 Global Medical X-ray Tube Geographic Demands and Production Hubs 50
8.1 Global Geographic Mapping Framework: Primary Hubs and Demand Centers 50
8.2 North America 51
8.2.1 United States: Sourcing Base and Clinical Replacement Velocity 52
8.2.2 Canada: Public Healthcare Capital Expenditure Cycles 54
8.3 Europe 55
8.3.1 Germany: Precision Manufacturing Epicenter and Modality Demand 56
8.3.2 Italy: Component Production Capabilities and Export Hubs 58
8.3.3 France: Diagnostic Fleet Modernization Initiatives 59
8.3.4 United Kingdom & Rest of Europe Market 60
8.4 Asia-Pacific 61
8.4.1 China: Domestic Substitution Ecosystem, High-Volume Sourcing, and Demand 62
8.4.2 Japan: Proprietary Tube Innovation Hub and High-Density Imaging Market 64
8.4.3 South Korea: Advanced Dental CBCT and Portable Diagnostic Manufacturing 65
8.4.4 India: High-Velocity CT Infrastructure Expansion and DR Conversion 66
8.5 Latin America 67
8.5.1 Brazil: Secondary Sourcing Hub and Refurbished Systems Intake 67
8.6 Middle East and Africa 68
8.6.1 Saudi Arabia and UAE: High-End Modality Upgrades and Healthcare Programs 68
Chapter 9 Competitive Landscape, Market Share, and Strategic Positioning 69
9.1 Competitive Taxonomy: Specialist Component Manufacturers vs. Captive OEM Units 69
9.2 Global Manufacturer Revenue and Volume Rankings (2025-2026) 70
9.3 Pricing Power, Raw Material Pass-Through, and Margin Analysis 72
9.4 Strategic Alliances, Joint Development Agreements, and M&A Vectors 73
Chapter 10 Corporate Intelligence and Financial Depth 75
10.1 Varex Imaging Corporation 75
10.1.1 Corporate Profile, Manufacturing Footprint, and Asset Base 75
10.1.2 Medical X-ray Tube Technical Portfolio and Bearing Innovation 76
10.1.3 Strategic SWOT Matrix 76
10.1.4 Operational Metrics: Volume, Price, Revenue, Cost, and Gross Margin (2021-2026) 77
10.1.5 Global Market Share Trajectory (2021-2026) 78
10.2 IAE S.p.A. 79
10.2.1 Corporate Profile, Foundry Capacity, and European Distribution 79
10.2.2 Aftermarket and OEM Medical X-ray Tube Architecture 80
10.2.3 Strategic SWOT Matrix 80
10.2.4 Operational Metrics: Volume, Price, Revenue, Cost, and Gross Margin (2021-2026) 81
10.2.5 Global Market Share Trajectory (2021-2026) 82
10.3 iRay Technology 83
10.3.1 Corporate Profile, R&D Infrastructure, and Vertical Integration Strategy 83
10.3.2 Medical X-ray Tube Portfolio for DR, Mammography, and CT 84
10.3.3 Strategic SWOT Matrix 84
10.3.4 Operational Metrics: Volume, Price, Revenue, Cost, and Gross Margin (2021-2026) 85
10.3.5 Global Market Share Trajectory (2021-2026) 86
10.4 Kunshan YiYuan Medical Technology Co. Ltd 87
10.4.1 Corporate Profile and Production Base Development 87
10.4.2 Diagnostic Tube Lines and Component Capabilities 88
10.4.3 Strategic SWOT Matrix 88
10.4.4 Operational Metrics: Volume, Price, Revenue, Cost, and Gross Margin (2021-2026) 89
10.4.5 Global Market Share Trajectory (2021-2026) 90
10.5 Hangzhou Wandong Electron Co. Ltd 91
10.5.1 Corporate Profile, Vacuum Tube Legacy, and Core Competencies 91
10.5.2 Medical X-ray Tube Offerings: General Radiography and Dental Units 92
10.5.3 Strategic SWOT Matrix 92
10.5.4 Operational Metrics: Volume, Price, Revenue, Cost, and Gross Margin (2021-2026) 93
10.5.5 Global Market Share Trajectory (2021-2026) 94
10.6 Coronas Medical Equipment (Shanghai) Co. Ltd. 95
10.6.1 Corporate Profile and Operational Scalability 95
10.6.2 Mid-to-High-End X-ray Tube Integration Capabilities 96
10.6.3 Strategic SWOT Matrix 96
10.6.4 Operational Metrics: Volume, Price, Revenue, Cost, and Gross Margin (2021-2026) 97
10.6.5 Global Market Share Trajectory (2021-2026) 98
10.7 Wuxi Guochen Medical Technology Co. Ltd. 99
10.7.1 Corporate Profile, Fabrication Facilities, and Capital Backing 99
10.7.2 Medical Rotating and Fixed Anode Pipeline 100
10.7.3 Strategic SWOT Matrix 100
10.7.4 Operational Metrics: Volume, Price, Revenue, Cost, and Gross Margin (2021-2026) 101
10.7.5 Global Market Share Trajectory (2021-2026) 102
10.8 X-RAY WorX GmbH 103
10.8.1 Corporate Profile and Precision Microfocus Tube Capabilities 103
10.8.2 Specialized Clinical and High-Resolution Medical Imaging Lines 104
10.8.3 Strategic SWOT Matrix 104
10.8.4 Operational Metrics: Volume, Price, Revenue, Cost, and Gross Margin (2021-2026) 105
10.8.5 Global Market Share Trajectory (2021-2026) 106
10.9 GE HealthCare (In-House Tube Operations) 107
10.9.1 Operational Structure, Captive Sourcing Footprint, and Integration Model 107
10.9.2 Proprietary Tube Innovations: Performix Series and CT Assemblies 108
10.9.3 Strategic SWOT Matrix 108
10.9.4 Operational Metrics: Volume, Price, Revenue, Cost, and Gross Margin (2021-2026) 109
10.9.5 Captive and External Sourcing Market Share Trajectory (2021-2026) 110
10.10 Siemens Healthineers (In-House Tube Operations) 111
10.10.1 Operational Structure and Center of Excellence for Tube Technology 111
10.10.2 Proprietary Tube Architecture: Straton and Vectron Direct-Drive Technology 112
10.10.3 Strategic SWOT Matrix 112
10.10.4 Operational Metrics: Volume, Price, Revenue, Cost, and Gross Margin (2021-2026) 113
10.10.5 Captive and External Sourcing Market Share Trajectory (2021-2026) 114
10.11 Philips Healthcare (In-House Tube Operations) 115
10.11.1 Operational Structure, Vacuum Facility Sites, and Assembly Nodes 115
10.11.2 Proprietary Tube Innovations: MRC and Spiral Groove Bearing Systems 116
10.11.3 Strategic SWOT Matrix 116
10.11.4 Operational Metrics: Volume, Price, Revenue, Cost, and Gross Margin (2021-2026) 117
10.11.5 Captive and External Sourcing Market Share Trajectory (2021-2026) 118
10.12 Canon Medical Systems (In-House Tube Operations) 119
10.12.1 Operational Structure, Electron Device Legacy, and Japan Production Bases 119
10.12.2 Proprietary Tube Portfolio: Ultra-High Heat Capacity CT and Angio Lines 120
10.12.3 Strategic SWOT Matrix 120
10.12.4 Operational Metrics: Volume, Price, Revenue, Cost, and Gross Margin (2021-2026) 121
10.12.5 Captive and External Sourcing Market Share Trajectory (2021-2026) 122
10.13 Fujifilm Healthcare (In-House Tube Operations) 123
10.13.1 Operational Structure, Integration of Acquired Assets, and Factory Setup 123
10.13.2 Radiography, Fluoroscopy, and Specialized Mammography Assemblies 124
10.13.3 Strategic SWOT Matrix 124
10.13.4 Operational Metrics: Volume, Price, Revenue, Cost, and Gross Margin (2021-2026) 125
10.13.5 Captive and External Sourcing Market Share Trajectory (2021-2026) 126
10.14 United Imaging Healthcare (In-House Tube Operations) 127
10.14.1 Operational Structure, Domestic Vertical Strategy, and Production Facilities 127
10.14.2 High-Tier CT and Interventional System In-House Tube Development 128
10.14.3 Strategic SWOT Matrix 128
10.14.4 Operational Metrics: Volume, Price, Revenue, Cost, and Gross Margin (2021-2026) 129
10.14.5 Captive and External Sourcing Market Share Trajectory (2021-2026) 130
10.15 Angell Technology 131
10.15.1 Corporate Profile, Upstream Module Integration, and Clinical Positioning 131
10.15.2 Medical X-ray Tube Deployment Across Radiographic Systems 132
10.15.3 Strategic SWOT Matrix 132
10.15.4 Operational Metrics: Volume, Price, Revenue, Cost, and Gross Margin (2021-2026) 133
10.15.5 Global Market Share Trajectory (2021-2026) 134
Table 2 Global Medical X-ray Tube Consumption Volume by Region (Units), 2021-2031 8
Table 3 Global Medical X-ray Tube Market Revenue by Region (USD Million), 2021-2031 10
Table 4 Global Average Selling Price (ASP) Dynamics by Tube Category (USD/Unit), 2021-2031 11
Table 5 Upstream High-Purity Refractory Metal Pricing and Supply Constraints (2021-2026) 15
Table 6 Cost Structure Breakdown for High-End CT X-ray Tube Production (2026) 19
Table 7 Global Import Tariffs on Vacuum Electron Tubes by Key Destination (2026) 23
Table 8 Rotating Anode X-Ray Tube Market Volume by Region (Units), 2021-2031 29
Table 9 Rotating Anode X-Ray Tube Market Revenue by Region (USD Million), 2021-2031 29
Table 10 Fixed Anode X-Ray Tube Market Volume by Region (Units), 2021-2031 32
Table 11 Fixed Anode X-Ray Tube Market Revenue by Region (USD Million), 2021-2031 33
Table 12 Global Medical X-ray Tube Market Revenue by Clinical Application (USD Million), 2021-2031 34
Table 13 CT X-Ray Tube Volume Consumption and Market Value (Units; USD Million), 2021-2031 36
Table 14 General Radiography and Fluoroscopy Tube Market Dynamics (Units; USD Million), 2021-2031 38
Table 15 Mammography X-Ray Tube Market Dynamics (Units; USD Million), 2021-2031 40
Table 16 Dental X-Ray Tube Market Dynamics (Units; USD Million), 2021-2031 42
Table 17 Interventional / DSA X-Ray Tube Market Dynamics (Units; USD Million), 2021-2031 44
Table 18 Global Medical X-ray Tube Revenue by Sales Channel (USD Million), 2021-2031 45
Table 19 OEM Sales Channel Volume and Procurement Expenditure (Units; USD Million), 2021-2031 47
Table 20 Aftermarket and Replacement Channel Volume and Revenue (Units; USD Million), 2021-2031 49
Table 21 North America Medical X-ray Tube Market by Segment (Units; USD Million), 2021-2031 51
Table 22 United States Medical X-ray Tube Sourcing, Consumption, and Revenue, 2021-2031 53
Table 23 Canada Medical X-ray Tube Market Volume and Value, 2021-2031 54
Table 24 Europe Medical X-ray Tube Market by Application (Units; USD Million), 2021-2031 55
Table 25 Germany Medical X-ray Tube Production, Consumption, and Export Value, 2021-2031 57
Table 26 Italy Medical X-ray Tube Production and Cross-Border Shipments, 2021-2031 58
Table 27 France Medical X-ray Tube Clinical Replacement Demand, 2021-2031 59
Table 28 United Kingdom Medical X-ray Tube Procurement Trends, 2021-2031 60
Table 29 Asia-Pacific Medical X-ray Tube Volume and Market Value by Country, 2021-2031 61
Table 30 China Medical X-ray Tube Domestic Output, Inflow, and Demand, 2021-2031 63
Table 31 Japan Medical X-ray Tube Market Value and Export Flows, 2021-2031 64
Table 32 South Korea Medical X-ray Tube Consumption and Dental Integration, 2021-2031 65
Table 33 India Medical X-ray Tube Import Inflows and Market Growth, 2021-2031 66
Table 34 Latin America Medical X-ray Tube Consumption Dynamics, 2021-2031 67
Table 35 Middle East and Africa Medical X-ray Tube Market Trajectory, 2021-2031 68
Table 36 Global Top 10 Medical X-ray Tube Manufacturers Revenue Share Ranking (2025-2026) 71
Table 37 Varex Imaging Corporation Medical X-ray Tube Sales, Price, Cost, and Gross Margin (2021-2026) 77
Table 38 IAE S.p.A. Medical X-ray Tube Sales, Price, Cost, and Gross Margin (2021-2026) 81
Table 39 iRay Technology Medical X-ray Tube Sales, Price, Cost, and Gross Margin (2021-2026) 85
Table 40 Kunshan YiYuan Medical Technology Medical X-ray Tube Sales, Price, Cost, and Gross Margin (2021-2026) 89
Table 41 Hangzhou Wandong Electron Medical X-ray Tube Sales, Price, Cost, and Gross Margin (2021-2026) 93
Table 42 Coronas Medical Equipment Medical X-ray Tube Sales, Price, Cost, and Gross Margin (2021-2026) 97
Table 43 Wuxi Guochen Medical Technology Medical X-ray Tube Sales, Price, Cost, and Gross Margin (2021-2026) 101
Table 44 X-RAY WorX GmbH Medical X-ray Tube Sales, Price, Cost, and Gross Margin (2021-2026) 105
Table 45 GE HealthCare Medical X-ray Tube Sales, Internal Transfer Price, Cost, and Gross Margin (2021-2026) 109
Table 46 Siemens Healthineers Medical X-ray Tube Sales, Internal Transfer Price, Cost, and Gross Margin (2021-2026) 113
Table 47 Philips Healthcare Medical X-ray Tube Sales, Internal Transfer Price, Cost, and Gross Margin (2021-2026) 117
Table 48 Canon Medical Systems Medical X-ray Tube Sales, Internal Transfer Price, Cost, and Gross Margin (2021-2026) 121
Table 49 Fujifilm Healthcare Medical X-ray Tube Sales, Price, Cost, and Gross Margin (2021-2026) 125
Table 50 United Imaging Healthcare Medical X-ray Tube Sales, Cost, and Production Output (2021-2026) 129
Table 51 Angell Technology Medical X-ray Tube Sales, Procurement Cost, and Internal Margins (2021-2026) 133
Figure 1 Global Medical X-ray Tube Market Research Triangulation Protocol 3
Figure 2 Global Medical X-ray Tube Volume and Net Revenue Projection (2021-2031) 8
Figure 3 Medical X-ray Tube Upstream-to-Downstream Process Flow and Node Margins 17
Figure 4 Global Medical X-ray Tube Patent Density Heatmap by Technology Node (2021-2026) 26
Figure 5 Global Rotating vs. Fixed Anode Market Share Comparison (2021 vs. 2026 vs. 2031) 28
Figure 6 Hydrodynamic Liquid Metal Bearing Adoption Curve in High-Tier CT Systems 30
Figure 7 Global Medical X-ray Tube Revenue Distribution by Clinical Modality (2026) 35
Figure 8 OEM vs. Aftermarket Revenue Velocity Discrepancy Index (2021-2031) 46
Figure 9 Global Diagnostic Fleet Average Age vs. Replacement Rate Index (2026) 48
Figure 10 Medical X-ray Tube Regional Market Share Distribution (2026 vs. 2031) 50
Figure 11 United States Medical X-ray Tube Sourcing Dependency Profile (2026) 53
Figure 12 Western European Diagnostic Fleet Imaging Load and Replacement Curve 56
Figure 13 China Medical X-ray Tube Localization Rate Projection (2021-2031) 63
Figure 14 Global Medical X-ray Tube Supplier Concentration Curve: HHI Index (2021-2026) 71
Figure 15 Varex Imaging Corporation Medical X-ray Tube Market Share Trajectory (2021-2026) 78
Figure 16 IAE S.p.A. Medical X-ray Tube Market Share Trajectory (2021-2026) 82
Figure 17 iRay Technology Medical X-ray Tube Market Share Trajectory (2021-2026) 86
Figure 18 Kunshan YiYuan Medical Technology Medical X-ray Tube Market Share Trajectory (2021-2026) 90
Figure 19 Hangzhou Wandong Electron Medical X-ray Tube Market Share Trajectory (2021-2026) 94
Figure 20 Coronas Medical Equipment Medical X-ray Tube Market Share Trajectory (2021-2026) 98
Figure 21 Wuxi Guochen Medical Technology Medical X-ray Tube Market Share Trajectory (2021-2026) 102
Figure 22 X-RAY WorX GmbH Medical X-ray Tube Market Share Trajectory (2021-2026) 106
Figure 23 GE HealthCare Medical X-ray Tube Operations Global Market Share (2021-2026) 110
Figure 24 Siemens Healthineers Medical X-ray Tube Operations Global Market Share (2021-2026) 114
Figure 25 Philips Healthcare Medical X-ray Tube Operations Global Market Share (2021-2026) 118
Figure 26 Canon Medical Systems Medical X-ray Tube Operations Global Market Share (2021-2026) 122
Figure 27 Fujifilm Healthcare Medical X-ray Tube Operations Global Market Share (2021-2026) 126
Figure 28 United Imaging Healthcare Medical X-ray Tube Operations Market Share (2021-2026) 130
Figure 29 Angell Technology Medical X-ray Tube Deployment Share (2021-2026) 134
Research Methodology
- Market Estimated Methodology:
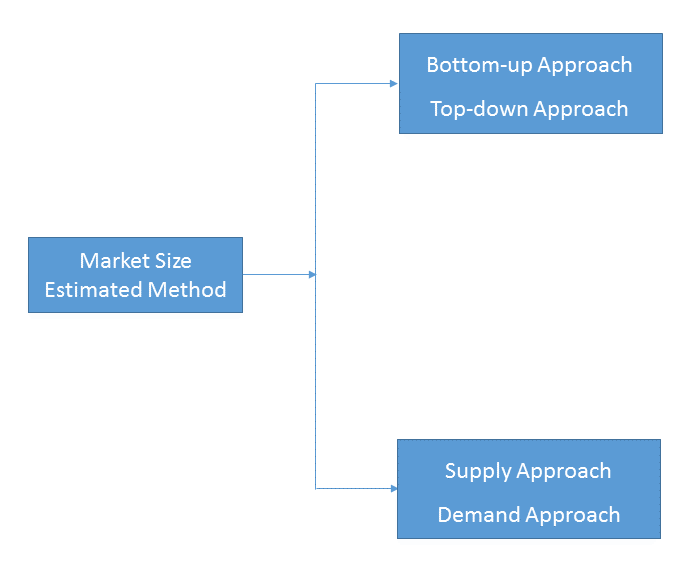
Bottom-up & top-down approach, supply & demand approach are the most important method which is used by HDIN Research to estimate the market size.
1)Top-down & Bottom-up Approach
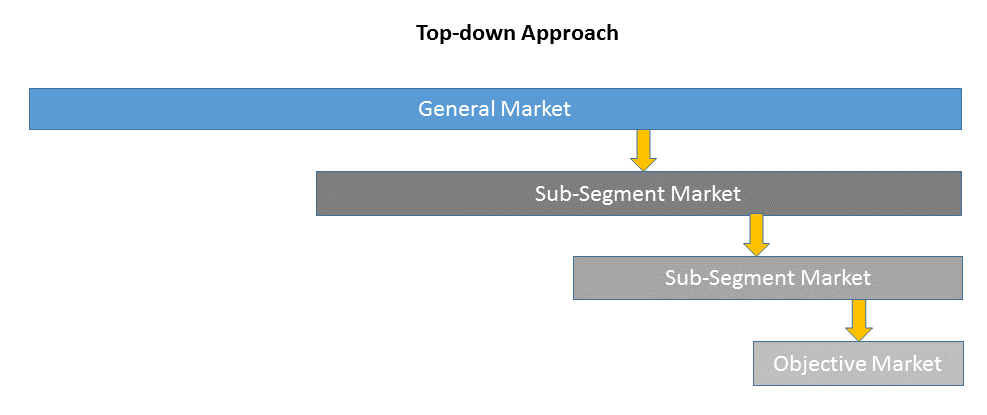
Top-down approach uses a general market size figure and determines the percentage that the objective market represents.
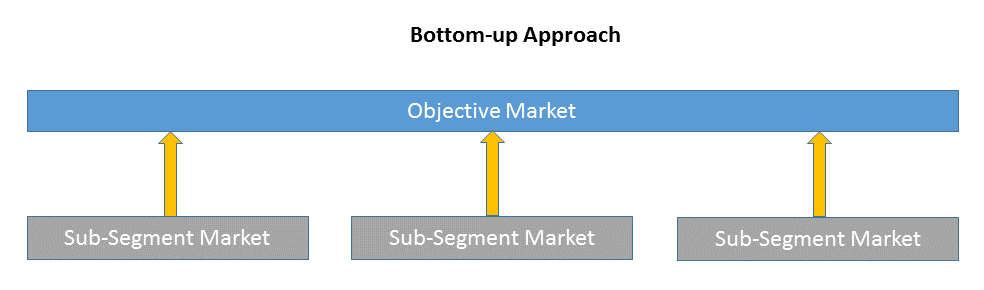
Bottom-up approach size the objective market by collecting the sub-segment information.
2)Supply & Demand Approach
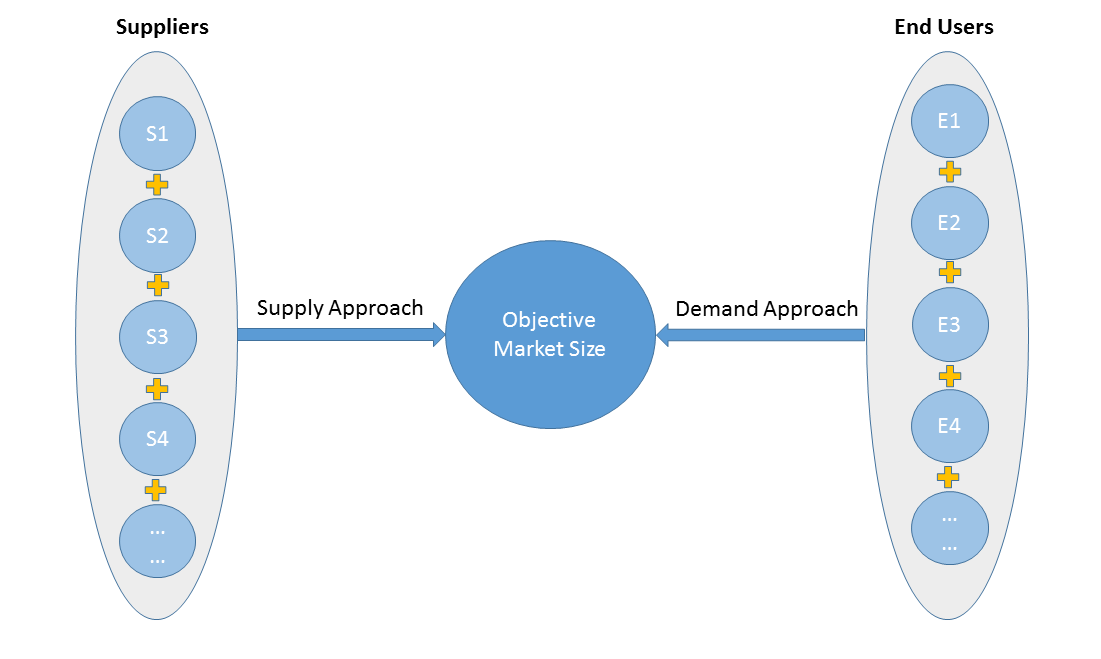
Supply approach is based on assessments of the size of each competitor supplying the objective market.
Demand approach combine end-user data within a market to estimate the objective market size. It is sometimes referred to as bottom-up approach.
- Forecasting Methodology
- Numerous factors impacting the market trend are considered for forecast model:
- New technology and application in the future;
- New project planned/under contraction;
- Global and regional underlying economic growth;
- Threatens of substitute products;
- Industry expert opinion;
- Policy and Society implication.
- Analysis Tools
1)PEST Analysis
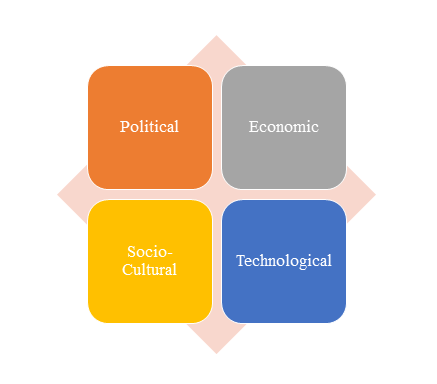
PEST Analysis is a simple and widely used tool that helps our client analyze the Political, Economic, Socio-Cultural, and Technological changes in their business environment.
- Benefits of a PEST analysis:
- It helps you to spot business opportunities, and it gives you advanced warning of significant threats.
- It reveals the direction of change within your business environment. This helps you shape what you’re doing, so that you work with change, rather than against it.
- It helps you avoid starting projects that are likely to fail, for reasons beyond your control.
- It can help you break free of unconscious assumptions when you enter a new country, region, or market; because it helps you develop an objective view of this new environment.
2)Porter’s Five Force Model Analysis
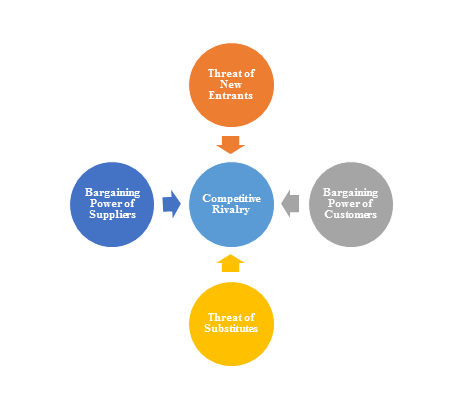
The Porter’s Five Force Model is a tool that can be used to analyze the opportunities and overall competitive advantage. The five forces that can assist in determining the competitive intensity and potential attractiveness within a specific area.
- Threat of New Entrants: Profitable industries that yield high returns will attract new firms.
- Threat of Substitutes: A substitute product uses a different technology to try to solve the same economic need.
- Bargaining Power of Customers: the ability of customers to put the firm under pressure, which also affects the customer's sensitivity to price changes.
- Bargaining Power of Suppliers: Suppliers of raw materials, components, labor, and services (such as expertise) to the firm can be a source of power over the firm when there are few substitutes.
- Competitive Rivalry: For most industries the intensity of competitive rivalry is the major determinant of the competitiveness of the industry.
3)Value Chain Analysis
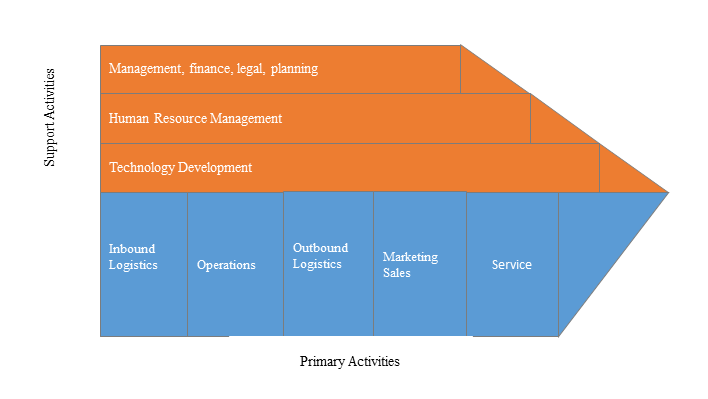
Value chain analysis is a tool to identify activities, within and around the firm and relating these activities to an assessment of competitive strength. Value chain can be analyzed by primary activities and supportive activities. Primary activities include: inbound logistics, operations, outbound logistics, marketing & sales, service. Support activities include: technology development, human resource management, management, finance, legal, planning.
4)SWOT Analysis
SWOT analysis is a tool used to evaluate a company's competitive position by identifying its strengths, weaknesses, opportunities and threats. The strengths and weakness is the inner factor; the opportunities and threats are the external factor. By analyzing the inner and external factors, the analysis can provide the detail information of the position of a player and the characteristics of the industry.
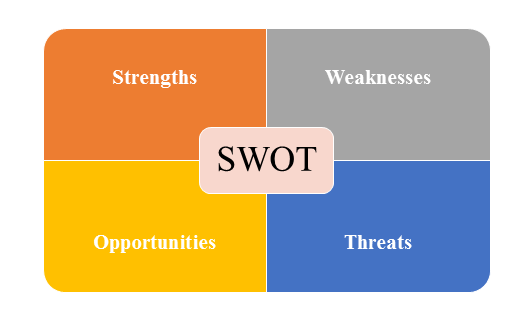
- Strengths describe what the player excels at and separates it from the competition
- Weaknesses stop the player from performing at its optimum level.
- Opportunities refer to favorable external factors that the player can use to give it a competitive advantage.
- Threats refer to factors that have the potential to harm the player.
- Data Sources
| Primary Sources | Secondary Sources |
|---|---|
| Face to face/Phone Interviews with market participants, such as: Manufactures; Distributors; End-users; Experts. Online Survey |
Government/International Organization Data: Annual Report/Presentation/Fact Book Internet Source Information Industry Association Data Free/Purchased Database Market Research Report Book/Journal/News |