Superconducting Magnet for Medical MRI Market Analysis
- Single User License (1 Users) $ 3,500
- Team License (2~5 Users) $ 4,500
- Corporate License (>5 Users) $ 5,500
The medical magnetic resonance imaging (MRI) superconducting magnet represents a critical capital- and technology-intensive node within the diagnostic imaging hardware ecosystem. Accounting for approximately 50% of the aggregate manufacturing bill-of-materials for an MRI core subsystem—encompassing the magnet, gradient assembly, and radiofrequency chain—these components define the clinical resolution, siting footprint, and total lifecycle economics of modern scanners. The global superconducting magnet for medical MRI market size is valued between 1.8 billion and 2.8 billion USD in 2026 and is projected to expand at a compound annual growth rate (CAGR) of 4.2% to 5.8% through 2031.
Superconducting MRI represent more than 90% of the worldwide diagnostic MRI installed base, having marginalized permanent and resistive magnet topologies due to field stability and signal-to-noise requirements. There are two converging factors for medical MRI market: an acute geopolitical and logistical vulnerability in the liquid helium supply chain, and the rapid deployment of conduction-cooled and micro-channel sealed architectures that dismantle long-standing civil engineering barriers.
The baseline value creation of superconducting magnet is concentrated in mid-to-high field strengths:
- The sub-1.5T segment accounts for specialized interventional systems, extremity units, and legacy open platforms.
- The 1.5T workhorse segment captures between 50% and 55% of global unit volume, sustained by broad reimbursement coverage and high clinical throughput.
- The 3.0T ultra-high-field category represents between 35% and 40% of hardware value generation, driven by diffusion, functional, and spectroscopic imaging protocols.
- The extreme-field research and whole-body tier (>3.0T, including 5.0T, 7.0T, and preclinical 9.4T systems) constitutes a high-margin, low-volume segment anchored by academic grants, brain initiative investments, and premium healthcare center differentiation.
Value distribution across the supply chain is heavily skewed toward proprietary intellectual property in cryogenic thermodynamic isolation, multi-filamentary superconducting wire winding precision, and active stray-field cancellation. Unit manufacturing costs range from under 200,000 USD for standard-bore 1.5T assemblies to well over 1.5 million USD for actively shielded, ultra-wide-bore 3.0T and whole-body 5.0T systems, with cryogenic packaging and superconducting wire representing the vast majority of direct material costs.
Superconducting Magnet Technical Architecture and Product Classification
1. By Magnetic Field Strength
- Low-to-Mid-Field Superconducting Magnets (<1.5T):
Operating largely between 0.5T and 1.0T, this tier encompasses dedicated extremity scanners, open C-arm form factors, and next-generation decentralized whole-body scanners. Low-field open geometries exploit hybrid iron-core electromagnetic configurations, requiring between one-tenth and one-twentieth of the cryogen inventory of legacy baths to deliver unrestricted lateral access for claustrophobic, bariatric, and real-time interventional procedures. Recent engineering pivots have seen 0.55T platforms emerge, targeting lower acoustic noise, reduced radiofrequency tissue deposition, and optimized susceptibility margins for pulmonary and gastrointestinal imaging.
- High-Field Superconducting Magnets (1.5T):
Operating at a proton Larmor frequency of approximately 63.8 MHz, 1.5T systems represent the dominant clinical asset across mature and emerging markets alike. The engineering profile strikes an optimal equilibrium among spatial resolution, signal-to-noise ratio (SNR), Specific Absorption Rate (SAR) limits, acoustic impact, and initial capital outlays. The technical standard has migrated decisively from 60 cm to 70 cm wide-bore configurations, integrated with zero-boil-off cryostats and conduction-cooled solid-state cryogen matrices.
- Ultra-High-Field Superconducting Magnets (3.0T):
Prevalent in tertiary care institutions and specialized clinical research units, 3.0T magnets operate at 127.7 MHz. These magnets deliver a twofold theoretical increase in SNR over 1.5T architectures, enabling millimeter-level micro-vascular reconstruction, dynamic functional MRI (fMRI), and high-b-value diffusion tensor imaging (DTI). Industrial production requires stringent electromagnetic tolerance control, dynamic balancing of multi-field coupling (simultaneous Lorentz stress fields, mechanical cryostat resonant vibrations, and eddy current mitigation), and heavy active shielding configurations to restrict the 5-Gauss line within standard hospital architectural footprints.
- Extreme-Field Whole-Body and Preclinical Magnets (>3T, 5.0T, 7.0T, 9.4T+):
This tier represents the physical frontier of human clinical diagnostics and preclinical molecular biology. Key milestones include whole-body 5.0T architectures, which overcome short-wavelength dielectric RF attenuation via multi-channel volume transmit arrays while conforming to standard 3.0T shielding perimeters. Human 7.0T whole-body systems (operating at 298 MHz) and small-bore preclinical platforms (such as 9.4T systems deployed for murine brain and oncology profiling) rely on specialized Niobium-Tin (Nb3Sn) coil sections alongside Niobium-Titanium (NbTi) outer windings to manage massive internal hoop stress and critical magnetic field thresholds.
2. By Cooling and Cryogen Technology
- Traditional Liquid Helium Cooled and Zero-Boil-Off (ZBO) Magnets:
Historically, superconducting coils were fully immersed in a liquid helium bath containing between 1,500 and 2,000 liters held at 4.2 Kelvin within an insulated double-walled vacuum cryostat. The modern baseline employs two-stage 4K-50K Gifford-McMahon (GM) or pulse-tube mechanical cryocoolers mounted to the recondenser assembly. These recondense evaporating helium gas back into the liquid vessel, delivering zero net boil-off under uncompromised, steady-state continuous electrical supply. However, vulnerability remains high during power loss, trans-oceanic transit, or spontaneous thermal quench events, which can deplete the entire multi-hundred-thousand-dollar helium reserve in minutes.
- Low-Helium and Sealed Micro-Cycling Magnets:
This transitional design isolates the superconducting coils from direct deep-pool submersion, routing liquid cryogen through narrow micro-channels, heat pipes, or capillary thermal siphons integrated directly into the structural winding casing. Sealed platforms permanently charge the system with minimal volumes, between 7 and 10 liters of liquid helium, hermetically sealing the circuit for its operational lifecycle. The structural benefit includes the elimination of expensive quench pipes, zero boil-off during mechanical servicing, and resilience against sudden external power failure without venting gas to the atmosphere.
- Dry, Conduction-Cooled Fully Helium-Free Magnets:
Representing a disruptive engineering paradigm, conduction-cooled architectures purge liquid cryogens from the hospital environment. Superconducting coil packages are thermally coupled via ultra-pure copper or aluminum solid-state thermal busbars directly to the multi-stage cold heads of pulse-tube or GM cryocoolers. This format eliminates helium replenishment budgets, prevents cryogenic room-pressurization hazards, enables automated remote cloud-managed ramp-up/ramp-down protocols, reduces static system weight by 30% to 50%, and lowers total siting expenditures by avoiding roof penetrations for emergency venting ducts.
3. By Aperture and Mechanical Form Factor
- Standard Bore Magnets (60 cm to 65 cm):
A solenoid layout configured to maximize homogeneous field distribution across a spherical volume (DSV) up to 50 cm. While cost-effective and compact, patient compliance is compromised by claustrophobic physical constraints and limitations when imaging bariatric or immobilized populations.
- Wide Bore Magnets (70 cm):
The global standard for 1.5T and 3.0T procurement. The 70 cm clearance mitigates claustrophobia-induced scan cancellations, facilitates pediatric docking, and enables flexible positioning of advanced surface array radiofrequency coils.
- Ultra-Wide Bore and Open Geometries (75 cm+ and Hybrid C-Arm):
A specialized engineering category designed for extreme bariatric patient access, image-guided intraoperative intervention, and radiation therapy positioning cradles. Symmetrical ultra-wide 75 cm solenoid configurations require sophisticated active shimming matrices to maintain field homogeneity under 0.1 parts per million (ppm) across the imaging field of view. Conversely, open hybrid geometries configure superconducting split coils anchored to an external iron yoke, trading higher field strength for structural patient access.
Downstream Application Verticals and Interventional Integration
The procurement and architectural design of medical superconducting magnets correspond to clinical imaging modalities and dedicated surgical applications:
1. Clinical Diagnostic Imaging
Neurology, oncology, musculoskeletal (MSK), and abdominal imaging form the baseline demand for high-throughput radiology departments. Clinical requirements necessitate robust 1.5T and 3.0T wide-bore platforms with low drift rates, rapid thermal stabilization during continuous multi-channel sequence firing, and full compatibility with low-resistance Silicon Carbide (SiC) gradient power amplifiers that dissipate large reactive mechanical forces into the magnet inner vacuum tube.
2. Surgical and Interventional Imaging (iMRI)
Intraoperative neurosurgery and image-guided percutaneous thermal ablation require specialized fringe-field geometry and wide-bore or open-axis clearances. Intraoperative setups deploy the superconducting magnet on ceiling rails or integrate dual-room sliding configurations, allowing the patient to transition between surgical sterile fields and the 5-Gauss line. The magnet must exhibit exceptional shielding against dynamic interference caused by surgical tools, robotic arms, and anesthesia apparatus operating adjacent to the bore.
3. Radiotherapy and Oncology Simulation (IGRT)
The clinical pivot toward MRI-guided linear accelerators (MR-Linac) and MRI radiation therapy planning systems requires custom superconducting magnet topologies. Central configurations include split-magnet architectures featuring a central radial gap that allows the megavoltage (MV) photon beam to cross unattenuated toward the tumor target. The magnet assembly must prevent secondary radiation backscatter from damaging internal coil windings, all while maintaining absolute spatial field uniformity to avert geometric spatial distortions that could skew target contouring.
4. Dedicated, Specialty, and Veterinary Diagnostic Imaging
Sub-segments including neonatal intensive care, localized orthopedic assessment, dental maxillofacial scanning, and high-tier veterinary diagnostics drive demand for compact, ultra-lightweight magnet platforms. The entry of dry, conduction-cooled 1.5T magnets enables direct vertical installation inside municipal outpatient clinics, veterinary trauma centers, and elevated hospital floors without structural load reinforcement or cryogen transport logistics.
Sales Channels and Commercialization Dynamics
1. Captive OEM Internal Supply Channel
Captive supply models govern more than 80% of global medical MRI superconducting magnet volume. Dominant diagnostic device conglomerates, including Siemens Healthineers, GE HealthCare, Philips, and United Imaging Healthcare, maintain proprietary, vertically integrated magnet engineering and fabrication facilities. This vertical integration protects core intellectual property in winding patterns, patent-protected cryostat insulation, and system-level resonance tuning, preventing tier-one system margins from leaking to independent merchants. Internal procurement ensures guaranteed production line delivery, tightly controls field-service telemetry, and creates a high barrier to entry against standalone system assemblers.
2. Independent Merchant OEM Channel
Specialized independent magnet manufacturers supply Tier-2 and Tier-3 medical imaging brand owners, including regional manufacturers across Europe, South America, and Asia-Pacific that choose not to capitalize internal cryogenics foundries. The independent merchant transaction model operates via multi-year strategic procurement master service agreements, joint engineering design-in programs, and co-development ventures. Merchant vendors must build agile production facilities capable of delivering multiple field strengths, custom cryostat outer diameters, and pre-integrated shim-coil envelopes to accommodate diverse third-party gantry enclosures.
3. Aftermarket, Cryocooler Refurbishment, and Logistics Models
Lifecycle maintenance drives high-margin secondary revenue streams across the estimated 12-to-15-year operational lifecycle of a clinical magnet:
- Cryogen Management: Emergency ramp-down recovery, vacuum layer re-pumping, and liquid helium replenishment cycles for legacy ZBO installations.
- Mechanical Subassembly Replacement: Scheduled overhaul of cold heads (GM displacer replacements typically mandated every 20,000 to 30,000 operating hours) and helium compressor lines.
- Cold vs. Hot Logistics Arbitrage: Historically, ZBO magnets required costly cold shipping, continuously cooled with active liquid helium under air-freight schedules to avoid vacuum degradation and thermal runaway. Merchant pioneers have deployed specialized shipping cryostats with extended maritime container thermal hold times, reducing transport costs across long international corridors. Concurrently, conduction-cooled, dry magnets are shipped completely warm at ambient room temperature, removing maritime hazardous material shipping restrictions and enabling non-specialized surface transport.
Supply Chain and Value Chain Architecture
1. Upstream Tier: Critical Raw Materials and Subcomponents
The bill-of-materials foundation relies on metallurgical and thermodynamic engineering:
- Superconducting Wire: Precision multi-filamentary composite wire consisting of continuous ductile Niobium-Titanium (NbTi) filaments embedded within a high-conductivity Oxygen-Free High Thermal Conductivity (OFHC) copper matrix. Ultra-high-field systems incorporate brittle Niobium-Tin (Nb3Sn) intermetallic strands, which require complex post-winding vacuum heat-treatment at temperatures approaching 650 to 700 degrees Celsius to form the A15 superconducting crystal phase. Wire quality directly governs persistent current decay rates and drift performance.
- Raw Cryogens: Ultra-high-purity Grade 5 to Grade 6 liquid helium sourced from targeted natural gas extraction fields across the United States, Qatar, Algeria, and the Russian Federation. Helium extraction volatility makes access a key variable in manufacturing cost structures.
- Cryocoolers and Vacuum Vessels: High-reliability two-stage 4K cold-heads, variable-frequency helium compressors, non-magnetic stainless steel (AISI 316L/316LN) forging shells, aluminum-alloy inner cold mass tanks, and multi-layer aluminized Mylar vacuum insulation blankets.
2. Midstream Tier: Magnet Manufacturing and Assembly Integration
The core value-add phase involves advanced electromagnetic manufacturing:
- Tension-Controlled Precision Winding: Continuous winding of multi-kilometer lengths of superconducting wire onto aluminum or composite bobbins under strict mechanical tension to prevent microscopic strand displacement during high-current Lorentz force loading.
- Vacuum Pressure Impregnation (VPI): Complete encapsulation of the wound coil packs using low-viscosity, radiation-resistant epoxy resins under alternating high-vacuum and pressure cycles, eliminating micro-voids that trigger frictional heating, wire motion, and subsequent thermal quench events.
- Cryogenic Packaging and Assembly: Mounting of low-heat-leak glass-fiber or carbon-fiber suspension struts capable of bearing multi-ton cold mass weights under dynamic shock loads while minimizing thermal bridging to ambient air.
- Persistent Current Switches and Shimming: Integration of thermal or magnetic superconducting switches that allow the magnet to close the circuit and function persistently with zero auxiliary power input, followed by cryogenic active shimming using iron shim matrices and superconducting correction coils to achieve magnetic homogeneity metrics below 0.1 ppm over the imaging volume.
3. Downstream Tier: System Integration and Diagnostic Deployment
Midstream magnet packages are handed off to medical system integrators. The magnet is married to the three-axis gradient coil assembly, body RF transmit coil, multi-channel dynamic digital receivers, and power distribution electronics. Downstream distribution terminates at tertiary hospitals, public health authorities, community imaging centers, and specialized diagnostic research laboratories worldwide.
Regional Market Dynamics and Growth Intervals
1. North America
The North American ecosystem represents a replacement-dominated, value-dense market characterized by high penetration rates of wide-bore 3.0T systems and rapid early adoption of sealed, low-helium platforms in outpatient imaging chains. Tight clinical labor markets, high installation overheads, and stringent regulatory demands emphasize platforms that eliminate quench pipe infrastructure, integrate low-siting-cost dry magnets, and offer remote digital telemetry for predictive cold-head servicing.
2. Europe
The region is driven by strict environmental protocols, aggressive energy-efficiency directives, and persistent liquid helium price volatility. Key healthcare networks across Germany, the United Kingdom, France, and the Nordic nations prioritize sustainable procurement frameworks, favoring lightweight zero-boil-off and conduction-cooled architectures that align with older hospital structural load limits. Ultra-high-field research installations remain anchored around recognized neuroscience institutes operating actively shielded 7.0T platforms.
3. Asia-Pacific
Asia-Pacific acts as the primary volume growth driver globally. China represents the largest single national market, propelled by national healthcare infrastructure policies, provincial hospital capacity building, and strong domestic manufacturing development. In tier-three and county-level hospitals, 1.5T systems continue to experience wide-scale deployment, while tier-one clinical facilities match Western institutions in 3.0T and 5.0T adoption. Japan remains a mature, high-density market leaning toward high-field wide-bore upgrades and low-noise platforms. Other markets, including India, South Korea, and Taiwan, China, exhibit sustained demand profiles driven by private diagnostic center investments, expanding public health coverage, and clinical tourism infrastructure.
4. South America
Healthcare spending is heavily focused in major metropolitan regions across Brazil, Argentina, and Colombia. The market is primarily served by 1.5T remanufactured and entry-level new platforms. Logistics-resistant, low-maintenance, and low-helium magnet systems hold a strategic advantage here, overcoming volatile long-distance cryogen supply routes and variable regional transport infrastructure.
5. Middle East and Africa (MEA)
The MEA region is characterized by a polarized demand model. Gulf Cooperation Council (GCC) nations, notably Saudi Arabia and the United Arab Emirates, procure top-tier 3.0T wide-bore and specialized ultra-high-field platforms, integrating them into new hospital facilities. Conversely, broader African markets rely on robust, high-stability 1.5T magnets capable of withstanding unpredictable grid power supplies and localized helium import delays, positioning dry, conduction-cooled and micro-cycling magnet platforms as viable options for long-term clinical deployment.
Competitive Profiles: In-House OEM Divisions and Merchant Manufacturers
1. In-House Captive Superconducting Magnet Divisions
- GE HealthCare
Strategic Trajectory and Technology Portfolio: GE HealthCare retains full vertical control over magnet manufacturing, anchoring its portfolio around clinical zero-boil-off 1.5T and 3.0T wide-bore architectures. The organization pioneered the Freelium sealed magnet platform, targeting sealed-for-life low-cryogen containment to bypass conventional quench pipe ducting and eliminate routine helium refills. GE HealthCare has fortified its ultra-high-field research position through the deployment of the whole-body actively shielded 7.0T UltraG system, alongside clinical development in specialized high-gradient head-only geometries (such as the MAGNUS platform) dedicated to microstructural neuro-diagnostic tracking.
- Siemens Healthineers
Strategic Trajectory and Technology Portfolio: Siemens Healthineers maintains one of the largest dedicated medical magnet engineering operations globally through OMT. The company leads the commercial pivot toward minimal cryogen volumes via its DryCool architecture, operationalized on the 0.55T MAGNETOM Free platforms, utilizing under one liter of liquid helium sealed within a conduction-cooled enclosure with an 80 cm ultra-wide bore. In the workhorse tier, its low-helium 1.5T platforms (such as the Flow series containing approximately 0.7 liters of cryogen) challenge the traditional multi-thousand-liter ZBO model, while its 3.0T wide-bore and 7.0T Terra and Terra.X platforms set technical benchmarks for spatial-temporal field stability under ultra-fast multi-channel gradient switching.
- Philips
Strategic Trajectory and Technology Portfolio: Philips concentrates its competitive moat on fully sealed micro-cooling engineering, embodied in its proprietary BlueSeal magnet technology. Integrated into commercial platforms such as the MR 5300 and Ingenia Ambition 1.5T, the system utilizes approximately 7 liters of micro-circulated liquid helium permanently sealed within the cold mass casing. The assembly fully eliminates external vent pipes, insulates the clinical user from helium price volatility, and provides rapid post-quench recovery without the need for manual off-site cryogen fills. The firm also sustains conventional high-performance zero-boil-off 3.0T platforms engineered for high-order multinuclear and multi-channel functional neuro-oncology imaging.
- United Imaging Healthcare (UIH)
Strategic Trajectory and Technology Portfolio: United Imaging operates an integrated in-house magnet production infrastructure across all clinical field tiers. The enterprise industrialized the uMR Jupiter 5.0T, the world's first commercially cleared whole-body 5.0T superconducting magnet, breaking the traditional 3.0T ceiling for systemic abdominal, cardiac, and musculoskeletal scans while fitting within standard spatial shielding clearances. UIH has expanded its mechanical portfolio through ultra-wide-bore platforms, engineering the 75 cm aperture uMR Omega 3.0T magnet with wide field-of-view capabilities for bariatric and radiation planning access, alongside high-volume zero-boil-off 1.5T workhorses and preclinical small-bore 9.4T systems.
- Neusoft Medical Systems
Strategic Trajectory and Technology Portfolio: Neusoft Medical Systems integrates in-house cryogenic magnet fabrication with domestic academic collaborations to supply accessible clinical platforms. The company produces the 1.5T zero-boil-off assemblies that power its NeuMR series, leveraging closed-loop 4K GM cryocoolers to maintain zero helium losses under uninterrupted run conditions. Neusoft is actively commercializing wide-bore 70 cm 3.0T clinical platforms, while prioritizing the development of conduction-cooled and minimal-cryogen architectures to capture regional and county-level hospital equipment upgrade cycles across domestic and emerging international territories.
2. Independent Third-Party Merchant Magnet Manufacturers
- Japan Superconductor Technology Inc. (JASTEC)
Headquarters: Kobe, Japan (Subsidiary of Kobe Steel, Ltd.).
Strategic Trajectory and Technology Portfolio: JASTEC operates as an established independent manufacturer of high-performance superconducting wires (NbTi, Nb3Sn) and fully integrated magnet systems. JASTEC supplies third-party clinical MRI integrators with high-stability 1.5T and 3.0T zero-boil-off magnet configurations, offering low drift rates and precision active-shield design. Beyond clinical whole-body assemblies, JASTEC dominates the ultra-high-resolution nuclear magnetic resonance (NMR) spectrometer ecosystem, providing extreme-field persistent magnet architectures reaching up to 1.0 GHz+ (23.5T+) for molecular structural biology and advanced materials characterization.
- Ningbo Jansen Superconducting Technologies Co. Ltd.
Headquarters: Ningbo, Zhejiang, China.
Strategic Trajectory and Technology Portfolio: Ningbo Jansen is an independent merchant developer specializing in medical MRI magnets, supplying domestic and international system integrators lacking captive magnet manufacturing capacity. The firm achieved a commercial milestone with the industrial release of an independent 1.5T liquid-helium-free, fully conduction-cooled superconducting magnet, utilizing high-efficiency mechanical cryocoolers and thermal conductive busbars to eliminate the liquid cryogen bath, quench pipe requirements, and related infrastructural burdens. Jansen also manufactures zero-boil-off 1.5T and 3.0T wide-bore clinical magnets, dedicated orthopedic extremity magnets, and high-field research magnets developed alongside academic institutions such as the Chinese Academy of Sciences.
- Shanghai Chenguang Medical Technologies Co. LTD
Headquarters: Shanghai, China.
Strategic Trajectory and Technology Portfolio: Shanghai Chenguang Medical is a publicly listed developer of core MRI hardware subassemblies, encompassing superconducting magnets, gradient assemblies, and specialized radiofrequency coils. The enterprise manufactures standard and wide-bore 1.5T and 3.0T zero-boil-off clinical magnets configured with integrated 4K recondensing units and tight 5-Gauss active-shield envelopes. Chenguang is advancing conduction-cooled, liquid-helium-free magnet topologies to serve decentralized diagnostic centers, while fabricating 7.0T preclinical research systems and dedicated high-field extremity magnets for advanced orthopedic and veterinary applications.
1.1 Research Framework and Market Definition 1
1.2 Primary Research and Industry Validation Framework 2
1.3 Secondary Data Filtration and Triangulation Models 3
1.4 Bottom-Up and Top-Down Market Sizing Methodologies 4
1.5 Macroeconomic, Cryogen Supply and Forecasting Assumptions 5
1.6 Abbreviations and Specialized Acronyms 6
Chapter 2 Global MRI Superconducting Magnet Industry Architecture and Value Chain 7
2.1 End-to-End Value Chain Structural Decomposition 7
2.2 Upstream Raw Materials: Niobium-Titanium (NbTi), Nb3Sn and High-Temperature Superconducting (HTS) Wire Sourcing 8
2.3 Liquid Helium Global Supply Vulnerability, SMR Recondensation and Cryogenic Stability 10
2.4 Precision Component Fabrication: Vacuum Cryostats, Thermal Radiation Shields and Shimming Systems 11
2.5 Industry Cost Breakdown: Raw Material, Cryogenic Assembly, Testing and Margin Distribution 12
Chapter 3 Global Superconducting Magnet for Medical MRI Market by Magnetic Field Strength 14
3.1 Technology Trajectory and Field-Strength Transition Dynamics 14
3.2 <1.5T Low-Field Superconducting Magnets: Market Volume (Units) and Market Size (USD Million), 2021-2031 15
3.3 1.5T Mainstream Clinical Superconducting Magnets: Market Volume (Units) and Market Size (USD Million), 2021-2031 16
3.4 3T High-Field Diagnostic Superconducting Magnets: Market Volume (Units) and Market Size (USD Million), 2021-2031 18
3.5 >3T Ultra-High Field Clinical and Research Magnets: Market Volume (Units) and Market Size (USD Million), 2021-2031 19
Chapter 4 Global Superconducting Magnet for Medical MRI Market by Cooling & Cryogen Technology 21
4.1 Cryogenic Management Shift: From Deep Immersion to Zero-Evaporation Architectures 21
4.2 Liquid Helium Cooled Magnets (Open and Standard Boil-Off Systems): Market Volume and Value, 2021-2031 22
4.3 Low-Helium / Sealed Micro-Cycling Magnets: Market Volume and Value, 2021-2031 24
4.4 Dry / Conduction-Cooled Fully Helium-Free Magnets: Market Volume and Value, 2021-2031 26
Chapter 5 Global Superconducting Magnet for Medical MRI Market by Sales Channel 28
5.1 Procurement Dynamics: OEM Integration versus Field Replacement Cycles 28
5.2 Original Equipment Manufacturer (OEM) Direct Integration: Sales Volume and Revenue, 2021-2031 29
5.3 Aftermarket Upgrades & Replacement Magnet Infrastructure: Sales Volume and Revenue, 2021-2031 31
Chapter 6 Global Superconducting Magnet for Medical MRI Market by Application 33
6.1 Downstream Modality Alignment and Clinical Utility Profiles 33
6.2 General Radiography (DR) Complementary Diagnostic Platforms: Volume and Value, 2021-2031 34
6.3 Dedicated Breast / Mammography Systems: Volume and Value, 2021-2031 35
6.4 Dental Imaging and Craniofacial Configurations: Volume and Value, 2021-2031 36
6.5 Surgical & Interventional Imaging (Intraoperative MRI Suites): Volume and Value, 2021-2031 37
6.6 Radiotherapy & Oncology (MR-Guided Radiotherapy / IGRT): Volume and Value, 2021-2031 38
6.7 Veterinary Diagnostic Imaging Systems: Volume and Value, 2021-2031 39
Chapter 7 Global Production Hubs, Cross-Border Logistics and Trade Flow Dynamics 41
7.1 Global Superconducting Magnet Manufacturing Concentration and Capacity Deployment 41
7.2 Core Exporting Nations: Production Surpluses and Cross-Border Outflows 42
7.3 Core Importing Markets: System Assembly Hubs and Clinical Demand Centers 43
7.4 Cryogenic Logistics, Pressurized Cold-Chain Transport and Quench Risk Management 44
7.5 Tariff Classifications, Dual-Use Material Regulations and Import Compliance 45
Chapter 8 Regional Consumption and Production Breakdown: North America and Europe 47
8.1 North America Superconducting Magnet Market Dynamics 47
8.1.1 United States: Production Output, Clinical Installations and Technology Upgrades 48
8.1.2 Canada: Secondary Demand Patterns and Healthcare System Procurement 50
8.2 Europe Superconducting Magnet Market Dynamics 51
8.2.1 Germany: Precision Cryogenic Engineering and OEM Manufacturing Hub 52
8.2.2 United Kingdom: Specialized Superconducting Research and Magnet Assembly 53
8.2.3 Netherlands: High-Field Diagnostic System Integration and Export Balance 54
8.2.4 Rest of Europe Market 55
Chapter 9 Regional Consumption and Production Breakdown: Asia-Pacific, Latin America, Middle East & Africa 56
9.1 Asia-Pacific Superconducting Magnet Market Dynamics 56
9.1.1 China: Domestic Supply Substitution, Indigenous Production Hubs and Healthcare Scaling 57
9.1.2 Japan: Advanced Wire Metallurgy, Superconducting Magnet Component Output 60
9.1.3 South Korea: High-End Hospital Diagnostic Procurement and Imaging Assembly 61
9.2 Latin America Market Consumption Overview 62
9.3 Middle East & Africa Healthcare Modernization and Magnet Demand 64
Chapter 10 Competitive Architecture and Global Vendor Positioning 66
10.1 Global Market Share Matrix: Merchant Magnet Suppliers versus Captive In-House OEM Divisions 66
10.2 Merchant-to-OEM Dependency Analysis and Integration Bottlenecks 67
10.3 Intellectual Property Landscapes, Patent Horizons and Cryogenic Shielding Barriers 69
Chapter 11 Corporate Intelligence: Commercial Merchant Magnet Suppliers 71
11.1 Shanghai Chenguang Medical Technologies Co. LTD 71
11.1.1 Corporate Profile and Superconducting Magnet Footprint 71
11.1.2 Product Matrix and Technical Benchmark Specifications 72
11.1.3 SWOT Strategic Assessment 72
11.1.4 Product-Specific Operational Metrics: Sales Volume, Revenue, Price, Cost and Gross Margin 73
11.1.5 Technological R&D Pipeline and Global GTM Strategy 74
11.2 Ningbo Jansen Superconducting Technologies Co. Ltd 75
11.2.1 Corporate Profile and Industrial Infrastructure 75
11.2.2 Product Matrix and Field-Strength Capabilities 76
11.2.3 SWOT Strategic Assessment 76
11.2.4 Product-Specific Operational Metrics: Sales Volume, Revenue, Price, Cost and Gross Margin 77
11.2.5 Manufacturing Scale, Cryostat Innovations and Customer Base 78
11.3 Japan Superconductor Technology Inc. 79
11.3.1 Corporate Profile and Superconducting Metallurgy Heritage 79
11.3.2 Product Matrix and Ultra-High Field Coil Configurations 80
11.3.3 SWOT Strategic Assessment 80
11.3.4 Product-Specific Operational Metrics: Sales Volume, Revenue, Price, Cost and Gross Margin 81
11.3.5 International Supply Contracts and Material Advancement Programs 82
Chapter 12 Corporate Intelligence: In-House Magnet Divisions of Global OEM Giants 83
12.1 GE HealthCare (Magnet Manufacturing Division) 83
12.1.1 Corporate Overview and In-House Cryogenic Asset Base (Florence Facility) 83
12.1.2 Magnet Portfolio, Sealed Cryogen Developments and Clinical Deployment 83
12.1.3 SWOT Strategic Assessment 84
12.1.4 Magnet Division Operational Metrics: Captive Sales Volume, Imputed Price, Production Cost, Margin and Share 84
12.1.5 Strategic R&D Trajectory and Platform Modernization 85
12.2 Siemens Healthineers (Magnet Technology Division) 86
12.2.1 Corporate Overview and Integrated Magnet Production Facilities (Oxford Center) 86
12.2.2 Low-Helium DryCool Technology Infrastructure and Platform Capabilities 86
12.2.3 SWOT Strategic Assessment 87
12.2.4 Magnet Division Operational Metrics: Captive Sales Volume, Imputed Price, Production Cost, Margin and Share 87
12.2.5 Strategic Technology Roadmap and Fleet Decarbonization 88
12.3 Philips (Cryomagnetics Division) 89
12.3.1 Corporate Overview and Specialized Magnet Manufacturing Base 89
12.3.2 Micro-Cooling BlueSeal Technology Ecosystem and Fielded Platforms 89
12.3.3 SWOT Strategic Assessment 90
12.3.4 Magnet Division Operational Metrics: Captive Sales Volume, Imputed Price, Production Cost, Margin and Share 90
12.3.5 Sustainability Directives and Next-Generation Bore Architecture 91
12.4 United Imaging (Superconducting Magnet Division) 92
12.4.1 Corporate Overview and Vertically Integrated Production Architecture (Changzhou Base) 92
12.4.2 Magnet System Matrix: From Clinical 1.5T/3.0T to Ultra-High Field 5.0T Platforms 92
12.4.3 SWOT Strategic Assessment 93
12.4.4 Magnet Division Operational Metrics: Captive Sales Volume, Imputed Price, Production Cost, Margin and Share 93
12.4.5 Domestic Supply Chain Consolidation and Global Market Expansion 94
12.5 Neusoft Medical Systems (Superconducting Magnet Technology Center) 95
12.5.1 Corporate Overview and Core Magnet Production Assets 95
12.5.2 Value-Tier and Mainstream Clinical Magnet Deployments 95
12.5.3 SWOT Strategic Assessment 96
12.5.4 Magnet Division Operational Metrics: Captive Sales Volume, Imputed Price, Production Cost, Margin and Share 96
12.5.5 Sourcing Optimization, Dual-Distribution and Expansion Strategy 97
Table 2 Raw Material Cost Breakdown for Superconducting MRI Magnets, 2021-2026 (USD/Unit) 13
Table 3 Global Superconducting Magnet for Medical MRI Market Volume by Field Strength, 2021-2031 (Units) 14
Table 4 Global Superconducting Magnet for Medical MRI Market Size by Field Strength, 2021-2031 (USD Million) 15
Table 5 Global <1.5T Superconducting Magnet Market Volume and Value by Region, 2021-2031 16
Table 6 Global 1.5T Superconducting Magnet Market Volume and Value by Region, 2021-2031 17
Table 7 Global 3T Superconducting Magnet Market Volume and Value by Region, 2021-2031 18
Table 8 Global >3T Superconducting Magnet Market Volume and Value by Region, 2021-2031 20
Table 9 Global Superconducting Magnet for Medical MRI Market Volume by Cooling Technology, 2021-2031 (Units) 21
Table 10 Global Superconducting Magnet for Medical MRI Market Size by Cooling Technology, 2021-2031 (USD Million) 22
Table 11 Global Liquid Helium Cooled Magnet Market Volume and Value by Region, 2021-2031 23
Table 12 Global Low-Helium / Sealed Micro-Cycling Magnet Market Volume and Value by Region, 2021-2031 25
Table 13 Global Dry / Conduction-Cooled Helium-Free Magnet Market Volume and Value by Region, 2021-2031 27
Table 14 Global Superconducting Magnet for Medical MRI Market Volume by Sales Channel, 2021-2031 (Units) 28
Table 15 Global Superconducting Magnet for Medical MRI Market Size by Sales Channel, 2021-2031 (USD Million) 29
Table 16 Global OEM Sales Channel Market Volume and Value by Region, 2021-2031 30
Table 17 Global Aftermarket & Replacement Sales Channel Market Volume and Value by Region, 2021-2031 32
Table 18 Global Superconducting Magnet Market Volume by Downstream Application, 2021-2031 (Units) 33
Table 19 Global Superconducting Magnet Market Size by Downstream Application, 2021-2031 (USD Million) 34
Table 20 Superconducting Magnets for General Radiography (DR) Hybrid Systems: Volume and Value, 2021-2031 35
Table 21 Superconducting Magnets for Mammography Systems: Volume and Value, 2021-2031 36
Table 22 Superconducting Magnets for Dental Imaging Systems: Volume and Value, 2021-2031 37
Table 23 Superconducting Magnets for Surgical & Interventional Imaging Suites: Volume and Value, 2021-2031 38
Table 24 Superconducting Magnets for Radiotherapy & Oncology (IGRT): Volume and Value, 2021-2031 39
Table 25 Superconducting Magnets for Veterinary Diagnostic Imaging: Volume and Value, 2021-2031 40
Table 26 Major Superconducting Magnet Manufacturing Facilities and Annual Capacity, 2026 42
Table 27 Global Cross-Border Trade Flows of Medical Superconducting Magnets, 2021-2026 (Units) 44
Table 28 North America Superconducting Magnet Market Volume and Value by Field Strength, 2021-2031 48
Table 29 United States Superconducting Magnet Production, Import, Export and Consumption, 2021-2031 49
Table 30 Europe Superconducting Magnet Market Volume and Value by Field Strength, 2021-2031 51
Table 31 Germany Superconducting Magnet Production, Import, Export and Consumption, 2021-2031 53
Table 32 United Kingdom Superconducting Magnet Production, Import, Export and Consumption, 2021-2031 54
Table 33 Netherlands Superconducting Magnet System Integration and Trade Volume, 2021-2031 55
Table 34 Asia-Pacific Superconducting Magnet Market Volume and Value by Field Strength, 2021-2031 57
Table 35 China Superconducting Magnet Production Output, OEM Integration and Trade Flows, 2021-2031 59
Table 36 Japan Superconducting Magnet Wire Consumption, Production and Net Exports, 2021-2031 60
Table 37 South Korea Clinical Superconducting Magnet Consumption, 2021-2031 62
Table 38 Latin America Superconducting Magnet Imports and Consumption Value, 2021-2031 63
Table 39 Middle East & Africa Superconducting Magnet Imports and Consumption Value, 2021-2031 65
Table 40 Global Superconducting Magnet Manufacturer Market Share Matrix, 2021-2026 (Sales Volume Basis) 67
Table 41 Global Superconducting Magnet Manufacturer Revenue Share Matrix, 2021-2026 (USD Million) 68
Table 42 Shanghai Chenguang Medical Technologies Superconducting Magnet Sales, Price, Cost and Gross Profit Margin (2021-2026) 73
Table 43 Ningbo Jansen Superconducting Technologies Superconducting Magnet Sales, Price, Cost and Gross Profit Margin (2021-2026) 77
Table 44 Japan Superconductor Technology Superconducting Magnet Sales, Price, Cost and Gross Profit Margin (2021-2026) 81
Table 45 GE HealthCare Superconducting Magnet Division Sales, Imputed Price, Production Cost and Gross Profit Margin (2021-2026) 85
Table 46 Siemens Healthineers Magnet Technology Division Sales, Imputed Price, Production Cost and Gross Profit Margin (2021-2026) 88
Table 47 Philips Cryomagnetics Division Sales, Imputed Price, Production Cost and Gross Profit Margin (2021-2026) 91
Table 48 United Imaging Superconducting Magnet Division Sales, Imputed Price, Production Cost and Gross Profit Margin (2021-2026) 94
Table 49 Neusoft Medical Systems Superconducting Magnet Sales, Imputed Price, Production Cost and Gross Profit Margin (2021-2026) 97
Figure 1 Global Medical MRI Superconducting Magnet Market Size Forecast (USD Million), 2021-2031 2
Figure 2 End-to-End Value Chain Map and Strategic Value Addition Nodes 8
Figure 3 Global Medical Liquid Helium Sourcing Volume and Price Index Trend (2021-2031) 10
Figure 4 Global Superconducting Magnet Unit Sales Share by Field Strength (2021, 2026, 2031) 15
Figure 5 Global Superconducting Magnet Market Value Share by Field Strength (2026) 19
Figure 6 Global Adoption Trajectory: Liquid Helium vs. Low-Helium vs. Conduction-Cooled Systems (2021-2031) 22
Figure 7 Global Superconducting Magnet Revenue Breakdown by Cooling Architecture (2026) 26
Figure 8 Channel Distribution Dynamics: OEM Supply vs. Aftermarket Replacement (2021-2031) 29
Figure 9 Application Revenue Distribution of Superconducting Magnets (2026) 34
Figure 10 Global Production Hubs and Export Corridors for MRI Superconducting Magnets (2026) 41
Figure 11 United States Medical Superconducting Magnet Volume vs. Value Evolution (2021-2031) 49
Figure 12 European Superconducting Magnet Consumption Breakdown by Core Country (2026) 52
Figure 13 China Superconducting Magnet Domestic Substitution Rate (2021-2031) 58
Figure 14 Asia-Pacific Superconducting Magnet Market Sizing Trajectory (2021-2031) 61
Figure 15 Global Market Concentration Index: In-House Captive vs. Merchant Manufacturers (2021-2026) 66
Figure 16 Shanghai Chenguang Medical Technologies Superconducting Magnet Market Share (2021-2026) 74
Figure 17 Ningbo Jansen Superconducting Technologies Superconducting Magnet Market Share (2021-2026) 78
Figure 18 Japan Superconductor Technology Superconducting Magnet Market Share (2021-2026) 82
Figure 19 GE HealthCare Superconducting Magnet Market Share (2021-2026) 85
Figure 20 Siemens Healthineers Superconducting Magnet Market Share (2021-2026) 88
Figure 21 Philips Superconducting Magnet Market Share (2021-2026) 91
Figure 22 United Imaging Superconducting Magnet Market Share (2021-2026) 94
Figure 23 Neusoft Medical Systems Superconducting Magnet Market Share (2021-2026) 97
Research Methodology
- Market Estimated Methodology:
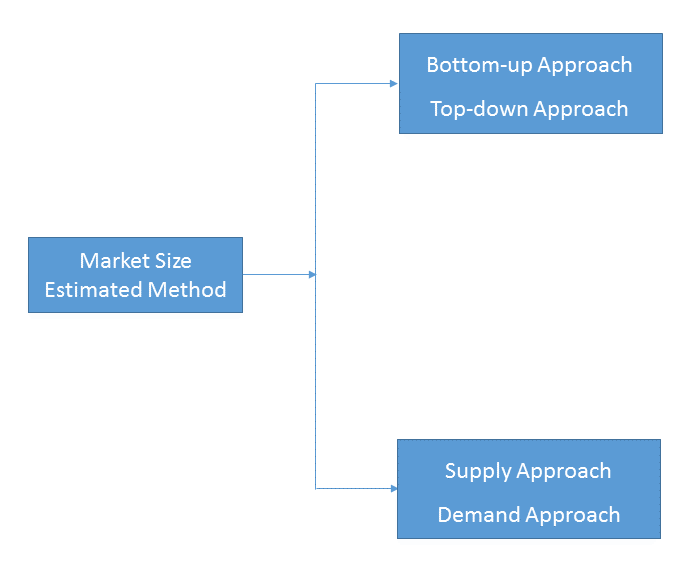
Bottom-up & top-down approach, supply & demand approach are the most important method which is used by HDIN Research to estimate the market size.
1)Top-down & Bottom-up Approach
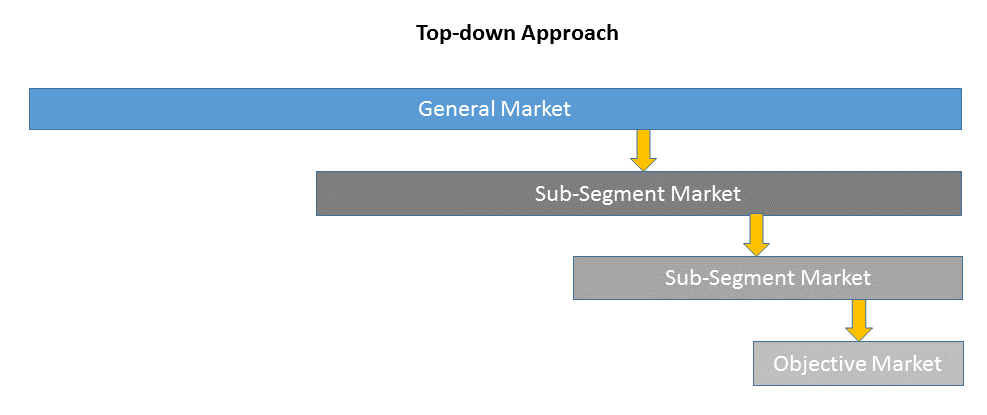
Top-down approach uses a general market size figure and determines the percentage that the objective market represents.
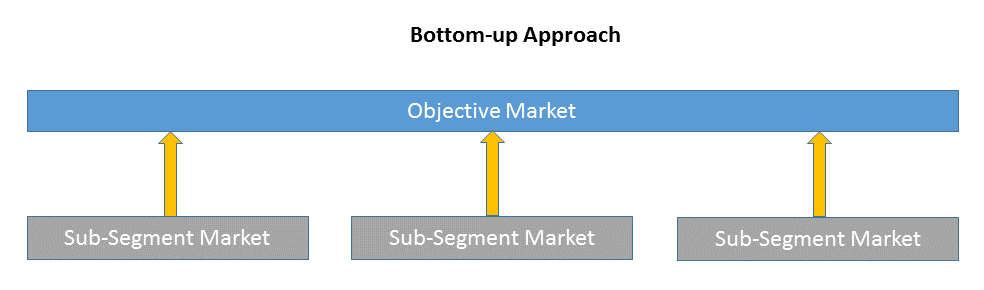
Bottom-up approach size the objective market by collecting the sub-segment information.
2)Supply & Demand Approach
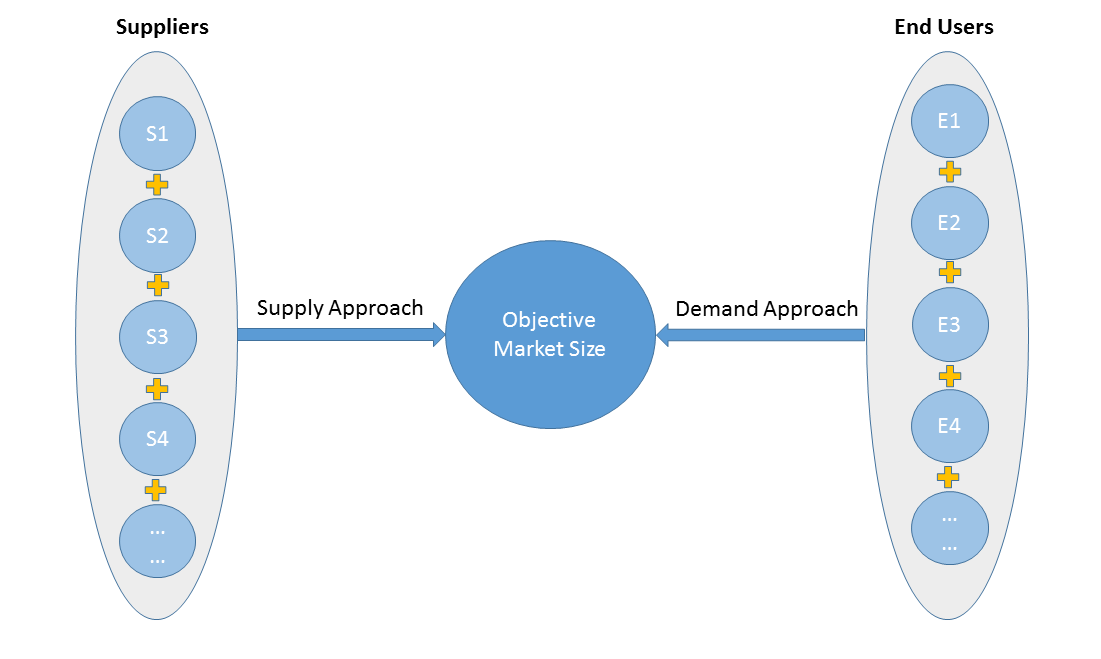
Supply approach is based on assessments of the size of each competitor supplying the objective market.
Demand approach combine end-user data within a market to estimate the objective market size. It is sometimes referred to as bottom-up approach.
- Forecasting Methodology
- Numerous factors impacting the market trend are considered for forecast model:
- New technology and application in the future;
- New project planned/under contraction;
- Global and regional underlying economic growth;
- Threatens of substitute products;
- Industry expert opinion;
- Policy and Society implication.
- Analysis Tools
1)PEST Analysis
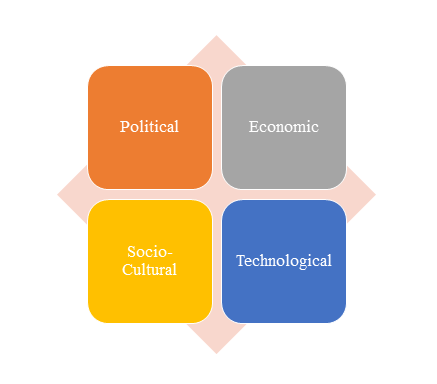
PEST Analysis is a simple and widely used tool that helps our client analyze the Political, Economic, Socio-Cultural, and Technological changes in their business environment.
- Benefits of a PEST analysis:
- It helps you to spot business opportunities, and it gives you advanced warning of significant threats.
- It reveals the direction of change within your business environment. This helps you shape what you’re doing, so that you work with change, rather than against it.
- It helps you avoid starting projects that are likely to fail, for reasons beyond your control.
- It can help you break free of unconscious assumptions when you enter a new country, region, or market; because it helps you develop an objective view of this new environment.
2)Porter’s Five Force Model Analysis
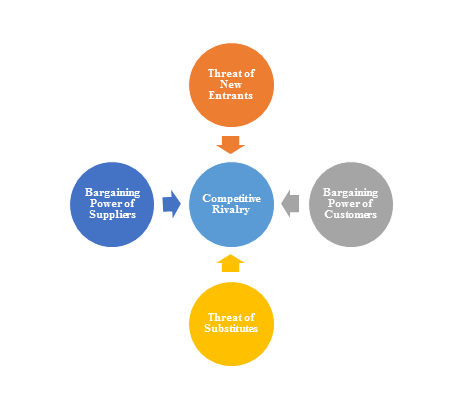
The Porter’s Five Force Model is a tool that can be used to analyze the opportunities and overall competitive advantage. The five forces that can assist in determining the competitive intensity and potential attractiveness within a specific area.
- Threat of New Entrants: Profitable industries that yield high returns will attract new firms.
- Threat of Substitutes: A substitute product uses a different technology to try to solve the same economic need.
- Bargaining Power of Customers: the ability of customers to put the firm under pressure, which also affects the customer's sensitivity to price changes.
- Bargaining Power of Suppliers: Suppliers of raw materials, components, labor, and services (such as expertise) to the firm can be a source of power over the firm when there are few substitutes.
- Competitive Rivalry: For most industries the intensity of competitive rivalry is the major determinant of the competitiveness of the industry.
3)Value Chain Analysis
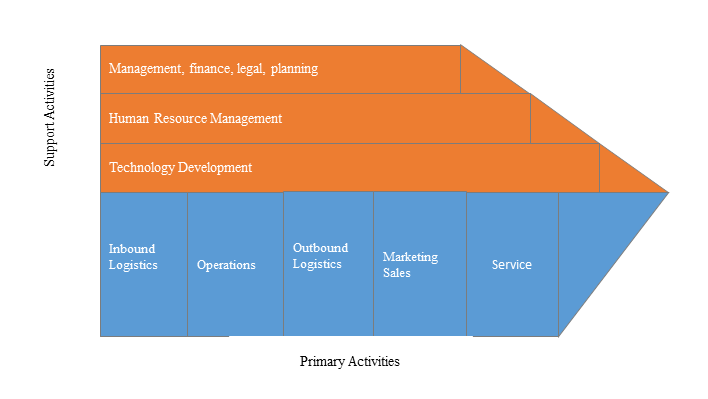
Value chain analysis is a tool to identify activities, within and around the firm and relating these activities to an assessment of competitive strength. Value chain can be analyzed by primary activities and supportive activities. Primary activities include: inbound logistics, operations, outbound logistics, marketing & sales, service. Support activities include: technology development, human resource management, management, finance, legal, planning.
4)SWOT Analysis
SWOT analysis is a tool used to evaluate a company's competitive position by identifying its strengths, weaknesses, opportunities and threats. The strengths and weakness is the inner factor; the opportunities and threats are the external factor. By analyzing the inner and external factors, the analysis can provide the detail information of the position of a player and the characteristics of the industry.
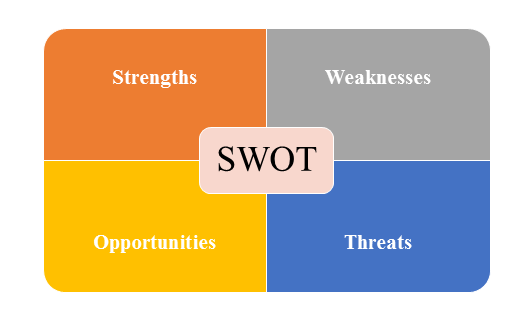
- Strengths describe what the player excels at and separates it from the competition
- Weaknesses stop the player from performing at its optimum level.
- Opportunities refer to favorable external factors that the player can use to give it a competitive advantage.
- Threats refer to factors that have the potential to harm the player.
- Data Sources
| Primary Sources | Secondary Sources |
|---|---|
| Face to face/Phone Interviews with market participants, such as: Manufactures; Distributors; End-users; Experts. Online Survey |
Government/International Organization Data: Annual Report/Presentation/Fact Book Internet Source Information Industry Association Data Free/Purchased Database Market Research Report Book/Journal/News |