X-ray Anti-Scatter Grids Market Report 2026-2031
- Single User License (1 Users) $ 3,500
- Team License (2~5 Users) $ 4,500
- Corporate License (>5 Users) $ 5,500
The global X-ray anti-scatter grids market size will reach an interval of 140 million to 180 million USD by 2026, expanding at a compound annual growth rate of 3.9% to 5.5% through 2031.
Positioned directly between the patient and the digital Flat Panel Detector (FPD) or legacy Computed Radiography (CR) cassette, the anti-scatter grid functions as an indispensable optomechanical filtering assembly. Diagnostic X-ray beams passing through human or animal tissue inevitably generate Compton scattered radiation. These non-collimated photons, if unattenuated, create diffuse background noise, degrade image contrast, and compromise detective quantum efficiency (DQE). By utilizing microscopic lead strips alternating with radiolucent interspacer materials, anti-scatter grids eliminate off-axis scatter while preserving primary beam fidelity, directly enabling high-contrast spatial resolution at minimal radiation dosage.
The underlying industrial structure presents a striking divergence between regulatory barriers and commercial moats. From a regulatory standpoint, anti-scatter grids operate under streamlined pathways, classified uniformly as Class 1 medical devices across jurisdictions such as the United States FDA, European Union MDR, and South Korean MFDS. This classification permits swift market notifications without prospective clinical trial burdens.
Conversely, commercial friction is exceptionally high. Grids represent critical, custom-tailored subassemblies engineered directly into OEM system homologations. Once a grid configuration is certified within a global system integrator's platform, the multi-year engineering validation and regulatory amendment costs generate severe vendor lock-in.
Production remains concentrated among a minimal cohort of precision manufacturers, most notably JPI Healthcare, Dunlee, Mitaya Manufacturing, Siemens Healthineers AG and Kiran Medical Systems, alongside captive production facilities such as Siemens Healthineers' vacuum technology hubs in Erlangen and Wuxi. As healthcare systems globally transition from analog radiography to high-sensitivity amorphous silicon (a-Si), indium gallium zinc oxide (IGZO), and complementary metal-oxide-semiconductor (CMOS) flat panel detectors, component design specifications are shifting toward higher strip frequencies, carbon fiber interspacers, and micro-machined geometries.
PRODUCT TOPOLOGY AND TECHNICAL ARCHITECTURE
The technical function of an anti-scatter grid is defined by its ability to maximize the primary radiation transmission ratio while suppressing secondary Compton scattering. Achieving this balance requires microscopic mechanical precision and material science optimization across three interdependent physical layers:
1. Shielding Strips
High-purity lead (Pb) foil serves as the universal radiation attenuation medium, configured with strip thicknesses ranging from 15 micrometers to 46 micrometers. Lead purity must exceed 99.9% to avoid density variations that create localized strip artifacts on high-resolution digital flat panel detectors. The strips are precisely tilted at progressively increasing angles from the center line outward, converging on an exact focal point matched to the Source-to-Image Distance (SID) of the diagnostic modality.
2. Interspace Transmissive Material
Positioned alternately between each lead foil strip, the interspace material provides structural stabilization while allowing unscattered primary photons to penetrate with minimal linear attenuation. Structural variants define operational performance:
- Aluminum (Al) Interspace: Sheet thicknesses vary between 60 micrometers and 250 micrometers. Aluminum provides high mechanical rigidity and environmental resilience at a competitive cost point, dominating standard digital radiography (DR) and mobile applications operating at higher tube voltages (70 to 120 kVp).
- Carbon Fiber and Graphite Interspace: Used in low-energy imaging environments, particularly mammography and tomosynthesis (25 to 35 kVp), where aluminum would absorb excessive primary diagnostic photons, leading to elevated patient dose.
- Organic Fiber and Paper Interspace: Lightweight structures that deliver low primary attenuation, historically prevalent in European OEM configurations.
- Micro-Engineered Air Gaps: High-complexity configurations deployed in specialized research and high-resolution industrial testing to eliminate spacer absorption entirely.
3. Protective Outer Cover and Framing
To shield the fragile lead-and-interspacer matrix from structural deflection, humidity intrusion, and direct mechanical impact, grids are encased within low-attenuation carbon fiber sheets or precision-drawn aluminum plates, sealed with specialized epoxy bonding adhesives under high-vacuum pressure.
Product Classification by Motion State:
- Stationary Grids: Fixed structural panels mounted directly onto portable wireless flat panel detectors, mobile bedside trauma units, and specialized mammography breast support plates. Because these grids do not move during exposure, they require ultra-high strip densities (typically 40 to 80 lines per centimeter) to ensure that the lead strip shadows remain invisible or easily suppressible via digital image post-processing algorithms.
- Moving Grids: Housed within motorized table Bucky stands or vertical wall chest stands. During the X-ray exposure cycle, an electromechanical drive oscillates the grid perpendicular to the lead strip orientation. This mechanical movement blurs the physical strip lines across the image receptor, enabling the use of lower line densities (28 to 40 lines per centimeter) without degrading visual clarity.
REGIONAL MARKET DYNAMICS
● North America
North America market is defined by high digital radiography replacement rates, rapid growth in outpatient Ambulatory Surgical Centers (ASCs), and stringent radiation stewardship standards such as Image Gently and Image Wisely protocols. The widespread adoption of Full-Field Digital Mammography (FFDM) and 3D Digital Breast Tomosynthesis (DBT) has accelerated the replacement of conventional aluminum grids with ultra-fine graphite and photo-etched stationary grids. Commercial procurement across North America is dominated by major multinational imaging OEMs, with JPI Healthcare Solutions Inc. maintaining an established direct import and logistics infrastructure to support regional tier-1 and tier-2 assembly operations.
● Europe
Growth patterns reflect heavy modernization across public hospital trusts, balanced by fiscal consolidation and stringent compliance demands under the European Medical Device Regulation (EU MDR 2017/745).
While anti-scatter grids qualify as Class 1 medical devices, OEM system-level recertifications have increased the barriers to changing subassembly suppliers. Demand patterns favor low-dose fiber-interspace configurations pioneered by Western European engineering centers, alongside high-precision interventional C-arm grids integrated into surgical suites. Key manufacturing and sub-assembly footprints are concentrated within specialized optomechanical clusters across the Netherlands, Germany, and Northern Italy.
● Asia-Pacific
Asia-Pacific represents the primary growth engine for diagnostic imaging components. This momentum is supported by extensive healthcare infrastructure development across mainland China, India, and Southeast Asian economies, combined with established precision manufacturing ecosystems in Japan, South Korea, and Taiwan, China.
● South America
Regional dynamics are shaped by retrofitting cycles, where mid-tier hospitals and private diagnostic networks transition from analog film and CR cassettes to retrofitted digital flat panel detectors.
Brazil and Argentina represent the principal consumption centers, though macroeconomic volatility, currency depreciation against the US dollar, and import tariff barriers complicate direct component procurement. Demand is heavily weighted toward standardized, rugged stationary aluminum grids for mobile trauma carts and general Bucky table replacements.
● Middle East and Africa (MEA)
Regional trends reflect diverging operational environments. The Gulf Cooperation Council (GCC) economies, spearheaded by Saudi Arabia and the United Arab Emirates, are investing heavily in greenfield smart-hospital infrastructure, procurement of high-end digital breast tomosynthesis systems, and dedicated interventional angiography suites, requiring premium graphite-interspace grids.
Concurrently, wider African markets focus procurement on rugged, cost-effective general radiography systems and mobile units capable of operating under volatile electrical grid conditions, driving predictable replacement cycles for baseline linear aluminum grids.
SUPPLY CHAIN AND VALUE CHAIN ARCHITECTURE
The X-ray anti-scatter grid industry relies on a multi-stage, high-precision optomechanical value chain characterized by extreme raw material tolerances, specialized mechanical assembly, and deep integration with digital imaging sensors.
● Upstream Value Chain: Raw Materials and Precision Tooling
The foundational production phase requires tight metallurgical and composite tolerances:
- Refined Lead Strip Processing: Commercial-grade lead cannot be utilized directly. Smelters and precision rolling mills process high-purity lead into ultra-thin continuous foils measuring between 15 and 46 micrometers, requiring absolute thickness uniformity across widths up to 500 millimeters. Thickness variations exceeding 1 micrometer create observable image artifacts.
- Spacer Feedstocks: Aerospace-grade aluminum foil (60 to 250 micrometers) subjected to specialized micro-surface leveling, alongside high-modulus carbon graphite blocks and phenolic-impregnated fiber sheets.
- Structural Encasements: Pre-impregnated carbon fiber sheets and high-purity aluminum alloys configured to provide absolute structural rigidity with minimal X-ray attenuation.
- Tooling and Capital Equipment: Midstream assembly depends on specialized machinery, including high-tension multi-wire slitting saws, micro-chemical photo-etching chambers, automated vacuum-lamination presses, and multi-axis optical alignment tables.
● Midstream Value Chain: Grid Manufacturing and Quality Assurance
Midstream processing represents the principal engineering bottleneck. Manufacturing involves alternating layers of ultra-thin lead foils and interspace sheets. Because modern grids incorporate between 28 and 80 lines per centimeter, a standard 43 cm by 43 cm detector grid contains thousands of individual strip layers.
Critical midstream milestones include:
- Angular Alignment: Every individual lead strip must be set at an exact angle, tilting progressively outward to match the diverging focal spot of the X-ray tube. A deviation of fractions of a degree causes severe primary radiation cutoff.
- Vacuum Resin Impregnation: The aligned stack is locked using structural epoxy adhesives inside an autoclave under high-vacuum pressure to prevent micro-bubble formation.
- Micro-Finishing: The cured block is sliced and polished to target thicknesses, then encapsulated inside carbon fiber or aluminum protective encasements.
- Calibration: Finished units undergo automated X-ray defect testing, modulation transfer function (MTF) benchmarking, and line-density consistency verification.
● Downstream Value Chain: System Integration and Distribution
The downstream phase is dominated by medical device OEMs who integrate anti-scatter grids with flat panel detectors, X-ray tubes, high-voltage generators, and mechanical gantries. Grids are directly incorporated into moving Bucky trays or permanently glued/clamped into portable FPD drop-resistant cassettes.
Value migration is moving steadily toward integrated optoelectronic subassemblies, where the grid, the scintillator (Cesium Iodide), and the thin-film transistor (TFT) sensor array are co-packaged to optimize the system-level Detective Quantum Efficiency (DQE).
COMMERCIAL DISTRIBUTION AND SALES CHANNEL ECONOMICS
● Original Equipment Manufacturer (OEM) Direct Channel (>80% Share)
Direct OEM supply contracts constitute the operational core of the global anti-scatter grid business. The sales cycle within this channel is defined by extensive design-in engineering:
- The co-engineering timeline spans 18 to 36 months, during which the grid manufacturer configures custom specifications matching the OEM's optical geometry. Variables include Source-to-Image Distance (typically 100 cm, 115 cm, 130 cm, 150 cm, or 180 cm), grid ratio (ranging from 4:1 for low-kVp pediatric/mammography work up to 15:1 for high-kVp chest imaging), line density, and outer mechanical clearances.
- Once qualified, the grid is formally incorporated into the OEM's regulatory filings (such as FDA 510(k) clearances or CE mark technical documentation).
- Changing suppliers after certification requires substantial engineering validation, risk analysis, and potential regulatory file amendments. This process creates high switching costs and vendor lock-in, generating multi-year recurring procurement contracts throughout the life of the imaging platform.
● Distributor and Aftermarket Replacement Channel
The remaining market volume flows through specialized regional distributor networks and authorized value-added resellers:
- This channel services small-to-mid-tier regional DR assemblers, localized system refurbishers, and direct hospital clinical engineering departments seeking component replacements for damaged portable grids.
- Field operational data indicates that portable DR grids deployed in emergency departments and intensive care units experience damage rates of 3% to 7% annually due to drops and excessive patient weight loads, sustaining a steady aftermarket replacement demand.
- Leading manufacturers support this channel through regional distribution agreements. For example, JPI Healthcare utilizes specialized regional partners, including Healthhome in China, Pinchet in Italy, and System Electronics in India, alongside its dedicated corporate marketing hubs, JPI Healthcare Solutions, Inc. (USA) and JPI Japan Co., Ltd.
DOWNSTREAM APPLICATIONS DETAILED MARKET ANALYSIS
● General Radiography and Mobile Digital Radiography
General radiography represents the largest volume segment, absorbing standardized linear grids across floor-mounted systems, ceiling-suspended dual-detector suites, vertical chest stands, table Buckys, and mobile trauma carts. Standard configurations employ aluminum interspace grids featuring line densities between 34 and 44 lines per centimeter and grid ratios of 8:1 to 12:1, optimized for focal distances of 100 cm to 180 cm.
Mobile radiography carts deployed in emergency wards, intensive care units, and orthopedics rely on clip-on stationary grids encasing wireless 14x17 inch and 17x17 inch flat panel detectors. In these dynamic environments, anti-scatter grids must withstand drop impacts while maintaining precise lead strip alignment to avoid diagnostic artifacts.
● Mammography and Digital Breast Tomosynthesis (DBT)
Mammography presents demanding physical performance requirements due to low-energy operating ranges (25 to 35 kVp) and the critical need to detect micro-calcifications smaller than 100 micrometers. Standard aluminum interspace grids are unsuitable here due to excessive primary beam attenuation.
This sector relies on specialized carbon graphite interspace grids and high-precision photo-etched cellular grids. The clinical transition from conventional 2D Full-Field Digital Mammography to 3D Digital Breast Tomosynthesis requires advanced grid designs. In DBT systems, the X-ray tube moves through an angular arc to capture volumetric slices, necessitating anti-scatter solutions that do not induce directional cut-off across varying incident angles.
● Surgical and Interventional Imaging
Interventional radiology suites, cardiac catheterization labs, and operating room mobile C-arms utilize grids configured for continuous and pulsed fluoroscopy. These systems demand high primary radiation transmission to minimize cumulative radiation exposure to both patients and clinical staff during extended operations.
Low-ratio (6:1 to 8:1) graphite or high-purity fiber interspace grids are standard, maximizing contrast during real-time fluoroscopic tracking, digital subtraction angiography (DSA), and endovascular stent deployments.
● Dental Cone-Beam CT and Mobile Diagnostic CT
Maxillofacial cone-beam computed tomography (CBCT) and point-of-care mobile CT systems utilize wide-beam geometries that generate elevated Compton scattering compared to narrow fan-beam CT systems. To prevent severe ring artifacts and low-contrast resolution degradation, these systems integrate specialized curved or circular anti-scatter grids tailored to the rotational arc of the diagnostic gantry.
● Veterinary Radiography and Industrial Non-Destructive Testing (NDT)
Veterinary clinics represent a steady demand segment, utilizing ruggedized, low-cost stationary aluminum grids optimized for anatomical variations across companion animals and equine species.
In industrial non-destructive testing, anti-scatter grids are integrated into automated X-ray inspection (AXI) setups for high-energy lithium-ion battery inspection, aerospace composite validation, and semiconductor packaging quality control. Industrial applications utilize high-ratio, heavy-lead grids capable of operating at tube voltages exceeding 150 to 220 kVp to eliminate structural scattering from dense materials.
COMPETITIVE PROFILES: STRATEGIC PIVOTS AND OPERATIONAL MOATS
● JPI Healthcare Co., Ltd.
- Corporate Foundation and Infrastructure: Founded in 1980 and publicly listed on the KOSDAQ market in 2025, JPI Healthcare operates as the leading independent merchant manufacturer of X-ray anti-scatter grids worldwide. Headquartered in South Korea, the company maintains precision manufacturing infrastructure with an annual production capacity of 66,000 grid units. In FY2025, JPI manufactured 56,507 units, reflecting an operational capacity utilization rate of 85.6%.
- Financial Performance Benchmark: Financial filings confirm that JPI Healthcare generated total net operating revenues of 48.47 billion KRW (34.10 million USD) in FY2025, demonstrating an annual expansion of 7.58% compared to 45.05 billion KRW (31.69 million USD) in FY2024 and 45.41 billion KRW (31.95 million USD) in FY2023. Anti-scatter grid revenue reached 29.26 billion KRW (20.59 million USD) in FY2025, accounting for 60.38% of total gross revenues.
- Commercial Moat and Channel Distribution: Over 80% to 90% of JPI's grid revenue is derived from global exports across 77 countries. In FY2025, export grid sales totaled 26.67 billion KRW (18.77 million USD), representing 91.15% of total grid business, while domestic South Korean sales contributed 2,590 million KRW (1.82 million USD). JPI maintains long-standing OEM design-in partnerships supplying over 300 medical device integrators globally, including GE HealthCare, Siemens Healthineers, Philips Healthcare, United Imaging Healthcare, and DRGEM. Its commercial reach is reinforced by dedicated marketing subsidiaries in the United States and Japan, supplemented by exclusive distributor agreements in China, Italy, and India.
● Dunlee
- Corporate Foundation and Operating Structure: Headquartered in the Netherlands and established in 1946, Dunlee operates as a specialized imaging component subsidiary of Royal Philips. Dunlee focuses on the development, precision assembly, and mass production of premium medical imaging components, including CT replacement tubes, high-voltage generators, and anti-scatter grids.
- Operational Moat and Strategic Pivot: Dunlee is the primary volume mass-producer of fiber interspace grids globally. The company benefits from a captive baseline demand structure, with internal audits indicating that more than 50% of its total grid output is absorbed directly by parent entity Philips Healthcare for integration across its premium DR, cardiovascular, and fluoroscopy product lines. Dunlee leverages this captive volume to lower per-unit production costs, selectively offering fiber and carbon grid components to external European, North American, and Asian OEM integrators.
● Mitaya Manufacturing Co., Ltd.
- Corporate Foundation and Historical Footprint: Founded in Japan in 1946, Mitaya Manufacturing is an engineering pioneer in radiation optics, having developed the world's first aluminum interspace anti-scatter grid in 1951.
- Operational Moat and Positioning: Mitaya has maintained a stable position within the Japanese domestic diagnostic imaging ecosystem, supplying high-density aluminum interspace grids to domestic OEMs such as Fujifilm, Canon Medical Systems, and Shimadzu Corporation. The company focuses on precision manufacturing, utilizing proprietary assembly tooling to produce high-line-density (up to 80 lines/cm) stationary grids with high spatial uniformity. Its primary operational moat lies in established domestic OEM relationships and precision manufacturing processes, though its direct export footprint outside East Asia remains secondary to dedicated merchant exporters.
● Kiran Medical Systems
- Corporate Structure and Ecosystem: Kiran Medical Systems operates as the radiation radiology component and accessories manufacturing division of Trivitron Healthcare, headquartered in India.
- Strategic Focus and Moat: Kiran has carved out a distinct market position by providing cost-effective aluminum interspace grids alongside radiation protection apparel, lead glass, and cassette products. Kiran's strategic moat is anchored in emerging market penetration, offering bundled radiographic accessory packages to small-to-mid-tier DR integrators across South Asia, the Middle East, Africa, and Latin America. Its manufacturing footprint balances labor cost advantages with automated stack assembly, addressing demand in price-sensitive hospital and clinic procurement segments.
● Siemens Healthineers AG
- Corporate Scale and In-House Integration: Siemens Healthineers reported consolidated net revenues of 23.38 billion EUR (26.43 billion USD) in FY2025, with its core Imaging division generating 13.18 billion EUR (14.90 billion USD), marking 8.5% comparable revenue growth.
- Captive Manufacturing Infrastructure: Unlike pure merchant component vendors, Siemens Healthineers operates internal precision component manufacturing and sub-assembly facilities, primarily through Siemens X-Ray Vacuum Technology Ltd. located in Erlangen, Germany, and Wuxi, China. These specialized industrial facilities engineer proprietary anti-scatter grids integrated directly into Siemens' high-end portfolios, including Artis angiography platforms, Luminos fluoroscopy suites, Mammomat digital breast systems, and Somatom CT platforms. This captive approach protects proprietary system performance, while external merchant grids are sourced for select mid-tier or localized general radiography product lines.
1.1 Report Scope and Research Objectives 1
1.2 Research Methodology and Estimation Modeling 2
1.2.1 Primary Intelligence Sourcing and Expert Validation 2
1.2.2 Secondary Data Aggregation and Quantitative Modeling 3
1.3 Key Market Assumptions and Currency Conversions 4
1.4 Strategic Definitions and System Classifications 5
1.5 Abbreviations and Acronyms 6
Chapter 2 Global Market Landscape and Strategic Architecture 7
2.1 Global X-ray Anti-Scatter Grids Market Volume and Value (2021-2031) 7
2.2 Value Migration and Supply-Demand Realignment 9
2.3 Grid Ratio and Strip Density Technological Transitions 10
Chapter 3 Value Chain, Supply Chain Resilience, and Manufacturing Analysis 12
3.1 Comprehensive Value Chain Architecture 12
3.2 Upstream Sourcing Dynamics: Lead Strips, Interspacing Materials (Aluminum, Fiber, Carbon Fiber) 13
3.3 Precision Manufacturing Technologies and Alignment Tolerance Metrics 15
3.4 Technology Intellectual Property and Patent Landscape (2021-2026) 17
Chapter 4 Global Trade Dynamics and Cross-Border Logistics 19
4.1 Cross-Border Regulatory Regimes and Tariff Frameworks 19
4.2 Key Exporting Hubs: Net Volume and Trade Outflow Analysis 20
4.3 Key Importing Markets: Sourcing Strategies and Supply Chain Exposure 22
4.4 Logistics Vulnerabilities, Packaging Integrity, and Cost Structure 23
Chapter 5 Global X-ray Anti-Scatter Grids Market by Motion State 25
5.1 Stationary Grids 25
5.1.1 Market Size, Volume, and Pricing Trends (2021-2031) 25
5.1.2 Mobile X-ray and Digital Radiography (DR) Retrofit Adoption 27
5.2 Moving Grids (Bucky Systems) 28
5.2.1 Market Size, Volume, and Pricing Trends (2021-2031) 28
5.2.2 Fixed Radiography and Fluoroscopy Table Integration Dynamics 30
Chapter 6 Global X-ray Anti-Scatter Grids Market by Application 31
6.1 Medical Diagnostic Radiography 31
6.1.1 Market Size, Volume, and Value Breakdown (2021-2031) 31
6.1.2 General Radiography, Mammography, and Interventional C-Arms 33
6.2 Veterinary Radiography 34
6.2.1 Small Animal vs. Equine Imaging Volume and Value Trends (2021-2031) 34
6.3 Non-Destructive Testing (NDT) 36
6.3.1 Industrial Metrology, Aerospace, and Weld Inspection Dynamics (2021-2031) 36
Chapter 7 North America X-ray Anti-Scatter Grids Market 38
7.1 Regional Market Sizing, Volume, and Forecast (2021-2031) 38
7.2 United States: Production Capacities, Medical Demand, and OEM Integration 40
7.3 Canada: Diagnostic Imaging Fleet Modernization and Replacement Cycles 43
Chapter 8 Europe X-ray Anti-Scatter Grids Market 45
8.1 Regional Market Sizing, Volume, and Forecast (2021-2031) 45
8.2 Germany: Advanced Component Engineering, Domestic Production, and OEM Demand 47
8.3 France: Public Healthcare Procurement and Clinical Radiography Demand 49
8.4 United Kingdom: Diagnostic Diagnostic Hubs and Equipment Upgrades 50
8.5 Italy: Hospital Infrastructure Reinvestment and Specialized Imaging 51
Chapter 9 Asia-Pacific X-ray Anti-Scatter Grids Market 52
9.1 Regional Market Sizing, Volume, and Forecast (2021-2031) 52
9.2 China: High-Density Manufacturing Ecosystem and Domestic Substitution 54
9.3 Japan: Precision Engineering Hubs and Ultra-High Strip Density Innovations 56
9.4 South Korea: Digital X-ray Flat Panel Integration and Export Footprint 57
9.5 India: Radiography Equipment Assembly Expansion and Cost-Driven Sourcing 58
Chapter 10 Latin America, Middle East, and Africa X-ray Anti-Scatter Grids Market 60
10.1 Regional Overview and Market Trends (2021-2031) 60
10.2 Brazil: Medical Imaging Equipment Modernization and Import Dynamics 61
10.3 Mexico: Cross-Border OEM Assembly and Nearshoring Supply Chains 62
10.4 GCC Countries: Advanced Clinical Facility Upgrades and Turnkey Installations 63
10.5 South Africa: Public-Private Healthcare Radiography Penetration 64
Chapter 11 Global Competitive Landscape and Tier Positioning 66
11.1 Competitive Market Structure and Tier Classifications (2026) 66
11.2 Supplier Concentration Ratio (CR4, CR8) and HHI Index Metrics 67
11.3 OEM Supply Contracts and Strategic Integration Alliances 68
Chapter 12 Corporate Intelligence and Strategic Operations 71
12.1 JPI Healthcare 71
12.1.1 Corporate Profile and Operational Footprint 71
12.1.2 SWOT Matrix and Strategic Posture 72
12.1.3 JPI Healthcare X-ray Anti-Scatter Grids Operational Performance 73
12.1.4 Product Innovation and Go-To-Market Pipeline 74
12.2 Dunlee 75
12.2.1 Corporate Profile and Component Integration Ecosystem 75
12.2.2 SWOT Matrix and Value Chain Leverage 76
12.2.3 Dunlee X-ray Anti-Scatter Grids Operational Performance 77
12.2.4 OEM Component Bundling Strategy 78
12.3 Mitaya Manufacturing Co. Ltd. 79
12.3.1 Corporate Profile and Japanese Manufacturing Infrastructure 79
12.3.2 SWOT Matrix and Precision Engineering Defensibility 80
12.3.3 Mitaya Manufacturing Co. Ltd. X-ray Anti-Scatter Grids Operational Performance 81
12.3.4 Global Direct and Indirect Distribution Channels 82
12.4 Kiran Medical Systems 83
12.4.1 Corporate Profile and Diagnostic Accessories Scale 83
12.4.2 SWOT Matrix and Cost Competitiveness 84
12.4.3 Kiran Medical Systems X-ray Anti-Scatter Grids Operational Performance 85
12.4.4 Emerging Market Penetration Strategy 86
12.5 Siemens Healthineers AG 87
12.5.1 Corporate Profile and Proprietary Imaging Systems Architecture 87
12.5.2 SWOT Matrix and Clinical Integration Synergies 88
12.5.3 Siemens Healthineers AG X-ray Anti-Scatter Grids Operational Performance 89
12.5.4 Advanced In-House Fabrication and Technology Roadmap 90
Table 2. Key Technical Parameters of Interspacing Materials (Aluminum, Cotton Fiber, Carbon Fiber) 14
Table 3. Key Global Patent Filings on X-ray Grid Alignment and Anti-Scatter Technologies, 2021-2026 18
Table 4. Global X-ray Anti-Scatter Grids Trade Volume by Major Exporting Countries, 2021-2026 21
Table 5. Global X-ray Anti-Scatter Grids Trade Volume by Major Importing Countries, 2021-2026 23
Table 6. Global X-ray Anti-Scatter Grids Market Volume by Motion State, 2021-2031 26
Table 7. Global X-ray Anti-Scatter Grids Market Size by Motion State, 2021-2031 27
Table 8. Stationary Grids Market Volume, Size, and ASP Dynamics, 2021-2031 28
Table 9. Moving Grids Market Volume, Size, and ASP Dynamics, 2021-2031 29
Table 10. Global X-ray Anti-Scatter Grids Market Volume by Application, 2021-2031 32
Table 11. Global X-ray Anti-Scatter Grids Market Size by Application, 2021-2031 33
Table 12. Medical Diagnostic Radiography Market Size and Volume by Sub-segment, 2021-2031 34
Table 13. Veterinary Radiography Market Size and Volume by Animal Modality, 2021-2031 35
Table 14. Non-Destructive Testing Market Size and Volume by End-Use Sector, 2021-2031 37
Table 15. North America X-ray Anti-Scatter Grids Market by Country, 2021-2031 39
Table 16. United States X-ray Anti-Scatter Grids Market by Application, 2021-2031 41
Table 17. Canada X-ray Anti-Scatter Grids Market by Application, 2021-2031 44
Table 18. Europe X-ray Anti-Scatter Grids Market by Country, 2021-2031 46
Table 19. Germany X-ray Anti-Scatter Grids Market by Application, 2021-2031 48
Table 20. France X-ray Anti-Scatter Grids Market by Application, 2021-2031 50
Table 21. United Kingdom X-ray Anti-Scatter Grids Market by Application, 2021-2031 51
Table 22. Italy X-ray Anti-Scatter Grids Market by Application, 2021-2031 52
Table 23. Asia-Pacific X-ray Anti-Scatter Grids Market by Country, 2021-2031 53
Table 24. China X-ray Anti-Scatter Grids Market by Application, 2021-2031 55
Table 25. Japan X-ray Anti-Scatter Grids Market by Application, 2021-2031 56
Table 26. South Korea X-ray Anti-Scatter Grids Market by Application, 2021-2031 58
Table 27. India X-ray Anti-Scatter Grids Market by Application, 2021-2031 59
Table 28. Latin America, Middle East, and Africa X-ray Anti-Scatter Grids Market by Region/Country, 2021-2031 61
Table 29. Brazil X-ray Anti-Scatter Grids Market by Application, 2021-2031 62
Table 30. Mexico X-ray Anti-Scatter Grids Market by Application, 2021-2031 63
Table 31. GCC Countries X-ray Anti-Scatter Grids Market by Application, 2021-2031 64
Table 32. South Africa X-ray Anti-Scatter Grids Market by Application, 2021-2031 65
Table 33. Global Market Share Ranking of Top Manufacturers, 2025-2026 67
Table 34. JPI Healthcare X-ray Anti-Scatter Grids Sales, Price, Cost and Gross Profit Margin (2021-2026) 73
Table 35. Dunlee X-ray Anti-Scatter Grids Sales, Price, Cost and Gross Profit Margin (2021-2026) 77
Table 36. Mitaya Manufacturing Co. Ltd. X-ray Anti-Scatter Grids Sales, Price, Cost and Gross Profit Margin (2021-2026) 81
Table 37. Kiran Medical Systems X-ray Anti-Scatter Grids Sales, Price, Cost and Gross Profit Margin (2021-2026) 85
Table 38. Siemens Healthineers AG X-ray Anti-Scatter Grids Sales, Price, Cost and Gross Profit Margin (2021-2026) 89
Figure 1. Global X-ray Anti-Scatter Grids Market Size Progression (USD Million), 2021-2031 8
Figure 2. End-to-End Value Chain and Margin Allocation Architecture 13
Figure 3. Lead Strip Fabrication and Alignment Tolerance Thresholds 16
Figure 4. Global Trade Flows of X-ray Anti-Scatter Grids (Major Corridors), 2026 21
Figure 5. Global Market Share Breakdown by Motion State (Stationary vs. Moving), 2026 26
Figure 6. Stationary vs. Moving Grids Growth Velocity Comparison (2026-2031) 29
Figure 7. Global Application Value Distribution (Medical, Veterinary, NDT), 2026 32
Figure 8. North America X-ray Anti-Scatter Grids Market Share by Country, 2026 39
Figure 9. United States OEM vs. Aftermarket Sales Split, 2021-2026 42
Figure 10. Europe X-ray Anti-Scatter Grids Market Share by Country, 2026 46
Figure 11. Germany Anti-Scatter Grid Production vs. Domestic Absorption Trends, 2021-2026 48
Figure 12. Asia-Pacific X-ray Anti-Scatter Grids Market Share by Country, 2026 53
Figure 13. China Domestic Sourcing Share versus Import Displacement, 2021-2031 55
Figure 14. Latin America, Middle East, and Africa Value Distribution, 2026 60
Figure 15. Market Concentration: Global Anti-Scatter Grid Manufacturer Tiers, 2026 68
Figure 16. JPI Healthcare X-ray Anti-Scatter Grids Market Share (2021-2026) 74
Figure 17. Dunlee X-ray Anti-Scatter Grids Market Share (2021-2026) 78
Figure 18. Mitaya Manufacturing Co. Ltd. X-ray Anti-Scatter Grids Market Share (2021-2026) 82
Figure 19. Kiran Medical Systems X-ray Anti-Scatter Grids Market Share (2021-2026) 86
Figure 20. Siemens Healthineers AG X-ray Anti-Scatter Grids Market Share (2021-2026) 90
Research Methodology
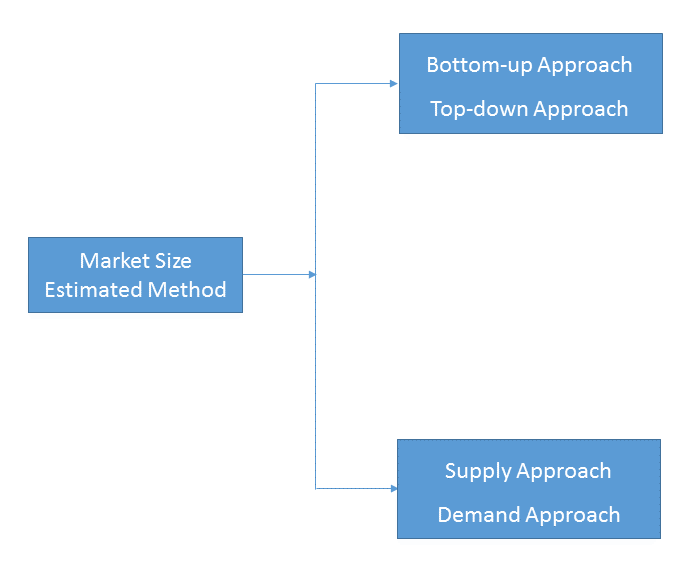
- Market Estimated Methodology:
Bottom-up & top-down approach, supply & demand approach are the most important method which is used by HDIN Research to estimate the market size.
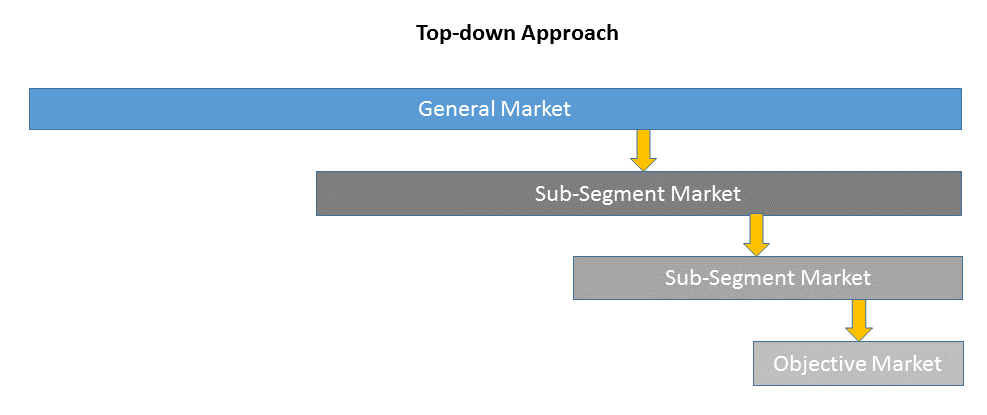
1)Top-down & Bottom-up Approach
Top-down approach uses a general market size figure and determines the percentage that the objective market represents.
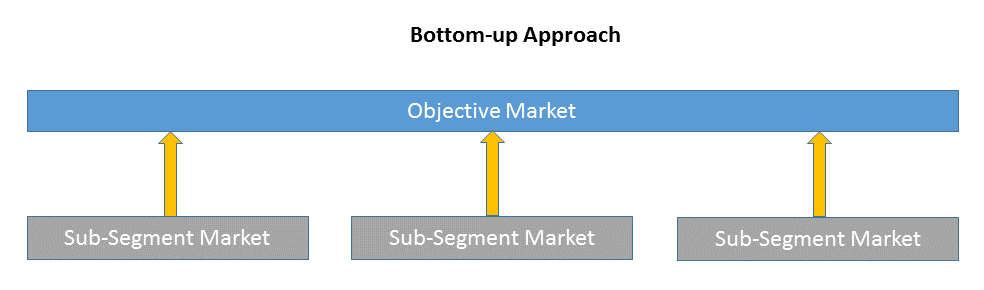
Bottom-up approach size the objective market by collecting the sub-segment information.
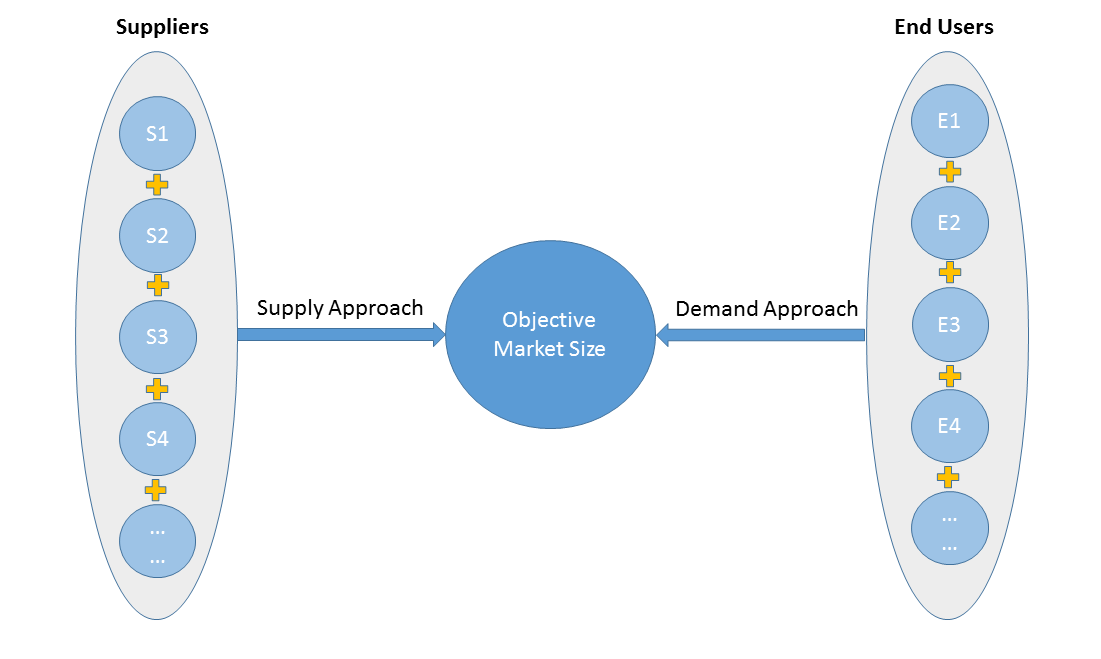
2)Supply & Demand Approach
Supply approach is based on assessments of the size of each competitor supplying the objective market.
Demand approach combine end-user data within a market to estimate the objective market size. It is sometimes referred to as bottom-up approach.
- Forecasting Methodology
- Numerous factors impacting the market trend are considered for forecast model:
- New technology and application in the future;
- New project planned/under contraction;
- Global and regional underlying economic growth;
- Threatens of substitute products;
- Industry expert opinion;
- Policy and Society implication.
- Analysis Tools
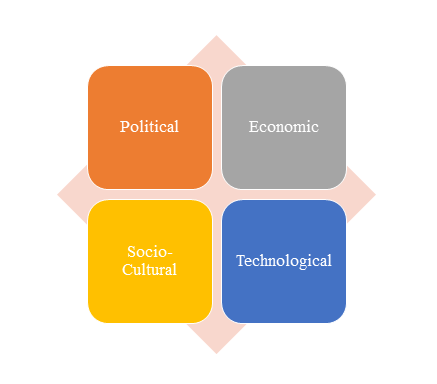
1)PEST Analysis
PEST Analysis is a simple and widely used tool that helps our client analyze the Political, Economic, Socio-Cultural, and Technological changes in their business environment.
- Benefits of a PEST analysis:
- It helps you to spot business opportunities, and it gives you advanced warning of significant threats.
- It reveals the direction of change within your business environment. This helps you shape what you’re doing, so that you work with change, rather than against it.
- It helps you avoid starting projects that are likely to fail, for reasons beyond your control.
- It can help you break free of unconscious assumptions when you enter a new country, region, or market; because it helps you develop an objective view of this new environment.
2)Porter’s Five Force Model Analysis
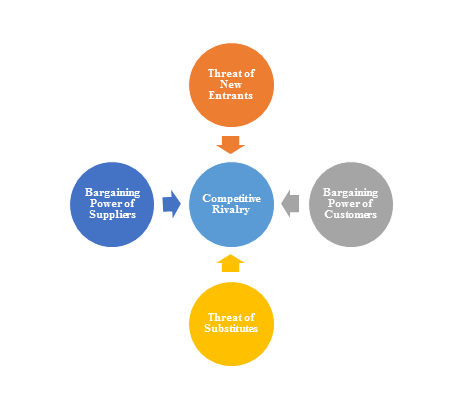
The Porter’s Five Force Model is a tool that can be used to analyze the opportunities and overall competitive advantage. The five forces that can assist in determining the competitive intensity and potential attractiveness within a specific area.
- Threat of New Entrants: Profitable industries that yield high returns will attract new firms.
- Threat of Substitutes: A substitute product uses a different technology to try to solve the same economic need.
- Bargaining Power of Customers: the ability of customers to put the firm under pressure, which also affects the customer's sensitivity to price changes.
- Bargaining Power of Suppliers: Suppliers of raw materials, components, labor, and services (such as expertise) to the firm can be a source of power over the firm when there are few substitutes.
- Competitive Rivalry: For most industries the intensity of competitive rivalry is the major determinant of the competitiveness of the industry.
3)Value Chain Analysis
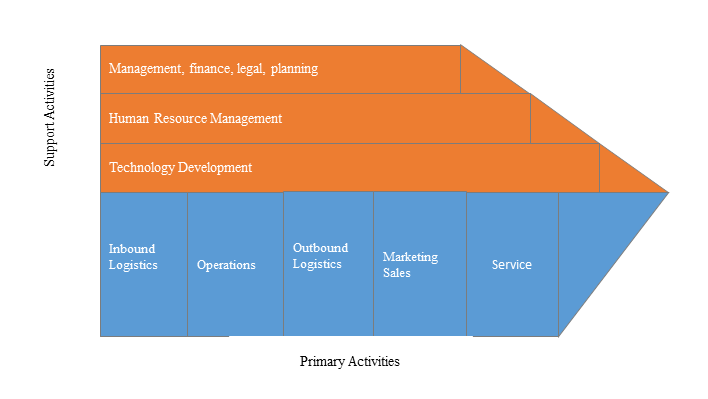
Value chain analysis is a tool to identify activities, within and around the firm and relating these activities to an assessment of competitive strength. Value chain can be analyzed by primary activities and supportive activities. Primary activities include: inbound logistics, operations, outbound logistics, marketing & sales, service. Support activities include: technology development, human resource management, management, finance, legal, planning.
4)SWOT Analysis
SWOT analysis is a tool used to evaluate a company's competitive position by identifying its strengths, weaknesses, opportunities and threats. The strengths and weakness is the inner factor; the opportunities and threats are the external factor. By analyzing the inner and external factors, the analysis can provide the detail information of the position of a player and the characteristics of the industry.
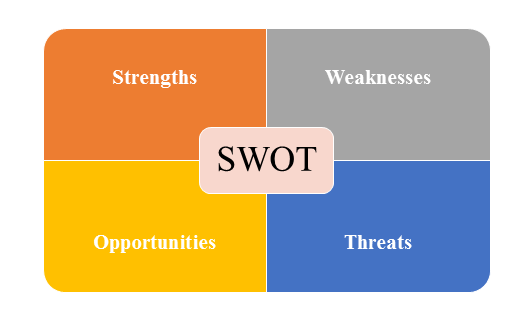
- Strengths describe what the player excels at and separates it from the competition
- Weaknesses stop the player from performing at its optimum level.
- Opportunities refer to favorable external factors that the player can use to give it a competitive advantage.
- Threats refer to factors that have the potential to harm the player.
- Data Sources
| Primary Sources | Secondary Sources |
|---|---|
| Face to face/Phone Interviews with market participants, such as: Manufactures; Distributors; End-users; Experts. Online Survey |
Government/International Organization Data: Annual Report/Presentation/Fact Book Internet Source Information Industry Association Data Free/Purchased Database Market Research Report Book/Journal/News |