Medical Endoscope System Market Analysis & Forecast 2026-2031
- Single User License (1 Users) $ 3,500
- Team License (2~5 Users) $ 4,500
- Corporate License (>5 Users) $ 5,500
The global medical endoscope system market size will reach between 23.1 billion USD and 26.1 billion USD in 2026, and is projected to expand at a compound annual growth rate (CAGR) between 5.2% and 7.2% through 2031. Mature commercial demand remains centered in North America and Western Europe, supported by mature reimbursement codes and Ambulatory Surgery Center (ASC) infrastructure. Rapid volume expansion is concentrated within the Asia-Pacific territory, specifically within mainland China, India, and Southeast Asia. Manufacturing and supply dependencies demonstrate extreme geographic clustering: optical lens arrays and specialized CMOS sensors originate primarily out of East Asia (Japan and Taiwan, China), while precision mechanical assembly remains distributed across Germany and specialized manufacturing zones in southern and eastern China. Market direction is governed by legacy Japanese optical consortiums (Olympus, Fujifilm, HOYA Pentax), American surgical visualization platforms (Stryker, Boston Scientific, Arthrex, Medtronic), and European precision engineering firms (KARL STORZ, Richard Wolf, B. Braun). Concurrently, single-use disrupters (Ambu, Zhuhai Pusen, OTU Medical) and high-velocity Chinese domestic manufacturers (Mindray, SonoScape, Shanghai Aohua) are actively challenging traditional market share dynamics through technological leapfrogging and localized cost structures.
PRODUCT CLASSIFICATIONS & TECHNICAL TAXONOMIES
1. Classification by Mechanical & Optical Architecture
● Rigid Endoscopes
Engineered with continuous metallic outer sheaths (typically surgical-grade stainless steel or titanium alloys), rigid scopes utilize classic HOPKINS rod-lens optical trains, prism systems, or rigid distal-chip sensor configurations. These scopes enter the body through surgical incisions via trocars or direct, straight natural anatomical channels. Core configurations include laparoscopes (0, 30, and 45-degree direction of view), arthroscopes, hysteroscopes, thoracoscopes, and rigid cystoscopes. Technical development is centered on wide-angle full-color 4K resolution, passive polarized or dual-sensor 3D stereoscopy, and near-infrared (NIR) indocyanine green (ICG) fluorescence imaging systems. They remain the dominant visual apparatus in open-conversion and minimally invasive cavity surgery.
● Flexible Endoscopes
Featuring multi-joint, actively articulating distal tips navigated via proximal control handles and dual-axis pull-wire assemblies, flexible endoscopes navigate convoluted gastrointestinal, respiratory, and urinary conduits. These systems house intricate internal working channels (ranging from 1.2mm to 4.2mm in diameter) dedicated to instrument insertion, air/water insufflation, and active suction. Standard sub-types encompass gastroscopes, duodenoscopes, colonoscopes, enteroscopes, bronchoscopes, choledochoscopes, and flexible ureteroscopes. Modern iterations universally utilize chip-on-the-tip digital sensors, eliminating fragile optical coherent fiber bundles while incorporating variable-stiffness insertion tubes to optimize procedural comfort and deep-cavity navigation.
● Semi-Rigid Endoscopes
Constructed using structural metallic alloy shafts that balance structural column strength with calibrated elastic deflection capabilities, semi-rigid endoscopes are targeted primarily at endourological applications (specifically semi-rigid ureteroscopy). These instruments allow physicians to negotiate the distal and mid-ureter to fragment calculi without the catastrophic optical rod-lens fracture risks that affect purely rigid systems, maintaining a lower cost profile and higher mechanical rigidity than fully flexible ureteroscopes.
● Capsule Endoscopy
Ingestible, patient-swallowed, wireless diagnostic modules designed to evaluate the gastrointestinal tract—predominantly the small intestine, which remains largely inaccessible via conventional push enteroscopy. These miniaturized, battery-operated units integrate micro-CMOS sensors, miniature optical objectives, multi-element LED illumination arrays, application-specific ASICs, and radiofrequency (RF) transmitters or human-body communication (HBC) transmission pathways. Advanced variants incorporate multi-axis external magnetic manipulation, enabling operators to steer the capsule actively across the gastric mucosa for sedate-free upper gastrointestinal evaluations.
2. Classification by Clinical Specialty
● Gastrointestinal (GI) Endoscopy
Gastroenterology represents the largest procedural volume and market value driver globally. Modalities span upper GI esophagogastroduodenoscopy (EGD), lower GI diagnostic and screening colonoscopy, small bowel enteroscopy, endoscopic ultrasound (EUS) for transmural tissue sampling, and pancreaticobiliary interventions via Endoscopic Retrograde Cholangiopancreatography (ERCP). Procedures are heavily therapeutic, requiring robust scope architecture to support electrocautery, mechanical clipping, mucosal resection (EMR), submucosal dissection (ESD), and radiofrequency ablation.
● Pulmonology & Interventional Respirology
Specialty visualization spanning the tracheobronchial tree. Interventions range from routine ICU airway clearance and diagnostic washings to complex endobronchial ultrasound-guided transbronchial needle aspiration (EBUS-TBNA) for mediastinal lymph node staging, peripheral pulmonary nodule biopsy, and rigid interventional airway stenting. This clinical domain acts as the leading beachhead for single-use scope penetration.
● Urological Endoscopy
Endourology encompasses diagnostic and therapeutic navigation across the urethra, bladder, ureters, and renal pelvic calyces. Key modalities comprise rigid and flexible cystoscopy, percutaneous nephrolithotomy (PCNL), and retrograde intrarenal surgery (RIRS) utilizing holmium or thulium fiber lasers for calculus pulverization. Scope design prioritizes minimal outer diameter (sub-9 French), high-angle distal deflection (up to 270-275 degrees), and dynamic fluid irrigation control.
● Surgical Minimally Invasive Endoscopy
Comprises specialized visualization suites deployed in surgical operating environments. Sub-specialties include Laparoscopy (abdominal and gynecological procedures), Arthroscopy (rotator cuff, cruciate ligament, and articular surface reconstruction), Thoracoscopy (video-assisted thoracic surgery [VATS]), Neuroendoscopy (transsphenoidal pituitary resection and ventricular tumor management), and Spinal Endoscopy (full-endoscopic interlaminar and transforaminal decompression). Optical configurations demand absolute geometric fidelity, depth perception, and seamless electrosurgical energy integration.
3. Classification by Lifecycle Paradigm
● Reusable Endoscopes
The historic operational foundation of clinical endoscopy. These systems are designed to withstand 500 to 1,500 clinical cycles, supported by meticulous intermediate reprocessing. This cycle involves manual bedside flushing, multi-stage enzymatic leak testing, automated cleaning inside AERs, and low-temperature chemical sterilization (peracetic acid, vaporized hydrogen peroxide) or high-temperature autoclaving for select rigid units. While offering high optical precision, low per-procedure marginal capital cost, and fine manual articulation dynamics, reusables carry severe hidden costs: continuous sterilization infrastructure maintenance, specialized labor inputs, scope degradation, routine factory overhaul fees, and documented risks of biofilm formation that can lead to multi-drug resistant superbug outbreaks.
● Single-Use (Disposable) Endoscopes
Sterile, factory-packaged, single-patient-use visualization systems engineered for disposal post-procedure. Driven by high-volume automated cleanroom assembly, single-use scopes replace polished optical glass with injection-molded optical polymers and employ low-cost micro-CMOS sensors coupled with integrated digital system-on-chip handles. The device is discarded post-intervention, completely removing capital repair budgets, chemical reprocessor operating leases, and contamination vectors. Current global market penetration hovers between 3% and 4% of total market value, with profound specialty variance: 20% in respiratory care, 10% in urology, 2% to 4% in ENT, and below 1% in therapeutic gastrointestinal procedures. Clinical projections forecast long-term normalization toward 70% single-use adoption across high-turnover, small-caliber specialty fields (respiratory, urology, ENT).
DOWNSTREAM APPLICATIONS & HEALTH ECONOMICS
● Gastroenterology & Pancreaticobiliary Care
Gastrointestinal applications drive procedural density worldwide, reflected in excess of 9 million upper GI endoscopies performed annually in the United States alone. Key diagnostic and interventional workflows encompass colorectal adenocarcinoma screening, targeted EMR/ESD of dysplastic lesions, ERCP sphincterotomy, stone extraction, and non-invasive transoral incisionless fundoplication. The segment remains heavily weighted toward reusable towers due to the extreme mechanical durability, broad instrument channel tolerances, and micro-steerability required for complex interventional maneuvering. However, duodenoscopes remain subject to intense institutional scrutiny due to the complex elevator mechanism harboring microbial vectors, stimulating transition towards single-use distal-cap hybrids and full single-use duodenoscope platforms.
● Urology & Endourology
Urology represents the fastest-growing transition domain for single-use flexible endoscopy platforms. Driven by the high global prevalence of nephrolithiasis and bladder neoplasia, procedures such as RIRS and flexible diagnostic cystoscopy demand severe instrument channel stress. Laser deflection, active basket retrieval, and sharp shaft torsion routinely cause internal channel puncture and optical bundle degradation in reusable scopes, resulting in substantial third-party repair bills (frequently between 4,000 USD and 7,000 USD per repair event). The adoption of single-use ureteroscopes increases procedural throughput by up to 50% through the elimination of scope availability bottlenecks while establishing fixed, predictable procedural supply costs.
● Pulmonology & Respiratory Care
Respiratory care serves as the most commercially mature single-use endoscopy sector (~20% global volume penetration). Bedside airway inspections in the Intensive Care Unit (ICU), difficult endotracheal intubations, bronchoalveolar lavage (BAL), and percutaneous tracheostomies present erratic, emergency schedules where the immediate availability of a sterile, pre-calibrated scope is paramount. Comprehensive health-economic models indicate that factoring in the amortized acquisition costs, reprocessing chemistry, microbiological verification testing, and technician wages, single-use bronchoscopes yield up to a 13% direct economic savings per procedure relative to reusable platforms in low-to-medium volume settings, entirely avoiding capital cross-contamination events.
● General & Laparoscopic Minimally Invasive Surgery
High-volume abdominal surgery encompasses cholecystectomy, bariatric bypass, colectomy, appendectomy, and inguinal hernia repairs. Technological differentiation centers around three pillars:
- 4K-UHD and native 3D dual-channel optical camera control units.
- Near-infrared (NIR) fluorescence imaging employing indocyanine green (ICG) to delineate intrahepatic biliary anatomy, assess intraoperative tissue perfusion, and execute real-time sentinel lymph node mapping.
- Integrated digital insufflation engines maintaining stable, low-pressure pneumoperitoneum with active aerosolized smoke evacuation to preserve optics and reduce peritoneal trauma.
● Orthopedics & Sports Medicine
Demand centers on joint reconstruction across the shoulder, knee, hip, and small extremities. Arthroscopic workflows require durable rigid optics capable of withstanding tight articular spaces alongside motorized bone shavers, radiofrequency ablation probes, and continuous high-flow fluid distention systems. Recent innovations feature chip-on-the-tip needle arthroscopes (sub-2.0mm diameters) that allow diagnostic evaluations to move out of the traditional operating room suite into office-based settings under local anesthesia.
● Otorhinolaryngology (ENT)
Covers flexible rhinolaryngoscopy, functional endoscopic sinus surgery (FESS), diagnostic stroboscopy, and micro-laryngeal procedures. The clinical environment is marked by high patient volume and rapid turnover within outpatient ambulatory practices. Disposable rhinolaryngoscopes have achieved strong initial market penetration, allowing clinical staff to avoid maintaining specialized liquid chemical disinfection stations within physician office footprints.
● Neurosurgery & Advanced Digital Pathology
Occupies the highest technical boundary of industrial optical engineering. Interventions require sub-millimeter visualization to navigate deep cranial corridors, perform transsphenoidal hypophysectomies, and treat intraventricular lesions. Integration with multi-axis surgical robotic arms and real-time Confocal Laser Endomicroscopy (CLE) allows neurosurgeons to transition from macroscopic gross visualization to in vivo optical biopsy. CLE leverages miniaturized laser-scanning mini-probes to achieve 1,000x cellular magnification, identifying tumor infiltration margins at a cellular level and potentially rendering preliminary physical frozen sections obsolete.
REGIONAL MARKET DYNAMICS
● North America
North America represents the largest regional market by revenue, commanding an aggregate share exceeding 40%. Structural market maturity is characterized by a rapid capital reallocation from standard inpatient hospital suites into ASCs and specialized diagnostic clinics. Purchasing authority is heavily gatekept by consolidated Group Purchasing Organizations (GPOs) such as Vizient, Premier, and HealthTrust, which dictate multi-year access contracts covering more than 80% of US acute care beds. Regulatory compliance is mediated via the US FDA 510(k) pathway, with growing scrutiny applied to reprocessing instructions for complex flexible scopes. This has catalyzed unprecedented institutional willingness to adopt single-use devices across bronchoscopy, cystoscopy, and ureteroscopy to insulate health systems from liability, eliminate dedicated sterilization labor, and stabilize balance sheets via Activity-Based Costing.
● Europe
Europe constitutes the second-largest theater, generating more than 26% of global demand. Market behavior is split between state-funded single-payer systems (such as the UK National Health Service and Nordic health authorities) and multi-payer social insurance models (Germany, France). Procurement strategies remain intensely value-driven, emphasizing whole-life asset costs and environmental waste profiles. The regulatory domain is entirely defined by the European Union Medical Device Regulation (EU MDR), which has increased clinical demonstration thresholds, expanded notified body audit timelines, and elevated post-market clinical follow-up costs. Consequently, smaller legacy European engineering houses face margin compression, prompting consolidation or strategic exits. Public hospital tenders increasingly penalize capital expenditure, favoring long-term equipment lease frameworks bundled with guaranteed scope exchange programs and integrated repair cycles.
● Asia-Pacific (APAC)
Asia-Pacific demonstrates the fastest growth trajectory globally. Growth patterns exhibit marked divergence between mature technology hubs and high-volume emerging sectors:
- Mainland China serves as the regional growth engine. The market is guided by two structural dynamics: aggressive import substitution under local-content procurement quotas and the national Volume-Based Procurement (VBP) policy. VBP has slashed distributor margins on high-value endourological consumables while creating immediate, high-volume market access runways for domestic leaders like Aohua, SonoScape, Mindray, and NovelBeam. National initiatives focusing on early digestive tract cancer screening are driving capital equipment deployments across secondary and county-level hospitals.
- Japan remains a tier-one technological bastion, serving as the research, design, and manufacturing origin for global flexible optical leaders (Olympus, Fujifilm, PENTAX). Domestic demand prioritizes advanced diagnostic optical modes, real-time optical magnification, and AI-driven computer-aided lesion assessment under PMDA oversight.
- South Korea functions as an advanced innovation testbed, championing niche optomechanical breakthroughs such as handheld multi-joint articulating laparoscopic devices (LivsMed) and localized capsule diagnostic variants (IntroMedic).
- Regional precision optical fabrication clusters throughout Taiwan, China remain vital nodes for upstream optoelectronic sensor assembly, sub-millimeter lens packaging, and high-density micro-interconnect fabrication.
- India and Southeast Asia are experiencing double-digit procedural volume increases in minimally invasive laparoscopy and endourology, largely fueled by private corporate hospital network investments and regional medical tourism corridors.
● South America
South America represents an expanding market. Brazilian and Argentine commercial access is determined by dual public-private healthcare infrastructure frameworks. The public tier depends on complex international competitive bidding processes subject to foreign exchange volatility and steep import tariffs, which favor durable, repairable reusable systems. Conversely, private tier networks are adopting single-use flexible ureteroscopes to circumvent capital constraints and eliminate centralized sterilization investments in satellite locations. Distribution models throughout the continent rely almost exclusively on third-party regional logistics partners with established domestic regulatory handling capabilities.
● Middle East and Africa (MEA)
The Gulf Cooperation Council (GCC) nations (principally Saudi Arabia and the United Arab Emirates) spearhead capital equipment modernization via comprehensive public health transformation agendas. Flagship hospital builds demand state-of-the-art integrated 4K/3D operating suites, hybrid surgical platforms, and robotic endoscope integration. Outside the GCC, resource-constrained sub-Saharan healthcare environments favor ruggedized, repairable semi-rigid endoscopes alongside low-complexity portable video processor modules capable of operating reliably amid variable power and water filtration conditions.
SUPPLY CHAIN & VALUE CHAIN ARCHITECTURE
● Upstream Optoelectronic & Material Subsystems
The upstream tier of the endoscopy value chain exhibits acute supplier concentration and technical moats. Structural inputs are bifurcated into raw material feeds and specialized micro-components:
- Core optical elements: High-purity optical glass, fused silica, and synthetic sapphire are sourced from specialized optical foundries. The fabrication of multi-element micro-lens arrays (sub-3mm outer diameter) requires extreme mechanical tolerances, handled by specialized Asian and German optical producers such as Largan Precision and specialized optical units across East Asia.
- Distal sensor architectures: Miniaturization of CMOS Image Sensors (CIS) and Application-Specific Integrated Circuits (ASICs) represents a critical structural bottleneck. The industry relies heavily on a handful of global semiconductor foundries (including Sony and Omnivision) for wafer-scale packaging and ultra-miniaturized chip-on-the-tip sensors capable of 720p to 4K capture within a sub-2.0mm footprint.
- Polymeric and mechanical feeds: Insertion tubes require medical-grade fluoropolymers (PTFE, FEP, Pebax), thermoplastic elastomers, biocompatible polyurethanes, and laser-welded braided stainless steel mesh jackets. Flexible mechanical control relies on tungsten pull-wires, high-nickel alloy steering rings, and micro-machined articulation linkages.
- Fiber optics: Light delivery channels utilize multi-filament borosilicate glass or high-transmission quartz optical fiber bundles, designed to endure repeated high-temperature mechanical deflection and autoclave sterilization cycles without micro-fracturing.
● Midstream System Integration & Firmware IP
The midstream phase transforms disparate optoelectronic inputs into validated clinical towers. This involves precision cleanroom assembly, micro-alignment of distal sensor assemblies (active optical alignment along six axes), and complex laser welding of hermetically sealed insertion tips.
- Image Signal Processing (ISP) algorithms constitute a primary operational moat. Midstream firms develop proprietary Field-Programmable Gate Array (FPGA) and ASIC architectures to convert raw photonic data into diagnostic imagery.
- Multi-spectral chromoendoscopy architectures (e.g., Narrow Band Imaging [NBI], Linked Color Imaging [LCI], Blue Light Imaging [BLI], Compound Banded Imaging [CBI]) utilize precise spectral filtration or switched multispectral solid-state LED/laser diode arrays to map hemoglobin absorption bands and enhance mucosal surface architecture.
- Value migration is increasingly directed toward internal software development: latency-free edge processing, real-time geometric barrel-distortion correction, high dynamic range (HDR) color remapping, and the integration of neural network inference modules for real-time computer-aided lesion detection.
● Downstream Healthcare Infrastructure & Capital Gateways
The downstream interface comprises acute-care teaching hospitals, specialized gastrointestinal suites, outpatient ambulatory centers, and multi-facility enterprise health networks. Value flow is mediated by:
- Group Purchasing Organizations (GPOs) and integrated tenders: Gatekeepers that negotiate enterprise pricing tiers, rebate schedules, and placement terms.
- Operational infrastructure: High-Level Disinfection (HLD) infrastructure, automated endoscope reprocessors (AERs), and drying and storage cabinets represent critical ancillary capital outlays required to maintain reusable scope fleets.
- Reimbursement coding architecture: Clinical adoption speed directly tracks procedural reimbursement under established Current Procedural Terminology (CPT) frameworks and Diagnostic Related Group (DRG) hospital payment allowances. Where payment mechanics treat single-use scopes as non-separately billable supply line items, adoption slows; where separate ambulatory pass-through codes or hospital-acquired infection (HAI) penalty frameworks exist, conversion accelerates.
SALES CHANNELS & GO-TO-MARKET LOGIC
● Direct Institutional Sales Force
Direct commercial teams dominate capital sales models across North America, Western Europe, and Tier 1 metropolitan centers throughout Asia. These organizations utilize a bifurcated sales architecture:
- Enterprise Capital Specialists: Focus on multi-year visual tower replacements, negotiating directly with hospital C-suites, biomedical engineering boards, and surgical value-analysis committees.
- Field Clinical Specialists: Stationed directly within hospital surgical suites to train nursing personnel, manage sterile processing education, ensure clinician comfort with handpiece ergonomics, and drive daily volume utilization of single-use scopes and specialized interventional accessories.
● Independent Distributors & Regional Dealer Networks
Distributor configurations dominate decentralized geographic markets, secondary healthcare networks, and cross-border territories (including segments of Latin America, Eastern Europe, and the Middle East). Specialized MedTech distributors manage regional regulatory approvals, secure local warehousing safety stock, run local logistics operations, bridge long payment collection terms, and provide localized frontline maintenance and field warranty services.
● Group Purchasing Organizations (GPOs) and Integrated Delivery Networks (IDNs)
GPOs represent an institutional gatekeeper across North America, negotiating multi-tier supply arrangements covering more than 80% of US acute care beds. To secure commercial access, device manufacturers must obtain contracted vendor status by providing enterprise volume price concessions and administrative rebate fees. IDNs deploy closed institutional formularies, centralizing all capital purchasing decisions to extract volume leverage, standardizing their system-wide visual equipment to a single hardware vendor, and eliminating procedural variations across their healthcare facilities.
● Consignment Inventory Frameworks
Consignment networks are widely deployed for interventional consumables, including single-use scopes, stone retrieval baskets, snare devices, non-vascular stents, and endoscopic clips. The vendor maintains unbilled safety stock directly inside hospital procedure suites or smart RFID inventory cabinets. Ownership remains with the vendor, and revenue recognition triggers only upon scanning and packaging destruction during a confirmed clinical procedure, transferring inventory-holding risks away from healthcare providers.
● Capital Placement & Hybrid SaaS Subscriptions
To navigate hospital capital expenditure constraints, manufacturers are pivoting toward hybrid commercial arrangements. Capital video processors are placed inside procedural suites at minimal upfront cost, contingent upon long-term contractual commitments to purchase minimum monthly quotas of single-use scopes or proprietary interventional accessories. Furthermore, software-centric visualization platforms are unbundling advanced AI processing—charging recurring annual SaaS fees for automated computer-aided lesion detection (CADe), automated surgical recording indexing, and operational performance telemetry.
GLOBAL MARKET PARTICIPANTS
● Flexible Video Endoscopy Leaders (GI & Pulmonology): Olympus Corporation, Fujifilm and HOYA Corporation (PENTAX Medical).
● Rigid Endoscopy, Laparoscopy & Arthroscopy Specialists: KARL STORZ
Stryker Corporation, Richard Wolf GmbH, Arthrex Inc., Smith & Nephew, and B. Braun (Aesculap).
● Single-Use & Disposable System Innovators: Ambu A/S, Boston Scientific Corp., Zhuhai Pusen Medical Technology Co., Ltd., OTU Medical Inc., Guangzhou Red Pine Medical Instrument Co., Ltd. (Redpine), Micro-Tech Endoscopy (Nanjing Micro-Tech), Teleflex and Merit Medical Systems Inc.
● Ingestible Capsule Endoscopy & Magnetically Controlled Systems: Medtronic, CapsoVision, Inc., IntroMedic Co., Ltd., AnX Robotics, Jinshan Science & Technology (Group) and Insight Medical Solutions Inc. (IMS).
● Specialized Optical Precision, Surgical Visualization & Robotic Platforms: Carl Zeiss Meditec AG, Schoelly Fiberoptic GmbH, Henke Sass Wolf GmbH (HSW), XION GmbH, Qingdao NovelBeam Technology Co., Ltd., LivsMed Inc. and Shandong Weigao Surgical Robot Co., Ltd.
● Emerging Multimodal Diagnostic & Chinese Endoscopy Manufacturers: Mindray Medical, SonoScape Medical Corp., Shanghai Aohua Photoelectricity Endoscope Co., Ltd. (Aohua Endoscopy), Shinva Medical Instrument Co., Ltd. and Beijing Huagen Anbang Technology Co., Ltd.
OPPORTUNITIES & INHIBITORS
1. Market Growth Vectors and Opportunities
● Under-Penetrated Single-Use Runway
Single-use endoscopy accounts for under 4% of total market value today, presenting a sustained multi-year conversion opportunity. While pulmonology displays an established baseline, endourology (ureteroscopy, cystoscopy) and ENT are entering high-growth phases. As micro-CMOS wafer yields scale and automated cleanroom assembly lines decrease single-use manufacturing costs, single-use solutions will expand into non-complex diagnostic gastrointestinal workflows, unlocking recurring, consumable-driven revenue streams.
● Outpatient Procedural Migration & Ambulatory Surgery Infrastructure
The structural transition of diagnostic evaluations and routine surgical interventions out of acute inpatient environments into Ambulatory Surgery Centers (ASCs) and private clinical offices fundamentally alters procurement models. ASCs prioritize asset turnover velocity, minimal chemical processing footprints, fixed per-procedure costs, and low direct labor overhead. Portable video platforms that interface with single-use flexible devices align with these operational requirements, capturing capital allocation at the expense of traditional, centralized reusable tower infrastructure.
● Edge-AI Integration and Automated Digital Pathology
The transition from pure optical magnification to automated diagnostic decision support represents an expansive value creation vector. Embedded machine learning inference models—such as real-time computer-aided polyp detection (CADe) and characterization (CADx)—reduce diagnostic miss rates for subtle flat dysplastic lesions (e.g., sessile serrated adenomas). In high-precision surgical domains, the integration of sub-micron Confocal Laser Endomicroscopy (CLE) directly into endoscopic channels bridges macro-visualization with digital optical pathology, accelerating surgical workflows and improving margin accuracy during tumor resections.
2. Systemic Industry Headwinds and Challenges
● Global Regulatory Overhead & Clinical Trial Burdens
Regulatory barriers across key mature markets are intensifying. The transition to the European Union Medical Device Regulation (EU MDR) has introduced clinical evidence burdens, extended Notified Body review timelines, and increased ongoing post-market clinical follow-up costs. Simultaneously, the US FDA has intensified regulatory scrutiny over reusable device cleaning validations and reprocessing design architectures. This prolonged regulatory lifecycle inflates research and development budgets, penalizing smaller optomechanical innovators and lengthening time-to-market metrics for disruptive platforms.
● Tender Price Compression & Institutional Margin Squeezes
State-directed pricing pressures are compressing margin profiles throughout the device value chain. In mainland China, national and provincial Volume-Based Procurement (VBP) policies have driven substantial price cuts across high-volume surgical consumables, including endourological accessories and single-use scopes. In North America and Europe, centralized GPO price-tier locking and hospital cost containment measures are squeezing the pricing leverage historically enjoyed by tier-one equipment providers, accelerating the commoditization of standard optical hardware.
● Upstream Supply Chain Vulnerabilities and Geopolitical Chokepoints
The medical endoscopy hardware stack relies heavily on specialized, highly concentrated upstream components. Advanced micro-CMOS image sensors, custom ASICs, high-transmission fiber bundles, and precision-molded micro-lenses originate from a concentrated cluster of specialized manufacturing centers across East Asia (Japan and Taiwan, China) and Germany. Disruption to trade corridors, localized raw material squeezes (such as optical fluorite or rare earth dopants for laser light engines), or export control barriers pose supply chain vulnerabilities that can cause assembly line shutdowns and limit operational resilience.
1.1 Executive Summary and Scope of Global Medical Endoscope System Market 1
1.2 Research Design and Multi-Tiered Market Engineering Methodology 2
1.3 Primary Source Calibration: KOLs, Regulatory Filings, and Industry Audits 3
1.4 Secondary Source Triangulation, Trade Registries, and Epidemiological Databases 4
1.5 Core Modeling Hypotheses, Macroeconomic Baselines, and Currency Parity 5
1.6 Standard Nomenclature and Acronym Index 6
Chapter 2: Global Medical Endoscope System Market Overview and Ecosystem Architecture 7
2.1 System Architecture: Image Processors, Light Sources, Optics, and Working Channels 7
2.2 Historical Market Evolution and Strategic Growth Trajectory (2021-2026) 8
2.3 Forward Growth Horizons and Structural Projections (2027-2031) 9
2.4 Technological Paradigm Shifts: CMOS-on-Tip, 4K/8K Ultra-High Definition, and 3D Systems 10
2.5 Artificial Intelligence Integration: Computer-Aided Detection (CADe) and Diagnosis (CADx) 11
2.6 Pricing Benchmarks, Total Cost of Ownership (TCO), and Capital Allocation Models 12
2.7 Global Competitive Intensity and Industry Consolidation Benchmarks 13
Chapter 3: Upstream Supply Chain, Component Sourcing, and Value Chain Economics 14
3.1 Comprehensive Value Chain Topology: Raw Materials to Tertiary Care Delivery 14
3.2 Optical Assemblies: Specialty Sapphire Lenses, Glass Fiber Bundles, and Rod Lenses 15
3.3 Sensor and Microelectronics Procurement: Micro-CMOS and High-Speed Video Processors 16
3.4 Micro-Mechanical Articulation, Distal Tips, and Medical-Grade Polymer Sourcing 17
3.5 Sterile Packaging, Sheathing, and Cleanroom Manufacturing Economics 18
3.6 Value Addition Dynamics and Margin Dissection Across Value Chain Nodes 19
3.7 Supply Chain Vulnerabilities, Geopolitical Friction, and Dual-Sourcing Strategies 20
Chapter 4: Global Medical Endoscope System Market by Mechanical and Optical Architecture 21
4.1 Mechanical Architecture Segment Comparison and Market Share Evolution 21
4.2 Rigid Endoscopes 22
4.2.1 Optical Train Architecture and Durability Profiles 22
4.2.2 Revenue Dynamics and Volume Projections (2021-2031) 23
4.3 Flexible Endoscopes 24
4.3.1 Video-Endoscopic Deflection Mechanisms and Maneuverability Dynamics 24
4.3.2 Revenue Dynamics and Volume Projections (2021-2031) 25
4.4 Semi-Rigid Endoscopes 26
4.5 Capsule Endoscopy 27
4.5.1 Wireless Telemetry, Battery Densities, and Magnetically Guided Capsule Platforms 27
Chapter 5: Global Medical Endoscope System Market by Lifecycle Model 28
5.1 Reusable Endoscopes 28
5.1.1 Reprocessing Workflows, Automated Endoscope Reprocessors (AER), and Biocompatibility 29
5.1.2 Capital Equipment Lifecycle and Service Maintenance Agreement Economics 30
5.2 Disposable (Single-Use) Endoscopes 31
5.2.1 Cross-Contamination Risk Mitigation and Nosocomial Infection Dynamics 32
5.2.2 Unit Economics, High-Volume Fabrication, and Environmental Lifecycle Impact 33
Chapter 6: Global Medical Endoscope System Market by Clinical Specialty System 34
6.1 Specialty System Distribution and Revenue Contribution Matrix 34
6.2 Gastrointestinal Endoscopy 35
6.3 Pulmonology and Interventional Respirology 36
6.4 Urological Endoscopy 37
6.5 Surgical Minimally Invasive Endoscopy Systems 38
6.5.1 Laparoscopes 38
6.5.2 Arthroscopes 39
6.5.3 Spinal Endoscopes 40
6.5.4 Neuroendoscopes and Thoracoscopes 41
Chapter 7: Global Medical Endoscope System Market by Downstream Care Setting and Application 42
7.1 Downstream Application Ecosystem and Procurement Protocol Matrix 42
7.2 Gastroenterology (GI) and Pancreaticobiliary Care 43
7.3 Urology and Endourology Interventions 44
7.4 Pulmonology and Advanced Respiratory Care 45
7.5 General and Laparoscopic Minimally Invasive Surgery 46
7.6 Orthopedics and Sports Medicine Arthroplasty 47
7.7 Otorhinolaryngology (ENT), Neurosurgery, and Advanced Digital Pathology 48
Chapter 8: Global Manufacturing Footprints, Trade Cross-Flows, and Regulatory Barricades 49
8.1 Global Manufacturing Concentration: Key Export Hubs and Production Facilities 49
8.2 Global Import Dependency and Strategic Stockpiling Policies 50
8.3 International Trade Flows: Tariff Impacts, MFN Tariffs, and Non-Tariff Barriers 51
8.4 Regulatory Compliance Frameworks: US FDA 510(k)/PMA, EU MDR 2017/745, and NMPA 52
8.5 Quality Management Systems: ISO 13485 and ISO 14971 Risk Management Directives 53
8.6 Traceability Standards, Unique Device Identification (UDI), and Sterilization Validations 54
8.7 Sustainability Directives, Medical Plastics Disposal, and Scope 3 Decarbonization Mandates 55
Chapter 9: Global Medical Endoscope System Geographic Consumption and Production Analysis 56
9.1 North America Market Trajectory 56
9.1.1 United States Consumption Dynamics and Manufacturing Operations 57
9.1.2 Canada Procurement Frameworks and Hospital Networks 58
9.2 Europe Market Trajectory 59
9.2.1 Germany Precision Optical Production Hub and Domestic Demand 60
9.2.2 France, United Kingdom, Italy, Spain and Rest of Europe Clinical Adoption Benchmarks 61
9.3 Asia-Pacific Market Trajectory 62
9.3.1 China Domestic Manufacturing Acceleration and Volume-Based Procurement (VBP) 63
9.3.2 Japan Optical Component Manufacturing and High-End Clinical Consumption 64
9.3.3 South Korea, India, Australia, and Taiwan (China) Market Dynamics 65
9.4 Latin America Market Trajectory: Brazil and Mexico 66
9.5 Middle East and Africa Market Trajectory: Saudi Arabia, UAE, and South Africa 67
Chapter 10: Industry Competitive Landscape, Benchmarking, and Strategic Positioning 68
Chapter 11: Corporate Intelligence and Competitive Profiles 69
11.1 Olympus Corporation 69
11.1.1 Corporate Overview and Strategic Positioning 69
11.1.2 Product Portfolio and Clinical Architecture Coverage 70
11.1.3 Financial Performance and Endoscopy Revenue Breakdown 71
11.1.4 SWOT and Technological Moat Analysis 72
11.2 Stryker Corporation 73
11.2.1 Corporate Overview and Strategic Positioning 73
11.2.2 Product Portfolio and Surgical Visualization Platforms 74
11.2.3 Financial Performance and Endoscopy Revenue Breakdown 75
11.2.4 SWOT and Technological Moat Analysis 76
11.3 Boston Scientific Corp. 77
11.3.1 Corporate Overview and Single-Use Commercial Strategy 77
11.3.2 Product Portfolio and Interventional Endoscopy Platforms 78
11.3.3 Financial Performance and Endoscopy Revenue Breakdown 79
11.3.4 SWOT and Technological Moat Analysis 80
11.4 HOYA Corporation (PENTAX Medical) 81
11.4.1 Corporate Overview and Global Distribution Structure 81
11.4.2 Product Portfolio and Flexible Endoscope Platforms 82
11.4.3 Financial Performance and Endoscopy Revenue Breakdown 83
11.4.4 SWOT and Technological Moat Analysis 84
11.5 Carl Zeiss Meditec AG 85
11.5.1 Corporate Overview and Microsurgical Visualization Strategy 85
11.5.2 Product Portfolio and Neuro/ENT Visualization Systems 86
11.5.3 Financial Performance and Endoscopy Revenue Breakdown 87
11.5.4 SWOT and Technological Moat Analysis 88
11.6 Fujifilm Holdings Corporation 89
11.6.1 Corporate Overview and Precision Optical Integration 89
11.6.2 Product Portfolio and ELUXEO Endoscopic Imaging Systems 90
11.6.3 Financial Performance and Endoscopy Revenue Breakdown 91
11.6.4 SWOT and Technological Moat Analysis 92
11.7 Teleflex Incorporated 93
11.7.1 Corporate Overview and Specialized Interventional Strategy 93
11.7.2 Product Portfolio and Airway/Urology Visualization Platforms 94
11.7.3 Financial Performance and Endoscopy Revenue Breakdown 95
11.7.4 SWOT and Technological Moat Analysis 96
11.8 Ambu A/S 97
11.8.1 Corporate Overview and Single-Use Endoscopy Leadership 97
11.8.2 Product Portfolio and High-Volume Pulmonology/GI Platforms 98
11.8.3 Financial Performance and Endoscopy Revenue Breakdown 99
11.8.4 SWOT and Technological Moat Analysis 100
11.9 Merit Medical Systems Inc. 101
11.9.1 Corporate Overview and Integrated Biopsy/Visualization Positioning 101
11.9.2 Product Portfolio and Pulmonary/Vascular Endoscopy Lines 102
11.9.3 Financial Performance and Endoscopy Revenue Breakdown 103
11.9.4 SWOT and Technological Moat Analysis 104
11.10 Medtronic plc 105
11.10.1 Corporate Overview and PillCam Diagnostic Ecosystem 105
11.10.2 Product Portfolio and Surgical/Capsule Endoscopy Platforms 106
11.10.3 Financial Performance and Endoscopy Revenue Breakdown 107
11.10.4 SWOT and Technological Moat Analysis 108
11.11 Smith & Nephew plc 109
11.11.1 Corporate Overview and Sports Medicine Visualization Focus 109
11.11.2 Product Portfolio and Arthroscopy Integration Architecture 110
11.11.3 Financial Performance and Endoscopy Revenue Breakdown 111
11.11.4 SWOT and Technological Moat Analysis 112
11.12 IntroMedic Co., Ltd. 113
11.12.1 Corporate Overview and Micro-System Engineering Capabilities 113
11.12.2 Product Portfolio and MiroCam Capsule Endoscope Platforms 114
11.12.3 Financial Performance and Endoscopy Revenue Breakdown 115
11.12.4 SWOT and Technological Moat Analysis 116
11.13 CapsoVision, Inc. 117
11.13.1 Corporate Overview and 360-Degree Panoramic Optics Focus 117
11.13.2 Product Portfolio and CapsoCam Diagnostic Architecture 118
11.13.3 Financial Performance and Endoscopy Revenue Breakdown 119
11.13.4 SWOT and Technological Moat Analysis 120
11.14 LivsMed Inc. 121
11.14.1 Corporate Overview and Articulating Laparoscopic Innovation 121
11.14.2 Product Portfolio and ArtiSential Visualization/Grasping Platforms 122
11.14.3 Financial Performance and Endoscopy Revenue Breakdown 123
11.14.4 SWOT and Technological Moat Analysis 124
11.15 Shanghai Aohua Photoelectricity Endoscope Co., Ltd. 125
11.15.1 Corporate Overview and Domestic Market Penetration Strategy 125
11.15.2 Product Portfolio and AQ Series High-Definition Video Platforms 126
11.15.3 Financial Performance and Endoscopy Revenue Breakdown 127
11.15.4 SWOT and Technological Moat Analysis 128
11.16 Zhuhai Pusen Medical Technology Co., Ltd. 129
11.16.1 Corporate Overview and High-Volume Single-Use Sourcing 129
11.16.2 Product Portfolio and Single-Use Ureteroscope Platforms 130
11.16.3 Financial Performance and Endoscopy Revenue Breakdown 131
11.16.4 SWOT and Technological Moat Analysis 132
11.17 Qingdao NovelBeam Technology Co., Ltd. 133
11.17.1 Corporate Overview and Optoelectronic Sub-Assembly OEM/ODM Strategy 133
11.17.2 Product Portfolio and Fluorescence Laparoscopy Systems 134
11.17.3 Financial Performance and Endoscopy Revenue Breakdown 135
11.17.4 SWOT and Technological Moat Analysis 136
11.18 Richard Wolf GmbH 137
11.18.1 Corporate Overview and German Precision Instrument Heritage 137
11.18.2 Product Portfolio and Rigid/Flexible System Integration 138
11.18.3 Financial Performance and Endoscopy Revenue Breakdown 139
11.18.4 SWOT and Technological Moat Analysis 140
11.19 KARL STORZ SE & Co. KG 141
11.19.1 Corporate Overview and Global Integrated Operating Room Strategy 141
11.19.2 Product Portfolio and IMAGE1 S Visualization Architecture 142
11.19.3 Financial Performance and Endoscopy Revenue Breakdown 143
11.19.4 SWOT and Technological Moat Analysis 144
11.20 Micro-Tech (Nanjing) Co., Ltd. 145
11.20.1 Corporate Overview and Consumables-to-Capital Cross-Selling Strategy 145
11.20.2 Product Portfolio and Single-Use Visualization Platforms 146
11.20.3 Financial Performance and Endoscopy Revenue Breakdown 147
11.20.4 SWOT and Technological Moat Analysis 148
11.21 OTU Medical Inc. 149
11.21.1 Corporate Overview and Cost-Disruptive Single-Use Endoscopy 149
11.21.2 Product Portfolio and WiScope Urological Visualization Suite 150
11.21.3 Financial Performance and Endoscopy Revenue Breakdown 151
11.21.4 SWOT and Technological Moat Analysis 152
11.22 Guangzhou Red Pine Medical Instrument Co., Ltd. 153
11.22.1 Corporate Overview and Minimally Invasive Surgical Positioning 153
11.22.2 Product Portfolio and Disposable Nephroscope/Cystoscope Suites 154
11.22.3 Financial Performance and Endoscopy Revenue Breakdown 155
11.22.4 SWOT and Technological Moat Analysis 156
11.23 Jinshan Science & Technology (Group) Co., Ltd. 157
11.23.1 Corporate Overview and Micro-Electro-Mechanical Systems (MEMS) Integration 157
11.23.2 Product Portfolio and Navigational Capsule Endoscopy Systems 158
11.23.3 Financial Performance and Endoscopy Revenue Breakdown 159
11.23.4 SWOT and Technological Moat Analysis 160
11.24 SonoScape Medical Corp. 161
11.24.1 Corporate Overview and Optoelectronic/Ultrasound Dual Platform Synergy 161
11.24.2 Product Portfolio and HD-550 Video Endoscopy Architectures 162
11.24.3 Financial Performance and Endoscopy Revenue Breakdown 163
11.24.4 SWOT and Technological Moat Analysis 164
11.25 AnX Robotics Inc. 165
11.25.1 Corporate Overview and Magnetically Controlled Capsule Engineering 165
11.25.2 Product Portfolio and NaviCam AI-Driven Capsule Suites 166
11.25.3 Financial Performance and Endoscopy Revenue Breakdown 167
11.25.4 SWOT and Technological Moat Analysis 168
11.26 Insight Medical Solutions Inc. 169
11.26.1 Corporate Overview and Magnetically Guided Endoscopy Strategy 169
11.26.2 Product Portfolio and Upper Gastrointestinal Capsule Systems 170
11.26.3 Financial Performance and Endoscopy Revenue Breakdown 171
11.26.4 SWOT and Technological Moat Analysis 172
11.27 Beijing Huagen Anbang Technology Co., Ltd. 173
11.27.1 Corporate Overview and Clinical Visualization Infrastructure 173
11.27.2 Product Portfolio and Specialized Rigid Surgical Systems 174
11.27.3 Financial Performance and Endoscopy Revenue Breakdown 175
11.27.4 SWOT and Technological Moat Analysis 176
11.28 XION GmbH 177
11.28.1 Corporate Overview and Specialized ENT Imaging Engineering 177
11.28.2 Product Portfolio and Matrix E LED Visualization Platforms 178
11.28.3 Financial Performance and Endoscopy Revenue Breakdown 179
11.28.4 SWOT and Technological Moat Analysis 180
11.29 Schoelly Fiberoptic GmbH 181
11.29.1 Corporate Overview and OEM High-End Visualization Engineering 181
11.29.2 Product Portfolio and Micro-Endoscopic Modular Imaging Chains 182
11.29.3 Financial Performance and Endoscopy Revenue Breakdown 183
11.29.4 SWOT and Technological Moat Analysis 184
11.30 Henke Sass Wolf GmbH 185
11.30.1 Corporate Overview and Medical Optical Component Manufacturing 185
11.30.2 Product Portfolio and Rigid Endoscopic OEM Solutions 186
11.30.3 Financial Performance and Endoscopy Revenue Breakdown 187
11.30.4 SWOT and Technological Moat Analysis 188
11.31 Arthrex, Inc. 189
11.31.1 Corporate Overview and Orthopedic Surgical Integration Strategy 189
11.31.2 Product Portfolio and Synergy UHD4 Imaging Platforms 190
11.31.3 Financial Performance and Endoscopy Revenue Breakdown 191
11.31.4 SWOT and Technological Moat Analysis 192
11.32 Shinva Medical Instrument Co., Ltd. 193
11.32.1 Corporate Overview and Comprehensive Hospital Supply Chain Integration 193
11.32.2 Product Portfolio and Endoscopic Reprocessing/Rigid Scopes 194
11.32.3 Financial Performance and Endoscopy Revenue Breakdown 195
11.32.4 SWOT and Technological Moat Analysis 196
11.33 Shandong Weigao Surgical Robot Co., Ltd. 197
11.33.1 Corporate Overview and Robotic-Assisted Endoscopic Surgery Strategy 197
11.33.2 Product Portfolio and Robotic Laparoscopic 3D Endoscopy 198
11.33.3 Financial Performance and Endoscopy Revenue Breakdown 199
11.33.4 SWOT and Technological Moat Analysis 200
11.34 Shenzhen Mindray Bio-Medical Electronics Co., Ltd. 201
11.34.1 Corporate Overview and Rapid Multi-Product Hospital Deployment 201
11.34.2 Product Portfolio and HyPixel 4K Endoscopic Systems 202
11.34.3 Financial Performance and Endoscopy Revenue Breakdown 203
11.34.4 SWOT and Technological Moat Analysis 204
11.35 B. Braun Melsungen AG 205
11.35.1 Corporate Overview and Aesculap Surgical Visualization Integration 205
11.35.2 Product Portfolio and EinsteinVision 3D Camera Systems 206
11.35.3 Financial Performance and Endoscopy Revenue Breakdown 207
11.35.4 SWOT and Technological Moat Analysis 208
Table 2: Pricing Benchmarks for Rigid, Flexible, and Single-Use Endoscope Platforms (2026) 12
Table 3: Upstream Raw Material and Sensor Cost Allocation Matrix 19
Table 4: Global Medical Endoscope System Revenue by Mechanical Architecture (2021-2031) 21
Table 5: Global Rigid Endoscope Revenue and Shipment Volumes (2021-2031) 23
Table 6: Global Flexible Endoscope Revenue and Shipment Volumes (2021-2031) 25
Table 7: Global Semi-Rigid and Capsule Endoscopy Revenue (2021-2031) 27
Table 8: Global Medical Endoscope System Revenue by Lifecycle Paradigm (2021-2031) 28
Table 9: Reprocessing Cost Per Procedure for Reusable Endoscopes across Major Markets 30
Table 10: Single-Use Endoscope Cost-Effectiveness Thresholds by Procedure Volume 33
Table 11: Global Medical Endoscope System Revenue by Clinical Specialty System (2021-2031) 34
Table 12: Global Gastrointestinal Endoscopy Revenue and Clinical Center Volume (2021-2031) 35
Table 13: Global Pulmonology Endoscopy Revenue by Product Class (2021-2031) 36
Table 14: Global Urological Endoscopy Revenue by System Configuration (2021-2031) 37
Table 15: Global Surgical Minimally Invasive Endoscopy Revenue by Specialty (2021-2031) 39
Table 16: Global Medical Endoscope System Revenue by Downstream Care Setting (2021-2031) 42
Table 17: Gastroenterology and Pancreaticobiliary Endoscopy Procedure Distribution 44
Table 18: Regulatory Pathways, Testing Norms, and Approval Latencies across Jurisdictions 53
Table 19: Global Medical Endoscope System Revenue by Region (2021-2031) 56
Table 20: North America Medical Endoscope System Revenue by Country (2021-2031) 57
Table 21: Europe Medical Endoscope System Revenue by Country (2021-2031) 59
Table 22: Asia-Pacific Medical Endoscope System Revenue by Country (2021-2031) 62
Table 23: Latin America and MEA Medical Endoscope System Revenue by Country (2021-2031) 66
Table 24: Olympus Corporation Medical Endoscope System Revenue, Cost and Gross Margin (2021-2026) 71
Table 25: Stryker Corporation Medical Endoscope System Revenue, Cost and Gross Margin (2021-2026) 75
Table 26: Boston Scientific Corp. Medical Endoscope System Revenue, Cost and Gross Margin (2021-2026) 79
Table 27: HOYA Corporation Medical Endoscope System Revenue, Cost and Gross Margin (2021-2026) 83
Table 28: Carl Zeiss Meditec AG Medical Endoscope System Revenue, Cost and Gross Margin (2021-2026) 87
Table 29: Fujifilm Medical Endoscope System Revenue, Cost and Gross Margin (2021-2026) 91
Table 30: Teleflex Medical Endoscope System Revenue, Cost and Gross Margin (2021-2026) 95
Table 31: Ambu A/S Medical Endoscope System Revenue, Cost and Gross Margin (2021-2026) 99
Table 32: Merit Medical Systems Inc. Medical Endoscope System Revenue, Cost and Gross Margin (2021-2026) 103
Table 33: Medtronic Medical Endoscope System Revenue, Cost and Gross Margin (2021-2026) 107
Table 34: Smith & Nephew Medical Endoscope System Revenue, Cost and Gross Margin (2021-2026) 111
Table 35: IntroMedic Medical Endoscope System Revenue, Cost and Gross Margin (2021-2026) 115
Table 36: CapsoVision Medical Endoscope System Revenue, Cost and Gross Margin (2021-2026) 119
Table 37: LivsMed Inc. Medical Endoscope System Revenue, Cost and Gross Margin (2021-2026) 123
Table 38: Shanghai Aohua Photoelectricity Endoscope Co. Ltd. Medical Endoscope System Revenue, Cost and Gross Margin (2021-2026) 127
Table 39: Zhuhai Pusen Medical Technology Medical Endoscope System Revenue, Cost and Gross Margin (2021-2026) 131
Table 40: Qingdao NovelBeam Technology Medical Endoscope System Revenue, Cost and Gross Margin (2021-2026) 135
Table 41: Richard Wolf GmbH Medical Endoscope System Revenue, Cost and Gross Margin (2021-2026) 139
Table 42: KARL STORZ Medical Endoscope System Revenue, Cost and Gross Margin (2021-2026) 143
Table 43: Micro-Tech Endoscopy Medical Endoscope System Revenue, Cost and Gross Margin (2021-2026) 147
Table 44: OTU Medical Medical Endoscope System Revenue, Cost and Gross Margin (2021-2026) 151
Table 45: Guangzhou Red Pine Medical Instrument Co. Ltd. Medical Endoscope System Revenue, Cost and Gross Margin (2021-2026) 155
Table 46: Jinshan Science & Technology (Group) Medical Endoscope System Revenue, Cost and Gross Margin (2021-2026) 159
Table 47: SonoScape Medical Corp. Medical Endoscope System Revenue, Cost and Gross Margin (2021-2026) 163
Table 48: AnX Robotics Medical Endoscope System Revenue, Cost and Gross Margin (2021-2026) 167
Table 49: Insight Medical Solutions Inc Medical Endoscope System Revenue, Cost and Gross Margin (2021-2026) 171
Table 50: Beijing Huagen Anbang Technology Co. Ltd. Medical Endoscope System Revenue, Cost and Gross Margin (2021-2026) 175
Table 51: XION GmbH Medical Endoscope System Revenue, Cost and Gross Margin (2021-2026) 179
Table 52: Schoelly Fiberoptic GmbH Medical Endoscope System Revenue, Cost and Gross Margin (2021-2026) 183
Table 53: Henke Sass Wolf GmbH Medical Endoscope System Revenue, Cost and Gross Margin (2021-2026) 187
Table 54: Arthrex Inc Medical Endoscope System Revenue, Cost and Gross Margin (2021-2026) 191
Table 55: Shinva Medical Instrument Co.Ltd. Medical Endoscope System Revenue, Cost and Gross Margin (2021-2026) 195
Table 56: Shandong Weigao Surgical Robot Co. Ltd. Medical Endoscope System Revenue, Cost and Gross Margin (2021-2026) 199
Table 57: Mindray Medical Endoscope System Revenue, Cost and Gross Margin (2021-2026) 203
Table 58: B. Braun Medical Endoscope System Revenue, Cost and Gross Margin (2021-2026) 207
Figure 1: Global Medical Endoscope System Market Size and Growth Rates (2021-2031) 8
Figure 2: Endoscopic System Signal Processing Architecture: Light Source, Sensor, and Display Chain 10
Figure 3: Medical Endoscope System Value Chain Breakdown from Upstream to Delivery 15
Figure 4: Global Optical Architecture Breakdown: Rigid vs. Flexible vs. Capsule (2026 vs. 2031) 22
Figure 5: High-Speed Articulation vs. Durability Matrix across Flexible Systems 24
Figure 6: Global Single-Use vs. Reusable Endoscope Market Penetration Shift (2021-2031) 31
Figure 7: Clinical Specialty Revenue Distribution in Global Endoscopy Market (2026) 35
Figure 8: Surgical Minimally Invasive Endoscopy Modality Split (2026) 38
Figure 9: Downstream Demand Share by Clinical Application (2021-2031) 43
Figure 10: Global Manufacturing Capacity Share by Region (2026) 49
Figure 11: International Trade Flow Corridor of Medical Endoscopic Optical Sub-Assemblies 51
Figure 12: Global Regional Consumption Distribution (2026 vs. 2031) 58
Figure 13: Asia-Pacific Endoscope System Growth Divergence by Sub-Region 63
Figure 14: Medical Endoscope System Global Market Share Matrix (2026) 68
Figure 15: Olympus Corporation Medical Endoscope System Market Share (2021-2026) 72
Figure 16: Stryker Corporation Medical Endoscope System Market Share (2021-2026) 76
Figure 17: Boston Scientific Corp. Medical Endoscope System Market Share (2021-2026) 80
Figure 18: HOYA Corporation Medical Endoscope System Market Share (2021-2026) 84
Figure 19: Carl Zeiss Meditec AG Medical Endoscope System Market Share (2021-2026) 88
Figure 20: Fujifilm Medical Endoscope System Market Share (2021-2026) 92
Figure 21: Teleflex Medical Endoscope System Market Share (2021-2026) 96
Figure 22: Ambu A/S Medical Endoscope System Market Share (2021-2026) 100
Figure 23: Merit Medical Systems Inc. Medical Endoscope System Market Share (2021-2026) 104
Figure 24: Medtronic Medical Endoscope System Market Share (2021-2026) 108
Figure 25: Smith & Nephew Medical Endoscope System Market Share (2021-2026) 112
Figure 26: IntroMedic Medical Endoscope System Market Share (2021-2026) 116
Figure 27: CapsoVision Medical Endoscope System Market Share (2021-2026) 120
Figure 28: LivsMed Inc. Medical Endoscope System Market Share (2021-2026) 124
Figure 29: Shanghai Aohua Photoelectricity Endoscope Co. Ltd. Medical Endoscope System Market Share (2021-2026) 128
Figure 30: Zhuhai Pusen Medical Technology Medical Endoscope System Market Share (2021-2026) 132
Figure 31: Qingdao NovelBeam Technology Medical Endoscope System Market Share (2021-2026) 136
Figure 32: Richard Wolf GmbH Medical Endoscope System Market Share (2021-2026) 140
Figure 33: KARL STORZ Medical Endoscope System Market Share (2021-2026) 144
Figure 34: Micro-Tech Endoscopy Medical Endoscope System Market Share (2021-2026) 148
Figure 35: OTU Medical Medical Endoscope System Market Share (2021-2026) 152
Figure 36: Guangzhou Red Pine Medical Instrument Co. Ltd. Medical Endoscope System Market Share (2021-2026) 156
Figure 37: Jinshan Science & Technology (Group) Medical Endoscope System Market Share (2021-2026) 160
Figure 38: SonoScape Medical Corp. Medical Endoscope System Market Share (2021-2026) 164
Figure 39: AnX Robotics Medical Endoscope System Market Share (2021-2026) 168
Figure 40: Insight Medical Solutions Inc Medical Endoscope System Market Share (2021-2026) 172
Figure 41: Beijing Huagen Anbang Technology Co. Ltd. Medical Endoscope System Market Share (2021-2026) 176
Figure 42: XION GmbH Medical Endoscope System Market Share (2021-2026) 180
Figure 43: Schoelly Fiberoptic GmbH Medical Endoscope System Market Share (2021-2026) 184
Figure 44: Henke Sass Wolf GmbH Medical Endoscope System Market Share (2021-2026) 188
Figure 45: Arthrex Inc Medical Endoscope System Market Share (2021-2026) 192
Figure 46: Shinva Medical Instrument Co.Ltd. Medical Endoscope System Market Share (2021-2026) 196
Figure 47: Shandong Weigao Surgical Robot Co. Ltd. Medical Endoscope System Market Share (2021-2026) 200
Figure 48: Mindray Medical Endoscope System Market Share (2021-2026) 204
Figure 49: B. Braun Medical Endoscope System Market Share (2021-2026) 208
Research Methodology
- Market Estimated Methodology:
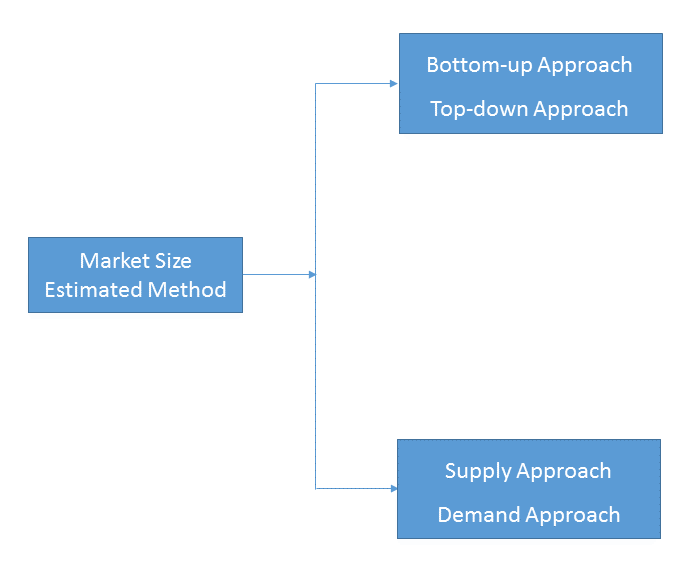
Bottom-up & top-down approach, supply & demand approach are the most important method which is used by HDIN Research to estimate the market size.
1)Top-down & Bottom-up Approach
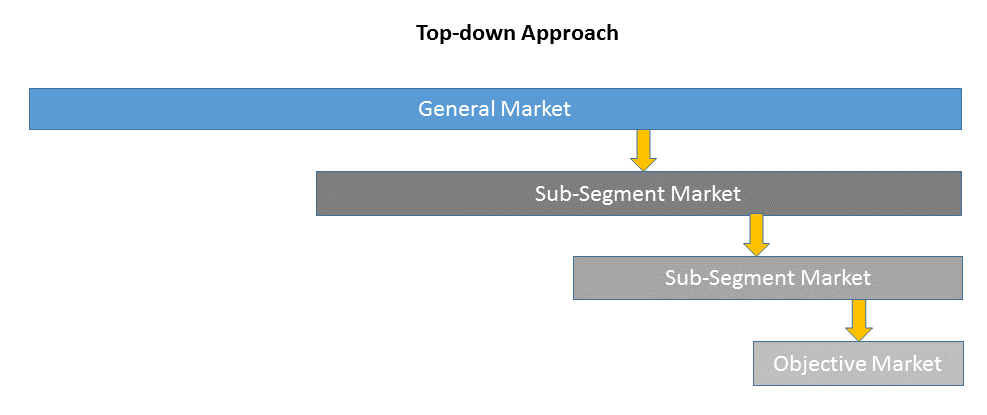
Top-down approach uses a general market size figure and determines the percentage that the objective market represents.
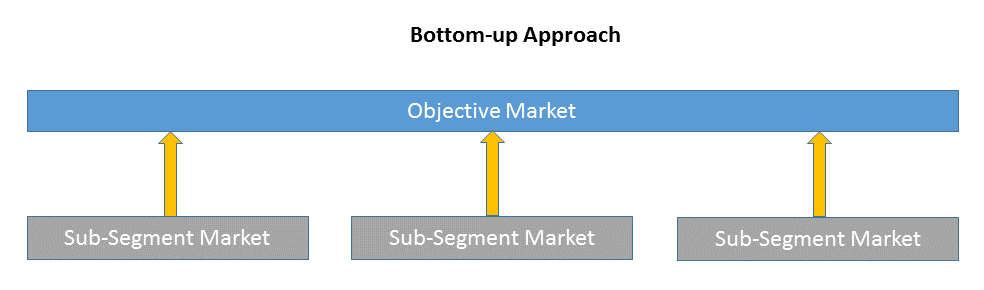
Bottom-up approach size the objective market by collecting the sub-segment information.
2)Supply & Demand Approach
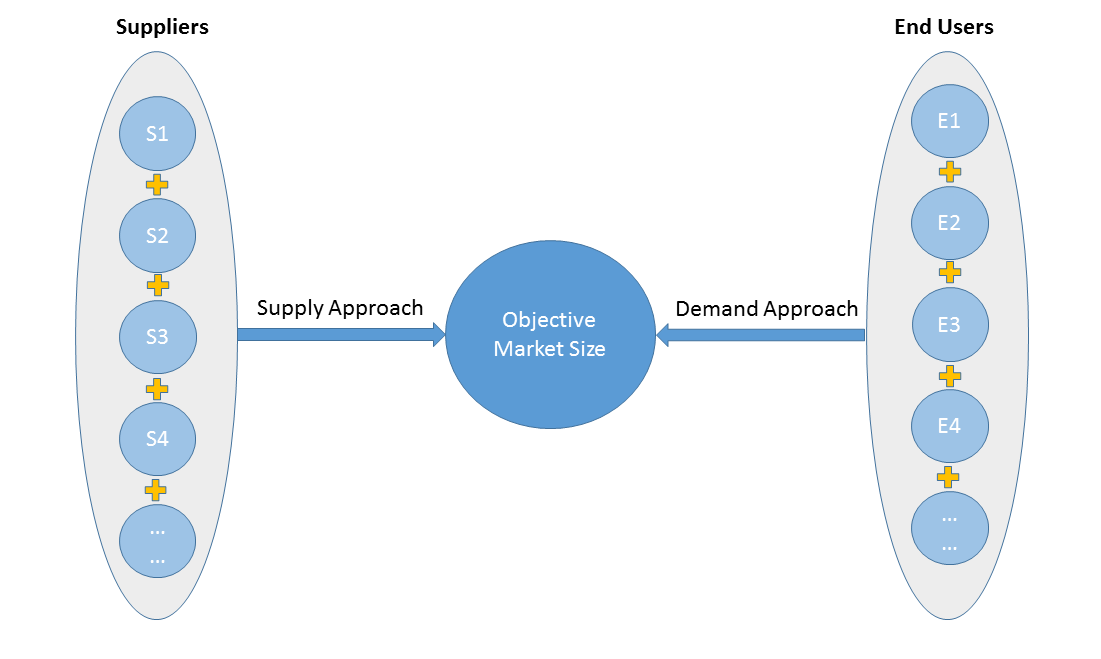
Supply approach is based on assessments of the size of each competitor supplying the objective market.
Demand approach combine end-user data within a market to estimate the objective market size. It is sometimes referred to as bottom-up approach.
- Forecasting Methodology
- Numerous factors impacting the market trend are considered for forecast model:
- New technology and application in the future;
- New project planned/under contraction;
- Global and regional underlying economic growth;
- Threatens of substitute products;
- Industry expert opinion;
- Policy and Society implication.
- Analysis Tools
1)PEST Analysis
PEST Analysis is a simple and widely used tool that helps our client analyze the Political, Economic, Socio-Cultural, and Technological changes in their business environment.
- Benefits of a PEST analysis:
- It helps you to spot business opportunities, and it gives you advanced warning of significant threats.
- It reveals the direction of change within your business environment. This helps you shape what you’re doing, so that you work with change, rather than against it.
- It helps you avoid starting projects that are likely to fail, for reasons beyond your control.
- It can help you break free of unconscious assumptions when you enter a new country, region, or market; because it helps you develop an objective view of this new environment.
2)Porter’s Five Force Model Analysis
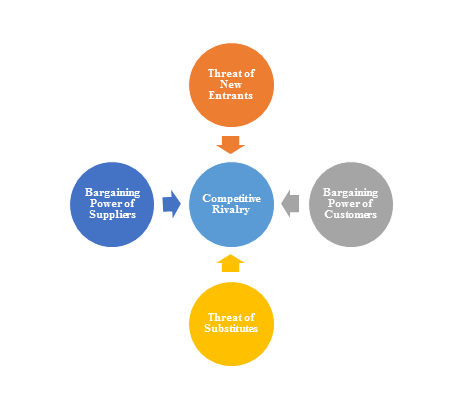
The Porter’s Five Force Model is a tool that can be used to analyze the opportunities and overall competitive advantage. The five forces that can assist in determining the competitive intensity and potential attractiveness within a specific area.
- Threat of New Entrants: Profitable industries that yield high returns will attract new firms.
- Threat of Substitutes: A substitute product uses a different technology to try to solve the same economic need.
- Bargaining Power of Customers: the ability of customers to put the firm under pressure, which also affects the customer's sensitivity to price changes.
- Bargaining Power of Suppliers: Suppliers of raw materials, components, labor, and services (such as expertise) to the firm can be a source of power over the firm when there are few substitutes.
- Competitive Rivalry: For most industries the intensity of competitive rivalry is the major determinant of the competitiveness of the industry.
3)Value Chain Analysis
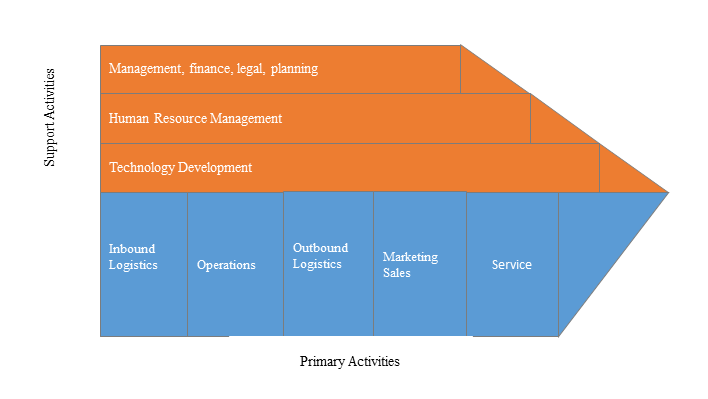
Value chain analysis is a tool to identify activities, within and around the firm and relating these activities to an assessment of competitive strength. Value chain can be analyzed by primary activities and supportive activities. Primary activities include: inbound logistics, operations, outbound logistics, marketing & sales, service. Support activities include: technology development, human resource management, management, finance, legal, planning.
4)SWOT Analysis
SWOT analysis is a tool used to evaluate a company's competitive position by identifying its strengths, weaknesses, opportunities and threats. The strengths and weakness is the inner factor; the opportunities and threats are the external factor. By analyzing the inner and external factors, the analysis can provide the detail information of the position of a player and the characteristics of the industry.
- Strengths describe what the player excels at and separates it from the competition
- Weaknesses stop the player from performing at its optimum level.
- Opportunities refer to favorable external factors that the player can use to give it a competitive advantage.
- Threats refer to factors that have the potential to harm the player.
- Data Sources
| Primary Sources | Secondary Sources |
|---|---|
| Face to face/Phone Interviews with market participants, such as: Manufactures; Distributors; End-users; Experts. Online Survey |
Government/International Organization Data: Annual Report/Presentation/Fact Book Internet Source Information Industry Association Data Free/Purchased Database Market Research Report Book/Journal/News |