Global Laparoscope Market Analysis & Strategic Outlook
- Single User License (1 Users) $ 3,500
- Team License (2~5 Users) $ 4,500
- Corporate License (>5 Users) $ 5,500
A laparoscope is an optical or digital surgical imaging scope inserted into the peritoneal or pelvic cavity through access trocars (typically 3mm to 12mm) to deliver real-time visual guidance for diagnostic and therapeutic minimally invasive procedures. The instrument operates as the core visual node of an interconnected surgical suite, comprising the optical probe, cold light engine (LED or solid-state laser), camera control unit (CCU) with dedicated image signal processors (ISP), automated carbon dioxide insufflators, and accompanying electrosurgical endo-instruments. The global laparoscope market size is projected to expand from an estimated 4.4-6.4 billion USD in 2026 to significant scale by 2031, advancing at a compound annual growth rate (CAGR) of 5.2%-7.2%. Market momentum is fundamentally anchored in the structural shift toward Ultra-High Definition (4K), stereoscopic 3D depth perception, and multi-spectral Near-Infrared (NIR) fluorescence imaging, primarily using indocyanine green (ICG). Concurrently, healthcare economics are redirecting high-volume elective laparoscopic operations from conventional inpatient tertiary facilities toward Ambulatory Surgical Centers (ASCs). This shift forces original equipment manufacturers (OEMs) to rethink hardware footprints, modularity, and total cost of ownership.
Product Architecture and Optical Classification
The laparoscope market is categorized across two core technical axes: mechanical/optical physical architecture and image dimension/visualization technology.
1. Mechanical and Optical Architecture
- Rigid Laparoscope: Serves as the historical workhorse across general surgery suites. Constructed from stainless steel or medical-grade titanium tubing, these scopes house high-precision optical rod lenses (such as classic Hopkins designs). Built to endure over 500 high-temperature autoclave or low-temperature hydrogen peroxide gas plasma sterilization cycles, rigid scopes are standardized at 3mm (pediatric), 5mm, 5.5mm, and 10mm outer diameters, with fixed 0-degree, 30-degree, and 45-degree angles of view. Market leaders include Karl Storz, Stryker, Olympus, CONMED, and specialized optical manufacturers like Qingdao NovelBeam.
- Video Laparoscope (Chip-on-the-Tip): Replaces conventional glass rod-lens channels with miniaturized CMOS image sensors mounted at the distal tip or inside an ergonomic camera handle. Direct digital conversion at the point of capture eliminates the optical attenuation typical of long optical trains, reducing overall assembly weight and facilitating direct high-speed digital interfaces with video processors.
- Flexible and Articulating Laparoscope: Combines flexible scope shafts or mechanical wrist-joint mechanisms at the distal tip, allowing surgeons to deflect the viewing trajectory around anatomical barriers without losing horizon orientation. Handheld multi-joint articulating systems, such as LivsMed's ArtiSential, bridge the gap between static laparoscopy and high-cost surgical robotics by delivering up to seven degrees of freedom.
2. Image Dimension and Optical Technology
- 2D Laparoscope: Standard visualization platforms delivering Full HD (1080P) video streams. While widely deployed throughout secondary and rural medical centers, baseline 2D systems face steady phase-out across tertiary academic surgical centers.
- 3D Stereoscopic Laparoscope: Integrates dual optical pathways or binocular CMOS sensors to reproduce true spatial depth. The restoration of natural stereoscopic depth shortens the technical learning curve for complex intracorporeal suturing, precise vessel skeletonization, and oncologic micro-dissections.
- Fluorescence Laparoscope: Employs multi-spectral optical filters and dual-band laser/LED light engines to combine standard 4K white light with NIR fluorescence (typically 800-900nm). This allows intraoperative visualization of ICG or targeted fluorescent tracers to evaluate microvascular perfusion, chart real-time biliary anatomy, and map sentinel lymph node drainage.
- Heated and Anti-Fogging Laparoscope: Implements distal electrical resistance heating elements, micro-fluidic channels, or integrated software defogging algorithms. These systems prevent lens condensation triggered by intra-abdominal humidity shifts, temperature gradients, and electrosurgical smoke.
- Integrated Quad-Modality Laparoscope: The modern technological benchmark, consolidating 4K UHD resolution, 3D stereoscopic vision, real-time NIR fluorescence, and active distal anti-fogging within a single scope and CCU architecture.
Downstream Clinical Applications and Demand Dynamics
Laparoscopic visualization platforms support high-acuity interventions across multiple surgical domains:
- General Surgery: The largest volume consumer of laparoscopic instrumentation. Core procedures comprise laparoscopic cholecystectomy, appendectomy, bariatric gastrectomy, hernia repairs utilizing prosthetic meshes, and oncologic resections of the gastrointestinal tract and liver.
- Gynecological Surgery: Demands exceptional spatial contrast and thermal tissue control for procedures such as total laparoscopic hysterectomies, deep infiltrating endometriosis excisions, myomectomies, and retroperitoneal lymph node dissections.
- Urological Surgery: Driven by partial and radical nephrectomies, pyeloplasty, and prostatectomies. Clinical workflows increasingly combine 3D fluorescence laparoscopy with real-time laparoscopic ultrasound probes to establish clean parenchymal resection margins during nephron-sparing surgeries.
- Thoracic Surgery (VATS): Employs specialized rigid and deflectable thoracoscopes for anatomic lung segmentectomies, lobectomies, and mediastinal mass excisions.
- Pediatric and Scarless Laparoscopy: Deploys 1.9mm to 3mm micro-laparoscopes for congenital corrections, limiting surgical trauma and post-operative tissue adhesion formation.
Commercial Sales Channels and Ecosystem Go-to-Market
- Direct Institutional Sales: Standard across primary markets including the United States, Western Europe, and Japan. Capital equipment providers maintain field clinical specialists and direct commercial representatives to support surgeon credentialing, operating room integration, and post-sale technical services.
- Group Purchasing Organizations (GPOs) and Integrated Delivery Networks (IDNs): In North America, dominant GPOs (such as Premier, Vizient, and HealthTrust) control commercial access across more than 80% of institutional hospital beds. Securing centralized contract awards through aggressive discounting, standardized administrative fees, and bundled clinical tiers is a prerequisite for broad market adoption.
- Independent Specialty Distributors: Dominant across emerging territories, decentralized public hospital systems, and secondary regional facilities. Distributors navigate local product clearances, manage import tariffs, participate in public tenders, and provide field-level repairs.
- Consignment and Capital-Consumable Bundling: High-turnover accessories, such as trocars, stapler cartridges, and specimen bags, are routinely supplied under consignment agreements where payment is triggered upon procedural utilization. High-end camera towers are frequently placed at subsidized capital cost when bundled with long-term procedural consumable commitments and multi-year maintenance service contracts.
Global Supply Chain and Value Chain Architecture
The laparoscope industry operates across three distinct structural tiers:
- Upstream Material and Sensor Core: Encompasses high-purity optical glass rods, synthetic sapphire cover crystals, low-dispersion transmission fibers, medical-grade titanium and surgical stainless steel, alongside advanced optoelectronic components. The primary value drivers are high-performance medical CMOS sensors, custom ASICs, and high-speed Field Programmable Gate Arrays (FPGAs) engineered for zero-latency video processing.
- Midstream Systems Integration and Algorithmic R&D: Involves hermetic laser welding, optical element alignment, glass-to-metal solder sealing capable of surviving repeated high-pressure steam autoclaves, and image processing algorithm engineering (ISP). Manufacturers must manage complex regulatory compliance matrices across the US FDA, EU MDR, China NMPA, and Japan PMDA.
- Downstream Clinical Delivery: Aggregated across national tender platforms, GPO purchasing consortiums, tertiary academic health centers, and independent surgical clinics.
Regional Market Landscapes and Policy Frameworks
- North America: Represents the largest revenue center, driven by advanced surgical procedure volumes and rapid ASC adoption. The regulatory path is governed by the FDA (transitioning from 21 CFR Part 820 toward the ISO 13485:2016-aligned QMSR framework). The Centers for Medicare & Medicaid Services (CMS) exerts significant pricing influence through outpatient and ASC fee schedules, establishing fixed procedural reimbursement that favors efficient, rapid-turnaround surgical devices.
- Asia-Pacific: The highest-growth geographic theater, projected to achieve top-tier CAGR through 2031. Growth is underpinned by healthcare infrastructure modernization, surging surgical volumes, and supportive national industry directives. In China, Volume-Based Procurement (VBP) continues to exert severe downward price adjustments on surgical consumables and staplers, while domestic evaluation policies (e.g., price appraisal discounts in state tenders) accelerate import substitution in visualization towers. Japan, home to optical pioneers Olympus and PENTAX, maintains high clinical penetration of 4K/3D systems under stringent PMDA technical oversight. South Korea leads innovation in articulated hand instruments, supported by expanding national health insurance codes. Emerging developments in India and Southeast Asia center on hospital modernization and the buildout of advanced surgical suites.
- Europe: The second-largest market, characterized by mature single-payer national health structures and strict infection prevention guidelines. Regulatory pathways are dictated by the European Medical Device Regulation (EU MDR 2017/745). Extended compliance deadlines (stretching to 2027/2028 depending on device risk class) have led to elevated clinical evaluation expenses and capacity constraints across European Notified Bodies. Specific regional containment measures, such as Italy's Medical Device Payback mechanism, compress manufacturer operating margins.
- South America: Marked by high public hospital procedural volumes alongside capital procurement limitations. Private healthcare networks across Brazil (ANVISA) and Mexico (COFEPRIS) support steady demand for 4K video systems, while public institutions prioritize durable, cost-effective rigid rod-lens systems with long working lifecycles.
- Africa and the Middle East (MEA): Characterized by substantial investments across Gulf Cooperation Council (GCC) healthcare infrastructure, featuring state-of-the-art digital surgical facilities. Regulatory alignment is supported by the African Medical Devices Forum (AMDF) and unified GCC registration processes, which routinely utilize FDA 510(k) clearances and CE marks for accelerated regional entry.
Company Profiles
- Medtronic: Leverages a comprehensive minimally invasive surgical platform. The company integrates its EleVision HD and 4K visualization systems with market-leading procedural portfolios, including Signia stapling lines, LigaSure vessel sealers, and the Hugo Robotic-Assisted Surgery (RAS) platform. Operational moat: deep surgical suite bundling power, broad direct distribution infrastructure, and unified capital-consumable contracting across global hospital systems.
- Olympus Corporation: A pioneer in endo-surgical visualization, Olympus anchors its footprint through the VISERA ELITE III system, which integrates 4K, 3D, and NIR imaging into a single CCU. Proprietary Narrow Band Imaging (NBI) and the articulating ENDOEYE 3D video laparoscope series provide high clinical differentiation. Strategic pivot: divesting non-core peripheral businesses to focus resources on advanced surgical energy platforms, chip-on-the-tip scopes, and single-port visualization solutions.
- Stryker Corporation: A global leader in hospital operating room technology. The 1788 4K imaging suite, combined with proprietary SPY-PHI Near-Infrared fluorescence technology, enables multi-wavelength navigation across visible and near-infrared light spectrums. Operational moat: the Connected OR suite, linking PneumoClear smoke evacuation insufflation directly to camera visualization control, supported by long-standing commercial ties to top-tier US GPO accounts.
- Qingdao NovelBeam Technology: A preeminent optical engineering specialist. NovelBeam operates as a critical ODM/OEM partner to Tier-1 global visualization companies (notably providing core optical modules and multi-spectral fluorescence scopes) while simultaneously commercializing branded 4K fluorescence systems across domestic and emerging markets. Technical moat: proprietary multi-band optical lens coatings, ultra-low chromatic aberration fabrication, and high-efficiency NIR transmission architectures.
- Mindray: A fast-scaling multinational medical device enterprise deploying an integrated cross-departmental strategy. The UX5 and SV7 imaging towers combine 4K resolution, 3D depth perception, and multi-mode ICG fluorescence with proprietary smoke-evacuating high-flow insufflators. Strategic pivot: leveraging its dominant market share in patient monitors, anesthesia workstations, and ultrasound to win multi-million-dollar comprehensive hospital ward and OR modernization packages.
- SonoScape Medical Corp.: Leveraging strong ultrasound engineering foundations, SonoScape commercializes the SV-M4K high-definition and SV-M4K200 4K/3D NIR laparoscopy systems. Operational moat: multi-modal fusion imaging capabilities, directly pairing high-resolution video laparoscopy with laparoscopic ultrasound probes (LAP8) to guide real-time parenchymal oncology dissections.
- B. Braun (Aesculap): Specializes in precision surgical instrumentation and digital stereoscopic visualization. The EinsteinVision 3.0 and 3.0 FI platforms integrate 3D UHD binocular visualization, active anti-fog heating elements, and automated robotic scope holding interfaces. Strategic pivot: advancing high-precision mechanical instrumentation and robotic OR integration to preserve surgeon comfort during complex, extended abdominal interventions.
- KARL STORZ: An established benchmark in precision rod-lens optical engineering. The IMAGE1 S platform unifies 4K UHD, stereoscopic 3D, and NIR fluorescence (Rubina series) via modular hardware. Proprietary S-Technologies (CLARA, CHROMA, SPECTRA) allow customized intraoperative optical tissue enhancements. Strategic moat: broad clinical loyalty, an extensive HOPKINS rod-lens patent foundation, and enterprise-scale OR1 digital operating room integration.
- Micro-Tech Endoscopy: Globally recognized for flexible endoscopic therapy accessories, Micro-Tech provides an expansive, cost-competitive consumable portfolio supporting laparoscopic access. Products include disposable optical trocars, single-use retrieval bags, ligation clips, and hybrid single-use visualization catheter tools. Operational moat: high-efficiency high-volume manufacturing lines and rapid distribution expansion across global outpatient networks.
- XION GmbH: A specialized German developer of endoscopic video systems, providing the Matrix series of universal video processors. The company specializes in multi-specialty adaptability, allowing unified processors to drive rigid 4K autoclavable laparoscopes alongside flexible chip-on-the-tip CMOS endoscopes for general surgery, gynecology, and head-and-neck procedures.
- SOMETECH Inc.: A South Korean surgical visualization provider emphasizing stereoscopic micro-imaging. SOMETECH develops dedicated 3D video laparoscopy consoles (such as the VLS-200), integrating binocular imaging channels, integrated cold LED sources, and polarized 3D display outputs to deliver depth-perceptive surgical visualization at competitive capital price points.
- Schoelly Fiberoptic GmbH: A premier German optical design and OEM/ODM engineering titan. Schoelly develops underlying 3D stereoscopic laparoscopes, 4K optical assemblies, and complex chip-on-the-tip modules for leading multinational surgical conglomerates. Technical moat: micro-optical engineering tolerances, structural channel symmetry for binocular optics, and durable hermetic scope sealing.
- Henke Sass Wolf GmbH: Headquartered in Tuttlingen, Germany, HSW is a foundational private-label developer and OEM partner for medical rigid endoscopes. Known for proprietary glass-to-metal solder joint sealing, sapphire protective covers, and high-transmission optical assemblies that deliver exceptional autoclave survivability without lens clouding.
- Arthrex Inc.: While anchored in sports medicine and arthroscopy, Arthrex exerts growing influence across multi-specialty laparoscopic general and gynecological surgery. The SynergyID all-in-one console merges 4K UHD resolution, quad-wavelength LED lighting, and NIR fluorescence with intuitive direct tablet control. Its micro-diameter NanoScope system provides single-incision diagnostic micro-laparoscopy capabilities in outpatient environments.
- Shinva Medical Instrument Co. Ltd.: A Chinese healthcare manufacturing conglomerate. Shinva manufactures integrated 4K laparoscopic imaging systems, high-flow heating insufflators, and specialized surgical hand instruments. Operational moat: direct alignment with central hospital sterile supply department (CSSD) infrastructure and comprehensive capital sterilization equipment across domestic public hospital tenders.
- Shandong Weigao Surgical Robot Co. Ltd.: The advanced robotics arm of Weigao Group, focusing on robotic minimally invasive surgery. The company developed the MicroHand robotic-assisted platform, integrating a 3D stereo-laparoscope on an automated arm with wristed micro-instruments to replicate open surgical dexterity through minimally invasive trocar ports.
- Shenyang Shenda Endoscope Co. Ltd.: One of the foundational rigid optical endoscopy manufacturers in China. Shenda engineers 4K UHD and fluorescent rigid laparoscopes, combining imported high-transmission optical elements with laser-welded stainless-steel assemblies compatible with global optical light guide standards.
Opportunities & Challenges
1. Strategic Drivers and Opportunities
- Value Acceleration Through Quad-Modality Integration: Capital consolidation within hospital procurement favors systems combining 4K, 3D, NIR ICG fluorescence, and active lens anti-fogging on a single CCU. This eliminates physical clutter in operating rooms, simplifies maintenance agreements, and expands clinical utility across general, thoracic, and urological surgery.
- Structural Procedure Migration to ASC Suites: The decentralization of standard interventions (such as cholecystectomies and inguinal hernia repairs) to ambulatory facilities demands high-efficiency, lightweight, low-maintenance visualization platforms. Suppliers designing streamlined camera towers with integrated smoke evacuation and low capital footprints are positioned to capture this shifting procedural volume.
- Handheld Articulation as a Bridge to Advanced Robotics: Full robotic-assisted surgical systems require multi-million-dollar capital outlays, dedicated floor space, and continuous per-procedure service and drape expenses. Handheld articulating laparoscopic systems with multiple degrees of freedom provide a cost-effective alternative. This enables mid-tier and community hospitals to perform complex minimally invasive operations without the financial overhead of full robotic platforms.
- Real-Time AI Surgical Navigation: The incorporation of computer vision and deep learning models into CCU image signal pipelines provides intraoperative anatomical landmark identification, real-time warning of critical structures (such as biliary ducts or major vessels), and automated surgical documentation. These capabilities enhance procedural safety and lower complication profiles.
2. Structural Industry Headwinds and Operational Challenges
- European Regulatory Bottlenecks (EU MDR): The administrative, clinical, and financial burdens imposed by EU MDR continue to challenge device commercialization across Europe. Delays in Notified Body reviews, paired with extensive post-market clinical follow-up requirements, create friction for optical device lifecycle updates and push manufacturers to prioritize North American and Asian product launches.
- Direct Price Compression via Centralized Procurement: Government-mandated tender models, notably China's Volume-Based Procurement (VBP) framework and Italy's Medical Device Payback legislation, compress gross margins across laparoscopic trocars, staplers, and consumable accessories. Suppliers must adapt by aggressively optimizing upstream manufacturing efficiencies, scaling production volumes, or pivoting to high-margin multi-spectral imaging towers.
- Geopolitical Sourcing Frictions and Localization Pressures: Ongoing trade investigations, shifting tariff policies (e.g., U.S. Section 232 reviews), and sovereign procurement domestic-content preferences (such as China's 20% price review discount for domestic medical technologies) challenge traditional cross-border supply chains. Global manufacturers must transition from centralized production toward distributed regional final-assembly strategies to protect market access.
- Capital Expenditure Constraints and Extended Scope Lifecycles: Global macroeconomic tightening and healthcare operating margin pressures frequently delay hospital capital replacement cycles. Many healthcare institutions choose to prolong the service life of existing 2D and Full HD camera platforms through outsourced third-party maintenance, temporarily damping the pace of hospital-wide conversion to next-generation 4K 3D fluorescence towers.
1.1 Study Perimeter and Industry Taxonomy 1
1.2 Bottom-Up and Top-Down Triangulation Methodology 2
1.3 Primary Source Validation and Expert Consensus Panels 3
1.4 Secondary Information Mining and Database Modeling 4
1.5 Core Model Assumptions and Forecast Determinants (2027-2031) 5
1.6 Acronyms and Technical Nomenclature 6
Chapter 2 Global Laparoscope Industry Ecosystem & Value Chain Dynamics 7
2.1 End-to-End Laparoscope Value Chain Architecture 7
2.2 Upstream Raw Materials, Precision Optical Components, and Rod Lens Sourcing 9
2.3 CMOS and CCD Image Sensors, Light Guide Bundles, and LED/Laser Illumination Feeds 11
2.4 Midstream Assembly, Optical Alignment, Laser Welding, and Hermetic Sealing 12
2.5 Downstream Distribution Channels, GPO Procurement, and Hospital Capital Cycles 13
Chapter 3 Global Production Capacity, Output, and Cross-Border Trade Flows 15
3.1 Global Manufacturing Capacity Footprint and Regional Cluster Mapping 15
3.2 Historical and Current Output Metrics: Global Volume and Value Trends (2021-2026) 17
3.3 Critical Exporting Hubs: Germany (Tuttlingen), Japan, China, and the United States 19
3.4 Cross-Border Tariff Landscapes, Regulatory Barriers (MDR/FDA), and Supply Vulnerabilities 21
Chapter 4 Global Laparoscope Market by Mechanical & Optical Architecture 24
4.1 Architectural Divergence: Optical Rigidity vs. Articulating Maneuverability 24
4.2 Rigid Laparoscopes: Market Sizing, Pricing Realization, and Demand (2021-2031) 25
4.3 Video Laparoscopes (Distal Sensor Technology): Scale, ASP, and Projections (2021-2031) 28
4.4 Flexible Laparoscopes: Ergonomics, Mechanical Durability, and Adoption (2021-2031) 30
Chapter 5 Global Laparoscope Market by Image Dimension & Advanced Technology 32
5.1 Standard 2D Laparoscopy Systems: Mature Base and Replacement Trends (2021-2031) 32
5.2 High-Definition 3D Laparoscopy: Depth Perception and Clinical Efficacy (2021-2031) 34
5.3 Fluorescence Laparoscopes (NIR/ICG Perfusion & Lymphatic Mapping) (2021-2031) 36
5.4 Heated/Anti-fogging Laparoscopy Platforms: Workflow Optimization (2021-2031) 38
5.5 Integrated All-in-1 Laparoscopes (Embedded Camera/Light Source/Control) (2021-2031) 39
Chapter 6 Downstream Surgical Applications & Clinical Adoption Trajectories 41
6.1 General Laparoscopic Surgeries (Cholecystectomy, Appendectomy, Hernia Repair) 41
6.2 Gynecological Laparoscopic Procedures (Hysterectomy, Myomectomy, Endometriosis) 43
6.3 Urological Interventions (Nephrectomy, Prostatectomy, Adrenalectomy) 45
6.4 Bariatric and Metabolic Interventions 46
6.5 Pediatric Minimally Invasive Surgery and Microlaparoscopy 47
Chapter 7 North America Laparoscope Market Analysis 49
7.1 United States: Premium 4K/3D/NIR Adoption, GPO Contracting, and Outpatient Surge 49
7.2 Canada: Public Health Procurement, Capital Equipment Cycles, and Volume Growth 53
Chapter 8 Europe Laparoscope Market Analysis & Manufacturing Clusters 56
8.1 Germany: Precision Manufacturing Center (Tuttlingen) and Domestic Uptake 56
8.2 France & United Kingdom: DRG Pressures, Sterilization Mandates, and Tender Trends 58
8.3 Italy, Spain, and Rest of Europe: Replacement Cycles and Public Tenders 60
Chapter 9 Asia-Pacific Laparoscope Market Dynamics 63
9.1 China: Domestic Substitution Policies, Volume-Based Procurement, and Export Scale 63
9.2 Japan: Advanced Micro-Optics Manufacturing, Aging Demographics, and Clinical Standards 66
9.3 South Korea: Advanced Medical Robotics Integration and Imaging Innovation 68
9.4 India & Southeast Asia: Hospital Infrastructure Modernization and Volume Uptake 70
Chapter 10 Latin America, Middle East & Africa Market Dynamics 72
10.1 Brazil & Mexico: Dual Public-Private Healthcare Dynamics and Import Dependency 72
10.2 GCC Economies (Saudi Arabia, UAE): Specialized Surgical Centers and Capital Expansion 74
10.3 South Africa & Rest of Middle East/Africa: Penetration Bottlenecks and Used Equipment 75
Chapter 11 Global Competitive Landscape & Market Structure Benchmarking 77
11.1 Global Tiered Market Share Distribution and Industry Consolidation 77
11.2 Technological Parity Benchmarking: Resolution, Sensor Placement, and Illumination 79
11.3 Sterilization Protocols, Autoclavability Benchmarks, and Single-Use Encroachment 81
11.4 Strategic M&A, Licensing, and Robotic Surgery Integration Agreements 82
Chapter 12 Corporate Intelligence & Competitive Benchmarking 84
12.1 Medtronic 84
12.1.1 Corporate Overview, Minimally Invasive Therapies Positioning, and Footprint 84
12.1.2 Product Portfolio Analysis and Technological Roadmaps 85
12.1.3 Strategic SWOT Diagnostic 86
12.1.4 Laparoscope Financials: Revenue, COGS, Gross Margin, and Share (2021-2026) 87
12.2 Olympus Corporation 88
12.2.1 Corporate Overview and Global Surgical Endoscopy Platform Analysis 88
12.2.2 Optical Innovation, 3D/4K EndoEYE Line, and Production Networks 89
12.2.3 Strategic SWOT Diagnostic 90
12.2.4 Laparoscope Financials: Revenue, COGS, Gross Margin, and Share (2021-2026) 91
12.3 Stryker Corporation 92
12.3.1 Corporate Overview, Endoscopy Division, and Integrated OR Ecosystems 92
12.3.2 Advanced Fluorescence Imaging (1688/1788 Platforms) and Commercial Strategy 93
12.3.3 Strategic SWOT Diagnostic 94
12.3.4 Laparoscope Financials: Revenue, COGS, Gross Margin, and Share (2021-2026) 95
12.4 Qingdao NovelBeam Technology 96
12.4.1 Corporate Profile, Optical Component Heritage, and System Integration 96
12.4.2 Fluorescence Endoscopy Core Technologies and Global ODM/OEM Partnerships 97
12.4.3 Strategic SWOT Diagnostic 98
12.4.4 Laparoscope Financials: Revenue, COGS, Gross Margin, and Share (2021-2026) 99
12.5 Mindray 100
12.5.1 Corporate Profile and Surgical System Business Unit Trajectory 100
12.5.2 High-Definition 4K and HyPixel R1 Integration Architecture 101
12.5.3 Strategic SWOT Diagnostic 102
12.5.4 Laparoscope Financials: Revenue, COGS, Gross Margin, and Share (2021-2026) 103
12.6 SonoScape Medical Corp. 104
12.6.1 Corporate Overview, Endoscopy Expansion, and Capital Resource Allocation 104
12.6.2 Laparoscopic Imaging Systems, Sensor Formats, and Global Channels 105
12.6.3 Strategic SWOT Diagnostic 106
12.6.4 Laparoscope Financials: Revenue, COGS, Gross Margin, and Share (2021-2026) 107
12.7 B. Braun 108
12.7.1 Corporate Structure and Aesculap Endoscopic Division Footprint 108
12.7.2 EinsteinVision 3D Camera Platforms and Mechanical Scope Engineering 109
12.7.3 Strategic SWOT Diagnostic 110
12.7.4 Laparoscope Financials: Revenue, COGS, Gross Margin, and Share (2021-2026) 111
12.8 KARL STORZ 112
12.8.1 Corporate Heritage, Tuttlingen Industrial Cluster, and Global Standing 112
12.8.2 IMAGE1 S Architecture, Specialized Rigid Scopes, and OPAL1 NIR/ICG 113
12.8.3 Strategic SWOT Diagnostic 114
12.8.4 Laparoscope Financials: Revenue, COGS, Gross Margin, and Share (2021-2026) 115
12.9 Micro-Tech Endoscopy 116
12.9.1 Corporate Background and Minimally Invasive Surgical Device Focus 116
12.9.2 Product Engineering, Single-Use vs. Reusable Portfolios, and Expansion 117
12.9.3 Strategic SWOT Diagnostic 118
12.9.4 Laparoscope Financials: Revenue, COGS, Gross Margin, and Share (2021-2026) 119
12.10 XION GmbH 120
12.10.1 Corporate Profile, German Precision Optics Base, and Product Lineup 120
12.10.2 Sensor-on-the-Tip Video Endoscopy Platforms and Clinical Ergonomics 121
12.10.3 Strategic SWOT Diagnostic 122
12.10.4 Laparoscope Financials: Revenue, COGS, Gross Margin, and Share (2021-2026) 123
12.11 SOMETECH Inc 124
12.11.1 Corporate Structure, South Korean R&D Infrastructure, and Market Base 124
12.11.2 3D Heads-Up Real-Time Laparoscopic Platforms and Compact Systems 125
12.11.3 Strategic SWOT Diagnostic 126
12.11.4 Laparoscope Financials: Revenue, COGS, Gross Margin, and Share (2021-2026) 127
12.12 Schoelly Fiberoptic GmbH 128
12.12.1 Corporate Background, Fiberoptic Specialization, and OEM Core Engine 128
12.12.2 Micro-Camera Modules, 3D Articulating Laparoscopes, and Optical Transducers 129
12.12.3 Strategic SWOT Diagnostic 130
12.12.4 Laparoscope Financials: Revenue, COGS, Gross Margin, and Share (2021-2026) 131
12.13 Henke Sass Wolf GmbH 132
12.13.1 Corporate Overview, Precision Flow and Medical Endoscopy Heritage 132
12.13.2 Optical Train Innovation, Sapphire Window Sealing, and OEM Manufacturing 133
12.13.3 Strategic SWOT Diagnostic 134
12.13.4 Laparoscope Financials: Revenue, COGS, Gross Margin, and Share (2021-2026) 135
12.14 Arthrex Inc 136
12.14.1 Corporate Scope, Synergy with Multispecialty Orthopedics and General Surgery 136
12.14.2 Synergy UHD4 Imaging Line, Autoclavable Optics, and Integrated Solutions 137
12.14.3 Strategic SWOT Diagnostic 138
12.14.4 Laparoscope Financials: Revenue, COGS, Gross Margin, and Share (2021-2026) 139
12.15 Shinva Medical Instrument Co. Ltd. 140
12.15.1 Corporate Profile, Hospital Engineering Infrastructure, and Endoscopy Unit 140
12.15.2 Rigid Laparoscope Product Lines, Hospital Tender Capabilities, and Capacity 141
12.15.3 Strategic SWOT Diagnostic 142
12.15.4 Laparoscope Financials: Revenue, COGS, Gross Margin, and Share (2021-2026) 143
12.16 Shandong Weigao Surgical Robot Co. Ltd. 144
12.16.1 Corporate Overview, Surgical Robotics Synergy, and Laparoscopic Integration 144
12.16.2 3D HD Endoscopic Platforms for Robotic and Manual Surgeries 145
12.16.3 Strategic SWOT Diagnostic 146
12.16.4 Laparoscope Financials: Revenue, COGS, Gross Margin, and Share (2021-2026) 147
12.17 Shenyang Shenda Endoscope Co. Ltd. 148
12.17.1 Corporate Heritage as Pioneer Optical Instrument Manufacturer in China 148
12.17.2 Domestic Rigid Laparoscopic Lineups, Distribution Networks, and Export Outlets 149
12.17.3 Strategic SWOT Diagnostic 150
12.17.4 Laparoscope Financials: Revenue, COGS, Gross Margin, and Share (2021-2026) 151
Table 2 Key Optical and Mechanical Design Specifications of Leading Laparoscope Formats 8
Table 3 Global Laparoscope Manufacturing Capacity by Region and Leading Hub (2021-2026) 16
Table 4 Global Laparoscope Production Output Volume by Region (Units, 2021-2026) 18
Table 5 Cross-Border Trade Matrix: Major Export Hubs vs. Core Ingestion Markets (2025) 20
Table 6 Global Laparoscope Revenue by Architecture (Rigid, Video, Flexible) (2021-2031) 24
Table 7 Global Rigid Laparoscope Sales Volume, Average Selling Price, and Value (2021-2031) 27
Table 8 Global Video Laparoscope Sales Volume, Average Selling Price, and Value (2021-2031) 29
Table 9 Global Flexible Laparoscope Sales Volume, Average Selling Price, and Value (2021-2031) 31
Table 10 Global Laparoscope Revenue by Technology (2D, 3D, NIR, Heated, Integrated) (2021-2031) 33
Table 11 Global 2D Laparoscope Market Size and Growth Metrics (2021-2031) 34
Table 12 Global 3D Laparoscope Market Size and Growth Metrics (2021-2031) 35
Table 13 Global Fluorescence (NIR/ICG) Laparoscope Market Size and Projections (2021-2031) 37
Table 14 Global Heated and Anti-fogging Laparoscope Market Penetration Metrics (2021-2031) 38
Table 15 Global Integrated All-in-1 Laparoscope Shipments and Market Scale (2021-2031) 40
Table 16 Global Laparoscope Demand by Clinical Application (2021-2031) 42
Table 17 North America Laparoscope Market Revenue by Product Architecture (2021-2031) 50
Table 18 United States Laparoscope Market Revenue by Technology Class (2021-2031) 52
Table 19 Canada Laparoscope Market Revenue by End-Use Setting (2021-2031) 54
Table 20 Europe Laparoscope Market Revenue by Key Country (2021-2031) 57
Table 21 Germany Laparoscope Production, Domestic Ingestion, and Export Shipments (2021-2031) 58
Table 22 France and United Kingdom Laparoscope Installation Base by Modality (2021-2031) 60
Table 23 Italy and Spain Laparoscope Market Sizing and Replacement Volume (2021-2031) 61
Table 24 Asia-Pacific Laparoscope Market Revenue by Country (2021-2031) 64
Table 25 China Laparoscope Market Consumption, Local Production, and Import Share (2021-2031) 65
Table 26 Japan Laparoscope Market Size, Replacement Rates, and Modality Split (2021-2031) 67
Table 27 South Korea Laparoscope Volume Demand and Robotic Interface Adoption (2021-2031) 69
Table 28 Latin America, Middle East & Africa Laparoscope Revenue by Region (2021-2031) 73
Table 29 Global Competitive Tiering: Top 5, Top 10, and Regional Player Market Share (2021-2026) 78
Table 30 Technical Benchmark: Sensor Type, Light Integration, Autoclavability Across Major Brands 80
Table 31 Medtronic Laparoscope Revenue, Cost, and Gross Margin (2021-2026) 87
Table 32 Olympus Corporation Laparoscope Revenue, Cost, and Gross Margin (2021-2026) 91
Table 33 Stryker Corporation Laparoscope Revenue, Cost, and Gross Margin (2021-2026) 95
Table 34 Qingdao NovelBeam Technology Laparoscope Revenue, Cost, and Gross Margin (2021-2026) 99
Table 35 Mindray Laparoscope Revenue, Cost, and Gross Margin (2021-2026) 103
Table 36 SonoScape Medical Corp. Laparoscope Revenue, Cost, and Gross Margin (2021-2026) 107
Table 37 B. Braun Laparoscope Revenue, Cost, and Gross Margin (2021-2026) 111
Table 38 KARL STORZ Laparoscope Revenue, Cost, and Gross Margin (2021-2026) 115
Table 39 Micro-Tech Endoscopy Laparoscope Revenue, Cost, and Gross Margin (2021-2026) 119
Table 40 XION GmbH Laparoscope Revenue, Cost, and Gross Margin (2021-2026) 123
Table 41 SOMETECH Inc Laparoscope Revenue, Cost, and Gross Margin (2021-2026) 127
Table 42 Schoelly Fiberoptic GmbH Laparoscope Revenue, Cost, and Gross Margin (2021-2026) 131
Table 43 Henke Sass Wolf GmbH Laparoscope Revenue, Cost, and Gross Margin (2021-2026) 135
Table 44 Arthrex Inc Laparoscope Revenue, Cost, and Gross Margin (2021-2026) 139
Table 45 Shinva Medical Instrument Co. Ltd. Laparoscope Revenue, Cost, and Gross Margin (2021-2026) 143
Table 46 Shandong Weigao Surgical Robot Co. Ltd. Laparoscope Revenue, Cost, and Gross Margin (2021-2026) 147
Table 47 Shenyang Shenda Endoscope Co. Ltd. Laparoscope Revenue, Cost, and Gross Margin (2021-2026) 151
Figure 1 Laparoscope Research Triangulation and Analytical Horizon (2021-2031) 3
Figure 2 End-to-End Laparoscope Industry Value Chain Breakdown 8
Figure 3 Primary Manufacturing Hubs vs. Demand Ingestion Centers Globally 16
Figure 4 Global Laparoscope Historic and Forecast Value Trajectory (2021-2031) 18
Figure 5 Global Trade Inflow and Outflow Balance for Surgical Laparoscopes (2025) 21
Figure 6 Global Architecture Share Dynamics: Rigid vs. Video vs. Flexible (2021-2031) 25
Figure 7 Global Laparoscope Revenue Share by Imaging Technology (2021-2031) 33
Figure 8 Adoption Acceleration Curve: NIR/ICG Fluorescence vs. Standard 2D Modalities 36
Figure 9 End-Use Distribution of Laparoscopes Across Surgical Specialties (2026) 42
Figure 10 North America Laparoscope Market Trajectory and Outpatient Center Share (2021-2031) 51
Figure 11 European Laparoscope Revenue Concentration Across Key Regional Markets 56
Figure 12 Asia-Pacific Laparoscope Expansion Velocity and Volume Evolution 63
Figure 13 Latin America and MEA Regional Growth Dynamics (2021-2031) 72
Figure 14 Global Laparoscope Manufacturer Herfindahl-Hirschman Index (HHI) (2021-2026) 78
Figure 15 Medtronic Laparoscope Global Market Share (2021-2026) 87
Figure 16 Olympus Corporation Laparoscope Global Market Share (2021-2026) 91
Figure 17 Stryker Corporation Laparoscope Global Market Share (2021-2026) 95
Figure 18 Qingdao NovelBeam Technology Laparoscope Global Market Share (2021-2026) 99
Figure 19 Mindray Laparoscope Global Market Share (2021-2026) 103
Figure 20 SonoScape Medical Corp. Laparoscope Global Market Share (2021-2026) 107
Figure 21 B. Braun Laparoscope Global Market Share (2021-2026) 111
Figure 22 KARL STORZ Laparoscope Global Market Share (2021-2026) 115
Figure 23 Micro-Tech Endoscopy Laparoscope Global Market Share (2021-2026) 119
Figure 24 XION GmbH Laparoscope Global Market Share (2021-2026) 123
Figure 25 SOMETECH Inc Laparoscope Global Market Share (2021-2026) 127
Figure 26 Schoelly Fiberoptic GmbH Laparoscope Global Market Share (2021-2026) 131
Figure 27 Henke Sass Wolf GmbH Laparoscope Global Market Share (2021-2026) 135
Figure 28 Arthrex Inc Laparoscope Global Market Share (2021-2026) 139
Figure 29 Shinva Medical Instrument Co. Ltd. Laparoscope Global Market Share (2021-2026) 143
Figure 30 Shandong Weigao Surgical Robot Co. Ltd. Laparoscope Global Market Share (2021-2026) 147
Figure 31 Shenyang Shenda Endoscope Co. Ltd. Laparoscope Global Market Share (2021-2026) 151
Research Methodology
- Market Estimated Methodology:
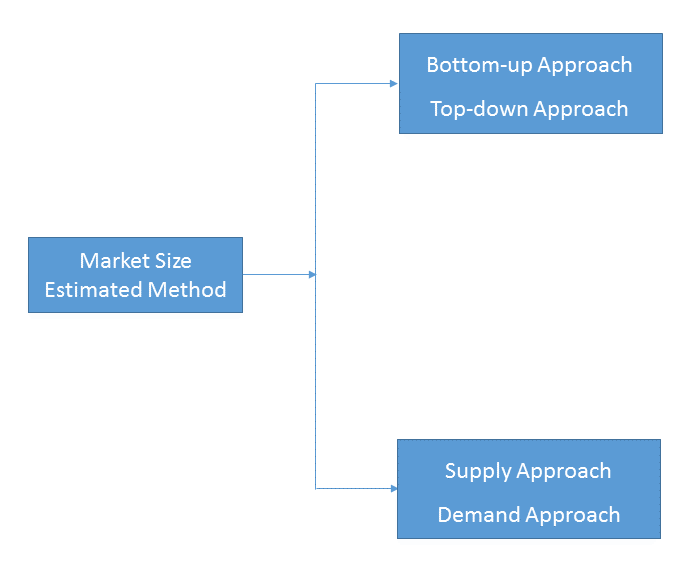
Bottom-up & top-down approach, supply & demand approach are the most important method which is used by HDIN Research to estimate the market size.
1)Top-down & Bottom-up Approach
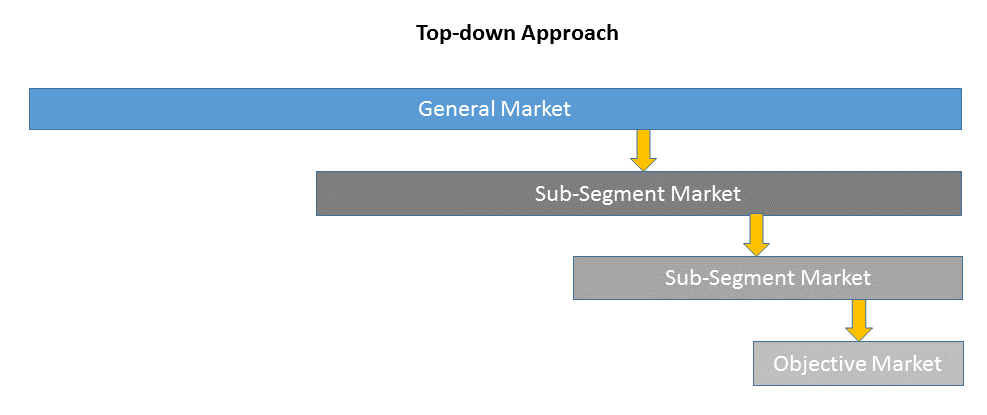
Top-down approach uses a general market size figure and determines the percentage that the objective market represents.
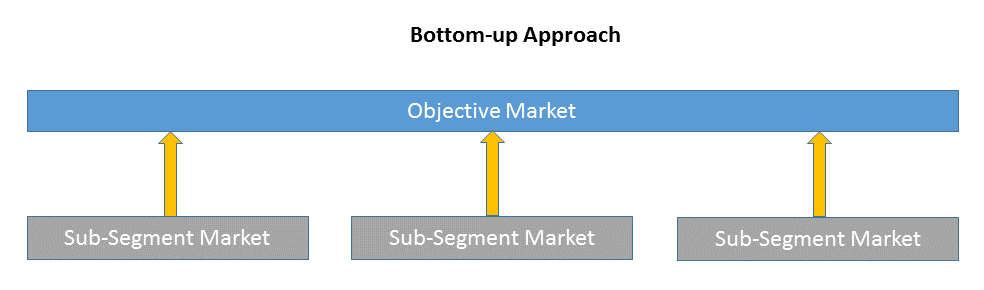
Bottom-up approach size the objective market by collecting the sub-segment information.
2)Supply & Demand Approach
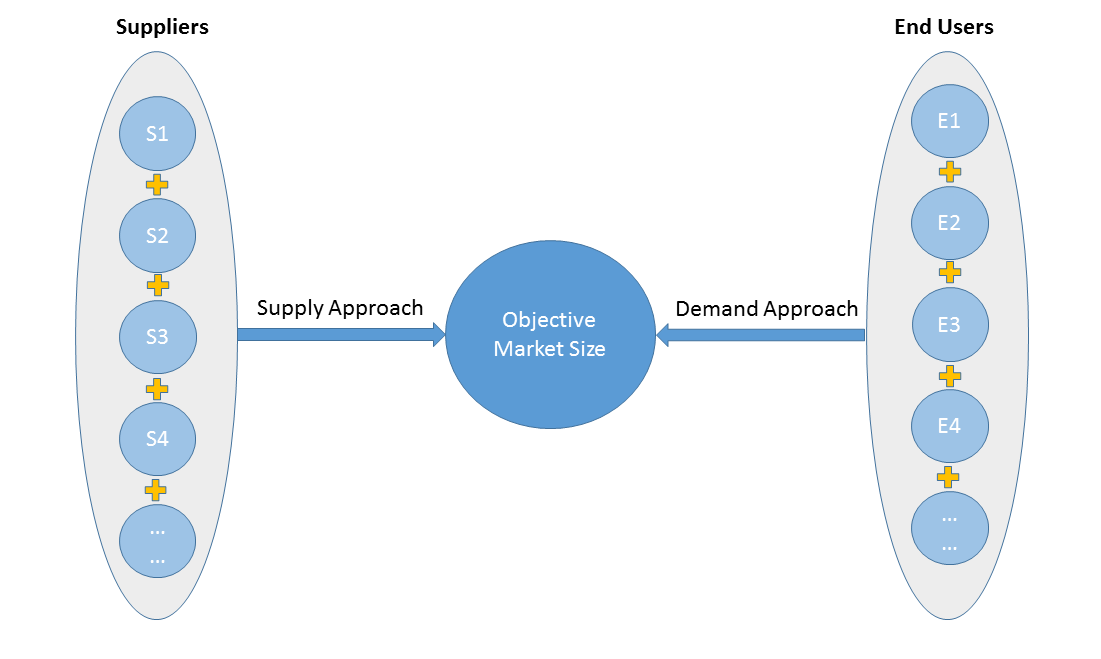
Supply approach is based on assessments of the size of each competitor supplying the objective market.
Demand approach combine end-user data within a market to estimate the objective market size. It is sometimes referred to as bottom-up approach.
- Forecasting Methodology
- Numerous factors impacting the market trend are considered for forecast model:
- New technology and application in the future;
- New project planned/under contraction;
- Global and regional underlying economic growth;
- Threatens of substitute products;
- Industry expert opinion;
- Policy and Society implication.
- Analysis Tools
1)PEST Analysis
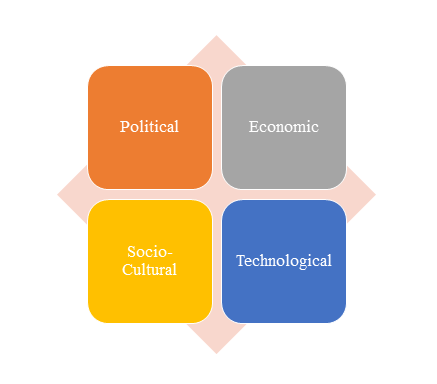
PEST Analysis is a simple and widely used tool that helps our client analyze the Political, Economic, Socio-Cultural, and Technological changes in their business environment.
- Benefits of a PEST analysis:
- It helps you to spot business opportunities, and it gives you advanced warning of significant threats.
- It reveals the direction of change within your business environment. This helps you shape what you’re doing, so that you work with change, rather than against it.
- It helps you avoid starting projects that are likely to fail, for reasons beyond your control.
- It can help you break free of unconscious assumptions when you enter a new country, region, or market; because it helps you develop an objective view of this new environment.
2)Porter’s Five Force Model Analysis
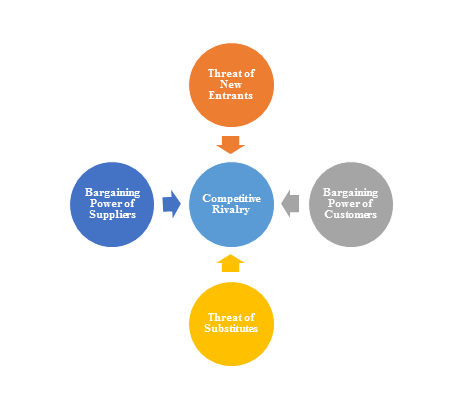
The Porter’s Five Force Model is a tool that can be used to analyze the opportunities and overall competitive advantage. The five forces that can assist in determining the competitive intensity and potential attractiveness within a specific area.
- Threat of New Entrants: Profitable industries that yield high returns will attract new firms.
- Threat of Substitutes: A substitute product uses a different technology to try to solve the same economic need.
- Bargaining Power of Customers: the ability of customers to put the firm under pressure, which also affects the customer's sensitivity to price changes.
- Bargaining Power of Suppliers: Suppliers of raw materials, components, labor, and services (such as expertise) to the firm can be a source of power over the firm when there are few substitutes.
- Competitive Rivalry: For most industries the intensity of competitive rivalry is the major determinant of the competitiveness of the industry.
3)Value Chain Analysis
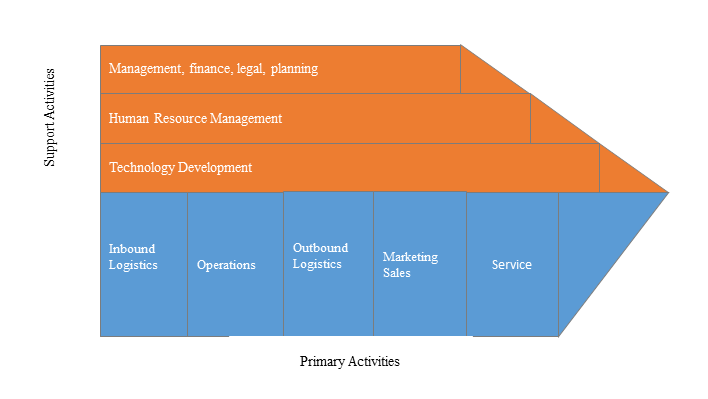
Value chain analysis is a tool to identify activities, within and around the firm and relating these activities to an assessment of competitive strength. Value chain can be analyzed by primary activities and supportive activities. Primary activities include: inbound logistics, operations, outbound logistics, marketing & sales, service. Support activities include: technology development, human resource management, management, finance, legal, planning.
4)SWOT Analysis
SWOT analysis is a tool used to evaluate a company's competitive position by identifying its strengths, weaknesses, opportunities and threats. The strengths and weakness is the inner factor; the opportunities and threats are the external factor. By analyzing the inner and external factors, the analysis can provide the detail information of the position of a player and the characteristics of the industry.
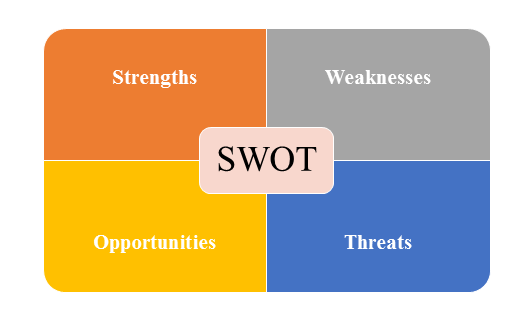
- Strengths describe what the player excels at and separates it from the competition
- Weaknesses stop the player from performing at its optimum level.
- Opportunities refer to favorable external factors that the player can use to give it a competitive advantage.
- Threats refer to factors that have the potential to harm the player.
- Data Sources
| Primary Sources | Secondary Sources |
|---|---|
| Face to face/Phone Interviews with market participants, such as: Manufactures; Distributors; End-users; Experts. Online Survey |
Government/International Organization Data: Annual Report/Presentation/Fact Book Internet Source Information Industry Association Data Free/Purchased Database Market Research Report Book/Journal/News |