Global Arthroscope Market Analysis & Strategic Outlook
- Single User License (1 Users) $ 3,500
- Team License (2~5 Users) $ 4,500
- Corporate License (>5 Users) $ 5,500
The global arthroscope market is driven by the decentralization of surgical care, shifts in optical sensor architectures, and an evolving interplay between capital hardware and high-margin soft tissue repair consumables. Functioning as the primary optomechatronic node in minimally invasive joint surgery, the arthroscope enables diagnostic visualization and therapeutic intervention through minimal arthrotomy portals. The global arthroscope market size is estimated between 1.2 billion USD and 2.2 billion USD in 2026, with a compound annual growth rate (CAGR) of 5.2% to 7.2% through 2031. Market expansion is propelled by an aging demographic requiring joint preservation, sustained innovation in biological augmentations for sports medicine, and the migration of orthopedic volume from inpatient operating rooms to Ambulatory Surgical Centers (ASCs). Concurrently, manufacturers face margin compression and inventory friction from centralized procurement mandates, including China's Volume-Based Procurement (VBP) and the European Union Medical Device Regulation (EU MDR) compliance framework.
Product Architecture and Technical Taxonomy
An arthroscope incorporates an outer medical-grade stainless steel sheath housing an optical relay train—traditionally composed of precision ground glass rod lenses or a miniaturized distal Complementary Metal Oxide Semiconductor (CMOS) sensor—surrounded by an integrated fiber-optic light bundle. It interfaces with an external optical trocar and cannula assembly providing high-flow fluid distension to expand intra-articular cavities and clear debris. The arthroscope acts as the visual terminal within a wider sports medicine tower ecosystem, interfacing with 4K camera processors, laser/LED illumination engines, automated fluid management pumps, motorized mechanical shavers, and radiofrequency ablation generators.
1. By Optical Architecture and Sensor Topology
● Hopkins Rod-Lens Arthroscope:
The dominant design across hospital operating environments relies on the Hopkins optical train. This architecture utilizes precision glass rod lenses with air spaces acting as thin lenses, producing superior spatial resolution, high depth of field, and minimal light attenuation. Modern iterations employ proprietary anti-reflective coatings and sapphire objective windows hermetically bonded to withstand repeated steam autoclave cycles. Innovation within this mature architecture centers on expanding the field of view (FOV). Precision optical designs, such as 110-degree wide-angle scopes developed by specialized manufacturers like Qingdao NovelBeam, reduce optical distortion to under 10% and limit peripheral defocusing relative to standard 70-degree optics. These assemblies are integrated directly into platforms such as Smith and Nephew's INTELLIO imaging ecosystem and OEM platforms distributed globally by Stryker.
● Digital Video Arthroscope (Chip-on-Tip / Sensor-Integrated):
This paradigm displaces the external camera head and mechanical rod-lens train by placing a sub-millimeter CMOS sensor directly at the distal tip of the scope or directly integrated into an ergonomic camera housing. Digital video scopes bypass optical-to-digital conversion losses, feeding raw digital signals directly into an image signal processor (ISP). This enables native 4K Ultra-HD capture, wide color gamut (BT.2020) reproduction, digital depth expansion, and multi-spectral imaging. The sensor integration facilitates fluorescence navigation, allowing near-infrared (NIR) imaging utilizing Indocyanine Green (ICG) or target-specific dyes to assess microvascular tissue perfusion during rotator cuff or labral repair. Stryker's 1788 4K platform, Smith and Nephew's TESSA spatial navigation architecture, and advanced Asian optoelectronic platforms exemplify this structural shift.
● Fiber-Optic Micro-Arthroscope:
Engineered for narrow articular geometries and diagnostic office applications, these scopes employ dense bundles of flexible optical glass fibers within shafts measuring under 2.0 mm in diameter. Micro-arthroscopes facilitate needle-arthroscopy under local anesthesia in outpatient procedure suites. This form factor circumvents surgical operating room bottlenecks, enabling direct dynamic assessment of small joint pathologies in the wrist, ankle, and elbow while minimizing soft tissue morbidity.
2. By Lifecycle Dynamics
● Reusable Arthroscope:
Manufactured from surgical stainless steel, titanium alloys, and synthetic sapphire, reusable arthroscopes are built to endure hundreds of high-temperature, high-pressure steam autoclave cycles (ISO 13485 compliance). While commanding a high upfront capital cost, their long-term cost per procedure is low for high-volume hospital central sterile supply departments (CSSDs). However, their operational deployment is constrained by repair overhead, seal degradation over time, and optical degradation from improper reprocessing.
● Single-Use / Disposable Arthroscope:
Comprising injection-molded medical polymers, thin-wall structural cannulas, and distal micro-CMOS sensors, single-use scopes are delivered pre-sterilized via ethylene oxide (EtO) or gamma irradiation. These systems eliminate the need for sterilization logistics, chemical reprocessing, and post-procedural scope turnaround time. Primarily adopted by high-turnover ASCs and outpatient diagnostic clinics, single-use visualization decouples facility throughput from CSSD capacity constraints, eliminating cross-contamination risks and scope wear-and-tear costs.
Downstream Clinical Applications and Procedural Migration
● Shoulder Arthroscopy:
Shoulder procedures represent the primary high-value segment within the arthroscope ecosystem. The segment is driven by procedures addressing rotator cuff tears (RCR), labral pathologies (Bankart and SLAP lesions), biceps tenodesis, and subacromial decompression. In the United States alone, the procedural volume for rotator cuff repair approximates 500,000 cases annually, creating an addressable soft tissue fixation and visualization market approaching 875.00 million USD. Because structural re-tear rates for standard mechanical repair historically vary between 20% and 40%, the clinical standard has shifted toward combining high-definition visualization with advanced biomaterials. Systems such as Smith and Nephew's REGENETEN bioinductive collagen implant (surpassing 200,000 surgical implantations) and specialized anchoring systems from CONMED and Stryker illustrate the integration of visualization platforms with regenerative biologic scaffolds to optimize structural outcomes.
● Knee Arthroscopy:
Maintaining the highest global procedural volume, knee arthroscopy encompasses meniscal repair and resection, anterior and posterior cruciate ligament (ACL/PCL) reconstruction, patellofemoral realignment, and chondral defect intervention. Visual clarity within tight articular compartments is essential for preserving the meniscal rim. Technological convergence is evident in the pairing of high-definition fluid-distension scopes with articulating repair systems, such as the FAST-FIX FLEX, and biologic scaffolds like the CARTIHEAL AGILI-C aragonite matrix. Concurrently, controlled plasma radiofrequency ablation (such as Coblation technology) is replacing mechanical resection for fine chondroplasty to minimize thermal damage to adjacent cartilage.
● Hip Arthroscopy and Joint Preservation:
Among the fastest-growing procedural sub-specialties, hip arthroscopy addresses femoroacetabular impingement (FAI), acetabular labral tearing, capsular laxity, and gluteal tendon pathology. The deep, constrained anatomy of the hip joint requires specialized visualization instruments, including elongated 70-degree rigid arthroscopes, high-pressure fluid distension circuits, and dedicated access cannulas. Labral refixation, knotless suture anchoring, and capsular closure systems dominate procedural spending within this high-growth clinical indication.
● Small Joint and Extremity Arthroscopy:
This category covers diagnostic and operative interventions across the wrist, elbow, ankle, and subtalar joints. Driven by dedicated micro-arthroscopic systems (1.9 mm and 2.7 mm diameters), extremity arthroscopy addresses chronic lateral ankle instability, syndesmotic disruptions, osteochondral lesions of the talus, and carpal instability. Procedural adoption in this segment relies heavily on pre-configured specialty kits that integrate micro-visualization optics with bioinductive augmentation materials.
Commercial Sales Channels and Go-to-Market Infrastructure
● Direct Enterprise Distribution:
In established medical device markets across North America, Western Europe, Japan, and Australia, commercial execution relies on dedicated direct sales organizations and authorized commercial agents. These sales forces interact directly with healthcare provider supply chains, Group Purchasing Organizations (GPOs), and Integrated Delivery Networks (IDNs). Sales personnel provide intraoperative technical support, advise on portal placement, and manage capital inventory across institutional networks.
● Emerging Market Distributor Networks:
Across emerging territories in the Asia-Pacific, Latin America, and the Middle East, manufacturers commercialize predominantly through multi-tier distribution channels, independent commercial dealers, and state-owned import-export intermediaries. Sales in these regions are heavily tied to national or provincial public hospital tendering frameworks, requiring local regulatory clearances and established distributor working-capital facilities.
● Capital-Consumable Placement Economics:
To circumvent capital spending freezes in both hospital networks and independent surgical centers, equipment manufacturers employ structured placement models. Core visualization hardware (4K digital camera processors, high-intensity cold light sources, mechanical shavers, and fluid pumps) is deployed at minimal or zero upfront capital cost. In exchange, the healthcare facility executes a multi-year master supply agreement (typically 12 to 36 months) committing to mandatory minimum purchase volumes of high-margin single-use procedural consumables. These consumables—including shaver blades, radiofrequency ablation probes, inflow-outflow fluid administration sets, and soft-tissue suture anchors—generate high-margin, recurring revenue streams that amortize the capital hardware over its functional lifecycle.
● Consignment Inventory Networks:
Due to procedural variation in patient anatomy and intra-articular pathology, orthopedic surgeons require immediate access to broad sizing matrices of implants, interference screws, and suture anchors. Manufacturers maintain extensive consigned inventory directly within hospital CSSDs and ASC storage facilities. Under this model, inventory holding costs are carried by the vendor; revenue is recognized only upon the formal logging of an opened and deployed implant during surgery.
● Government-Mandated Centralized Procurement:
Centrally administered procurement policies increasingly disrupt conventional commercial channels. China's Volume-Based Procurement (VBP) framework provides a clear case study: initially implemented for Sports Medicine Joint Repair implants, VBP led to severe reductions in average selling prices (ASPs) across national bidding pools. The subsequent expansion of VBP into arthroscopic enabling technologies (mechanical shavers, radiofrequency probes) and related surgical disciplines creates channel margin compression, requiring suppliers to optimize manufacturing costs and realign distribution arrangements.
Supply Chain Architecture and Value Migration
● Upstream: Material Synthesis and Optoelectronic Sourcing
The arthroscope supply chain relies on specialized medical-grade raw materials and precision optoelectronic components:
- Structural Alloys and Biomaterials: Medical-grade 304/316L stainless steel, surgical titanium alloys, and high-performance polyether ether ketone (PEEK) form the structural backbone of rigid cannulas, shaver burrs, and suture anchors. Biocompatible components include bioresorbable polymers (poly-L-lactic acid - PLLA), highly organized bovine collagen matrices, and marine-derived calcium carbonate (aragonite) scaffolds.
- Optical Substrates and Electronic Components: Core optical systems require optical-grade glass blanks, high-purity synthetic single-crystal sapphire for distal windows, and optical fiber bundles. Sensor integration depends on specialized CMOS image sensors, high-output LED and solid-state laser diode arrays, dichroic prisms, optical filters, and Field Programmable Gate Arrays (FPGAs) engineered for real-time edge computing and image signal processing.
● Midstream: Cleanroom Manufacturing, Hermetic Assembly, and OEM/ODM Integration
Precision assembly occurs in certified ISO 13485 cleanroom facilities:
- Optical Alignment and Sealing: Glass rod lenses are aligned along micro-toleranced optical axes, bonded using medical-grade epoxies, and encased within structural sheaths. To withstand steam autoclaving, components undergo automated micro-laser welding and glass-to-metal solder sealing, preventing moisture ingress and optical fogging.
- OEM/ODM Partnerships: A significant proportion of the global rigid arthroscope market is driven by specialized contract design and manufacturing partners. Specialized optical enterprises, such as Henke Sass Wolf in Germany and Qingdao NovelBeam in China, manufacture core optical trains, optomechanical adapters, and finished rigid scopes for multinational brand owners.
- System Software Integration: Modern visualization towers rely heavily on integrated software architectures. Image signal processing engines must dynamically handle auto-exposure, wide dynamic range, electronic noise reduction, and near-infrared spectral processing.
● Downstream: Clinical Distribution, Surgeon Education, and Reprocessing
- Specialized Logistics and Consignment Tracking: Distribution infrastructure requires RFID-tracked temperature-controlled logistics networks to trace consigned implants and ensure immediate availability in sterile processing units.
- Clinical Education Infrastructure: Surgical adoption is tightly linked to medical education programs. Major corporations run physical training institutes and accredited surgical simulation suites—including virtual reality (VR) navigation—to train orthopedic residents and practicing surgeons on minimally invasive portal creation, suture management, and repair techniques.
- Maintenance, Reprocessing, and Circularity: Reusable platforms require post-market support networks, including rapid-turnaround optical scope repair, seal testing, and automated endoscope reprocessing (AER) protocols. In parallel, vendors are developing post-use recycling programs for single-use plastic instrument cannulas and packaging materials to comply with institutional environmental sustainability goals.
Regional Market Dynamics and Regulatory Environments
● North America (United States and Canada)
North America represents the primary market, generating approximately 50% of global arthroscope revenue. Market expansion is driven by high procedural volumes, favorable reimbursement for joint preservation, and rapid infrastructure expansion across the ASC landscape. The region's regulatory and clinical landscape is shaped by:
- Center for Medicare and Medicaid Services (CMS) Policies: CMS mandates reporting of Quality Measures and Patient-Reported Outcome Measures (PROMs) within outpatient care settings, driving hospital systems and ASCs to adopt integrated digital operating platforms that document surgical metrics.
- Trade Policy and Tariffs: Tariffs imposed on Chinese and European industrial components have driven multinational corporations to alter supply chain footprints. In response, global component suppliers have shifted high-volume sub-assembly operations to alternative Southeast Asian hubs, such as Thailand and Vietnam, to secure tariff-neutral market access into the United States.
- Growth Range: North American market revenue is projected to expand at an estimated CAGR of 5.4% to 7.0% through 2031.
● Asia-Pacific (APAC)
The Asia-Pacific region demonstrates the fastest unit volume growth globally, characterized by expanding hospital infrastructure, increasing sports-related injuries, and healthcare modernizations across China, India, Japan, South Korea, and Australia.
- China's Volume-Based Procurement (VBP): Centralized national and provincial procurement strategies have systematically reduced device margins across Chinese public hospitals. Suture anchor pricing faced steep reductions under early sports medicine tenders, and the expansion of VBP to shavers, radiofrequency probes, and basic optics limits the operating margins of legacy Western import portfolios. This dynamic accelerates market share gains for domestic manufacturers capable of low-cost manufacturing.
- Domestic Substitution Directives: Chinese administrative directives prioritize domestic medical device procurements in public healthcare tenders, incentivizing regional tier-1 hospitals to acquire domestically manufactured 4K rigid endoscopes and soft-tissue repair kits.
● Europe
Europe represents a mature market characterized by clinical sophistication, public healthcare budget discipline, and rigorous regulatory standards across Germany, the United Kingdom, France, and Italy.
- European Union Medical Device Regulation (EU MDR): The transition from the MDD to EU MDR has impacted the European market. Tightened requirements for clinical evaluation, continuous post-market surveillance, and the recertification of legacy devices have increased regulatory overhead. As a result, कई multinational corporations have rationalized product catalogs, discontinuing low-volume or niche arthroscopic instruments and passing compliance expenses through the supply chain. Extended transitional timelines (spanning 2026 to 2028 depending on device risk profiles) have eased near-term supply bottlenecks but sustained elevated administrative overhead.
- Southern European Fiscal Clawbacks: Frameworks like Italy's Payback Law, which requires medical device companies to cover regional healthcare budget overages, introduce financial volatility into commercial operations and strain channel partner relationships.
● Latin America
Commercial operations in Latin America rely on independent regional distributors, combined with direct commercial subsidiaries in large healthcare economies, notably Brazil and Mexico. Access to capital visualization platforms is often constrained by local currency volatility, high import duties, and complex local certification pathways (such as Brazil's ANVISA/INMETRO regulations). Growth is concentrated in private healthcare systems catering to affluent patient demographics and medical tourism.
● Middle East and Africa (MEA)
The MEA region, managed commercially within broader EMEA divisions, exhibits substantial infrastructure variance. Wealthier Gulf Cooperation Council (GCC) economies, led by Saudi Arabia and the United Arab Emirates, are allocating capital to build orthopedic centers of excellence. Procurement occurs through centralized public health ministry tenders, denominated in US Dollars or USD-pegged local currencies, with high demand for premium 4K visualization systems. Conversely, broader African markets remain constrained by healthcare infrastructure deficits, relying largely on second-hand capital systems, standard-definition legacy scopes, and non-governmental health programs.
Competitive Profiles: Market Participants
● Arthrex Inc.: Arthrex maintains an integrated market position focused exclusively on orthopedic sports medicine, joint restoration, and arthroscopic visualization.
● Smith & Nephew: Smith & Nephew operates a major global sports medicine division, pairing capital visualization with high-margin soft tissue repair consumables and robotic orthopedic platforms.
● Stryker Corporation: Stryker maintains a diverse portfolio within its multi-specialty Endoscopy and Sports Medicine units.
● The rest of companies covered in the report: Richard Wolf GmbH, Henke Sass Wolf GmbH (HSW), Endovision Co. Ltd., Shenyang Shenda Endoscope Co. Ltd. and Micro-Tech Endoscopy (Nanjing Micro-Tech).
Opportunities and Industry Headwinds
1. Growth Opportunities and Technology Drivers
● Recurring Revenue Transition via Single-Use Instruments:
Surgical providers are increasingly structuring capital contracts around recurring consumable commitments. By placing 4K consoles, light sources, and fluid pumps at low margins or under loaned-asset placements, manufacturers lock healthcare networks into multi-year contracts for single-use resection burrs, radiofrequency wands, fluid tubing, and soft-tissue anchors. This recurring consumable model mitigates exposure to capital equipment expenditure cycles while maintaining high gross margins.
● Regenerative Biologic Scaffolding Integration:
The introduction of clinical data validating bioinductive augmentation represents a major driver for sports medicine procedures. Clinical studies documenting substantial reductions in rotator cuff re-tear rates (e.g., using collagen-derived patches) and knee cartilage preservation (e.g., aragonite osteochondral scaffolds) have earned formal clinical guideline support. Manufacturers that integrate proprietary regenerative materials into their arthroscopic visualization and instrument portfolios can capture substantial procedure-level value.
● Product Customization for ASC Operating Environments:
The shift toward outpatient surgical centers rewards equipment manufacturers that optimize hardware for ASC constraints. Vendors offering low-footprint, mobile capital towers, modular all-in-one processors, and consolidated instrument tray programs (reducing sterile reprocessing volume by up to 70%) secure preferential status across large ASC operating groups.
2. Barriers, Headwinds, and Structural Risks
● Global Tariff Policies and Regional Supply Friction:
The application of protective import tariffs across major trade routes introduces friction into medical device supply chains. Companies lacking diversified global manufacturing footprints face direct margin erosion. Maintaining competitive margins requires established players to build redundant, geographically diversified manufacturing operations across tariff-neutral manufacturing hubs.
● Centralized Procurement and Downward Price Re-benchmarking:
Centralized cost-containment frameworks represent a structural risk to hardware and consumable pricing. China's VBP policy has dramatically lowered pricing for soft tissue implants and is expanding into capital-adjacent consumables such as shaver blades and RF wands. Concurrently, regional policies like Italy's Payback Law introduce unpredictable retroactive liabilities for medical device distributors. These dynamics necessitate ongoing manufacturing cost reduction and lower operational expenditure structures.
● Regulatory Compliance Costs under EU MDR:
The cost of compliance under the European Union Medical Device Regulation (EU MDR) remains an administrative headwind. The demands of extensive clinical trials, post-market surveillance systems, and notified-body audit queues have raised barriers to entry, prompting manufacturers to discontinue mature, lower-volume arthroscopic instrument lines.
1.1 Executive Research Summary and Core Findings 1
1.2 Industry Taxonomy & Categorization Framework 2
1.3 Research Design and Multi-Tier Data Modeling Methodology 3
1.4 Primary Source Validation: Key Opinion Leaders and Industry Interviews 4
1.5 Secondary Source Ingestion, Trade Corroboration and Triangulation 5
1.6 Standardized Acronyms, Operational Definitions and Currency Benchmarks 6
Chapter 2 Global Arthroscope Industry Ecosystem & Upstream-Downstream Value Chain Dynamics 7
2.1 End-to-End Value Chain Structural Topology 7
2.2 Upstream Precision Components: Optical Glass Rods, Objective Lenses and Light Guides 8
2.3 Precision Sensor and Optoelectronic Assembly: CMOS/CCD Image Sensors and Micro-Camera Modules 9
2.4 Structural Mechanics and Medical-Grade Metallurgy: Stainless Steel Tubes and Nitinol Sheaths 10
2.5 Midstream Original Equipment Manufacturing and Contract Design Manufacturing Dynamics 11
2.6 Downstream Hospital Procurement Channels, Ambulatory Surgical Centers and Sterilization Ecosystems 12
2.7 Value Chain Margin Distribution, Cost Stack Modeling and Profitability Pressure Points 13
Chapter 3 Global Arthroscope Market Sizing, Macroeconomic Drivers & Technological Inflection 14
3.1 Global Arthroscope Market Trajectory: Historical Dynamics and Forecast Horizon (2021-2031) 14
3.2 Macro Drivers: Global Aging Demographics, Osteoarthritis Prevalence and Sports Injury Incidence 15
3.3 Technological Inflection: 4K UHD, 3D Visualization and Integration with Robotic-Assisted Surgery 16
3.4 Shift Towards Minimally Invasive Surgery and Day-Surgery Economic Mandates 17
3.5 Regulatory Clearances, FDA 510(k), EU MDR Compliance and Biocompatibility Thresholds 18
3.6 Supply Chain Fragility, Geopolitical Realignment and Sourcing Diversification 19
3.7 Cross-Elasticity Analysis: Reusable Systems vs. Single-Use Arthroscopy Economics 20
Chapter 4 Global Arthroscope Market by Optical Architecture & Sensor Topology 21
4.1 Architectural Breakdown: Optical Path Engineering and Image Capture Paradigms 21
4.2 Hopkins Rod-Lens Arthroscope: Optical Clarity, Durability and Installed Base Economics 22
4.2.1 Global Revenue, Volume Shipments and Price Elasticity (2021-2031) 23
4.3 Digital Video Arthroscope (Chip-on-the-Tip): Sensor Miniaturization and Signal Transmission 24
4.3.1 Global Revenue, Volume Shipments and Forecast Modeling (2021-2031) 25
4.4 Fiber-Optic Micro-Arthroscope: Flexibility, Ultra-Fine Calibers and Micro-Joint Visualization 26
4.4.1 Global Revenue, Volume Shipments and Market Potential (2021-2031) 27
4.5 Comparative Optical Performance, Resolution Degradation and Cost-per-Procedure Metrics 28
Chapter 5 Global Arthroscope Market by Lifecycle & Capital Model 29
5.1 Lifecycle Taxonomy: Capitalized Asset Paradigms vs. Single-Use Operational Consumables 29
5.2 Reusable Arthroscope Systems: Reprocessing Workflows, Autoclave Fatigue and Repair Cycles 30
5.2.1 Market Sizing, Institutional Capital Expenditure and Depreciated Fleet Modeling (2021-2031) 31
5.3 Disposable (Single-Use) Arthroscopes: Cross-Contamination Elimination and Turnaround Efficiency 32
5.3.1 Market Sizing, Unit Cost Deflation and Hospital Adoption Elasticity (2021-2031) 33
5.4 Total Cost of Ownership Comparison: Sterilization, Labor, Damage Repair vs. Unit Acquisition Cost 34
5.5 Environmental Footprint: Medical Waste Lifecycle Assessment vs. Autoclave Energy Footprint 35
Chapter 6 Global Arthroscope Market by Clinical Application 36
6.1 Clinical Specialty Distribution and Surgical Penetration Modeling 36
6.2 Knee Arthroscopy: Meniscectomy, ACL/PCL Reconstruction and Articular Cartilage Repair 37
6.2.1 Sizing, Procedural Volume and Device Utilization Trends (2021-2031) 38
6.3 Shoulder Arthroscopy: Rotator Cuff Repair, Labral Stabilization and Subacromial Decompression 39
6.3.1 Sizing, Procedural Volume and Device Utilization Trends (2021-2031) 40
6.4 Hip Arthroscopy & Preservation: Femoroacetabular Impingement and Labral Reconstruction 41
6.5 Small Joint & Extremity Arthroscopy: Wrist, Elbow, Ankle and Micro-Cartilage Interventions 42
Chapter 7 Global Trade Dynamics, Tariff Environments & Cross-Border Supply Networks 43
7.1 Global Trade Matrix: Optical Cross-Border Flows, Export Hubs and Import Deficits 43
7.2 Primary Manufacturing Hubs: High-Precision Assembly in Germany, US, China and South Korea 44
7.3 HS Code Classification, Cross-Border Tariff Surcharges and Non-Tariff Trade Barriers 45
7.4 Global Supply Chain De-risking: Dual-Sourcing Strategies and Nearshoring Trends 46
7.5 Export Control Regimes and Supply Chain Transparency in Optical Grade Components 47
Chapter 8 North America Arthroscope Market Analysis & Country Drilldown 48
8.1 Regional Overview: Ambulatory Surgery Migration and Reimbursement Schedules (CPT Coding) 48
8.2 North America Market Valuation, Volume Shipments and Segmentation (2021-2031) 49
8.3 United States: Manufacturing Epicenter, High-End Imaging Demand and Single-Use Uptake 50
8.4 Canada: Provincial Healthcare Tenders, Capital Equipment Refresh Cycles and Clinical Adoption 52
Chapter 9 Europe Arthroscope Market Analysis & Country Drilldown 53
9.1 Regional Overview: Regulatory Rigor Under EU MDR and Public Healthcare Constraints 53
9.2 Europe Market Valuation, Volume Shipments and Product Breakdown (2021-2031) 54
9.3 Germany: Optical Engineering Leadership, Export Dominance and Hospital Purchasing Dynamics 55
9.4 United Kingdom: NHS Procurement Frameworks, Day-Surgery Expansion and Cost Restraints 56
9.5 France: Public-Private Surgical Volume, DRG Reimbursement and Technology Adoption 57
Chapter 10 Asia-Pacific Arthroscope Market Analysis & Country Drilldown 58
10.1 Regional Overview: Rapid Modernization, High-Volume Procedures and Domestic Substitution 58
10.2 Asia-Pacific Market Valuation, Volume Forecast and Application Breakdown (2021-2031) 59
10.3 China: Centralized Volume-Based Procurement, Localized Manufacturing and Class-III Hospitals 60
10.4 Japan: Ultra-High Precision Demand, Aging Patient Base and Endoscopy Infrastructure 61
10.5 South Korea: Advanced Minimally Invasive Adoption, Domestic OEM Hubs and Private Clinics 62
Chapter 11 Latin America, Middle East & Africa Arthroscope Market Analysis 63
11.1 Latin America: Macro Sizing, Import Vulnerability and Tier-1 Hospital Modernization 63
11.2 Middle East & Africa: Healthcare Infrastructure Development, Surgical Tourism and GPO Tenders 64
Chapter 12 Competitive Benchmarking & Global Market Share Concentration 65
12.1 Industry Concentration Metrics: Herfindahl-Hirschman Index (HHI) and Tier Archetypes 65
12.2 Global Top 5 Manufacturer Competitive Heatmap and Market Share Benchmarking (2021-2026) 66
12.3 Strategic Moves: M&A, Proprietary Sensor Technology Licensing and Disposable Platform IP 67
Chapter 13 Corporate Strategic Intelligence: Key Global Arthroscope Manufacturers 68
13.1 Stryker Corporation 68
13.1.1 Corporate Profile, Surgical Visualization Portfolio and Global Operational Footprint 68
13.1.2 SWOT Strategic Diagnostic 69
13.1.3 Arthroscope Financials: Revenue, Cost Analysis and Gross Margin (2021-2026) 70
13.1.4 Market Share Matrix, Integrated Video Platforms and Cross-Selling Ecosystems 71
13.2 Smith & Nephew 72
13.2.1 Corporate Profile, Sports Medicine Visualization Infrastructure and Global Operations 72
13.2.2 SWOT Strategic Diagnostic 73
13.2.3 Arthroscope Financials: Revenue, Cost Analysis and Gross Margin (2021-2026) 74
13.2.4 Market Share Trajectory, 4K Optical Innovation and Resection-Scope Co-Packaging 75
13.3 Micro-Tech Endoscopy 76
13.3.1 Corporate Profile, High-Precision Manufacturing Base and Global Expansion Footprint 76
13.3.2 SWOT Strategic Diagnostic 77
13.3.3 Arthroscope Financials: Revenue, Cost Analysis and Gross Margin (2021-2026) 78
13.3.4 Market Share Trajectory, Single-Use Pipeline and Cost-Advantage Execution 79
13.4 Endovision Co. Ltd. 80
13.4.1 Corporate Profile, Korean Optoelectronic Design Hub and Product Portfolio 80
13.4.2 SWOT Strategic Diagnostic 81
13.4.3 Arthroscope Financials: Revenue, Cost Analysis and Gross Margin (2021-2026) 82
13.4.4 Market Share Trajectory, Digital Visualization Innovations and OEM Partnerships 83
13.5 Richard Wolf GmbH 84
13.5.1 Corporate Profile, German Optical Engineering Lineage and Global Footprint 84
13.5.2 SWOT Strategic Diagnostic 85
13.5.3 Arthroscope Financials: Revenue, Cost Analysis and Gross Margin (2021-2026) 86
13.5.4 Market Share Trajectory, Hopkins Rod-Lens Systems and Premium Hospital Contracts 87
13.6 Henke Sass Wolf GmbH 88
13.6.1 Corporate Profile, Contract Manufacturing Leadership and Core Micro-Optics Capabilities 88
13.6.2 SWOT Strategic Diagnostic 89
13.6.3 Arthroscope Financials: Revenue, Cost Analysis and Gross Margin (2021-2026) 90
13.6.4 Market Share Trajectory, White-Label Production and Single-Use Design Evolution 91
13.7 Arthrex Inc 92
13.7.1 Corporate Profile, Proprietary Minimally Invasive Ecosystem and Vertical Integration 92
13.7.2 SWOT Strategic Diagnostic 93
13.7.3 Arthroscope Financials: Revenue, Cost Analysis and Gross Margin (2021-2026) 94
13.7.4 Market Share Trajectory, NanoScope Platform Disruption and Ambulatory Dominance 95
13.8 Shenyang Shenda Endoscope Co. Ltd. 96
13.8.1 Corporate Profile, Domestic Optical Heritage and Manufacturing Expansion 96
13.8.2 SWOT Strategic Diagnostic 97
13.8.3 Arthroscope Financials: Revenue, Cost Analysis and Gross Margin (2021-2026) 98
13.8.4 Market Share Trajectory, Public Hospital Penetration and Export Channel Strategy 99
Table 2 Primary Research Panel Distribution: Clinical Key Opinion Leaders, Hospital Procurement and R&D Heads 4
Table 3 Global Arthroscope Market Revenue and Unit Shipments (2021-2031) 14
Table 4 Regulatory Pathways Comparison for Arthroscopy Devices: US FDA 510(k), EU MDR and China NMPA 18
Table 5 Global Arthroscope Market Revenue by Optical Architecture & Sensor Topology (2021-2031, USD Million) 21
Table 6 Global Arthroscope Market Volume Shipments by Optical Architecture & Sensor Topology (2021-2031, Units) 22
Table 7 Hopkins Rod-Lens Arthroscope Market Revenue, Volume and ASP Dynamics (2021-2031) 23
Table 8 Digital Video Arthroscope Market Revenue, Volume and ASP Dynamics (2021-2031) 25
Table 9 Fiber-Optic Micro-Arthroscope Market Revenue, Volume and ASP Dynamics (2021-2031) 27
Table 10 Optical Architecture Comparative Technical Benchmarking: Resolution, Field of View and Depth 28
Table 11 Global Arthroscope Market Revenue by Lifecycle & Capital Model (2021-2031, USD Million) 29
Table 12 Global Arthroscope Market Volume Shipments by Lifecycle & Capital Model (2021-2031, Units) 30
Table 13 Reusable Arthroscope Systems Revenue and Fleet Depletion Projections (2021-2031) 31
Table 14 Disposable (Single-Use) Arthroscope Revenue, Consumption Units and Price Trajectory (2021-2031) 33
Table 15 Comparative 100-Procedure Total Cost of Ownership: Reusable vs. Single-Use Arthroscopy 34
Table 16 Global Arthroscope Market Revenue by Clinical Application (2021-2031, USD Million) 36
Table 17 Global Arthroscopic Surgical Procedure Volume by Target Anatomical Joint (2021-2031, Thousand Procedures) 37
Table 18 Knee Arthroscopy Market Revenue and Device Utilization Trends (2021-2031) 38
Table 19 Shoulder Arthroscopy Market Revenue and Device Utilization Trends (2021-2031) 40
Table 20 Hip Arthroscopy & Preservation Market Revenue and Procedural Growth (2021-2031) 41
Table 21 Small Joint & Extremity Arthroscopy Market Revenue and Penetration (2021-2031) 42
Table 22 Global Cross-Border Arthroscope Trade Volume and Value Matrix by Key Hubs (2021-2026) 43
Table 23 Trade Tariffs and Cross-Border Regulatory Classification (HS Codes 9018.90) by Major Market 45
Table 24 North America Arthroscope Market Revenue by Country (2021-2031, USD Million) 49
Table 25 United States Arthroscope Market Breakdown by Optical Architecture (2021-2031, USD Million) 51
Table 26 United States Arthroscope Market Breakdown by Clinical Application (2021-2031, USD Million) 51
Table 27 Canada Arthroscope Market Revenue by Product Architecture and Lifecycle (2021-2031, USD Million) 52
Table 28 Europe Arthroscope Market Revenue by Country (2021-2031, USD Million) 54
Table 29 Germany Arthroscope Market Revenue and Production Export Valuation (2021-2031, USD Million) 55
Table 30 United Kingdom Arthroscope Market Revenue by Lifecycle Segment (2021-2031, USD Million) 56
Table 31 France Arthroscope Market Revenue by Clinical Application (2021-2031, USD Million) 57
Table 32 Asia-Pacific Arthroscope Market Revenue by Country (2021-2031, USD Million) 59
Table 33 China Arthroscope Market Revenue, Domestic vs. Imported Split (2021-2031, USD Million) 60
Table 34 Japan Arthroscope Market Revenue by Optical Architecture (2021-2031, USD Million) 61
Table 35 South Korea Arthroscope Market Revenue by Target Joint Application (2021-2031, USD Million) 62
Table 36 Latin America Arthroscope Market Sizing by Core Country (2021-2031, USD Million) 63
Table 37 Middle East & Africa Arthroscope Market Sizing by Sub-Region (2021-2031, USD Million) 64
Table 38 Global Top 5 Arthroscope Manufacturers Market Share and Consolidation Index (2021-2026) 66
Table 39 Stryker Corporation Arthroscope Revenue, Cost and Gross Margin (2021-2026) 70
Table 40 Smith & Nephew Arthroscope Revenue, Cost and Gross Margin (2021-2026) 74
Table 41 Micro-Tech Endoscopy Arthroscope Revenue, Cost and Gross Margin (2021-2026) 78
Table 42 Endovision Co. Ltd. Arthroscope Revenue, Cost and Gross Margin (2021-2026) 82
Table 43 Richard Wolf GmbH Arthroscope Revenue, Cost and Gross Margin (2021-2026) 86
Table 44 Henke Sass Wolf GmbH Arthroscope Revenue, Cost and Gross Margin (2021-2026) 90
Table 45 Arthrex Inc Arthroscope Revenue, Cost and Gross Margin (2021-2026) 94
Table 46 Shenyang Shenda Endoscope Co. Ltd. Arthroscope Revenue, Cost and Gross Margin (2021-2026) 98
Figure 1 Global Arthroscope Research Methodology Data Architecture 3
Figure 2 Arthroscope Optical and Structural Value Chain Ecosystem 7
Figure 3 Cost Breakdown of Precision Optomechanical Arthroscope Production 10
Figure 4 Global Arthroscope Market Valuation and YoY Growth Trajectory (2021-2031) 15
Figure 5 Global Arthroscope Market Share by Optical Architecture & Sensor Topology (2021 vs. 2026 vs. 2031) 21
Figure 6 Hopkins Rod-Lens Arthroscope Global Revenue Expansion Curve (2021-2031) 23
Figure 7 Digital Video Arthroscope Adoption Curve and Penetration Ratio (2021-2031) 25
Figure 8 Fiber-Optic Micro-Arthroscope Market Volume Dynamics (2021-2031) 27
Figure 9 Global Arthroscope Market Share by Lifecycle Model (2021-2031) 29
Figure 10 Reusable Arthroscope Fleet Replacement Cycles and Capital Outlay (2021-2031) 31
Figure 11 Disposable Arthroscope S-Curve Commercial Adoption Rate (2021-2031) 33
Figure 12 Per-Procedure Economic Comparison: Reusable Systems vs. Single-Use Disposable Units 35
Figure 13 Global Arthroscope Procedural Revenue Distribution by Clinical Specialty (2026) 36
Figure 14 Knee Arthroscopy Global Market Trajectory (2021-2031) 38
Figure 15 Shoulder Arthroscopy Procedural Demand and Visualization Uptake (2021-2031) 40
Figure 16 Hip Preservation Procedural Shift and Arthroscope Sizing (2021-2031) 41
Figure 17 Global Arthroscope Net Trade Balance by Producing and Consuming Hubs (2026) 44
Figure 18 North America Arthroscope Revenue Breakdown by Country (2021-2031) 49
Figure 19 United States Arthroscope Market Evolution by Lifecycle Segmentation (2021-2031) 50
Figure 20 Europe Arthroscope Market Regional Distribution (2026) 54
Figure 21 Germany Arthroscope Domestic Production vs. Export Ratio (2021-2026) 55
Figure 22 Asia-Pacific Arthroscope Market Expansion Rate by Key Economy (2021-2031) 58
Figure 23 China Arthroscope Market Share: Domestic vs. Multinational Competitors (2021-2031) 60
Figure 24 Arthroscope Market Concentration and Herfindahl-Hirschman Index Curve (2021-2026) 65
Figure 25 Stryker Corporation Arthroscope Market Share (2021-2026) 71
Figure 26 Smith & Nephew Arthroscope Market Share (2021-2026) 75
Figure 27 Micro-Tech Endoscopy Arthroscope Market Share (2021-2026) 79
Figure 28 Endovision Co. Ltd. Arthroscope Market Share (2021-2026) 83
Figure 29 Richard Wolf GmbH Arthroscope Market Share (2021-2026) 87
Figure 30 Henke Sass Wolf GmbH Arthroscope Market Share (2021-2026) 91
Figure 31 Arthrex Inc Arthroscope Market Share (2021-2026) 95
Figure 32 Shenyang Shenda Endoscope Co. Ltd. Arthroscope Market Share (2021-2026) 99
Research Methodology
- Market Estimated Methodology:
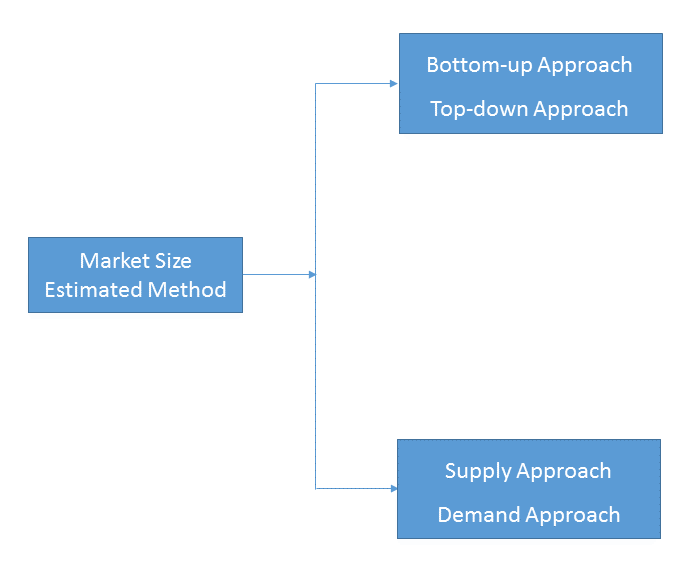
Bottom-up & top-down approach, supply & demand approach are the most important method which is used by HDIN Research to estimate the market size.
1)Top-down & Bottom-up Approach
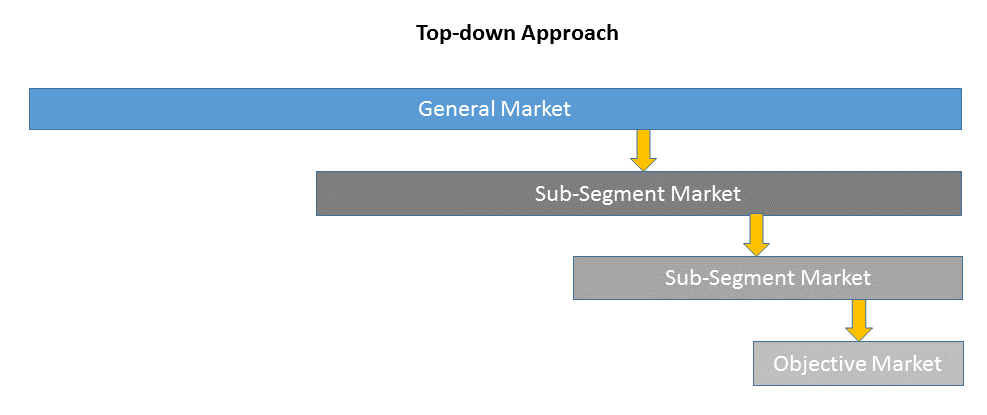
Top-down approach uses a general market size figure and determines the percentage that the objective market represents.
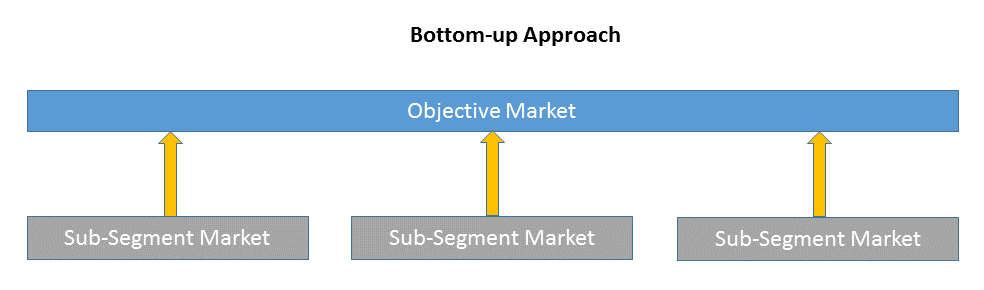
Bottom-up approach size the objective market by collecting the sub-segment information.
2)Supply & Demand Approach
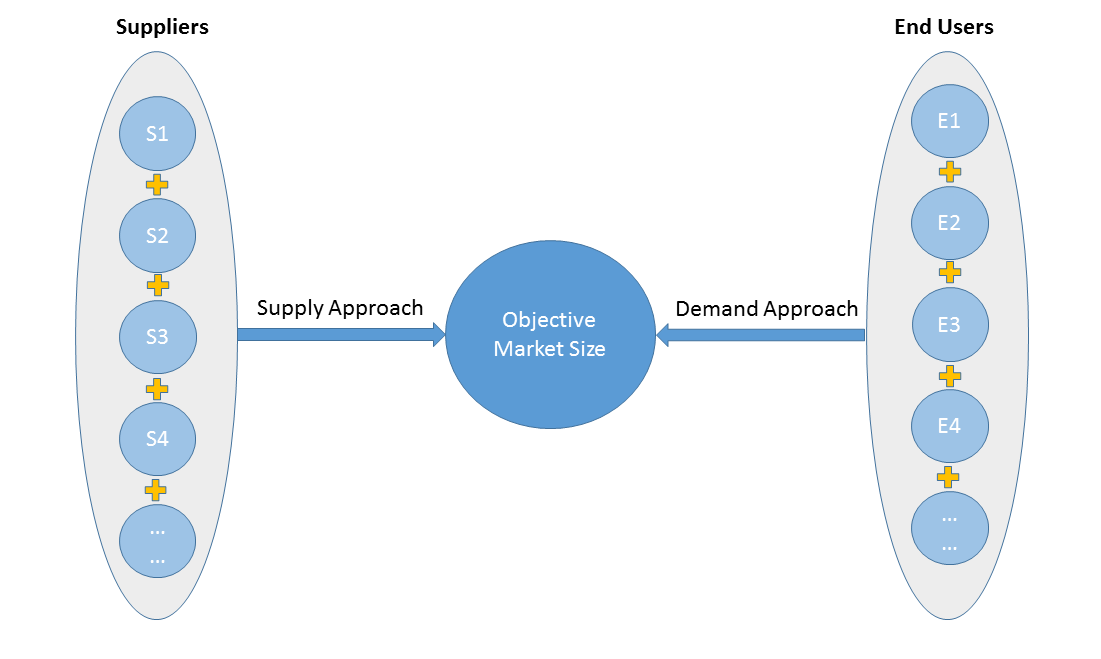
Supply approach is based on assessments of the size of each competitor supplying the objective market.
Demand approach combine end-user data within a market to estimate the objective market size. It is sometimes referred to as bottom-up approach.
- Forecasting Methodology
- Numerous factors impacting the market trend are considered for forecast model:
- New technology and application in the future;
- New project planned/under contraction;
- Global and regional underlying economic growth;
- Threatens of substitute products;
- Industry expert opinion;
- Policy and Society implication.
- Analysis Tools
1)PEST Analysis
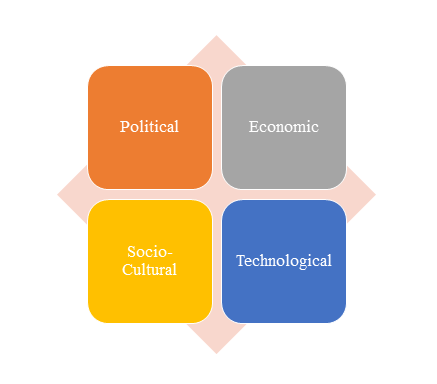
PEST Analysis is a simple and widely used tool that helps our client analyze the Political, Economic, Socio-Cultural, and Technological changes in their business environment.
- Benefits of a PEST analysis:
- It helps you to spot business opportunities, and it gives you advanced warning of significant threats.
- It reveals the direction of change within your business environment. This helps you shape what you’re doing, so that you work with change, rather than against it.
- It helps you avoid starting projects that are likely to fail, for reasons beyond your control.
- It can help you break free of unconscious assumptions when you enter a new country, region, or market; because it helps you develop an objective view of this new environment.
2)Porter’s Five Force Model Analysis
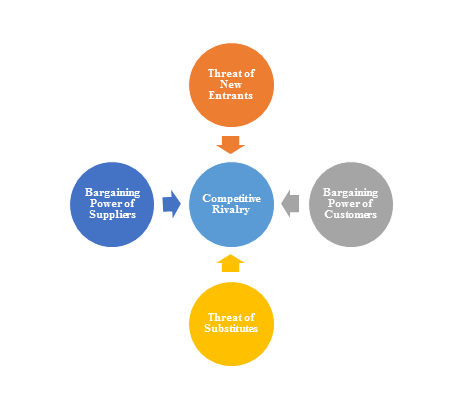
The Porter’s Five Force Model is a tool that can be used to analyze the opportunities and overall competitive advantage. The five forces that can assist in determining the competitive intensity and potential attractiveness within a specific area.
- Threat of New Entrants: Profitable industries that yield high returns will attract new firms.
- Threat of Substitutes: A substitute product uses a different technology to try to solve the same economic need.
- Bargaining Power of Customers: the ability of customers to put the firm under pressure, which also affects the customer's sensitivity to price changes.
- Bargaining Power of Suppliers: Suppliers of raw materials, components, labor, and services (such as expertise) to the firm can be a source of power over the firm when there are few substitutes.
- Competitive Rivalry: For most industries the intensity of competitive rivalry is the major determinant of the competitiveness of the industry.
3)Value Chain Analysis
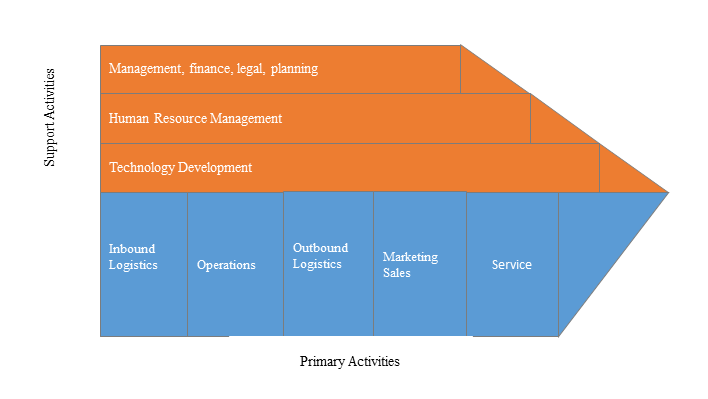
Value chain analysis is a tool to identify activities, within and around the firm and relating these activities to an assessment of competitive strength. Value chain can be analyzed by primary activities and supportive activities. Primary activities include: inbound logistics, operations, outbound logistics, marketing & sales, service. Support activities include: technology development, human resource management, management, finance, legal, planning.
4)SWOT Analysis
SWOT analysis is a tool used to evaluate a company's competitive position by identifying its strengths, weaknesses, opportunities and threats. The strengths and weakness is the inner factor; the opportunities and threats are the external factor. By analyzing the inner and external factors, the analysis can provide the detail information of the position of a player and the characteristics of the industry.
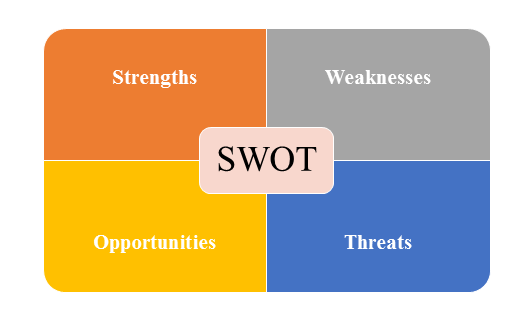
- Strengths describe what the player excels at and separates it from the competition
- Weaknesses stop the player from performing at its optimum level.
- Opportunities refer to favorable external factors that the player can use to give it a competitive advantage.
- Threats refer to factors that have the potential to harm the player.
- Data Sources
| Primary Sources | Secondary Sources |
|---|---|
| Face to face/Phone Interviews with market participants, such as: Manufactures; Distributors; End-users; Experts. Online Survey |
Government/International Organization Data: Annual Report/Presentation/Fact Book Internet Source Information Industry Association Data Free/Purchased Database Market Research Report Book/Journal/News |