Capsule Endoscope System Market: Analysis & Forecast 2026-2031
- Single User License (1 Users) $ 3,500
- Team License (2~5 Users) $ 4,500
- Corporate License (>5 Users) $ 5,500
Traditional flexible optical endoscopy imposes elevated procedural costs, depends heavily on scarce specialist operator availability, requires conscious sedation, and carries cross-contamination liabilities. In contrast, ingestible wireless capsule platforms provide non-invasive, sedation-free visualization across previously inaccessible physiological corridors, most notably the twenty-foot small bowel tract. Who is leading this industrial reconfiguration involves legacy endoscopic conglomerates such as Medtronic and Olympus defending entrenched footprints against architectural innovators such as CapsoVision, IntroMedic, and an assertive cohort of Chinese and Asian technology pioneers including ANKON Technologies, AnX Robotics, Jinshan Science & Technology, and Insight Medical Solutions. The industrial value chain is simultaneously dividing into two technological trajectories: passive, peristalsis-driven capsules migrating toward wire-free onboard flash architectures with cloud SaaS interpretation, and active, magnetically controlled capsule endoscopy navigating upper gastrointestinal lumens with robotic sub-millimeter precision.
The global capsule endoscope system market size will reach between 500 million to 700 million USD by 2026, expanding at a compound annual growth rate within the 6.5% to 9.5% range through 2031.
Taxonomy and Architectural Classification
Capsule endoscope systems are categorized by targeted clinical anatomy and underlying locomotion control mechanisms. This structural segmentation determines physical form factor, optical layout, battery endurance requirements, and downstream commercial adoption curves.
1. Classification by Anatomical Target and Clinical Indication
● Small Bowel Capsule Endoscopy (SBCE):
Small bowel capsule endoscopy represents the established commercial anchor of the industry, commanding the highest procedure volumes worldwide. Clinically, SBCE serves as the recognized first-line diagnostic modality for obscure gastrointestinal bleeding, unexplained iron-deficiency anemia, initial diagnosis and mucosal healing monitoring in Crohn's disease, refractory celiac disease, polyposis syndromes such as Peutz-Jeghers, and small-bowel neoplastic lesions. Because the jejunum and ileum cannot be comprehensively visualized via standard upper esophagogastroduodenoscopy or lower colonoscopy without deep enteroscopy, SBCE resolves a major anatomical access void. Recent regulatory milestones have broadened this cohort, including premarket clearance for pediatric populations down to two years of age. Standard commercial devices operate on single-end axial optics or multi-camera panoramic lateral configurations, utilizing adaptive frame rate capture over operational lifetimes spanning 8 to 15 hours.
● Colon Capsule Endoscopy (CCE):
Designed to provide comprehensive, sedation-free luminal mapping of the entire colonic tract from the cecum to the rectum, colon capsule endoscopy operates primarily as an advanced diagnostic alternative for incomplete optical colonoscopies resulting from redundant loops, severe diverticular disease, pelvic adhesions, or patient intolerance. It also serves individuals exhibiting elevated contraindications to moderate sedation or invasive intubation. CCE architectures differ substantially from small-bowel variants; they require dual-ended optical configurations to account for wide luminal diameters and bidirectional fluid turbulence, along with high-velocity dynamic image sensors capable of accelerating frame capture up to 35 to 48 frames per second during active peristaltic propulsion. Commercial expansion is concentrated on widening clinical indications beyond failed colonoscopy salvage toward frontline colorectal cancer screening and non-invasive polyp surveillance.
● Esophageal Capsule Endoscopy (ECE):
Esophageal systems address rapid mucosal transit through the high-velocity esophageal corridor, where typical passage occurs in under thirty seconds. These devices incorporate dual optical assemblies capturing high-speed bursts (up to 14 to 30 frames per second per side) to document the squamocolumnar junction, identify erosive reflux esophagitis, evaluate specialized intestinal metaplasia in Barrett's esophagus, and screen cirrhotic patients for esophageal varices. Eliminating trans-nasal or trans-oral sedated intubation offers major utility in outpatient surveillance regimens, mitigating cardiovascular and hemodynamic destabilization risks in advanced liver disease populations.
● Panenteric GI Pipeline Systems:
Representing the clinical convergence of small bowel and colonic imaging, panenteric diagnostic capsules are engineered to evaluate the entire gastrointestinal tract within a single ingestion event. Designed primarily to overcome the fragmented assessment of inflammatory bowel disease, these total-gut platforms enable systemic quantification of mucosal inflammation across both the small intestine and colon in Crohn's disease and ulcerative colitis. Regulatory and clinical adoption is underpinned by integrated scoring indices that benchmark systemic mucosal healing rather than localized segment evaluation. Extended battery chemistries, algorithmic energy management, and high-capacity micro-packaging define this product frontier.
2. Classification by Locomotion and Control Mechanism
● Peristalsis-Driven (Passive) Capsule Endoscopy:
Passive systems depend entirely on natural enteric peristalsis, physiological fluid mechanics, and gravity to traverse the digestive tract. The primary engineering objective within passive platforms is power conservation, biocompatible lubricity, and optical orientation stabilization. To mitigate tumbling artifacts and maintain central luminal alignment within large-diameter compartments such as the colon, passive devices have evolved specialized physical adaptations. These include integrated self-inflating elastomer balloons housed within enteric dissolvable shells that activate after small bowel transit, maintaining buoyancy and central orientation across prolonged colonic operations without external manipulation.
● Magnetically Controlled Capsule Endoscopy (MCCE):
Magnetically controlled systems transition capsule technology from passive drift to deterministic robotic navigation. Primarily targeted at upper gastrointestinal and gastric evaluation, MCCE resolves the historical limitation wherein a passive capsule fails to adequately inspect the large, compliant gastric cavity. MCCE integrates high-coercivity permanent micro-magnets within the hermetically sealed capsule body. Externally, the platform employs either a multi-axis robotic arm housing an industrial permanent magnet or an integrated multi-coil electromagnetic gantry configured over the patient.
Clinicians manipulate dual-joystick consoles or software-guided inspection vectors, altering external magnetic field gradients to exert five-to-six-degree-of-freedom control (pitch, yaw, elevation, translation, and rotation) over the capsule. This enables systematic, floating interrogation of the gastric fundus, greater curvature, lesser curvature, body, angularis, and antrum within a 15-to-20-minute procedure. Specialized variants utilize handheld magnetic guidance wands or hybrid ultra-thin, smooth tethers that supply continuous external power and instantaneous image transfer while permitting physical depth retrieval.
Value Chain Architecture and Sourcing Dynamics
The global capsule endoscope supply chain exhibits distinct regional specialization, characterized by high component concentration upstream, clinical-regulatory gatekeeping midstream, and complex multi-channel distribution downstream.
1. Upstream Component Supply:
The upstream layer represents a concentrated choke point characterized by geographical dependencies in East Asia.
● CMOS Image Sensors:
CMOS sensor production demands extreme miniaturization, low operating voltage, high frame rate agility, and elevated dynamic range to handle variable gastrointestinal illumination. Specialized semiconductor manufacturers, predominantly located in Japan, provide custom sensor platforms. Key commercial participants leverage long-term proprietary partnerships, such as multi-year co-development arrangements between medical device manufacturers and Japanese micro-optics and semiconductor conglomerates to supply next-generation HDR sensors. Sensor ASICs represent a major line-item raw material cost, exposing manufacturers to wafer foundry allocation cycles.
● Precision Micro-Optics:
Micro-optical lens assemblies must deliver ultra-wide fields of view (frequently exceeding 150 degrees for axial lenses, or spanning 360 degrees when utilizing lateral multi-lens arrays) with zero optical distortion through a curved, transparent capsule dome. The specialized engineering capability required to manufacture sub-millimeter compound lenses is heavily concentrated in Taiwan, China, where precision optical fabrication leaders supply the majority of global medical capsule lens modules.
ASICs, Micro-Packaging, and Flash Memory:
Integrated circuits executing image signal processing (ISP), custom run-length compression, and high-density multi-chip flash packages are outsourced to dedicated design houses and packaging specialists in Taiwan, China, and South Korea. Disruptions in advanced micro-packaging or foundry access directly threaten capsule production continuity.
● Specialized Power and Materials:
Power sources demand custom micro-battery configurations (such as high-density silver oxide or customized lithium chemistries) engineered to prevent leakage, maintain steady voltage discharge across varying metabolic temperatures, and deliver uninterrupted operation for up to 24 hours. The integration of specialized components, such as magnetic attraction cores, enteric dissolvable coatings, and micro-LED substrates, requires specialized tier-two materials suppliers adhering to ISO 13485 quality regimes.
2. Midstream Manufacturing and Systems Integration:
Midstream operations involve high-precision surface-mount technology (SMT) assembly, micro-robotic optical alignment, hermetic encapsulation, sterilization, and system calibration. While raw sub-assemblies and printed circuit boards are predominantly fabricated in Taiwan, China, and South Korea, final assembly, optical testing, calibration, and rigorous quality assurance frequently occur within corporate headquarters and certified cleanroom facilities across North America, Western Europe, and East Asia. Midstream players invest significant capital into clinical trial execution, regulatory submissions across diverse jurisdictions, and the intellectual property securing computer-aided detection (CADe) algorithms.
3. Downstream Commercialization Channels:
The downstream segment manages the complex interface of clinical procurement, institutional reimbursement, and physician workflow. Medical device manufacturers deploy bifurcated commercial channels:
● Core Domestic Direct Sales Forces:
In high-margin markets such as the United States and selected Western European territories (e.g., Germany), manufacturers increasingly field direct sales organizations. These teams, comprised of regional commercial directors and clinical territory managers, engage directly with academic medical centers, large gastroenterology practices, and hospital outpatient departments, securing high institutional retention rates.
● Group Purchasing Organizations (GPOs) and Integrated Delivery Networks (IDNs):
In the United States, commercial hospital penetration requires successful contracting with multi-hospital GPOs and IDNs. GPO agreements establish multi-year pricing structures, rebate tiers, and administrative fee frameworks in exchange for vendor access to thousands of member health systems.
● International Master Distributor Networks:
In non-core and geographically fragmented markets across the European Union, Asia-Pacific, Latin America, and the Middle East, manufacturers rely almost exclusively on qualified master distributors. These distributors manage country-specific regulatory approvals, fund local clinical symposia, navigate public healthcare procurement tenders, and absorb inventory carrying risk.
Downstream Applications and Demand Mechanics
1. Human Clinical Healthcare
The application landscape within human clinical healthcare is stratified across diverse care settings and distinct disease categories:
● Tertiary Hospitals and Inpatient Departments:
Hospitals serve as the primary environment for high-acuity gastrointestinal diagnostics, addressing acute obscure gastrointestinal bleeding, post-operative complications, deep Crohn's disease staging, and incomplete optical colonoscopy salvage. Inpatient settings prioritize rapid procedural turnaround, immediate bed-side data extraction, and integration with hospital-wide picture archiving and communication systems (PACS).
● Ambulatory Surgical Centers (ASCs) and Outpatient GI Practices:
Outpatient clinics drive high-volume screening and disease surveillance. These environments are highly sensitive to procedural throughput, staff utilization, and equipment capital expenditures. Systems eliminating external receiver belts and dedicated reading rooms significantly reduce outpatient operational overhead.
● Telemedicine and Decentralized Home Screening:
Regulatory approvals enabling remote capsule ingestion supervision have established a new paradigm in decentralized healthcare delivery. Under telehealth protocols, patients receive the capsule and preparation regimens at home, undergo virtual ingestion verification with a clinician, and proceed with normal daily activities. Following natural egestion, the device is mailed via specialized bio-transport containers directly to processing hubs. This model decouples gastrointestinal diagnostics from hospital facility constraints, drastically reducing patient waitlists.
Disease Indications:
● Obscure Gastrointestinal Bleeding (OGIB):
OGIB represents approximately 5% of all gastrointestinal hemorrhages, with the vast majority localized within the small bowel. Small bowel capsule endoscopy yields an established diagnostic accuracy of 30% to 70%, markedly outperforming push enteroscopy (approximately 31%), double-balloon enteroscopy (approximately 23%), and standard radiographic barium series (under 10%).
● Crohn's Disease and Inflammatory Bowel Disease (IBD):
Capsule endoscopy achieves high sensitivity (91% to 100%) and specificity (91% to 92%) in detecting superficial mucosal ulcerations in early small-bowel Crohn's disease, frequently prompting therapeutic reclassification in up to 78% of evaluated cases. The clinical deployment of dissolvable patency capsules prior to diagnostic capsule ingestion allows physicians to rule out intestinal strictures, eliminating the risk of symptomatic capsule retention.
● Colorectal Cancer (CRC) Screening and Failed Optical Colonoscopy:
Optical colonoscopy fails to achieve complete cecal intubation in 4% to 25% of cases due to anatomical tortuosity, prior surgical adhesions, or severe diverticulosis. Colon capsule endoscopy provides an effective, non-invasive rescue modality, exhibiting a significantly higher diagnostic yield for polyps larger than 5 mm compared to computed tomography colonography (CTC).
2. Veterinary and Companion Animal Healthcare
An emergent, non-human application sector centers on veterinary and companion animal medicine. Gastrointestinal disorders represent one of the most frequent clinical presentations in canine and feline practice. Conventional flexible endoscopy in animals requires full general anesthesia, posing substantial cardiovascular and respiratory risks while imposing elevated costs on pet owners.
Ingestible capsule endoscopy platforms adapted for veterinary use enable non-invasive visualization of the gastric, jejunal, and colonic mucosal lining in conscious companion animals. Strategic partnerships between veterinary academic medical centers, animal hospital networks, and capsule manufacturers have driven veterinary-specific medical device registrations. Commercial distribution is maintained through specialized animal healthcare channels, providing non-anesthetic enteroscopy options to private veterinary practices.
Regional Market Dynamics
● North America:
The North American theater, led by the United States and Canada, constitutes the largest regional market by revenue, supported by established reimbursement infrastructure and rapid institutional uptake of diagnostic innovations. In the United States, commercial adoption is anchored by Current Procedural Terminology (CPT) codes administered by the Centers for Medicare and Medicaid Services (CMS) and commercial private payers. Reimbursement for small bowel capsule endoscopy is fully entrenched for obscure GI bleeding and Crohn's disease.
In contrast, colon capsule endoscopy reimbursement has historically been restricted to patients with documented lower GI bleeding combined with major optical colonoscopy contraindications, or those who experienced incomplete colonoscopies. To overcome this limitation and unlock large-scale colorectal cancer screening indications, manufacturers are funding large-scale, multi-center U.S. pivotal trials enrolling hundreds of subjects to establish non-inferiority to optical colonoscopy.
From a regulatory standpoint, the U.S. Food and Drug Administration (FDA) continues to govern access via the 510(k) premarket notification framework, evaluating substantial equivalence against historical predicate platforms, with emerging focus on AI computer-aided detection clearances and breakthrough device designations for upper GI oncological indications.
● Europe:
Europe ranks as the second-largest regional market, characterized by mature public healthcare frameworks and expanding clinical guideline endorsements for capsule diagnostics. A defining commercial shift within the European Economic Area involves manufacturers transitioning away from exclusive third-party distributor models toward direct corporate sales subsidiaries in key Western European economies, most notably Germany, to secure higher gross margins and strengthen direct customer relationships.
Regulatory dynamics are governed by the rigorous EU Medical Devices Regulation (MDR), which has significantly raised the evidentiary bar for CE Mark certification. The MDR mandates extensive clinical evaluation documentation, unannounced manufacturing audits, and strict post-market clinical follow-up (PMCF) registries, driving industry consolidation as smaller players struggle to absorb compliance overhead.
Reimbursement remains fragmented, negotiated at individual member-state levels where public health systems enforce strict cost-containment frameworks, diagnostic price caps, and Health Technology Assessments (HTA).
● Asia-Pacific:
The Asia-Pacific territory represents the fastest-growing geographical market, while functioning as the global nerve center for manufacturing, sub-assembly, and optical sensor fabrication. Japan, South Korea, and China possess highly active clinical ecosystems. In South Korea, domestic device manufacturers benefit from an agile Ministry of Food and Drug Safety (MFDS) regulatory environment that has cleared next-generation AI reading software platforms.
In China, regulatory modernization by the National Medical Products Administration (NMPA) has enabled widespread commercialization of domestically manufactured Magnetically Controlled Capsule Endoscope systems. MCCE has been formally integrated into national gastric cancer screening guidelines, supported by inclusion within regional medical insurance directories and specialized hospital health check-up centers.
Upstream component assembly remains critically dependent on industrial infrastructure in Taiwan, China, for precision lens fabrication and ASIC packaging, alongside Japan for advanced CMOS sensor design. Competitive pricing pressures are pronounced across APAC, where domestic Chinese manufacturers offer aggressive average selling price (ASP) structures that disrupt legacy Western market pricing tiers.
● Latin America:
Latin American markets are characterized by reliance on regional master distributors and dual-tier healthcare structures. Commercial deployment is concentrated in major urban centers across Brazil, Mexico, Colombia, and Argentina. Regulatory agencies such as ANVISA in Brazil and INVIMA in Colombia maintain registration pathways that heavily leverage prior U.S. FDA clearances or European CE marks to expedite national sanitary approvals.
Public sector healthcare systems face severe budgetary constraints, which slow capital equipment purchases and limit capsule procedure reimbursement. Consequently, commercial momentum is driven primarily by private hospital networks and self-pay patient populations seeking non-invasive diagnostic alternatives.
● Middle East and Africa:
The Middle East and Africa region exhibits significant economic stratification. The Gulf Cooperation Council (GCC) nations, particularly Saudi Arabia and the United Arab Emirates, represent high-value markets investing heavily in advanced healthcare infrastructure, modern ambulatory centers, and novel digital health platforms. In these affluent sub-regions, private and semi-private healthcare providers rapidly integrate premium capsule endoscope technologies, driven by rising lifestyle-related gastrointestinal conditions, inflammatory bowel disease, and high colorectal cancer screening imperatives.
Conversely, across broader African territories, market penetration remains restricted to elite private surgical clinics and academic referral centers. The critical structural shortage of certified flexible endoscopists across developing regional economies positions capsule endoscopy as a viable long-term tele-diagnostic alternative, provided manufacturing costs can be scaled downward.
Competitive Dossiers: Key Market Players
● Medtronic: Medtronic maintains an entrenched global commercial position in capsule endoscopy, anchored by its historical acquisition of Given Imaging and the legacy PillCam franchise. The company's primary moat resides in its comprehensive brand equity, deep clinical literature validation spanning over two decades, and extensive global institutional contracting through established GPO and health-system frameworks. Medtronic's operational strategy revolves around offering a total gastrointestinal platform encompassing small bowel, colon, esophageal, and dedicated panenteric systems, coupled with artificial intelligence integration.
PillCam SB 3 represents the industry's historical clinical benchmark for evaluating obscure gastrointestinal bleeding and Crohn's disease, incorporating an adaptive frame rate mechanism (2 to 6 frames per second) that dynamically adjusts to peristaltic velocity across a 156-degree field of view. PillCam COLON 2 integrates dual optical heads providing 344-degree aggregate coverage, with variable frame capture scaling up to 35 frames per second during rapid passage to maximize colonic mucosal observation. PillCam Crohn's System offers a single-procedure panenteric visualization tool. PillCam UGI and ESO deliver high-frame-rate esophageal and upper digestive transit evaluations. Data processing is managed through the proprietary RAPID software suite, which integrates deep-learning computer-assisted reading tools to reduce physician interpretation times.
● Olympus: Olympus leverages its dominance in traditional flexible optical endoscopy, where it controls a massive share of the global gastrointestinal visualization market, to drive its wireless capsule enteroscopy presence. The operational moat of Olympus lies in its optical manufacturing heritage, premium image quality algorithms, and integrated customer relationships with hospital endoscopy suites worldwide. Olympus positions capsule endoscopy as an essential, complementary triaging modality that directly feeds interventional enteroscopy and therapeutic colonoscopy workflows.
The flagship EndoCapsule 10 (EC-S10) platform is engineered for high-resolution small bowel diagnostic evaluation.
● The rest of companies covered in the report: IntroMedic Co., Ltd., CapsoVision, Inc., ANKON Technologies, AnX Robotics, Jinshan Science & Technology (Group), Insight Medical Solutions Inc. and Beijing Huagen Anbang Technology Co. Ltd.
Strategic Market Perspectives: Opportunities and Systemic Bottlenecks
1. Transformative Market Opportunities
● Decentralized Telehealth Models and Home Care Delivery:
The authorization of remote ingestion protocols represents a structural paradigm shift for gastrointestinal diagnostics. Traditional clinical workflows require patients to occupy clinical procedure rooms, tie up specialized nursing staff, and wear bulky recording hardware that limits daily mobility. Telehealth-enabled capsule procedures eliminate these facility bottlenecks entirely. Patients execute bowel preparation protocols at home, ingest the capsule under remote video supervision, and proceed with their typical schedules. By removing clinic footprint requirements, healthcare systems can expand diagnostic screening capacity without incremental capital infrastructure investments, addressing deep colonoscopy backlogs across public health programs.
● Deep Learning Acceleration and 3D Quantitative Metrology:
Physician interpretation fatigue remains an operational bottleneck in capsule endoscopy. The institutionalization of FDA-cleared and CE-marked convolutional neural networks capable of pre-screening video data cuts interpretation times by up to 50%, transforming clinical economics. Furthermore, the integration of proprietary 3D structured-light sensing addresses a major limitation of 2D mucosal photography: the inability to accurately size lesions. By measuring polyp dimensions in vivo, artificial intelligence platforms empower clinicians to differentiate clinically insignificant diminutive polyps under 6 mm from advanced adenomas, avoiding unnecessary follow-on optical colonoscopies.
● High-Yield Oncological Indication Expansion:
While small-bowel diagnostics are clinically mature, expanding capsule endoscopy into upper gastrointestinal and pancreatic cancer screening creates substantial growth opportunities. Standard axial-view capsules deliver low duodenal papilla (Ampulla of Vater) identification rates (typically 10% to 15%) due to fast transit and complex anatomy. Advanced 360-degree panoramic lateral viewing architectures have demonstrated papilla detection rates exceeding 80% in clinical evaluations. Because periampullary mucosal irregularities serve as critical indicators for occult pancreatic and biliary neoplasms, securing dedicated regulatory indications for upper GI oncological screening can expand capsule endoscopy into high-value preventative oncology markets.
● Veterinary Market Expansion:
Adapting ingestible wireless platforms to companion animal medicine establishes an incremental, low-regulatory-hurdle revenue stream. The domestic pet healthcare market exhibits sustained demand for advanced diagnostics, yet veterinary enteroscopy is constrained by the necessity and physiological risks of general anesthesia. Anesthesia-free capsule endoscopy addresses these owner concerns, supported by institutional distribution channels, veterinary academic protocols, and specialized animal health registrations.
2. Structural Headwinds and Systemic Constraints
● Upstream Supply Chain Vulnerabilities:
The global capsule endoscope ecosystem faces severe geographical and supplier concentration risks. The critical micro-optical lens modules, low-power high-dynamic-range CMOS sensors, and custom ASICs are single-sourced from a concentrated cluster of precision manufacturers in Taiwan, China, and Japan. Geopolitical volatility, trade disruptions, or semiconductor fab capacity allocation shifts directly impact production continuity. Furthermore, rising input costs for micro-electronic sub-assemblies compress manufacturer gross margins, which cannot be immediately offset by procedural price increases in price-controlled healthcare systems.
● Pivotal Clinical Trial Burdens and Regulatory Friction:
Securing expanded indications—most notably transitioning colon capsule systems from salvage diagnostic tools to frontline colorectal cancer screening modalities—demands substantial capital allocation. Clinical validation necessitates multi-center pivotal clinical trials enrolling hundreds of patients across dozens of clinical trial sites to prove non-inferiority against optical colonoscopy. Regulatory reviews present significant timeline risks; shifts in regulatory scrutiny regarding optical stitching algorithms, panoramic video compression, or statistical endpoints can result in protocol expansions, trial delays, or potential classification shifts toward costlier Premarket Approval (PMA) pathways.
● Reimbursement Restrictions and GPO Price Erosion:
Clinical adoption curves are governed by third-party payer coverage frameworks. In the United States, strict CMS coverage limits for colon capsule endoscopy—requiring prior documentation of incomplete colonoscopy or lower GI bleeding combined with absolute anesthesia contraindications—restrict addressable volume. Concurrently, institutional contracting across hospital networks is dominated by Group Purchasing Organizations. GPOs enforce rigid multi-year fixed-pricing frameworks, product standardization requirements, and mandatory administrative fee structures, limiting manufacturer pricing power.
● Aggressive Low-Cost Market Disruption:
The international commercial landscape is experiencing intensifying price competition driven by an assertive tier of China-based manufacturers. Supported by high-volume domestic manufacturing capacity, lower internal development expenditures, and strong state-backed industrial incentives, these market entrants offer small bowel, colon, and magnetically controlled systems at substantial discounts to legacy Western platforms. This pricing differential is particularly disruptive across price-sensitive public healthcare tenders in Europe, Latin America, and Southeast Asia, eroding baseline average selling prices (ASPs) and forcing established market leaders to defend market share through service bundling and aggressive software discounting.
1.1 Research Methodology and Analytical Framework 1
1.2 Data Sourcing, Primary Interviews, and Secondary Verification 2
1.3 Market Size Formulation, Currency Calibration, and Econometric Modeling 3
1.4 Base-Year Assumptions and Forecasting Parameters (2021-2031) 4
1.5 Scope of the Report and Strategic Classification 5
1.6 Industry Terminology and Standard Abbreviations 6
Chapter 2 Global Capsule Endoscope System Market Landscape & Strategic Overview 7
2.1 Capsule Endoscope System Industry Executive Summary 7
2.2 Global Market Revenue Trajectory and Volume Dynamics (2021-2031) 8
2.3 Technological Paradigm Shift: From Passive Telemetry to Active Robotic Navigation 9
2.4 Artificial Intelligence and Computer-Aided Polyp/Lesion Detection Algorithms 10
2.5 Global Healthcare Reimbursement Frameworks and Clinical Adoption Barriers 11
2.6 Competitive Concentration and Market Evolution Matrix (2021-2026) 12
Chapter 3 Global Capsule Endoscope System Market by Anatomical Target & Clinical Indication 13
3.1 Small Bowel Capsule Endoscopy (SBCE) Revenue, Volume, and Clinical Utilization (2021-2031) 13
3.2 Colon Capsule Endoscopy (CCE) Non-Invasive Screening Adoption and Efficacy (2021-2031) 15
3.3 Esophageal Capsule Endoscopy (ECE) for Portal Hypertension and GERD (2021-2031) 17
3.4 Panenteric GI Pipeline System Integration and Whole-Gut Diagnostic Tracking (2021-2031) 18
Chapter 4 Global Capsule Endoscope System Market by Locomotion & Control Mechanism 19
4.1 Peristalsis-driven Capsule Endoscopes: Hardware Reliability and Power Budget (2021-2031) 19
4.2 Magnetically Controlled Capsule Endoscopy (MCCE): Real-Time 5-DoF/6-DoF Precision Navigation (2021-2031) 21
4.3 External Magnetic Actuation Platforms vs. Handheld Controller Consoles 23
4.4 Power Management, RF Telemetry, and High-Density Sensor Integration Benchmarks 24
Chapter 5 Global Capsule Endoscope System Market by End-Use Application 25
5.1 Human Clinical Healthcare Dynamics (2021-2031) 25
5.1.1 Tertiary Hospitals and Inpatient Endoscopy Suites 26
5.1.2 Ambulatory Surgical Centers (ASCs) and Outpatient Diagnostic Clinics 27
5.1.3 Decentralized At-Home and Tele-Endoscopy Deployment Frameworks 28
5.2 Veterinary & Pet Healthcare Dynamics (2021-2031) 29
5.2.1 Companion Animal Gastrointestinal Pathological Diagnostics 29
5.2.2 Equine and Specialized Exotic Animal Diagnostic Applications 30
Chapter 6 Capsule Endoscope System Value Chain, Upstream Components, and Manufacturing Architecture 31
6.1 Comprehensive Industrial Value Chain and Margin Distribution Mapping 31
6.2 Upstream Component Sourcing and Fabrication Ecosystem 32
6.2.1 Ultra-Low-Power CMOS Image Sensors (CIS) and Optical Lens Modules 32
6.2.2 Micro-Battery Form Factors, Silver-Oxide Cells, and Wireless Power Transfer (WPT) 33
6.2.3 Biocompatible Polymer Envelopes, Anti-Reflective Optical Domes, and Micro-Magnets 34
6.3 Midstream Manufacturing Processes, Automated Micro-Assembly, and Hermetic Sealing 35
6.4 Downstream System Integration: Image Processors, Sensor Belts, and Cloud AI Consoles 36
Chapter 7 Global Regulatory Pathways, Cross-Border Trade, and Geopolitical Dynamics 37
7.1 Medical Device Regulatory Matrix (US FDA 510(k)/PMA, EU MDR Class IIa/IIb, NMPA) 37
7.2 Global Trade Flows: Primary Manufacturing Hubs vs. Net Consuming Regions 38
7.3 Export-Import Flow Architecture: Diagnostic Imaging Transceivers and Ingestible Nodes 39
7.4 Cross-Border Logistics, Sterilization Protocols, and Cold-Chain Resilience 40
7.5 Tariff Structures, Supply Chain De-risking, and Dual-Sourcing Mandates 41
Chapter 8 North America Capsule Endoscope System Market Analysis 42
8.1 Regional Market Trajectory, Reimbursement Coding (CPT Codes), and Dynamics (2021-2031) 42
8.2 North America Market by Indication, Locomotion Mechanism, and Application 43
8.3 United States Production Capacities, Clinical Adoption, and ASC Expansion 44
8.4 Canada Public Health System Procurement and Decentralized Screening Programs 48
Chapter 9 Europe Capsule Endoscope System Market Analysis 50
9.1 Regional Macro Overview, EU MDR Implementation Impacts, and Trends (2021-2031) 50
9.2 Europe Market Breakdown by Clinical Indication and Locomotion Architecture 51
9.3 Germany Precision Optical Manufacturing, Clinical Trials, and Diagnostic Adoption 52
9.4 France Public Healthcare Screening and Tele-Endoscopy Expansion 53
9.5 United Kingdom NHS Diagnostic Hubs and Community Capsule Screening Rollouts 54
9.6 Italy Clinical Adoption and Gastrointestinal Diagnostic Infrastructure 55
9.7 Spain & Rest of Europe Market 56
Chapter 10 Asia-Pacific Capsule Endoscope System Market Analysis 58
10.1 Asia-Pacific Industrial Dominance, Manufacturing Clusters, and Growth Outlook (2021-2031) 58
10.2 Asia-Pacific Segmentation Breakdown by Indication and Locomotion Mechanism 59
10.3 China Magnetically Controlled Capsule Endoscopy Industrial Base and Health Checkup Chains 60
10.4 Japan High-Resolution Optical Integration, Reimbursement Policies, and Clinical Adoption 62
10.5 South Korea Smart Healthcare Infrastructure, Telemetry R&D, and Production Clusters 63
10.6 Taiwan (China) Microelectronics Ecosystem, Sensor Assembly, and Clinical Deployments 64
10.7 Australia Private Diagnostic Suites and Remote Rural Screening Initiatives 65
10.8 India Cost-Effective Capsule Adoption and Corporate Hospital Network Deployment 66
Chapter 11 Rest of the World Capsule Endoscope System Market Analysis 68
11.1 Latin America Healthcare Infrastructure and Private Diagnostic Clinics 68
11.1.1 Brazil Private Healthcare Consortia and Regulatory ANVISA Clearances 69
11.1.2 Mexico Cross-Border Medical Tourism and Tier-1 Diagnostic Expansion 70
11.2 Middle East & Africa High-End Specialized Healthcare Dynamics 71
11.2.1 GCC Private Hospital Infrastructure and Advanced Robotic Endoscopy Deployments 72
11.2.2 South Africa Regional Reference Laboratories and Tertiary Medical Centers 73
Chapter 12 Corporate Intelligence and Competitive Benchmarking 74
12.1 Competitive Tiering, Product Portfolio Matrices, and Strategic Positioning 74
12.2 Medtronic 75
12.2.1 Corporate Overview, Global Operations, and Production Footprint 75
12.2.2 PillCam SB3, PillCam Colon 2, and PillCam Crohn's Technical Architecture 76
12.2.3 Commercial Performance, Financial Realization, and Gross Margin Analysis 77
12.2.4 Strategic Outlook, AI Diagnostic Pipeline, and Enterprise SWOT Analysis 78
12.3 Olympus Corporation 79
12.3.1 Corporate Profile, Imaging Lineage, and System Interoperability 79
12.3.2 EC Capsule Endoscope Lineup and High-Yield Optical Telemetry 80
12.3.3 Enterprise Financial Trajectory, Production Costs, and Margins 81
12.3.4 Strategic Roadmap, Distribution Alliances, and Enterprise SWOT Analysis 82
12.4 IntroMedic Co., Ltd. 83
12.4.1 Corporate Profile, Micro-Electronics Base, and Korean Production Hub 83
12.4.2 MiroCam System Proprietary Human Body Communication (HBC) Architecture 84
12.4.3 Revenue Structure, Device Cost Elements, and Profitability Metrics 85
12.4.4 International Market Expansion, Regulatory Approvals, and SWOT Analysis 86
12.5 CapsoVision, Inc. 87
12.5.1 Corporate Profile, Silicon Valley R&D, and Cloud Infrastructure 87
12.5.2 CapsoCam Plus 360-Degree Panoramic Lateral Viewing Technology 88
12.5.3 Commercial Revenues, Manufacturing Cost Distribution, and Operating Margins 89
12.5.4 At-Home Diagnostic Telehealth Integration and Corporate SWOT Analysis 90
12.6 ANKON Technologies Co., Ltd. 91
12.6.1 Corporate Overview, Wuhan Advanced Robotics Base, and Global Footprint 91
12.6.2 Navicaps Magnetically Controlled Capsule Endoscopy (MCCE) System Platform 92
12.6.3 Financial Execution, Commercial Volume Sales, and Margin Profile 93
12.6.4 Clinical Trial Scale, Preventive Health Checkup Strategy, and SWOT Analysis 94
12.7 Jinshan Science & Technology (Group) Co., Ltd. 95
12.7.1 Corporate Structure, Chongqing Industrial Facilities, and Global Export Matrix 95
12.7.2 OMOM Series (Small Bowel, Colon, and MCCE Navigation Suites) 96
12.7.3 Product-Specific Revenue, Bill of Materials Cost, and Margin Realization 97
12.7.4 Global Expansion, Strategic Partnerships, and Corporate SWOT Analysis 98
12.8 AnX Robotics Inc. 99
12.8.1 Corporate Profile, Precision Magnetic Control Focus, and Regulatory Milestones 99
12.8.2 NaviCam Robotic MCCE System and Small Bowel Artificial Intelligence Integration 100
12.8.3 Financial Performance, Production Cost Ratios, and Gross Margin Trends 101
12.8.4 Commercial Strategy, Ambulatory Market Penetration, and SWOT Analysis 102
12.9 Insight Medical Solutions Inc. 103
12.9.1 Corporate Background, Taiwan (China) Precision Engineering Hub, and Operations 103
12.9.2 Magnetically Assisted Upper GI Capsule Endoscope System (InsightEyes) 104
12.9.3 Capital Structure, Product Revenues, Unit Production Costs, and Profit Margins 105
12.9.4 Clinical Partnerships, Global Expansion Roadmap, and Corporate SWOT Analysis 106
12.10 Beijing Huagen Anbang Technology Co., Ltd. 107
12.10.1 Corporate Profile, Proprietary Engineering Infrastructure, and Domestic Footprint 107
12.10.2 Dedicated Ingestible System Portfolio and Specialized GI Inspection Software 108
12.10.3 Revenue Performance, Fabrication Cost Accounting, and Margin Development 109
12.10.4 Strategic Channels, Hospital Procurement Integration, and SWOT Analysis 110
Table 2 Global Capsule Endoscope System Market Value and Volume (2021-2031) 8
Table 3 Global Capsule Endoscope System Market Share by Indication (2021-2031) 13
Table 4 Global Small Bowel Capsule Endoscopy (SBCE) Revenue and Volume (2021-2031) 14
Table 5 Global Colon Capsule Endoscopy (CCE) Revenue and Volume (2021-2031) 16
Table 6 Global Esophageal Capsule Endoscopy (ECE) Revenue and Volume (2021-2031) 17
Table 7 Global Panenteric GI Pipeline System Revenue and Volume (2021-2031) 18
Table 8 Global Capsule Endoscope System Market by Locomotion Mechanism (2021-2031) 19
Table 9 Global Peristalsis-driven Capsule Endoscopes Revenue and Volume (2021-2031) 20
Table 10 Global Magnetically Controlled Capsule Endoscopy (MCCE) Revenue and Volume (2021-2031) 22
Table 11 Global Capsule Endoscope System Market Revenue by End-Use Application (2021-2031) 25
Table 12 Global Human Clinical Healthcare Market Revenue by Facility Type (2021-2031) 26
Table 13 Global Veterinary & Pet Healthcare Capsule Endoscopy Revenue by Animal Type (2021-2031) 29
Table 14 Global Capsule Endoscopy Value Chain Cost and Gross Margin Structure (2021-2026) 31
Table 15 Regulatory Classification and Premarket Clearance Pathways by Key Jurisdiction 37
Table 16 Global Cross-Border Export Value of Capsule Endoscope Systems by Export Hub (2021-2026) 38
Table 17 Global Cross-Border Import Value of Capsule Endoscope Systems by Target Region (2021-2026) 39
Table 18 North America Capsule Endoscope System Revenue by Country (2021-2031) 42
Table 19 North America Capsule Endoscope System Revenue by Clinical Indication (2021-2031) 43
Table 20 North America Capsule Endoscope System Revenue by Locomotion Mechanism (2021-2031) 44
Table 21 United States Capsule Endoscope System Revenue, ASP, and Volume (2021-2031) 45
Table 22 United States Capsule Endoscope System Revenue by Application (2021-2031) 46
Table 23 Canada Capsule Endoscope System Revenue by Clinical Indication (2021-2031) 48
Table 24 Europe Capsule Endoscope System Revenue by Country (2021-2031) 50
Table 25 Europe Capsule Endoscope System Revenue by Locomotion Mechanism (2021-2031) 51
Table 26 Germany Capsule Endoscope System Market Revenue and Volume (2021-2031) 52
Table 27 France Capsule Endoscope System Market Revenue and Volume (2021-2031) 53
Table 28 United Kingdom Capsule Endoscope System Market Revenue and Volume (2021-2031) 54
Table 29 Italy Capsule Endoscope System Market Revenue and Volume (2021-2031) 55
Table 30 Spain Capsule Endoscope System Market Revenue and Volume (2021-2031) 56
Table 31 Asia-Pacific Capsule Endoscope System Revenue by Country/Region (2021-2031) 58
Table 32 Asia-Pacific Capsule Endoscope System Revenue by Indication (2021-2031) 59
Table 33 China Capsule Endoscope System Market Revenue and Volume (2021-2031) 60
Table 34 China Magnetically Controlled Capsule Endoscopy Market Volume and Adoption Rates (2021-2031) 61
Table 35 Japan Capsule Endoscope System Market Revenue and Volume (2021-2031) 62
Table 36 South Korea Capsule Endoscope System Market Revenue and Volume (2021-2031) 63
Table 37 Taiwan (China) Capsule Endoscope System Market Revenue and Volume (2021-2031) 64
Table 38 Australia Capsule Endoscope System Market Revenue and Volume (2021-2031) 65
Table 39 India Capsule Endoscope System Market Revenue and Volume (2021-2031) 66
Table 40 Latin America Capsule Endoscope System Revenue by Key Country (2021-2031) 68
Table 41 Brazil Capsule Endoscope System Market Revenue and Volume (2021-2031) 69
Table 42 Mexico Capsule Endoscope System Market Revenue and Volume (2021-2031) 70
Table 43 Middle East & Africa Capsule Endoscope System Revenue by Sub-Region (2021-2031) 71
Table 44 GCC Capsule Endoscope System Market Revenue and Volume (2021-2031) 72
Table 45 South Africa Capsule Endoscope System Market Revenue and Volume (2021-2031) 73
Table 46 Global Key Capsule Endoscope System Manufacturers Benchmarking Matrix 74
Table 47 Medtronic Capsule Endoscope System Revenue, Cost and Gross Margin (2021-2026) 77
Table 48 Olympus Corporation Capsule Endoscope System Revenue, Cost and Gross Margin (2021-2026) 81
Table 49 IntroMedic Capsule Endoscope System Revenue, Cost and Gross Margin (2021-2026) 85
Table 50 CapsoVision Capsule Endoscope System Revenue, Cost and Gross Margin (2021-2026) 89
Table 51 ANKON Technologies Capsule Endoscope System Revenue, Cost and Gross Margin (2021-2026) 93
Table 52 Jinshan Science & Technology (Group) Capsule Endoscope System Revenue, Cost and Gross Margin (2021-2026) 97
Table 53 AnX Robotics Capsule Endoscope System Revenue, Cost and Gross Margin (2021-2026) 101
Table 54 Insight Medical Solutions Inc Capsule Endoscope System Revenue, Cost and Gross Margin (2021-2026) 105
Table 55 Beijing Huagen Anbang Technology Co. Ltd. Capsule Endoscope System Revenue, Cost and Gross Margin (2021-2026) 109
Figure 1 Capsule Endoscopy System Market Sizing and Econometric Verification Funnel 3
Figure 2 Global Capsule Endoscope System Market Revenue Forecast (2021-2031) 8
Figure 3 Global Capsule Endoscope System Market Share by Indication (2026 vs 2031) 14
Figure 4 Global Small Bowel Capsule Endoscopy (SBCE) Growth Trajectory (2021-2031) 15
Figure 5 Global Colon Capsule Endoscopy (CCE) Adoption Curve (2021-2031) 16
Figure 6 Global Capsule Endoscope System Share by Locomotion Mechanism (2026) 20
Figure 7 MCCE Navigation Console vs. Passive System Growth Velocity (2021-2031) 22
Figure 8 Human Clinical vs. Veterinary End-Use Revenue Proportions (2021-2031) 25
Figure 9 Ambulatory Surgical Centers vs. Hospital Outpatient Utilization Trends (2021-2031) 27
Figure 10 Capsule Endoscope Bill of Materials (BOM) Cost Breakdown Structure 32
Figure 11 Global Logistics and Cross-Border Flow Matrix for Capsule Endoscopy Systems 39
Figure 12 North America Capsule Endoscope System Regional Market Share Breakdown (2026) 43
Figure 13 United States Capsule Endoscope Annual Procedural Volume Expansion (2021-2031) 47
Figure 14 Europe Capsule Endoscope System Market Share by Core Nation (2026) 51
Figure 15 Asia-Pacific Capsule Endoscope System Revenue Trajectory (2021-2031) 59
Figure 16 China Ingestible Endoscopy Penetration Rate across Tier-3 vs Private Health Checkup Clinics 61
Figure 17 Global Capsule Endoscope System Tier-1 Competitive Market Share (2026) 75
Figure 18 Medtronic Capsule Endoscope System Market Share (2021-2026) 78
Figure 19 Olympus Capsule Endoscope System Market Share (2021-2026) 82
Figure 20 IntroMedic Capsule Endoscope System Market Share (2021-2026) 86
Figure 21 CapsoVision Capsule Endoscope System Market Share (2021-2026) 90
Figure 22 ANKON Technologies Capsule Endoscope System Market Share (2021-2026) 94
Figure 23 Jinshan Science & Technology (Group) Capsule Endoscope System Market Share (2021-2026) 98
Figure 24 AnX Robotics Capsule Endoscope System Market Share (2021-2026) 102
Figure 25 Insight Medical Solutions Inc Capsule Endoscope System Market Share (2021-2026) 106
Figure 26 Beijing Huagen Anbang Technology Co. Ltd. Capsule Endoscope System Market Share (2021-2026) 110
Research Methodology
- Market Estimated Methodology:
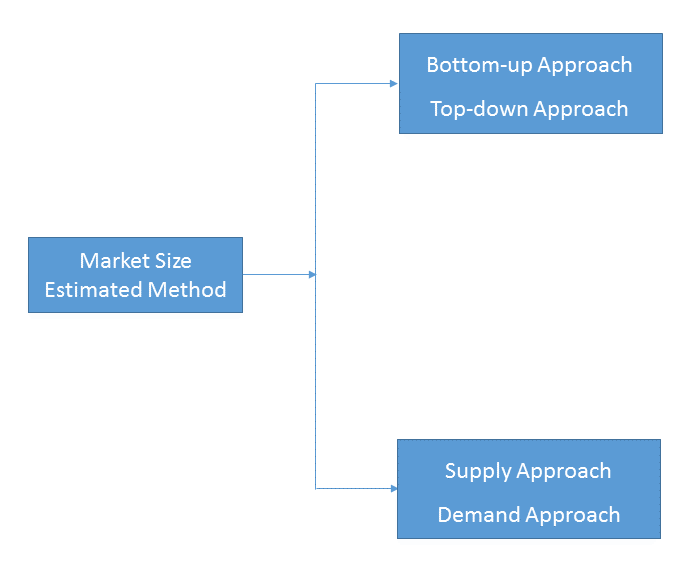
Bottom-up & top-down approach, supply & demand approach are the most important method which is used by HDIN Research to estimate the market size.
1)Top-down & Bottom-up Approach
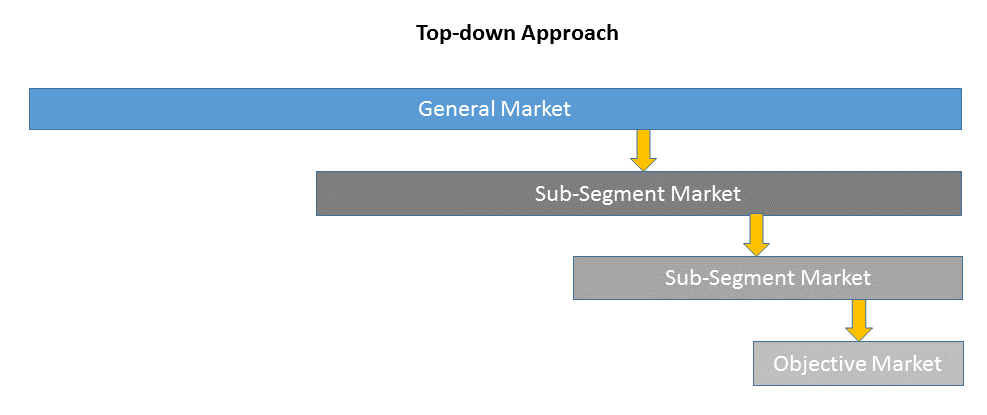
Top-down approach uses a general market size figure and determines the percentage that the objective market represents.
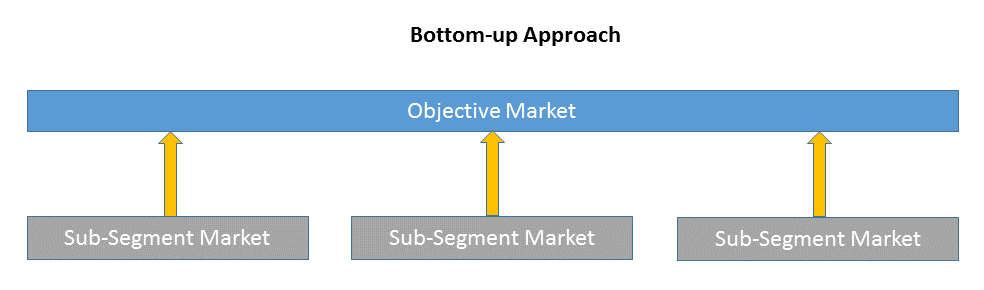
Bottom-up approach size the objective market by collecting the sub-segment information.
2)Supply & Demand Approach
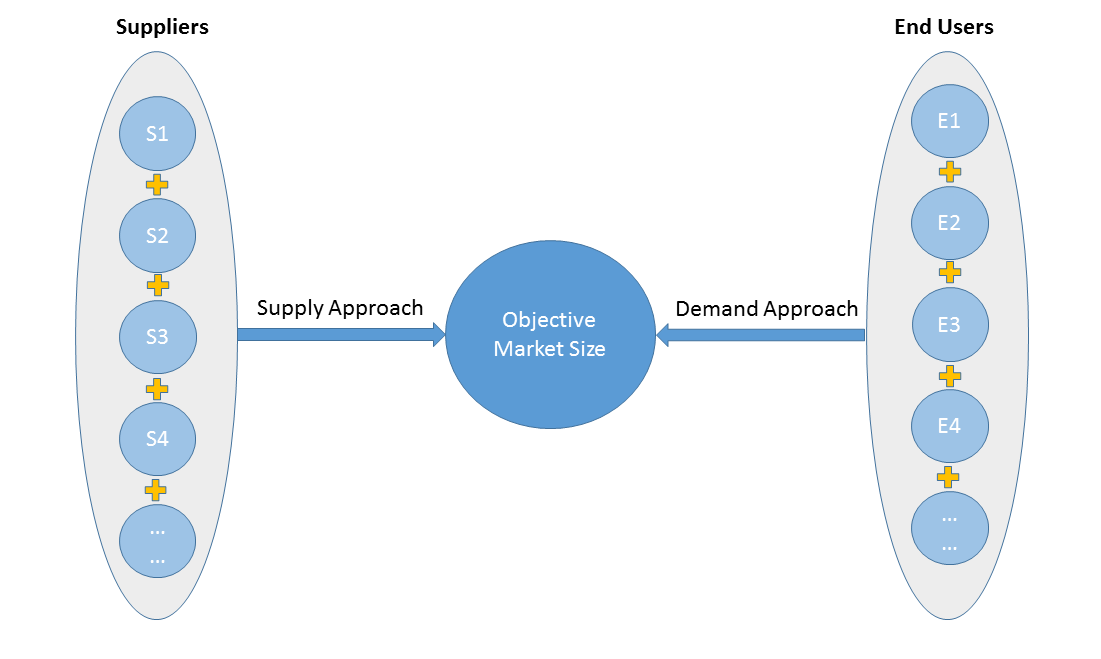
Supply approach is based on assessments of the size of each competitor supplying the objective market.
Demand approach combine end-user data within a market to estimate the objective market size. It is sometimes referred to as bottom-up approach.
- Forecasting Methodology
- Numerous factors impacting the market trend are considered for forecast model:
- New technology and application in the future;
- New project planned/under contraction;
- Global and regional underlying economic growth;
- Threatens of substitute products;
- Industry expert opinion;
- Policy and Society implication.
- Analysis Tools
1)PEST Analysis
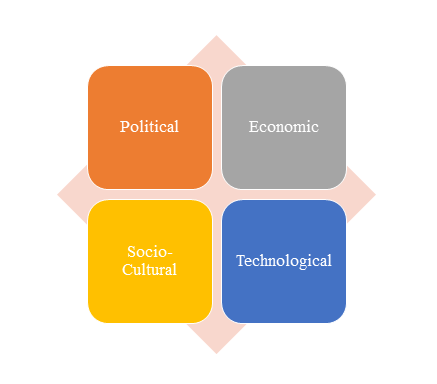
PEST Analysis is a simple and widely used tool that helps our client analyze the Political, Economic, Socio-Cultural, and Technological changes in their business environment.
- Benefits of a PEST analysis:
- It helps you to spot business opportunities, and it gives you advanced warning of significant threats.
- It reveals the direction of change within your business environment. This helps you shape what you’re doing, so that you work with change, rather than against it.
- It helps you avoid starting projects that are likely to fail, for reasons beyond your control.
- It can help you break free of unconscious assumptions when you enter a new country, region, or market; because it helps you develop an objective view of this new environment.
2)Porter’s Five Force Model Analysis
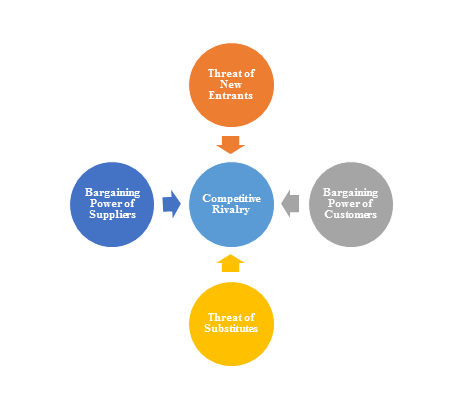
The Porter’s Five Force Model is a tool that can be used to analyze the opportunities and overall competitive advantage. The five forces that can assist in determining the competitive intensity and potential attractiveness within a specific area.
- Threat of New Entrants: Profitable industries that yield high returns will attract new firms.
- Threat of Substitutes: A substitute product uses a different technology to try to solve the same economic need.
- Bargaining Power of Customers: the ability of customers to put the firm under pressure, which also affects the customer's sensitivity to price changes.
- Bargaining Power of Suppliers: Suppliers of raw materials, components, labor, and services (such as expertise) to the firm can be a source of power over the firm when there are few substitutes.
- Competitive Rivalry: For most industries the intensity of competitive rivalry is the major determinant of the competitiveness of the industry.
3)Value Chain Analysis
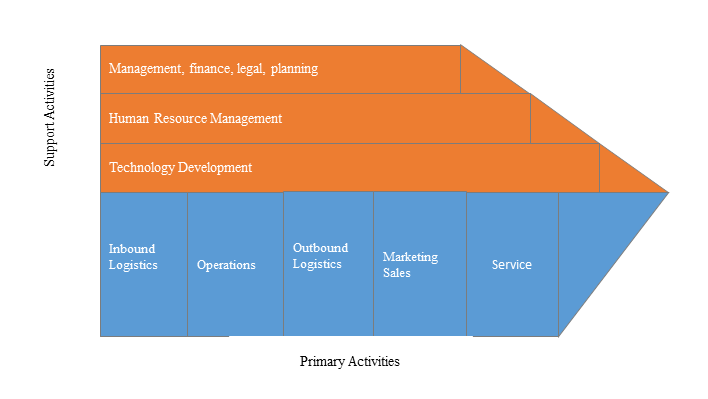
Value chain analysis is a tool to identify activities, within and around the firm and relating these activities to an assessment of competitive strength. Value chain can be analyzed by primary activities and supportive activities. Primary activities include: inbound logistics, operations, outbound logistics, marketing & sales, service. Support activities include: technology development, human resource management, management, finance, legal, planning.
4)SWOT Analysis
SWOT analysis is a tool used to evaluate a company's competitive position by identifying its strengths, weaknesses, opportunities and threats. The strengths and weakness is the inner factor; the opportunities and threats are the external factor. By analyzing the inner and external factors, the analysis can provide the detail information of the position of a player and the characteristics of the industry.
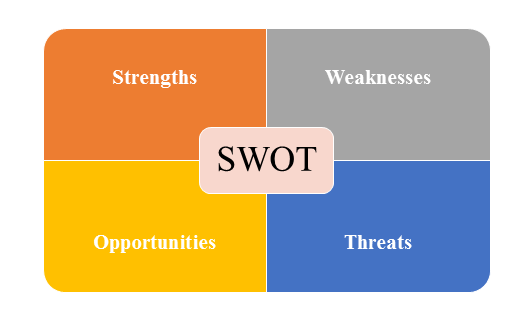
- Strengths describe what the player excels at and separates it from the competition
- Weaknesses stop the player from performing at its optimum level.
- Opportunities refer to favorable external factors that the player can use to give it a competitive advantage.
- Threats refer to factors that have the potential to harm the player.
- Data Sources
| Primary Sources | Secondary Sources |
|---|---|
| Face to face/Phone Interviews with market participants, such as: Manufactures; Distributors; End-users; Experts. Online Survey |
Government/International Organization Data: Annual Report/Presentation/Fact Book Internet Source Information Industry Association Data Free/Purchased Database Market Research Report Book/Journal/News |