Global Recreational Vehicle Market Analysis: 2026-2031
- Single User License (1 Users) $ 3,500
- Team License (2~5 Users) $ 4,500
- Corporate License (>5 Users) $ 5,500
The original equipment manufacturer (OEM) recreational vehicle (RV) market is entering an operational recalibration cycle, characterized by dealer inventory normalization, structural demographic transitions, and powertrain modernization. The global new RV market size is projected to sit between 40 billion USD and 46 billion USD in 2026 with a compound annual growth rate (CAGR) between 3.5% and 4.5% through 2031. Market dynamics have shifted from the supply-constrained post-pandemic delivery peaks to channel equilibrium. High-interest environments elevated floorplan financing carrying costs for independent dealerships across North America and Western Europe throughout 2024 and 2025, triggering systematic factory curtailments and promotional destocking. Dealer lot inventories have substantially rightsized in 2026, with North American wholesale-to-retail balance reaching an operational floor and European pipeline friction clearing following the regulatory transition to Euro 6e chassis standards.
Simultaneously, the target demographic is undergoing its most significant transition in four decades. While the retiree segment (ages 55 to 65) retains outsized capital reserves for high-margin Class A motorhomes and premium linework, the median age of North American RV consumers compressed to 49 years by 2025. Younger cohorts (ages 35 to 54) represent 46% of total vehicle registrations. This shift has altered capital allocation toward compact Class B campervans, high-voltage off-grid electrification architectures, and accessible travel trailers. Strategic developments in Asia-Pacific, headlined by China's State Council Notice No. 82 in late 2026, establish structural tailwinds by lifting mandatory vehicle scrapping limits and mandating public campsite utility integration. These developments unlock substantial long-term capacity across emerging travel corridors.
PRODUCT TAXONOMY AND SYSTEM SPECIFICATIONS
The recreational vehicle ecosystem divides into three distinct structural typologies: Motorized RVs, Towable RVs, and Park Model RVs.
1. Motorized RVs (Motorhomes and Motorcaravans)
Motorized RVs integrate living quarters directly onto self-propelled automotive frames, classified by gross vehicle weight ratings (GVWR), chassis cutaways, and structural coachbuilding methods.
- Class A Motorhomes: Represent the pinnacle of structural scale and amenities, extending up to 45 feet in length on commercial truck frames, bus chassis, or specialized rear-engine diesel pushers. Features include multi-zone slide-outs, high-output auxiliary generators, full-size residential kitchens, and basement storage. Unit pricing ranges from entry-level gas variants up to 1.7 million USD for bespoke bus conversions.
- Class B Motorhomes (Campervans): Built entirely within unmodified OEM automotive cargo van bodies (principally Mercedes-Benz Sprinter, Ford Transit, RAM ProMaster, and Fiat Ducato). Spanning 16 to 22 feet, Class B units deliver agile on-road handling, lower curb weights, and advanced off-grid capabilities for 2 to 4 occupants. They show rapid volume penetration among younger demographics as dual-purpose utility and remote-work vehicles.
- Class C and Super-C Motorhomes: Constructed on cutaway van or medium-duty commercial truck cabs, characterized by an overhead cab-over alcove serving as sleeping or gear storage. Super-C variants leverage heavy commercial diesel platforms (Freightliner, International), unlocking high towing capacities for trailers and performance utility.
- European Motorcaravan Architectures: Dictated by the 3.5-tonne driving license ceiling and urban spatial limits. The market categorizes units into Integrated (A-Class composite coachwork replacing the OEM cab), Semi-Integrated (low-profile profile maintaining OEM metal cabin), Alcove/Capucine (cab-over living box), and Urban Vehicles (pop-up roof minivans with modular living pods).
2. Towable RVs (Trailers and Caravans)
Towable RVs lack propulsion systems and depend on external passenger cars, pickups, or commercial vehicles. They comprise the largest portion of unit volume globally due to lower entry costs.
- Conventional Travel Trailers: Ranging from single-axle 10-foot tear drops to 35-foot dual-axle units, attached to tow vehicles via standard bumper-mounted or receiver hitches. Major variants include aerodynamic aluminum shells and composite fiberglass panels.
- Fifth-Wheel Trailers: Heavy towables coupled via a specialized kingpin hitch mounted in the bed of an open pickup truck. The bi-level architecture over the pickup box provides elevated vertical clearances, ceiling heights, and floorplans spanning up to 400 square feet.
- Touring Caravans and Pop-Tops: The dominant design across Europe, the United Kingdom, and Australasia. Engineered with lightweight composite bodies, independent rubber-torsion or trailing-arm suspensions, and compact envelopes optimized for smaller displacement passenger vehicles.
- Off-Road Hybrids and Towable Electric RVs (towable ERVs): Specialized niches featuring heavy-gauge chassis, continuous trailing-arm suspensions, high ground clearances, and dedicated high-capacity traction battery packs. The towable ERV segment introduces battery-powered driven axles that synchronize with tow vehicle telemetry to neutralize towing drag.
3. Park Model RVs
Park Model RVs are non-motorized, relocatable seasonal living structures built on a single rolling chassis for long-term placement at leased campground sites, mobile home parks, and resort developments. Constrained by North American standards (ANSI A119.5) to a maximum footprint of 400 square feet (37.2 square meters), they require specialized transport permits. Park models feature pitched roofs, architectural exterior siding, full residential hookups (water, 50-amp electricity, sewer), and residential-grade appliances, serving as affordable vacation properties and resort operational infrastructure.
SALES CHANNELS AND DISTRIBUTION ARCHITECTURE
1. Wholesale B2B Sales Channel (Independent Dealer Networks)
The wholesale B2B channel represents over 85% of OEM transaction value worldwide. OEMs market production allocations directly to independent, non-franchised dealerships via national wholesale sales groups.
- Geographic Footprint: Leading North American conglomerates interact with networks spanning 700 to 2,000 independent dealer locations across the United States and Canada. Strategic consolidation has yielded major national retail groups that wield significant purchasing power. In Europe, OEMs manage diversified distribution through authorized multi-brand distribution facilities and brand-exclusive dealerships.
- Floorplan Financing and OEM Repurchase Liabilities: Independent dealerships acquire inventory through commercial floorplan credit facilities provided by specialized institutional lenders. Under established standard agreements, OEMs sign floorplan repurchase obligations. If a dealership defaults on its debt servicing, the manufacturing OEM is contractually required to repossess and buy back the new, unsold inventory at residual invoice balances for periods typically lasting 18 to 24 months. These repurchase agreements expose OEMs to credit and inventory risk during macroeconomic downturns.
2. B2C Channel and Direct Retail Integration
Direct-to-consumer distribution models remain specialized, utilized to capture downstream retail gross margins, regulate transaction pricing, and collect immediate product feedback.
- Proprietary Retail Networks: Selected European and Australasian manufacturers manage wholly owned retail hubs across core metropolitan areas to control pre-delivery inspection quality, retail trade-ins, and accessory distribution.
- Vertically Integrated Rental Dealerships: Tourism operators execute end-to-end retail distribution by operating company-owned sales centers across key leisure corridors, selling new proprietary lines alongside decommissioned rental fleet units.
- Direct-to-Consumer Custom Builders: Specialized high-end boutique fabricators bypass intermediate dealership markups entirely, selling four-season, high-durability composite trailers directly to end-users via factory showrooms and digital configurators.
VALUE CHAIN ARCHITECTURE AND OPERATIONAL BOTTLENECKS
The recreation vehicle value chain spans three distinct processing tiers, characterized by sharp supply concentration at upstream chassis nodes and variable assembly efficiency at midstream nodes.
1. Upstream Tier: Sourcing, Metallurgy, and Automotive Chassis
Upstream operations cover structural materials (extruded aluminum, tubular steel, engineered plywood, composite skins, polyurethane insulation, and high-performance adhesives) alongside two critical Tier-1 inputs:
- The Motorized Chassis Supply Bottleneck: Motorized RV builders do not fabricate internal combustion powertrains, automated transmissions, or active automotive suspension gear in-house. They rely on light and medium commercial chassis platforms procured from a consolidated cohort of automotive OEMs, including Ford, Stellantis, Mercedes-Benz, General Motors, Freightliner, MAN, Volkswagen, and Iveco. Because commercial van and truck chassis production operates under rigid factory allocation systems, RV OEMs face acute supply vulnerability whenever automotive suppliers experience component shortfalls, work stoppages, or emissions revisions.
- Specialized Interior Equipment and Appliances: Tier-1 suppliers maintain near-monopolistic positioning over safety-rated, mobile-specific living infrastructure. Specialized component groups control patents across absorption and compressor refrigeration, compact air conditioning, roof hatches, slide-out hydraulic actuators, windows, and heavy entry doors. Recent consolidation has concentrated interior component pricing leverage into a handful of multi-brand suppliers.
2. Midstream Tier: OEM Engineering, Fabrication, and Modular Assembly
Midstream processing focuses on coachbuilding, structural panel bonding, cabinetry routing, systems integration, and final inspection.
- Build-to-Order Production Models: To mitigate capital drag, tier-one manufacturers operate flexible assembly lines under a built-to-dealer-order discipline, manufacturing batches aligned strictly with forward order backlogs rather than speculative inventory holdings.
- Cross-Border Supply Integration: A prominent structural development is cross-border value chain decoupling. Selected high-volume regions combine low-cost, capital-intensive chassis fabrication, metal stamping, and flat-pack cabinetry produced in China with final localized assembly, custom ADR/DOT wiring, and compliance certification completed in target delivery markets.
3. Downstream Tier: Dealership Ecosystem, Aftermarket, and Infrastructure
The downstream sector manages marketing, unit retail, warranty repair, and lifecycle support. Value generation shifts increasingly toward the recurring aftermarket sector, including seasonal winterization, hitch installations, high-voltage battery retrofits, and extended service contracts. The downstream lifecycle is deeply tied to regional infrastructure availability, namely campsite hookup capacity, blackwater dump stations, and long-term secure vehicle storage.
GLOBAL MARKET STATUS AND STRUCTURAL TRENDS
1. Industry Normalization and Channel De-Stocking
Following extreme production surges from 2021 through early 2023, the global RV landscape experienced a cyclical trough throughout 2024 and 2025. Rising borrowing costs inflated dealer floorplan expense ratios, causing dealer orders to plunge. OEMs responded with widespread factory furloughs, reduced operational shifts, and wholesale price discounting to clear older unit inventories. By the midpoint of 2026, channel data demonstrates that independent inventory portfolios have corrected to operational floors. North American dealer inventories contracted to approximately 64,000 units, representing balanced supply days. European channels have cleared backlogs caused by Euro 6e emissions changeovers, establishing stabilized baseline conditions for steady wholesale replacement orders.
2. Demographic Lowering and the Urban-Compact Pivot
The global buyer pool is diversifying beyond the historical retiree core. The average age of the global RV owner has declined toward late middle age, accelerated by outdoor recreation trends, distributed workplace flexibility, and adventure travel lifestyles. The incoming 35-to-54 consumer cohort exhibits lower household savings than traditional retirement buyers, dampening demand for massive 40-foot Class A motorcoaches. Instead, growth vectors have shifted toward Class B campervans, compact overland tear drops, and entry-level travel trailers that can be towed with standard half-ton pickups, mid-sized crossovers, or electric SUVs.
3. Powertrain Modernization, 400V Architectures, and System Electrification
Product architectures are pivoting rapidly from internal combustion auxiliary power units (noisy gas or diesel generators) toward silent, automotive-grade high-voltage energy systems.
- High-Voltage House Power Systems: Leading manufacturers are deploying 48-volt and 400-volt lithium iron phosphate (LiFePO4) storage systems with up to 15 kilowatt-hours of usable capacity. Paired with roof-mounted photovoltaic arrays and high-output secondary engine alternators, these systems recharge up to eight times faster than traditional AGM batteries, powering multi-day air conditioning and induction cooking without shore power connections.
- Towable Hybrid and EV Propulsion Systems: Advanced development projects target powered trailer chassis integrated with localized battery banks and axle-mounted traction motors. These smart towable platforms offset their own weight resistance via regenerative braking and active propulsion, preserving the driving range of electric towing vehicles.
REGIONAL MARKET DYNAMICS AND POLICY FRAMEWORKS
1. North America
North America remains the largest RV market by volume and revenue, representing over 50% of worldwide factory deliveries. Industry manufacturing capacity remains concentrated around Northern Indiana.
- Wholesale and Retail Throughput: For the first half of 2026, North American factory wholesale deliveries stabilized at approximately 163,644 units, comprising roughly 143,149 towable trailers and 20,495 motorized motorhomes. Retail registrations tracked shipments closely at approximately 159,030 units, confirming the restoration of inventory parity between factory output and end-consumer demand.
- Policy and Tax Framework: Capital recovery dynamics are anchored by the One Big Beautiful Bill Act (OBBB), enacted in mid-2025. This legislation instituted 100% bonus depreciation for qualifying capital equipment and accelerated the domestic deductibility of research and development expenses, providing substantial balance-sheet relief to major manufacturers and corporate dealer conglomerates. Operational safety and field actions remain closely overseen by the National Highway Traffic Safety Administration (NHTSA) under the Motor Vehicle Safety Act, alongside strict regional formaldehyde, VOC, and chassis tailpipe emissions requirements. Public funding initiatives support modernization projects across state and federal park systems, expanding high-amp campsite hookups.
2. Europe
Europe is the second-largest geographic market, accounting for over 35% of global revenue. Strongest unit volume sits within the motorized motorcaravan and campervan segments, driven by lifestyle patterns across Germany, France, the United Kingdom, Sweden, and Italy.
- Core Markets: Germany represents the continental anchor, generating 94,134 new motorhome and caravan registrations in 2025, heavily skewed toward motorized configurations (75,368 motorhomes versus 18,766 touring caravans).
- Emissions Regulations and the 2035 Horizon: The transition to Euro 6e emissions requirements disrupted light commercial vehicle chassis output through 2024 and 2025, creating transient supply mismatches. Looking forward, the European Union's projected 2035 phase-out of fossil-fuel combustion powertrains for new passenger and light commercial vehicles presents complex technical hurdles for motorhomes built on 3.5-tonne and 4.25-tonne platforms. This accelerates OEM joint development of battery-electric and hydrogen fuel cell base chassis.
- Sustainability Mandates and Tax Policy Shifts: Continental reporting requirements are governed by the EU Taxonomy Regulation and the Corporate Sustainability Reporting Directive (CSRD), driving aggressive supply chain tracking and life-cycle material auditing. Regional tax adjustments demonstrate rapid impact; Sweden's removal of its bonus-malus vehicle tax on motorhomes generated an immediate 46% surge in national registrations throughout 2025.
3. Asia-Pacific (APAC)
The Asia-Pacific region is characterized by advanced, high-efficiency manufacturing centers across China and deep outdoor recreation penetration across Australia and New Zealand.
- The China National Policy Catalyst: State Council Notice No. 82 (2026): A significant regulatory shift occurred in September 2026 with the release of Several Measures on Promoting Recreational Vehicle Consumption (State Council General Office Notice No. 82), jointly enacted by ten central ministries. This sweeping policy directly addresses historical systemic barriers:
1. De-Linking Mandatory Scrapping: Small and micro non-commercial motorized RVs are officially reclassified alongside standard passenger motor vehicles, freeing them from arbitrary compulsory retirement horizons. Operational lifespans for commercial rental motorhomes are formally increased from 15 to 25 years, while towable trailers see limits increased from 15 to 20 years.
2. Road Access and Licensing Reforms: The directive accelerates testing facilities for the C6 light towing license and strictly prohibits municipal transport bureaus from mounting uncoordinated overhead height barriers that block standard RV clearance on primary and suburban arteries.
3. Campsite Spatial Integration: RV park allocations are integrated into national land zoning plans. The directive approves the creation of unpaved, ecologically sensitive campgrounds without demanding changes to underlying agricultural or forestry zoning classifications, and orders all national highway service plazas and major state parks to install functional water, charging, and sewage pump stations.
4. Credit and Insurance Modernization: Notice No. 82 promotes structured personal property and specialized casualty insurance coverage for living quarters, while incentivizing nationwide deposit-free rental models and cross-regional drop-offs.
- Australasian Market Realities: Australasia represents an established, high-penetration market. Engineering operations adhere strictly to rigorous Australian Design Rules (ADR) and vehicle safety systems capable of withstanding unsealed corrugations. New Zealand enforces strict self-contained vehicle regulations for freedom camping, mandating permanently plumbed cassette or blackwater tank infrastructure.
4. South America and Latin America
The Latin American RV footprint remains an emerging, fleet-led segment. Regional activity centers on multi-passenger commercial vehicle conversions, municipal mobile medical units, and specialty tourism operators in Brazil, Argentina, and Mexico. Downstream demand expansion is tied to national tourism infrastructure spending, relaxed commercial lending terms, and local fleet modernizations.
5. Middle East and Africa (MEA)
The MEA region comprises commercial fleet operations and extreme-climate expedition vehicles. Gulf Cooperation Council (GCC) markets demonstrate growing affinity for luxury desert-camping caravans, heavy-duty 4x4 or 6x6 expedition rigs, and mobile hospitality trailers. Southern Africa supports an active safari rental network serving domestic and inbound European tourists. Regional operations face supply chain and operational friction, including geopolitical conflict across the Red Sea and Persian Gulf, resulting in volatile maritime container freight surcharges, extended chassis delivery lead times, and extreme ambient thermal requirements requiring upgraded insulation and secondary cooling systems.
COMPETITIVE DOSSIERS: KEY MARKET PARTICIPANTS
1. North American Conglomerates and Specialists
● Thor Industries Inc.: The world's largest RV manufacturer by revenue, executing a decentralized portfolio strategy that spans independent, competitive operating subsidiaries across North America and Europe.
- RV Portfolio: Airstream, Keystone RV, Thor Motor Coach, Jayco (North America), Entegra Coach, Heartland RV, Dutchmen, Starcraft RV, CrossRoads RV, Cruiser RV, Tiffin Motorhomes, and Erwin Hymer Group.
- Core Offerings: Full-spectrum portfolio covering Class A, Class B, and Class C motorhomes, iconic luxury travel trailers, fifth wheels, toy haulers, and European campervans.
● Forest River Inc.: A major subsidiary of Berkshire Hathaway, operating diversified manufacturing facilities producing recreational vehicles, commercial buses, cargo trailers, and pontoon watercraft.
- RV Portfolio: Forest River RV, Coachmen RV, Dynamax, Palomino, Prime Time Manufacturing, Shasta, Cherokee, Rockwood, Flagstaff, Salem, Wildwood.
- Core Offerings: Entry-level to luxury conventional travel trailers, fifth wheels, toy haulers, pop-up camping trailers, Class A gas and diesel motorhomes, and Super-C motorcoaches.
● Winnebago Industries Inc.: A historic American motorized leisure vehicle pioneer that transformed its corporate profile through targeted acquisitions of high-end towable and luxury diesel motorcoach brands.
- RV Portfolio: Winnebago, Grand Design RV, Newmar Corporation.
- Core Offerings: Class B off-road campervans (Revel, Travato), Class C motorhomes (Ekko, View), ultra-luxury Class A diesel motorcoaches (Newmar King Aire, Dutch Star), and premium lightweight and full-profile fifth wheels (Grand Design Solitude, Reflection, Imagine).
● REV Group Inc.: A diversified manufacturer of specialty municipal, commercial, and recreation vehicles, maintaining an elite portfolio of motorcoach and custom van brands.
- RV Portfolio: American Coach, Fleetwood RV, Holiday Rambler, Renegade RV, Midwest Automotive Designs, Lance Camper.
- Core Offerings: Luxury Class A diesel pushers, premium gas Class A motorhomes, heavy-duty Super-C coaches, bespoke luxury executive Class B van conversions, and premium truck campers.
● Gulf Stream Coach Inc.: One of the largest privately held, family-operated recreational vehicle builders in North America, focused on value-engineered family towables and light motorhomes.
- RV Portfolio: Gulf Stream Coach (Innsbruck, Amer-Lite, Kingsport, Vintage Cruiser, BT Cruiser, Conquest).
- Core Offerings: Entry-level lightweight travel trailers, retro-styled trailers, seasonal destination trailers, and fuel-efficient Class C/B+ motorhomes.
● NeXus RV LLC: An independent manufacturer situated in Elkhart, Indiana, distinguished by structural all-steel cage framing and composite wall designs.
- RV Portfolio: NeXus RV (Ghost, Rebel, Wraith, Triumph, Phantom, Viper, Maybach).
- Core Offerings: Commercial-grade Super C diesel motorhomes, Class C cutaways, Class B+ crossovers, and Class A gas and diesel coaches.
● Northwood Manufacturing Inc.: A Pacific Northwest manufacturer specializing in heavy-duty, off-road capable, four-season towables and truck campers designed for severe environments.
- RV Portfolio: Arctic Fox, Nash, Desert Fox, Fox Mountain, Wolf Creek.
- Core Offerings: Heavy-duty truck campers, true four-season travel trailers, toy haulers, and structural fifth wheels.
● Triple E Recreational Vehicles: A Canadian luxury manufacturer that streamlined its entire manufacturing portfolio to concentrate exclusively on high-end compact motorhomes under a single banner.
- RV Portfolio: Leisure Travel Vans (LTV).
- Core Offerings: Luxury Class B+ and compact Class C motorhomes constructed on Mercedes-Benz Sprinter and Ford Transit platforms (Unity and Wonder product lines).
● Eveland's Inc. (Scamp Trailers): A family-owned Minnesota builder manufacturing lightweight, two-piece aerodynamic molded fiberglass travel trailers since the 1970s.
- RV Portfolio: Scamp Trailers.
- Core Offerings: Ultra-lightweight molded fiberglass towables (13-foot and 16-foot trailers) and compact 19-foot fifth-wheel trailers towable by light trucks.
● Oliver Travel Trailers Inc.: A direct-to-consumer Tennessee manufacturer specializing in premium, aircraft-inspired double-hulled fiberglass travel trailers engineered for four-season durability.
- RV Portfolio: Oliver Travel Trailers.
- Core Offerings: High-end double-shelled molded fiberglass trailers on custom aluminum frames, featuring the Legacy Elite (18.5 ft) and tandem-axle Legacy Elite II (23.5 ft).
2. European Conglomerates and Heritage Builders
● Trigano S.A.: Europe's largest RV manufacturing group, operating a network of manufacturing plants and retail subsidiaries across France, Germany, Italy, Spain, and the UK.
- RV Portfolio: Adria Mobil, Chausson, Challenger, Roller Team, CI, Benimar, Autostar, Font Vendome, McLouis, Mobilvetta, Rimor, Eura Mobil, Karmann-Mobil.
- Core Offerings: Semi-integrated and fully integrated motorcaravans, overcab family motorhomes, factory panel campervans, and lightweight touring caravans.
● Knaus Tabbert AG: A major German recreational vehicle manufacturer covering entry-level to ultra-luxury market tiers, with primary plants in Germany and Hungary.
- RV Portfolio: Knaus, Tabbert, Weinsberg, T@B, Morelo.
- Core Offerings: Semi-integrated and integrated motorhomes, campervans, teardrop and touring caravans, and first-class luxury liners.
● Hobby (including Fendt-Caravan GmbH): A major global caravan manufacturing group based in Schleswig-Holstein, Germany, encompassing the family brand Hobby and its premium subsidiary Fendt-Caravan.
- RV Portfolio: Hobby, Fendt-Caravan.
- Core Offerings: Entry-level to luxury touring caravans, compact campervans, and semi-integrated coachbuilt motorhomes.
● Rapido Group: A French family-owned group that expanded via strategic acquisitions into a multi-brand pan-European specialist in cabinetry, compact campervans, and luxury motorhomes.
- RV Portfolio: Rapido, Itineo, Dreamer, Campereve, Westfalia, Giottiline, Fleurette, Florium, Stylevan.
- Core Offerings: High-end low-profile and integrated motorhomes, modular campervans, compact pop-top campers, and boutique motorcaravans.
● Pilote: A historic French leisure vehicle manufacturer with production centers in France and Germany, operating across integrated motorhomes and van segments.
- RV Portfolio: Pilote, Bavaria, Le Voyageur, Frankia, Danbury.
- Core Offerings: Semi-integrated and integrated A-class motorhomes, panel campervans, and German-engineered luxury liners (Frankia Platin and Titan series).
● Carthago Reisemobilbau GmbH: A prominent independent German manufacturer focused entirely on the premium and luxury motorcaravan tiers.
- RV Portfolio: Carthago, Malibu.
- Core Offerings: High-end integrated and semi-integrated A-class motorhomes (chic c-line, liner-for-two) and premium compact campervans (Malibu Van).
● Hymer GmbH & Co. KG: The cornerstone German brand of the Erwin Hymer Group (a Thor Industries subsidiary), serving as a benchmark for European motorized leisure vehicle engineering.
- RV Portfolio: Hymer, Hymer Camper Vans, Eriba.
- Core Offerings: High-spec integrated motorhomes (B-Class MasterLine), rugged all-wheel-drive semi-integrated platforms (ML-T, Venture S), and lightweight aerodynamic touring caravans (Eriba Touring).
● Dethleffs GmbH & Co. KG: An established German marque within the Erwin Hymer Group, recognized for constructing the first German caravan in 1931, with a long-standing focus on family touring.
- RV Portfolio: Dethleffs, Sunlight.
- Core Offerings: Touring caravans, semi-integrated family motorhomes, overcabs, and large A-class integrated units.
● Burstner GmbH & Co. KG: A German brand within the Erwin Hymer Group, renowned for pioneering space-saving interior concepts, notably the motorized drop-down bed (Hubbett).
- RV Portfolio: Burstner.
- Core Offerings: Semi-integrated and integrated motorhomes (Lyseo TD, Elegance), compact campervans, urban runabouts (Copa), and lightweight caravans.
● KABE Group AB: Sweden's premier leisure vehicle manufacturer, specializing in high-specification winterized RVs engineered for extreme Scandinavian sub-zero environments.
- RV Portfolio: KABE, Affinity.
- Core Offerings: Premium winter-proof caravans with hydronic underfloor heating, luxury integrated and semi-integrated motorhomes, and high-end campervan conversions.
● SoliferPolar AB
- Overview: A specialized Swedish caravan and motorhome fabricator based in Dorotea, combining the heritage Polar and Solifer brand names.
- RV Portfolio: Polar, Solifer.
- Core Offerings: Handcrafted extreme-winter touring caravans (Polar Original, Customized) and all-weather motorhomes.
● Swift Group Limited: The United Kingdom's largest manufacturer of touring caravans, motorhomes, and static holiday homes, headquartered in East Yorkshire.
- RV Portfolio: Swift, Sprite, Monza.
- Core Offerings: Aerodynamic touring caravans, coachbuilt low-profile motorhomes, compact campervans, and stationary luxury holiday homes.
● Bailey of Bristol: The United Kingdom's longest-standing independent caravan manufacturer, noted for inventing the patented Alu-Tech body construction framework.
- RV Portfolio: Bailey (Discovery, Phoenix, Unicorn, Alicanto Grande, Adamo, Alora, Endeavour).
- Core Offerings: Single- and twin-axle touring caravans, low-profile coachbuilt motorhomes, and Ford Transit-based campervans.
3. Australasian Manufacturers and Fleet Operators
● Jayco Corporation Pty Ltd: Australia's largest RV manufacturer, operating independently from the US Jayco brand and controlling nearly half of the Australian domestic market.
- RV Portfolio: Jayco (Australia).
- Core Offerings: Severe-duty off-road caravans, touring caravans (Silverline, Journey, All-Terrain), pop-tops, fold-out camper trailers, Class B campervans, and Class C motorhomes.
● Tourism Holdings Limited (thl): A New Zealand-based global tourism operator that merged with Apollo Tourism and Leisure; it is the largest commercial motorhome rental operator in the world.
- RV Portfolio: Maui, Britz, Mighty, Apollo, KEA, Road Bear RV, El Monte RV, Action Manufacturing.
- Core Offerings: Commercial rental campervans, 2-to-6 berth coachbuilt motorhomes, 4WD pop-top safari campers, and purpose-built specialty commercial vehicles.
● Supreme Caravans: A long-standing Melbourne-based manufacturer specialized in semi-off-road and heavy-duty off-road caravans engineered for harsh Australian conditions.
- RV Portfolio: Supreme Caravans, Leader Caravans.
- Core Offerings: Heavy-duty custom off-road caravans and family bunk layouts (Supreme Territory, Classic).
● JB Caravans: An Australian manufacturer known for high-durability off-road touring caravans, utilizing vertically integrated in-house steel chassis fabrication.
- RV Portfolio: JB Caravans.
- Core Offerings: Off-road caravans, rough-road luxury caravans, and custom family configurations (Scorpion Sting, Gator, Dirt Road).
● Lotus Caravans: A boutique Australian manufacturer focused on extreme-luxury, rugged off-road caravans with aggressive styling and high-capacity off-grid power.
- RV Portfolio: Lotus Caravans.
- Core Offerings: Heavy-duty off-road caravans with custom independent suspensions and checker-plate armor (Trooper, Freelander, Off-Grid).
4. Chinese Automakers and Specialty Manufacturers
● SAIC Motor Corporation Limited (SAIC Maxus RV): The dedicated recreational vehicle business arm of state-owned Chinese automotive manufacturer SAIC Motor, operating high-volume automated RV facilities in Liyang, Jiangsu.
- RV Portfolio: SAIC Maxus RV.
- Core Offerings: Factory-built Class B campervans (V90/V80 Traveler series), Class C slide-out motorhomes (Life Home series), and hybrid/electric conceptual RV lines.
● Zhengzhou Yutong Group: The dedicated leisure vehicle division of Yutong Bus, one of the world's largest commercial coach and bus manufacturers.
- RV Portfolio: Yutong RV.
- Core Offerings: Class C motorhomes built on Iveco Daily and Mercedes-Benz platforms, Class B campervans, and coach-style Class A luxury recreational vehicles.
● Weihai Guangtai (Guangtai Special Vehicle Co., Ltd.): A publicly listed Chinese specialty vehicle manufacturer and airport ground support equipment builder with specialized coachbuilding c
1.1 Study Objectives and Global Scope Definition 1
1.2 Primary and Secondary Data Validation Architecture 2
1.3 Bottom-Up and Top-Down Econometric Forecasting Models (2021-2031) 3
1.4 Base Year Currency Calibration, Deflators, and Unit Metrics 4
1.5 Nomenclature, Standard Industry Classifications, and Abbreviations 5
Chapter 2 Global Recreational Vehicle (RV) Market Trajectory and Macro Dynamics
2.1 Global RV Market Size by Value (USD Billion) and Shipments (Thousand Units) (2021-2031) 6
2.2 Post-Pandemic Normalization, Channel Inventory Destocking, and Financing Rate Impact 8
2.3 Powertrain Transition: Hybrid Platforms, 48V Off-Grid Architectures, and Electric RVs 10
2.4 Lightweight Structural Composites and Global Regulatory Safety Harmonization 11
Chapter 3 Global RV Market Breakdown by Product Segmentation
3.1 Motorized RV Market Size, Volume, and ASP Analysis (2021-2031) 13
3.1.1 Class A Motorhomes: Heavy Chassis Engineering and Luxury Fleet Dynamics 14
3.1.2 Class B Campervans: Urban Compactness, Van-Life Demand, and OEM Cutaway Chassis 16
3.1.3 Class C Motorhomes: Family Mid-Segment Adoption and Rental Fleet Absorption 17
3.2 Towable RV Market Size, Volume, and ASP Analysis (2021-2031) 18
3.2.1 Conventional and Lightweight Travel Trailers 19
3.2.2 Fifth-Wheel Trailers: Dual-Axle Towing and Long-Haul Residential Trends 20
3.2.3 Folding Camping Trailers and Compact Expansions 21
3.3 Park Model RVs: Semi-Permanent Tourism Infrastructure and Micro-Living Utility 22
Chapter 4 Global RV Market Analysis by Sales Channel
4.1 Wholesale B2B Franchise Dealer Networks: Inventory Floorplans and Floorplan Financing 23
4.2 B2C Direct-to-Consumer and Factory-Direct Models: Margin Optimization and Custom Builds 26
4.3 Commercial Fleet Procurement: Rental Operators, Eco-Tourism Resorts, and Peer-to-Peer 28
Chapter 5 RV Supply Chain Architecture, Bill of Materials, and Value Migration
5.1 Tier-1 Chassis Platforms: Sourcing Dynamics (Ford, Mercedes-Benz, Stellantis, Iveco) 30
5.2 Critical Subsystems: Lithium Power Banks, Inverters, HVAC, and Lightweight Slide-Outs 32
5.3 Value Chain Margin Distribution: Raw Materials, Assembly, Distribution, and Retail 34
5.4 Supply Chain Vulnerabilities: Semi-Finished Inventory Lag and Sourcing Diversification 36
Chapter 6 Cross-Border Trade Flows, Logistics, and Tariff Architecture
6.1 Global Export Command Centers: United States, Germany, and China 38
6.2 Primary Import Absorption Destinations: Canada, Australia, and Northern Europe 40
6.3 Trade Defense Instruments, Technical Homologation, and Non-Tariff Barriers 42
Chapter 7 North America RV Market Supply and Consumption Analysis
7.1 United States: Production Consolidation in Indiana and Regional Dealership Economics 44
7.2 Canada: Import Vulnerability, Extreme Weather Engineering, and Cross-Border Sourcing 48
Chapter 8 Europe RV Market Supply and Consumption Analysis
8.1 Germany: Industrial Scale, Erwin Hymer Cluster, and B2B Chassis Sourcing 52
8.2 France: Compact B-Class Penetration and Camping Municipal Infrastructure 54
8.3 United Kingdom: Right-Hand-Drive Caravan Manufacturing and Domestic Tourism Resilience 55
8.4 Sweden: Arctic Winterization Standards and Premium Caravan Demand 57
8.5 The Rest of Europe Market 58
Chapter 9 Asia-Pacific and Australasia RV Market Supply and Consumption Analysis
9.1 Australia and New Zealand: Heavy-Duty Off-Road Caravan Manufacturing and Out-Back Utilities 59
9.2 China: High-Growth Assembly Capabilities, Commercial Fleet Pilots, and Export Footprint 62
9.3 Japan: Kei-Van Conversions and Disaster-Response Auxiliary Housing Applications 64
Chapter 10 Global Competitive Landscape and Corporate Concentration
10.1 Global Market Share Concentration (CR4, CR8, and Herfindahl-Hirschman Index) 66
10.2 OEM Platform Commonality, M&A Consolidations, and Vertical Integration 68
10.3 Competitive Matrix: Electrification Benchmarking, Dealer Density, and Operating Margins 70
Chapter 11 Corporate Intelligence and Operating Performance Benchmarking
11.1 Thor Industries Inc.
11.1.1 Corporate Profile, Brand Architecture, and Global Footprint 72
11.1.2 Strategic SWOT Analysis and Production Footprint 73
11.1.3 RV Sales Volume, Revenue, Unit Price, Unit Cost, and Gross Margin (2021-2026) 74
11.1.4 Global RV Market Share and Dealer Network Exposure 75
11.2 Trigano S.A.
11.2.1 Corporate Profile, Brand Architecture, and Global Footprint 76
11.2.2 Strategic SWOT Analysis and Production Footprint 77
11.2.3 RV Sales Volume, Revenue, Unit Price, Unit Cost, and Gross Margin (2021-2026) 78
11.2.4 Global RV Market Share and Dealer Network Exposure 79
11.3 Knaus Tabbert AG
11.3.1 Corporate Profile, Brand Architecture, and Global Footprint 80
11.3.2 Strategic SWOT Analysis and Production Footprint 81
11.3.3 RV Sales Volume, Revenue, Unit Price, Unit Cost, and Gross Margin (2021-2026) 82
11.3.4 Global RV Market Share and Dealer Network Exposure 83
11.4 REV Group Inc.
11.4.1 Corporate Profile, Brand Architecture, and Global Footprint 84
11.4.2 Strategic SWOT Analysis and Production Footprint 84
11.4.3 RV Sales Volume, Revenue, Unit Price, Unit Cost, and Gross Margin (2021-2026) 85
11.4.4 Global RV Market Share and Dealer Network Exposure 86
11.5 Winnebago Industries Inc
11.5.1 Corporate Profile, Brand Architecture, and Global Footprint 87
11.5.2 Strategic SWOT Analysis and Production Footprint 88
11.5.3 RV Sales Volume, Revenue, Unit Price, Unit Cost, and Gross Margin (2021-2026) 89
11.5.4 Global RV Market Share and Dealer Network Exposure 90
11.6 Tourism Holdings Limited
11.6.1 Corporate Profile, Brand Architecture, and Global Footprint 91
11.6.2 Strategic SWOT Analysis and Production Footprint 92
11.6.3 RV Sales Volume, Revenue, Unit Price, Unit Cost, and Gross Margin (2021-2026) 93
11.6.4 Global RV Market Share and Dealer Network Exposure 94
11.7 KABE Group AB
11.7.1 Corporate Profile, Brand Architecture, and Global Footprint 95
11.7.2 Strategic SWOT Analysis and Production Footprint 95
11.7.3 RV Sales Volume, Revenue, Unit Price, Unit Cost, and Gross Margin (2021-2026) 96
11.7.4 Global RV Market Share and Dealer Network Exposure 97
11.8 Forest River Inc.
11.8.1 Corporate Profile, Brand Architecture, and Global Footprint 98
11.8.2 Strategic SWOT Analysis and Production Footprint 99
11.8.3 RV Sales Volume, Revenue, Unit Price, Unit Cost, and Gross Margin (2021-2026) 100
11.8.4 Global RV Market Share and Dealer Network Exposure 101
11.9 Hobby (including Fendt-Caravan GmbH)
11.9.1 Corporate Profile, Brand Architecture, and Global Footprint 102
11.9.2 Strategic SWOT Analysis and Production Footprint 103
11.9.3 RV Sales Volume, Revenue, Unit Price, Unit Cost, and Gross Margin (2021-2026) 104
11.9.4 Global RV Market Share and Dealer Network Exposure 105
11.10 Rapido Group
11.10.1 Corporate Profile, Brand Architecture, and Global Footprint 106
11.10.2 Strategic SWOT Analysis and Production Footprint 107
11.10.3 RV Sales Volume, Revenue, Unit Price, Unit Cost, and Gross Margin (2021-2026) 108
11.10.4 Global RV Market Share and Dealer Network Exposure 109
11.11 Pilote
11.11.1 Corporate Profile, Brand Architecture, and Global Footprint 110
11.11.2 Strategic SWOT Analysis and Production Footprint 111
11.11.3 RV Sales Volume, Revenue, Unit Price, Unit Cost, and Gross Margin (2021-2026) 112
11.11.4 Global RV Market Share and Dealer Network Exposure 113
11.12 Dethleffs
11.12.1 Corporate Profile, Brand Architecture, and Global Footprint 114
11.12.2 Strategic SWOT Analysis and Production Footprint 114
11.12.3 RV Sales Volume, Revenue, Unit Price, Unit Cost, and Gross Margin (2021-2026) 115
11.12.4 Global RV Market Share and Dealer Network Exposure 116
11.13 Carthago Reisemobilbau GmbH
11.13.1 Corporate Profile, Brand Architecture, and Global Footprint 117
11.13.2 Strategic SWOT Analysis and Production Footprint 118
11.13.3 RV Sales Volume, Revenue, Unit Price, Unit Cost, and Gross Margin (2021-2026) 119
11.13.4 Global RV Market Share and Dealer Network Exposure 120
11.14 Hymer GmbH & Co. KG
11.14.1 Corporate Profile, Brand Architecture, and Global Footprint 121
11.14.2 Strategic SWOT Analysis and Production Footprint 122
11.14.3 RV Sales Volume, Revenue, Unit Price, Unit Cost, and Gross Margin (2021-2026) 123
11.14.4 Global RV Market Share and Dealer Network Exposure 124
11.15 Bürstner GmbH & Co. KG
11.15.1 Corporate Profile, Brand Architecture, and Global Footprint 125
11.15.2 Strategic SWOT Analysis and Production Footprint 126
11.15.3 RV Sales Volume, Revenue, Unit Price, Unit Cost, and Gross Margin (2021-2026) 127
11.15.4 Global RV Market Share and Dealer Network Exposure 128
11.16 SoliferPolar AB
11.16.1 Corporate Profile, Brand Architecture, and Global Footprint 129
11.16.2 Strategic SWOT Analysis and Production Footprint 130
11.16.3 RV Sales Volume, Revenue, Unit Price, Unit Cost, and Gross Margin (2021-2026) 131
11.16.4 Global RV Market Share and Dealer Network Exposure 132
11.17 Supreme Caravans
11.17.1 Corporate Profile, Brand Architecture, and Global Footprint 133
11.17.2 Strategic SWOT Analysis and Production Footprint 134
11.17.3 RV Sales Volume, Revenue, Unit Price, Unit Cost, and Gross Margin (2021-2026) 135
11.17.4 Global RV Market Share and Dealer Network Exposure 136
11.18 JB Caravans
11.18.1 Corporate Profile, Brand Architecture, and Global Footprint 137
11.18.2 Strategic SWOT Analysis and Production Footprint 137
11.18.3 RV Sales Volume, Revenue, Unit Price, Unit Cost, and Gross Margin (2021-2026) 138
11.18.4 Global RV Market Share and Dealer Network Exposure 139
11.19 Lotus Caravans
11.19.1 Corporate Profile, Brand Architecture, and Global Footprint 140
11.19.2 Strategic SWOT Analysis and Production Footprint 141
11.19.3 RV Sales Volume, Revenue, Unit Price, Unit Cost, and Gross Margin (2021-2026) 142
11.19.4 Global RV Market Share and Dealer Network Exposure 143
11.20 Gulf Stream Coach Inc.
11.20.1 Corporate Profile, Brand Architecture, and Global Footprint 144
11.20.2 Strategic SWOT Analysis and Production Footprint 145
11.20.3 RV Sales Volume, Revenue, Unit Price, Unit Cost, and Gross Margin (2021-2026) 146
11.20.4 Global RV Market Share and Dealer Network Exposure 147
11.21 NeXus RV LLC
11.21.1 Corporate Profile, Brand Architecture, and Global Footprint 148
11.21.2 Strategic SWOT Analysis and Production Footprint 149
11.21.3 RV Sales Volume, Revenue, Unit Price, Unit Cost, and Gross Margin (2021-2026) 150
11.21.4 Global RV Market Share and Dealer Network Exposure 151
11.22 Swift Group Limited
11.22.1 Corporate Profile, Brand Architecture, and Global Footprint 152
11.22.2 Strategic SWOT Analysis and Production Footprint 153
11.22.3 RV Sales Volume, Revenue, Unit Price, Unit Cost, and Gross Margin (2021-2026) 154
11.22.4 Global RV Market Share and Dealer Network Exposure 155
11.23 Northwood Manufacturing Inc.
11.23.1 Corporate Profile, Brand Architecture, and Global Footprint 156
11.23.2 Strategic SWOT Analysis and Production Footprint 157
11.23.3 RV Sales Volume, Revenue, Unit Price, Unit Cost, and Gross Margin (2021-2026) 158
11.23.4 Global RV Market Share and Dealer Network Exposure 159
11.24 Triple E Recreational Vehicles
11.24.1 Corporate Profile, Brand Architecture, and Global Footprint 160
11.24.2 Strategic SWOT Analysis and Production Footprint 161
11.24.3 RV Sales Volume, Revenue, Unit Price, Unit Cost, and Gross Margin (2021-2026) 162
11.24.4 Global RV Market Share and Dealer Network Exposure 163
11.25 Bailey of Bristol
11.25.1 Corporate Profile, Brand Architecture, and Global Footprint 164
11.25.2 Strategic SWOT Analysis and Production Footprint 164
11.25.3 RV Sales Volume, Revenue, Unit Price, Unit Cost, and Gross Margin (2021-2026) 165
11.25.4 Global RV Market Share and Dealer Network Exposure 166
11.26 Jayco Corporation Pty Ltd
11.26.1 Corporate Profile, Brand Architecture, and Global Footprint 167
11.26.2 Strategic SWOT Analysis and Production Footprint 168
11.26.3 RV Sales Volume, Revenue, Unit Price, Unit Cost, and Gross Margin (2021-2026) 169
11.26.4 Global RV Market Share and Dealer Network Exposure 170
11.27 Eveland's Inc
11.27.1 Corporate Profile, Brand Architecture, and Global Footprint 171
11.27.2 Strategic SWOT Analysis and Production Footprint 172
11.27.3 RV Sales Volume, Revenue, Unit Price, Unit Cost, and Gross Margin (2021-2026) 173
11.27.4 Global RV Market Share and Dealer Network Exposure 174
11.28 Oliver Travel Trailers Inc.
11.28.1 Corporate Profile, Brand Architecture, and Global Footprint 175
11.28.2 Strategic SWOT Analysis and Production Footprint 176
11.28.3 RV Sales Volume, Revenue, Unit Price, Unit Cost, and Gross Margin (2021-2026) 177
11.28.4 Global RV Market Share and Dealer Network Exposure 178
11.29 New Gonow Recreational Vehicles Inc.
11.29.1 Corporate Profile, Brand Architecture, and Global Footprint 179
11.29.2 Strategic SWOT Analysis and Production Footprint 180
11.29.3 RV Sales Volume, Revenue, Unit Price, Unit Cost, and Gross Margin (2021-2026) 181
11.29.4 Global RV Market Share and Dealer Network Exposure 182
11.30 Weihai Guangtai
11.30.1 Corporate Profile, Brand Architecture, and Global Footprint 183
11.30.2 Strategic SWOT Analysis and Production Footprint 183
11.30.3 RV Sales Volume, Revenue, Unit Price, Unit Cost, and Gross Margin (2021-2026) 184
11.30.4 Global RV Market Share and Dealer Network Exposure 185
11.31 SAIC Motor Corporation Limited
11.31.1 Corporate Profile, Brand Architecture, and Global Footprint 186
11.31.2 Strategic SWOT Analysis and Production Footprint 187
11.31.3 RV Sales Volume, Revenue, Unit Price, Unit Cost, and Gross Margin (2021-2026) 188
11.31.4 Global RV Market Share and Dealer Network Exposure 189
11.32 Zhengzhou Yutong Group
11.32.1 Corporate Profile, Brand Architecture, and Global Footprint 190
11.32.2 Strategic SWOT Analysis and Production Footprint 191
11.32.3 RV Sales Volume, Revenue, Unit Price, Unit Cost, and Gross Margin (2021-2026) 192
11.32.4 Global RV Market Share and Dealer Network Exposure 193
Table 2 Industry Nomenclature and Technical Acronym Taxonomy 5
Table 3 Global RV Market Size (USD Billion) and Shipments (Thousand Units) by Region (2021-2026) 7
Table 4 Global RV Market Forecast by Region (2027-2031) 8
Table 5 Global RV Market Volume by Product Type (Thousand Units) (2021-2031) 13
Table 6 Global RV Market Value by Product Type (USD Billion) (2021-2031) 14
Table 7 Global Motorized RV Shipments and Average Selling Price by Class (2021-2031) 15
Table 8 Global Towable RV Shipments and Average Selling Price by Sub-Segment (2021-2031) 19
Table 9 Global Park Model RV Market Size and Volume Projections (2021-2031) 22
Table 10 Global RV Market Volume by Sales Channel (Thousand Units) (2021-2031) 24
Table 11 Global RV Market Value by Sales Channel (USD Billion) (2021-2031) 25
Table 12 Dealer Floorplan Financing Rates and Absorption Times by Major Hub (2021-2026) 26
Table 13 Rental Fleet Procurement Volumes and Operating Cycles (2021-2031) 29
Table 14 Tier-1 OEM Chassis Supply Split for Class A, B, and C Motorhomes (2021-2026) 31
Table 15 Bill of Materials (BOM) Cost Breakdown for Typical Class C and Towable RVs (2026) 35
Table 16 Global Cross-Border RV Export Shipments by Country of Origin (2021-2026) 39
Table 17 Global Cross-Border RV Import Receipts by Destination Market (2021-2026) 41
Table 18 Applicable Tariff Tariffs, Homologation Costs, and Import Duties by Region (2026) 43
Table 19 North America RV Shipments and Market Value by Type (2021-2031) 45
Table 20 United States RV Wholesale Shipments and Retail Registrations (2021-2026) 46
Table 21 Canada RV Import Volume and Regional Sales Breakdown (2021-2026) 49
Table 22 Europe RV Market Shipments and Market Value by Type (2021-2031) 53
Table 23 Germany RV Production, Domestic Sales, and Export Volumes (2021-2026) 54
Table 24 France RV New Registrations and Fleet Expansion Dynamics (2021-2026) 55
Table 25 United Kingdom Touring Caravan and Motorhome Registrations (2021-2026) 56
Table 26 Sweden Winterized RV Market Volume and Price Distribution (2021-2026) 58
Table 27 Asia-Pacific and Australasia RV Market Dynamics by Country (2021-2031) 60
Table 28 Australia Off-Road Caravan Local Production vs Import Volumes (2021-2026) 61
Table 29 China RV Production Capacity, Domestic Sales, and Exports (2021-2026) 63
Table 30 Japan Compact Campervan Registrations and Conversion Volume (2021-2026) 65
Table 31 Global RV Market Share Ranking and Operating Margins of Top 10 OEMs (2025-2026) 67
Table 32 Major Mergers, Acquisitions, and Equity Transactions in the RV Sector (2021-2026) 69
Table 33 Thor Industries Inc. RV Sales, Price, Cost and Gross Profit Margin (2021-2026) 74
Table 34 Trigano S.A. RV Sales, Price, Cost and Gross Profit Margin (2021-2026) 78
Table 35 Knaus Tabbert AG RV Sales, Price, Cost and Gross Profit Margin (2021-2026) 82
Table 36 REV Group Inc. RV Sales, Price, Cost and Gross Profit Margin (2021-2026) 85
Table 37 Winnebago Industries Inc RV Sales, Price, Cost and Gross Profit Margin (2021-2026) 89
Table 38 Tourism Holdings Limited RV Sales, Price, Cost and Gross Profit Margin (2021-2026) 93
Table 39 KABE Group AB RV Sales, Price, Cost and Gross Profit Margin (2021-2026) 96
Table 40 Forest River Inc. RV Sales, Price, Cost and Gross Profit Margin (2021-2026) 100
Table 41 Hobby (including Fendt-Caravan GmbH) RV Sales, Price, Cost and Gross Profit Margin (2021-2026) 104
Table 42 Rapido Group RV Sales, Price, Cost and Gross Profit Margin (2021-2026) 108
Table 43 Pilote RV Sales, Price, Cost and Gross Profit Margin (2021-2026) 112
Table 44 Dethleffs RV Sales, Price, Cost and Gross Profit Margin (2021-2026) 115
Table 45 Carthago Reisemobilbau GmbH RV Sales, Price, Cost and Gross Profit Margin (2021-2026) 119
Table 46 Hymer GmbH & Co. KG RV Sales, Price, Cost and Gross Profit Margin (2021-2026) 123
Table 47 Bürstner GmbH & Co. KG RV Sales, Price, Cost and Gross Profit Margin (2021-2026) 127
Table 48 SoliferPolar AB RV Sales, Price, Cost and Gross Profit Margin (2021-2026) 131
Table 49 Supreme Caravans RV Sales, Price, Cost and Gross Profit Margin (2021-2026) 135
Table 50 JB Caravans RV Sales, Price, Cost and Gross Profit Margin (2021-2026) 138
Table 51 Lotus Caravans RV Sales, Price, Cost and Gross Profit Margin (2021-2026) 142
Table 52 Gulf Stream Coach Inc. RV Sales, Price, Cost and Gross Profit Margin (2021-2026) 146
Table 53 NeXus RV LLC RV Sales, Price, Cost and Gross Profit Margin (2021-2026) 150
Table 54 Swift Group Limited RV Sales, Price, Cost and Gross Profit Margin (2021-2026) 154
Table 55 Northwood Manufacturing Inc. RV Sales, Price, Cost and Gross Profit Margin (2021-2026) 158
Table 56 Triple E Recreational Vehicles RV Sales, Price, Cost and Gross Profit Margin (2021-2026) 162
Table 57 Bailey of Bristol RV Sales, Price, Cost and Gross Profit Margin (2021-2026) 165
Table 58 Jayco Corporation Pty Ltd RV Sales, Price, Cost and Gross Profit Margin (2021-2026) 169
Table 59 Eveland's Inc RV Sales, Price, Cost and Gross Profit Margin (2021-2026) 173
Table 60 Oliver Travel Trailers Inc. RV Sales, Price, Cost and Gross Profit Margin (2021-2026) 177
Table 61 New Gonow Recreational Vehicles Inc. RV Sales, Price, Cost and Gross Profit Margin (2021-2026) 181
Table 62 Weihai Guangtai RV Sales, Price, Cost and Gross Profit Margin (2021-2026) 184
Table 63 SAIC Motor Corporation Limited RV Sales, Price, Cost and Gross Profit Margin (2021-2026) 188
Table 64 Zhengzhou Yutong Group RV Sales, Price, Cost and Gross Profit Margin (2021-2026) 192
Figure 1 Research Architecture and Bottom-Up Data Validation Workflow 3
Figure 2 Global RV Market Size Evolution and Forecast (USD Billion, 2021-2031) 7
Figure 3 Global RV Shipment Volume Trajectory (Thousand Units, 2021-2031) 9
Figure 4 Global RV Market Share by Product Type (2026 vs 2031) 14
Figure 5 Motorized RV Segment Growth Comparison: Class A vs B vs C (2021-2031) 16
Figure 6 Towable RV Sub-Segment Market Share Split (2026) 20
Figure 7 Global RV Market Volume Split by Sales Channel (2021-2031) 25
Figure 8 Dealer Margin Compression vs Inventory Days On Hand (2021-2026) 27
Figure 9 RV End-to-End Value Chain Margin Waterfall (2026) 35
Figure 10 Global RV Supply Chain Logistics Flow and Geopolitical Bottlenecks 37
Figure 11 Trade Balance Matrix: Major RV Net Exporting vs Net Importing Nations (2026) 40
Figure 12 North America RV Production Share: Elkhart Cluster vs Other Regions 47
Figure 13 Europe Motorized vs Towable RV Adoption Dynamics (2021-2031) 53
Figure 14 Australasia Off-Road Towable Market Share Trend (2021-2026) 61
Figure 15 China RV Domestic Production vs Export Shipments (2021-2031) 64
Figure 16 Global Market Share Concentration (CR4 and CR8, 2021-2026) 68
Figure 17 Thor Industries Inc. RV Market Share (2021-2026) 75
Figure 18 Trigano S.A. RV Market Share (2021-2026) 79
Figure 19 Knaus Tabbert AG RV Market Share (2021-2026) 83
Figure 20 REV Group Inc. RV Market Share (2021-2026) 86
Figure 21 Winnebago Industries Inc RV Market Share (2021-2026) 90
Figure 22 Tourism Holdings Limited RV Market Share (2021-2026) 94
Figure 23 KABE Group AB RV Market Share (2021-2026) 97
Figure 24 Forest River Inc. RV Market Share (2021-2026) 101
Figure 25 Hobby (including Fendt-Caravan GmbH) RV Market Share (2021-2026) 105
Figure 26 Rapido Group RV Market Share (2021-2026) 109
Figure 27 Pilote RV Market Share (2021-2026) 113
Figure 28 Dethleffs RV Market Share (2021-2026) 116
Figure 29 Carthago Reisemobilbau GmbH RV Market Share (2021-2026) 120
Figure 30 Hymer GmbH & Co. KG RV Market Share (2021-2026) 124
Figure 31 Bürstner GmbH & Co. KG RV Market Share (2021-2026) 128
Figure 32 SoliferPolar AB RV Market Share (2021-2026) 132
Figure 33 Supreme Caravans RV Market Share (2021-2026) 136
Figure 34 JB Caravans RV Market Share (2021-2026) 139
Figure 35 Lotus Caravans RV Market Share (2021-2026) 143
Figure 36 Gulf Stream Coach Inc. RV Market Share (2021-2026) 147
Figure 37 NeXus RV LLC RV Market Share (2021-2026) 151
Figure 38 Swift Group Limited RV Market Share (2021-2026) 155
Figure 39 Northwood Manufacturing Inc. RV Market Share (2021-2026) 159
Figure 40 Triple E Recreational Vehicles RV Market Share (2021-2026) 163
Figure 41 Bailey of Bristol RV Market Share (2021-2026) 166
Figure 42 Jayco Corporation Pty Ltd RV Market Share (2021-2026) 170
Figure 43 Eveland's Inc RV Market Share (2021-2026) 174
Figure 44 Oliver Travel Trailers Inc. RV Market Share (2021-2026) 178
Figure 45 New Gonow Recreational Vehicles Inc. RV Market Share (2021-2026) 182
Figure 46 Weihai Guangtai RV Market Share (2021-2026) 185
Figure 47 SAIC Motor Corporation Limited RV Market Share (2021-2026) 189
Figure 48 Zhengzhou Yutong Group RV Market Share (2021-2026) 193
Research Methodology
- Market Estimated Methodology:
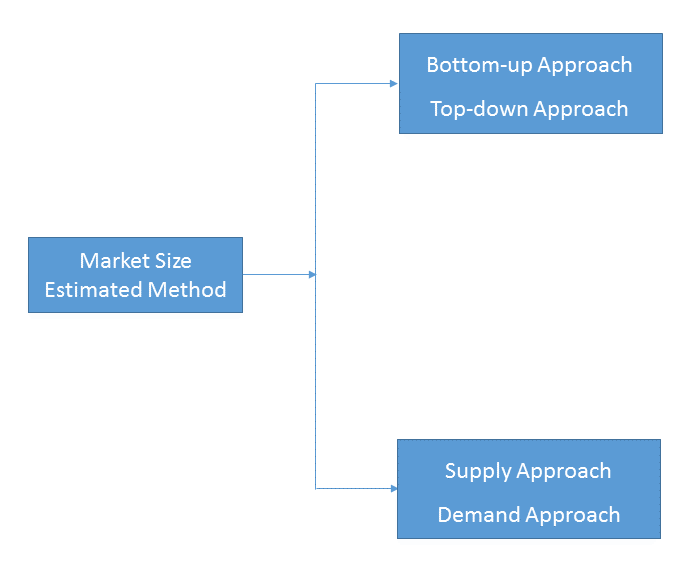
Bottom-up & top-down approach, supply & demand approach are the most important method which is used by HDIN Research to estimate the market size.
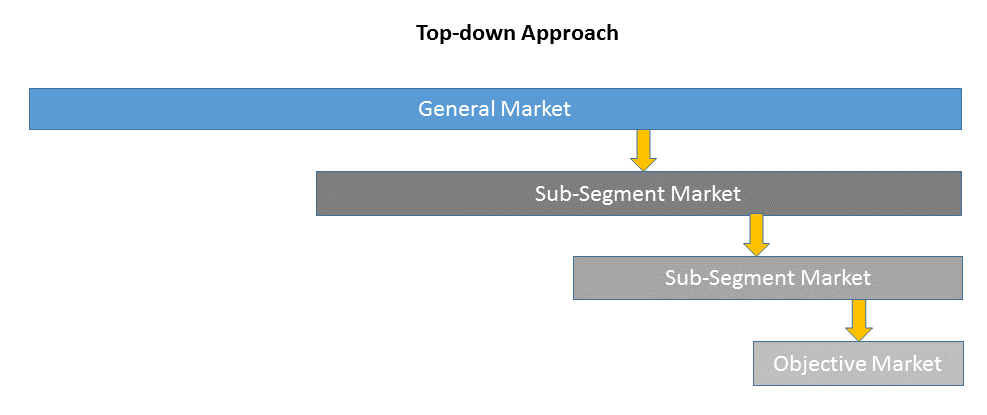
1)Top-down & Bottom-up Approach
Top-down approach uses a general market size figure and determines the percentage that the objective market represents.
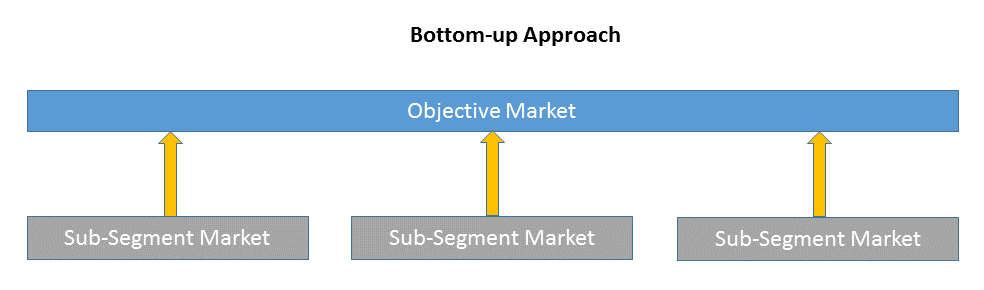
Bottom-up approach size the objective market by collecting the sub-segment information.
2)Supply & Demand Approach
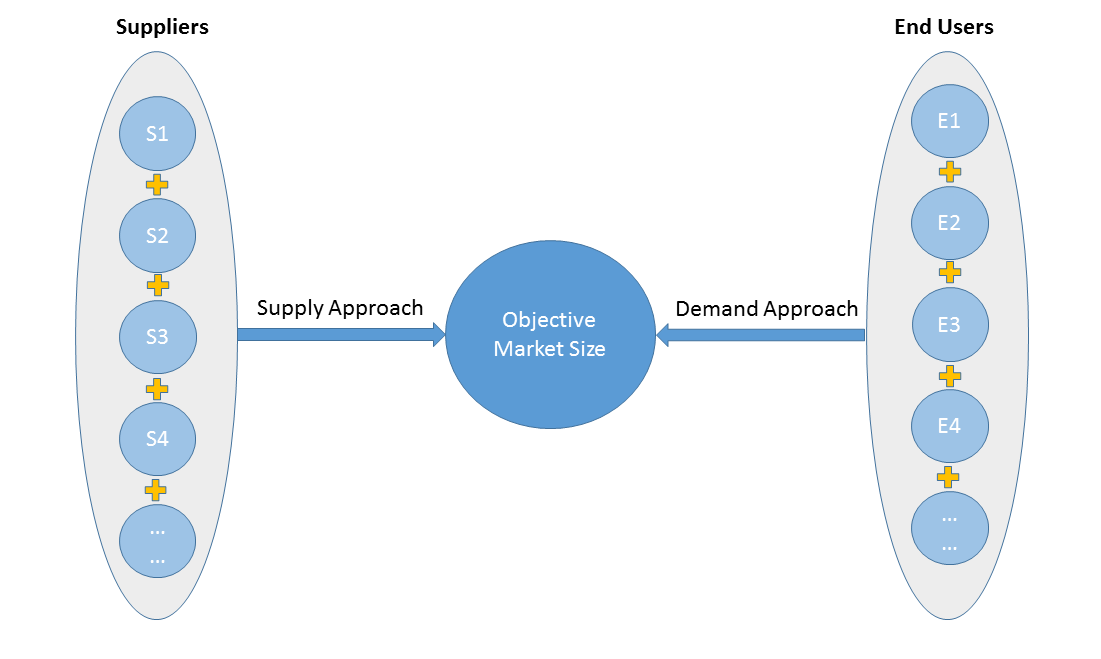
Supply approach is based on assessments of the size of each competitor supplying the objective market.
Demand approach combine end-user data within a market to estimate the objective market size. It is sometimes referred to as bottom-up approach.
- Forecasting Methodology
- Numerous factors impacting the market trend are considered for forecast model:
- New technology and application in the future;
- New project planned/under contraction;
- Global and regional underlying economic growth;
- Threatens of substitute products;
- Industry expert opinion;
- Policy and Society implication.
- Analysis Tools
1)PEST Analysis
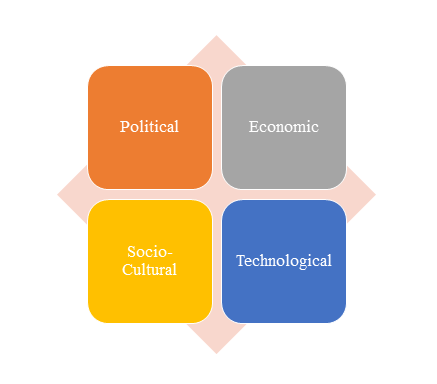
PEST Analysis is a simple and widely used tool that helps our client analyze the Political, Economic, Socio-Cultural, and Technological changes in their business environment.
- Benefits of a PEST analysis:
- It helps you to spot business opportunities, and it gives you advanced warning of significant threats.
- It reveals the direction of change within your business environment. This helps you shape what you’re doing, so that you work with change, rather than against it.
- It helps you avoid starting projects that are likely to fail, for reasons beyond your control.
- It can help you break free of unconscious assumptions when you enter a new country, region, or market; because it helps you develop an objective view of this new environment.
2)Porter’s Five Force Model Analysis
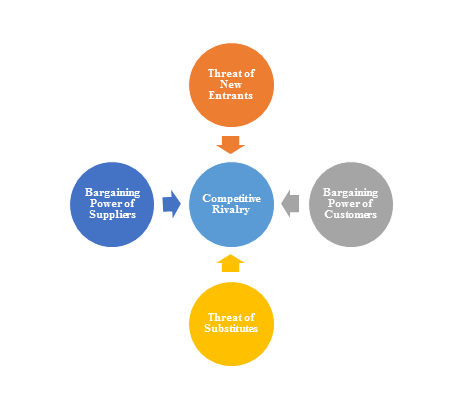
The Porter’s Five Force Model is a tool that can be used to analyze the opportunities and overall competitive advantage. The five forces that can assist in determining the competitive intensity and potential attractiveness within a specific area.
- Threat of New Entrants: Profitable industries that yield high returns will attract new firms.
- Threat of Substitutes: A substitute product uses a different technology to try to solve the same economic need.
- Bargaining Power of Customers: the ability of customers to put the firm under pressure, which also affects the customer's sensitivity to price changes.
- Bargaining Power of Suppliers: Suppliers of raw materials, components, labor, and services (such as expertise) to the firm can be a source of power over the firm when there are few substitutes.
- Competitive Rivalry: For most industries the intensity of competitive rivalry is the major determinant of the competitiveness of the industry.
3)Value Chain Analysis
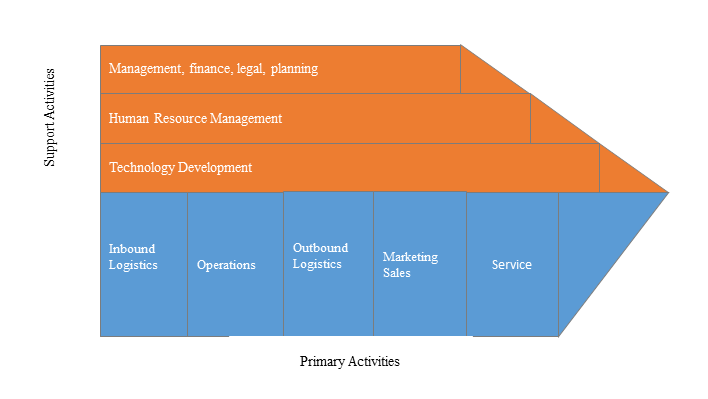
Value chain analysis is a tool to identify activities, within and around the firm and relating these activities to an assessment of competitive strength. Value chain can be analyzed by primary activities and supportive activities. Primary activities include: inbound logistics, operations, outbound logistics, marketing & sales, service. Support activities include: technology development, human resource management, management, finance, legal, planning.
4)SWOT Analysis
SWOT analysis is a tool used to evaluate a company's competitive position by identifying its strengths, weaknesses, opportunities and threats. The strengths and weakness is the inner factor; the opportunities and threats are the external factor. By analyzing the inner and external factors, the analysis can provide the detail information of the position of a player and the characteristics of the industry.
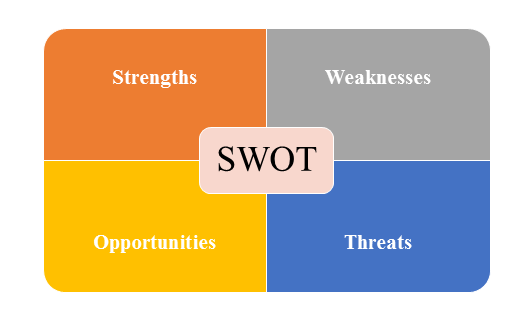
- Strengths describe what the player excels at and separates it from the competition
- Weaknesses stop the player from performing at its optimum level.
- Opportunities refer to favorable external factors that the player can use to give it a competitive advantage.
- Threats refer to factors that have the potential to harm the player.
- Data Sources
| Primary Sources | Secondary Sources |
|---|---|
| Face to face/Phone Interviews with market participants, such as: Manufactures; Distributors; End-users; Experts. Online Survey |
Government/International Organization Data: Annual Report/Presentation/Fact Book Internet Source Information Industry Association Data Free/Purchased Database Market Research Report Book/Journal/News |