Surgical Robot Market Size, Trends & Forecast 2026-2031
- Single User License (1 Users) $ 3,500
- Team License (2~5 Users) $ 4,500
- Corporate License (>5 Users) $ 5,500
The global surgical robot market is projected to reach between 25 billion USD and 30 billion USD in 2026, advancing at a compound annual growth rate (CAGR) within the 12% to 18% corridor through 2031. Growth is underpinned by procedural expansion outside legacy pelvic surgery into high-volume general surgery, the adoption of single-port architectures, and the incorporation of artificial intelligence into preoperative spatial workflows.
A surgical robot is an advanced computer-assisted, master-slave operated or semi-autonomous intelligent medical device designed to overcome human mechanical, visual, and ergonomic limitations inherent in open and traditional laparoscopic procedures. The baseline multi-port and single-port system comprises a Surgeon Console (master controller), a Patient-Side Cart (slave platform holding electromechanical arms), and a Vision/Imaging Cart. Hand sensors at the console capture real-time wrist and finger movements, convert signals via dynamic kinematic mapping algorithms, and execute corresponding sub-millimeter micro-movements of wristed instruments inside the patient.
Instruments feature 7 to 9 degrees of freedom (DoF) at the end-effector, matching or surpassing human joint articulation within constrained operative corridors. Systems incorporate stereoscopic endoscopes providing high-definition 3D/4K views with up to 10x optical magnification, paired with physiological tremor filtration and motion scaling. These systems transform extensive open incisions into micro-incisions (1.8cm single-port or keyhole multi-port access), minimizing blood loss, tissue trauma, and recovery times, while mitigating operator fatigue and eliminating occupational radiation exposure.
Product Classifications by Clinical Domain
1. Laparoscopic and Thoracoscopic Robots
Multi-port systems remain the volume anchor of clinical adoption, utilizing three to four articulating arms deployed via individual ports across abdominal and thoracic cavities. Platforms such as Intuitive Surgical’s da Vinci 5, Xi, and X, Medtronic’s Hugo RAS, MicroPort MedBot’s Toumai, Shenzhen Edge Medical’s MP1000, SS Innovations’ SSi Mantra 3, and meerecompany’s Revo-i populate this tier. Concurrently, single-port (SP) platforms present an alternative kinematic approach, deploying all wristed instruments and a stereoscopic optical line through an approximate 1.8cm single incision or natural orifice. Notable commercial architectures include Intuitive’s da Vinci SP, Beijing Surgerii’s SR-ENS-600/660 (which leverages continuum snake-arm deform-control mechanics), Edge Medical’s SP1000, MicroPort MedBot’s Toumai SP, and Vicarious Surgical System’s decoupled actuator layout.
2. Endoluminal and Endovascular Robots
Targeting tortuous vascular and bronchial pathways, these systems execute remote catheter and guidewire manipulation for coronary, peripheral, and neurovascular interventions, as well as pulmonary lesion navigation. Representative platforms include Intuitive’s Ion endoluminal system for robotic bronchoscopy, Microbot Medical’s LIBERTY disposable endovascular platform, Stereotaxis’ Genesis and Niobe systems employing robotic magnetic navigation, Rainmed’s caFFR/caIMR interventional devices, and MicroPort MedBot’s R-ONE and UniPath. Clinical demand is catalyzed by persistent macro incidence rates across cardiovascular interventions and stroke management, where automated trajectory guidance limits radiation exposure and physical strain for operators.
3. Orthopedic and Hard Tissue Robots
Engineered for reconstructive joint arthroplasty and spine stabilization, these systems integrate optical tracking, pre- or intra-operative CT/imageless navigation, and motorized milling or haptic boundaries for total knee arthroplasty (TKA), partial knee arthroplasty (PKA), total hip arthroplasty (THA), shoulder reconstruction, and spinal pedicle screw insertion. Key market platforms include Stryker’s Mako SmartRobotics, Zimmer Biomet’s ROSA platform, Smith & Nephew’s CORI system, Globus Medical’s ExcelsiusGPS and ExcelsiusFlex, Medtronic’s Mazor and Stealth Autoguide, Tinavi’s Tianji series, and MicroPort MedBot’s Honghu. Adoption metrics continue to validate this segment: Stryker has cleared over 2 million Mako procedures globally, while domestic tracking in China showed Tinavi exceeding 49,000 orthopedic cases within 2025 alone, surpassing an aggregate of 150,000 completed cases.
4. Neurosurgical and Stereotactic Cranial Robots
These platforms translate multi-modal image fusion (CT, MRI, PET) into stereotactic trajectories for deep brain stimulation (DBS), stereotactic electroencephalography (SEEG) electrode alignment, targeted biopsies, hematoma evacuation, and magnetic resonance-guided laser interstitial thermal therapy (MRgLITT). Core solutions comprise Sinovation’s NS1 and MRgLITT LS1 systems, Medtronic’s StealthStation S8/Stealth Autoguide, and Globus Medical’s ExcelsiusGPS Cranial. These platforms reduce targeting error and procedural durations by displacing heavy physical stereotactic frames with optical registration and automated robotic positioning.
5. Microsurgery and Ophthalmic Robots
Operating at the anatomical frontier of micro-anastomosis, these systems execute microsuturing on sub-2mm structures, supporting lymphaticovenular anastomosis, microvascular reconstruction, pediatric cardiac repair, and retinal micro-interventions. Systems rely on dynamic tremor filtration, sub-millimeter positional resolution, and motion scaling reaching up to 10:1 ratios, allowing surgical precision on continuous cardiac or micro-neural targets that manual instruments cannot reliably match.
Downstream Applications and Procedural Utilization
1. General Surgery
Representing the largest aggregate volume pool, general surgery covers ventral and inguinal hernia repair, colorectal resections, cholecystectomy, bariatric conversions, and upper gastrointestinal interventions. Demonstrating segment volume, Intuitive Surgical documented 1,250,000 general surgery cases in the United States (+18% year-over-year) and 334,000 international cases (+31% year-over-year) during 2025. Inguinal and ventral hernia repairs alongside deep pelvic colorectal procedures represent the primary procedural volume drivers.
2. Urologic Surgery
Historically serving as the clinical anchor for robotic capital adoption, urology remains deeply penetrated. Standard indications comprise radical prostatectomy, partial nephrectomy, radical cystectomy, and benign prostatic hyperplasia (BPH) resection. For 2025, Intuitive logged 201,000 domestic US urology cases alongside 507,000 international procedures. While mature in the United States where robotic prostatectomy represents the de facto standard of care, procedural growth continues across secondary and tertiary facilities internationally.
3. Gynecologic Surgery
Covering both oncological and benign conditions, this application spectrum spans hysterectomy, sacrocolpopexy, myomectomy, and complex endometriosis excision. Intuitive recorded 468,000 US gynecological cases (+11% year-over-year) and 181,000 international cases (+28% year-over-year) in 2025. In emerging configurations, specialized single-port platforms, such as Beijing Surgerii's multi-center registered clinical trials across 63 gynecological cohorts, continue to validate micro-incision approaches.
4. Orthopedic and Spine Surgery
Procedural allocations focus on structural biomechanics: TKA, PKA, THA, traumatic fracture stabilization, and pedicle screw alignment. Arthroplasty volume conversion is reinforced by commercial integration between proprietary implants and robotic software ecosystems.
5. Other Indications: Cardiothoracic, Head and Neck, Pulmonology
Cardiothoracic indications focus on internal mammary artery dissection, totally endoscopic coronary artery bypass (TECAB), and mitral valve repair; SS Innovations, for example, has logged over 400 cardiac surgeries utilizing its SSi Mantra platform. Transoral Robotic Surgery (TORS) accesses oropharyngeal lesions without open mandibular split osteotomies. Concurrently, endoluminal pulmonology has accelerated; Intuitive’s Ion platform completed 144,100 procedures in 2025 (+51% year-over-year), supported by an installed base of 995 operational units.
Commercial Delivery and Sales Channel Architecture
Robotics manufacturers navigate healthcare capital procurement using direct-distributor commercial models supported by a razor-and-blade business design.
1. Direct and Indirect Geographic Distribution
Mature healthcare zones—specifically the US, Western Europe, Japan, South Korea, India, and Canada—are managed primarily via direct sales operations. These teams split into Capital Sales, targeting hospital executives, Integrated Delivery Networks (IDNs), and Group Purchasing Organizations (GPOs), and Clinical Field Specialists, who provide intraoperative technical support, drive system utilization, and handle supply chain replenishment. In contrast, emerging markets across Latin America, the Middle East, and parts of the Asia-Pacific utilize specialized medical distributor channels to navigate localized regulatory barriers, tenders, and clinical onboarding. In China, localization mandates drive hybrid joint-venture operations; Intuitive operates through its Intuitive Surgical-Fosun joint venture, producing da Vinci Xi systems directly out of its Shanghai manufacturing facility to satisfy local domestic tender requirements.
2. Revenue Mechanics: Capital, Consumables, and Services
- Capital Equipment Sales: Upfront capital sales involve significant outlays, with soft-tissue multi-port systems ranging from $0.7 million to $3.1 million USD per system, while dedicated platforms like the Ion system sit between $500,000 and $815,000 USD.
- Operating and Sales-Type Leases: To reduce capital procurement barriers, OEMs deploy structured operating leases, sales-type leases, and pay-per-procedure utilization models. In 2025, 51% of Intuitive's 1,721 global da Vinci placements utilized operating lease mechanics (comprising 496 usage-based structures and 376 fixed-payment models). Challengers like SS Innovations utilize pay-per-procedure frameworks combining a baseline monthly lease fee with variable case fees.
- Consumables and Specialized Instruments: Proprietary articulating instruments—such as micro-forceps, energy dissectors, and robotic staplers—contain embedded EEPROM or RFID tracking chips that restrict mechanical usage cycles. Recurring instrument spend ranges between $900 and $3,700 USD per individual procedure across soft-tissue applications.
- Maintenance and Service Contracts: Following initial warranty expirations, long-term service agreements generate recurring annual fees ranging from $95,000 to $225,000 USD per multi-port system ($55,000 to $70,000 USD for Ion). These agreements cover ongoing field engineering, 24/7 technical monitoring, and proprietary software upgrades. For market incumbents, recurring revenue streams (consumables plus service agreements) now account for over 80% of aggregate top-line revenue.
Supply Chain Architecture and Value Chain Bottlenecks
The surgical robotics value chain is characterized by severe technological interdependencies, single-source component nodes, and strict global regulatory certifications spanning its upstream, midstream, and downstream tiers.
1. Upstream Engineering: Actuation, Optics, and Metallurgy
The structural framework requires miniaturized, high-torque brushless DC motors, harmonic drive speed reducers, and decoupled mechanical pulleys. Single-port and continuum systems rely heavily on nitinol (NiTi) super-elastic shape memory alloy tubes and high-tensile wire arrays to execute multi-directional articulation without buckling. Magnetic navigation requires high-grade sintered neodymium permanent magnets. Optical stacks depend on stereoscopic dual-sensor 4K/3D CMOS image chips, real-time optical encoders, infrared/fluorescence filters, and high-bandwidth EtherCAT communications buses.
Supplier Concentration Risk: The supply chain exhibits acute single-source vulnerabilities. Precision micro-motors, surgical-grade nitinol tubing, high-resolution optical image sensors, and specialized medical transducers are concentrated among a narrow band of specialized Tier-1 component fabricators in Germany, Japan, Switzerland, and the United States. Geopolitical volatility, trade tariffs, and localized production disruptions create direct operating risks for downstream device integrators.
2. Midstream Integration: IP Thickets and Manufacturing Standards
Midstream activities center on kinematic software integration, inverse kinematics processing, continuum deformation modeling, tremor cancellation software, and low-latency image pipeline transmission. Modern platforms increasingly embed AI-assisted surgical mapping engines (such as PROCEPT’s FirstAssist AI and Medtronic’s UNiD adaptive spine platform). Manufacturing assembly requires precision cleanroom operations under strict ISO 13485, MDSAP, and US FDA Quality System Regulation (QSR) environments.
Barriers to Entry:
- Intellectual Property Walls: Incumbent players hold dense patent thickets protecting multi-joint kinematics, cable-drive mechanisms, trocar docking, and master-slave ergonomics, forcing late entrants to design complex architectural workarounds.
- Capital and Development Cycles: Platform development involves extended R&D cycles requiring significant initial capital before generating commercial cash flows.
- Regulatory Clearances: Securing Class II/III approvals across jurisdictions involves multi-year review cycles through US FDA 510(k), De Novo, or PMA tracks; the European Union Medical Device Regulation (EU MDR); and China’s National Medical Products Administration (NMPA) special approval green channels.
3. Downstream Market Mechanics: Provider Infrastructure and Reimbursement
End-user purchasing nodes include academic medical centers, tertiary hospitals, public health authorities, and Ambulatory Surgical Centers (ASCs). The migration of musculoskeletal, gynecological, and minor soft-tissue procedures to ASCs is driving procurement toward smaller-footprint, modular systems (e.g., Smith & Nephew’s CORI, Moon Surgical’s Maestro, and Vicarious Surgical).
Reimbursement Realities: In the US and several international markets, procedures utilize established Current Procedural Terminology (CPT) codes and Diagnosis-Related Group (DRG) hospital payment frameworks. Third-party commercial payors and public systems rarely provide differential or premium payments simply because a procedure was completed using robotic assistance. The capital amortization, maintenance costs, and recurring instrument charges must generally be absorbed within existing surgical DRG margins. System adoption must therefore be justified through operational returns: reduced lengths of stay, lower complication and readmission rates, improved surgeon retention, and higher aggregate procedural throughput.
Regional Market Dynamics
1. North America (United States and Canada)
Holding over 50% of the world’s installed systems and procedural volume, North America remains the primary commercial core. Market expansion in this mature region is characterized by replacement cycles, the transition to next-generation systems, and expansion into ambulatory environments. In 2025, Intuitive expanded its US operational footprint to 6,364 da Vinci units and over 805 Ion installations, with US da Vinci procedure volume expanding 15% year-over-year to 2.012 million procedures. General surgery volume grew 18% (1.250 million cases), and gynecological volume expanded 11% (468,000 cases). Over 60% of the approximately 4,000 orthopedic-focused US ASCs now support sports medicine alongside reconstructive surgeries, prioritizing compact systems like Smith & Nephew’s CORI. Near-term hospital capital expenditure headwinds include high capital costs and isolated procedural declines, such as GLP-1 pharmaceutical adoption softening bariatric procedural volumes by high-single-digit margins.
2. Asia-Pacific (APAC)
Representing the fastest-expanding macro-region. Growth profiles diverge between mature replacement-focused markets and emerging volume corridors.
- China: As APAC's largest single market, surpassing 1 billion USD, procurement operates under state-directed centralized quota allocations and volume-based purchasing (VBP). Despite near-term hospital procurement delays resulting from systemic healthcare compliance reviews, expansion is reinforced by import substitution directives and domestic robotic innovations.
- India: Representing an active expansion environment, India's broader healthcare delivery ecosystem is scaling rapidly, handling over 30 million surgical procedures annually. The demand for modular, cost-accessible platforms is accelerating domestic installations, driven by lower capital-cost entries such as the SSi Mantra.
- Japan and South Korea: Japan operates under statutory medical fee schedules that determine reimbursement additions for robotic procedures. South Korea, recovering from 2024 physician labor disputes, is experiencing renewed procedural volume alongside domestic clinical adoption of systems like meerecompany’s Revo-i and Curexo’s CUVIS platforms.
- Taiwan, China: Functions as an advanced regional early-adoption market for complex multi-port oncology resections and microsurgical training hubs across East Asia.
3. Europe
Europe is the second-largest commercial theater. Intuitive maintained an active base of 2,168 da Vinci platforms in Europe at the close of 2025. European multi-port procedures expanded to 656,000 cases in 2025 (representing a 16.7% CAGR over 2020), while single-port procedures accounted for 14,000 cases. System adoption is governed by country-level single-payer reimbursement structures (such as the UK NHS, France’s HAS, and Germany’s G-BA DRG frameworks) alongside the stringent clinical data requirements imposed by EU MDR 2017/745.
4. Latin America
Adoption across Brazil, Mexico, and Colombia is moving beyond private hospitals into broader regional institutions. Incumbents maintain direct sales infrastructure in Brazil and Mexico, while secondary manufacturers are securing local regulatory approvals: SS Innovations has established footprints across Colombia, Ecuador, and Guatemala, while MicroPort MedBot has secured ANVISA clearances in Brazil for its Honghu orthopedic and Toumai soft-tissue platforms.
5. Middle East and Africa (MEA)
MEA demand is concentrated around sovereign healthcare modernization programs across the GCC (notably Saudi Arabia's Vision 2030 and UAE smart healthcare infrastructure). Specialized private healthcare groups across North and South Africa are also establishing robotic surgery centers. Cross-regional clinical integrations are emerging; MicroPort MedBot’s Toumai system logged over 400 complex procedures at Clinique Ain Diab Littoral in Morocco, while SS Innovations secured regulatory clearances across the UAE, Oman, Kenya, and Nigeria.
Regulatory Frameworks and Policy Environments
1. United States Regulatory and Reimbursement Environment
The US Food and Drug Administration (FDA) regulates robotic platforms under Class II and Class III controls. Standard market entries utilize the 510(k) Premarket Notification path by proving substantial equivalence to a predicate system, or the De Novo classification for novel low-to-moderate risk architectures lacking a commercial predicate (e.g., PROCEPT AquaBeam or Vicarious Surgical). Complex, high-risk platforms require Premarket Approval (PMA) supported by controlled clinical trial endpoints. Manufacturers frequently leverage the FDA Breakthrough Devices Program or Safer Technologies Program (STeP)—which Vicarious Surgical entered in 2024 for its single-port ventral hernia system—to accelerate review interactions.
Reimbursement via Medicare Severity Diagnosis-Related Groupings (MS-DRGs) and Current Procedural Terminology (CPT) maintains fixed procedural payments regardless of robotic assistance. Consequently, hospital purchasing committees evaluate robotics through operational metrics: operating room turn times, post-operative recovery acceleration, and overall complication rate reductions. Corporate operations must also navigate compliance oversight under the Physician Payments Sunshine Act, False Claims Act, and Anti-Kickback Statutes regarding surgeon training proctorships and capital placement contracts.
2. China Regulatory, Quota, and Pricing Environment
The National Medical Products Administration (NMPA) designates soft-tissue, single-port, and orthopedic systems as Class III medical devices. Leading domestic platforms frequently leverage the NMPA Innovation Medical Device Special Approval Channel (the "Green Channel") for expedited technical review.
Capital equipment procurement is governed by the Class B Major Medical Equipment Quota Catalogue administered by the National Health Commission (NHC). The 14th Five-Year Plan quota framework allocated 559 new laparoscopic surgical robotic quotas, establishing a national cumulative target of 819 units, with hospital procurement requiring quota allocations prior to public tendering.
In January 2026, the National Healthcare Security Administration (NFSA) issued the Guidelines for Medical Service Price Items of Surgical and Treatment Auxiliary Operations (Trial), providing a standardized fee schedule framework for robotic surgical navigation, execution, and 5G telesurgical operations. Regional adoption began in early 2026 across early-implementing provinces like Hunan and Guangdong. This pricing framework ties robotic surgical fee add-ons to underlying baseline procedural fees while prohibiting unbundled fee billing. System utilization is also shaped by centralized Volume-Based Procurement (VBP) pricing pressures on consumable implants, alongside sustained regulatory oversight of hospital procurement practices.
3. European Union MDR Environment
The transition to EU Medical Device Regulation (EU MDR 2017/745) has raised evidence requirements for robotic systems. MDR requires extensive prospective clinical data, unannounced Notified Body factory assessments, proactive Post-Market Clinical Follow-up (PMCF), and continuous risk tracking under ISO 13485:2016. MDR compliance deadlines extend through 2027 to 2028 based on device risk classification. Domestic Chinese and Asian systems, including Beijing Surgerii’s SR-ENS-600, Edge Medical’s MP1000/SP1000, and MicroPort’s Toumai/Honghu, have obtained MDR CE marks to support commercial expansion into Europe and aligned international markets.
Global Market Trends
1. Shift from Multi-Port to Single-Port and Natural Orifice Access
Multi-port systems remain the volume standard, but single-port (SP) platforms deploying via a single ~1.8cm port or natural lumen are the fastest-expanding architectural segment. This migration is driven by snake-arm continuum robotics and miniaturized wristed mechanics, reducing abdominal wall trauma and post-operative pain while improving cosmetic outcomes across urology, gynecology, and transoral procedures.
2. Commercialization of Global Telesurgery and Satellite Networks
Tele-operated remote surgery has transitioned from demonstration trials to repeatable clinical practice. Telecommunication advancements using high-bandwidth 5G and low-earth orbit (LEO) satellite constellations have enabled cross-continental interventions, including operations spanning distances over 17,000 km. This capability helps address regional surgeon misallocations by allowing specialized surgeons to operate remotely across global clinical networks.
3. Artificial Intelligence Integration and Supervised Autonomy
Robotics architecture is transitioning beyond direct master-slave manipulation toward supervised autonomy. Systems are integrating computer vision and multimodal spatial models to support real-time tissue differentiation, critical boundary segmentation, dynamic optical tracking, and step-by-step procedural assistance. This foundational shift aims to reduce intraoperative human error and standardize procedural execution times across varying surgeon skill levels.
4. Decentralization into Ambulatory Surgical Centers (ASCs)
Surgical procedural volumes—predominantly across joint arthroplasty, hernia repair, and basic pelvic surgeries—continue to shift toward outpatient ambulatory surgical environments. This dynamic is driving market demand away from centralized multi-million-dollar footprints toward mobile, modular, and lower-capital platforms designed for smaller operating rooms and rapid turnover cycles.
Opportunities and Strategic Challenges
● Opportunities:
- Single-Port Clinical Expansion: Single-port procedures are positioned for accelerated adoption across major surgical economies, expanding surgical robotic viability within pediatric surgery, transoral resection, and transvesical urology where anatomical corridors are constrained.
- Telesurgery Democratization: Remote surgery platforms offer high operational utility for decentralized public health networks. Platforms that have proven operational stability across cross-border distances—such as the over 800 remote procedures performed on the Toumai platform and regulatory milestones achieved by SS Innovations in India—provide clear routes for expanding specialty access across secondary and regional healthcare tiers.
- Algorithmic Surgical Workflow Automation: Integrating procedural automation (such as PROCEPT's autonomous resection or experimental large-model soft-tissue automation) presents significant long-term potential. Automating repetitive surgical sequences can reduce operative variance, shorten anesthesia times, and improve overall facility operating room throughput.
- Developing Economy Import Substitution: Markets across APAC, Latin America, and MEA present substantial unaddressed operative volumes. Regional market challengers offering functional systems at 30% to 50% lower capital outlays compared to legacy platforms are positioned to drive procurement across tier-two regional and private health facilities.
● Challenges:
- High Capital Acquisition Costs and Financing Constraints: Capital outlays between $0.7 million and $3.1 million USD per system, combined with ongoing annual maintenance overheads running 10% to 20% of equipment acquisition costs, encounter friction during hospital budget reviews, elevated financing rates, and tightened public tenders.
- Operating Margin Squeeze: Because public and commercial health coverage systems rarely reimburse robotic interventions at a dedicated premium over standard laparoscopic procedures, hospital operators must internalize consumable instrument costs ranging from $900 to $3,700 USD per case. Where regional price schedules establish strict fee ceilings on patient-facing robotic add-ons, operating margins compress, constraining discretionary capital expenditure.
- Critical Supply Chain Interdependencies: Global robotics manufacturers rely on specialized sole-source suppliers for critical precision components, such as micro-motors, super-elastic nitinol arrays, specialized imaging transducers, and neodymium magnets. Trade disputes, tariff changes, and regional regulatory constraints continue to introduce cost volatility and assembly continuity risks.
- Intellectual Property and Lifecycle Litigation: Complex IP thickets surrounding kinematic wrist designs, actuation couplings, and master-slave ergonomics continue to create patent infringement risks for late-stage market entrants. Additionally, legal and antitrust scrutiny regarding post-market maintenance agreements, proprietary consumable locks, and instrument repair restrictions creates ongoing operational challenges for incumbent business models.
Company Information
● Multi-Specialty Conglomerates
Johnson and Johnson
- Strategic Pivot: Constructing an integrated digital healthcare ecosystem that bridges orthopedics, endoluminal diagnostics, and core soft-tissue laparoscopy to secure institutional hospital contracts.
- Operational Moat: The MONARCH endoluminal system provides robotic bronchoscopy access for peripheral lung biopsies and percutaneous nephrolithotomy (PCNL). The VELYS Robotic-Assisted Solution provides an imageless, table-mounted system for total knee arthroplasty, integrating directly with existing implant lines. The OTTAVA platform integrates robotic arms into a standard operating table to preserve operating room space. J and J leverages its established clinical distribution reach and multi-line institutional sales arrangements to insulate its market positioning.
Medtronic
- Strategic Pivot: Deploying modular system footprints across soft-tissue applications to counter monolithic cart systems, while integrating spine robotics into a digital spinal surgical ecosystem.
- Operational Moat: The Hugo Robotic-Assisted Surgery (RAS) system features independent, mobile arm carts designed for flexible positioning and cross-room mobility across general surgery, urology, and gynecology. In spine surgery, the Mazor X Stealth Edition integrates Medtronic’s surgical navigation and CT-based planning software with robotic guidance for pedicle screw placement. This is further supported by the UNiD adaptive spine AI platform, which models patient biomechanics to drive utilization across Medtronic's proprietary spinal implant portfolio.
● Soft Tissue and Laparoscopic Robotics Companies: Intuitive Surgical Inc., CMR Surgical Ltd., Medicaroid Corporation, meerecompany Inc., Asensus Surgical Inc. / KARL STORZ, Distalmotion SA, Moon Surgical SAS, SS Innovations International Inc., Vicarious Surgical Inc., Virtual Incision Corporation, Shanghai MicroPort MedBot (Group) Co. Ltd., Shenzhen Edge Medical Co. Ltd., Beijing Surgerii Robotics Company Limited, Harbin Sagebot Intelligent Medical Equipment Co. Ltd., Shandong Weigao Group.
● Orthopedic and Spine Robotics Companies: Stryker, Zimmer Biomet, Smith and Nephew, Globus Medical, THINK Surgical, Corin Group, Curexo, Beijing TINAVI Medical Technologies Co. Ltd., AK Medical, Chunli Medical, Hangzhou Jianjia Medical Technology, Beijing HURWA-Robot Medical Technology, Zoezen Robot Co. Ltd., Yuanhua Tech, Tuodao Medical Technology, 8i Robotics Inc., Shenzhen Futurtec Medical.
● Endovascular and Interventional Robotics Companies: Siemens Healthineers, Stereotaxis, Robocath, LN Robotics Inc., Sentante, Microbot Medical Inc., WeMed Medical.
● Endoluminal, Urology, and Targeted Specialty Robotics Companies: PROCEPT BioRobotics Corporation, Noah Medical Corporation, Biobot Surgical.
1.1 Research Objective and Study Scope 1
1.2 Market Definition and Taxonomic Boundaries 2
1.3 Primary Research and Secondary Data Synthesis 3
1.4 Bottom-Up and Top-Down Forecasting Models 4
1.5 Analytical Assumptions and Currency Standardizations 5
1.6 Standard Nomenclature and Abbreviations 6
Chapter 2 Global Surgical Robot Market Landscape and Macro-Environment 7
2.1 Global Market Sizing and Dynamic Trajectory (2021-2031) 7
2.2 Macroeconomic Drivers, Healthcare Expenditure, and Capital Allocation 10
2.3 Clinical Paradigm Shift: Minimally Invasive Surgery Adoption Curves 12
2.4 Demographic Transitions and Complex Surgical Volume Projections 14
2.5 Hospital Capital Equipment Procurement Cycles and Leasing Models 16
Chapter 3 Value Chain Architecture and Upstream Component Integration 19
3.1 End-to-End Surgical Robot Industry Value Chain Mapping 19
3.2 High-Precision Actuators, Harmonic Drives, and Servomotors 22
3.3 3D HD Endoscopic Vision Systems and Optical Tracking Sensors 25
3.4 Master Consoles, Teleoperation Interfaces, and Haptic Feedback Modules 28
3.5 Sterile Consumables, Specialized End-Effectors, and Instrument Reprocessing 30
Chapter 4 Global Surgical Robot Market Segmentation by Type 32
4.1 Segment Overview and Technology Roadmap Evaluation 32
4.2 Laparoscopic and Thoracoscopic Robot Systems 34
4.3 Endoluminal and Endovascular Robot Systems 37
4.4 Orthopedic and Hard Tissue Robot Systems 40
4.5 Neurosurgical and Stereotactic Cranial Robot Systems 43
4.6 Microsurgery and Ophthalmic Robot Systems 45
Chapter 5 Global Surgical Robot Market Segmentation by Downstream Application 46
5.1 Application Spectrum and Cross-Specialty Utilization Dynamics 46
5.2 General Surgery Procedures and Clinical Outgrowth 48
5.3 Urologic Surgery Procedures and Penetration Baselines 50
5.4 Gynecologic Surgery Procedures and Adoption Barriers 52
5.5 Orthopedic and Spine Surgery Procedural Volume Expansion 54
5.6 Other Interventional and Specialized Surgical Applications 56
Chapter 6 Global Regulatory Architecture, Cross-Border Trade, and Geopolitics 58
6.1 Regulatory Approval Pathways: US FDA, EU MDR, and China NMPA 58
6.2 Global Supply Chain Resilience and Specialized Component Trade Flows 61
6.3 Export Control Regimes, Cross-Border Tariffs, and Device Classifications 64
6.4 Intellectual Property Landscapes, Patent Thickets, and Freedom-to-Operate 67
Chapter 7 North America Surgical Robot Market Dynamic Assessment 70
7.1 Macro Regional Trends and Capital Equipment Replacement Rates 70
7.2 United States: Primary Production Clusters and Downstream Utilization 73
7.3 Canada: Public Healthcare Procurement Dynamics and Device Adoption 78
Chapter 8 Europe Surgical Robot Market Dynamic Assessment 82
8.1 European Market Framework, MDR Compliance Costs, and Tendering Patterns 82
8.2 Germany: High-Precision Component Manufacturing and Hospital Integration 84
8.3 France: Public Health Reimbursement Structures and Regional Centers 86
8.4 United Kingdom: NHS Digital Transformation and Robotic Hub Deployments 88
8.5 Switzerland: MedTech Engineering Hubs and Specialized Export Volumes 90
8.6 Italy & Rest of Europe: Regional Healthcare Autonomy and Surgical Adoption Trends 92
Chapter 9 Asia-Pacific Surgical Robot Market Dynamic Assessment 94
9.1 Rapid Clinical Scalability, Infrastructure Expansion, and Dual Circulation 94
9.2 China: Domestic Substitution Policies, High-Volume Manufacturing, and Adoption 96
9.3 Japan: Aging Demographics, Regulatory Harmonization, and Robotics Synergy 100
9.4 South Korea: Domestic Robot Commercialization and High-Density Installation 102
9.5 India: Tertiary Private Care Growth and Low-Cost System Diffusion 104
9.6 Singapore and Australia: Advanced Reference Centers and Clinical Trials 106
Chapter 10 Latin America, Middle East, and Africa Market Assessment 108
10.1 Emerging Healthcare Infrastructure and Robotic Surgery Penetration 108
10.2 Brazil: Private Hospital Group Capital Expenditure Dynamics 110
10.3 Mexico: Cross-Border Medical Tourism and Tier-1 Hospital Adoption 112
10.4 Israel: Surgical Robotics Innovation Incubators and Clinical Validation 114
10.5 Saudi Arabia and United Arab Emirates: Sovereign Health Investments 116
Chapter 11 Global Competitive Structure and Strategic Benchmarking 118
11.1 Competitive Tiering and Installed Base Market Share Matrix 118
11.2 Strategic Moats: Razor-and-Blade Business Models and Consumables Margin 121
11.3 Clinical Training Ecosystems, Surgeon Credentialing, and Switching Costs 124
11.4 Strategic Mergers, Platform Acquisitions, and Joint Ventures 126
Chapter 12 Corporate Intelligence: Key Global Market Players 128
12.1 Intuitive Surgical Inc 128
12.2 Microbot Medical Inc 132
12.3 Vicarious Surgical Inc. 135
12.4 PROCEPT BioRobotics Corporation 138
12.5 SS Innovations International Inc. 142
12.6 Johnson & Johnson 145
12.7 Medtronic 149
12.8 Zimmer Biomet 153
12.9 Smith & Nephew 156
12.10 Stryker 160
12.11 Globus Medical 163
12.12 Stereotaxis 167
12.13 THINK Surgical 170
12.14 Siemens Healthineers 174
12.15 Robocath 177
12.16 LN Robotics Inc 181
12.17 Sentante 184
12.18 CMR Surgical Ltd. 188
12.19 Distalmotion SA 191
12.20 Medicaroid Corporation 195
12.21 meerecompany Inc. 198
12.22 Noah Medical Corporation 202
12.23 Asensus Surgical Inc./KARL STORZ 205
12.24 Virtual Incision Corporation 209
12.25 Biobot Surgical 212
12.26 Beijing TINAVI Medical Technologies Co. Ltd. 216
12.27 Shanghai MicroPort MedBot (Group) Co. Ltd. 219
12.28 Shenzhen Edge Medical Co. Ltd. 223
12.29 Beijing Surgerii Robotics Company Limited 226
12.30 Harbin Sagebot Intelligent Medical Equipment Co. Ltd. 230
12.31 Shandong Weigao Group 233
12.32 AK Medical 237
12.33 Chunli Medical 240
12.34 Corin Group 244
12.35 Curexo 247
12.36 8i Robotics Inc. 251
12.37 Tuodao Medical Technology 254
12.38 Hangzhou Jianjia Medical Technology 258
12.39 Beijing HURWA-Robot Medical Technology 261
12.40 Zoezen Robot Co. Ltd. 265
12.41 Yuanhua Tech 268
12.42 Shenzhen Futurtec Medical 272
12.43 WeMed Medical 275
12.44 Moon Surgical SAS 278
Chapter 13 Future Industry Outlook and Technology Roadmap (2027-2031) 282
Table 2 List of Standard Industry Acronyms and Operational Abbreviations 6
Table 3 Global Surgical Robot Market Sizing, Average Selling Price, and Growth Rates (2021-2031) 9
Table 4 Global Surgical Robot Market Revenue by Product Type (2021-2031, USD Million) 33
Table 5 Global Surgical Robot System Shipments by Product Type (2021-2031, Units) 34
Table 6 Laparoscopic and Thoracoscopic Robot Market Revenue by Sub-Segment (2021-2031, USD Million) 36
Table 7 Endoluminal and Endovascular Robot Market Revenue by Sub-Segment (2021-2031, USD Million) 39
Table 8 Orthopedic and Hard Tissue Robot Market Revenue by Sub-Segment (2021-2031, USD Million) 42
Table 9 Neurosurgical and Stereotactic Cranial Robot Market Revenue (2021-2031, USD Million) 44
Table 10 Microsurgery and Ophthalmic Robot Market Revenue (2021-2031, USD Million) 45
Table 11 Global Surgical Robot Market Revenue by Application (2021-2031, USD Million) 47
Table 12 General Surgery Robotic Procedural Volumes and Market Revenue (2021-2031) 49
Table 13 Urologic Surgery Robotic Procedural Volumes and Market Revenue (2021-2031) 51
Table 14 Gynecologic Surgery Robotic Procedural Volumes and Market Revenue (2021-2031) 53
Table 15 Orthopedic and Spine Robotic Procedural Volumes and Market Revenue (2021-2031) 55
Table 16 Other Interventional Applications Market Revenue (2021-2031, USD Million) 57
Table 17 Global Surgical Robot Tariff Classifications, HS Codes, and Import Duty Rates 65
Table 18 Global Surgical Robot Revenue by Geographic Region (2021-2031, USD Million) 71
Table 19 North America Surgical Robot Revenue by Country (2021-2031, USD Million) 72
Table 20 United States Surgical Robot Market Sizing by Type (2021-2031, USD Million) 76
Table 21 Canada Surgical Robot Market Sizing by Type (2021-2031, USD Million) 80
Table 22 Europe Surgical Robot Revenue by Country (2021-2031, USD Million) 83
Table 23 Germany Surgical Robot Market Sizing by Application (2021-2031, USD Million) 85
Table 24 France Surgical Robot Market Sizing by Application (2021-2031, USD Million) 87
Table 25 United Kingdom Surgical Robot Market Sizing by Application (2021-2031, USD Million) 89
Table 26 Switzerland Surgical Robot Market Sizing by Application (2021-2031, USD Million) 91
Table 27 Italy Surgical Robot Market Sizing by Application (2021-2031, USD Million) 93
Table 28 Asia-Pacific Surgical Robot Revenue by Country (2021-2031, USD Million) 95
Table 29 China Surgical Robot Market Sizing by Type (2021-2031, USD Million) 98
Table 30 Japan Surgical Robot Market Sizing by Type (2021-2031, USD Million) 101
Table 31 South Korea Surgical Robot Market Sizing by Type (2021-2031, USD Million) 103
Table 32 India Surgical Robot Market Sizing by Type (2021-2031, USD Million) 105
Table 33 Rest of Asia-Pacific Surgical Robot Market Sizing by Type (2021-2031, USD Million) 107
Table 34 Latin America, Middle East, and Africa Revenue by Country (2021-2031, USD Million) 109
Table 35 Brazil Surgical Robot Market Sizing by Application (2021-2031, USD Million) 111
Table 36 Mexico Surgical Robot Market Sizing by Application (2021-2031, USD Million) 113
Table 37 Israel Surgical Robot Market Sizing by Application (2021-2031, USD Million) 115
Table 38 GCC Region Surgical Robot Market Sizing by Application (2021-2031, USD Million) 117
Table 39 Global Surgical Robot System Installed Base by Leading Competitor (2021-2026, Units) 120
Table 40 Intuitive Surgical Inc Surgical Robot Revenue, Cost and Gross Margin (2021-2026) 130
Table 41 Microbot Medical Inc Surgical Robot Revenue, Cost and Gross Margin (2021-2026) 133
Table 42 Vicarious Surgical Inc. Surgical Robot Revenue, Cost and Gross Margin (2021-2026) 136
Table 43 PROCEPT BioRobotics Corporation Surgical Robot Revenue, Cost and Gross Margin (2021-2026) 140
Table 44 SS Innovations International Inc. Surgical Robot Revenue, Cost and Gross Margin (2021-2026) 143
Table 45 Johnson & Johnson Surgical Robot Revenue, Cost and Gross Margin (2021-2026) 147
Table 46 Medtronic Surgical Robot Revenue, Cost and Gross Margin (2021-2026) 151
Table 47 Zimmer Biomet Surgical Robot Revenue, Cost and Gross Margin (2021-2026) 154
Table 48 Smith & Nephew Surgical Robot Revenue, Cost and Gross Margin (2021-2026) 158
Table 49 Stryker Surgical Robot Revenue, Cost and Gross Margin (2021-2026) 161
Table 50 Globus Medical Surgical Robot Revenue, Cost and Gross Margin (2021-2026) 165
Table 51 Stereotaxis Surgical Robot Revenue, Cost and Gross Margin (2021-2026) 168
Table 52 THINK Surgical Surgical Robot Revenue, Cost and Gross Margin (2021-2026) 172
Table 53 Siemens Healthineers Surgical Robot Revenue, Cost and Gross Margin (2021-2026) 175
Table 54 Robocath Surgical Robot Revenue, Cost and Gross Margin (2021-2026) 179
Table 55 LN Robotics Inc Surgical Robot Revenue, Cost and Gross Margin (2021-2026) 182
Table 56 Sentante Surgical Robot Revenue, Cost and Gross Margin (2021-2026) 186
Table 57 CMR Surgical Ltd. Surgical Robot Revenue, Cost and Gross Margin (2021-2026) 189
Table 58 Distalmotion SA Surgical Robot Revenue, Cost and Gross Margin (2021-2026) 193
Table 59 Medicaroid Corporation Surgical Robot Revenue, Cost and Gross Margin (2021-2026) 196
Table 60 meerecompany Inc. Surgical Robot Revenue, Cost and Gross Margin (2021-2026) 200
Table 61 Noah Medical Corporation Surgical Robot Revenue, Cost and Gross Margin (2021-2026) 203
Table 62 Asensus Surgical Inc./KARL STORZ Surgical Robot Revenue, Cost and Gross Margin (2021-2026) 207
Table 63 Virtual Incision Corporation Surgical Robot Revenue, Cost and Gross Margin (2021-2026) 210
Table 64 Biobot Surgical Surgical Robot Revenue, Cost and Gross Margin (2021-2026) 214
Table 65 Beijing TINAVI Medical Technologies Co. Ltd. Surgical Robot Revenue, Cost and Gross Margin (2021-2026) 217
Table 66 Shanghai MicroPort MedBot (Group) Co. Ltd. Surgical Robot Revenue, Cost and Gross Margin (2021-2026) 221
Table 67 Shenzhen Edge Medical Co. Ltd. Surgical Robot Revenue, Cost and Gross Margin (2021-2026) 224
Table 68 Beijing Surgerii Robotics Company Limited Surgical Robot Revenue, Cost and Gross Margin (2021-2026) 228
Table 69 Harbin Sagebot Intelligent Medical Equipment Co. Ltd. Surgical Robot Revenue, Cost and Gross Margin (2021-2026) 231
Table 70 Shandong Weigao Group Surgical Robot Revenue, Cost and Gross Margin (2021-2026) 235
Table 71 AK Medical Surgical Robot Revenue, Cost and Gross Margin (2021-2026) 238
Table 72 Chunli Medical Surgical Robot Revenue, Cost and Gross Margin (2021-2026) 242
Table 73 Corin Group Surgical Robot Revenue, Cost and Gross Margin (2021-2026) 245
Table 74 Curexo Surgical Robot Revenue, Cost and Gross Margin (2021-2026) 249
Table 75 8i Robotics Inc. Surgical Robot Revenue, Cost and Gross Margin (2021-2026) 252
Table 76 Tuodao Medical Technology Surgical Robot Revenue, Cost and Gross Margin (2021-2026) 256
Table 77 Hangzhou Jianjia Medical Technology Surgical Robot Revenue, Cost and Gross Margin (2021-2026) 259
Table 78 Beijing HURWA-Robot Medical Technology Surgical Robot Revenue, Cost and Gross Margin (2021-2026) 263
Table 79 Zoezen Robot Co. Ltd. Surgical Robot Revenue, Cost and Gross Margin (2021-2026) 266
Table 80 Yuanhua Tech Surgical Robot Revenue, Cost and Gross Margin (2021-2026) 270
Table 81 Shenzhen Futurtec Medical Surgical Robot Revenue, Cost and Gross Margin (2021-2026) 273
Table 82 WeMed Medical Surgical Robot Revenue, Cost and Gross Margin (2021-2026) 276
Table 83 Moon Surgical SAS Surgical Robot Revenue, Cost and Gross Margin (2021-2026) 280
Figure 1 Global Surgical Robot Market Sizing and Growth Forecast (2021-2031, USD Billion) 8
Figure 2 Surgical Robot Value Chain Architecture and Operational Margin Distribution 21
Figure 3 Upstream Component Sourcing Concentration and Cost Breakdown 24
Figure 4 Global Surgical Robot Market Share by Type (2021, 2026, and 2031) 33
Figure 5 Laparoscopic vs Endoluminal Growth Momentum Matrix (2021-2031) 38
Figure 6 Global Surgical Robot Market Share by Application (2021, 2026, and 2031) 47
Figure 7 Global Distribution of Active Surgical Robot Systems by Macro-Region (2026) 72
Figure 8 United States Surgical Robot Market Growth Trajectory (2021-2031, USD Million) 75
Figure 9 Europe Surgical Robot Revenue Share by Country (2026) 83
Figure 10 Asia-Pacific Surgical Robot Market Trajectory and Installed Base (2021-2031) 95
Figure 11 China Surgical Robot Domestic vs Imported Revenue Distribution (2021-2031) 97
Figure 12 Global Surgical Robot Market Share Concentration by Leading Vendors (2026) 119
Figure 13 Business Model Revenue Breakdown: Systems vs Consumables vs Services (2021-2031) 122
Figure 14 Intuitive Surgical Inc Surgical Robot Market Share (2021-2026) 131
Figure 15 Microbot Medical Inc Surgical Robot Market Share (2021-2026) 134
Figure 16 Vicarious Surgical Inc. Surgical Robot Market Share (2021-2026) 137
Figure 17 PROCEPT BioRobotics Corporation Surgical Robot Market Share (2021-2026) 141
Figure 18 SS Innovations International Inc. Surgical Robot Market Share (2021-2026) 144
Figure 19 Johnson & Johnson Surgical Robot Market Share (2021-2026) 148
Figure 20 Medtronic Surgical Robot Market Share (2021-2026) 152
Figure 21 Zimmer Biomet Surgical Robot Market Share (2021-2026) 155
Figure 22 Smith & Nephew Surgical Robot Market Share (2021-2026) 159
Figure 23 Stryker Surgical Robot Market Share (2021-2026) 162
Figure 24 Globus Medical Surgical Robot Market Share (2021-2026) 166
Figure 25 Stereotaxis Surgical Robot Market Share (2021-2026) 169
Figure 26 THINK Surgical Surgical Robot Market Share (2021-2026) 173
Figure 27 Siemens Healthineers Surgical Robot Market Share (2021-2026) 176
Figure 28 Robocath Surgical Robot Market Share (2021-2026) 180
Figure 29 LN Robotics Inc Surgical Robot Market Share (2021-2026) 183
Figure 30 Sentante Surgical Robot Market Share (2021-2026) 187
Figure 31 CMR Surgical Ltd. Surgical Robot Market Share (2021-2026) 190
Figure 32 Distalmotion SA Surgical Robot Market Share (2021-2026) 194
Figure 33 Medicaroid Corporation Surgical Robot Market Share (2021-2026) 197
Figure 34 meerecompany Inc. Surgical Robot Market Share (2021-2026) 201
Figure 35 Noah Medical Corporation Surgical Robot Market Share (2021-2026) 204
Figure 36 Asensus Surgical Inc./KARL STORZ Surgical Robot Market Share (2021-2026) 208
Figure 37 Virtual Incision Corporation Surgical Robot Market Share (2021-2026) 211
Figure 38 Biobot Surgical Surgical Robot Market Share (2021-2026) 215
Figure 39 Beijing TINAVI Medical Technologies Co. Ltd. Surgical Robot Market Share (2021-2026) 218
Figure 40 Shanghai MicroPort MedBot (Group) Co. Ltd. Surgical Robot Market Share (2021-2026) 222
Figure 41 Shenzhen Edge Medical Co. Ltd. Surgical Robot Market Share (2021-2026) 225
Figure 42 Beijing Surgerii Robotics Company Limited Surgical Robot Market Share (2021-2026) 229
Figure 43 Harbin Sagebot Intelligent Medical Equipment Co. Ltd. Surgical Robot Market Share (2021-2026) 232
Figure 44 Shandong Weigao Group Surgical Robot Market Share (2021-2026) 236
Figure 45 AK Medical Surgical Robot Market Share (2021-2026) 239
Figure 46 Chunli Medical Surgical Robot Market Share (2021-2026) 243
Figure 47 Corin Group Surgical Robot Market Share (2021-2026) 246
Figure 48 Curexo Surgical Robot Market Share (2021-2026) 250
Figure 49 8i Robotics Inc. Surgical Robot Market Share (2021-2026) 253
Figure 50 Tuodao Medical Technology Surgical Robot Market Share (2021-2026) 257
Figure 51 Hangzhou Jianjia Medical Technology Surgical Robot Market Share (2021-2026) 260
Figure 52 Beijing HURWA-Robot Medical Technology Surgical Robot Market Share (2021-2026) 264
Figure 53 Zoezen Robot Co. Ltd. Surgical Robot Market Share (2021-2026) 267
Figure 54 Yuanhua Tech Surgical Robot Market Share (2021-2026) 271
Figure 55 Shenzhen Futurtec Medical Surgical Robot Market Share (2021-2026) 274
Figure 56 WeMed Medical Surgical Robot Market Share (2021-2026) 277
Figure 57 Moon Surgical SAS Surgical Robot Market Share (2021-2026) 281
Figure 58 Next-Generation Technology Convergence: AI, Navigation, and Telepresence Roadmaps (2027-2031) 285
Research Methodology
- Market Estimated Methodology:
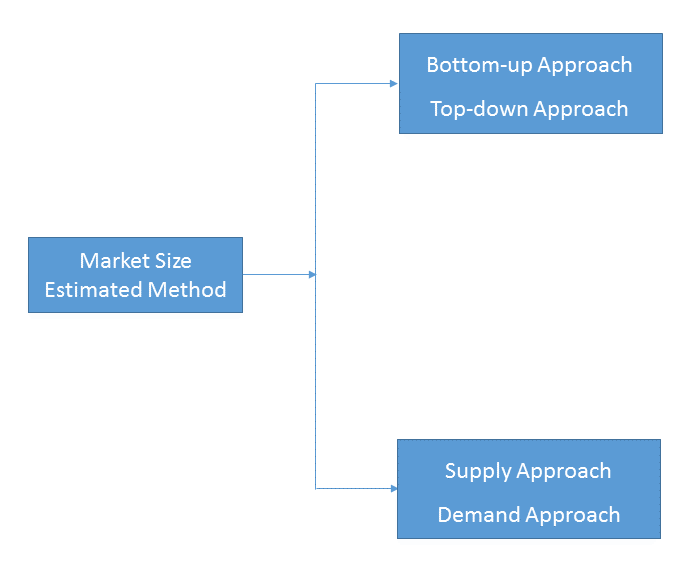
Bottom-up & top-down approach, supply & demand approach are the most important method which is used by HDIN Research to estimate the market size.
1)Top-down & Bottom-up Approach
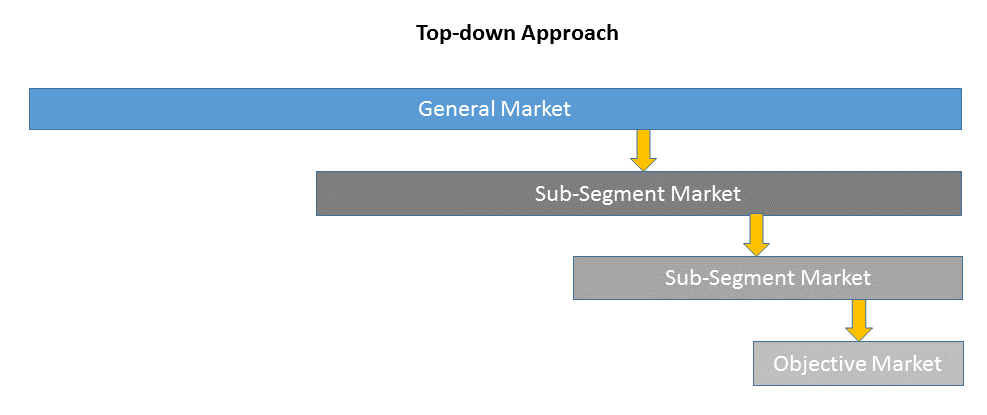
Top-down approach uses a general market size figure and determines the percentage that the objective market represents.
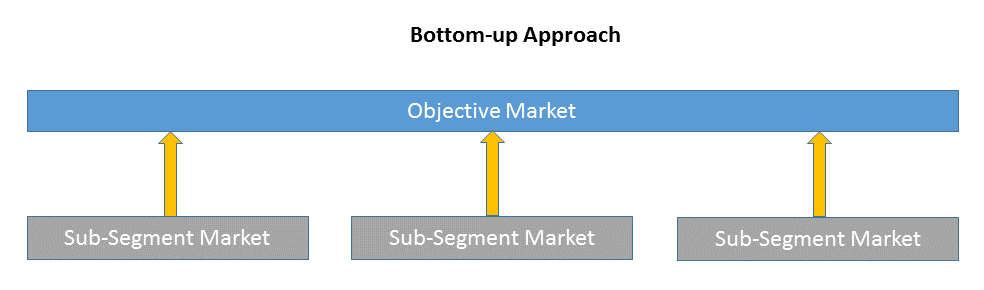
Bottom-up approach size the objective market by collecting the sub-segment information.
2)Supply & Demand Approach
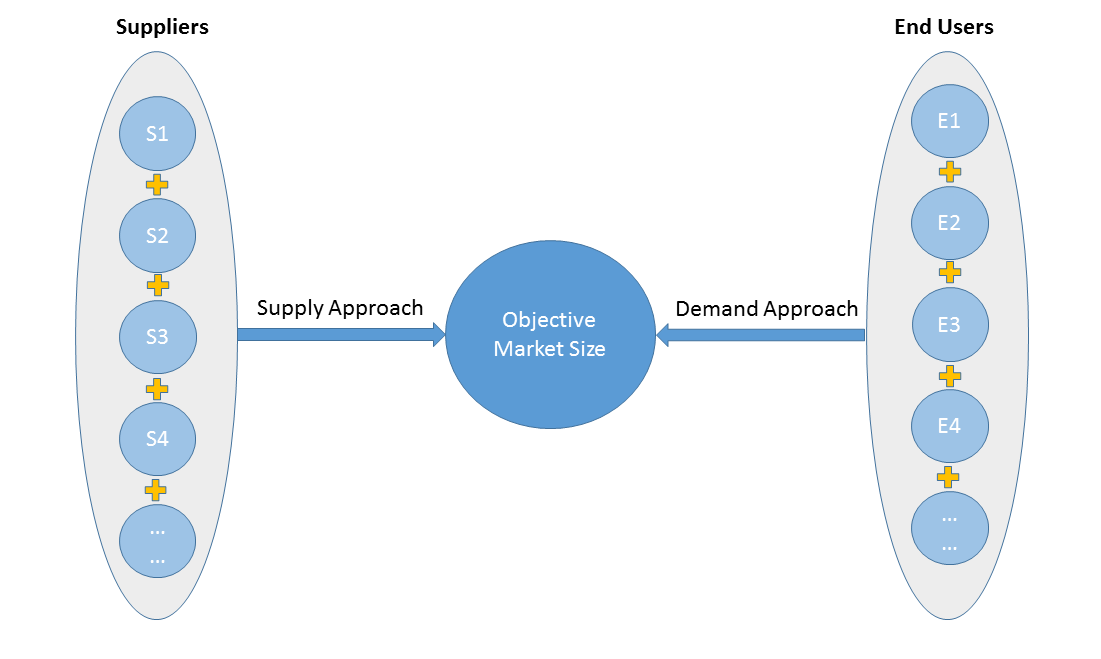
Supply approach is based on assessments of the size of each competitor supplying the objective market.
Demand approach combine end-user data within a market to estimate the objective market size. It is sometimes referred to as bottom-up approach.
- Forecasting Methodology
- Numerous factors impacting the market trend are considered for forecast model:
- New technology and application in the future;
- New project planned/under contraction;
- Global and regional underlying economic growth;
- Threatens of substitute products;
- Industry expert opinion;
- Policy and Society implication.
- Analysis Tools
1)PEST Analysis
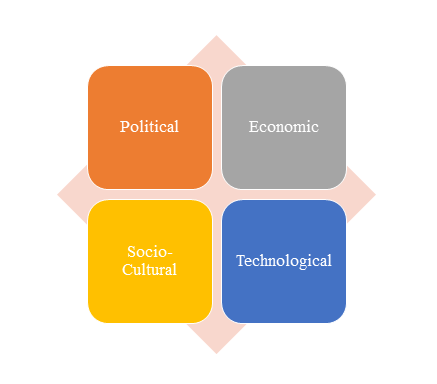
PEST Analysis is a simple and widely used tool that helps our client analyze the Political, Economic, Socio-Cultural, and Technological changes in their business environment.
- Benefits of a PEST analysis:
- It helps you to spot business opportunities, and it gives you advanced warning of significant threats.
- It reveals the direction of change within your business environment. This helps you shape what you’re doing, so that you work with change, rather than against it.
- It helps you avoid starting projects that are likely to fail, for reasons beyond your control.
- It can help you break free of unconscious assumptions when you enter a new country, region, or market; because it helps you develop an objective view of this new environment.
2)Porter’s Five Force Model Analysis
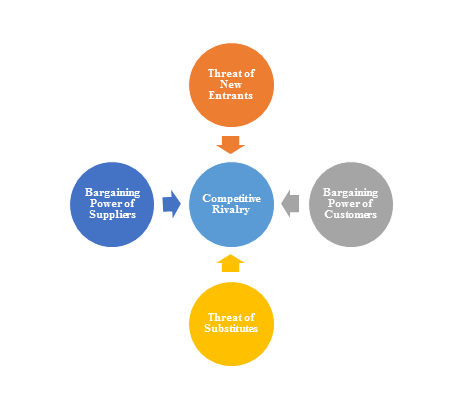
The Porter’s Five Force Model is a tool that can be used to analyze the opportunities and overall competitive advantage. The five forces that can assist in determining the competitive intensity and potential attractiveness within a specific area.
- Threat of New Entrants: Profitable industries that yield high returns will attract new firms.
- Threat of Substitutes: A substitute product uses a different technology to try to solve the same economic need.
- Bargaining Power of Customers: the ability of customers to put the firm under pressure, which also affects the customer's sensitivity to price changes.
- Bargaining Power of Suppliers: Suppliers of raw materials, components, labor, and services (such as expertise) to the firm can be a source of power over the firm when there are few substitutes.
- Competitive Rivalry: For most industries the intensity of competitive rivalry is the major determinant of the competitiveness of the industry.
3)Value Chain Analysis
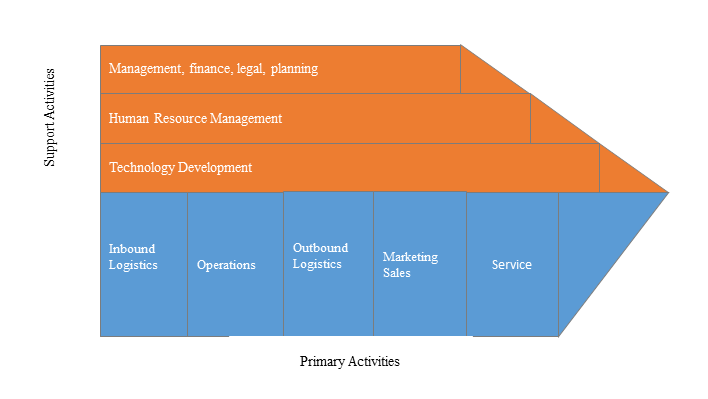
Value chain analysis is a tool to identify activities, within and around the firm and relating these activities to an assessment of competitive strength. Value chain can be analyzed by primary activities and supportive activities. Primary activities include: inbound logistics, operations, outbound logistics, marketing & sales, service. Support activities include: technology development, human resource management, management, finance, legal, planning.
4)SWOT Analysis
SWOT analysis is a tool used to evaluate a company's competitive position by identifying its strengths, weaknesses, opportunities and threats. The strengths and weakness is the inner factor; the opportunities and threats are the external factor. By analyzing the inner and external factors, the analysis can provide the detail information of the position of a player and the characteristics of the industry.
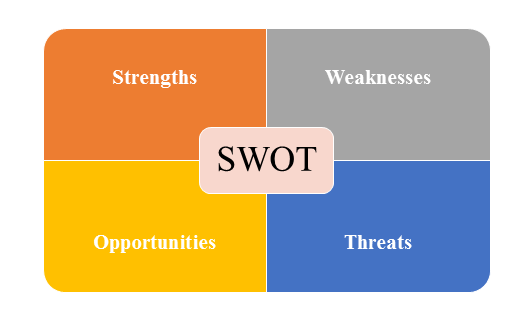
- Strengths describe what the player excels at and separates it from the competition
- Weaknesses stop the player from performing at its optimum level.
- Opportunities refer to favorable external factors that the player can use to give it a competitive advantage.
- Threats refer to factors that have the potential to harm the player.
- Data Sources
| Primary Sources | Secondary Sources |
|---|---|
| Face to face/Phone Interviews with market participants, such as: Manufactures; Distributors; End-users; Experts. Online Survey |
Government/International Organization Data: Annual Report/Presentation/Fact Book Internet Source Information Industry Association Data Free/Purchased Database Market Research Report Book/Journal/News |