Antibody-Drug Conjugates (ADCs) Market Intelligence: Global Pipeline and Commercial Strategy
- Single User License (1 Users) $ 3,500
- Team License (2~5 Users) $ 4,500
- Corporate License (>5 Users) $ 5,500
The commercialization of Antibody-Drug Conjugates (ADCs) has altered the therapeutic paradigm for systemic oncology, transforming targeted drug delivery from a theoretical construct into a major clinical modality. Built as molecular triads linking targeted monoclonal antibodies to potent small-molecule cytotoxic agents via stable chemical linkers, ADCs combine receptor-specific targeting with sub-nanomolar antiproliferative warheads.
The global ADC market to expand from an estimated 15.0 to 18.0 billion USD in 2026 at a compound annual growth rate (CAGR) of 10% to 16% through 2031. Growth will be driven by earlier-line clinical integration, biomarker-agnostic label expansions, and the industrial shift toward topoisomerase I inhibitor platforms.
The ADC market remains heavily consolidated. Five biopharmaceutical enterprises—Daiichi Sankyo/AstraZeneca, Roche, Pfizer, Gilead Sciences, and AbbVie—account for more than 90% of global commercial ADC revenue. Concurrently, an innovation corridor has emerged from China, where developers including四川百利天恒 (Sichuan Baili Tianheng), Kelun-Biotech, RemeGen, Lepu Biopharma, and Jiangsu Hengrui are executing multi-billion-dollar global out-licensing agreements, fundamentally realigning oncology supply chains and midstream clinical assets.
Market expansion faces several operational challenges:
* Significant Chemistry, Manufacturing, and Controls (CMC) barriers driven by Occupational Exposure Band 5 and 6 containment requirements.
* Class-specific toxicological liabilities, such as interstitial lung disease and severe peripheral neuropathy.
* Impending patent expirations for first- and second-generation blockbuster assets, most notably Kadcyla and Adcetris, between 2025 and 2028.
* Pricing scrutiny across both the United States, via Medicare price negotiation under the Inflation Reduction Act, and China, via National Reimbursement Drug List negotiations.
PRODUCT DEFINITION AND PHARMACODYNAMIC ARCHITECTURE
An Antibody-Drug Conjugate functions through a three-part biopharmaceutical design:
* Monoclonal Antibody Backbone: Primarily formatted as human or humanized immunoglobulin G1 (IgG1), the antibody binds with nanomolar affinity to tumor-associated antigens overexpressed on malignant cells with limited normal tissue expression. Beyond targeted delivery, the IgG1 backbone provides an extended circulating half-life via neonatal Fc receptor (FcRn) recycling and engages immune effector mechanisms, including antibody-dependent cellular cytotoxicity (ADCC).
* Chemical Linker: A synthetic bridge covalently tethering the antibody to the cytotoxic warhead. The linker maintains structural stability in systemic circulation to prevent premature toxic payload shedding while enabling efficient cleavage within the lysosomal environment of tumor cells.
* Cytotoxic Payload: An ultra-potent small-molecule agent exhibiting sub-nanomolar antiproliferative potency. The warhead and linker cassette dictate the therapeutic index and bystander permeability of the intact conjugate.
● Intracellular Processing Cascade
The canonical cytotoxic pathway follows a sequential biological cascade:
* The antibody domain binds to its target cell-surface antigen.
* The antigen-conjugate complex internalizes via receptor-mediated endocytosis.
* Vesicular trafficking routes the internalized complex into endolysosomes.
* Acidic proteases (such as cathepsin B) cleave the linker, or the entire antibody scaffold undergoes lysosomal degradation.
* The liberated payload exits the endolysosome, accessing intracellular targets to induce cell cycle arrest and apoptosis by inhibiting topoisomerase I or disrupting the microtubule cytoskeleton.
● Secondary Effector Pathways
Beyond direct target-cell lethality, modern ADCs deploy two critical secondary antitumor mechanisms:
* Bystander Killing Effect: Membrane-permeable, neutral payloads diffuse out of antigen-positive cancer cells and penetrate adjacent cells. This clears surrounding antigen-negative or low-expressing malignant clones, directly overcoming tumor antigen heterogeneity.
* Immunogenic Cell Death: Intracellular damage and subsequent tumor lysis induce the exposure of calreticulin and the release of damage-associated molecular patterns (DAMPs) alongside tumor neoantigens. This primes dendritic cells and promotes tumor-infiltrating lymphocyte activity, providing a biological rationale for combining ADCs with PD-1 and PD-L1 immune checkpoint inhibitors.
GENERATIONAL EVOLUTION AND MODALITY CLASSIFICATION
● First-Generation ADCs
* Representative Commercial Agents: Mylotarg (gemtuzumab ozogamicin) and Besponsa (inotuzumab ozogamicin).
* Molecular Design: Characterized by stochastic conjugation targeting native lysine residues or partially reduced interchain disulfides. Formulated with acid-labile hydrazone linkers and DNA-cleaving calicheamicin payloads.
* Structural Limitations: Pronounced structural heterogeneity with drug-to-antibody ratios (DAR) varying from 0 to 8. Hydrazone linkers proved unstable at physiologic pH, leading to premature systemic payload release, severe off-target toxicities (including sinusoidal obstruction syndrome / hepatic veno-occlusive disease), and narrow therapeutic windows.
● Second-Generation ADCs
* Representative Commercial Agents: Adcetris (brentuximab vedotin) and Kadcyla (trastuzumab emtansine).
* Molecular Design: Introduced stable chemical linkers, such as cathepsin-cleavable valine-citrulline dipeptides and non-cleavable thioether linkers (SMCC). Armed with potent microtubule inhibitors, notably monomethyl auristatin E (MMAE) and maytansinoids (DM1).
* Structural Limitations: Achieved improved clinical outcomes, but remained limited by stochastic DAR distributions averaging 3.5 to 4.0. Hydrophobic payloads served as substrates for P-glycoprotein (MDR1) efflux pumps, contributing to secondary drug resistance. Non-cleavable linkers also limited bystander activity in antigen-heterogeneous solid tumors.
● Third-Generation and Next-Generation Platforms
* Representative Commercial Agents: Enhertu (trastuzumab deruxtecan), Trodelvy (sacituzumab govitecan), Datroway (datopotamab deruxtecan), Padcev (enfortumab vedotin), Tivdak (tisotumab vedotin), Elahere (mirvetuximab soravtansine), and Emrelis (telisotuzumab vedotin).
* Structural Characteristics:
- Topoisomerase I Inhibitor Dominance: Over 75% to 95% of active clinical pipelines incorporate camptothecin derivatives (DXd, SN-38, exatecan, CPT113/CPT116, ZD06519). These payloads overcome tubulin-directed resistance, demonstrate high bystander permeability, and possess wide therapeutic windows.
- Homogeneous High DAR: Lower intrinsic payload hydrophobicity enables stable bioconjugation at DAR 6 to 8 without triggering protein aggregation or accelerated hepatic clearance.
- Advanced Bioconjugation: Site-specific bioconjugation technologies—such as carbon-bridge cysteine re-pairing, enzymatic transglutaminase or glycan conjugation, and unnatural amino acid incorporation—reduce circulating free toxin levels by 5- to 25-fold.
● Advanced Conjugate Modalities
* Bispecific and Biparatopic ADCs: Designed to cross-link two distinct tumor antigens (e.g., BL-B01D1 targeting EGFR and HER3) or two epitopes on the same target (e.g., JSKN003 targeting HER2 domains II and IV), enhancing receptor internalization and sparing normal cells that express single targets.
* Dual-Payload ADCs: Constructs loading complementary payloads (such as topoisomerase I and tubulin inhibitors) onto a single antibody backbone to prevent clonal tumor resistance.
* Degrader-Antibody Conjugates (DACs): Replacing classical toxins with targeted protein degraders (PROTACs) to degrade intracellular oncogenic drivers while reducing off-target cytotoxic side effects.
* Immune-Stimulating Antibody Conjugates (ISACs): Utilizing toll-like receptor (TLR7/8) or STING agonists to repolarize tumor-associated macrophages and stimulate long-term antitumor immunity.
* Antibody-Oligonucleotide Conjugates (AOCs): Coupling monoclonal antibodies with oligonucleotides (siRNA, PMO) to direct RNA-targeting therapeutics into extrahepatic tissues, such as skeletal muscle.
DOWNSTREAM CLINICAL SECTORS
● Solid Tumors
Solid tumors represent the primary revenue source for ADC platforms:
* Breast Cancer: Represents the largest commercial volume driver. Enhertu and Kadcyla serve as core standards in HER2-positive and HER2-low disease, while Gilead's Trodelvy is established in metastatic triple-negative breast cancer. Datroway is approved for HR-positive, HER2-negative metastatic breast cancer.
* Urothelial Carcinoma: Pfizer and Astellas' Padcev, in combination with pembrolizumab, serves as a frontline standard of care, replacing platinum chemotherapy. Pipeline programs such as Mabwell's 9MW2821 and Corbus/CSPC's CRB-701 are advancing through clinical development.
* Lung Cancers: AbbVie's Emrelis is approved in c-Met-overexpressing NSCLC, and Datroway is approved in pretreated EGFR-mutated NSCLC. In small cell lung cancer (SCLC), camptothecin-based candidates targeting DLL3 (ZL-1310, IDE849), B7-H3 (ifinatamab deruxtecan, HS-20093), and SEZ6 (HWK-206) are showing meaningful activity.
* Gastrointestinal Cancers: Enhertu is commercialized in advanced HER2-positive gastric and gastroesophageal junction (GEJ) cancer. The Claudin 18.2 space is competitive, led by Keymed/AstraZeneca's AZD0901, Innovent/Takeda's IBI343, and Hengrui's SHR-A1904.
* Gynecological Cancers: AbbVie's Elahere targets FR-alpha in platinum-resistant ovarian cancer, competing with late-stage Topo1 programs such as Genmab's Rina-S. Cervical cancer is addressed by Genmab and Pfizer's Tivdak.
* Head and Neck Cancers: Lepu Biopharma's Meiyouheng (MRG003) represents the first approved EGFR-directed ADC in China for relapsed or metastatic nasopharyngeal carcinoma.
● Hematologic Malignancies
Hematologic indications provided the clinical foundation for ADC development:
* Diffuse Large B-Cell Lymphoma (DLBCL): Roche's Polivy, combined with R-CHP, serves as a frontline standard of care. ADC Therapeutics' Zynlonta targets CD19 in later-line relapsed and refractory settings.
* Multiple Myeloma: GSK's Blenrep (BCMA-targeted) returned to commercial markets following clinical outcomes in the Phase III DREAMM-7 and DREAMM-8 trials. Heidelberg Pharma and Huadong Medicine are advancing the RNA polymerase II inhibitor HDP-101.
* Hodgkin Lymphoma: Pfizer and Takeda's Adcetris remains the frontline standard for CD30-expressing lymphoproliferative disorders.
* Acute Leukemias: Commercialized therapies include Pfizer's Mylotarg and Besponsa. Early clinical pipelines include Baili Tianheng's BL-M11D1 (anti-CD33) and Aptabio's nucleolin-targeted aptamer conjugate Apta-16.
● Non-Oncology Modalities
* Autoimmune and Inflammatory Disorders: Developers are testing cell-depleting and immunomodulatory ADCs outside of cancer. DualityBio is evaluating DB-2304 (anti-BDCA2) to suppress plasmacytoid dendritic cells in lupus, while Leads Biolabs is developing LBL-047. Zymeworks is evaluating ZW1528 in chronic obstructive pulmonary disease.
* Neuromuscular and Genetic Diseases: Avidity Biosciences is developing AOC candidates using anti-transferrin receptor (TfR1) antibodies to deliver therapeutic oligonucleotides to skeletal muscle, including Phase III trials for del-desiran (myotonic dystrophy type 1) and del-brax (facioscapulohumeral muscular dystrophy).
REGIONAL MARKET DYNAMICS
● North America
* Market Profile: The United States and Canada represent the largest commercial territory for ADCs, characterized by early clinical adoption, broad reimbursement access, and annual per-patient treatment costs frequently ranging between 150,000 and 300,000 USD.
* Competitive Dynamics: Dominated by commercial incumbents including Pfizer, Gilead Sciences, AbbVie, Genmab, Daiichi Sankyo, AstraZeneca, and ADC Therapeutics. Mid-stage clinical development is driven by Eli Lilly, Merck (MSD), Day One Biopharmaceuticals, Corbus, Immunome, and Whitehawk.
* Distribution Channels: Wholesaling is concentrated among three distributors—McKesson Corporation, Cencora, and Cardinal Health—which handle between 79% and 90% of US commercial oncology product movement. Products flow to hospital outpatient departments and oncology practices via specialty distribution units and Group Purchasing Organizations (GPOs). Physician-administered products are reimbursed primarily under Medicare Part B using Average Sales Price (ASP) methodologies.
● Asia-Pacific (APAC)
* China: Following domestic approvals of earlier-generation products, the Chinese market is expanding rapidly. Commercial innovators include RemeGen (Aidexi), Kelun-Biotech (Shoutailai), Lepu Biopharma (Meiyouheng), and Huadong Medicine (Elahere). The advanced clinical pipeline features Jiangsu Hengrui (SHR-A1811, SHR-A2102), Innovent Biologics (IBI343), Sichuan Baili Tianheng (BL-B01D1), DualityBio, Hansoh Pharma, Mabwell, and Alphamab. Distribution is governed by the statutory Two-Invoice System and provincial centralized procurement platforms. Universal hospital reimbursement requires inclusion in the National Reimbursement Drug List (NRDL) via pricing concessions typically averaging 50% to 70%, supplemented by Dual-Channel Direct-to-Patient (DTP) pharmacies and the Commercial Health Insurance Innovative Drug List (CHIIDL).
* Japan: A major originator hub driven by Daiichi Sankyo, Astellas Pharma, Takeda Pharmaceutical, and Eisai. Clinical uptake is supported by the universal National Health Insurance framework, with development accelerated by PMDA Sakigake designations.
* South Korea: An established bioconjugation technology cluster, home to Celltrion, IntoCell, Aimed Bio, ABL Bio, Chong Kun Dang, Aptabio, and Genome & Company, supported by large-scale domestic biomanufacturing from Samsung Biologics.
* India: A manufacturing base for oncology biosimilars, supported by developers such as Zydus Lifesciences, which has advanced a second biosimilar ADC candidate into Phase III registration trials alongside novel early-stage pipelines.
* Taiwan, China: Specializes in follow-on biosimilar development and novel multi-targeting conjugates. Formosa Pharmaceuticals is progressing TSY-110 (Kadcyla biosimilar) and TSY-310 (bispecific ADC), while PharmaEssentia is scaling internal linker-payload integration capabilities.
● Europe
* Market Profile: Represents the second-largest commercial regional market. Regulatory evaluation is centralized via the European Medicines Agency (EMA), followed by Member State pricing evaluations, statutory rebates, and hospital tenders. Germany, France, the UK, and Italy account for the largest volumes.
* Key Players: Anchored by regional multinational operations including Roche, AstraZeneca, GSK, BioNTech, Genmab, Sanofi, Merck KGaA, and Heidelberg Pharma.
* Regulatory Dynamics: Governed by the EU Health Technology Assessment Regulation (EU HTAR; Regulation 2021/2282). Enacted in January 2025, it mandates centralized Joint Clinical Assessments (JCAs) for all newly approved oncology therapies, standardizing comparative clinical evaluation across Member States.
● Latin America and the Middle East & Africa (MEA)
* Latin America: Brazil and Mexico lead regional uptake. Access is characterized by a dual-tier structure: private health insurers rapidly cover FDA/EMA-approved therapies, whereas public systems (such as Brazil's SUS) rely on strict cost-effectiveness reviews, centralized negotiations, and judicialized patient access claims.
* Middle East and Africa: Diverges sharply between Gulf Cooperation Council (GCC) economies (Saudi Arabia, UAE, Qatar) and sub-Saharan Africa. GCC nations offer fast registration pathways, subsidized national oncology coverage, and high healthcare spending. Broader African markets remain largely reliant on international health programs and tender purchases, creating demand for cost-effective ADC biosimilars.
REGULATORY AND REIMBURSEMENT ARCHITECTURE
● United States Frameworks
* FDA Expedited Programs: Commercial developers rely heavily on Accelerated Approval based on surrogate endpoints (such as overall response rate or progression-free survival).
* FDORA Mandates: Enacted under the Food and Drug Omnibus Reform Act of 2022, the FDA holds expanded statutory power over accelerated approvals. The agency can mandate that confirmatory Phase III post-marketing studies be enrolled and active prior to approval, requires regular progress reporting, and can use streamlined procedures to withdraw authorizations if clinical trials fail.
* Inflation Reduction Act (IRA):
- Medicare Drug Price Negotiation Program: Authorizes CMS to set a Maximum Fair Price (MFP) for single-source therapies that have been commercialized without generic or biosimilar competition for 11 years (for biologics). Following price revisions for Part D drugs taking effect in 2026, Part B physician-administered infused therapies (covering most oncology ADCs) become eligible for negotiation starting in 2028.
- Inflation Penalties: Penalizes biopharma companies that raise Medicare prices above the rate of general inflation, requiring statutory rebates to CMS and impacting gross-to-net realization.
- Part D Modernization: Enacted caps on annual patient out-of-pocket expenses, shifting financial responsibilities onto commercial drug plans and manufacturers.
● China Frameworks
* CDE Regulatory Optimization: The National Medical Products Administration (NMPA) maintains an expedited 30-working-day review procedure for priority clinical applications, supporting breakthrough designations and simultaneous global development programs.
* Centralized NRDL Integration: Managed by the National Healthcare Security Administration (NHSA). The NRDL enables coverage across public hospitals in exchange for substantial price concessions (50% to 70%).
* Commercial Health Insurance Catalog (CHIIDL): Launched in December 2025, this initiative covers high-cost innovative therapies with moderate discounts (15% to 50%), providing commercial reimbursement ahead of basic public insurance inclusion.
* Distribution and Procurement: The Two-Invoice System strictly limits distribution to two invoices between the biopharma manufacturer and the hospital. Public hospitals operate under zero-markup drug rules and manage spending using Diagnosis-Related Group (DRG) and Big Data Diagnosis-Intervention Packet (DIP) reimbursement frameworks.
● European Union Framework
* EU HTAR Execution: Standardizes Joint Clinical Assessments for new oncology biologics, completing 13 initial reviews in 2025 and projecting roughly 50 new clinical evaluations across 2026. Member States must incorporate JCA clinical reports into their national pricing decisions, impacting regional launch timing.
VALUE CHAIN AND INDUSTRIAL CDMO ARCHITECTURE
● Upstream Operations
* Monoclonal Antibody Engineering: Mammalian cell line engineering (primarily Chinese Hamster Ovary cells) and humanized antibody discovery. Platforms deploy Fc-engineering to optimize effector responses, alongside conditional masking (such as BioAtla's CAB or Adagene's SAFEbody) to restrict antibody binding to acidic tumor microenvironments.
* Highly Potent API (HPAPI) Synthesis: Synthesis of cytotoxic payloads (exatecans, MMAE, DM1, SN-38, amanitin). Production requires high-containment suites meeting Occupational Exposure Band (OEB) 5 or 6 standards, with airborne limits below 10 ng/m3.
* Linker and Bioconjugation Platforms: Synthesis of cleavable peptides, PEG spacers, and functional coupling chemistries. Proprietary bioconjugation technologies include IntoCell's OHPAS, Hangzhou DAC / Whitehawk's CPT113/CPT116 carbon-bridge platform, Sutro's cell-free XpressCF+, and Tot Biopharm's GL-DisacLink.
● Midstream Operations
* Bioprocessing: Fed-batch or perfusion mammalian bioreactor culture, followed by downstream Protein A affinity chromatography, viral inactivation, and polishing.
* Bioconjugation Reaction: Controlled interchain reduction or enzymatic linker activation, followed by stoichiometric coupling of the linker-payload in the presence of organic cosolvents (DMSO, DMA).
* Ultrafiltration and Fill-Finish: Tangential Flow Filtration (TFF) removes residual free drug and process cosolvents. Purified conjugates are filled into vials and lyophilized to preserve long-term product stability.
* Analytical and Quality Control Testing: Lot release relies on Hydrophobic Interaction Chromatography (HIC-HPLC) for DAR distribution, Size-Exclusion Chromatography (SEC-HPLC) for aggregation, Capillary Electrophoresis (CE-SDS) for purity, and LC-MS for peptide mapping.
● CDMO Ecosystem
* Outsourcing Penetration: Due to high facility costs and the dual demands of chemical containment and biological cleanrooms, biopharmaceutical companies outsource more than 70% of ADC manufacturing, compared to 30% to 40% for conventional therapeutics.
* Contract Providers: Major contract partners include WuXi XDC, Tot Biopharm, Lonza, Samsung Biologics, and Formosa Laboratories. The industry continues to transition toward single-campus, integrated facilities where antibody generation, toxin synthesis, conjugation, and sterile fill-finish take place within one site, reducing transportation and supply-chain risks.
● Downstream Operations
* Cold-Chain Logistics: Bioconjugates require temperature-controlled cold-chain shipping (2 to 8 degrees Celsius, or frozen states) to prevent protein denaturation or chemical linker breakdown.
* Regulatory Traceability: Compliance with the US Drug Supply Chain Security Act (DSCSA) and China Good Supply Practice (GSP) requirements mandates end-to-end electronic unit serialization across the supply chain.
COMPETITIVE DOSSIER: COMMERCIAL PRODUCTS
● Enhertu (Trastuzumab Deruxtecan)
● Kadcyla (Trastuzumab Emtansine)
● Padcev (Enfortumab Vedotin)
● Polivy (Polatuzumab Vedotin)
● Trodelvy (Sacituzumab Govitecan)
● Adcetris (Brentuximab Vedotin)
● Datroway (Datopotamab Deruxtecan)
● Elahere (Mirvetuximab Soravtansine)
● Emrelis (Telisotuzumab Vedotin)
● Tivdak (Tisotumab Vedotin)
● Zynlonta (Loncastuximab Tesirine)
● Blenrep (Belantamab Mafodotin)
● Besponsa (Inotuzumab Ozogamicin) and Mylotarg (Gemtuzumab Ozogamicin)
● Aidexi (Disitamab Vedotin / RC48)
● Shoutailai (Boduotrastuzumab / A166)
● Meiyouheng (MRG003)
● Decnupaz (Pivekimab Sunirine)
● Yizekang (Izalontamab Brengitecan / BL-B01D1)
CLINICAL PIPELINE ARCHITECTURE
● Phase IV Post-Marketing Confirmatory Trials
* LOTIS-5 (ADC Therapeutics)
* ASCENT-04 (Gilead Sciences)
* DESTINY-Breast06 & 09 (Daiichi Sankyo / AstraZeneca)
* EV-302 / KEYNOTE-A39 (Pfizer / Astellas)
* innovaTV 301 (Genmab / Pfizer / Zai Lab)
* Emrelis Confirmatory Trial (AbbVie)
* Meiyouheng Registry (Lepu Biopharma)
* Aidexi Line Expansion (RemeGen)
● Phase III Registrational Pipeline
* SHR-A1811 (Jiangsu Hengrui)
* Sacituzumab Tirumotecan / SKB264 / MK-2870 (Kelun-Biotech / MSD)
* BL-B01D1 (Sichuan Baili Tianheng / BMS)
* IBI343 (Innovent / Takeda)
* IBI354 (Innovent Biologics)
* DB-1303 / BNT323 (DualityBio / BioNTech)
* CMG901 / AZD0901 (Keymed / Lepu / AstraZeneca)
* Patritumab Deruxtecan / HER3-DXd (Daiichi Sankyo / MSD)
* Ifinatamab Deruxtecan / I-DXd (Daiichi Sankyo / MSD)
* Raludotatug Deruxtecan / R-DXd (Daiichi Sankyo / MSD)
* Rinatabart Sesutecan / Rina-S (Genmab / ProfoundBio)
* Risvutatug Rezetecan / HS-20093 (Hansoh Pharma / GSK)
* Mocertatug Rezetecan / HS-20089 (Hansoh Pharma / GSK)
* 9MW2821 (Mabwell Bioscience)
* JSKN003 (Alphamab Oncology)
* FDA018 (Shanghai Fudan-Zhangjiang)
* SHR-A2102, SHR-A1904, SHR-A2009, SHR-A1912 (Jiangsu Hengrui)
* Zilovertamab Vedotin (MSD)
* Sigvotatug Vedotin (Pfizer)
* MRG004A (Lepu Biopharma)
* BL-M05D1 (Sichuan Baili Tianheng)
* Zydus Biosimilar ADC (Zydus Lifesciences)
* Del-desiran & Del-brax (Avidity Biosciences)
● Phase II Clinical Pipeline
* ZL-1310 (Zai Lab)
* SHR-4849 / IDE849 (Hengrui / IDEAYA)
* SHR-1826 (Hengrui)
* ATG-022 (Antengene)
* LCB84 (Johnson & Johnson / LegoChem)
* DB-1311 & DB-1305 (BioNTech / DualityBio)
* YL202 / BNT326 (BioNTech / MediLink)
* BA3011 & BA3021 (BioAtla)
* AZD5335 (AstraZeneca)
* MRG001 & MRG006A (Lepu Biopharma)
* BL-M11D1 (Sichuan Baili Tianheng)
* XNW27011 (Astellas / Evopoint)
* CRB-701 (Corbus / CSPC)
* TSY-110 (Formosa Pharmaceuticals / EirGenix / Formosa Labs)
* Del-zota (Avidity Biosciences)
● Phase I and Exploratory Conjugates
* YL201 (Roche / MediLink) and IBI3009 (Roche / Innovent)
* PF-08046876 and HBM9033 (Pfizer / Harbour BioMed)
* CS5001 (CStone / LegoChem) and IM-1021 (Immunome)
* ZW191 and ZW251 (Zymeworks)
* STRO-004 (Sutro Biopharma)
* MRG007 (ArriVent / Lepu) and HWK-007 (Whitehawk)
* IDE034 (IDEAYA / Biocytogen)
* MGC026 & MGC028 (MacroGenics)
* SIM0505 and LNCB74 (NextCure / Simcere / LigaChem)
* HDP-101 and TAK-ATAC (Heidelberg Pharma / Huadong / Takeda)
* CT-P70, CT-P71, CT-P73 (Celltrion)
* ITC-6146RO (IntoCell)
* AMB302 & AMB303 (Aimed Bio / Samsung Biologics):
* Chong Kun Dang c-Met ADC
* KM501 (Xuanzhu Biopharm)
* Precemtabart Tocentecan / M9140 (Merck KGaA) and SAR445953 (Sanofi)
* LY4170156, LY4175408, LY4052031, LY4101174 (Eli Lilly)
* BG-C0902 (BeOne Medicines)
* AK146D1 (Akeso)
* BDC-4182 (Bolt Biotherapeutics)
* SJP1604 / Apta-16 (Aptabio / Samjin)
CROSS-BORDER LICENSING DYNAMICS
Chinese biopharma developers have emerged as primary sources for late-stage pipeline in-licensing by Western multinational corporations:
* Sichuan Baili Tianheng and Bristol Myers Squibb: Partnered on the bispecific ADC BL-B01D1 (EGFRxHER3) in a transaction with 800 million USD upfront and potential milestones up to 8.4 billion USD.
* Kelun-Biotech and Merck (MSD): Strategic alliance covering sacituzumab tirumotecan (SKB264 / MK-2870; TROP2), SKB315 (CLDN18.2), and SKB535, with total deal terms exceeding 9.5 billion USD.
* Innovent Biologics and Takeda / Roche: Out-licensed ex-Greater China rights for IBI343 (CLDN18.2) and an option for IBI3001 (B7-H3/EGFR) to Takeda in a deal totaling 1.2 billion USD in upfront and equity investments; out-licensed IBI3009 (DLL3) to Roche.
* Hansoh Pharma and GSK: Out-licensed global ex-China rights for risvutatug rezetecan (HS-20093; B7-H3) and mocertatug rezetecan (HS-20089; B7-H4) in licensing packages valued up to 1.7 billion USD and 1.5 billion USD, respectively.
* DualityBio and BioNTech / GSK / BeiGene: Out-licensed DB-1303, DB-1311, and DB-1305 to BioNTech; partnered DB-1324 (CDH17) with GSK; and out-licensed DB-1312 (B7-H4) to BeiGene.
* Lepu Biopharma / Keymed and AstraZeneca / ArriVent: Out-licensed CMG901 (CLDN18.2) to AstraZeneca for 63 million USD upfront and up to 1.1 billion USD in milestones; partnered MRG007 (CDH17) with ArriVent in a 1.2 billion USD deal.
* Jiangsu Hengrui and IDEAYA Biosciences: Out-licensed global rights ex-Greater China for the DLL3 Topo1 ADC SHR-4849 (IDE849) for clinical development in neuroendocrine and small cell lung cancers.
GROWTH CATALYSTS AND SYSTEMIC CHALLENGES
● Commercial Catalysts
* Frontline Displacement: Transitioning from later-line salvage therapies to frontline settings (e.g., Padcev plus pembrolizumab displacing platinum chemotherapies in bladder cancer) increases per-patient treatment duration and market penetration.
* Bystander Permeability and Pan-Tumor Activity: Low-hydrophobicity Topo1 payloads diffuse across adjacent tumor tissue, enabling activity in heterogeneous tumors (e.g., HER2-low and HER2-ultralow breast cancer) and securing tumor-agnostic indications.
* Bispecific Architecture: Multi-targeting constructs (such as BL-B01D1 and JSKN003) increase receptor internalizing rates, lower off-target normal tissue binding, and help bypass target-loss resistance mechanisms.
* Immuno-Oncology Combinations: Payloads that trigger immunogenic cell death convert immunologically cold tumors into inflamed environments, creating biological synergies with PD-1 and PD-L1 inhibitors.
* Modality Broadening: Expanding beyond cytotoxic chemotherapy into antibody-oligonucleotide conjugates for muscular dystrophies (Avidity Biosciences) and targeted immunosuppressive conjugates for autoimmune conditions (DualityBio, Leads Biolabs) expands total addressable patient populations.
* Biosimilar Market Entry: As earlier blockbuster products reach patent expiration, the biosimilar ADC sector is projected to expand significantly by 2030, led by developers such as Zydus Lifesciences and Formosa Pharmaceuticals.
● Operational and Clinical Bottlenecks
* Class-Specific Toxicities:
- Interstitial Lung Disease (ILD) / Pneumonitis: Camptothecin and DXd derivatives carry risks of non-specific uptake by alveolar macrophages, which can trigger pulmonary inflammation. Safety events led the FDA to place a partial clinical hold on the Phase III IDeate-Lung02 trial for ifinatamab deruxtecan.
- Tubulin-Driven Adverse Events: Auristatin and maytansinoid payloads frequently cause dose-limiting peripheral neuropathy, neutropenia, and ocular microcystic keratopathy, requiring routine clinical monitoring.
* Acquired Tumor Resistance: In frontline bladder cancer regimens, roughly 50% of patients experience disease progression within 12 months. Resistance mechanisms include target antigen shedding, mutations in endocytosis machinery, altered lysosomal cleavage, and the upregulation of P-glycoprotein (MDR1) efflux pumps.
* High CMC Manufacturing Barriers:
- Containment Controls: Handling cytotoxic payloads with sub-nanomolar activity requires OEB 5 or 6 isolator suites, where exposure limits fall below 10 ng/m3.
- Complex Synthesis: Manufacturing requires linking three distinct sub-components: mammalian antibody expression, organic payload-linker synthesis, and sterile bioconjugation with ultrafiltration.
- Characterization Requirements: Analytics require rigorous testing to confirm stable DAR distributions (HIC-HPLC), monitor protein aggregation (SEC-HPLC), and map peptide structures (LC-MS).
* Payer and Pricing Pressures: In the United States, upcoming Medicare Part B price negotiations under the Inflation Reduction Act alongside mandatory inflation rebates will compress net realized pricing. In China, hospital access remains contingent on steep discounts during annual NRDL rounds alongside internal public hospital DRG/DIP cost controls.
PATENT CLIFF DYNAMICS AND EXCLUSIVITY RUNWAYS
● Immediate Expiration Window (2025 to 2028)
* Kadcyla (Roche): Primary compound patents have expired in Europe and face expiration in the United States between 2024 and 2026. The 12-year US regulatory exclusivity period expired in February 2025, clearing regulatory pathways for biosimilar developers in India, China, and Taiwan, China.
* Adcetris (Pfizer / Takeda): Basic US patents expire in 2026, with European protections and supplementary protection certificates concluding between 2026 and 2028, opening the franchise to follow-on biosimilars.
* Trodelvy (Gilead Sciences): The composition-of-matter patent expires in the United States in 2028 and in Europe in 2029. While US regulatory data exclusivity continues through April 2032, the product faces commercial competition from next-generation TROP2 ADCs, including Datroway and sacituzumab tirumotecan.
● Intermediate Expiration Window (2029 to 2033)
* Polivy (Roche): Composition patents in the US and Europe expire between 2029 and 2033, with US data exclusivity concluding in June 2031.
* Padcev (Pfizer / Astellas): Major US and European product patents extend through 2033, backed by US reference product exclusivity through December 2031.
* Zynlonta (ADC Therapeutics): Utility patents extend through 2033 to 2042, with US reference exclusivity ending in April 2033.
* Enhertu (Daiichi Sankyo / AstraZeneca): US reference product exclusivity ends in December 2031, but linker-payload, composition, and manufacturing patents provide protection through 2033 to 2036.
● Long-Range Expiration Horizon (2034 to 2046+)
* Datroway (Daiichi Sankyo / AstraZeneca): Platform and derivative patents extend through 2039 to 2044, with US reference data exclusivity extending to January 2037.
* Emrelis (AbbVie): Approved in May 2025, Emrelis holds US reference data protection through May 2037, with platform patents continuing through 2037 to 2040.
* Next-Generation Innovation Platforms: Newly commercialized and late-stage clinical programs—such as Sichuan Baili Tianheng's BL-B01D1, Jiangsu Hengrui's SHR-A1811, Innovent's IBI343, DualityBio's DB-1303, and Whitehawk's HWK-007—carry patent portfolios protecting antibody sequences, linkers, and conjugations extending through 2040 to 2046, establishing sustained competitive differentiation for the next wave of targeted biopharmaceuticals.
1.1 Executive Summary and 2026 ADC Industry Baseline 1
1.2 Scope, Taxonomy, and Structural Matrix of Antibody-Drug Conjugates 2
1.3 Research Methodology and Econometric Forecasting Model 3
1.4 Primary and Secondary Data Sourcing Matrix 4
1.5 Critical Forecasting Assumptions and Quantitative Parameters 5
1.6 List of Industry Abbreviations and Standardized Terminology 6
Chapter 2 Global Antibody-Drug Conjugates Market Landscape and Trajectory (2021-2031)
2.1 Global Market Valuation and Volume Trajectory (2021-2031) 7
2.2 Primary Industry Drivers, Technological Accelerators, and Commercial Restraints 9
2.3 Market Concentration Index and Industry Competitive Structure 11
2.4 Global Regulatory Approvals, Expedited Review Frameworks, and HTA Decisions 13
Chapter 3 Global ADC Value Chain, Bioconjugation Ecosystem, and CDMO Dynamics
3.1 Upstream Value Chain: Monoclonal Antibodies, Linker Chemistry, and Cytotoxic Payloads 15
3.2 Midstream Bioconjugation Platforms, Site-Specific Engineering, and Formulation 17
3.3 Downstream Sterile Fill-Finish, Cold-Chain Distribution, and Release Testing 19
3.4 Specialized Biologics CDMO/CMO Capacity Utilization and Outsourcing Trends 21
Chapter 4 Global ADC Market Breakdown by Generational Evolution
4.1 First-Generation ADCs: Non-Specific Chemical Conjugation and Market Performance 24
4.2 Second-Generation ADCs: Enhanced Linker Stability and Validated Targets 26
4.3 Third-Generation and Next-Generation ADCs: Site-Specific Conjugation and Bispecific Modalities 28
Chapter 5 Global ADC Market Breakdown by Therapeutic Application
5.1 Solid Tumors: Breast, Non-Small Cell Lung, Gastric, Bladder, and Gynecological Cancers 32
5.2 Hematologic Malignancies: Multiple Myeloma, Hodgkin and Non-Hodgkin Lymphomas, Leukemias 35
5.3 Emerging Non-Oncology Indications: Autoimmune, Fibrotic, and Infectious Pathologies 37
Chapter 6 Global Cross-Border Licensing, Trade Corridors, and Regulatory Architecture
6.1 Out-Licensing Transactions, Cross-Border Asset Transfers, and Upfront/Royalty Structures 40
6.2 Global Supply Chain Trade Corridors, Payload Intermediate Shipping, and Import Tariffs 42
6.3 International Regulatory Convergence, Quality Audits, and Biosimilar ADC Approvals 44
6.4 Intellectual Property Cliffs, Freedom-to-Operate Analysis, and Patent Litigation Dynamics 46
Chapter 7 North America ADC Market Development and Commercial Infrastructure
7.1 United States: Clinical Trial Clustering, Commercial Reimbursement, and Domestic CDMO Scale 48
7.2 Canada: Formulary Reviews, Federal Drug Pricing Schemes, and Academic Pipeline Growth 52
Chapter 8 Europe ADC Regional Ecosystem and Commercial Trajectory
8.1 Germany: Central European Biomanufacturing and Statutory Health Insurance Reimbursement 55
8.2 Switzerland: Global Corporate Headquarters, Bioconjugation Innovations, and Payload Synthesis 57
8.3 United Kingdom: Clinical Translation Centers, MHRA Approvals, and NICE Value Appraisals 59
8.4 Rest of Europe: France, Italy, Spain, and Nordic Clinical Uptake 61
Chapter 9 Asia-Pacific and Rest of World ADC Market Expansion
9.1 China: Domestic Licensing Powerhouses, IND Volume, and National Reimbursement Inclusion 64
9.2 Japan: Advanced Payload Chemistry, PMDA Accelerated Approvals, and Out-Licensing Volume 67
9.3 South Korea: Platform Biotech Commercialization and Contract Development Ecosystem 69
9.4 India: Process Engineering, Biomanufacturing Infrastructure, and Value-Tier Penetration 71
9.5 Taiwan (China): Targeted Conjugate Research, Formulation Science, and Clinical Trial Hubs 72
9.6 Latin America, Middle East, and Africa: Specialty Healthcare Access and Market Potential 73
Chapter 10 Corporate Intelligence: Commercialized ADC Market Leaders
10.1 F. Hoffmann-La Roche Ltd 74
10.1.1 Corporate Profile and Oncology Strategic Positioning 74
10.1.2 SWOT Matrix 75
10.1.3 Commercial ADC Financial Performance and Operational Metrics 76
10.1.4 Manufacturing Scale, R&D Allocations, and Lifecycle Expansion 77
10.2 AbbVie Inc. 78
10.2.1 Corporate Profile and Oncology Strategic Positioning 78
10.2.2 SWOT Matrix 79
10.2.3 Commercial ADC Financial Performance and Operational Metrics 80
10.2.4 Manufacturing Scale, R&D Allocations, and Lifecycle Expansion 81
10.3 Daiichi Sankyo Company, Limited 82
10.3.1 Corporate Profile and Oncology Strategic Positioning 82
10.3.2 SWOT Matrix 83
10.3.3 Commercial ADC Financial Performance and Operational Metrics 84
10.3.4 Manufacturing Scale, R&D Allocations, and Lifecycle Expansion 85
10.4 Pfizer Inc. 86
10.4.1 Corporate Profile and Oncology Strategic Positioning 86
10.4.2 SWOT Matrix 87
10.4.3 Commercial ADC Financial Performance and Operational Metrics 88
10.4.4 Manufacturing Scale, R&D Allocations, and Lifecycle Expansion 89
10.5 Astellas Pharma Inc. 90
10.5.1 Corporate Profile and Oncology Strategic Positioning 90
10.5.2 SWOT Matrix 91
10.5.3 Commercial ADC Financial Performance and Operational Metrics 92
10.5.4 Manufacturing Scale, R&D Allocations, and Lifecycle Expansion 93
10.6 Gilead Sciences, Inc. 94
10.6.1 Corporate Profile and Oncology Strategic Positioning 94
10.6.2 SWOT Matrix 95
10.6.3 Commercial ADC Financial Performance and Operational Metrics 96
10.6.4 Manufacturing Scale, R&D Allocations, and Lifecycle Expansion 97
10.7 AstraZeneca PLC 98
10.7.1 Corporate Profile and Oncology Strategic Positioning 98
10.7.2 SWOT Matrix 99
10.7.3 Commercial ADC Financial Performance and Operational Metrics 100
10.7.4 Manufacturing Scale, R&D Allocations, and Lifecycle Expansion 101
10.8 Eisai Co., Ltd. 102
10.8.1 Corporate Profile and Oncology Strategic Positioning 102
10.8.2 SWOT Matrix 103
10.8.3 Commercial ADC Financial Performance and Operational Metrics 104
10.8.4 Manufacturing Scale, R&D Allocations, and Lifecycle Expansion 105
10.9 ADC Therapeutics SA 106
10.9.1 Corporate Profile and Oncology Strategic Positioning 106
10.9.2 SWOT Matrix 107
10.9.3 Commercial ADC Financial Performance and Operational Metrics 108
10.9.4 Manufacturing Scale, R&D Allocations, and Lifecycle Expansion 109
10.10 Genmab A/S 110
10.10.1 Corporate Profile and Oncology Strategic Positioning 110
10.10.2 SWOT Matrix 111
10.10.3 Commercial ADC Financial Performance and Operational Metrics 112
10.10.4 Manufacturing Scale, R&D Allocations, and Lifecycle Expansion 113
10.11 GlaxoSmithKline plc 114
10.11.1 Corporate Profile and Oncology Strategic Positioning 114
10.11.2 SWOT Matrix 115
10.11.3 Commercial ADC Financial Performance and Operational Metrics 116
10.11.4 Manufacturing Scale, R&D Allocations, and Lifecycle Expansion 117
10.12 Takeda Pharmaceutical Company Limited 118
10.12.1 Corporate Profile and Oncology Strategic Positioning 118
10.12.2 SWOT Matrix 119
10.12.3 Commercial ADC Financial Performance and Operational Metrics 120
10.12.4 Manufacturing Scale, R&D Allocations, and Lifecycle Expansion 121
10.13 Sichuan Kelun-Biotech Biopharmaceutical Co., Ltd. 122
10.13.1 Corporate Profile and Oncology Strategic Positioning 122
10.13.2 SWOT Matrix 123
10.13.3 Commercial ADC Financial Performance and Operational Metrics 124
10.13.4 Manufacturing Scale, R&D Allocations, and Lifecycle Expansion 125
10.14 RemeGen Co., Ltd. 126
10.14.1 Corporate Profile and Oncology Strategic Positioning 126
10.14.2 SWOT Matrix 127
10.14.3 Commercial ADC Financial Performance and Operational Metrics 128
10.14.4 Manufacturing Scale, R&D Allocations, and Lifecycle Expansion 129
10.15 Jiangsu Hengrui Pharmaceuticals Co., Ltd. 130
10.15.1 Corporate Profile and Oncology Strategic Positioning 130
10.15.2 SWOT Matrix 131
10.15.3 Commercial ADC Financial Performance and Operational Metrics 132
10.15.4 Manufacturing Scale, R&D Allocations, and Lifecycle Expansion 133
10.16 Zydus Lifesciences Limited 134
10.16.1 Corporate Profile and Oncology Strategic Positioning 134
10.16.2 SWOT Matrix 135
10.16.3 Commercial ADC Financial Performance and Operational Metrics 136
10.16.4 Manufacturing Scale, R&D Allocations, and Lifecycle Expansion 137
10.17 Lepu Biopharma Co., Ltd. 138
10.17.1 Corporate Profile and Oncology Strategic Positioning 138
10.17.2 SWOT Matrix 139
10.17.3 Commercial ADC Financial Performance and Operational Metrics 140
10.17.4 Manufacturing Scale, R&D Allocations, and Lifecycle Expansion 141
10.18 Huadong Medicine Co., Ltd. 142
10.18.1 Corporate Profile and Oncology Strategic Positioning 142
10.18.2 SWOT Matrix 143
10.18.3 Commercial ADC Financial Performance and Operational Metrics 144
10.18.4 Manufacturing Scale, R&D Allocations, and Lifecycle Expansion 145
10.19 Sichuan Baili Tianheng Pharmaceutical Co., Ltd. 146
10.19.1 Corporate Profile and Oncology Strategic Positioning 146
10.19.2 SWOT Matrix 147
10.19.3 Commercial ADC Financial Performance and Operational Metrics 148
10.19.4 Manufacturing Scale, R&D Allocations, and Lifecycle Expansion 149
Chapter 11 Corporate Intelligence: Clinical Pipeline and Emerging Biopharma Innovators
11.1 Eli Lilly and Company 150
11.1.1 Corporate Profile and Clinical Pipeline Architecture 150
11.1.2 SWOT Matrix and ADC R&D Strategy 151
11.1.3 Pipeline ADC Financial Estimates and Project Valuation Metrics 152
11.2 Johnson & Johnson 153
11.2.1 Corporate Profile and Clinical Pipeline Architecture 153
11.2.2 SWOT Matrix and ADC R&D Strategy 154
11.2.3 Pipeline ADC Financial Estimates and Project Valuation Metrics 155
11.3 Sanofi S.A. 156
11.3.1 Corporate Profile and Clinical Pipeline Architecture 156
11.3.2 SWOT Matrix and ADC R&D Strategy 157
11.3.3 Pipeline ADC Financial Estimates and Project Valuation Metrics 158
11.4 Merck & Co., Inc. (MSD) 159
11.4.1 Corporate Profile and Clinical Pipeline Architecture 159
11.4.2 SWOT Matrix and ADC R&D Strategy 160
11.4.3 Pipeline ADC Financial Estimates and Project Valuation Metrics 161
11.5 Merck KGaA 162
11.5.1 Corporate Profile and Clinical Pipeline Architecture 162
11.5.2 SWOT Matrix and ADC R&D Strategy 163
11.5.3 Pipeline ADC Financial Estimates and Project Valuation Metrics 164
11.6 ABL Bio Inc. 165
11.6.1 Corporate Profile and Clinical Pipeline Architecture 165
11.6.2 SWOT Matrix and ADC R&D Strategy 166
11.6.3 Pipeline ADC Financial Estimates and Project Valuation Metrics 167
11.7 Actinium Pharmaceuticals, Inc. 168
11.7.1 Corporate Profile and Clinical Pipeline Architecture 168
11.7.2 SWOT Matrix and ADC R&D Strategy 169
11.7.3 Pipeline ADC Financial Estimates and Project Valuation Metrics 170
11.8 Adagene Inc. 171
11.8.1 Corporate Profile and Clinical Pipeline Architecture 171
11.8.2 SWOT Matrix and ADC R&D Strategy 172
11.8.3 Pipeline ADC Financial Estimates and Project Valuation Metrics 173
11.9 Aimed Bio Inc. 174
11.9.1 Corporate Profile and Clinical Pipeline Architecture 174
11.9.2 SWOT Matrix and ADC R&D Strategy 175
11.9.3 Pipeline ADC Financial Estimates and Project Valuation Metrics 176
11.10 Akari Therapeutics Plc 177
11.10.1 Corporate Profile and Clinical Pipeline Architecture 177
11.10.2 SWOT Matrix and ADC R&D Strategy 178
11.10.3 Pipeline ADC Financial Estimates and Project Valuation Metrics 179
11.11 ALX Oncology Holdings Inc. 180
11.11.1 Corporate Profile and Clinical Pipeline Architecture 180
11.11.2 SWOT Matrix and ADC R&D Strategy 181
11.11.3 Pipeline ADC Financial Estimates and Project Valuation Metrics 182
11.12 Aptabio Therapeutics Inc. 183
11.12.1 Corporate Profile and Clinical Pipeline Architecture 183
11.12.2 SWOT Matrix and ADC R&D Strategy 184
11.12.3 Pipeline ADC Financial Estimates and Project Valuation Metrics 185
11.13 ArriVent Biopharma, Inc. 186
11.13.1 Corporate Profile and Clinical Pipeline Architecture 186
11.13.2 SWOT Matrix and ADC R&D Strategy 187
11.13.3 Pipeline ADC Financial Estimates and Project Valuation Metrics 188
11.14 Avidity Biosciences, Inc. 189
11.14.1 Corporate Profile and Clinical Pipeline Architecture 189
11.14.2 SWOT Matrix and ADC R&D Strategy 190
11.14.3 Pipeline ADC Financial Estimates and Project Valuation Metrics 191
11.15 BeOne Medicines Ltd. 192
11.15.1 Corporate Profile and Clinical Pipeline Architecture 192
11.15.2 SWOT Matrix and ADC R&D Strategy 193
11.15.3 Pipeline ADC Financial Estimates and Project Valuation Metrics 194
11.16 BioAtla, Inc. 195
11.16.1 Corporate Profile and Clinical Pipeline Architecture 195
11.16.2 SWOT Matrix and ADC R&D Strategy 196
11.16.3 Pipeline ADC Financial Estimates and Project Valuation Metrics 197
11.17 BioNTech SE 198
11.17.1 Corporate Profile and Clinical Pipeline Architecture 198
11.17.2 SWOT Matrix and ADC R&D Strategy 199
11.17.3 Pipeline ADC Financial Estimates and Project Valuation Metrics 200
11.18 Bolt Biotherapeutics, Inc. 201
11.18.1 Corporate Profile and Clinical Pipeline Architecture 201
11.18.2 SWOT Matrix and ADC R&D Strategy 202
11.18.3 Pipeline ADC Financial Estimates and Project Valuation Metrics 203
11.19 Celltrion Inc. 204
11.19.1 Corporate Profile and Clinical Pipeline Architecture 204
11.19.2 SWOT Matrix and ADC R&D Strategy 205
11.19.3 Pipeline ADC Financial Estimates and Project Valuation Metrics 206
11.20 Corbus Pharmaceuticals Holdings, Inc. 207
11.20.1 Corporate Profile and Clinical Pipeline Architecture 207
11.20.2 SWOT Matrix and ADC R&D Strategy 208
11.20.3 Pipeline ADC Financial Estimates and Project Valuation Metrics 209
11.21 Day One Biopharmaceuticals, Inc. 210
11.21.1 Corporate Profile and Clinical Pipeline Architecture 210
11.21.2 SWOT Matrix and ADC R&D Strategy 211
11.21.3 Pipeline ADC Financial Estimates and Project Valuation Metrics 212
11.22 Genome & Company 213
11.22.1 Corporate Profile and Clinical Pipeline Architecture 213
11.22.2 SWOT Matrix and ADC R&D Strategy 214
11.22.3 Pipeline ADC Financial Estimates and Project Valuation Metrics 215
11.23 Heidelberg Pharma AG 216
11.23.1 Corporate Profile and Clinical Pipeline Architecture 216
11.23.2 SWOT Matrix and ADC R&D Strategy 217
11.23.3 Pipeline ADC Financial Estimates and Project Valuation Metrics 218
11.24 IDEAYA Biosciences, Inc. 219
11.24.1 Corporate Profile and Clinical Pipeline Architecture 219
11.24.2 SWOT Matrix and ADC R&D Strategy 220
11.24.3 Pipeline ADC Financial Estimates and Project Valuation Metrics 221
11.25 IMBiologics Corp. 222
11.25.1 Corporate Profile and Clinical Pipeline Architecture 222
11.25.2 SWOT Matrix and ADC R&D Strategy 223
11.25.3 Pipeline ADC Financial Estimates and Project Valuation Metrics 224
11.26 Immunome, Inc. 225
11.26.1 Corporate Profile and Clinical Pipeline Architecture 225
11.26.2 SWOT Matrix and ADC R&D Strategy 226
11.26.3 Pipeline ADC Financial Estimates and Project Valuation Metrics 227
11.27 IntoCell Inc. 228
11.27.1 Corporate Profile and Clinical Pipeline Architecture 228
11.27.2 SWOT Matrix and ADC R&D Strategy 229
11.27.3 Pipeline ADC Financial Estimates and Project Valuation Metrics 230
11.28 MacroGenics, Inc. 231
11.28.1 Corporate Profile and Clinical Pipeline Architecture 231
11.28.2 SWOT Matrix and ADC R&D Strategy 232
11.28.3 Pipeline ADC Financial Estimates and Project Valuation Metrics 233
11.29 NextCure, Inc. 234
11.29.1 Corporate Profile and Clinical Pipeline Architecture 234
11.29.2 SWOT Matrix and ADC R&D Strategy 235
11.29.3 Pipeline ADC Financial Estimates and Project Valuation Metrics 236
11.30 Perspective Therapeutics, Inc. 237
11.30.1 Corporate Profile and Clinical Pipeline Architecture 237
11.30.2 SWOT Matrix and ADC R&D Strategy 238
11.30.3 Pipeline ADC Financial Estimates and Project Valuation Metrics 239
11.31 Qurient Co., Ltd. 240
11.31.1 Corporate Profile and Clinical Pipeline Architecture 240
11.31.2 SWOT Matrix and ADC R&D Strategy 241
11.31.3 Pipeline ADC Financial Estimates and Project Valuation Metrics 242
11.32 Sutro Biopharma, Inc. 243
11.32.1 Corporate Profile and Clinical Pipeline Architecture 243
11.32.2 SWOT Matrix and ADC R&D Strategy 244
11.32.3 Pipeline ADC Financial Estimates and Project Valuation Metrics 245
11.33 VERAXA Biotech Holding 246
11.33.1 Corporate Profile and Clinical Pipeline Architecture 246
11.33.2 SWOT Matrix and ADC R&D Strategy 247
11.33.3 Pipeline ADC Financial Estimates and Project Valuation Metrics 248
11.34 Whitehawk Therapeutics, Inc. 249
11.34.1 Corporate Profile and Clinical Pipeline Architecture 249
11.34.2 SWOT Matrix and ADC R&D Strategy 250
11.34.3 Pipeline ADC Financial Estimates and Project Valuation Metrics 251
11.35 Zymeworks Inc. 252
11.35.1 Corporate Profile and Clinical Pipeline Architecture 252
11.35.2 SWOT Matrix and ADC R&D Strategy 253
11.35.3 Pipeline ADC Financial Estimates and Project Valuation Metrics 254
11.36 Innovent Biologics, Inc. 255
11.36.1 Corporate Profile and Clinical Pipeline Architecture 255
11.36.2 SWOT Matrix and ADC R&D Strategy 256
11.36.3 Pipeline ADC Financial Estimates and Project Valuation Metrics 257
11.37 Zai Lab Limited 258
11.37.1 Corporate Profile and Clinical Pipeline Architecture 258
11.37.2 SWOT Matrix and ADC R&D Strategy 259
11.37.3 Pipeline ADC Financial Estimates and Project Valuation Metrics 260
11.38 Transcenta Holding Limited 261
11.38.1 Corporate Profile and Clinical Pipeline Architecture 261
11.38.2 SWOT Matrix and ADC R&D Strategy 262
11.38.3 Pipeline ADC Financial Estimates and Project Valuation Metrics 263
11.39 Jacobio Pharmaceuticals Group Co., Ltd. 264
11.39.1 Corporate Profile and Clinical Pipeline Architecture 264
11.39.2 SWOT Matrix and ADC R&D Strategy 265
11.39.3 Pipeline ADC Financial Estimates and Project Valuation Metrics 266
11.40 Nanjing Leads Biolabs Co., Ltd. 267
11.40.1 Corporate Profile and Clinical Pipeline Architecture 267
11.40.2 SWOT Matrix and ADC R&D Strategy 268
11.40.3 Pipeline ADC Financial Estimates and Project Valuation Metrics 269
11.41 Formosa Pharmaceuticals, Inc. 270
11.41.1 Corporate Profile and Clinical Pipeline Architecture 270
11.41.2 SWOT Matrix and ADC R&D Strategy 271
11.41.3 Pipeline ADC Financial Estimates and Project Valuation Metrics 272
11.42 Harbour BioMed 273
11.42.1 Corporate Profile and Clinical Pipeline Architecture 273
11.42.2 SWOT Matrix and ADC R&D Strategy 274
11.42.3 Pipeline ADC Financial Estimates and Project Valuation Metrics 275
11.43 CStone Pharmaceuticals 276
11.43.1 Corporate Profile and Clinical Pipeline Architecture 276
11.43.2 SWOT Matrix and ADC R&D Strategy 277
11.43.3 Pipeline ADC Financial Estimates and Project Valuation Metrics 278
11.44 Alphamab Oncology 279
11.44.1 Corporate Profile and Clinical Pipeline Architecture 279
11.44.2 SWOT Matrix and ADC R&D Strategy 280
11.44.3 Pipeline ADC Financial Estimates and Project Valuation Metrics 281
11.45 Akeso, Inc. 282
11.45.1 Corporate Profile and Clinical Pipeline Architecture 282
11.45.2 SWOT Matrix and ADC R&D Strategy 283
11.45.3 Pipeline ADC Financial Estimates and Project Valuation Metrics 284
11.46 Keymed Biosciences Inc. 285
11.46.1 Corporate Profile and Clinical Pipeline Architecture 285
11.46.2 SWOT Matrix and ADC R&D Strategy 286
11.46.3 Pipeline ADC Financial Estimates and Project Valuation Metrics 287
11.47 Shanghai Fudan-Zhangjiang Bio-Pharmaceutical Co., Ltd. 288
11.47.1 Corporate Profile and Clinical Pipeline Architecture 288
11.47.2 SWOT Matrix and ADC R&D Strategy 289
11.47.3 Pipeline ADC Financial Estimates and Project Valuation Metrics 290
11.48 Luye Pharma Group Ltd. 291
11.48.1 Corporate Profile and Clinical Pipeline Architecture 291
11.48.2 SWOT Matrix and ADC R&D Strategy 292
11.48.3 Pipeline ADC Financial Estimates and Project Valuation Metrics 293
11.49 Antengene Corporation Limited 294
11.49.1 Corporate Profile and Clinical Pipeline Architecture 294
11.49.2 SWOT Matrix and ADC R&D Strategy 295
11.49.3 Pipeline ADC Financial Estimates and Project Valuation Metrics 296
11.50 Hansoh Pharmaceutical Group Company Limited 297
11.50.1 Corporate Profile and Clinical Pipeline Architecture 297
11.50.2 SWOT Matrix and ADC R&D Strategy 298
11.50.3 Pipeline ADC Financial Estimates and Project Valuation Metrics 299
11.51 Xuanzhu Biopharm Co., Ltd. 300
11.51.1 Corporate Profile and Clinical Pipeline Architecture 300
11.51.2 SWOT Matrix and ADC R&D Strategy 301
11.51.3 Pipeline ADC Financial Estimates and Project Valuation Metrics 302
11.52 Bio-Thera Solutions, Ltd. 303
11.52.1 Corporate Profile and Clinical Pipeline Architecture 303
11.52.2 SWOT Matrix and ADC R&D Strategy 304
11.52.3 Pipeline ADC Financial Estimates and Project Valuation Metrics 305
11.53 Chong Kun Dang Pharmaceutical Corp. 306
11.53.1 Corporate Profile and Clinical Pipeline Architecture 306
11.53.2 SWOT Matrix and ADC R&D Strategy 307
11.53.3 Pipeline ADC Financial Estimates and Project Valuation Metrics 308
Table 2 Global ADC Market Sales Volume and Treatment Courses (Units), 2021-2031 9
Table 3 Herfindahl-Hirschman Index (HHI) and Market Share Breakdown, 2021-2026 12
Table 4 Major Commercial ADC Regulatory Milestones and Label Expansions 14
Table 5 Upstream Linker and Payload Unit Pricing and Production Yield Matrix 16
Table 6 Global ADC CDMO Dedicated Bioreactor and Bioconjugation Capacity (Liters), 2021-2026 22
Table 7 Global ADC Market Size by Generational Evolution (USD Million), 2021-2031 25
Table 8 First-Generation ADC Revenue and Volume Trajectory, 2021-2031 26
Table 9 Second-Generation ADC Revenue and Target Breakdown, 2021-2031 28
Table 10 Third-Generation and Next-Generation ADC Market Revenue Projections, 2021-2031 30
Table 11 Global ADC Market Size by Application Segment (USD Million), 2021-2031 33
Table 12 Solid Tumors ADC Revenue Breakdown by Cancer Type (USD Million), 2021-2031 34
Table 13 Hematologic Malignancies ADC Revenue Breakdown (USD Million), 2021-2031 36
Table 14 Non-Oncology ADC Indications Clinical Trial Progression and Potential Market Value 38
Table 15 Top ADC Cross-Border In-Licensing and Collaboration Transactions, 2021-2026 41
Table 16 North America ADC Market Size by Country (USD Million), 2021-2031 49
Table 17 United States ADC Treatment Uptake and Pricing Structures, 2021-2026 51
Table 18 Canada ADC Market Valuation and Reimbursement Timeline, 2021-2031 53
Table 19 Europe ADC Market Size by Country (USD Million), 2021-2031 56
Table 20 Germany ADC Market Consumption and Hospital Tender Metrics, 2021-2031 57
Table 21 Switzerland ADC Production Volume, Trade Exports, and Market Size, 2021-2031 59
Table 22 United Kingdom ADC NHS Procurement and Market Valuation, 2021-2031 61
Table 23 Asia-Pacific ADC Market Size by Country (USD Million), 2021-2031 65
Table 24 China ADC Market Valuation, NRDL Dynamics, and Volume Demand, 2021-2031 66
Table 25 Japan ADC Market Size, NHI Price Revisions, and Consumption, 2021-2031 68
Table 26 South Korea ADC Market Trajectory and Biomanufacturing Index, 2021-2031 70
Table 27 India ADC Clinical Trials, Domestic Formulation Uptake, and Market Size, 2021-2031 72
Table 28 Taiwan (China) ADC Market Size and Research Pipeline Progress, 2021-2031 73
Table 29 F. Hoffmann-La Roche Ltd ADC Revenue, Cost and Gross Margin (2021-2026) 76
Table 30 AbbVie Inc. ADC Revenue, Cost and Gross Margin (2021-2026) 80
Table 31 Daiichi Sankyo Company, Limited ADC Revenue, Cost and Gross Margin (2021-2026) 84
Table 32 Pfizer Inc. ADC Revenue, Cost and Gross Margin (2021-2026) 88
Table 33 Astellas Pharma Inc. ADC Revenue, Cost and Gross Margin (2021-2026) 92
Table 34 Gilead Sciences, Inc. ADC Revenue, Cost and Gross Margin (2021-2026) 96
Table 35 AstraZeneca PLC ADC Revenue, Cost and Gross Margin (2021-2026) 100
Table 36 Eisai Co., Ltd. ADC Revenue, Cost and Gross Margin (2021-2026) 104
Table 37 ADC Therapeutics SA ADC Revenue, Cost and Gross Margin (2021-2026) 108
Table 38 Genmab A/S ADC Revenue, Cost and Gross Margin (2021-2026) 112
Table 39 GlaxoSmithKline plc ADC Revenue, Cost and Gross Margin (2021-2026) 116
Table 40 Takeda Pharmaceutical Company Limited ADC Revenue, Cost and Gross Margin (2021-2026) 120
Table 41 Sichuan Kelun-Biotech Biopharmaceutical Co., Ltd. ADC Revenue, Cost and Gross Margin (2021-2026) 124
Table 42 RemeGen Co., Ltd. ADC Revenue, Cost and Gross Margin (2021-2026) 128
Table 43 Jiangsu Hengrui Pharmaceuticals Co., Ltd. ADC Revenue, Cost and Gross Margin (2021-2026) 132
Table 44 Zydus Lifesciences Limited ADC Revenue, Cost and Gross Margin (2021-2026) 136
Table 45 Lepu Biopharma Co., Ltd. ADC Revenue, Cost and Gross Margin (2021-2026) 140
Table 46 Huadong Medicine Co., Ltd. ADC Revenue, Cost and Gross Margin (2021-2026) 144
Table 47 Sichuan Baili Tianheng Pharmaceutical Co., Ltd. ADC Revenue, Cost and Gross Margin (2021-2026) 148
Table 48 Eli Lilly and Company ADC Pipeline Valuation, R&D Cost and Projected Metrics (2021-2026) 152
Table 49 Johnson & Johnson ADC Pipeline Valuation, R&D Cost and Projected Metrics (2021-2026) 155
Table 50 Sanofi S.A. ADC Pipeline Valuation, R&D Cost and Projected Metrics (2021-2026) 158
Table 51 Merck & Co., Inc. (MSD) ADC Pipeline Valuation, R&D Cost and Projected Metrics (2021-2026) 161
Table 52 Merck KGaA ADC Pipeline Valuation, R&D Cost and Projected Metrics (2021-2026) 164
Table 53 ABL Bio Inc. ADC Pipeline Valuation, R&D Cost and Projected Metrics (2021-2026) 167
Table 54 Actinium Pharmaceuticals, Inc. ADC Pipeline Valuation, R&D Cost and Projected Metrics (2021-2026) 170
Table 55 Adagene Inc. ADC Pipeline Valuation, R&D Cost and Projected Metrics (2021-2026) 173
Table 56 Aimed Bio Inc. ADC Pipeline Valuation, R&D Cost and Projected Metrics (2021-2026) 176
Table 57 Akari Therapeutics Plc ADC Pipeline Valuation, R&D Cost and Projected Metrics (2021-2026) 179
Table 58 ALX Oncology Holdings Inc. ADC Pipeline Valuation, R&D Cost and Projected Metrics (2021-2026) 182
Table 59 Aptabio Therapeutics Inc. ADC Pipeline Valuation, R&D Cost and Projected Metrics (2021-2026) 185
Table 60 ArriVent Biopharma, Inc. ADC Pipeline Valuation, R&D Cost and Projected Metrics (2021-2026) 188
Table 61 Avidity Biosciences, Inc. ADC Pipeline Valuation, R&D Cost and Projected Metrics (2021-2026) 191
Table 62 BeOne Medicines Ltd. ADC Pipeline Valuation, R&D Cost and Projected Metrics (2021-2026) 194
Table 63 BioAtla, Inc. ADC Pipeline Valuation, R&D Cost and Projected Metrics (2021-2026) 197
Table 64 BioNTech SE ADC Pipeline Valuation, R&D Cost and Projected Metrics (2021-2026) 200
Table 65 Bolt Biotherapeutics, Inc. ADC Pipeline Valuation, R&D Cost and Projected Metrics (2021-2026) 203
Table 66 Celltrion Inc. ADC Pipeline Valuation, R&D Cost and Projected Metrics (2021-2026) 206
Table 67 Corbus Pharmaceuticals Holdings, Inc. ADC Pipeline Valuation, R&D Cost and Projected Metrics (2021-2026) 209
Table 68 Day One Biopharmaceuticals, Inc. ADC Pipeline Valuation, R&D Cost and Projected Metrics (2021-2026) 212
Table 69 Genome & Company ADC Pipeline Valuation, R&D Cost and Projected Metrics (2021-2026) 215
Table 70 Heidelberg Pharma AG ADC Pipeline Valuation, R&D Cost and Projected Metrics (2021-2026) 218
Table 71 IDEAYA Biosciences, Inc. ADC Pipeline Valuation, R&D Cost and Projected Metrics (2021-2026) 221
Table 72 IMBiologics Corp. ADC Pipeline Valuation, R&D Cost and Projected Metrics (2021-2026) 224
Table 73 Immunome, Inc. ADC Pipeline Valuation, R&D Cost and Projected Metrics (2021-2026) 227
Table 74 IntoCell Inc. ADC Pipeline Valuation, R&D Cost and Projected Metrics (2021-2026) 230
Table 75 MacroGenics, Inc. ADC Pipeline Valuation, R&D Cost and Projected Metrics (2021-2026) 233
Table 76 NextCure, Inc. ADC Pipeline Valuation, R&D Cost and Projected Metrics (2021-2026) 236
Table 77 Perspective Therapeutics, Inc. ADC Pipeline Valuation, R&D Cost and Projected Metrics (2021-2026) 239
Table 78 Qurient Co., Ltd. ADC Pipeline Valuation, R&D Cost and Projected Metrics (2021-2026) 242
Table 79 Sutro Biopharma, Inc. ADC Pipeline Valuation, R&D Cost and Projected Metrics (2021-2026) 245
Table 80 VERAXA Biotech Holding ADC Pipeline Valuation, R&D Cost and Projected Metrics (2021-2026) 248
Table 81 Whitehawk Therapeutics, Inc. ADC Pipeline Valuation, R&D Cost and Projected Metrics (2021-2026) 251
Table 82 Zymeworks Inc. ADC Pipeline Valuation, R&D Cost and Projected Metrics (2021-2026) 254
Table 83 Innovent Biologics, Inc. ADC Pipeline Valuation, R&D Cost and Projected Metrics (2021-2026) 257
Table 84 Zai Lab Limited ADC Pipeline Valuation, R&D Cost and Projected Metrics (2021-2026) 260
Table 85 Transcenta Holding Limited ADC Pipeline Valuation, R&D Cost and Projected Metrics (2021-2026) 263
Table 86 Jacobio Pharmaceuticals Group Co., Ltd. ADC Pipeline Valuation, R&D Cost and Projected Metrics (2021-2026) 266
Table 87 Nanjing Leads Biolabs Co., Ltd. ADC Pipeline Valuation, R&D Cost and Projected Metrics (2021-2026) 269
Table 88 Formosa Pharmaceuticals, Inc. ADC Pipeline Valuation, R&D Cost and Projected Metrics (2021-2026) 272
Table 89 Harbour BioMed ADC Pipeline Valuation, R&D Cost and Projected Metrics (2021-2026) 275
Table 90 CStone Pharmaceuticals ADC Pipeline Valuation, R&D Cost and Projected Metrics (2021-2026) 278
Table 91 Alphamab Oncology ADC Pipeline Valuation, R&D Cost and Projected Metrics (2021-2026) 281
Table 92 Akeso, Inc. ADC Pipeline Valuation, R&D Cost and Projected Metrics (2021-2026) 284
Table 93 Keymed Biosciences Inc. ADC Pipeline Valuation, R&D Cost and Projected Metrics (2021-2026) 287
Table 94 Shanghai Fudan-Zhangjiang Bio-Pharmaceutical Co., Ltd. ADC Pipeline Valuation, R&D Cost and Projected Metrics (2021-2026) 290
Table 95 Luye Pharma Group Ltd. ADC Pipeline Valuation, R&D Cost and Projected Metrics (2021-2026) 293
Table 96 Antengene Corporation Limited ADC Pipeline Valuation, R&D Cost and Projected Metrics (2021-2026) 296
Table 97 Hansoh Pharmaceutical Group Company Limited ADC Pipeline Valuation, R&D Cost and Projected Metrics (2021-2026) 299
Table 98 Xuanzhu Biopharm Co., Ltd. ADC Pipeline Valuation, R&D Cost and Projected Metrics (2021-2026) 302
Table 99 Bio-Thera Solutions, Ltd. ADC Pipeline Valuation, R&D Cost and Projected Metrics (2021-2026) 305
Table 100 Chong Kun Dang Pharmaceutical Corp. ADC Pipeline Valuation, R&D Cost and Projected Metrics (2021-2026) 308
Figure 1 Global Antibody-Drug Conjugates Market Trajectory (USD Million), 2021-2031 8
Figure 2 ADC Market Structural Growth Rates and Segment Velocity Comparison, 2026-2031 10
Figure 3 Value Chain Margin Capture across mAbs, Linkers, Payloads, and Conjugation 18
Figure 4 Global Biologics CDMO Bioconjugation Cleanroom Expansion Index, 2021-2026 23
Figure 5 Market Share Shift by Generational ADC Platforms, 2021-2031 29
Figure 6 Clinical Target Distribution of Active ADC Pipeline Programs, 2026 Baseline 35
Figure 7 Global ADC Therapeutic Share Breakdown: Solid Tumors vs Hematology vs Non-Oncology 37
Figure 8 Cross-Border ADC Deal Values and Upfront Payment Trajectory, 2021-2026 43
Figure 9 North America ADC Market Share by Country, 2026 vs 2031 50
Figure 10 Europe ADC Regional Revenue Contribution Breakdown, 2021-2031 58
Figure 11 Asia-Pacific ADC Innovation and Revenue Trajectory, 2021-2031 66
Figure 12 F. Hoffmann-La Roche Ltd ADC Market Share (2021-2026) 77
Figure 13 AbbVie Inc. ADC Market Share (2021-2026) 81
Figure 14 Daiichi Sankyo Company, Limited ADC Market Share (2021-2026) 85
Figure 15 Pfizer Inc. ADC Market Share (2021-2026) 89
Figure 16 Astellas Pharma Inc. ADC Market Share (2021-2026) 93
Figure 17 Gilead Sciences, Inc. ADC Market Share (2021-2026) 97
Figure 18 AstraZeneca PLC ADC Market Share (2021-2026) 101
Figure 19 Eisai Co., Ltd. ADC Market Share (2021-2026) 105
Figure 20 ADC Therapeutics SA ADC Market Share (2021-2026) 109
Figure 21 Genmab A/S ADC Market Share (2021-2026) 113
Figure 22 GlaxoSmithKline plc ADC Market Share (2021-2026) 117
Figure 23 Takeda Pharmaceutical Company Limited ADC Market Share (2021-2026) 121
Figure 24 Sichuan Kelun-Biotech Biopharmaceutical Co., Ltd. ADC Market Share (2021-2026) 125
Figure 25 RemeGen Co., Ltd. ADC Market Share (2021-2026) 129
Figure 26 Jiangsu Hengrui Pharmaceuticals Co., Ltd. ADC Market Share (2021-2026) 133
Figure 27 Zydus Lifesciences Limited ADC Market Share (2021-2026) 137
Figure 28 Lepu Biopharma Co., Ltd. ADC Market Share (2021-2026) 141
Figure 29 Huadong Medicine Co., Ltd. ADC Market Share (2021-2026) 145
Figure 30 Sichuan Baili Tianheng Pharmaceutical Co., Ltd. ADC Market Share (2021-2026) 149
Figure 31 Eli Lilly and Company ADC Market Share and Pipeline Share (2021-2026) 152
Figure 32 Johnson & Johnson ADC Market Share and Pipeline Share (2021-2026) 155
Figure 33 Sanofi S.A. ADC Market Share and Pipeline Share (2021-2026) 158
Figure 34 Merck & Co., Inc. (MSD) ADC Market Share and Pipeline Share (2021-2026) 161
Figure 35 Merck KGaA ADC Market Share and Pipeline Share (2021-2026) 164
Figure 36 ABL Bio Inc. ADC Market Share and Pipeline Share (2021-2026) 167
Figure 37 Actinium Pharmaceuticals, Inc. ADC Market Share and Pipeline Share (2021-2026) 170
Figure 38 Adagene Inc. ADC Market Share and Pipeline Share (2021-2026) 173
Figure 39 Aimed Bio Inc. ADC Market Share and Pipeline Share (2021-2026) 176
Figure 40 Akari Therapeutics Plc ADC Market Share and Pipeline Share (2021-2026) 179
Figure 41 ALX Oncology Holdings Inc. ADC Market Share and Pipeline Share (2021-2026) 182
Figure 42 Aptabio Therapeutics Inc. ADC Market Share and Pipeline Share (2021-2026) 185
Figure 43 ArriVent Biopharma, Inc. ADC Market Share and Pipeline Share (2021-2026) 188
Figure 44 Avidity Biosciences, Inc. ADC Market Share and Pipeline Share (2021-2026) 191
Figure 45 BeOne Medicines Ltd. ADC Market Share and Pipeline Share (2021-2026) 194
Figure 46 BioAtla, Inc. ADC Market Share and Pipeline Share (2021-2026) 197
Figure 47 BioNTech SE ADC Market Share and Pipeline Share (2021-2026) 200
Figure 48 Bolt Biotherapeutics, Inc. ADC Market Share and Pipeline Share (2021-2026) 203
Figure 49 Celltrion Inc. ADC Market Share and Pipeline Share (2021-2026) 206
Figure 50 Corbus Pharmaceuticals Holdings, Inc. ADC Market Share and Pipeline Share (2021-2026) 209
Figure 51 Day One Biopharmaceuticals, Inc. ADC Market Share and Pipeline Share (2021-2026) 212
Figure 52 Genome & Company ADC Market Share and Pipeline Share (2021-2026) 215
Figure 53 Heidelberg Pharma AG ADC Market Share and Pipeline Share (2021-2026) 218
Figure 54 IDEAYA Biosciences, Inc. ADC Market Share and Pipeline Share (2021-2026) 221
Figure 55 IMBiologics Corp. ADC Market Share and Pipeline Share (2021-2026) 224
Figure 56 Immunome, Inc. ADC Market Share and Pipeline Share (2021-2026) 227
Figure 57 IntoCell Inc. ADC Market Share and Pipeline Share (2021-2026) 230
Figure 58 MacroGenics, Inc. ADC Market Share and Pipeline Share (2021-2026) 233
Figure 59 NextCure, Inc. ADC Market Share and Pipeline Share (2021-2026) 236
Figure 60 Perspective Therapeutics, Inc. ADC Market Share and Pipeline Share (2021-2026) 239
Figure 61 Qurient Co., Ltd. ADC Market Share and Pipeline Share (2021-2026) 242
Figure 62 Sutro Biopharma, Inc. ADC Market Share and Pipeline Share (2021-2026) 245
Figure 63 VERAXA Biotech Holding ADC Market Share and Pipeline Share (2021-2026) 248
Figure 64 Whitehawk Therapeutics, Inc. ADC Market Share and Pipeline Share (2021-2026) 251
Figure 65 Zymeworks Inc. ADC Market Share and Pipeline Share (2021-2026) 254
Figure 66 Innovent Biologics, Inc. ADC Market Share and Pipeline Share (2021-2026) 257
Figure 67 Zai Lab Limited ADC Market Share and Pipeline Share (2021-2026) 260
Figure 68 Transcenta Holding Limited ADC Market Share and Pipeline Share (2021-2026) 263
Figure 69 Jacobio Pharmaceuticals Group Co., Ltd. ADC Market Share and Pipeline Share (2021-2026) 266
Figure 70 Nanjing Leads Biolabs Co., Ltd. ADC Market Share and Pipeline Share (2021-2026) 269
Figure 71 Formosa Pharmaceuticals, Inc. ADC Market Share and Pipeline Share (2021-2026) 272
Figure 72 Harbour BioMed ADC Market Share and Pipeline Share (2021-2026) 275
Figure 73 CStone Pharmaceuticals ADC Market Share and Pipeline Share (2021-2026) 278
Figure 74 Alphamab Oncology ADC Market Share and Pipeline Share (2021-2026) 281
Figure 75 Akeso, Inc. ADC Market Share and Pipeline Share (2021-2026) 284
Figure 76 Keymed Biosciences Inc. ADC Market Share and Pipeline Share (2021-2026) 287
Figure 77 Shanghai Fudan-Zhangjiang Bio-Pharmaceutical Co., Ltd. ADC Market Share (2021-2026) 290
Figure 78 Luye Pharma Group Ltd. ADC Market Share and Pipeline Share (2021-2026) 293
Figure 79 Antengene Corporation Limited ADC Market Share and Pipeline Share (2021-2026) 296
Figure 80 Hansoh Pharmaceutical Group Company Limited ADC Market Share (2021-2026) 299
Figure 81 Xuanzhu Biopharm Co., Ltd. ADC Market Share and Pipeline Share (2021-2026) 302
Figure 82 Bio-Thera Solutions, Ltd. ADC Market Share and Pipeline Share (2021-2026) 305
Figure 83 Chong Kun Dang Pharmaceutical Corp. ADC Market Share and Pipeline Share (2021-2026) 308
Research Methodology
- Market Estimated Methodology:
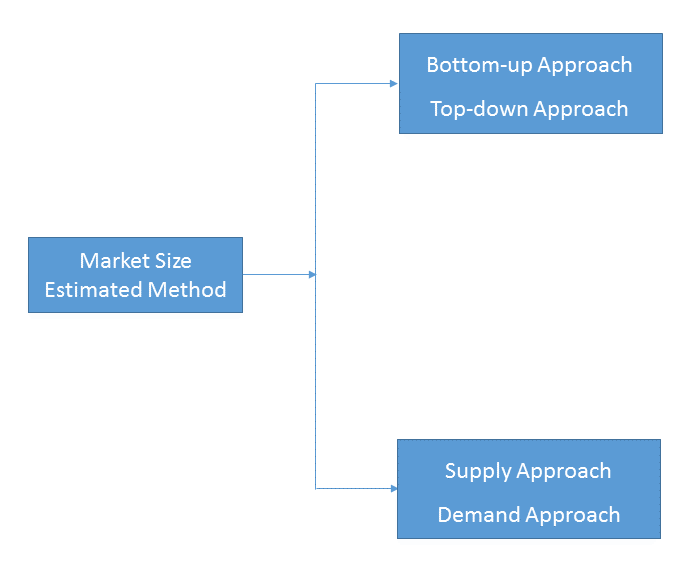
Bottom-up & top-down approach, supply & demand approach are the most important method which is used by HDIN Research to estimate the market size.
1)Top-down & Bottom-up Approach
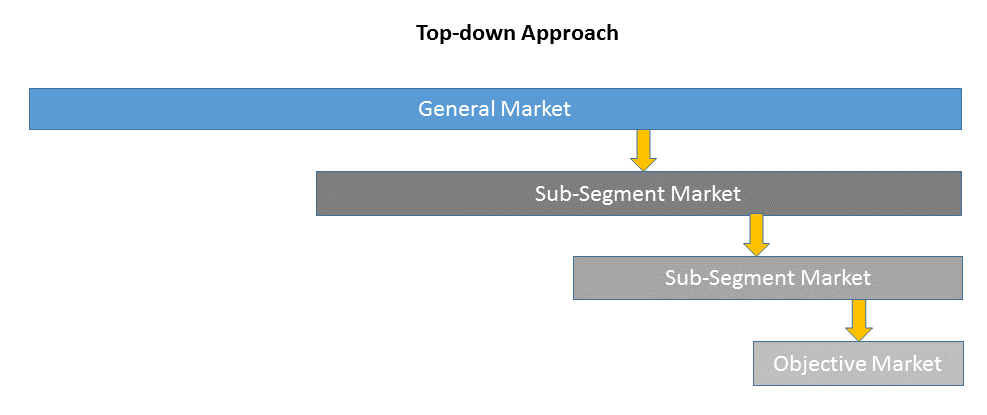
Top-down approach uses a general market size figure and determines the percentage that the objective market represents.
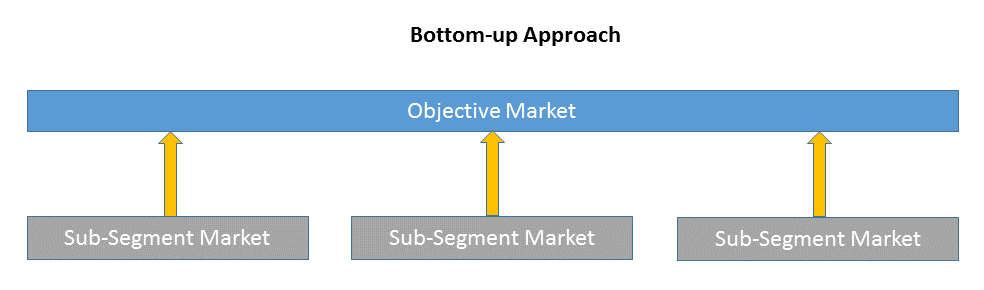
Bottom-up approach size the objective market by collecting the sub-segment information.
2)Supply & Demand Approach
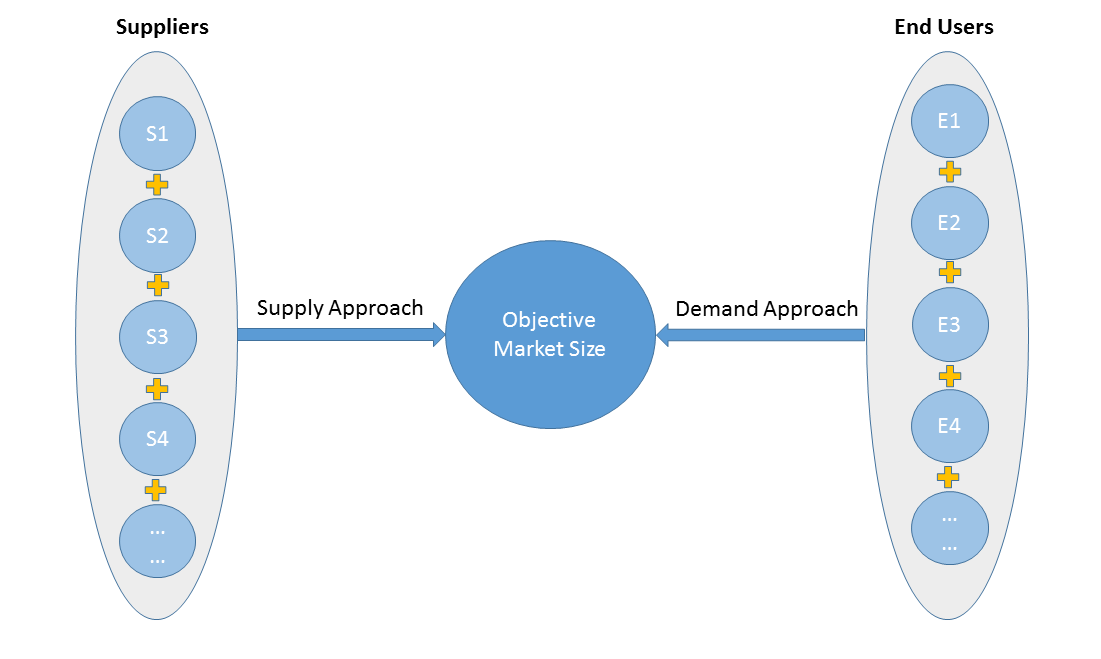
Supply approach is based on assessments of the size of each competitor supplying the objective market.
Demand approach combine end-user data within a market to estimate the objective market size. It is sometimes referred to as bottom-up approach.
- Forecasting Methodology
- Numerous factors impacting the market trend are considered for forecast model:
- New technology and application in the future;
- New project planned/under contraction;
- Global and regional underlying economic growth;
- Threatens of substitute products;
- Industry expert opinion;
- Policy and Society implication.
- Analysis Tools
1)PEST Analysis
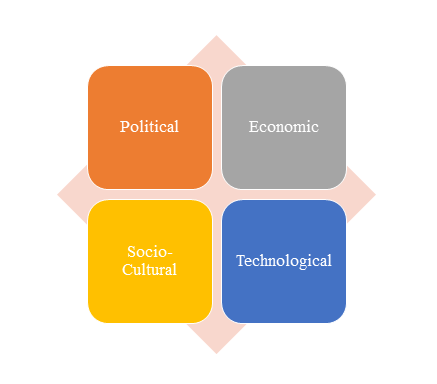
PEST Analysis is a simple and widely used tool that helps our client analyze the Political, Economic, Socio-Cultural, and Technological changes in their business environment.
- Benefits of a PEST analysis:
- It helps you to spot business opportunities, and it gives you advanced warning of significant threats.
- It reveals the direction of change within your business environment. This helps you shape what you’re doing, so that you work with change, rather than against it.
- It helps you avoid starting projects that are likely to fail, for reasons beyond your control.
- It can help you break free of unconscious assumptions when you enter a new country, region, or market; because it helps you develop an objective view of this new environment.
2)Porter’s Five Force Model Analysis
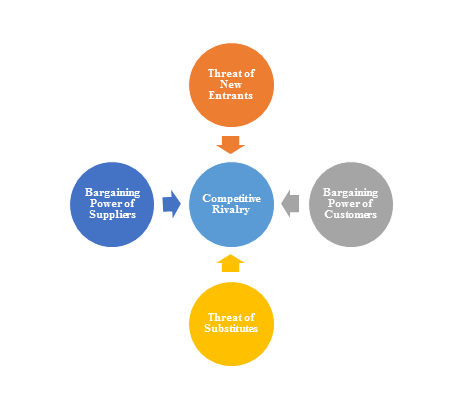
The Porter’s Five Force Model is a tool that can be used to analyze the opportunities and overall competitive advantage. The five forces that can assist in determining the competitive intensity and potential attractiveness within a specific area.
- Threat of New Entrants: Profitable industries that yield high returns will attract new firms.
- Threat of Substitutes: A substitute product uses a different technology to try to solve the same economic need.
- Bargaining Power of Customers: the ability of customers to put the firm under pressure, which also affects the customer's sensitivity to price changes.
- Bargaining Power of Suppliers: Suppliers of raw materials, components, labor, and services (such as expertise) to the firm can be a source of power over the firm when there are few substitutes.
- Competitive Rivalry: For most industries the intensity of competitive rivalry is the major determinant of the competitiveness of the industry.
3)Value Chain Analysis
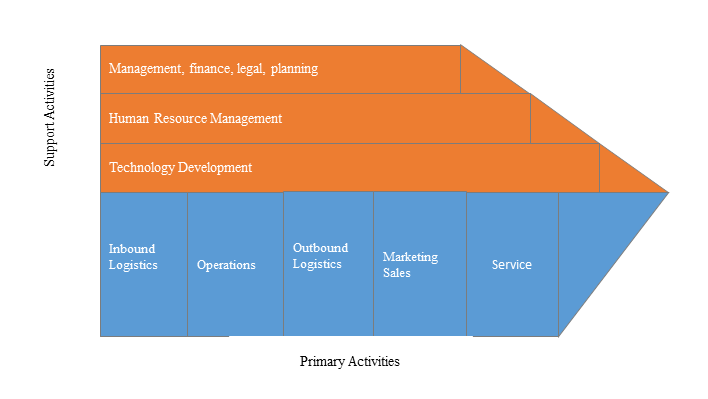
Value chain analysis is a tool to identify activities, within and around the firm and relating these activities to an assessment of competitive strength. Value chain can be analyzed by primary activities and supportive activities. Primary activities include: inbound logistics, operations, outbound logistics, marketing & sales, service. Support activities include: technology development, human resource management, management, finance, legal, planning.
4)SWOT Analysis
SWOT analysis is a tool used to evaluate a company's competitive position by identifying its strengths, weaknesses, opportunities and threats. The strengths and weakness is the inner factor; the opportunities and threats are the external factor. By analyzing the inner and external factors, the analysis can provide the detail information of the position of a player and the characteristics of the industry.
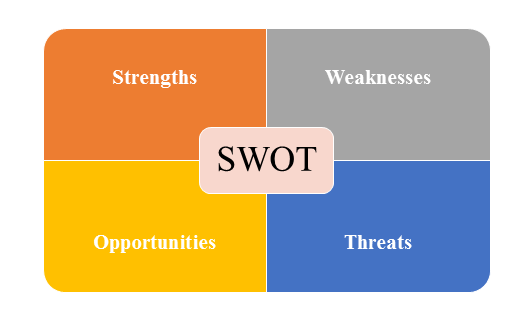
- Strengths describe what the player excels at and separates it from the competition
- Weaknesses stop the player from performing at its optimum level.
- Opportunities refer to favorable external factors that the player can use to give it a competitive advantage.
- Threats refer to factors that have the potential to harm the player.
- Data Sources
| Primary Sources | Secondary Sources |
|---|---|
| Face to face/Phone Interviews with market participants, such as: Manufactures; Distributors; End-users; Experts. Online Survey |
Government/International Organization Data: Annual Report/Presentation/Fact Book Internet Source Information Industry Association Data Free/Purchased Database Market Research Report Book/Journal/News |