Industrial Gases Market: 2026-2031 Strategic Outlook
- Single User License (1 Users) $ 3,500
- Team License (2~5 Users) $ 4,500
- Corporate License (>5 Users) $ 5,500
Industrial gases are an essential utility spine for modern industrial economies, functioning as a non-substitutable input across heavy manufacturing, chemicals, microelectronics fabrication, and clinical healthcare. Characterized as the circulating blood of modern industry, this sector exhibits extreme barriers to entry rooted in capital-intensive asset bases, localized distribution moats, proprietary cryogenic separation engineering, and long-tenure contractual lock-ins. By 2026, the global industrial gases market is evaluated at between 120 billion and 150 billion USD, expanding at a compound annual growth rate of 3.2% to 4.2% through 2031.
A high structural oligopoly defines global industry governance. Three multinational entities—Linde plc, L'Air Liquide S.A., and Air Products and Chemicals, Inc.—control the commanding heights of multi-regional tonnage networks and electronic gas synthesis. Beneath this triad, a resilient cadre of regional leaders anchors localized market basins, including Nippon Sanso Holdings Corporation, Air Water Inc., Messer Group, SOL S.p.A., INOX Air Products, and Hangzhou Oxygen Plant Group (Hangyang). Market momentum is propelled by four overarching secular developments: the accelerating global decaptivation trend where sovereign industrial operators outsource captive air separation infrastructure to specialist gas managers; multi-billion-dollar low-carbon hydrogen and autothermal reforming builds for refining and basic metals; unprecedented ultra-high purity carrier gas consumption in advanced sub-2nm semiconductor fabrication; and tightening cross-border environmental regulations requiring carbon capture, utilization, and storage retrofits.
PRODUCT TAXONOMY AND MOLECULAR ECONOMICS
Industrial gases encompass purified chemical elements, elemental molecules, and synthesized compound mixtures extracted via cryogenic atmospheric fractionation, hydrocarbon reforming, chemical synthesis, or byproduct separation. Four core molecules—Nitrogen, Hydrogen, Oxygen, and Carbon Dioxide—command more than 80% of aggregate sector value.
1. Atmospheric Gases
Atmospheric air comprises roughly 78.08% nitrogen, 20.95% oxygen, 0.93% argon, and trace fractions of noble gases. Extraction requires cryogenic Air Separation Units (ASUs) utilizing multi-stage compression, molecular sieve chilling to scrub moisture and carbon dioxide, and subsequent fractional distillation in dual-pressure columns operating below minus 150 degrees Celsius.
- Oxygen (O2): Cryogenically separated at scale, or produced via localized non-cryogenic Vacuum Pressure Swing Adsorption (VPSA) for decentralized requirements. Oxygen functions as a potent oxidizing agent and combustion accelerator, lifting thermal efficiencies across blast furnaces, basic oxygen furnaces, and electric arc systems, while acting as a chemical reactant in ethylene oxide synthesis and an active pharmaceutical ingredient in clinical respiratory therapies.
- Nitrogen (N2): Cryogenic co-product of oxygen separation, with localized small-to-medium needs fulfilled by hollow-fiber polymeric membranes or Pressure Swing Adsorption (PSA). Its primary utility stems from chemical inertness, providing continuous line purging, vessel blanketing, and explosion prevention in petrochemical complexes, while serving as a sub-micron carrier gas in semiconductor fabs and an ultra-cold agent (minus 196 degrees Celsius) in food chilling.
- Argon (Ar): Extracted via intermediate side-arm distillation columns from crude oxygen-argon fractions, present at 0.93% ambient concentration. Argon serves as a totally inert shield in Gas Tungsten Arc Welding and Gas Metal Arc Welding, a crucial degassing and stirring agent in Argon Oxygen Decarburization stainless steel processing, and an ionizing plasma base for silicon wafer sputtering.
- Rare and Noble Gases (Neon, Krypton, Xenon): Recovered from non-condensable purge streams and liquid oxygen basins in world-scale ASUs. Neon acts as the vital balance gas for excimer laser photolithography mixtures (ArF and KrF lasers) in advanced lithography scanners. Krypton and Xenon provide high-performance insulating window fill, space satellite electric ion propulsion, and advanced high-aspect-ratio plasma dry etch chemistries for deep 3D-NAND tier etching.
2. Process Gases
Process molecules rely on hydrocarbon processing, chemical synthesis, or industrial off-gas recovery rather than ambient fractionation.
- Hydrogen (H2): Produced primarily via high-temperature Steam Methane Reforming (SMR) or Autothermal Reforming (ATR) of natural gas over nickel catalysts, yielding synthesis gas followed by water-gas shift conversion and PSA purification. Progressive pathways deploy SMR/ATR with carbon capture (blue hydrogen) or water electrolysis (green hydrogen). Hydrogen functions as an essential chemical reducing agent for petroleum desulfurization, ammonia synthesis, and direct reduced iron steel manufacturing.
- Carbon Dioxide (CO2): Captured predominantly as an industrial off-gas byproduct from ammonia plants, bio-ethanol fermentation units, and ethylene oxide reactors, followed by scrubbing, compression, and cryogenic liquefaction. It is utilized in carbonated beverage bottling, modified atmosphere food packaging, cryogenic transit via dry ice, and industrial wastewater pH stabilization.
- Carbon Monoxide (CO) and Synthesis Gas (Syngas): Sourced from SMR, ATR, or partial oxidation of hydrocarbons. Cryogenic cold-box distillation isolates pure CO, which operates as a fundamental C1 chemical building block for polycarbonates, acetic acid, and isocyanates (MDI/TDI), alongside specialized 4N5 electronic grades deployed in dielectric plasma dry etching.
- Acetylene (C2H2): Synthesized from calcium carbide hydration or hydrocarbon cracking, providing ultra-high flame temperatures for metal fabrication and serving as an intermediate in organic chemical synthesis.
- Helium (He): Extracted exclusively from natural gas reserves bearing trace concentrations (notably in the United States, Qatar, and Algeria) through multi-stage cryogenic separation. Irreplaceable for liquid cooling of Magnetic Resonance Imaging superconducting coils at 4 Kelvin, leak detection in high-vacuum chambers, and purge sweeps in space launch vehicle propellent systems.
3. Specialty and Electronic Gases
The highest unit-margin sector cohort, electronic specialty gases operate at ultra-high purity thresholds (5N to 7N, or 99.999% to 99.99999%).
- Fluorinated Etch and Chamber Cleaning Chemistries: Nitrogen Trifluoride (NF3) serves as the primary plasma chamber clean agent with minimal residue. Tungsten Hexafluoride (WF6) delivers chemical vapor deposition metallization for contact plugs. Specialized fluorocarbons (CF4, C4F8, C4F6) enable precise, high-aspect-ratio dielectric trench etching in multi-layer architectures.
- Hydrides and Silicon Precursors: Silane (SiH4) and Disilane (Si2H6) support epitaxial silicon and dielectric deposition; Germane (GeH4) and Phosphine (PH3) enable atomic-level wafer implantation and doping.
COMMERCIAL DELIVERY ARCHITECTURE AND UNIT ECONOMICS
The industrial gas commercial model operates across three distinct distribution modes, determined by customer volume consumption, required delivery pressure and purity, geographic density, and capital intensity.
1. On-Site and Pipeline Supply (Tonnage Mode)
- Customer Archetype: Large-scale, continuous-process facilities such as integrated steelworks, petrochemical refining hubs, and leading semiconductor fabs.
- Contract Architecture: Executed via long-term contracts spanning 10 to 20 years, operating predominantly on a Build-Own-Operate (BOO) structure. The gas supplier finances, builds, owns, and operates the dedicated ASU or SMR over the fence.
- Risk and Margin Mechanics: Incorporates structural take-or-pay covenants requiring the customer to pay fixed facility fees irrespective of volume consumption. Absolute pass-through provisions shield the gas producer from raw electricity and natural gas price volatility. Switching costs are prohibitive due to co-located piping infrastructure, granting the gas producer defensive cash flow stability. In key industrial nodes, such as the US Gulf Coast or the Antwerp-Rotterdam corridor, integrated pipeline networks connect multiple supply units, creating robust supply redundancy and formidable competitive entry moats.
2. Merchant Bulk Liquid Supply
- Customer Archetype: Medium-volume consumption across regional food processing facilities, medical hospitals, metal fabricators, and glass furnaces requiring cryogenic storage without justifying dedicated ASU construction.
- Distribution Economics: Molecules are liquefied via cryogenic liquefiers and hauled in vacuum-insulated road tankers, ISO containers, or tube trailers. Distribution is constrained by an economic haulage radius of 250 to 300 kilometers from the central ASU due to freight logistics, driver labor costs, and cryogenic boil-off degradation. Scarcer, high-value molecules such as liquid helium, liquid argon, and electronic silanes transcend this distance boundary, moving inter-regionally.
- Commercial Terms: Supply agreements span 3 to 7 years. Contracts integrate electricity surcharges, fuel indexation formulas, and monthly tank lease fees. Crucially, the gas producer maintains legal ownership of the on-site vacuum-insulated cryogenic vessels, telemetry units, and vaporizers installed at customer grounds, creating friction against mid-contract vendor substitution.
3. Packaged and Cylinder Gas Supply
- Customer Archetype: Fragmented, low-volume consumers totaling millions of independent fabrication shops, analytical laboratories, research institutes, and maintenance centers.
- Operational Structure: Bulk cryogenic liquid is transferred from centralized ASUs to local filling stations, compressed, and filled into high-pressure steel or aluminum cylinders, multi-cylinder bundles, and proprietary sub-atmospheric absorbent vessels (for toxic electronic specialties) at pressures between 150 bar and 300 bar.
- Economic Mechanics: Contracts span 1 to 3 years or direct transactional spot purchase orders. Suppliers capture revenues from molecule sales, container rental demurrage fees, and welding hardgoods equipment sales. While producing the highest gross margins per volume unit, the packaged gas division requires heavy working capital, route density optimization, and localized logistics management.
VALUE CHAIN DECOMPOSITION AND SUPPLY BOTTLENECKS
The industrial gas value chain integrates raw material sourcing, heavy cryogenic plant engineering, regional distribution networks, and customer process integrations.
● Upstream Inputs and Engineering Capability:
Raw materials vary between free, infinite atmospheric air and hydrocarbon feedstocks such as natural gas, fuel oil, and chemical off-gases. Electricity functions as the single largest variable operational expenditure in atmospheric gas extraction, accounting for the vast majority of ASU operational cash outlays. Tier-1 gas providers mitigate technology execution risks by maintaining integrated, captive engineering units (such as Air Liquide Engineering and Construction, or Linde Engineering). These specialized divisions design, patent, and manufacture brazed aluminum heat exchangers, cryogenic distillation cold boxes, turbo-expanders, and hydrogen reforming reactors internally.
● Midstream Operations and Regional Hub Economics:
Atmospheric air is drawn into high-horsepower multi-stage compressors, cleaned of moisture and trace hydro-compounds through molecular sieves, cooled via counter-current heat exchangers, and sent into cryogenic columns for fractional separation. Because raw gaseous molecules cannot be held economically at ambient pressures, liquefiers shrink molecule volumes by roughly 800 to 1, facilitating liquid storage in double-walled, vacuum-insulated tanks. Facilities operate as regional hub-and-spoke anchors: central pipeline-integrated plants feed localized high-pressure pipeline loops, while their merchant liquefaction capacity supplies peripheral liquid storage tanks and cylinder-filling facilities.
● Downstream Delivery, Decaptivation, and Total Fluid Management:
The global manufacturing ecosystem is defined by progressive decaptivation. Historically, primary chemical processors and metallurgical conglomerates engineered and maintained captive ASUs in-house. To optimize balance sheets, these operators continue to divest captive units to specialized industrial gas majors under multi-decade utility supply contracts. Gas suppliers deepen this customer integration by offering Total Gas and Chemical Management (TGCM), on-site analytical quality assurance, specialized food freezing engineering, and closed-loop cylinder monitoring systems, cementing operational moats.
DOWNSTREAM APPLICATION INTELLIGENCE
1. Chemicals and Petrochemicals
Industrial gas infrastructure operates directly linked with petrochemical platforms. Hydrogen and syngas supply continuous feedstock streams for ammonia, urea, methanol, and specialty polymer syntheses. Massive quantities of oxygen feed partial oxidation reactors for ethylene oxide, propylene oxide, and titanium dioxide manufacturing. High-purity nitrogen blankets chemical storage terminals, pressurizes transfer lines, and pneumatically conveys combustible plastic pellets, eliminating explosion hazards.
2. Steelmaking and Metallurgy
In basic oxygen steelmaking, supersonic oxygen streams decarburize molten pig iron, stripping carbon, silicon, and phosphorus impurities. Ladle metallurgy depends on continuous argon purging through porous plugs to homogenize thermal gradients and float non-metallic inclusions. In stainless steel processing, the Argon Oxygen Decarburization (AOD) pathway uses argon-diluted oxygen to prevent valuable chromium oxidation. The industry's push toward net-zero metallurgy accelerates the deployment of green hydrogen in Direct Reduced Iron (DRI) shaft furnaces to replace coke-fueled blast furnaces.
3. Refining and Midstream Energy
Downstream refineries are major consumers of pipeline-delivered hydrogen, utilizing it in high-pressure hydrotreating and hydrocracking units to strip organic sulfur from crude fractions to comply with strict fuel mandates. Nitrogen is continuously used across refineries for turnaround catalyst regeneration, system purge sequences, and emergency blanketing. In midstream natural gas liquefaction (LNG), cryogenic liquid nitrogen pre-cools cryogenic heat exchangers, purges storage tanks, and provides safety barriers during maritime shipping.
4. Electronics and Photovoltaic
Semiconductor wafer fabrication facilities operate as continuous consumers of ultra-high purity carrier gases and sub-micron chemical agents. Modern mega-fabs require tens of thousands of cubic meters per hour of ultra-pure nitrogen (>6N) to purge front-opening unified pods (FOUPs), maintain cleanroom atmospheres, and isolate tools. Photolithography relies on excimer laser gas mixtures containing neon, argon, and krypton. Advanced chemical vapor deposition (CVD) and atomic layer deposition (ALD) deploy silane, disilane, and organometallic precursors, while dry plasma etching uses fluorinated compounds (NF3, CF4, C4F8) for precision dielectric patterning. The solar photovoltaic sector requires large volumes of silane, ammonia, and nitrogen for polysilicon synthesis and passivation layer deposition.
5. Food and Beverage
Cryogenic liquid nitrogen is injected into immersion tunnels to fast-freeze meats, seafood, and prepared meals at minus 196 degrees Celsius, preventing large ice crystal growth to protect cellular texture. Liquid nitrogen droplet dosing provides internal rigidity to lightweight beverage cans before sealing. Carbon dioxide carbonates soft drinks and beer, acts as dry ice for cold chain logistics, and forms Modified Atmosphere Packaging (MAP) mixtures with nitrogen to suppress aerobic bacterial decay in packaged perishables.
6. Healthcare
Medical oxygen is regulated globally as an active pharmaceutical ingredient, delivered via cryogenic vacuum-insulated bulk tanks connected to hospital distribution manifolds, or through high-pressure cylinders. The post-2020 expansion of central hospital oxygen systems created a permanently elevated baseline for healthcare demand. Additional medical products include nitrous oxide for surgical anesthesia, liquid helium to cool Magnetic Resonance Imaging superconducting magnets, and lung diffusion gas blends for diagnostic equipment calibration.
7. Manufacturing and Automotive
Metal structural fabrication, automotive assembly lines, and heavy machinery production rely on standardized shielding gas blends (argon, carbon dioxide, oxygen, and helium mixtures) to shield automated robotic GMAW and GTAW weld pools from atmospheric embrittlement. Nitrogen and oxygen serve as assist gases for industrial high-speed fiber laser plate cutting. Heat-treatment operations deploy nitrogen-hydrogen atmospheres to prevent surface decarburization during automotive gear and transmission annealing. Electric vehicle manufacturing expands demand for helium leak-detection across battery pack modules and nitrogen blanketing during battery recycling.
8. Other Specialized Sectors
- Aerospace and Defense: Liquid oxygen and liquid hydrogen function as high-energy cryogenic propellants for space launch vehicles. High-pressure helium purges fuel lines and actuates cryogenic engine valves. Xenon provides reaction mass for satellite electric ion thrusters.
- Glass and Ceramics: Oxy-fuel burner retrofits replace ambient air with pure oxygen, elevating furnace melting efficiency, reducing fuel consumption, and lowering nitrogen oxide emissions.
- Environmental and CCUS: Proprietary cryogenic separation systems isolate, compress, and liquefy carbon dioxide from blast furnace flue streams and cement kiln exhausts, facilitating permanent geological storage or synthetic fuel synthesis.
REGIONAL MARKET DYNAMICS
1. Asia-Pacific (APAC)
Asia-Pacific holds the largest share of the global industrial gases market, generating more than 38% of worldwide demand, driven by heavy industrial output, infrastructure investment, and regional semiconductor, display, and solar supply chain concentration.
- China: The largest country market in the region. Historically, international majors (Linde, Air Liquide, Air Products, Nippon Sanso Holdings, Messer) controlled roughly 40% of the domestic market. However, domestic players such as Hangzhou Oxygen Plant Group (Hangyang) and Pujiang International (Tangsteel Gas) continue expanding market presence via machinery manufacturing integration and local outsourcing. Cyclical adjustments in the domestic steel market have weighed on merchant liquid spot prices and compressed rare gas margins, particularly for helium and krypton-xenon mixes.
- India: The fastest-expanding large economy in the region. Oxygen represents the primary molecule by volume and market value, anchored by domestic steel expansions and hospital infrastructure. Nitrogen holds the second position, followed in scale by Hydrogen, Argon, and Helium. Key participants include INOX Air Products Limited, Linde India Ltd., Air Water India Pvt. Ltd., Ellenbarrie Industrial Gases, and Air algorithm-aligned entities. In October 2025, Air Liquide completed the acquisition of NovaAir, strengthening distribution across eastern and southern industrial corridors.
- Japan: A mature, technologically sophisticated market dominated by Nippon Sanso Holdings Corporation and Air Water Inc., supported by regional producers such as Koatsu Gas Kogyo, Koike Sanso Kogyo, and Toho Acetylene. Muted domestic basic chemical and steel operations have directed strategic investments toward advanced electronic specialty gases and hydrogen distribution networks. Japanese chemical suppliers remain primary producers of advanced electronics-grade gases.
- South Korea: The fourth-largest regional gas market, anchored by concentrated memory chip, foundry, and EV battery plants. In August 2025, Air Liquide entered an agreement to acquire DIG Airgas (formerly Daesung Industrial Gases), closing the deal on January 13, 2026. The transaction added 60 production facilities and 220 km of pipeline networks generating approximately 900 million EUR (1,017.54 million USD) in annual revenue, effectively doubling Air Liquide's national operational capacity.
- Southeast Asia: Indonesia represents a primary growth basin, where PT Samator Indo Gas Tbk controls approximately 75% to 80% of healthcare medical gases and roughly 40% of merchant bulk and cylinder segments. Market expansion is supported by sovereign mineral downstreaming mandates that compel domestic smelting of nickel, bauxite, and alumina. Taiwan, China continues to see strong demand for electronic carrier gases, fluorinated etch chemistries, and ultra-high purity engineering systems driven by advanced semiconductor node manufacturing.
2. North America
The United States represents the largest single national market by revenue globally. The region features integrated pipeline infrastructures traversing the US Gulf Coast, supplying world-scale petrochemical, refining, and ammonia processing complexes under multi-decade take-or-pay tonnage contracts. Growth is supported by domestic re-industrialization, CHIPS-funded semiconductor fab constructions, and carbon capture infrastructure deployments.
3. Europe
Europe is a technically advanced market with high per-capita gas consumption, strict decarbonization directives, and extensive clinical healthcare integration. While structural demand across heavy metallurgy and commodity petrochemicals has faced headwinds due to elevated baseline power inputs, operating margins have been defended through structural contract pass-through pricing, operational cost streamlining, and growing demand for carbon-capture and low-carbon hydrogen projects.
4. South America
South American demand centers on natural resource extraction, non-ferrous metallurgy, agricultural processing, and urban clinical gas delivery networks. Localized industrial clusters in Brazil and Argentina support on-site and pipeline units, while broader geographic areas rely on long-haul merchant liquid tankers and packaged gas distribution.
5. Middle East and Africa (MEA)
The Middle East serves as a key strategic node for world-scale petrochemical, refining, and hydrogen-ammonia operations. Production complexes in Saudi Arabia, the United Arab Emirates, and Qatar anchor major hydrogen and syngas supply agreements. Across Africa, demand centers on mining metallurgy, basic manufacturing, and healthcare infrastructure, with South Africa serving as the primary cryogenic separation and coal-to-liquids gas hub.
COMPETITIVE DOSSIERS AND STRATEGIC MOATS
1. Global Tier-1 Multinationals
- Linde plc: The largest industrial gases group globally by market capitalization and revenue. Linde maintains competitive advantages through regional pipeline density along core industrial corridors, advanced in-house design capabilities via Linde Engineering, and strict capital allocation disciplines. The group operates across on-site, merchant, and packaged delivery models, consistently executing contract-based energy cost pass-throughs and structural pricing adjustments across global merchant operations.
- L'Air Liquide S.A.: A global multinational focused on balanced exposure across industrial merchant, large industries (tonnage), electronics, and healthcare. Technological differentiation centers on proprietary CCUS systems (Cryocap), cryogenic engineering, and water electrolysis builds (such as the 200 MW ELYgator plant in the Port of Rotterdam). The strategic acquisition of DIG Airgas in South Korea and NovaAir in India demonstrates targeted consolidation of regional electronic and merchant positions.
- Air Products and Chemicals, Inc.: A major operator of industrial gas networks that has strategically prioritized world-scale energy transition projects, blue and green hydrogen megaprojects, and high-volume synthesis gas ventures across the Middle East, North America, and Europe. Air Products retains leading market shares in merchant hydrogen processing and syngas supply to refining complexes, supported by extensive equity affiliate joint ventures.
2. Mid-Tier and Regional Consolidators
- Nippon Sanso Holdings Corporation: The leading industrial gas group in Japan, controlling substantial market share through Taiyo Nippon Sanso, while operating global business footprints via Matheson Tri-Gas in the United States and Nippon Gases in Europe. The company holds strong technological differentiation in electronic specialty gases, stainless steel welding mixtures, and high-purity cylinder purification systems.
- Air Water Inc.: A major diversified Japanese conglomerate operating dense production networks across domestic basic chemicals, electronics, and agricultural logistics. The company has pursued targeted overseas expansions, building an operational presence in India and North America to support regional merchant gas and engineering requirements.
- Messer Group: The world's largest privately owned industrial gas specialist, maintaining strong competitive positions across Europe, China, and the Americas. Messer maintains a flexible operational model focused on merchant bulk liquid reliability, regional cylinder networks, and selective on-site tonnage plants.
- Hangzhou Oxygen Plant Group (Hangyang): The leading domestic air separation plant manufacturer and gas supplier in China. Hangyang has evolved from a pure-play machinery manufacturer into an integrated gas utility operator, expanding its portfolio of Build-Own-Operate on-site tonnage contracts across the chemical, metallurgical, and new energy segments.
-Other Mid-Tier and Regional Players incuding INOX Air Products Limited, SOL S.p.A.,PT Samator Indo Gas Tbk, Ellenbarrie Industrial Gases Ltd. (EIGL), Sapio Group, ADNOC Gas and Gulf Cryo, EuroChem Group, NIPPON STEEL Chemical & Material Co. Ltd., AirPower Technologies Limited, Yingde Gases Group, Suzhou Jinhong Gas, Guanggang Gases & Energy, Sichuan Qiaoyuan Gas, Hubei Heyuan Gas, Hunan Kaimeite Gases, Shanghai Huayi Industrial Gases, Pujiang International, Oriental Union Chemical Corporation [OUCC], Deokyang Energen, Taekyung Chemical, Approtium, SPG Hydrogen, Ghani Chemical Industries Limited, Pakistan Oxygen Limited, Koatsu Gas Kogyo, Koike Sanso Kogyo, Toho Acetylene.
3. Electronic Specialty Gas and High-Purity Material Producers
- Merck KGaA, Entegris, and Resonac: Premier global producers of ultra-high purity specialty chemistries, advanced atomic layer deposition precursors, sub-atmospheric cylinder packaging systems, and PFAS-free formulations for global semiconductor manufacturing.
- Specialized Asian Electronic Gas Leaders: SK specialty, WONIK MATERIALS, Ion Electronic Materials, Peric Special Gases, Guangdong Huate Gas, Jiangsu Nata Opto-electronic Material, Jiangsu Yoke Technology, Haohua Gas, Linggas, FOOSUNG, Central Glass, Sumitomo Seika Chemicals, Kanto Denka Kogyo, KNW, TEMC, Zhongjuxin Technology, REC Silicon, Henan Silane Technology Development.
STRATEGIC GROWTH VECTORS AND CAPITAL VULNERABILITIES
1. Strategic Growth Opportunities
- Decaptivation Momentum: The global transition away from captive asset ownership provides durable project pipelines. Steel, chemical, and non-ferrous manufacturing enterprises continue to divest legacy air separation infrastructure, contracting with industrial gas operators under 15- to 20-year BOO contracts. This shift unlocks capital for industrial customers while providing gas operators with multi-decade, inflation-indexed cash flow streams.
- Deepening Microelectronics Node Complexity: The expansion of sub-2nm foundry nodes, high-density 3D-NAND architectures (surpassing 200 physical tiers), and artificial intelligence hardware deployment requires exponential increases in gas purity and consumption volumes. Mega-fabs require dedicated, multi-loop carrier gas distribution systems delivering ultra-pure nitrogen, argon, and hydrogen with purity thresholds exceeding 99.9999%, alongside advanced organometallic precursors for atomic-level metallization.
- Low-Carbon Hydrogen and Industrial CCUS: Industrial gas majors are central participants in heavy industrial decarbonization. Through modular cryogenic separation (such as Air Liquide's Cryocap systems) and autothermal reforming with integrated carbon sequestration, gas operators provide hard-to-abate sectors (cement, blast furnace steel, and refining) with actionable compliance pathways against tightening international emissions policies.
2. Industry Headwinds and Capital Vulnerabilities
- Power and Feedstock Volatility: Electricity represents the primary cash operational expenditure in cryogenic atmospheric distillation, while natural gas governs reforming economics for hydrogen. Although long-term on-site contracts feature formulaic energy pass-through mechanisms, merchant bulk liquid and packaged cylinder segments face operational margin compression when energy cost spikes cannot be immediately recovered in price-sensitive downstream markets.
- Rare Gas and Helium Price Normalization: Elevated spot prices and supply volatility across 2022 and 2023 incentivized capacity additions that triggered price normalization for neon, krypton, xenon, and helium across 2024 and 2025. This dynamic has weighed on merchant revenue realizations across regional extraction hubs.
- Capital Expenditure Inflation and Execution Timelines: The deployment of mega-scale ASUs and autothermal reforming complexes requires substantial upfront capital. Large-scale air separation plants (>500 tons per day) demand significant capital investments, with project budgets challenged by equipment inflation, elevated borrowing costs, and protracted environmental permitting processes. These capital requirements present execution risks for project returns, prompting operators to maintain disciplined underwriting criteria for world-scale energy transition ventures.
- Geopolitical and Supply Chain Logistics Frictions: Regional conflicts and trade route disruptions in critical maritime corridors have periodically inflated bulk distribution freight expenses, disrupted merchant chemical utilization rates, and caused localized raw material imbalances. Managing these global exposures requires gas operators to maintain dynamic route density, flexible distribution assets, and disciplined contractual risk-sharing frameworks.
1.1 Research Objectives and Definitional Perimeter 1
1.2 Bottom-Up and Top-Down Data Modeling Methodologies 2
1.3 Primary Source Validation and Expert Consensus Delphi Panel 3
1.4 Secondary Knowledge Graphs and Trade Database Verification 4
1.5 Micro- and Macro-Economic Forecasting Assumptions (2027-2031) 5
1.6 Standard Terminology, Conversion Metrics and Abbreviations 6
Chapter 2 Global Industrial Gases Industry Ecosystem and Value Chain Architecture 7
2.1 End-to-End Value Chain Structural Topology 7
2.2 Upstream Sourcing: Power Grids, Feedstock Hydrocarbons and Atmospheric Separation Feeds 8
2.3 Midstream Processing, Liquefaction, Purification and Purification Yields 9
2.4 Downstream Integration: Pipeline Grids, Bulk Tankers and Packaged Cylinder Networks 10
2.5 Supply Chain Bottlenecks, Redundancy Protocols and Cost Accretion Breakdown 12
2.6 Environmental, Social, and Governance (ESG) Directives and Decarbonization Mandates 14
Chapter 3 Global Industrial Gases Market Dynamics, Capacity Trends and Technological Trajectories 15
3.1 Historical Volume and Revenue Matrix (2021-2025) and Base-Year Sizing (2026) 15
3.2 Structural Industry Transformation: Decarbonization, Electrolysis and Clean H2 Scaling 16
3.3 Cryogenic Air Separation Unit (ASU) Modularization vs. Mega-Scale Facility Economics 17
3.4 Non-Cryogenic On-Site Separation Technologies (Pressure Swing Adsorption & Membranes) 19
3.5 Energy Transition Dynamics: Power Purchase Agreements (PPAs) and Grid Volatility 20
3.6 Global Supply-Demand Balance, CapEx Cycles and Production Capacity Outlook (2027-2031) 22
Chapter 4 Global Industrial Gases Market by Commercial Supply Model 23
4.1 Commercial Supply Model Overview and Capital Intensity Profiles 23
4.2 On-Site and Pipeline Supply Networks 24
4.3 Merchant Bulk Liquid Distribution 26
4.4 Packaged and Cylinder Gases 28
4.5 Supply Model Comparative Sizing, Margin Realization and Growth Forecast (2021-2031) 30
Chapter 5 Global Industrial Gases Market by Product Type 31
5.1 Product Hierarchy and Molecular Split Matrix 31
5.2 Atmospheric Gases 32
5.2.1 Oxygen (Industrial, Medical, Ultra-High Purity) 32
5.2.2 Nitrogen (Gaseous Inerting, Liquid Cryogenic, Electronic Grades) 33
5.2.3 Argon (Standard Shielding, High-Purity Laser, Semiconductor Grades) 34
5.3 Process Gases and Syngas 35
5.3.1 Hydrogen (Steam Methane Reforming, By-Product Recovery, Green Water Electrolysis) 35
5.3.2 Carbon Dioxide (Capture, Purification, Sequestration and Food-Grade Recirculation) 36
5.3.3 Carbon Monoxide and Synthesis Gas (Syngas Complex Solutions) 37
5.4 Noble and Specialty Rare Gases 38
5.4.1 Helium (Primary Extraction, Trans-Oceanic ISO Container Logistics, Cryogenics) 38
5.4.2 Krypton, Xenon and Neon (Deep Cryogenic ASU Extraction and Lithography Feeds) 39
5.5 Other Specialized and Fluorinated Precursor Gases 40
5.6 Comparative Market Valuation, Pricing Elasticity and Forecast by Product Type (2021-2031) 41
Chapter 6 Global Industrial Gases Market by Downstream Application 42
6.1 Downstream Demand Taxonomy and Strategic End-Use Penetration 42
6.2 Chemicals and Petrochemicals 43
6.3 Steelmaking and Metallurgy 44
6.4 Refining and Midstream Energy 45
6.5 Electronics and Photovoltaics 46
6.6 Food and Beverage Processing 47
6.7 Healthcare and Life Sciences 48
6.8 Manufacturing and Automotive Engineering 49
6.9 Other Emerging Industrial Applications 50
Chapter 7 Global Trade Flows, Logistics Infrastructure and Cross-Border Interconnects 51
7.1 Global Trade Matrix for Bulk Liquefied and Specialty Rare Gases 51
7.2 Deep-Sea ISO Cryogenic Container Fleet Capacity and Port Terminal Bottlenecks 52
7.3 Pipeline Grid Interconnects Across Multi-Tenant Industrial Parks 53
7.4 Cross-Border Customs Regimes, Strategic Reserves and Export Control Frameworks 54
7.5 Tariff Structures, Geopolitical De-Risking and Freight Cost Fluctuations (2021-2026) 55
7.6 Regional Net Export/Import Balances and Trade Flow Projections (2027-2031) 56
Chapter 8 Global Regional Analysis: Production Hubs and Consumption Centers 57
8.1 Global Geographic Architecture and Macro-Regional Overview 57
8.2 North America 58
8.2.1 United States: Gulf Coast Petrochemical Hubs, Clean H2 Hubs and Chip Manufacturing 58
8.2.2 Canada: Resource Extraction, Metallurgical Refining and Merchant Sourcing 59
8.3 Europe 60
8.3.1 Germany, France and United Kingdom 60
8.3.2 Rest of Europe Market 61
8.4 Asia-Pacific 62
8.4.1 China: Mega-Scale ASUs, Heavy Industry Decarbonization and Coal-to-Chemicals 62
8.4.2 Japan and South Korea: Semiconductor Gas Precursors, Advanced Metallurgy and H2 63
8.4.3 India and Southeast Asia: Infrastructure Expansion, Steelmaking and Manufacturing 63
8.4.4 Taiwan (China): Advanced Semiconductor Foundry Fabs and Specialty Precursor Demand 64
8.5 Latin America and Middle East & Africa 64
8.5.1 Brazil and Mexico: Merchant Liquid Expansion and Manufacturing Modernization 64
8.5.2 Saudi Arabia and United Arab Emirates: Gas-to-Chemicals and Blue Hydrogen Hubs 64
Chapter 9 Competitive Landscape, Market Share Analysis and Strategic Positioning 65
9.1 Tier-1 Global Oligopoly vs. Regional Independent Operator Dynamics 65
9.2 Market Concentration Metrics: Herfindahl-Hirschman Index (HHI) (2021-2026) 66
9.3 Mergers, Acquisitions, Asset Divestments and Strategic Joint Ventures 67
9.4 Capital Expenditure Benchmarking and Capacity Growth Strategies (2027-2031) 68
Chapter 10 Enterprise Profiles and Competitive Benchmarking 69
10.1 Air Liquide 69
10.1.1 Enterprise Overview, Footprint and Strategic Positioning 69
10.1.2 SWOT Analysis and Vulnerability Profiling 70
10.1.3 Industrial Gases Financial Performance: Revenue, Cost and Gross Margin (2021-2026) 71
10.1.4 Global Market Share, CapEx and Technology Pipeline 72
10.2 Linde Plc. 73
10.2.1 Enterprise Overview, Footprint and Strategic Positioning 73
10.2.2 SWOT Analysis and Vulnerability Profiling 74
10.2.3 Industrial Gases Financial Performance: Revenue, Cost and Gross Margin (2021-2026) 75
10.2.4 Global Market Share, CapEx and Technology Pipeline 76
10.3 Air Products and Chemicals Inc. 77
10.3.1 Enterprise Overview, Footprint and Strategic Positioning 77
10.3.2 SWOT Analysis and Vulnerability Profiling 78
10.3.3 Industrial Gases Financial Performance: Revenue, Cost and Gross Margin (2021-2026) 79
10.3.4 Global Market Share, CapEx and Technology Pipeline 80
10.4 Nippon Sanso Holdings Corporation 81
10.4.1 Enterprise Overview, Footprint and Strategic Positioning 81
10.4.2 SWOT Analysis and Vulnerability Profiling 82
10.4.3 Industrial Gases Financial Performance: Revenue, Cost and Gross Margin (2021-2026) 83
10.4.4 Global Market Share, CapEx and Technology Pipeline 84
10.5 Air Water Inc 85
10.5.1 Enterprise Overview, Footprint and Strategic Positioning 85
10.5.2 SWOT Analysis and Vulnerability Profiling 86
10.5.3 Industrial Gases Financial Performance: Revenue, Cost and Gross Margin (2021-2026) 87
10.5.4 Global Market Share, CapEx and Technology Pipeline 88
10.6 Messer 89
10.6.1 Enterprise Overview, Footprint and Strategic Positioning 89
10.6.2 SWOT Analysis and Vulnerability Profiling 90
10.6.3 Industrial Gases Financial Performance: Revenue, Cost and Gross Margin (2021-2026) 91
10.6.4 Global Market Share, CapEx and Technology Pipeline 92
10.7 SOL S.p.A. 93
10.7.1 Enterprise Overview, Footprint and Strategic Positioning 93
10.7.2 SWOT Analysis and Vulnerability Profiling 94
10.7.3 Industrial Gases Financial Performance: Revenue, Cost and Gross Margin (2021-2026) 95
10.7.4 Global Market Share, CapEx and Technology Pipeline 96
10.8 AirPower Technologies Limited 97
10.8.1 Enterprise Overview, Footprint and Strategic Positioning 97
10.8.2 SWOT Analysis and Vulnerability Profiling 98
10.8.3 Industrial Gases Financial Performance: Revenue, Cost and Gross Margin (2021-2026) 99
10.8.4 Global Market Share, CapEx and Technology Pipeline 100
10.9 Koatsu Gas Kogyo Co. Ltd. 101
10.9.1 Enterprise Overview, Footprint and Strategic Positioning 101
10.9.2 SWOT Analysis and Vulnerability Profiling 102
10.9.3 Industrial Gases Financial Performance: Revenue, Cost and Gross Margin (2021-2026) 103
10.9.4 Global Market Share, CapEx and Technology Pipeline 104
10.10 Koike Sanso Kogyo Co. Ltd. 105
10.10.1 Enterprise Overview, Footprint and Strategic Positioning 105
10.10.2 SWOT Analysis and Vulnerability Profiling 106
10.10.3 Industrial Gases Financial Performance: Revenue, Cost and Gross Margin (2021-2026) 107
10.10.4 Global Market Share, CapEx and Technology Pipeline 108
10.11 Toho Acetylene Co. Ltd. 109
10.11.1 Enterprise Overview, Footprint and Strategic Positioning 109
10.11.2 SWOT Analysis and Vulnerability Profiling 110
10.11.3 Industrial Gases Financial Performance: Revenue, Cost and Gross Margin (2021-2026) 111
10.11.4 Global Market Share, CapEx and Technology Pipeline 112
10.12 Sapio Group 113
10.12.1 Enterprise Overview, Footprint and Strategic Positioning 113
10.12.2 SWOT Analysis and Vulnerability Profiling 114
10.12.3 Industrial Gases Financial Performance: Revenue, Cost and Gross Margin (2021-2026) 115
10.12.4 Global Market Share, CapEx and Technology Pipeline 116
10.13 Hangzhou Oxygen Plant Group 117
10.13.1 Enterprise Overview, Footprint and Strategic Positioning 117
10.13.2 SWOT Analysis and Vulnerability Profiling 118
10.13.3 Industrial Gases Financial Performance: Revenue, Cost and Gross Margin (2021-2026) 119
10.13.4 Global Market Share, CapEx and Technology Pipeline 120
10.14 Suzhou Jinhong Gas Co. Ltd 121
10.14.1 Enterprise Overview, Footprint and Strategic Positioning 121
10.14.2 SWOT Analysis and Vulnerability Profiling 122
10.14.3 Industrial Gases Financial Performance: Revenue, Cost and Gross Margin (2021-2026) 123
10.14.4 Global Market Share, CapEx and Technology Pipeline 124
10.15 Yingde Gases Group Company Limited 125
10.15.1 Enterprise Overview, Footprint and Strategic Positioning 125
10.15.2 SWOT Analysis and Vulnerability Profiling 126
10.15.3 Industrial Gases Financial Performance: Revenue, Cost and Gross Margin (2021-2026) 127
10.15.4 Global Market Share, CapEx and Technology Pipeline 128
10.16 NIPPON STEEL Chemical & Material Co. Ltd. 129
10.16.1 Enterprise Overview, Footprint and Strategic Positioning 129
10.16.2 SWOT Analysis and Vulnerability Profiling 130
10.16.3 Industrial Gases Financial Performance: Revenue, Cost and Gross Margin (2021-2026) 131
10.16.4 Global Market Share, CapEx and Technology Pipeline 132
10.17 EuroChem Group 133
10.17.1 Enterprise Overview, Footprint and Strategic Positioning 133
10.17.2 SWOT Analysis and Vulnerability Profiling 134
10.17.3 Industrial Gases Financial Performance: Revenue, Cost and Gross Margin (2021-2026) 135
10.17.4 Global Market Share, CapEx and Technology Pipeline 136
10.18 Ellenbarrie Industrial Gases Ltd. (EIGL) 137
10.18.1 Enterprise Overview, Footprint and Strategic Positioning 137
10.18.2 SWOT Analysis and Vulnerability Profiling 138
10.18.3 Industrial Gases Financial Performance: Revenue, Cost and Gross Margin (2021-2026) 139
10.18.4 Global Market Share, CapEx and Technology Pipeline 140
10.19 ADNOC Gas 141
10.19.1 Enterprise Overview, Footprint and Strategic Positioning 141
10.19.2 SWOT Analysis and Vulnerability Profiling 142
10.19.3 Industrial Gases Financial Performance: Revenue, Cost and Gross Margin (2021-2026) 143
10.19.4 Global Market Share, CapEx and Technology Pipeline 144
10.20 Gulf Cryo 145
10.20.1 Enterprise Overview, Footprint and Strategic Positioning 145
10.20.2 SWOT Analysis and Vulnerability Profiling 146
10.20.3 Industrial Gases Financial Performance: Revenue, Cost and Gross Margin (2021-2026) 147
10.20.4 Global Market Share, CapEx and Technology Pipeline 148
10.21 PT Samator Indo Gas Tbk 149
10.21.1 Enterprise Overview, Footprint and Strategic Positioning 149
10.21.2 SWOT Analysis and Vulnerability Profiling 150
10.21.3 Industrial Gases Financial Performance: Revenue, Cost and Gross Margin (2021-2026) 151
10.21.4 Global Market Share, CapEx and Technology Pipeline 152
10.22 Oriental Union Chemical Corporation (OUCC) 153
10.22.1 Enterprise Overview, Footprint and Strategic Positioning 153
10.22.2 SWOT Analysis and Vulnerability Profiling 154
10.22.3 Industrial Gases Financial Performance: Revenue, Cost and Gross Margin (2021-2026) 155
10.22.4 Global Market Share, CapEx and Technology Pipeline 156
10.23 Inox Air Products Limited 157
10.23.1 Enterprise Overview, Footprint and Strategic Positioning 157
10.23.2 SWOT Analysis and Vulnerability Profiling 158
10.23.3 Industrial Gases Financial Performance: Revenue, Cost and Gross Margin (2021-2026) 159
10.23.4 Global Market Share, CapEx and Technology Pipeline 160
10.24 Deokyang Energen Co. Ltd. 161
10.24.1 Enterprise Overview, Footprint and Strategic Positioning 161
10.24.2 SWOT Analysis and Vulnerability Profiling 162
10.24.3 Industrial Gases Financial Performance: Revenue, Cost and Gross Margin (2021-2026) 163
10.24.4 Global Market Share, CapEx and Technology Pipeline 164
10.25 Taekyung Chemical Co. Ltd. 165
10.25.1 Enterprise Overview, Footprint and Strategic Positioning 165
10.25.2 SWOT Analysis and Vulnerability Profiling 166
10.25.3 Industrial Gases Financial Performance: Revenue, Cost and Gross Margin (2021-2026) 167
10.25.4 Global Market Share, CapEx and Technology Pipeline 168
10.26 Approtium 169
10.26.1 Enterprise Overview, Footprint and Strategic Positioning 169
10.26.2 SWOT Analysis and Vulnerability Profiling 170
10.26.3 Industrial Gases Financial Performance: Revenue, Cost and Gross Margin (2021-2026) 171
10.26.4 Global Market Share, CapEx and Technology Pipeline 172
10.27 SPG Hydrogen Co. Ltd. 173
10.27.1 Enterprise Overview, Footprint and Strategic Positioning 173
10.27.2 SWOT Analysis and Vulnerability Profiling 174
10.27.3 Industrial Gases Financial Performance: Revenue, Cost and Gross Margin (2021-2026) 175
10.27.4 Global Market Share, CapEx and Technology Pipeline 176
10.28 Sichuan Qiaoyuan Gas Co. Ltd. 177
10.28.1 Enterprise Overview, Footprint and Strategic Positioning 177
10.28.2 SWOT Analysis and Vulnerability Profiling 178
10.28.3 Industrial Gases Financial Performance: Revenue, Cost and Gross Margin (2021-2026) 179
10.28.4 Global Market Share, CapEx and Technology Pipeline 180
10.29 Guanggang Gases & Energy 181
10.29.1 Enterprise Overview, Footprint and Strategic Positioning 181
10.29.2 SWOT Analysis and Vulnerability Profiling 182
10.29.3 Industrial Gases Financial Performance: Revenue, Cost and Gross Margin (2021-2026) 183
10.29.4 Global Market Share, CapEx and Technology Pipeline 184
10.30 Hubei Heyuan Gas Co. Ltd. 185
10.30.1 Enterprise Overview, Footprint and Strategic Positioning 185
10.30.2 SWOT Analysis and Vulnerability Profiling 186
10.30.3 Industrial Gases Financial Performance: Revenue, Cost and Gross Margin (2021-2026) 187
10.30.4 Global Market Share, CapEx and Technology Pipeline 188
10.31 Hunan Kaimeite Gases Co Ltd 189
10.31.1 Enterprise Overview, Footprint and Strategic Positioning 189
10.31.2 SWOT Analysis and Vulnerability Profiling 190
10.31.3 Industrial Gases Financial Performance: Revenue, Cost and Gross Margin (2021-2026) 191
10.31.4 Global Market Share, CapEx and Technology Pipeline 192
10.32 Pujiang International Group Limited 193
10.32.1 Enterprise Overview, Footprint and Strategic Positioning 193
10.32.2 SWOT Analysis and Vulnerability Profiling 194
10.32.3 Industrial Gases Financial Performance: Revenue, Cost and Gross Margin (2021-2026) 195
10.32.4 Global Market Share, CapEx and Technology Pipeline 196
10.33 Shanghai Huayi Industrial Gases Co. Ltd. 197
10.33.1 Enterprise Overview, Footprint and Strategic Positioning 197
10.33.2 SWOT Analysis and Vulnerability Profiling 198
10.33.3 Industrial Gases Financial Performance: Revenue, Cost and Gross Margin (2021-2026) 199
10.33.4 Global Market Share, CapEx and Technology Pipeline 200
10.34 Merck KGaA 201
10.34.1 Enterprise Overview, Footprint and Strategic Positioning 201
10.34.2 SWOT Analysis and Vulnerability Profiling 202
10.34.3 Industrial Gases Financial Performance: Revenue, Cost and Gross Margin (2021-2026) 203
10.34.4 Global Market Share, CapEx and Technology Pipeline 204
10.35 Entegris 205
10.35.1 Enterprise Overview, Footprint and Strategic Positioning 205
10.35.2 SWOT Analysis and Vulnerability Profiling 206
10.35.3 Industrial Gases Financial Performance: Revenue, Cost and Gross Margin (2021-2026) 207
10.35.4 Global Market Share, CapEx and Technology Pipeline 208
10.36 Resonac 209
10.36.1 Enterprise Overview, Footprint and Strategic Positioning 209
10.36.2 SWOT Analysis and Vulnerability Profiling 210
10.36.3 Industrial Gases Financial Performance: Revenue, Cost and Gross Margin (2021-2026) 211
10.36.4 Global Market Share, CapEx and Technology Pipeline 212
10.37 WONIK MATERIALS 213
10.37.1 Enterprise Overview, Footprint and Strategic Positioning 213
10.37.2 SWOT Analysis and Vulnerability Profiling 214
10.37.3 Industrial Gases Financial Performance: Revenue, Cost and Gross Margin (2021-2026) 215
10.37.4 Global Market Share, CapEx and Technology Pipeline 216
10.38 SK specialty Co. Ltd. 217
10.38.1 Enterprise Overview, Footprint and Strategic Positioning 217
10.38.2 SWOT Analysis and Vulnerability Profiling 218
10.38.3 Industrial Gases Financial Performance: Revenue, Cost and Gross Margin (2021-2026) 219
10.38.4 Global Market Share, CapEx and Technology Pipeline 220
10.39 Ion Electronic Materials Co. Ltd. 221
10.39.1 Enterprise Overview, Footprint and Strategic Positioning 221
10.39.2 SWOT Analysis and Vulnerability Profiling 222
10.39.3 Industrial Gases Financial Performance: Revenue, Cost and Gross Margin (2021-2026) 223
10.39.4 Global Market Share, CapEx and Technology Pipeline 224
10.40 Peric Special Gases Co. Ltd. 225
10.40.1 Enterprise Overview, Footprint and Strategic Positioning 225
10.40.2 SWOT Analysis and Vulnerability Profiling 226
10.40.3 Industrial Gases Financial Performance: Revenue, Cost and Gross Margin (2021-2026) 227
10.40.4 Global Market Share, CapEx and Technology Pipeline 228
10.41 Guangdong Huate Gas Co. Ltd 229
10.41.1 Enterprise Overview, Footprint and Strategic Positioning 229
10.41.2 SWOT Analysis and Vulnerability Profiling 230
10.41.3 Industrial Gases Financial Performance: Revenue, Cost and Gross Margin (2021-2026) 231
10.41.4 Global Market Share, CapEx and Technology Pipeline 232
10.42 Jiangsu Nata Opto-electronic Material Co. Ltd. 233
10.42.1 Enterprise Overview, Footprint and Strategic Positioning 233
10.42.2 SWOT Analysis and Vulnerability Profiling 234
10.42.3 Industrial Gases Financial Performance: Revenue, Cost and Gross Margin (2021-2026) 235
10.42.4 Global Market Share, CapEx and Technology Pipeline 236
10.43 Jiangsu Yoke Technology Co. Ltd. 237
10.43.1 Enterprise Overview, Footprint and Strategic Positioning 237
10.43.2 SWOT Analysis and Vulnerability Profiling 238
10.43.3 Industrial Gases Financial Performance: Revenue, Cost and Gross Margin (2021-2026) 239
10.43.4 Global Market Share, CapEx and Technology Pipeline 240
10.44 Haohua Gas Co. Ltd. 241
10.44.1 Enterprise Overview, Footprint and Strategic Positioning 241
10.44.2 SWOT Analysis and Vulnerability Profiling 242
10.44.3 Industrial Gases Financial Performance: Revenue, Cost and Gross Margin (2021-2026) 243
10.44.4 Global Market Share, CapEx and Technology Pipeline 244
10.45 Linggas Ltd 245
10.45.1 Enterprise Overview, Footprint and Strategic Positioning 245
10.45.2 SWOT Analysis and Vulnerability Profiling 246
10.45.3 Industrial Gases Financial Performance: Revenue, Cost and Gross Margin (2021-2026) 247
10.45.4 Global Market Share, CapEx and Technology Pipeline 248
10.46 FOOSUNG Co. Ltd. 249
10.46.1 Enterprise Overview, Footprint and Strategic Positioning 249
10.46.2 SWOT Analysis and Vulnerability Profiling 250
10.46.3 Industrial Gases Financial Performance: Revenue, Cost and Gross Margin (2021-2026) 251
10.46.4 Global Market Share, CapEx and Technology Pipeline 252
10.47 Ghani Chemical Industries Limited 253
10.47.1 Enterprise Overview, Footprint and Strategic Positioning 253
10.47.2 SWOT Analysis and Vulnerability Profiling 254
10.47.3 Industrial Gases Financial Performance: Revenue, Cost and Gross Margin (2021-2026) 255
10.47.4 Global Market Share, CapEx and Technology Pipeline 256
10.48 Pakistan Oxygen Limited 257
10.48.1 Enterprise Overview, Footprint and Strategic Positioning 257
10.48.2 SWOT Analysis and Vulnerability Profiling 258
10.48.3 Industrial Gases Financial Performance: Revenue, Cost and Gross Margin (2021-2026) 259
10.48.4 Global Market Share, CapEx and Technology Pipeline 260
10.49 Kanto Denka Kogyo Co. Ltd. 261
10.49.1 Enterprise Overview, Footprint and Strategic Positioning 261
10.49.2 SWOT Analysis and Vulnerability Profiling 262
10.49.3 Industrial Gases Financial Performance: Revenue, Cost and Gross Margin (2021-2026) 263
10.49.4 Global Market Share, CapEx and Technology Pipeline 264
10.50 KNW Co. Ltd. 265
10.50.1 Enterprise Overview, Footprint and Strategic Positioning 265
10.50.2 SWOT Analysis and Vulnerability Profiling 266
10.50.3 Industrial Gases Financial Performance: Revenue, Cost and Gross Margin (2021-2026) 267
10.50.4 Global Market Share, CapEx and Technology Pipeline 268
10.51 Central Glass 269
10.51.1 Enterprise Overview, Footprint and Strategic Positioning 269
10.51.2 SWOT Analysis and Vulnerability Profiling 270
10.51.3 Industrial Gases Financial Performance: Revenue, Cost and Gross Margin (2021-2026) 271
10.51.4 Global Market Share, CapEx and Technology Pipeline 272
10.52 Sumitomo Seika Chemicals 273
10.52.1 Enterprise Overview, Footprint and Strategic Positioning 273
10.52.2 SWOT Analysis and Vulnerability Profiling 274
10.52.3 Industrial Gases Financial Performance: Revenue, Cost and Gross Margin (2021-2026) 275
10.52.4 Global Market Share, CapEx and Technology Pipeline 276
10.53 TEMC Co. Ltd. 277
10.53.1 Enterprise Overview, Footprint and Strategic Positioning 277
10.53.2 SWOT Analysis and Vulnerability Profiling 278
10.53.3 Industrial Gases Financial Performance: Revenue, Cost and Gross Margin (2021-2026) 279
10.53.4 Global Market Share, CapEx and Technology Pipeline 280
10.54 Zhongjuxin Technology 281
10.54.1 Enterprise Overview, Footprint and Strategic Positioning 281
10.54.2 SWOT Analysis and Vulnerability Profiling 282
10.54.3 Industrial Gases Financial Performance: Revenue, Cost and Gross Margin (2021-2026) 283
10.54.4 Global Market Share, CapEx and Technology Pipeline 284
10.55 REC Silicon 285
10.55.1 Enterprise Overview, Footprint and Strategic Positioning 285
10.55.2 SWOT Analysis and Vulnerability Profiling 286
10.55.3 Industrial Gases Financial Performance: Revenue, Cost and Gross Margin (2021-2026) 287
10.55.4 Global Market Share, CapEx and Technology Pipeline 288
10.56 Henan Silane Technology Development 289
10.56.1 Enterprise Overview, Footprint and Strategic Positioning 289
10.56.2 SWOT Analysis and Vulnerability Profiling 290
10.56.3 Industrial Gases Financial Performance: Revenue, Cost and Gross Margin (2021-2026) 291
10.56.4 Global Market Share, CapEx and Technology Pipeline 292
Table 2 Cost Structure Breakdown Across Atmospheric and Synthesized Industrial Gases (2021-2026) 13
Table 3 Global Industrial Gases Production Capacity and Installed ASU Fleet by Region (2021-2031) 21
Table 4 Global Industrial Gases Market Revenue by Commercial Supply Model (USD Billion, 2021-2031) 30
Table 5 Global Industrial Gases Market Volume by Commercial Supply Model (Million Metric Tons, 2021-2031) 30
Table 6 Global Industrial Gases Market Revenue by Product Type (USD Billion, 2021-2031) 41
Table 7 Global Industrial Gases Market Volume by Product Type (Million Metric Tons, 2021-2031) 41
Table 8 Global Industrial Gases Market Revenue by Downstream Application (USD Billion, 2021-2031) 50
Table 9 Major Cross-Border Seaborne Trade Routes for Helium and Rare Gases (2021-2026) 55
Table 10 Global Industrial Gases Market Value by Region (USD Billion, 2021-2031) 57
Table 11 North America Industrial Gases Market Revenue by Country (USD Billion, 2021-2031) 59
Table 12 Europe Industrial Gases Market Revenue by Country (USD Billion, 2021-2031) 61
Table 13 Asia-Pacific Industrial Gases Market Revenue by Country/Region (USD Billion, 2021-2031) 63
Table 14 Global Industrial Gases Producer Market Share Concentration and HHI Score (2021-2026) 66
Table 15 Air Liquide Industrial Gases Revenue, Cost and Gross Margin (2021-2026) 71
Table 16 Linde Plc. Industrial Gases Revenue, Cost and Gross Margin (2021-2026) 75
Table 17 Air Products and Chemicals Inc. Industrial Gases Revenue, Cost and Gross Margin (2021-2026) 79
Table 18 Nippon Sanso Holdings Corporation Industrial Gases Revenue, Cost and Gross Margin (2021-2026) 83
Table 19 Air Water Inc Industrial Gases Revenue, Cost and Gross Margin (2021-2026) 87
Table 20 Messer Industrial Gases Revenue, Cost and Gross Margin (2021-2026) 91
Table 21 SOL S.p.A. Industrial Gases Revenue, Cost and Gross Margin (2021-2026) 95
Table 22 AirPower Technologies Limited Industrial Gases Revenue, Cost and Gross Margin (2021-2026) 99
Table 23 Koatsu Gas Kogyo Co. Ltd. Industrial Gases Revenue, Cost and Gross Margin (2021-2026) 103
Table 24 Koike Sanso Kogyo Co. Ltd. Industrial Gases Revenue, Cost and Gross Margin (2021-2026) 107
Table 25 Toho Acetylene Co. Ltd. Industrial Gases Revenue, Cost and Gross Margin (2021-2026) 111
Table 26 Sapio Group Industrial Gases Revenue, Cost and Gross Margin (2021-2026) 115
Table 27 Hangzhou Oxygen Plant Group Industrial Gases Revenue, Cost and Gross Margin (2021-2026) 119
Table 28 Suzhou Jinhong Gas Co. Ltd Industrial Gases Revenue, Cost and Gross Margin (2021-2026) 123
Table 29 Yingde Gases Group Company Limited Industrial Gases Revenue, Cost and Gross Margin (2021-2026) 127
Table 30 NIPPON STEEL Chemical & Material Co. Ltd. Industrial Gases Revenue, Cost and Gross Margin (2021-2026) 131
Table 31 EuroChem Group Industrial Gases Revenue, Cost and Gross Margin (2021-2026) 135
Table 32 Ellenbarrie Industrial Gases Ltd. (EIGL) Industrial Gases Revenue, Cost and Gross Margin (2021-2026) 139
Table 33 ADNOC Gas Industrial Gases Revenue, Cost and Gross Margin (2021-2026) 143
Table 34 Gulf Cryo Industrial Gases Revenue, Cost and Gross Margin (2021-2026) 147
Table 35 PT Samator Indo Gas Tbk Industrial Gases Revenue, Cost and Gross Margin (2021-2026) 151
Table 36 Oriental Union Chemical Corporation (OUCC) Industrial Gases Revenue, Cost and Gross Margin (2021-2026) 155
Table 37 Inox Air Products Limited Industrial Gases Revenue, Cost and Gross Margin (2021-2026) 159
Table 38 Deokyang Energen Co. Ltd. Industrial Gases Revenue, Cost and Gross Margin (2021-2026) 163
Table 39 Taekyung Chemical Co. Ltd. Industrial Gases Revenue, Cost and Gross Margin (2021-2026) 167
Table 40 Approtium Industrial Gases Revenue, Cost and Gross Margin (2021-2026) 171
Table 41 SPG Hydrogen Co. Ltd. Industrial Gases Revenue, Cost and Gross Margin (2021-2026) 175
Table 42 Sichuan Qiaoyuan Gas Co. Ltd. Industrial Gases Revenue, Cost and Gross Margin (2021-2026) 179
Table 43 Guanggang Gases & Energy Industrial Gases Revenue, Cost and Gross Margin (2021-2026) 183
Table 44 Hubei Heyuan Gas Co. Ltd. Industrial Gases Revenue, Cost and Gross Margin (2021-2026) 187
Table 45 Hunan Kaimeite Gases Co Ltd Industrial Gases Revenue, Cost and Gross Margin (2021-2026) 191
Table 46 Pujiang International Group Limited Industrial Gases Revenue, Cost and Gross Margin (2021-2026) 195
Table 47 Shanghai Huayi Industrial Gases Co. Ltd. Industrial Gases Revenue, Cost and Gross Margin (2021-2026) 199
Table 48 Merck KGaA Industrial Gases Revenue, Cost and Gross Margin (2021-2026) 203
Table 49 Entegris Industrial Gases Revenue, Cost and Gross Margin (2021-2026) 207
Table 50 Resonac Industrial Gases Revenue, Cost and Gross Margin (2021-2026) 211
Table 51 WONIK MATERIALS Industrial Gases Revenue, Cost and Gross Margin (2021-2026) 215
Table 52 SK specialty Co. Ltd. Industrial Gases Revenue, Cost and Gross Margin (2021-2026) 219
Table 53 Ion Electronic Materials Co. Ltd. Industrial Gases Revenue, Cost and Gross Margin (2021-2026) 223
Table 54 Peric Special Gases Co. Ltd. Industrial Gases Revenue, Cost and Gross Margin (2021-2026) 227
Table 55 Guangdong Huate Gas Co. Ltd Industrial Gases Revenue, Cost and Gross Margin (2021-2026) 231
Table 56 Jiangsu Nata Opto-electronic Material Co. Ltd. Industrial Gases Revenue, Cost and Gross Margin (2021-2026) 235
Table 57 Jiangsu Yoke Technology Co. Ltd. Industrial Gases Revenue, Cost and Gross Margin (2021-2026) 239
Table 58 Haohua Gas Co. Ltd. Industrial Gases Revenue, Cost and Gross Margin (2021-2026) 243
Table 59 Linggas Ltd Industrial Gases Revenue, Cost and Gross Margin (2021-2026) 247
Table 60 FOOSUNG Co. Ltd. Industrial Gases Revenue, Cost and Gross Margin (2021-2026) 251
Table 61 Ghani Chemical Industries Limited Industrial Gases Revenue, Cost and Gross Margin (2021-2026) 255
Table 62 Pakistan Oxygen Limited Industrial Gases Revenue, Cost and Gross Margin (2021-2026) 259
Table 63 Kanto Denka Kogyo Co. Ltd. Industrial Gases Revenue, Cost and Gross Margin (2021-2026) 263
Table 64 KNW Co. Ltd. Industrial Gases Revenue, Cost and Gross Margin (2021-2026) 267
Table 65 Central Glass Industrial Gases Revenue, Cost and Gross Margin (2021-2026) 271
Table 66 Sumitomo Seika Chemicals Industrial Gases Revenue, Cost and Gross Margin (2021-2026) 275
Table 67 TEMC Co. Ltd. Industrial Gases Revenue, Cost and Gross Margin (2021-2026) 279
Table 68 Zhongjuxin Technology Industrial Gases Revenue, Cost and Gross Margin (2021-2026) 283
Table 69 REC Silicon Industrial Gases Revenue, Cost and Gross Margin (2021-2026) 287
Table 70 Henan Silane Technology Development Industrial Gases Revenue, Cost and Gross Margin (2021-2026) 291
Figure 1 Global Industrial Gases End-to-End Value Chain Map 8
Figure 2 Levelized Cost of Production Architecture for Air Separation Units 11
Figure 3 Global Industrial Gases Historical and Forecast Market Size (USD Billion, 2021-2031) 16
Figure 4 Clean Hydrogen Production Scaling and SMR Decarbonization Pathways 18
Figure 5 Global Industrial Gases Market Share by Commercial Supply Model (2026) 23
Figure 6 On-Site vs. Merchant Bulk vs. Packaged Gas Gross Margin Variance Curve (2021-2026) 29
Figure 7 Global Industrial Gases Revenue Contribution by Product Type (2026) 31
Figure 8 Electronic Specialty Gases vs. Bulk Industrial Gases Pricing Volatility Index 40
Figure 9 Downstream Demand Share Matrix by Sector (2026) 42
Figure 10 Electronics and Semiconductor Segment Consumption Trajectory (2021-2031) 47
Figure 11 Global Liquefied Rare Gases and Merchant Liquid Seaborne Logistics Corridors 52
Figure 12 Regional Industrial Gases Revenue Share Matrix (2026) 57
Figure 13 Tier-1 Industrial Gas Oligopoly Global Market Share Structure (2026) 65
Figure 14 Air Liquide Industrial Gases Market Share (2021-2026) 72
Figure 15 Linde Plc. Industrial Gases Market Share (2021-2026) 76
Figure 16 Air Products and Chemicals Inc. Industrial Gases Market Share (2021-2026) 80
Figure 17 Nippon Sanso Holdings Corporation Industrial Gases Market Share (2021-2026) 84
Figure 18 Air Water Inc Industrial Gases Market Share (2021-2026) 88
Figure 19 Messer Industrial Gases Market Share (2021-2026) 92
Figure 20 SOL S.p.A. Industrial Gases Market Share (2021-2026) 96
Figure 21 AirPower Technologies Limited Industrial Gases Market Share (2021-2026) 100
Figure 22 Koatsu Gas Kogyo Co. Ltd. Industrial Gases Market Share (2021-2026) 104
Figure 23 Koike Sanso Kogyo Co. Ltd. Industrial Gases Market Share (2021-2026) 108
Figure 24 Toho Acetylene Co. Ltd. Industrial Gases Market Share (2021-2026) 112
Figure 25 Sapio Group Industrial Gases Market Share (2021-2026) 116
Figure 26 Hangzhou Oxygen Plant Group Industrial Gases Market Share (2021-2026) 120
Figure 27 Suzhou Jinhong Gas Co. Ltd Industrial Gases Market Share (2021-2026) 124
Figure 28 Yingde Gases Group Company Limited Industrial Gases Market Share (2021-2026) 128
Figure 29 NIPPON STEEL Chemical & Material Co. Ltd. Industrial Gases Market Share (2021-2026) 132
Figure 30 EuroChem Group Industrial Gases Market Share (2021-2026) 136
Figure 31 Ellenbarrie Industrial Gases Ltd. (EIGL) Industrial Gases Market Share (2021-2026) 140
Figure 32 ADNOC Gas Industrial Gases Market Share (2021-2026) 144
Figure 33 Gulf Cryo Industrial Gases Market Share (2021-2026) 148
Figure 34 PT Samator Indo Gas Tbk Industrial Gases Market Share (2021-2026) 152
Figure 35 Oriental Union Chemical Corporation (OUCC) Industrial Gases Market Share (2021-2026) 156
Figure 36 Inox Air Products Limited Industrial Gases Market Share (2021-2026) 160
Figure 37 Deokyang Energen Co. Ltd. Industrial Gases Market Share (2021-2026) 164
Figure 38 Taekyung Chemical Co. Ltd. Industrial Gases Market Share (2021-2026) 168
Figure 39 Approtium Industrial Gases Market Share (2021-2026) 172
Figure 40 SPG Hydrogen Co. Ltd. Industrial Gases Market Share (2021-2026) 176
Figure 41 Sichuan Qiaoyuan Gas Co. Ltd. Industrial Gases Market Share (2021-2026) 180
Figure 42 Guanggang Gases & Energy Industrial Gases Market Share (2021-2026) 184
Figure 43 Hubei Heyuan Gas Co. Ltd. Industrial Gases Market Share (2021-2026) 188
Figure 44 Hunan Kaimeite Gases Co Ltd Industrial Gases Market Share (2021-2026) 192
Figure 45 Pujiang International Group Limited Industrial Gases Market Share (2021-2026) 196
Figure 46 Shanghai Huayi Industrial Gases Co. Ltd. Industrial Gases Market Share (2021-2026) 200
Figure 47 Merck KGaA Industrial Gases Market Share (2021-2026) 204
Figure 48 Entegris Industrial Gases Market Share (2021-2026) 208
Figure 49 Resonac Industrial Gases Market Share (2021-2026) 212
Figure 50 WONIK MATERIALS Industrial Gases Market Share (2021-2026) 216
Figure 51 SK specialty Co. Ltd. Industrial Gases Market Share (2021-2026) 220
Figure 52 Ion Electronic Materials Co. Ltd. Industrial Gases Market Share (2021-2026) 224
Figure 53 Peric Special Gases Co. Ltd. Industrial Gases Market Share (2021-2026) 228
Figure 54 Guangdong Huate Gas Co. Ltd Industrial Gases Market Share (2021-2026) 232
Figure 55 Jiangsu Nata Opto-electronic Material Co. Ltd. Industrial Gases Market Share (2021-2026) 236
Figure 56 Jiangsu Yoke Technology Co. Ltd. Industrial Gases Market Share (2021-2026) 240
Figure 57 Haohua Gas Co. Ltd. Industrial Gases Market Share (2021-2026) 244
Figure 58 Linggas Ltd Industrial Gases Market Share (2021-2026) 248
Figure 59 FOOSUNG Co. Ltd. Industrial Gases Market Share (2021-2026) 252
Figure 60 Ghani Chemical Industries Limited Industrial Gases Market Share (2021-2026) 256
Figure 61 Pakistan Oxygen Limited Industrial Gases Market Share (2021-2026) 260
Figure 62 Kanto Denka Kogyo Co. Ltd. Industrial Gases Market Share (2021-2026) 264
Figure 63 KNW Co. Ltd. Industrial Gases Market Share (2021-2026) 268
Figure 64 Central Glass Industrial Gases Market Share (2021-2026) 272
Figure 65 Sumitomo Seika Chemicals Industrial Gases Market Share (2021-2026) 276
Figure 66 TEMC Co. Ltd. Industrial Gases Market Share (2021-2026) 280
Figure 67 Zhongjuxin Technology Industrial Gases Market Share (2021-2026) 284
Figure 68 REC Silicon Industrial Gases Market Share (2021-2026) 288
Figure 69 Henan Silane Technology Development Industrial Gases Market Share (2021-2026) 292
Research Methodology
- Market Estimated Methodology:
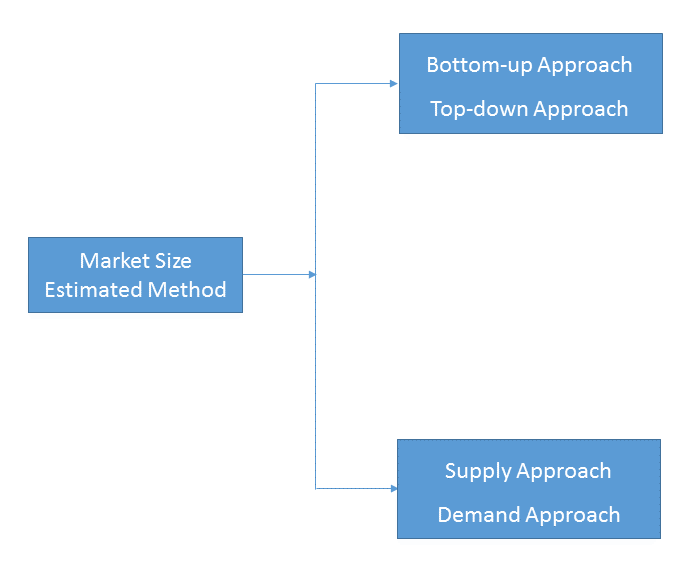
Bottom-up & top-down approach, supply & demand approach are the most important method which is used by HDIN Research to estimate the market size.
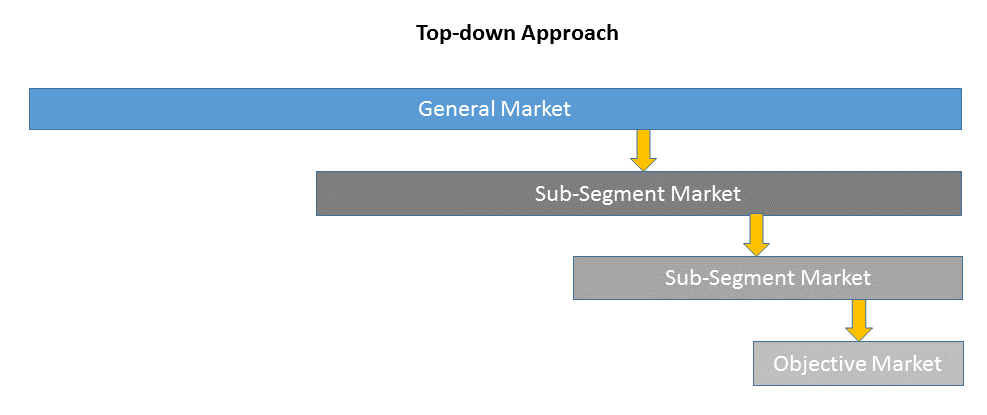
1)Top-down & Bottom-up Approach
Top-down approach uses a general market size figure and determines the percentage that the objective market represents.
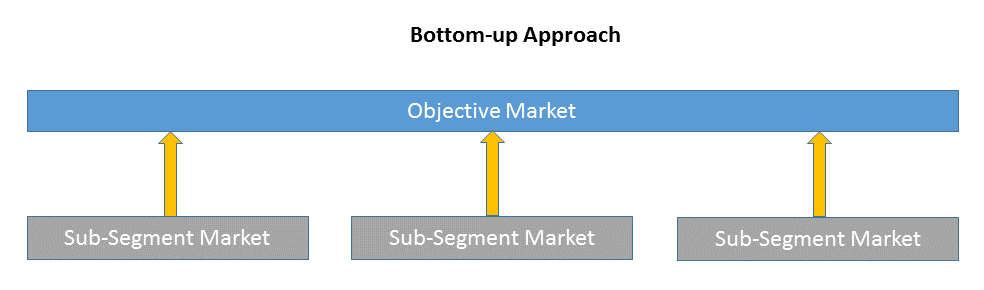
Bottom-up approach size the objective market by collecting the sub-segment information.
2)Supply & Demand Approach
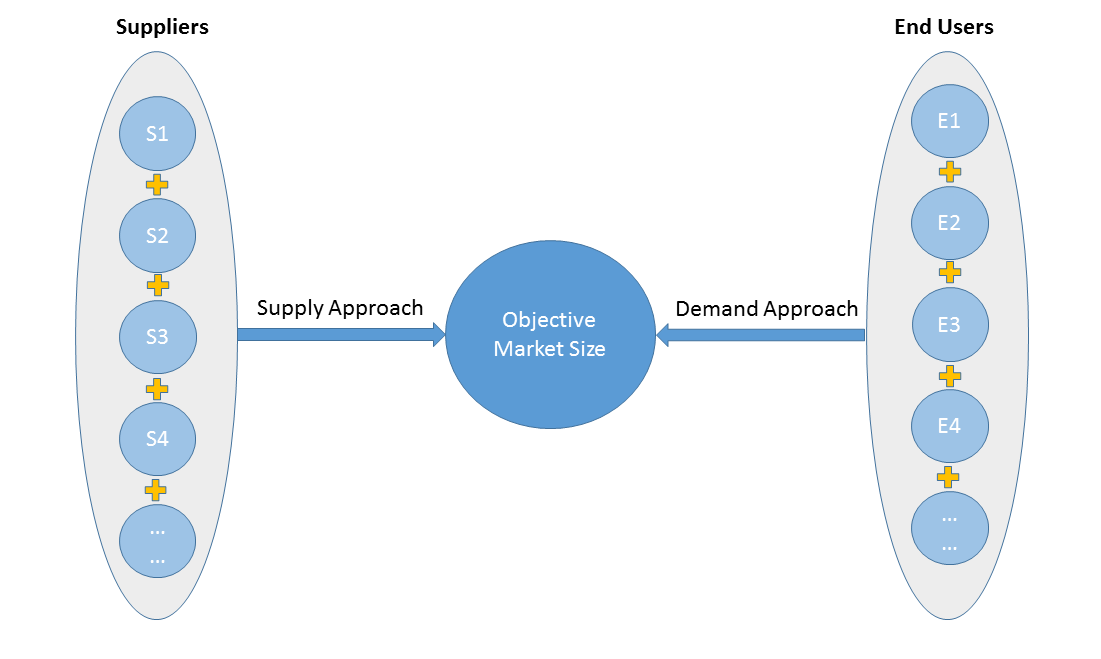
Supply approach is based on assessments of the size of each competitor supplying the objective market.
Demand approach combine end-user data within a market to estimate the objective market size. It is sometimes referred to as bottom-up approach.
- Forecasting Methodology
- Numerous factors impacting the market trend are considered for forecast model:
- New technology and application in the future;
- New project planned/under contraction;
- Global and regional underlying economic growth;
- Threatens of substitute products;
- Industry expert opinion;
- Policy and Society implication.
- Analysis Tools
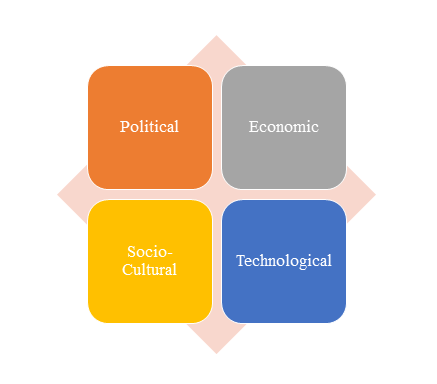
1)PEST Analysis
PEST Analysis is a simple and widely used tool that helps our client analyze the Political, Economic, Socio-Cultural, and Technological changes in their business environment.
- Benefits of a PEST analysis:
- It helps you to spot business opportunities, and it gives you advanced warning of significant threats.
- It reveals the direction of change within your business environment. This helps you shape what you’re doing, so that you work with change, rather than against it.
- It helps you avoid starting projects that are likely to fail, for reasons beyond your control.
- It can help you break free of unconscious assumptions when you enter a new country, region, or market; because it helps you develop an objective view of this new environment.
2)Porter’s Five Force Model Analysis
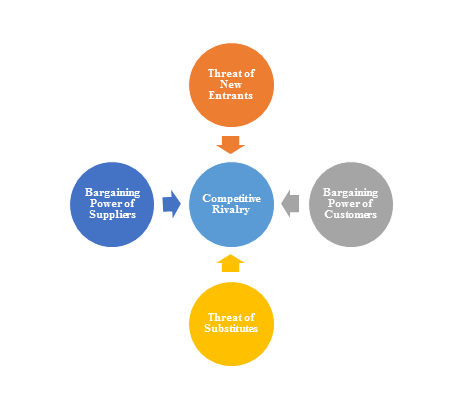
The Porter’s Five Force Model is a tool that can be used to analyze the opportunities and overall competitive advantage. The five forces that can assist in determining the competitive intensity and potential attractiveness within a specific area.
- Threat of New Entrants: Profitable industries that yield high returns will attract new firms.
- Threat of Substitutes: A substitute product uses a different technology to try to solve the same economic need.
- Bargaining Power of Customers: the ability of customers to put the firm under pressure, which also affects the customer's sensitivity to price changes.
- Bargaining Power of Suppliers: Suppliers of raw materials, components, labor, and services (such as expertise) to the firm can be a source of power over the firm when there are few substitutes.
- Competitive Rivalry: For most industries the intensity of competitive rivalry is the major determinant of the competitiveness of the industry.
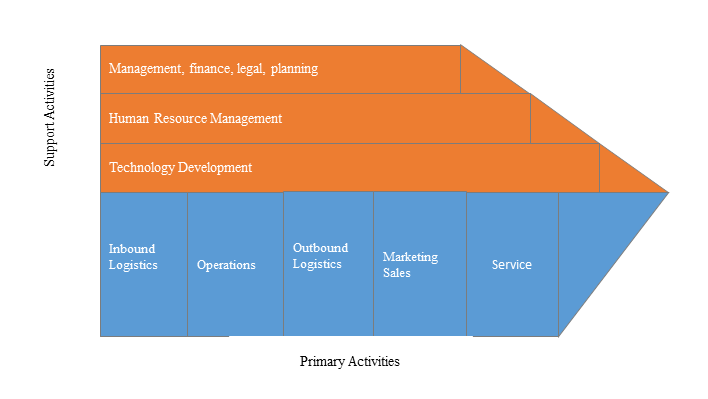
3)Value Chain Analysis
Value chain analysis is a tool to identify activities, within and around the firm and relating these activities to an assessment of competitive strength. Value chain can be analyzed by primary activities and supportive activities. Primary activities include: inbound logistics, operations, outbound logistics, marketing & sales, service. Support activities include: technology development, human resource management, management, finance, legal, planning.
4)SWOT Analysis
SWOT analysis is a tool used to evaluate a company's competitive position by identifying its strengths, weaknesses, opportunities and threats. The strengths and weakness is the inner factor; the opportunities and threats are the external factor. By analyzing the inner and external factors, the analysis can provide the detail information of the position of a player and the characteristics of the industry.
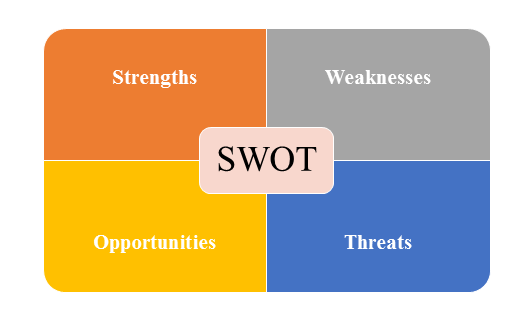
- Strengths describe what the player excels at and separates it from the competition
- Weaknesses stop the player from performing at its optimum level.
- Opportunities refer to favorable external factors that the player can use to give it a competitive advantage.
- Threats refer to factors that have the potential to harm the player.
- Data Sources
| Primary Sources | Secondary Sources |
|---|---|
| Face to face/Phone Interviews with market participants, such as: Manufactures; Distributors; End-users; Experts. Online Survey |
Government/International Organization Data: Annual Report/Presentation/Fact Book Internet Source Information Industry Association Data Free/Purchased Database Market Research Report Book/Journal/News |