Electronic Speciality Gases Market Trends & Forecast
- Single User License (1 Users) $ 3,500
- Team License (2~5 Users) $ 4,500
- Corporate License (>5 Users) $ 5,500
Electronic Speciality Gases (ESGs) represent ultra-high-purity (UHP) chemical compounds—operating at certified purities spanning 5N (99.999%) to 7N+ (99.99999%)—that serve as functional reactive agents across microelectronics fabrication. Unlike inert electronic bulk gases, ESGs actively participate in chemical reactions at atomic scales, functioning as etching media, thin-film deposition precursors, atomic dopants, chamber-cleaning reagents, and coherent excimer laser light sources. Frontline microelectronics manufacturing remains concentrated within East Asian foundry, memory, and display clusters, while strategic fab expansions underway across North America and Europe are altering historical delivery logistics and procurement patterns. Within modern wafer fab economics, specialty gases represent 13% to 14% of total consumable operational expenditure. This places ESGs as the second-largest raw material expense in wafer processing, exceeded only by blank silicon substrates. Because a minor contamination event measured in parts-per-billion (ppb) or parts-per-trillion (ppt) can induce wafer lattice displacement, threshold leakage, or whole-lot scrapping, semiconductor foundries exhibit zero tolerance for process variability.
Global electronic speciality gas market size is projected to reach 15 to 20 billion USD by 2026, advancing at a Compound Annual Growth Rate (CAGR) of 6.2% to 9.2% through 2031. This expansion is governed by architectural transitions in sub-2nm logic nodes, high-stack 3D NAND fabrication, and AI-accelerated high-bandwidth memory (HBM) packaging. An incumbent oligopoly comprising Linde, Air Liquide, Nippon Sanso Holdings, Merck KGaA, Entegris, Resonac, Messer, and REC Silicon ASA controls mission-critical supply networks. Simultaneously, aggressive regional chemical synthesizers in China (Peric Special Gases, Haohua Technology, Guangdong Huate Gas, Suzhou Jinhong Gas, Jiangsu Nata Opto-electronic, Zhongjuxin Technology, Henan Silane Technology Development, Hubei Heyuan Gas, Hunan Kaimet Gas, Jiangsu Yoke Technology Co. Ltd., Linggas Ltd.), South Korea (Wonik Materials, TEMC, SK specialty, SK ecoplant materials, FOOSUNG, KNW / BGF Eco Specialties), Japan (Kanto Denka Kogyo, Sumitomo Seika Chemicals, Central Glass) and Taiwan, China (Taiwan Speciality Chemicals Corporation, Ion Electronic Materials, Ingentec Corporation) are capturing volume share in scaled molecules and localized supply arrangements.
TECHNICAL BOUNDARY AND MOLECULAR CLASSIFICATION
Distinct from standard industrial atmospheric gases and electronic bulk gases, ESGs are characterized by strict functional, purity, and containment specifications:
1. Bulk versus Specialty Boundary
- Purity Profiles: Bulk gases (N2, O2, Ar, H2, He, CO2) operate with parts-per-million (ppm) contaminant tolerances. ESGs mandate analytical purity thresholds from 99.99% (4N) to 99.99999% (7N), restricting moisture, trace oxygen, hydrocarbons, and transition metal ions to sub-ppb and ppt limits.
- Process Functionality: Bulk gases provide macro-environment inerting, atmospheric blanketing, thermal moderation, and line purging. ESGs execute discrete, atomic-scale chemical surface modifications via reactive ion bombardment, chemical vapor deposition, atomic layer deposition, and excimer light emission.
- Logistics and Containment: Bulk gases are piped from over-the-fence air separation units (ASUs) or delivered in cryogenic trailers. ESGs are packaged in mirror-polished, chemically passivated high-pressure cylinders, Y-cylinders, ton tanks, or sub-atmospheric adsorbent delivery systems (SDS/VAC), governed by stringent hazardous chemical classifications spanning extreme toxicity, pyrophoricity, and high corrosiveness.
2. Functional Process Taxonomy
- Etching and Chamber Cleaning Gases: Reactive fluorine-, chlorine-, and bromine-based chemistries that selectively remove materials or volatilize residual dielectric crusts from tool vacuum chambers. Key molecules include Nitrogen Trifluoride (NF3), Carbon Tetrafluoride (CF4), Octafluorocyclobutane (C4F8), Hexafluorobutadiene (C4F6), Chlorine (Cl2), Hydrogen Chloride (HCl), Hydrogen Bromide (HBr), Boron Trichloride (BCl3), and Sulfur Hexafluoride (SF6).
- Deposition, Epitaxy, and Thin-Film Formation Precursors: Volatile silicon, metal, and dielectric compounds that thermally decompose or react to build crystalline, dielectric, or conductive films. Core chemistries encompass Monosilane (SiH4), Disilane (Si2H6), Dichlorosilane (DCS), Hexachlorodisilane (HCDS), Tungsten Hexafluoride (WF6), Bis(diethylamino)silane (BDEAS), Tetraethyl Orthosilicate (TEOS), Germane (GeH4), and Titanium Tetrachloride (TiCl4).
- Doping and Ion Implantation Gases: Donor and acceptor source molecules ionized in high-energy implanters or introduced via thermal diffusion to modify semiconductor conductive properties. Prominent chemistries include Arsine (AsH3), Phosphine (PH3), Diborane (B2H6), Boron Trifluoride (BF3), Silicon Tetrafluoride (SiF4), and Germanium Tetrafluoride (GeF4).
- Lithography and Excimer Laser Gas Mixtures: Multicomponent noble gas and halogen formulations that produce coherent deep-ultraviolet (DUV) pulsed laser outputs under electrical discharge. Essential blends include Argon-Fluorine-Neon (Ar/F/Ne for 193nm ArF immersion) and Krypton-Fluorine-Neon (Kr/F/Ne for 248nm KrF scanners).
3. Chemical Family Taxonomy
- Fluorine-Based Gases: Possess elevated bond energies and strong dielectric properties. Synthesized via electrochemical fluorination (ECF) in anhydrous HF electrolytes or direct elemental fluorination. Key products include NF3, WF6, SF6, and advanced fluorocarbons (C4F6, C4F8, CF4).
- Hydride Gases: Covalently bonded hydrogen compounds of Groups III, IV, and V. Pyrophoric, highly toxic, and reducing agents synthesized via hydride reductions or silane disproportionation. Key products include SiH4, Si2H6, PH3, AsH3, GeH4, and B2H6.
- Noble Gases: Chemically inert elemental gases (Ne, Kr, Xe) extracted exclusively as cryogenic fractions from metallurgical ASUs. Utilized in lithography laser chambers and high-density plasma etching of vertical aspect ratios.
- Halogenated and Acidic Gases: Corrosive Lewis acids and halides requiring electropolished 316L, Hastelloy, and sub-50 ppb internal moisture environments. Key products include electronic HCl, Cl2, HBr, BCl3, and anhydrous HF.
DOWNSTREAM APPLICATION DYNAMICS
● Semiconductor Integrated Circuits (ICs) represent 43% of total specialty gas market demand, operating as the primary catalyst for molecular innovation:
- Advanced Logic Nodes (Sub-5nm to 2nm): Gate-All-Around (GAA) nanosheets and multi-patterning lithography drive substantial consumption of excimer mixtures, while low-temperature ALD demands disilane, trisilane, and specialized organosilicons (HCDS, BDEAS). High-pressure deuterium (D2) annealing is applied in advanced logic and DRAM to passivate dangling interface bonds and prevent tunneling leakage.
- High-Stack 3D NAND Memory: Vertical scaling past 200 to 300 oxide-nitride-oxide layers demands extreme aspect ratio dry etching. This architectural transition has elevated per-wafer consumption of high-selectivity fluorocarbons (C4F6, C4F8) alongside heavy rare gas balancers (krypton, xenon). Word-line metallization remains reliant on UHP WF6.
- Advanced Packaging and High-Bandwidth Memory (HBM): High-density Through-Silicon Via (TSV) etching for 2.5D/3D stacked architectures accelerates demand for specialized fluorocarbon mixtures and inerting process streams.
● Flat Panel Display (FPD) manufacturing constitutes the second-largest consumption segment:
- Array backplane fabrication for AMOLED and high-generation TFT-LCD lines (Gen 8.5 to 10.5) requires high-volume consumption of monosilane (SiH4), ultra-pure ammonia (NH3, 5N5 to 7N), and nitrous oxide (N2O) for silicon nitride (SiNx) and silicon dioxide (SiO2) insulating films deposited via PECVD.
- Large-area vacuum chambers require periodic, in-situ radical-driven residue volatilization, consuming substantial volumes of NF3 and SF6.
● Light Emitting Diodes and Compound Semiconductors capture 13% of demand:
- Epitaxial growth of wide bandgap power electronics (SiC, GaN) and RF communication devices (GaAs, InP) via MOCVD consumes high-purity ammonia as a nitrogen donor alongside arsine and phosphine, combined with metalorganic compounds (TMGa, TMIn, TMAl).
- Fine-pitch Mini/Micro LED displays necessitate defect-free MOCVD operations, requiring stable carrier gas streams and laser lift-off halogen mixtures.
● Photovoltaics (PV) and Emerging Adjacent Sectors:
- High-efficiency N-type solar cells (TOPCon and Heterojunction/HJT) have raised silane and ammonia consumption per gigawatt to deposit ultra-thin passivating polysilicon and anti-reflective films.
- In next-generation energy storage, monosilane is decomposing in fluidized bed CVD systems to deposit nano-silicon coatings within porous carbon matrices for high-capacity EV battery anodes.
- Telecommunications optical fiber preforms consume ultra-pure chlorine for vapor-phase dehydration of soot cores to eliminate light-attenuating hydroxyl radicals, alongside deuterium to suppress long-term hydrogen aging.
SUPPLY CHAIN ARCHITECTURE AND BOTTLENECK RESILIENCE
The value chain spans upstream primary extraction, midstream deep purification and containment engineering, down to frontline fab hook-up.
1. Upstream Raw Material Vulnerability and Hardware Constraints
- Upstream feedstocks rely on foundational chemical industries: Anhydrous Hydrofluoric Acid (AHF, derived from acid-grade fluorspar), industrial liquid ammonia, metallurgical-grade silicon, anhydrous hydrogen chloride, and industrial by-product tail gases (carbon dioxide, nitrous oxide).
- Rare gas recovery (Ne, Kr, Xe) depends directly on large-scale air separation infrastructure serving metallurgical steel operations. Geopolitical supply disruption highlights structural vulnerabilities in rare gas sourcing, accelerating the integration of on-site recovery and recycling platforms within frontline fabs.
- Upstream containment and fluid conveyance hardware represent critical chokepoints. Strict cleanliness demands require mirror-polished seamless steel cylinders, electropolished (EP) 316L stainless steel tubing, sub-atmospheric carbon adsorbent substrates, bellows-sealed valves, and analytical instrumentation (APIMS, CRDS) capable of detection at ppt thresholds.
2. Midstream Purification and Synthetic Moats
- Synthesis pathways encompass electrochemical fluorination (ECF) in molten potassium bifluoride for NF3, direct elemental fluorination for WF6, and catalytic disproportionation of trichlorosilane for SiH4.
- Deep purification technologies deploy multistage cryogenic fractional distillation to separate close-boiling trace impurities, followed by catalytic deoxidation, solid-state getter beds, and organometallic scavengers to reduce atmospheric contaminants below target limits.
- Containment preparation represents an operational barrier: Cylinders undergo ultrasonic degreasing, internal abrasive mirror finishing, high-temperature vacuum baking, and surface passivation to avoid gas-wall chemical decay over extended shelf lives.
- Cleanroom filling stations operate under Class 100/1000 parameters to restrict airborne particulate introduction.
3. Fab Customer Qualification and Value Migration
- Tier-1 microelectronics manufacturers maintain lengthy qualification protocols: Laboratory analytical screening (6 months), pilot-line evaluation (6 to 12 months), and full-scale fab integration trials (12 to 24 months). Total validation timelines extend from 1 to 2 years for displays and 2 to 3+ years for advanced semiconductor foundries.
- Value migration continues to shift toward integrated product portfolios that bundle high-margin precursors, hazardous delivery systems (SDS/VAC platforms), and Total Gas Management (TGM) on-site contracts, raising commercial entry barriers against unintegrated single-molecule producers.
REGIONAL MARKET DYNAMICS
● Asia-Pacific captures over 70% of global ESG consumption, anchored by dense concentrations of semiconductor foundries, memory plants, and display fabrication facilities.
- China: Operates as the largest regional market by volume, driven by semiconductor capacity buildouts, display line scaling, and extensive solar manufacturing. Domestic chemical producers are executing capital expenditure programs to localize supply across mature and mid-node chemistries, reducing reliance on multinational conglomerates.
- Japan: Maintains intellectual property leadership in fluorochemical synthesis, high-aspect-ratio etching formulations (C4F6, CH2F2), MoO2Cl2 precursors, and excimer laser gas certifications. Domestic manufacturing clusters supply high-purity inputs globally.
- Republic of Korea: Anchored by memory fabrication giants in Pyeongtaek, Giheung, and Icheon. The market is defined by intense consumption of WF6, C4F6, NF3, UHP NH3, and rare gases for 3D NAND and DRAM fabrication. The domestic supply chain operates through tight vendor integration backed by state-sponsored localization policies.
- Taiwan, China: Represents the global hub for advanced foundry manufacturing. While historically reliant on multinational joint ventures, escalating supply security priorities have driven material localization strategies. Domestic suppliers have successfully commercialized mission-critical molecules including disilane, C4F6, and sub-atmospheric ion implant cylinders.
- Southeast Asia and India: Singapore is expanding advanced front-end wafer fabrication through joint ventures, drawing utility investments for on-site electronic gas infrastructure. Malaysia expands backend advanced packaging footprints, while India's initial gas demand remains centered on expanding photovoltaic manufacturing alongside preliminary semiconductor mission investments.
● North America ranks as the second-largest market, supported by reshoring initiatives and federal incentives under the CHIPS and Science Act. Investment is concentrated in greenfield and brownfield mega-fab projects across Arizona, Texas, Ohio, and Oregon, which require local specialty gas distribution networks, on-site bulk systems, and transfilling hubs.
● Europe represents the third-largest regional market. Consumption centers on power semiconductor fabrication, automotive microcontrollers, and specialized laboratory applications. Regional demand is conditioned by strict chemical directives and environmental targets, shifting development toward low-GWP cleaning and etching chemistries.
● South America and Middle East & Africa (MEA) occupy peripheral consumption positions, predominantly focused on legacy discrete components, photovoltaic assembly, and localized industrial R&D installations.
REGULATORY LANDSCAPE AND STRATEGIC DIRECTIVES
Industrial policy and environmental regulations are shaping competitive dynamics across the global ESG landscape:
1. Semiconductor Industrial Policies
- United States: The CHIPS and Science Act allocates direct capital subsidies, loan guarantees, and Advanced Manufacturing Investment Tax Credits to reconstitute domestic microelectronics supply chains. Supply chain participants receive direct support to build UHP filtration and hazardous gas chemical packaging facilities within domestic borders.
- European Union: The European Chips Act mobilizes billions in combined public-private funding to target a 20% global production share by 2030, supported by joint undertakings (such as the GENESIS initiative) focused on establishing sustainable electronic material ecosystems.
- China: The 14th and 15th Five-Year Plans, supported by the National Integrated Circuit Industry Investment Fund Phase III, classify electronic specialty gases as critical strategic materials. Catalogs issued by the Ministry of Industry and Information Technology prioritize CH3F, HBr, ClF3, HF, Si2H6, and GeH4 for domestic adoption, while trade measures emphasize domestic supplier validation.
- Republic of Korea: The Materials, Parts, and Equipment (SoBuJang) Strategy formalizes tax and operational support to localize electronic etching and deposition gases following historical cross-border trade disruptions.
- India: The India Semiconductor Mission (ISM) deploy capital outlays alongside Production Linked Incentive schemes to support foundry development and associated chemical feedstocks.
2. Environmental Directives and Climate Quotas
- Kigali Amendment to the Montreal Protocol: Enforces a structural phase-down of high Global Warming Potential (GWP) hydrofluorocarbons (HFCs).
- National Environmental Quota Systems: China has implemented production and consumption caps for HFCs through 2030, restricting unrestrained capacity expansions of high-GWP fluorocarbons. South Korea's quota system on HFC process gases enforces emission limits on fab operations, requiring the qualification of alternative low-GWP substitutes and catalytic abatement installations.
- Per- and Polyfluoroalkyl Substances (PFAS) Scrutiny: Evolving regulatory proposals across Europe and North America targeting persistent fluorinated substances are accelerating research into alternative fluorine gas mixtures and low-GWP etching agents.
OPPORTUNITIES AND CHALLENGES
● Opportunities
- High-Bandwidth Memory (HBM) and Advanced Packaging Expansion: The expansion of AI compute architectures requires HBM stacks interconnected via dense Through-Silicon Vias (TSVs). The high aspect ratios of TSV trenches accelerate consumption of fluorocarbon etching formulations (C4F6, C4F8) and silicon precursors per manufactured silicon unit.
- Vertical Scaling in 3D NAND: Memory layer progression beyond 200 to 300 layers increases aspect ratios exponentially. This structural shift expands per-wafer unit consumption of high-selectivity etching gases (C4F6) and noble gas plasma moderators (krypton and xenon), while word-line interconnects drive sustained WF6 consumption.
- Structural Supply Chain Nearshoring: Global fab expansions catalyzed by geopolitical incentives are requiring redundant, localized chemical supply chains. Qualified regional gas suppliers capable of passing 2- to 3-year validation cycles gain opportunities to secure multi-year supply arrangements with non-incumbent foundries.
- Energy Storage Adjacency: The commercial scaling of silicon-carbon composite battery anodes is creating an external demand driver for electronic monosilane (SiH4). Fluidized bed CVD carbon-pore filling applications leverage electronic silane synthesis assets, providing alternative off-take channels outside microelectronics.
● Challenges
- Capacity Concentration and Price Compression: Rapid capital investment across standardized molecules—notably Nitrogen Trifluoride (NF3), standard fluorocarbons, and monosilane—has produced localized supply surpluses. Unrestricted capacity scaling by regional players has pressured market prices, compressing gross margins across mature, non-differentiated gas varieties.
- High Inertia and Customer Switching Moats: Because specialty gases account for 13% to 14% of wafer processing costs, yet an off-spec chemical delivery risks batch-level scrap valued in millions of dollars, foundry engineers resist transitioning qualified materials to unproven suppliers. New entrants face qualification periods of 2 to 3+ years with high capital carrying costs.
- Upstream Feedstock Vulnerability and Geopolitical Controls: The ESG value chain remains vulnerable to upstream shocks. Critical input materials are subject to national mining quotas, export restrictions, and geopolitical exposure—including rare gas extraction concentrations at steel complexes and mining controls on fluorspar and tungsten feedstocks.
- Environmental Quotas and Decarbonization Mandates: Accelerating regulatory schedules under the Kigali Amendment, regional HFC quota baselines, and pending PFAS restrictions are targeting long-chain and high-GWP fluorocarbons. Producers face substantial capital expenditure requirements to develop low-GWP, climate-aligned alternative molecules and install advanced exhaust destruction systems.
1.1 Executive Summary and Scope 1
1.2 Research Methodology and Estimation Modeling 3
1.2.1 Primary Intelligence Verification 3
1.2.2 Secondary Data Sources and Synthesis 4
1.2.3 Macro-Economic and Semiconductor Node Assumptions 5
1.3 Standard Industry Abbreviations 6
Chapter 2 Global Electronic Speciality Gases Market Overview and Macro Dynamics 7
2.1 Market Architecture and Evolutionary Trajectory 7
2.2 Historical Revenue and Volume Metrics (2021-2025) 9
2.3 Baseline Assessment and Projection Vectors (2026-2031) 11
2.4 Technological Disruption and Purity Escalation (7N to 9N Purity Requirements) 13
Chapter 3 Value Chain Architecture and Manufacturing Ecosystem 15
3.1 Upstream Feedstock Sourcing and Synthesis Precursors 15
3.2 Purification, Liquefaction, and Synthesis Engineering 17
3.3 Cylinder Treatment, Packaging Metallurgy, and Ultra-High Purity Logistics 19
3.4 On-Site Gas Generation versus Packaged Bulk Distribution Models 21
Chapter 4 Global Market Breakdown by Functional Process Classification 23
4.1 Etching and Chamber Cleaning Gases 23
4.2 Deposition, Epitaxy, and Thin-Film Formation Gases (Precursors) 25
4.3 Doping and Ion Implantation Gases 27
4.4 Lithography and Excimer Laser Gases 29
Chapter 5 Global Market Breakdown by Chemical Family Classification 32
5.1 Fluorine-Based Gases (NF3, CF4, C4F6, C4F8, WF6, SF6) 32
5.2 Hydride Gases (SiH4, Si2H6, PH3, AsH3, B2H6, GeH4) 34
5.3 Noble and Inert Atmospheric Gases (Kr, Xe, Ne, Ultra-Pure Ar and He) 36
5.4 Halogenated and Acidic Gases (HCl, HBr, Cl2, BCl3) 38
Chapter 6 Global Market Breakdown by Downstream Application 41
6.1 Advanced Semiconductor Manufacturing (Sub-3nm Logic, Advanced Packaging, 3D NAND, Leading DRAM) 41
6.2 Flat Panel Displays (OLED, Micro-LED, Advanced Oxide TFT LCD) 43
6.3 Compound Semiconductors and LEDs (GaN, SiC, Micro-LED) 45
6.4 Photovoltaics and High-Efficiency Solar Cells (TOPCon, HJT, Perovskite Tandem) 46
6.5 Emerging Applications 47
Chapter 7 Cross-Border Trade Flows, Export Controls, and Supply Chain Security 49
7.1 Global Trade Flows and Strategic Interdependence 49
7.2 Export Control Regimes, Multilateral Sanctions, and Strategic Supply Security 51
7.3 Specialized Transport Infrastructure and ISO Tanker Container Fleet Dynamics 53
Chapter 8 Regional Production Hubs and Consumption Dynamics 56
8.1 Asia-Pacific Ecosystem 56
8.1.1 China (Mainland) 56
8.1.2 Taiwan (China) 57
8.1.3 South Korea 58
8.1.4 Japan 59
8.1.5 Southeast Asia & India 59
8.2 North America 60
8.3 Europe 61
8.3.1 Germany, France, and UK 61
8.3.2 Rest of Europe 62
Chapter 9 Competitive Landscape, Market Share, and Strategic Positioning 63
9.1 Tier-1 Vendor Positioning and Concentration Index (HHI) 63
9.2 M&A Trajectory, Joint Ventures, and Capacity Realignment 64
Chapter 10 Competitive Intelligence and Corporate Profiles 66
10.1 Linde 66
10.1.1 Corporate Profile and Electronic Gases Operational Footprint 66
10.1.2 SWOT Matrix and Strategic Moat Analysis 67
10.1.3 Electronic Speciality Gases Financial Performance: Revenue, Cost, and Gross Margin (2021-2026) 68
10.1.4 Global Market Share Evaluation and Capacity Pipeline 69
10.2 Air Liquide 70
10.2.1 Corporate Profile and Electronic Gases Operational Footprint 70
10.2.2 SWOT Matrix and Strategic Moat Analysis 71
10.2.3 Electronic Speciality Gases Financial Performance: Revenue, Cost, and Gross Margin (2021-2026) 72
10.2.4 Global Market Share Evaluation and Capacity Pipeline 73
10.3 Nippon Sanso Holdings 74
10.3.1 Corporate Profile and Electronic Gases Operational Footprint 74
10.3.2 SWOT Matrix and Strategic Moat Analysis 75
10.3.3 Electronic Speciality Gases Financial Performance: Revenue, Cost, and Gross Margin (2021-2026) 76
10.3.4 Global Market Share Evaluation and Capacity Pipeline 77
10.4 Merck KGaA 78
10.4.1 Corporate Profile and Electronic Gases Operational Footprint 78
10.4.2 SWOT Matrix and Strategic Moat Analysis 79
10.4.3 Electronic Speciality Gases Financial Performance: Revenue, Cost, and Gross Margin (2021-2026) 80
10.4.4 Global Market Share Evaluation and Capacity Pipeline 81
10.5 Messer 82
10.5.1 Corporate Profile and Electronic Gases Operational Footprint 82
10.5.2 SWOT Matrix and Strategic Moat Analysis 83
10.5.3 Electronic Speciality Gases Financial Performance: Revenue, Cost, and Gross Margin (2021-2026) 84
10.5.4 Global Market Share Evaluation and Capacity Pipeline 85
10.6 Entegris 86
10.6.1 Corporate Profile and Electronic Gases Operational Footprint 86
10.6.2 SWOT Matrix and Strategic Moat Analysis 87
10.6.3 Electronic Speciality Gases Financial Performance: Revenue, Cost, and Gross Margin (2021-2026) 88
10.6.4 Global Market Share Evaluation and Capacity Pipeline 89
10.7 Resonac 90
10.7.1 Corporate Profile and Electronic Gases Operational Footprint 90
10.7.2 SWOT Matrix and Strategic Moat Analysis 91
10.7.3 Electronic Speciality Gases Financial Performance: Revenue, Cost, and Gross Margin (2021-2026) 92
10.7.4 Global Market Share Evaluation and Capacity Pipeline 93
10.8 WONIK MATERIALS 94
10.8.1 Corporate Profile and Electronic Gases Operational Footprint 94
10.8.2 SWOT Matrix and Strategic Moat Analysis 95
10.8.3 Electronic Speciality Gases Financial Performance: Revenue, Cost, and Gross Margin (2021-2026) 96
10.8.4 Global Market Share Evaluation and Capacity Pipeline 97
10.9 SK ecoplant materials 98
10.9.1 Corporate Profile and Electronic Gases Operational Footprint 98
10.9.2 SWOT Matrix and Strategic Moat Analysis 99
10.9.3 Electronic Speciality Gases Financial Performance: Revenue, Cost, and Gross Margin (2021-2026) 100
10.9.4 Global Market Share Evaluation and Capacity Pipeline 101
10.10 SK specialty Co. Ltd. 102
10.10.1 Corporate Profile and Electronic Gases Operational Footprint 102
10.10.2 SWOT Matrix and Strategic Moat Analysis 103
10.10.3 Electronic Speciality Gases Financial Performance: Revenue, Cost, and Gross Margin (2021-2026) 104
10.10.4 Global Market Share Evaluation and Capacity Pipeline 105
10.11 Ion Electronic Materials Co. Ltd. 106
10.11.1 Corporate Profile and Electronic Gases Operational Footprint 106
10.11.2 SWOT Matrix and Strategic Moat Analysis 107
10.11.3 Electronic Speciality Gases Financial Performance: Revenue, Cost, and Gross Margin (2021-2026) 108
10.11.4 Global Market Share Evaluation and Capacity Pipeline 109
10.12 Peric Special Gases Co. Ltd. 110
10.12.1 Corporate Profile and Electronic Gases Operational Footprint 110
10.12.2 SWOT Matrix and Strategic Moat Analysis 111
10.12.3 Electronic Speciality Gases Financial Performance: Revenue, Cost, and Gross Margin (2021-2026) 112
10.12.4 Global Market Share Evaluation and Capacity Pipeline 113
10.13 Guangdong Huate Gas Co. Ltd 114
10.13.1 Corporate Profile and Electronic Gases Operational Footprint 114
10.13.2 SWOT Matrix and Strategic Moat Analysis 115
10.13.3 Electronic Speciality Gases Financial Performance: Revenue, Cost, and Gross Margin (2021-2026) 116
10.13.4 Global Market Share Evaluation and Capacity Pipeline 117
10.14 Jiangsu Nata Opto-electronic Material Co. Ltd. 118
10.14.1 Corporate Profile and Electronic Gases Operational Footprint 118
10.14.2 SWOT Matrix and Strategic Moat Analysis 119
10.14.3 Electronic Speciality Gases Financial Performance: Revenue, Cost, and Gross Margin (2021-2026) 120
10.14.4 Global Market Share Evaluation and Capacity Pipeline 121
10.15 Jiangsu Yoke Technology Co. Ltd. 122
10.15.1 Corporate Profile and Electronic Gases Operational Footprint 122
10.15.2 SWOT Matrix and Strategic Moat Analysis 123
10.15.3 Electronic Speciality Gases Financial Performance: Revenue, Cost, and Gross Margin (2021-2026) 124
10.15.4 Global Market Share Evaluation and Capacity Pipeline 125
10.16 Suzhou Jinhong Gas Co. Ltd. 126
10.16.1 Corporate Profile and Electronic Gases Operational Footprint 126
10.16.2 SWOT Matrix and Strategic Moat Analysis 127
10.16.3 Electronic Speciality Gases Financial Performance: Revenue, Cost, and Gross Margin (2021-2026) 128
10.16.4 Global Market Share Evaluation and Capacity Pipeline 129
10.17 Haohua Gas Co. Ltd. 130
10.17.1 Corporate Profile and Electronic Gases Operational Footprint 130
10.17.2 SWOT Matrix and Strategic Moat Analysis 131
10.17.3 Electronic Speciality Gases Financial Performance: Revenue, Cost, and Gross Margin (2021-2026) 132
10.17.4 Global Market Share Evaluation and Capacity Pipeline 133
10.18 Linggas Ltd 134
10.18.1 Corporate Profile and Electronic Gases Operational Footprint 134
10.18.2 SWOT Matrix and Strategic Moat Analysis 135
10.18.3 Electronic Speciality Gases Financial Performance: Revenue, Cost, and Gross Margin (2021-2026) 136
10.18.4 Global Market Share Evaluation and Capacity Pipeline 137
10.19 FOOSUNG Co. Ltd. 138
10.19.1 Corporate Profile and Electronic Gases Operational Footprint 138
10.19.2 SWOT Matrix and Strategic Moat Analysis 139
10.19.3 Electronic Speciality Gases Financial Performance: Revenue, Cost, and Gross Margin (2021-2026) 140
10.19.4 Global Market Share Evaluation and Capacity Pipeline 141
10.20 Kanto Denka Kogyo Co. Ltd. 142
10.20.1 Corporate Profile and Electronic Gases Operational Footprint 142
10.20.2 SWOT Matrix and Strategic Moat Analysis 143
10.20.3 Electronic Speciality Gases Financial Performance: Revenue, Cost, and Gross Margin (2021-2026) 144
10.20.4 Global Market Share Evaluation and Capacity Pipeline 145
10.21 KNW Co. Ltd. 146
10.21.1 Corporate Profile and Electronic Gases Operational Footprint 146
10.21.2 SWOT Matrix and Strategic Moat Analysis 147
10.21.3 Electronic Speciality Gases Financial Performance: Revenue, Cost, and Gross Margin (2021-2026) 148
10.21.4 Global Market Share Evaluation and Capacity Pipeline 149
10.22 Central Glass 150
10.22.1 Corporate Profile and Electronic Gases Operational Footprint 150
10.22.2 SWOT Matrix and Strategic Moat Analysis 151
10.22.3 Electronic Speciality Gases Financial Performance: Revenue, Cost, and Gross Margin (2021-2026) 152
10.22.4 Global Market Share Evaluation and Capacity Pipeline 153
10.23 Sumitomo Seika Chemicals 154
10.23.1 Corporate Profile and Electronic Gases Operational Footprint 154
10.23.2 SWOT Matrix and Strategic Moat Analysis 155
10.23.3 Electronic Speciality Gases Financial Performance: Revenue, Cost, and Gross Margin (2021-2026) 156
10.23.4 Global Market Share Evaluation and Capacity Pipeline 157
10.24 TEMC Co. Ltd. 158
10.24.1 Corporate Profile and Electronic Gases Operational Footprint 158
10.24.2 SWOT Matrix and Strategic Moat Analysis 159
10.24.3 Electronic Speciality Gases Financial Performance: Revenue, Cost, and Gross Margin (2021-2026) 160
10.24.4 Global Market Share Evaluation and Capacity Pipeline 161
10.25 Zhongjuxin Technology 162
10.25.1 Corporate Profile and Electronic Gases Operational Footprint 162
10.25.2 SWOT Matrix and Strategic Moat Analysis 163
10.25.3 Electronic Speciality Gases Financial Performance: Revenue, Cost, and Gross Margin (2021-2026) 164
10.25.4 Global Market Share Evaluation and Capacity Pipeline 165
10.26 REC Silicon 166
10.26.1 Corporate Profile and Electronic Gases Operational Footprint 166
10.26.2 SWOT Matrix and Strategic Moat Analysis 167
10.26.3 Electronic Speciality Gases Financial Performance: Revenue, Cost, and Gross Margin (2021-2026) 168
10.26.4 Global Market Share Evaluation and Capacity Pipeline 169
10.27 Henan Silane Technology Development 170
10.27.1 Corporate Profile and Electronic Gases Operational Footprint 170
10.27.2 SWOT Matrix and Strategic Moat Analysis 171
10.27.3 Electronic Speciality Gases Financial Performance: Revenue, Cost, and Gross Margin (2021-2026) 172
10.27.4 Global Market Share Evaluation and Capacity Pipeline 173
10.28 Taiwan Speciality Chemicals Corporation 174
10.28.1 Corporate Profile and Electronic Gases Operational Footprint 174
10.28.2 SWOT Matrix and Strategic Moat Analysis 175
10.28.3 Electronic Speciality Gases Financial Performance: Revenue, Cost, and Gross Margin (2021-2026) 176
10.28.4 Global Market Share Evaluation and Capacity Pipeline 177
10.29 Ingentec Corporation 178
10.29.1 Corporate Profile and Electronic Gases Operational Footprint 178
10.29.2 SWOT Matrix and Strategic Moat Analysis 179
10.29.3 Electronic Speciality Gases Financial Performance: Revenue, Cost, and Gross Margin (2021-2026) 180
10.29.4 Global Market Share Evaluation and Capacity Pipeline 181
Table 2 Global Electronic Speciality Gases Market Value (USD Million) and Volume (Tons), 2021-2026 10
Table 3 Global Electronic Speciality Gases Market Value (USD Million) and Volume (Tons) Forecast, 2027-2031 12
Table 4 High-Purity Synthesis Thresholds and Contaminant Limits for Critical Electronic Gases 18
Table 5 Global Electronic Speciality Gases Market by Functional Process (USD Million), 2021-2026 24
Table 6 Global Electronic Speciality Gases Market Forecast by Functional Process (USD Million), 2027-2031 25
Table 7 Etching and Chamber Cleaning Gas Sub-Segment Breakdown (USD Million), 2021-2031 25
Table 8 Deposition and Thin-Film Precursor Gas Sub-Segment Breakdown (USD Million), 2021-2031 27
Table 9 Doping and Ion Implantation Gas Sub-Segment Breakdown (USD Million), 2021-2031 29
Table 10 Lithography and Excimer Laser Gas Sub-Segment Breakdown (USD Million), 2021-2031 31
Table 11 Global Electronic Speciality Gases Market by Chemical Family (USD Million), 2021-2026 33
Table 12 Global Electronic Speciality Gases Market Forecast by Chemical Family (USD Million), 2027-2031 34
Table 13 Fluorine-Based Electronic Gases Breakdown by Molecule (USD Million), 2021-2031 34
Table 14 Hydride Electronic Gases Breakdown by Molecule (USD Million), 2021-2031 36
Table 15 Noble Electronic Gases Breakdown by Molecule (USD Million), 2021-2031 38
Table 16 Halogenated and Acidic Gases Breakdown by Molecule (USD Million), 2021-2031 40
Table 17 Global Electronic Speciality Gases Market by Application (USD Million), 2021-2026 42
Table 18 Global Electronic Speciality Gases Market Forecast by Application (USD Million), 2027-2031 43
Table 19 Global Electronic Speciality Gases Trade Flow Matrix by Origin and Destination (USD Million), 2026 50
Table 20 Regulatory Controls and Critical Chemical Precursor Framework Comparison by Region 52
Table 21 Global Electronic Speciality Gases Production Capacity by Region (Tons), 2021-2031 56
Table 22 Global Electronic Speciality Gases Consumption Value by Region (USD Million), 2021-2031 58
Table 23 Linde Electronic Speciality Gases Revenue, Cost, and Gross Margin (2021-2026) 68
Table 24 Air Liquide Electronic Speciality Gases Revenue, Cost, and Gross Margin (2021-2026) 72
Table 25 Nippon Sanso Holdings Electronic Speciality Gases Revenue, Cost, and Gross Margin (2021-2026) 76
Table 26 Merck KGaA Electronic Speciality Gases Revenue, Cost, and Gross Margin (2021-2026) 80
Table 27 Messer Electronic Speciality Gases Revenue, Cost, and Gross Margin (2021-2026) 84
Table 28 Entegris Electronic Speciality Gases Revenue, Cost, and Gross Margin (2021-2026) 88
Table 29 Resonac Electronic Speciality Gases Revenue, Cost, and Gross Margin (2021-2026) 92
Table 30 WONIK MATERIALS Electronic Speciality Gases Revenue, Cost, and Gross Margin (2021-2026) 96
Table 31 SK ecoplant materials Electronic Speciality Gases Revenue, Cost, and Gross Margin (2021-2026) 100
Table 32 SK specialty Co. Ltd. Electronic Speciality Gases Revenue, Cost, and Gross Margin (2021-2026) 104
Table 33 Ion Electronic Materials Co. Ltd. Electronic Speciality Gases Revenue, Cost, and Gross Margin (2021-2026) 108
Table 34 Peric Special Gases Co. Ltd. Electronic Speciality Gases Revenue, Cost, and Gross Margin (2021-2026) 112
Table 35 Guangdong Huate Gas Co. Ltd Electronic Speciality Gases Revenue, Cost, and Gross Margin (2021-2026) 116
Table 36 Jiangsu Nata Opto-electronic Material Co. Ltd. Electronic Speciality Gases Revenue, Cost, and Gross Margin (2021-2026) 120
Table 37 Jiangsu Yoke Technology Co. Ltd. Electronic Speciality Gases Revenue, Cost, and Gross Margin (2021-2026) 124
Table 38 Suzhou Jinhong Gas Co. Ltd. Electronic Speciality Gases Revenue, Cost, and Gross Margin (2021-2026) 128
Table 39 Haohua Gas Co. Ltd. Electronic Speciality Gases Revenue, Cost, and Gross Margin (2021-2026) 132
Table 40 Linggas Ltd Electronic Speciality Gases Revenue, Cost, and Gross Margin (2021-2026) 136
Table 41 FOOSUNG Co. Ltd. Electronic Speciality Gases Revenue, Cost, and Gross Margin (2021-2026) 140
Table 42 Kanto Denka Kogyo Co. Ltd. Electronic Speciality Gases Revenue, Cost, and Gross Margin (2021-2026) 144
Table 43 KNW Co. Ltd. Electronic Speciality Gases Revenue, Cost, and Gross Margin (2021-2026) 148
Table 44 Central Glass Electronic Speciality Gases Revenue, Cost, and Gross Margin (2021-2026) 152
Table 45 Sumitomo Seika Chemicals Electronic Speciality Gases Revenue, Cost, and Gross Margin (2021-2026) 156
Table 46 TEMC Co. Ltd. Electronic Speciality Gases Revenue, Cost, and Gross Margin (2021-2026) 160
Table 47 Zhongjuxin Technology Electronic Speciality Gases Revenue, Cost, and Gross Margin (2021-2026) 164
Table 48 REC Silicon Electronic Speciality Gases Revenue, Cost, and Gross Margin (2021-2026) 168
Table 49 Henan Silane Technology Development Electronic Speciality Gases Revenue, Cost, and Gross Margin (2021-2026) 172
Table 50 Taiwan Speciality Chemicals Corporation Electronic Speciality Gases Revenue, Cost, and Gross Margin (2021-2026) 176
Table 51 Ingentec Corporation Electronic Speciality Gases Revenue, Cost, and Gross Margin (2021-2026) 180
Figure 1 Electronic Speciality Gases Research Methodology and Data Triangulation Framework 4
Figure 2 Global Electronic Speciality Gases Market Revenue Growth Trajectory (USD Million), 2021-2031 9
Figure 3 Technology Node Progression and Associated Speciality Gas Intensity (Grams per Wafer) 14
Figure 4 Electronic Speciality Gases Value Chain Architecture and Value Addition Steps 16
Figure 5 Global Electronic Speciality Gases Market Share by Functional Process, 2026 vs. 2031 24
Figure 6 Global Electronic Speciality Gases Market Share by Chemical Family, 2026 33
Figure 7 Global Electronic Speciality Gases Revenue Breakdown by Downstream Sector, 2021-2031 42
Figure 8 Global Supply-Demand Trade Balance Across Key Semiconductor Geographies, 2026 50
Figure 9 Global Electronic Speciality Gases Regional Consumption Share, 2026 57
Figure 10 Global Electronic Speciality Gases Market Concentration and Tier-1 Player Shares, 2026 64
Figure 11 Linde Electronic Speciality Gases Market Share (2021-2026) 69
Figure 12 Air Liquide Electronic Speciality Gases Market Share (2021-2026) 73
Figure 13 Nippon Sanso Holdings Electronic Speciality Gases Market Share (2021-2026) 77
Figure 14 Merck KGaA Electronic Speciality Gases Market Share (2021-2026) 81
Figure 15 Messer Electronic Speciality Gases Market Share (2021-2026) 85
Figure 16 Entegris Electronic Speciality Gases Market Share (2021-2026) 89
Figure 17 Resonac Electronic Speciality Gases Market Share (2021-2026) 93
Figure 18 WONIK MATERIALS Electronic Speciality Gases Market Share (2021-2026) 97
Figure 19 SK ecoplant materials Electronic Speciality Gases Market Share (2021-2026) 101
Figure 20 SK specialty Co. Ltd. Electronic Speciality Gases Market Share (2021-2026) 105
Figure 21 Ion Electronic Materials Co. Ltd. Electronic Speciality Gases Market Share (2021-2026) 109
Figure 22 Peric Special Gases Co. Ltd. Electronic Speciality Gases Market Share (2021-2026) 113
Figure 23 Guangdong Huate Gas Co. Ltd Electronic Speciality Gases Market Share (2021-2026) 117
Figure 24 Jiangsu Nata Opto-electronic Material Co. Ltd. Electronic Speciality Gases Market Share (2021-2026) 121
Figure 25 Jiangsu Yoke Technology Co. Ltd. Electronic Speciality Gases Market Share (2021-2026) 125
Figure 26 Suzhou Jinhong Gas Co. Ltd. Electronic Speciality Gases Market Share (2021-2026) 129
Figure 27 Haohua Gas Co. Ltd. Electronic Speciality Gases Market Share (2021-2026) 133
Figure 28 Linggas Ltd Electronic Speciality Gases Market Share (2021-2026) 137
Figure 29 FOOSUNG Co. Ltd. Electronic Speciality Gases Market Share (2021-2026) 141
Figure 30 Kanto Denka Kogyo Co. Ltd. Electronic Speciality Gases Market Share (2021-2026) 145
Figure 31 KNW Co. Ltd. Electronic Speciality Gases Market Share (2021-2026) 149
Figure 32 Central Glass Electronic Speciality Gases Market Share (2021-2026) 153
Figure 33 Sumitomo Seika Chemicals Electronic Speciality Gases Market Share (2021-2026) 157
Figure 34 TEMC Co. Ltd. Electronic Speciality Gases Market Share (2021-2026) 161
Figure 35 Zhongjuxin Technology Electronic Speciality Gases Market Share (2021-2026) 165
Figure 36 REC Silicon Electronic Speciality Gases Market Share (2021-2026) 169
Figure 37 Henan Silane Technology Development Electronic Speciality Gases Market Share (2021-2026) 173
Figure 38 Taiwan Speciality Chemicals Corporation Electronic Speciality Gases Market Share (2021-2026) 177
Figure 39 Ingentec Corporation Electronic Speciality Gases Market Share (2021-2026) 181
Research Methodology
- Market Estimated Methodology:
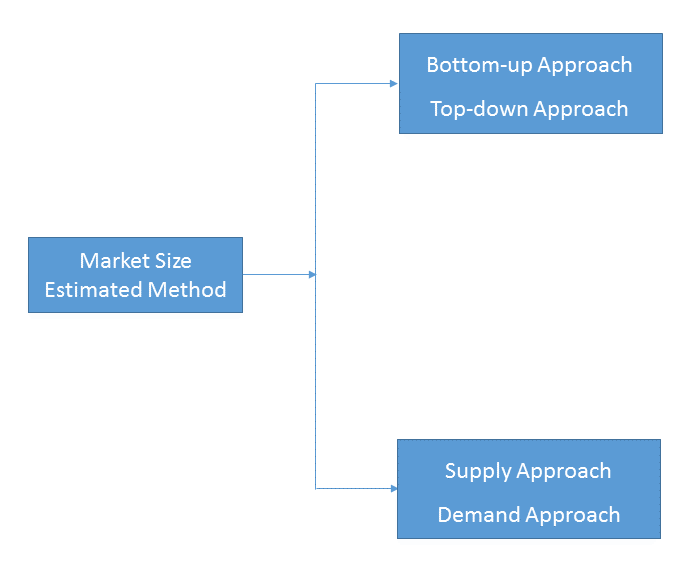
Bottom-up & top-down approach, supply & demand approach are the most important method which is used by HDIN Research to estimate the market size.
1)Top-down & Bottom-up Approach
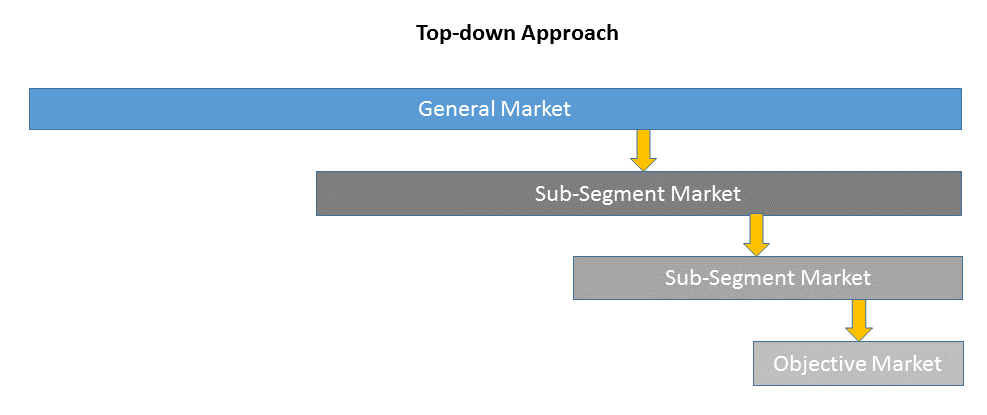
Top-down approach uses a general market size figure and determines the percentage that the objective market represents.
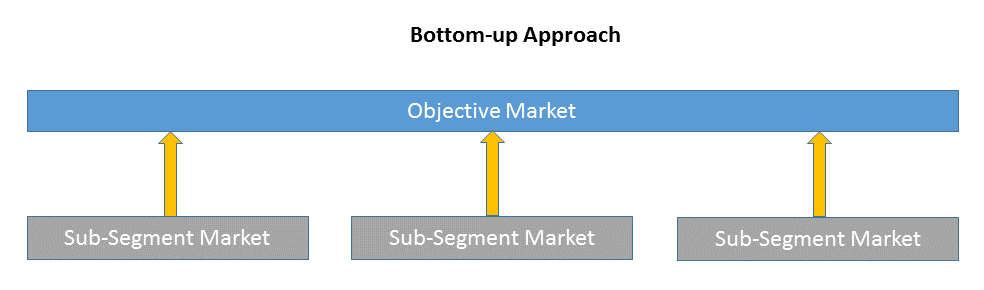
Bottom-up approach size the objective market by collecting the sub-segment information.
2)Supply & Demand Approach
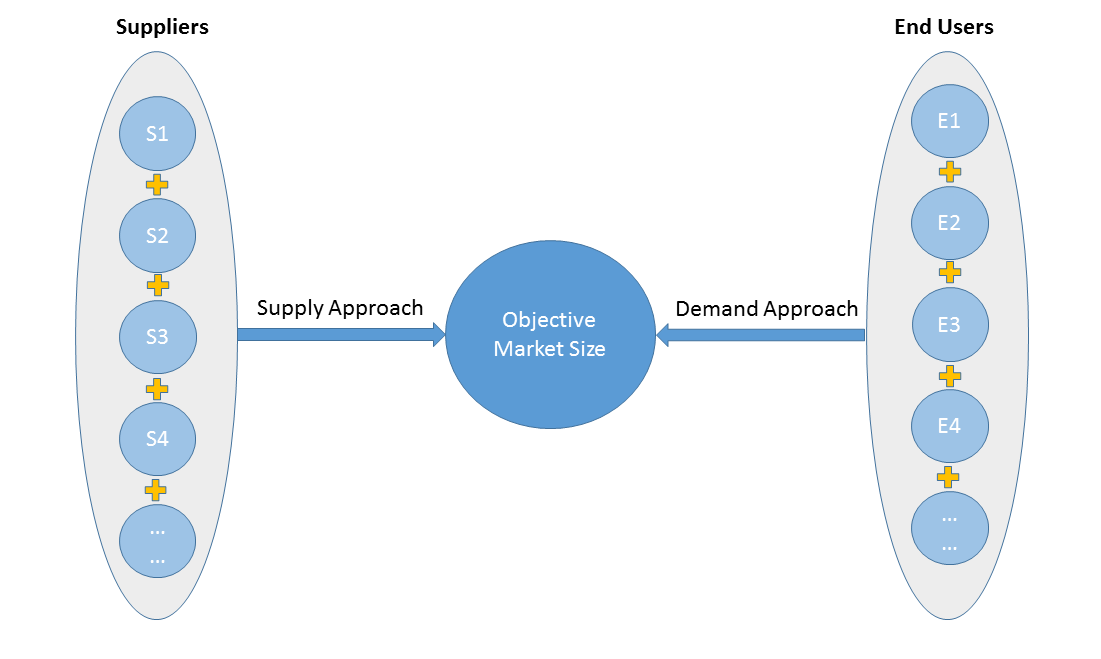
Supply approach is based on assessments of the size of each competitor supplying the objective market.
Demand approach combine end-user data within a market to estimate the objective market size. It is sometimes referred to as bottom-up approach.
- Forecasting Methodology
- Numerous factors impacting the market trend are considered for forecast model:
- New technology and application in the future;
- New project planned/under contraction;
- Global and regional underlying economic growth;
- Threatens of substitute products;
- Industry expert opinion;
- Policy and Society implication.
- Analysis Tools
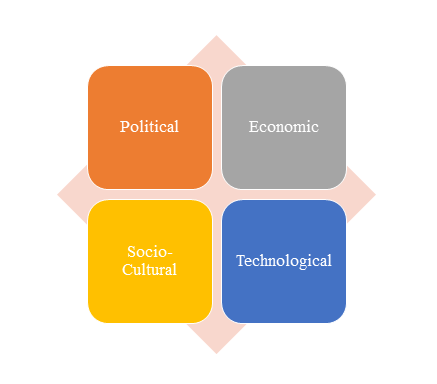
1)PEST Analysis
PEST Analysis is a simple and widely used tool that helps our client analyze the Political, Economic, Socio-Cultural, and Technological changes in their business environment.
- Benefits of a PEST analysis:
- It helps you to spot business opportunities, and it gives you advanced warning of significant threats.
- It reveals the direction of change within your business environment. This helps you shape what you’re doing, so that you work with change, rather than against it.
- It helps you avoid starting projects that are likely to fail, for reasons beyond your control.
- It can help you break free of unconscious assumptions when you enter a new country, region, or market; because it helps you develop an objective view of this new environment.
2)Porter’s Five Force Model Analysis
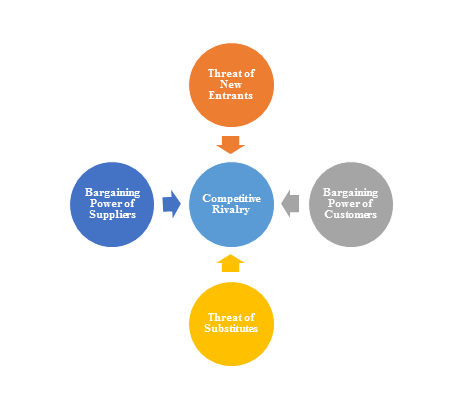
The Porter’s Five Force Model is a tool that can be used to analyze the opportunities and overall competitive advantage. The five forces that can assist in determining the competitive intensity and potential attractiveness within a specific area.
- Threat of New Entrants: Profitable industries that yield high returns will attract new firms.
- Threat of Substitutes: A substitute product uses a different technology to try to solve the same economic need.
- Bargaining Power of Customers: the ability of customers to put the firm under pressure, which also affects the customer's sensitivity to price changes.
- Bargaining Power of Suppliers: Suppliers of raw materials, components, labor, and services (such as expertise) to the firm can be a source of power over the firm when there are few substitutes.
- Competitive Rivalry: For most industries the intensity of competitive rivalry is the major determinant of the competitiveness of the industry.
3)Value Chain Analysis
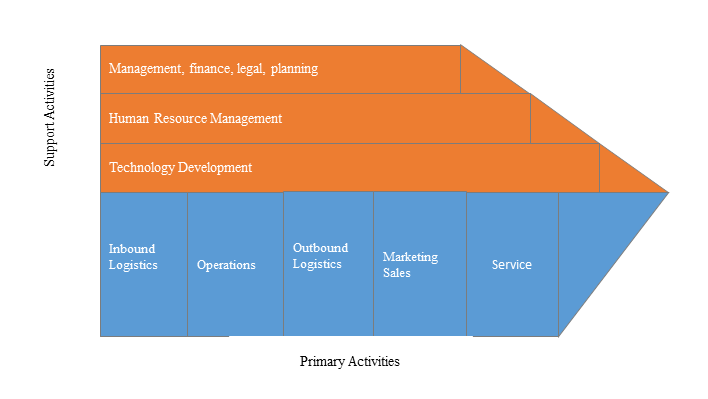
Value chain analysis is a tool to identify activities, within and around the firm and relating these activities to an assessment of competitive strength. Value chain can be analyzed by primary activities and supportive activities. Primary activities include: inbound logistics, operations, outbound logistics, marketing & sales, service. Support activities include: technology development, human resource management, management, finance, legal, planning.
4)SWOT Analysis
SWOT analysis is a tool used to evaluate a company's competitive position by identifying its strengths, weaknesses, opportunities and threats. The strengths and weakness is the inner factor; the opportunities and threats are the external factor. By analyzing the inner and external factors, the analysis can provide the detail information of the position of a player and the characteristics of the industry.
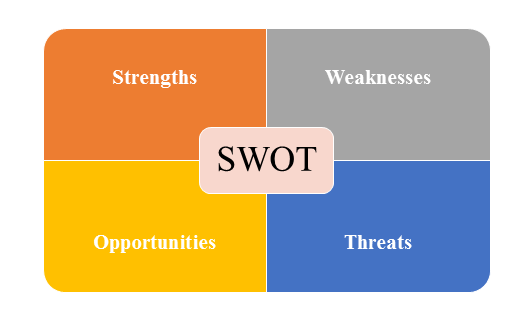
- Strengths describe what the player excels at and separates it from the competition
- Weaknesses stop the player from performing at its optimum level.
- Opportunities refer to favorable external factors that the player can use to give it a competitive advantage.
- Threats refer to factors that have the potential to harm the player.
- Data Sources
| Primary Sources | Secondary Sources |
|---|---|
| Face to face/Phone Interviews with market participants, such as: Manufactures; Distributors; End-users; Experts. Online Survey |
Government/International Organization Data: Annual Report/Presentation/Fact Book Internet Source Information Industry Association Data Free/Purchased Database Market Research Report Book/Journal/News |