Medical Gases Market Report 2026-2031
- Single User License (1 Users) $ 3,500
- Team License (2~5 Users) $ 4,500
- Corporate License (>5 Users) $ 5,500
The global medical gases market size is valued at an estimated range of 11.5 billion USD to 14.5 billion USD in 2026, the market is modeled to expand at a compound annual growth rate (CAGR) within the 4% to 5% interval through 2031. Structural consumption spans mature, value-accretive homecare and acute care ecosystems in North America and Europe, rapidly scaling tertiary hospital networks across Asia-Pacific (led by India, China, and Southeast Asia), and emerging decentralized clinical delivery corridors across Latin America and the Middle East and Africa.
Unlike cyclical merchant industrial gas volumes that track heavy manufacturing, primary metals, and basic chemicals, medical gas consumption decouples from industrial macroeconomic cycles. Demand is underpinned by secular demographic tailwinds, specifically global population aging, rising prevalence of chronic respiratory indications such as Chronic Obstructive Pulmonary Disease (COPD) and obstructive sleep apnea (OSA), and the structural expansion of centralized hospital piped infrastructure in developing nations. Post-pandemic health system capitalization permanently altered the procurement landscape. The World Health Organization documented that peak pandemic conditions accelerated hospital medical oxygen demand more than five-fold across low- and middle-income countries. This historical supply shock precipitated widespread institutional transitions away from fragmented cylinder procurement toward permanently installed vacuum-insulated evaporator (VIE) bulk cryogenic storage, secondary on-site pressure swing adsorption (PSA) infrastructure, and comprehensive Medical Gas Pipeline Systems (MGPS).
The competitive landscape is structured around a multinational oligopoly consisting of Air Liquide, Linde plc, Air Products and Chemicals Inc., Nippon Sanso Holdings, Messer, Sapio Group, SOL S.p.A., and Air Water Inc., which collectively control over 90% of global revenues. Concurrently, regional market share is anchored by specialized domestic champions, including INOX Air Products, PT Samator Indo Gas, Hangyang Group, Jinhong Gas, Sichuan Qiaoyuan Gas, Guangdong Huate Gas, Hubei Heyuan Gas, Yingde Gases, Koike Sanso Kogyo, Pakistan Oxygen Limited, Ghani Chemical Industries, and Ellenbarrie Industrial Gases.
PHARMACEUTICAL REGULATORY MOATS AND ASSET INTEGRATION
Medical gases operate under a stringent dual regulatory paradigm that differentiates them from conventional merchant atmospheric gases. Major health authorities worldwide classify medical gases as prescription drugs or Active Pharmaceutical Ingredients (APIs), while classifying the associated storage vessels, vaporizers, regulators, and distribution pipelines as medical devices. This dual taxonomy establishes severe barriers to entry.
● Drug Designations and Marketing Authorizations
Gas producers cannot commercialize medical gases without country-specific Marketing Authorisations (MA) and Drug Registration Certificates for every molecule, volume specification, and package variant.
- In the European Union, market participation requires compliance with the European Pharmacopoeia and national drug licensing. For example, SOL S.p.A. maintains 146 active Marketing Authorisations across 26 countries, covering 19 European Union member states and 7 non-EU countries.
- In China, domestic producers navigate rigorous National Medical Products Administration (NMPA) certifications. Sichuan Qiaoyuan Gas maintains National Drug Registration Certificates for liquid medical oxygen, and operating units of Hubei Heyuan Gas are licensed under provincial Drug Production Licenses.
- In India, production and wholesale supply are strictly regulated under the statutory licensing provisions of the Drugs and Cosmetics Act, 1940, and the Drugs and Cosmetics Rules, 1945, requiring specialized Form 25 and Form 28 drug manufacturing permits.
● Good Manufacturing Practice and Distribution Rigor
Primary cryogenic air separation units (ASUs), transfilling depots, and secondary chemical synthesis facilities are classified as pharmaceutical manufacturing sites. They must pass routine Good Manufacturing Practice (GMP) and Good Distribution Practice (GDP) audits administered by bodies such as the US FDA, European national medicines agencies, and the Indian Central Drugs Standard Control Organisation (CDSCO).
Operational audits demand continuous in-line analytical verification of critical quality attributes, including assay purity, moisture content, carbon monoxide, and hydrocarbon contamination. Cryogenic transfilling lines require validated cylinder evacuation cycles, vacuum baking, and hydro-testing protocols. Illustrating this regulatory burden, SOL Group reported undergoing 14 national GMP facility audits and 5 GDP logistics inspections within its European footprint in 2025 alone.
● Closed-Loop Cylinder Fleets and Mechanical Safety Standards
To eliminate toxic cross-contamination between industrial and medical supply chains, operators must maintain closed-loop, strictly segregated cylinder asset fleets. Medical containers are subjected to internal ultrasonic cleaning, dedicated vacuum degreasing, hydraulic pressure recertification, and mechanical keying via Pin-Index Safety Systems (PISS) or Compressed Gas Association (CGA) medical valve connections. Regulatory bodies, guided by regional entities including the Asia Industrial Gases Association (AIGA), the European Industrial Gases Association (EIGA), and the CGA, mandate tamper-evident shrink wrapping and batch-traceable pharmacovigilance barcoding across all mobile medical assets.
● Transition to the European Medical Device Regulation (MDR 2017/745)
The regulatory boundary extends past the gaseous molecule to downstream administration hardware. Equipment including vacuum-insulated evaporators, clinical digital manifolds, point-of-care gas mixers, and bedhead terminal units must comply with medical device statutes. In Europe, the complete enforcement of MDR 2017/745 by 2025 eliminated legacy CE-mark self-certification, forcing gas majors to conduct multi-year clinical safety evaluations, re-engineer technical files, and establish permanent post-market surveillance systems for their medical gas delivery equipment.
PRODUCT CLASSIFICATION AND TECHNICAL TAXONOMY
The industry is structured into three primary product segments based on pharmacological action, purity parameters, and clinical utility:
1. Clinical and Therapeutic Gases
- Medical Oxygen (Liquid Medical Oxygen / LMO and Compressed Gas, O2): The dominant high-volume product across the clinical sector. Sourced primarily via fractional cryogenic distillation of ambient air at purities meeting or exceeding 99.5% to 99.6%. It provides foundational life support for hypoxemic patients, mechanical ventilation in intensive care units, emergency resuscitation, and hyperbaric treatment.
- Medical Air: An ultra-pure, dry, oil-free synthetic or compressed gas blend containing 20.9% oxygen and 79.1% nitrogen. Manufactured either via cryogenic blending or through dedicated on-site hospital compressor skids equipped with desiccant drying towers, carbon absorbers, and bacterial filtration systems. Medical air serves as a carrier gas for nebulized medications, an oxygen-diluting balance gas in neonatal mechanical ventilation circuits, and an energy source for pneumatically driven surgical tools, dermatomes, and orthopedic bone saws.
- Therapeutic Nitric Oxide (NO): Delivered in micro-dosing formulations (typically 100 to 1,000 ppm diluted in high-purity nitrogen carrier gas) via specialized ICU electronic delivery platforms. Inhaled nitric oxide acts as a selective pulmonary vasodilator, reducing pulmonary arterial hypertension and improving ventilation-perfusion matching in neonates with Persistent Pulmonary Hypertension of the Newborn (PPHN) and adults with severe Acute Respiratory Distress Syndrome (ARDS), without lowering systemic arterial pressure. Multinationals such as Air Liquide deploy proprietary clinical nitric oxide platforms across hospital intensive care sectors.
2. Anesthetic and Analgesic Gases
- Medical Nitrous Oxide (N2O): Manufactured through the controlled, thermally induced chemical decomposition of ammonium nitrate, followed by extensive caustic and acid scrubbing, catalytic reduction, drying, and cryogenic liquefaction. Nitrous oxide serves as an inhaled anesthetic adjunct and analgesic agent across surgical suites, day-surgery clinics, and dental operatories.
- Medical Xenon (Xe): An ultra-rare noble gas extracted as an atmospheric distillation sub-product (atmospheric presence is approximately 0.087 ppm). Xenon exhibits high clinical efficacy as a non-toxic inhalation anesthetic characterized by remarkable cardiovascular stability, rapid onset and emergence kinetics, and documented neuroprotective and cardioprotective qualities. It is also utilized in specialized functional lung imaging via hyperpolarized xenon-129 magnetic resonance applications.
3. Other Medical Gases
- Medical Carbon Dioxide (CO2): Recovered from chemical and fertilizer industrial off-gas streams and processed to pharmaceutical purity. Sourced primarily for minimally invasive procedures as an insufflation medium during laparoscopy, arthroscopy, and robotic surgeries due to its high blood solubility, non-combustibility, and rapid peritoneal elimination. It is also used as a calibration standard in respiratory physiology assessments, as a cooling medium in dermatological cryosurgery, and as a medium for specialized surgical laser cutting.
- Medical Nitrogen (N2): High-purity gaseous nitrogen powers surgical pneumatic drills and instruments in environments where medical air compressors are unviable. In its liquid cryogenic state (-196 degrees Celsius), nitrogen is extensively utilized for the cryosurgical destruction of benign and malignant dermatological lesions, as well as the long-term biobanking of cellular specimens, cord blood, reproductive gametes, and tissue allografts.
- Liquid Helium for Diagnostic Imaging (LHe): Sourced from geological natural gas extraction and liquefied to 4 Kelvin (-269 degrees Celsius). Liquid helium is indispensable to medical diagnostics, providing cooling to keep the superconducting magnetic coils of hospital Magnetic Resonance Imaging (MRI) scanners below critical temperatures. Helium replenishment contracts form high-margin technical recurring revenue streams for gas distributors.
- Diagnostic and Calibration Gas Mixtures: Encompasses multi-component formulations containing trace carbon monoxide, methane, and acetylene used for measuring the Diffusing Capacity of the Lungs for Carbon Monoxide (DLCO), alongside certified high-precision balance mixtures of oxygen and carbon dioxide for point-of-care arterial blood gas analyzers.
DOWNSTREAM DEMAND VECTORS AND CLINICAL DELIVERY MODELS
Market consumption is delineated across four downstream channels:
● Acute Hospital Inpatient Care
Acute hospital facilities represent the baseline for volumetric consumption. Large institutional medical complexes require centralized, continuous delivery of bulk liquid medical oxygen, compressed air, and specialty surgical gases.
- Global leaders like Air Liquide deliver gas solutions to more than 20,000 hospital sites globally.
- In developing markets, domestic providers establish regional distribution ties. In Indonesia, PT Samator Indo Gas has installed comprehensive medical gas systems across over 280 public and private hospital centers.
- In India, private healthcare operators and provincial governments are deploying between 24,500 and 25,500 additional hospital beds between fiscal 2026 and 2029, directly expanding the addressable base for pipeline gas installations.
Hospitals rely on structural redundancy within their Medical Gas Pipeline Systems (MGPS), deploying secondary and tertiary back-up systems including emergency high-pressure cylinder manifolds and automated switchover banks. Specialized suppliers, such as Pakistan Oxygen Limited with its proprietary OxyMed engineering range, fabricate localized clinical engineering hardware, including ICU ceiling beams, motorized surgical pendants, bedhead terminal assemblies, and digitized pipeline alarm infrastructure.
● Chronic Homecare (Home Healthcare)
Homecare represents the fastest-growing and highest-margin commercial vertical within corporate portfolios. Driven by shifting healthcare economics that prioritize home-based convalescence to relieve overloaded acute facilities, homecare delivery models center on long-term oxygen therapy (LTOT), continuous positive airway pressure (CPAP) for obstructive sleep apnea, non-invasive ventilation (NIV), and home infusion.
- Air Liquide oversees clinical homecare management programs for roughly 2.3 million chronic respiratory patients worldwide.
- Linde plc dominates the North American homecare footprint through operating subsidiaries including Lincare Holdings Inc., American HomePatient, and Option One Home Medical Equipment.
- In Japan, Air Water Inc. and Koike Medical operate home oxygen therapy (HOT) and CPAP rental networks catering to a large elderly demographic.
Homecare operating margins surpass bulk hospital gas sales because revenue is driven by medical hardware leasing (stationary and portable oxygen concentrators), recurring sales of disposable consumables (masks, cannulas, tubing), remote digital monitoring, and clinical home visits by respiratory therapists.
● Diagnostic Imaging and Biobanking
The operational maintenance of the global MRI installed base requires constant liquid helium transfilling to mitigate thermal boil-off and preserve zero-resistance superconductivity. In parallel, the rapid growth of cell and gene therapy, reproductive medicine, and clinical biorepositories drives stable consumption of liquid nitrogen across insulated cryo-storage dewars, supported by specialized vapor-phase management hardware. Pathology laboratories generate recurring requirements for certified instrument-calibration standards.
● Proximity and Ambulatory Healthcare
This sector comprises dental surgeries, outpatient day-surgery facilities, veterinary practices, and municipal emergency paramedic rescue squads. Consumption is characterized by low volumetric demand but high packaged product margins. Core equipment includes small, lightweight aluminum cylinders featuring integrated pressure-reducing valves (VIPRs) and pre-blended 50/50 nitrous oxide-oxygen analgesic mixtures (such as Entonox) designed for rapid pain relief in emergency transport and minor procedures. Furthermore, specialized ophthalmic clinics consume high-purity argon, neon, and fluorine excimer laser gas mixtures to drive refractive LASIK eye surgeries.
COMMERCIAL FULFILLMENT ARCHITECTURE AND VALUE CHAIN ECONOMICS
● Upstream Infrastructure and Feedstock Dynamics
The upstream segment is highly capital- and energy-intensive. Atmospheric air serves as the free primary feedstock for oxygen, nitrogen, and argon, but isolating these molecules requires cryogenic air separation plants powered by multi-stage main air compressors (MAC) and expansion turbines. Upstream profitability is directly exposed to electricity tariffs, cooling water access, and capital equipment costs for cold boxes, vacuum-insulated holding tanks, and fractional columns.
Non-atmospheric medical gases rely on chemical manufacturing inputs: nitrous oxide is dependent on the commercial supply and thermal decomposition of ammonium nitrate, carbon dioxide requires industrial carbon-capture processing, and helium depends on natural gas extraction. Containment systems require specialized raw material conversion into seamless chrome-moly steel cylinders, lightweight aluminum vessels, vacuum-jacketed cryogenic road tankers, and high-pressure brass valve hardware.
● Midstream Refining and Supply Chain Architecture
Midstream operations focus on pharmaceutical-grade purification, transfilling, quality assurance, and multimodal distribution:
- Merchant Bulk Liquid Supply: Bulk liquid constitutes the baseline of high-volume hospital logistics. Cryogenic road tankers deliver liquid medical oxygen to hospital-sited vacuum-insulated evaporators (VIEs). Due to continuous thermal boil-off losses and transportation economics, liquid bulk delivery operates within an optimal logistical radius of 200 to 250 kilometers around primary ASUs.
- Packaged Cylinder Networks: Compressed medical gases (charged between 137 and 200 bar) are distributed via seamless steel or composite cylinders and multi-cylinder bundles. Cylinders provide secondary backup redundancy for acute facilities and direct clinical delivery for remote hospitals, clinics, and emergency responders. Operators manage dense, licensed transfilling depots where bulk liquids are vaporized, compressed, and filled into dedicated medical containers under strict pharmacopoeia protocols.
- On-Site Non-Cryogenic Generation (PSA Units): Pressure Swing Adsorption units separate medical oxygen directly from ambient air using zeolite molecular sieves. Although historically restricted by pharmacopoeia limits to purities of 93% (+/- 3%), on-site PSA systems gained market acceptance as emergency backup systems and decentralized primary solutions for rural or isolated medical networks where cryogenic logistics fail.
- Contracting Frameworks and Telemetry: Acute hospital supply is dominated by public or private competitive tenders spanning one to five years. Profitability hinges on equipment leasing agreements; gas suppliers typically retain ownership of the hospital VIE tanks, vaporizers, and telemetry systems. Long-term contracts incorporate pass-through indexing formulas linked to electricity tariffs, diesel freight surcharges, and consumer price indexes.
Digital packaging innovations are transforming fleet management. Air Liquide has scaled more than 130,000 OYAN connected cylinders across European healthcare providers alongside its Intelli-OX platform in the United States, utilizing digital displays and real-time contents tracking. Nippon Sanso Holdings deploys its RingWell cloud architecture to manage medical gas inventory remotely, and Pakistan Oxygen Limited fields its TeleTel telemetry system to monitor customer tank levels and homecare delivery in real time.
REGIONAL MARKET DYNAMICS
● North America
The North American market, dominated by the United States, represents a mature medical gas and home healthcare ecosystem. Macroeconomic demand is driven by the clinical burden of chronic respiratory conditions, extensive hospital procedural volumes, and high healthcare spending per capita. Home respiratory therapy makes up an outsized portion of market profitability. Linde plc exercises considerable pricing influence and distribution scale in this segment through its Lincare, American HomePatient, and Option One Home Medical Equipment networks. Air Products and Chemicals Inc. remains a key domestic merchant supplier, maintaining bulk liquid contracts with clinical hospital systems alongside specialized clinical packaged gas supply networks. The market is characterized by high integration of digital cylinder assets and structured insurance reimbursement frameworks for respiratory therapies.
● Asia-Pacific
Asia-Pacific forms the fastest-growing region, driven by public investments in clinical infrastructure, rising hospital bed capacity, and expanding domestic industrial gas production capabilities.
- India: Medical gases represent an estimated 10% to 12% of the broader Indian industrial gas sector. While multinational corporations command extensive capacity, domestic manufacturers are aggressively expanding market share. Linde India operates cryogenic separation facilities and dedicated tanker fleets serving major hospital networks. Air Water India Pvt. Ltd. (AWIPL) has expanded its domestic footprint, managing large ASUs in Jamshedpur (3 x 875 tonnes per day), Bellary (1,800 tonnes per day), and Hyderabad (65 tonnes per day), supported by 132 cryogenic road tankers delivering to hospital groups including Manipal Hospitals and Fortis Healthcare. Air Liquide India expanded output at its Mathura facility by adding over 300 tonnes per day of liquid capacity, commissioned a 200 tonne-per-day ASU in Gujarat, and acquired NovaAir in October 2025 to scale its distribution footprint. Concurrently, domestic giant INOX Air Products maintains a leading market position, driving liquid medical oxygen and nitrous oxide supply. Regional producers, including Ellenbarrie Industrial Gases, support the eastern and southern industrial and clinical corridors.
- Japan: Characterized by an aging demographic that drives constant clinical demand for Home Oxygen Therapy (HOT) and advanced operating room infrastructure. The competitive arena is populated by sophisticated domestic majors: Air Water Inc. executes turnkey hospital medical engineering, surgical suite modernization, and nationwide home oxygen services; Nippon Sanso Holdings coordinates clinical gas logistics and digital remote patient oversight through Taiyo Nippon Sanso, Nihon Megacare, and IMI Co.; Koike Sanso Kogyo operates specialized transfilling and respiratory medical hardware production through its consolidated subsidiary, Koike Medical Co., Ltd.
- China: The Chinese medical gas landscape is transitioning from multinational dominance to domestic independence. While global majors retain accounts across elite Tier-3 urban hospitals, domestic producers, including Hangyang Group, Jinhong Gas, Sichuan Qiaoyuan Gas, and Yingde Gases, are capturing substantial market share. This domestic expansion is supported by state-driven healthcare localization directives and local manufacturing investments.
- Southeast Asia: Representing a high-growth territory within the Asia-Pacific basin, Southeast Asia is benefiting from infrastructure improvements and expanded national health expenditure. Indonesia serves as a prime market example: the Indonesian State Budget allocated 218.5 trillion IDR to healthcare in 2025, expanding to 244 trillion IDR in 2026. PT Samator Indo Gas Tbk leads this regional market, having supplied more than 1.6 million medical gas cylinders and installed medical pipeline engineering across more than 280 public and private hospital centers nationwide.
● Europe
Europe is characterized by stringent pharmaceutical regulatory oversight and sophisticated home respiratory care models. The competitive arena is led by Air Liquide, Linde plc, Messer, Sapio Group, and SOL S.p.A., alongside operations from Air Products and Chemicals Inc. and Nippon Sanso Holdings. Profitability is influenced by state healthcare reimbursement schemes, where national health systems across France, Germany, and the United Kingdom tie homecare service payouts to documented patient therapeutic adherence. The operational landscape absorbed substantial capital adjustments in 2025 due to mandatory compliance costs associated with the EU Medical Device Regulation (MDR 2017/745).
● Latin America
Latin America balances bulk hospital consumption with an expanding private home healthcare sector. Multinational operators and established European specialists steer regional activity. Air Liquide reports expanding homecare patient registries in Brazil and neighboring economies. SOL S.p.A. has established an operational homecare presence across Brazil through specialized subsidiaries, including BLA Servicos Hospitalares, Global Care, JML Servicos Hospitalares, Pronep Lar, Unit Care, and Vitoria Medicina Domiciliar, alongside regional medical and industrial operations in Ecuador (via Swissgas) and Peru (via Industrias Criogenica del Peru). Linde commands significant distribution capacity across South America through historical operating networks, including Praxair do Brasil, Praxair Argentina, Praxair Chile, and Oxigenos de Colombia.
● Middle East and Africa
The Middle East and Africa region presents distinct market realities between resource-rich Gulf states and underserved Sub-Saharan nations.
- Sub-Saharan Africa: Public health authorities prioritize expanding foundational access to medical oxygen. Air Liquide scaled its Access Oxygen corporate program, delivering medical oxygen to an estimated 3,449,284 individuals across 384 healthcare centers throughout South Africa, Senegal, Kenya, and Mali in 2025. Air Liquide further strengthened regional supply resilience through the acquisition and operational integration of major Sasol air separation assets in South Africa.
- Middle East: Healthcare investments focus on modern hospital pipeline systems and high-end specialized therapies. Air Liquide operates healthcare joint ventures, including Vitalaire Arabia LLC in Saudi Arabia, with associated operations in Egypt (Air Liquide Alexandria) and Tunisia. SOL S.p.A. has secured hospital supply Marketing Authorisations in Morocco through Flosit Pharma, established Vivisol Kuwait WLL, and formed healthcare equipment distribution partnerships in Dubai to capture specialized regional demand.
OPPORTUNITIES AND CHALLENGES
● OPPORTUNITIES
- High-Margin Economics of Home Respiratory Therapy: The structural aging of the population across Japan, North America, and Europe has driven long-term demand for chronic respiratory support, specifically for COPD, sleep apnea, and neuromuscular conditions. Homecare presents a compelling margin profile: while bulk liquid medical oxygen sold to acute hospitals functions as a commoditized molecule sensitive to competitive tendering, homecare operates as an integrated service platform. Revenue is driven by equipment leasing, recurring consumable delivery, and software-enabled therapeutic adherence monitoring, insulating suppliers from upstream commodity volatility.
- Healthcare Infrastructure Expansion in Emerging Economies: Developing countries are systematically increasing hospital bed capacity and upgrading clinical infrastructure. National initiatives, including India's Ayushman Bharat, Pradhan Mantri Jan Arogya Yojana (PMJAY), and the National Oxygen Stewardship Programme, alongside expanding public health allocations in Indonesia and the Middle East, are replacing fragmented cylinder systems with integrated hospital pipelines. This structural transition creates stable multi-decade anchor customer relationships for suppliers that provide both cryogenic molecule delivery and proprietary VIE storage tank leasing.
- Digital Fleet Intelligence and Telemetry Integration: The integration of Internet of Things (IoT) sensors, cloud-connected digital contents gauges, and remote telemetry transmitters across mobile cylinder fleets and stationary hospital tanks is transforming industry economics. Proprietary platforms, such as Air Liquide's OYAN and Intelli-OX, Nippon Sanso's RingWell, and Pakistan Oxygen's TeleTel, provide hospitals with automated replenishment alerts and usage tracking. This continuous data visibility limits cylinder hoarding, reduces asset loss rates, optimizes tanker logistics schedules, and establishes switching barriers that support customer retention during contract renewal cycles.
● CHALLENGES
- Escalating Regulatory Compliance and MDR Overheads: The classification of medical gases as finished prescription pharmaceuticals, coupled with the enforcement of the European Union Medical Device Regulation (MDR 2017/745), imposes substantial operational costs. Maintaining active Marketing Authorisations across dozens of legal jurisdictions requires specialized pharmacovigilance teams, regular analytical validation of cleanroom filling lines, and continuous quality system updates. Gas suppliers face capital commitments to maintain analytical infrastructure (such as gas chromatography and trace-hydrocarbon analyzers), and must fund clinical safety documentation for gas delivery hardware, which compresses margins for smaller market participants.
- Energy Intensity and Upstream Input Cost Exposure: The production of medical gases is fundamentally dependent on high-voltage electricity to drive cryogenic air separation compressors. Sharp swings in regional industrial power rates, carbon-pricing adjustments, and diesel logistics costs introduce margin risk for bulk liquid contracts. Because public hospital supply contracts frequently feature rigid administrative pricing structures or delayed price-escalation indexing, suppliers that do not implement real-time pass-through clauses risk operational margin compression during energy price spikes.
- Institutional Pricing Deflation and Public Tendering Constraints: Public hospital systems and state healthcare authorities operate under persistent fiscal constraints, often utilizing centralized reverse auctions to lower medical gas procurement costs. Tenders often commoditize the gaseous molecule, driving downward price pressure on bulk liquid oxygen and standard nitrous oxide. To protect gross margins, gas producers must transition their sales models toward bundled, differentiated clinical service packages, integrating the supply of the molecule with hardware maintenance, clinical training, digital telemetry, and homecare follow-up. Suppliers that cannot provide these integrated services face volume displacement by localized lower-cost debulkers and merchant intermediaries.
1.1 Executive Summary and Scope of the Study 1
1.2 Research Design and Multi-Factor Modeling Architecture 2
1.3 Primary Data Sourcing and Expert Verification Protocols 3
1.4 Secondary Data Mining and Cross-Validation Engines 4
1.5 Key Assumptions, Currency Conversions, and Forecasting Parameters 5
1.6 Acronyms and Abbreviations Directory 6
Chapter 2 Global Medical Gases Market Overview and Macroeconomic Context 7
2.1 Market Definition, Nomenclature, and Pharmacopeial Classifications 7
2.2 Global Healthcare Expenditure Trends and Hospital Infrastructure Modernization 8
2.3 Aging Demographics, Chronic Respiratory Morbidity, and Epidemiological Pressures 10
2.4 Energy Price Volatility, Power Grid Reliability, and Air Separation Plant Economics 12
2.5 Global Medical Gases Market Revenue and Volume Historical Baseline (2021-2025) 13
2.6 Mid-Term Forecast Outlook and Growth Trajectory (2026-2031) 14
Chapter 3 Global Medical Gases Industry Value Chain and Regulatory Framework 15
3.1 Upstream Raw Gas Sourcing, Power Ingestion, and Equipment Manufacturing Landscape 15
3.2 Midstream Cryogenic Air Separation Units (ASU), Synthesis, and Purification Architecture 16
3.3 Bulk Liquid Logistics, Microbulk Distribution, and High-Pressure Cylinder Handling 18
3.4 Point-of-Care Medical Gas Pipeline Systems (MGPS) and Secondary Delivery Equipment 19
3.5 Global Regulatory Compliance: Good Manufacturing Practice (GMP) for Medicinal Gases 20
3.6 Environmental, Health, and Safety (EHS) Protocols and Decarbonization Mandates 21
3.7 Value Chain Margin Distribution and Cost Composition Breakdown 22
Chapter 4 Global Medical Gases Production, Capacity and Cross-Border Trade Dynamics 23
4.1 Global Cryogenic Air Separation and Chemical Synthesis Infrastructure Footprint 23
4.2 Regional Capacity Utilization Rates and Onsite Facility Allocation Dynamics 24
4.3 Transnational Trade Architecture and Inter-Regional Supply Flows 25
4.4 Export Volume and Value Matrix Across Key Manufacturing Hubs (2021-2026) 26
4.5 Import Dependency and Supply Risk Profiling Across Net Consuming Markets 28
Chapter 5 Global Medical Gases Market Breakdown by Product Type 31
5.1 Clinical & Therapeutic Gases Overview and Market Trajectory 31
5.1.1 Medical Oxygen (Cryogenic Liquid and Compressed Gas) 32
5.1.2 Medical Air (Synthetic and Compressor-Purified) 34
5.1.3 Nitric Oxide (Inhaled Vasodilator Formulations) 35
5.2 Anesthetic & Analgesic Gases Overview and Market Trajectory 36
5.2.1 Medical Nitrous Oxide (Pre-Mixed and Pure Grades) 37
5.2.2 Medical Xenon (Neuroprotective and Anesthetic Applications) 38
5.3 Other Medical Gases Overview and Market Trajectory 39
5.3.1 Medical Carbon Dioxide (Insufflation and Cryotherapy) 39
5.3.2 Medical Nitrogen (Cryosurgery and Biological Preservation) 40
5.3.3 Specialized Medical Calibration and Laboratory Gas Mixtures 41
Chapter 6 Global Medical Gases Market Breakdown by Downstream Application 42
6.1 Acute Hospital Inpatient Care 42
6.2 Homecare and Long-Term Respiratory Management 46
6.3 Diagnostic Imaging, Laboratory Analysis, and Biobanking 49
6.4 Other Outpatient Clinics, Dental Surgery, and Veterinary Medical Care 50
Chapter 7 North America Medical Gases Market Analysis 51
7.1 Regional Regulatory Standards (US FDA, Health Canada) and Procurement Patterns 51
7.2 United States Production Infrastructure, Clinical Demand, and Forecast (2021-2031) 52
7.3 Canada Healthcare Modernization, Distributed Networks, and Forecast (2021-2031) 54
7.4 Cross-Border Pipeline and Distribution Logistics Across North America 56
7.5 North America Market Revenue, Volume, and Pricing Differential Analysis 57
Chapter 8 Europe Medical Gases Market Analysis 58
8.1 European Medicines Agency (EMA) Medicinal Licensing and Harmonization 58
8.2 Germany Production Clusters, Inpatient Demand, and Forecast (2021-2031) 59
8.3 France Hospital Procurement Framework and Forecast (2021-2031) 60
8.4 United Kingdom National Health Service (NHS) Delivery Models and Forecast (2021-2031) 61
8.5 Italy Regional Cryogenic Distribution Economics and Forecast (2021-2031) 62
8.6 Spain Public Health Infrastructure Dynamics and Forecast (2021-2031) 63
8.7 Rest of Europe Market Consolidation Overview 64
Chapter 9 Asia-Pacific Medical Gases Market Analysis 65
9.1 Macro-Demographics, Hospital Bed Expansion, and Universal Health Coverage 65
9.2 China Production Self-Sufficiency, ASU Investments, and Forecast (2021-2031) 66
9.3 Japan & South Korea Advanced Geriatric Healthcare Infrastructure and Forecast (2021-2031) 68
9.4 India & Pakistan Public Health Procurement, Tier-2 Hospitalization, and Forecast (2021-2031) 69
9.5 Southeast Asia Decentralized Archipelagic Gas Logistics and Forecast (2021-2031) 71
9.6 Rest of Asia-Pacific Clinical and Industrial Gas Convergence Dynamics 73
Chapter 10 Latin America and Middle East & Africa Medical Gases Market Analysis 74
10.1 Latin America Regional Overview and Healthcare Resource Disparities 74
10.1.1 Brazil Unified Health System (SUS) Expansion and Forecast (2021-2031) 75
10.1.2 Mexico Institutional Hospital Networks and Forecast (2021-2031) 76
10.1.3 Rest of Latin America Clinical Logistics and Infrastructure Bottlenecks 77
10.2 Middle East & Africa Regional Overview and Healthcare Modernization Programs 78
10.2.1 Saudi Arabia Vision 2030 Healthcare Transformation and Forecast (2021-2031) 79
10.2.2 United Arab Emirates Specialized Tertiary Hubs and Forecast (2021-2031) 80
10.2.3 Rest of Middle East & Africa Supply Resilience and Bottling Networks 81
Chapter 11 Competitive Landscape and Strategic Industry Benchmarking 82
11.1 Global Competitive Matrix and Four-Firm Concentration Ratio (CR4) 82
11.2 Onsite Long-Term Hospital Pipelining vs. Merchant Cylinder Channel Control 83
11.3 Mergers, Acquisitions, Asset Divestitures, and Joint Venture Strategic Mapping 84
11.4 Entry Barriers, Capital Intensity, Licensing Compliance, and Switching Costs 85
Chapter 12 Corporate Intelligence: Key Market Players 86
12.1 Air Liquide 86
12.1.1 Corporate Profile, Healthcare Division Structure, and Global Footprint 86
12.1.2 Strategic SWOT Analysis 87
12.1.3 Medical Gases Financial Performance, Cost Structure, and Market Share 88
12.2 Linde plc 89
12.2.1 Corporate Profile, Healthcare Division Structure, and Global Footprint 89
12.2.2 Strategic SWOT Analysis 90
12.2.3 Medical Gases Financial Performance, Cost Structure, and Market Share 91
12.3 Air Products and Chemicals Inc. 92
12.3.1 Corporate Profile, Healthcare Division Structure, and Global Footprint 92
12.3.2 Strategic SWOT Analysis 93
12.3.3 Medical Gases Financial Performance, Cost Structure, and Market Share 94
12.4 Nippon Sanso Holdings 95
12.4.1 Corporate Profile, Healthcare Division Structure, and Global Footprint 95
12.4.2 Strategic SWOT Analysis 96
12.4.3 Medical Gases Financial Performance, Cost Structure, and Market Share 97
12.5 Messer 98
12.5.1 Corporate Profile, Healthcare Division Structure, and Global Footprint 98
12.5.2 Strategic SWOT Analysis 99
12.5.3 Medical Gases Financial Performance, Cost Structure, and Market Share 100
12.6 Sapio Group 101
12.6.1 Corporate Profile, Healthcare Division Structure, and Global Footprint 101
12.6.2 Strategic SWOT Analysis 102
12.6.3 Medical Gases Financial Performance, Cost Structure, and Market Share 103
12.7 SOL S.p.A. 104
12.7.1 Corporate Profile, Healthcare Division Structure, and Global Footprint 104
12.7.2 Strategic SWOT Analysis 105
12.7.3 Medical Gases Financial Performance, Cost Structure, and Market Share 106
12.8 Air Water Inc. 107
12.8.1 Corporate Profile, Healthcare Division Structure, and Global Footprint 107
12.8.2 Strategic SWOT Analysis 108
12.8.3 Medical Gases Financial Performance, Cost Structure, and Market Share 109
12.9 Koike Sanso Kogyo 110
12.9.1 Corporate Profile, Healthcare Division Structure, and Global Footprint 110
12.9.2 Strategic SWOT Analysis 111
12.9.3 Medical Gases Financial Performance, Cost Structure, and Market Share 112
12.10 Hangyang Group 113
12.10.1 Corporate Profile, Healthcare Division Structure, and Global Footprint 113
12.10.2 Strategic SWOT Analysis 114
12.10.3 Medical Gases Financial Performance, Cost Structure, and Market Share 115
12.11 Jinhong Gas 116
12.11.1 Corporate Profile, Healthcare Division Structure, and Global Footprint 116
12.11.2 Strategic SWOT Analysis 117
12.11.3 Medical Gases Financial Performance, Cost Structure, and Market Share 118
12.11.4 Specialty Purification Technology and In-Hospital Engineering Service Depth 118
12.12 Yingde Gases Group Company Limited 119
12.12.1 Corporate Profile, Healthcare Division Structure, and Global Footprint 119
12.12.2 Strategic SWOT Analysis 120
12.12.3 Medical Gases Financial Performance, Cost Structure, and Market Share 121
12.13 Sichuan Qiaoyuan Gas 122
12.13.1 Corporate Profile, Healthcare Division Structure, and Global Footprint 122
12.13.2 Strategic SWOT Analysis 123
12.13.3 Medical Gases Financial Performance, Cost Structure, and Market Share 124
12.14 Guangdong Huate Gas 125
12.14.1 Corporate Profile, Healthcare Division Structure, and Global Footprint 125
12.14.2 Strategic SWOT Analysis 126
12.14.3 Medical Gases Financial Performance, Cost Structure, and Market Share 127
12.15 Hubei Heyuan Gas 128
12.15.1 Corporate Profile, Healthcare Division Structure, and Global Footprint 128
12.15.2 Strategic SWOT Analysis 129
12.15.3 Medical Gases Financial Performance, Cost Structure, and Market Share 130
12.16 PT Samator Indo Gas Tbk 131
12.16.1 Corporate Profile, Healthcare Division Structure, and Global Footprint 131
12.16.2 Strategic SWOT Analysis 132
12.16.3 Medical Gases Financial Performance, Cost Structure, and Market Share 133
12.17 INOX Air Products Limited 134
12.17.1 Corporate Profile, Healthcare Division Structure, and Global Footprint 134
12.17.2 Strategic SWOT Analysis 135
12.17.3 Medical Gases Financial Performance, Cost Structure, and Market Share 136
12.18 Pakistan Oxygen Limited 137
12.18.1 Corporate Profile, Healthcare Division Structure, and Global Footprint 137
12.18.2 Strategic SWOT Analysis 138
12.18.3 Medical Gases Financial Performance, Cost Structure, and Market Share 139
12.19 Ghani Chemical Industries 140
12.19.1 Corporate Profile, Healthcare Division Structure, and Global Footprint 140
12.19.2 Strategic SWOT Analysis 141
12.19.3 Medical Gases Financial Performance, Cost Structure, and Market Share 142
12.20 Ellenbarrie Industrial Gases 143
12.20.1 Corporate Profile, Healthcare Division Structure, and Global Footprint 143
12.20.2 Strategic SWOT Analysis 144
12.20.3 Medical Gases Financial Performance, Cost Structure, and Market Share 145
Table 2 Global Medical Gases Market Revenue and Growth Projections (2021-2031) 13
Table 3 Global Medical Gases Market Volume and Year-on-Year Growth (2021-2031) 14
Table 4 Cost Structure Breakdown of Medical Gas Production via Cryogenic ASU 22
Table 5 Global Operating Capacity of Medical-Grade Air Separation Units by Region (2021-2026) 24
Table 6 Global Medical Gas Cross-Border Trade Flow Matrix by Country Pair (2021-2026) 26
Table 7 Top Medical Gas Exporting Countries by Volume and Dollar Value (2021-2026) 27
Table 8 Top Medical Gas Net Importing Countries and Vulnerability Scorecard (2021-2026) 28
Table 9 Global Medical Gases Market Revenue by Product Type (2021-2031) 31
Table 10 Global Clinical & Therapeutic Gases Market Revenue by Sub-Segment (2021-2031) 32
Table 11 Global Medical Oxygen Consumption Volume and Revenue by Delivery Mode (2021-2031) 33
Table 12 Global Medical Air Market Value and Installation Mode (2021-2031) 34
Table 13 Global Nitric Oxide Market Revenue and Specialty Dose Projections (2021-2031) 35
Table 14 Global Anesthetic & Analgesic Gases Revenue by Sub-Segment (2021-2031) 36
Table 15 Global Medical Nitrous Oxide Consumption and Pricing Dynamics (2021-2031) 37
Table 16 Global Medical Xenon Supply Volume, Pricing, and Market Value (2021-2031) 38
Table 17 Global Other Medical Gases Revenue by Sub-Segment (2021-2031) 39
Table 18 Global Medical Carbon Dioxide Market Revenue and Volume (2021-2031) 40
Table 19 Global Medical Nitrogen Market Revenue and Cryogenic Demand (2021-2031) 41
Table 20 Global Medical Gases Market Revenue by Downstream Application (2021-2031) 42
Table 21 Acute Hospital Inpatient Care Medical Gas Revenue by Facility Type (2021-2031) 43
Table 22 Intensive Care Unit Medical Gas Procurement Volume by Tier (2021-2031) 44
Table 23 Surgical Suites and Operating Theater Gas Delivery Volume (2021-2031) 45
Table 24 Emergency and Rapid Response Gas Logistics Revenue (2021-2031) 46
Table 25 Homecare Medical Gases Market Value by Disease Indication (2021-2031) 47
Table 26 Home Oxygen Therapy Patient Population and Cylinder/Concentrator Volume (2021-2031) 48
Table 27 Diagnostic Imaging and Biobanking Cryogenic Gas Consumption (2021-2031) 49
Table 28 Outpatient, Dental, and Ambulatory Surgical Centers Gas Demand (2021-2031) 50
Table 29 North America Medical Gases Market Revenue by Product Type (2021-2031) 51
Table 30 North America Medical Gases Market Revenue by Application (2021-2031) 52
Table 31 United States Medical Gases Market Volume, Value, and Channel Breakdown (2021-2031) 53
Table 32 Canada Medical Gases Market Volume, Value, and Channel Breakdown (2021-2031) 55
Table 33 Europe Medical Gases Market Revenue by Product Type (2021-2031) 58
Table 34 Europe Medical Gases Market Revenue by Application (2021-2031) 59
Table 35 Germany Medical Gases Market Volume, Value, and Procurement Split (2021-2031) 60
Table 36 France Medical Gases Market Volume, Value, and Procurement Split (2021-2031) 61
Table 37 United Kingdom Medical Gases Market Volume, Value, and NHS Contracts (2021-2031) 62
Table 38 Italy Medical Gases Market Volume, Value, and Tender Pricing (2021-2031) 63
Table 39 Spain Medical Gases Market Volume, Value, and Tender Pricing (2021-2031) 64
Table 40 Asia-Pacific Medical Gases Market Revenue by Product Type (2021-2031) 65
Table 41 Asia-Pacific Medical Gases Market Revenue by Application (2021-2031) 66
Table 42 China Medical Gases Market Volume, Revenue, and Provincial Supply Hubs (2021-2031) 67
Table 43 Japan Medical Gases Market Volume, Revenue, and Distribution Tiers (2021-2031) 68
Table 44 India Medical Gases Market Volume, Revenue, and Hospital Accreditation Split (2021-2031) 70
Table 45 Indonesia Medical Gases Market Volume, Revenue, and Inter-Island Logistics (2021-2031) 71
Table 46 Pakistan Medical Gases Market Volume, Revenue, and Local Production (2021-2031) 73
Table 47 Latin America Medical Gases Market Revenue by Country (2021-2031) 74
Table 48 Brazil Medical Gases Market Volume, Revenue, and SUS Distribution (2021-2031) 75
Table 49 Mexico Medical Gases Market Volume, Revenue, and Hospital Demand (2021-2031) 76
Table 50 Middle East & Africa Medical Gases Market Revenue by Country (2021-2031) 78
Table 51 Saudi Arabia Medical Gases Market Volume, Revenue, and Vision 2030 Expansions (2021-2031) 79
Table 52 United Arab Emirates Medical Gases Market Volume, Revenue, and Medical Hubs (2021-2031) 80
Table 53 Global Medical Gases Market Share Matrix for Leading Operators (2021-2026) 83
Table 54 Air Liquide Medical Gases Revenue, Cost and Gross Margin (2021-2026) 88
Table 55 Linde plc Medical Gases Revenue, Cost and Gross Margin (2021-2026) 91
Table 56 Air Products and Chemicals Inc. Medical Gases Revenue, Cost and Gross Margin (2021-2026) 94
Table 57 Nippon Sanso Holdings Medical Gases Revenue, Cost and Gross Margin (2021-2026) 97
Table 58 Messer Medical Gases Revenue, Cost and Gross Margin (2021-2026) 100
Table 59 Sapio Group Medical Gases Revenue, Cost and Gross Margin (2021-2026) 103
Table 60 SOL S.p.A. Medical Gases Revenue, Cost and Gross Margin (2021-2026) 106
Table 61 Air Water Inc. Medical Gases Revenue, Cost and Gross Margin (2021-2026) 109
Table 62 Koike Sanso Kogyo Medical Gases Revenue, Cost and Gross Margin (2021-2026) 112
Table 63 Hangyang Group Medical Gases Revenue, Cost and Gross Margin (2021-2026) 115
Table 64 Jinhong Gas Medical Gases Revenue, Cost and Gross Margin (2021-2026) 118
Table 65 Yingde Gases Group Company Limited Medical Gases Revenue, Cost and Gross Margin (2021-2026) 121
Table 66 Sichuan Qiaoyuan Gas Medical Gases Revenue, Cost and Gross Margin (2021-2026) 124
Table 67 Guangdong Huate Gas Medical Gases Revenue, Cost and Gross Margin (2021-2026) 127
Table 68 Hubei Heyuan Gas Medical Gases Revenue, Cost and Gross Margin (2021-2026) 130
Table 69 PT Samator Indo Gas Tbk Medical Gases Revenue, Cost and Gross Margin (2021-2026) 133
Table 70 INOX Air Products Limited Medical Gases Revenue, Cost and Gross Margin (2021-2026) 136
Table 71 Pakistan Oxygen Limited Medical Gases Revenue, Cost and Gross Margin (2021-2026) 139
Table 72 Ghani Chemical Industries Medical Gases Revenue, Cost and Gross Margin (2021-2026) 142
Table 73 Ellenbarrie Industrial Gases Medical Gases Revenue, Cost and Gross Margin (2021-2026) 145
Figure 1 Global Medical Gases Market Research Methodology Architecture 3
Figure 2 Secondary Data Verification and Triangulation Model 5
Figure 3 Medical Gases Pharmacopeia Compliance and Purity Standards 7
Figure 4 Global Healthcare Expenditure vs. Medical Gas Consumption Intensity 9
Figure 5 Epidemiological Incidence of Chronic Respiratory Conditions (2021-2031) 11
Figure 6 Global Medical Gases Revenue Growth Curve (2021-2031) 13
Figure 7 Global Medical Gases Volume Progression in Million Normal Cubic Meters (2021-2031) 14
Figure 8 End-to-End Medical Gas Supply Chain and Value Architecture 17
Figure 9 Last-Mile Hospital Gas Distribution Flow: Bulk Tank to Terminal Unit 19
Figure 10 Medical Gas Production and Supply Cost Structure Breakdown 22
Figure 11 Global Map of Medical Cryogenic Air Separation Facilities 24
Figure 12 Major Cross-Border Medical Gas Trade Routes and Corridor Densities 25
Figure 13 Share of Global Medical Gas Exports by Key Manufacturing Nations (2026) 27
Figure 14 Net Import Reliance and Vulnerability Index for Consuming Regions 29
Figure 15 Global Medical Gases Market Breakdown by Product Type (2021-2031) 31
Figure 16 Medical Oxygen Demand Curve by Inpatient vs. Ambulatory Modes 33
Figure 17 Medical Air Compression vs. Synthetic Blending Share (2021-2031) 34
Figure 18 Medical Nitric Oxide Clinical Adoption Trajectory (2021-2031) 36
Figure 19 Anesthetic & Analgesic Gases Market Share Distribution (2026) 37
Figure 20 Global Rare Gas Market: Medical Xenon Extraction and Supply Balance 38
Figure 21 Medical Carbon Dioxide Consumption by Minimally Invasive Surgical Volume 40
Figure 22 Global Medical Gases Application Share Breakdown (2026 vs. 2031) 43
Figure 23 Hospital ICU Bed Expansion Correlation with Medical Oxygen Draw 45
Figure 24 Operating Theater Expansion and Demand for Inhaled Analgesics 46
Figure 25 Home Respiratory Care Market Penetration by Delivery Architecture 48
Figure 26 Cryogenic Biobanking and Diagnostic Gas Demand Drivers 50
Figure 27 North America Medical Gases Market Revenue Forecast (2021-2031) 53
Figure 28 United States Inpatient vs. Homecare Gas Consumption Split 54
Figure 29 Canada Provincial Medical Gas Supply Network Distribution 56
Figure 30 Europe Medical Gases Market Revenue Forecast (2021-2031) 58
Figure 31 Germany Hospital Bed Occupancy vs. Bulk Liquid Oxygen Ingestion 60
Figure 32 France Medical Gas Supply Pipeline and Retail Delivery Structure 61
Figure 33 United Kingdom Long-Term Oxygen Therapy (LTOT) Homecare Demographics 62
Figure 34 Asia-Pacific Medical Gases Market Share by Country (2026) 66
Figure 35 China Clinical Gas Market Growth Driven by Tier-3 Hospital Additions 67
Figure 36 Japan Aging Index and Homecare Medical Oxygen Consumption 69
Figure 37 India Medical Oxygen Grid Expansion: Cryogenic Storage at District Hospitals 70
Figure 38 Indonesia Inter-Island Logistics Lead-Time and Distribution Hubs 72
Figure 39 Pakistan Medical Gas Demand vs. Domestic ASU Installed Capacity 73
Figure 40 Latin America Medical Gases Market Trajectory by Country (2021-2031) 75
Figure 41 Brazil Medical Gas Ingestion by Regional Health Authorities 76
Figure 42 Middle East & Africa Medical Gases Market Revenue Forecast (2021-2031) 78
Figure 43 Saudi Arabia Healthcare Infrastructure Investment Pipeline to 2031 80
Figure 44 Global Medical Gases Market Concentration: Tier-1 Dominance Analysis 82
Figure 45 Strategic Porter's Five Forces Analysis for the Global Medical Gas Sector 85
Figure 46 Air Liquide Medical Gases Market Share (2021-2026) 88
Figure 47 Linde plc Medical Gases Market Share (2021-2026) 91
Figure 48 Air Products and Chemicals Inc. Medical Gases Market Share (2021-2026) 94
Figure 49 Nippon Sanso Holdings Medical Gases Market Share (2021-2026) 97
Figure 50 Messer Medical Gases Market Share (2021-2026) 100
Figure 51 Sapio Group Medical Gases Market Share (2021-2026) 103
Figure 52 SOL S.p.A. Medical Gases Market Share (2021-2026) 106
Figure 53 Air Water Inc. Medical Gases Market Share (2021-2026) 109
Figure 54 Koike Sanso Kogyo Medical Gases Market Share (2021-2026) 112
Figure 55 Hangyang Group Medical Gases Market Share (2021-2026) 115
Figure 56 Jinhong Gas Medical Gases Market Share (2021-2026) 118
Figure 57 Yingde Gases Group Company Limited Medical Gases Market Share (2021-2026) 121
Figure 58 Sichuan Qiaoyuan Gas Medical Gases Market Share (2021-2026) 124
Figure 59 Guangdong Huate Gas Medical Gases Market Share (2021-2026) 127
Figure 60 Hubei Heyuan Gas Medical Gases Market Share (2021-2026) 130
Figure 61 PT Samator Indo Gas Tbk Medical Gases Market Share (2021-2026) 133
Figure 62 INOX Air Products Limited Medical Gases Market Share (2021-2026) 136
Figure 63 Pakistan Oxygen Limited Medical Gases Market Share (2021-2026) 139
Figure 64 Ghani Chemical Industries Medical Gases Market Share (2021-2026) 142
Figure 65 Ellenbarrie Industrial Gases Medical Gases Market Share (2021-2026) 145
Research Methodology
- Market Estimated Methodology:
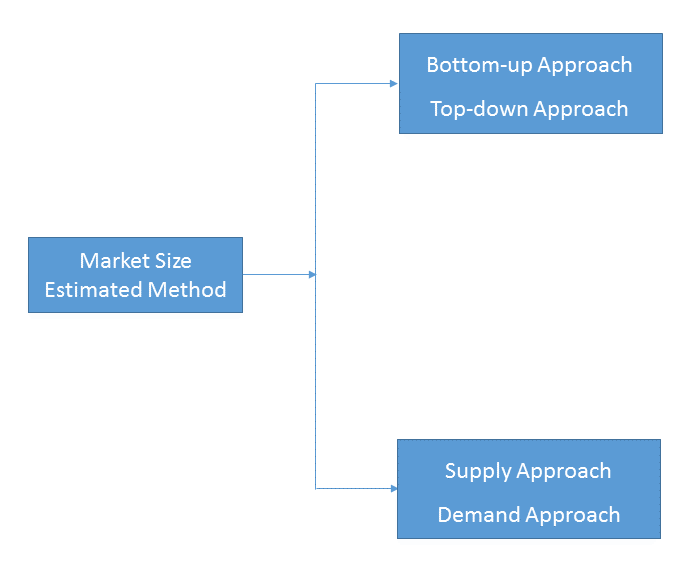
Bottom-up & top-down approach, supply & demand approach are the most important method which is used by HDIN Research to estimate the market size.
1)Top-down & Bottom-up Approach
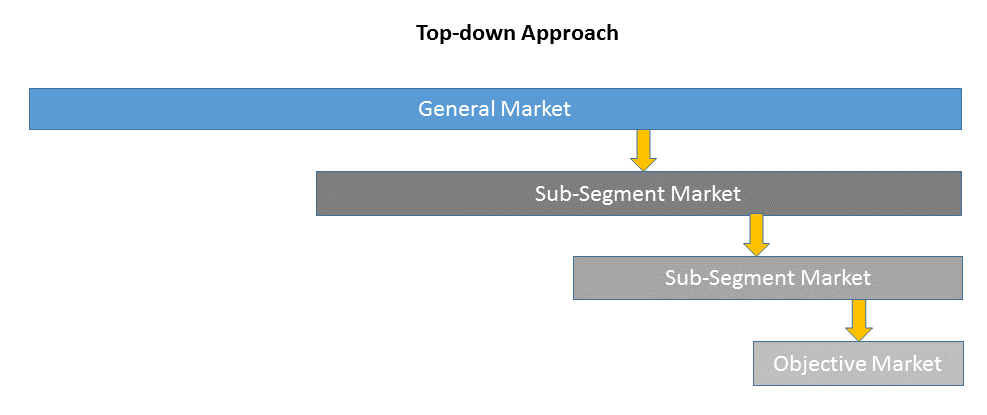
Top-down approach uses a general market size figure and determines the percentage that the objective market represents.
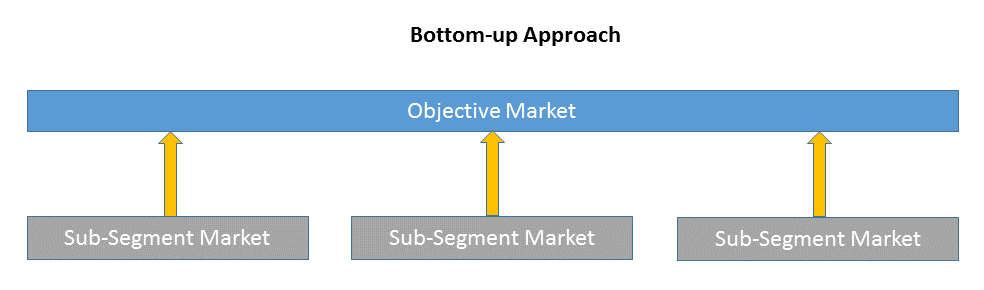
Bottom-up approach size the objective market by collecting the sub-segment information.
2)Supply & Demand Approach
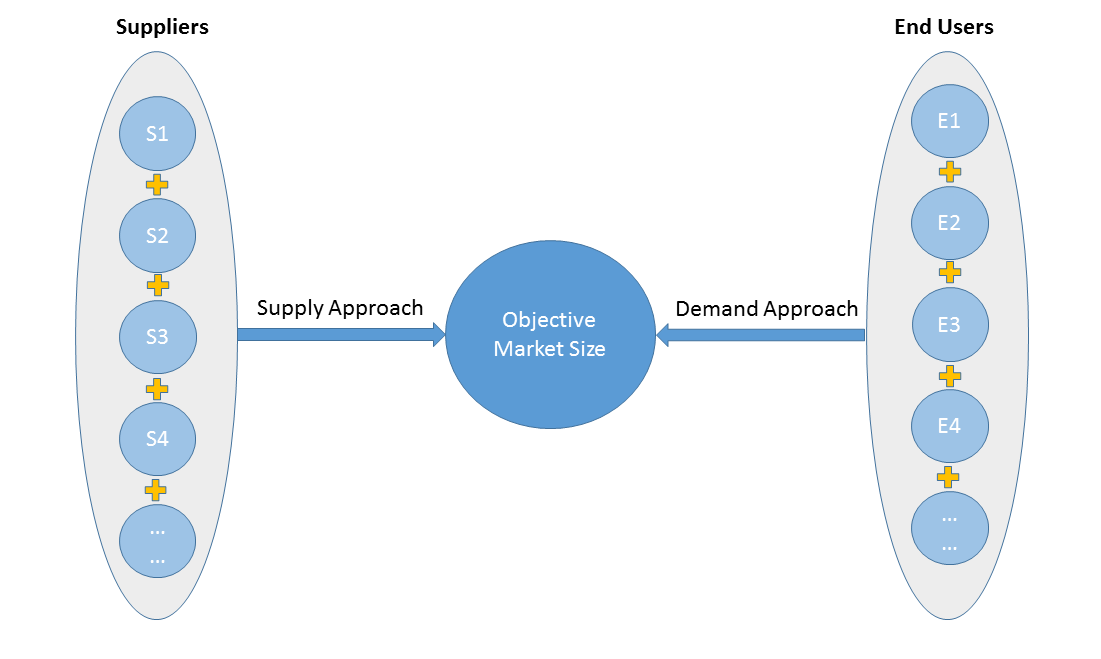
Supply approach is based on assessments of the size of each competitor supplying the objective market.
Demand approach combine end-user data within a market to estimate the objective market size. It is sometimes referred to as bottom-up approach.
- Forecasting Methodology
- Numerous factors impacting the market trend are considered for forecast model:
- New technology and application in the future;
- New project planned/under contraction;
- Global and regional underlying economic growth;
- Threatens of substitute products;
- Industry expert opinion;
- Policy and Society implication.
- Analysis Tools
1)PEST Analysis
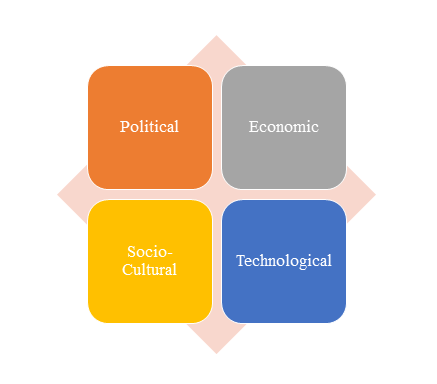
PEST Analysis is a simple and widely used tool that helps our client analyze the Political, Economic, Socio-Cultural, and Technological changes in their business environment.
- Benefits of a PEST analysis:
- It helps you to spot business opportunities, and it gives you advanced warning of significant threats.
- It reveals the direction of change within your business environment. This helps you shape what you’re doing, so that you work with change, rather than against it.
- It helps you avoid starting projects that are likely to fail, for reasons beyond your control.
- It can help you break free of unconscious assumptions when you enter a new country, region, or market; because it helps you develop an objective view of this new environment.
2)Porter’s Five Force Model Analysis
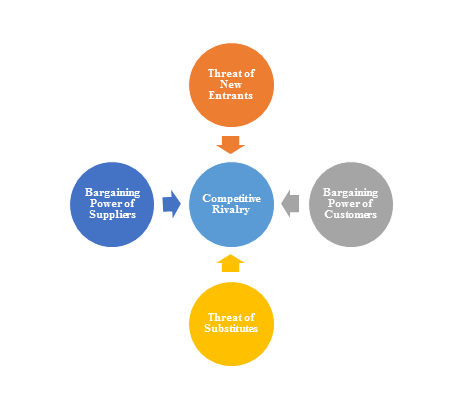
The Porter’s Five Force Model is a tool that can be used to analyze the opportunities and overall competitive advantage. The five forces that can assist in determining the competitive intensity and potential attractiveness within a specific area.
- Threat of New Entrants: Profitable industries that yield high returns will attract new firms.
- Threat of Substitutes: A substitute product uses a different technology to try to solve the same economic need.
- Bargaining Power of Customers: the ability of customers to put the firm under pressure, which also affects the customer's sensitivity to price changes.
- Bargaining Power of Suppliers: Suppliers of raw materials, components, labor, and services (such as expertise) to the firm can be a source of power over the firm when there are few substitutes.
- Competitive Rivalry: For most industries the intensity of competitive rivalry is the major determinant of the competitiveness of the industry.
3)Value Chain Analysis
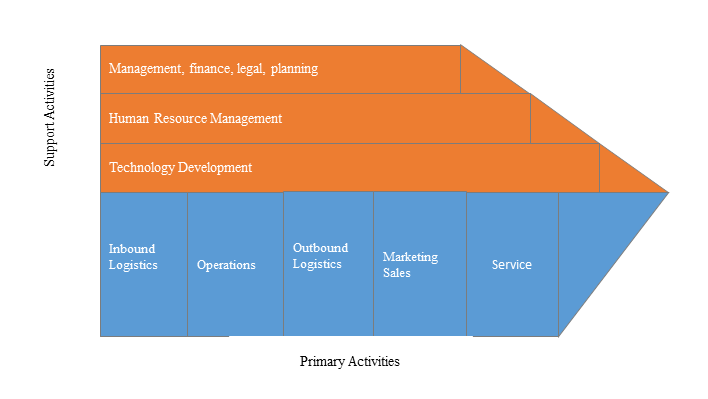
Value chain analysis is a tool to identify activities, within and around the firm and relating these activities to an assessment of competitive strength. Value chain can be analyzed by primary activities and supportive activities. Primary activities include: inbound logistics, operations, outbound logistics, marketing & sales, service. Support activities include: technology development, human resource management, management, finance, legal, planning.
4)SWOT Analysis
SWOT analysis is a tool used to evaluate a company's competitive position by identifying its strengths, weaknesses, opportunities and threats. The strengths and weakness is the inner factor; the opportunities and threats are the external factor. By analyzing the inner and external factors, the analysis can provide the detail information of the position of a player and the characteristics of the industry.
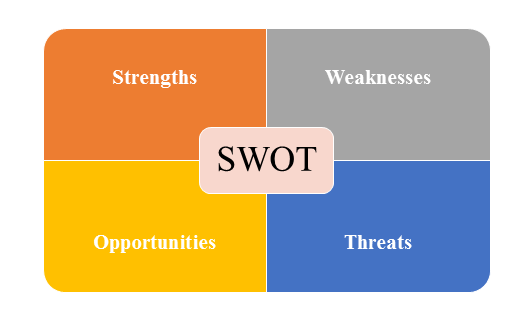
- Strengths describe what the player excels at and separates it from the competition
- Weaknesses stop the player from performing at its optimum level.
- Opportunities refer to favorable external factors that the player can use to give it a competitive advantage.
- Threats refer to factors that have the potential to harm the player.
- Data Sources
| Primary Sources | Secondary Sources |
|---|---|
| Face to face/Phone Interviews with market participants, such as: Manufactures; Distributors; End-users; Experts. Online Survey |
Government/International Organization Data: Annual Report/Presentation/Fact Book Internet Source Information Industry Association Data Free/Purchased Database Market Research Report Book/Journal/News |