Medical Aesthetics Skincare Market Analysis & Forecast
- Single User License (1 Users) $ 3,500
- Team License (2~5 Users) $ 4,500
- Corporate License (>5 Users) $ 5,500
The global medical aesthetic skincare market size is estimated at between $10.8 billion and $15.8 billion in 2026, and is positioned to expand at a compound annual growth rate (CAGR) of 7.5% to 11.5% through 2031. This expansion is driven by two trends: the convergence of energy-based interventions with topical biologic regimens, and the rapid therapeutic pivot toward regenerative biostimulation over passive soft-tissue volumization.
Medical aesthetics skincare operates distinct from over-the-counter retail beauty. It is characterized by formulations and hardware operating under pharmaceutical current Good Manufacturing Practices (cGMP) or medical device quality management frameworks (such as ISO 13485). The domain encompasses three primary regulatory and procedural pillars: Class III biologics and implantable polymers (cross-linked hyaluronic acid, poly-L-lactic acid, polycaprolactone, poly-D,L-lactic acid, and botulinum neurotoxins); Class II medical dressings and barrier repair matrices (recombinant humanized collagen sheets, sterile hyaluronic acid liquids, and wound healing sprays); and high-potency physician-dispensed cosmeceuticals engineered for pre-procedural conditioning and intra- or post-procedural barrier reconstruction. The industry demonstrates high resilience against macro-volatility due to cash-pay insulation and recurring clinical replenishment cycles. The procedural ecosystem is experiencing accelerated patient volume driven by the post-GLP-1 metabolic treatment wave, where acute facial lipoatrophy and skin laxity necessitate combination therapy involving subdermal biostimulators, mechanical tissue contraction, and cell-signaling topical formulations.
REGIONAL MARKET DYNAMICS
● North America
North America represents the highest-value commercial territory, supported by mature physician networks, dense medical spa penetration, and elevated per capita aesthetic spending. The market environment reflects a shift away from high-capital equipment expenditures toward defensive consumable pull-through. Practices facing elevated equipment financing rates and operational cost pressures have prioritized single-use radiofrequency microneedling cartridges, neurotoxin injections, and medical-grade topical regimens that yield dependable cash margins without expanding balance-sheet liabilities. Furthermore, consumer demand has concentrated around peri-procedural recovery systems that compress post-laser and post-injection downtime, cementing physician-dispensed skincare as a fundamental practice margin driver.
● Asia-Pacific
Asia-Pacific serves as the primary global growth vector. The region combines large target consumer populations aged 20 to 35 with domestic manufacturing infrastructure in South Korea and mainland China.
- People's Republic of China: Non-surgical modalities account for over 74% of aesthetic procedure volumes. While multinational corporations maintain defensible positions in tier-one metropolitan hospitals, domestic biopharmaceutical enterprises have systematically captured mid-tier market share via cost-effective Class III hyaluronic acid and recombinant collagen solutions. Regulatory reforms enforcing strict medical classifications for mesotherapy have consolidated market share among fully compliant domestic leaders.
- South Korea: The market size stands between 1.5 billion USD and 2.5 billion USD. The domestic ecosystem functions as an R&D and clinical engineering incubator, exporting energy-based devices and biomaterial formulations worldwide. The sector is defined by elevated consumer procedural literacy, competitive local pricing, and substantial inward medical tourism from neighboring Asian jurisdictions.
- Japan: Characterized by clinical conservatism and preference for low-downtime, subtle aesthetic modifications. Foreign market entrants frequently leverage Named Patient Basis frameworks to distribute novel formulations through hospital networks ahead of domestic approval.
- Taiwan, China: An established regional clinical training hub exhibiting dense clinic distribution and early clinical adoption of multi-modal radiofrequency and novel bio-stimulatory injectables.
- Southeast Asia: Thailand, Singapore, and Indonesia represent high-growth frontiers, with multinational players establishing direct regional operating subsidiaries to service expanding private clinic chains and medical tourism infrastructure.
● Europe
Europe maintains a mature, defensive market posture. Market development is dictated by stringent physician-administered injection regulations and extensive documentation compliance under European Medical Device Regulation (EU MDR 2017/745). While broad macroeconomic expansion across Western Europe remains measured, private aesthetic practices demonstrate strong pricing power. Demand is steered toward natural facial preservation and regenerative cell therapy rather than overt contour alteration. Southern European markets, supplemented by medical tourism channels in adjacent territories, generate steady seasonal procedure volume in light-based skin rejuvenation and dermal barrier repair.
● Latin America
Latin America displays elevated per-capita procedure rates, particularly in Brazil, Mexico, and Colombia. Aesthetic interventions are culturally institutionalized within urban demographic segments. Brazil consistently ranks among the top global territories for surgical and non-surgical interventions per capita. The regional landscape is characterized by high physician procedural sophistication, direct commercial distribution models bypassing third-party wholesalers, and widespread clinical integration of large-volume biostimulatory protocols for both facial correction and non-facial body contouring.
● Middle East and Africa
The Middle East, specifically the Gulf Cooperation Council (GCC) framework of Saudi Arabia, the United Arab Emirates, Qatar, and Kuwait, functions as an affluent, high-average-revenue-per-user market. Consumer behavior prioritizes high-potency medical dermocosmetics, deep-penetration fractional laser treatments, and multi-syringe total-face rejuvenation protocols. The rapid establishment of regional corporate headquarters in Riyadh and Dubai highlights the migration of commercial leadership into the GCC corridor to capture localized private healthcare capital expenditures.
SUPPLY CHAIN & VALUE CHAIN ARCHITECTURE
● Upstream Biomaterial and Optical Hardware Inputs
The foundation of the value chain is bifurcated into biological or synthetic raw materials and precision energy-delivery hardware.
- Hyaluronic Acid Fermentation: Industrial production depends on high-yield Streptococcus zooepidemicus microbial fermentation, followed by multi-stage purification processes to eliminate bacterial endotoxins, proteins, and nucleic acids. Upstream operating margins for pharmaceutical-grade active pharmaceutical ingredients (APIs) exceed 75% to 85%. Control over molecular weight distribution (ranging from low Dalton fragments for topical absorption to high Dalton chains for mechanical fillers) dictates downstream viscoelastic characteristics.
- Regenerative Polymers: Medical-grade Poly-L-Lactic Acid (PLLA), Poly-D,L-Lactic Acid (PDLLA), and Polycaprolactone (PCL) demand exact control over monomer purity, intrinsic viscosity, and microsphere size distribution (20 to 50 microns). Tight calibration avoids intra-arterial micro-embolisms while sustaining mechanical stimulation of foreign-body phagocytes without triggering chronic granulomatous reactions.
- Hardware Components: Energy-based systems depend on specialty components, including vertical-cavity surface-emitting laser (VCSEL) semiconductor arrays, flashlamps, RF generator modules, and sapphire contact cooling interfaces. Supply vulnerabilities remain concentrated in specialized optical crystal fabrication and medical-grade borosilicate glass syringe manufacturing.
● Midstream R&D, Sterile Formulation, and Regulatory Moats
The midstream captures the greatest economic profit pools through proprietary chemical formulation and regulatory capital expenditure.
- Formulation Engineering: Key competencies include the design of cross-linking networks (utilizing BDDE, DVS, or lysine links) to convert linear polymers into three-dimensional viscoelastic gels exhibiting tuned elastic modulus (G-prime) and complex viscosity. Midstream manufacturers incorporate local anesthetics (e.g., 0.3% lidocaine hydrochloride) into hydrogels without compromising long-term thermal stability or extrusion force.
- Regulatory Capital Barriers: Navigating Class III premarket evaluations (such as US FDA Premarket Approvals, EU MDR notified body audits, and Chinese NMPA clinical trials) requires multi-center, randomized, double-blind non-inferiority trials. Development timelines span three to seven years, creating defensible regulatory barriers around incumbent formulations.
● Downstream Delivery Infrastructure and Consumable Economics
Clinical delivery operates across university hospital dermatology units, multi-site aesthetic healthcare conglomerates, boutique physician practices, and medical spas.
- Cash-Pay Insulation: Unlike standard therapeutic pharmaceutical products, aesthetic treatments exist outside statutory reimbursement structures, shielding providers from institutional price deflation while exposing them directly to consumer discretionary spending fluctuations.
- The Recurring Consumable Model: Midstream device makers have integrated closed-loop commercial architectures. Systems like monopolar radiofrequency, fractional RF microneedling, and cryolipolysis require single-use, serialized, electronically authenticated consumable tips. This architecture insulates manufacturers against device sales cyclicality, generating structural, high-margin, recurring software and tip revenues that mirror injectable replenishment cycles.
PRODUCT TAXONOMY & TECHNOLOGICAL PLATFORMS
1. Injectable Aesthetics
● Neuromodulators (Botulinum Toxins)
- Mechanism: Cleavage of the SNAP-25 protein within the presynaptic nerve terminal, blocking the exocytotic release of acetylcholine at the neuromuscular junction, inducing temporary flaccid chemical denervation of facial mimetic musculature.
- Structural Paradigms: The market encompasses high molecular weight 900 kDa neurotoxin protein complexes, purified 150 kDa formulations lacking complexing accessory proteins to mitigate secondary non-responsiveness and antibody formation, and ready-to-use liquid platforms engineered to eliminate manual reconstitution variances and cold-chain liabilities. Advanced platforms are deploying non-bacterial recombinant biological production systems to streamline production consistency.
● Dermal Fillers (Hyaluronic Acid Hydrogels)
- Mechanism: Subdermal or supraperiosteal implantation of cross-linked hyaluronan to hold water and project tissue mechanically, correcting structural volume loss and effacing static rhytids.
- Rheological Divergence: Formulations are differentiated by rheological engineering. High G-prime, low-swelling formulations mimic structural bone support in the mandibular and malar regions. In contrast, low-modulus, high-stretch, cohesive gels adapt to dynamic mechanical shear stress within the perioral, lip, and superficial dermal planes.
● Regenerative Biostimulators
- Mechanism: Intentional elicitation of a sub-clinical, macrophage-mediated foreign-body response triggering local fibroblast proliferation, neo-collagenesis (Type I and Type III collagen deposition), neo-vascularization, and extracellular matrix remodeling over an 18 to 36 month biological lifecycle.
- Material Compositions: Comprises pure PLLA microspheres requiring reconstitution, smooth micro-porous PDLLA sponge structures that encourage early cellular infiltration, PCL microspheres delivered in carboxymethylcellulose hydrogel carriers offering initial mechanical filling, and hybrid biostimulators that combine micro-particulate calcium hydroxylapatite (CaHA) with cross-linked hyaluronic acid carriers.
● Biologic Solutions and Compound Mesotherapy
- Polynucleotides (PN) and Polydeoxyribonucleotides (PDRN): Salmon-derived or biosynthetically engineered DNA fragments that activate adenosine A2A receptors, promoting tissue salvage, microcirculatory angiogenesis, and cellular DNA salvage synthesis.
- Recombinant Humanized Collagen: Type III collagen synthesized via recombinant microbial expression systems, exhibiting zero animal-derived pathogen transmission risks, low immunogenicity, and precise biocompatibility for intradermal mesotherapy and tissue restoration.
- Multi-component Biorevitalizers: Uncross-linked hyaluronic acid solutions complexed with essential amino acids, antioxidants, and vitamins engineered to replenish structural skin components and address cellular senescence.
2. Non-Injectables and Energy-Based Platforms
● Surgical and Subdermal Contraction Platforms
- Subdermal Plasma and RF: Integration of cold helium plasma beams and radiofrequency-assisted lipolysis (RFAL) delivered through minimally invasive internal cannulas to thermally coagulate and contract the subdermal fibroseptal network and soft tissue envelope.
- Ultrasonic Tissue Emulsification: Ultrasound-assisted liposuction technologies that selectively liquefy targeted fat deposits while preserving the surrounding stromal vascular networks, minimizing post-operative trauma.
● Laser and Light-Based Energy Systems
- Fractional Ablative and Non-Ablative Lasers: Dual-wavelength diode systems, fractional CO2 (10,600 nm), and Er:YAG lasers generating microscopic thermal zones to stimulate re-epithelialization and eliminate atrophic scarring.
- Picosecond Acoustic Lasers: Ultrashort pulse platforms (755 nm, 1064 nm, 532 nm) delivering photo-acoustic shockwaves that fracture dermal pigment particles without causing excessive lateral thermal tissue necrosis.
- High-Peak Intense Pulsed Light (IPL): Polychromatic filtered light spectrums delivering optimized energy bursts across vascular (hemoglobin) and pigmented (melanin) clinical targets.
● Radiofrequency and Acoustic Ultrasound Devices
- High-Intensity Focused Ultrasound (HIFU): Non-invasive delivery of focused acoustic energy into the superficial musculoaponeurotic system (SMAS) at depths of 1.5 mm, 3.0 mm, and 4.5 mm, generating micro-thermal coagulation zones that induce tissue contraction without disrupting the epidermis.
- Monopolar and Bipolar Radiofrequency: Continuous impedance-monitored high-frequency alternating electrical currents driving deep volumetric heating within the reticular dermis to denature collagen fibrils and stimulate subsequent neocollagenesis.
- Radiofrequency Microneedling: Precision micro-needle arrays delivering fractional RF thermal coagulation directly into the deep dermis, bypassing epidermal melanin to mitigate post-inflammatory hyperpigmentation risks.
● Cryolipolysis and Body Contouring
- Controlled Cryotherapy: Application of non-invasive cooling plates to induce selective apoptosis in lipid-rich adipocytes without harming surrounding nervous or dermal tissues, with metabolic clearance occurring via the lymphatic system over 60 to 90 days.
● Clinical Cosmeceuticals and Functional Dermocosmetics
- Formulations: High-potency physician-dispensed topicals incorporating patented peptides, stabilized L-ascorbic acid, lipo-hydroxy acids, and recombinant epidermal growth factors (rhEGF). These preparations are clinically indicated for pre-procedural conditioning, post-treatment barrier recovery, and sustained cellular maintenance.
Companies Covered in the report:
● Multinational Pharmaceutical and Aesthetic Corporations: AbbVie (Allergan Aesthetics), Galderma, L'Oréal (Dermatological Beauty Division), Colgate-Palmolive (Skin Health Group), Unilever (Prestige Beauty & Wellbeing).
● Energy-Based Device & Surgical Innovators: Solta Medical / Bausch Health, InMode Ltd, Classys Inc., Cynosure Lutronic, Candela Corporation, Cutera Inc., Sisram Medical (Alma Lasers), EL.En. S.p.A., Apyx Medical Corp., BTL Group of Companies, Lumenis Be Ltd.
● Specialized Regional Bio-Pharmaceutical & Biomaterial Leaders: Imeik Technology, Bloomage Biotechnology, Shanghai Haohai Biological, Sihuan Pharmaceutical, Huadong Medicine (Sinclair Pharma), Hugel, Medytox Inc., Daewoong Pharmaceutical / Evolus, PharmaResearch Co. Ltd, HansBiomed, Caregen Co. Ltd., BioPlus Co. Ltd., WonTech Co. Ltd., VIOL Medical Co. Ltd.
DOWNSTREAM CLINICAL INDICATIONS & TREATMENT PATHWAYS
● Facial Contouring and Rhytid Management
- Dynamic Wrinkles: Addressed via intramuscular micro-injections of botulinum neurotoxin Type A, reducing hyperkinetic muscle pull along the glabellar complex, frontalis, and orbicularis oculi.
- Structural Tissue Restoration: Restoring deep malar fat compartments, pyriform aperture recession, and temporal hollows via supraperiosteal bolus delivery of high-viscoelasticity HA or regenerative PLLA/PCL microspheres.
- Dynamic Perioral and Superficial Fine Lines: Addressed using low-cohesive, cross-linked hyaluronic acid hydrogels, multi-point intradermal mesotherapy, and non-ablative fractional resurfacing.
● Tissue Laxity and Gravitational Ptosis
- Subdermal Contraction Protocols: Treating progressive descent of the superficial musculoaponeurotic system (SMAS) and platysma bands through high-intensity focused ultrasound (HIFU) or monopolar RF volumetric heating, stimulating long-term neocollagenesis.
- Mechanical Suspension: Deploying molded, barbed polydioxanone (PDO) or PCL suspension sutures to physically reposition descended soft-tissue envelopes in the mid- and lower face.
● Post-GLP-1 Metabolic Weight Loss Restoration ("Ozempic Face")
- Etiology: Rapid systemic adipose depletion mediated by GLP-1 receptor agonists induces severe facial lipoatrophy, pronounced dermal redundancy, mid-face structural collapse, and compromised skin elasticity.
- Multi-Modal Protocols: Clinicians combine structural bio-stimulatory injectables (e.g., PLLA to induce broad dermal redensification) with focal high-modulus hyaluronic acid boluses, followed by external radiofrequency microneedling or minimally invasive helium plasma skin contraction to retract the redundant cutaneous envelope.
● Post-Interventional Barrier Repair and Maintenance
- Clinical Requirement: Mitigating erythema, secondary hyperpigmentation, and transepidermal water loss (TEWL) induced by controlled thermal or mechanical tissue injury.
- Regimen: Rapid application of sterile Class II recombinant collagen dressings, topical recombinant epidermal growth factor (rhEGF) sprays, and specialized post-procedure serums containing biomimetic peptides and antioxidants that facilitate barrier repair and accelerate patient re-entry into daily social routines.
REGULATORY DEMARCATIONS & POLICY DEVELOPMENTS
● Global Regulatory Classification Standards
- Class III Implants and Biologics: Subdermal and intra-dermal implants, including cross-linked hyaluronic acid hydrogels, polymer microspheres (PLLA, PCL, PDLLA), and botulinum neurotoxins. Major regulatory agencies (including the US FDA, European Notified Bodies under MDR, and China's NMPA) classify injectable skin-booster solutions destined for intra-dermal delivery as Class III medical devices or biological drugs, requiring comprehensive premarket approval, human clinical safety endpoints, and manufacturing sterility validation.
- Class II Medical Dressings / Barrier Repair Devices: Sterile post-procedure medical topical products, such as recombinant collagen sheets, sterile HA wound reparative sprays, and post-laser protective hydrogels. These products require demonstrated cytocompatibility, sterile processing validation, and verified manufacturing quality compliance.
- Physician-Dispensed Cosmeceuticals / Dermocosmetics: High-potency topical formulations distributed exclusively through professional clinical channels. While evaluated primarily under cosmetics regulatory frameworks, they are held to rigorous dermatological testing and pre-procedural clinical compatibility requirements.
● Regional Compliance Directives
- United States: Intensified enforcement by the FDA and the Federal Trade Commission (FTC) regarding off-label clinical promotion, undisclosed influencer endorsements, and unsubstantiated regenerative claims concerning non-approved stem cell or exosome products.
- European Union: The transition from the Medical Device Directive to the EU MDR (2017/745) significantly increased premarket clinical data requirements, unannounced factory audits, and ongoing Post-Market Clinical Follow-up (PMCF) for Class III and Class IIb aesthetic products. Extended transitional deadlines (Regulation EU 2023/607) provided operational relief to manufacturers navigating Notified Body capacity constraints.
- People's Republic of China: Normalization of regulatory oversight across medical aesthetics. The NMPA enforced Class III registration requirements across all mesotherapy and skin-booster injections, eliminating cosmetic-grade topicals from injection channels. National regulatory guidelines standardized cosmetic surgery pricing classifications, while State Council decrees introduced a dual-punishment system imposing operational bans on corporate officers for distributing illicit injectables. Unique Device Identification (UDI) systems have been mandated to ensure end-to-end serialized traceability from manufacturing cleanrooms to patient charts.
- International MDSAP Convergence: Leading global manufacturers standardize facility quality systems under the Medical Device Single Audit Program (MDSAP), satisfying regulatory audit criteria across the United States, Canada, Brazil, Japan, and Australia concurrently.
OPPORTUNITIES & INHIBITORS
● Market Expansion Drivers and Structural Catalysts
- Synergy with Metabolic Therapeutics: The mainstream adoption of prescription GLP-1 weight-loss medications functions as a sustained procedure driver for aesthetic practices. Rapid loss of subcutaneous adipose tissue drives clinical need for combined skin redensification and contraction protocols, positioning biostimulatory injectables and soft-tissue energy devices as essential adjunct interventions.
- Demographic Broadening ("Prejuvenation"): Aesthetic interventions have penetrated the 20-to-35 demographic cohort. This customer segment utilizes low-dose neurotoxin micro-injections, preventative energy-based skin treatments, and medical-grade topical regimens to inhibit dynamic line formation, establishing an extended lifetime commercial engagement.
- Transition toward Dynamic Regenerative Materials: Patient sentiment is moving from inert, static volumizing fillers toward dynamic biostimulators and biosynthetic collagens that stimulate endogenous tissue synthesis. This shift delivers longer-lasting, physiologically integrated aesthetic outcomes while reducing late-onset tissue migration risks.
● Structural Headwinds and Operational Vulnerabilities
- Macro-Sensitivity of Elective Cash Expenditures: Because aesthetic interventions represent out-of-pocket, non-reimbursed consumer spending, patient acquisition rates remain vulnerable to macroeconomic downshifts, regional cost-of-living increases, and consumer sentiment volatility. While neurotoxins demonstrate defensive stability, premium multi-syringe dermal filler packages and capital equipment investments face extended decision cycles during periods of economic deceleration.
- Regulatory Capital Friction and Timelines: The implementation of EU MDR standards and rigorous NMPA Class III classification hurdles has lengthened development timelines to three to seven years. Escalating clinical trial expenditures restrict innovation capacity among mid-sized aesthetic developers while disproportionately benefiting well-capitalized multi-national incumbents.
- Equipment Financing and Interest Rate Constraints: Elevated commercial lending rates increase capital equipment acquisition costs for independent physician clinics, dampening direct platform sales and forcing device manufacturers to expand subscription, lease, or consumable-weighted commercial placements.
- Illicit Gray Market Infiltration: Parallel importation of non-approved neurotoxins, counterfeit dermal fillers, and uncertified copycat energy devices continues to erode pricing power in less regulated distribution corridors, demanding increased capital expenditure by brand owners on digital serialization, anti-counterfeiting tracking, and practitioner authentication systems.
1.1 Study Framework and Research Objectives 1
1.2 Medical Aesthetics Skincare Product Taxonomy and Classification Matrix 2
1.3 Research Methodology and Econometric Modeling 3
1.3.1 Primary Field Research and KOL Interviews 3
1.3.2 Secondary Data Aggregation and Cross-Validation 4
1.3.3 Market Engineering and Bottom-Up Triangulation 5
1.4 Nomenclature, Conversion Rates, and Currency Benchmarks 5
1.5 Acronyms and Abbreviations 6
Chapter 2 Global Medical Aesthetics Skincare Market Overview and Macro Environment
2.1 Global Medical Aesthetics Market Revenue Trajectory (2021-2031) 7
2.2 Demographic Shifts, Aging Populations, and Aesthetic Adoption Rates 9
2.3 Technological Paradigm Shifts: Convergence of Topicals, Devices, and Biologics 11
2.4 Consumer Purchasing Behavior and Clinical Provider Practice Economics 13
2.5 Macroeconomic Headwinds, Currency Fluctuations, and Inflationary Pressures 15
2.6 Environmental, Social, and Governance (ESG) Standards in Aesthetics Manufacturing 17
Chapter 3 Upstream Supply Chain, Raw Material Ecosystem, and Value Chain Architecture
3.1 Comprehensive Value Chain Topology: From Sourcing to Patient Delivery 19
3.2 Hyaluronic Acid (HA) API Sourcing and Microbial Fermentation Economics 21
3.3 Botulinum Neurotoxin Strain Derivation, Fermentation, and Stabilization 22
3.4 Medical-Grade Polymers (PLLA, PCL, Calcium Hydroxylapatite) Raw Material Sourcing 23
3.5 Energy-Based Device Optical, Radiofrequency, and Ultrasound Component Ecosystems 24
3.6 Contract Development and Manufacturing Organizations (CDMO) Penetration 25
3.7 Clinical Packaging, Cold-Chain Logistics, and Anti-Counterfeiting Integrity 26
Chapter 4 Global Medical Aesthetics Skincare Market Breakdown by Modality
4.1 Modality Revenue Comparison and Volume Dynamics (2021-2031) 28
4.2 Injectable Aesthetics 29
4.2.1 Botulinum Toxin Formulations and Neurotoxin Market Dynamics 30
4.2.2 Dermal Fillers (HA, Cross-Linked Technologies, Non-Animal Stabilized HA) 32
4.2.3 Regenerative Biostimulators (PLLA, PCL, Polydeoxyribonucleotide/PDRN) 34
4.2.4 Other Injectable Modalities (Skin Boosters, Mesotherapy, Lipolytics) 36
4.3 Non-Injectable Aesthetics 37
4.3.1 Energy-Based Systems: Laser and Light-Based Platforms 38
4.3.2 Energy-Based Systems: Radiofrequency (RF) and Focused Ultrasound (HIFU) 39
4.3.3 Hydrafacial and Hydro-Dermabrasion Platforms 40
4.3.4 Cryotherapy and Non-Invasive Adipose Reduction Systems 41
4.3.5 Photodynamic Therapy (PDT) and LED Rejuvenation Platforms 42
4.3.6 Professional Chemical Peels and Exfoliation Formulations 43
4.3.7 Microneedling and Targeted Transdermal Delivery Platforms 44
Chapter 5 Global Medical Aesthetics Skincare Market by Application and Distribution Channel
5.1 Market Segmentation by Clinical Indication (2021-2031) 45
5.1.1 Facial Anti-Aging, Wrinkle Effacement, and Skin Tightening 46
5.1.2 Facial Volumization, Contour Sculpting, and Rhinoplasty 48
5.1.3 Pigmentation, Vascular Lesions, and Photoaging Correction 49
5.1.4 Body Contouring, Skin Laxity, and Cellulite Reduction 50
5.1.5 Scar Remodeling, Acne Management, and Striae Revision 51
5.2 Market Segmentation by End-User Facility 52
5.2.1 Dermatology and Plastic Surgery Private Practices 53
5.2.2 Medical Spas (MedSpas) and Branded Aesthetic Clinics 54
5.2.3 Hospital Outpatient Aesthetic Surgery Departments 55
5.3 Commercial Distribution Channels (B2B Physician-Dispensed vs. Professional Retail) 56
Chapter 6 Global Cross-Border Trade Flows, Regulatory Frameworks, and Pricing Dynamics
6.1 Global Trade Matrix: Manufacturing Hubs to Regional Demand Epicenters 57
6.2 Export-Import Economics for Injectable Biologics and Energy-Based Devices 59
6.3 Regulatory Approval Pathways: US FDA (PMA/510k), EU MDR, China NMPA, Korea MFDS 61
6.4 Intellectual Property Landscape, Patent Cliffs, and Biosimilar/Device Infringements 63
6.5 Reimbursement Limitations, Cash-Pay Elasticity, and Clinical Tiered Pricing 65
6.6 Gray Market Infiltration, Parallel Imports, and Traceability Compliance 67
Chapter 7 North America Medical Aesthetics Skincare Market Dynamics
7.1 Regional Market Size, Growth Trajectory, and Market Share (2021-2031) 68
7.2 US Aesthetic Device and Biopharmaceutical Manufacturing 70
7.3 Canada Market Trends 77
Chapter 8 Europe Medical Aesthetics Skincare Market Dynamics
8.1 European Market Size, Macroeconomic Factors, and Regulatory Transitions (2021-2031) 81
8.2 Core European Production Hubs (Germany, France, Italy, Switzerland) 83
8.3 Germany Medical Aesthetics Consumption and Clinical Device Standards 85
8.4 France Luxury Dermal Filler Innovation and Cosmetic Surgery Consumption 87
8.5 Italy Laser Technology Ecosystem and Aesthetic Dermatology Penetration 89
8.6 United Kingdom Private Clinic Chains and Regulatory Tightening on Injectables 91
8.7 Rest of Europe Market Dynamics and Emerging Central European Hubs 93
Chapter 9 Asia-Pacific Medical Aesthetics Skincare Market Dynamics
9.1 Asia-Pacific Market Size, Consumption Expansion, and Export Competitiveness (2021-2031) 94
9.2 South Korea Production Powerhouse: K-Aesthetic Devices, Toxins, and Exosome Innovation 96
9.3 South Korea Domestic Consumption and Global Medical Tourism Impact 98
9.4 China Production Hub Evolution: Domestic Fermentation HA and Clinical Devices 100
9.5 China Domestic Consumption Dynamics, NMPA Compliance, and Tier-City Diffusion 102
9.6 Japan Premium Device Penetration, Rejuvenation Preference, and Regenerative Medicine 104
9.7 Australia and New Zealand High-Penetration Consumption Profile 106
9.8 Southeast Asia Emerging Production Partnerships and High-Growth Demand Centers 108
Chapter 10 Latin America, Middle East, and Africa Market Dynamics
10.1 Latin America Regional Overview and Procedural Volume Dominance (2021-2031) 111
10.2 Brazil Plastic Surgery Influence, Gluteal Sculpting, and Filler Consumption 113
10.3 Mexico Medical Tourism, Border Aesthetics, and Device Imports 115
10.4 Middle East Aesthetic Hubs: UAE and Saudi Arabia Luxury Aesthetic Infrastructure 117
10.5 Rest of Latin America and Africa Emerging Consumer Segments 120
Chapter 11 Market Share, Competitive Intensity, and Strategic Positioning
11.1 Global Tier-1 Aesthetic Enterprise Market Concentration (CR4, CR8, HHI Analysis) 123
11.2 Strategic Consolidation: M&A, Licensing In-Out Deals, and Strategic Alliances (2021-2026) 125
11.3 Competitive Positioning Matrix: Pure-Play Aesthetics vs. Diversified Pharma Conglomerates 127
11.4 Device vs. Injectable Portfolio Integration: Cross-Selling Strategies 129
Chapter 12 Corporate Intelligence: Key Market Players
12.1 AbbVie Inc. (Allergan Aesthetics) 132
12.1.1 Corporate Profile and Operational Footprint 132
12.1.2 Aesthetic Portfolio Analysis (Botox, Juvéderm, CoolSculpting) 133
12.1.3 Financial Metrics: Aesthetics Revenue, Cost, and Margin (2021-2026) 134
12.1.4 SWOT Analysis and Strategic Roadmap 135
12.2 Galderma S.A. 136
12.2.1 Corporate Profile and Operational Footprint 136
12.2.2 Aesthetic Portfolio Analysis (Dysport, Restylane, Sculptra) 137
12.2.3 Financial Metrics: Aesthetics Revenue, Cost, and Margin (2021-2026) 138
12.2.4 SWOT Analysis and Strategic Roadmap 139
12.3 L’Oréal S.A. (Active Cosmetics/Dermatological Beauty) 140
12.3.1 Corporate Profile and Operational Footprint 140
12.3.2 Aesthetic Skincare Portfolio (SkinCeuticals, CeraVe, Skinbetter Science) 141
12.3.3 Financial Metrics: Aesthetic Skincare Revenue, Cost, and Margin (2021-2026) 142
12.3.4 SWOT Analysis and Strategic Roadmap 143
12.4 Unilever PLC 144
12.4.1 Corporate Profile and Operational Footprint 144
12.4.2 Prestige and Clinical Skincare Portfolio Overview 145
12.4.3 Financial Metrics: Professional Skincare Revenue, Cost, and Margin (2021-2026) 146
12.4.4 SWOT Analysis and Strategic Roadmap 147
12.5 Colgate-Palmolive Company (PCA Skin, EltaMD, Filorga) 148
12.5.1 Corporate Profile and Operational Footprint 148
12.5.2 Medical Skincare and Dermal Rejuvenation Portfolio 149
12.5.3 Financial Metrics: Medical Aesthetics Revenue, Cost, and Margin (2021-2026) 150
12.5.4 SWOT Analysis and Strategic Roadmap 151
12.6 Solta Medical / Bausch Health Companies Inc. 152
12.6.1 Corporate Profile and Operational Footprint 152
12.6.2 Energy-Based Portfolio (Thermage, Fraxel, Clear + Brilliant) 153
12.6.3 Financial Metrics: Aesthetics Revenue, Cost, and Margin (2021-2026) 154
12.6.4 SWOT Analysis and Strategic Roadmap 155
12.7 InMode Ltd. 156
12.7.1 Corporate Profile and Operational Footprint 156
12.7.2 RF Technology Platforms (Morpheus8, BodyTite, EmbraceRF) 157
12.7.3 Financial Metrics: Aesthetics Revenue, Cost, and Margin (2021-2026) 158
12.7.4 SWOT Analysis and Strategic Roadmap 159
12.8 Hugel, Inc. 160
12.8.1 Corporate Profile and Operational Footprint 160
12.8.2 Product Portfolio (Letybo, Dermalax, The Chaeum) 161
12.8.3 Financial Metrics: Aesthetics Revenue, Cost, and Margin (2021-2026) 162
12.8.4 SWOT Analysis and Strategic Roadmap 163
12.9 Evolus, Inc. 164
12.9.1 Corporate Profile and Operational Footprint 164
12.9.2 Product Portfolio (Jeuveau, Evolysse Fillers) 165
12.9.3 Financial Metrics: Aesthetics Revenue, Cost, and Margin (2021-2026) 166
12.9.4 SWOT Analysis and Strategic Roadmap 167
12.10 EL.En. S.p.A. 168
12.10.1 Corporate Profile and Operational Footprint 168
12.10.2 Medical Laser Portfolio (Deka, Asclepion, Quanta System) 169
12.10.3 Financial Metrics: Aesthetics Revenue, Cost, and Margin (2021-2026) 170
12.10.4 SWOT Analysis and Strategic Roadmap 171
12.11 Chong Kun Dang Pharmaceutical Corp. 172
12.11.1 Corporate Profile and Operational Footprint 172
12.11.2 Aesthetic Portfolio (CKDBT, HA Fillers, Suture Threads) 173
12.11.3 Financial Metrics: Aesthetics Revenue, Cost, and Margin (2021-2026) 174
12.11.4 SWOT Analysis and Strategic Roadmap 175
12.12 Daewoong Pharmaceutical Co., Ltd. 176
12.12.1 Corporate Profile and Operational Footprint 176
12.12.2 Aesthetics Portfolio (Nabota/Jeuveau, V-Olet) 177
12.12.3 Financial Metrics: Aesthetics Revenue, Cost, and Margin (2021-2026) 178
12.12.4 SWOT Analysis and Strategic Roadmap 179
12.13 Sisram Medical Ltd (Alma Lasers) 180
12.13.1 Corporate Profile and Operational Footprint 180
12.13.2 Energy-Based and Injectables Portfolio (Soprano, Harmony, Profhilo Distribution) 181
12.13.3 Financial Metrics: Aesthetics Revenue, Cost, and Margin (2021-2026) 182
12.13.4 SWOT Analysis and Strategic Roadmap 183
12.14 Classys Inc. 184
12.14.1 Corporate Profile and Operational Footprint 184
12.14.2 Aesthetic Device Portfolio (Ultraformer/HIFU, Clatuu, Volnewmer) 185
12.14.3 Financial Metrics: Aesthetics Revenue, Cost, and Margin (2021-2026) 186
12.14.4 SWOT Analysis and Strategic Roadmap 187
12.15 Medytox Inc. 188
12.15.1 Corporate Profile and Operational Footprint 188
12.15.2 Botulinum Toxin and Filler Portfolio (Meditoxin, Innotox, Neuramis) 189
12.15.3 Financial Metrics: Aesthetics Revenue, Cost, and Margin (2021-2026) 190
12.15.4 SWOT Analysis and Strategic Roadmap 191
12.16 Merz Pharma GmbH & Co. KGaA 192
12.16.1 Corporate Profile and Operational Footprint 192
12.16.2 Aesthetic Portfolio (Xeomin, Radiesse, Belotero, Ultherapy) 193
12.16.3 Financial Metrics: Aesthetics Revenue, Cost, and Margin (2021-2026) 194
12.16.4 SWOT Analysis and Strategic Roadmap 195
12.17 Revance Therapeutics, Inc. 196
12.17.1 Corporate Profile and Operational Footprint 196
12.17.2 Aesthetic Portfolio (Daxxify, RHA Collection Distribution) 197
12.17.3 Financial Metrics: Aesthetics Revenue, Cost, and Margin (2021-2026) 198
12.17.4 SWOT Analysis and Strategic Roadmap 199
12.18 Prollenium Medical Technologies 200
12.18.1 Corporate Profile and Operational Footprint 200
12.18.2 Dermal Filler Portfolio (Revanesse Collection) 201
12.18.3 Financial Metrics: Aesthetics Revenue, Cost, and Margin (2021-2026) 202
12.18.4 SWOT Analysis and Strategic Roadmap 203
12.19 Cutera, Inc. 204
12.19.1 Corporate Profile and Operational Footprint 204
12.19.2 Dermatological Device Systems (AviClear, excel V+, truSculpt) 205
12.19.3 Financial Metrics: Aesthetics Revenue, Cost, and Margin (2021-2026) 206
12.19.4 SWOT Analysis and Strategic Roadmap 207
12.20 Cynosure Lutronic 208
12.20.1 Corporate Profile and Operational Footprint 208
12.20.2 Integrated Energy Platform Portfolio (PicoSure, Potenza, Clarity II) 209
12.20.3 Financial Metrics: Aesthetics Revenue, Cost, and Margin (2021-2026) 210
12.20.4 SWOT Analysis and Strategic Roadmap 211
12.21 Apyx Medical Corporation 212
12.21.1 Corporate Profile and Operational Footprint 212
12.21.2 Helium Plasma Technology Portfolio (Renuvion/J-Plasma) 213
12.21.3 Financial Metrics: Aesthetics Revenue, Cost, and Margin (2021-2026) 214
12.21.4 SWOT Analysis and Strategic Roadmap 215
12.22 Venus Concept Inc. 216
12.22.1 Corporate Profile and Operational Footprint 216
12.22.2 Multi-Technology Platform Portfolio (Venus Versa, Venus Legacy, Venus Bliss) 217
12.22.3 Financial Metrics: Aesthetics Revenue, Cost, and Margin (2021-2026) 218
12.22.4 SWOT Analysis and Strategic Roadmap 219
12.23 BTL Group of Companies 220
12.23.1 Corporate Profile and Operational Footprint 220
12.23.2 Non-Invasive Body and Facial Platforms (Emsculpt Neo, Emface, Exilis) 221
12.23.3 Financial Metrics: Aesthetics Revenue, Cost, and Margin (2021-2026) 222
12.23.4 SWOT Analysis and Strategic Roadmap 223
12.24 Lumenis Be Ltd. 224
12.24.1 Corporate Profile and Operational Footprint 224
12.24.2 Aesthetic Laser and IPL Platforms (Stellar M22, UltraPulse, NuEra Tight) 225
12.24.3 Financial Metrics: Aesthetics Revenue, Cost, and Margin (2021-2026) 226
12.24.4 SWOT Analysis and Strategic Roadmap 227
12.25 Candela Corporation 228
12.25.1 Corporate Profile and Operational Footprint 228
12.25.2 Aesthetic Device Systems (Gentle Pro Series, Nordlys, PicoWay, Profound) 229
12.25.3 Financial Metrics: Aesthetics Revenue, Cost, and Margin (2021-2026) 230
12.25.4 SWOT Analysis and Strategic Roadmap 231
12.26 PharmaResearch Co., Ltd. 232
12.26.1 Corporate Profile and Operational Footprint 232
12.26.2 Polynucleotide Regenerative Aesthetics (Rejuran Series, Conjuran) 233
12.26.3 Financial Metrics: Aesthetics Revenue, Cost, and Margin (2021-2026) 234
12.26.4 SWOT Analysis and Strategic Roadmap 235
12.27 HansBiomed Corp. 236
12.27.1 Corporate Profile and Operational Footprint 236
12.27.2 Aesthetic Tissue Engineering Portfolio (BellaGel, MINT Lift Suture) 237
12.27.3 Financial Metrics: Aesthetics Revenue, Cost, and Margin (2021-2026) 238
12.27.4 SWOT Analysis and Strategic Roadmap 239
12.28 Green Cross WellBeing Co., Ltd. 240
12.28.1 Corporate Profile and Operational Footprint 240
12.28.2 Aesthetic Injections and Placenta-Derived Therapeutics (Laennec) 241
12.28.3 Financial Metrics: Aesthetics Revenue, Cost, and Margin (2021-2026) 242
12.28.4 SWOT Analysis and Strategic Roadmap 243
12.29 YA-MAN LTD. 244
12.29.1 Corporate Profile and Operational Footprint 244
12.29.2 Professional and Clinical-Grade Home Aesthetic Devices 245
12.29.3 Financial Metrics: Aesthetics Revenue, Cost, and Margin (2021-2026) 246
12.29.4 SWOT Analysis and Strategic Roadmap 247
12.30 WonTech Co., Ltd. 248
12.30.1 Corporate Profile and Operational Footprint 248
12.30.2 Energy-Based Aesthetic Platforms (Oligio Monopolar RF, PicoCare) 249
12.30.3 Financial Metrics: Aesthetics Revenue, Cost, and Margin (2021-2026) 250
12.30.4 SWOT Analysis and Strategic Roadmap 251
12.31 Humedix Co., Ltd. / Huons Global 252
12.31.1 Corporate Profile and Operational Footprint 252
12.31.2 HA Fillers and Toxin Portfolio (Elravie Premier, Liztox) 253
12.31.3 Financial Metrics: Aesthetics Revenue, Cost, and Margin (2021-2026) 254
12.31.4 SWOT Analysis and Strategic Roadmap 255
12.32 BNC Korea Co., Ltd. 256
12.32.1 Corporate Profile and Operational Footprint 256
12.32.2 Biopolymer Fillers and Wound Healing Aesthetics (Cutegel) 257
12.32.3 Financial Metrics: Aesthetics Revenue, Cost, and Margin (2021-2026) 258
12.32.4 SWOT Analysis and Strategic Roadmap 259
12.33 JETEMA Co., Ltd. 260
12.33.1 Corporate Profile and Operational Footprint 260
12.33.2 Toxin and Premium HA Filler Solutions (e.p.t.q., The Tox) 261
12.33.3 Financial Metrics: Aesthetics Revenue, Cost, and Margin (2021-2026) 262
12.33.4 SWOT Analysis and Strategic Roadmap 263
12.34 Caregen Co., Ltd. 264
12.34.1 Corporate Profile and Operational Footprint 264
12.34.2 Biomimetic Peptide Aesthetics (Dermaheal, Revofil, Prostrolane) 265
12.34.3 Financial Metrics: Aesthetics Revenue, Cost, and Margin (2021-2026) 266
12.34.4 SWOT Analysis and Strategic Roadmap 267
12.35 BioPlus Co., Ltd. 268
12.35.1 Corporate Profile and Operational Footprint 268
12.35.2 DVB-Crosslinked Hydrogel Aesthetics (SkinPlus HYAL, HyalDew) 269
12.35.3 Financial Metrics: Aesthetics Revenue, Cost, and Margin (2021-2026) 270
12.35.4 SWOT Analysis and Strategic Roadmap 271
12.36 VIOL Medical Co., Ltd. 272
12.36.1 Corporate Profile and Operational Footprint 272
12.36.2 RF Microneedling Platforms (Sylfirm X, Scarlet) 273
12.36.3 Financial Metrics: Aesthetics Revenue, Cost, and Margin (2021-2026) 274
12.36.4 SWOT Analysis and Strategic Roadmap 275
12.37 Asterasys Co., Ltd. 276
12.37.1 Corporate Profile and Operational Footprint 276
12.37.2 Lifting and Contouring Technologies (Liftera HIFU, Coolfase) 277
12.37.3 Financial Metrics: Aesthetics Revenue, Cost, and Margin (2021-2026) 278
12.37.4 SWOT Analysis and Strategic Roadmap 279
12.38 BTB Korea Co., Ltd. 280
12.38.1 Corporate Profile and Operational Footprint 280
12.38.2 Aesthetic Medical Consumables and Specialized Formulations 281
12.38.3 Financial Metrics: Aesthetics Revenue, Cost, and Margin (2021-2026) 282
12.38.4 SWOT Analysis and Strategic Roadmap 283
12.39 Laseroptek Co., Ltd. 284
12.39.1 Corporate Profile and Operational Footprint 284
12.39.2 Solid-State Aesthetic Laser Platforms (PicoLO, Helios 785, W醫) 285
12.39.3 Financial Metrics: Aesthetics Revenue, Cost, and Margin (2021-2026) 286
12.39.4 SWOT Analysis and Strategic Roadmap 287
12.40 GFC Life Science Co., Ltd. 288
12.40.1 Corporate Profile and Operational Footprint 288
12.40.2 Exosome and Bio-Active Aesthetic Ingredients 289
12.40.3 Financial Metrics: Aesthetics Revenue, Cost, and Margin (2021-2026) 290
12.40.4 SWOT Analysis and Strategic Roadmap 291
12.41 Lameditech Co., Ltd. 292
12.41.1 Corporate Profile and Operational Footprint 292
12.41.2 Laser Blood Sampling and Transdermal Aesthetic Platforms (Puraxel) 293
12.41.3 Financial Metrics: Aesthetics Revenue, Cost, and Margin (2021-2026) 294
12.41.4 SWOT Analysis and Strategic Roadmap 295
12.42 Hironic Co., Ltd. 296
12.42.1 Corporate Profile and Operational Footprint 296
12.42.2 Non-Invasive Ultrasound and RF Devices (Doublo Gold, V-RO) 297
12.42.3 Financial Metrics: Aesthetics Revenue, Cost, and Margin (2021-2026) 298
12.42.4 SWOT Analysis and Strategic Roadmap 299
12.43 DongBang Medical Co., Ltd. 300
12.43.1 Corporate Profile and Operational Footprint 300
12.43.2 Aesthetic Cannulas, PDO Threads, and Filler Distribution 301
12.43.3 Financial Metrics: Aesthetics Revenue, Cost, and Margin (2021-2026) 302
12.43.4 SWOT Analysis and Strategic Roadmap 303
12.44 RFTECH Co., Ltd. (Youthfill Co., Ltd.) 304
12.44.1 Corporate Profile and Operational Footprint 304
12.44.2 Premium Monophasic HA Fillers (Youthfill) and Toxin R&D 305
12.44.3 Financial Metrics: Aesthetics Revenue, Cost, and Margin (2021-2026) 306
12.44.4 SWOT Analysis and Strategic Roadmap 307
12.45 Imeik Technology Development Co., Ltd. 308
12.45.1 Corporate Profile and Operational Footprint 308
12.45.2 Rejuvenation and Contour Portfolio (Hearty, Bonetta, Hi-Twist) 309
12.45.3 Financial Metrics: Aesthetics Revenue, Cost, and Margin (2021-2026) 310
12.45.4 SWOT Analysis and Strategic Roadmap 311
12.46 Freda Pharma (Shandong Freda Pharmaceutical Group) 312
12.46.1 Corporate Profile and Operational Footprint 312
12.46.2 Medical HA Raw Materials and Functional Aesthetic Topicals (Rellet) 313
12.46.3 Financial Metrics: Aesthetics Revenue, Cost, and Margin (2021-2026) 314
12.46.4 SWOT Analysis and Strategic Roadmap 315
12.47 Huadong Medicine Co., Ltd. (Sinclair Pharma) 316
12.47.1 Corporate Profile and Operational Footprint 316
12.47.2 Global Aesthetic Brand Portfolio (Ellansé, MaiLi, Reaction, Glacial Rx) 317
12.47.3 Financial Metrics: Aesthetics Revenue, Cost, and Margin (2021-2026) 318
12.47.4 SWOT Analysis and Strategic Roadmap 319
12.48 Sihuan Pharmaceutical Holdings Group Ltd. 320
12.48.1 Corporate Profile and Operational Footprint 320
12.48.2 Medical Aesthetics Division (Hugel Distribution, Letybo, Fillers) 321
12.48.3 Financial Metrics: Aesthetics Revenue, Cost, and Margin (2021-2026) 322
12.48.4 SWOT Analysis and Strategic Roadmap 323
12.49 Bloomage Biotechnology Corporation Limited 324
12.49.1 Corporate Profile and Operational Footprint 324
12.49.2 Fermentation HA API, BioMED Injectables (BioHyalux, Dermashine) 325
12.49.3 Financial Metrics: Aesthetics Revenue, Cost, and Margin (2021-2026) 326
12.49.4 SWOT Analysis and Strategic Roadmap 327
12.50 Shanghai Haohai Biological Technology Co., Ltd. 328
12.50.1 Corporate Profile and Operational Footprint 328
12.50.2 Cross-Linked HA Fillers and RF Devices (Matrifill, Janfield) 329
12.50.3 Financial Metrics: Aesthetics Revenue, Cost, and Margin (2021-2026) 330
12.50.4 SWOT Analysis and Strategic Roadmap 331
12.51 Obagi Medical (Waldencast plc) 332
12.51.1 Corporate Profile and Operational Footprint 332
12.51.2 Physician-Dispensed Therapeutic Aesthetics (Nu-Derm, Obagi-C) 333
12.51.3 Financial Metrics: Medical Aesthetics Revenue, Cost, and Margin (2021-2026) 334
12.51.4 SWOT Analysis and Strategic Roadmap 335
Chapter 13 Global Market Forecast and Horizon Analysis (2027-2031)
13.1 Econometric Projections by Modality and Technology Sector 336
13.2 Regional Market Expansion and Emerging Demand Vectors 338
13.3 Disruptive Technology Horizon: Cell-Free Therapies, Exosomes, and AI Diagnostics 340
13.4 Supply Chain Reshoring and Future Trade Tariff Scenarios 342
13.5 Concluding Strategic Summary 344
Table 2 Medical Aesthetics Modality Breakdown: Injectables vs. Non-Injectables (2021-2026) 29
Table 3 Global Botulinum Toxin Market Revenue by Region (2021-2031) 31
Table 4 Global Dermal Fillers Market Revenue by Polymer Sub-Type (2021-2031) 33
Table 5 Global Regenerative Biostimulators Market Volume and Average Selling Price (2021-2031) 35
Table 6 Global Energy-Based Devices Market Revenue by Energy Modality (2021-2031) 38
Table 7 Global Chemical Peels and Microneedling Market Value (2021-2031) 44
Table 8 Global Aesthetics Skincare Market Value by Clinical Indication (2021-2031) 47
Table 9 Global Aesthetics Skincare Market by Provider Facility Type (2021-2031) 53
Table 10 Global Trade Matrix: Major Export Hubs of Aesthetics Injectables (2021-2026) 58
Table 11 Global Trade Matrix: Major Export Hubs of Energy-Based Devices (2021-2026) 60
Table 12 Regulatory Approval Pathways and Time-to-Market by Core Jurisdiction 62
Table 13 North America Medical Aesthetics Market Revenue by Country (2021-2031) 69
Table 14 United States Medical Aesthetics Market by Modality (2021-2031) 73
Table 15 Canada Medical Aesthetics Market by Modality (2021-2031) 77
Table 16 Europe Medical Aesthetics Market Revenue by Leading Country (2021-2031) 82
Table 17 Germany Medical Aesthetics Market by Modality (2021-2031) 86
Table 18 France Medical Aesthetics Market by Modality (2021-2031) 88
Table 19 Italy Medical Aesthetics Market by Modality (2021-2031) 90
Table 20 United Kingdom Medical Aesthetics Market by Modality (2021-2031) 92
Table 21 Asia-Pacific Medical Aesthetics Market Revenue by Country (2021-2031) 95
Table 22 South Korea Medical Aesthetics Market by Modality (2021-2031) 99
Table 23 China Medical Aesthetics Market by Modality (2021-2031) 103
Table 24 Japan Medical Aesthetics Market by Modality (2021-2031) 105
Table 25 Australia Medical Aesthetics Market by Modality (2021-2031) 107
Table 26 Latin America Medical Aesthetics Market Revenue by Country (2021-2031) 112
Table 27 Brazil Medical Aesthetics Market by Modality (2021-2031) 114
Table 28 Mexico Medical Aesthetics Market by Modality (2021-2031) 116
Table 29 Middle East and Africa Aesthetics Market Revenue by Country (2021-2031) 118
Table 30 Global Medical Aesthetics Competitive Concentration Ratios (CR4, CR8, HHI) (2021-2026) 124
Table 31 AbbVie Inc. Medical Aesthetics Skincare Revenue, Cost, and Gross Margin (2021-2026) 134
Table 32 Galderma S.A. Medical Aesthetics Skincare Revenue, Cost, and Gross Margin (2021-2026) 138
Table 33 L’Oréal S.A. Medical Aesthetics Skincare Revenue, Cost, and Gross Margin (2021-2026) 142
Table 34 Unilever PLC Medical Aesthetics Skincare Revenue, Cost, and Gross Margin (2021-2026) 146
Table 35 Colgate-Palmolive Company Medical Aesthetics Skincare Revenue, Cost, and Gross Margin (2021-2026) 150
Table 36 Solta Medical / Bausch Health Medical Aesthetics Skincare Revenue, Cost, and Gross Margin (2021-2026) 154
Table 37 InMode Ltd. Medical Aesthetics Skincare Revenue, Cost, and Gross Margin (2021-2026) 158
Table 38 Hugel, Inc. Medical Aesthetics Skincare Revenue, Cost, and Gross Margin (2021-2026) 162
Table 39 Evolus, Inc. Medical Aesthetics Skincare Revenue, Cost, and Gross Margin (2021-2026) 166
Table 40 EL.En. S.p.A. Medical Aesthetics Skincare Revenue, Cost, and Gross Margin (2021-2026) 170
Table 41 Chong Kun Dang Pharmaceutical Medical Aesthetics Skincare Revenue, Cost, and Gross Margin (2021-2026) 174
Table 42 Daewoong Pharmaceutical Medical Aesthetics Skincare Revenue, Cost, and Gross Margin (2021-2026) 178
Table 43 Sisram Medical Ltd Medical Aesthetics Skincare Revenue, Cost, and Gross Margin (2021-2026) 182
Table 44 Classys Inc. Medical Aesthetics Skincare Revenue, Cost, and Gross Margin (2021-2026) 186
Table 45 Medytox Inc. Medical Aesthetics Skincare Revenue, Cost, and Gross Margin (2021-2026) 190
Table 46 Merz Pharma Medical Aesthetics Skincare Revenue, Cost, and Gross Margin (2021-2026) 194
Table 47 Revance Therapeutics Medical Aesthetics Skincare Revenue, Cost, and Gross Margin (2021-2026) 198
Table 48 Prollenium Medical Technologies Medical Aesthetics Skincare Revenue, Cost, and Gross Margin (2021-2026) 202
Table 49 Cutera, Inc. Medical Aesthetics Skincare Revenue, Cost, and Gross Margin (2021-2026) 206
Table 50 Cynosure Lutronic Medical Aesthetics Skincare Revenue, Cost, and Gross Margin (2021-2026) 210
Table 51 Apyx Medical Corporation Medical Aesthetics Skincare Revenue, Cost, and Gross Margin (2021-2026) 214
Table 52 Venus Concept Inc. Medical Aesthetics Skincare Revenue, Cost, and Gross Margin (2021-2026) 218
Table 53 BTL Group of Companies Medical Aesthetics Skincare Revenue, Cost, and Gross Margin (2021-2026) 222
Table 54 Lumenis Be Ltd. Medical Aesthetics Skincare Revenue, Cost, and Gross Margin (2021-2026) 226
Table 55 Candela Corporation Medical Aesthetics Skincare Revenue, Cost, and Gross Margin (2021-2026) 230
Table 56 PharmaResearch Co., Ltd. Medical Aesthetics Skincare Revenue, Cost, and Gross Margin (2021-2026) 234
Table 57 HansBiomed Corp. Medical Aesthetics Skincare Revenue, Cost, and Gross Margin (2021-2026) 238
Table 58 Green Cross WellBeing Co., Ltd. Medical Aesthetics Skincare Revenue, Cost, and Gross Margin (2021-2026) 242
Table 59 YA-MAN LTD. Medical Aesthetics Skincare Revenue, Cost, and Gross Margin (2021-2026) 246
Table 60 WonTech Co., Ltd. Medical Aesthetics Skincare Revenue, Cost, and Gross Margin (2021-2026) 250
Table 61 Humedix Co., Ltd. / Huons Global Medical Aesthetics Skincare Revenue, Cost, and Gross Margin (2021-2026) 254
Table 62 BNC Korea Co., Ltd. Medical Aesthetics Skincare Revenue, Cost, and Gross Margin (2021-2026) 258
Table 63 JETEMA Co., Ltd. Medical Aesthetics Skincare Revenue, Cost, and Gross Margin (2021-2026) 262
Table 64 Caregen Co., Ltd. Medical Aesthetics Skincare Revenue, Cost, and Gross Margin (2021-2026) 266
Table 65 BioPlus Co., Ltd. Medical Aesthetics Skincare Revenue, Cost, and Gross Margin (2021-2026) 270
Table 66 VIOL Medical Co., Ltd. Medical Aesthetics Skincare Revenue, Cost, and Gross Margin (2021-2026) 274
Table 67 Asterasys Co., Ltd. Medical Aesthetics Skincare Revenue, Cost, and Gross Margin (2021-2026) 278
Table 68 BTB Korea Co., Ltd. Medical Aesthetics Skincare Revenue, Cost, and Gross Margin (2021-2026) 282
Table 69 Laseroptek Co., Ltd. Medical Aesthetics Skincare Revenue, Cost, and Gross Margin (2021-2026) 286
Table 70 GFC Life Science Co., Ltd. Medical Aesthetics Skincare Revenue, Cost, and Gross Margin (2021-2026) 290
Table 71 Lameditech Co., Ltd. Medical Aesthetics Skincare Revenue, Cost, and Gross Margin (2021-2026) 294
Table 72 Hironic Co., Ltd. Medical Aesthetics Skincare Revenue, Cost, and Gross Margin (2021-2026) 298
Table 73 DongBang Medical Co., Ltd. Medical Aesthetics Skincare Revenue, Cost, and Gross Margin (2021-2026) 302
Table 74 RFTECH Co., Ltd. Medical Aesthetics Skincare Revenue, Cost, and Gross Margin (2021-2026) 306
Table 75 Imeik Technology Development Co., Ltd. Medical Aesthetics Skincare Revenue, Cost, and Gross Margin (2021-2026) 310
Table 76 Freda Pharma Medical Aesthetics Skincare Revenue, Cost, and Gross Margin (2021-2026) 314
Table 77 Huadong Medicine Co., Ltd. Medical Aesthetics Skincare Revenue, Cost, and Gross Margin (2021-2026) 318
Table 78 Sihuan Pharmaceutical Holdings Medical Aesthetics Skincare Revenue, Cost, and Gross Margin (2021-2026) 322
Table 79 Bloomage Biotechnology Corporation Medical Aesthetics Skincare Revenue, Cost, and Gross Margin (2021-2026) 326
Table 80 Shanghai Haohai Biological Technology Medical Aesthetics Skincare Revenue, Cost, and Gross Margin (2021-2026) 330
Table 81 Obagi Medical Medical Aesthetics Skincare Revenue, Cost, and Gross Margin (2021-2026) 334
Table 82 Global Medical Aesthetics Skincare Market Forecast by Modality (2027-2031) 337
Table 83 Global Medical Aesthetics Skincare Market Forecast by Region (2027-2031) 339
Figure 1 Global Medical Aesthetics Skincare Market Size and Growth Trajectory (2021-2031) 8
Figure 2 Medical Aesthetics Skincare Upstream-to-Downstream Value Chain Structure 20
Figure 3 Global Injectables vs. Non-Injectables Revenue Share Matrix (2021-2031) 29
Figure 4 Global Botulinum Toxin Market Volume Expansion (2021-2031) 31
Figure 5 Global Dermal Fillers Market Share by Material Type (2026) 33
Figure 6 Global Energy-Based Systems Market Share by Energy Source (2026) 39
Figure 7 Global Aesthetics Market Revenue Distribution by Application Indication (2026) 46
Figure 8 Global Aesthetic Procedure Share by Clinical End-User Facility (2026) 52
Figure 9 International Trade Routes and Export Balances for Aesthetic Medical Equipment (2026) 59
Figure 10 North America Medical Aesthetics Skincare Market Size by Country (2021-2031) 69
Figure 11 United States Aesthetic Provider Volume and Revenue Breakdown (2021-2031) 74
Figure 12 Europe Medical Aesthetics Skincare Regional Market Share Distribution (2026) 82
Figure 13 Germany vs. France Aesthetic Procedure Volume Analysis (2021-2026) 85
Figure 14 Asia-Pacific Medical Aesthetics Revenue Trajectory by Sub-Region (2021-2031) 95
Figure 15 South Korea Export Volume of Botulinum Toxin and HA Fillers (2021-2026) 97
Figure 16 China Domestic Aesthetic Consumption Growth and Penetration Curve (2021-2031) 101
Figure 17 Latin America Aesthetic Procedure Market Share by Nation (2026) 112
Figure 18 Middle East Medical Aesthetic Expenditure Per Capita (2021-2026) 119
Figure 19 Top 10 Global Medical Aesthetics Enterprise Market Share Concentration (2026) 124
Figure 20 AbbVie Inc. Medical Aesthetics Skincare Market Share (2021-2026) 135
Figure 21 Galderma S.A. Medical Aesthetics Skincare Market Share (2021-2026) 139
Figure 22 L’Oréal S.A. Medical Aesthetics Skincare Market Share (2021-2026) 143
Figure 23 Unilever PLC Medical Aesthetics Skincare Market Share (2021-2026) 147
Figure 24 Colgate-Palmolive Company Medical Aesthetics Skincare Market Share (2021-2026) 151
Figure 25 Solta Medical / Bausch Health Medical Aesthetics Skincare Market Share (2021-2026) 155
Figure 26 InMode Ltd. Medical Aesthetics Skincare Market Share (2021-2026) 159
Figure 27 Hugel, Inc. Medical Aesthetics Skincare Market Share (2021-2026) 163
Figure 28 Evolus, Inc. Medical Aesthetics Skincare Market Share (2021-2026) 167
Figure 29 EL.En. S.p.A. Medical Aesthetics Skincare Market Share (2021-2026) 171
Figure 30 Chong Kun Dang Pharmaceutical Medical Aesthetics Skincare Market Share (2021-2026) 175
Figure 31 Daewoong Pharmaceutical Medical Aesthetics Skincare Market Share (2021-2026) 179
Figure 32 Sisram Medical Ltd Medical Aesthetics Skincare Market Share (2021-2026) 183
Figure 33 Classys Inc. Medical Aesthetics Skincare Market Share (2021-2026) 187
Figure 34 Medytox Inc. Medical Aesthetics Skincare Market Share (2021-2026) 191
Figure 35 Merz Pharma Medical Aesthetics Skincare Market Share (2021-2026) 195
Figure 36 Revance Therapeutics Medical Aesthetics Skincare Market Share (2021-2026) 199
Figure 37 Prollenium Medical Technologies Medical Aesthetics Skincare Market Share (2021-2026) 203
Figure 38 Cutera, Inc. Medical Aesthetics Skincare Market Share (2021-2026) 207
Figure 39 Cynosure Lutronic Medical Aesthetics Skincare Market Share (2021-2026) 211
Figure 40 Apyx Medical Corporation Medical Aesthetics Skincare Market Share (2021-2026) 215
Figure 41 Venus Concept Inc. Medical Aesthetics Skincare Market Share (2021-2026) 219
Figure 42 BTL Group of Companies Medical Aesthetics Skincare Market Share (2021-2026) 223
Figure 43 Lumenis Be Ltd. Medical Aesthetics Skincare Market Share (2021-2026) 227
Figure 44 Candela Corporation Medical Aesthetics Skincare Market Share (2021-2026) 231
Figure 45 PharmaResearch Co., Ltd. Medical Aesthetics Skincare Market Share (2021-2026) 235
Figure 46 HansBiomed Corp. Medical Aesthetics Skincare Market Share (2021-2026) 239
Figure 47 Green Cross WellBeing Co., Ltd. Medical Aesthetics Skincare Market Share (2021-2026) 243
Figure 48 YA-MAN LTD. Medical Aesthetics Skincare Market Share (2021-2026) 247
Figure 49 WonTech Co., Ltd. Medical Aesthetics Skincare Market Share (2021-2026) 251
Figure 50 Humedix Co., Ltd. / Huons Global Medical Aesthetics Skincare Market Share (2021-2026) 255
Figure 51 BNC Korea Co., Ltd. Medical Aesthetics Skincare Market Share (2021-2026) 259
Figure 52 JETEMA Co., Ltd. Medical Aesthetics Skincare Market Share (2021-2026) 263
Figure 53 Caregen Co., Ltd. Medical Aesthetics Skincare Market Share (2021-2026) 267
Figure 54 BioPlus Co., Ltd. Medical Aesthetics Skincare Market Share (2021-2026) 271
Figure 55 VIOL Medical Co., Ltd. Medical Aesthetics Skincare Market Share (2021-2026) 275
Figure 56 Asterasys Co., Ltd. Medical Aesthetics Skincare Market Share (2021-2026) 279
Figure 57 BTB Korea Co., Ltd. Medical Aesthetics Skincare Market Share (2021-2026) 283
Figure 58 Laseroptek Co., Ltd. Medical Aesthetics Skincare Market Share (2021-2026) 287
Figure 59 GFC Life Science Co., Ltd. Medical Aesthetics Skincare Market Share (2021-2026) 291
Figure 60 Lameditech Co., Ltd. Medical Aesthetics Skincare Market Share (2021-2026) 295
Figure 61 Hironic Co., Ltd. Medical Aesthetics Skincare Market Share (2021-2026) 299
Figure 62 DongBang Medical Co., Ltd. Medical Aesthetics Skincare Market Share (2021-2026) 303
Figure 63 RFTECH Co., Ltd. Medical Aesthetics Skincare Market Share (2021-2026) 307
Figure 64 Imeik Technology Development Co., Ltd. Medical Aesthetics Skincare Market Share (2021-2026) 311
Figure 65 Freda Pharma Medical Aesthetics Skincare Market Share (2021-2026) 315
Figure 66 Huadong Medicine Co., Ltd. Medical Aesthetics Skincare Market Share (2021-2026) 319
Figure 67 Sihuan Pharmaceutical Holdings Medical Aesthetics Skincare Market Share (2021-2026) 323
Figure 68 Bloomage Biotechnology Corporation Medical Aesthetics Skincare Market Share (2021-2026) 327
Figure 69 Shanghai Haohai Biological Technology Medical Aesthetics Skincare Market Share (2021-2026) 331
Figure 70 Obagi Medical Medical Aesthetics Skincare Market Share (2021-2026) 335
Figure 71 Global Medical Aesthetics Market Revenue Share by Modality Forecast (2031) 338
Figure 72 Regional Share Shift Analysis: 2026 vs. 2031 Market Comparison 341
Research Methodology
- Market Estimated Methodology:
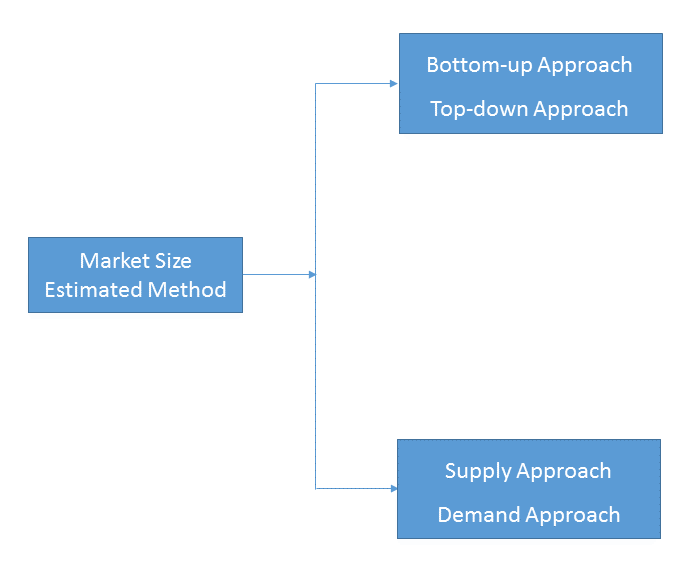
Bottom-up & top-down approach, supply & demand approach are the most important method which is used by HDIN Research to estimate the market size.
1)Top-down & Bottom-up Approach
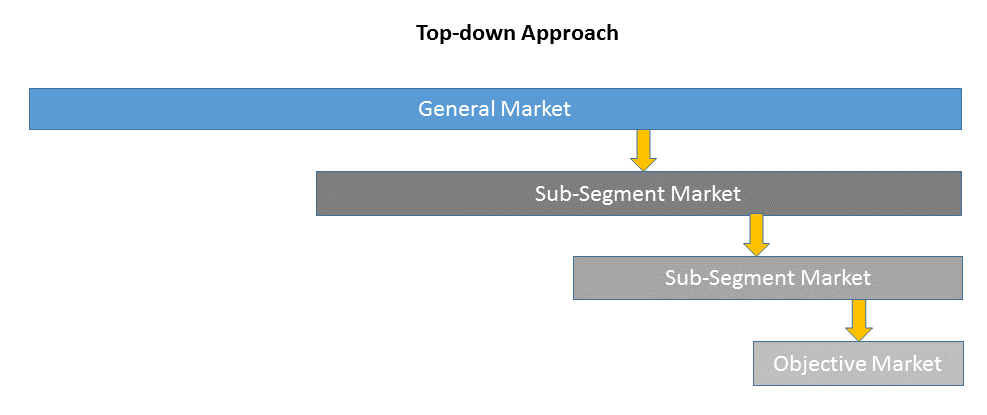
Top-down approach uses a general market size figure and determines the percentage that the objective market represents.
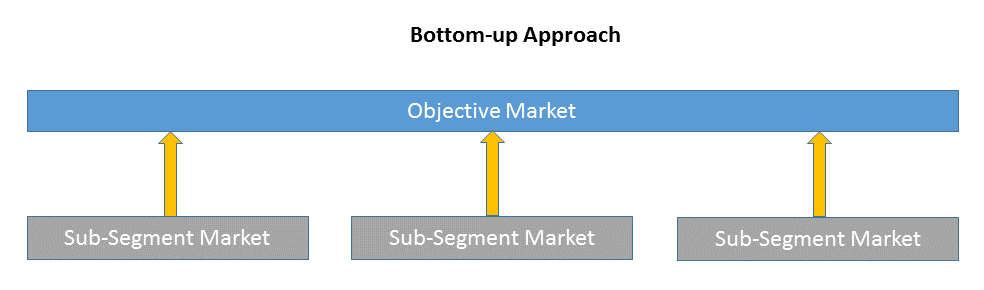
Bottom-up approach size the objective market by collecting the sub-segment information.
2)Supply & Demand Approach
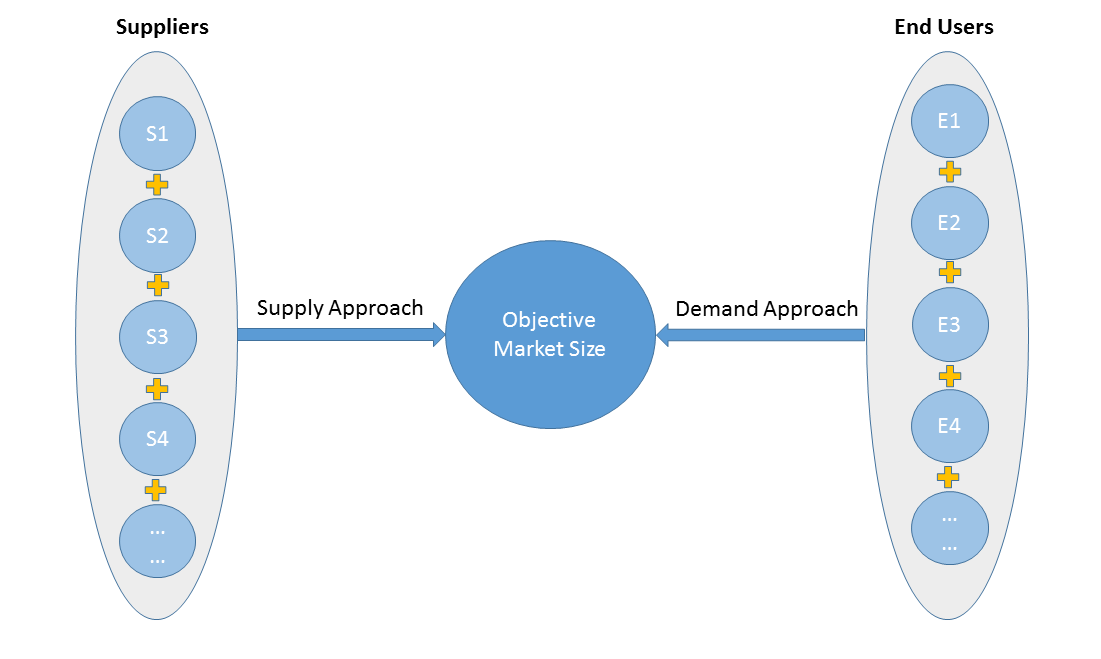
Supply approach is based on assessments of the size of each competitor supplying the objective market.
Demand approach combine end-user data within a market to estimate the objective market size. It is sometimes referred to as bottom-up approach.
- Forecasting Methodology
- Numerous factors impacting the market trend are considered for forecast model:
- New technology and application in the future;
- New project planned/under contraction;
- Global and regional underlying economic growth;
- Threatens of substitute products;
- Industry expert opinion;
- Policy and Society implication.
- Analysis Tools
1)PEST Analysis
PEST Analysis is a simple and widely used tool that helps our client analyze the Political, Economic, Socio-Cultural, and Technological changes in their business environment.
- Benefits of a PEST analysis:
- It helps you to spot business opportunities, and it gives you advanced warning of significant threats.
- It reveals the direction of change within your business environment. This helps you shape what you’re doing, so that you work with change, rather than against it.
- It helps you avoid starting projects that are likely to fail, for reasons beyond your control.
- It can help you break free of unconscious assumptions when you enter a new country, region, or market; because it helps you develop an objective view of this new environment.
2)Porter’s Five Force Model Analysis
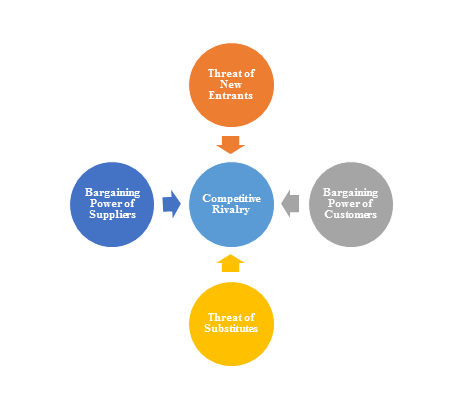
The Porter’s Five Force Model is a tool that can be used to analyze the opportunities and overall competitive advantage. The five forces that can assist in determining the competitive intensity and potential attractiveness within a specific area.
- Threat of New Entrants: Profitable industries that yield high returns will attract new firms.
- Threat of Substitutes: A substitute product uses a different technology to try to solve the same economic need.
- Bargaining Power of Customers: the ability of customers to put the firm under pressure, which also affects the customer's sensitivity to price changes.
- Bargaining Power of Suppliers: Suppliers of raw materials, components, labor, and services (such as expertise) to the firm can be a source of power over the firm when there are few substitutes.
- Competitive Rivalry: For most industries the intensity of competitive rivalry is the major determinant of the competitiveness of the industry.
3)Value Chain Analysis
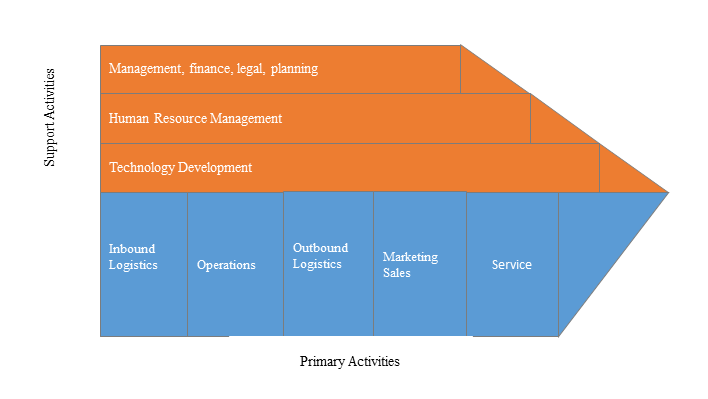
Value chain analysis is a tool to identify activities, within and around the firm and relating these activities to an assessment of competitive strength. Value chain can be analyzed by primary activities and supportive activities. Primary activities include: inbound logistics, operations, outbound logistics, marketing & sales, service. Support activities include: technology development, human resource management, management, finance, legal, planning.
4)SWOT Analysis
SWOT analysis is a tool used to evaluate a company's competitive position by identifying its strengths, weaknesses, opportunities and threats. The strengths and weakness is the inner factor; the opportunities and threats are the external factor. By analyzing the inner and external factors, the analysis can provide the detail information of the position of a player and the characteristics of the industry.
- Strengths describe what the player excels at and separates it from the competition
- Weaknesses stop the player from performing at its optimum level.
- Opportunities refer to favorable external factors that the player can use to give it a competitive advantage.
- Threats refer to factors that have the potential to harm the player.
- Data Sources
| Primary Sources | Secondary Sources |
|---|---|
| Face to face/Phone Interviews with market participants, such as: Manufactures; Distributors; End-users; Experts. Online Survey |
Government/International Organization Data: Annual Report/Presentation/Fact Book Internet Source Information Industry Association Data Free/Purchased Database Market Research Report Book/Journal/News |