Global Connector Market Analysis & 2026-2031 Strategic Forecast
- Single User License (1 Users) $ 3,500
- Team License (2~5 Users) $ 4,500
- Corporate License (>5 Users) $ 5,500
The global connector market size is estimated at 95 to 115 billion USD by 2026, subsequently expanding at a compound annual growth rate (CAGR) between 5.6% and 7.6% through 2031. This expansion is governed by an oligopolistic supply architecture where corporate consolidation continues to pool pricing power and intellectual property within an elite tier of manufacturers. The industry remains anchored by top-tier suppliers including TE Connectivity, Amphenol Corporation, Molex, Aptiv, Foxconn Interconnect Technology (FIT), Luxshare Precision, Yazaki Corporation, Rosenberger, BizLink Holding, and Japan Aviation Electronics Industry (JAE).
Connector Classification by Transmission Medium
Connectors operate as separable conductive or optical junctions engineered to preserve signal integrity and power efficiency across decoupled sub-assemblies. The market is stratified across three transmission media:
● Electrical Connectors
Electrical connectors constitute the largest revenue pool, segmented by voltage class, frequency boundary, and mechanical topology:
- Low-Frequency and Power Interconnects: Engineered for direct current and alternating current distribution below 100 MHz. These comprise automotive wire harness terminals, industrial terminal blocks, battery cell contact systems (CCS), and modular power distribution units (PDUs).
- High-Voltage and High-Current Systems: Operating across potentials of 400V to 1,000V DC and handling sustained current loads from 100A to 1,500A. Deployed in electric vehicle drivetrains and utility-scale Battery Energy Storage Systems (BESS), these components integrate touch-proof plastic shrouds, internal High-Voltage Interlock Loops (HVIL), and busbar interfaces compliant with Open Compute Project (OCP) ORV3 standards.
- High-Speed Digital Form Factors: Optimized for data channels running beyond 1 Gbps per lane and utilizing PAM4 modulation schemes to achieve 56G, 112G, and 224G configurations. Key form factors include fine-pitch board-to-board (BTB) mezzanine connectors (down to 0.35mm pitch), floating BTB systems with three-axis tolerance absorption (+/-0.7mm), CPU Land Grid Array sockets (such as LGA 4677 and LGA 6096), PCIe Gen5/Gen6 card-edge interfaces, and near-package internal copper assemblies (MCIO, SlimSAS, OverPass) designed to bypass lossy substrate traces.
● Radio Frequency (RF) and Coaxial Connectors
RF connectors preserve continuous characteristic impedance across high-frequency bands (from 100 MHz to beyond 40 GHz) using concentric geometries consisting of a central pin conductor, a precise dielectric insulator, and an outer electromagnetic interference (EMI) shield:
- Subminiature Telecommunication Interfaces: SMA (up to 18 GHz), 3.5mm precision variants (up to 26.5 GHz), and push-on blind-mate interfaces (SMP, SMPM, RSMP) utilized in active antenna units (AAUs) and phased-array radar sub-assemblies.
- Micro-Coaxial Consumer Interfaces: Low-profile board-mounted miniature receptacles (IPEX/U.FL) engineered for internal antenna routing in mobile and IoT hardware.
- Automotive RF Standards: Legacy FAKRA connectors (operating up to 6 GHz) are being rapidly superseded by Mini-FAKRA (HF-FAKRA) configurations. Mini-FAKRA supports operating bandwidths up to 20 GHz and 20 Gbps data throughput while delivering an 80% spatial footprint reduction, packaged in multi-port gang modules with IPX9K environmental sealing for ADAS cameras and radar arrays.
● Fiber-Optic Connectors
Fiber-optic connectors guide and mate glass cores with sub-micron radial alignment, eliminating electromagnetic vulnerability across high-capacity communication routes:
- Multi-Fiber High-Density Connectors: Dominated by Multi-Fiber Push-On (MPO/MTP) interfaces utilizing polyphenylene sulfide (PPS) MT ferrules with precision stainless guide pins. These align 12, 16, 24, or 32 fibers per ferrule for high-density AI data center switches.
- Discrete Single-Fiber Connectors: Zirconia ceramic ferrule systems (LC, SC) delivering insertion loss metrics below 0.2 dB across telecom backbones and SFP/QSFP optical transceivers.
- Harsh-Environment and Expanded-Beam Interfaces: Circular military-grade assemblies (e.g., J599 series) utilizing integrated ball lenses to expand optical beams, reducing sensitivity to dust, mechanical shock, and moisture in avionics and naval platforms.
- Integrated Co-Packaged Optics (CPO) and Optical Circuit Switches (OCS): Advanced physical configurations where micro-lens arrays interface directly with multi-chip silicon photonics substrates, enabling 800 Gbps through 3.2 Tbps aggregate bandwidth per socket while reducing energy consumption relative to re-timed copper channels.
Downstream Applications and Structural Dynamics
● Telecommunications and Data Communications
Representing the single largest end-market by economic value, this sector has eclipsed automotive demand due to the accelerated deployment of generative AI infrastructure.
- Cloud Compute Hardware: The massive scaling of accelerated GPU clusters requires 112G and 224G backplane connectors, high-density pluggable I/O cages (QSFP-DD, OSFP, OSFP-XD), and direct-attach copper (DAC) or active copper (ACC) cables. Server racks require point-to-point copper bypass jumpers to eliminate motherboard dielectric losses, expanding unit usage of near-package connectors (such as MCIO and KOOLIO architectures).
- Carrier Networks: The global deployment of 5G-Advanced and 5.5G infrastructure requires blind-mate board-to-board RF connectors, hybrid fiber/power-to-the-antenna (HTTA) outdoor assemblies, and IP68-rated quick-lock circular interfaces.
● Automotive
Automotive applications represent the second-largest market, serving as the primary volume driver for high-margin power and high-frequency interconnects.
- Powertrain Electrification: Transitioning to 800V battery architectures requires specialized high-voltage connectors, busbars, cell contact systems (CCS), and liquid-cooled charging inlets capable of handling up to 600A continuously. A battery electric vehicle contains 2,500 to 3,500 connection points, elevating connector bill-of-materials value to 3-5 times that of an internal combustion engine vehicle.
- Autonomous Driving & Digital Cockpit: Level 2+ and Level 3 automation programs require multi-port Mini-FAKRA, High-Speed Data (HSD), and Single-Pair automotive Ethernet (100Base-T1 through multi-gigabit) links to integrate 8MP vision sensors, LiDAR units, and central computing clusters.
● Computers and Computing Peripherals
Standing as the third-largest application sector, this segment is defined by standardized, high-pin-count interfaces across hyperscale server motherboards and client computing devices.
- System Motherboards: Driven by high-performance enterprise CPUs, motherboards incorporate LGA sockets with up to 6,096 pins, surface-mount DDR5/DDR6 Long-DIMM sockets, PCIe Gen5/Gen6 expansion slots, and M.2/EDSFF enterprise storage interfaces.
- Client Displays and Peripheral Links: High-speed peripheral channels have unified around DisplayPort 2.1 (UHBR20), HDMI 2.1/2.2, USB4, and Thunderbolt 4/5 interfaces, which require advanced shielding to mitigate EMI emissions.
● Industrial and Automation
Ranking as the fifth-largest sector, industrial demand is governed by long lifecycle requirements and harsh operational conditions.
- Factory Automation and Robotics: Programmable logic controllers, articulated robotic arms, and CNC machinery utilize M-series circular connectors (M8, M12, M23), heavy-duty rectangular modular connectors (HDC), and Single-Pair Ethernet (SPE / 10BASE-T1L) interfaces that transmit deterministic data and power over a single twisted pair up to 1,000 meters.
- Renewable Energy & Grid Storage: Photovoltaic installations and utility-scale BESS require high-amperage DC connectors, touch-safe battery quick-disconnects, and solar junction boxes certified to UL 1973 and IEC 62930.
● Consumer Electronics and Mobile Terminals
The sixth-largest sector exhibits severe cost-down pressures balanced by extreme miniaturization.
- Regulatory Convergence: The European Union universal charging directive mandating USB Type-C on mobile devices and laptops by 2024-2026 has made Type-C and USB4 the universal baseline, driving automated high-speed stamping and insert-molding capacity.
- Micro-Packaging: Smartphones, foldable hardware, smart glasses, and wearable devices mandate board-to-board connectors with pitch profiles below 0.35mm, ultra-thin battery connectors, and hermetically sealed sub-miniature input ports.
● Transportation Infrastructure
Covering high-speed passenger rail, heavy freight locomotives, urban metros, and maritime transport, this sector prioritizes mechanical longevity.
- Heavy Transit Interconnects: Train roofs, bogies, and inter-car gangways deploy automatic train couplers, multi-pin aluminum circular housings, and high-vibration power connectors engineered to resist rock impact, trackside vibration, and environmental weathering.
- Marine Extraction and Shipping: Marine systems use subsea pressure-balanced oil-filled (PBOF) connectors and corrosion-resistant naval brass or bronze interfaces.
● Aerospace and Defense
Characterized by high qualification barriers, long supply lifecycles, and stable pricing dynamics.
- Tactical and Spaceflight Connectors: Governed by military standards (MIL-DTL-38999, Micro-D/J30J, VPX architectures), these interconnects operate under operational temperature extremes (-65°C to +200°C), mechanical shock profiles exceeding 300g, and high-altitude dielectric stresses. Low Earth Orbit (LEO) commercial satellite constellations have accelerated demand for lightweight composite-shell connectors.
● Medical
Medical applications require specialized interconnects engineered for diagnostic imaging (CT, MRI, ultrasound), surgical robotics, and life-support platforms.
- Clinical Assemblies: Connectors require medical-grade silicone overmolding, high-cycle push-pull latching, fluidic and pneumatic hybrid integration, and chemical resistance to withstand repeated autoclave steam cycles, wipe-down disinfectants, and gamma sterilization.
● Others
Encompasses commercial office automation, intelligent point-of-sale hardware, commercial unmanned aerial vehicles (UAVs), and emerging humanoid robotic platforms requiring compact multi-axis rotary joints and high-density slip rings.
Supply Chain and Value Chain Architecture
● Upstream Material and Tooling Inputs
Upstream inputs comprise raw physical materials and high-precision tooling, representing roughly 60% of total connector manufacturing cost:
- Metallic Conductors: Terminals are stamped from phosphor bronze (C5191, C5210) for general spring contacts, while beryllium copper (C17200) and titanium copper alloys are utilized for miniaturized, high-stress, and high-temperature terminals to prevent stress relaxation. Cold-rolled steel (SPCC) and die-cast zinc/aluminum alloys form the external shielding shells.
- High-Performance Engineering Resins: Polymer housings require UL 94V-0 flammability ratings, high dielectric breakdown resistance, and continuous heat resistance exceeding 260°C to withstand SMT reflow soldering. Liquid Crystal Polymer (LCP) is utilized for thin-walled micro-connectors; Polyphenylene Sulfide (PPS) for server backplanes and EV housings; and Polybutylene Terephthalate (PBT) and Polyamides (PA66, PA46) for industrial and automotive harnesses.
- Contact Plating Materials: Terminals receive reel-to-reel continuous selective plating. Nickel acts as a barrier layer; cobalt-hardened gold (15u" to 30u") is deposited on separable contact touchpoints to prevent oxidation and fretting wear; pure matte tin is applied to solder tails; and silver or palladium-nickel alloys are used in high-voltage EV and high-frequency contacts.
- Tooling Bottlenecks: Precision tooling represents the primary capital barrier. Fabricating progressive multi-station stamping dies and sub-micron multi-cavity injection molds requires ultra-precision wire EDM, CNC jig grinders, and multi-physics simulation software. Tooling development cycles typically require 8 to 16 weeks.
● Midstream Fabrication and Value-Add Assembly
Midstream processing integrates stamping, injection, plating, and automated assembly:
- High-Speed Stamping: Automated mechanical presses operate progressive dies at rates exceeding 600 to 1,200 strokes per minute, producing continuous reels of stamped contact terminals with micron-level tolerances.
- Injection Molding: High-tonnage electric injection molding presses shoot molten resins into chilled molds, maintaining thin-wall geometries down to 0.15mm without structural warping.
- Surface Finishing and Plating: Environmental compliance has forced electroplating operations into dedicated regional industrial zones or vertically integrated zero-discharge facilities.
- Automated Assembly & Testing: Automated lines insert contacts into housings, perform continuous pin-retention checks, deploy high-speed automated optical inspection (AOI) to verify true position and coplanarity, and execute 100% electrical continuity and insulation checks.
- Value Migration to Cable Assemblies: Connector manufacturers capture downstream margins by integrating discrete components into complete cable assemblies, including high-speed active copper cables (ACC/AEC), optical patch cables, and complex automotive wiring harnesses.
● Downstream Integration and Platform OEM Specification
Downstream distribution routes finished assemblies into Tier-1 subsystem integrators, contract manufacturing networks, and OEM assembly hubs:
- Automotive Integrators: Automotive wire harness specialists (such as Aptiv, Yazaki, Sumitomo, and Leoni) integrate connectors into complete vehicle electrical distribution systems (EDS), which are sequenced directly into automotive OEM assembly lines.
- Hyperscale Datacom Integrators: Server ODMs (Foxconn, Quanta, Pegatron, Wiwynn) source backplane and high-speed cages dictated by hyperscale cloud platforms (Google, Microsoft, AWS, Meta) to manufacture finished compute racks.
- Industrial and Aerospace Integrators: System assemblers integrate ruggedized modular connectors into factory automation cells, flight avionics bays, and defense platforms.
Commercial Models and Channel Dynamics
● Direct Sales Operations
Direct engagement constitutes the primary commercial route for Tier-1 connector manufacturers serving major global accounts, accounting for the large majority of revenue across listed market leaders.
- Pre-Design Engagement: Because advanced interconnects involve proprietary designs, dedicated Key Account Managers (KAM) and Field Application Engineers (FAEs) embed inside customer R&D centers 18 to 24 months before commercial production. This early integration locks in connector specifications, contact geometry, signal integrity modeling, and design-for-manufacturability (DFM) verification.
● Authorized Distribution Networks
Distributor networks manage account fragmentation, deliver localized warehousing, and serve low-to-medium volume customers, accounting for 10% to 20% of net sales for diversified players.
- Inventory Buffers: Broadline distributors (Arrow, Avnet, WPG Holdings) and specialized catalog distributors hold stock, execute cut-and-crimp modifications, and absorb working capital exposure across disparate regional industrial, defense, and IoT equipment builders.
● Tripartite B2B2B EMS/ODM Procurement Routing
Modern high-volume electronics procurement operates within a tripartite architecture:
- Architectural AVL Dictation: Strategic system brand owners (such as NVIDIA, Apple, Dell, and Cisco) design equipment architectures, maintain Approved Vendor Lists (AVL), and mandate specific connector part numbers.
- Operational Fulfillment: Contract manufacturing entities (EMS and ODM providers such as Foxconn, Quanta, Jabil, and Celestica) issue commercial purchase orders, handle inbound logistics, and mount connectors onto printed circuit boards. Connector vendors must consequently coordinate technical specifications with the brand owner while negotiating commercial schedules with contract manufacturing buyers.
Regional Market Dynamics
● Asia-Pacific
Asia-Pacific operates as the world's largest connector production base and regional consumption market, capturing the primary share of global unit volumes. Regional growth is projected within a CAGR range of 6.2% to 8.2% through 2031.
- China: Anchored by a mature domestic electronics supply chain, high domestic electric vehicle output, and national infrastructure projects such as "East Data West Computing," China remains the largest single market. Local suppliers, initially focused on consumer hardware, have consolidated strong market shares across automotive high-voltage architectures, commercial aerospace, and 112G/224G server interconnects.
- Taiwan, China: Functions as the epicenter of global server, PC, and computing hardware engineering. Local connector suppliers maintain dominance in CPU sockets, card-edge slots, high-current server busbars, and enterprise high-speed backplanes.
- Japan: While broad assembly volumes have shifted offshore, Japanese suppliers retain competitive moats in high-precision micro-pitch board-to-board connectors, automotive floating connectors, micro-coaxial switches, and industrial robotics interfaces.
- Republic of Korea: Supported by domestic consumer electronics, automotive, and memory fabrication hubs, Korean manufacturers supply precision board-to-board connectors, display interfaces, and automotive wiring harnesses.
- Southeast Asia and India: Vietnam, Thailand, Malaysia, and India are capturing substantial electronics assembly capacity under "China Plus One" diversification programs, prompting Tier-1 connector suppliers to build automated stamping, molding, and harness assembly facilities in these jurisdictions.
● North America
North America maintains the second-largest share of global connector consumption. Growth is projected within a CAGR range of 5.0% to 7.0% through 2031.
- Market Structure: Demand is concentrated in high-value, high-margin sectors: AI hyperscale data centers, defense electronics, commercial space platforms, and high-tier automotive systems. Leading multinational connector manufacturers headquartered in North America dominate global I/O, backplane, and military interface standards.
● Europe
Europe represents the third-largest regional market. Growth is projected within a conservative CAGR range of 4.2% to 6.2% through 2031.
- Market Structure: Growth is tied to automotive engineering, industrial automation, railway transit, and renewable energy infrastructure. Although the European market faces elevated industrial energy costs and slower automotive production growth, demand remains steady for industrial heavy-duty connectors, single-pair Ethernet interfaces, and specialized RF/optical components.
● South America
South America represents an emerging market capturing under 4% of global connector demand, with expected growth between 4.0% and 6.0% CAGR through 2031.
- Market Structure: Regional demand is centered on Brazilian automotive production clusters, mining extraction instrumentation across Chile and Peru, and baseline urban telecommunications infrastructure.
● Middle East and Africa (MEA)
A fast-growing frontier market with projected growth between 4.8% and 6.8% CAGR through 2031.
- Market Structure: Demand is concentrated in harsh-environment, hermetically sealed connectors for upstream oil and gas production, utility-scale photovoltaic solar farms, and infrastructure modernization across the Arabian Peninsula.
Regulatory Policy and Industrial Frameworks
● Interface Standardization Mandates
- European Union Universal Charger Mandate: The European Union enacted Directive 2022/2380, mandating USB Type-C as the standardized charging and data interface across smartphones, tablets, cameras, and portable electronics, extending the scope to include notebook computers by 2026. This policy has phased out legacy proprietary interfaces, establishing USB Type-C and USB4 specifications as the universal baseline.
● Automotive Decarbonization and Electrification
- Internal Combustion Engine Bans: Statutory legislation in the European Union requiring zero carbon emissions from new passenger vehicles by 2035, alongside Zero Emission Vehicle (ZEV) mandates across North American states and Asian nations, requires automotive OEMs to transition investments into high-voltage powertrain connector designs.
- Charging Interface Harmonization: The commercialization of electric vehicle charging infrastructure is converging around regional standards: CCS2 across Europe, and the North American Charging Standard (NACS / SAE J3400) in North America, requiring connector manufacturers to adjust tooling for commercial charging guns and vehicle inlet ports.
● Digital Infrastructure and Energy Consumption Directives
- Data Center Compute Targets: National digital infrastructure programs, such as China's "East Data West Computing" guidelines, drive computing capacity investments. Concurrently, tightening municipal Power Usage Effectiveness (PUE) requirements (targeting thresholds below 1.25) mandate the transition toward low-power passive direct copper cabling (DAC) and liquid-cooled interconnect manifolds.
● Trade Compliance and Supply Chain Geopolitics
- Tariffs and Origin Rules: Elevated tariffs under Section 301 on electromechanical hardware originating from China continue to influence commercial routing. In response, Tier-1 manufacturers have operationalized redundant multi-region production facilities across Southeast Asia, North America, and Eastern Europe to insulate supply chains against cross-border disruptions.
● Environmental, Chemical, and ESG Directives
- Hazardous Material Bans: Connector manufacturing processes are governed by EU RoHS, REACH, and halogen-free industry mandates, restricting the use of specific leaded copper alloys, hexavalent chromium surface treatments, and brominated flame retardants in engineering resins. Corporate sustainability criteria increasingly evaluate the carbon intensity of terminal electroplating and resin recyclability.
Competitive Profiles of Key Market Participants
● North America
- Amphenol Corporation: Operates an agile, decentralized organizational structure with primary market share across military-aerospace, cloud datacom, and automotive sectors. Core competitive assets include high-speed backplane architectures (Paladin, ExaMAX), MIL-DTL cylindrical connectors, and high-density near-chip copper assemblies.
- Molex LLC (Lisle, Illinois, USA): A subsidiary of Koch Industries with broad technical capabilities in micro-miniature board-to-board interfaces, high-density server I/O transceivers (QSFP-DD, OSFP), and Brad industrial circular connectors.
- Glenair, Inc. : Maintains operational moats within tactical military, space-rated, and severe harsh-environment sectors. Product specializations include high-density circular interfaces (Mighty Mouse), hermetic glass-to-metal connectors, and composite backshells.
- Samtec, Inc.: Focuses on ultra-high-density board-to-board mezzanine systems (SEARAY), 112G/224G high-speed backplanes, and FireFly optical flyover cable assemblies, backed by quick-turn prototyping capabilities.
- Belden Inc.: Operates in enterprise network and industrial factory connectivity through specialized brands including Lumberg Automation and Hirschmann, providing IP67/IP69K-rated M8 and M12 circular connectors and industrial Ethernet interfaces.
- Corning Incorporated: Holds proprietary optical patents across multi-fiber push-on (MTP/MPO) connectors, hardened outdoor fiber interfaces (OptiTap), and advanced micro-lens arrays engineered for co-packaged optics (CPO).
- Sensata Technologies: Specializes in mission-critical automotive and industrial sensor connections, high-voltage battery safety disconnect terminals, and glass-to-metal hermetic seals.
- Pulse Electronics: Produces Integrated Connector Modules (ICMs), specifically RJ45 jacks with integrated magnetics for 10GBase-T enterprise Ethernet and automotive Ethernet nodes.
- Hubbell Incorporated: Specializes in high-amperage industrial pin-and-sleeve plugs (IEC 60309), heavy electrical distribution connectors, and utility-scale grid power terminations.
● Europe
- TE Connectivity Ltd.: The largest global connector manufacturer by market share, maintaining market positions across automotive, enterprise compute, and industrial automation. Core product lines include AMP, DEUTSCH, and MCON automotive terminals, 800V EV power connectors, and 224G server backplanes.
- Aptiv PLC: Focuses on automotive vehicle electrical distribution systems (EDS), manufacturing high-voltage EV harness connectors, low-voltage signal terminals, and sealed ADAS domain controller housings.
- Rosenberger Hochfrequenztechnik GmbH & Co. KG: Specializes in high-frequency automotive and telecommunications RF architectures. The company pioneered automotive FAKRA and Mini-FAKRA (HFM) standards, H-MTD high-speed differential links, and high-voltage vehicle powertrain connectors.
- HUBER+SUHNER AG: Focuses on precision RF, microwave, and optical connectivity. Core products include high-power liquid-cooled electric vehicle charging systems (RADOX HPC), RF test connectors, and Polatis optical circuit switches.
- Phoenix Contact GmbH & Co. KG: Specializes in industrial interface technology, including COMBICON PCB terminal blocks, HEAVYCON industrial connectors, and DC fast-charging plugs (CCS, NACS).
- HARTING Technology Group: Established standard industrial modular rectangular connectors (Han family), while pioneering Single-Pair Ethernet (ix Industrial, SPE T1) interfaces for smart manufacturing.
- Weidmüller Group: Produces industrial cabinet wiring terminals, OMNIMATE PCB terminal blocks, RockStar heavy-duty connectors, and IP67 circular fieldbus interfaces.
- Radiall SA: Focuses on civil aerospace, defense, and telecommunication hardware, with expertise in multi-pin modular rack-and-panel connectors (EPX, ARINC 600) and high-frequency coaxial connectors.
- Cembre S.p.A.: Specializes in industrial electrical compression connectors, crimping lugs, and railway trackside and traction interconnect assemblies.
● Asia-Pacific
- Foxconn Interconnect Technology / FIT: Focuses on enterprise cloud server connections (QSFP-DD, OSFP, CPU sockets), consumer computing I/O (USB-C), and automotive EV charging interfaces.
- Yazaki Corporation: A global leader in automotive wire harnesses, junction boxes, high-voltage vehicle connectors, and battery connection terminals.
- BizLink Holding Inc.: Produces high-speed data center cables, electric vehicle charging harnesses, and industrial robotic cable assemblies.
- Japan Aviation Electronics Industry / JAE: Focuses on fine-pitch consumer micro-connectors, automotive electronics interfaces (MX series), and industrial sealed connectors.
- Hirose Electric Co., Ltd.: Specializes in ultra-miniature board-to-board connectors (pitches down to 0.3mm), micro-coaxial connectors, and automotive high-speed camera connectors.
- LOTES Co., Ltd.: A global manufacturer of CPU server/desktop sockets (Intel and AMD platforms), memory module sockets (DDR5 Long-DIMM), and PCIe expansion interfaces.
- Korea Electric Terminal / KET: The leading South Korean manufacturer of automotive wire harness terminals, sealed housings, and high-voltage EV battery connectors.
- Iriso Electronics Co., Ltd.: Specializes in floating board-to-board connectors engineered to absorb multi-axis vibration in automotive powertrain, radar, and ADAS hardware.
- Sumitomo Electric Industries: Manufactures sealed automotive harness terminals, EV high-voltage connectors, and telecommunications optical fiber connectors.
- J.S.T. Mfg. Co., Ltd.: Manufactures standard crimp-style disconnectable wire-to-board and wire-to-wire connectors (XH, PH, VH series) across household appliance and automotive applications.
- Luxshare Precision Industry Co., Ltd.: A vertically integrated leader supplying consumer electronics micro-connectors (Type-C), AI data center interconnects (QSFP-DD, OSFP, 112G/224G backplane), and automotive high-voltage architectures. Its footprint was expanded through the acquisition of European automotive harness supplier Leoni AG.
- Jonhon Optronic Technology / AVIC JONHON: Focuses on high-reliability interconnects for commercial aerospace, defense, telecommunications, and new energy vehicles, with products encompassing circular harsh-environment interfaces, optical assemblies, and liquid-cooling couplings.
- Electric Connector Technology / ECT: Specializes in micro RF connectors, automotive Mini-FAKRA and HSD interfaces, and high-precision board-to-board connectors.
- Additional Regional Suppliers: I-PEX Inc., Murata, Yokowo, Panasonic Industry, Hosiden, MinebeaMitsumi, SMK Corp., Omron, KEL Corporation; CNPLUS, JNTC, KISTRON, Shinhwa Contech, UJU Electronics; ACES Electronics, SINBON Electronics, Singatron Group, Lintes Technology, Alltop Technology, SpeedTech, Chant Sincere, UDE, Wieson Technologies, Pan-International, CviLux, Cheng Uei (Foxlink), JPC Connectivity, Bellwether, Tai Twun Enterprise, CWB Automotive Electronics, Shenzhen Uniconn Technology, YD Electronic Technology, Wenzhou Yihua Connector, Henan Carve Electronic Technology, Shenzhen Chuangyitong Technology, Shenzhen Deren Electronic, Weifang Genius Electronics, WCON ELECTRONICS, Shenglan Technology, Guizhou Space Appliance, Hongrida Technology, DongGuan DingTong Precision Metal Co., Ltd, Shenzhen Everwin Precision Technology Co., Ltd., Zhejiang Yonggui Electric Equipment Co., Ltd., Sichuan Huafeng Technology, Suzhou Recodeal Interconnect System Co., Ltd..
High-Impact Catalysts and Structural Risks
● Strategic Growth Catalysts
- Generative AI Hardware Upgrades: The deployment of dense GPU clusters is driving demand for high-speed interconnects. Transitioning from 112G to 224G and 448G transmission lines reduces PCB trace length tolerances, accelerating adoption of near-package copper flyover cartridges (such as MCIO and PCIe Gen6/Gen7 harnesses) and high-density I/O cages. In NVL-class rack systems, connector content per computing unit increases by a factor of four to five relative to standard CPU servers.
- High-Voltage 800V Automotive Platforms: The expansion of 800V DC electric vehicle powertrains and multi-megawatt public charging hubs represents an expanding market for high-current copper terminals, active thermal monitoring sensors, high-voltage interlocks, and liquid-cooled charging assemblies.
- Battery Energy Storage System (BESS) Scale: Global grid storage deployments drive high volume requirements for touch-safe high-current battery disconnects, automated Cell Contact Systems (CCS), and modular rack busbars engineered to mitigate thermal runaway risks.
- Factory Digitization via Single-Pair Ethernet: Industrial adoption of the 10BASE-T1L and 100BASE-T1 standards enables direct Ethernet-to-sensor field transmission, phasing out legacy fieldbuses and spurring retrofits of industrial circular and modular rectangular connectors.
● Structural Industry Risks
- Tooling Capital Intensity and Platform Delays: Developing micro-pitch tooling for sub-0.35mm BTB or 224G backplane connectors requires substantial capital expenditure. Delays in next-generation chip architectures or consumer platform redesigns create capital allocation risks for midstream suppliers.
- Raw Material and Feedstock Inflation: Metallic alloys (beryllium copper, phosphor bronze), precious electroplating chemicals (gold, palladium), and specialized engineering resins (LCP, PPS) represent roughly 60% of manufacturing costs. Commodity price volatility can compress gross margins when supplier contracts restrict immediate cost pass-through.
- Operational Duplication from Trade Barriers: Tariff policies, national security screening, and localized sourcing mandates have forced connector manufacturers to build redundant production lines outside their home regions. Managing split operations across multiple facilities increases depreciation costs and fragments economies of scale.
- Commodity Margin Compression in Low-Complexity Form Factors: Standard consumer interfaces and legacy low-voltage automotive terminals face intense price competition from regional component fabricators, prompting Tier-1 manufacturers to divest or deprioritize commodity product lines in favor of specialized high-speed, high-voltage interconnects.
1.1 Market Definition and Product Taxonomy 1
1.2 Research Methodology and Analytical Framework 2
1.2.1 Primary Sourcing and Industry Delphi Panels 2
1.2.2 Secondary Modeling and Bottom-Up Aggregation 3
1.3 Macroeconomic Assumptions and Forecast Horizon (2021-2031) 4
1.4 Base Year Calibration and Unit Economics 5
1.5 Acronyms and Technical Nomenclature 6
Chapter 2 Executive Strategic Briefing 7
2.1 Global Connector Industry Trajectory and Market Matrix (2021-2031) 7
2.2 Disruptive Megatrends: Electrification, High-Frequency Transmission, and AI Workloads 9
2.3 Strategic Battlegrounds Across Key Value Tiers 11
2.4 Cross-Sectoral Demand Shifts and High-Velocity Verticals 13
Chapter 3 Global Connector Value Chain and Manufacturing Architecture 16
3.1 Comprehensive Value Chain Topology 16
3.2 Upstream Sourcing Dynamics and Raw Material Volatility 18
3.3 Critical Manufacturing Methodologies 24
Chapter 4 Cross-Border Trade Dynamics, Tariff Environments, and Supply Chain Realignment 31
4.1 Global Flow of Goods and Interconnect Trade Corridors 31
4.2 Strategic De-Risking, China+1 Shifts, and Regionalization of Production Hubs 33
4.3 Export Controls, Technical Barriers to Trade, and Carbon Border Adjustments 35
4.4 Logistics Friction Points, Inventory Buffering, and Critical Lead-Time Analytics 38
Chapter 5 Global Connector Market Breakdown by Transmission Medium 43
5.1 Electrical Connector Market Dynamics 43
5.2 RF and Coaxial Connector Market Dynamics 50
5.3 Fiber-Optic Connector Market Dynamics 55
Chapter 6 Global Connector Market Breakdown by Downstream Application 58
6.1 Automotive 58
6.2 Consumer Electronics and Mobile Terminals 63
6.3 Telecom & Datacom 68
6.4 Computers and Computing Peripherals 73
6.5 Industrial & Automation 78
6.6 Medical 82
6.7 Aerospace & Defense 84
6.8 Transportation Infrastructure 85
6.9 Others 85
Chapter 7 Global Geographic Dynamics: Production Hubs vs. Demand Centers 86
7.1 North America 86
7.1.1 United States: Aerospace, AI Data Centers, and Advanced Automotive Demand 88
7.1.2 Mexico: Nearshore Manufacturing Corridors and Automotive Harness Clusters 92
7.1.3 Canada: Specialized Industrial, Harsh-Environment, and Power Grid Integration 95
7.2 Europe 97
7.2.1 Germany: Automotive Electrification and High-End Industrial Automation 99
7.2.2 France: Civil Aerospace, Rail Transit, and Defense Systems 102
7.2.3 Italy: Factory Automation and Specialized Electronic Components 105
7.2.4 United Kingdom: Advanced Datacom and High-Reliability Electronics 107
7.2.5 Rest of Europe: Nordic Datacenter Clusters and Central European Assembly Hubs 109
7.3 Asia-Pacific 111
7.3.1 China: Global Electronics Assembly Epicenter and Expanding EV Ecosystem 113
7.3.2 Japan: Ultra-Precision Micro-Connectors and High-Reliability Material Hub 117
7.3.3 South Korea: Memory Infrastructure, Mobile Terminals, and Automotive Battery Links 120
7.3.4 Taiwan (China): Advanced Computing Substrates, Server Harnesses, and Foundries 122
7.3.5 Vietnam & Southeast Asia: Diversification Corridors for Consumer Interconnects 124
7.3.6 India: High-Growth Smartphone Assembly and Railway Electrification Programs 125
7.4 Latin America 126
7.5 Middle East & Africa 126
Chapter 8 Competitive Benchmarking & Market Concentration Matrix 127
8.1 Global Market Share Breakdown and Industry Concentration Ratios (CR4, CR8, HHI) 127
8.2 Strategic Positioning Matrix: Global Diversified Leaders vs. Specialized Purveyors 131
8.3 Mergers, Acquisitions, and Strategic Alliances (2021-2026) 134
8.4 Patent Landscapes, Proprietary Terminal Designs, and Interoperability Standards 137
Chapter 9 Corporate Intelligence: North American & European Interconnect Leaders 143
9.1 Amphenol 143
9.1.1 Enterprise Overview and Global Footprint 143
9.1.2 SWOT Analysis 144
9.1.3 Connector Financial Performance and Market Share Analytics 145
9.2 TE Connectivity 146
9.2.1 Enterprise Overview and Global Footprint 146
9.2.2 SWOT Analysis 147
9.2.3 Connector Financial Performance and Market Share Analytics 148
9.3 Molex 149
9.3.1 Enterprise Overview and Global Footprint 149
9.3.2 SWOT Analysis 150
9.3.3 Connector Financial Performance and Market Share Analytics 151
9.4 Aptiv 152
9.4.1 Enterprise Overview and Global Footprint 152
9.4.2 SWOT Analysis 153
9.4.3 Connector Financial Performance and Market Share Analytics 154
9.5 Glenair 155
9.5.1 Enterprise Overview and Global Footprint 155
9.5.2 SWOT Analysis 156
9.5.3 Connector Financial Performance and Market Share Analytics 157
9.6 Samtec 158
9.6.1 Enterprise Overview and Global Footprint 158
9.6.2 SWOT Analysis 159
9.6.3 Connector Financial Performance and Market Share Analytics 160
9.7 Belden Inc. 161
9.7.1 Enterprise Overview and Global Footprint 161
9.7.2 SWOT Analysis 162
9.7.3 Connector Financial Performance and Market Share Analytics 163
9.8 Corning 164
9.8.1 Enterprise Overview and Global Footprint 164
9.8.2 SWOT Analysis 165
9.8.3 Connector Financial Performance and Market Share Analytics 166
9.9 Radiall 167
9.9.1 Enterprise Overview and Global Footprint 167
9.9.2 SWOT Analysis 168
9.9.3 Connector Financial Performance and Market Share Analytics 169
9.10 HUBER+SUHNER 170
9.10.1 Enterprise Overview and Global Footprint 170
9.10.2 SWOT Analysis 171
9.10.3 Connector Financial Performance and Market Share Analytics 172
9.11 Sensata Technologies 173
9.11.1 Enterprise Overview and Global Footprint 173
9.11.2 SWOT Analysis 174
9.11.3 Connector Financial Performance and Market Share Analytics 175
9.12 Rosenberger 176
9.12.1 Enterprise Overview and Global Footprint 176
9.12.2 SWOT Analysis 177
9.12.3 Connector Financial Performance and Market Share Analytics 178
9.13 Phoenix Contact 179
9.13.1 Enterprise Overview and Global Footprint 179
9.13.2 SWOT Analysis 180
9.13.3 Connector Financial Performance and Market Share Analytics 181
9.14 Cembre 182
9.14.1 Enterprise Overview and Global Footprint 182
9.14.2 SWOT Analysis 183
9.14.3 Connector Financial Performance and Market Share Analytics 184
9.15 HARTING Technology Group 185
9.15.1 Enterprise Overview and Global Footprint 185
9.15.2 SWOT Analysis 186
9.15.3 Connector Financial Performance and Market Share Analytics 187
9.16 Weidmüller 188
9.16.1 Enterprise Overview and Global Footprint 188
9.16.2 SWOT Analysis 189
9.16.3 Connector Financial Performance and Market Share Analytics 190
9.17 Pulse Electronics 191
9.17.1 Enterprise Overview and Global Footprint 191
9.17.2 SWOT Analysis 192
9.17.3 Connector Financial Performance and Market Share Analytics 193
9.18 Hubbell Incorporated 194
9.18.1 Enterprise Overview and Global Footprint 194
9.18.2 SWOT Analysis 195
9.18.3 Connector Financial Performance and Market Share Analytics 196
Chapter 10 Corporate Intelligence: Japanese & South Korean Interconnect Leaders 197
10.1 Hirose Electric 197
10.1.1 Enterprise Overview and Global Footprint 197
10.1.2 SWOT Analysis 198
10.1.3 Connector Financial Performance and Market Share Analytics 199
10.2 YAZAKI Corporation 200
10.2.1 Enterprise Overview and Global Footprint 200
10.2.2 SWOT Analysis 201
10.2.3 Connector Financial Performance and Market Share Analytics 202
10.3 IRISO Electronics 203
10.3.1 Enterprise Overview and Global Footprint 203
10.3.2 SWOT Analysis 204
10.3.3 Connector Financial Performance and Market Share Analytics 205
10.4 Japan Aviation Electronics Industry (JAE) 206
10.4.1 Enterprise Overview and Global Footprint 206
10.4.2 SWOT Analysis 207
10.4.3 Connector Financial Performance and Market Share Analytics 208
10.5 Korea Electric Terminal (KET) 209
10.5.1 Enterprise Overview and Global Footprint 209
10.5.2 SWOT Analysis 210
10.5.3 Connector Financial Performance and Market Share Analytics 211
10.6 KEL Corporation 212
10.6.1 Enterprise Overview and Global Footprint 212
10.6.2 SWOT Analysis 213
10.6.3 Connector Financial Performance and Market Share Analytics 214
10.7 Yokowo Co. Ltd. 215
10.7.1 Enterprise Overview and Global Footprint 215
10.7.2 SWOT Analysis 216
10.7.3 Connector Financial Performance and Market Share Analytics 217
10.8 Hosiden Corporation 218
10.8.1 Enterprise Overview and Global Footprint 218
10.8.2 SWOT Analysis 219
10.8.3 Connector Financial Performance and Market Share Analytics 220
10.9 SMK Corp. 221
10.9.1 Enterprise Overview and Global Footprint 221
10.9.2 SWOT Analysis 222
10.9.3 Connector Financial Performance and Market Share Analytics 223
10.10 Omron Corporation 224
10.10.1 Enterprise Overview and Global Footprint 224
10.10.2 SWOT Analysis 225
10.10.3 Connector Financial Performance and Market Share Analytics 226
10.11 Panasonic 227
10.11.1 Enterprise Overview and Global Footprint 227
10.11.2 SWOT Analysis 228
10.11.3 Connector Financial Performance and Market Share Analytics 229
10.12 MinebeaMitsumi 230
10.12.1 Enterprise Overview and Global Footprint 230
10.12.2 SWOT Analysis 231
10.12.3 Connector Financial Performance and Market Share Analytics 232
10.13 Murata 233
10.13.1 Enterprise Overview and Global Footprint 233
10.13.2 SWOT Analysis 234
10.13.3 Connector Financial Performance and Market Share Analytics 235
10.14 I-PEX Inc. 236
10.14.1 Enterprise Overview and Global Footprint 236
10.14.2 SWOT Analysis 237
10.14.3 Connector Financial Performance and Market Share Analytics 238
10.15 Sumitomo Electric 239
10.15.1 Enterprise Overview and Global Footprint 239
10.15.2 SWOT Analysis 240
10.15.3 Connector Financial Performance and Market Share Analytics 241
10.16 J.S.T. Mfg. Co. Ltd. 242
10.16.1 Enterprise Overview and Global Footprint 242
10.16.2 SWOT Analysis 243
10.16.3 Connector Financial Performance and Market Share Analytics 244
10.17 CNPLUS 245
10.17.1 Enterprise Overview and Global Footprint 245
10.17.2 SWOT Analysis 246
10.17.3 Connector Financial Performance and Market Share Analytics 247
10.18 JNTC 248
10.18.1 Enterprise Overview and Global Footprint 248
10.18.2 SWOT Analysis 249
10.18.3 Connector Financial Performance and Market Share Analytics 250
10.19 KISTRON 251
10.19.1 Enterprise Overview and Global Footprint 251
10.19.2 SWOT Analysis 252
10.19.3 Connector Financial Performance and Market Share Analytics 253
10.20 Shinhwa Contech 254
10.20.1 Enterprise Overview and Global Footprint 254
10.20.2 SWOT Analysis 255
10.20.3 Connector Financial Performance and Market Share Analytics 256
10.21 UJU Electronics 257
10.21.1 Enterprise Overview and Global Footprint 257
10.21.2 SWOT Analysis 258
10.21.3 Connector Financial Performance and Market Share Analytics 259
Chapter 11 Corporate Intelligence: Greater China Interconnect Leaders 260
11.1 Foxconn Interconnect Technology Limited (FIT) 260
11.1.1 Enterprise Overview and Global Footprint 260
11.1.2 SWOT Analysis 261
11.1.3 Connector Financial Performance and Market Share Analytics 262
11.2 Luxshare 263
11.2.1 Enterprise Overview and Global Footprint 263
11.2.2 SWOT Analysis 264
11.2.3 Connector Financial Performance and Market Share Analytics 265
11.3 DongGuan DingTong Precision Metal Co. Ltd 266
11.3.1 Enterprise Overview and Global Footprint 266
11.3.2 SWOT Analysis 267
11.3.3 Connector Financial Performance and Market Share Analytics 268
11.4 Jonhon Optronic Technology 269
11.4.1 Enterprise Overview and Global Footprint 269
11.4.2 SWOT Analysis 270
11.4.3 Connector Financial Performance and Market Share Analytics 271
11.5 SINBON Electronics 272
11.5.1 Enterprise Overview and Global Footprint 272
11.5.2 SWOT Analysis 273
11.5.3 Connector Financial Performance and Market Share Analytics 274
11.6 Singatron Group 275
11.6.1 Enterprise Overview and Global Footprint 275
11.6.2 SWOT Analysis 276
11.6.3 Connector Financial Performance and Market Share Analytics 277
11.7 Tai Twun Enterprise 278
11.7.1 Enterprise Overview and Global Footprint 278
11.7.2 SWOT Analysis 279
11.7.3 Connector Financial Performance and Market Share Analytics 280
11.8 CWB Automotive Electronics Co. Ltd 281
11.8.1 Enterprise Overview and Global Footprint 281
11.8.2 SWOT Analysis 282
11.8.3 Connector Financial Performance and Market Share Analytics 283
11.9 Lintes Technology 284
11.9.1 Enterprise Overview and Global Footprint 284
11.9.2 SWOT Analysis 285
11.9.3 Connector Financial Performance and Market Share Analytics 286
11.10 LOTES 287
11.10.1 Enterprise Overview and Global Footprint 287
11.10.2 SWOT Analysis 288
11.10.3 Connector Financial Performance and Market Share Analytics 289
11.11 Sichuan Huafeng Technology 290
11.11.1 Enterprise Overview and Global Footprint 290
11.11.2 SWOT Analysis 291
11.11.3 Connector Financial Performance and Market Share Analytics 292
11.12 Shenzhen Uniconn Technology 293
11.12.1 Enterprise Overview and Global Footprint 293
11.12.2 SWOT Analysis 294
11.12.3 Connector Financial Performance and Market Share Analytics 295
11.13 YD Electronic Technology 296
11.13.1 Enterprise Overview and Global Footprint 296
11.13.2 SWOT Analysis 297
11.13.3 Connector Financial Performance and Market Share Analytics 298
11.14 ACES Electronics 299
11.14.1 Enterprise Overview and Global Footprint 299
11.14.2 SWOT Analysis 300
11.14.3 Connector Financial Performance and Market Share Analytics 301
11.15 Pan-International 302
11.15.1 Enterprise Overview and Global Footprint 302
11.15.2 SWOT Analysis 303
11.15.3 Connector Financial Performance and Market Share Analytics 304
11.16 Wenzhou Yihua Connector Co. Ltd. 305
11.16.1 Enterprise Overview and Global Footprint 305
11.16.2 SWOT Analysis 306
11.16.3 Connector Financial Performance and Market Share Analytics 307
11.17 Henan Carve Electronic Technology 308
11.17.1 Enterprise Overview and Global Footprint 308
11.17.2 SWOT Analysis 309
11.17.3 Connector Financial Performance and Market Share Analytics 310
11.18 Zhejiang Yonggui Electric Equipment Co. Ltd 311
11.18.1 Enterprise Overview and Global Footprint 311
11.18.2 SWOT Analysis 312
11.18.3 Connector Financial Performance and Market Share Analytics 313
11.19 Shenzhen Chuangyitong Technology 314
11.19.1 Enterprise Overview and Global Footprint 314
11.19.2 SWOT Analysis 315
11.19.3 Connector Financial Performance and Market Share Analytics 316
11.20 Shenzhen Deren Electronic 317
11.20.1 Enterprise Overview and Global Footprint 317
11.20.2 SWOT Analysis 318
11.20.3 Connector Financial Performance and Market Share Analytics 319
11.21 Shenzhen Everwin Precision Technology 320
11.21.1 Enterprise Overview and Global Footprint 320
11.21.2 SWOT Analysis 321
11.21.3 Connector Financial Performance and Market Share Analytics 322
11.22 Weifang Genius Electronics 323
11.22.1 Enterprise Overview and Global Footprint 323
11.22.2 SWOT Analysis 324
11.22.3 Connector Financial Performance and Market Share Analytics 325
11.23 CviLux 326
11.23.1 Enterprise Overview and Global Footprint 326
11.23.2 SWOT Analysis 327
11.23.3 Connector Financial Performance and Market Share Analytics 328
11.24 Electric Connector Technology Co. Ltd. (ECT) 329
11.24.1 Enterprise Overview and Global Footprint 329
11.24.2 SWOT Analysis 330
11.24.3 Connector Financial Performance and Market Share Analytics 331
11.25 WCON ELECTRONICS 332
11.25.1 Enterprise Overview and Global Footprint 332
11.25.2 SWOT Analysis 333
11.25.3 Connector Financial Performance and Market Share Analytics 334
11.26 Shenglan Technology Co. Ltd. 335
11.26.1 Enterprise Overview and Global Footprint 335
11.26.2 SWOT Analysis 335
11.26.3 Connector Financial Performance and Market Share Analytics 335
11.27 Suzhou Recodeal Interconnect System Co. Ltd 336
11.27.1 Enterprise Overview and Global Footprint 336
11.27.2 SWOT Analysis 336
11.27.3 Connector Financial Performance and Market Share Analytics 336
11.28 Chant Sincere 337
11.28.1 Enterprise Overview and Global Footprint 337
11.28.2 SWOT Analysis 337
11.28.3 Connector Financial Performance and Market Share Analytics 337
11.29 Guizhou Space Appliance Co. LTD 338
11.29.1 Enterprise Overview and Global Footprint 338
11.29.2 SWOT Analysis 338
11.29.3 Connector Financial Performance and Market Share Analytics 338
11.30 Wieson Technologies 339
11.30.1 Enterprise Overview and Global Footprint 339
11.30.2 SWOT Analysis 339
11.30.3 Connector Financial Performance and Market Share Analytics 339
11.31 Hongrida Technology 340
11.31.1 Enterprise Overview and Global Footprint 340
11.31.2 SWOT Analysis 340
11.31.3 Connector Financial Performance and Market Share Analytics 340
11.32 BizLink 341
11.32.1 Enterprise Overview and Global Footprint 341
11.32.2 SWOT Analysis 341
11.32.3 Connector Financial Performance and Market Share Analytics 341
11.33 Cheng Uei Precision Industry Co. Ltd. (Foxlink) 342
11.33.1 Enterprise Overview and Global Footprint 342
11.33.2 SWOT Analysis 342
11.33.3 Connector Financial Performance and Market Share Analytics 342
11.34 JPC Connectivity 343
11.34.1 Enterprise Overview and Global Footprint 343
11.34.2 SWOT Analysis 343
11.34.3 Connector Financial Performance and Market Share Analytics 343
11.35 Alltop Technology 344
11.35.1 Enterprise Overview and Global Footprint 344
11.35.2 SWOT Analysis 344
11.35.3 Connector Financial Performance and Market Share Analytics 344
11.36 SpeedTech 345
11.36.1 Enterprise Overview and Global Footprint 345
11.36.2 SWOT Analysis 345
11.36.3 Connector Financial Performance and Market Share Analytics 345
11.37 U. D. ELECTRONIC CORP. 346
11.37.1 Enterprise Overview and Global Footprint 346
11.37.2 SWOT Analysis 346
11.37.3 Connector Financial Performance and Market Share Analytics 346
11.38 Bellwether 347
11.38.1 Enterprise Overview and Global Footprint 347
11.38.2 SWOT Analysis 347
11.38.3 Connector Financial Performance and Market Share Analytics 347
Table 2 Key Connector Industry Raw Materials: Price Elasticity and Sourcing Exposure 19
Table 3 Global Connector Market Value by Transmission Medium (2021-2031) 43
Table 4 Global Electrical Connector Market by Configuration Type (2021-2031) 45
Table 5 Global RF and Coaxial Connector Market by Frequency Tier (2021-2031) 50
Table 6 Global Fiber-Optic Connector Market by Polish and Channel Density (2021-2031) 55
Table 7 Global Connector Market Revenue by Downstream Application (2021-2031) 58
Table 8 Automotive Connector Consumption by Sub-Application (2021-2031) 60
Table 9 Consumer Electronics Connector Consumption by Device Type (2021-2031) 64
Table 10 Telecom & Datacom Connector Market by Deployment Architecture (2021-2031) 69
Table 11 Global Connector Market Value by Region (2021-2031) 87
Table 12 North America Connector Market Revenue by Country (2021-2031) 87
Table 13 Europe Connector Market Revenue by Country (2021-2031) 98
Table 14 Asia-Pacific Connector Market Revenue by Country (2021-2031) 112
Table 15 Global Top 10 Connector Vendors Revenue and Market Concentration Ratios (2021-2026) 128
Table 16 Amphenol Connector Revenue, Cost and Gross Margin (2021-2026) 145
Table 17 TE Connectivity Connector Revenue, Cost and Gross Margin (2021-2026) 148
Table 18 Molex Connector Revenue, Cost and Gross Margin (2021-2026) 151
Table 19 Aptiv Connector Revenue, Cost and Gross Margin (2021-2026) 154
Table 20 Glenair Connector Revenue, Cost and Gross Margin (2021-2026) 157
Table 21 Samtec Connector Revenue, Cost and Gross Margin (2021-2026) 160
Table 22 Belden Inc. Connector Revenue, Cost and Gross Margin (2021-2026) 163
Table 23 Corning Connector Revenue, Cost and Gross Margin (2021-2026) 166
Table 24 Radiall Connector Revenue, Cost and Gross Margin (2021-2026) 169
Table 25 HUBER+SUHNER Connector Revenue, Cost and Gross Margin (2021-2026) 172
Table 26 Sensata Technologies Connector Revenue, Cost and Gross Margin (2021-2026) 175
Table 27 Rosenberger Connector Revenue, Cost and Gross Margin (2021-2026) 178
Table 28 Phoenix Contact Connector Revenue, Cost and Gross Margin (2021-2026) 181
Table 29 Cembre Connector Revenue, Cost and Gross Margin (2021-2026) 184
Table 30 HARTING Technology Group Connector Revenue, Cost and Gross Margin (2021-2026) 187
Table 31 Weidmüller Connector Revenue, Cost and Gross Margin (2021-2026) 190
Table 32 Pulse Electronics Connector Revenue, Cost and Gross Margin (2021-2026) 193
Table 33 Hubbell Incorporated Connector Revenue, Cost and Gross Margin (2021-2026) 196
Table 34 Hirose Electric Connector Revenue, Cost and Gross Margin (2021-2026) 199
Table 35 YAZAKI Corporation Connector Revenue, Cost and Gross Margin (2021-2026) 202
Table 36 IRISO Electronics Connector Revenue, Cost and Gross Margin (2021-2026) 205
Table 37 Japan Aviation Electronics Industry (JAE) Connector Revenue, Cost and Gross Margin (2021-2026) 208
Table 38 Korea Electric Terminal (KET) Connector Revenue, Cost and Gross Margin (2021-2026) 211
Table 39 KEL Corporation Connector Revenue, Cost and Gross Margin (2021-2026) 214
Table 40 Yokowo Co. Ltd. Connector Revenue, Cost and Gross Margin (2021-2026) 217
Table 41 Hosiden Corporation Connector Revenue, Cost and Gross Margin (2021-2026) 220
Table 42 SMK Corp. Connector Revenue, Cost and Gross Margin (2021-2026) 223
Table 43 Omron Corporation Connector Revenue, Cost and Gross Margin (2021-2026) 226
Table 44 Panasonic Connector Revenue, Cost and Gross Margin (2021-2026) 229
Table 45 MinebeaMitsumi Connector Revenue, Cost and Gross Margin (2021-2026) 232
Table 46 Murata Connector Revenue, Cost and Gross Margin (2021-2026) 235
Table 47 I-PEX Inc. Connector Revenue, Cost and Gross Margin (2021-2026) 238
Table 48 Sumitomo Electric Connector Revenue, Cost and Gross Margin (2021-2026) 241
Table 49 J.S.T. Mfg. Co. Ltd. Connector Revenue, Cost and Gross Margin (2021-2026) 244
Table 50 CNPLUS Connector Revenue, Cost and Gross Margin (2021-2026) 247
Table 51 JNTC Connector Revenue, Cost and Gross Margin (2021-2026) 250
Table 52 KISTRON Connector Revenue, Cost and Gross Margin (2021-2026) 253
Table 53 Shinhwa Contech Connector Revenue, Cost and Gross Margin (2021-2026) 256
Table 54 UJU Electronics Connector Revenue, Cost and Gross Margin (2021-2026) 259
Table 55 Foxconn Interconnect Technology Limited (FIT) Connector Revenue, Cost and Gross Margin (2021-2026) 262
Table 56 Luxshare Connector Revenue, Cost and Gross Margin (2021-2026) 265
Table 57 DongGuan DingTong Precision Metal Co. Ltd Connector Revenue, Cost and Gross Margin (2021-2026) 268
Table 58 Jonhon Optronic Technology Connector Revenue, Cost and Gross Margin (2021-2026) 271
Table 59 SINBON Electronics Connector Revenue, Cost and Gross Margin (2021-2026) 274
Table 60 Singatron Group Connector Revenue, Cost and Gross Margin (2021-2026) 277
Table 61 Tai Twun Enterprise Connector Revenue, Cost and Gross Margin (2021-2026) 280
Table 62 CWB Automotive Electronics Co. Ltd Connector Revenue, Cost and Gross Margin (2021-2026) 283
Table 63 Lintes Technology Connector Revenue, Cost and Gross Margin (2021-2026) 286
Table 64 LOTES Connector Revenue, Cost and Gross Margin (2021-2026) 289
Table 65 Sichuan Huafeng Technology Connector Revenue, Cost and Gross Margin (2021-2026) 292
Table 66 Shenzhen Uniconn Technology Connector Revenue, Cost and Gross Margin (2021-2026) 295
Table 67 YD Electronic Technology Connector Revenue, Cost and Gross Margin (2021-2026) 298
Table 68 ACES Electronics Connector Revenue, Cost and Gross Margin (2021-2026) 301
Table 69 Pan-International Connector Revenue, Cost and Gross Margin (2021-2026) 304
Table 70 Wenzhou Yihua Connector Co. Ltd. Connector Revenue, Cost and Gross Margin (2021-2026) 307
Table 71 Henan Carve Electronic Technology Connector Revenue, Cost and Gross Margin (2021-2026) 310
Table 72 Zhejiang Yonggui Electric Equipment Co. Ltd Connector Revenue, Cost and Gross Margin (2021-2026) 313
Table 73 Shenzhen Chuangyitong Technology Connector Revenue, Cost and Gross Margin (2021-2026) 316
Table 74 Shenzhen Deren Electronic Connector Revenue, Cost and Gross Margin (2021-2026) 319
Table 75 Shenzhen Everwin Precision Technology Connector Revenue, Cost and Gross Margin (2021-2026) 322
Table 76 Weifang Genius Electronics Connector Revenue, Cost and Gross Margin (2021-2026) 325
Table 77 CviLux Connector Revenue, Cost and Gross Margin (2021-2026) 328
Table 78 Electric Connector Technology Co. Ltd. (ECT) Connector Revenue, Cost and Gross Margin (2021-2026) 331
Table 79 WCON ELECTRONICS Connector Revenue, Cost and Gross Margin (2021-2026) 334
Table 80 Shenglan Technology Co. Ltd. Connector Revenue, Cost and Gross Margin (2021-2026) 335
Table 81 Suzhou Recodeal Interconnect System Co. Ltd Connector Revenue, Cost and Gross Margin (2021-2026) 336
Table 82 Chant Sincere Connector Revenue, Cost and Gross Margin (2021-2026) 337
Table 83 Guizhou Space Appliance Co. LTD Connector Revenue, Cost and Gross Margin (2021-2026) 338
Table 84 Wieson Technologies Connector Revenue, Cost and Gross Margin (2021-2026) 339
Table 85 Hongrida Technology Connector Revenue, Cost and Gross Margin (2021-2026) 340
Table 86 BizLink Connector Revenue, Cost and Gross Margin (2021-2026) 341
Table 87 Cheng Uei Precision Industry Co. Ltd. (Foxlink) Connector Revenue, Cost and Gross Margin (2021-2026) 342
Table 88 JPC Connectivity Connector Revenue, Cost and Gross Margin (2021-2026) 343
Table 89 Alltop Technology Connector Revenue, Cost and Gross Margin (2021-2026) 344
Table 90 SpeedTech Connector Revenue, Cost and Gross Margin (2021-2026) 345
Table 91 U. D. ELECTRONIC CORP. Connector Revenue, Cost and Gross Margin (2021-2026) 346
Table 92 Bellwether Connector Revenue, Cost and Gross Margin (2021-2026) 347
Figure 1 Global Connector Market Valuation Trajectory (2021-2031) 8
Figure 2 Interconnect End-to-End Value Chain Margin Distribution 17
Figure 3 Global Connector Value Share by Transmission Medium (2026 vs. 2031) 44
Figure 4 Downstream Application Market Share Shifts (2021-2031) 59
Figure 5 Regional Demand Share Distribution for Connectors (2026) 86
Figure 6 Amphenol Connector Market Share (2021-2026) 145
Figure 7 TE Connectivity Connector Market Share (2021-2026) 148
Figure 8 Molex Connector Market Share (2021-2026) 151
Figure 9 Aptiv Connector Market Share (2021-2026) 154
Figure 10 Glenair Connector Market Share (2021-2026) 157
Figure 11 Samtec Connector Market Share (2021-2026) 160
Figure 12 Belden Inc. Connector Market Share (2021-2026) 163
Figure 13 Corning Connector Market Share (2021-2026) 166
Figure 14 Radiall Connector Market Share (2021-2026) 169
Figure 15 HUBER+SUHNER Connector Market Share (2021-2026) 172
Figure 16 Sensata Technologies Connector Market Share (2021-2026) 175
Figure 17 Rosenberger Connector Market Share (2021-2026) 178
Figure 18 Phoenix Contact Connector Market Share (2021-2026) 181
Figure 19 Cembre Connector Market Share (2021-2026) 184
Figure 20 HARTING Technology Group Connector Market Share (2021-2026) 187
Figure 21 Weidmüller Connector Market Share (2021-2026) 190
Figure 22 Pulse Electronics Connector Market Share (2021-2026) 193
Figure 23 Hubbell Incorporated Connector Market Share (2021-2026) 196
Figure 24 Hirose Electric Connector Market Share (2021-2026) 199
Figure 25 YAZAKI Corporation Connector Market Share (2021-2026) 202
Figure 26 IRISO Electronics Connector Market Share (2021-2026) 205
Figure 27 Japan Aviation Electronics Industry (JAE) Connector Market Share (2021-2026) 208
Figure 28 Korea Electric Terminal (KET) Connector Market Share (2021-2026) 211
Figure 29 KEL Corporation Connector Market Share (2021-2026) 214
Figure 30 Yokowo Co. Ltd. Connector Market Share (2021-2026) 217
Figure 31 Hosiden Corporation Connector Market Share (2021-2026) 220
Figure 32 SMK Corp. Connector Market Share (2021-2026) 223
Figure 33 Omron Corporation Connector Market Share (2021-2026) 226
Figure 34 Panasonic Connector Market Share (2021-2026) 229
Figure 35 MinebeaMitsumi Connector Market Share (2021-2026) 232
Figure 36 Murata Connector Market Share (2021-2026) 235
Figure 37 I-PEX Inc. Connector Market Share (2021-2026) 238
Figure 38 Sumitomo Electric Connector Market Share (2021-2026) 241
Figure 39 J.S.T. Mfg. Co. Ltd. Connector Market Share (2021-2026) 244
Figure 40 CNPLUS Connector Market Share (2021-2026) 247
Figure 41 JNTC Connector Market Share (2021-2026) 250
Figure 42 KISTRON Connector Market Share (2021-2026) 253
Figure 43 Shinhwa Contech Connector Market Share (2021-2026) 256
Figure 44 UJU Electronics Connector Market Share (2021-2026) 259
Figure 45 Foxconn Interconnect Technology Limited (FIT) Connector Market Share (2021-2026) 262
Figure 46 Luxshare Connector Market Share (2021-2026) 265
Figure 47 DongGuan DingTong Precision Metal Co. Ltd Connector Market Share (2021-2026) 268
Figure 48 Jonhon Optronic Technology Connector Market Share (2021-2026) 271
Figure 49 SINBON Electronics Connector Market Share (2021-2026) 274
Figure 50 Singatron Group Connector Market Share (2021-2026) 277
Figure 51 Tai Twun Enterprise Connector Market Share (2021-2026) 280
Figure 52 CWB Automotive Electronics Co. Ltd Connector Market Share (2021-2026) 283
Figure 53 Lintes Technology Connector Market Share (2021-2026) 286
Figure 54 LOTES Connector Market Share (2021-2026) 289
Figure 55 Sichuan Huafeng Technology Connector Market Share (2021-2026) 292
Figure 56 Shenzhen Uniconn Technology Connector Market Share (2021-2026) 295
Figure 57 YD Electronic Technology Connector Market Share (2021-2026) 298
Figure 58 ACES Electronics Connector Market Share (2021-2026) 301
Figure 59 Pan-International Connector Market Share (2021-2026) 304
Figure 60 Wenzhou Yihua Connector Co. Ltd. Connector Market Share (2021-2026) 307
Figure 61 Henan Carve Electronic Technology Connector Market Share (2021-2026) 310
Figure 62 Zhejiang Yonggui Electric Equipment Co. Ltd Connector Market Share (2021-2026) 313
Figure 63 Shenzhen Chuangyitong Technology Connector Market Share (2021-2026) 316
Figure 64 Shenzhen Deren Electronic Connector Market Share (2021-2026) 319
Figure 65 Shenzhen Everwin Precision Technology Connector Market Share (2021-2026) 322
Figure 66 Weifang Genius Electronics Connector Market Share (2021-2026) 325
Figure 67 CviLux Connector Market Share (2021-2026) 328
Figure 68 Electric Connector Technology Co. Ltd. (ECT) Connector Market Share (2021-2026) 331
Figure 69 WCON ELECTRONICS Connector Market Share (2021-2026) 334
Figure 70 Shenglan Technology Co. Ltd. Connector Market Share (2021-2026) 335
Figure 71 Suzhou Recodeal Interconnect System Co. Ltd Connector Market Share (2021-2026) 336
Figure 72 Chant Sincere Connector Market Share (2021-2026) 337
Figure 73 Guizhou Space Appliance Co. LTD Connector Market Share (2021-2026) 338
Figure 74 Wieson Technologies Connector Market Share (2021-2026) 339
Figure 75 Hongrida Technology Connector Market Share (2021-2026) 340
Figure 76 BizLink Connector Market Share (2021-2026) 341
Figure 77 Cheng Uei Precision Industry Co. Ltd. (Foxlink) Connector Market Share (2021-2026) 342
Figure 78 JPC Connectivity Connector Market Share (2021-2026) 343
Figure 79 Alltop Technology Connector Market Share (2021-2026) 344
Figure 80 SpeedTech Connector Market Share (2021-2026) 345
Figure 81 U. D. ELECTRONIC CORP. Connector Market Share (2021-2026) 346
Figure 82 Bellwether Connector Market Share (2021-2026) 347
Research Methodology
- Market Estimated Methodology:
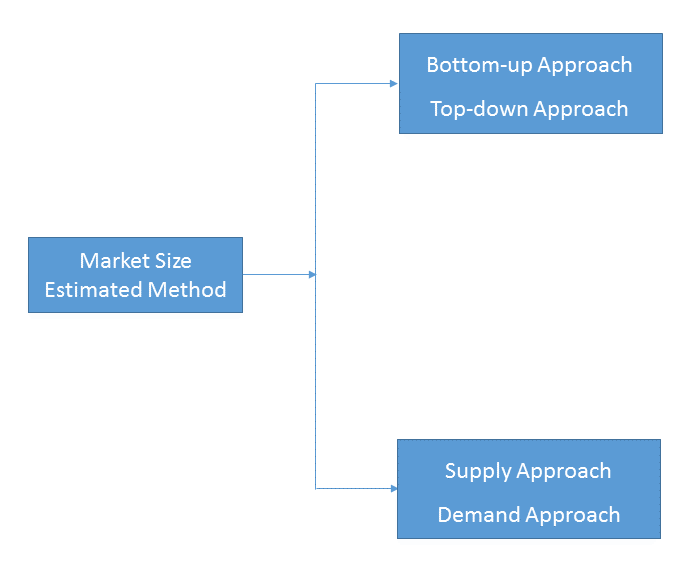
Bottom-up & top-down approach, supply & demand approach are the most important method which is used by HDIN Research to estimate the market size.
1)Top-down & Bottom-up Approach
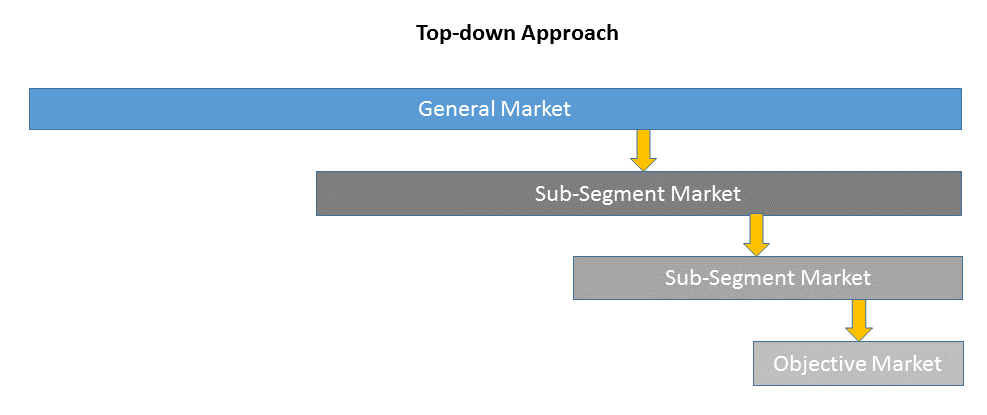
Top-down approach uses a general market size figure and determines the percentage that the objective market represents.
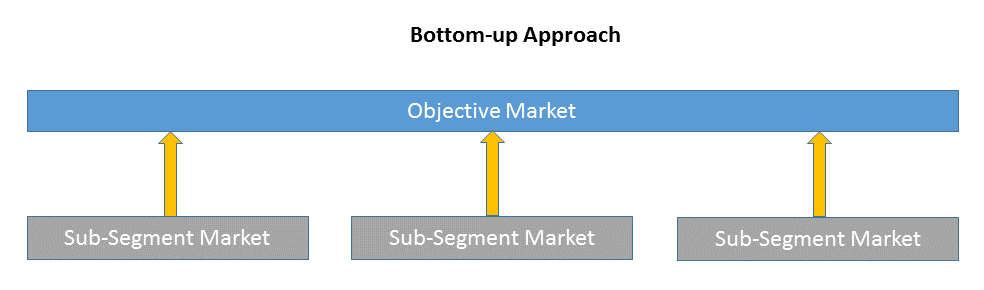
Bottom-up approach size the objective market by collecting the sub-segment information.
2)Supply & Demand Approach
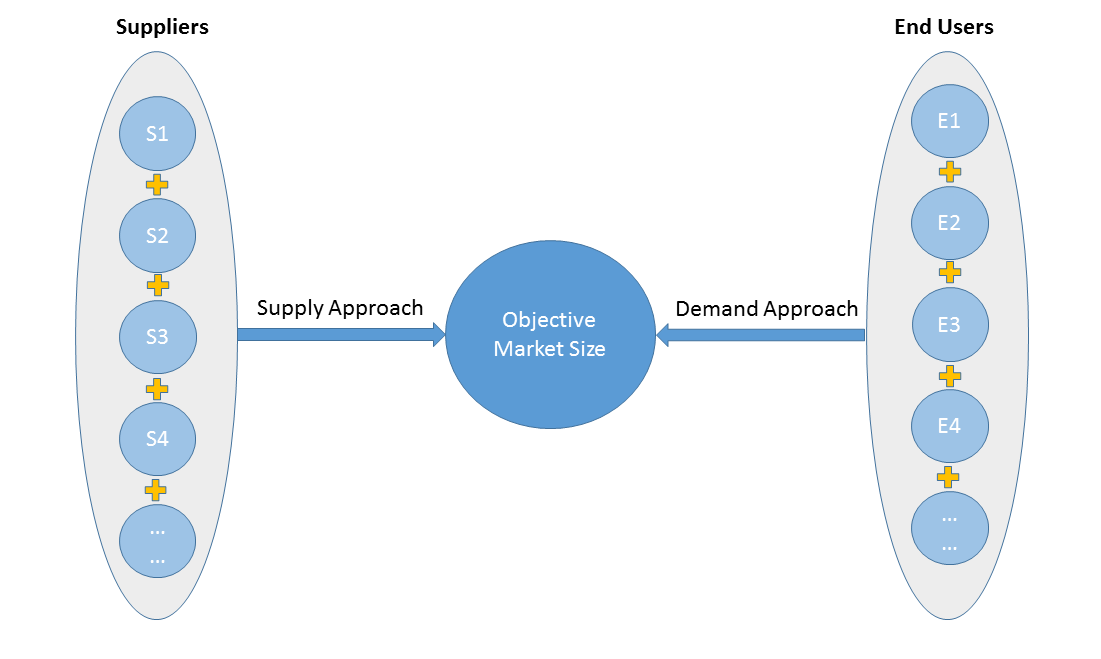
Supply approach is based on assessments of the size of each competitor supplying the objective market.
Demand approach combine end-user data within a market to estimate the objective market size. It is sometimes referred to as bottom-up approach.
- Forecasting Methodology
- Numerous factors impacting the market trend are considered for forecast model:
- New technology and application in the future;
- New project planned/under contraction;
- Global and regional underlying economic growth;
- Threatens of substitute products;
- Industry expert opinion;
- Policy and Society implication.
- Analysis Tools
1)PEST Analysis
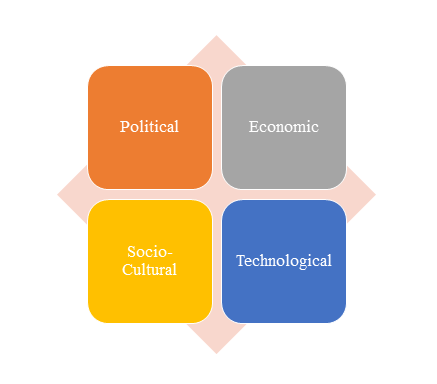
PEST Analysis is a simple and widely used tool that helps our client analyze the Political, Economic, Socio-Cultural, and Technological changes in their business environment.
- Benefits of a PEST analysis:
- It helps you to spot business opportunities, and it gives you advanced warning of significant threats.
- It reveals the direction of change within your business environment. This helps you shape what you’re doing, so that you work with change, rather than against it.
- It helps you avoid starting projects that are likely to fail, for reasons beyond your control.
- It can help you break free of unconscious assumptions when you enter a new country, region, or market; because it helps you develop an objective view of this new environment.
2)Porter’s Five Force Model Analysis
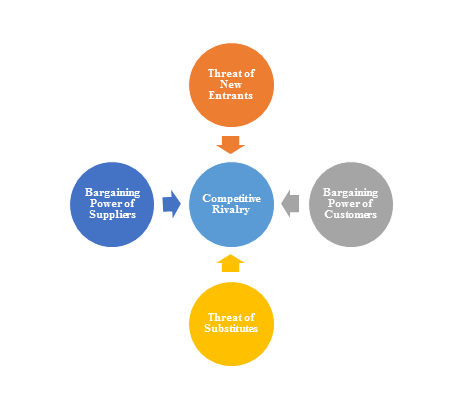
The Porter’s Five Force Model is a tool that can be used to analyze the opportunities and overall competitive advantage. The five forces that can assist in determining the competitive intensity and potential attractiveness within a specific area.
- Threat of New Entrants: Profitable industries that yield high returns will attract new firms.
- Threat of Substitutes: A substitute product uses a different technology to try to solve the same economic need.
- Bargaining Power of Customers: the ability of customers to put the firm under pressure, which also affects the customer's sensitivity to price changes.
- Bargaining Power of Suppliers: Suppliers of raw materials, components, labor, and services (such as expertise) to the firm can be a source of power over the firm when there are few substitutes.
- Competitive Rivalry: For most industries the intensity of competitive rivalry is the major determinant of the competitiveness of the industry.
3)Value Chain Analysis
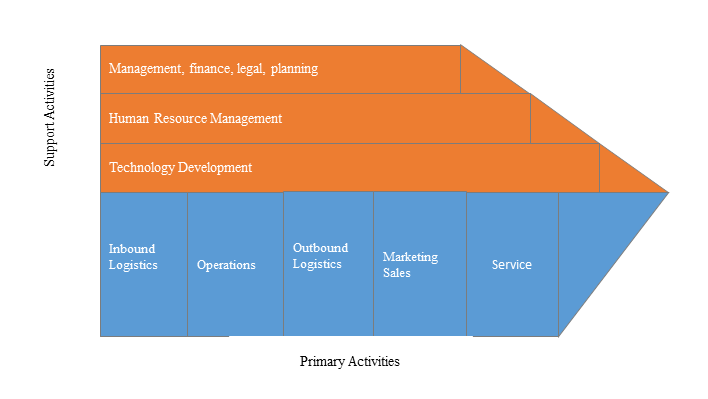
Value chain analysis is a tool to identify activities, within and around the firm and relating these activities to an assessment of competitive strength. Value chain can be analyzed by primary activities and supportive activities. Primary activities include: inbound logistics, operations, outbound logistics, marketing & sales, service. Support activities include: technology development, human resource management, management, finance, legal, planning.
4)SWOT Analysis
SWOT analysis is a tool used to evaluate a company's competitive position by identifying its strengths, weaknesses, opportunities and threats. The strengths and weakness is the inner factor; the opportunities and threats are the external factor. By analyzing the inner and external factors, the analysis can provide the detail information of the position of a player and the characteristics of the industry.
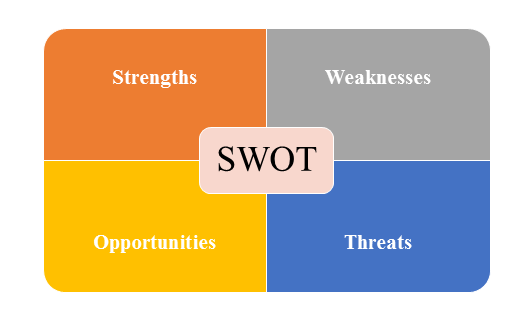
- Strengths describe what the player excels at and separates it from the competition
- Weaknesses stop the player from performing at its optimum level.
- Opportunities refer to favorable external factors that the player can use to give it a competitive advantage.
- Threats refer to factors that have the potential to harm the player.
- Data Sources
| Primary Sources | Secondary Sources |
|---|---|
| Face to face/Phone Interviews with market participants, such as: Manufactures; Distributors; End-users; Experts. Online Survey |
Government/International Organization Data: Annual Report/Presentation/Fact Book Internet Source Information Industry Association Data Free/Purchased Database Market Research Report Book/Journal/News |