Cosmetics & Fragrances Packaging Market: 2026-2031 Strategic Outlook
- Single User License (1 Users) $ 3,500
- Team License (2~5 Users) $ 4,500
- Corporate License (>5 Users) $ 5,500
The global cosmetics and fragrances packaging market size is valued between 28 billion USD and 38 billion USD in 2026 with a compound annual growth rate (CAGR) of 4% to 5% through 2031. Decarbonization mandates, legislative enforcement around post-consumer recycled (PCR) resin adoption, and the harmonization of medical-grade cleanroom standards across beauty formats are transforming the supply landscape. Brand owners are actively rationalizing their vendor rosters, prioritizing packaging converters with integrated technical tooling, certified mono-material platforms, and agile localized supply footprints over simple component fabricators.
Structural Market Shifts & Analytical Theses
● Bifurcation between High-Barrier Dispensing Systems and Commoditized Primary Containers
The market displays a stark margin divide across technical tiers. At the upper tier, specialized dispensing technologies—such as metal-free airless pumps, micro-dose fragrance actuators (0.05 cc to 0.15 cc), multi-chamber delivery mechanisms, and pouch-in-bottle barrier structures—command gross margins between 25% and 35%. These systems protect active cosmetic ingredients from photo-oxidation and atmospheric degradation, creating high switching costs for brand owners due to extensive compatibility testing cycles lasting 12 to 24 months.
Conversely, standard polyolefin bottles, flexible squeeze tubes lacking active barriers, and open-mouth injection-molded containers occupy an intensely price-sensitive layer. This commoditized segment is burdened by persistent regional overcapacity, low capital barriers to entry, and vulnerability to petrochemical resin price swings. Converters lacking proprietary mechanical designs or advanced finishing technologies are forced into defensive volume-preservation strategies, where operating margins hover in single digits.
● The Merging Frontier of Cosmetics and Pharmaceuticals
The boundary between topical dermatological skincare and pharmaceutical therapeutics is dissolving rapidly. Driven by the mainstreaming of medical-grade aesthetics, topical retinoids, stabilized L-ascorbic acid, and subcutaneous aesthetic formulations, beauty brands are borrowing primary packaging formats directly from the medical device and parenteral drug industries.
Packaging converters are expanding capacity in Class 7 and Class 8 cleanroom production environments, deploying automated vision inspection systems, and converting Type I borosilicate glass into precision ampoules, cartridges, and pre-fillable syringes. In parallel, de-sulfurization processes on glass surfaces are utilized to eliminate alkali leaching when storing complex cosmetic peptide formulations. This operational convergence unlocks sustained pricing premiums for converters capable of navigating both ISO 15378 medical packaging quality standards and dynamic aesthetic beauty requirements.
● Decarbonization, Mono-Material Circularity, and Lightweighting as Core Entry Barriers
Regulatory directives and institutional ESG targets have repositioned circular design from an optional marketing attribute to a non-negotiable procurement standard. Technical priorities have pivoted toward single-polymer packaging architectures. Mechanical dispensing engines are replacing legacy multi-material structures—which traditionally incorporated metal coil springs, POM poppets, and elastomeric valves—with all-polyethylene (PE) or all-polypropylene (PP) spring designs that pass cleanly through standard sorting and mechanical recycling streams.
Simultaneously, tube converters are deploying barrier laminates that substitute heavy aluminum foils with thin ethylene vinyl alcohol (EVOH) co-extrusions, securing APR (Association of Plastic Recyclers) and RecyClass Class A compliance without sacrificing shelf-life performance. In luxury perfumery, high-cullet formulations containing up to 40% to 60% post-consumer recycled glass are becoming industry benchmarks, paired with chemical lightweighting to reduce molten glass consumption while preserving the acoustic "clink" and optical mass demanded by prestige luxury brands.
Product Scope and Technical Classification
1. By Material Matrix
● Glass Packaging
Moulded glass, manufactured through blow-and-blow or press-and-blow processes, remains the foundational material for luxury fragrance flacons and prestige skincare creams. It offers complete chemical inertness, infinite recyclability, zero formulation migration, and distinct optical mass. Operational developments center on high-flint formulations with elevated clarity and feeder-colored glass variants.
Tubular glass, converted from precision-drawn Type I neutral borosilicate glass tubes, serves clinical beauty, unit-dose serums, and medical aesthetic applications. It provides high thermal shock resistance and hydrolytic barrier properties, completely mitigating the risk of product-container interactions in unpreserved, sterile skincare solutions.
● Rigid & Flexible Plastics
Rigid configurations rely on polymethyl methacrylate (PMMA / Acrylic) for optical glass imitation, shatter resistance, and heavy-walled cosmetic jars; polyethylene terephthalate (PET and PETG) for clear aesthetic bottles; alongside polypropylene (PP) and high-density polyethylene (HDPE) for functional closures, airless chassis, and durable containers.
The flexible substrate space encompasses multi-layer co-extruded films and extruded tubes. Industry engineering efforts are directed toward replacing mixed-material laminates with mono-material PE and PP barrier films, incorporating post-consumer recycled resin levels between 30% and 70% in non-contact container walls, and applying thin-gauge EVOH barrier layers to prevent volatile essential oil migration.
● Metal Packaging
Dominated by high-purity aluminum alloys processed via impact extrusion to manufacture continuous monobloc aerosol cans, recloseable bottles, and shaped containers. This format controls personal care categories requiring pressurized or aerosolized delivery, including dry shampoos, body sprays, and sun mists. Aluminum provides an absolute barrier to light, gases, and moisture, paired with exceptionally high recycling rates. In secondary components, stamped aluminum and anodized metal collars, weights, and outer sheaths remain the preferred substrates for luxury lipstick barrels and fine fragrance caps.
● Paperboard & Fiber Packaging
Encompasses virgin bleached sulfate board, folding boxboard (FBB), and uncoated recycled paperboard (URB) configured into secondary folding cartons, multi-piece rigid presentation boxes, and high-strength display assemblies. Technical evolution focuses on plastic-free barrier coatings, mineral pigment lacquers, embossed structural security features, and molded pulp interior inserts designed to displace thermoformed plastic trays in fragrance unboxing sets.
2. By Packaging Format
● Bottles & Flacons
Engineered containers with narrow necks, ranging from 5 ml travel sprayers to 1,000 ml salon formats. In prestige perfumery, flacons require thick glass bases, invisible internal walls, perfectly distributed wall thicknesses, and high neck-finish precision to support crimp-on or snap-on fine mist pumps. In functional personal care, bottles integrate ergonomic finger grips, e-commerce leak-proof neck finishes, and post-consumer polyolefin blends.
● Jars & Pots
Wide-mouth vessels tailored for high-viscosity formulations such as rich moisturizers, sleep masks, and hair waxes. Innovation centers on transitioning from open-mouth designs to airless, center-dispensing jars. These assemblies deploy internal pistons, flexible elastomeric diaphragms, or push-button actuators that seal formulations away from ambient oxidation and bacterial transfer during consumer use. Premium implementations employ double-wall architectures, using clear PMMA or heavy-gauge PET outers paired with removable, recyclable PP inner pods.
● Tubes (Laminated & Extruded)
Collapsible cylindrical structures that deliver controlled dosing under manual pressure. Divided into:
- Plastic Barrier Laminates (PBL): Multi-layer webs with integrated EVOH barriers, offering full-surface photographic flexographic printing and all-polyolefin recyclability.
- Aluminum Barrier Laminates (ABL): High-barrier substrates featuring a micro-thin aluminum foil core, standard for aggressive active formulations, professional hair colorants, and therapeutic ointments.
- Extruded Plastic Tubes: Seamless sleeves produced via continuous polymer extrusion, preferred in premium cosmetic lines for soft-touch exterior finishes, continuous 360-degree graphics, and multi-layer co-extruded barrier options.
● Sticks & Pens
Mechanical packaging employing rotary screw actuators, push-up slides, or click-metering feeds. These formats are purpose-built for solid or semi-solid sticks, including lipsticks, deodorants, sunscreen balms, and spot-treatment correctors. Advanced variations feature hermetic sealing chambers to protect volatile solvents from drying out, pin-less all-plastic mechanisms to enhance mechanical recycling sorting efficiency, and replaceable inner cartridges for secondary refilling.
● Compacts & Palettes
Hinged or sliding shallow cases containing internal wells for dry-pressed powders, baked powders, hot-poured foundations, or liquid-soaked sponge cushions. Modern designs prioritize airtight sealing gaskets and ultrasonic-welded seals to preserve volatile foundation solvents. Mechanical designs are increasingly abandoning traditional metal hinge pins and magnetic closures, replacing them with mono-material mechanical living hinges or all-polyolefin snap locks.
Downstream Application Sectors & Formulation Dynamics
● Color Cosmetics
Formulations in this sector are characterized by high pigment loadings, volatile solvent bases (such as isododecane), and varied fluid rheologies. The primary packaging requirements center on extreme structural dimensional tolerances and mechanical durability. Packaging components, such as liquid lip gloss vials, mascara wands, and airtight foundation pumps, must ensure complete chemical compatibility with volatile silicones and organic esters.
Applicators represent a critical competitive battleground: custom-molded elastomeric mascara brushes and flock-coated wand tips dictate physical application performance. Furthermore, structural design in this segment must project high aesthetic quality through decorative vacuum metallization, physical vapor deposition (PVD), and tactile weight balancing.
● Skin Care
Driven by clean beauty initiatives, reduced preservative levels, and active dermatological ingredients (pure retinol, ascorbic acid, resveratrol, and encapsulated peptides), skincare packaging must deliver absolute formulation defense. The primary packaging requirement is the complete mitigation of oxygen permeation, moisture loss, and ultraviolet degradation.
Converters utilize airless dispensing bottles, multi-layer co-extruded EVOH tubes, and opaque amber or coated glass to shield active compounds. Skincare packaging also integrates direct-to-skin applicators, such as ceramic cooling tips, surgical-grade stainless steel roll-on spheres, and micro-dropper pipettes to elevate consumer application routines.
● Fragrances & Perfumery
Fragrance solutions are ethanol-based systems containing delicate aromatic compounds, essential oils, and synthetic aroma chemicals. Chemical inertness is paramount; packaging must withstand aggressive alcohol solvents without plasticizer migration, structural stress cracking, or discoloration. The category is dominated by thick-bottomed moulded glass flacons engineered with optical clarity.
Dispensing mechanics require fine-mist atomizers engineered to produce specific droplet distribution spectrums (typically 30 to 50 microns) for optimal olfactory diffusion. Secondary aesthetic embellishments, such as heavy alloy zamak caps, multi-layered silk-screening, internal bottle coating, and precision laser cutting, define brand prestige.
● Hair Care & Styling
This sector is marked by high-volume container formats, moisture-dense operating environments (showers and salons), and aggressive surfactant or oxidant formulations. Functional packaging encompasses large-capacity HDPE and PP rigid bottles (250 ml to 1,000 ml) paired with high-output dispensing pumps (2 cc to 4 cc dosing volumes), impact-extruded aluminum aerosol cans for styling mousses and dry shampoos, and flexible barrier tubes for deep conditioning treatments. Packaging solutions must deliver robust drop impact resistance, water ingress prevention around the pump actuator, and smooth evacuation of high-viscosity emulsions.
● Personal Care & Toiletries
Covering daily hygiene products, including body washes, liquid hand soaps, deodorants, antiperspirants, and oral care. This application represents the highest physical unit volume in the packaging industry. The operational focus centers squarely on structural cost efficiency, high-speed automated line filling, structural container lightweighting, and maximum integration of post-consumer recycled polyolefins. Standard dispensing architectures include wide-orifice flip-top closures, continuous aerosol valves, and cost-optimized, metal-free lotion pumps.
● Medical-Grade Aesthetics & Subcutaneous Cosmetics
This rapidly growing intersection represents the most technically rigorous sector in beauty packaging. Encompassing cross-linked hyaluronic acid dermal fillers, botulinum toxins, bio-revitalizing mesotherapy solutions, and chemical peel acids. Requirements transition completely from standard cosmetic specifications into strict pharmaceutical regulatory oversight.
Packaging formats include pre-fillable Type I borosilicate glass syringes, siliconized elastomeric plunger stoppers, cyclic olefin copolymer (COC) polymer barrels, sterile glass ampoules, and de-sulfurized tubular glass vials. Manufacturing must occur in verified Class 5 to Class 8 ISO cleanrooms to eliminate particulate contamination, ensure pyrogen-free conditions, and maintain long-term sterility.
Value Chain Architecture & Bottleneck Resilience
● Raw Material Dynamics & Upstream Pressures
The packaging industry's upstream base is divided across large-scale commodity petrochemical suppliers (polyethylene, polypropylene, PET), specialty engineering chemical firms (PMMA, EVOH, elastomers), industrial mineral glass cullet processors, and primary aluminum converters. Midstream converters face continuous margin exposure linked directly to crude oil benchmarks, electricity and natural gas inputs for glass and metal melting furnaces, and regional supply-demand imbalances.
To insulate operating margins, sophisticated converters implement index-linked pricing contracts, formulaic resin pass-through clauses, and dual-sourcing programs for critical inputs like EVOH and optical-grade PMMA. Tooling fabrication constitutes a vital upstream barrier; companies that operate dedicated high-precision CNC tooling centers control multi-cavity mold production internally, achieving lower cycle times, tighter part tolerances, and faster speed-to-market than competitors reliant on third-party mold makers.
● Midstream Converting & Value-Add Secondary Finishing
The midstream is the core operational engine of the industry. Base conversion operations—such as multi-cavity injection molding, stretch blow molding, glass furnace feeding, and aluminum impact extrusion—operate as capital-intensive baselines.
True enterprise value and margin expansion are unlocked through precision downstream processing and multi-component assembly:
- Cleanroom Assembly: Automated high-speed assembly of dispensing mechanisms containing up to eight individual components, operating at speeds exceeding 120 units per minute with zero visual defects.
- Surface Engineering: Vacuum metallization, automated spray lacquering, high-definition silkscreening, multi-axis hot-stamping, and in-mold labeling (IML). These processes convert simple plastic and glass blanks into luxury visual touchpoints.
- Barrier Application: Plasma deposition and co-extrusion technology to deposit nanoscale silica or EVOH barrier coatings inside plastic containers.
● Downstream Channel Dynamics & Commercial Models
Converters interface with the beauty ecosystem through three primary business channels:
- Direct FMCG Strategic Accounts: Long-term global enterprise supply agreements with beauty conglomerates. Characterized by multi-year stability, high production volumes, shared mold investments, and rigorous vendor scorecards evaluating carbon emissions and quality control.
- Contract Fillers and OEM/ODM Manufacturers: Converters provide components directly to third-party contract formulators who blend bulk product, fill containers, and assemble final SKUs for brands. To capture additional value, leading packaging converters are backwards-integrating, establishing internal compounding, filling, and packaging lines to market complete turnkey solutions.
- Industrial Distributor Networks & Emerging Brands: Packaging producers leverage regional distributors to service early-stage and indie beauty brands. Distributors manage inventory holding costs and buffer stock, allowing converters to capture high unit margins on stock bottle and pump formats without managing micro-order minimum order quantities (MOQs).
Regional Market Dynamics
● North America
North America remains the premier commercial packaging market by gross revenue. Demand patterns show significant divergence across categories: while mass personal care lotion pumps, aluminum aerosol containers, and hair care bottles remain stable, prestige facial skincare packaging has experienced temporary volume corrections linked to retailer inventory realignments and slower funding cycles for indie skincare brands.
Regional demand is pivoting toward functional convenience, e-commerce safe transit certification (ISTA-6 compliance to prevent leakage during parcel transit), and integrated flow-control silicone valves. Packaging operations in the United States and Mexico are increasingly constrained by raw material tariff volatility, driving brands toward domestic packaging fabrication to mitigate cross-border supply chain risks.
● Asia-Pacific
Asia-Pacific serves as both the highest-volume manufacturing base and the most dynamically evolving consumer market.
- China: Marked by structural market dynamics where domestic beauty brands ("C-Beauty") are capturing substantial market share through rapid product formulation cycles. Packaging converters operate within an intensely competitive operational layer between large petrochemical resin suppliers and consolidated brand owners, creating structural price competition in standard formats. The operational winners are converters pivoting to automated cleanrooms, precision glass manufacturing, and proprietary dispensing systems.
- Republic of Korea: Recognized as the global benchmark for mechanical innovation, specialized mold design, and rapid prototyping. South Korean converters lead the development of airtight cushion compacts, mechanical stick dispensers, and all-polyolefin airless pumps, servicing domestic K-Beauty brands and global luxury accounts.
- Southeast Asia (ASEAN): Thailand, Vietnam, and Indonesia are expanding rapidly as global beauty brands diversify production footprints outside mainland China. Foreign direct investment into local converting facilities is accelerating regional capacity for tube extrusion and blow-molded personal care packaging.
- Taiwan, China: Operates as an established technical hub for heavy-walled PMMA/acrylic cosmetic jars, precision plastic injection molding, and luxury secondary surface metallization.
- India: Serves as a global export center for high-volume barrier laminated tubes, supported by domestic engineering capabilities and expanding regional personal care consumption.
● Europe
Europe represents the global center of luxury beauty packaging design, fine perfumery glass manufacturing, and environmental packaging legislation. European demand is driven by high-end fragrance flacons, prestige dermo-cosmetic skincare jars, and sustainable design innovations.
While baseline consumer cosmetics demand expands moderately, the luxury perfumery and clinical dermo-cosmetic segments consistently outperform broader economic cycles. European converters lead the world in structural decarbonization, integrating electric and hybrid glass-melting furnaces, formulating circular polymers, and complying with the European Union’s Packaging and Packaging Waste Regulation (PPWR).
● South America
Anchored industrially by Brazil and Colombia, South America is a high-volume consumer packaging market characterized by elevated per capita consumption of hair care, personal deodorants, and body mists.
Packaging consumption centers on cost-effective, durable configurations: high-output lotion pumps, flexible refill pouches for shampoos and body cleansers, and collapsible laminated tubes. Direct-sales cosmetic conglomerates and regional beauty leaders direct packaging strategies toward high post-consumer resin integration and low-cost, refillable pouch systems.
● Middle East & Africa
The MEA territory functions as a dual-role regional ecosystem: an indigenous high-value consumer market for high-concentration perfumes (attars, Eau de Parfum) and an emerging manufacturing hub connecting South Asia and Southern Europe.
In the Gulf Cooperation Council (GCC) nations, consumer preference demands heavy glass flacons, intricate metallic closures, and elaborate secondary presentation boxes. In North and Sub-Saharan Africa, market demand is focused on foundational personal care packaging, highlighting low unit-cost flexible sachets, small-format tubes, and economy polyolefin jars.
Company Profiles: Strategic Pivots & Operational Moats
1. Prestige & Specialty Glass Flacons and Containers
● Verescence: Transitioning operational capacity toward fully decarbonized luxury glass making, utilizing advanced electric-furnace melting technologies alongside commercial-scale PCR cullet integration.
● Groupe Pochet (Pochet du Courval): Integrating multi-material luxury hardware with sustainable glass finishing, executing closed-loop water treatment and low-carbon thermal finishing.
● Heinz-Glas Group: Deployment of hybrid electric melting furnaces to achieve near-zero carbon container production, paired with the internal engineering of matching monomaterial closures.
● Stoelzle Glass Group: Expansion of specialized dermo-cosmetic and selective perfumery production lines, prioritizing rapid mold customization and low-energy feeder-coloration techniques.
● Bormioli Luigi S.p.A.: Focus on ultra-high transmission, sparkling flint glass for niche and selective fragrance houses, eliminating intermediate plastic components via direct glass-on-glass sealing stoppers.
● PGP Glass Limited: Geographic capacity optimization across South Asia and North America, delivering high-volume cosmetic containers with low total landed costs.
● Gerresheimer AG: Direct convergence of medical-grade pharmaceutical manufacturing standards with luxury dermo-cosmetic primary packaging.
● Guangdong Huaxing Glass Co., Ltd.: Modernization of large-scale glass melting infrastructure via automated inspection and energy optimization systems to serve growing domestic Chinese beauty brands.
2. Dispensing Systems, Precision Pumps & Airless Solutions
● AptarGroup, Inc.: Complete redesign of legacy mechanical dispensing platforms into certified fully-recyclable mono-material PE and PP pump engines; expansion of micro-dispensing sampling lines.
● Silgan Holdings Inc.: Aggressive portfolio conversion toward all-polyolefin, metal-free dispensing systems (Pearl and Sinfonia lines) engineered for complete recycling compatibility.
● Yonwoo Co., Ltd.: Integration into the Kolmar Korea industrial platform, creating end-to-end formulation-to-packaging development cycles for dermo-cosmetics and prestige skincare.
● Lumson S.p.A.: Industrialization of high-end luxury circular dispensing platforms, combining aesthetic glass vessels with separable pouch-in-bottle airless internal architectures.
● PUM-TECH KOREA Co., Ltd.: Rapid commercialization of complex mechanical delivery formats, including airtight cushion compacts and all-PP mono-material twist dispensing sticks.
● Zhejiang Z&Z Industrial Co., Ltd.: Automation of mass-market dispensing pump assembly lines to achieve cost leadership while qualifying mono-material polyolefin spray mechanisms.
3. Extruded & Laminated Barrier Tubes
● EPL Limited: Complete commercial transition from traditional multi-material aluminum barrier tubes to fully recyclable mono-material Platina (all-HDPE) laminates.
● TUPACK Groupe: Integration of high-percentage post-consumer recycled polyolefins into seamless extruded tubes for selective dermo-skincare lines.
● Shenzhen Beauty Star Co., Ltd.: Vertical integration of sustainable raw materials, bio-based resins, and fully automated multi-axis decoration lines for tubes and rigid bottles.
4. Color Cosmetic Hardware & Rigid Plastic Components
● Albéa Group: Structural transformation toward circular color cosmetic components, featuring refillable guided lipstick mechanisms and mono-material mascara assemblies.
● PSB Industries: Development of 100% bio-sourced and circular polyolefin compacts and luxury makeup hardware through its Texen beauty business unit.
● Libo Cosmetics Co., Ltd.: Engineering of luxury refillable makeup systems, utilizing interchangeable internal polymer cartridges enclosed in durable metal-plastic hybrid chassis.
● Bookuk T&C Co., Ltd.: Development of advanced airtight and micro-dosing foundation compacts engineered for fluid, volatile makeup formulas.
● Yonyu Plastics Co., Ltd.: Backward integration into contract filling and formulation ODM services, paired with verified carbon footprint (CFP) certifications for European export lines.
● Zhejiang Jinsheng New Materials Co., Ltd.: Substitution of conventional acrylics with high-optical-clarity recyclable alternatives, while developing integrated double-wall container formats.
5. Metal Packaging, Impact-Extruded Aerosols & Metallized Hardware
● Ball Corporation: Commercial deployment of specialized low-carbon aluminum alloys (such as ReAl) incorporating up to 75% recycled scrap into impact-extruded aerosol cans.
● Massilly Group: Expansion of decorative tinplate packaging portfolios as sustainable, plastic-free gift packaging solutions for luxury fragrance houses.
● Tecnocap Group: Modernization of impact extrusion lines to produce infinitely recyclable aluminum monobloc bottles and aerosol containers paired with specialty metal closures.
● Zhejiang Axilone Shunhua Aluminium & Plastic Co., Ltd.: Application of automated physical vapor deposition and zero-discharge anodization processes to manufacture luxury hardware components.
6. Secondary Paperboard & Specialty Folding Cartons
● Shanghai Sunglow Packaging Technology Co., Ltd.: Deployment of structural anti-counterfeiting tracking technology and UV-cured low-migration inks across luxury secondary packaging lines.
● Sonoco Products Company: Transitioning secondary fragrance canisters and beauty cylinders toward 100% uncoated recycled paperboard (URB) with bio-based barrier linings.
Operational Moat: World-class engineering in spiral-wound paperboard canisters, rigid cylindrical composite packaging, and luxury retail display structures.
7. Global Diversified Packaging Conglomerates Platforms
● Amcor plc: Execution of comprehensive portfolio circularity, commercializing all-polyolefin spouted refill pouches and high-PCR rigid bottles for global personal care brands.
● Ileos Group: Historical private-equity platform whose structural breakup shaped the modern beauty packaging supply chain (yielding independent market leaders Axilone and Arcade Beauty).
Strategic Opportunities
● Margin Capture via the High-Barrier Tube Transition
As FMCG brands seek cost and weight reductions by transitioning away from rigid containers, laminated barrier tubes offer superior value capture. Converters operating proprietary mono-material all-HDPE and all-PP barrier platforms with EVOH layers are expanding operating margins significantly. By securing official RecyClass and APR Class A certifications, suppliers establish preferred vendor status with multinational accounts, extracting pricing premiums over commodity extruded tubes while protecting formulations from oxidation.
● The Economics of the Circularity Premium
Brand owners are under regulatory deadlines to eliminate unrecyclable mixed-material packaging. Packaging converters that successfully commercialize functional, mono-material dispensing engines—specifically metal-free, all-polyolefin lotion and spray pumps—can capture a sustained circularity premium. These mechanical innovations eliminate internal stainless steel springs in favor of precision plastic flexure engines, allowing consumers to discard the entire container into standard recycling streams without component disassembly.
● Operational Expansion into Medical Aesthetics
The crossover of dermatological skincare into medical-grade clinical beauty represents a highly defensive, high-margin opportunity. By investing in Class 7 and Class 8 ISO cleanrooms, automated optical sorting, and Type I neutral borosilicate glass lines, converters can transition from price-competitive cosmetic jars into high-value ampoules, de-sulfurized vials, and pre-fillable syringe systems. These formats command high gross margins and insulate converters from typical beauty fashion cycles through clinical validation barriers.
● The Turnkey Integration Frontier
Midstream converters are moving beyond simple component manufacturing by backwards-integrating into formulation research, blending, and automated contract filling. By delivering a turnkey "formula + container + outer carton" ODM solution, converters capture broader value across the supply chain, lower transactional friction for emerging beauty brands, and create substantial switching barriers compared to pure component molders.
Operational Challenges & Structural Risks
● Petrochemical Volatility and Lack of Price Pass-Through Protection
Thermoplastic resins (PP, PE, PMMA, PETG), aluminum slugs, and natural gas represent the primary operating cost inputs for packaging converters. Global crude oil price swings and geopolitical disruptions directly threaten converting gross margins. Converters that fail to negotiate formal, contractually indexed price pass-through mechanisms with downstream brand owners face immediate margin compression during inflationary spikes.
● Brand Volatility in the Indie Segment vs. Enterprise Concentration
While direct enterprise supply agreements with multinational FMCG conglomerates provide multi-year volume baselines, they enforce strict margin limits and rigorous vendor scorecards. Conversely, emerging venture-backed "indie" brands offer higher unit pricing but present elevated demand volatility, brief SKU lifecycles, and high default risks. Converters must actively balance their portfolio risks between large-account volume stability and indie-brand profitability.
● Structural Overcapacity in Commoditized Converting Formats
In standard, low-barrier formats—specifically open-mouth injection-molded PP jars and basic extrusion blow-molded bottles—regional overcapacity remains persistent across East Asia and Southeast Asia. The low capital cost of standard converting equipment has saturated the low-to-mid tier market, driving predatory pricing. Converters operating in this layer without proprietary intellectual property, unique aesthetic finishing, or integrated cleanrooms face ongoing margin degradation.
● Capital Expenditure Strain from Environmental Compliance
Complying with complex global environmental mandates—such as the EU PPWR, global Extended Producer Responsibility registries, and corporate Scope 1-3 decarbonization roadmaps—demands relentless capital deployment. Mid-sized converters must continuously direct capital toward multi-cavity all-electric molding machinery, optical quality inspection automation, digital carbon accounting systems, and clean energy retrofits. Firms unable to finance these continuous balance-sheet investments risk operational exclusion from elite global packaging supply chains.
1.1 Study Framework and Scope Definition 1
1.2 Research Methodology and Statistical Modeling 2
1.2.1 Primary Data Sourcing and Expert Delphi Panels 2
1.2.2 Secondary Data Synthesis and Econometric Triangulation 3
1.3 Market Estimation Architecture and Forecasting Assumptions (2021-2031) 4
1.4 Standardized Industry Abbreviations and Unit Metrics 5
Chapter 2 Global Cosmetics & Fragrances Packaging Market Landscape and Macro Trends 7
2.1 Global Market Valuation and Volume Trajectory (2021-2031) 7
2.2 Cross-Industry Megatrends: Circular Economy Mandates, PCR Adoption, and Refillable Architectures 9
2.3 Regulatory Compliance 11
2.4 Premiumization vs. Mass-Market Cost Pressures: Strategic Margin Analysis 13
Chapter 3 Global Supply Chain Architecture and Upstream Feedstock Dynamics 14
3.1 Upstream Raw Material 14
3.2 Packaging Manufacturing Process Matrix 16
3.3 Margin Waterfall and Value Capture Across Conversion Tiers 18
3.4 Supply Chain Vulnerability Mapping: Dual-Sourcing Strategies and Decoupling Risks 19
Chapter 4 Global Cosmetics & Fragrances Packaging Market Breakdown by Material 21
4.1 Glass Packaging 21
4.2 Rigid & Flexible Plastics 23
4.3 Metal Packaging 25
4.4 Paperboard & Fiber Packaging 27
Chapter 5 Global Cosmetics & Fragrances Packaging Market Breakdown by Packaging Format 29
5.1 Bottles & Flacons: Perfumery Masterpieces, Serums, and Rotary Crimp Dispensing Systems 29
5.2 Jars & Pots: High-Wall Luxury Cosmetic Jars and Refillable Polymer Pods 31
5.3 Tubes: Multi-Layer Polyfoil, Barrier Laminate (ABL/PBL), and Extruded Sleeves 33
5.4 Sticks & Pens: Precision Lip Care, Foundation Twist Mechanisms, and Concealer Applicators 34
5.5 Compacts & Palettes: Single-Material Cushion Cases, Magnetic Closures, and Pan Systems 35
Chapter 6 Global Cosmetics & Fragrances Packaging Market Breakdown by Downstream Application 37
6.1 Fragrances & Perfumery 37
6.2 Skin Care 39
6.3 Color Cosmetics 41
6.4 Hair Care & Styling 42
6.5 Personal Care & Toiletries 43
6.6 Medical-Grade Aesthetics & Subcutaneous Cosmetics 44
Chapter 7 Global Trade Dynamics, Export-Import Flows, and Cross-Border Tariffs 45
7.1 Global Trade Corridor Mapping: Trans-Pacific, Inter-European, and Intra-Asian Freight Flux 45
7.2 Export Powerhouses: Chinese Molded Plastics, French Prestige Glass, and Italian Custom Componentry 47
7.3 Nearshoring and Regional Supply Hub Realignments 49
Chapter 8 Regional and Country-Level Market Analysis: Primary Manufacturing Hubs & Consumption Centers 51
8.1 North America: High Consumption Intensity and Localized Filling Automation 51
8.1.1 United States: Premiumization Engines, Indie Brand Expansion, and Onshore Supply Reconfiguration 52
8.1.2 Canada and Mexico: Contract Filling Specialization and Cross-Border Assembly 53
8.2 Europe: Luxury Heritage, High-Performance Flaconnage, and Regulatory Vanguard 54
8.2.1 France: Prestige Fragrance Ecosystems and Cosmetic Valley Precision Injection 55
8.2.2 Germany: High-Precision Engineered Glass and Sustainable Polymer Compounding 56
8.2.3 Italy & Rest of Europe Market 57
8.3 Asia-Pacific: Massive Manufacturing Hubs and Exploding Skincare Consumption 58
8.3.1 China: Global Conversion Epicenter, Tooling Supremacy, and Integrated Decoration Capabilities 58
8.3.2 South Korea: K-Beauty Airless Innovation, Rapid Prototyping, and Cushion Mechanism Leadership 58
8.3.3 Japan: Precision Dispensing Tolerances, Ultra-High-End Finishing, and Circular Resin Research 58
8.3.4 India & Southeast Asia: Expanding Low-Cost Manufacturing Clusters, Tube Extrusion, and Domestic Consumer Scale 58
8.3.5 Taiwan (China): High-Precision Plastic Tooling, Acrylic Containers, and Cosmetic Component Export 58
8.4 Latin America & Middle East: Emerging Prestige Consumption and Fragrance Capital Expenditure 58
Chapter 9 Industry Competitive Dynamics, Market Concentration and Capacity Share 59
9.1 Tier-1 vs. Tier-2 Strategic Positioning Matrix 59
9.2 Mergers, Acquisitions, and Horizontal Consolidation Dynamics 61
9.3 Tooling Capacity Utilization, Mold Amortization, and Minimum Order Quantity (MOQ) Benchmarks 63
Chapter 10 Company Profiles and Operational Metrics 65
10.1 Amcor plc 65
10.1.1 Corporate Profile and Strategic Footprint 65
10.1.2 Product Portfolio and Manufacturing Footprint 66
10.1.3 Strategic SWOT Matrix 67
10.1.4 Financial Performance and Product Segment Margins (2021-2026) 68
10.2 AptarGroup 69
10.2.1 Corporate Profile and Strategic Footprint 69
10.2.2 Product Portfolio and Manufacturing Footprint 70
10.2.3 Strategic SWOT Matrix 71
10.2.4 Financial Performance and Product Segment Margins (2021-2026) 72
10.3 Silgan Holdings 73
10.3.1 Corporate Profile and Strategic Footprint 73
10.3.2 Product Portfolio and Manufacturing Footprint 74
10.3.3 Strategic SWOT Matrix 75
10.3.4 Financial Performance and Product Segment Margins (2021-2026) 76
10.4 Sonoco 77
10.4.1 Corporate Profile and Strategic Footprint 77
10.4.2 Product Portfolio and Manufacturing Footprint 78
10.4.3 Strategic SWOT Matrix 79
10.4.4 Financial Performance and Product Segment Margins (2021-2026) 80
10.5 Ball Corp. 81
10.5.1 Corporate Profile and Strategic Footprint 81
10.5.2 Product Portfolio and Manufacturing Footprint 82
10.5.3 Strategic SWOT Matrix 83
10.5.4 Financial Performance and Product Segment Margins (2021-2026) 84
10.6 Gerresheimer AG 85
10.6.1 Corporate Profile and Strategic Footprint 85
10.6.2 Product Portfolio and Manufacturing Footprint 86
10.6.3 Strategic SWOT Matrix 87
10.6.4 Financial Performance and Product Segment Margins (2021-2026) 88
10.7 Albéa 89
10.7.1 Corporate Profile and Strategic Footprint 89
10.7.2 Product Portfolio and Manufacturing Footprint 90
10.7.3 Strategic SWOT Matrix 91
10.7.4 Financial Performance and Product Segment Margins (2021-2026) 92
10.8 Massilly 93
10.8.1 Corporate Profile and Strategic Footprint 93
10.8.2 Product Portfolio and Manufacturing Footprint 94
10.8.3 Strategic SWOT Matrix 95
10.8.4 Financial Performance and Product Segment Margins (2021-2026) 96
10.9 Tecnocap 97
10.9.1 Corporate Profile and Strategic Footprint 97
10.9.2 Product Portfolio and Manufacturing Footprint 98
10.9.3 Strategic SWOT Matrix 99
10.9.4 Financial Performance and Product Segment Margins (2021-2026) 100
10.10 Groupe Pochet 101
10.10.1 Corporate Profile and Strategic Footprint 101
10.10.2 Product Portfolio and Manufacturing Footprint 102
10.10.3 Strategic SWOT Matrix 103
10.10.4 Financial Performance and Product Segment Margins (2021-2026) 104
10.11 TUPACK Groupe 105
10.11.1 Corporate Profile and Strategic Footprint 105
10.11.2 Product Portfolio and Manufacturing Footprint 106
10.11.3 Strategic SWOT Matrix 107
10.11.4 Financial Performance and Product Segment Margins (2021-2026) 108
10.12 Ileos Group 109
10.12.1 Corporate Profile and Strategic Footprint 109
10.12.2 Product Portfolio and Manufacturing Footprint 110
10.12.3 Strategic SWOT Matrix 111
10.12.4 Financial Performance and Product Segment Margins (2021-2026) 112
10.13 Verescence 113
10.13.1 Corporate Profile and Strategic Footprint 113
10.13.2 Product Portfolio and Manufacturing Footprint 114
10.13.3 Strategic SWOT Matrix 115
10.13.4 Financial Performance and Product Segment Margins (2021-2026) 116
10.14 PSB Industries 117
10.14.1 Corporate Profile and Strategic Footprint 117
10.14.2 Product Portfolio and Manufacturing Footprint 118
10.14.3 Strategic SWOT Matrix 119
10.14.4 Financial Performance and Product Segment Margins (2021-2026) 120
10.15 Heinz-Glas Group 121
10.15.1 Corporate Profile and Strategic Footprint 121
10.15.2 Product Portfolio and Manufacturing Footprint 122
10.15.3 Strategic SWOT Matrix 123
10.15.4 Financial Performance and Product Segment Margins (2021-2026) 124
10.16 Stoelzle Glass Group 125
10.16.1 Corporate Profile and Strategic Footprint 125
10.16.2 Product Portfolio and Manufacturing Footprint 126
10.16.3 Strategic SWOT Matrix 127
10.16.4 Financial Performance and Product Segment Margins (2021-2026) 128
10.17 Bormioli Luigi S.p.A. 129
10.17.1 Corporate Profile and Strategic Footprint 129
10.17.2 Product Portfolio and Manufacturing Footprint 130
10.17.3 Strategic SWOT Matrix 131
10.17.4 Financial Performance and Product Segment Margins (2021-2026) 132
10.18 Lumson S.p.A. 133
10.18.1 Corporate Profile and Strategic Footprint 133
10.18.2 Product Portfolio and Manufacturing Footprint 134
10.18.3 Strategic SWOT Matrix 135
10.18.4 Financial Performance and Product Segment Margins (2021-2026) 136
10.19 PUM-TECH KOREA Co. Ltd. 137
10.19.1 Corporate Profile and Strategic Footprint 137
10.19.2 Product Portfolio and Manufacturing Footprint 138
10.19.3 Strategic SWOT Matrix 139
10.19.4 Financial Performance and Product Segment Margins (2021-2026) 140
10.20 Yonwoo 141
10.20.1 Corporate Profile and Strategic Footprint 141
10.20.2 Product Portfolio and Manufacturing Footprint 142
10.20.3 Strategic SWOT Matrix 143
10.20.4 Financial Performance and Product Segment Margins (2021-2026) 144
10.21 Bookuk T&C 145
10.21.1 Corporate Profile and Strategic Footprint 145
10.21.2 Product Portfolio and Manufacturing Footprint 146
10.21.3 Strategic SWOT Matrix 147
10.21.4 Financial Performance and Product Segment Margins (2021-2026) 148
10.22 PGP Glass Limited 149
10.22.1 Corporate Profile and Strategic Footprint 149
10.22.2 Product Portfolio and Manufacturing Footprint 150
10.22.3 Strategic SWOT Matrix 151
10.22.4 Financial Performance and Product Segment Margins (2021-2026) 152
10.23 EPL Limited 153
10.23.1 Corporate Profile and Strategic Footprint 153
10.23.2 Product Portfolio and Manufacturing Footprint 154
10.23.3 Strategic SWOT Matrix 155
10.23.4 Financial Performance and Product Segment Margins (2021-2026) 156
10.24 Shanghai Sunglow Packaging Technology Co Ltd. 157
10.24.1 Corporate Profile and Strategic Footprint 157
10.24.2 Product Portfolio and Manufacturing Footprint 158
10.24.3 Strategic SWOT Matrix 159
10.24.4 Financial Performance and Product Segment Margins (2021-2026) 160
10.25 Yonyu Plastics Co. Ltd. 161
10.25.1 Corporate Profile and Strategic Footprint 161
10.25.2 Product Portfolio and Manufacturing Footprint 162
10.25.3 Strategic SWOT Matrix 163
10.25.4 Financial Performance and Product Segment Margins (2021-2026) 164
10.26 Zhejiang Jinsheng New Materials Co. Ltd. 165
10.26.1 Corporate Profile and Strategic Footprint 165
10.26.2 Product Portfolio and Manufacturing Footprint 166
10.26.3 Strategic SWOT Matrix 167
10.26.4 Financial Performance and Product Segment Margins (2021-2026) 168
10.27 Libo Cosmetics 169
10.27.1 Corporate Profile and Strategic Footprint 169
10.27.2 Product Portfolio and Manufacturing Footprint 170
10.27.3 Strategic SWOT Matrix 171
10.27.4 Financial Performance and Product Segment Margins (2021-2026) 172
10.28 Zhejiang Z&Z Industrial 173
10.28.1 Corporate Profile and Strategic Footprint 173
10.28.2 Product Portfolio and Manufacturing Footprint 174
10.28.3 Strategic SWOT Matrix 175
10.28.4 Financial Performance and Product Segment Margins (2021-2026) 176
10.29 Shenzhen Beauty Star 177
10.29.1 Corporate Profile and Strategic Footprint 177
10.29.2 Product Portfolio and Manufacturing Footprint 178
10.29.3 Strategic SWOT Matrix 179
10.29.4 Financial Performance and Product Segment Margins (2021-2026) 180
10.30 Zhejiang Axilone Shunhua Aluminium & Plastic Co. Ltd. 181
10.30.1 Corporate Profile and Strategic Footprint 181
10.30.2 Product Portfolio and Manufacturing Footprint 182
10.30.3 Strategic SWOT Matrix 183
10.30.4 Financial Performance and Product Segment Margins (2021-2026) 184
10.31 Guangdong Huaxing Glass Co.Ltd. 185
10.31.1 Corporate Profile and Strategic Footprint 185
10.31.2 Product Portfolio and Manufacturing Footprint 186
10.31.3 Strategic SWOT Matrix 187
10.31.4 Financial Performance and Product Segment Margins (2021-2026) 188
Table 2 Regulatory Parameters for Recycled Content and Single-Use Restrictions by Target Geography 12
Table 3 Raw Material Price Evolution: Glass Cullet, Virgin Polypropylene, Recycled PET, and Pure Aluminum (2021-2026) 15
Table 4 Global Cosmetics & Fragrances Packaging Market Value by Material, 2021-2026 (USD Million) 22
Table 5 Global Cosmetics & Fragrances Packaging Market Value Forecast by Material, 2027-2031 (USD Million) 22
Table 6 Global Cosmetics & Fragrances Packaging Market Volume by Material, 2021-2026 (Million Units) 24
Table 7 Global Cosmetics & Fragrances Packaging Market Volume Forecast by Material, 2027-2031 (Million Units) 26
Table 8 Global Cosmetics & Fragrances Packaging Market Value by Packaging Format, 2021-2026 (USD Million) 30
Table 9 Global Cosmetics & Fragrances Packaging Market Value Forecast by Packaging Format, 2027-2031 (USD Million) 32
Table 10 Global Cosmetics & Fragrances Packaging Market Volume by Packaging Format, 2021-2026 (Million Units) 34
Table 11 Global Cosmetics & Fragrances Packaging Market Volume Forecast by Packaging Format, 2027-2031 (Million Units) 36
Table 12 Global Cosmetics & Fragrances Packaging Market Value by Downstream Application, 2021-2026 (USD Million) 38
Table 13 Global Cosmetics & Fragrances Packaging Market Value Forecast by Downstream Application, 2027-2031 (USD Million) 40
Table 14 Global Cosmetics & Fragrances Packaging Market Volume by Downstream Application, 2021-2026 (Million Units) 42
Table 15 Global Cosmetics & Fragrances Packaging Market Volume Forecast by Downstream Application, 2027-2031 (Million Units) 44
Table 16 Cross-Border Freight Volumes and Tariffs by Core Trade Lane (2021-2026) 46
Table 17 Global Cosmetics & Fragrances Packaging Market Value by Region, 2021-2026 (USD Million) 52
Table 18 Global Cosmetics & Fragrances Packaging Market Value Forecast by Region, 2027-2031 (USD Million) 54
Table 19 North America Market Breakdown by Packaging Material, 2021-2026 (USD Million) 53
Table 20 Europe Market Breakdown by Packaging Material, 2021-2026 (USD Million) 56
Table 21 Asia-Pacific Market Breakdown by Packaging Material, 2021-2026 (USD Million) 58
Table 22 Tier-1 Packaging Manufacturers Market Concentration Ratios (CR4, CR8, HHI) (2021-2026) 60
Table 23 Recent Major Mergers, Acquisitions, and Divestitures in Cosmetics Packaging (2021-2026) 62
Table 24 Tooling CapEx, Average Cycle Times, and Amortization Schedules by Component Format 64
Table 25 Amcor plc Cosmetics & Fragrances Packaging Revenue, Cost and Gross Margin (2021-2026) 68
Table 26 AptarGroup Cosmetics & Fragrances Packaging Revenue, Cost and Gross Margin (2021-2026) 72
Table 27 Silgan Holdings Cosmetics & Fragrances Packaging Revenue, Cost and Gross Margin (2021-2026) 76
Table 28 Sonoco Cosmetics & Fragrances Packaging Revenue, Cost and Gross Margin (2021-2026) 80
Table 29 Ball Corp. Cosmetics & Fragrances Packaging Revenue, Cost and Gross Margin (2021-2026) 84
Table 30 Gerresheimer AG Cosmetics & Fragrances Packaging Revenue, Cost and Gross Margin (2021-2026) 88
Table 31 Albéa Cosmetics & Fragrances Packaging Revenue, Cost and Gross Margin (2021-2026) 92
Table 32 Massilly Cosmetics & Fragrances Packaging Revenue, Cost and Gross Margin (2021-2026) 96
Table 33 Tecnocap Cosmetics & Fragrances Packaging Revenue, Cost and Gross Margin (2021-2026) 100
Table 34 Groupe Pochet Cosmetics & Fragrances Packaging Revenue, Cost and Gross Margin (2021-2026) 104
Table 35 TUPACK Groupe Cosmetics & Fragrances Packaging Revenue, Cost and Gross Margin (2021-2026) 108
Table 36 Ileos Group Cosmetics & Fragrances Packaging Revenue, Cost and Gross Margin (2021-2026) 112
Table 37 Verescence Cosmetics & Fragrances Packaging Revenue, Cost and Gross Margin (2021-2026) 116
Table 38 PSB Industries Cosmetics & Fragrances Packaging Revenue, Cost and Gross Margin (2021-2026) 120
Table 39 Heinz-Glas Group Cosmetics & Fragrances Packaging Revenue, Cost and Gross Margin (2021-2026) 124
Table 40 Stoelzle Glass Group Cosmetics & Fragrances Packaging Revenue, Cost and Gross Margin (2021-2026) 128
Table 41 Bormioli Luigi S.p.A. Cosmetics & Fragrances Packaging Revenue, Cost and Gross Margin (2021-2026) 132
Table 42 Lumson S.p.A. Cosmetics & Fragrances Packaging Revenue, Cost and Gross Margin (2021-2026) 136
Table 43 PUM-TECH KOREA Co. Ltd. Cosmetics & Fragrances Packaging Revenue, Cost and Gross Margin (2021-2026) 140
Table 44 Yonwoo Cosmetics & Fragrances Packaging Revenue, Cost and Gross Margin (2021-2026) 144
Table 45 Bookuk T&C Cosmetics & Fragrances Packaging Revenue, Cost and Gross Margin (2021-2026) 148
Table 46 PGP Glass Limited Cosmetics & Fragrances Packaging Revenue, Cost and Gross Margin (2021-2026) 152
Table 47 EPL Limited Cosmetics & Fragrances Packaging Revenue, Cost and Gross Margin (2021-2026) 156
Table 48 Shanghai Sunglow Packaging Technology Co Ltd. Cosmetics & Fragrances Packaging Revenue, Cost and Gross Margin (2021-2026) 160
Table 49 Yonyu Plastics Co. Ltd. Cosmetics & Fragrances Packaging Revenue, Cost and Gross Margin (2021-2026) 164
Table 50 Zhejiang Jinsheng New Materials Co. Ltd. Cosmetics & Fragrances Packaging Revenue, Cost and Gross Margin (2021-2026) 168
Table 51 Libo Cosmetics Cosmetics & Fragrances Packaging Revenue, Cost and Gross Margin (2021-2026) 172
Table 52 Zhejiang Z&Z Industrial Cosmetics & Fragrances Packaging Revenue, Cost and Gross Margin (2021-2026) 176
Table 53 Shenzhen Beauty Star Cosmetics & Fragrances Packaging Revenue, Cost and Gross Margin (2021-2026) 180
Table 54 Zhejiang Axilone Shunhua Aluminium & Plastic Co. Ltd. Cosmetics & Fragrances Packaging Revenue, Cost and Gross Margin (2021-2026) 184
Table 55 Guangdong Huaxing Glass Co.Ltd. Cosmetics & Fragrances Packaging Revenue, Cost and Gross Margin (2021-2026) 188
Figure 1 Global Cosmetics & Fragrances Packaging Market Revenue and Growth Rate (2021-2031) 8
Figure 2 Price Spread Trajectory: Virgin Resins vs. Post-Consumer Recycled Feedstocks (2021-2026) 15
Figure 3 Manufacturing Value Chain Cost Allocation Breakdown (Raw Material, Tooling, Energy, Labor, Logistics) 18
Figure 4 Global Cosmetics & Fragrances Packaging Market Share by Material Type (2026 vs. 2031) 23
Figure 5 Global Cosmetics & Fragrances Packaging Market Share by Packaging Format (2026 vs. 2031) 31
Figure 6 Global Cosmetics & Fragrances Packaging Market Share by Downstream Application (2026 vs. 2031) 39
Figure 7 Major Global Trade Flux Routes and Container Volume Dispatches (2026) 47
Figure 8 Regional Market Value Breakdown: North America, Europe, Asia-Pacific, Latin America, Middle East & Africa (2021-2031) 51
Figure 9 Primary Production Footprints vs. Consumption Density by Country 55
Figure 10 Global Market Share Consolidation Curve (Top 5, Top 10, Remainder) (2021-2026) 60
Figure 11 Amcor plc Cosmetics & Fragrances Packaging Market Share (2021-2026) 68
Figure 12 AptarGroup Cosmetics & Fragrances Packaging Market Share (2021-2026) 72
Figure 13 Silgan Holdings Cosmetics & Fragrances Packaging Market Share (2021-2026) 76
Figure 14 Sonoco Cosmetics & Fragrances Packaging Market Share (2021-2026) 80
Figure 15 Ball Corp. Cosmetics & Fragrances Packaging Market Share (2021-2026) 84
Figure 16 Gerresheimer AG Cosmetics & Fragrances Packaging Market Share (2021-2026) 88
Figure 17 Albéa Cosmetics & Fragrances Packaging Market Share (2021-2026) 92
Figure 18 Massilly Cosmetics & Fragrances Packaging Market Share (2021-2026) 96
Figure 19 Tecnocap Cosmetics & Fragrances Packaging Market Share (2021-2026) 100
Figure 20 Groupe Pochet Cosmetics & Fragrances Packaging Market Share (2021-2026) 104
Figure 21 TUPACK Groupe Cosmetics & Fragrances Packaging Market Share (2021-2026) 108
Figure 22 Ileos Group Cosmetics & Fragrances Packaging Market Share (2021-2026) 112
Figure 23 Verescence Cosmetics & Fragrances Packaging Market Share (2021-2026) 116
Figure 24 PSB Industries Cosmetics & Fragrances Packaging Market Share (2021-2026) 120
Figure 25 Heinz-Glas Group Cosmetics & Fragrances Packaging Market Share (2021-2026) 124
Figure 26 Stoelzle Glass Group Cosmetics & Fragrances Packaging Market Share (2021-2026) 128
Figure 27 Bormioli Luigi S.p.A. Cosmetics & Fragrances Packaging Market Share (2021-2026) 132
Figure 28 Lumson S.p.A. Cosmetics & Fragrances Packaging Market Share (2021-2026) 136
Figure 29 PUM-TECH KOREA Co. Ltd. Cosmetics & Fragrances Packaging Market Share (2021-2026) 140
Figure 30 Yonwoo Cosmetics & Fragrances Packaging Market Share (2021-2026) 144
Figure 31 Bookuk T&C Cosmetics & Fragrances Packaging Market Share (2021-2026) 148
Figure 32 PGP Glass Limited Cosmetics & Fragrances Packaging Market Share (2021-2026) 152
Figure 33 EPL Limited Cosmetics & Fragrances Packaging Market Share (2021-2026) 156
Figure 34 Shanghai Sunglow Packaging Technology Co Ltd. Cosmetics & Fragrances Packaging Market Share (2021-2026) 160
Figure 35 Yonyu Plastics Co. Ltd. Cosmetics & Fragrances Packaging Market Share (2021-2026) 164
Figure 36 Zhejiang Jinsheng New Materials Co. Ltd. Cosmetics & Fragrances Packaging Market Share (2021-2026) 168
Figure 37 Libo Cosmetics Cosmetics & Fragrances Packaging Market Share (2021-2026) 172
Figure 38 Zhejiang Z&Z Industrial Cosmetics & Fragrances Packaging Market Share (2021-2026) 176
Figure 39 Shenzhen Beauty Star Cosmetics & Fragrances Packaging Market Share (2021-2026) 180
Figure 40 Zhejiang Axilone Shunhua Aluminium & Plastic Co. Ltd. Cosmetics & Fragrances Packaging Market Share (2021-2026) 184
Figure 41 Guangdong Huaxing Glass Co.Ltd. Cosmetics & Fragrances Packaging Market Share (2021-2026) 188
Research Methodology
- Market Estimated Methodology:
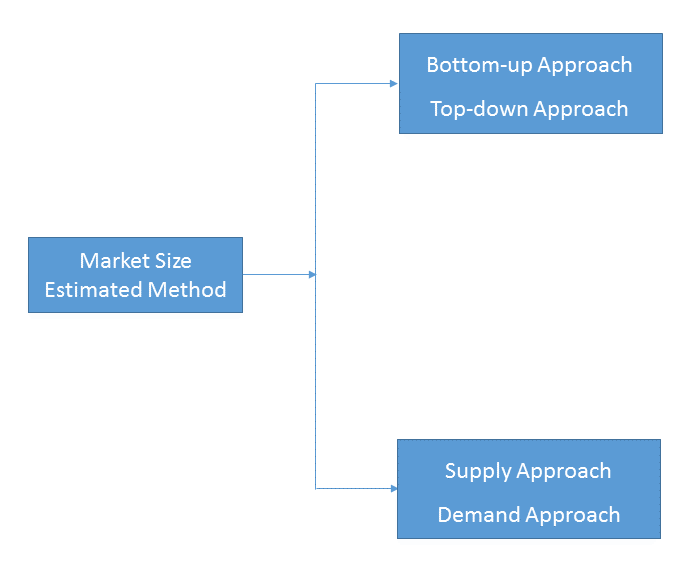
Bottom-up & top-down approach, supply & demand approach are the most important method which is used by HDIN Research to estimate the market size.
1)Top-down & Bottom-up Approach
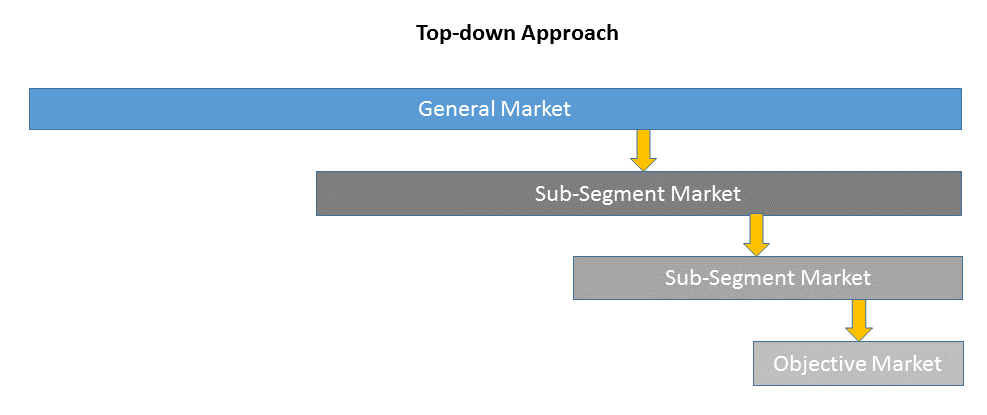
Top-down approach uses a general market size figure and determines the percentage that the objective market represents.
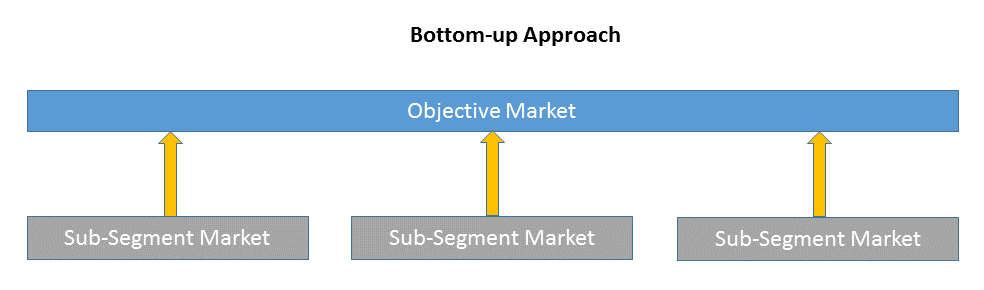
Bottom-up approach size the objective market by collecting the sub-segment information.
2)Supply & Demand Approach
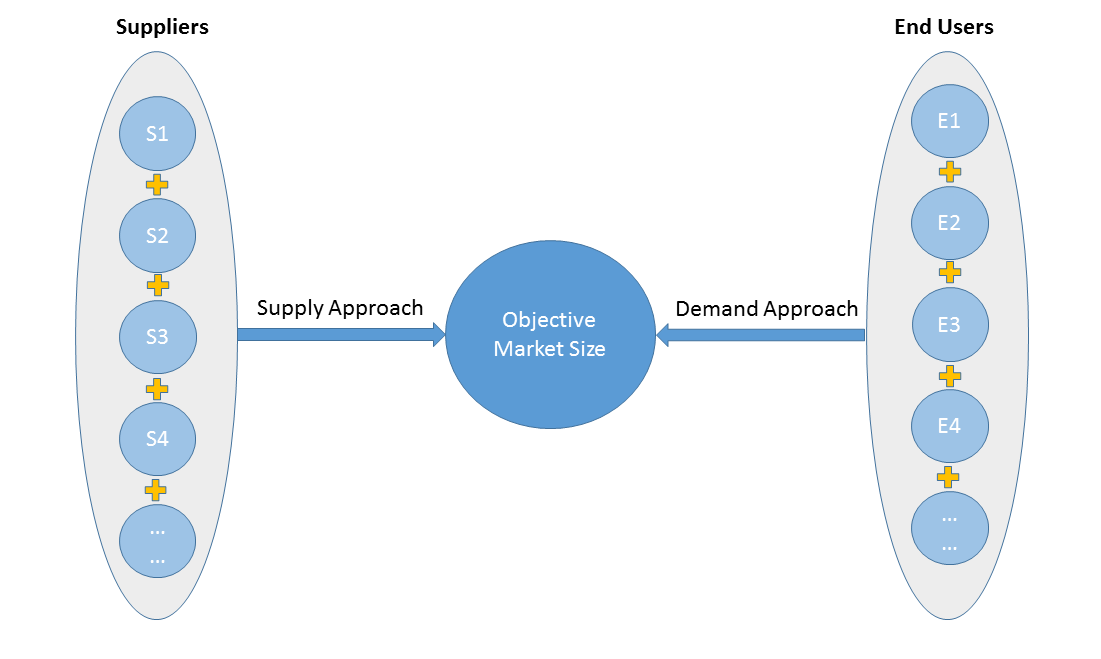
Supply approach is based on assessments of the size of each competitor supplying the objective market.
Demand approach combine end-user data within a market to estimate the objective market size. It is sometimes referred to as bottom-up approach.
- Forecasting Methodology
- Numerous factors impacting the market trend are considered for forecast model:
- New technology and application in the future;
- New project planned/under contraction;
- Global and regional underlying economic growth;
- Threatens of substitute products;
- Industry expert opinion;
- Policy and Society implication.
- Analysis Tools
1)PEST Analysis
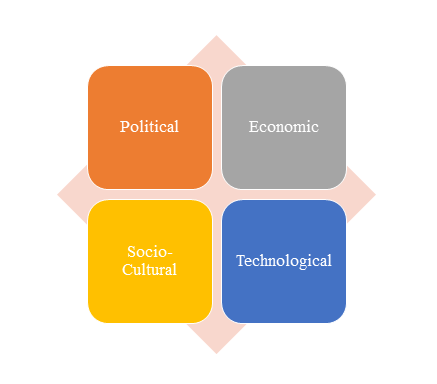
PEST Analysis is a simple and widely used tool that helps our client analyze the Political, Economic, Socio-Cultural, and Technological changes in their business environment.
- Benefits of a PEST analysis:
- It helps you to spot business opportunities, and it gives you advanced warning of significant threats.
- It reveals the direction of change within your business environment. This helps you shape what you’re doing, so that you work with change, rather than against it.
- It helps you avoid starting projects that are likely to fail, for reasons beyond your control.
- It can help you break free of unconscious assumptions when you enter a new country, region, or market; because it helps you develop an objective view of this new environment.
2)Porter’s Five Force Model Analysis
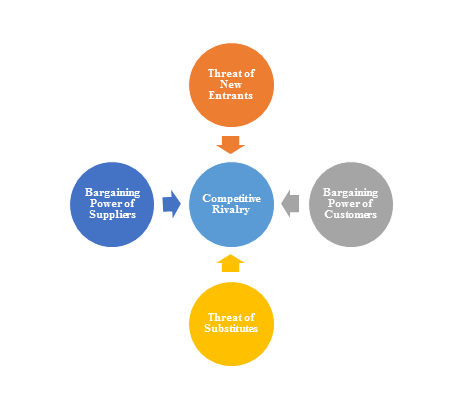
The Porter’s Five Force Model is a tool that can be used to analyze the opportunities and overall competitive advantage. The five forces that can assist in determining the competitive intensity and potential attractiveness within a specific area.
- Threat of New Entrants: Profitable industries that yield high returns will attract new firms.
- Threat of Substitutes: A substitute product uses a different technology to try to solve the same economic need.
- Bargaining Power of Customers: the ability of customers to put the firm under pressure, which also affects the customer's sensitivity to price changes.
- Bargaining Power of Suppliers: Suppliers of raw materials, components, labor, and services (such as expertise) to the firm can be a source of power over the firm when there are few substitutes.
- Competitive Rivalry: For most industries the intensity of competitive rivalry is the major determinant of the competitiveness of the industry.
3)Value Chain Analysis
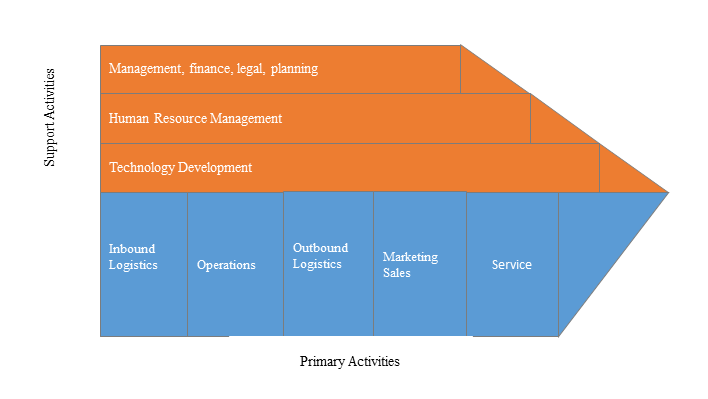
Value chain analysis is a tool to identify activities, within and around the firm and relating these activities to an assessment of competitive strength. Value chain can be analyzed by primary activities and supportive activities. Primary activities include: inbound logistics, operations, outbound logistics, marketing & sales, service. Support activities include: technology development, human resource management, management, finance, legal, planning.
4)SWOT Analysis
SWOT analysis is a tool used to evaluate a company's competitive position by identifying its strengths, weaknesses, opportunities and threats. The strengths and weakness is the inner factor; the opportunities and threats are the external factor. By analyzing the inner and external factors, the analysis can provide the detail information of the position of a player and the characteristics of the industry.
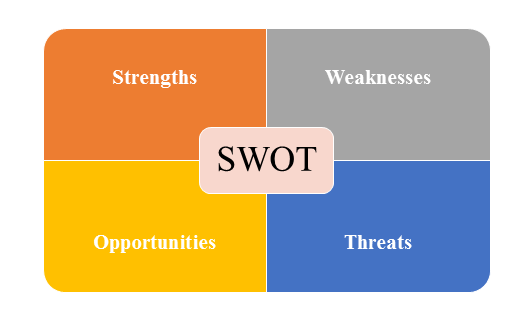
- Strengths describe what the player excels at and separates it from the competition
- Weaknesses stop the player from performing at its optimum level.
- Opportunities refer to favorable external factors that the player can use to give it a competitive advantage.
- Threats refer to factors that have the potential to harm the player.
- Data Sources
| Primary Sources | Secondary Sources |
|---|---|
| Face to face/Phone Interviews with market participants, such as: Manufactures; Distributors; End-users; Experts. Online Survey |
Government/International Organization Data: Annual Report/Presentation/Fact Book Internet Source Information Industry Association Data Free/Purchased Database Market Research Report Book/Journal/News |